Background information and methodology for financial year ending 2025
Published 22 October 2026
Applies to England, Scotland and Wales

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/statistics/income-related-benefits-estimates-of-take-up-financial-year-ending-2025/background-information-and-methodology-for-financial-year-ending-2025
Introduction
This background report accompanies the main Income-related benefits: estimates of take-up report for financial year ending (FYE) 2025.
These statistics are designed to give an estimate of the take-up of benefits within the entitled population. They aim to provide an indication of whether, and to what extent, Pension Credit (PC) and Housing Benefit (HB) are taken up by the pensioner population entitled to PC and HB. Additionally, to what extent Universal Credit (UC) or equivalent benefits are taken up by the working age population entitled to them. These have been included for the first time in the FYE 2025 release, as official statistics in development.
The purpose of this report is to provide further contextual information to aid understanding of the statistics presented in the main report and data tables. It outlines points to note as well as strengths and limitations of the information presented in each section of the main report, alternative data sources, as well as changes this year.
A detailed description of the estimates of take-up methodology, data processing and quality assurance is presented within the relevant sections in this report.
For further detail in years prior to FYE 2025, please refer to the FYE 2024 release, Background information and methodology for financial year ending 2024
This document, the statistics release and data tables, along with previous releases, can be found on the collections page.
Editorial Team
Publication Leads: Kate Martin, Julia Jagelman
Take-up team: John Bilverstone, Tommi Kelha, Priti Sunuwar, Daniel Kiddier
Acknowledgements
We wish to give special acknowledgement to:
- Michael Holland and the Policy Simulation Model team, for their contribution to the development and creation of these statistics
- all those who have contributed to the FYE 2025 publication, through their provision of quality assurance
Feedback
We welcome feedback.
If you have any comments or questions, please contact: irb.takeup@dwp.gov.uk
1. Overview of the statistics
1.1 History of the statistics
These statistics are designed to give an estimate of the take-up of benefits within the entitled pensioner and working age populations. They aim to provide an indication of whether, and to what extent:
- Pension Credit (PC) and Housing Benefit (HB) are taken up by the pensioner population entitled to them
- Universal Credit (UC) or equivalent benefits (see section 4) are taken up by the working age population entitled to them
The current broad methodology to produce the take-up statistics dates back to FYE 2020 for pensioner estimates, and the first UC (or equivalent benefits) estimates from the FYE 2025 publication. Take-up estimates using different methodologies have been produced for a number of years and the approach and publication have evolved over that time.
In recent years, this report focused on the methodology for the take-up estimates in the pension age population only, badged as Official Statistics. In this release we will also cover the methodology for the new take-up estimates in the working age population, which are Official Statistics in Development. As outlined by the Office for Statistics Regulation (OSR), these are defined as Official Statistics that are undergoing a development; they may be new or existing statistics, and will be tested with users, in line with the standards of trustworthiness, quality, and value in the Code of Practice for Statistics.
The Department for Work and Pensions (DWP) previously published estimates for working age take-up of income-related benefits. However, the introduction of Universal Credit (UC) in 2013 created a need for substantial methodological changes for the published report. In July 2012, these statistics underwent an initial consultation regarding the Proposed cessation of ‘Income related benefits: estimates of take-up’ statistics. Following this, the decision was made to reduce the coverage of benefits, with the FYE 2013 release being the last full year of data prior to major welfare reform.
From December 2018 there were no new claims for any of the working age legacy benefits/tax credits. Legacy benefits are the older, means-tested UK welfare payments that are replaced by Universal Credit. Therefore, from FYE 2020 onwards this publication was focused on take-up for pensioners only.
Estimates for legacy benefits/tax credits in the past can be found here: Income-related benefits: estimates of take-up and Child Tax Credit and Working Tax Credit (tax credits published by HMRC).
Since FYE 2020, DWP has continued to routinely publish annual Official Statistics on estimates of take-up for Pension Credit and Housing Benefit (for pension age only) in Great Britain. Meanwhile, information on the development of a new composite measure (‘composite’ meaning UC or equivalent legacy benefits/ tax credits) has been referenced in the public domain on the published Income-related benefits: estimates of take-up: release strategy and the Statistical work programme.
There were several complex conceptual and methodological issues we had to work through in the development of a methodology that takes account of both UC and legacy benefits/tax credits. For example, defining and calculating the estimate of Entitled Non-Recipients and their entitled amounts, as well as developing our understanding of new datasets for this analysis and creating our estimate of those in receipt.
We are now at a point where we have successfully worked through several data issues and can publish the first estimates of take-up of Universal Credit (or equivalent benefits) within the entitled working age population, in compliance with the Code of Practice for Statistics. This new composite measure assesses the take-up of Universal Credit or equivalent income-related benefits. While there are still large numbers of people in receipt of legacy benefits and tax credits, a UC-only take-up rate would not provide the full picture of what is happening for the entitled working age population. A composite measure is therefore required to allow an understanding of working age income-related benefit take-up overall.
Further information regarding the history of Income-related Benefits: Estimates of take-up can be found via the National Archives.
1.2 Status of the statistics
The statistics covering pension age benefits (Housing Benefit for pensioners and Pension Credit) are Official Statistics.
The statistics on take-up of working age benefits (UC or equivalent) are currently labelled as Official Statistics in Development.
They have undergone thorough quality assurance in line with the Code of Practice for Statistics. All types of Official Statistics should comply with the Code of Practice for Statistics which makes sure official statistics are trustworthy, have public value, and are of high quality. The strengths and limitations of these statistics are explained in section 10.
We will continue to refine our methodology to meet user needs and reflect changes in the benefit landscape. With the phased move to UC timetable, we expect transition into UC-only working age take-up estimates in FYE 2027. This publication is expected to be released in Autumn 2028. We will review if the estimates can be labelled as Official Statistics, and will continue to develop breakdowns provided based on user feedback.
These statistics are being published now to engage with current and potential users in the developments and make improvements that meet user needs. You can send your comments by email to: irb.takeup@dwp.gov.uk.
Our statistical practice is regulated by the Office for Statistics Regulation (OSR). OSR sets the standards of trustworthiness, quality, and value in the Code of Practice for Statistics that all producers of official statistics should adhere to.
You are welcome to contact us directly with any comments about how we meet these standards, by email to: irb.takeup@dwp.gov.uk.
Alternatively, you can contact OSR by emailing: regulation@statistics.gov.uk or via the Office for Statistics Regulation website.
1.3 Recent improvements to the statistics
The introduction of take-up statistics for Universal Credit (or equivalent benefits) from FYE 2024 as Official Statistics in Development. This change has led to a revised publication including new tables and an updated background information and methodology document. These estimates use a composite measure which draws from multiple data sources to capture take-up across the legacy benefits, tax credits and Universal Credit. This allows DWP to understand working age income-related benefit take-up as a whole and reinstates reporting in this area. For more detail please see section 6.
For FYE 2024, we incorporated improved linking of administrative data to the Family Resources Survey (FRS), to better identify those in receipt of Pension Credit, Housing Benefit, Universal Credit (or equivalent benefits). Take-up estimates were already based on administrative data linking and there were minimal impacts to estimates with this latest improvement to the approach used. This methodological change was implemented from FYE 2024 and was not backdated to previous years.
In March 2026, the first integrated Family Resources Survey based on linked benefits data was published, relating to FYE 2025 data. This has no impact on the take-up estimates as the FYE 2024 results were based on the same linking approach, but in effect means 1 less step in producing the publication as the administrative data linking is already incorporated in the source FRS data. For further details, please access this technical paper and quality assessment report.
We have amended figures in earlier years to account for leap years. This affects the conversion from weekly to annual expenditure estimates, but changes are small. This methodological improvement has been incorporated within this FYE 2025 release and therefore previous data should not be used.
2. Background Information
A comprehensive set of data tables complementing the results presented are available alongside the publication. These tables are referenced throughout the published report.
2.1 Relevance
These statistics can be used for:
- increasing awareness / take-up of benefits
- measuring the effect of take-up initiatives
- policy development
- answering ministerial briefings, ad-hoc enquiries, Freedom of Information (FOI) requests, and Parliamentary Questions (PQs) published on the UK Parliament website
There are both internal and external users of these statistics. It is a key source of information that is used to inform government thinking on relevant policies, as well as related programmes and projects. DWP uses these statistics for policy analysis, decision making, and answering queries. Our external users include press, journalists, researchers, academics, voluntary organisations, and charities. These groups use the statistics for research purposes and awareness.
2.2 Accessibility and Clarity
Accessibility
We have reviewed our publication tables and supporting guidance to ensure accessibility to users. For compliance with The Public Sector Bodies (Websites and Mobile Applications) Accessibility Regulations 2018, some formatting in the ODS tables, such as merged cells, has been avoided. For more information, please see the Accessibility statement for DWP statistics.
Clarity
Within each published data table, there is additional guidance to help in interpreting the take-up estimates. There is also a glossary of key terms, found at the end of this document (see section 12).
See section 9 for more detail on coherence and comparability, and section 10 for more information regarding the limitations and strengths of the statistics.
Contact email irb.takeup@dwp.gov.uk for further information.
2.3 Timeliness and Punctuality
Take-up statistics are modelled estimates based on FRS data. Modelling work to produce the Policy Simulation Model (PSM) dataset can only start once the final FRS dataset is published.
Given the use of the FRS, extensive quality assurance takes place before the FRS dataset is released, 12 months after fieldwork has been completed. See section 7 for more information on the detail.
Due to the complexity of the various data sources, take-up processes and quality assurance that is carried out, we now publish the take-up report approximately 6 to 7 months after the FRS publication.
In terms of punctuality, data has been released both as planned and as announced in the release calendar.
2.4 Confidentiality and security
Personal identifiers on the data provided from administrative systems are encrypted to prevent identification of individuals within the data.
Data is held securely. Access is only given to analysts who have completed internal data access and security training and who have the business need to access the data.
In accordance with the Code of Practice for Statistics (Trustworthiness, Be Transparent), access to statistics before their public release is limited to those involved in the production of the statistics and the preparation of the release, and for quality assurance and operational purposes. Analysis of data, either in tabular or chart form is given to a group of subject matter experts for quality assurance purposes.
Accurate records of those who have access before the data are finalised are maintained. Several controls are applied to this access.
Anyone with access prior to the publication release is made clear about their role and the need to prevent any disclosure that is any indication of the statistics or messages they convey. Access is restricted to named individuals within teams, who are restricted from discussing the statistics with their colleagues during that access period.
3. Concepts and definitions
Take-up refers to the receipt of benefits that a benefit unit or family is entitled to. Such a benefit unit is referred to as an Entitled Recipient (ER). There are also families who are entitled to benefits, but not in receipt of them. Such a family is referred to as an Entitled Non-Recipient (ENR).
The take-up rates are based on the following definition:
(In Receipt) ÷ (In Receipt + Entitled Not in Receipt)
Where the take-up rate is defined as the proportion receiving the benefit of all those entitled (that is those receiving the benefit they are entitled to and those who are entitled but not receiving the benefit).
Take-up is estimated in 2 ways – by caseload and by expenditure:
- caseload take-up compares the number of benefit recipients/families, averaged over the year, with the estimated number that would be receiving if everyone took up their entitlement for the full period of their entitlement
- expenditure take-up compares the total amount of benefit received, over a year, with the estimated total amount that would be received if everyone took up their entitlement for the full period of their entitlement
For both pensioner and working age benefit estimates, the same approach and definitions apply as above. However, for working age estimates this is a composite measure rather than take-up of a single benefit. The recipients and expenditure estimates include those in receipt of Universal Credit or income-related legacy benefits/tax credits. Working age ENR’s are for UC-only and not any of the equivalent benefits, given that there are no new claims for the legacy benefits/tax credits.
Our modelled ENR estimates are based on certain assumptions for eligibility to benefits and the amount that would be received. So, there is also uncertainty in the estimates depending on the assumptions used. There are limitations to how much variation we can account for. The amount of UC that a family receives from 1 assessment period to the next can vary, as does the amount by family, due to the different elements of UC. For the working age estimates there is the assumption of no change to the amount being claimed by a family throughout the year which does lead to uncertainty in the results as by design, the amounts received by families can change during the year, and our estimates cannot reflect that variability. Whereas PC has less within-year variability than UC and so there is little additional uncertainty in our estimates, as the assumption of no change throughout the year generally reflects what happens in practice.
4. Context of the statistics
The benefits covered in the pension age publication are:
- Pension Credit (PC)
- Housing Benefit (HB) for pensioners
The working age benefits included in the new composite measure UC (or equivalent benefits) are:
- Universal Credit (UC)
- Income-based Jobseeker’s Allowance (JSA (IB))
- Income-related Employment and Support Allowance (ESA (IR))
- Income Support (IS)
- Working Tax Credit (WTC)
- Child Tax Credit (CTC)
- Housing Benefit (HB) for working age claimants
The detail of each benefit is given in turn below, beginning with Pension Credit, then Housing Benefit (for both pensioner and working age), followed by the working age benefits.
Pension age benefits
Pension Credit (PC)
Overview
Pension Credit (PC) is an income-related benefit that was introduced on 6 October 2003 and replaced the Minimum Income Guarantee.
There are 2 parts to PC:
- Guarantee Credit (GC)
- Savings Credit (SC)
Claimants may qualify for either or both parts of PC.
To qualify:
- the claimant must live in Great Britain (GB)
- the claimant (and, from 15 May 2019, their partner) must have reached PC qualifying age. Therefore, from FYE 2020 onwards both parties in a couple must be State Pension age (SPa) or above to be entitled to claim PC (unless the couple are in receipt of HB (for pensioners) where only 1 party in a couple needs to be above SPa)
GC tops up the claimant’s income to a guaranteed level (a higher guaranteed level applies for couples). The level may increase if the claimant is a carer, severely disabled, responsible for a child or young person, or has certain housing costs.
Savings Credit (SC) is an entitlement for people who have made provision for their retirement above the Savings Credit threshold (SCT) (such as savings or a second pension).
Most people who reached SPa on or after 6 April 2016 will not be eligible for SC.
However, if a single claimant has reached SPa before 6 April 2016, or a claimant is in a couple and 1 of them reached SPa before 6 April 2016, then they may be entitled to SC.
If a claimant who is a member of a couple in the circumstances above stops being entitled to SC for any reason, they will not be able to receive it again.
As of 6 May 2020, DWP introduced an online claim option to support existing methods of applying for PC by telephone or post.
Please see GOV.UK for more information on current PC entitlement rules.
Benefit rates
The Standard Minimum Guarantee (SMG) is the minimum level of income that is guaranteed through GC. This is uprated each year by at least the level of the increase in earnings.
The SCT determines the level of income at which someone becomes eligible for SC, while the SC Maximum (SC max) is the maximum amount of SC that can be awarded. In recent years, the rate of the increase of the SCT has had the effect of reducing the SC max.
Up-rating
In April 2024 the ‘triple lock’ ensures that the basic State Pension and new State Pension increase every year by whichever is the highest of the following: earnings, prices as measured by the Consumer Prices Index (CPI), or 2.5%. In FYE 2025, both the Basic and New State Pension increased by 8.5%. The Basic State Pension increased from £156.20 per week to £169.50 per week, a cash increase of £13.30 per week. The New State Pension increased from £203.85 per week to £221.20 per week, a cash increase of £17.35 per week.
Also in April 2024, the SMG in PC increased by 8.5%. For those who were single, the SMG in Pension Credit increased from £201.05 per week in FYE 2024 to £218.15 per week in FYE 2025, a cash increase of £17.10 per week. For couples, this increased from £306.85 per week in FYE 2024 to £332.95 per week in FYE 2025, a cash increase of £26.10 per week.
The rates are taken from: Benefit and pension rates 2024 to 2025.
The qualifying age
The qualifying age for PC is linked to SPa. For FYE 2025 the SPa for both males and females was 66. As SPa continues to increase, so will the qualifying age for PC. More information can be found in the SPa timetable: State Pension age timetables
Mixed age couples
From 15 May 2019, mixed age couples were no longer able to choose whether they claimed UC or PC or pension age HB. Both parties of a couple will have to reach the PC qualifying age before they can be entitled to either PC or pension age HB or both. From 15 May 2019, if a claimant who receives HB or PC’s circumstances change, or they take a break from claiming, they may have to claim UC instead. Some changes that affect claims include:
- a change of address to a different local council area
- going abroad for more than 4 weeks
- a change in the amount of capital a claimant has
- stopping claiming a benefit that helps a claimant qualify for PC or HB
- separating from a partner and then getting back together
The working age publication includes mixed-age couples in its combined caseload estimates.
Winter Fuel Payment
Eligibility for Winter Fuel Payments (WFP) changed in FYE 2025. Prior to this change, WFP was a near-universal benefit for pensioners living in the UK, provided they met the residence and other eligibility conditions.
On 29 July 2024, the Government announced that they would implement a targeted approach to Winter Fuel Payment eligibility in England and Wales from Winter 2024/2025. Eligibility was restricted to pensioner households in England and Wales with someone receiving Pension Credit or certain other income-related benefits.
In Scotland, winter heating assistance is a devolved policy area. For Winter 2024/2025, the Scottish Government brought forward new legislation in the Scottish Parliament for a Pension Age Winter Heating Payment that replaced the Winter Fuel Payment in Scotland – which was linked to Pension Credit and other qualifying benefits in the same way as in England and Wales.
Housing Benefit (HB) (pension age and working age)
Overview
Housing Benefit (HB) helps tenants who are on a low income to pay their rent. HB is administered by local authorities who decide whether a claimant is eligible for HB, and how much they qualify for. Tenants can apply for HB irrespective of whether they are in work, or out-of-work. It may be paid alongside other income-related benefits, non-income-related benefits, or on its own. Since December 2018, due to the rollout of UC, new claims for HB can only be made in certain circumstances.
Subject to having an eligible rent liability, the vast majority of those on the GC part of PC, IS, or ESA (IR) are automatically eligible for maximum HB.
Claimants not in receipt of 1 of the benefits listed above may have their HB reduced if they have capital or income more than certain thresholds. If their capital or income is too high, they may not qualify for HB at all.
The amount awarded can also vary based on the numbers, age, and disabilities of members of the household. For many claimants in the private rented sector, the level of their eligible rent is also limited by the Local Housing Allowance (LHA) rates which apply to where they live. The size and composition of the claimant’s household determines the size of the accommodation which they might need. In turn, the specific LHA rate is used to assess entitlement to HB.
There are some exceptions. Those that do not qualify for HB include:
- those who live in the home of a close relative
- any full-time students - unless they are disabled or have children
- asylum seekers or those sponsored to be in the United Kingdom (UK)
As of December 2018, new claims for HB can only be made if:
- a claimant (and, from 15 May 2019, their partner) has reached SPa. Therefore, from FYE 2020 onwards both parties in a couple must be SPa or above before being entitled to claim HB (unless the couple are in receipt of PC where only 1 party in a couple needs to be above SPa)
- a claimant lives in supported, sheltered or temporary housing
See more information on current HB entitlement rules.
Benefit rates
There is no set rate of HB that a claimant will receive, but the thresholds used for the means-tested side of the HB assessment are aligned to rates of other benefits. Claimants in the private rented sector are usually restricted to the LHA rate for their family size and postcode.
Interaction with other income-related benefits
HB can be paid alongside PC. For most working age claimants, HB has been replaced by the UC housing element. HB can still be claimed by some groups such as pensioners and people in certain types of temporary or supported accommodation. For anyone still claiming legacy benefits like ESA or JSA, HB is paid as a top-up.
HB is calculated based on an ‘applicable amount’ intended to cover basic weekly living expenses. The amount of benefit is calculated by comparing a person’s income with their applicable amount, taking account of the size and make-up of the household.
If the net income is equal to or is less than the applicable amount or they are in receipt of an income-related benefit, they will receive 100% of the rent for which benefit can be paid less any non-dependent deductions. This would be subject to any deductions for non-dependents who live with them and help with rent would not exceed the LHA rate which applies to their household. If the net income is more than the applicable amount, they will receive reduced HB. For each pound of extra income over the applicable amount, after disregards, 65 pence will be deducted.
Read the Housing Benefit official statistics.
Working age benefits
Detail is provided for the benefits included in our new UC (or equivalent) take-up estimates. As well as HB detailed above, we provide an overview on Universal Credit as the main benefit included. We have also outlined the equivalent benefits included in the take-up composite measure.
These estimates are a composite measure for the take-up of UC (or equivalent benefits) while the transition from legacy benefits and tax credits takes place.
UC (or equivalent benefits) refers to families receiving Universal Credit, legacy income-related benefits or tax credits, during the transition to UC. While there are still people in receipt of legacy benefits and tax credits a UC-only take-up rate would not provide the full picture of what is happening for the entitled working age population. A composite measure is therefore required to allow an understanding of working age income-related benefit take-up overall.
Universal Credit
Universal Credit is a payment to help with living costs for individuals/families who are on a low income, out of work or who cannot work. It has been replacing income-related legacy benefits/ tax credits, since 2013.
Overview
The main features of Universal Credit are the following:
Eligibility
UC is a single monthly payment for individuals/families who are unemployed, have caring responsibilities, have a low income, or are unable to work because of ill health.
Claimants must:
- live in the UK
- be aged 18 or over (special exceptions if 16-17)
- be under SPa
- have £16,000 or less in money, savings and investments
Monthly assessment period: income and savings and circumstances are assessed each month to determine the payment amount.
Conditionality
Claimant commitment: a personalised agreement is made between the claimant and DWP, outlining what they must do, which they must agree to, in order to receive UC.
Claimants are placed into different categories to outline expectations:
- all work-related requirements (actively seeking work or increase earnings)
- work preparation (in preparation for future work)
- work-focused interviews only (attend periodic check ins)
- no work related activity (severe disability or full time carers)
If claimants do not meet their commitments, they may face temporary sanctions (reduction in payment).
UC has a taper rate: as a claimant earns more, their UC decreases gradually (a 55% deduction as earnings rise, in both FYE 2024 and FYE 2025).
Elements
UC is calculated using a standard allowance, plus extra ‘elements’ depending on claimant circumstances.
Standard allowance is the minimum basic payment, designed to cover essential living costs. It is determined by age (under/over 25) and whether claimants are single/in a couple.
Additional elements include:
- Child Element: generally payable for up to 2 children, subject to the 2 child policy and associated exceptions
- the 2 child limit ended on 6 April 2026, which is after the period we are reporting on
- Childcare Costs Element: covers up to 85% of registered childcare costs
- Housing Costs Element: help with rent and some service charges
- Limited Capability for Work: available for claimants with health conditions or a disability affecting their ability to work
- Carer’s Element: extra support if caring for more than 35 hours per week
Interaction with other income-related benefits
Universal Credit was gradually rolled out in stages to replace other working age income-related benefits. It was initially available to a limited range of claimants, principally single working age people with no children and seeking work. The national expansion of Universal Credit to the full range of claimants was started in May 2016. By December 2018 it was available in every Jobcentre across Great Britain, for new claims. Claimants moved by voluntary migration, natural migration (change of circumstance prompting a new claim to UC), or managed migration (being informed they must claim UC to maintain their benefit entitlement).
A pilot for the managed migration of claimants on benefits being replaced by Universal Credit began in July 2019 in Harrogate, which was suspended due to the pandemic. DWP resumed moving customers in May 2022, initially focussing on those that were solely in receipt of WTC and/or CTC, ahead of the close of tax credits on 5 April 2025.
From April 2024, DWP began sending migration notices to households receiving particular combinations of benefits, in stages. From September 2024, all remaining combinations of income-based benefits administered by DWP began receiving migration notices. For more information, see the Completing the move to Universal Credit publication.
DWP completed the move of all legacy income-related benefits to UC by end of June 2026; with the exception of a small group of ESA(IR) customers who require an appointee to make a claim to UC. There are also families in receipt of Housing Benefit (HB) and residing within temporary or supported accommodation, who will not have their housing support migrated to UC.
Benefit rates
UC is paid monthly and is based on a standard allowance and additional ‘Elements’ depending on the claimant’s circumstances. Claimant circumstances are reviewed regularly by a case worker, and the monthly payment may change depending on any change in circumstances reported.
The rates are published here: Benefit and pension rates 2024 to 2025
Up-rating
In April 2024 Universal Credit (UC) standard allowances and inflation-linked benefits increased by 6.7% in line with the September 2023 Consumer Prices Index (CPI) rate of inflation.
For those who were single and aged 25 and over, the standard allowance increased from £368.74 per month in FYE 2024 to £393.45 per month in FYE 2025, a cash increase of £24.71 per month. For couples with 1 or both aged 25 and over, this increased from £578.82 per month in FYE 2024 to £617.60 per month in FYE 2025, a cash increase of £38.78 per month.
Income-based Jobseeker’s Allowance (JSA IB))
Background: A working age benefit that is paid to help people while they look for work. No new claims can be made, but some people were still in receipt in the years reported on, until income-based JSA ended on 31 March 2026.
Benefit rates
JSA (IB) is paid fortnightly and usually uprated each year by the increase in prices (Consumer Prices Index). The amount paid is dependent on the age of the claimant, and whether they are claiming as a couple.
The rates are published here: Benefit and pension rates 2024 to 2025
JSA (IB) also has premiums (additional payments) available for specific needs. Information on the premiums for JSA (IB) can be found at the link above.
Interaction with other income-related benefits
No new claims for JSA (IB) can be made - any current recipients will continue to get JSA until their claim ends or they move to Universal Credit. JSA (IB) could be paid in conjunction with HB but not with IS or ESA (IR).
Income Support (IS)
Background: IS is a benefit to help people on a low income with their living costs. No new claims can be made, but some people were still in receipt in the years reported on, until IS ended on 31 March 2026.
Benefit rates
IS payments are made fortnightly and includes:
- a basic payment (personal allowance)
- extra payments (premiums)
A claimant’s income and any savings may affect how much they receive.
The rates are published here: Benefit and pension rates 2024 to 2025
An IS ‘premium’ is extra money provided based on various claimant circumstances. More information can be found at the link above.
Interaction with other income-related benefits
No new claims for IS can be made – those on low income who need help to cover living costs can apply for Universal Credit instead. IS could be paid in conjunction with HB but not with JSA (IB) or ESA (IR).
Income-related Employment and Support Allowance (ESA)
Background: Income-related Employment and Support Allowance (ESA IR) is a means-tested legacy benefit for those unable to work due to illness or disability. No new claims can be made, but some people were still in receipt in the years reported on. DWP completed the move of all legacy income-related benefits to UC by end of June 2026; with the exception of a small group of ESA(IR) to be migrated.
Benefit rates
ESA (IR) claimants first receive an ‘assessment rate’ for 13 weeks while their claim is assessed. After assessment, if successful, claimants are placed into 1 of 2 groups and paid a ‘main phase’ rate. If they can get back into work in the future, they are put into the work-related activity group. Otherwise, they are put into the support group.
ESA (IR) payments are made fortnightly and include:
- a basic payment (personal allowance)
- extra payments (premiums)
A claimant’s income and any savings may affect how much they receive.
The rates are published here: Benefit and pension rates 2024 to 2025
An ESA (IR) ‘premium’ is extra money provided based on various claimant circumstances. More information can be found at the link above.
Interaction with other income-related benefits
No new claims for ESA (IR) can be made - any current recipients will continue to get ESA until their claim ends or they move to Universal Credit. ESA (IR) could be paid in conjunction with HB but not with JSA (IB) or IS.
Working Tax Credit (WTC)
Background: Working Tax Credit (WTC) was an income-related payment that topped up the earnings of low-income workers. No new claims can be made, and all remaining claims ended when tax credits closed in April 2025, except for a small residual of administrative cases.
Savings were disregarded for WTC eligibility, however families with more than £16,000 in savings will not be eligible for UC. Further differences are that WTC was claimed annually, whereas UC is reviewed monthly for changes in circumstances and eligibility.
Benefit rates
WTC payments were made either weekly or every 4 weeks. The maximum annual rates are published here: Child Benefit, Guardian’s Allowance and tax credits — rates and allowances
There was also the childcare element of WTC. This was a weekly payment which covers part of registered childcare costs.
Interaction with other income-related benefits
No new claims for WTC can be made, but some people were still in receipt in the years reported on. WTC could be paid in conjunction with legacy income-related benefits.
Child Tax Credit (CTC)
Background: Child Tax Credit (CTC) was an income-related payment designed to help families with the costs of raising a child. No new claims can be made, and all remaining claims ended when tax credits closed in April 2025, except for a small residual of administrative cases.
Savings were disregarded for CTC eligibility, however families with more than £16,000 in savings will not be eligible for UC. Further differences are that CTC was claimed annually, whereas UC is reviewed monthly for changes in circumstances and eligibility.
Benefit rates
CTC payments were made either weekly or every 4 weeks. The maximum annual rates are published here: Child Benefit, Guardian’s Allowance and tax credits — rates and allowances
Interaction with other income-related benefits
No new claims for CTC can be made, but some people were still in receipt in the years reported on. CTC could be paid in conjunction with legacy income-related benefits.
5. Source of the statistics
Figures in this analysis are based on DWP and HMRC administrative data, Local Authority administrative data, and data from the FRS. The survey data from the Family Resources Survey (FRS) is the base dataset for the static microsimulation model known as the Policy Simulation Model (PSM). A more detailed explanation can be found in the Data Sources, Compilation and Methodology section below.
6. Data sources, compilation and methodology
6.1. Data sources
Introduction
The following information within this section is a broad outline and there are improvements, changes and differing data sources made to this approach over time as needed.
Use the background information and methodology document as a source of information for details relevant to that year.
Some key changes in recent years are outlined in the Improvements and Refinements section of this document.
Overview
To produce the take-up estimates, information can be taken from DWP administrative data sources to present the average number of those in receipt of the benefit along with the average amount claimed. However, because administrative benefit entitlement datasets do not exist, survey-based estimates of the population and unclaimed amounts of those who are entitled but not receiving are needed. These survey-based estimates come from the adjusted PSM dataset.
The take-up estimates are derived using information taken directly from several data sources and a small number of evidence-based adjustments are introduced where necessary.
ENR estimates are for private households only. Therefore, those in nursing homes, student halls of residence, military barracks, prison or temporarily living in bed and breakfast accommodation, will not be included
Main data sources for receipts and ENR estimates
National Statistics datasets (NSD) for PC receipt
The NSD provides a point in time caseload of all benefit claims that were live on the reference date, drawing from various DWP computer systems to provide anonymised claimant and claim information which can be matched on to other available datasets
The NSD is used to produce receipt estimates for PC as it provides 100% DWP administrative records for all those receiving the benefits. The datasets are available quarterly.
The NSD is also used to remove benefit units that are in non-private households in the receipt estimates for PC. This removal ensures the estimate of the average numbers receiving each benefit is consistent with the estimate of the average number of ENRs, which are for private households only.
This data is used to estimate caseload and expenditure receipt, for those on PC.
Single Housing Benefit Extract (SHBE) for HB receipt (pensioners)
SHBE is a monthly electronic scan taken directly from local authority computer systems and provided to DWP for analysis. Each local authority monthly scan taken, contains 100% administrative records of all those receiving HB in that local authority during that month. The data are used as they provide 100% administrative records for all those receiving HB.
Some local authorities are unable to provide some monthly scans to the DWP, but this is a very small number of all HB administrative records that the DWP receives overall. No adjustment is made for this deficit of records.
The SHBE is the data source used for Housing Benefit (HB) receipt. As predominantly only private households can receive HB, no adjustment is made to remove non-private households for the receipt estimates.
This data is used to estimate caseload and expenditure receipt, for pensioners on HB.
Read more Housing Benefit information.
Legacy to Universal Credit (L2UC) for working age receipt
The Legacy to UC (L2UC) database was developed as a single, central database on Universal Credit (UC) migrations for DWP and is made of 8 relational datasets (which includes 1 for each of the legacy benefits) which describe the historical legacy benefit caseload. The creation of this dataset has enabled us to create these estimates, accounting for the Move to UC in our receipt estimates.
The datasets are 1 row per legacy benefit unit per month, containing information about any legacy benefit claims live at the end of each month. If a benefit unit has off-flowed from legacy, the end date is captured within the L2UC database, and if there is a migration to UC the data will also contain information about the new contract(s) and first assessment period(s).
The database brings together administrative data from:
- DWP legacy benefits: Jobseeker’s Allowance (JSA), Employment and Support Allowance (ESA), and Income Support (IS)
- Housing Benefit (HB): provided by Local Authorities
- HMRC tax credits: Child Tax Credit (CTC) and Working Tax Credit (WTC), excluding nil‑payment cases
The DWP benefits data (via the National Benefit Database) and Housing Benefit inputs are aligned with those used for published DWP statistics on DWP Stat‑Xplore to feed into L2UC data extracts.
L2UC also incorporates General Matching Service (GMS) scans to capture up‑to‑date claimant characteristics. L2UC data covers Great Britain only.
L2UC is designed to manage detailed benefit unit level microdata, tracking monthly claimant activity and changes to characteristics at both individual and household levels. This data is used to estimate caseload and expenditure receipt, for those on legacy benefits and tax credits.
Universal Credit Household Official Statistics (UCOS) for UC receipt
The Universal Credit Official Statistics were developed to provide the primary official source of information about people and households on Universal Credit, and claims and starts to Universal Credit.
They enable a variety of users to be informed about different elements of the benefit, as well as geographic information and personal characteristics of those taking up Universal Credit.
The statistics are published in a timely manner to best meet user needs without compromising the quality of the data. The statistical release for claims, starts, people and households on Universal Credit is published quarterly. All data is available on Stat-Xplore.
A household is counted in Universal Credit statistics when they have an assessment period that spans the count date (the second Thursday of the month). There is a further condition that entitlement must have been calculated for the period. This will include households with claims that are live and in payment, live and have a nil award (due to earnings or deductions) or temporarily suspended.
A household will be classed as ‘in payment’ if they receive a payment of any amount of Universal Credit in an assessment period, as long as it is greater than £0. On the other hand, a household will be classed as ‘not in payment’ if they do not receive any payment of Universal Credit in an assessment period (or they are recorded as receiving a payment amount of £0).
It may be the case that a household has their Universal Credit award reduced to ‘nil’ by earnings, deductions or sanctions. In this case, the household will be recorded as receiving a payment amount of £0 and therefore will be classified as ‘not in payment.’
This is the base data used to estimate caseload and expenditure receipt, for those on UC.
Universal Credit Full Service (UCFS) for UC receipt
The main data source for the administration of Universal Credit claims. Information is entered by the claimant and verified by the jobcentre officials.
UCFS data is a snapshot on the count date. Consequently, this data only represents the circumstances that claimants are in at that particular point in time.
Throughout the month, there will be slight changes as some claimants may have a change in circumstances. For example, it may be that a claimant is in work on the date a snapshot is taken, but 2 days later loses their job.
A copy of administrative data is taken 2 full days after the count date. This is then converted by data teams into datasets that can be processed for internal analysis and statistical publications.
For this publication, certain aspects of the UCFS data are merged with the UCOS household data in order to:
- restrict the UC household data to remove non-private households within Great Britain after calculating what proportion of the households are classed as private/non-private
- remove transitional protection amounts from each family’s UC final payment
Hence this data is used to make adjustments to the caseload and expenditure receipt for UC produced initially via UCOS Household data.
Family Resources Survey (FRS) for ENR estimates
The FRS is an annual survey, collecting information on private households in the UK, although only GB information is used within this analysis. Its primary function is to collect information on household income received from all sources, including wages and salaries, state benefits, payable tax credits, private (occupational and personal) pension schemes, and investments. The information allows analysis at an individual level, benefit unit level and household level. The survey is sponsored by the DWP and for FYE 2025, this was a survey of over 16,000 private households.
Read more information about the Family Resources Survey.
Administrative data linking to the FRS has always been used to allow for more accurate classification of the benefit units as ENRs to take-up estimates. The approach has evolved over time and in March 2026, the first integrated Family Resources Survey based on linked benefits data was published, relating to FYE 2025 data. This has no impact on the take-up estimates as the FYE 2024 results were based on the same linking approach, but in effect means 1 less step in producing the publication as the administrative data linking is already incorporated in the source FRS data. For further details, please access this technical paper and quality assessment report.
Policy Simulation Model (PSM) for ENR estimates
The DWP’s PSM is a static microsimulation model of the UK tax and benefit system. It takes reported information from the FRS on benefit units and then simulates (or models) what the benefit unit might be entitled to, based on the tax and benefit rules in the FRS year. The model estimates what a similar benefit unit, with those same characteristics, might be entitled to for future financial years, accounting for the tax and benefit rules in that future year. The PSM is used extensively by DWP analysts for policy evaluation and costing of policy options.
Some important adjustments are made to the default PSM dataset to provide more precise estimates of ENRs and their average weekly amounts unclaimed (see section 6.4). The adjusted PSM dataset is used to derive the ENR estimates. It provides modelled benefit entitlements, for the survey year for the income-related benefits in this report.
6.2 Data compilation and methodology
Introduction
To produce the take-up estimates, information can be taken from DWP administrative data sources to present the average number of those in receipt of the benefit along with the average amount claimed. However, because administrative benefit entitlement datasets do not exist, survey-based estimates of the population and unclaimed amounts of those who are entitled but not receiving are needed. These survey-based estimates come from the adjusted PSM dataset.
The methodology used, aims to provide the best estimate based on the evidence available, using the FRS. At the same time, there are limitations with the methodology as there are known data issues in the FRS, including under-reporting of benefit receipt. The integration of administrative data helps address this under-reporting but does not remove it completely. More information can be found in this technical paper and quality assessment report.
This report presents the methodology which is based on using the evidence available from administrative sources and the PSM, to produce the take-up estimates.
Figure 1: Flow chart of how take-up estimates are calculated
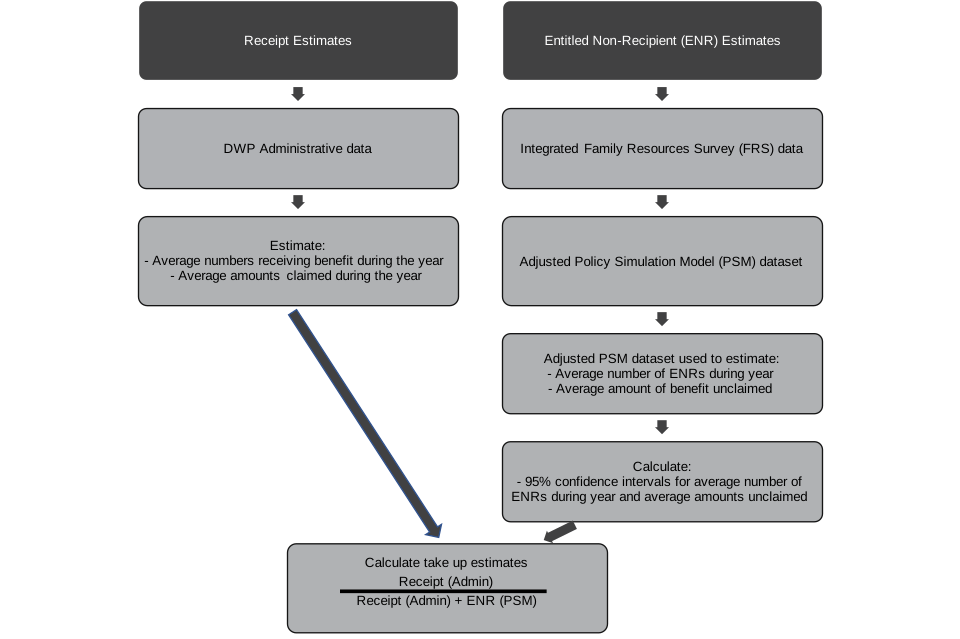
Figure composes of a flow chart that demonstrates the process to create the receipt and ENR estimates, which feed into the take-up formula. The receipt estimates come from administrative data giving an estimate for both the average numbers receiving the benefit and the average amounts claimed during the year.
The Entitled Non-Recipients (ENR) estimates come from the integrated Family Resources Survey data, which is used in the adjusted Policy Simulation Model. This estimates the average number of ENRs and the average amount of benefit unclaimed, and we calculate 95% confidence intervals.
The bottom of the flowchart shows the take-up estimates are calculated using the receipt estimates as the numerator, and the receipt and ENR estimates as the denominator.
6.3 Estimating Receipt
Pension age receipt estimates
Pension Credit (PC)
The NSD is used to estimate the average number of those receiving PC and average amounts claimed for the financial year, using data taken at the end of each quarter. Estimates are produced for the type of PC claimed (whether GC and/or SC) and by family type.
The take-up estimates for PC focus on private households only, so these receipt estimates based on the NSD are lower than published DWP estimates, which include all households. Benefit units that are in non-private households in the receipt estimates are removed from the NSD. This removal ensures the estimate of the average numbers receiving each benefit is consistent with the estimate of the average number of ENRs, which are for private households only. Estimates of average amounts claimed are not adjusted as private households account for around 95% of all households receiving PC. It is assumed that the average amounts claimed remain representative of private households.
Housing Benefit (HB) for pensioners
SHBE datasets from each month of the financial year, are combined and a 12-month average is estimated for the number of those receiving HB and average amounts of HB claimed. HB is predominantly only available to people living in private households so no separate removal of non-private household cases is required.
For HB for pensioners, the take-up receipt estimates for FYE 2013 onwards are similar to published DWP estimates.
For working age, the data comes from L2UC as detailed in the next section. The initial source is also SHBE, but L2UC combines working age benefits into a single dataset as below.
Working age receipt estimates
This section goes into detail on the targeted eligible working age population we are estimating, as well as the data used and the process to obtain receipt estimates. We also detail some of the adjustments and decisions made.
UC (or equivalent benefits)
To create the composite UC (or equivalent benefits) receipt estimates we need a combination of the working age income-related benefits receipts. We estimate those in receipt of at least 1 of Universal Credit, income-related working age legacy benefits or tax credits. But it is essential that for those receiving multiple legacy benefits or tax credits that they are only counted once in the caseload receipts, while their full average amount received is included in the estimates. In this way we account for the move to UC as we are looking at anyone in receipt of UC or an equivalent benefit, to provide an overall composite measure of working age take-up. We make some adjustments to this as set out in this section, including to remove those who received a legacy benefit/tax credits but would not be eligible for UC.
Eligible population
First we need to define who is the eligible group for receipt of UC (or equivalent benefits). We include those in receipt of UC (or equivalent benefits) but do not include legacy ERs who are not eligible to move to UC. The diagram below illustrates the overlap between those who are eligible for legacy benefits and in scope to move to UC, and those that are not – the orange section that does not overlap with the grey section are excluded from these take-up estimates.
An example of a family that would have received legacy benefits but not be eligible for UC, would be those that received tax credits but have over £16,000 in savings. They would then not be eligible for UC due to their savings. Other cases include those in receipt of Housing Benefit (HB) and residing within temporary or supported accommodation, who will not have their housing support migrated to UC.
The L2UC and UCOS data that we use for our receipts caseload, does not allow us to remove legacy/tax credits claimants not entitled to and not receiving UC (NENR). This group is represented by the orange section that does not overlap with the grey section. However, using the PSM modelled data, we have successfully removed these cases from the receipts caseload, by calculating the proportion of UC NENR cases of the overall PSM caseload, and reducing our final legacy only receipts caseload by the same proportion.
Figure 2: Venn diagram of who is included in estimates
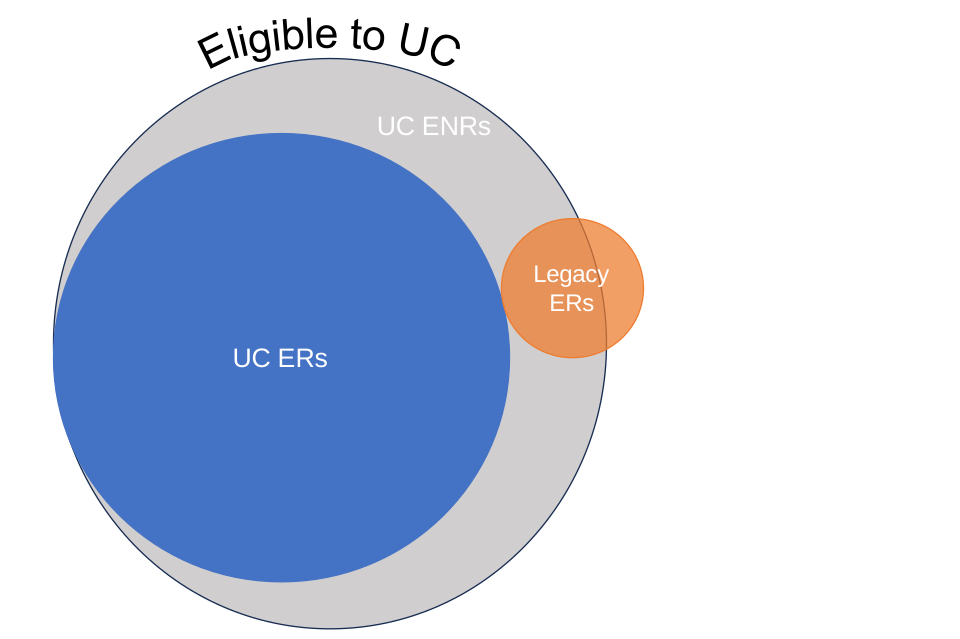
The Venn diagram uses 3 overlapping circles, where larger circles represent a larger proportion of working age adults. Those in the largest circle are those eligible to UC, within that circle is a smaller blue circle which represents those who are UC ERs, and therefore are eligible and claiming, the grey remainder of the larger circle represents the UC ENRs, who are eligible but not claiming UC. There is a smaller orange circle representing legacy ERs. This orange circle does not overlap the blue circle, but does include some UC ENRs and also some outside of the eligible for UC circle. It is used to demonstrate that those outside the grey circle are excluded from our estimates (those who are a legacy ER, and not a UC ENR). The size of the circles change each year over the period of the move to UC. The diagram is illustrative and not to scale.
Estimating receipts using the L2UC and UCOS datasets
The L2UC database is the primary data source used to produce working age legacy benefit receipt estimates for families who are entitled to and receiving legacy benefits or tax credits. We can do this as the dataset already accounts for any deduplication of those receiving multiple benefits and has been built with knowledge of how all the possible benefits interact with each other. We obtain L2UC data and all associated claimant and household characteristics, for every month of the financial year we are reporting on.
We then also obtain information on families who are entitled to and receiving UC from the Universal Credit Official Statistics (UCOS) data extracts, for every month of the year we are reporting on.
To create a composite receipt measure we merge the L2UC monthly data extracts and UCOS monthly data extracts together, using the claimant national insurance number, the partner national insurance number (if applicable) and month, from each dataset. This gives us 1 record per month per benefit unit (also referred to as family), along with the household characteristics and the details of any benefits in payment.
Where any family is found to be in receipt of both a legacy benefit and UC for any month, then we set the details for that family, to only be in receipt of UC for that month.
Within the L2UC data, couples have been identified by locating partner NINOs from 1 of 3 sources: HB Statistics data (published SHBE), tax credits data, or ESA partner scans. For claimants receiving IS only, we assume they are single, as IS is a legacy benefit primarily intended for lone parents (the vast majority group) or carers, provided they meet the <16‑hour work rule or the 35‑hour caring requirement. For claimants receiving Jobseeker’s Allowance (JSA) only, we also assume they are single.
As the FRS is a survey of private households, we adjust the administrative data used for the estimates to exclude families living in non-private households. The UCOS data contains information on the type of housing establishment, and so families in non-private households can be removed. Legacy data does not contain this information and so the number of families in non-private households as a proportion of the total number of UC families, is applied to the number of families in receipt of legacy benefits/tax credits.
Our working age receipt caseload and expenditure estimates for each financial year are then derived from this merged dataset.
Housing Benefit recipients residing in temporary or supported accommodation
Those in receipt of Housing Benefit (HB) and residing within temporary or supported accommodation, will not have their housing support migrated to UC. These cases are identifiable via data fields within L2UC data (assumed to be accurate). Therefore:
- if they are in receipt of HB only (in terms of income-related benefits), then we remove these cases from our receipt caseload and remove their expenditure from our total expenditure
- if they are cases in receipt of HB and another income-related benefit, then:
- we remove the HB expenditure associated with these cases
- they remain within our overall caseload but with no HB details associated with them
Ages Of Claimants
The following are general rules which we have applied when processing the L2UC and UCOS data, in order for families to be counted within our receipts caseload:
- claimant and partner (if applicable) ages for each family are calculated from their date of birth details that are sourced from either the L2UC data or the UC data
- families consisting of single claimants, must be of working age (i.e. less than 66 for this publication) or unknown (if no date of birth details are known)
- families consisting of couples, must contain at least 1 claimant who is of working age (i.e. less than 66 for this publication) or unknown
- claimants of unknown age are assumed to be of working age if they are in receipt of a working age benefit
- mixed age couples are included in the working age take-up estimates.
For Housing Benefit, new claims can only be made by pension age claimants (with some exceptions) but existing claimants can be working age or pension age households. We have checked the date that the claim started for these cases to identify if they are claiming at working age or pension age. Pension age Housing Benefit details are removed from the working age receipt caseload.
Other adjustments made
Nil payments
Each family must be in receipt of a benefit (UC or a legacy benefit or both) with a weekly value greater than £0 during any month, during the financial year being measured, to be included within our receipts caseload.
JSA and ESA contributory amounts
If a family is in receipt of contributory only JSA/ESA then the amount is excluded from expenditure, and they are removed from the caseload (if they are not in receipt of any other income-related benefit or UC). However, if a family is in receipt of both income-based and contributory JSA/ESA, then we cannot separate out the income-based amount from the contributory amount. Therefore, the receipt data includes these contributory amounts. The scale of contributory payments is estimated in the Benefit expenditure and caseload tables.
This is the same approach taken in previous working age publications.
Transitional Protection (TP)
Those moving to UC under migration notices are given transitional protection if their UC entitlement is lower than their legacy entitlement.
In creating these receipt expenditure figures, the Transitional Protection amounts have been excluded from the receipt amounts within the UC data, using the UCFS data to exclude TP. This is to ensure figures are more comparable with the ENR estimates, which do not include the Transitional Protection element.
If UC receipt is £0 for any benefit unit after TP is removed, they are excluded from the caseload and expenditure receipt estimates.
6.4 Estimating Entitled Non-Recipients (ENRs)
Overview
DWP administrative data does not identify people who are entitled to a benefit but do not receive it. The DWP Policy Simulation Model (PSM) is therefore used to estimate this population.
From FYE 2025, the default PSM is based on the integrated FRS, which includes linkage to administrative data, to reduce the under-reporting of benefit receipt. Reported receipt from the FRS is used for benefit units where data linking was not possible. To produce the ENR estimates, some adjustments are made to the default PSM dataset to create a bespoke adjusted PSM dataset. The adjusted PSM dataset is used to obtain the average number of ENRs and the average amounts unclaimed.
In the PSM entitlement is modelled at the family level. These groupings are known as ‘benefit units’ (BUs). For example, 2 adults and 1 child would form 1 BU, while an additional adult in the same surveyed household would form a separate BU. Tax liability and welfare entitlement are modelled for each BU. A BU is referred to as a family throughout the publication.
A BU is recorded as receiving benefits if it is reported in the integrated FRS dataset during the FRS interview or identified through linked administrative records. Comparing recorded benefit receipt with modelled entitlement allows BUs to be classified into 3 groups:
- Entitled Non-Recipients (ENRs)
- Entitled Recipients (ERs)
- Non-Entitled, Non-Recipients (NENRs)
From this, the average numbers of ENRs, and the average amounts unclaimed are estimated, along with 95% confidence intervals to reflect uncertainty. These estimates are combined with the receipt estimates to produce the lower bound, central, and upper bound take-up estimates. It should be noted that, if existing, any ‘Non-Entitled Recipients’ are assumed to be entitled to the benefits they get.
Some specific assumptions are needed to produce the estimates for the composite measure compared to the individual pension age benefits.
This section includes detail on the PSM dataset; the adjustment made to create the adjusted PSM for take-up; and the assumptions used in particular for the new working age estimates.
The PSM dataset
The PSM is a static microsimulation model of the UK tax and benefit system. It uses information from the FRS such as information on earnings, benefit income and family circumstances, then applies tax and benefit policy rules to model welfare entitlement. The PSM applies the policies in place during the relevant FRS survey period.
The PSM dataset is based on the integrated FRS data. Benefit receipt is taken from the admin-linked records (where data linkage has been possible). It uses the admin-linked award values to overwrite the PSM’s modelled award values for benefit recipients.
From FYE 2025, this admin-linking is already incorporated in the FRS source data and is no longer an additional part of the process to create the take-up statistics. Further information can be found in integrating-administrative-data-into-the-FRS. In FYE 2024 and FYE 2025, it was possible to link data for over 95% of all families.
Improvements in the coverage and quality of data linking means that more administrative data can be used in the production of the take-up estimates, improving their accuracy. An increased amount of linked data provides a better estimate of the number of ENRs for a benefit where benefit under-reporting has occurred in the FRS. This influences the mean and median amounts unclaimed. The actual effect on the take-up estimates will depend on the observed data for each survey year.
Creating the adjusted PSM dataset for take-up statistics
The adjustments made to the default PSM dataset are:
The take-up estimates are only provided for GB
The UK-based PSM dataset is adjusted to remove any Northern Ireland benefit units, so that the average number of ENRs and average amounts unclaimed are on the same basis as the receipt estimates (i.e. at GB level).
Grossing-up to Great Britain (GB) control totals
Grossing-up is the term usually given to the process of applying factors to sample data so that they yield estimates for the overall population. The simplest grossing system would be a single factor, for example the number of households in the population divided by the number in the achieved sample of a survey. However, surveys are normally grossed by a more complex set of grossing factors that attempt to correct for differential non-response at the same time as they scale up sample estimates.
The bespoke grossing control variables for FYE 2025, in addition to population grossing control variables, along with their breakdowns and data sources used to gross up the PSM dataset to the GB population are:
| Grossing Control Variable | Breakdowns Used | Data Source |
|---|---|---|
| Household numbers | Country and region | Housing statistics – Office for National Statistics (ONS) |
| Housing tenure (household level) | None – GB level only | Housing statistics - MHCLG, Welsh Government and National Records of Scotland |
| Council Tax bands (household level) | None – GB level only | Council Tax statistics - Valuation Office and Scottish Government |
| Employment (individual level) | Age and gender | Employment caseloads – Office for Budget Responsibility (OBR) using Labour Force Survey data |
| Benefit caseloads (individual or benefit unit level) | Variable by benefit | Administrative data for Attendance Allowance (AA), Disability Living Allowance (DLA) and Personal Independence Payment (PIP), ESA; Contributory and Income Related, JSA; Contributory and Income Based, IS, HB; working age and pension age, UC, PC – DWP. Administrative data for Child Benefit, CTC, WTC - HMRC |
From FYE 2024 additional grossing controls have been added to the PSM output dataset as a result of implementing the new approach which uses calibrated outputs. This improves the representativeness of the weighted survey sample, with respect to benefit caseloads, which refines the weights for the sample of ENR cases. It also ensures a consistent approach with other statistics. Aligning total working age caseloads and expenditure more closely with administrative data improves the internal consistency of the take-up framework.
Aligning total working age caseloads and expenditure more closely with administrative data improves the internal consistency of the take‑up framework.
There are issues unique to using the PSM as a model to estimate entitlement that go beyond standard sample to grossing caveats. It is not possible to gross to entitlement figures because it is not known what these are. As noted elsewhere this is why we create a model to estimate them.
The use of the integrated FRS reduces the level of benefit under-reporting but does not remove it completely. It is possible that ENRs are over or under-represented by large amounts and grossing cannot correct for this. This is an unknown, but the implicit assumption is that after grossing, ENRs are accurately represented. Grossing to a total for chosen variables can also distort sub-population variables that are not grossed. It is possible that ENR totals are subject to this kind of distortion.
Removal of National Minimum Wage (NMW) and National Living Wage (NLW) adjustment
By default, the PSM ensures that all reported wages are at least at the level of a given person’s minimum wage. This adjustment if not included in the adjusted PSM dataset used for the take-up statistics. No adjustment is made to the earnings data reported in the FRS.
Estimating ENRs
FRS cases who are shown to be receiving benefit are automatically allocated to the ER group. FRS cases who are not receiving benefit are classed as either ENRs or NENRs depending on whether they are modelled as entitled according to the PSM.
For benefit units that are unmatched (which is a very small percentage of cases due to improved data linking), modelled PSM entitlement to the benefit is compared to FRS reported receipt of the benefit to determine whether they are an ER, ENR or NENR.
Having created the adjusted PSM dataset the average numbers of ENRs and the average amounts unclaimed are estimated by different characteristics and breakdowns for each income-related benefit and for the composite measure. Due to small sample sizes for certain characteristics, further detailed breakdowns are not possible.
Mixed age couples
Mixed-age couples, where 1 member is above State Pension age and the other is below, are modelled as entitled to UC only because they have only been able to make new claims for UC since FYE 2020. However, if they receive Pension Credit, they are modelled as receiving Pension Credit.
Other adjustments include:
- Technically, a claimant cannot be in receipt of certain legacy benefits and UC at the same time. However, simultaneous receipt of UC and legacy working age income-related benefits or tax credits is allowed where this is shown in the administrative data.
- Nil UC Awards: A UC nil award value is possible when the benefit unit is part of the UC caseload but does not receive a payment in the relevant assessment period. A core principle in constructing the adjusted PSM dataset is that administrative data is treated as the most reliable source of information on benefit receipt. This principle applies to admin-linked FRS cases reporting a nil award for Universal Credit. In these cases, any modelled entitlement is set to zero and the benefit unit is classified as a non‑entitled non‑recipient (NENR). As a result, such cases do not contribute to the estimated number of entitled non‑recipients or to the total value of unclaimed expenditure.
Assumptions made when estimating ENR caseload and unclaimed amounts for UC (or equivalent benefits)
The following section details additional assumptions and decisions made, when estimating ENRs, which were particular to the new working age estimates.
Income-related benefits ENR caseload
The PSM estimates ENR caseloads and unclaimed amounts for Pension Credit (PC), pension age Housing Benefit (HB) and Universal Credit (UC). There are no entitled non-recipients of legacy working age benefits because new claims cannot be made to these benefits.
Claimant Commitment
If a benefit unit meets the other UC eligibility rules, the following assumptions are made about whether it’s members would agree to the UC claimant commitment:
Those who are unemployed are assumed to agree to the claimant commitment and are therefore considered eligible for UC. Here, unemployment is defined using the ILO definition: not in employment, available to start within 2 weeks, and either looked for work in the last 4 weeks or waiting to start a new job.
Those who are employed or self-employed are assumed to agree to a claimant commitment to increase their earnings and are therefore considered eligible for UC.
Those who are economically inactive and not looking for work, without an accepted reason, are not considered eligible for UC in the estimates.
Those who are not looking for work but are disabled, have caring responsibilities or are lone parents are still considered for UC eligibility in the estimates.
The estimates assume that those who are otherwise eligible and either, unemployed and looking for work or employed on low income, would agree to the claimant commitment and therefore be an eligible non-recipient for UC.
In the adjusted PSM, admin-linking of UC awards overrules those benefit units prevented from having a UC entitlement calculated. The admin-linked award value will overwrite the PSM’s modelled entitlement.
Estimating unclaimed amounts
The PSM is designed to calculate benefit entitlements in a way that mirrors the relevant eligibility rules as closely as possible, based on data from the FRS and other sources. In broad terms, UC is modelled by calculating the maximum entitlement, before making deductions and applying the earnings taper. The benefit cap is also applied to ensure that the modelled entitlement does not exceed the imposed maximum.
These calculations draw upon household and benefit unit characteristics as reported in the FRS. For example: number of children, disability status, childcare arrangements, other benefit receipt (e.g. contributory benefits, carer benefits, disability benefits, Winter Fuel Payments), income from earnings and pensions. Other data sources may contribute, such as local authority data for eligible rental rates applying to housing costs.
The maximum UC entitlement incorporates all the constituent elements of the UC award. Specifically, these include the standard allowance, child element, child disability element, childcare element, limited capability for work and work-related activity (LCWRA) element, carer element and housing element.
Entitlement to each element is assessed based on the characteristics reported during the FRS interview. For example, a flat rate of £287.92 per month (in FYE 2025) is given for each child in the BU. This accounts for the 2 child limit policy, which was in place in the years reported on.
Any applicable deductions are subtracted from the maximum entitlement, including non-dependant deductions and income-related deductions. Some income-related deductions include carers allowance and contributory benefits. Non-dependant deductions are reductions on the maximum entitlement to reflect the income of non-dependants living in the household.
The income of the BU is totalled up for means testing. It is primarily composed of earnings. There are more complex calculations for those that are self-employed which won’t be explained in detail here but is available to view online. For every £1 of income over the UC work allowance, £0.55 is deducted from the entitlement. Not all BUs are eligible for a work allowance, and so their award is tapered for any amount of income.
A similar calculation occurs for capital, where every £250 of capital above £6k results in a deduction of £1 from the entitlement. This occurs up to a limit of £16k, beyond which the BU is ineligible for UC.
Finally, the entitlement is capped at the level of the UC benefit cap.
The UC entitlement modelling does not take advances and sanctions into account. This means that deductions due to advance repayments or sanctions received are not factored into the modelled entitlement.
6.5 Uncertainty in the receipt and ENR estimates
The receipt and ENR estimates are fully reliant on the accuracy of the data used and any subsequent adjustments, evidence-based assumptions, and modelling. Any errors in the data or these processes will affect uncertainty around the estimates.
Uncertainty in the receipt estimates is assumed to be marginal due to the processes in place to produce accurate DWP administrative data for publication as statistics. Therefore, no estimate of confidence intervals or similar is undertaken.
For the ENR estimates, the level of uncertainty is higher as they are reliant on reported information from FRS sample data and the subsequent modelling of entitlement in the PSM. Therefore, the estimates are affected by known areas of uncertainty surrounding survey results and using a model to estimate ENRs. While processes are in place to limit this uncertainty, such as the data cleaning of FRS responses and admin-linking to produce the published FRS dataset and continuous development of the PSM methodology, confidence intervals are used to present the uncertainty in the final take-up estimates. Note that confidence intervals only estimate the sampling error, the difference between the sample and population values, and do not include other forms of uncertainty.
In some cases, survey responses may be categorised as ENRs when they are not actually eligible.
Our modelled ENR estimates are based on certain assumptions for eligibility to benefits and the amount that would be received. So, there is also uncertainty in the estimates depending on the assumptions used. There are limitations to how much variation we can account for. The amount of UC that a family receives from 1 assessment period to the next can vary, as does the amount by family, due to the different elements of UC. For the working age estimates there is the assumption of no change to the amount being claimed by a family throughout the year which does lead to uncertainty in the results as by design, the amounts received by families can change during the year, and our estimates cannot reflect that variability. Whereas PC has less within-year variability than UC and so there is little additional uncertainty in our estimates, as the assumption of no change throughout the year generally reflects what happens in practice.
6.6 What are confidence intervals?
A confidence interval is a range of values that is likely to contain the true population parameter with a specified level of confidence. The level of confidence is typically expressed as a percentage, such as 95%. The larger the sample size, the narrower the confidence interval tends to be, and the more precise the estimate of the population parameter.
When the sample size is small, the confidence interval tends to be wider because there is more uncertainty in the estimate. This means that the range of values that could plausibly contain the true population parameter is larger.
As the sample size increases, the standard error of the estimate decreases, and the confidence interval becomes narrower. This means that the range of plausible values for the population parameter becomes smaller, and the estimate becomes more precise. For FYE 2025, the FRS achieved a sample of over 16,000 households (of which 5,000 were pensioner households) which was then grossed up to reflect the UK population.
As stated above, the confidence intervals estimate the sampling error, and are narrower for working age estimates as they are based on a larger sample size than for pensioners. However not all forms of uncertainty are included in the confidence intervals, including variation in the unclaimed amount across families and within families over the year. This variation is greater for UC, by nature of it consisting of different elements, than for pensioner benefits.
Figure 3: Info-graphic summarising the purpose of confidence intervals
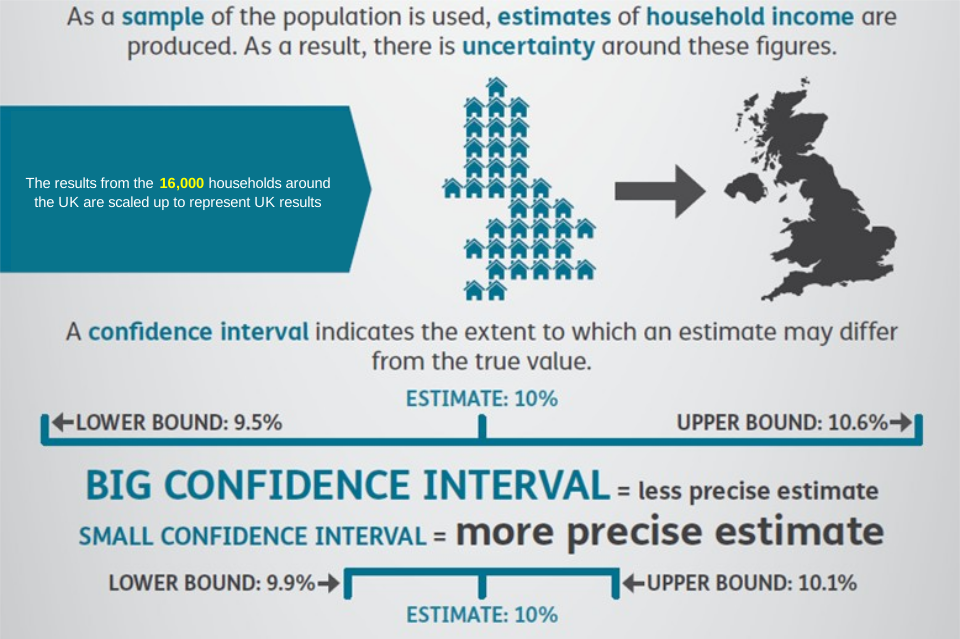
Figure demonstrates the purpose and interpretation of confidence intervals. It states that as a sample of the population is used, that estimates of household income are produced, and as a result there is uncertainty around these figures.
The results from the 16,000 households around the UK are scaled up to represent UK results. A confidence interval indicates the extent to which an estimate may differ from the true value.
For example, with a 10% estimate if the lower bound and upper bound estimates are 9.5% and 10.6% then this would be a big confidence interval representing a less precise estimate.
This is in comparison to a lower bound and upper bound estimate of 9.9% and 10.1%, which is a small confidence interval representing a more precise estimate.
6.7 Confidence intervals for the ENR estimates
As the ENR estimates are heavily reliant on the FRS sample, the level of uncertainty can be estimated by exploring how that estimate would change if many survey samples were drawn for the same time period instead of just 1. From this, a range around the estimate can be defined, known as a confidence interval. This indicates how likely it is that the real value that the survey is trying to measure lies within that range. Confidence intervals are typically set up to be 95% certain that the true value lies within the range. This is known as a 95% confidence interval.
Confidence intervals are used to show how much the estimate may differ from the true value. Bigger confidence intervals show less precise estimates and smaller confidence intervals show more precise estimates.
For comparison purposes, where the confidence intervals are not overlapping, there is a statistically significant difference.
Method
The ‘variance estimation based on sample design’ method was used to produce confidence intervals for the take-up estimates as:
- the sampling frame of the FRS is taken into consideration in this method
- it is appropriate when calculating the prevalence of a characteristic in a population, such as those entitled and not receiving
The ENR estimates are derived from the adjusted PSM dataset rather than the published FRS dataset. However, this should not affect the sampling error, as this occurs at the stage of the sampling, and therefore any modelling of FRS sample benefit units in the PSM should not affect the confidence intervals. The average numbers of ENRs, and the average amounts unclaimed are estimated, along with 95% confidence intervals to reflect uncertainty. These estimates are combined with the receipt estimates to produce the lower bound, central, and upper bound take-up estimates.
6.8 Estimating take-up rates
Overview
The take-up rates are based on the following definition:
(In Receipt) ÷ (In Receipt + Entitled Not in Receipt)
Where the take-up rate is defined as the proportion receiving the benefit of all those entitled (that is those receiving the benefit they are entitled to and those who are entitled but not receiving the benefit). A central estimate take-up rate is calculated using the central estimate of those entitled and not in receipt. The lower and upper take-up rate bounds are calculated using the upper and lower bound estimates of those entitled and not in receipt.
Caseload formulae
The formulae for lower bound, central estimate and upper bound are as follows.
| Formula | |
|---|---|
| Lower Bound | Average number of benefit units receiving benefit ÷ (Average number of benefit units receiving benefit + Upper average number of ENR benefit units) |
| Central Estimate | Average number of benefit units receiving benefit ÷ (Average number of benefit units receiving benefit + Central average number of ENR benefit units) |
| Upper Bound | Average number of benefit units receiving benefit ÷ (Average number of benefit units receiving benefit + Lower average number of ENR benefit units) |
Expenditure formulae
For the expenditure formulae, the average weekly amounts claimed (received) and unclaimed (not received) are converted to yearly amounts (accounting for leap years).
The expenditure take-up formulae are as follows.
| Formula | |
|---|---|
| Lower Bound | Total amount of benefit received ÷ (Total amount of benefit received + Upper total amount of benefit not received) |
| Central Estimate | Total amount of benefit received ÷ (Total amount of benefit received + Central total amount of benefit not received) |
| Upper Bound | Total amount of benefit received ÷ (Total amount of benefit received + Lower total amount of benefit not received) |
Total amount of benefit received formula
The formulae for the total amount of benefit received and not received are as follows.
| Total amount of benefit received formula | Total amount of benefit not received formula | |
|---|---|---|
| Lower Bound | Average number of benefit units receiving benefit × Average amount of benefit received × Week to Year Factor | Lower total = Lower average number of benefit units ENRs × Lower average amount not received × Week to Year Factor |
| Central Estimate | Average number of benefit units receiving benefit × Average amount of benefit received × Week to Year Factor | Central total = Central average number of benefit unit ENRs × Central average amount not received × Week to Year Factor |
| Upper Bound | Average number of benefit units receiving benefit × Average amount of benefit received × Week to Year Factor | Upper total = Upper average number of benefit units ENRs × Upper average amount not received × Week to Year Factor |
7. Quality Management
7.1 Initial data checks
The administrative data that feeds into the receipts process of take-up has:
- initial checks carried out by the data loading team to ensure the data is accurate and fit for purpose
- caseload counts taken, as well as checks on field format/sizes, as if the data does not match the original data specification it will not load correctly
When the data is loaded into SAS (analytical software package) DWP statisticians perform the following quality assurance checks:
- comparison of current quarters caseload with the caseload from previous quarters
- frequency counts conducted against all the fields contained in the data to check volumes against previous quarters
- checks to ensure no erroneous values/formats entered
If data irregularities are found, statisticians work with the DWP data loading team to provide context to any changes, or resolve issues, and subsequently repeat the quality assurance checks on any new and corrected data.
More information on the quality assurance checks that take place can be found in the Quality statement DWP benefits.
These are all checks that take place before the take-up team access the data to start processing it for the take-up statistics.
The original FRS survey data undergoes a rigorous quality assurance process during development and processing. In March 2026, the first integrated Family Resources Survey based on linked benefits data was published, relating to FYE 2025 data. This has no impact on the take-up estimates as the FYE 2024 results were based on the same linking approach, but in effect means 1 less step in producing the publication as the administrative data linking is already incorporated in the source FRS data. For further details, please access this technical paper and quality assessment report.
The FRS dataset is then provided to the PSM team who produce entitlement data. This data is then quality assured internally.
As such, the take-up estimates are based on several data sources, all of which have their own processes in place to ensure their quality. When producing the take-up estimates, all content has been independently quality assured by different members of the team to ensure the methodology is fit for purpose. All commentary in the publication is reviewed by the team and analysts from the relevant policy areas to ensure the information presented is accurate and meets user needs.
Data Quality of the L2UC Database
The L2UC database has been used for the first time in these take-up statistics, to feed into the new working age estimates, as Official Statistics in Development. This data will also be used in the next 2 releases where the reporting period is before completion of move to UC. The database is supported by a comprehensive quality assurance (QA) framework designed to ensure accuracy, reliability, and fitness for purpose. This includes benchmarking, stakeholder and customer feedback, regular updates and sensitivity analysis. Some uncertainty is unavoidable - for example, due to policy changes, retrospective amendments to administrative data, backdated claims, or inherent limitations within administrative systems. Engagement with users and stakeholders helps identify uncertainties early and supports timely action to address them.
7.2 Standard Quality Assurance
Every SAS program:
- has its log checked to ensure no errors or warning messages are flagged when ran
- where updates to code are required before running, this is highlighted within the program with examples of how this should have been updated
- checks that code has been updated correctly form part of the quality assurance of each section of the overall take-up process
7.3 Independent assessors
Quality Assurance is conducted by:
- members of the Surveys Branch team
- a specifically defined quality assurance group, consisting of people within the Surveys team, and specific analysts from within DWP, who are experts on the benefits being measured within the final publication
Advice on methodological approach sought by an expert advisory group on Survey-based Income Statistics. Members of the Group include key users of the FRS and related outputs including:
- academic experts
- users from third-sector organisations
- methodology input from the Office for National Statistics
8. Accuracy and Reliability
8.1 Use of administrative data
It is assumed that DWP administrative data are an accurate record of benefit receipt. We accept all benefit recipients as being entitled with any ‘Non-Entitled Recipients’ ignored for the purpose of this publication. However, the data are subject to error at all stages of the process of data collection: from recipients giving inaccurate information, to input error, to data cleaning and analysis.
8.2 Use of survey data
The size of the FRS sample and the way in which the sample is selected are carefully designed to ensure that it is representative of the UK, whilst bearing in mind practical considerations like time and cost constraints. Survey results are always estimates, not precise figures. This means that they are subject to a level of uncertainty which can affect how changes, especially over the short term, should be interpreted.
The FRS is subject to the nuances of using a survey.
Sampling error
Two different random samples from 1 population are unlikely to give the same survey results, which are likely to differ again from the results if the whole population was surveyed. This level of sampling error varies to a greater or lesser extent depending on the level of breakdowns at which results are presented.
Non-response error
The overall response rate for the FRS, as a percentage of the issued sample who were eligible to take part, was 31%.
Survey coverage
The FRS covers private households in the UK, therefore, those in nursing homes, student halls of residence, military barracks, prison or temporarily living in bed and breakfast accommodation, will not be included. This means that figures relating to the most elderly individuals may not be representative of the UK population, as many of those at this age will have moved into homes where they can receive more frequent help.
Survey design
The FRS uses a clustered sample design to produce strong estimates at regional level - the FRS is therefore not suitable for analysis below this level.
Sample size
From April 2011, the target achieved UK sample size for the FRS was reduced by 5,000 households from 25,000 to 20,000 households a year. A published assessment concluded that this reduced sample still allowed the core outputs from the FRS to be produced.
Further details on the FRS sample can be found in the FRS background information and methodology and in the FRS quality assessment report.
8.3 Under-reporting receipt in the FRS
There is a known issue of benefit under-reporting in the FRS. The integration of administrative data in the FRS dataset reduces the under-reporting and benefit confusion as we no longer rely on FRS participants correctly reporting the benefits they receive.
In March 2026, the first integrated Family Resources Survey based on linked benefits data was published, relating to FYE 2025 data. This has no impact on the take-up estimates as the FYE 2024 results were based on the same linking approach, but in effect means 1 less step in producing the publication as the administrative data linking is already incorporated in the source FRS data. For further details, please access this technical paper and quality assessment report.
To reduce under-reporting, data linking allows recorded benefit amounts in DWP administrative data to replace reported FRS receipt or modelled PSM receipt in the PSM dataset. This was possible for over 95% of FRS respondents in FYE 2025.
For the remaining small number of unlinked cases, it is possible that the PSM categorises a benefit unit into the wrong group. The benefit unit could be modelled as an ENR, despite receiving UC as they did not report receipt or give an amount in the FRS interview. In other situations, the benefit unit might not report important information which is used to identify which group they should be allocated to, such as receiving Attendance Allowance for the estimation of PC and HB entitlement.
8.4 Imperfect modelling of entitlement
Imperfect modelling of the tax and benefit system rules in the PSM could result in:
- over-statement of entitlement - this is where the benefit unit is incorrectly modelled to be entitled and/ or the modelled amount is too high
- under-statement of entitlement - this is where the benefit is incorrectly modelled to not be entitled and/ or the modelled amount is too low
If there is a linked amount in the administrative data then entitlement becomes the linked amount, not the modelled amount. Processes are in place to regularly review and develop the modelling to ensure the PSM accurately represents the tax and benefit system rules for each year. However, as it is heavily reliant on reported information in the FRS, the PSM inherits the areas of uncertainty of the FRS.
Additionally, the FRS does not currently flag individuals with a ‘No Recourse to Public Funds’ condition on their visa. This is a UK immigration condition, meaning an individual is not eligible to claim certain benefits. So, it is possible some individuals may be being flagged as Entitled Non-Recipients (ENR), when in reality they are Non-Entitled, Non-Recipients (NENRs).
8.5 Inaccurate grossing-up to the GB population
The PSM grossing method uses several control variables to ensure that various characteristics of the benefit units are considered in deriving the grossing factors. But it is another potential source of uncertainty as it does assume that many of the characteristics of the ENR sample are representative of all GB benefit units. The PSM grossing method (as detailed in section 6.4 b of this report) is distinct to the method used by the FRS, more detail in the FRS background information and methodology.
9. Coherence and comparability
Given the adjustments and coverage of the take-up methodology, receipt and expenditure estimates here will not be the same as the Official Statistics published by DWP. DWP publishes a wide range of statistics on receipt of benefits and benefit expenditure.
Read about DWP Official Statistics
Read about Benefit expenditure and caseload tables.
Read about Pension Credit Official Statistics.
Read about Universal Credit Official Statistics.
Stat-Xplore is a DWP tool that provides users with access to data. Users can download and analyse statistics on a range of different benefits, programmes, and other information collected and stored by DWP.
HMRC published estimates of the take-up of tax credits. The FYE 2018 publication of tax credits take-up rates was the last in the series of publications as from January 2019 it was no longer possible for most people to make a new claim for tax credits. HMRC continues to publish statistics on the take-up of child benefit: Child Benefit Statistics: annual release, data at August 2025
DWP released an ad hoc publication, “Analysis of households potentially eligible for Pension Credit, and eligible households in receipt of Pension Credit – 2023/24”, in October 2025. This publication provided analysis of the characteristics of households potentially eligible for, but not claiming, Pension Credit with, a focus on local area estimates.
For further information please see the ad hoc publication.
DWP release a publication to go alongside the annual Fraud and Error in the Benefit system publication. This is called “Unfulfilled eligibility in the benefit system Financial Year Ending (FYE) 2025”.
This publication estimates how much extra money benefit claimants could be getting if they told DWP accurately about their circumstances. These people are already getting some money on a certain benefit but may not be getting all the money they could be eligible for on this benefit – this is called unfulfilled eligibility. This complements the Income-related benefits: estimates of take-up publication which focuses on ENRs.
For further information please contact Fraud and Error Measurement Analysis (FEMA) at enquiries.fema@dwp.gov.uk.
10. Limitations and strengths of the statistics
There is general uncertainty in our estimates, especially in those of ENRs of benefits, given the complexity of estimation. The FRS, used in the estimation of ENRs, is not designed specifically to measure entitlement criteria to the same extent as an application for a specific benefit. It is a multi-purpose household survey.
The estimates of ENRs are based on PSM data, which is modelled FRS data, and are therefore subject to sampling variation and other forms of error associated with a sample survey. These include reporting errors, under-reporting of benefit receipt which has been reduced with the integration of administrative data into the FRS in FYE 2025, systematic bias, and random sampling error. For more details, please see the FRS background information and methodology and the FRS quality assessment report.
Due to restrictions in modelling and available data, certain populations are excluded from our analysis. As such the results do not include:
- those living in non-private households
- estimates for Northern Ireland (Only figures for GB are reported) due to the differences in benefit systems
Take-up statistics are not available at a lower level of geography than GB. This is because the FRS uses a clustered sample design to produce strong estimates at regional level, and it is therefore not suitable for analysis below this level. Further, the survey sample sizes for ENRs are too small to calculate take-up rates in smaller geographical areas. Similarly, HB (for pensioners) take-up statistics are only available as totals. This is also because the survey sample sizes for ENRs are too small to be able to calculate take-up rates for sub-groups.
With the abolition of SC for new pensioners from April 2016, and the reducing number of SC only cases in the eligible population, we are no longer able to estimate SC breakdowns with a sufficient level of confidence. Therefore, from FYE 2022 onwards, SC breakdowns are not included in the data tables. Historic SC breakdowns can be found in previous releases.
Breakdowns of take-up for UC (or equivalent benefits) are a composite measure. When we are able to report on take-up for UC-only we will review if further breakdowns possible.
Take-up of benefits can be affected by multiple factors. Trying to explain the reasons for non-take-up is difficult and we do not have data in our modelling to do this. Eurofound 2015 has stated “non-take-up can largely be explained by a varying mix of the following reasons:
• lack of awareness or misperceptions about entitlement or application procedures
• complexity of the application procedure or lack of resources such as time and capabilities to navigate the system
• stigma, perceived lack of need, pride and lack of trust in institutions
Despite the above limitations, the strengths of these estimates are that they provide a national estimate for take-up. They use DWP’s administrative data to provide coverage for GB for caseload and expenditure. When estimating ENRs we have information from the FRS to determine benefit eligibility that is not possible from administrative data alone, for example household savings. This is input into the PSM to generate estimated ENRs and unclaimed amounts. The receipt data and ENR data are made as consistent as possible in terms of exclusions and inclusions to allow for comparable figures to estimate take-up.
11. Improvements and refinements
The take-up estimates use a complex methodology that uses numerous data sources. Each year the team checks all the contributing codes and processes for any potential improvements that could be made to improve the accuracy of the take-up estimates produced. DWP’s policy statement describes how DWP will handle revisions.
For improvements in years prior to FYE 2025, please refer to this section in the FYE 2024 release, Background information and methodology for financial year ending 2024
11.1 First release of take-up estimates for UC (or equivalent benefits)
Introduction of take-up statistics for Universal Credit (or equivalent benefits) for FYE 2024 and FYE 2025 as Official Statistics in Development, in the FYE 2025 release. This publication includes new tables and also an updated background information and methodology document.
11.2 Integration of administrative data into the FRS
In March 2026, the first integrated Family Resources Survey based on linked benefits data was published, relating to FYE 2025 data. This has no impact on the take-up estimates as the FYE 2024 results were based on the same linking approach, but in effect means 1 less step in producing the publication as the administrative data linking is already incorporated in the source FRS data. For further details, please access this technical paper and quality assessment report.
11.3 Revision to account for leap years
We have made a methodological improvement in earlier years to account for leap years. This affects the conversion from weekly to annual expenditure estimates, but changes are small. This has been implemented within this FYE 2025 release and therefore previous data should not be used.
12. Glossary
This glossary gives a brief explanation for each of the key terms used in the take-up Publication.
Contact
Further details on these definitions, are available on request from the DWP Take-Up Team at: irb.takeup@dwp.gov.uk
See the income and earnings Glossary produced by the ONS.
Average
See Mean.
Benefits
Financial support from the government. Most of these benefits are administered by DWP. The major exceptions are Housing Benefit and Council Tax Reduction, which are administered by local authorities and certain Scottish benefits administered by Social Security Scotland.
Benefit unit or family
There are various types of benefit unit:
A single adult or married or cohabiting couple, and any dependent children. We may sometimes refer to a benefit unit as a family throughout this report.
Examples of Benefit units:
- pensioner couple: Benefit units where both partners are over SPa
- working age couple: Benefit units where at least 1 partner is of working age (under SPa)
- single male pensioner: Benefit units headed by a single male adult over SPa
- single female pensioner: Benefit units headed by a single female adult over SPa
- single male adult: Benefit units headed by a single male adult under SPa
- single female adult: Benefit units headed by a single female adult under SPa
- couple with children: Benefit units where at least 1 partner is of working age, with dependent children
- couple without children: Benefit units where at least 1 partner is of working age, with no dependent children
- single with children: Benefit unit containing a single adult (male or female) under SPa, with dependent children
- single without children: Benefit unit containing a single adult (male or female) under SPa, with no dependent children
Caseload
The number of people claiming a benefit.
In our estimates, take-up compares the number of benefit recipients/families, averaged over the year, with the estimated number that would be receiving if everyone took up their entitlement for the full period of their entitlement.
Claimant or Customer
A person making a claim for a benefit.
Composite measure
For the working age take-up measure we combine UC and legacy income-related benefits/tax credits, including JSA, ESA, IS, HB, WTC and CTC.
Confidence interval
A measure of sampling error. A confidence interval is a range around an estimate which states how likely it is that the real value that the survey is trying to measure lies within that range. A wider confidence interval indicates a greater uncertainty around the estimate. Generally, a smaller sample size will lead to estimates that have a wider confidence interval than estimates from larger sample sizes. This is because a smaller sample is less likely to reflect the characteristics of the total population and therefore there will be more uncertainty around the estimate derived from the sample. Note that a confidence interval ignores any systematic errors that may be present in the survey and analysis processes.
Dependent children
Children under 16, or young people aged 16-19 in full-time non-advanced education (education up to A levels or equivalent).
Employment and Support Allowance (ESA)
A working age benefit that is paid to support people who have a disability or health condition that affects how much they can work.
Entitled
A family is said to be entitled to receive a benefit if they satisfy the qualifying conditions for that benefit.
Entitlement
Entitlement is the amount an entitled family is estimated to be paid in benefit, according to the linked amount or modelling.
Entitled Non-Recipient (ENR)
A family that is modelled to be entitled to a benefit but is not receiving it is said to be an ENR.
Entitled Recipient (ER)
A family that is modelled to be entitled to a benefit and is receiving it is said to be an ER.
Expenditure
The amount that recipients claim.
In our estimates, take-up compares the total amount of benefit received, over a year, with the estimated total amount that would be received if everyone took up their entitlement for the full period of their entitlement.
Non-Entitled Non-Recipient (NENR)
A family that is modelled to be not entitled to a benefit and is not receiving it is said to be an NENR.
Family
See Benefit unit.
Family Resources Survey (FRS)
The FRS is one of the largest cross-sectional household surveys in the country. In FYE 2025 the sample size achieved was just over 16,000.
Read the latest FRS information and publication.
Household
A household consists of 1 person living alone or a group of people (not necessarily related) living at the same address, who share cooking facilities and share a living room or sitting room or dining area. A household will consist of 1 or more benefit units.
Housing Benefit (HB)
Housing Benefit (HB) helps tenants who are on a low income to pay their rent. HB is administered by local authorities who decide whether a claimant is eligible for HB, and how much they qualify for. Tenants can apply for HB irrespective of whether they are in work, or out-of-work. It may be paid alongside other income-related benefits, non-income-related benefits, or on its own. Since December 2018, due to the rollout of UC, new claims for HB can only be made in certain circumstances.
Income-related benefit
Benefits where a potential claimant’s income is considered when deciding whether they are entitled to the benefit.
Income Support (IS)
A working age benefit that is paid to support people on low income or none at all. No new claims can be made.
Jobseeker’s Allowance (JSA)
A working age benefit that is paid to help people while they look for work. No new claims can be made.
Legacy Benefit
The term used to collectively refer to the following benefits: Working Tax Credit, Child Tax Credit, Housing Benefit, Income Support, JSA (IB) and ESA (IR), which are being phased out. These benefits are replaced by Universal Credit.
Local Housing Allowance
Used to calculate Housing Benefit for tenants in the private rented sector.
Mean
The mean weekly amount claimed or unclaimed, is the average, found by adding up the amount for each benefit unit in a population and dividing the result by the total number of benefit units.
Means-tested benefits
See Income-related benefit.
Median
The median weekly unclaimed amount is the value that divides the population of ENRs, when ranked by their modelled entitlements, into 2 equal-sized groups. In other words, the median is the exact middle point where half the ENRs have larger unclaimed amounts and half have smaller unclaimed amounts.
Minimum Income Guarantee
A system of social welfare provision that guarantees that all citizens or families have an income sufficient to live on, provided they meet certain conditions.
Mixed age couple
A couple where 1 member is above SPa and the other is below.
National Living Wage
The minimum wage for workers aged 25 and over.
National Minimum Wage
The minimum wage for workers aged 16 to 24.
Non-dependant deductions
A reduction in Housing Benefit or Universal Credit when an adult friend or family member lives with the claimant.
Non-means tested benefits
Benefits where a potential claimant’s income is not considered when deciding whether they are entitled to the benefit.
Pension Credit (PC)
The primary income-related benefit for those of SPa and above.
Policy Simulation Model (PSM)
A microsimulation model using household information from the Family Resources Survey and current policy on benefit entitlement rules to estimate who is entitled to benefits and the amount they could receive. The resulting dataset is used to produce estimates of benefit take-up, including estimates of ERs and ENRs.
Private household
Private households are defined as those that are not communal settings, such that students in halls of residence, residents of nursing homes, individuals living in military barracks, those in prison and those living temporarily in bed and breakfast accommodation are excluded.
Private Rented Sector
Properties being rented which are owned by a landlord.
Sampling error
The uncertainty in the estimates which arises from taking a random sample of the household population. The likely size of this error for a particular statistic can be identified and expressed as a confidence interval.
Social Rented Sector
Properties being rented which are owned by the local council or a housing association (not-for-profit organisations that own, let, and manage rented housing).
Spare Room Subsidy
A reduction in Housing Benefit when the recipient lives in a property in the social rented sector that is deemed to have at least 1 spare bedroom.
State Pension (SP)
State Pension is a payment made to qualifying individuals who have reached SPa. A new single-tier State Pension launched on 6 April 2016 for people who reach SPa on or after April 2016, to replace the previous system. This consolidated the basic State Pension and Additional State Pension into 1 single amount.
People who reached SPa before 6 April 2016 continue to receive the basic State Pension and Additional State Pension if eligible. Read more information on the State Pension.
State Pension age (SPa)
SPa is the earliest age you can start receiving your State Pension. For FYE 2025, individuals are defined to be of SPa based on their date of birth and the date of interview. Since 6 April 2010, the SPa has been gradually increasing. The FRS data contained in this report were collected throughout FYE 2025 during which the SPa for pensioners remained at 66 years. Increases to the SPa are being phased in between 2026 and 2028, bringing the SPa up to 67 years.
Statistical significance
This is a technical concept that says whether a reported change is likely to have arisen only by chance due to variations in the sampling.
Tax Credits
Working Tax Credit (WTC) and Child Tax Credit (CTC) were paid by HMRC.
Tax credits ended on 5 April 2025, except for a small residual of administrative cases, and were replaced by Universal Credit (UC). Read more information on tax credits.
In this publication tax credits are included in the umbrella term ‘Legacy benefit’ as it forms part of the composite measure used in the estimates of working age take-up.
Tenant
A person who rents a property in the social rented sector or private rented sector.
Triple lock
The basic State Pension and the new State Pension increases every year by whichever is the highest of the following:
- earnings - the average percentage growth in wages (in GB)
- prices - the percentage growth in prices in the UK as measured by the Consumer Prices Index (CPI)
- 2.5%
In FYE 2025, the increase was 8.5%, in line with average weekly earnings.
Universal Credit (UC)
A single, usually monthly payment, administered by DWP. Universal Credit (UC) is now the primary working age benefit. UC replaces all the following state support: income-based Jobseeker’s Allowance, income-related Employment and Support Allowance, Income Support, Working Tax Credit, Child Tax Credit and Housing Benefit.
Most customers will be of working age, though customers can be over SPa if their partner is still of working age. UC supports those on low incomes with their housing and living costs, as well as child and childcare support where appropriate. It is not just for those who are out of work; it is also for those who are working, but whose earnings are low enough to qualify. Customers must have capital of less than a set limit to be eligible.
By December 2018 UC was available in every Jobcentre across Great Britain. DWP completed the move of all legacy benefits to UC by the end of June 2026; with the exception of a small group of ESA(IR)/HB customers.
Working age benefit
A benefit paid to a working age person.
Working age person
A person aged between 16 years and SPa.