DESNZ Public Attitudes Tracker: Energy infrastructure and energy security, Summer 2026, UK
Published 27 October 2026

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/statistics/desnz-public-attitudes-tracker-summer-2026/desnz-public-attitudes-tracker-energy-infrastructure-and-energy-security-summer-2026-uk
The DESNZ Public Attitudes Tracker is a nationally representative annual survey of adults (aged 16 and over) in the UK that tracks public awareness, attitudes, and behaviours relating to the policies of the Department for Energy Security and Net Zero (DESNZ), such as energy and climate change.
This report provides a summary of the headline findings relating to energy infrastructure and energy security from the Summer 2026 wave of the Tracker, which ran from 7 July to 12 August 2026.
Notes for interpretation of findings
Differences between groups are only reported where they are statistically significant at the 95% confidence level.
The annual personal income referred to in the report is a self-reported measure.
Line charts included in this report, based on a longer time series, use abbreviated season names in the x-axis (for example, Summer 2026 = Sum 2026).
The age-related findings are reported using six age groups (16-24, 25-34, 35-44, 45-54, 55-64, 65 and over). In some cases, findings across age groups have been combined to describe a general trend; for example, ‘between 78% and 88% of people aged 45 and above’ refers to the range of percentages for the three age groups 45-54, 55-64, and 65 and over.
Some of the geographical findings have fluctuated over time. These variations may, in part, be due to the base sizes in specific areas and the wide geographic area covered by regions. This also applies to other subgroup findings that have low base sizes.
Two summary self-reported measures are used in this report:
- ‘Awareness’ encompasses all respondents who said they had heard of a particular concept or technology, including those who said they knew ‘hardly anything but I’ve heard of this’, ‘a little’, ‘a fair amount’, or ‘a lot’.
- ‘Knowledge’ encompasses those who said that they knew ‘a fair amount’ or ‘a lot’ about a topic.
Awareness and support for new electricity network infrastructure
A question on awareness of the need for new electricity network infrastructure is asked in Summer and Winter waves.[footnote 1]
Before being presented with the questions, the topic was introduced as follows: ‘As the UK increases the amount of electricity generated from low carbon and renewable sources, more electricity network infrastructure will be required to transfer electricity from where it is generated to where it is needed. This will include pylons, overhead power lines, and substations. Substations are sites which connect the main network to the distribution networks that supply homes and businesses. This includes sites that connect the offshore electricity transmission network onshore. Substations vary in size, however some sites can cover large areas and include steel pylons.’[footnote 2]
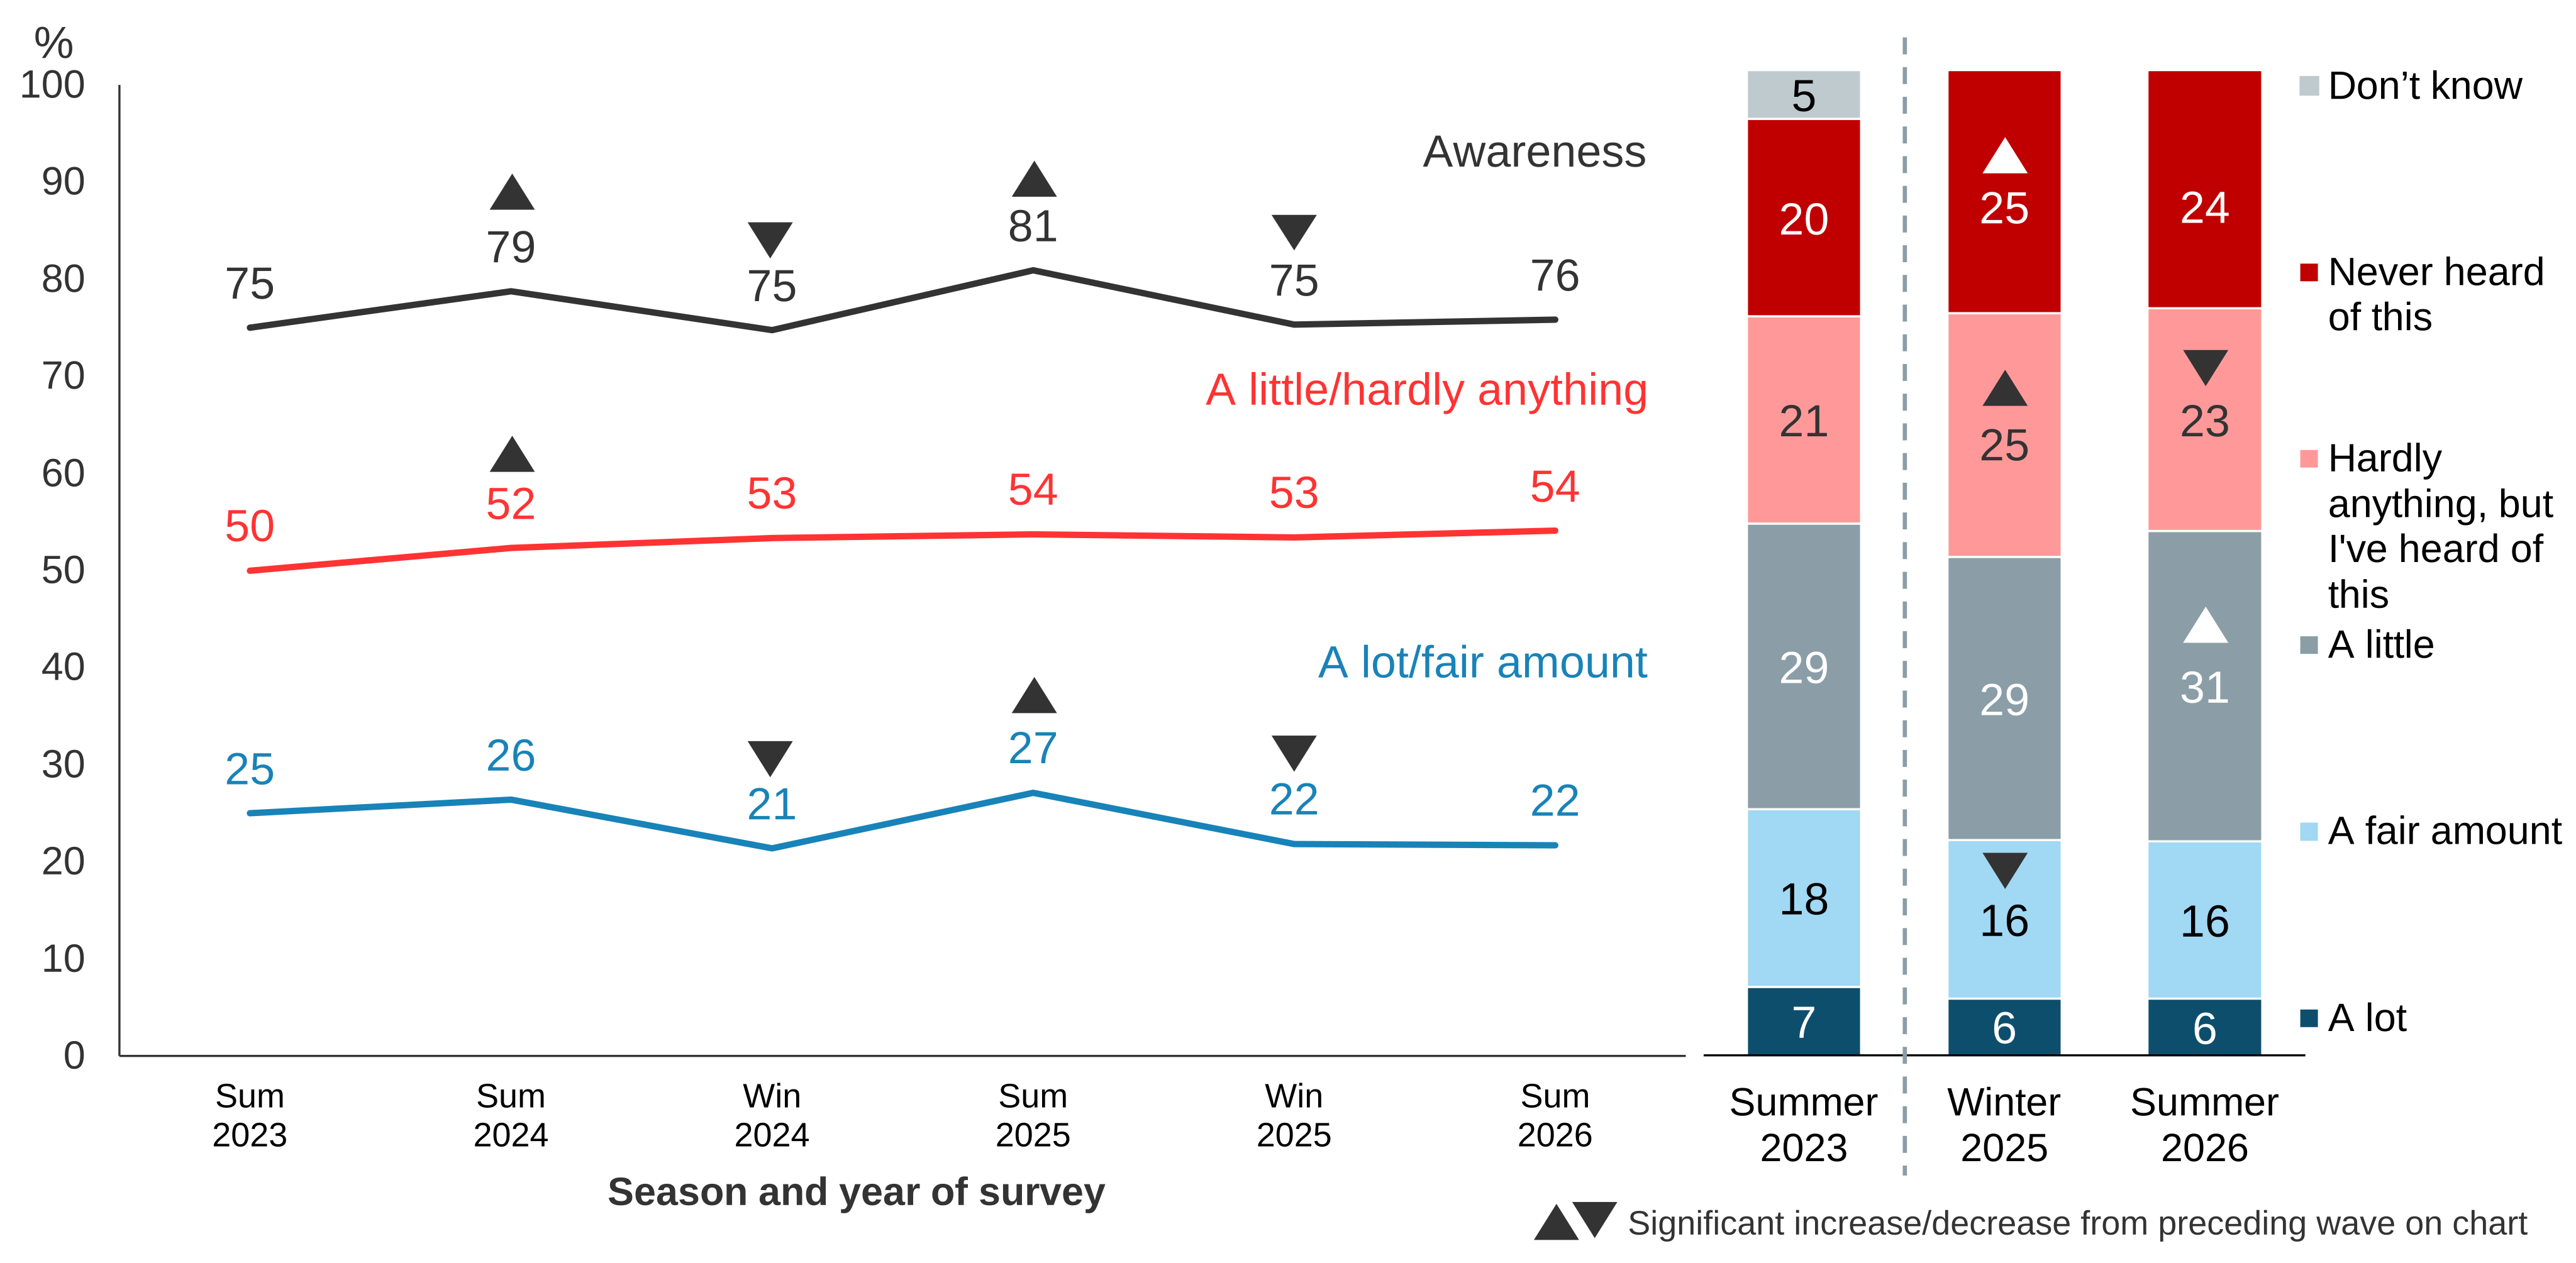
Figure 3.1 shows the longer-term trends in overall awareness (had at least heard of it) and knowledge (a lot/fair amount) of new electricity network infrastructure (line chart). It also shows more detailed awareness and knowledge data for the most recent two waves alongside the baseline (bar chart). Levels of awareness (76%) and knowledge (22%) in Summer 2026 about the need to build new infrastructure remained similar to those recorded in Winter 2025 (Figure 3.1).
In the longer term there was no sustained change in awareness since the Summer 2023 baseline. While awareness usually decreases in winter waves and increases in summer waves, there was no such increase in Summer 2026.
Knowledge declined from 25% in Summer 2023 to 22% in Summer 2026, again with some seasonal variation.
Figure 3.1: Awareness of the need to build more electricity network infrastructure (% based on all people), Summer 2023, Summer and Winter 2024, Summer* and Winter 2025, Summer 2026
INFRAKNOW. Before today how much, if anything, did you know about the need to build more electricity network infrastructure as part of the UK’s transition to low carbon and renewable energy? *‘Don’t know’ option not included in answer list from Winter 2024.
Base: All wave respondents – Summer 2023 (4,000), Summer 2024 (3,642), Winter 2024 (3,211), Summer 2025 (3,436), Winter 2025 (3,280), Summer 2026 (3,235).
*The findings for Summer 2025 have been rebased to ensure comparability with Winter 2024. See footnote at the start of this section for further details.
Note: On the line chart, arrows denote a significant difference between one wave and the next. For the bar chart, significant differences are noted between Summer 2023 and Winter 2025, and between Winter 2025 and Summer 2026.
Analysis by subgroups
Knowledge about the need to build more electricity network infrastructure was higher among the following subgroups:
- Older people: 28% of those aged 65 and over compared with 17% of those aged 16 to 24.
- People with a degree: 28% compared with 19% of those with another kind of qualification and 13% of those with no qualifications.
- People living in Wales (33%) and the East of England (29%); in contrast the lowest levels of knowledge were recorded in the North East (16%).
A similar pattern of subgroup findings was observed for overall awareness.
The following introduction was then provided as context to a further question on attitudes towards new electricity infrastructure being built locally: ‘Now imagine that there are plans for new electricity network infrastructure to be constructed in your local area. This could include building a substation and large steel pylons supporting overhead power lines’.
In previous Summer waves, people had been asked how happy or unhappy they would be to have new electricity network infrastructure built in the local area. In Summer 2026 the question was revised to ask about the extent to which people would support or oppose such construction. As a result, it is not possible to make comparisons over time.
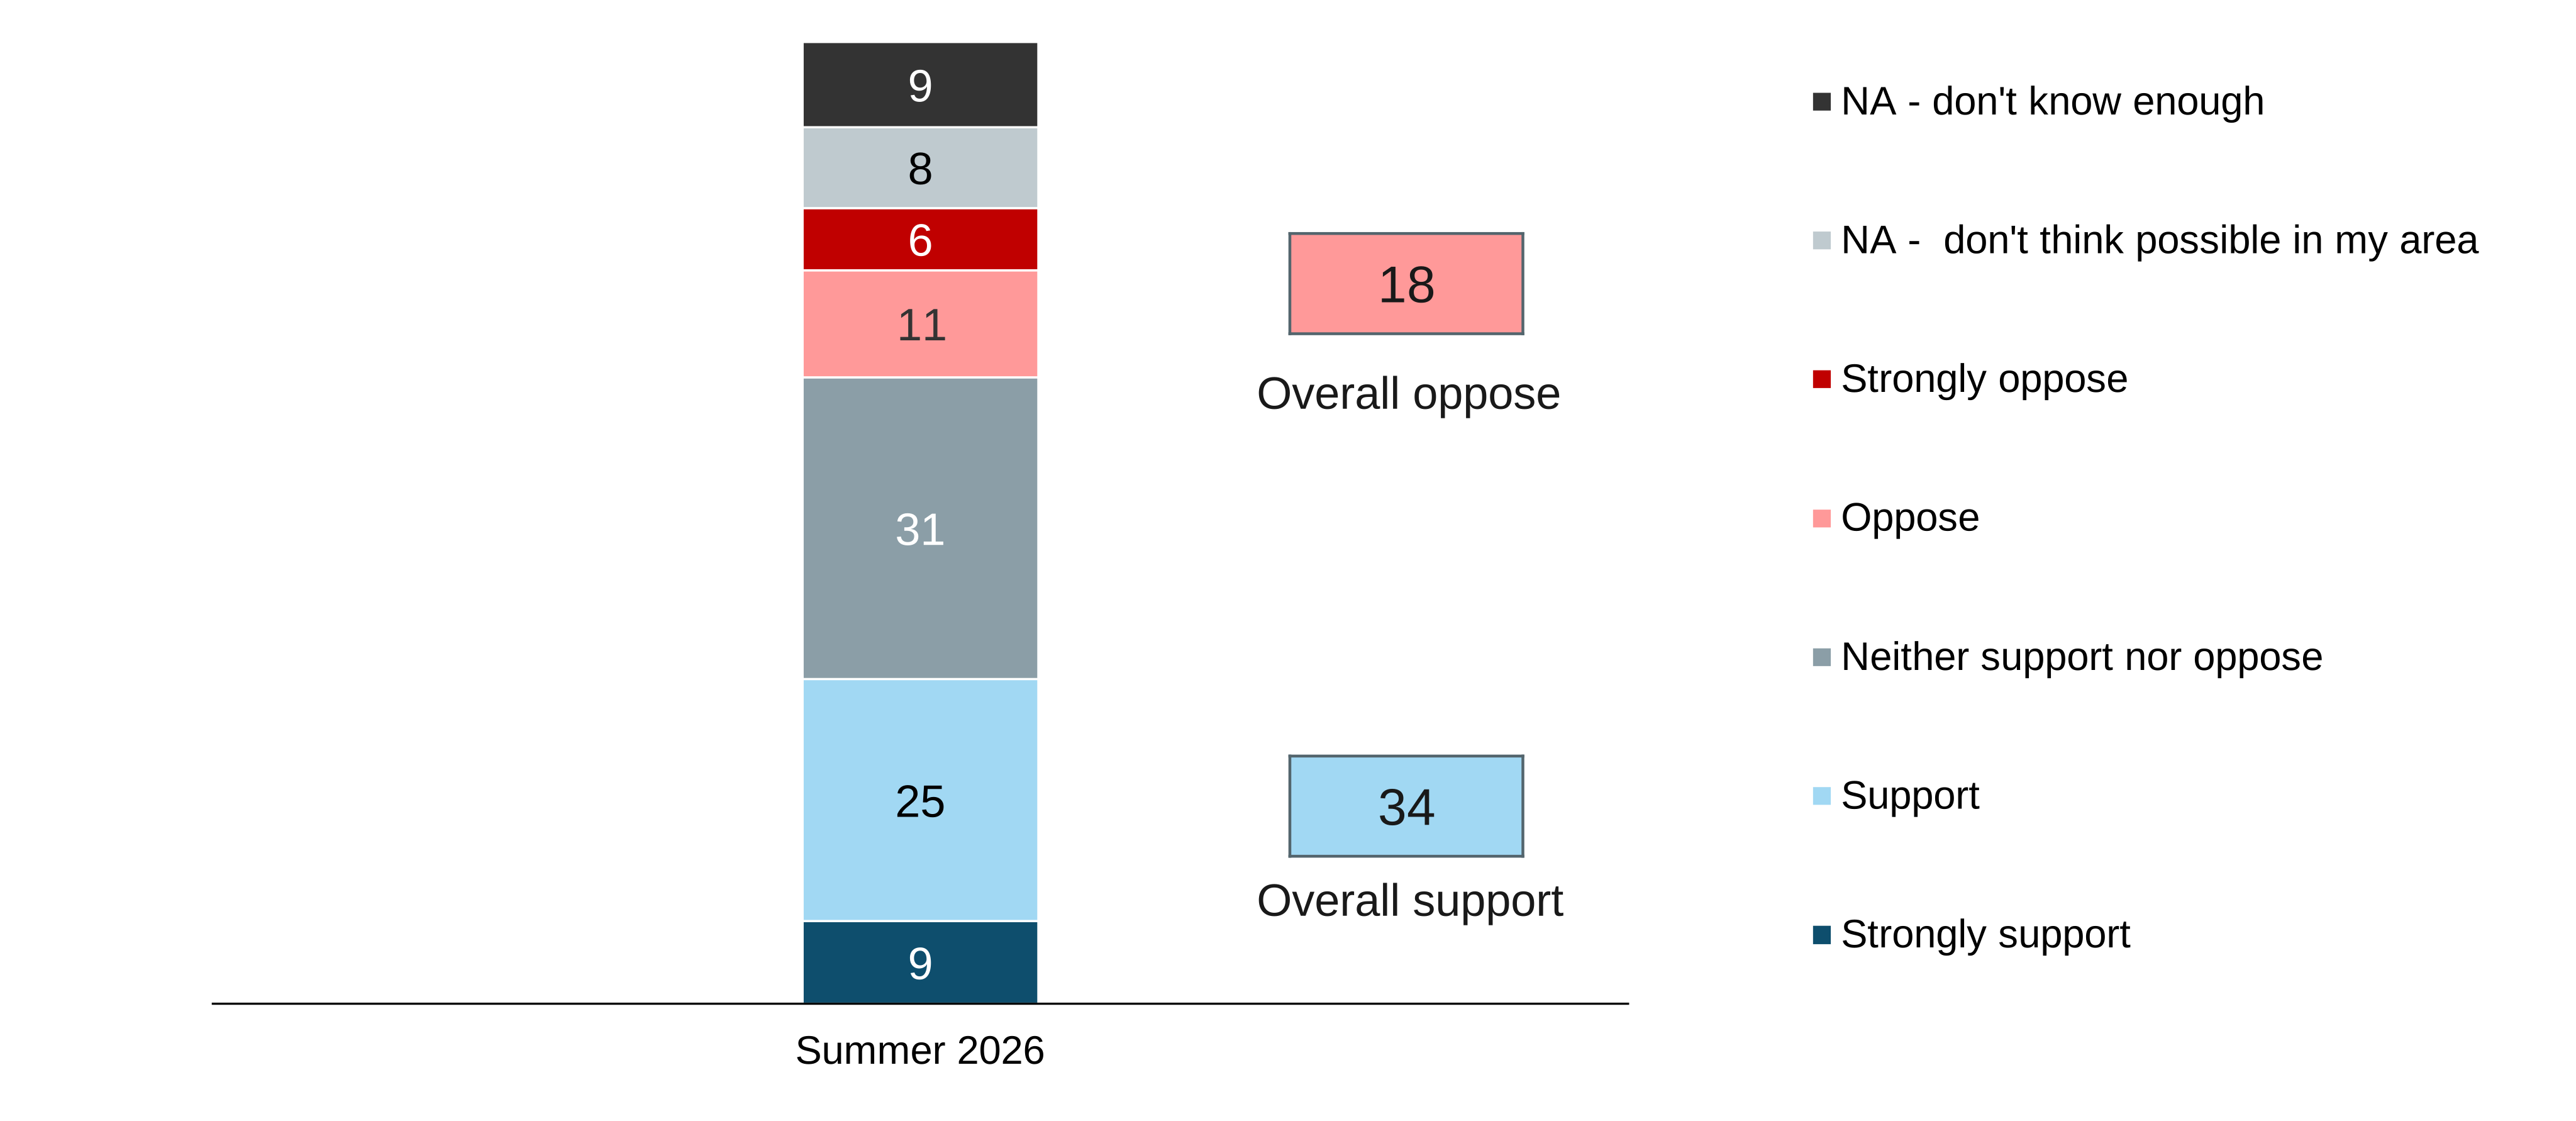
In Summer 2026, 34% of people said they would support (strongly or at all) and 18% said that they would oppose new electricity network infrastructure being built in their local area (Figure 3.2). A large proportion said they would neither support nor oppose this (31%).
Figure 3.2: Extent to which support new electricity network infrastructure being built in the local area (% based on all people), Summer 2026
INFRASUPP. To what extent would you support or oppose this? If you already have this in your local area, answer on the basis of how you feel about this now.
Base: All wave respondents – Summer 2026 (3,231).
Analysis by subgroups
Overall support for new local electricity infrastructure was higher among the following subgroups:
- People with a degree (41%) compared with those with another kind of qualification (30%) and those with no qualifications (33%).
- People living in Wales (45%) and London (38%); in contrast support was lowest in the East Midlands (28%) and the East of England (29%).
- People living in urban areas (35%) compared with those in rural areas (26%).
People in age groups 55 and over were more likely to oppose new local electricity infrastructure (between 24% and 25% compared with between 9% and 16% of those in age groups under 55).
Respondents who expressed support for building more local electricity network infrastructure (34% overall) were asked to choose their reasons from a provided list[footnote 3]. In Summer 2026, the most selected reason for support was enabling the use of more sustainable sources of power (68%). Around half of those who expressed support mentioned the need to update existing infrastructure (53%), cheaper energy bills (49%), lower dependence on foreign energy sources (47%), and benefiting the UK economy (45%). Job creation was chosen by 41% of those who were supportive of local infrastructure.
Those who said they would oppose the building of local electricity infrastructure (18% overall) were also asked to select their reasons from a list[footnote 4]. In Summer 2026, the main concerns were the impacts on the view (60%) and on local plant and animal life (54%). Several other reasons were selected by around half of those who were opposed: concerns about the impact on house prices (49%), health impacts (46%), and the infrastructure being noisy (46%), while 38% were concerned about the disruption caused by construction. A smaller proportion were concerned about a perceived lack of benefit to the local community (27%) and local economy (19%), and increased electricity bills (20%).
Of those who would oppose new local infrastructure, 12% said that this was because they did not think there was a need to reduce carbon emissions.
Concerns about energy security
Annually, in summer waves, people are asked about their level of concern regarding a range of issues relating to energy security in the next 10 to 20 years (Figure 3.3).
The findings in this section relating to energy costs and security should be viewed in the light of volatile energy prices over the period between the Summer 2022 and Summer 2026 survey waves.[footnote 5]
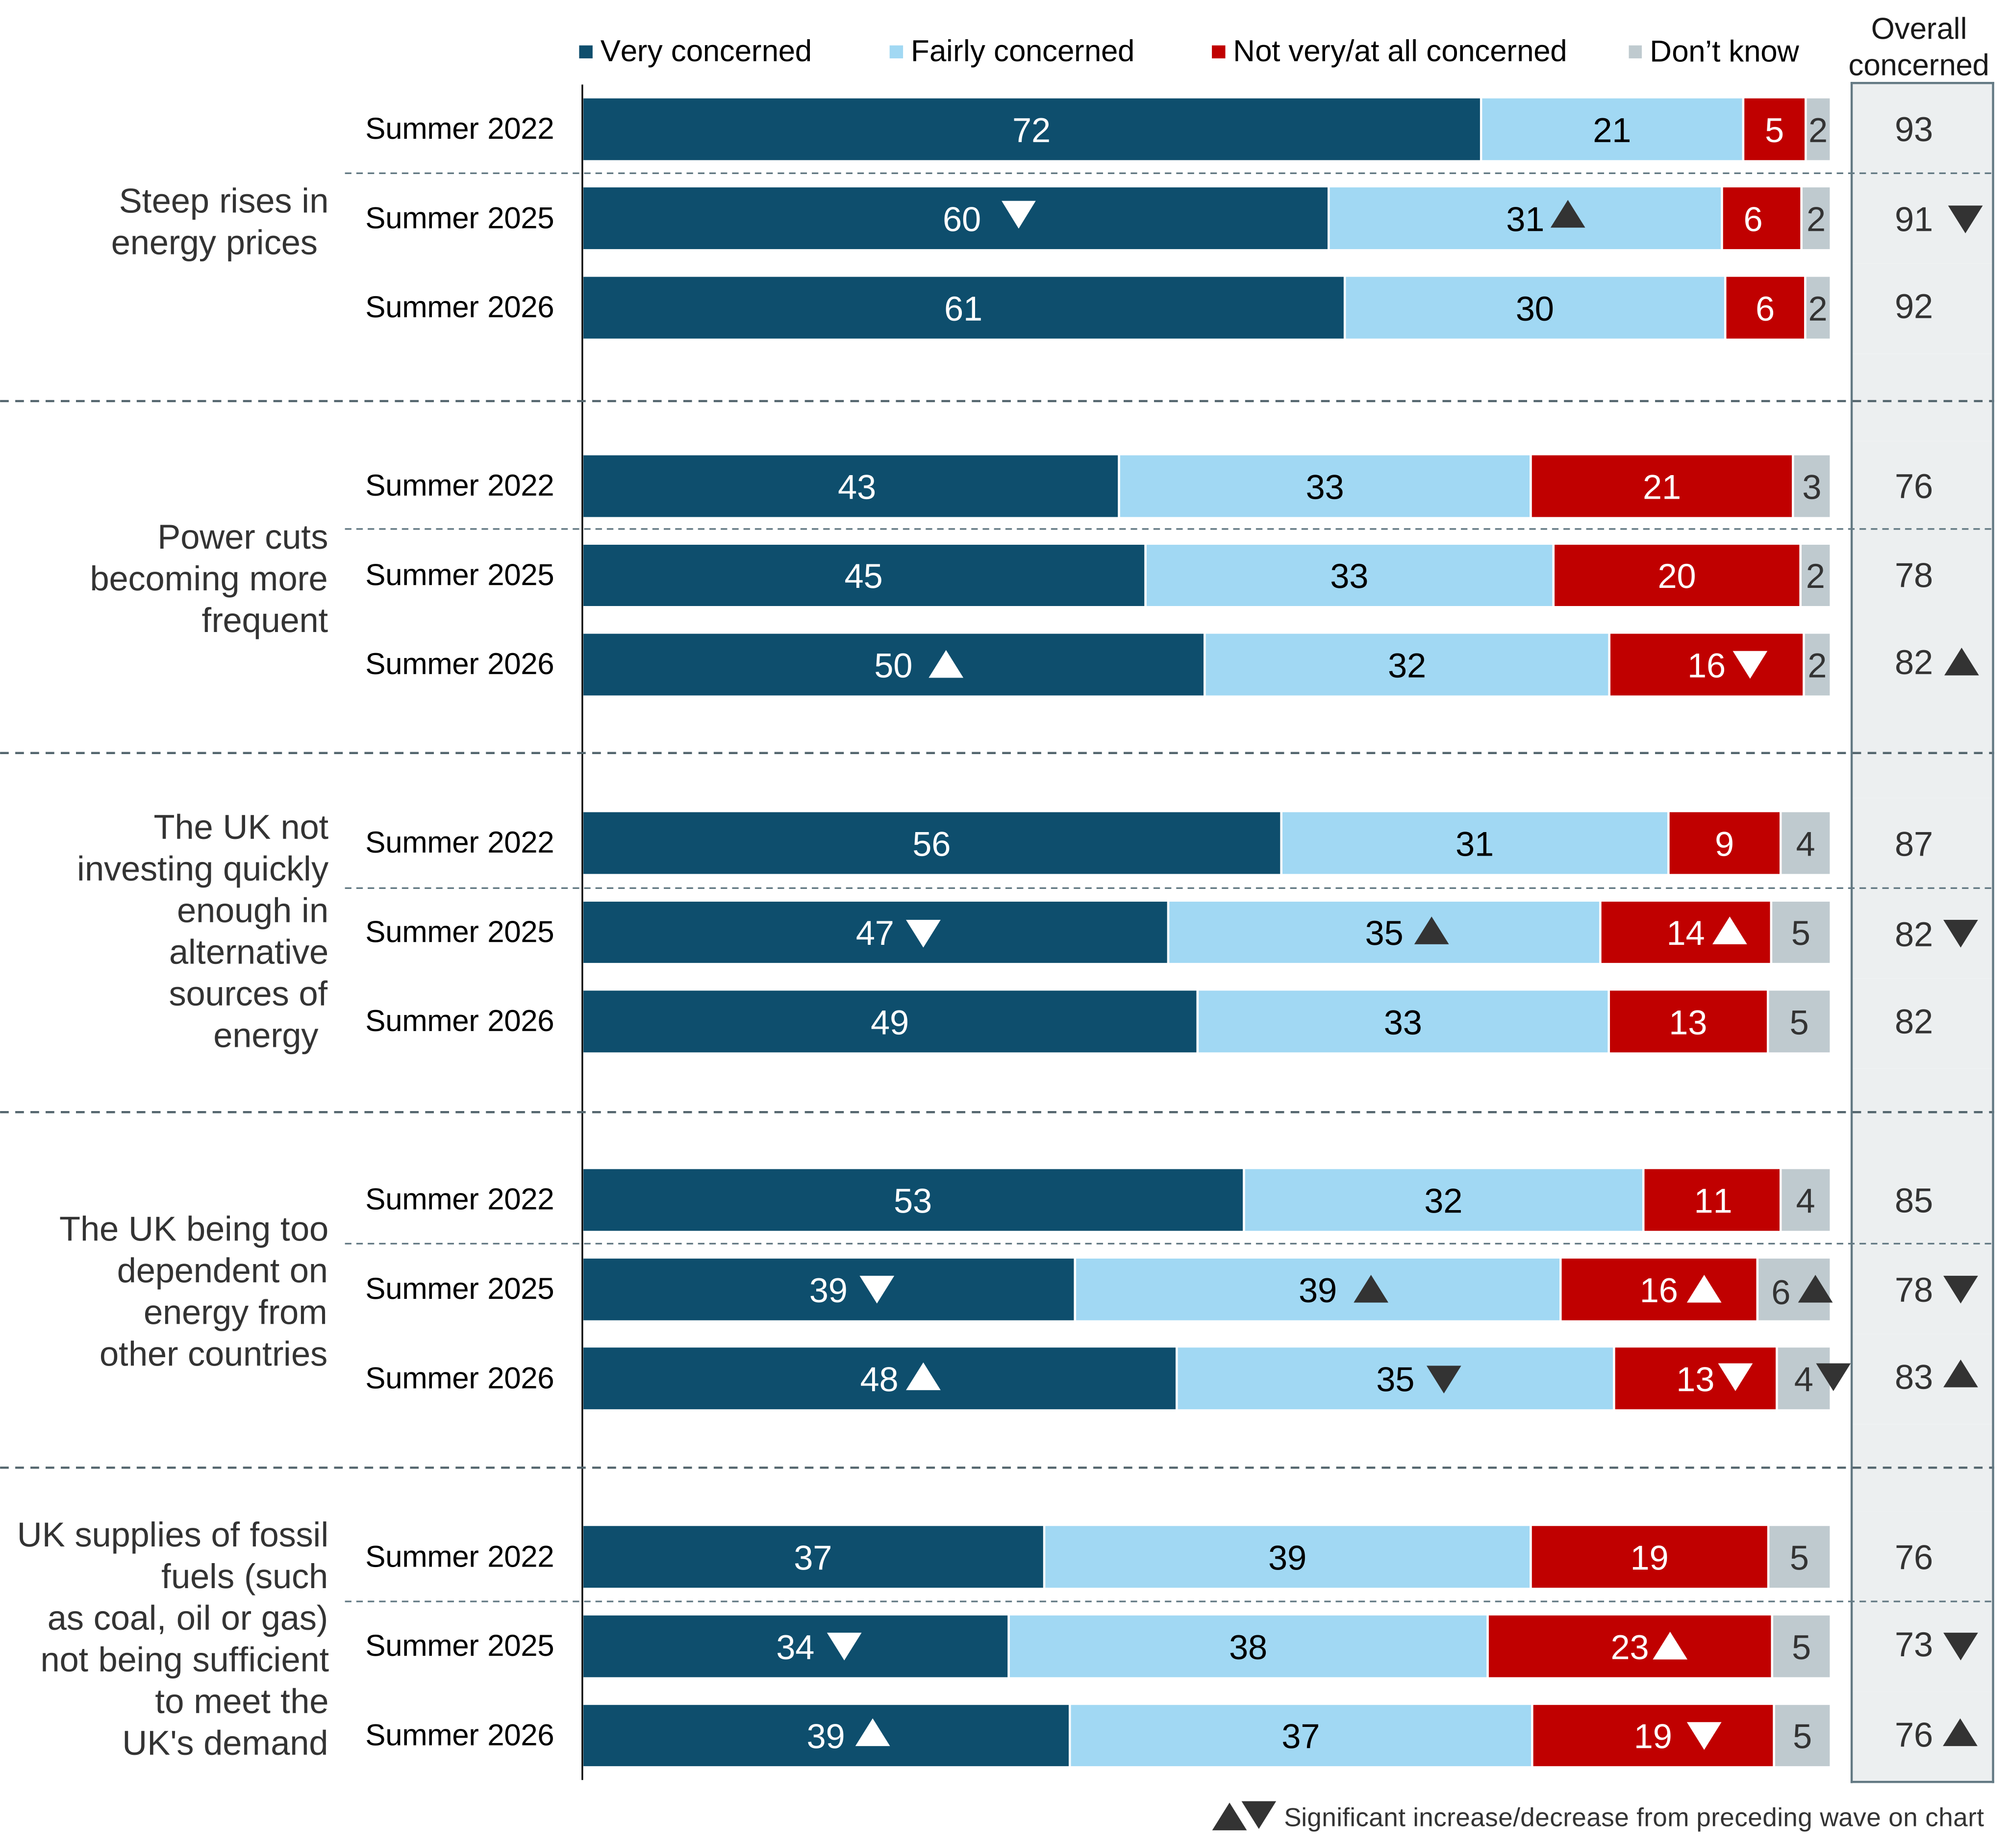
In Summer 2026, the findings can be summarised as follows (Figure 3.3):
- Around nine in ten people (92%) were concerned about steep rises in energy prices and 61% were very concerned about this.
- Over eight in ten were concerned about more frequent power cuts (82%), insufficient investment in alternative sources of energy (82%), and over-dependence on energy from other countries (83%). Around half said they were very concerned about each of these.
- Just over three-quarters (76%) expressed concern about insufficient UK supplies of fossil fuels with 39% very concerned.
- There were some increases in overall concern since Summer 2025, and these were driven by increases in the proportion who were very concerned:
- Power cuts becoming more frequent: 82% up from 78% overall.
- Being overdependent on energy from other countries: 83% up from 78%
- Insufficient UK supplies of fossil fuels: 76% up from 73%
- In the longer term, since the Summer 2022 baseline, there has been:
- An increase in overall concern about more frequent power cuts (82% up from 76%)
- A decrease in concern about the UK not investing quickly enough in alternative energy sources (82% down from 87%).
Figure 3.3: Concern about energy security in future (% based on all people), baseline (Summer 2022) and two most recent waves (Summer 2025 and Summer 2026)
ENSECCONCERN1-4,6. Now some questions about how concerned you are about various things happening in the future. By ‘the future’ we mean the next 10-20 years. So, how concerned, if at all, are you about…
Base: All wave respondents – Summer 2022/ Summer 2025/Summer 2026: Steep rises (4,487/3,526/3,238), Power cuts (4,462/3,522/3,234), Not investing (4,472/3,525/3,234), Too dependent (4,479/3,514/3,237), Supplies not being sufficient (4,469/3,525/3,235).
Analysis by subgroups
By age:
- Older people were more likely than younger people to be concerned overall about more frequent power cuts (88% of people aged 65 and over compared with 78% of people aged under 25).
- Older people were also more likely to be concerned overall about UK dependency on foreign energy sources (between 89% and 91% of those in age groups 55 and over compared with 62% of those aged under 25).
- Those in age groups 35 and over were more likely to be concerned overall about steep rises in energy prices (between 91% and 95% compared with 85% of those aged under 25).
By education:
- People with a degree were most likely to be very concerned about the UK not investing quickly enough in alternative energy sources (56% vs 42% of those with no qualifications).
People who were very or fairly concerned about the UK becoming too dependent on energy from other countries (83% overall) were asked to identify the specific energy sources they had in mind[footnote 6]. In Summer 2026, the most common responses were gas (71%), oil (67%), and electricity (47%), while 12% said they were not thinking about any specific sources.
The proportion saying they had been thinking about oil increased sharply to 67%, from 55% in Summer 2025, returning close to the levels seen at the Summer 2022 baseline (70%). The proportion thinking about gas (71%) had not changed significantly since Summer 2025 (68%) and remained lower than at the Summer 2022 baseline (76%).
Support for domestic production of oil and gas
A further question is asked annually to assess support for reducing domestic production of oil and gas, even if that means buying more from other countries.
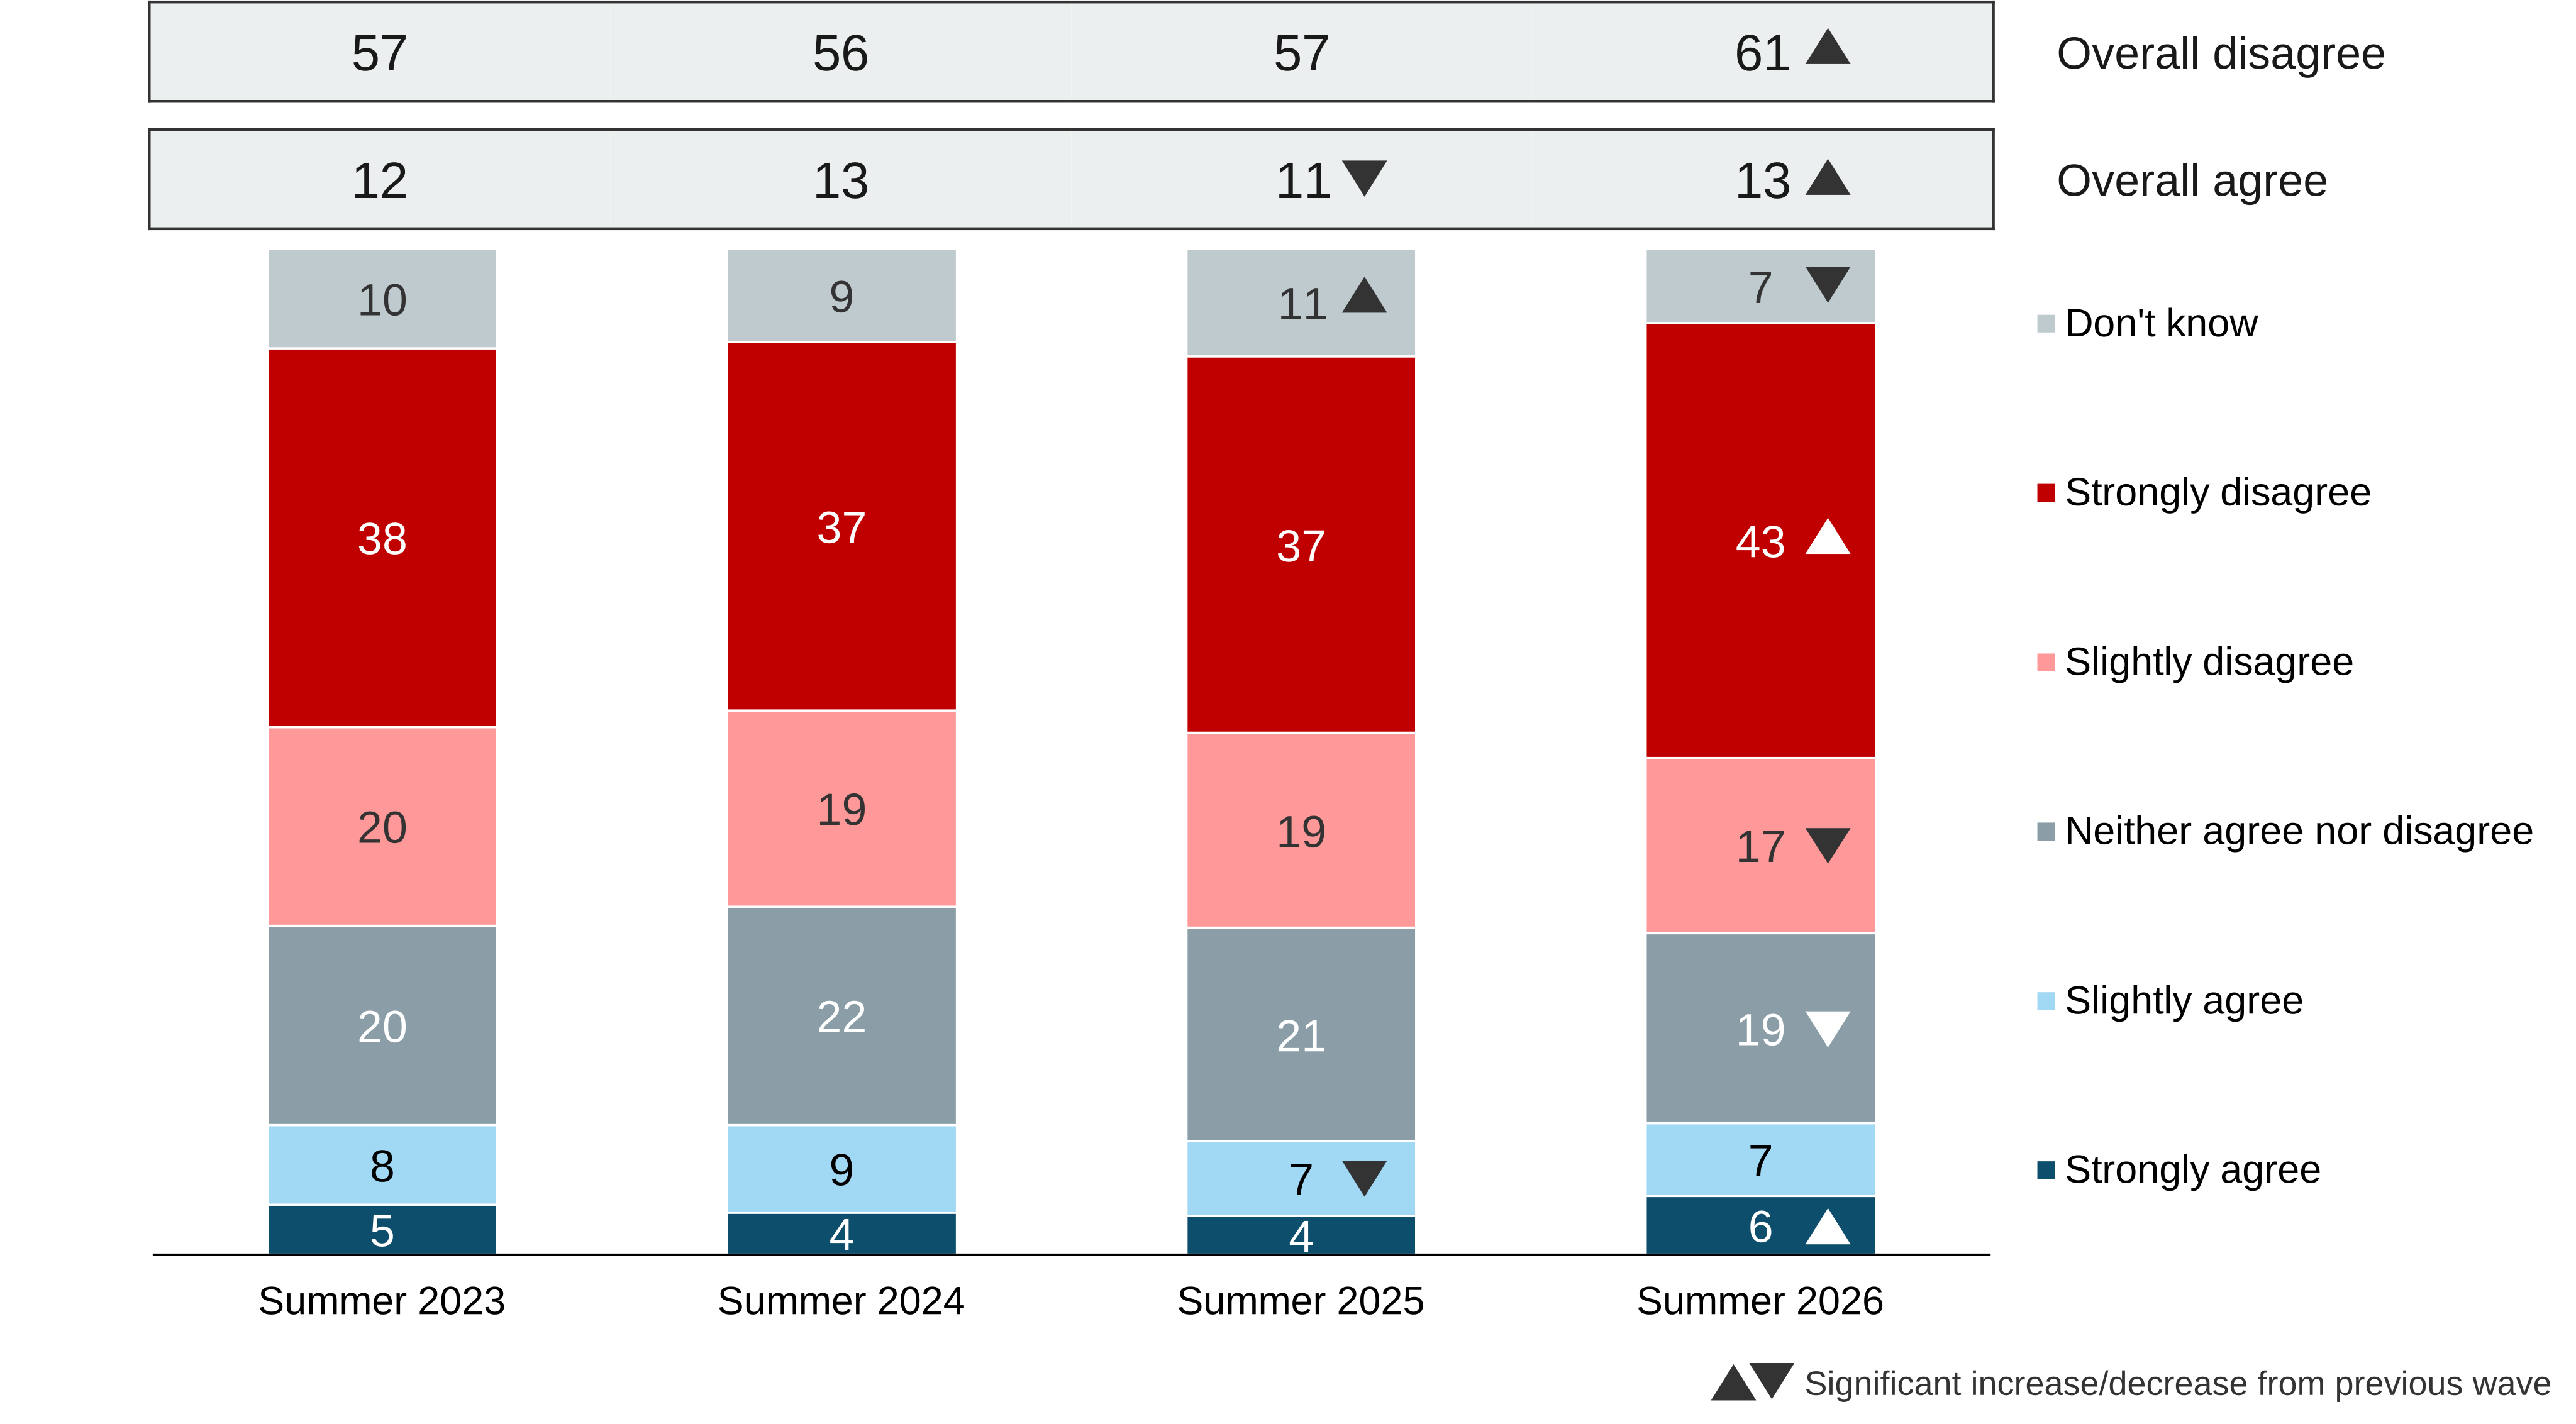
In Summer 2026, 13% agreed that the UK should reduce domestic production of oil and gas, even if that means buying more from other countries, back up from 11% in Summer 2025 (Figure 3.4). Representing an increase from previous waves, 61% disagreed, up from 57% in Summer 2025 and at the Summer 2023 baseline, while 43% disagreed strongly, up from 37% in Summer 2025 and 38% at the baseline.
Figure 3.4: Extent to which agree that the UK should produce less of its own oil and gas even if that means buying more fuel from other countries (% based on all people), Summer 2023 to 2026
ENSECOWN. How much do you agree or disagree with the following statement? The UK should produce less of its own oil and gas, even if that means we need to buy more fuel from other countries.
Base: All wave respondents – Summer 2023 (3,986), Summer 2024 (3,634), Summer 2025 (3,470), Summer 2026 (3,233).
Analysis by subgroups
Overall disagreement that the UK should reduce domestic production was higher among people in age groups 55 and over (between 74% and 76%) compared with those aged 16 to 24 (39%).
Perceived importance of different aspects of energy policy
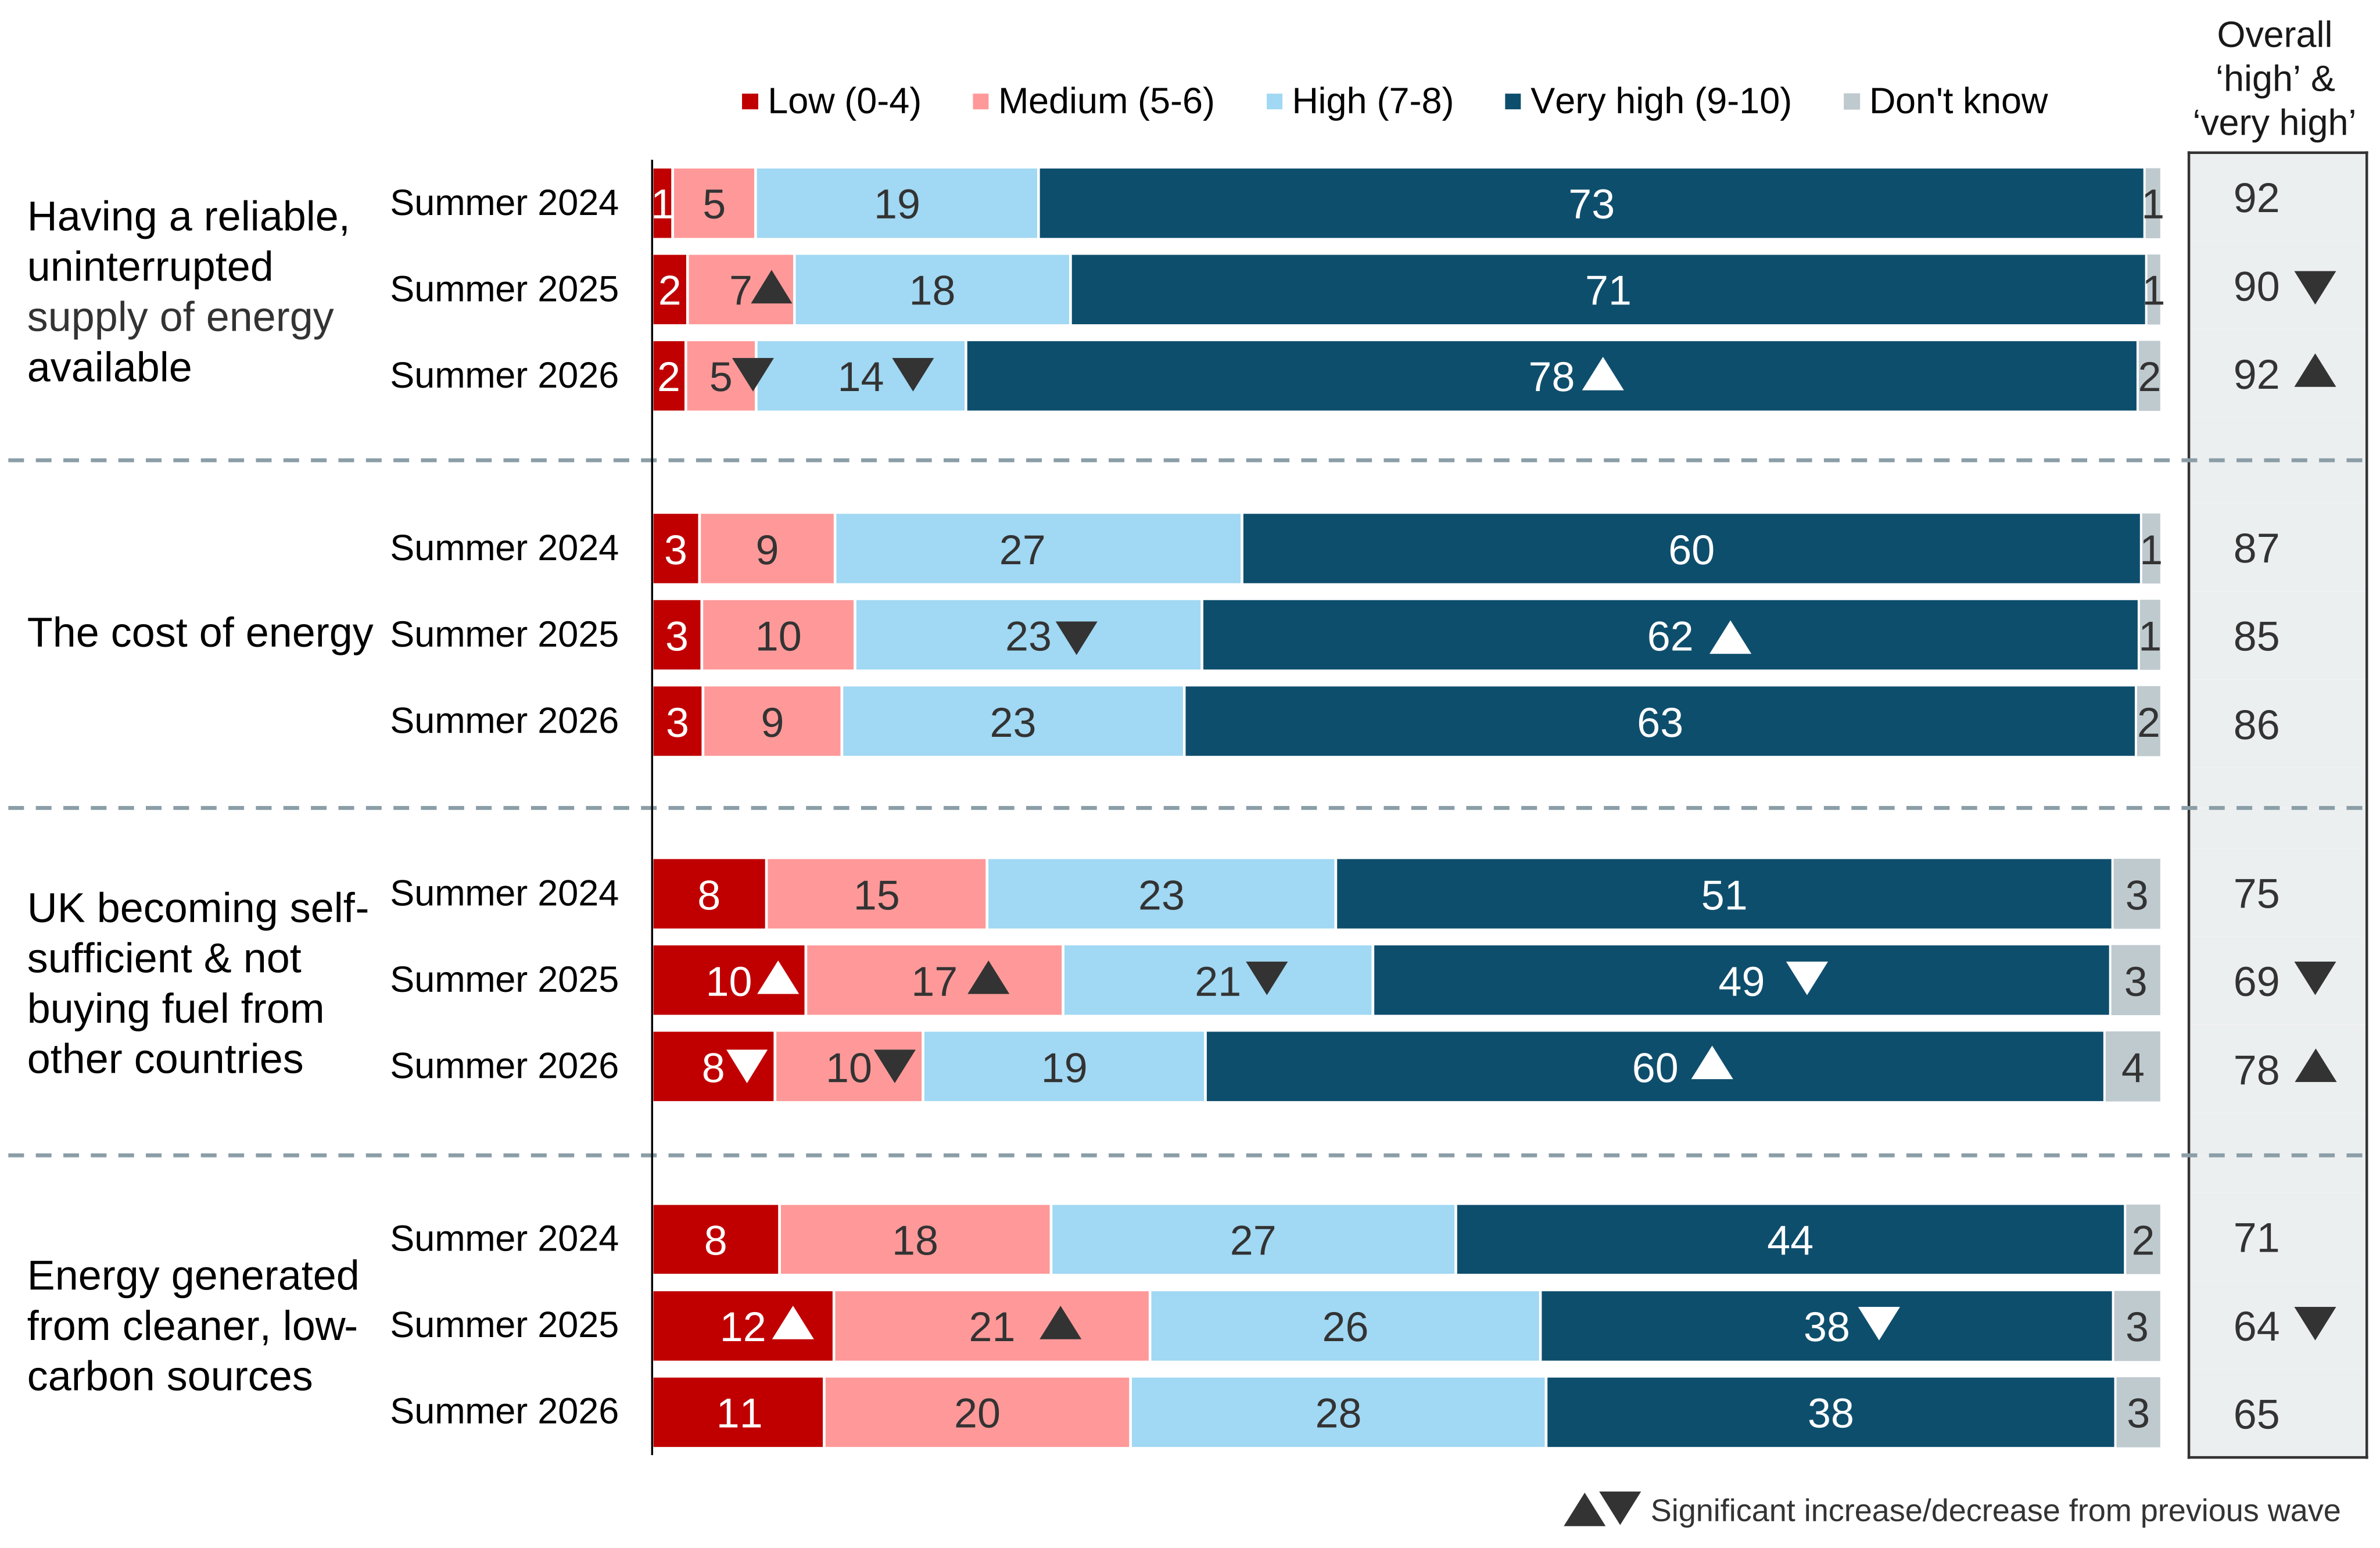
An annual question was introduced in Summer 2024, asking respondents how important various aspects of energy policy were to them personally (Figure 3.5). Two items (cost of energy and uninterrupted supply of energy) relate to factors which affect people on a day-to-day basis, while the other two items (UK energy independence and low-carbon generated energy[footnote 7]) relate to broader issues.
People were originally asked to rate the four items on a scale of 0 to 10, where 0 was least important and 10 was most important. In 2026 the end points of the scale were relabelled so that 0 was not at all and 10 was extremely important. Importance rating scores were banded into low (0 to 4), medium (5 to 6), high (7 to 8), and very high (9 to 10). Overall high importance includes ratings of seven or more. Comparisons have been made in Summer 2026 with data waves conducted before the change in wording. It is possible that this change may, to some extent, have reduced comparability.
In Summer 2026, all the different aspects of energy policy were widely regarded as important, with at least 65% giving a high or very high importance score of 7 or more to each. Issues affecting day-to-day life were regarded as most important.
Findings below are based on two summary ratings: high importance (score of 7 or more) and very high importance (9 to 10). In Summer 2026:
- 92% of people rated a reliable, uninterrupted supply of energy as being of high importance (back up from 90% in Summer 2025), with 78% rating this as of very high importance, up from 71% in Summer 2025 and 73% at the Summer 2024 baseline.
- 86% rated the cost of energy as being of high importance, with 63% rating this as very high importance. The very high importance proportion remained higher than at the baseline (60%).
- 78% rated the UK becoming self-sufficient and not buying fuel from other countries as being of high importance (back up from 69% in Summer 2025), while 60% said this was of very high importance (up substantially from 49% in Summer 2025 and 51% in Summer 2024).
- 65% rated energy from cleaner sources as being of high importance (remaining below 71% in Summer 2024), while 38% said this was of very high importance (stable compared with Summer 2025, but below the 44% recorded in Summer 2024).
Figure 3.5: Importance of different aspects of energy policy (% based on all people), Summer 2024 to 2026
ENERG3A-D. Now thinking about energy. Summer 2024/2025: On a scale from 0 to 10, with 0 being the least important and 10 being the most important, please indicate how important each of these is to you personally… Summer 2026: On a scale from 0 to 10, with 0 being not at all important and 10 being extremely important, please indicate how important each of these is to you personally …
Note: change to wording of scale in 2026 may have affected comparability between Summer 2026 and previous waves.
Base: All wave respondents – Summer 2024 / Summer 2025 / Summer 2026: reliable energy supply (3,639/3,523/3,231), cost of energy (3,640/3,525/3,234), UK becoming self-sufficient (3,639/3,524/3,232), cleaner energy sources (3,638/3,520/3,230).
Analysis by subgroups
By age:
- Older people were more likely than younger people to assign a very high importance score (9 to 10) to the UK becoming self-sufficient: 73% of those aged 65 and over, compared with 32% of those aged under 25.
- People aged 25 and over were more likely than those aged under 25 to give a very high importance score to: the cost of energy (between 62% and 71% of those aged 25 and over compared with 35% of those aged under 25); and having a reliable, uninterrupted supply (between 75% and 88% compared with 48%).
By education:
- People with no qualifications (66%) and those with a non-degree qualification (67%) were more likely to assign a very high importance score to the cost of energy, compared with those with a degree (55%).
By geography:
- People living in Wales (71%) were most likely to assign a very high importance score to the cost of energy; this was lowest in London (55%).
- People in Wales were also more likely to assign a very high score to the UK becoming self-sufficient (68%) as were those in Yorkshire and the Humber (66%); this was lowest in London (51%).
- Those living in Yorkshire and the Humber were also most likely to assign a very high score to having a reliable, uninterrupted supply (82%), while this was lowest in the East Midlands (73%).
- Those in the East Midlands were most likely to assign a very high score to energy generated from cleaner sources (42%), while this was lowest in Scotland (32%).
By self-reported knowledge of net zero:
- People who said they knew a lot or a fair amount about net zero were more likely than those not aware of net zero to give a very high importance score to having a reliable, uninterrupted supply (81% vs 67%) and to the UK becoming self-sufficient (64% vs 52%).
Awareness of greenhouse gas removals
An annual question was introduced in Summer 2024 to assess awareness of greenhouse gas removals (GGRs)[footnote 8]. Before being asked about level of awareness, respondents were provided with a brief description of GGRs as follows:
Now some questions about greenhouse gas removals (GGRs). These are methods that remove greenhouse gases such as carbon dioxide from the atmosphere to help tackle climate change. The purpose of GGRs is to help achieve net zero in the UK by 2050, balancing out emissions from industries such as air travel and farming, where eliminating greenhouse gas emissions will be more challenging. Greenhouse Gas Removals (GGRs) can be based on natural approaches. However, they can also be based on engineered approaches. Engineered approaches use technology to remove greenhouse gases from the environment and store them permanently, for example offshore in underground storage sites.
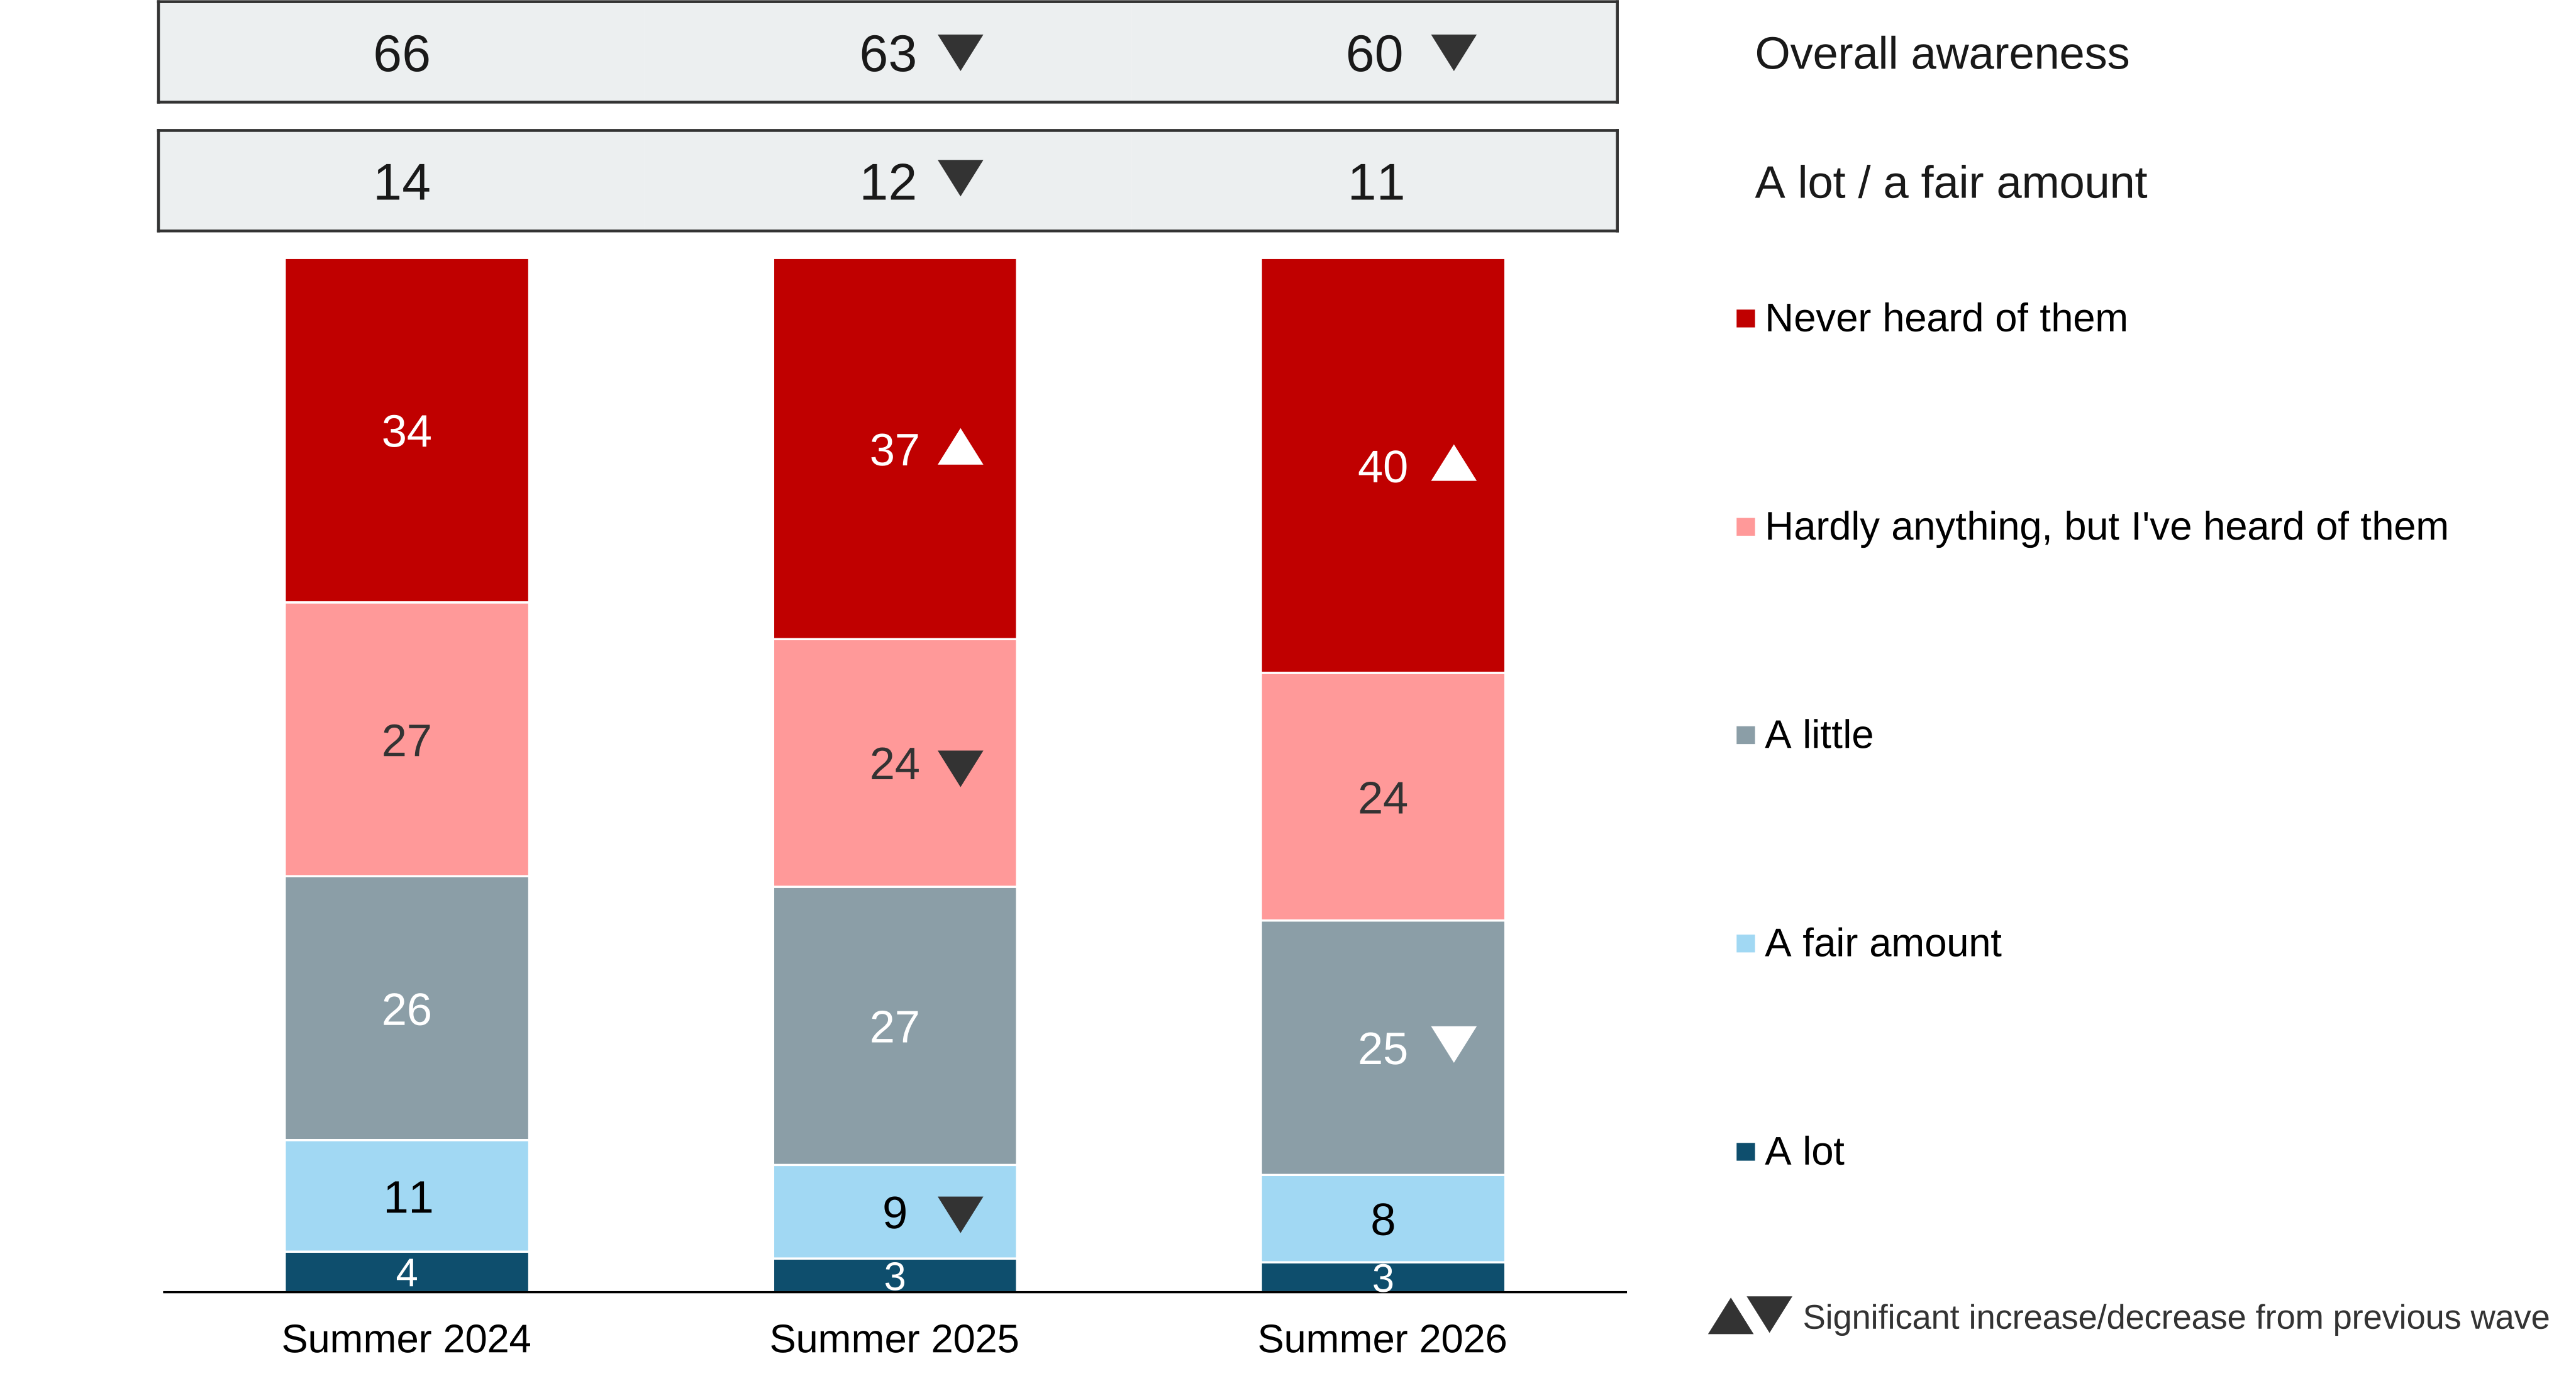
In Summer 2026, 60% said that they were aware of GGRs, down from 63% in Summer 2025 and 66% in Summer 2024 (Figure 3.6). Knowledge (a lot or a fair amount) was low and stable compared with Summer 2025 at 11%, but remained below the level recorded in Summer 2024 (14%).
Figure 3.6: Awareness of greenhouse gas removals (% based on all people), Summer 2024 to 2026
GGRKNOW. Before today, how much, if anything, did you know about engineered greenhouse gas removals (GGRs)?
Base: All wave respondents – Summer 2024 (3,642), Summer 2025 (3,519), Summer 2026 (3,234).
Analysis by subgroups
Self-reported awareness of GGRs was higher among:
- People in age groups 45 and over (between 63% and 64% compared with 53% of those in age groups from 25 to 44).
- People with a degree (66% compared with 53% of those with no qualifications). There was a similar pattern of difference for knowledge.
- People in Wales (73%), with this lowest in the East Midlands (49%). There was a similar pattern of regional difference for knowledge.
Further findings on energy infrastructure and energy security
In previous waves, questions were included on other topics relating to energy infrastructure and energy security. The latest findings relating to these topics can be found as follows:
- What information people would find most useful to know about during the planning stage, see Winter 2025 report on energy infrastructure and energy sources – section on ‘Awareness of new electricity network infrastructure’
- Levels of happiness with electricity network infrastructure being built in the local area and reasons for happiness and unhappiness, see Summer 2025 report on energy infrastructure – section on ‘Awareness and support for new electricity network infrastructure’
- Attitudes towards nuclear energy, see Winter 2025 report on energy infrastructure – section on ‘Nuclear Energy’
- Attitudes towards fusion energy, hydrogen, small modular reactors, carbon capture and storage, local nuclear power stations, and trust in information about emerging energy sources - see Spring 2026 report on ‘Energy infrastructure’
-
It should be noted that the tracking data is not wholly comparable due to a change in the question. The ‘don’t know’ answer code was removed from Winter 2024 onwards to be more consistent with other questions of this style. However, it was erroneously added back in Summer 2025. To ensure comparability with Winter 2024, Summer 2025 results were rebased on results excluding the 4% of people who answered ‘don’t know’. ↩
-
The last sentence of this explanation was added in Summer 2026 following cognitive testing. ↩
-
INFRAWHYSUPP: You said you would strongly support or support electricity network infrastructure to be built in your local area. Why is this? (Base size: 1,065) ↩
-
INFRAWHYNO: You said you would strongly oppose or oppose electricity transmission network infrastructure to be built in your local area. Why is this? (Base size: 674) ↩
-
An overview of domestic energy price changes can be found here: https://commonslibrary.parliament.uk/research-briefings/cbp-9714/ ↩
-
ENSECSOURCE: You said that you are very or fairly concerned about the UK being too dependent on energy from other countries. When you gave this answer, were you thinking about specific energy types? (Base size: 2,795) ↩
-
In Summer 2026 an example (‘e.g. renewable energy’) was added to the ‘energy generated from cleaner, low carbon sources’ option. ↩
-
To improve question ordering this question was moved to later in the questionnaire in Summer 2025, from before the ‘climate change’ section, to the ‘net zero’ section, after the existing net zero questions. ↩