UK Betting and Gaming Statistics commentary (August 2025 to July 2026)
Updated 30 September 2026
© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/statistics/uk-betting-and-gaming-statistics/uk-betting-and-gaming-statistics-commentary-october-2022-to-march-2023
Released: 30 September 2026. Next Release: September 2027.
1. Headlines
The latest headlines for the betting and gaming statistics are:
-
the provisional 2026 to 2027 financial year to date (April to July) total for betting and gaming receipts is £1,933 million, which is £309 million (19%) higher than the same period during the previous financial year
-
the majority of provisional 2026 to 2027 financial year to date (April to July) total betting and gaming receipts comes from Remote Gaming Duty (RGD)(50.0%) and General Betting Duty (GBD)(16.6%)
-
increases in total betting and gaming receipts are expected to reflect, in part, the increase in the Remote Gaming Duty rate from 21% to 40% from April 2026
2. About this release
This publication provides statistics for:
- Bingo Duty
- Gaming Duty
- General Betting Duty (GBD)
- Lottery Duty
- Machine Games Duty (MGD)
- Pool Betting Duty (PBD)
- Remote Gaming Duty
New information includes receipts data for all duties and MGD liabilities data from August 2025 to July 2026. Further details for each of the betting and gaming duties can be found within accompanying UK Betting and Gaming Statistics background and references and Historical UK Betting and Gaming duty rates.
MGD liabilities from April 2018 onwards are refreshed using the latest extract and may therefore be revised as late returns are received. Historical periods prior to April 2018 are not revised.
National Statistics are accredited official statistics.
3. Total betting and gaming receipts
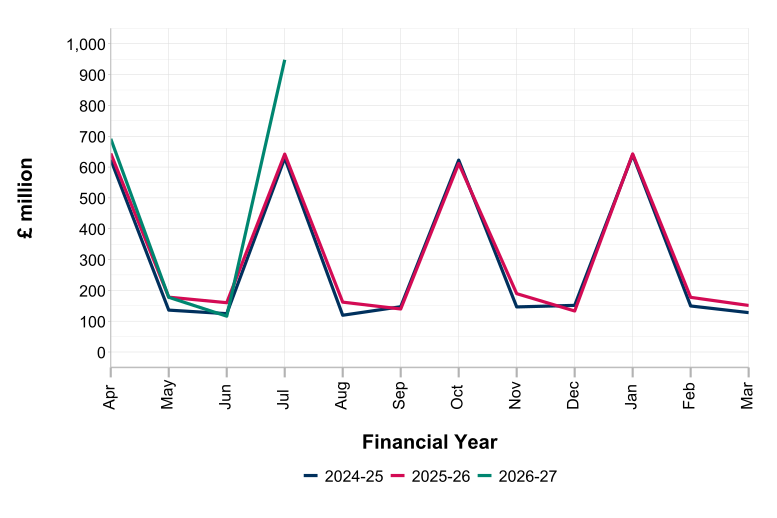
Figure 1: UK betting and gaming receipts in the current and previous 2 financial years.
For the full dataset relating to Figure 1 see the UK Betting and Gaming Statistics tables which accompany this commentary.
Significant points about Figure 1 and the related data concerning total betting and gaming receipts:
-
the provisional April to June total betting and gaming receipts in 2026 to 2027 were £985 million, which is £3 million (0.3%) higher than in the same period of the previous financial year
-
the increase in the Remote Gaming Duty rate from 21% to 40% from April 2026 is expected to have contributed to higher betting and gaming receipts from July 2026 onwards
4. Betting duties receipts
There are 2 betting duties: General Betting Duty (GBD) and Pool Betting Duty (PBD).
GBD is a duty charged on fixed-odds bets made with bookmakers in UK premises or remotely by UK persons, other than on-course betting.
PBD is charged on betting not at fixed-odds (for example, where winnings are determined by contributions made to a prize pool) in UK premises or by UK persons. Both are charged on money received for bets less money paid out for winnings.
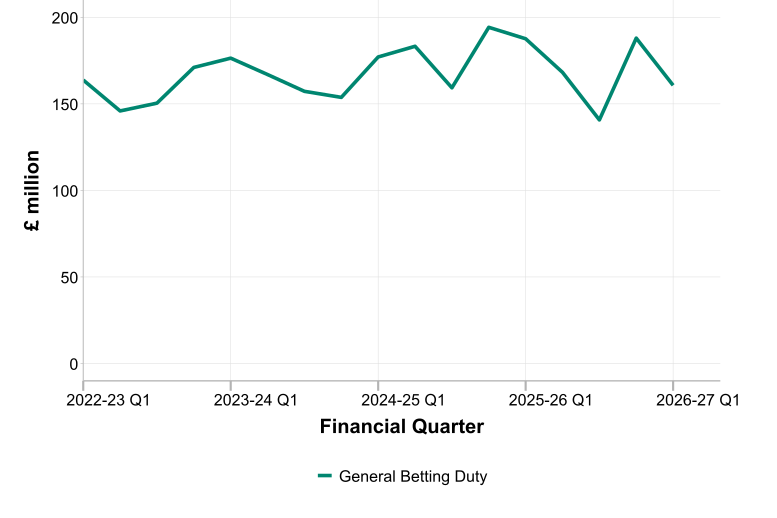
Figure 2: General Betting Duty receipts in the current and previous 4 financial years.
For the full dataset relating to Figure 2 see the UK Betting and Gaming Statistics tables which accompany this commentary.
Significant points about Figure 2 and the related data concerning GBD receipts:
-
the provisional April to June GBD receipts in 2026 to 2027 were £161 million, which is £27 million (14%) lower than in the same period of the previous financial year
-
total GBD receipts fluctuated across the period shown above. Receipts were £631 million in 2022 to 2023. They then increased by £23 million to £654 million in 2023 to 2024, increased by £60 million to £714 million in 2024 to 2025, and decreased by £29 million to £685 million in 2025 to 2026
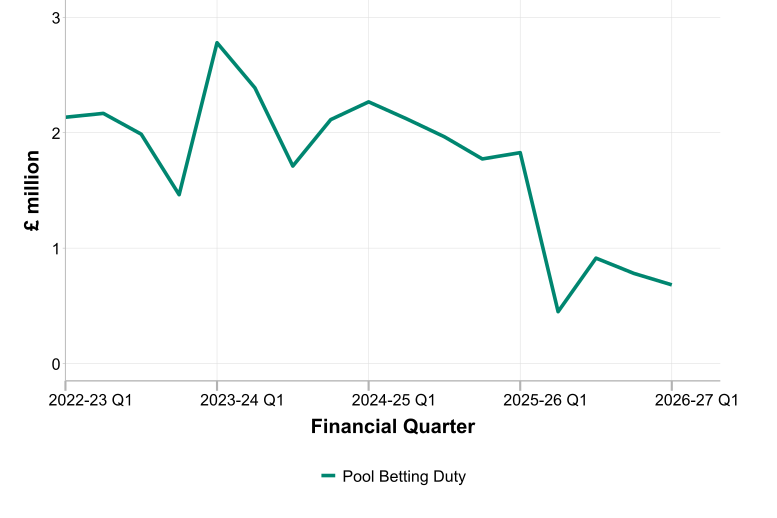
Figure 3: Pool Betting Duty receipts in the current and previous 4 financial years.
For the full dataset relating to Figure 3 see the UK Betting and Gaming Statistics tables which accompany this commentary.
Significant points about Figure 3 and the related data concerning PBD receipts:
-
the low overall level of PBD receipts means that small changes look large in percentage terms
-
the provisional April to June PBD receipts in 2026 to 2027 were £0.7 million, which is £1.1 million (61%) lower than in the same period of the previous financial year
-
total PBD receipts fluctuated across the period shown above. In 2022 to 2023, total PBD receipts were £7.8 million. Total PBD receipts then increased to £9 million in 2023 to 2024, before they decreased to £8.1 million in 2024 to 2025. Within the 2025 to 2026 financial year, PBD receipts decreased further to £4 million
5. Lottery Duty receipts
Introduced in November 1994, Lottery Duty is a duty on taking a chance or ticket in a lottery that is promoted in the UK. It is paid by the promoter of the National Lottery. All other lawful lotteries are exempt.
The duty applies to lottery tickets and scratch-cards. Duty payable is based on stake money received from ticket sales. The duty rate of 12% has remained the same since its introduction in 1994.
Lottery Duty follows monthly accounting, meaning that periods can be 4 or 5 weeks while payment is due within 15 days after accounting periods.
Figure 4: Lottery Duty receipts in the current and previous 4 financial years.
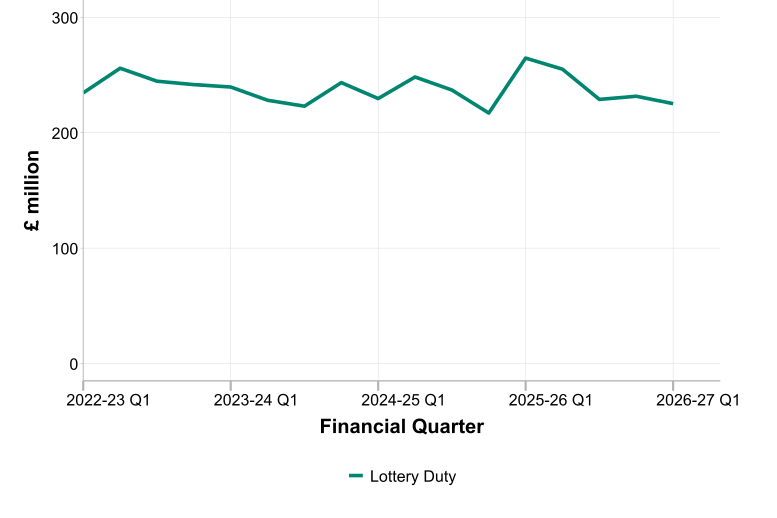
For the full dataset relating to Figure 4 see the UK Betting and Gaming Statistics tables which accompany this commentary.
Significant points about Figure 4 and the related data concerning Lottery Duty receipts:
-
the provisional April to June Lottery receipts in 2026 to 2027 were £225 million, which is £39 million (15%) lower than in the same period of the previous financial year
-
Lottery Duty receipts fluctuated across the period shown above. In 2022 to 2023, Lottery Duty receipts were £976.7 million. Lottery Duty receipts then decreased to £934.1 million in 2023 to 2024, before they decreased to £931.9 million in 2024 to 2025. Within the 2025 to 2026 financial year, Lottery Duty receipts increased further to £980.1 million
6. Gaming duties receipts
There are 4 duties on gaming.
-
Remote Gaming Duty (RGD) which is charged on gaming providers’ profits from remote gaming with UK persons, remote gaming is defined as the playing of a game-of-chance for a prize by remote communication via any kind of electronic or other technology for facilitating communication
-
the rate of RGD increased from 21% to 40% from April 2026
-
Machine Gaming Duty (MGD) which is a duty of excise which is charged on ‘dutiable machine games’ played in the UK. A machine game is a game, whether of chance or skill, or both, played on a machine for a prize where at least one of the prizes that can be won is, or includes, cash to a value greater than the cost to play once
-
Gaming Duty which is charged on premises (casinos), where ‘dutiable gaming’ takes place, such as roulette, poker and blackjack.
-
Bingo Duty which is charged on the profits of bingo promoters’ from bingo played in the UK. Bingo Duty was abolished from April 2026.
The standard accounting period for RGD and MGD is quarterly, with accounting periods set up on one of 3 ‘staggers’ in which payment is due within 1 month.
Figure 5: Gaming duties receipts in the current and previous 4 financial years.
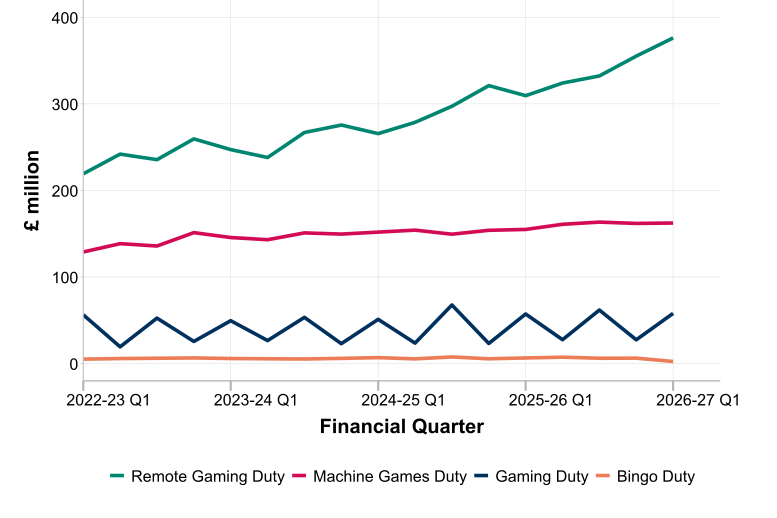
For the full dataset relating to Figure 5 see the UK Betting and Gaming Statistics tables which accompany this commentary.
Significant points about Figure 5 and the related data concerning the 4 gaming duties’ receipts:
-
RGD is the largest of the 4 gaming duties
-
the provisional April to June Remote Gaming Duty receipts in 2026 to 2027 were £376 million, which is £67 million (22%) higher than in the same period of the previous financial year
-
the provisional April to June Machine Games Duty receipts in 2026 to 2027 were £162 million, which is £7 million (5%) higher than in the same period of the previous financial year
-
the provisional April to June Gaming Duty receipts in 2026 to 2027 were £58 million, which is £1 million (2%) higher than in the same period of the previous financial year
-
the provisional April to June Bingo Duty receipts in 2026 to 2027 were £2 million, which is £4 million (67%) lower than in the same period of the previous financial year
7. Machine Games Duty liability breakdown
7.1 MGD rates
There are 3 rates of MGD:
- Lower rate of 5% applies to ‘Type 1’ machines
- Standard rate of 20% applies to ‘Type 2’ machines
- Higher rate of 25% applies to all other machines
Go to HMRC Excise Notice 452: Machine Games Duty for further MGD information.
7.2 Machine Games Duty declared liabilities
MGD is payable to HMRC in the month following the end of an accounting period. This results in a one month lag between the end of the accounting period and cash being received meaning the latest available complete data for MGD liabilities is one month behind that of receipts. MGD receipts and liabilities data has been updated to July 2026 within this release.
MGD liabilities from April 2018 onwards are refreshed using the latest extract and may therefore be revised as late returns are received. Historical periods prior to April 2018 are not revised.
7.3 Year to date liabilities
Current year-to-date total liabilities and standard rate liabilities for MGD are as follows:
-
the provisional 2026 to 2027 year-to-date (April to July) total for declared MGD liabilities is £203 million, which is £7 million (3%) higher than the same period during the previous financial year-to-date
-
the provisional 2026 to 2027 year-to-date (April to July) standard rate MGD liabilities is £201 million, which is £7 million (4%) higher than the same period during the previous financial year-to-date
Figure 6: MGD liabilities by duty rate in the current and previous 4 financial years.
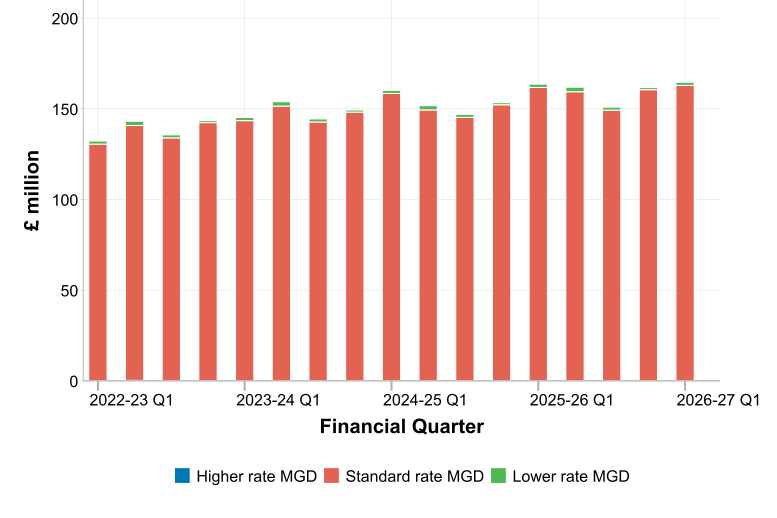
For the full dataset relating to Figure 6 see the UK Betting and Gaming Statistics tables which accompany this commentary.
Significant points about Figure 6 and the related data concerning MGD liabilities:
-
the provisional 2026 to 2027 financial year has seen a continuation of the general trend, whereby overall MGD liabilities have generally increased over the period shown above.
-
in the financial year 2019 to 2020, standard rate became the largest contributor to MGD liabilities. This was due to policy changes from April 2019 which reduced maximum stakes for fixed-odds betting terminals (FOBTs)
-
higher rate liabilities have decreased in recent years since the FOBTs policy changes. The last quarter in which they contributed significantly was the first quarter of 2019 to 2020, where the liabilities were £30 million
8. Contacts
The UK Betting and Gaming Statistics publication is produced by the Indirect Tax Receipts Monitoring team as part of the Excise duties, VAT, and other tax statistics collection.
For statistical enquiries, contact:
For media enquiries, see HMRC press office.