Council Tax: challenges and changes statistical summary
Published 29 October 2026
Applies to England and Wales

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/statistics/council-tax-challenges-and-changes-in-england-and-wales-march-2025/council-tax-challenges-and-changes-statistical-summary
About this release:
This release includes statistics on challenges against and changes made to the England and Wales Council Tax valuation lists between 1 April 2024 and 31 March 2025.
Following the implementation of the Valuation Operating System (VOS) for Council Tax in 2025, the data source used for this publication has changed. As a result, this release contains summary statistics for the 2024 to 2025 financial year only and does not include time series tables. Statistics on amendments to council tax lists are not available in this release. Information on amendments, insertions and deletions to council tax lists will be published separately at a later date.
The new data feed continues to undergo assurance and quality assessment for use in the production of official statistics, while improvements to the underlying source data are being made. Consequently, the statistics presented in this release should be regarded as provisional until the data feed and associated processes have stabilised.
Responsible statistician
Anna McReady
Statistical enquiries
Date of next publication
Summer 2027
1. Headline facts and figures – 1 April 2024 to 31 March 2025
Across the Council Tax valuation lists for England (1993) and Wales (2005):
-
The number of challenges received in 2024 to 2025 was 47,030, up from 43,820 in 2023 to 2024
-
The number of challenges resolved in 2024 to 2025 was 38,180, down from 39,590 in 2023 to 2024
-
The number of outstanding challenges as at 31 March 2025 was 22,330, up from 14,160 as at 31 March 2024
-
The percentage of challenges resulting in no change to the Council Tax band in 2024 to 2025 was 62%, down from 65% in 2023 to 2024
The number of challenges received has increased since 2024. This is primarily associated with an increase in proposals to delete entries from the Council Tax list. During this period, a process change resulted in a greater proportion of deletion requests being submitted directly to the Valuation Office as proposals.
There was also a slight delay in processing some challenges at the end of the 24-25 financial year due to the introduction of the new Valuation Operating System. As challenges are counted using the date they are registered (in line with previous versions of this publication), and some challenges were not registered until after April 2025, these are counted within the 2025-2026 figures rather than 2024-2025. As a result, this increases the overall number received in 2025-2026.
2. About these statistics
The statistics in this publication relate to England and Wales only. The Valuation Office (VO) does not carry out Council Tax valuations in Scotland and Northern Ireland, where the valuation law and practice differ from England and Wales.
The statistics are available at national, regional, and billing authority level.
This publication is released to bring greater transparency to VO functions. The data are also used to inform government policy and conduct analyses to support the operations of the VO.
3. Challenges against the Council Tax valuation lists for England (1993)
Prior to 1 April 2008 in England, challenges consist of informal challenges (previously band reviews) and appeals. From 1 April 2008 in England, challenges consist of informal challenges, proposals and, of these proposals, the number sent to the Valuation Tribunal Service for appeal, referred to as appeals.
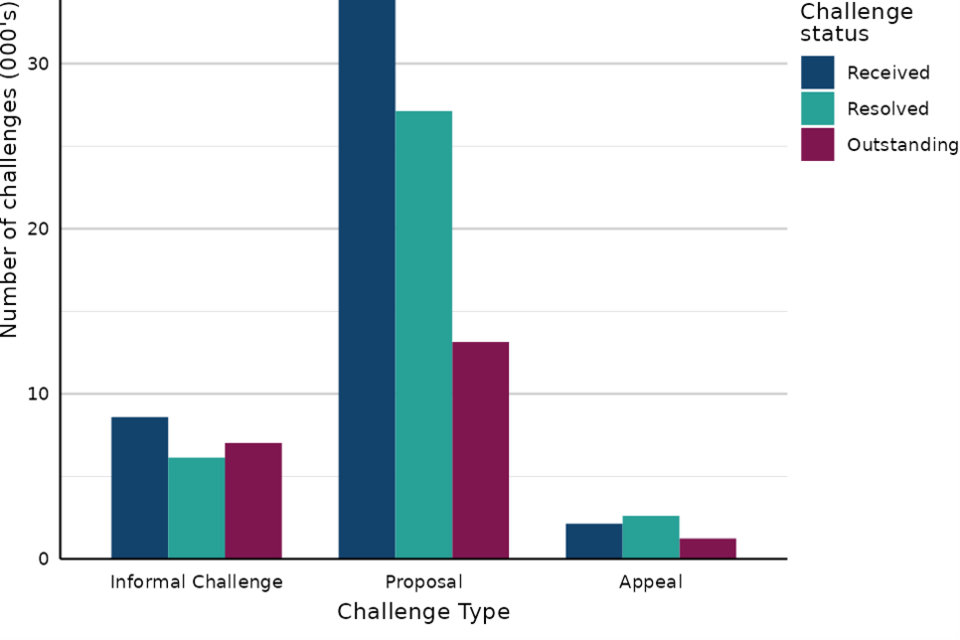
Figure 1: Number of challenges received, resolved and outstanding in England, 1 April 2024 to 31 March 2025
Source: Tables CTCAC1.2 to CTCAC1.4
Figure 1 shows that of the 44,570 challenges received by the Valuation Office in England in 2024 to 2025, there were:
-
33,850 (76%) proposals
-
8,590 (19%) informal challenges
-
2,130 (5%) appeals.
Of the 35,870 challenges resolved by the Valuation Office in England in 2024 to 2025, there were:
-
27,120 (76%) proposals
-
6,140 (17%) informal challenges
-
2,610 (7%) appeals.
Of the resolved challenges in England:
-
63% resulted in no change to the Council Tax band
-
16% resulted in a reduction to the Council Tax band
-
less than 1% resulted in an increase to the Council Tax band
-
17% resulted in a property being deleted from the Council Tax list
-
1% resulted in a new entry to the list
-
2% resulted in either a property being split or multiple properties being merged.
Of the 21,400 challenges outstanding in England at 31 March 2025, there were:
-
7,020 (33%) informal challenges
-
13,140 (61%) proposals
-
1,240 (6%) appeals.
3.1 Informal Challenges (previously band reviews) against the Council Tax valuation lists for England (1993)
An informal challenge is carried out when the taxpayer brings a potential inaccuracy to the attention of the VO. The taxpayer must provide sufficient evidence to the VO to show why they consider their Council Tax band to be incorrect. The VO will investigate the matter and inform the taxpayer of the outcome. The taxpayer does not have the right to appeal the outcome of an informal challenge.
3.1.1 Outcomes of informal challenges in England
Informal challenges can either result in a Council Tax band increase, a Council Tax band decrease or no change to the Council Tax band.
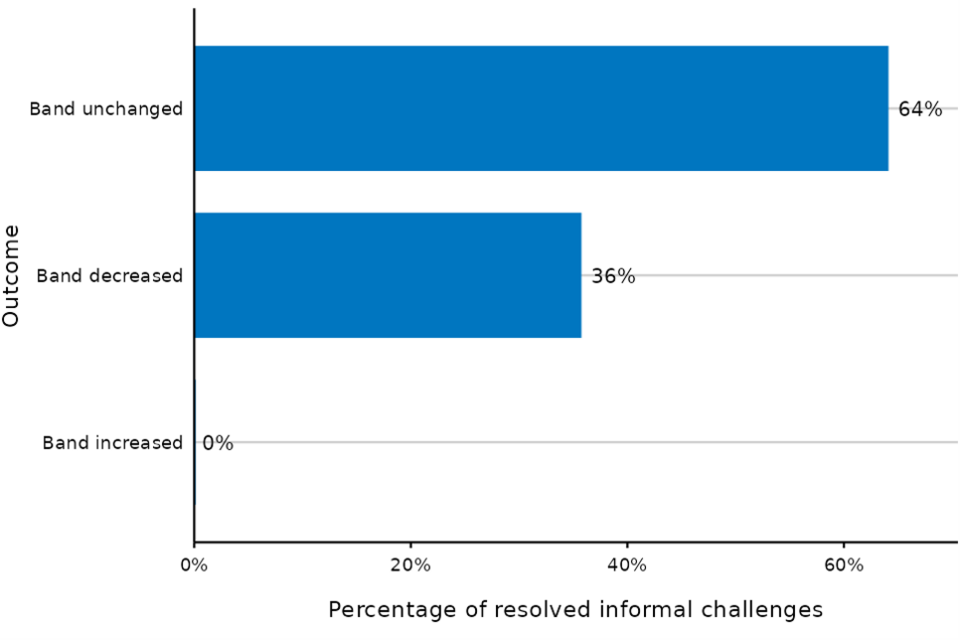
Figure 2: Outcomes of informal challenges resolved in England, 1 April 2024 to 31 March 2025
Source: Table CTCAC1.2
Between 1 April 2024 and 31 March 2025:
-
3,930 (64%) resolved informal challenges resulted in no change to the Council Tax Band
-
2,190 (36%) resolved informal challenges resulted in a reduction to the band
-
10 (less than 1%) resolved informal challenges resulted in an increase to the band.
3.2 Proposals in England
A proposal is a formal challenge to a Council Tax list entry. There are limited circumstances under which a proposal can be accepted; the main route is that of a new occupier making a proposal within the first six months of becoming the taxpayer for their home. If the taxpayer has a statutory right to make a proposal, they do not need to provide evidence upfront that the banding is wrong unlike informal challenges.
In England since 1 April 2008, the VO will review the proposal and provide the taxpayer with a written decision, usually within two months. The taxpayer then has up to three months to appeal to a Valuation Tribunal.
3.2.1 Outcomes of proposals in England
Proposals can result in a Council Tax band increase, a Council Tax band decrease, no change to the Council Tax band, a new entry to the Council Tax list, a deleted entry from the list or a property on the list being either split or merged.
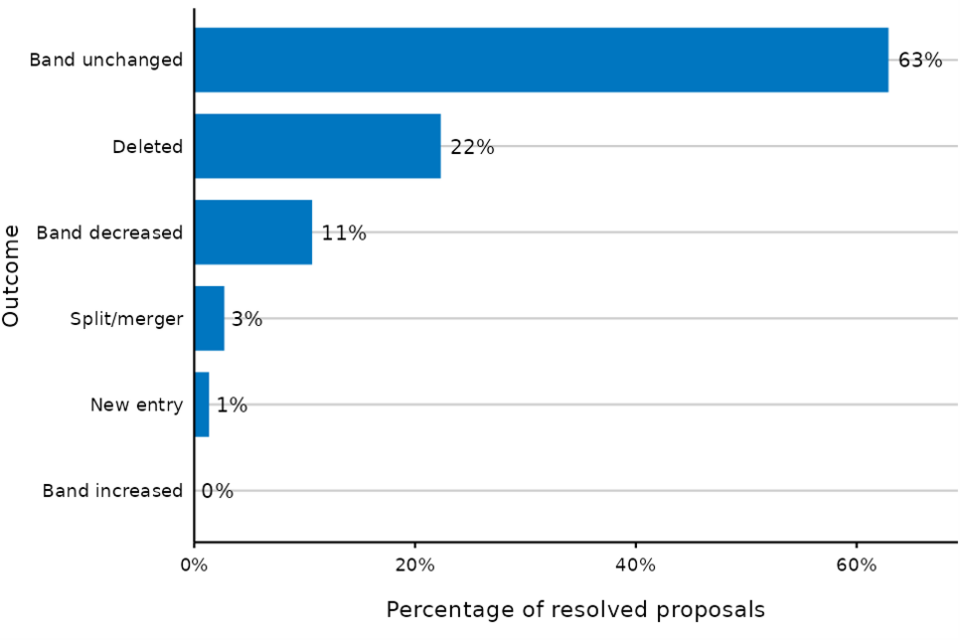
Figure 3: Outcomes of proposals resolved in England, 1 April 2024 to 31 March 2025
Source: Table CTCAC1.3
Between 1 April 2024 and 31 March 2025:
-
17,060 (63%) resolved proposals resulted in no change to the Council Tax Band
-
2,900 (11%) resolved proposals resulted in a reduction to the band
-
10 (less than 1%) resolved proposals resulted in an increase to the band
-
6,060 (22%) resolved proposals resulted in a property deletion
-
740 (3%) resolved proposals resulted in a split or merger
-
370 (1%) resolved proposals resulted in a property insertion
3.3. Appeals in England
In England from 1 April 2008, the VO will review a proposal and provide the taxpayer with a written decision, usually within two months. The taxpayer then has up to three months to appeal this decision to an independent Valuation Tribunal.
In previous releases, time series tables for appeals showed the number of resolved proposals that were subsequently appealed. As this release only includes statistics for the 2024-25 financial year, appeal statistics are based on the number of appeals received (Table CTCAC1.4) or resolved (Tables CTCAC1.5 and CTCAC1.6) within the financial year.
3.3.1 Outcomes of appeals in England
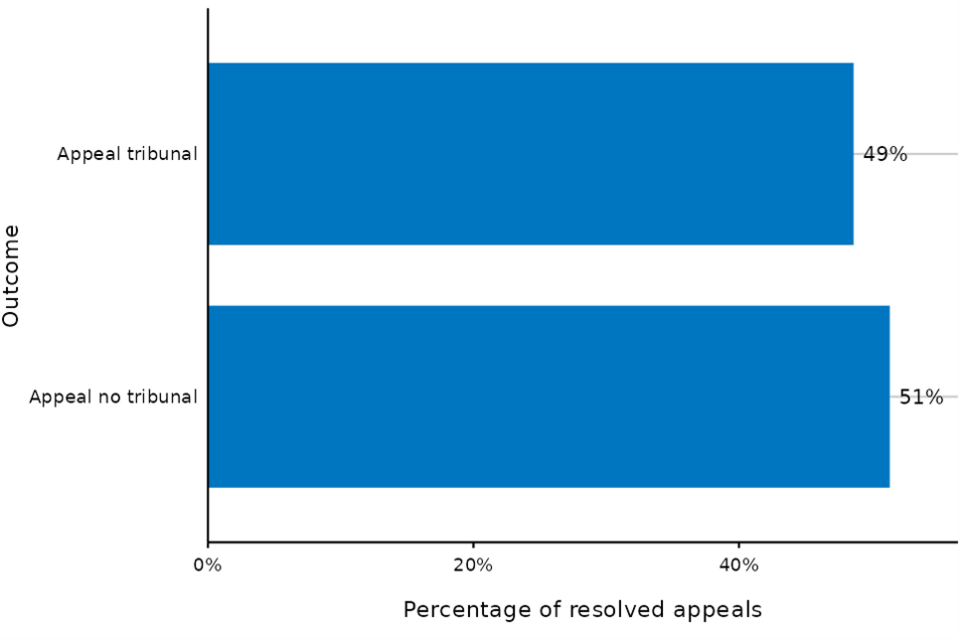
Appeals are often withdrawn or settled before reaching the Valuation Tribunal.
Figure 4: Percentage of appeals resolved without a Valuation Tribunal and resolved at Valuation Tribunal in England, 1 April 2024 to 31 March 2025
Source: Table CTCAC1.5 and CTCAC1.6
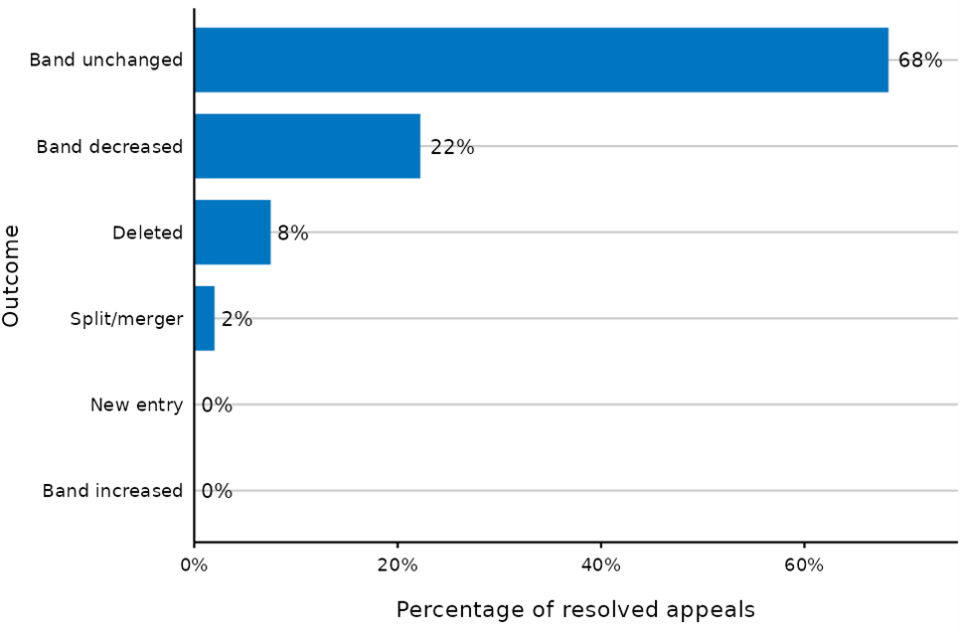
Appeals, like proposals, can result in a Council Tax band increase, a Council Tax band decrease, no change to the Council Tax band, a new entry to the Council Tax list, a deleted entry from the list, or a property on the list being either split or merged.
Figure 5: Outcomes of resolved appeals in England, 1 April 2024 to 31 March 2025
Source: Table CTCAC1.4
Between 1 April 2024 and 31 March 2025:
-
1,780 (68%) resolved appeals resulted in no change to the Council Tax Band
-
580 (22%) resolved appeals resulted in a reduction to the band
-
0 (0%) resolved appeals resulted in an increase to the band
-
200 (8%) resolved appeals resulted in a property deletion
-
50 (2%) resolved appeals resulted in split or merger
-
0 (0%) resolved appeals resulted in a property insertion
4. Challenges against the Council Tax valuation lists for Wales (2005)
Challenges in Wales before 1 February 2026 consist of informal challenges and appeals. Prior to 1 February 2026, all proposals received in Wales, if unresolved, were automatically transmitted as appeals to Valuation Tribunal Service (VTS) within 30 days of receiving them. From 1 February 2026, Wales followed the same system as England, where challenges consist of informal challenges, proposals, and appeals.
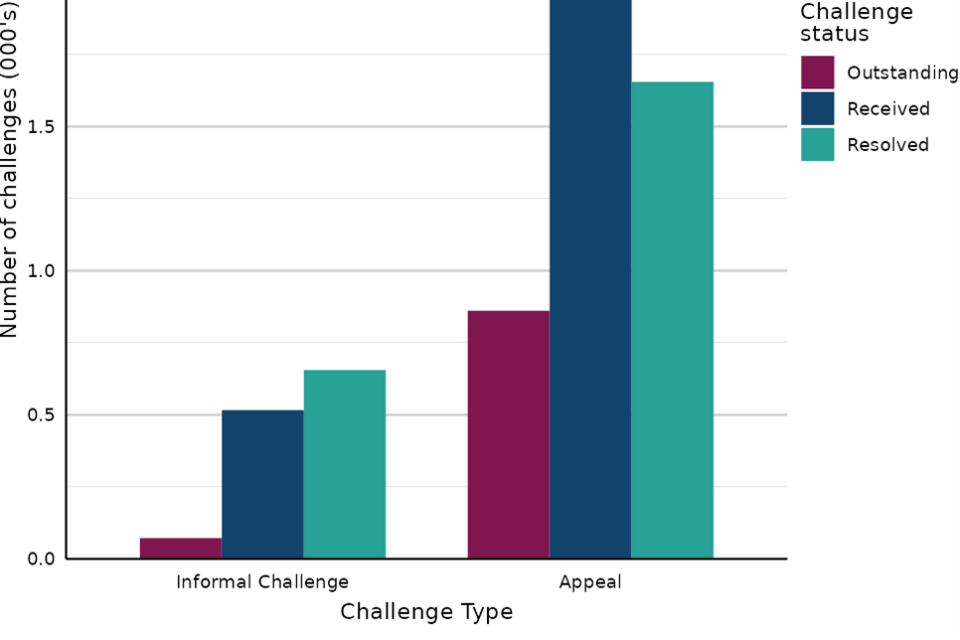
Figure 6: Number of challenges received, resolved and outstanding in Wales, 1 April 2024 to 31 March 2025
Source: Tables CTCAC1.2 to CTCAC1.4
Figure 6 shows that of the 2,460 challenges received by the Valuation Office in Wales in 2024 to 2025, there were:
- 520 (21%) informal challenges
- 1,940 (79%) appeals.
Of the 2,310 challenges resolved by the Valuation Office in Wales in 2024 to 2025, there were:
- 660 (28%) informal challenges
- 1,660 (72%) appeals.
Of the resolved challenges:
- 47% resulted in no change to the Council Tax band
- 22% resulted in a reduction to the Council Tax band
- less than 1% resulted in an increase to the Council Tax band
- 27% resulted in a property being deleted from the Council Tax list
- less than 1% resulted in a new entry to the list
- 3% resulted in either a property being split or multiple properties being merged.
Of the 930 challenges outstanding in Wales at 31 March 2025, there were:
-
70 (8%) informal challenges
-
860 (92%) appeals.
4.1 Informal challenges in Wales
Informal challenges follow the same process in Wales as in England.
4.1.1 Outcomes of informal challenges in Wales
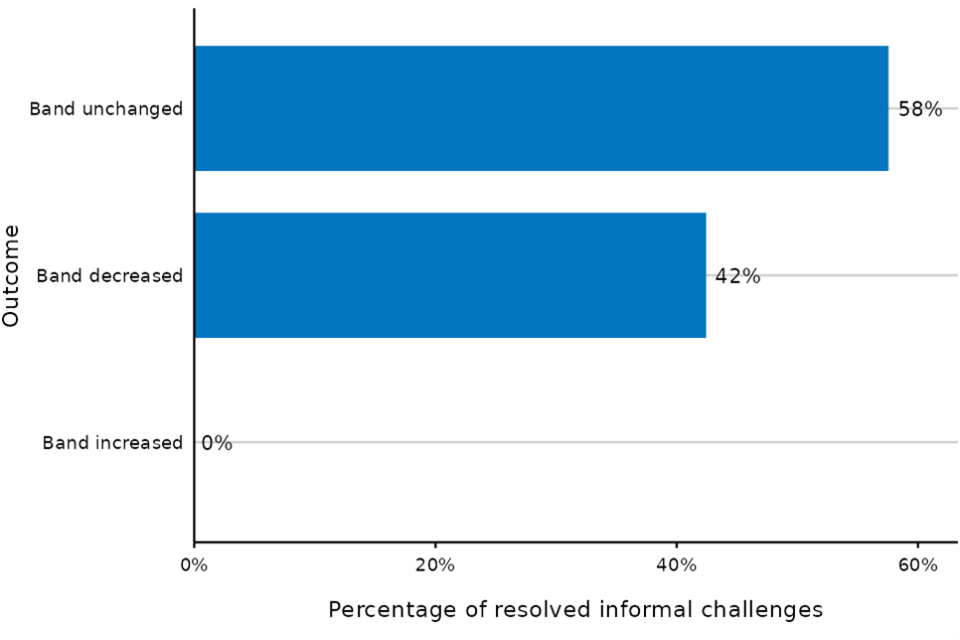
Informal challenges can result in a Council Tax band increase, a Council Tax band decrease or no change to the Council Tax band.
Figure 7: Outcomes of informal challenges resolved in Wales, 1 April 2024 to 31 March 2025
Source: Table CTCAC1.2
Between 1 April 2024 and 31 March 2025:
-
380 (58%) resolved informal challenges resulted in no change to the Council Tax Band
-
280 (42%) resolved informal challenges resulted in a reduction to the band
-
0 resolved informal challenges resulted in an increase to the band.
4.2 Appeals in Wales
In Wales, unresolved proposals are automatically transmitted to appeal after 30 days.
4.2.1 Outcomes of appeals in Wales
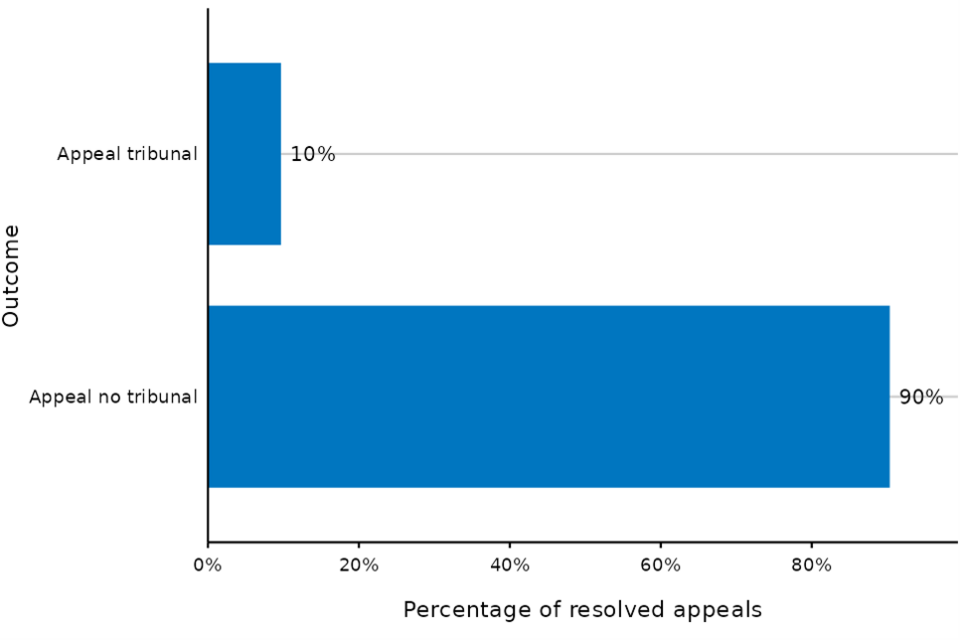
Appeals are often withdrawn or settled before reaching the Valuation Tribunal.
Figure 8: Percentage of appeals resolved without a Valuation Tribunal and resolved at Valuation Tribunal in Wales, 1 April 2024 to 31 March 2025
Source: Tables CTCAC1.5 and CTCAC1.6
Appeals can result in a Council Tax band increase, a Council Tax band decrease, no change to the Council Tax band, a new entry to the Council Tax list, a deleted entry from the list, or a property on the list being either split or merged.
Figure 9: Outcomes of resolved appeals in Wales, 1 April 2024 to 31 March 2025
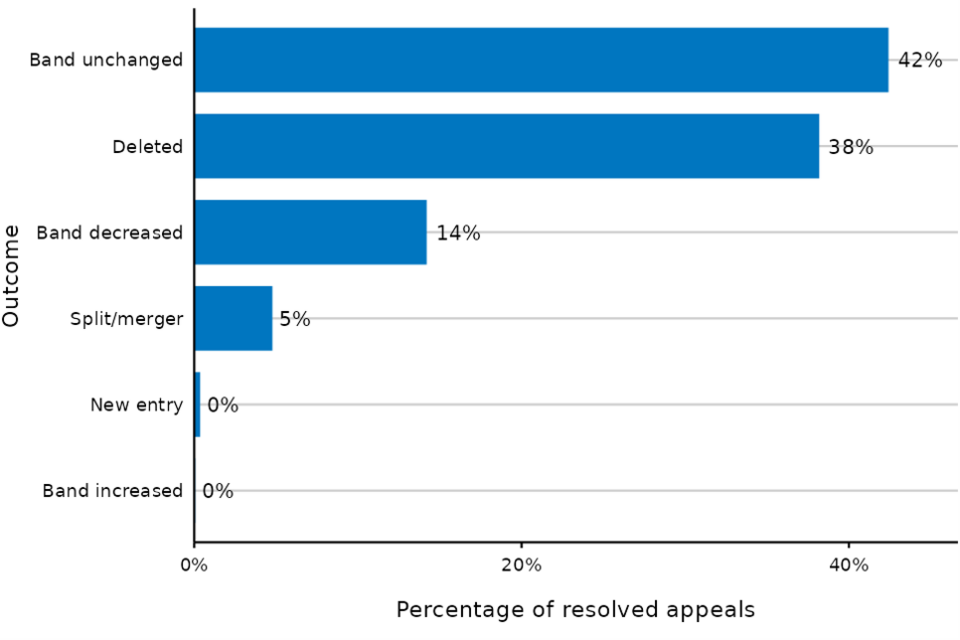
Source: Table CTCAC1.4
Between 1 April 2024 and 31 March 2025:
-
700 (42%) resolved appeals resulted in no change to the Council Tax Band
-
240 (14%) resolved appeals resulted in a reduction to the band
-
fewer than 5 resolved appeals resulted in an increase to the band
-
630 (38%) resolved appeals resulted in a property deletion
-
80 (5%) resolved appeals resulted in a split or merger
-
10 (0%) resolved appeals resulted in a property insertion
Further information
Further information about the data and methodology presented in this summary can be found in the Background information.
GOV.UK has more information on:
Timings of future releases are regularly placed on the HMRC research and statistics calendar.