Energy use on farms in England 2024/25
Updated 3 September 2026
Applies to England

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/statistics/energy-use-on-farms-in-england/energy-use-on-farms-in-england-202324
This release provides details on the types of fuel used by farm businesses, and the generation and sale of renewable energy, including plans for the future. It also contains details on farm carbon audits, the most commonly used carbon calculators and the actions farms have taken based on their carbon audits.
Revisions to 2023/24 data
A data error was discovered in the red diesel use dataset of the 2023/24 Energy use on farms publication. This inflated values for red diesel used by contractors; dairy farms were the most affected. The underlying data has now been corrected and the 2023/24 figures revised in this publication and the accompanying dataset.
Official statistics in development
The survey module used to collect the data for this publication is still under development, with improvements planned for the collection process and data validation. This publication is therefore categorised as official statistics in development. For more information, see Section 5.2.
Points which apply throughout
- The Farm Business Survey (FBS) is the source for all data presented in tables and charts unless otherwise stated.
- All figures relate to England, unless otherwise stated, and cover a March to February fiscal year, with the most recent year shown ending in February 2025. Fiscal years are shown in YYYY/YY format, for example, the period of 1 March 2024 to 28 February 2025 is shown as 2024/25. To ensure consistency in harvest/crop year and commonality of subsidies within any one Farm Business Survey year, only farm businesses which have accounting years ending between 31 December and 30 April are included in the survey. Aggregate results are presented in terms of an accounting year ending on the last day of February, which is the approximate average of all farms in the Farm Business Survey.
- Numbers of farms and red diesel quantities are rounded to the nearest 100. Percentages have been calculated on unrounded data and are rounded to the nearest 1%.
- Due to the small sample sizes, pig and poultry farms have been combined into one farm type.
- The acronym ‘LFA’ refers to Less Favoured Area. These areas were established in 1975 to provide support to mountainous and hill farming areas. They are areas where the natural characteristics (geology, altitude, climate, short growing season, low soil fertility, or remoteness) make it difficult for farmers to compete.
- The Farm Business Survey only includes farm businesses with a Standard Output of at least £21 thousand. These results refer only to these commercial farm businesses. Further details can be found in Section 6.2 Survey coverage and weighting.
- Where dataset tables are referred to in the text, this refers to the dataset files, which can be found on the publication landing page.
1. Key results
-
In 2024/25, the most common fuel was red diesel, which was used by 98% of commercial farm businesses.
-
On average, a farm used around 13,000 litres of red diesel in 2024/25, compared to 11,500 litres in 2023/24. Usage rates increased with farm size (based on Standard Labour Requirement).
-
In 2024/25, 33% of farms generated some form of renewable energy, solar power was the most popular option
-
89% of the farms generating solar power in 2024/25 had solar panels installed on farm building rooftops and 6% had solar panels installed in fields.
-
76% of farms generating solar energy did so to reduce the cost of their energy bills.
-
By 2024/25, 19% of farms had carried out a carbon audit, with dairy farms having the highest uptake, at 54% of farms.
2. Fuel and energy use
Farm businesses use a wide variety of energy and fuel types in their activities. A detailed explanation of each fuel type can be found in the definitions section of this publication.
2.1 Fuel usage by type of fuel
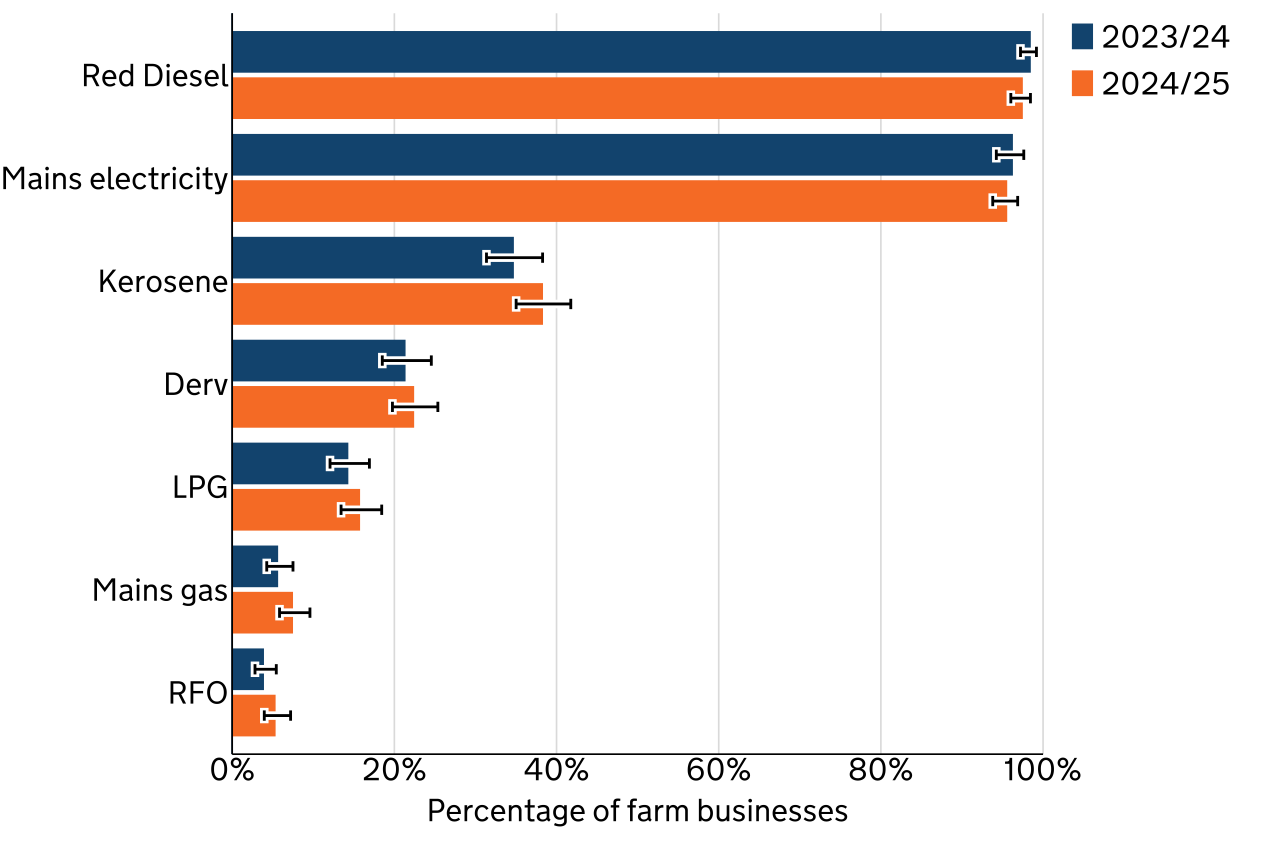
Figure 2.1: Fuel usage by type of fuel on farms in England, 2023/24 and 2024/25
Source: Dataset tables 1.3, 1.8, 1.13, 1.15 and 1.16
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Some fuel types have been abbreviated: Derv refers to diesel engine road vehicle, also known as white diesel; LPG refers to liquefied petroleum gas; RFO refers to residual fuel oil.
Figure 2.1 shows that red diesel (used mainly in tractors, other farm vehicles and for heating) was the most commonly used fuel type in 2023/24 and 2024/25, with 98% of farms using it in each year. This was followed closely by mains electricity at 96%. In contrast, residual fuel oil (RFO), which is mostly used in older heating systems, was the least used fuel in both years, at only 4% and 5% of farms respectively.
2.2 Red diesel usage
A data error was discovered in the red diesel use dataset of the 2023/24 Energy use on farms publication. This inflated values for red diesel used by contractors; dairy farms were the most affected. The underlying data has now been corrected and the 2023/24 figures revised in this publication and the accompanying dataset.
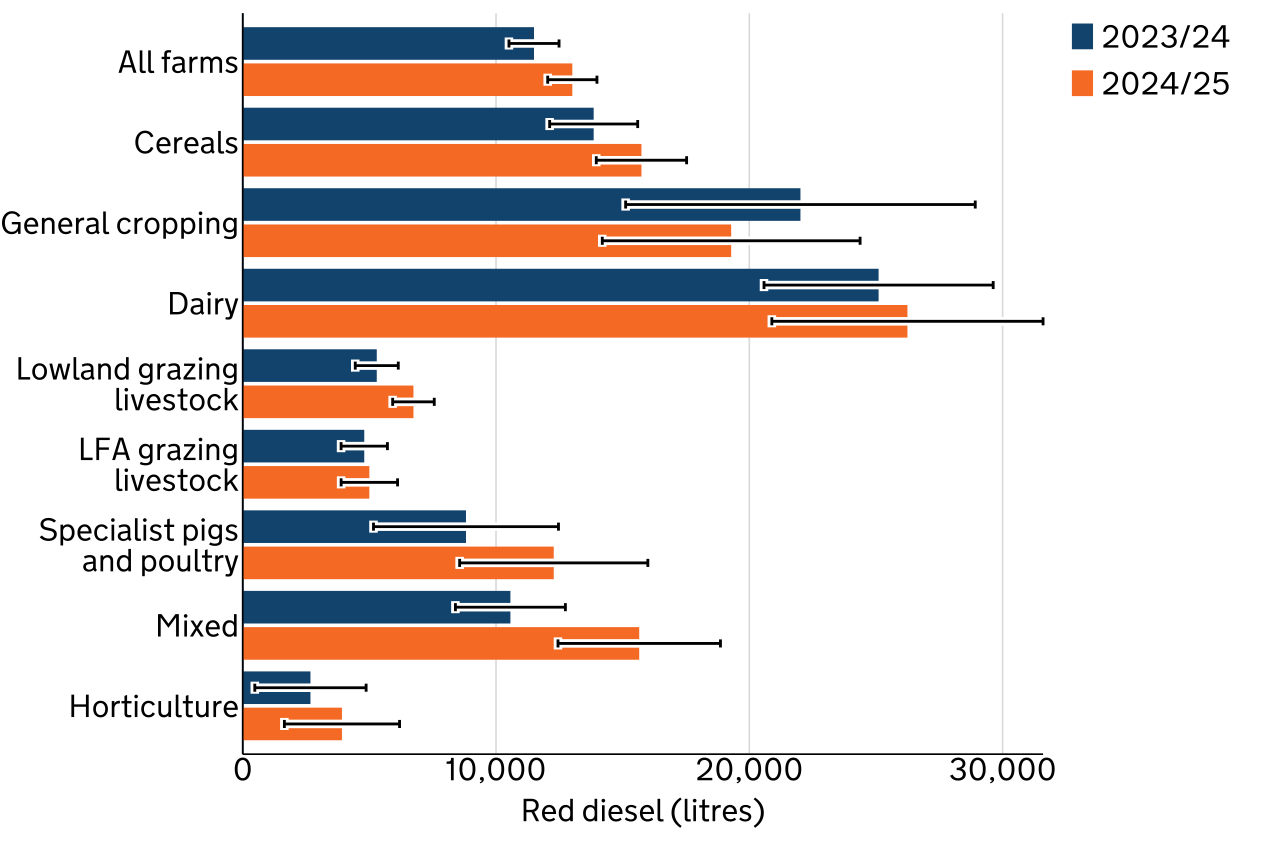
Figure 2.2: Average (mean) red diesel used by farm type on farms (including by contractors) in England, 2023/24 and 2024/25
Source: Dataset table 1.5
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
Figure 2.2 shows that, on average, farms used 13,000 litres of red diesel in 2024/25, compared to 11,500 litres in 2023/24. This included fuel used by contractors.
Dairy and general cropping farms were highest consumers of red diesel in both years, with dairy farms using 26,200 litres in 2024/25 and general cropping farms 19,300 litres. Dairy farming is dominated by large and very large farms that generally employ relatively intensive production systems. These farms make extensive use of heavy diesel-powered machinery on a daily basis for tasks including slurry handling and bedding management. Many dairy farms also produce their own fodder crops and may grow additional arable crops, further increasing machinery requirements. Likewise, general cropping farms are primarily focused on arable production, a sector characterised by high machinery use. Key stages of crop production, for example, ploughing, fertiliser application and harvesting, all rely heavily on diesel-powered machinery.
In contrast, horticulture farms were the lowest consumers of red diesel in both years.
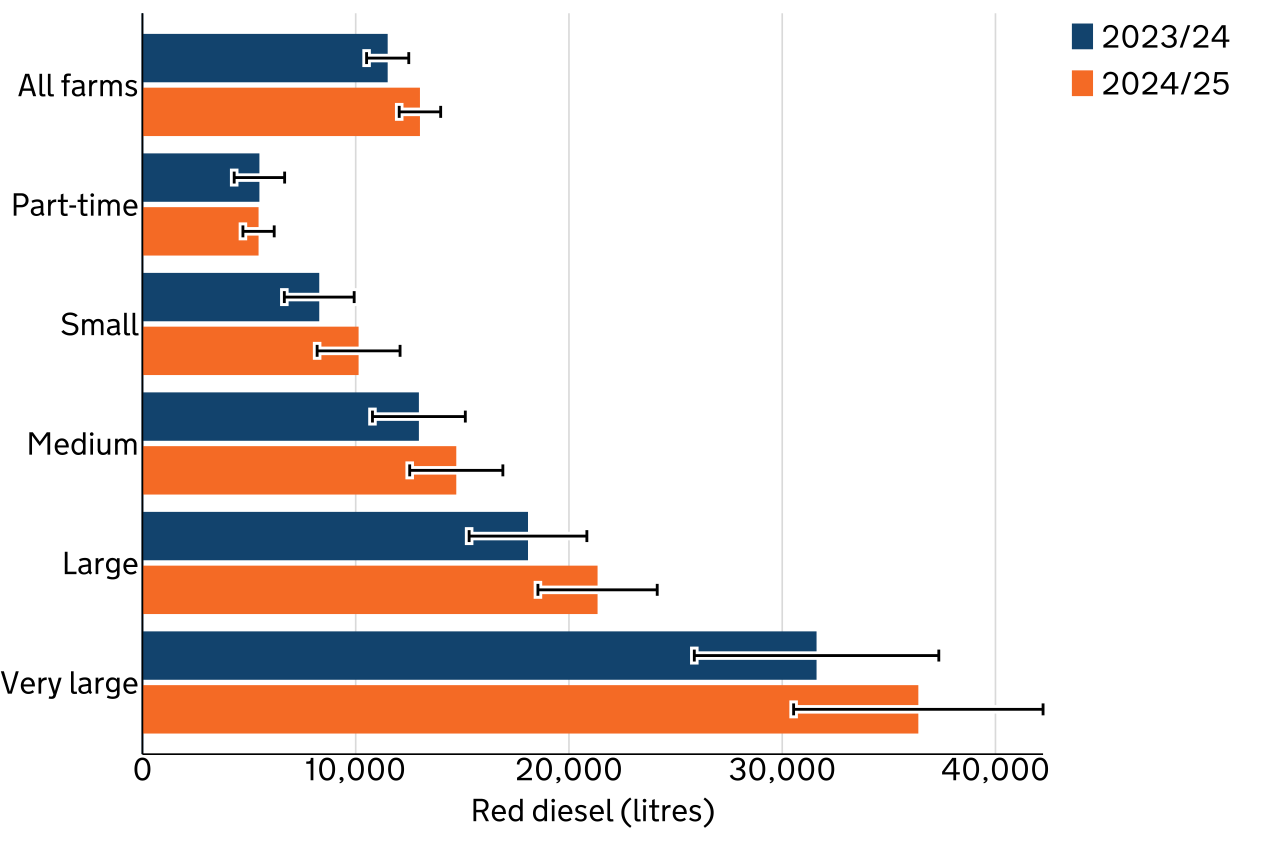
Figure 2.3: Average (mean) red diesel used on farms (including by contractors) in England by farm size (based on SLR), 2023/24 and 2024/25
Source: Dataset table 1.5
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
Farm size is based on the Standard Labour Requirement (SLR) of the business, rather than its land area. For more detail see Table 7.1.
Figure 2.3 shows that, perhaps unsurprisingly, as the farm size increased so did total red diesel usage. Very large farms used around 36,400 litres in 2024/25, while part-time farms used only 5,400 litres. With the exception of part-time farms, all farm sizes saw an increase in their average red diesel use compared to 2023/24. However, the confidence intervals showed substantial overlaps, so it is not clear if these differences were significant.
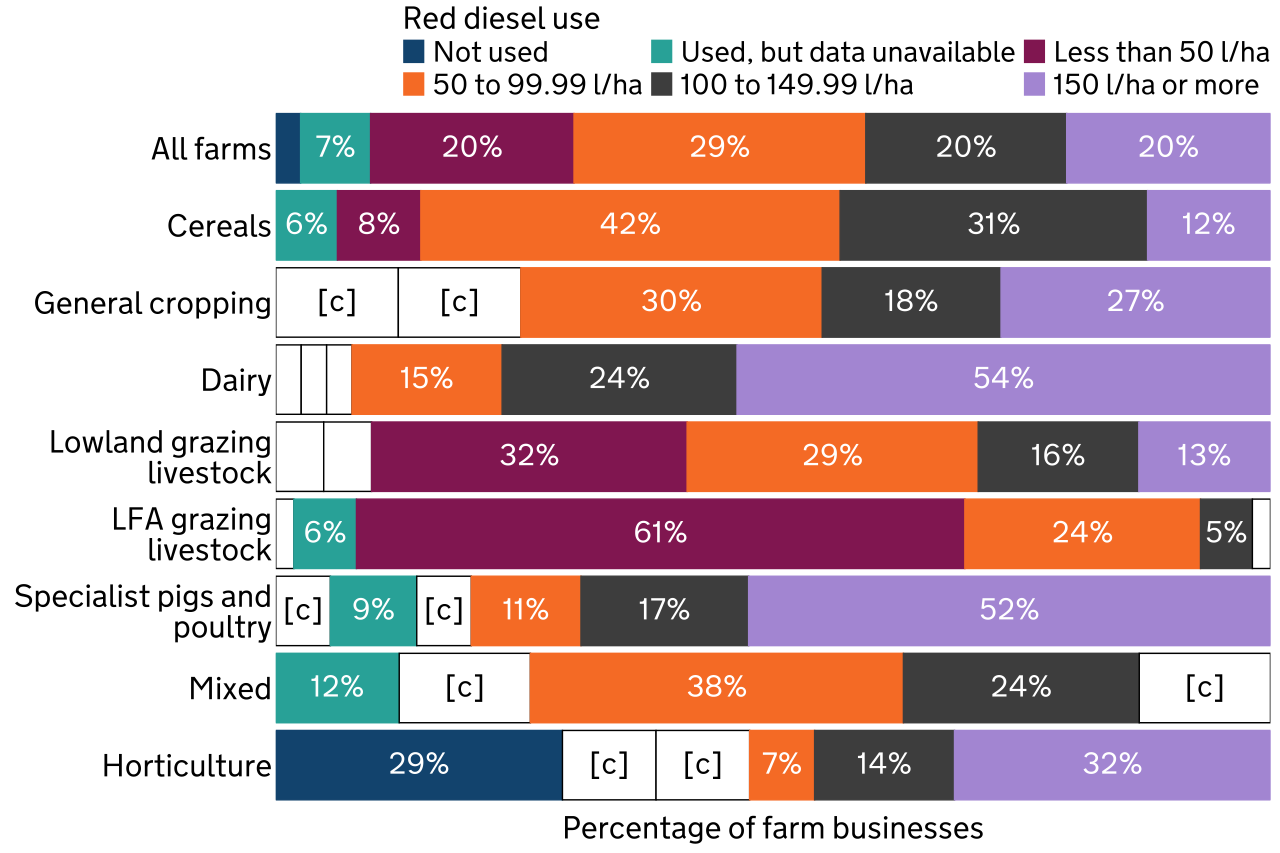
Figure 2.4: Distribution of farms in England by red diesel use (litres per hectare, l/ha) and farm type, 2024/25
Source: Dataset table 1.9
Figure notes:
-
The legend is presented in the same order as the bars (read the top row left to right, then the bottom row left to right).
-
White bars with black outlines and the symbol [c] indicate that results have been suppressed due to a small sample size. Where the bar is less than 5% wide, the symbol [c] is not displayed. The size of the bar does not indicate the suppressed value. Suppressed values are included in the ‘All farms’ averages.
Figure 2.4 shows that the use of red diesel (litres per hectare) varied greatly between farm types in 2024/25, reflecting the differences in practices and farm operations across types. LFA grazing livestock and lowland grazing livestock farms had the lowest usage rates, with 61% and 32% respectively using less than 50 litres per hectare.
Dairy and specialist pigs and poultry farms had the highest red diesel usage rates, with over half of these farms using more than 150 litres per hectare (54% and 52% respectively).
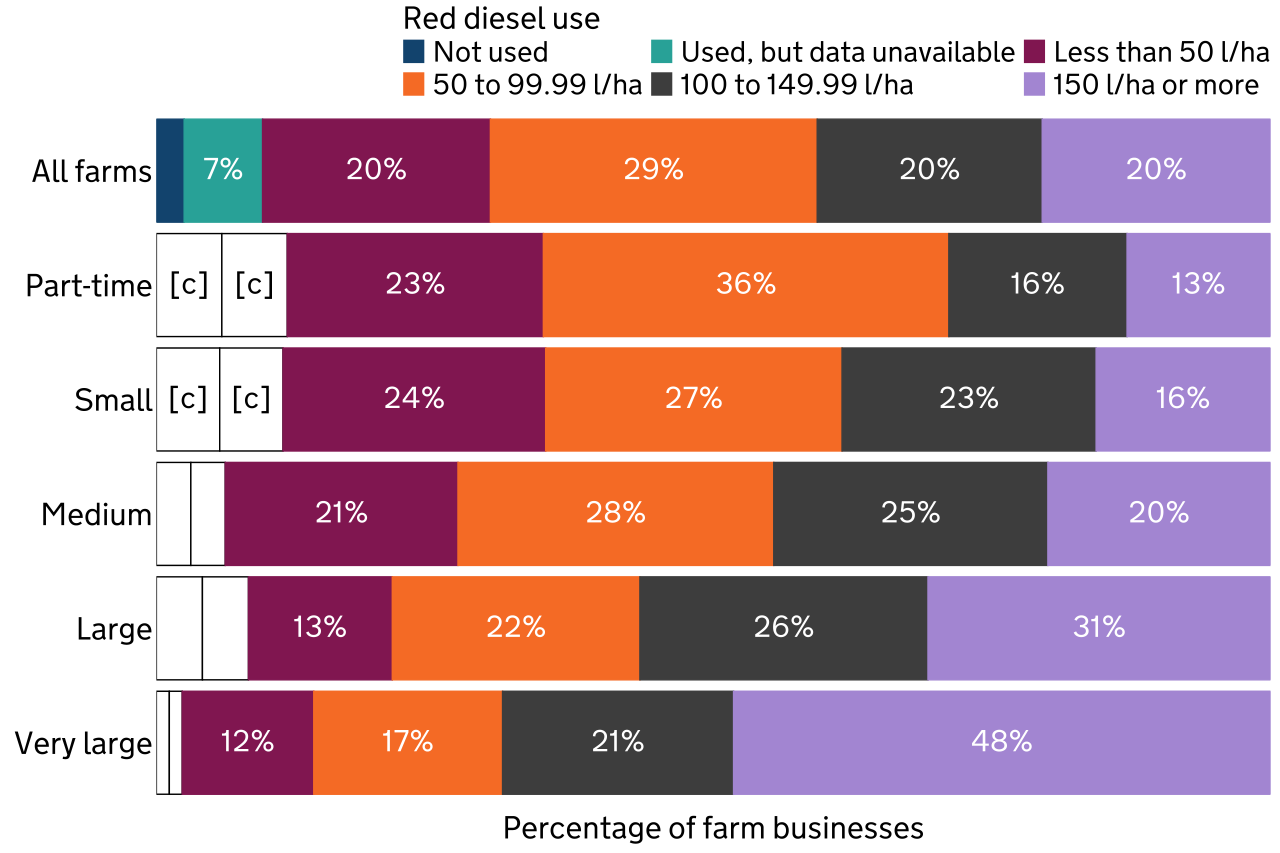
Figure 2.5: Distribution of farms in England by red diesel use (litres per hectare, l/ha) and farm size (based on SLR), 2024/25
Source: Dataset table 1.9
Figure notes:
-
The legend is presented in the same order as the bars (read the top row left to right, then the bottom row left to right).
-
White bars with black outlines and the symbol [c] indicate that results have been suppressed due to a small sample size. Where the bar is less than 5% wide, the symbol [c] is not displayed. The size of the bar does not indicate the suppressed value. Suppressed values are included in the ‘All farms’ averages.
Farm size is based on the Standard Labour Requirement (SLR) of the business, rather than its land area. For more detail see Table 7.1.
Figure 2.5 shows that, in 2024/25, red diesel use (litres per hectare) tended to increase as farm size increased, but this was more pronounced in large and very large farms. The very large size band had the highest proportion of farms using more than 150 litres per hectare at 48%, and the lowest proportion of farms using less than 50 litres per hectare, at 12%.
Small and part-time farms had the largest proportion of farms using less than 50 litres per hectare of red diesel, at 24% and 23%, respectively.
The distribution pattern observed here is in part a reflection of the farm type distributions across size bands, for example, as seen in figure 2.2 and 2.4, dairy farms tended to have the highest red diesel usage across farm type, and a large proportion of very large farms are dairy farms (for more insight see Table 16 Farm accounts in England).
2.3 Electricity usage
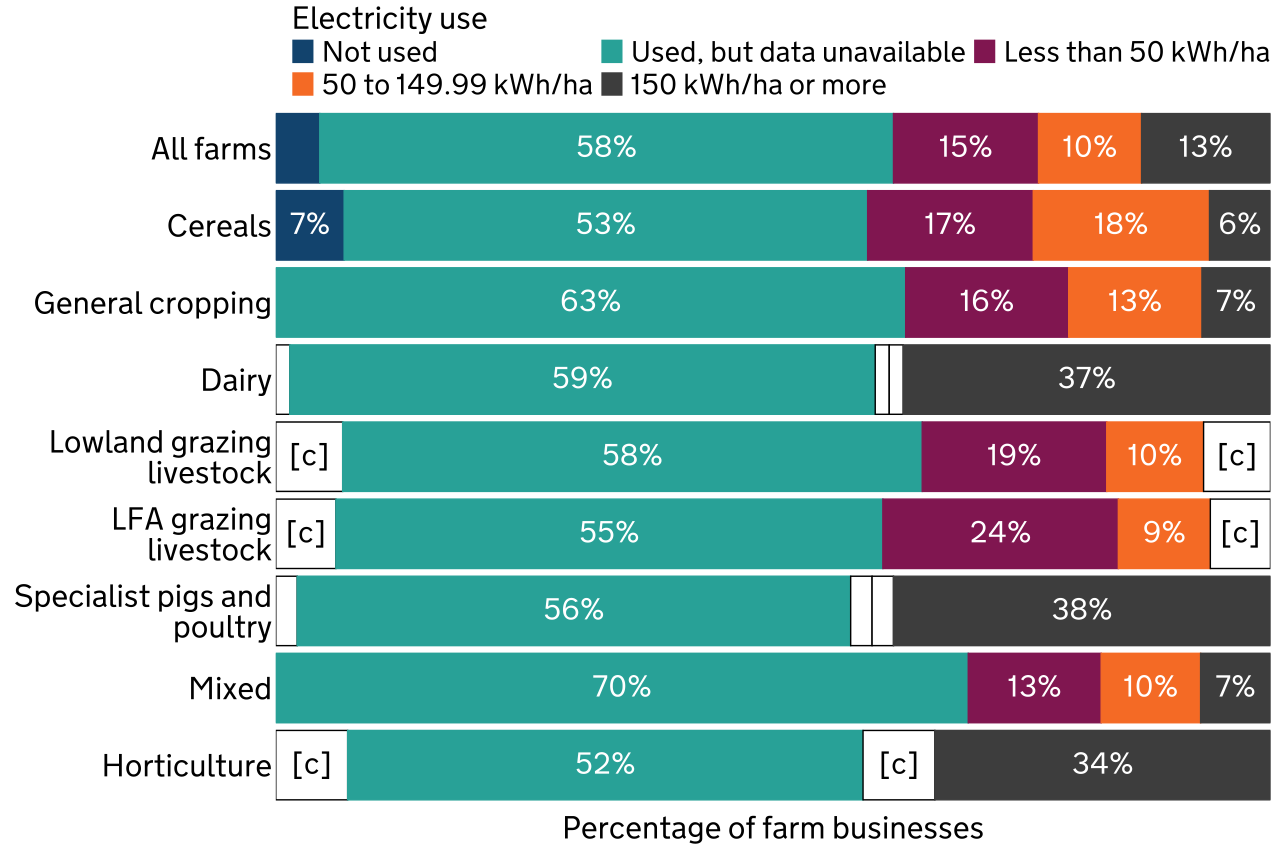
Figure 2.6: Distribution of farms in England by mains electricity use (kilowatt-hour per hectare, kWh/ha) and farm type, 2024/25
Source: Dataset table 1.4
Figure notes:
-
The legend is presented in the same order as the bars (read the top row left to right, then the bottom row left to right).
-
White bars with black outlines and the symbol [c] indicate that results have been suppressed due to a small sample size. Where the bar is less than 5% wide, the symbol [c] is not displayed. The size of the bar does not indicate the suppressed value. Suppressed values are included in the ‘All farms’ averages.
Figure 2.6 shows that, despite electricity being the second most used form of energy on farms, the survey was not able to collect data on the amount used for the majority of farms There are many potential reasons for this. For example, it may not have been possible to accurately separate personal and farm business use, or farms might not have accurate records on electricity use. However, there are some notable patterns in electricity use across farm types.
In 2024/25, electricity use per hectare was highest on specialist pigs and poultry, dairy and horticulture farms, with around a third of these farms using at least 150 kilowatt-hours per hectare in 2024/25. This reflects the practices often used in these farm types. For example, horticulture and pig and poultry farms use indoor systems more frequently, which generally operate over a smaller area than outdoor systems and require heating and lighting. Dairy farms are less likely to be entirely indoor but usually use electronic milking systems, resulting in relatively high energy use.
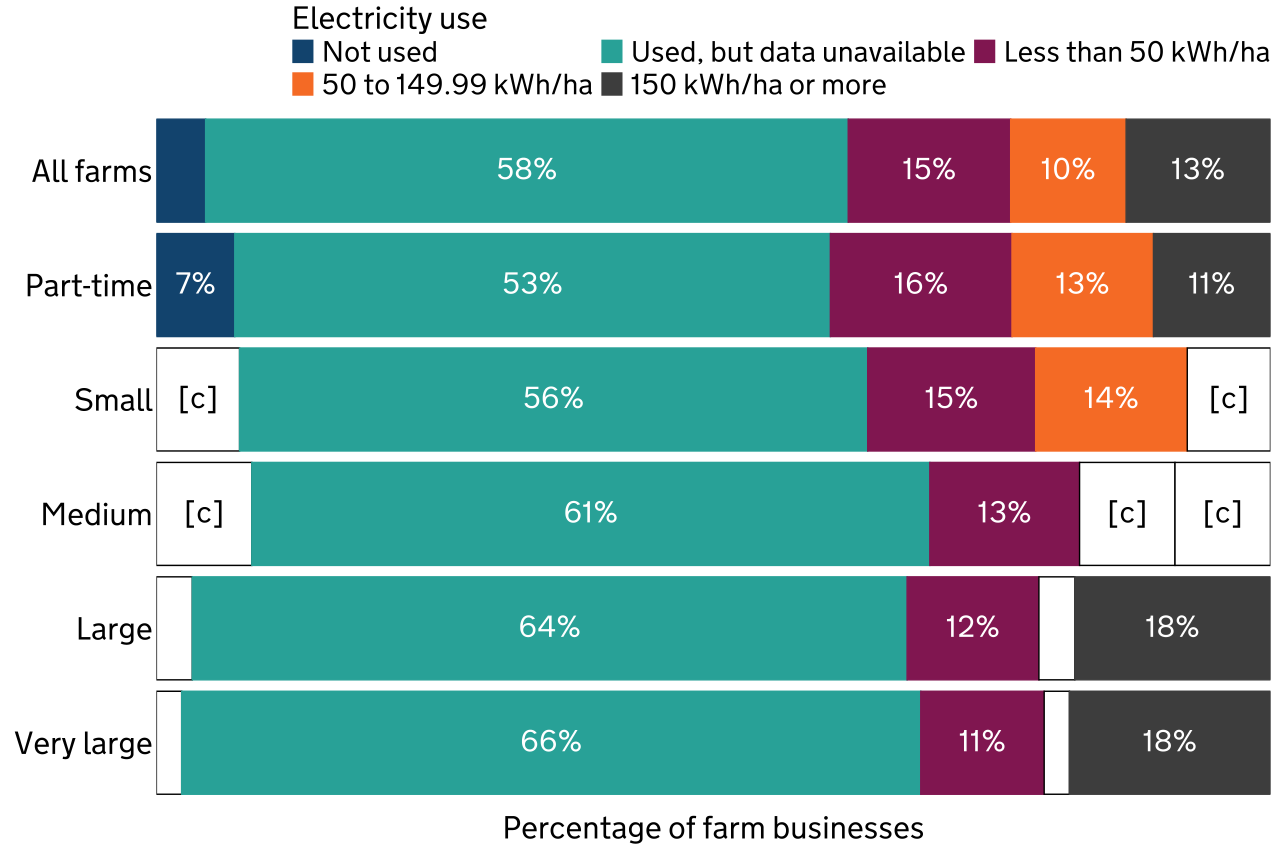
Figure 2.7: Distribution of farms in England by electrical use (kilowatt-hour per hectare, kWh/ha) and farm size (based on SLR), 2024/25
Source: Dataset table 1.4
Figure notes:
-
The legend is presented in the same order as the bars (read the top row left to right, then the bottom row left to right).
-
White bars with black outlines and the symbol [c] indicate that results have been suppressed due to a small sample size. Where the bar is less than 5% wide, the symbol [c] is not displayed. The size of the bar does not indicate the suppressed value. Suppressed values are included in the ‘All farms’ averages.
Farm size is based on the Standard Labour Requirement (SLR) of the business, rather than its land area. For more detail see Table 7.1.
Figure 2.7 shows that, in 2024/25, as farm size increased, electricity use per hectare also rose. Within large and very large farm businesses, 18% used at least 150 kilowatt-hours per hectare of electricity, in contrast to only 11% of part-time farms. Additionally, part-time and small farms had the highest proportions of farms using less than 50 kilowatt-hours per hectare, at 16% and 15%, respectively.
3. Renewable energy generation by farms
As well as buying fuel in, farms may also install technology which generates renewable energy. A detailed explanation of each energy source can be found in the definitions section of this publication.
3.1 Renewable energy generation
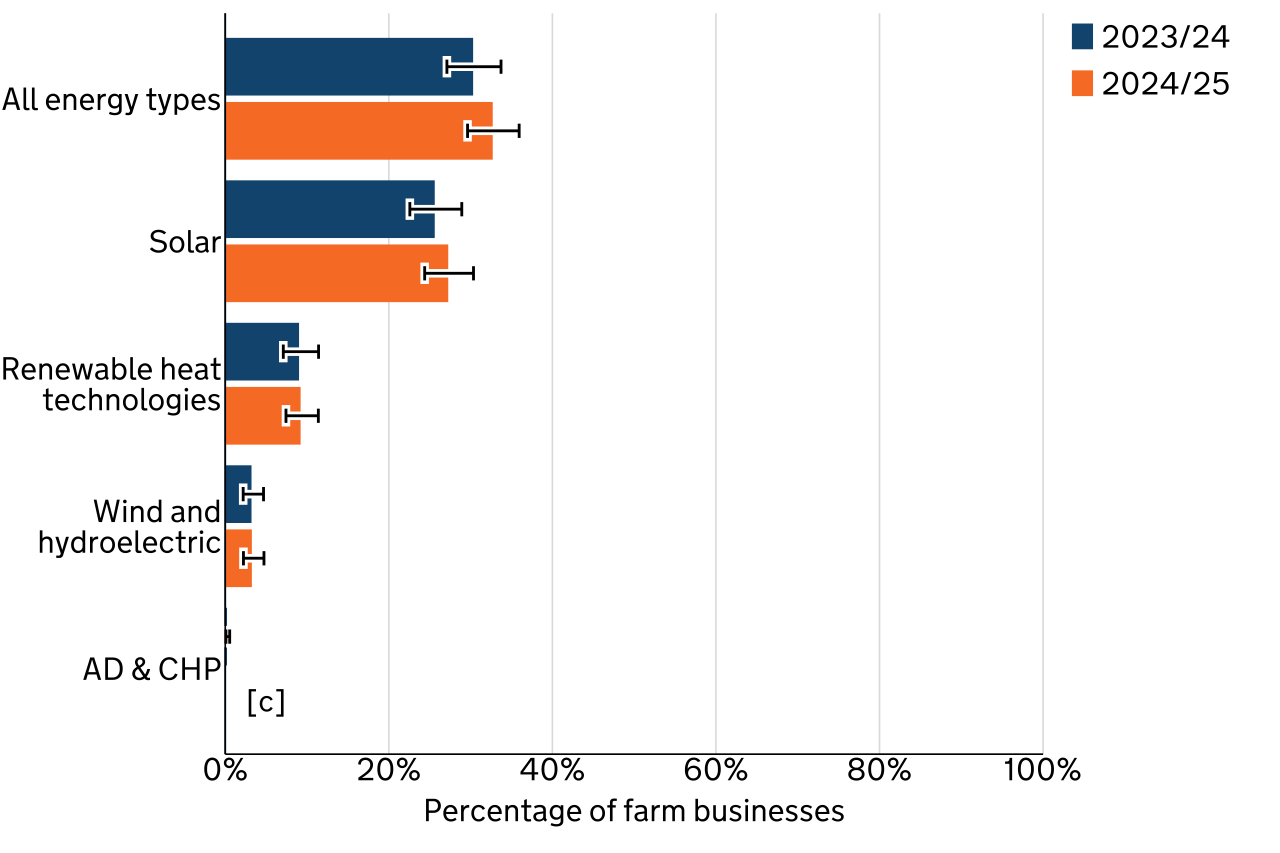
Figure 3.1: Percentage of farms in England generating renewable energy, 2023/24 and 2024/25
Source: Dataset table 2.1
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
The ‘All energy types’ category includes solar, renewable heat technologies, wind and hydroelectric, anaerobic digestion (AD), and combined heat and power (CHP).
-
Due to small sample sizes, anaerobic digestion (AD) and combined heat and power (CHP) have been combined.
Figure 3.1 shows that in 2024/25, 33% of all farms, generated some form of renewable energy, a slight increase from 30% in 2023/24.
Solar was the most common type of renewable energy generation, with 27% of farms undertaking this activity in 2024/25. This was followed by energy generation via renewable heat technologies at 9%, then wind and hydroelectric at 3%. Together, anaerobic digestion and combined heat and power had the lowest uptake. All types saw very little difference in uptake between 2023/24 and 2024/25.
3.2 Solar energy
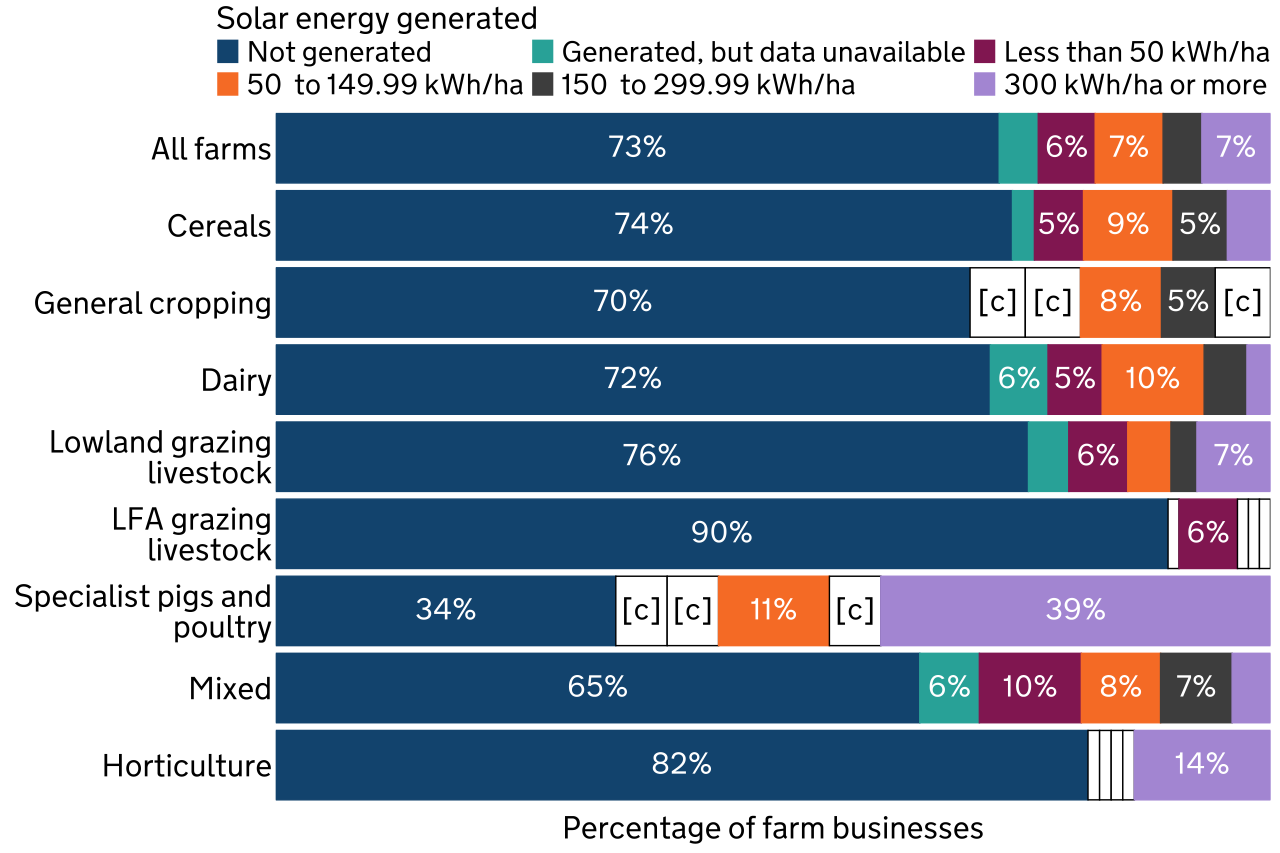
Figure 3.2: Distribution of farms in England by solar energy generated (kilowatt-hour per hectare, kWh/ha) and farm type, 2024/25
Source: Dataset table 2.11
Figure notes:
-
The legend is presented in the same order as the bars (read the top row left to right, then the bottom row left to right).
-
White bars with black outlines and the symbol [c] indicate that results have been suppressed due to a small sample size. Where the bar is less than 5% wide, the symbol [c] is not displayed. The size of the bar does not indicate the suppressed value. Suppressed values are included in the ‘All farms’ averages.
Figure 3.2 shows that in 2024/25, 66% of specialist pigs and poultry farms generated solar energy. The second-highest proportion were mixed farms at 35%, while LFA grazing livestock had the lowest uptake at 10% of farms.
Notably, while only 18% of horticulture farms generated solar energy, most of those produced more than 300 kilowatt-hours per hectare. This suggests that when horticulture farms do invest in solar, they tend to fall into the highest levels of production.
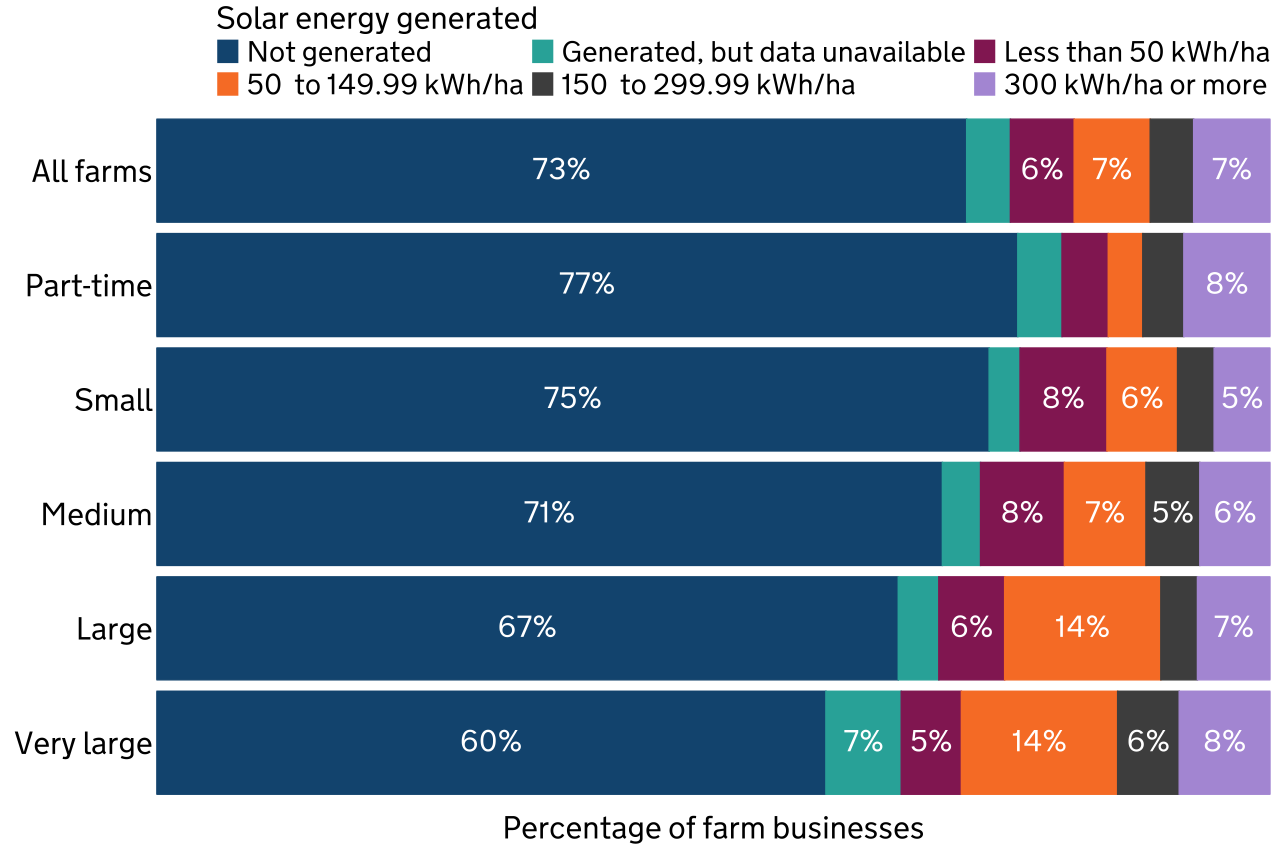
Figure 3.3: Distribution of farms in England by solar energy generated (kilowatt-hour per hectare, kWh/ha) and farm size (based on SLR), 2024/25
Source: Dataset table 2.11
Figure notes:
-
The legend is presented in the same order as the bars (read the top row left to right, then the bottom row left to right).
-
White bars with black outlines and the symbol [c] indicate that results have been suppressed due to a small sample size. Where the bar is less than 5% wide, the symbol [c] is not displayed. The size of the bar does not indicate the suppressed value. Suppressed values are included in the ‘All farms’ averages.
Farm size is based on the Standard Labour Requirement (SLR) of the business, rather than its land area. For more detail see Table 7.1.
Figure 3.3 shows that, in 2024/25, the likelihood of farms generating solar energy rose as the SLR of the business increased. While 40% of very large farms were generating solar energy, only 23% of part-time farms were doing so.
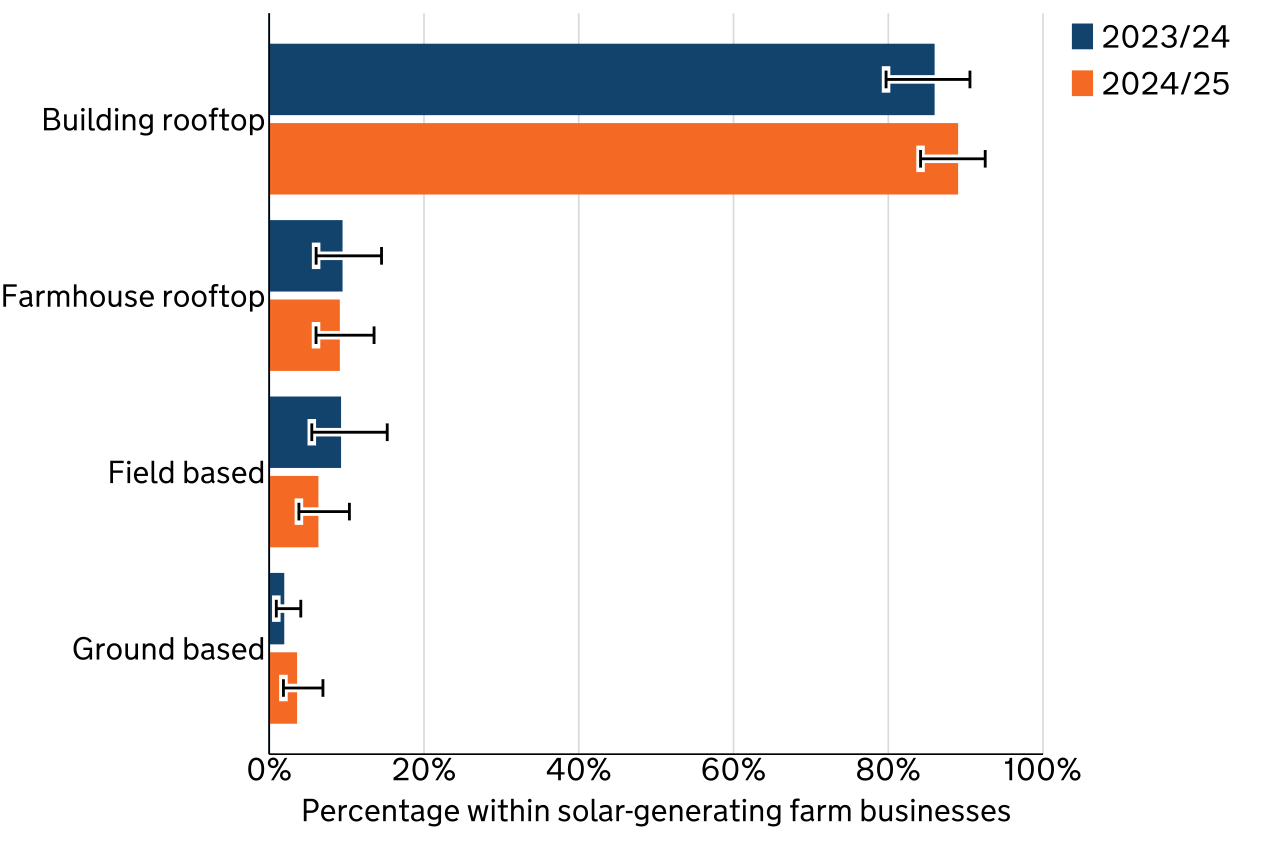
Figure 3.4: Location of solar panels on farms in England, 2023/24 and 2024/25
Source: Dataset table 3.3
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Only farm businesses that had solar panels installed are included in this analysis.
-
Farms were able to choose more than one response; therefore, values may sum to more than 100%.
Figure 3.4 shows where farms had solar panels in 2023/24 and 2024/25. Solar panels can be installed on farm buildings or farmhouse rooftops, or they can be field or ground based.
To be classed as field based, panels must be installed on land previously used for agriculture and be part of the farm business. However, this does not mean the land is no longer used for agriculture as fields with solar panels may continue to be used for agricultural purposes, such as livestock grazing. When solar panels are installed on land which has not previously been used for agricultural purposes, this is classed as ground based.
Land that is rented out to energy companies is not included here; instead, this is included in the ‘letting out building’ category within the farm’s diversification income; details can be found in Farm Accounts in England . Data on the area of land occupied by solar panels is available in the Agricultural land use in England publication.
In 2024/25, 89% of the farms generating solar power had panels on farm building rooftops, which was an increase of 3 percentage points compared to 2023/24. In both years, 9% had solar panels on the farmhouse rooftop. In 2023/24, 9% of solar generating farm businesses had field based solar panels, but in 2024/25 this fell to 6%. Ground based solar panels were the least common choice in both years.
The FBS also gave the option to report solar panels installed in other locations, for example on canopies or glasshouse covers. However, none were reported in any of these locations.
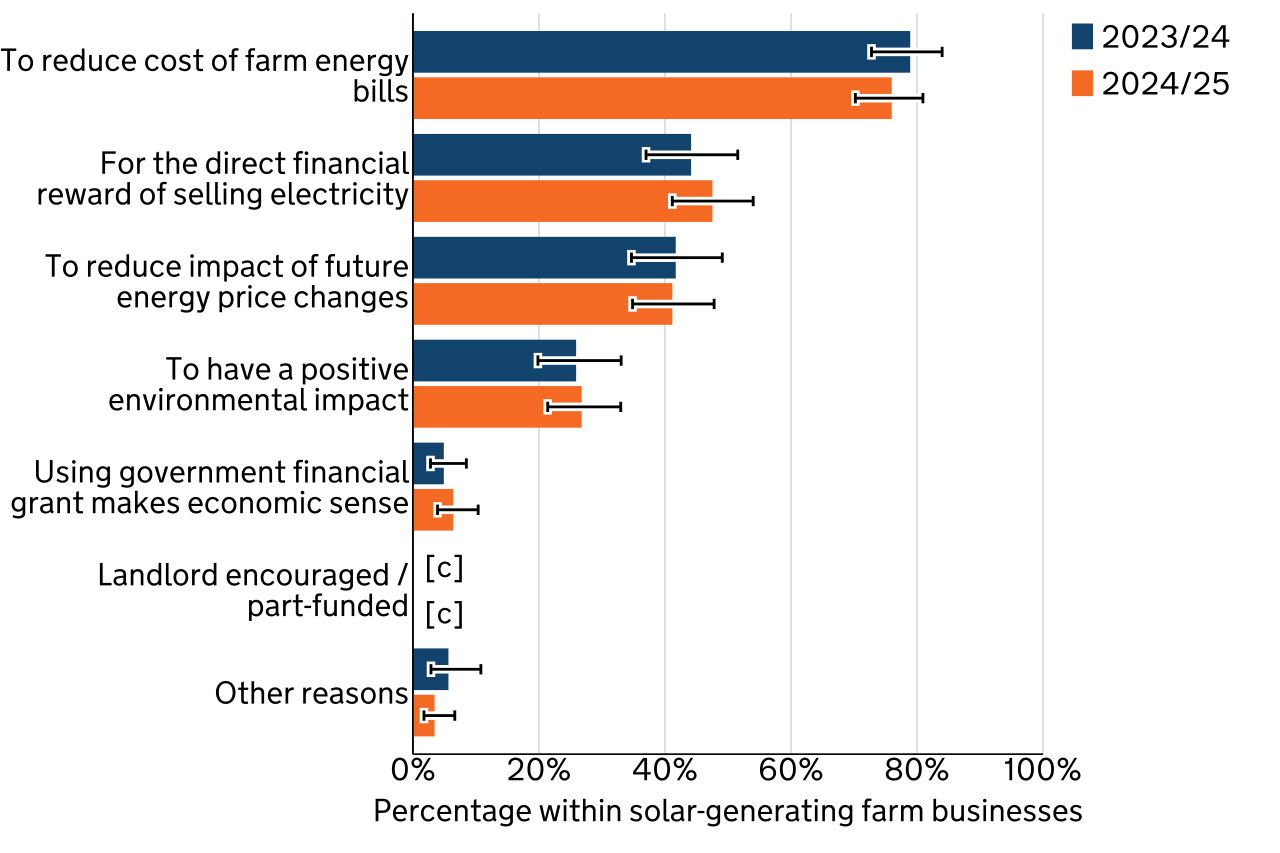
Figure 3.5: Reasons for first installation of solar panels on farms in England, 2023/24 and 2024/25
Source: Dataset table 3.4
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
In cases where the sample contains between 1 and 5 farms, results are suppressed with the symbol ‘c’ (confidential).
-
Farms were able to choose more than one response; therefore, values may sum to more than 100%.
Figure 3.5 shows that, in 2023/24 and 2024/25, outcomes relating to direct financial incentives were the most common reasons why farms installed solar panels.
In 2024/25, 76% of the farms with solar panels installed them to reduce their farm energy bill. The financial reward of selling electricity was the motivation for 48% of farms, while reducing the impact of future energy price changes was also a popular reason at 41% of farms. Compared to 2023/24, there was little change in any of these values.
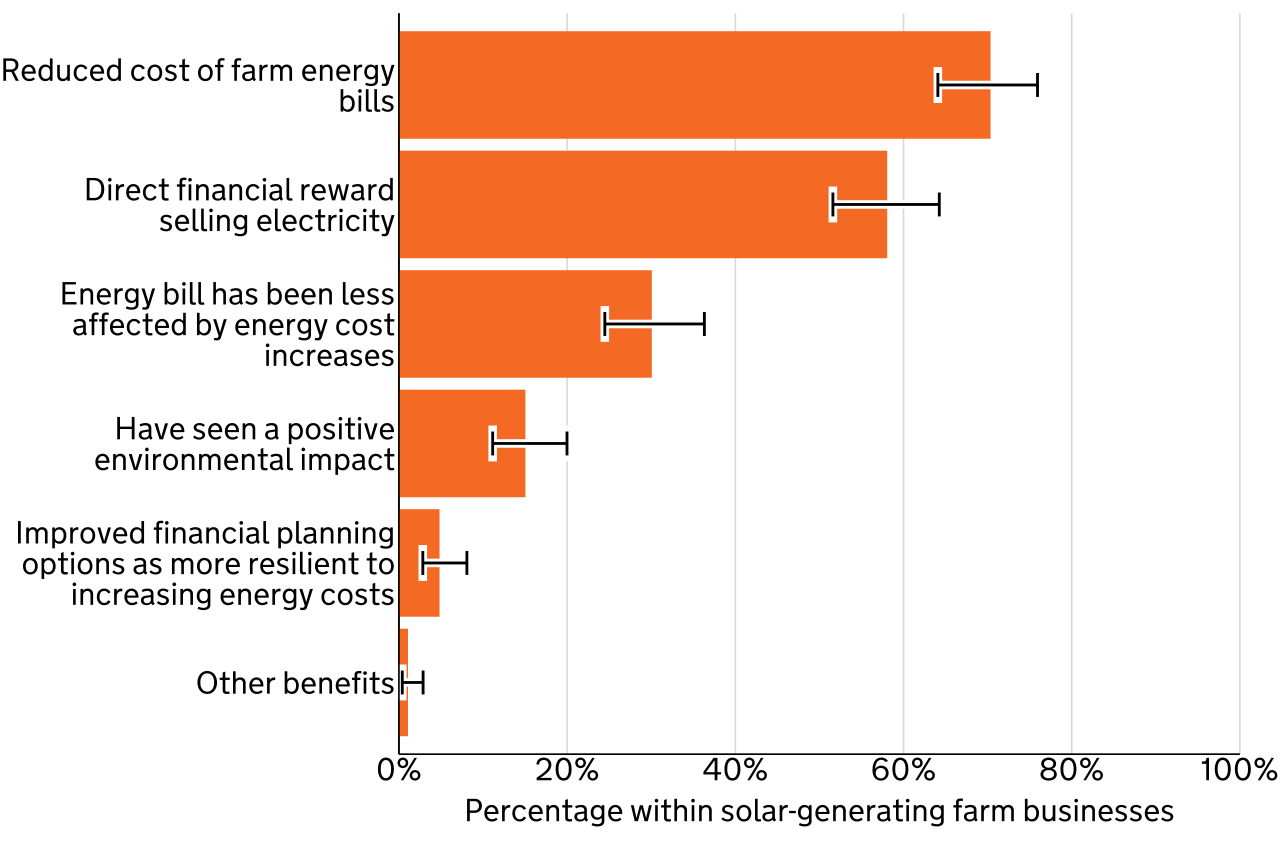
Figure 3.6: Benefits of installing solar panels on farms in England, 2024/25
Source: Dataset table 3.7
Figure notes:
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Farms were able to choose more than one response; therefore, values may sum to more than 100%.
-
Only farm businesses that had solar panels installed are included in this analysis.
-
This question was first introduced in the 2024/25 survey year.
Figure 3.6 shows that financial gains were the greatest benefits realised by installing solar panels; 70% of farms with installed solar panels saw their energy cost decrease, 58% had direct financial rewards from selling electricity and 30% were less affected by the energy cost increases.
3.3 Reasons why farms had not installed renewable energy
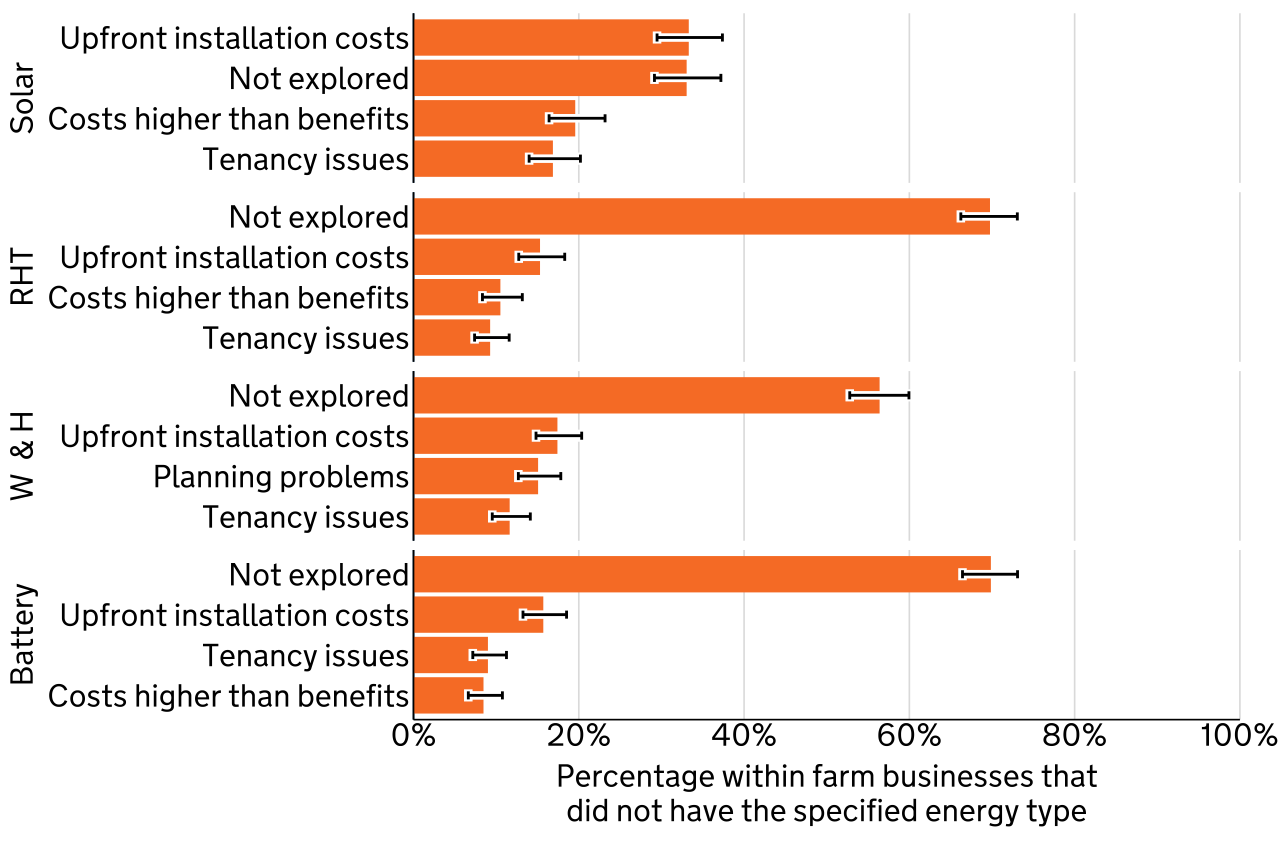
Figure 3.7: The top four reasons for not installing renewable energy generation on farms in England, 2024/25
Source: Dataset table 3.6
Figure notes:
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Farms were able to choose more than one response; therefore, values may sum to more than 100%.
-
More data on this question can be found in the dataset table 3.6.
-
Some energy types have been abbreviated: RHT refers to renewable heat technologies; W & H refers to wind and hydroelectric.
Figure 3.7 shows that a high proportion of farms had not explored most renewable energy options, this was the most common reason for not installing across all energy types except solar power. For solar power, the most common barrier was upfront installation costs.
For most energy types, costs being higher than benefits was also one of the main reasons for not installing, along with tenancy issues and/or planning problems.
4. Carbon audits in farm businesses
Carbon audits measure the greenhouse gas emissions of organisations and their activities. They are undertaken for many reasons, but the main objectives are usually to measure the amount of carbon-containing greenhouse gases that are produced by the business (also known as the carbon footprint), identify and assess how the different activities contribute to emissions, and to get recommendations for improvements to reduce emissions.
There has been increasing interest and use of carbons audits across many sectors. This section looks at the prevalence of carbon audits among farm businesses in 2023/24 and 2024/25. Where farms undertook carbon audits, details are shown on the recommendations they received and what actions they took based on those recommendations.
4.1 Carbon audits
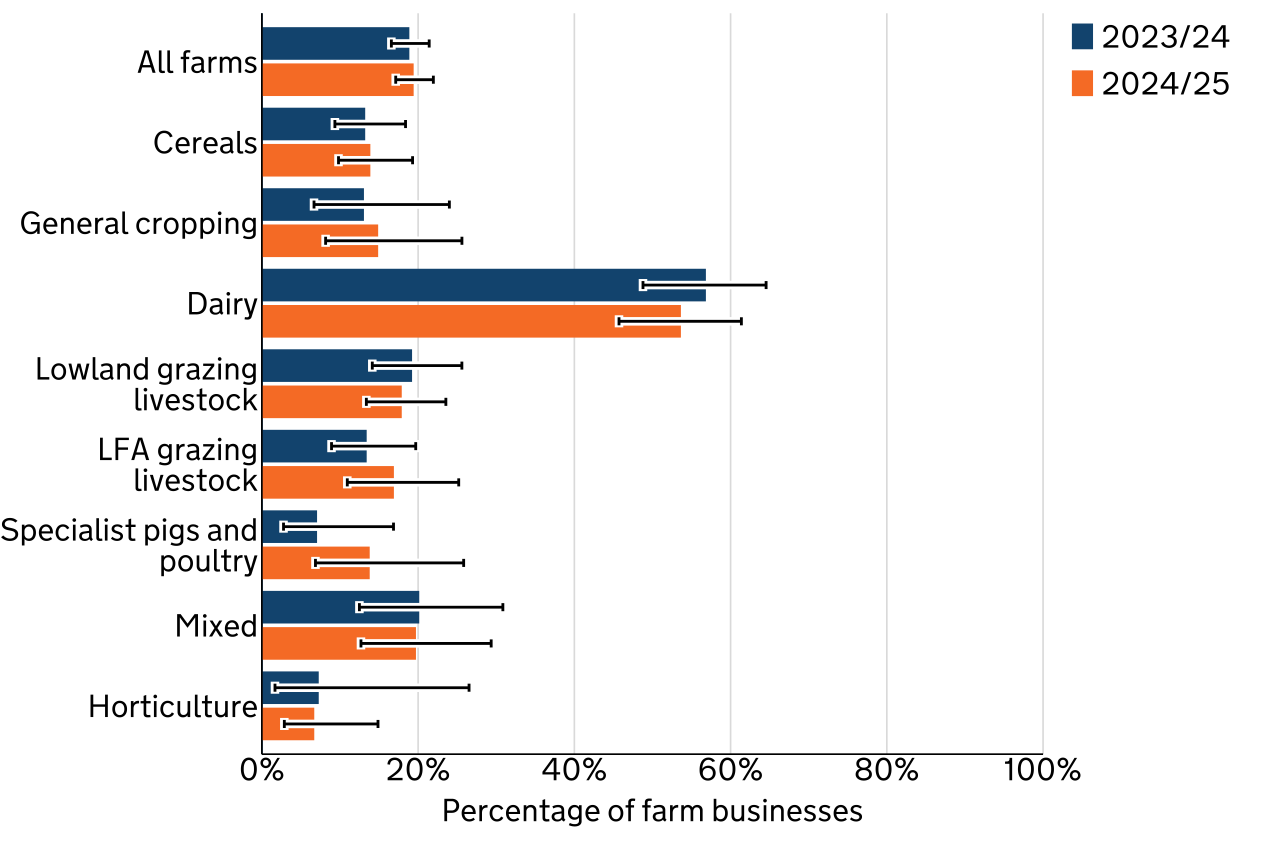
Figure 4.1: Percentage of farms in England which have completed a carbon audit by farm type, 2023/24 and 2024/25
Source: Dataset table 4.1
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Because some farms included here received a carbon audit that was available to FBS participants, the estimated percentage of farms shown here completing carbon audits is likely to be higher than the true value in the sampled population.
Figure 4.1 shows that by 2024/25, 19% of farms (around 9,600 farms), had completed a carbon audit at some point, the same proportion as in 2023/24. Overall, there were no meaningful differences between 2023/24 and 2024/25 across any farm type, owing to the relatively wide confidence intervals.
Over half of dairy farms had completed a carbon audit, by far the largest proportion of any farm type. This may reflect dairy companies and retailers requiring carbon audits for their supply chain as part of sustainability initiatives. The reasons farms perform carbon audits are explored further in Figure 4.3.
Horticulture farms had the lowest proportion of farms completing a carbon audit, at 7% in both years. Within the remaining farm types, between 14% and 20% of farms had completed a carbon audit.
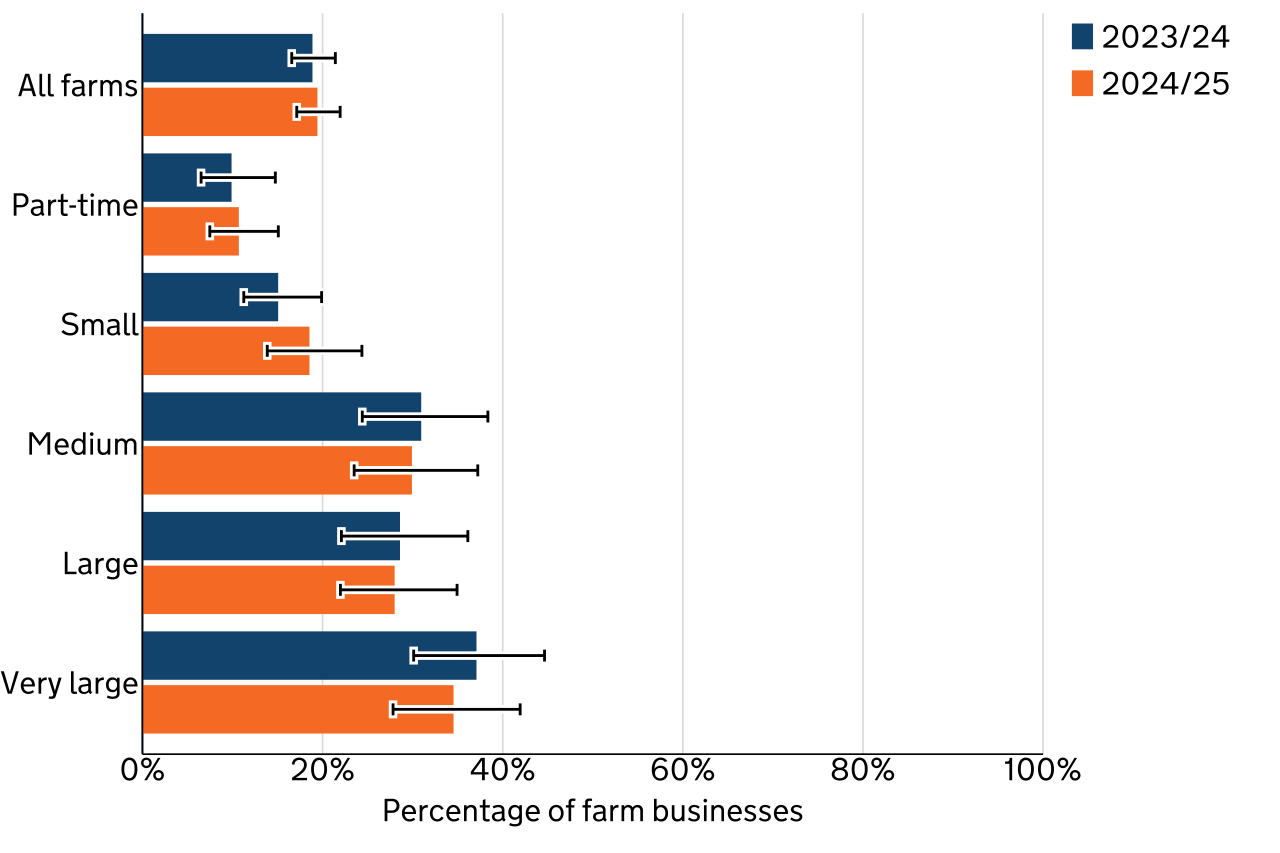
Figure 4.2: Percentage of farms in England which have completed a carbon audit by farm size (based on SLR), England 2023/24 and 2024/25
Source: Dataset table 4.1
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Because some farms included here received a carbon audit that was available to FBS participants, the estimated percentage of farms shown here completing carbon audits is likely to be higher than the true value in the sampled population.
Farm size is based on the Standard Labour Requirement (SLR) of the business, rather than its land area. For more detail see Table 7.1.
Figure 4.2 shows that, in general, larger farm businesses – meaning those which a higher SLR – were more likely to have performed a carbon audit than smaller farms. The distribution pattern observed here is in part a reflection of the dairy farm distributions across size bands, as seen in figure 4.1 dairy farms were the most likely farm type to have completed a carbon audit, and the majority of dairy farms are in the large and very large size categories (for more insight see Table 16 Farm accounts in England). As with farm type, there were no meaningful differences between 2023/24 and 2024/25 due to the relatively wide confidence intervals.
Of the 9,600 farms that had completed a carbon audit by 2024/25. The most commonly used calculators were Agrecalc and Farm Carbon Calculator, at 3,700 and 1,900 farms respectively.
Figure 4.3: Reasons why farms in England completed a carbon audit 2023/24 and 2024/25
Source: Dataset table 4.6
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Only farm businesses that had completed a carbon audit are included in this analysis.
-
Farms were able to choose more than one response; therefore, values may sum to more than 100%.
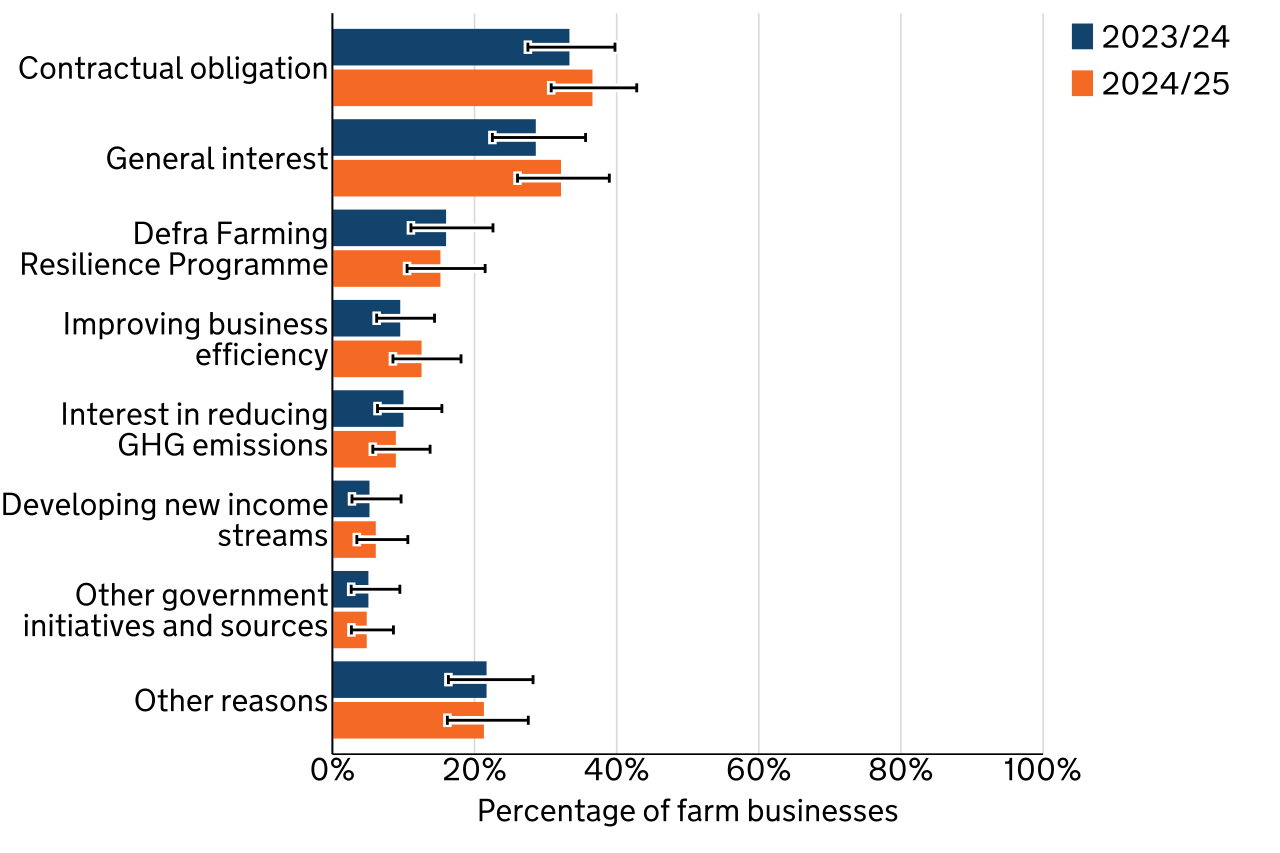
Figure 4.3 shows that in 2024/25, of the 9,600 farms that had completed a carbon audit, the most common reasons for doing so were contractual obligation and general interest, at 37% and 32% of farms respectively. The Defra Farming Resilience Programme was the third most common reason, at 15% of farms. There were no meaningful differences between 2023/24 and 2024/25.
Figure 4.4: Reasons why farms in England had not completed a carbon audit, 2023/24 and 2024/25
Source: Dataset table 4.7
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Only farm businesses that have not completed a carbon audit are included in this analysis.
-
Farms were able to choose more than one response; therefore, values may sum to more than 100%.
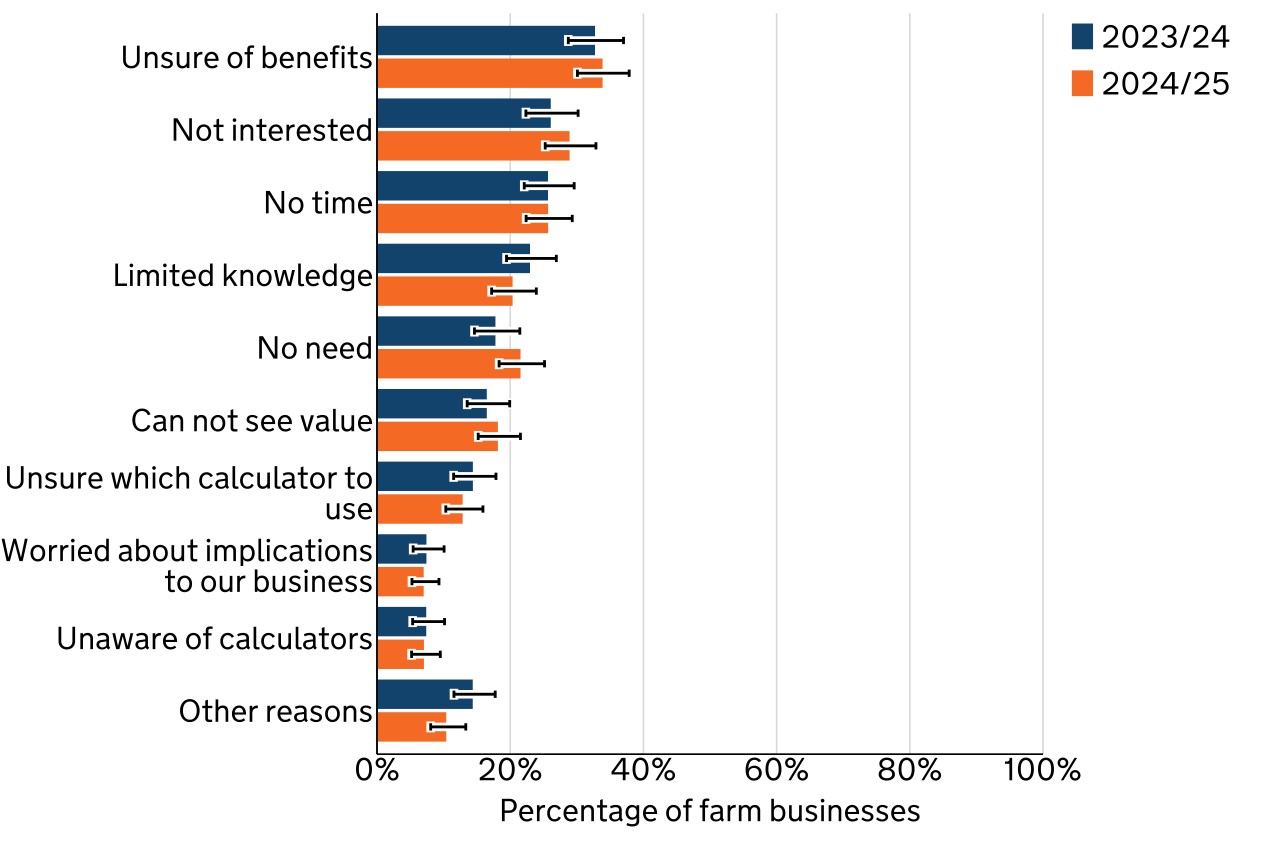
In 2024/25, 39,700 farms had never completed a carbon audit. Figure 4.4 shows that lack of knowledge of carbon audits might play a big part in this; of those farms which had never had a carbon audit, 34% were unsure of the benefits they provide while 20% cited limited knowledge. There was also a significant proportion of farms (22%) that felt they had no need for a carbon audit. Lack of interest and time were also some of the most popular reasons, at 29% and 26% of farms respectively.
There were again no meaningful differences between 2023/24 and 2024/25, as all differences were within confidence intervals.
4.2 Farms following up on carbon audits results
Table 4.1: Response of farms in England to carbon audit recommendations 2024/25
| Recommendations | Number of farm businesses | Percentage within carbon audited farms |
|---|---|---|
| Did not receive any recommendations | 1,800 | 19% |
| No longer had a record of the recommendations | 2,200 | 22% |
| Received recommendations but had not followed any of them | 1,500 | 15% |
| Received recommendations and had followed at least one of them | 4,100 | 43% |
Source: Dataset table 4.3
Table 4.1 shows that, of the 9,600 farms that had carried out a carbon audit by 2024/25, 19% did not receive any recommendations. This may occur when the carbon audit is commissioned by another business in the supply chain, for example, a packer or a retailer, and the recommendations are not shared with the farm. Some of the surveyed farms may also have been waiting to receive their recommendations at the time of the survey.
An additional 22% of farms could not remember their recommendations and did not have any record of them, while 15% did not follow the recommendations they received. The reasons why farms did not follow recommendations are explored in Figure 4.6.
The remaining 43% of the carbon-audited farms followed at least one of the recommendations from their audit.
Figure 4.5: Actions taken by farms in England following recommendations from carbon audits, 2023/24 and 2024/25
Source: Dataset table 4.4
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
Only farm businesses that had completed a carbon audit are included in this analysis.
-
In cases where the sample contains between 1 and 5 farms, results are suppressed with the symbol ‘c’ (confidential).
-
The option ‘Action(s) completed prior to audit’ was added to the 2024/25 survey, the lack of this option is marked with the symbol ‘x’ (not available).
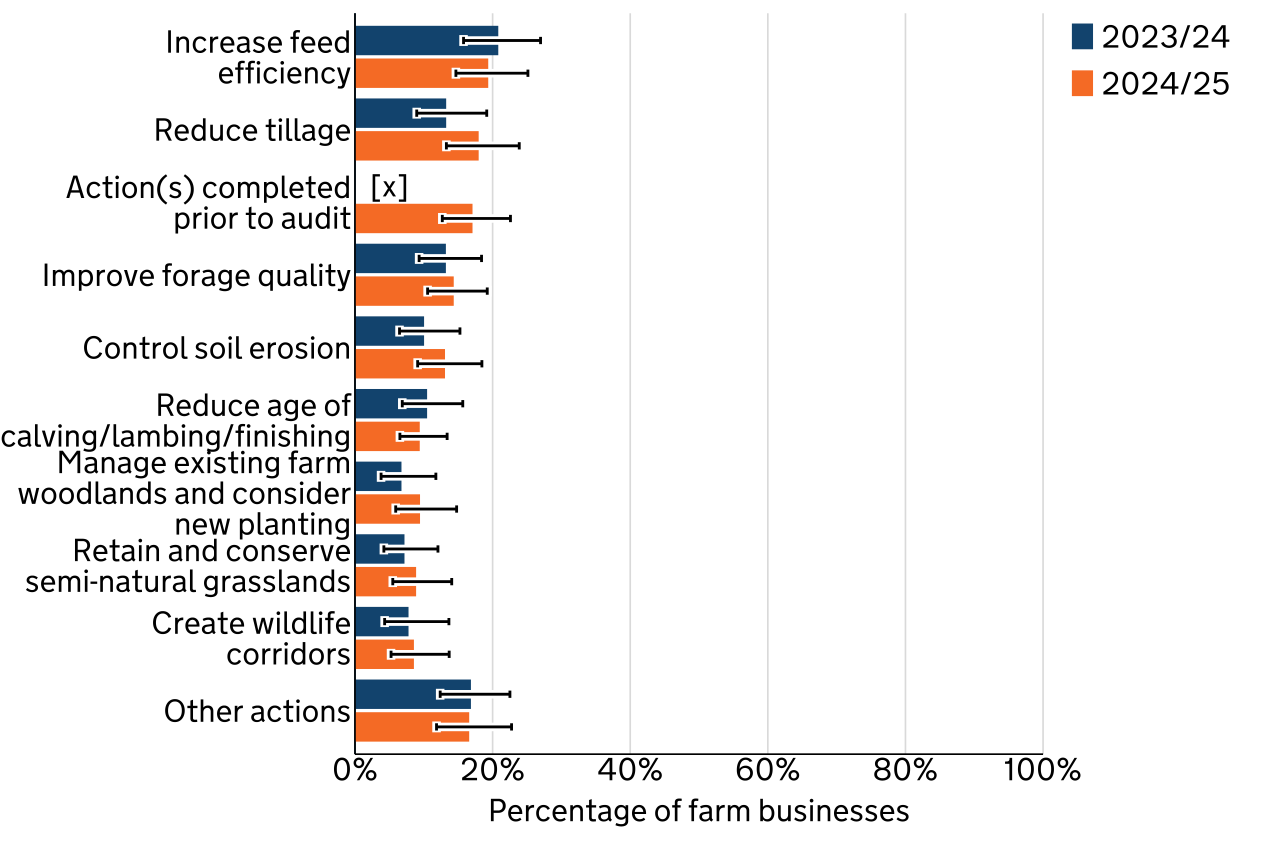
Figure 4.5 shows that, of the 9,600 farms which had completed a carbon audit by 2024/25, the most common resulting actions were increasing feed efficiency at 19% and tillage reduction at 18%.
The more environmentally centred actions were the least commonly completed, with managing existing farm woodlands, retaining and conserving semi-natural grasslands and creating wildlife corridors all at around 9% of farms in 2024/25.
There were no meaningful differences between 2023/24 and 2024/25.
Figure 4.6: Reasons why farms in England did not follow carbon audit recommendations, 2023/24 and 2024/25
Source: Dataset table 4.5
Figure notes:
-
The legend is presented in the same order as the bars.
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
In cases where the sample contains between 1 and 5 farms, results are suppressed with the symbol ‘c’ (confidential).
-
Only farm businesses that had completed a carbon audit are included in this analysis.
-
Farms were able to choose more than one response; therefore, values may sum to more than 100%.
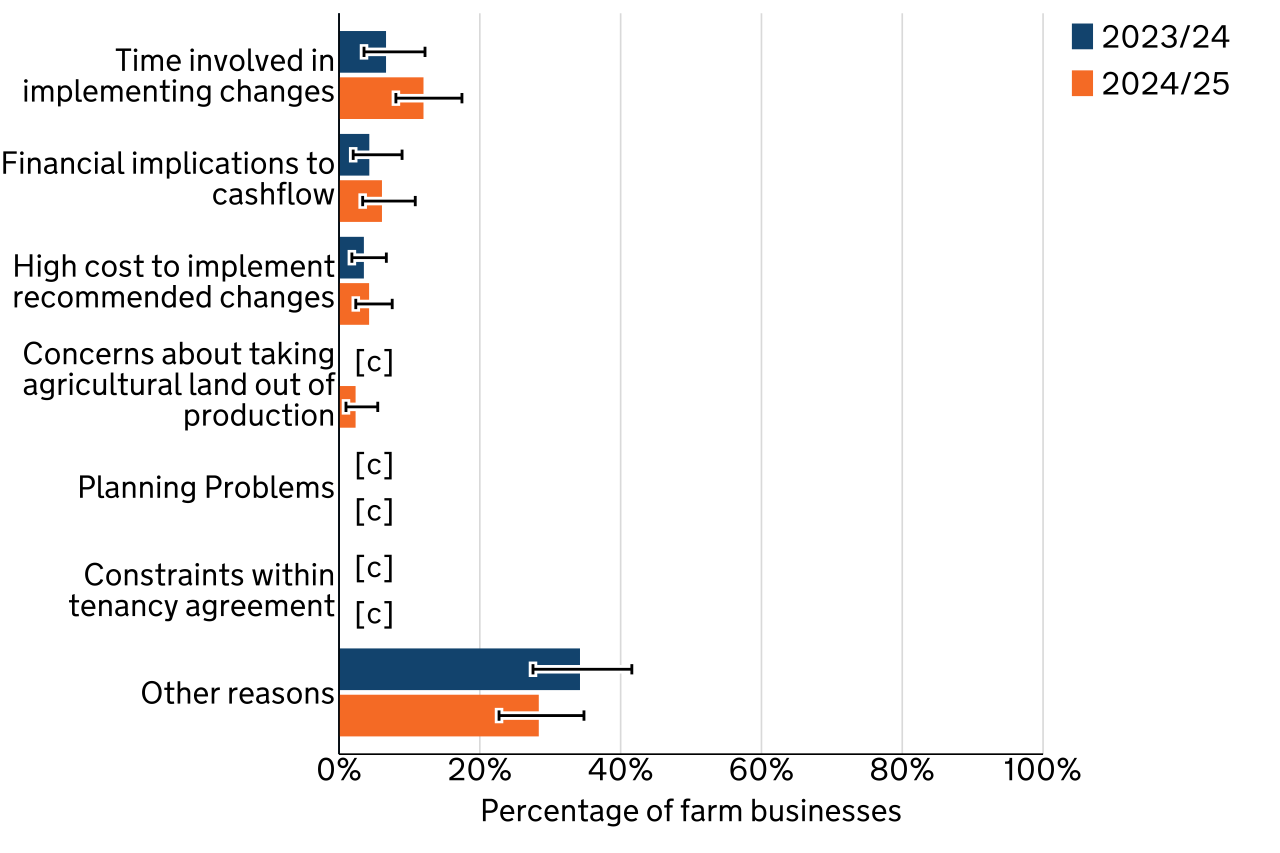
Figure 4.6 shows that, in 2024/25, of the 9,600 farms that had completed a carbon audit, 12% had not followed their recommendations because of the time involved in implementing changes. Furthermore 6% had not done so due to financial implications to cashflow and 4% had not because of the high implementation cost.
There were no meaningful differences between 2023/24 and 2024/25, due to the relatively wide confidence intervals.
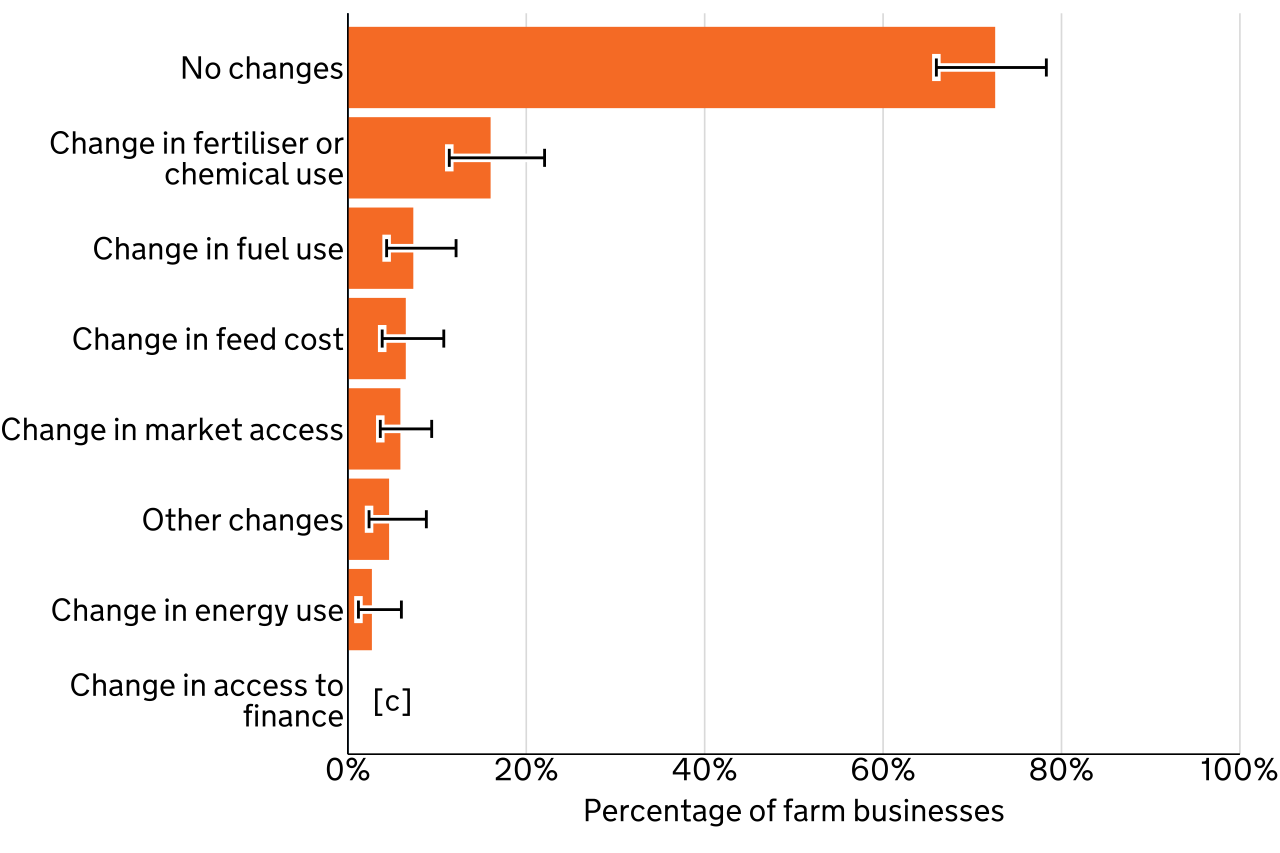
Figure 4.7: Tangible benefits seen by farms in England after completing a carbon audit, 2024/25
Source: Dataset table 4.8
Figure notes:
-
The black line on each bar indicates the 95% confidence interval of the value, which gives an indication of statistical uncertainty. Wider intervals mean more uncertainty; see Section 6.3 for more details.
-
In cases where the sample contains between 1 and 5 farms, results are suppressed with the symbol ‘c’ (confidential).
-
Only farm businesses that had completed a carbon audit are included in this analysis.
-
Farms were able to choose more than one response; therefore, values may sum to more than 100%.
-
This question was first introduced in the 2024/25 survey year.
Figure 4.7 shows that 73% of the farms which completed a carbon audit saw no tangible benefit from it. This fell to 53% for the farms which received recommendations and followed at least one (Table 4.1). The most common benefit was change in fertiliser or chemical use, at 16% of farms.
5. What you need to know about this release
5.1 Contact details
Responsible statistician: Filipe de Jesus Colwell
Public enquiries: fbs.queries@defra.gov.uk
For media queries between 9am and 6pm on weekdays:
Telephone: 0330 041 6560
Email: newsdesk@defra.gov.uk
5.2 Official Statistics in Development
Official statistics in development are official statistics that are undergoing a development; a full explanation can be found on the Office for Statistics Regulation website. Our statistical practice is regulated by the Office for Statistics Regulation (OSR). OSR sets the standards of trustworthiness, quality and value in the Code of Practice for Statistics that all producers of official statistics should adhere to.
The survey module used to collect the data used in this publication is still under development, with improvements planned for the collection process and data validation. For example, adding more options for responses to some questions, so that future publications can contain more detailed data.
You are welcome to contact us directly with any comments about how we meet these standards, using the details in section 5.1. Alternatively, you can contact OSR by emailing regulation@statistics.gov.uk or via the OSR website.
Since the latest review by the Office for Statistics Regulation, we have continued to comply with the Code of Practice for Statistics, and have made the following improvements:
- Reviewed and improved data presentation to better meet accessibility guidelines.
- Automated production of the statistics using Reproducible Analytical Pipelines (RAP).
- Reviewed and improved accompanying commentary.
5.3 User engagement
In line with Defra’s User Engagement for Statistics Policy Statement and the Code of Practice for Official Statistics, we are committed to ensuring that our statistics are of value and meet user needs, and we welcome any feedback or suggestions regarding this publication. To provide feedback, you can email us at: fbs.queries@defra.gov.uk.
You can also register as a user of the FBS statistics publications. Registering as a user means we will be able to contact you regarding any user engagement activities that we may run, such as seeking feedback on proposed changes.
5.4 Survey content, methodology and data uses
The Farm Business Survey (FBS) is an annual survey providing information on the financial position, physical characteristics, and economic performance of farm businesses in England. The sample of farm businesses covers all regions of England and all types of farming.
Data for the FBS is collected through face-to-face interviews with farmers, conducted by highly trained research officers.
The data are widely used by the industry for benchmarking and inform wider research into the economic performance of the agricultural industry, as well as for evaluating and monitoring current policies. The data will also help to monitor farm businesses throughout the Agricultural Transition period.
5.5 Availability of results
This release contains headline results for each section. The full breakdown of results (when sampling permits), by farm type, farm business size (based on SLR), region, farm tenure, farmer age and farm economic performance can be found in the dataset tables.
All Defra statistical notices can be viewed on the Statistics at Defra page.
More publications and results from the Farm Business Survey are available on the Farm Business Survey Collection page.
6 Survey details
6.1 Background
There has been growing interest in more detailed energy usage data alongside greater insight into both the renewable energy and carbon audit sectors. As a result, the Farm Business Survey (FBS) has collected data on fuel and electricity use on farm businesses along with the quantity of renewable energy generation. The survey has also included follow up questions on the reasons for installing or not installing different types of renewable energy. The FBS also asked farms whether they had completed a carbon audit, the actions taken as a result, the reasons for performing a carbon audit and, to those farms without a carbon audit, the reasons for not completing one.
6.2 Survey coverage and weighting
The Farm Business Survey only includes farm businesses with a Standard Output of at least £21 thousand, based on activity recorded in the previous June Survey of Agriculture and Horticulture. In 2024/25, the sample of 1,426 farms represented approximately 49,300 farm businesses in England.
Initial weights are applied to the Farm Business Survey records based on the inverse sampling fraction for each design stratum (farm type and farm size). Dataset table 16 from the Farm Accounts in England publication shows the distribution of the sample compared with the distribution of businesses from the 2024 June Survey of Agriculture. These initial weights are then adjusted, using calibration weighting, so that they can produce unbiased estimates of a number of different target variables. These variables have been updated due to the BPS data no longer being available in 2024/25. The detailed technical note on the weighting methodology has been updated to reflect the changes in the calibration model. More detailed information about the Farm Business Survey can be found on the technical notes and guidance page. This includes information on the data collected, information on calibration weighting and definitions used within the Farm Business Survey.
The data used for this analysis is from those farms present in the Farm Business Survey that have completed the energy module. In 2024/25 this subsample consisted of 1,124 farms (79% of the full sample). This subsample has been reweighted using a method that preserves marginal totals for populations according to farm type and farm size groups. As such, values shown in this publication may not exactly match results calculated using the main FBS weights.
6.3 Accuracy and reliability of the results
As it is impractical to survey the entire population of farms, estimates derived from the Farm Business Survey data are inherently subject to sampling error. This is a core principle in statistical survey methodology, which aims to infer population parameters by obtaining a representative sample through carefully designed sampling techniques. To quantify sampling error and provide a measure of uncertainty, this publication presents 95% confidence intervals for estimated means. These intervals, shown in the tables and as error bars in bar plots, indicate the range within which we expect the true population mean to lie for 95% of similarly constructed samples. Narrower confidence intervals typically indicate larger sample sizes or less variability within the sample, thereby offering more precise estimates of the population mean. Conversely, wider confidence intervals often result from smaller sample sizes or greater sample standard deviations, signalling less precision. These wider intervals should be interpreted with greater caution. Statistically, a confidence interval provides a plausible range for the true population mean based on the sample data. Specifically, a 95% confidence interval reflects a process that, under repeated sampling, would contain the true population mean in 95% of such intervals, rather than indicating a 95% probability for any single interval to include the population mean.
Percentage changes may not necessarily agree with the difference of their components due to rounding.
7 Definitions
Carbon audit
Carbon auditing, also known as carbon footprinting or carbon accounting, is the process of assessing and quantifying the amount of greenhouse gas emissions produced directly or indirectly by an individual, organisation, product, or event. In the context of this publication, it is the emissions of the farm business. It involves measuring and calculating the total amount of greenhouse gases emitted as a result of on-farm of activities.
First-time carbon audits allow for the creation of a baseline and identify opportunities to reduce future emissions. Continued assessments can track how actions taken have impacted these emissions and provide advice for further improvements.
Farm area
This area classification is the area designated to belong to the farm business (including woodland, roads and buildings), any land that is leased to the farm on either a permanent basis or part of a formal tenancy agreement. It does not include land rented out but does include land rented in.
Farm business size
Farm business size is classified using the Standard Labour Requirement (SLR), rather than by Standard Output grouping or land area. The SLR of a farm represents the normal labour requirement for all the farm’s cropping and livestock activities under typical conditions. This is measured in Full Time Equivalents (FTE), which is the number of full-time workers required. The SLR is calculated from standard coefficients applied to each enterprise on the farm. The standard coefficients represent the input of labour required per head of livestock or per hectare of crops for enterprises of average size and performance.
The most recent update to SLR coefficients was in 2024, which was based on data from the 2019/20 to 2022/23 surveys. Before this, the previous update was in 2009, which was based on data from the 2004/05 to 2007/08 surveys.
Table 7.1 Standard Labour Requirement (SLR) of each farm business size category
| Farm business size | SLR |
|---|---|
| Part-time | Less than 1 FTE |
| Small | 1 to less than 2 FTE |
| Medium | 2 to less than 3 FTE |
| Large | 3 to less than 5 FTE |
| Very Large | 5 or more FTE |
Farm type
This refers to the ‘robust type’, which is a standardised farm classification system.
In this publication, pig and poultry have been combined into one farm type.
Fuel types
Derv: An acronym of ‘diesel engine road vehicle’ and is also known as ‘white diesel’; this is the diesel fuel available to any road-going vehicle in the UK.
Kerosene: Mainly used for heating farm buildings and in crop dryers.
Liquefied petroleum gas (LPG): In the UK, LPG is typically made of just propane, hence the terms LPG and propane are frequently used to refer to the same product. As with kerosene, LPG is mainly used for heating buildings and crop drying machinery in farming, but it can also be used to power vehicles, for example, some forklifts, cars and lorries.
Mains electricity: Refers to electricity drawn from the national grid for use on the farm business; electricity generated from generators or renewable energy is not considered in the electricity fuel use.
Mains gas: The rural nature of farm businesses means that mains gas is not common, however, there are some farms connected to the gas distribution network. Mains gas is mainly used for heating buildings and cooking.
Red diesel: Also known as ‘gas oil’ or ‘rebate diesel’, it is subject to lower fuel tax then derv and is reserved solely for off-road vehicles. Red diesel is the main fuel used in tractors and other farm vehicles and is also used for heating.
Residual fuel oil (RFO): Also known as heavy fuel oil or bunker oil, RFO is the leftover oil after the hydrocarbons of higher quality (such as kerosene, gasoline and diesel) are extracted from crude oil. Currently, the main users of RFO are large marine vessels, where it is the main fuel type, and some power plants. In agriculture, use of RFO will be limited to farms that have older heating installations still in use.
Fuel use, electrical use and renewable energy generation
There are some instances where it is not possible to get accurate values from a farm. In cases where the data is still reliable, the research officer provides an estimate. In cases where the data is not reliable (but are confirmed users) the farms will be included in the data unavailable band of breakdowns.
Fuel use includes fuel used by the farm business directly and any fuel used by contractors.
Renewable energy types
Anaerobic Digestion: A natural process in which micro-organisms break down the organic matter found in wet biomass waste (such as animal manure and slurry) in the absence of oxygen, to produce biogas (mainly a mixture of around 60% methane and 40% carbon dioxide) and digestate (a nitrogen rich fertiliser). In a farming context, the biogas collected from an anaerobic digester can be used within the farm business (e.g. heating) or sold to third parties.
Battery Storage: Using batteries to store the renewable energy generated, for use at a later time.
Combined Heat and Power: Units generate electricity and heat using fuel that would typically be used only to generate either heat or electricity. For example, biogas when used only for heating, would fall into the anaerobic digestion category, but when used to provide both, it falls into the combined heat and power (CHP) category. CHP units can be fitted in domestic (micro-CHP) or large non-domestic (packaged or mini-CHP) buildings.
Renewable heat technologies: Refers to technologies that use renewable sources for the generation of heat as an alternative to fossil fuels. In the context of this publication, it covers a range of technologies including: Solid biomass (e.g. woodchips, pellets logs and straw), Solar thermal, Energy from waste, Ground and air source heat pumps, Deep geothermal.
Solar: Using photovoltaics (PV) to convert daylight into electricity.
Wind & Hydroelectric: Wind power generation is the process of converting the kinetic energy of wind into electricity using wind turbines. Hydroelectric power generation is the process of producing electricity by harnessing the kinetic energy of moving water. Micro or mini-hydro is the term used for installations generating power from harnessing the energy in flowing or falling water, usually referring to schemes with a generating capacity of below 100 kW – many of the schemes considered at farm scale are in this category. Smaller schemes, generating below 5 kW are often referred to as pico-hydro.