Economic and fiscal outlook – October 2026
Updated 30 October 2026

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/publications/october-2026-economic-and-fiscal-outlook/economic-and-fiscal-outlook-october-2026
Foreword
This Economic and fiscal outlook (EFO) sets out our central forecast, alongside the risks and uncertainties that surround it, for the five years to 2031-32. It takes account of recent data and other developments, alongside government policies announced since our last forecast – up to and including the October 2026 Budget. The forecasts presented in this document represent our view as the three independent members of the OBR’s Budget Responsibility Committee (BRC). We take full responsibility for the judgements that underpin them and for the conclusions we have reached.
As always, we have been greatly supported in our work by the staff of the OBR. We are very grateful for their hard work and expertise. We have also drawn on the work and expertise of officials across government in preparing these forecasts. We are grateful for their engagement and insight.
We present the economy forecast in calendar years and produce quarterly paths. The fiscal forecast is typically presented on a financial year basis which runs from April to March. For the current fiscal year, 2026-27, outturn data is incomplete and is, therefore, presented as an OBR forecast. Our online detailed forecast tables, and charts and tables data files, detail the points where individual forecast variables are outturn and forecasts.
On 20 July, we provided an assessment of the outlook for the economy and public finances to the incoming Chancellor of the Exchequer, to support his initial preparations ahead of the Budget. This assessment was subsequently used for the initial round of our pre-measures forecast. The date for the Budget was then announced on 31 July, which provided more than the ten weeks’ notice required by the Memorandum of understanding between the Office for Budget Responsibility, HM Treasury, the Department for Work and Pensions and HM Revenue and Customs (MoU). After this, the timetable for the production of the forecast proceeded as follows:
-
Over the remainder of the summer, the OBR developed the pre-measures economic forecast, drawing on new data releases and other information available during this period. At various points, using the economic determinants from these forecasts (such as the components of nominal income and spending, unemployment, inflation, and interest rates), we commissioned updated forecasts from the relevant government departments for the various tax and spending items that in aggregate determine the position of the public finances. We discussed these in detail with the officials producing them, which allowed us to investigate proposed changes in forecasting methodology and to assess the significance of recent tax and spending outturn data.
-
The pre-measures economy forecast was completed on 8 September and was based on financial and energy market data averaged over the 10 working days to 19 August. This is a longer gap between the closure of the pre-measures economy forecast and publication of the final forecast than is set out within the MoU, and was requested by the Treasury to allow for greater policy decision-making time after receiving the final pre-measures forecast. We agreed to this change on the basis that it would also provide the OBR with greater time to effectively scrutinise the economic and fiscal impact of policy decisions, and to finalise and quality assure our analysis. We will review the effectiveness of this change with the Treasury ahead of our next forecast.
-
Once completed, the pre-measures economy forecast was sent to government departments to produce individual tax and spending forecasts and they returned them on the same day. These fed into a final pre-measures fiscal forecast that was completed on 18 September. The fiscal forecast is consistent with the ONS Public sector finances (PSF) release on 21 August, including ONS estimates of revisions that would arise in the 22 September release, as well as management information on tax receipts for August. In line with recent practice, we took a later window for interest rates in the fiscal forecast, over the five working days to 15 September. This results in very minor discrepancies between the economy and fiscal forecast which we judge to be immaterial.
-
The final pre-measures economic and fiscal forecast was sent to the Chancellor on 18 September. At the request of the Treasury, this was the only pre-measures economic and fiscal forecast round that was shared with them during this forecast. This represented a change from the process followed in recent years, when we shared interim rounds of the pre-measures economic and fiscal forecasts with the Treasury as they were completed. No further material adjustments were made to our economy or fiscal forecasts after this, other than to take account of the impact of policy measures provided by the Treasury. We always reserve the right to reopen our pre-measures forecasts in the event of exceptional circumstances which lead to a significant and structural change in the economic and fiscal outlook. We did not judge that to be the case at this event.
-
In parallel to the production of the forecast, we scrutinised the costing of a number of individual tax and spending measures announced since the March 2026 forecast. As usual, OBR staff and the BRC requested further information and/or changes to many of the draft costings prepared by HMRC, DWP and other departments.
-
We made an initial assessment of the economic and fiscal effects of the emerging Budget policy package that was provided by the Treasury on 25 September. We incorporated this package into an initial post-measures forecast, to provide an early view on the effect of policy measures on the economy and public finances, which we sent to the Chancellor on 2 October. This forecast round was produced using our internal ready-reckoner models rather than being sent to departmental forecasters.
-
In line with the agreed timetable, on 9 October the Treasury provided the final package of measures that could cause movements in our economy forecast. We sent the resulting final economy forecast to the Treasury on 16 October and a near-final fiscal forecast on 20 October. Final policy decisions, that would only affect the fiscal forecast, were returned by the Treasury on 20 October, and our forecast was then finalised and sent to the Treasury on 22 October.
The Treasury made a written request, as provided for in the MoU between us, that we provide the Chancellor and an agreed list of special advisers and officials with a near-final draft of the EFO on 22 October. This allowed the Treasury to prepare the Chancellor’s statement and accompanying documents. We also provided pre-release access to the full and final EFO on 26 October.
The agreed forecast timetable was largely adhered to. Small changes were made to the parameters of one policy measure following the costings certification deadline, meaning that, although we have no concerns about the methodology used, we have not been able to certify this costing. We have used the Government’s estimates of its fiscal impact and will return to it at the next forecast. In addition, two policy measures with direct impacts on our economy forecast were altered after it had been finalised. Had we been able to incorporate these, they would have only made a small difference to our final economy forecast.
During the forecasting period, the BRC held dozens of scrutiny and challenge meetings with officials from other departments, in addition to numerous further meetings at staff level and with external stakeholders. We have been provided with all the information and analysis that we requested and have come under no pressure from Ministers, advisers, or officials to change any of our conclusions. A full log of our substantive contact with Ministers, their offices, and special advisers since we published our previous forecast in March 2026 can be found on our website. This includes the list of special advisers and officials who received the near-final draft of the EFO on 22 October.
In this EFO, we present a detailed central forecast in line with the responsibility in our primary legislation to assess the extent to which the fiscal mandate has been, or is likely to be, achieved. The fiscal mandate is currently defined as a target in the third year of our forecast. This requires us to produce a precise forecast for a set of very uncertain outcomes. For example, the borrowing forecast represents the difference between over £1.5 trillion each of receipts and expenditure by the end of the forecast period. We therefore also present a range of different indicators of uncertainty to illustrate the potential effects of alternative scenarios, sensitivities and risks that inevitably lie around the central forecast. For fiscal policy-makers, and those who scrutinise fiscal policy, we see this analysis as being as important as the central forecast. The central forecast remains our best estimate of the central outlook for the economy and public finances, within the constraints in which we are required to make it.
We would be pleased to receive feedback on any aspect of the content or presentation of our analysis. This can be sent to feedback@obr.uk.
The Budget Responsibility Committee
Professor Jonathan Haskel CBE, Professor David Miles CBE and Tom Josephs
Chapter 1: Executive summary
Overview
1.1 The UK’s economic and fiscal position remains very challenging. Since 2008, repeated adverse shocks have contributed to persistently weak GDP growth and elevated levels of government borrowing. This has resulted in a sharp increase in government debt as a share of GDP, to a level that is high by both recent historical and international standards.
1.2 There have been further adverse developments since our March forecast, with both interest rates and energy prices rising significantly. As a net importer of energy, the rise in energy prices constitutes a negative terms-of-trade shock for the UK, which pushes up on inflation and lowers real household disposable incomes. In the central forecast – the mid-point of a wide range of possible outcomes – CPI inflation is 3½ per cent in 2027, compared to 2 per cent expected in March. Real GDP growth slows from around 1¼ per cent in 2026 to 1 per cent in 2027 – the latter around a ½ percentage point lower than the March forecast. Assuming energy prices subsequently decline in line with market pricing, inflation returns to 2 per cent by 2028 and GDP returns to the level expected in March by 2030. After falling slightly in the near term, per person real household disposable income in 2030-31 is over ¾ per cent below our March forecast and only 2 per cent above its pre-pandemic level.
1.3 The rise in interest rates and increase in the inflation forecast leaves pre-measures borrowing an average of £11 billion per year higher than in March. The direct effects of policy measures further increase borrowing by £8 billion in 2026-27, £4 billion in 2027-28, and £0.4 billion in 2028-29, and then reduce borrowing by £7 billion, on average, in the years thereafter. Overall, while borrowing as a share of GDP is still forecast to decline over the forecast to just under 2 per cent of GDP, these changes slow the near-term pace of consolidation compared to previous plans. Public sector net debt peaks around 97 per cent of GDP in 2028-29, before falling slightly to 96 per cent in 2031-32. In the central forecast, the fiscal mandate for the current budget to be in surplus in 2029-30 is met by a margin of £15 billion. The supplementary target for public sector net financial liabilities (PSNFL) to be falling as a share of GDP in 2029-30 is met by a margin of £24 billion.
1.4 The outlook for the economy and public finances is uncertain, with significantly better or worse outcomes of broadly equal probability. If energy prices reach a higher and more sustained peak, borrowing could be £17 billion above the central forecast in 2027-28, while a lower energy price path could reduce borrowing by £12 billion. A one per cent change in interest rates could raise or reduce government debt interest costs by £16 billion. If productivity growth were 0.5 percentage points higher or lower than forecast, borrowing could reach £50 billion lower or £40 billion higher. Significant pressures on departmental spending include higher inflation, public sector pay, and policy ambitions such as defence.
Economic and fiscal context
1.5 Adverse shocks have continued to hit the UK since the 2008 global financial crisis, including rising barriers to trade after EU exit, the pandemic, and the 2022 energy price spike. These shocks, alongside other structural trends, have resulted in weak growth in GDP per person, periods of elevated inflation, and low growth in real household disposable incomes. On top of these, since we finalised our March forecast, there has been another spike in energy prices and a significant rise in interest rates. Gilt yields have returned closer to their long-run averages following a period of exceptionally low rates after the financial crisis.
1.6 These adverse shocks and low economic growth have resulted in elevated levels of government borrowing and debt in the UK. Chart 1.1 shows that UK borrowing has followed a similar trend to the G7 and advanced economy average over the past two decades but at a consistently higher level. As a result, UK government debt as a share of GDP has increased by more than in any other G7 economy, rising from 38 per cent in 2006 to reach 93 per cent in 2026. The cost of servicing this debt has also increased sharply recently – from 1.7 per cent of GDP (£39 billion) in 2019-20 to 3.5 per cent of GDP (£109 billion) in 2025-26. In the IMF’s forecasts, UK borrowing falls to close to the advanced economy average by 2031, which would lead to debt stabilising at around the G7 average.
Chart 1.1: General government borrowing and net debt in advanced economies
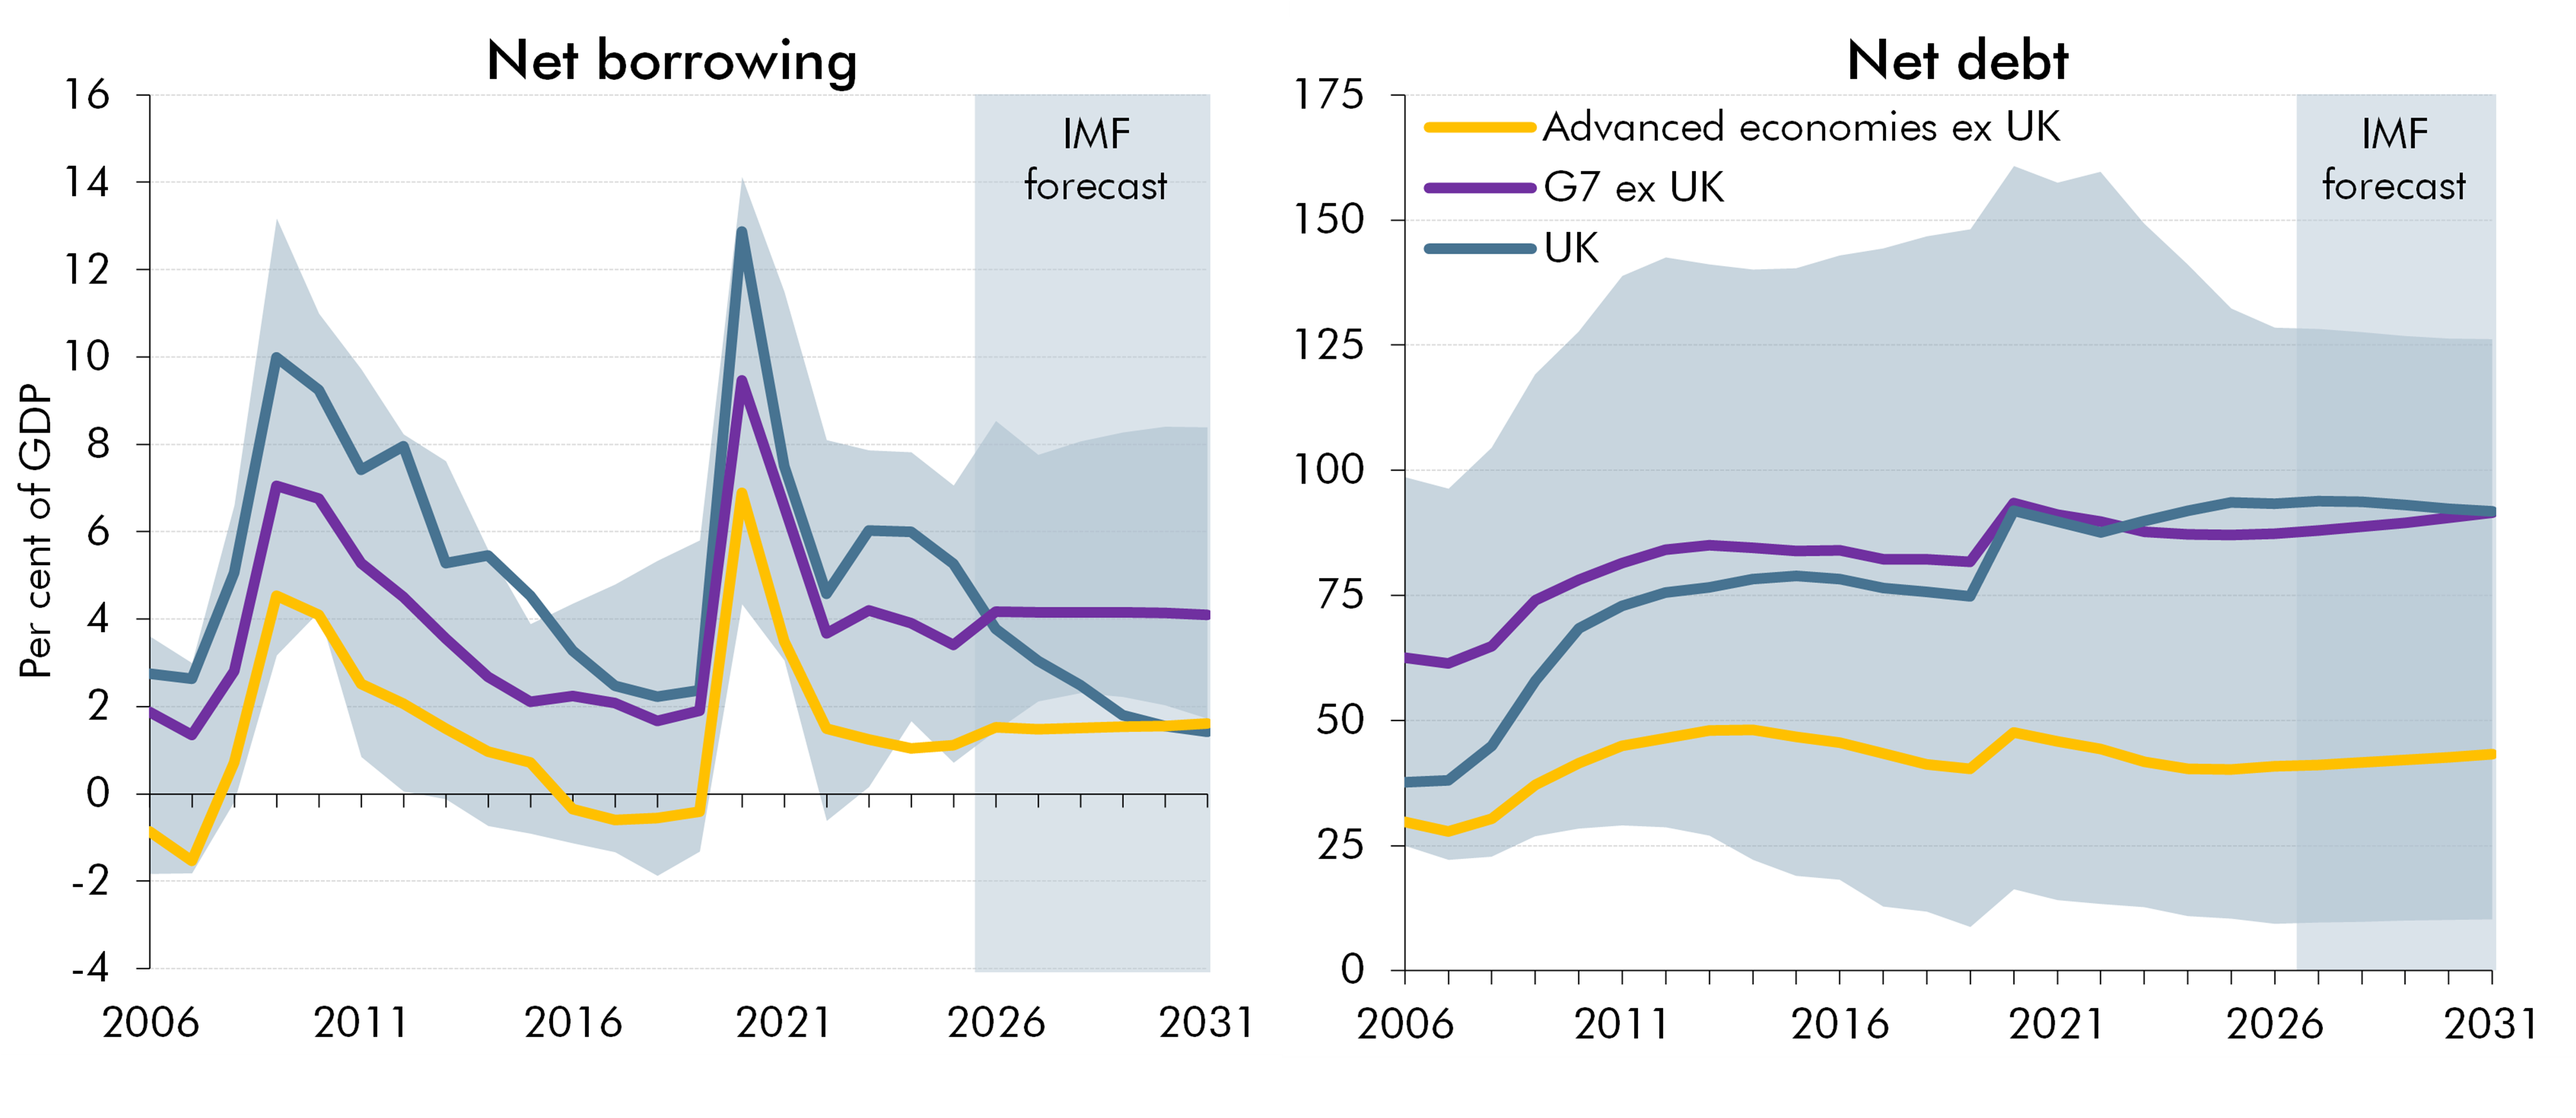
Note: This chart shows IMF outturn (2006-2025) and forecast (2026-2031) for general government net borrowing and net debt which excludes the activity of public corporations. The lines show borrowing and debt for the UK, the unweighted G7 average excluding the UK and the unweighted advanced economy average excluding the UK. The advanced economies included in the average are those detailed in the IMF World economic outlook. The swathe shows the range of borrowing and debt for G7 economies excluding the UK.
Source: IMF, OBR
Economic outlook
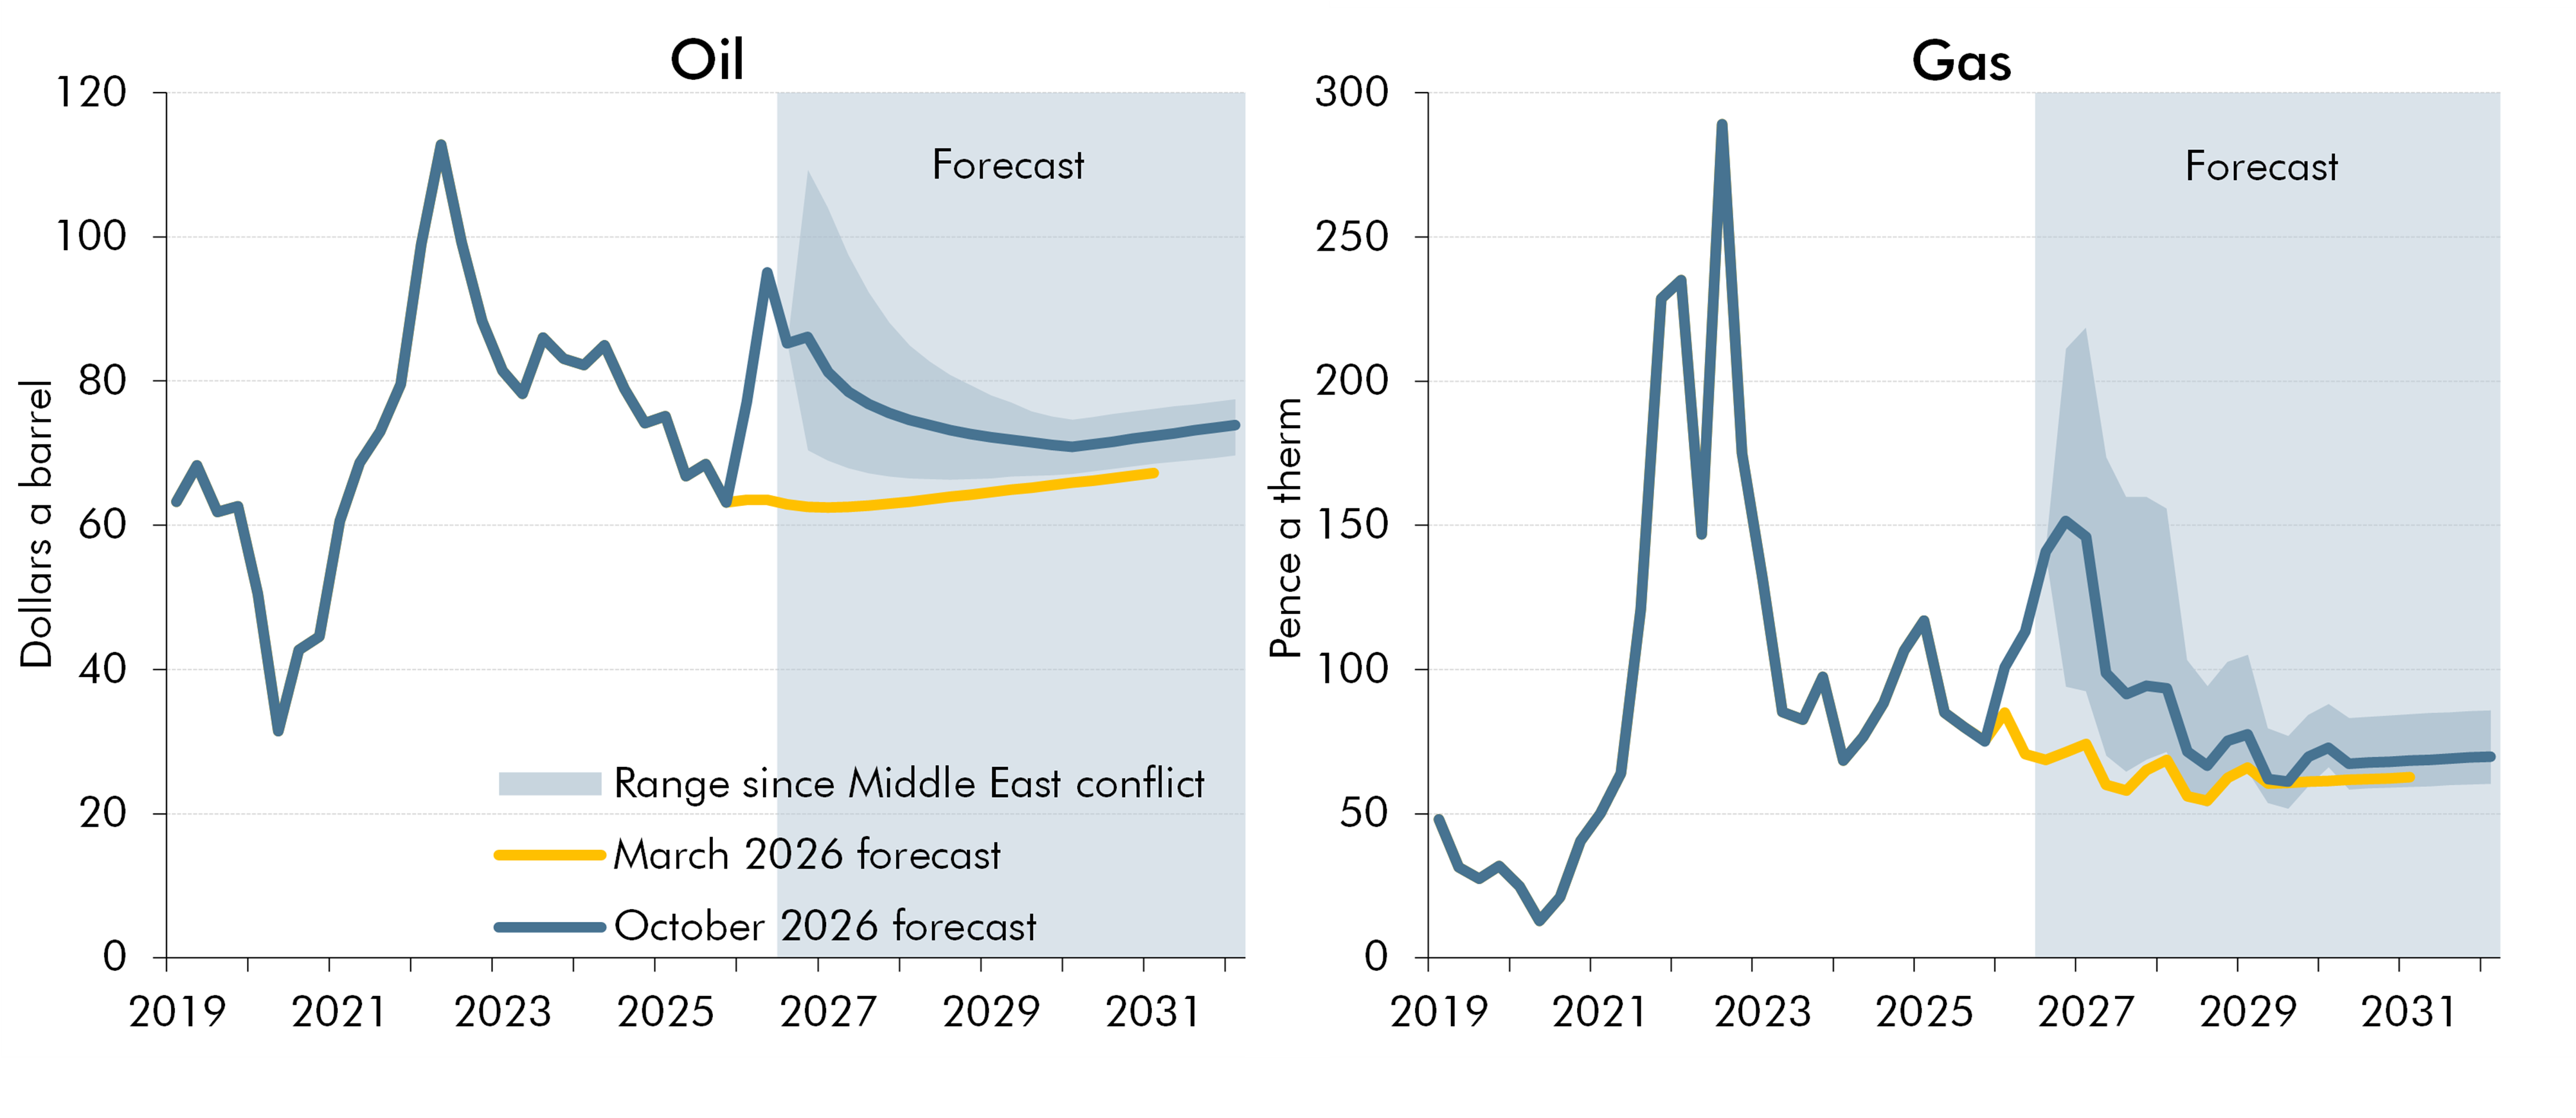
1.7 Energy prices have increased sharply since our last forecast in March. The left panel of Chart 1.2 shows that market pricing, at the time that our forecast was conditioned, implied that oil prices would fall from their peak of 95 dollars a barrel in the second quarter of this year to just above 70 dollars a barrel by late 2028 and remain around that level thereafter. The right panel shows that gas prices were expected to peak at around 150 pence a therm at the end of this year before falling back to around 70 pence a therm from mid-2028. Compared with the March forecast, market pricing for oil and gas is significantly higher in the near term, by 30 and 80 per cent respectively, but in our central forecast they are only around 10 per cent higher in 2030. Oil and gas futures have increased further since we took market expectations – at the time of finalising this report, they were close to the top of the range since the beginning of the Middle East conflict. Given the uncertainty around the outlook for energy prices, we have produced scenarios assessing the potential economic and fiscal implications of alternative paths for these in Chapter 7.
Chart 1.2: Energy prices
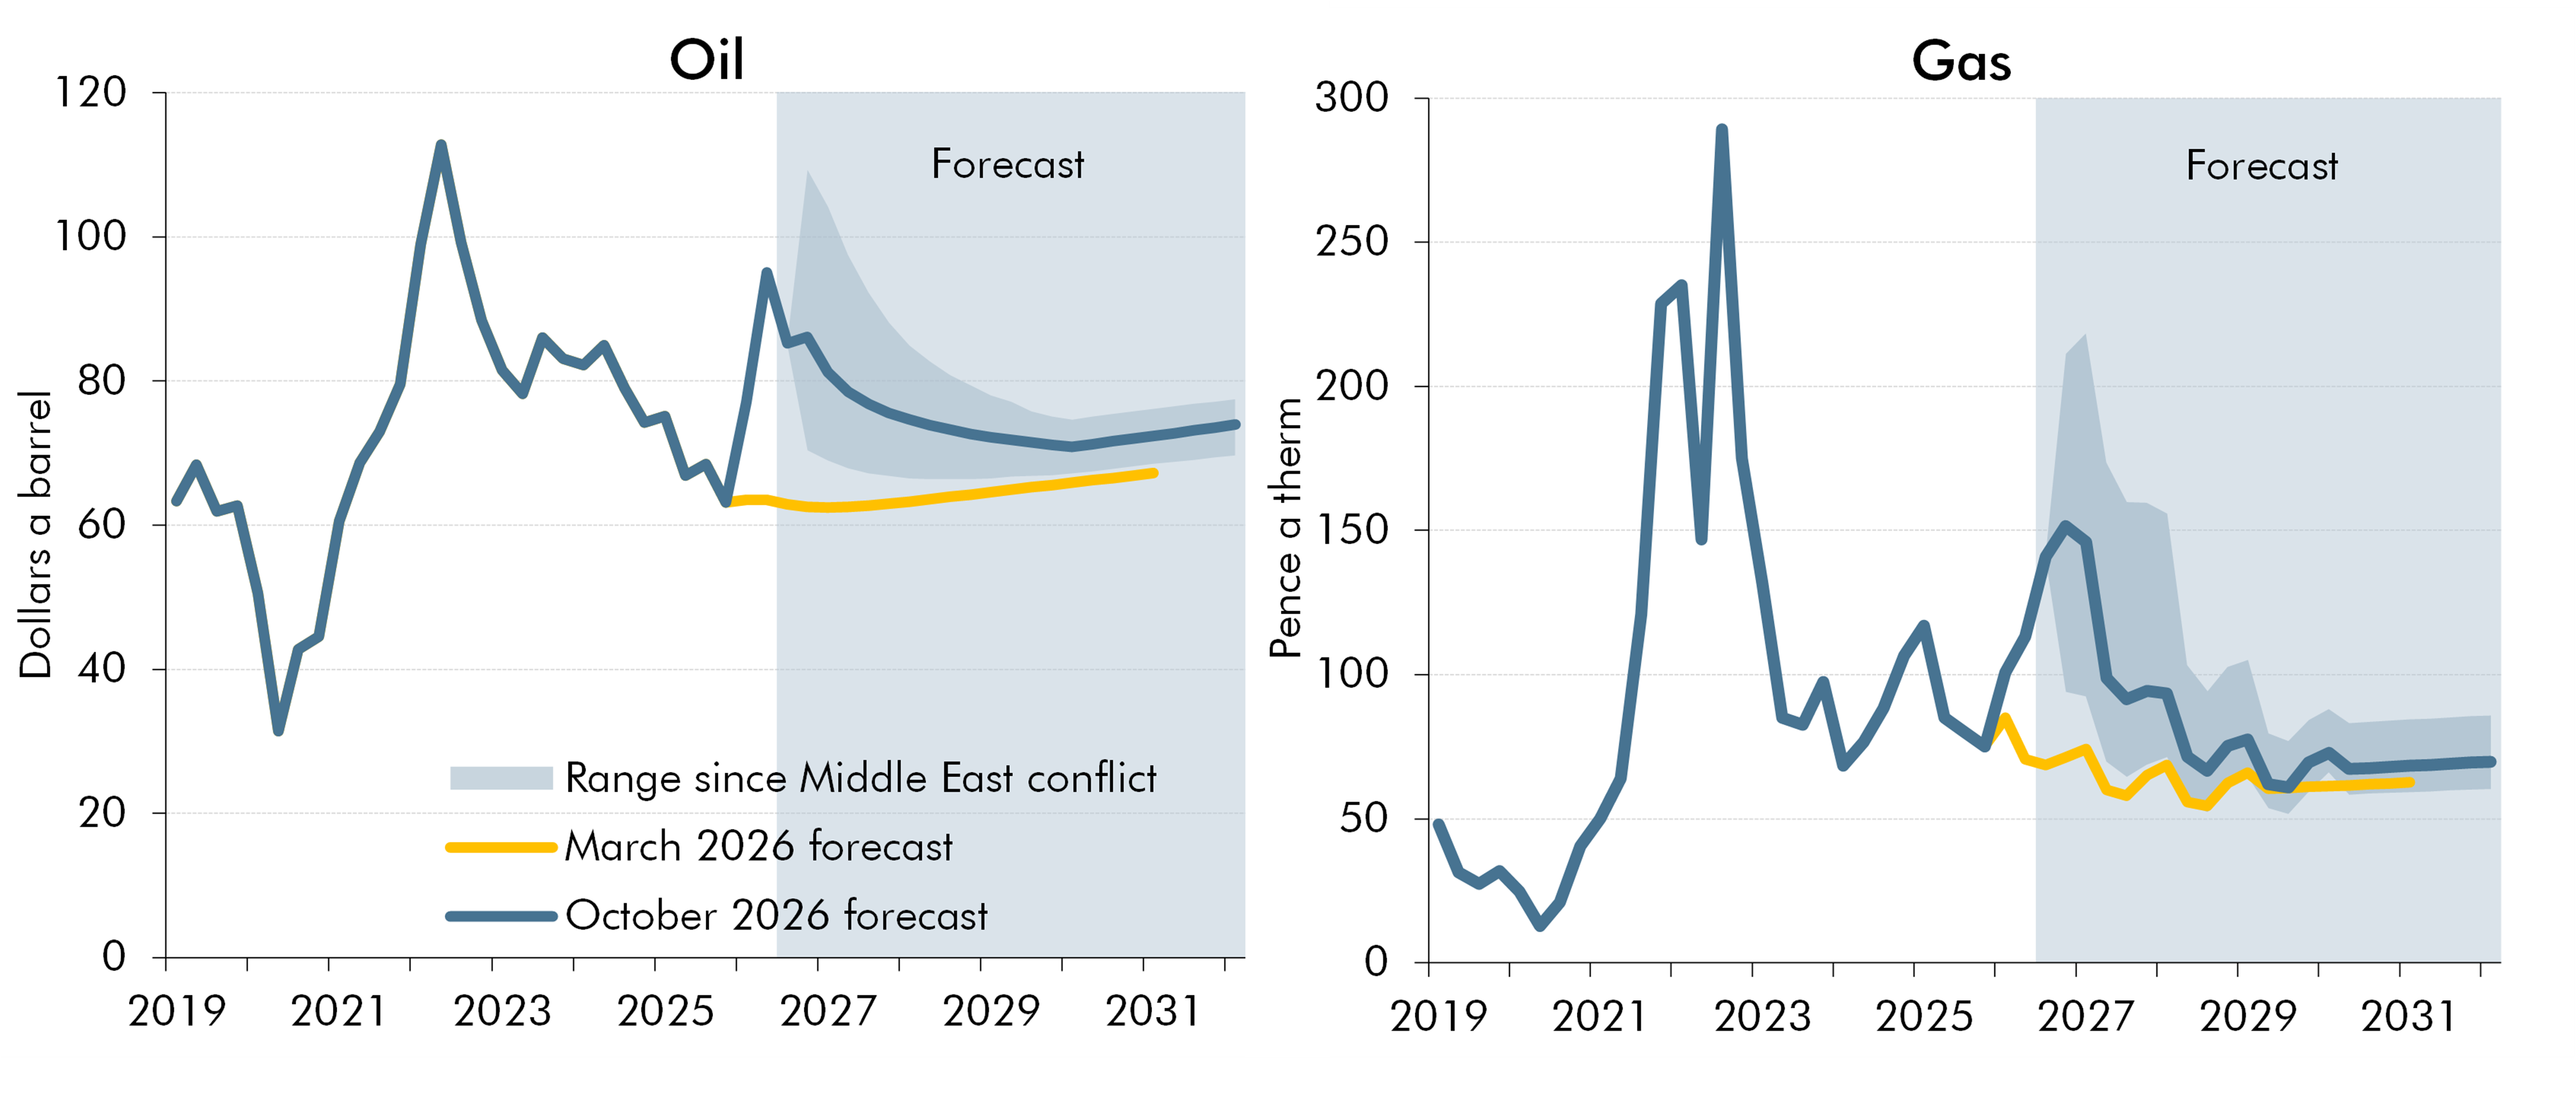
Note: October 2026 forecast uses the 10 working days to 19 August and March 2026 forecast uses the 10 working days to 22 January. Range since Middle East conflict is range between 2 March and 20 October.
Source: Bloomberg, Ofgem, OBR
1.8 The future market-implied path of Bank Rate and gilt yields has also increased significantly since our March forecast (Chart 1.3). Our central economy forecast is conditioned on Bank Rate reaching just over 4¼ per cent by mid-2027 and just over 4½ per cent by the end of the forecast period, around ¾ and ½ a percentage point higher than our March forecast, respectively. In our fiscal forecast, which was finalised later than the economy forecast, Bank Rate is a further ¼ percentage point higher on average. Gilt yields have risen substantially across all maturities since our March forecast.
Chart 1.3: Bank Rate and gilt yields
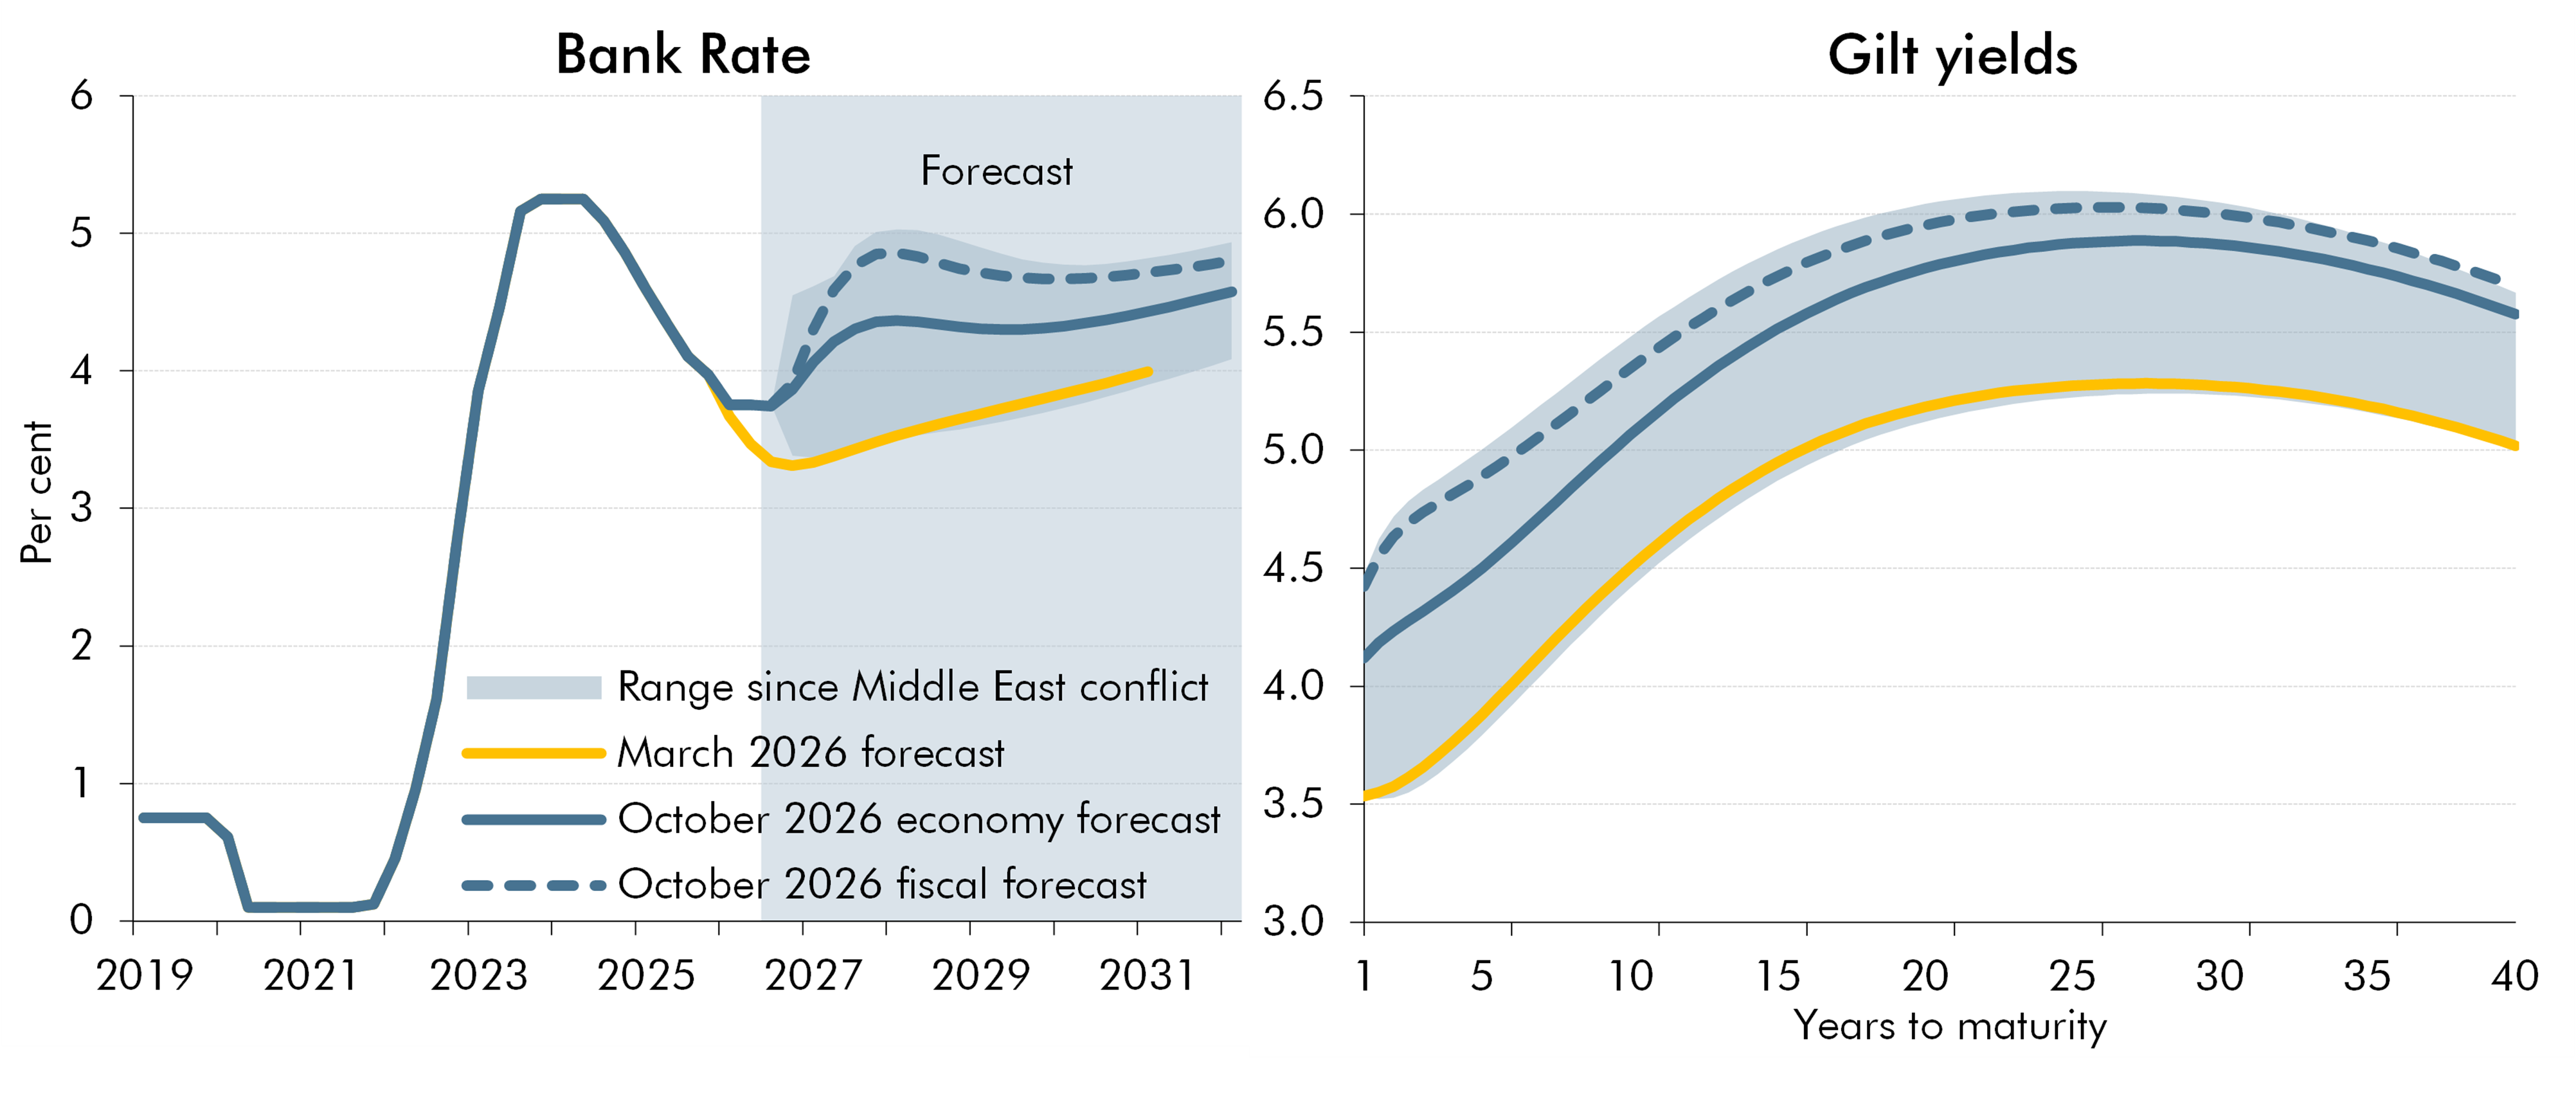
Note: October 2026 economy forecast uses 10 working days to 19 August, October 2026 fiscal forecast uses 5 working days to 15 September, and March 2026 forecast uses the 10 working days to 22 January. Range since Middle East conflict is range between 2 March and 20 October.
Source: Bank of England, OBR
1.9 As Chart 1.4 shows, in our central forecast, higher energy prices contribute to CPI inflation increasing to a quarterly peak of 3¾ per cent in early 2027. It is then forecast to fall to 2 per cent in 2028 as energy prices drop back. Inflation is about ¾ and 1½ percentage points higher in 2026 and 2027, respectively, than the March forecast and returns to target around one year later. This reflects the direct effect of higher energy prices on fuel prices and utilities, the indirect effect of energy prices as an input into the cost of other products, and some second-round effects of higher inflation through wage growth. But we judge that these second-round effects will be less inflationary than those following the previous energy price spike in 2022, as a significantly looser labour market restricts workers’ capacity to bargain for higher wages. This means that nominal wage growth in the central forecast is only around ½ and ¾ percentage points higher in 2026 and 2027, respectively, than in March.
1.10 The outlook for inflation is highly uncertain, including the extent to which energy prices generate second-round effects through wages. This is important for the fiscal forecast given the high effective tax rate on labour income and frozen income tax thresholds. Based purely on past forecast errors, Chart 1.4 suggests that there is a one-in-five chance that CPI inflation in 2027 will be above 4½ per cent and a similar probability that it will be below 2½ per cent.
Chart 1.4: CPI inflation
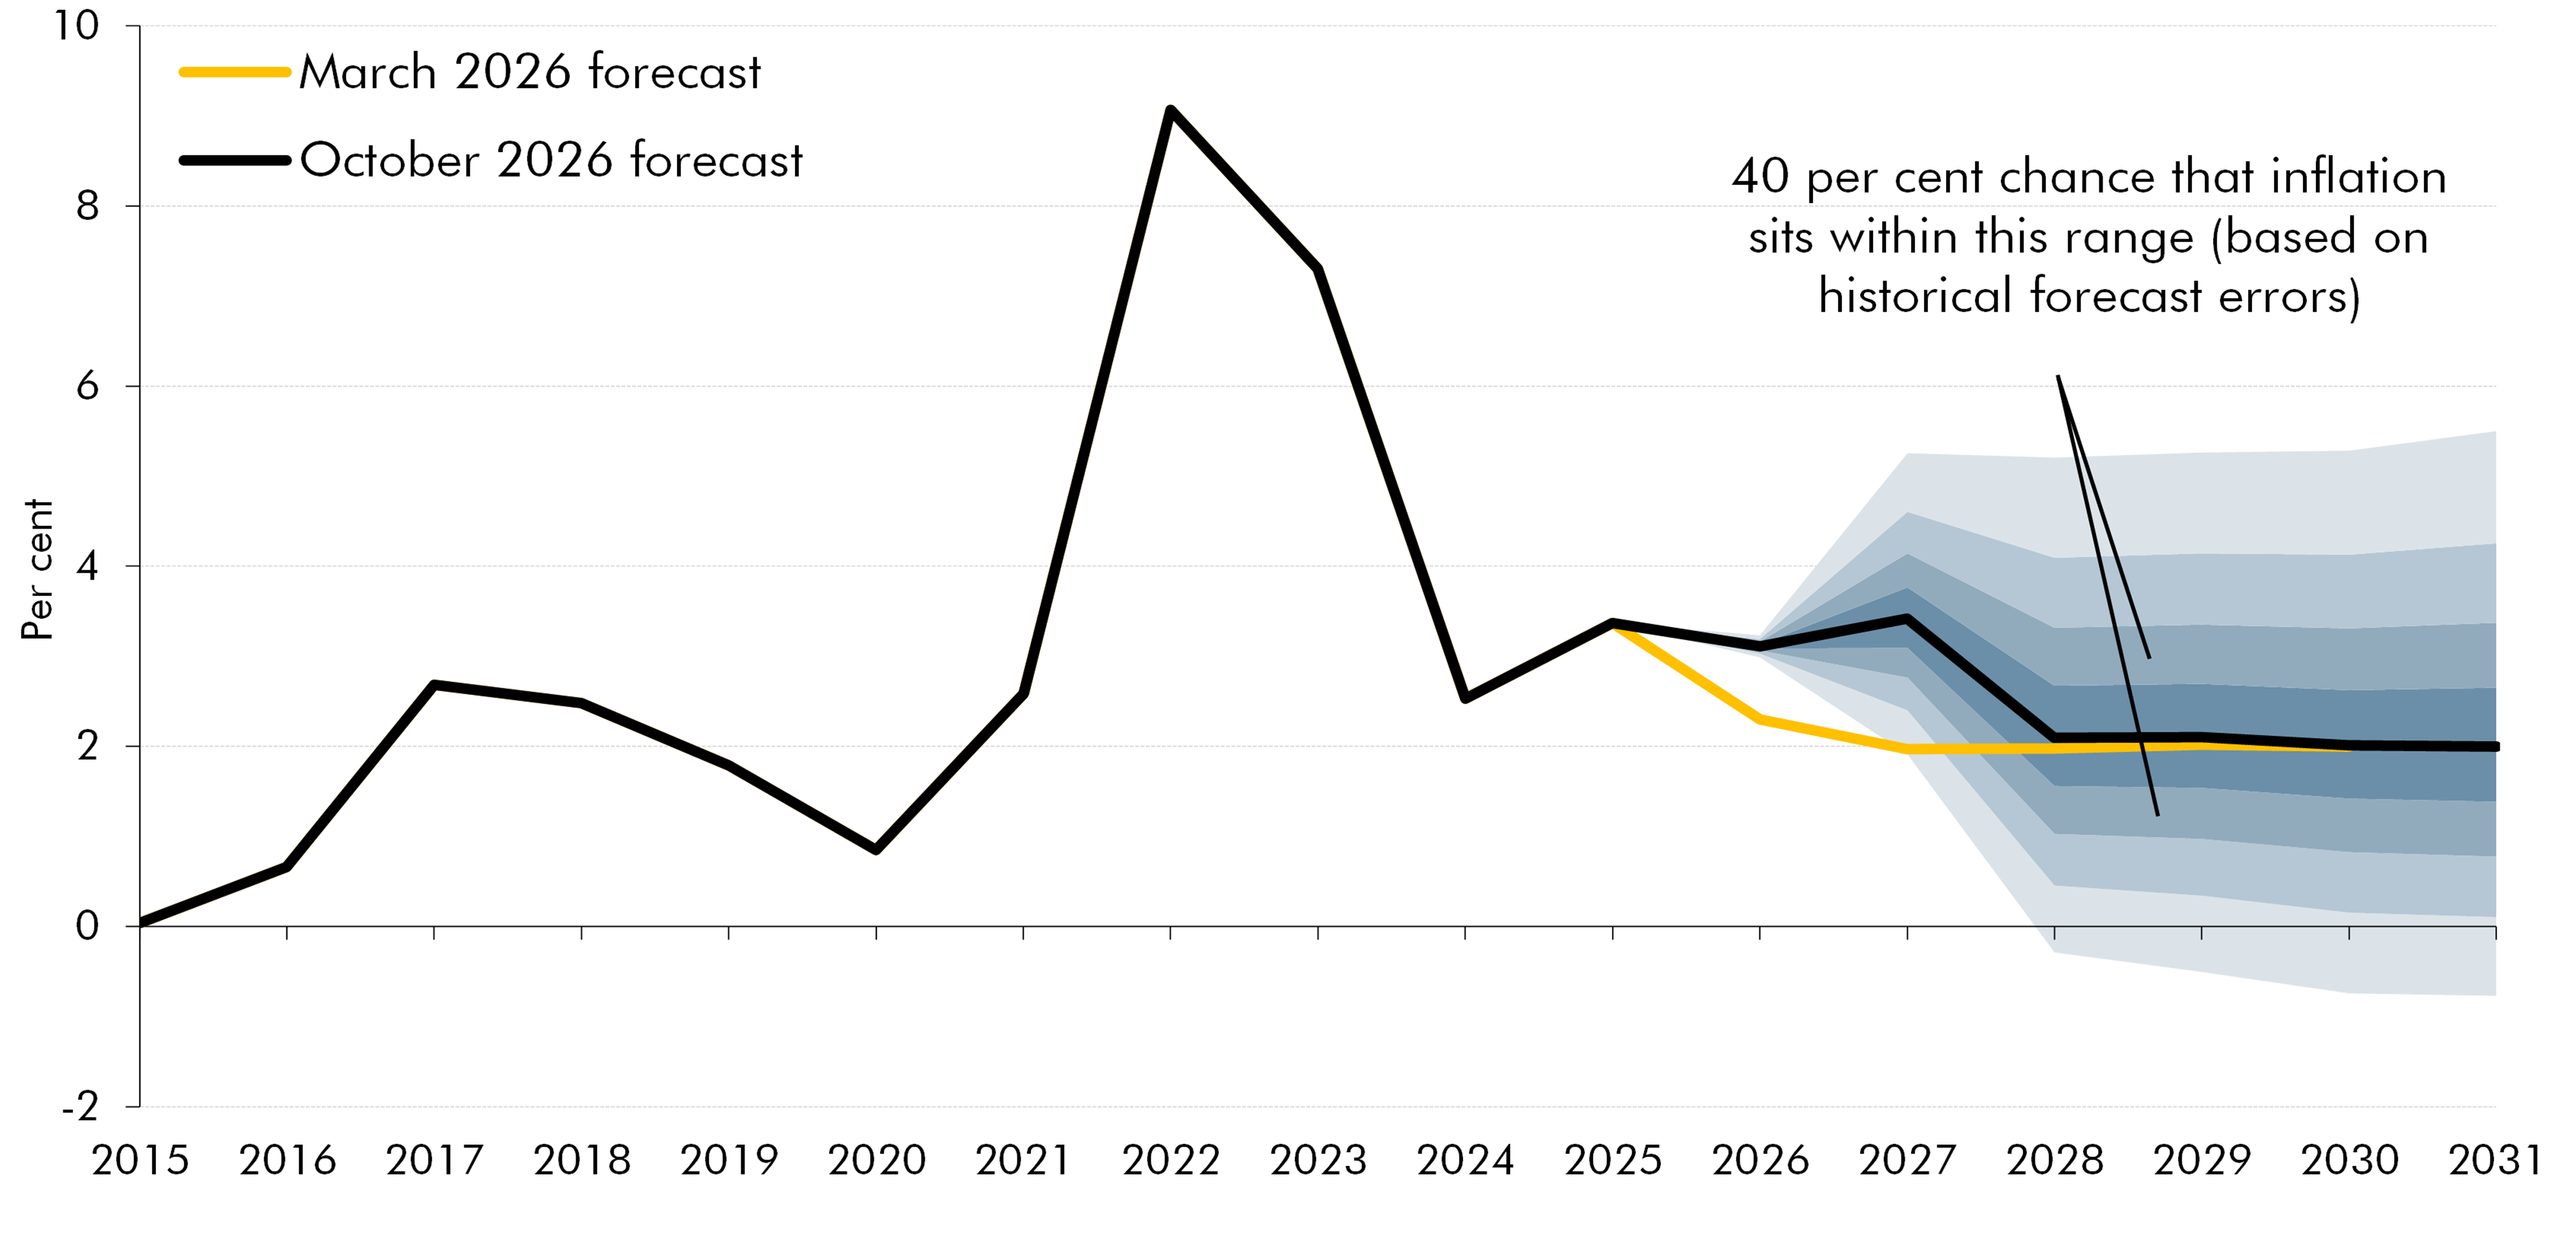
Note: The chart shows annual average CPI inflation. The forecast starts from 2026. The fan chart uses past forecast errors, assumes that these are representative of future errors, and does not take into account the current level of uncertainty. Successive pairs of lighter-shaded areas around our central forecast represent 20 per cent probability bands.
Source: ONS, OBR
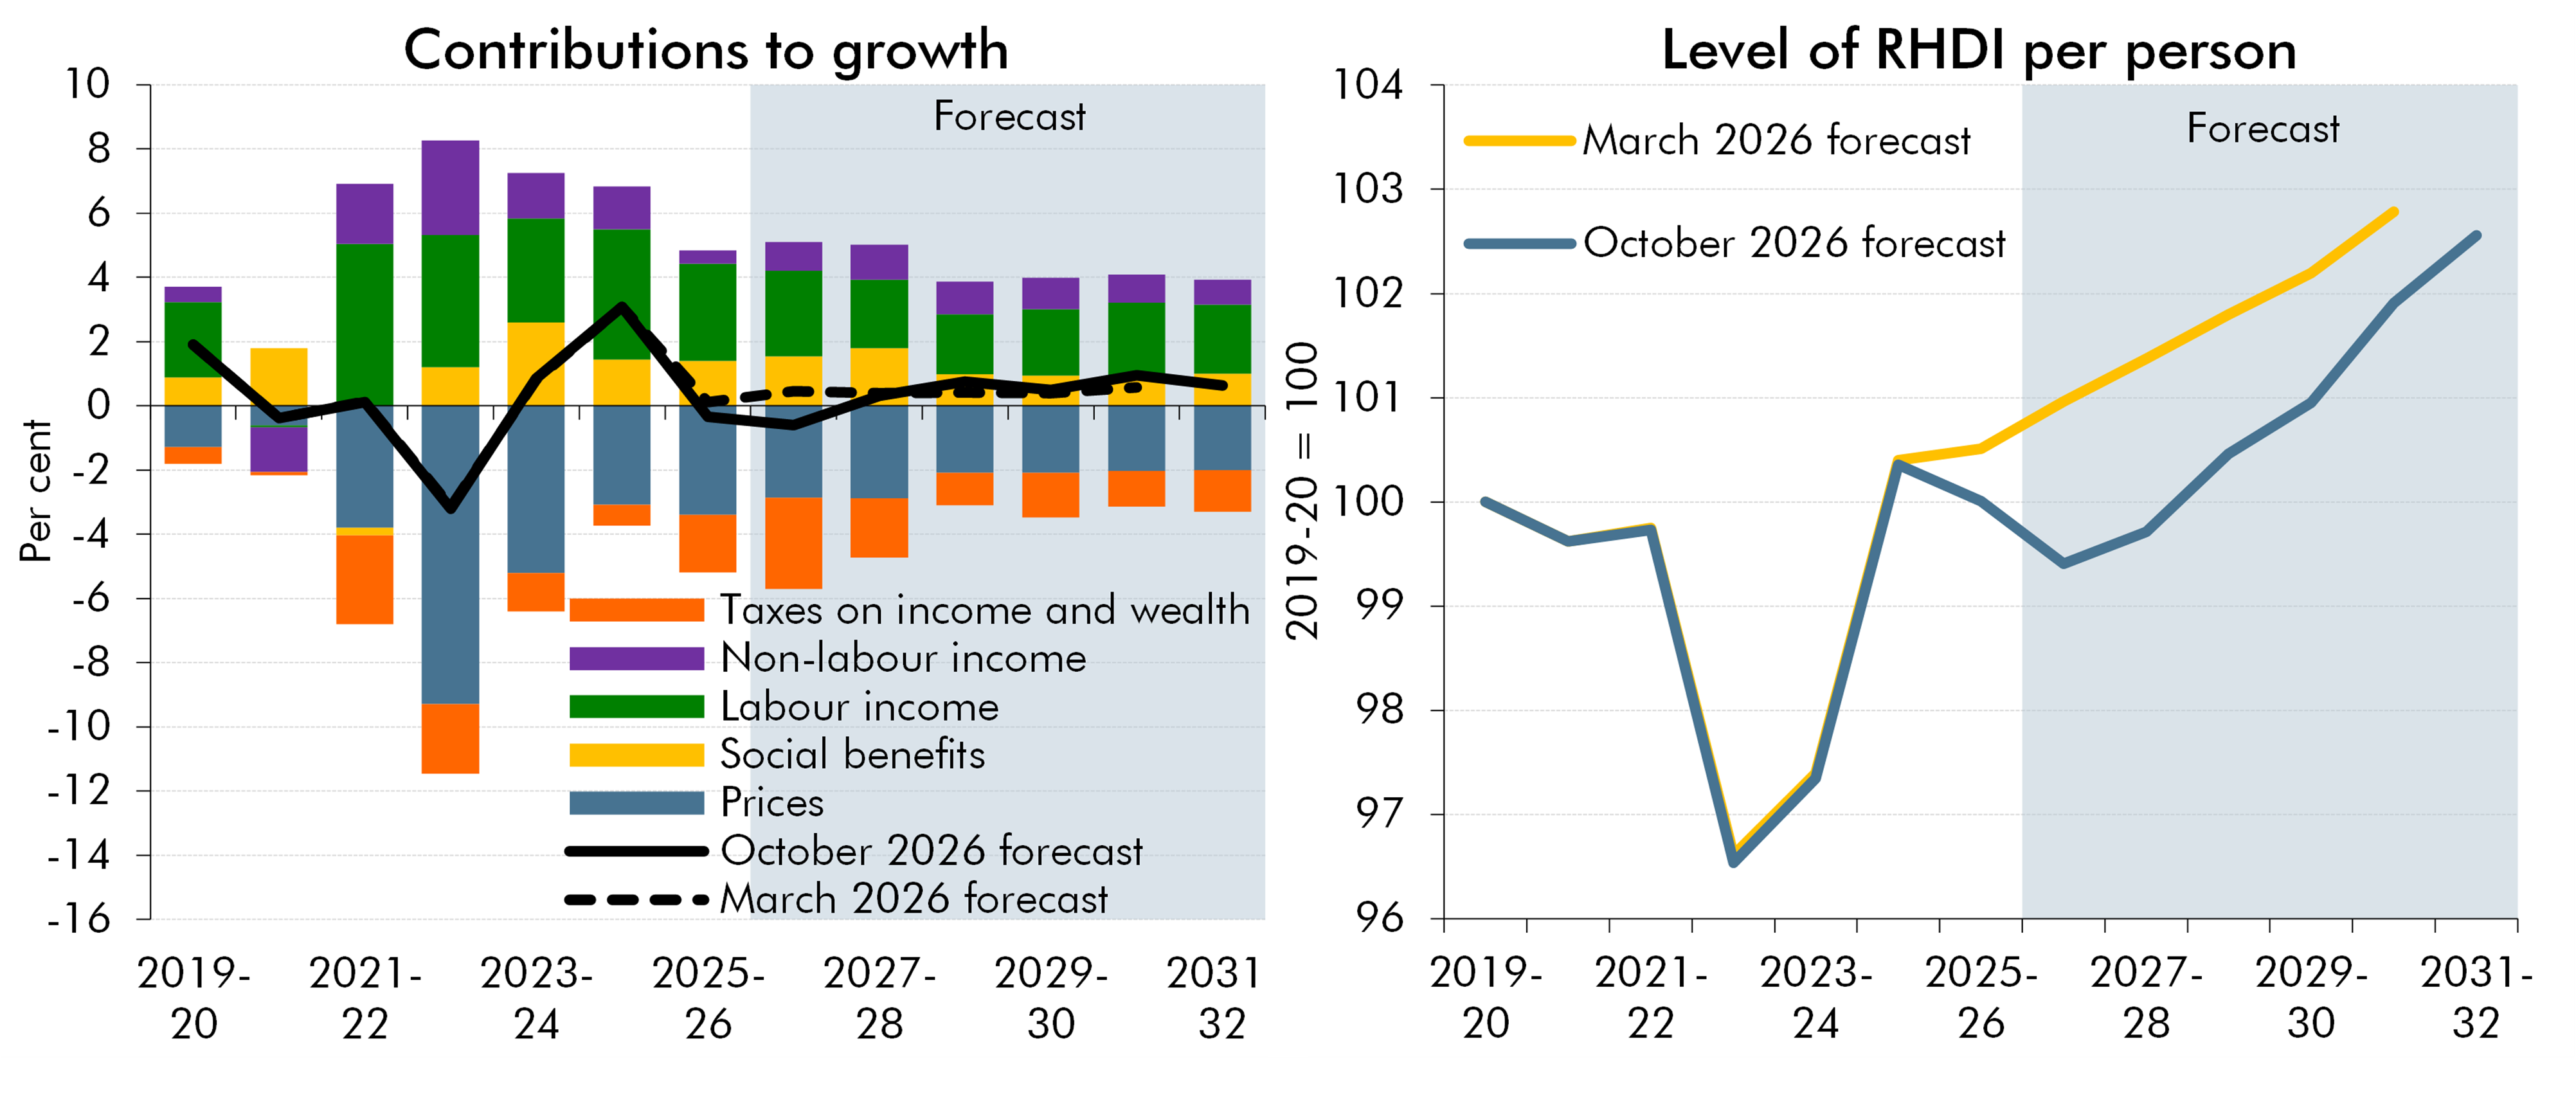
1.11 In the central forecast, limited second-round effects of externally driven inflation on nominal wages – and labour market looseness – means we expect no real earnings growth in 2027. Real wage growth then recovers to around ½ a per cent a year by 2030, as energy prices drop back. That medium-term growth rate is slightly below growth in output per worker as we expect firms to rebuild profit margins and the rate of return on capital to recover. Subdued real wage growth, alongside the combined effect of frozen income tax thresholds and higher nominal earnings growth, means we expect RHDI per person – an indicator of living standards – to fall slightly in the near term (Chart 1.5). RHDI per person then partially recovers as the energy price shock subsides. But, in 2030-31, it is only around 2 per cent above pre-pandemic levels and is about ¾ per cent below the level from our March forecast.
Chart 1.5: Real household disposable income per person
Source: ONS, OBR
1.12 Our central estimate of the level of potential output in the medium term is broadly unchanged from March. Recent GDP growth has been stronger than we expected – and we judge this to be structural – raising the starting level of potential output. We also have a slightly higher forecast for business investment – which raises capital deepening and productivity growth a little. Offsetting this, we expect net migration to be 70,000 lower on average per year, which has a small negative impact on our potential output forecast. But we judge that these migrants would have had broadly the same labour market characteristics as the domestic population, so the migration change has no impact on potential output on a per person basis. The higher starting point for potential output and the increased capital deepening forecast means that our central forecast for GDP per person has been revised up slightly in the medium term relative to March.
1.13 Our forecast for growth in total factor productivity in the medium term is unchanged relative to our March forecast. This is a highly uncertain judgement – and there is even uncertainty around the historical growth rates, which we explore further in Box 2.2. We have also assessed the impact of the Employment Rights Act 2025 in this forecast. We judge that while it will likely have a negative impact on potential output, the size of the effect is too uncertain to make an explicit adjustment at this forecast.
1.14 We expect real GDP growth of around 1¼ per cent this year – slightly higher than in March as the UK economy has, so far, been resilient to higher energy prices. We anticipate growth of around 1 per cent in 2027 – down about ½ a percentage point from March – as it takes time for higher global energy prices and increased interest rates to weigh on activity. Based on energy prices falling back, as suggested by the market pricing that underpins our forecast, we expect GDP growth to then recover and for the level of GDP to be broadly unchanged from our March forecast by 2030. Over the forecast, average annual real GDP growth is largely unchanged from March at around 1½ per cent. We judge the risks around our central forecast are broadly balanced. Looking at the distribution of historical forecast errors shown in Chart 1.6, in 2027, there is a one-in-five chance that real GDP growth could be higher than 2¼ per cent and a similar chance that it contracts.
Chart 1.6: Real GDP growth
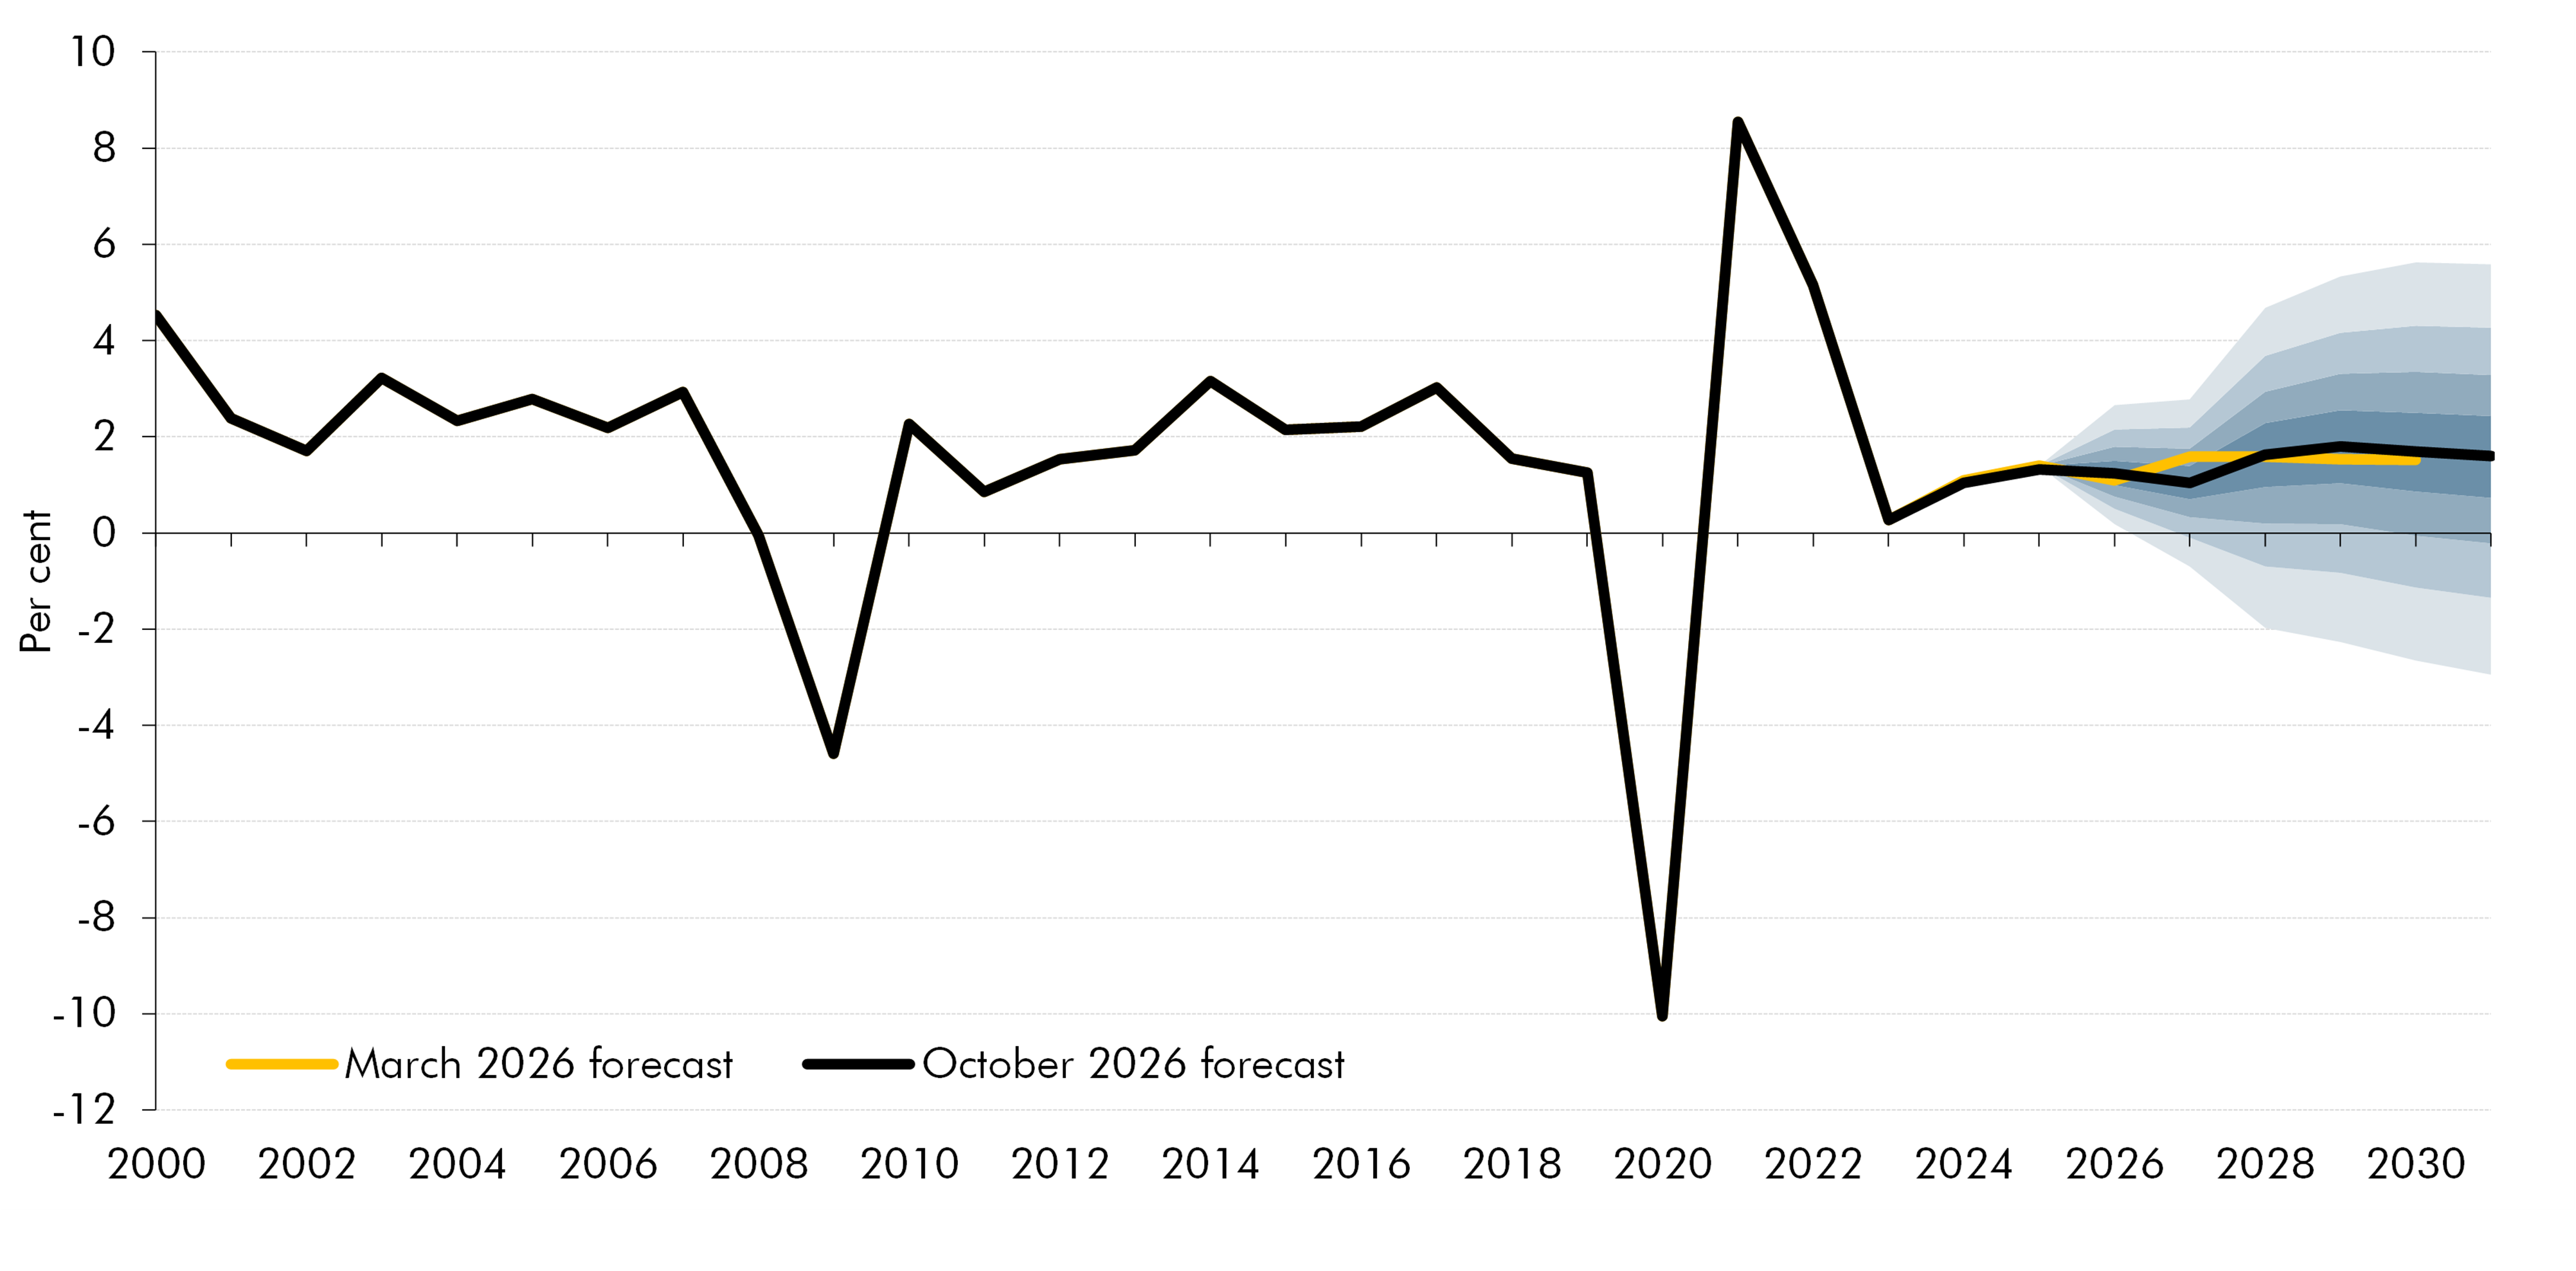
Note: The chart shows annual real GDP growth. The forecast starts from 2026. The fan chart uses past forecast errors, assumes that these are representative of future errors, and does not take into account the current level of uncertainty. Successive pairs of lighter-shaded areas around our central forecast represent 20 per cent probability bands.
Source: ONS, OBR
1.15 In the central forecast, net additions to the housing stock fall from around 230,000 in 2025-26 to 220,000 in 2026-27, before increasing to 260,000 in 2030-31. Compared to March, we expect 190,000 fewer cumulative net additions over the forecast period. We have not revised our judgement that the 2024 planning reforms will have a positive impact on housebuilding. Instead, this change is driven by wider pressures in the construction sector because of weak demand, rising material costs and the impact of other regulatory changes.
1.16 We expect cumulative growth in the GDP deflator over the forecast to be around 1 percentage point higher than in March. This is due to higher energy prices received by domestic producers of oil and gas, and the second-round effects that higher inflation has through wage growth. This is the main driver of our upward revision to our central forecast for cumulative growth in nominal GDP over the forecast period – which is 1¼ percentage points higher than March. This drives higher growth in all of the main tax bases – labour income, corporate profits and nominal consumption.
Fiscal outlook
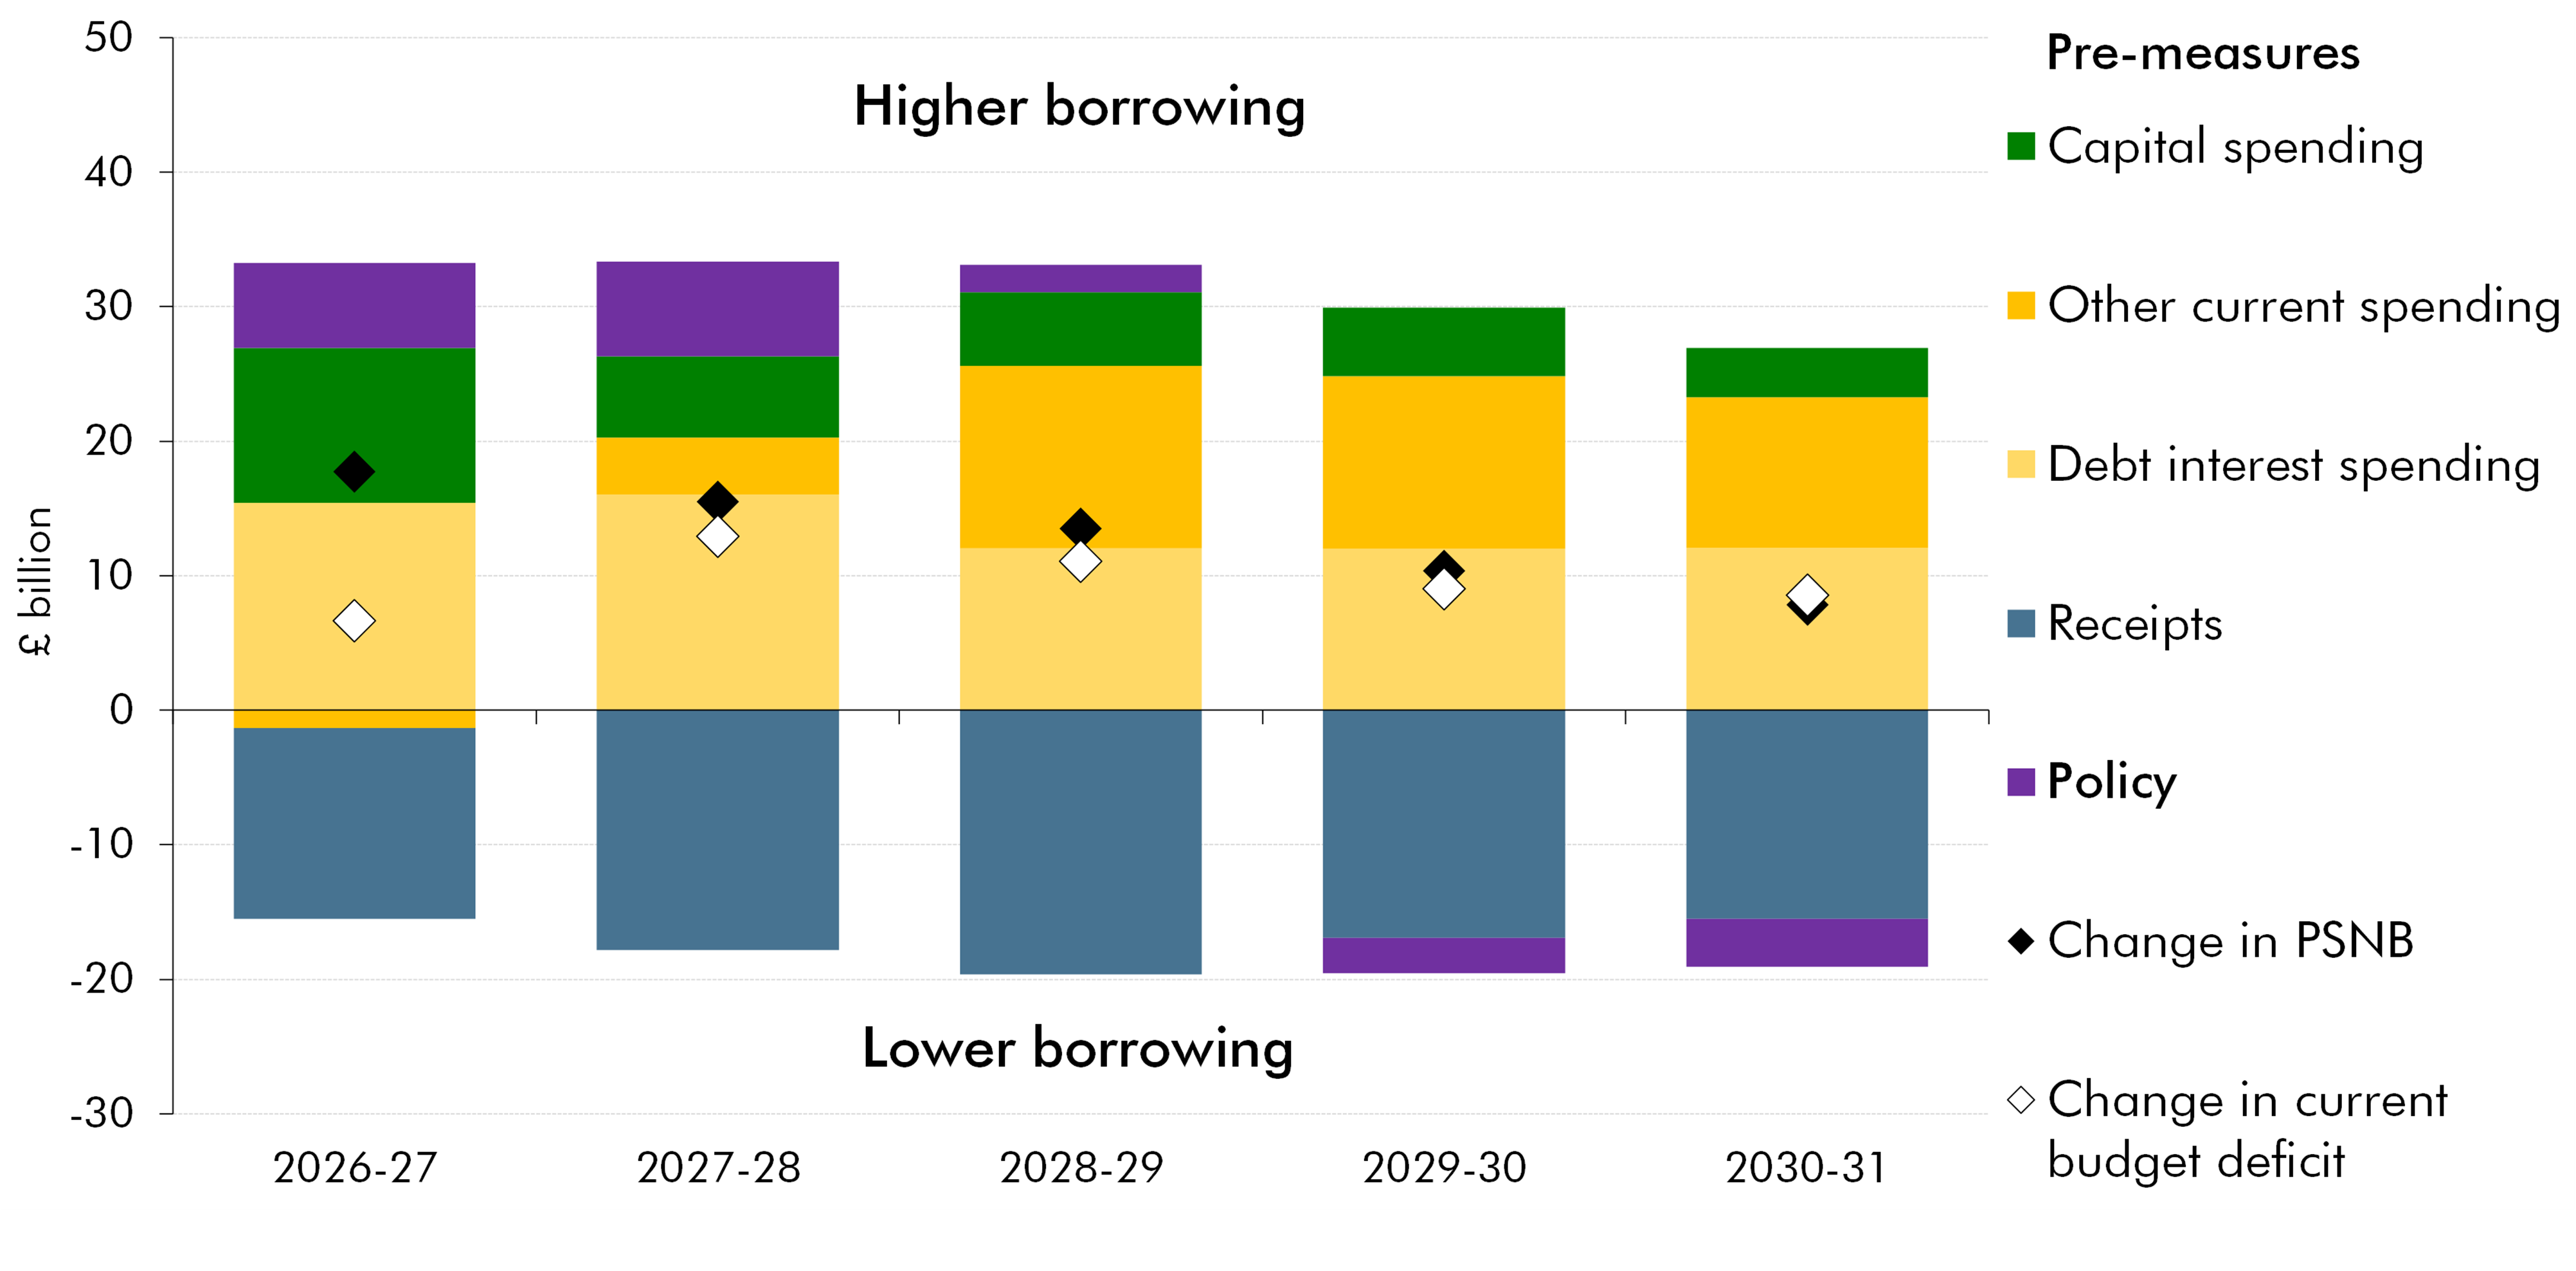
1.17 Relative to March, there is a moderate deterioration in the medium-term fiscal outlook, primarily due to the impact of higher debt interest costs. Public sector net borrowing is expected to be higher compared to March in every year of the forecast – by around £18 billion this year, £16 billion in 2027-28, and an average of £11 billion a year thereafter. As shown in Chart 1.7, the main drivers of the change in borrowing since March are:
-
Debt interest spending in the pre-measures forecast is expected to be £15 billion higher this year, driven by increased inflation raising the cost of index-linked gilts. Debt interest is then forecast to be £12 billion higher on average in the medium term, reflecting increased forecasts for gilt yields and Bank Rate.
-
Other areas of current public spending are £8 billion higher on average in the pre-measures forecast, including from higher inflation raising welfare spending and the cost of public service pensions. Capital spending items that are higher than forecast in March include departmental spending in 2026-27, and over the medium term local government and public corporations’ capital expenditure.
-
Upwards revisions to the pre-measures receipts forecast leave it £17 billion higher on average compared to March, largely driven by increased income tax and NICs, and corporation tax. This reflects higher inflation leading to upward revisions to the forecasts for nominal earnings and profits, respectively, alongside higher-than-expected receipts outturn so far this year.
-
The direct effects of policy measures increase borrowing by £8 billion in 2026-27, £4 billion in 2027-28, and £0.4 billion in 2028-29, and then reduce borrowing by £4 billion in 2029-30, £5 billion in 2030-31, and £12 billion in 2031-32. In the near term, this mainly reflects policies which increase spending. In the medium term, the reduction in borrowing is from a combination of tax increases and a reduction to the pre-measures spending assumption in 2031-32. The indirect effects of policy measures increase borrowing by a further £2 billion on average per year.
-
The changes to the forecast for the current deficit compared to March are very similar to the changes to borrowing, particularly in the medium term (Chart 1.7). The largest difference is in 2026-27 where a £12 billion forecast increase in capital spending, in large part due to departments spending more of their capital budgets than expected, does not affect the current budget. As a result, the current deficit is forecast to be only £7 billion higher than in March in 2026-27.
Chart 1.7: Changes in borrowing and the current budget deficit since March
Source: OBR
1.18 As a result of these changes, our central forecast is for borrowing to fall from 4.4 per cent of GDP (£134 billion) in 2025-26 to 4.2 per cent of GDP (£133 billion) this year. It is then expected to fall steadily over the medium term to reach 1.8 per cent of GDP (£67 billion) in 2030-31 and remain broadly unchanged thereafter (Chart 1.8). The outlook for borrowing is particularly uncertain as it represents the difference between around £1.5 trillion of both tax and spending by the end of the forecast period. Based on the distribution of historical shocks, there is a 60 per cent chance of PSNB being between a surplus of 1.0 per cent of GDP (£38 billion) and a deficit of 4.4 per cent of GDP (£168 billion) in 2031-32.
1.19 The right panel of Chart 1.8 shows that since 2022 plans to consolidate borrowing have been repeatedly delayed. This is due to a combination of subsequent unexpected shocks, lower-than-expected GDP growth, and discretionary policy choices to delay fiscal consolidation. Borrowing has now declined from around 5 per cent of GDP between 2022-23 and 2024-25, to 4.4 per cent of GDP in 2025-26. It is forecast to decline further to 4.2 per cent of GDP this year, and in the current central forecast is set to decline to just under 2 per cent of GDP in 2030-31. However, in the near-term the pace of this consolidation has again slowed, with borrowing between 2026-27 and 2028-29 now forecast to be around 0.5 per cent of GDP a year higher on average than forecast in November 2025. If the current forecast for borrowing to fall to around 2 per cent of GDP in 2029-30 is achieved, it would be 2 years later than forecast in November 2022.
Chart 1.8: Fan chart and successive forecasts for borrowing
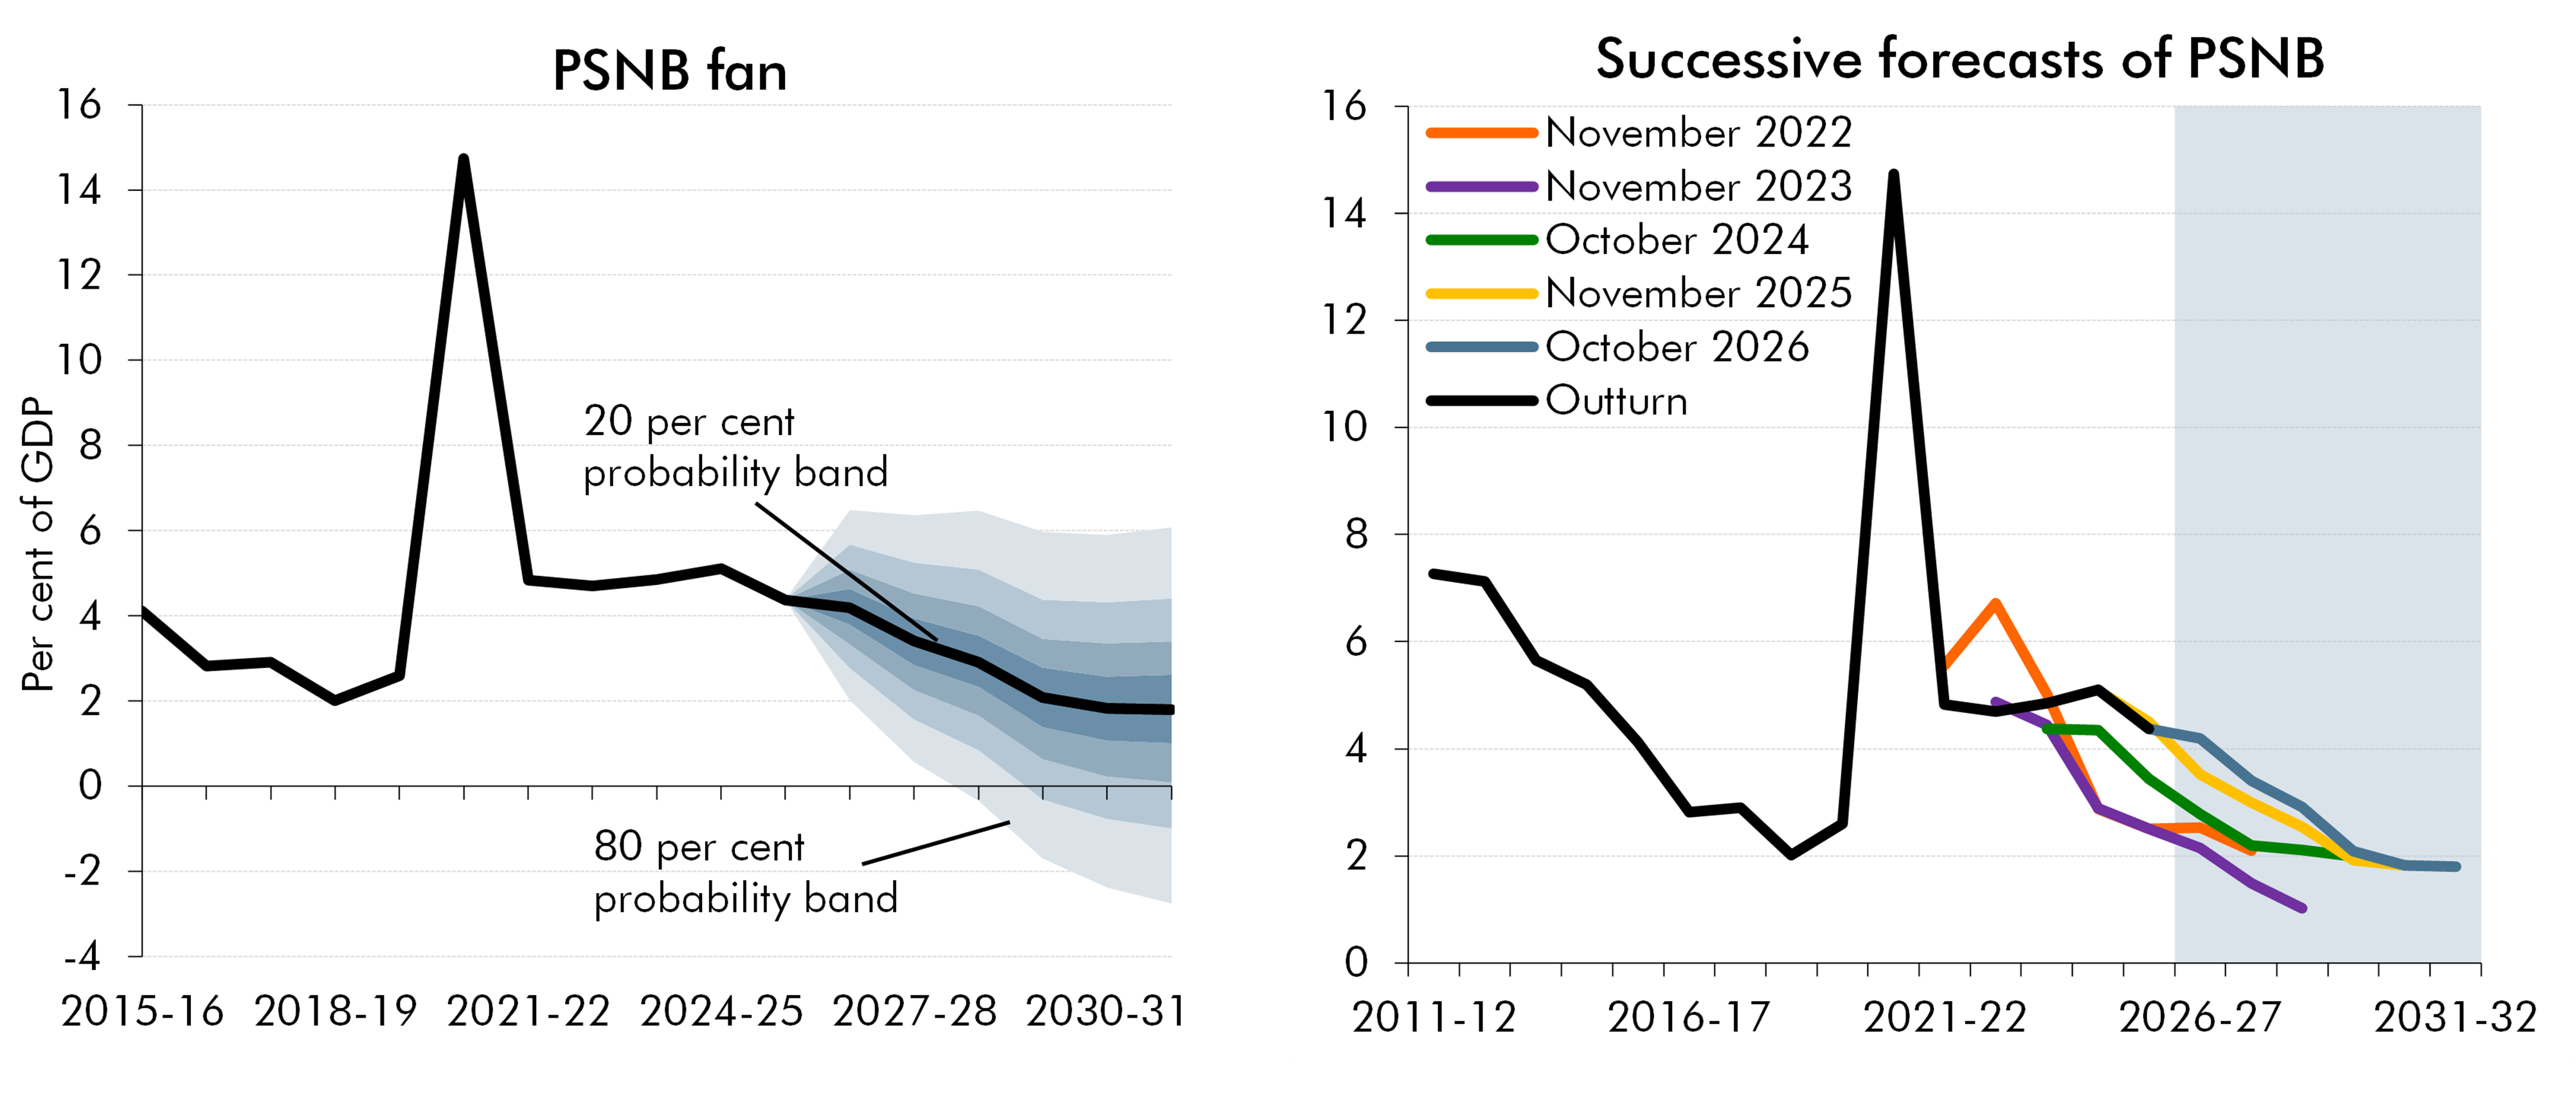
Note: On the left panel, the solid black line shows our median forecast, with successive pairs of lighter shaded areas around it representing 20 per cent probability bands, with 20 per cent of the distribution outside the fan. On the right panel, forecast lines are presented as the nominal forecast for PSNB divided by the outturn and forecast for March-centred nominal GDP that are consistent with this forecast.
Source: ONS, OBR
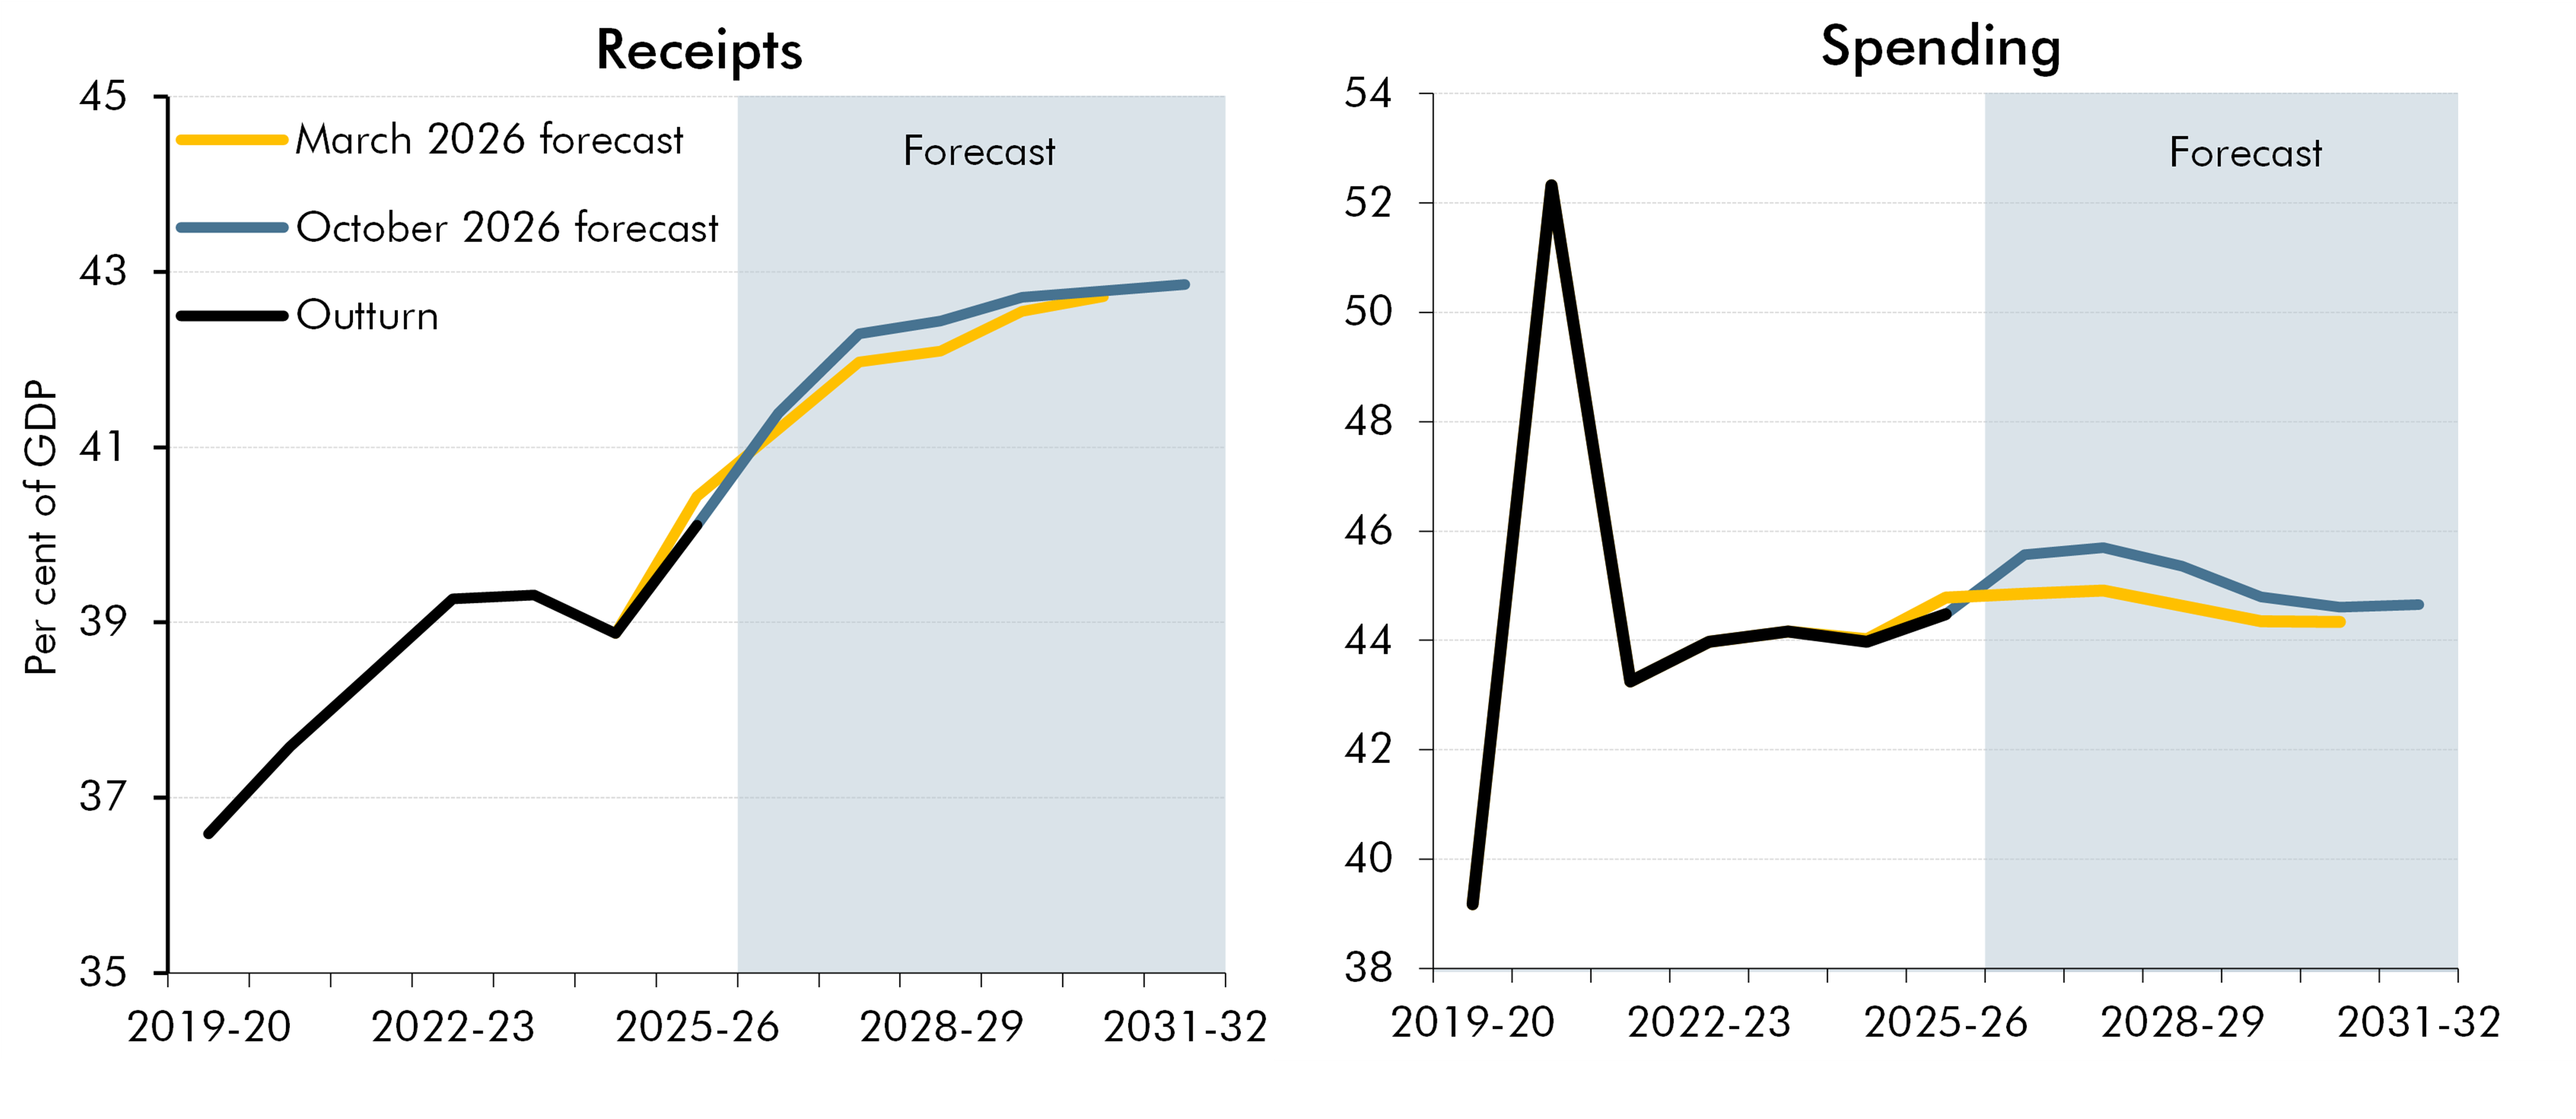
1.20 In the central forecast, around sixty per cent of the projected 2.4 per cent of GDP decline in borrowing between 2026-27 and 2031-32 is driven by rising receipts as a share of GDP. A 0.9 per cent of GDP fall in spending accounts for the remainder:
-
Receipts are forecast to increase from 41.4 per cent of GDP this year to 42.9 per cent by 2031-32. The tax-to-GDP ratio is expected to surpass its historical high of 37.2 per cent in 2027-28 and to reach almost 6 per cent of GDP above the pre-pandemic level by 2031-32. The main drivers of this increase are rising personal taxes, capital taxes, and corporation tax.
-
Spending is forecast to increase from 45.6 per cent of GDP this year to a peak of 45.7 per cent in 2027-28, before declining to 44.7 per cent in 2031-32. The reduction in spending as a share of GDP is driven by planned reductions to departmental spending, which fall from 21.5 per cent of GDP in 2026-27, to 20.8 per cent in 2027-28 before falling further to 20.0 per cent in 2031-32.
Chart 1.9: Receipts and spending as a share of GDP
Source: OBR
1.21 In the pre-measures forecast, borrowing as a share of GDP starts to rise slightly from 1.9 per cent in 2030-31 to 2 per cent in 2031-32. This unusual feature is because some of the long-term pressures that we identified in the 2026 Fiscal risks and sustainability report (FRS) are already starting to bite. The increase reflects a combination of an increased pensioner population placing upward pressure on welfare spending, declining receipts from fuel duty due to the transition to electric vehicles, and increased spending on debt interest driven by significant redemptions of gilts at higher interest rates. This rise has been fully offset by policy measures announced by the Government at this Budget so that in the post-measures forecast borrowing as a share of GDP is flat between 2030-31 and 2031-32.
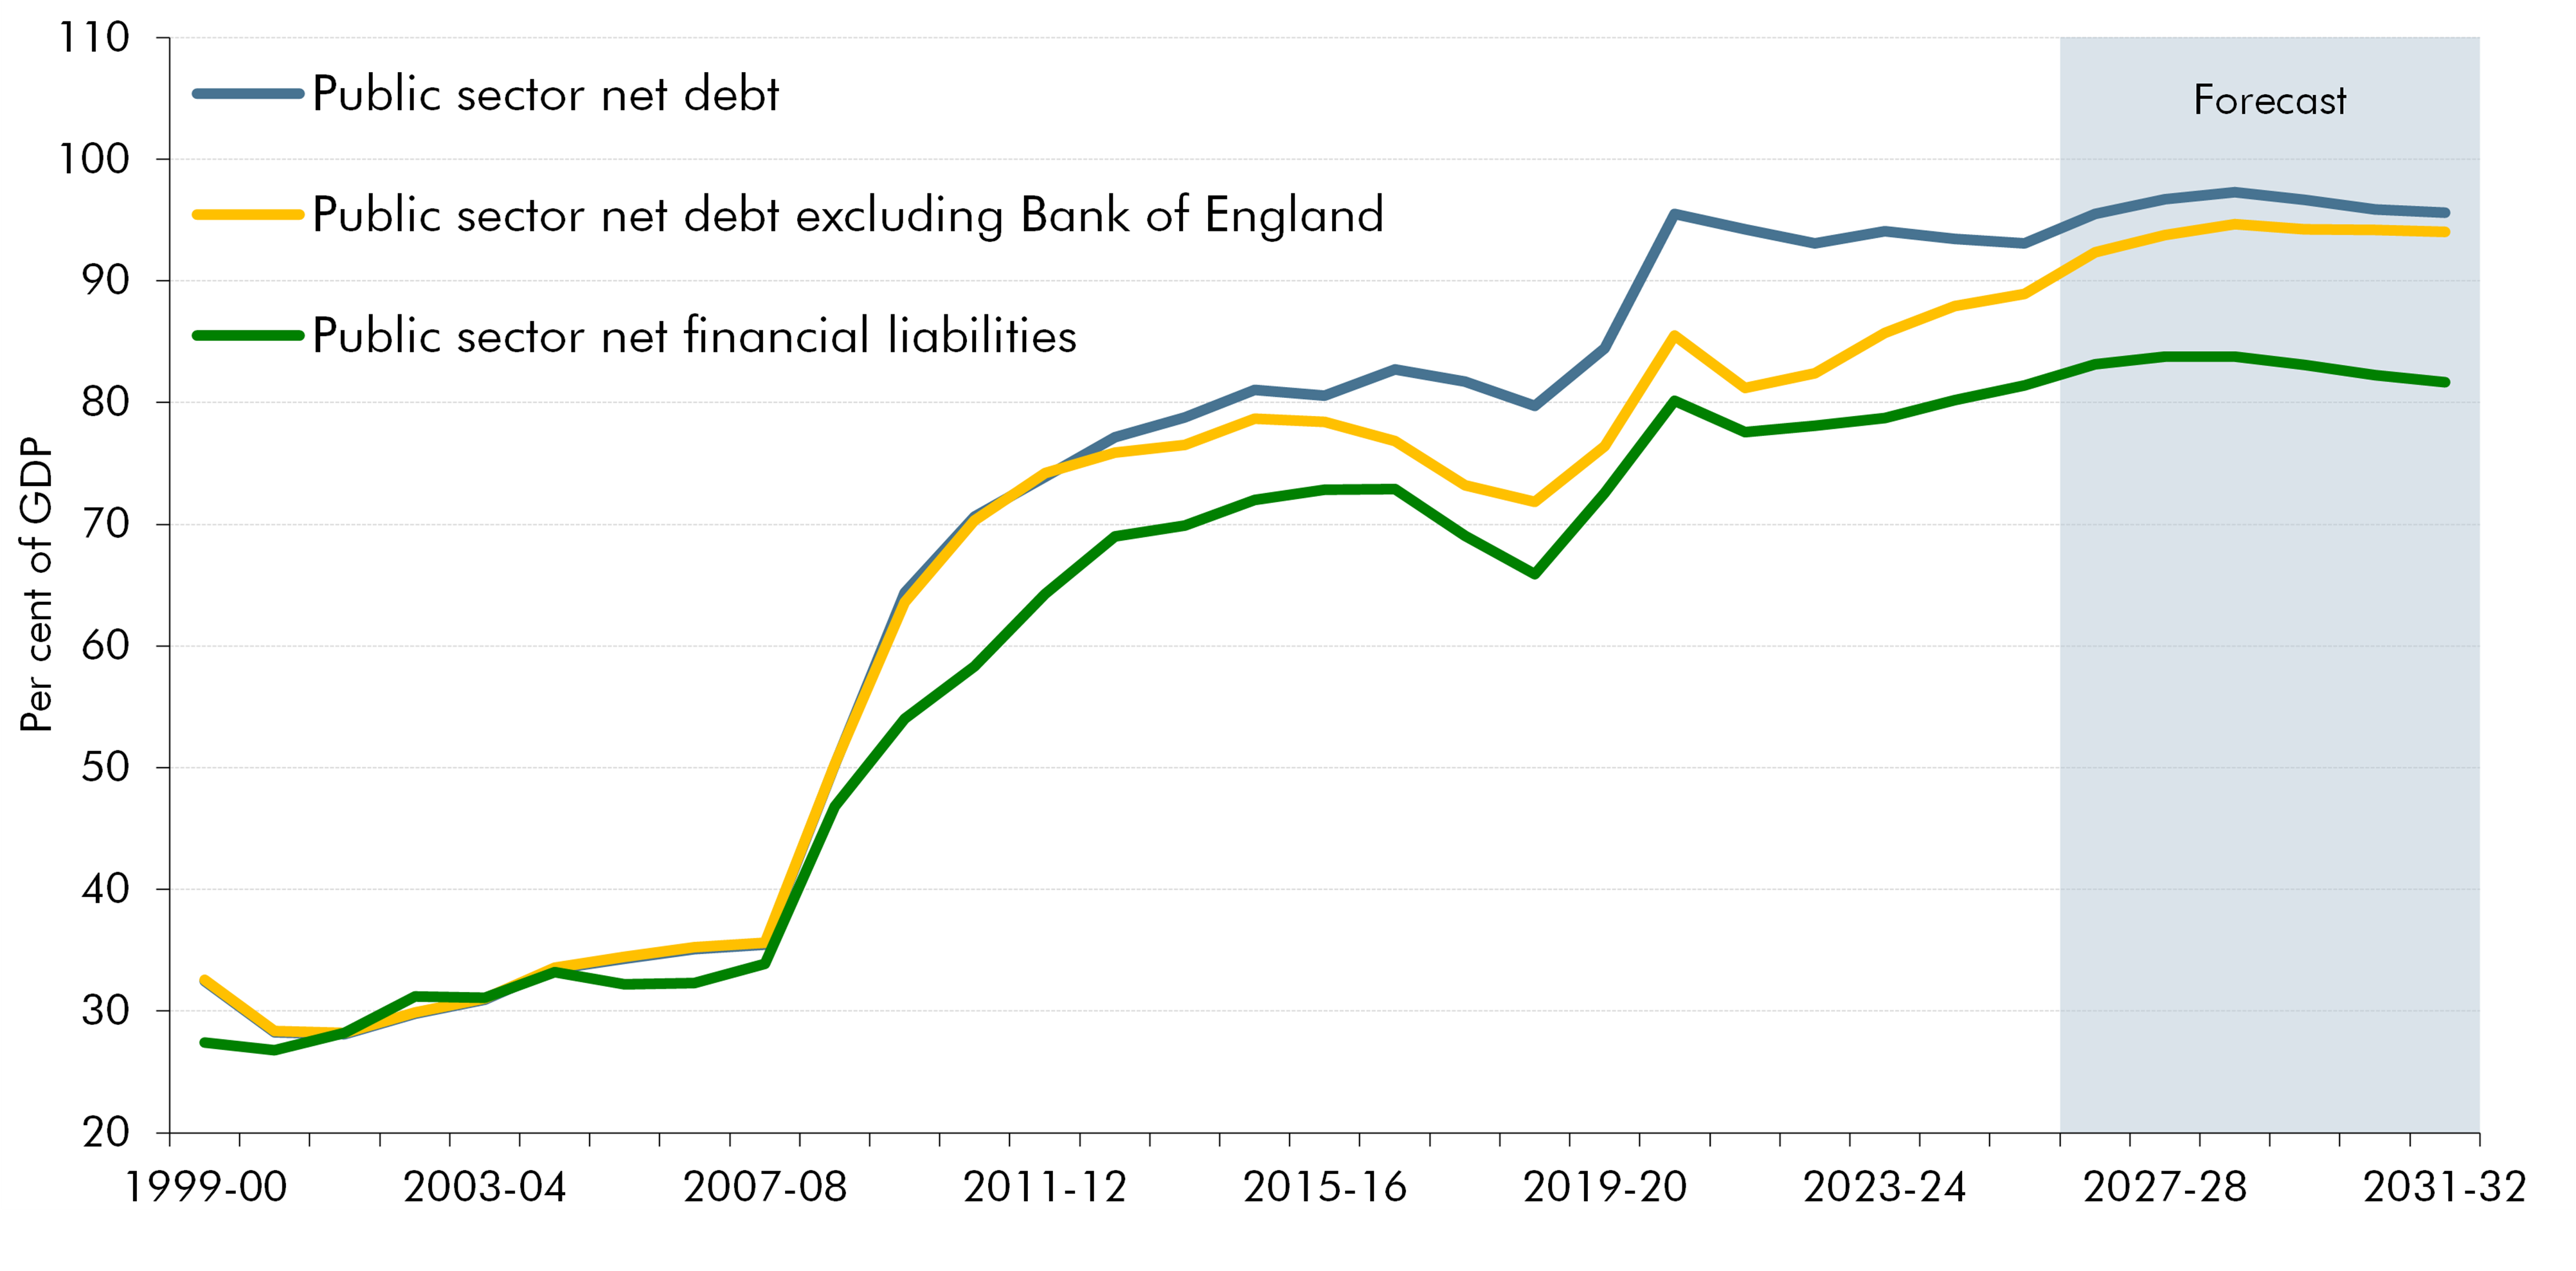
1.22 In the post-measures forecast, public sector net debt rises from 96 per cent of GDP in this year to peak at 97 per cent of GDP in 2028-29. It then falls back to 96 per cent in 2031-32, the final year of the forecast. This would be 0.6 per cent of GDP higher than in the final year of the March 2026 forecast. Net debt excluding the Bank of England is forecast to rise from 92 per cent of GDP this year to stabilise around 94 per cent in the final three years of the forecast. Debt on either measure is forecast to be no lower in 2031-32 than in the current year. Public sector net financial liabilities (PSNFL) are forecast to rise from 83 per cent of GDP this year to peak just under 84 per cent in 2027-28, and then to fall gradually in each subsequent year to 82 per cent at the end of the forecast.
Chart 1.10: Measures of the public sector balance sheet
Source: ONS, OBR
Performance against the Government’s fiscal targets
1.23 In the central forecast, the current budget deficit declines from 1.5 per cent of GDP (£47 billion) in 2025-26 to 1.3 per cent (£41 billion) this year (Chart 1.11). It is then forecast to improve gradually to reach a surplus of 0.4 per cent of GDP (£15 billion) in 2029-30, and then to stabilise at around 0.6 per cent on average in 2030-31 and 2031-32 (at £22 and £21 billion, respectively).
1.24 As a result, the Government’s fiscal mandate for the current budget to be in surplus in 2029-30 is met by a margin of £15 billion. This is £7 billion lower than when the fiscal rules were last formally assessed at Budget 2025. The probability of meeting the fiscal mandate is now estimated at 56 per cent, which compares to a probability of 59 per cent at Budget 2025. For the probability of meeting the fiscal mandate to be 60 or 70 per cent, it would require the current budget to be in surplus by around £25 and £50 billion respectively, in 2029-30.
1.25 The supplementary target, for public sector net financial liabilities to be falling as a share of GDP in 2029-30, is forecast to be met by a margin of £24 billion. This is unchanged relative to Budget 2025, when the fiscal targets were last assessed. For the probability of meeting the supplementary target to be 60 or 70 per cent, it would require PSNFL to be falling by 1.8 or 3.9 per cent of GDP in 2029-30 respectively, instead of the current forecast margin of a fall of 0.7 per cent of GDP.
Chart 1.11: Fan charts for the current budget deficit and PSNFL
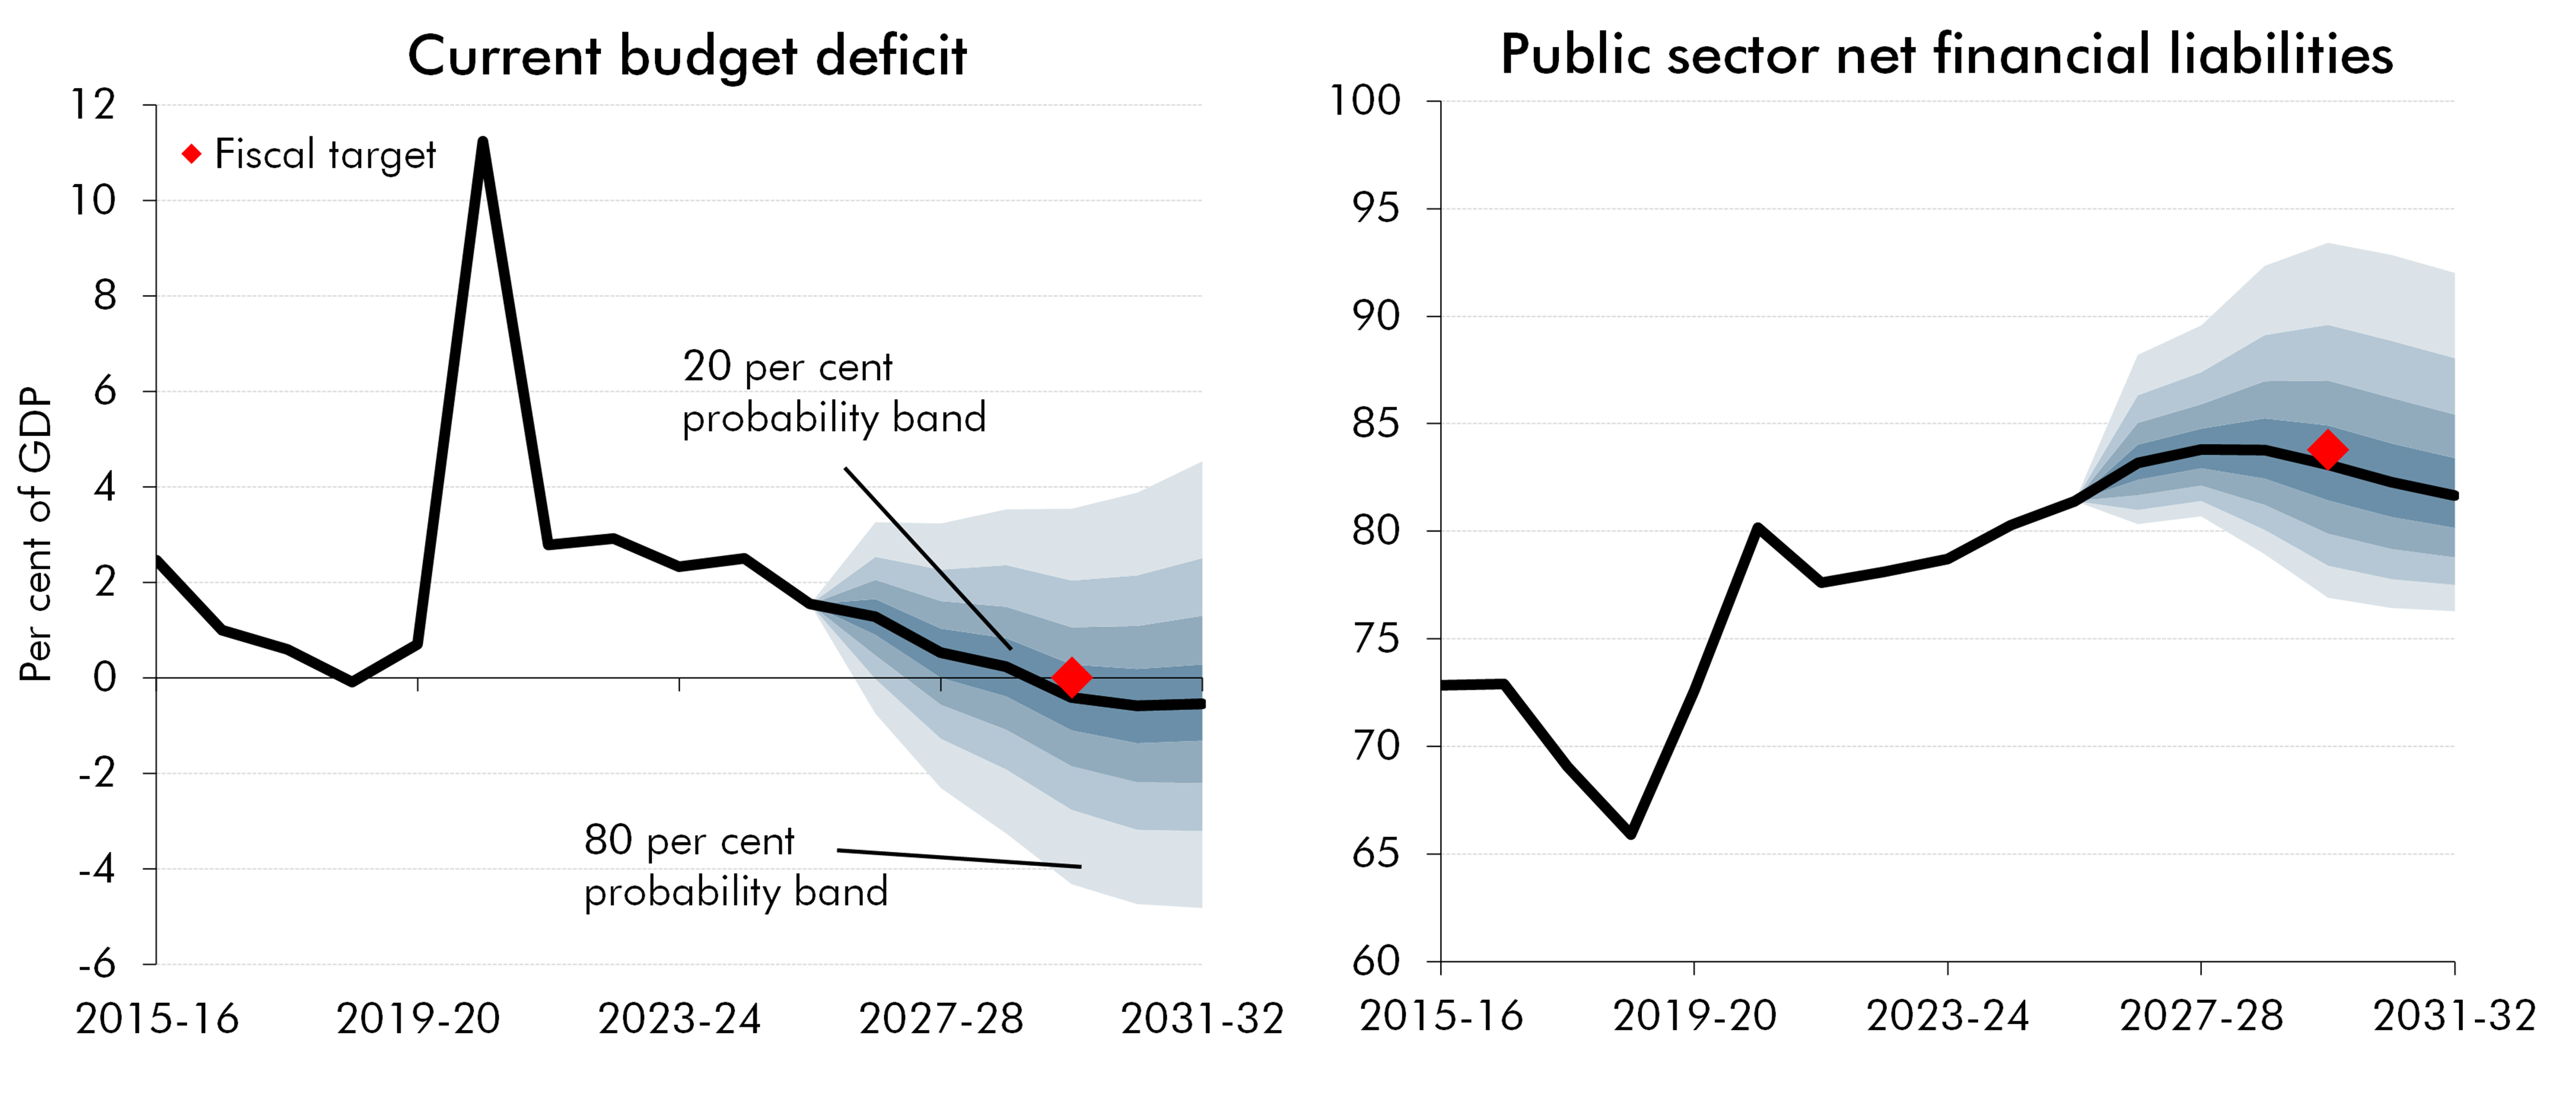
Note: The solid black line shows our median forecast, with successive pairs of lighter shaded areas around it representing 20 per cent probability bands, with 20 per cent of the distribution outside the fan.
Source: OBR
Risks and uncertainties
1.26 These margins against the fiscal targets are very small compared to the inherent risk and uncertainty around any medium-term fiscal forecast. The central forecast is an estimate of the middle of a range of possible outcomes, which means outturns substantially below and above our central forecast are likely and of broadly equal probability. Small percentage changes in the forecast for either tax or spending can lead to large percentage changes in borrowing. Since the pandemic, the average revision to pre-measures borrowing in the third year of the forecast has been £18 billion. The median three-year-ahead difference between forecast and outturn, since 2010, has been £34 billion. The margins against the fiscal mandate set out above are below the average margin of close to £30 billion held by Chancellors since 2010.
1.27 Key risks to our economy forecast include:
-
The evolution of the conflict in the Middle East, and its implications for energy prices, interest rates and inflation. Energy markets remain volatile – at the time of finalising this report, oil and gas futures pricing was close to the top of the range observed since the beginning of the Middle East conflict. Scenario analysis in Chapter 7 illustrates that if energy prices were to peak at a higher level and remain elevated for longer, we would expect increased inflation, weaker near-term GDP growth and a potential tightening of financial conditions. This could raise borrowing by as much as £17 billion in 2027-28, and by £6 billion in 2031-32, alongside an erosion of real-terms departmental spending power. If energy prices return to our March forecast path, we would expect more rapid disinflation, stronger near-term GDP growth and a potential easing of financial conditions – which could result in a decrease in borrowing of around £7 billion by 2031-32. The fiscal impacts would be particularly dependent on changes in financial conditions, the extent of pass-through of an inflation shock to wages given tax thresholds are currently frozen, and any policy response to inflationary pressures on departmental spending.
-
The outlook for productivity growth is a key risk to the economic and fiscal forecasts. The development and adoption of artificial intelligence could have a significant positive effect – our central forecast is for it to boost productivity growth by 0.2 percentage points a year by the medium term – but the scale and timing of any effect is highly uncertain. Revised ONS data on average hours, discussed in Box 2.2, suggest that UK productivity growth slowed after the financial crisis, but that the magnitude of the slowdown was closer to international comparators than previously suggested. In the November 2025 EFO, we illustrated that if annual productivity growth were 0.5 percentage points higher or lower than our central forecast in the medium term, borrowing could be around £50 billion lower or £40 billion higher by 2030-31.
-
There are several sources of uncertainty around the labour market outlook. There is significant uncertainty around the size and composition of future migration flows, given the post-Brexit change in the migration regime and the recent spike and subsequent fall in net migration. And there are risks around the outlook for unemployment. In the March EFO, we produced scenarios on the fiscal implications of alternative paths for the labour market. These suggested that if unemployment returned to its estimated equilibrium rate two years earlier than the central forecast, borrowing could be £16 billion a year lower on average, or if it instead peaked at around 7 per cent, borrowing could be an average of £20 billion a year higher than our central forecast.
1.28 Key additional risks to the fiscal forecast include:
-
The cost of servicing government debt – which had already increased sharply since 2021, before rising further in recent months following the start of the current Middle East conflict. Debt interest spending has risen from £39 billion (1.7 per cent of GDP) in 2019-20 to £109 billion (3.5 per cent of GDP) in 2025-26. It is now forecast to rise to £160 billion (4.2 per cent of GDP) in 2031-32. Gilt yields have recently been volatile, with the ten-year yield ranging from around 4.5 per cent to 5.5 per cent since March. But yields within this range are not unusual by historical standards. A 1 percentage point change in gilt yields and Bank Rate expectations across the forecast could lead to a medium-term change in borrowing of £16 billion.
-
There are a number of pressures on departmental spending. Since the Spending Review envelope was set, higher inflation has reduced the real value of the original spending limits by £7 billion each year. There are further pressures in the later years of the forecast for which departmental spending limits have not been set. Based on the Government’s assumption for total spending over this period – after taking into account policy commitments in areas including the NHS, defence and schools – spending would have to be £11 billion higher in 2031-32 to prevent ‘unprotected’ areas of day-to-day spending from falling in real terms from 2028-29.
In the longer term, there are further pressures on public spending plans, including from the Government’s commitment to reform the social care system and to spend 3.5 per cent of GDP on defence by 2035. -
There is also uncertainty around the outlook for welfare spending, especially related to health and disability benefits which have seen very significant rises in caseloads since the pandemic. In the central forecast, we assume that caseloads will continue to rise but at a slower rate. If they were to continue to rise at the post-pandemic growth rate, this could add around £25 billion to welfare spending by 2031-32. Or if caseload growth were to slow to pre-pandemic rates, then spending could be around £13 billion lower by 2031-32.
-
The tax-to-GDP ratio is expected to surpass its historical high of 37.2 per cent in 2027-28 and continue increasing in every year of the forecast. A higher level of the tax take increases the risk that incentives within the tax system constrain economic activity by more than expected. The single largest driver of the increase in the tax-GDP-ratio is from rising income tax and NICs which are highly sensitive to growth in nominal earnings, especially with personal tax thresholds frozen. Increased revenue from capital taxes is also a key component of the increase but the expected yield is highly sensitive to both equity prices and uncertain behavioural responses from affected taxpayers. The forecast also assumes the tax gap – a measure of tax compliance – will decline over the forecast period following a recent period where it has remained broadly flat.
1.29 The Government has taken some steps to address previously identified fiscal risks. The recently-announced reforms to the triple lock should significantly reduce the projected increase in the cost of state pension uprating over the long term relative to the previous policy. This is because the reforms remove the ‘ratchet’ effect whereby any increase in the value of pensions relative to earnings are permanently embedded and compound over time. However, alongside this reform, the Government also announced an intention to expand state provision of social care. The overall impact of these announcements on the public finances over the long term, therefore, depends on the additional cost of the social care reforms which is dependent on the final policy design and the timing of its introduction. In addition, the fiscal mandate now targets the third year of the forecast. This means that, from the next spending review, detailed spending allocations will be required for the year in which the fiscal targets bind which should reduce the risks around meeting these targets.
1.30 In practice, uncertainties around the central forecast are likely to be different to those in the past and go beyond the ones described above. As recent years show, there is a significant risk of unforeseeable adverse shocks having a large negative impact on the economy and public finances. Any such shocks over the forecast period, during which debt is forecast to remain elevated at approximately 95 per cent of GDP, would place further pressure on the UK’s fiscal sustainability.
1.31 Our 2026 FRS showed that fiscal pressures are likely to build over the long term. The drivers of this included an ageing population, wider health cost pressures, commitments to increase defence spending, and the fiscal costs of the transition to net zero. Long-term projections such as these are highly uncertain. However, in nearly all the scenarios we produced, including with different assumptions for long-term policy, debt would move on to an unsustainable upward trajectory within the next couple of decades unless policy action was taken to prevent this.
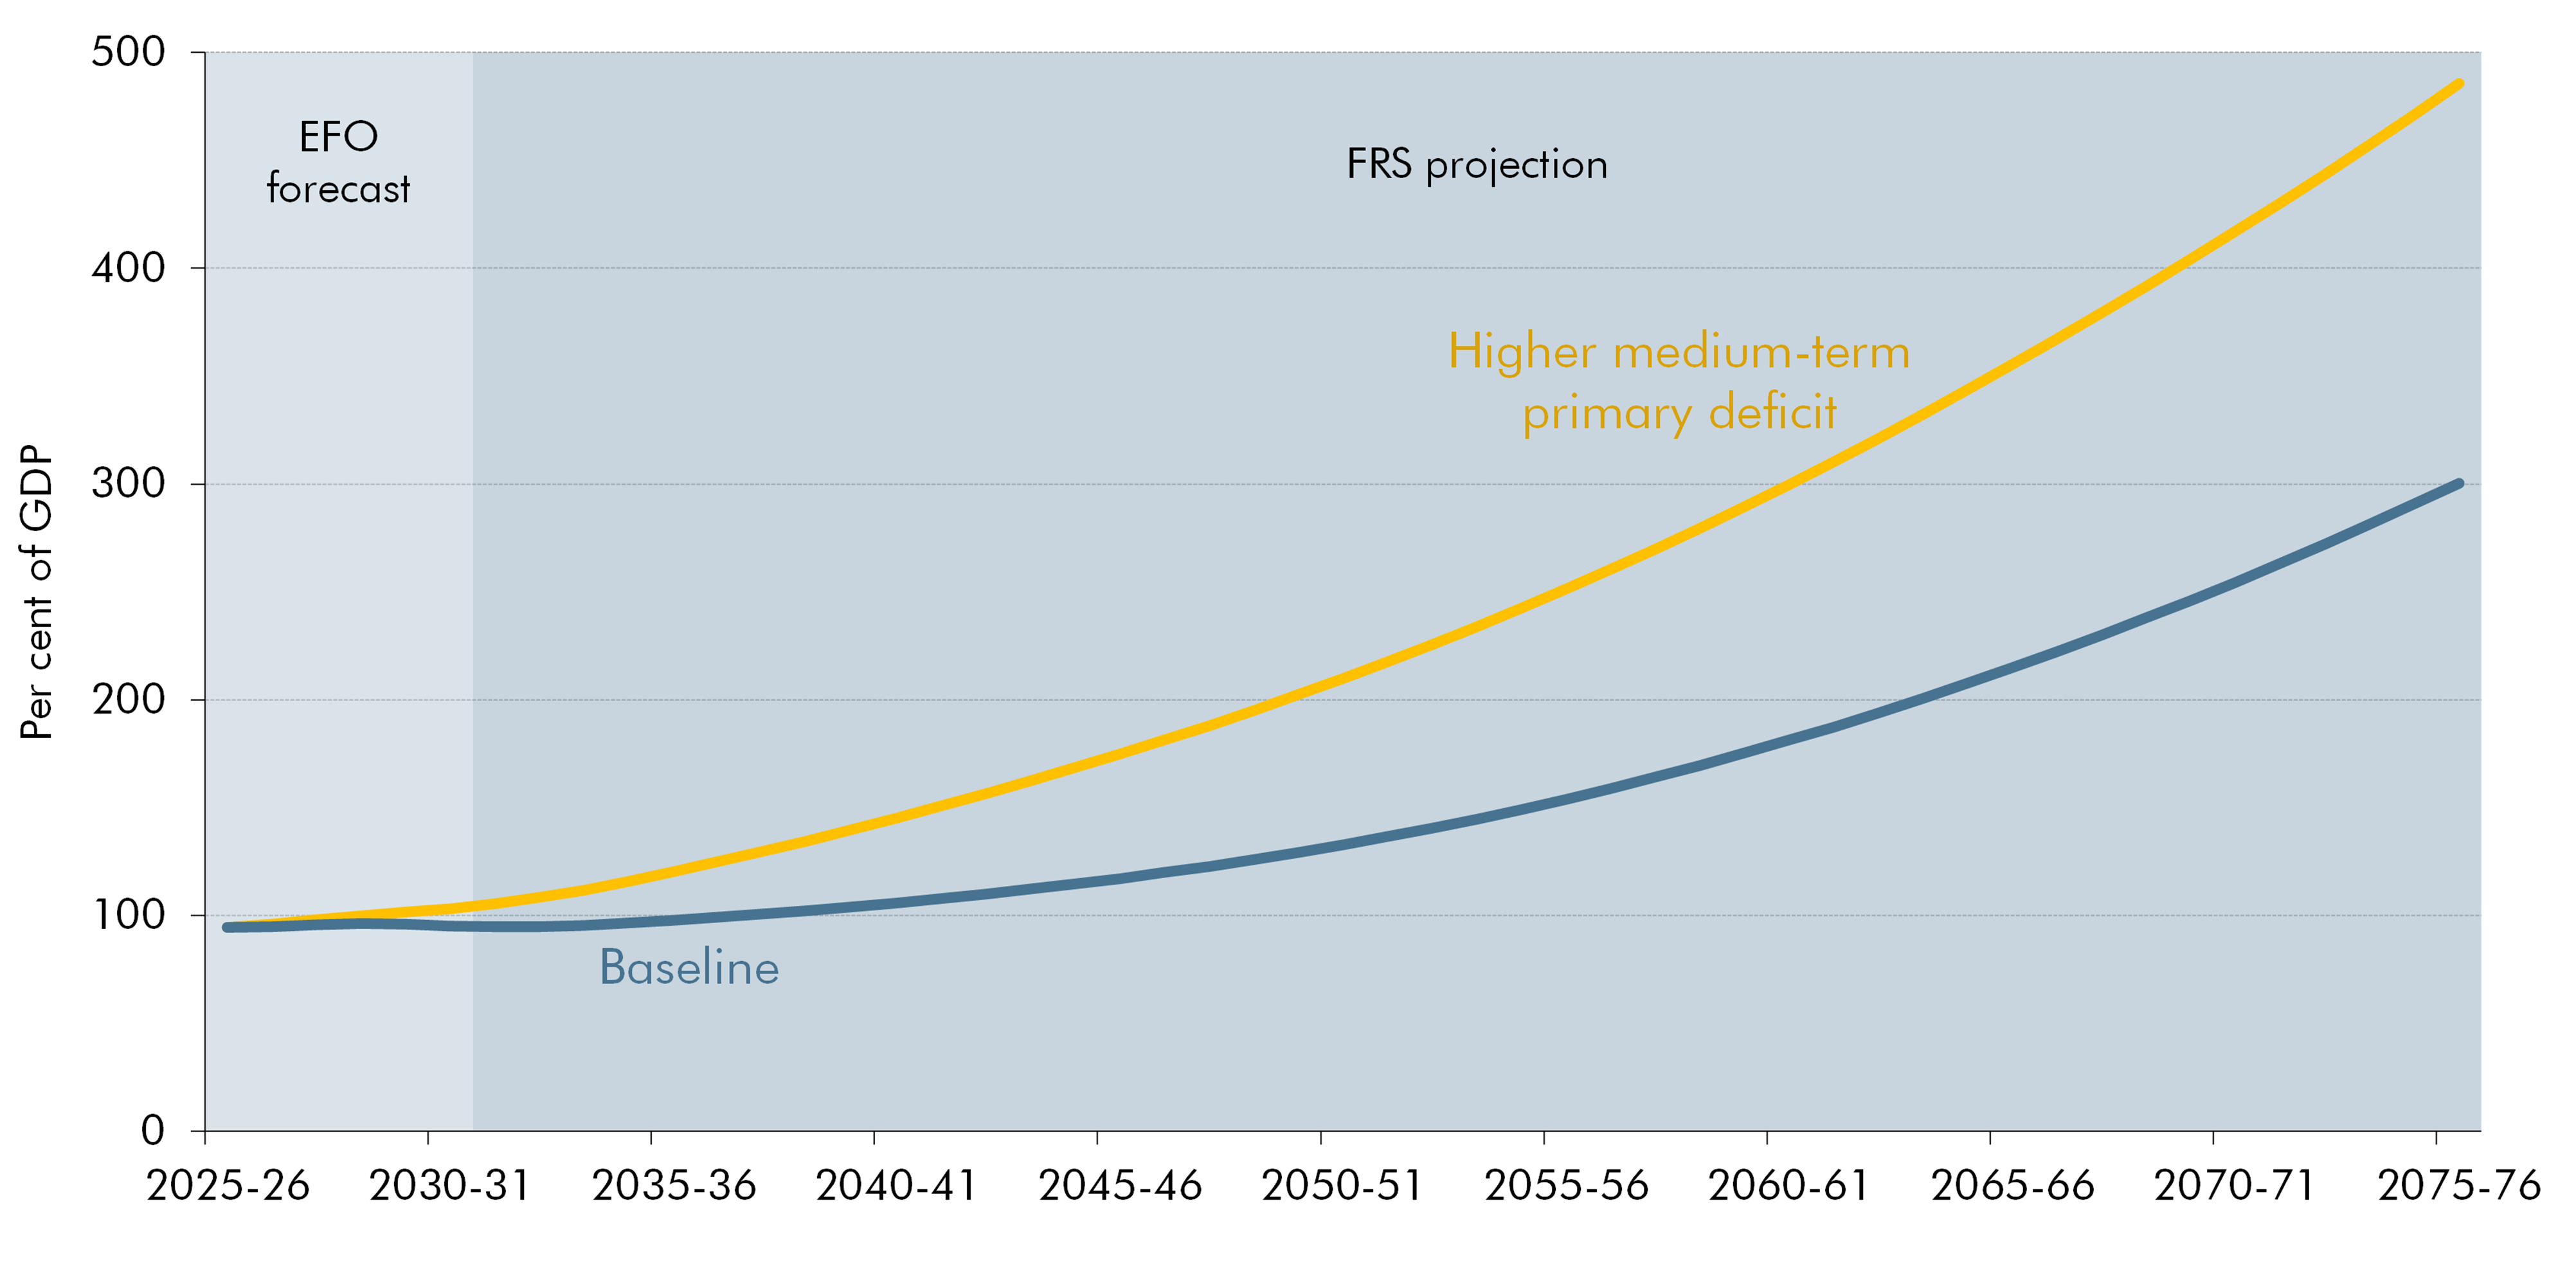
1.32 In the baseline long-term scenario in the FRS, debt moved to an unsustainable upward trajectory in the 2040s (Chart 1.12). This was based on the plans for fiscal consolidation in the March 2026 forecast, in which the primary balance – a measure that excludes debt interest spending – was projected to be in surplus by 1.5 per cent of GDP by 2030-31. If achieved, this would be the largest primary surplus since 2000-01. As set out above, since 2022, successive governments have set out similar plans for medium-term consolidation which have not subsequently been achieved. If we assume that the primary deficit in 2030-31 was at the same level as in 2025-26, then the unsustainable upward trajectory of debt would start in the 2030s. This underlines the importance for fiscal sustainability of delivering the current planned medium-term consolidation.
Chart 1.12: Long term debt scenarios: 2026 Fiscal risks and sustainability report
Source: OBR
Chapter 2: Economic outlook
Summary of the economy forecast
2.1 The UK’s economic position remains challenging. A series of major adverse shocks since the global financial crisis, interacting with underlying structural trends, have contributed to persistently weak growth in per person GDP, episodes of sustained high inflation and subdued growth in real household disposable incomes. A broad range of factors, many of which originate outside the UK, will influence the UK’s future economic performance. Further adverse shocks may prolong or worsen recent weak growth, while stronger productivity growth, for example from advances in artificial intelligence (AI), may offset or reverse recent trends.
2.2 We finalised our March 2026 forecast just before the start of the current conflict in the Middle East. That forecast was conditioned on market pricing for Bank Rate to be cut twice by the end of this year. We expected inflation to fall back to around 2 per cent by the end of this year and GDP growth to rise to around 1½ per cent in 2027. Since then, energy prices have risen substantially – though by less than following the Russian invasion of Ukraine. As the UK is a net importer of energy, this constitutes a negative terms-of-trade shock and has already raised CPI inflation. While real GDP growth over the year to date has been more resilient than expected, the labour market remains weak, with job vacancies continuing to fall and some data suggesting an ongoing drop in the number of payrolled employees. Market pricing suggests interest rates will be significantly higher than anticipated in March.
2.3 Table 2.1 summarises the key conditioning assumptions and judgements which underpin our latest central forecast. Our central forecast for real GDP growth in 2027 is 1 per cent – ½ a percentage point below our March forecast, as a result of higher energy prices and interest rates. We expect CPI inflation to peak at close to 4 per cent in early 2027, driven largely by the direct and indirect effects of higher energy prices, with relatively modest second-round effects through earnings. We expect no growth in real earnings in 2027 and 2028, and a slight fall in real household disposable income (RHDI) per person in the near term. Market pricing suggests energy prices will fall sharply from mid-2027. This would contribute to inflation falling back to its 2 per cent target in our central forecast by 2028, and to the level of real GDP in 2030 being broadly unchanged from our March forecast. But we expect RHDI per person to continue its recent trend of weak growth such that in 2029-30, it is only expected to be 1 per cent higher than its pre-pandemic level.
2.4 Our central economy forecast is a point estimate within a wide range of possible outcomes. It is also a conditional forecast based on market pricing in mid-August for current and future energy prices and interest rates. Energy prices have been highly volatile and, at the point at which we finalised this Economic and fiscal outlook (EFO) publication, had increased significantly compared to those levels. Therefore, we set out alternative energy price scenarios in Chapter 7 to assess the impact that higher or lower energy prices could have for the economic and fiscal outlook. We also discuss a wide range of other risks around our central forecast throughout this EFO, including through the use of fan charts of probability ranges and sensitivity analysis. One of our most important and most uncertain judgements is around the outlook for productivity growth. Box 2.2 explores the recent ONS revisions to historical productivity, which show that even the recent evolution of productivity growth is highly uncertain.
Table 2.1: Summary of the central economy forecast
| Key variable | |||
|---|---|---|---|
| (per cent unless otherwise stated) | Measure of the variable | EFO forecast | |
| March 2026 | October 2026 | ||
| Conditioning assumptions(1) | |||
| Oil price (dollars a barrel) | Average in 2026 and 2027 | 63 | 82 |
| Gas price (pence a therm) | Average in 2026 and 2027 | 69 | 117 |
| Bank Rate | Average in 2026 and 2027 | 3.4 | 4.0 |
| 10-year gilt yield | Average in 2026 and 2027 | 4.6 | 5.0 |
| Key near-term forecasts | |||
| CPI inflation | Average in 2026 and 2027 | 2.1 | 3.3 |
| Nominal earnings growth | Average in 2026 and 2027 | 2.9 | 3.4 |
| RHDI per person growth | Average in 2026 and 2027 | 0.4 | -0.4 |
| Output gap | Average in 2026 and 2027 | -0.7 | -1.1 |
| Real GDP growth | Average in 2026 and 2027 | 1.3 | 1.1 |
| LFS unemployment rate | Average in 2026 and 2027 | 5.1 | 5.0 |
| Key medium-term forecasts | |||
| Potential output | Average growth from 2026 to 2030 | 1.25 | 1.25 |
| Net migration (thousand) | Annual average from mid-2026 to mid-2031 | 253 | 182 |
| Real GDP per person | Average growth from 2026 to 2030 | 1.1 | 1.3 |
| Nominal GDP | Cumulative growth across the forecast(2) | 18.6 | 19.3 |
| Corporate profits | Cumulative growth across the forecast(2) | 20.1 | 23.6 |
| 1) Average market values over ten working days, ending 22 January for March 2026 forecast, and 19 August for October 2026 forecast. |
| 2) For March 2026 forecast, growth is taken from 2025-26 to 2030-31; for October 2026, growth is taken from 2026-27 to 2031-32. |
| Source: Bank of England, Bloomberg, ONS, OBR |
Conditioning assumptions
2.5 We conditioned our economy forecast on market pricing over the 10 working days to 19 August. The final pre-measures fiscal forecast is produced after the pre-measures economy forecast, enabling us to use a later reading for interest rates in the fiscal forecast – based on the five working days to 15 September. Below we describe the conditioning assumptions used in the economy forecast, consistent with the earlier window, and briefly explain where the fiscal assumptions differ.
Energy prices
2.6 As Chart 2.1 illustrates, wholesale energy prices have increased significantly since our March forecast, largely as a result of the conflict in the Middle East. Energy prices have also been volatile over this period, with Brent crude spot prices ranging between 72 and 114 dollars a barrel (with the highs close to the 2022 peak) and UK natural gas spot prices ranging between 97 and 216 pence a therm (still significantly below the 2022 peak).
2.7 Our central forecast, shown in Chart 2.1, is based on market pricing over the 10 working days to 19 August. Based on those prices, over the forecast period:
-
Oil prices fall from a peak of 95 dollars a barrel in the second quarter of this year to between 70 and 75 dollars a barrel by 2028, and remain around that level thereafter. Compared to our March forecast, oil prices are 30 per cent higher in 2026 and 2027 and around 8 per cent higher in 2030.
-
Natural gas prices reach around 150 pence a therm at the end of this year, more than double our March forecast but significantly below the 2022 peak. They then fall to around 95 pence a therm by late 2027 and average just under 70 pence a therm from mid-2028 (12 per cent higher than the March forecast).
-
Electricity prices peak at around 125 pounds a megawatt hour at the end of this year (around 65 per cent higher than in the March forecast) before falling to under 70 pounds per megawatt hour from mid-2028 (5 per cent below our March forecast). The reduction in medium-term electricity prices since March, despite the rise in medium-term gas prices, illustrates their continued gradual decoupling, discussed in Box 2.1.
2.8 Oil and gas prices have increased further since we took market expectations on the 10 working days to 19 August, and remain volatile. Since the start of the conflict in the Middle East, futures prices for 2027 have ranged between 70 and 95 dollars a barrel for oil and 75 and 180 pence a therm for gas. At the time of finalising this report, oil and gas futures were close to the top end of this range. We set out scenarios which assess the impact of higher and lower oil and gas prices for the economic and fiscal outlook in Chapter 7.
Chart 2.1: Energy prices
Note: October 2026 forecast uses the 10 working days to 19 August and March 2026 forecast uses the 10 working days to 22 January. Range since Middle East conflict is range between 2 March and 20 October.
Source: Bloomberg, Ofgem, OBR
Box 2.1: The impact of energy price shocks on economic activity
Oil and gas prices have risen significantly since the start of the current conflict in the Middle East. This comes four years after the spike in oil and particularly gas prices following the Russian invasion of Ukraine in 2022. The impact of an energy price shock on UK economic activity depends on a range of factors beyond the change in wholesale prices – including longer-term trends in the UK’s energy mix and energy intensity, the UK’s dependence on energy imports, the pass-through of wholesale prices to those paid by firms and households, and underlying economic conditions.
Chart A shows the annual nominal change in fossil fuel prices weighted by the UK’s changing relative total consumption of coal, oil, and natural gas over time. Fossil fuel prices rose by 83 per cent in the year to September 2026, just under a third of the peak rate seen in 2022, and less than half of that seen in the 1973 shock.a There is some evidence that ample pre-shock supply and inventories, supply responses elsewhere, and reduced global demand – especially from China – have helped cushion the initial price shock in 2026.b
Chart A: Fossil fuel price inflation
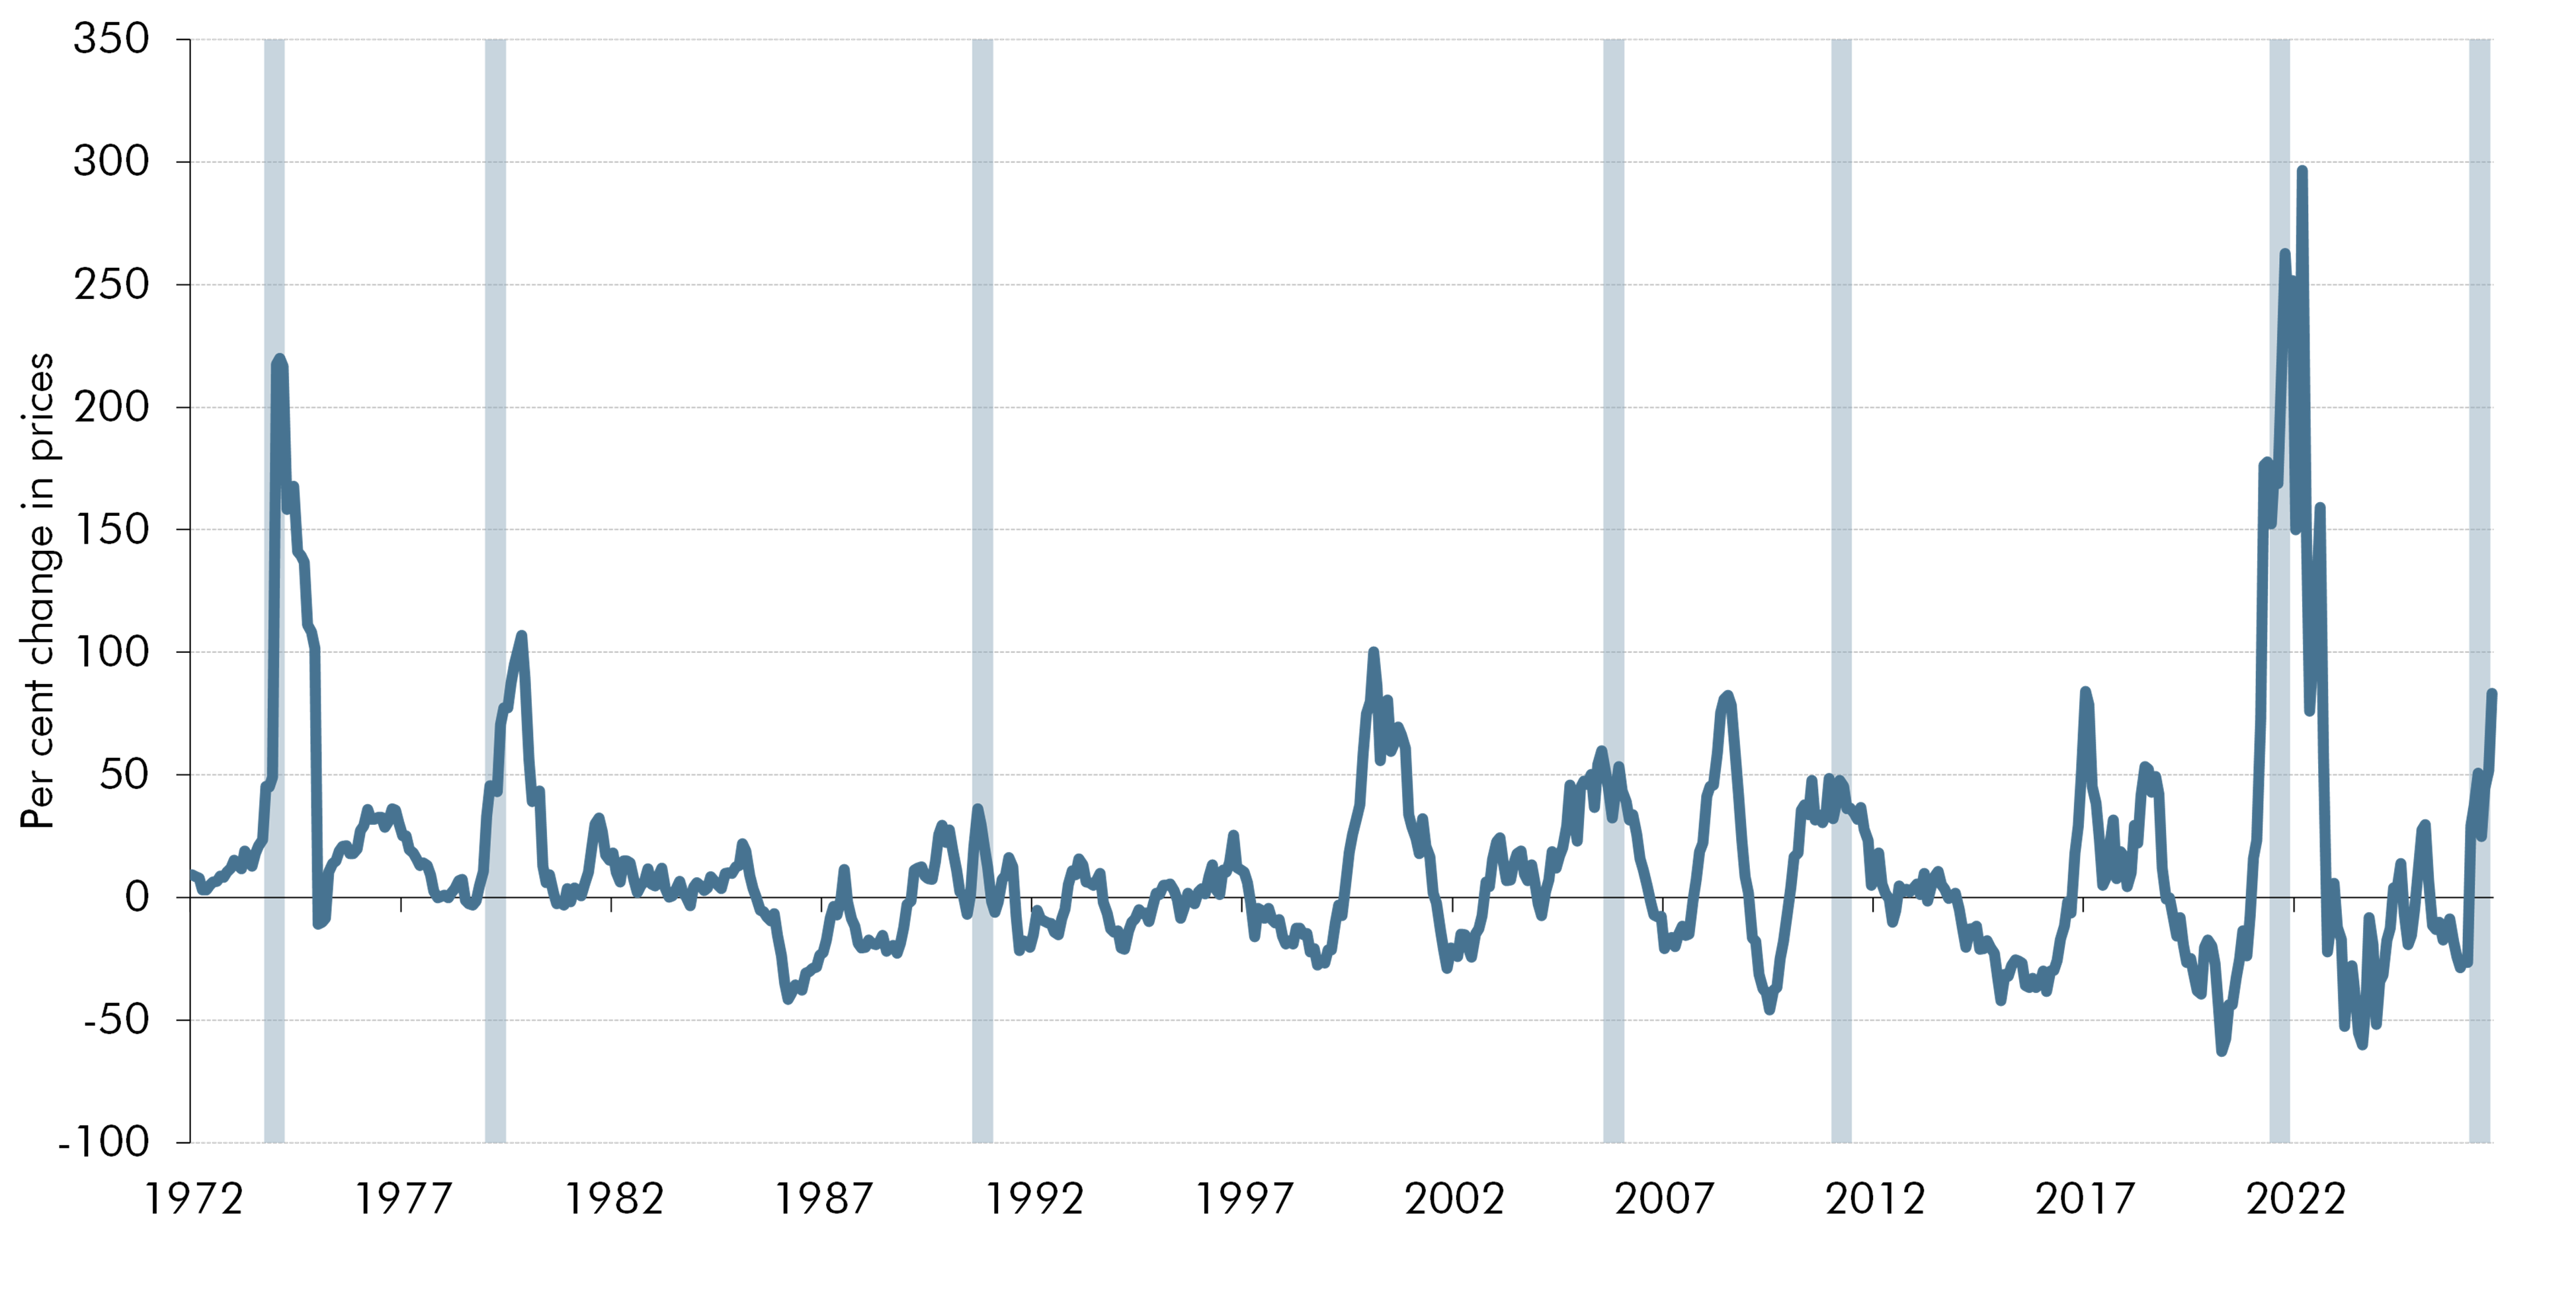
Note: Shaded areas represent historical energy price shocks based on Dhingra, S., Running on empty: Climate risks and the fragility of global energy and food supply chains, Bank of England, June 2026. The last data point on the chart is for September 2026.
Source: Bloomberg, DESNZ, World Bank, OBR
Structural changes in the UK’s energy usage influence the impact of energy price shocks on economic activity.c Since the 1970s:
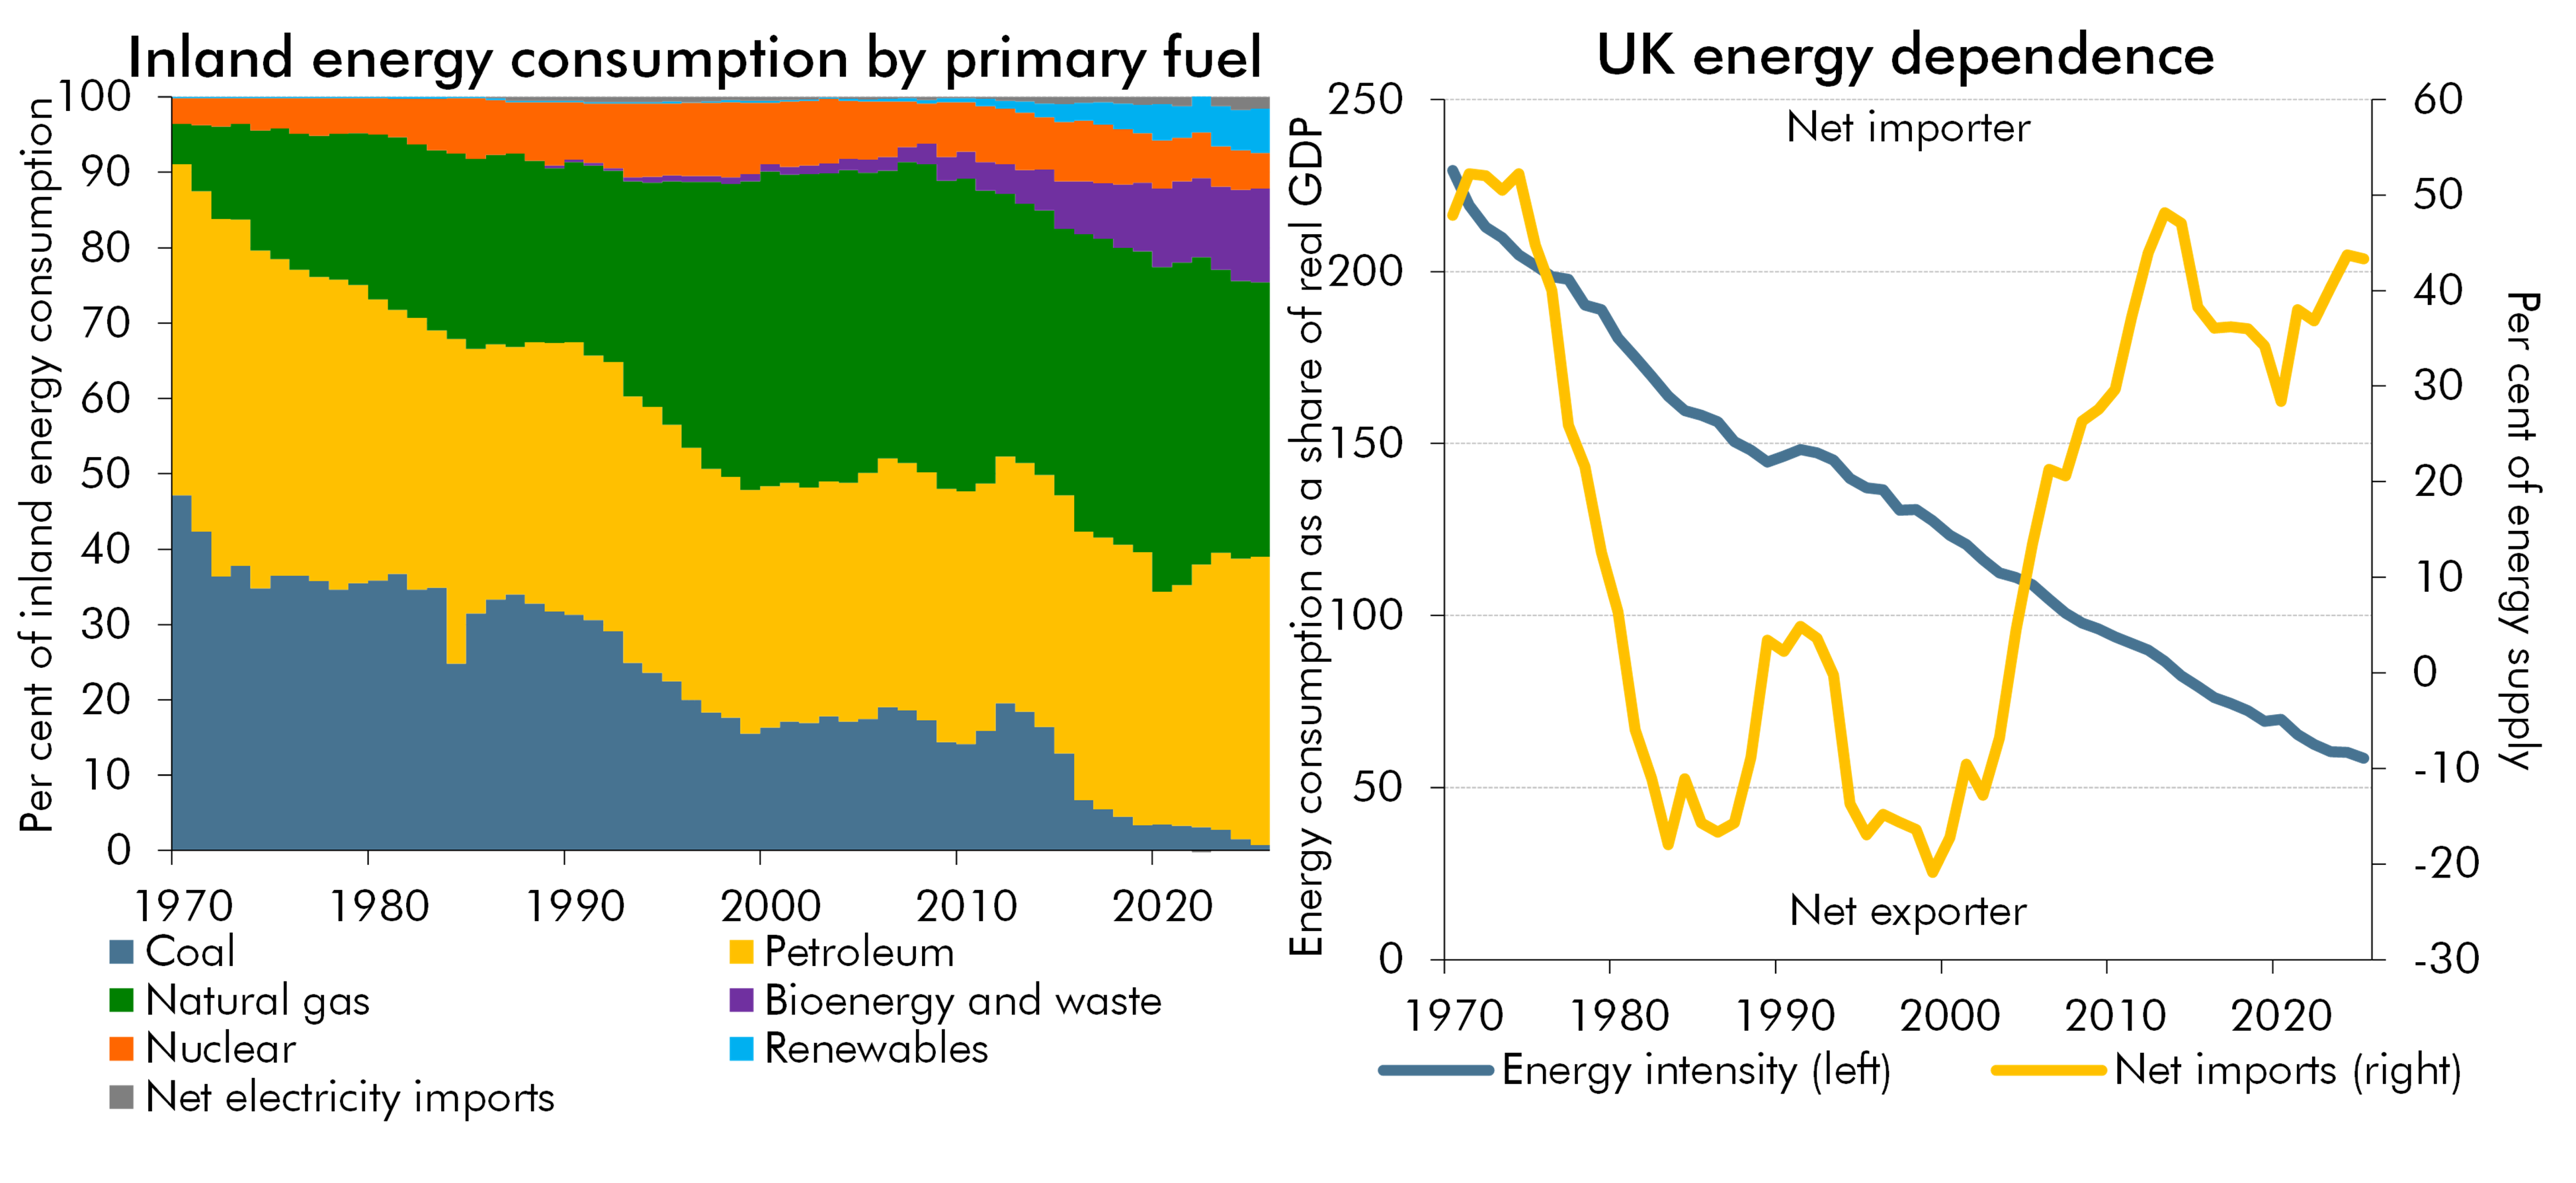
The UK’s energy mix has become more diverse, with the share of energy consumption from fossil fuels falling from 96 per cent in 1970 to 75 per cent in 2025 (Chart B, left panel). Coal has been nearly eliminated as an energy source and replaced by a combination of renewables and gas, with the latter’s supply disrupted by both the 2022 and 2026 shocks. In the long term, greater electrification of transport and heating is expected to shift direct energy demand further from oil and gas, and towards the increasingly renewable inputs used to produce electricity.d
The UK’s energy intensity has fallen significantly, with energy consumption per unit of real GDP now one quarter of its value in 1970 (Chart B, right panel). All else equal, this reduces the economy-wide impact of a given energy price shock. Reduced energy intensity reflects improvements in energy efficiency and changes in the composition of economic activity.
The UK’s reliance on energy imports has varied significantly. The right panel of Chart B illustrates how North Sea production turned the UK from a substantial net importer in the 1970s into a net exporter, before declining production reversed this from the mid-2000s. This drives the size and sign of the terms-of-trade shock when international prices vary, and therefore the scale of the effect on real incomes.
Chart B: Sources and dependence of UK energy since 1970
Note: In the right panel, energy intensity is calculated as tonnes in oil equivalent divided by real GDP (£ million, 2023 prices). Net energy imports are measured as a percentage of inland energy consumption of primary fuels plus marine bunkers. The latest data in both charts is for 2025.
Source: DESNZ, OBR
The pass-through of fossil fuel prices to electricity prices depends in part on marginal pricing, because the wholesale electricity price is set by the last and most expensive generator needed to meet demand. In the UK, this is often relatively expensive gas-fired generation, so higher gas prices can feed through to wholesale electricity prices even when most generation does not depend on gas. This link has weakened recently as the share of renewable generation has increased.e Furthermore, wholesale electricity and gas costs were only expected to make up 47 per cent of the average domestic consumer’s bill in the fourth quarter of 2026,f with the remainder from a combination of taxes, levies, and other costs. Consumers have been shielded from higher prices in recent years by bespoke government support and fuel duty not being uprated. Government support in 2022-23 totalled £52.2 billion.g
Underlying economic conditions also play a significant role in the ultimate economic impact of an energy price shock. Chart C illustrates that the labour market was considerably looser at the start of 2026 than at the start of 2022, with the vacancies-to-unemployment ratio at less than half of its 2022 level. Our estimated negative output gap of -1.0 per cent of potential output at the start of 2026, compared to a positive output gap of 2.1 per cent at the start of 2022, implies a much greater degree of spare capacity in the economy. Monetary policy was also looser in 2022, when Bank Rate was initially 0.5 per cent compared to 3.75 per cent. The 2022 shock also came when inflation was already high and rising, amid severe global supply chain disruption as the global economy rebalanced after the pandemic. Relative to 2022, these factors should reduce the risk of the current shock propagating strongly through wages and creating significant domestically generated inflation. However, the scale of second-round effects remains uncertain: for example, inflation expectations may now be more responsive to energy and food price movements after several years of above-target inflation.h
Chart C: Initial conditions for previous energy price shocks
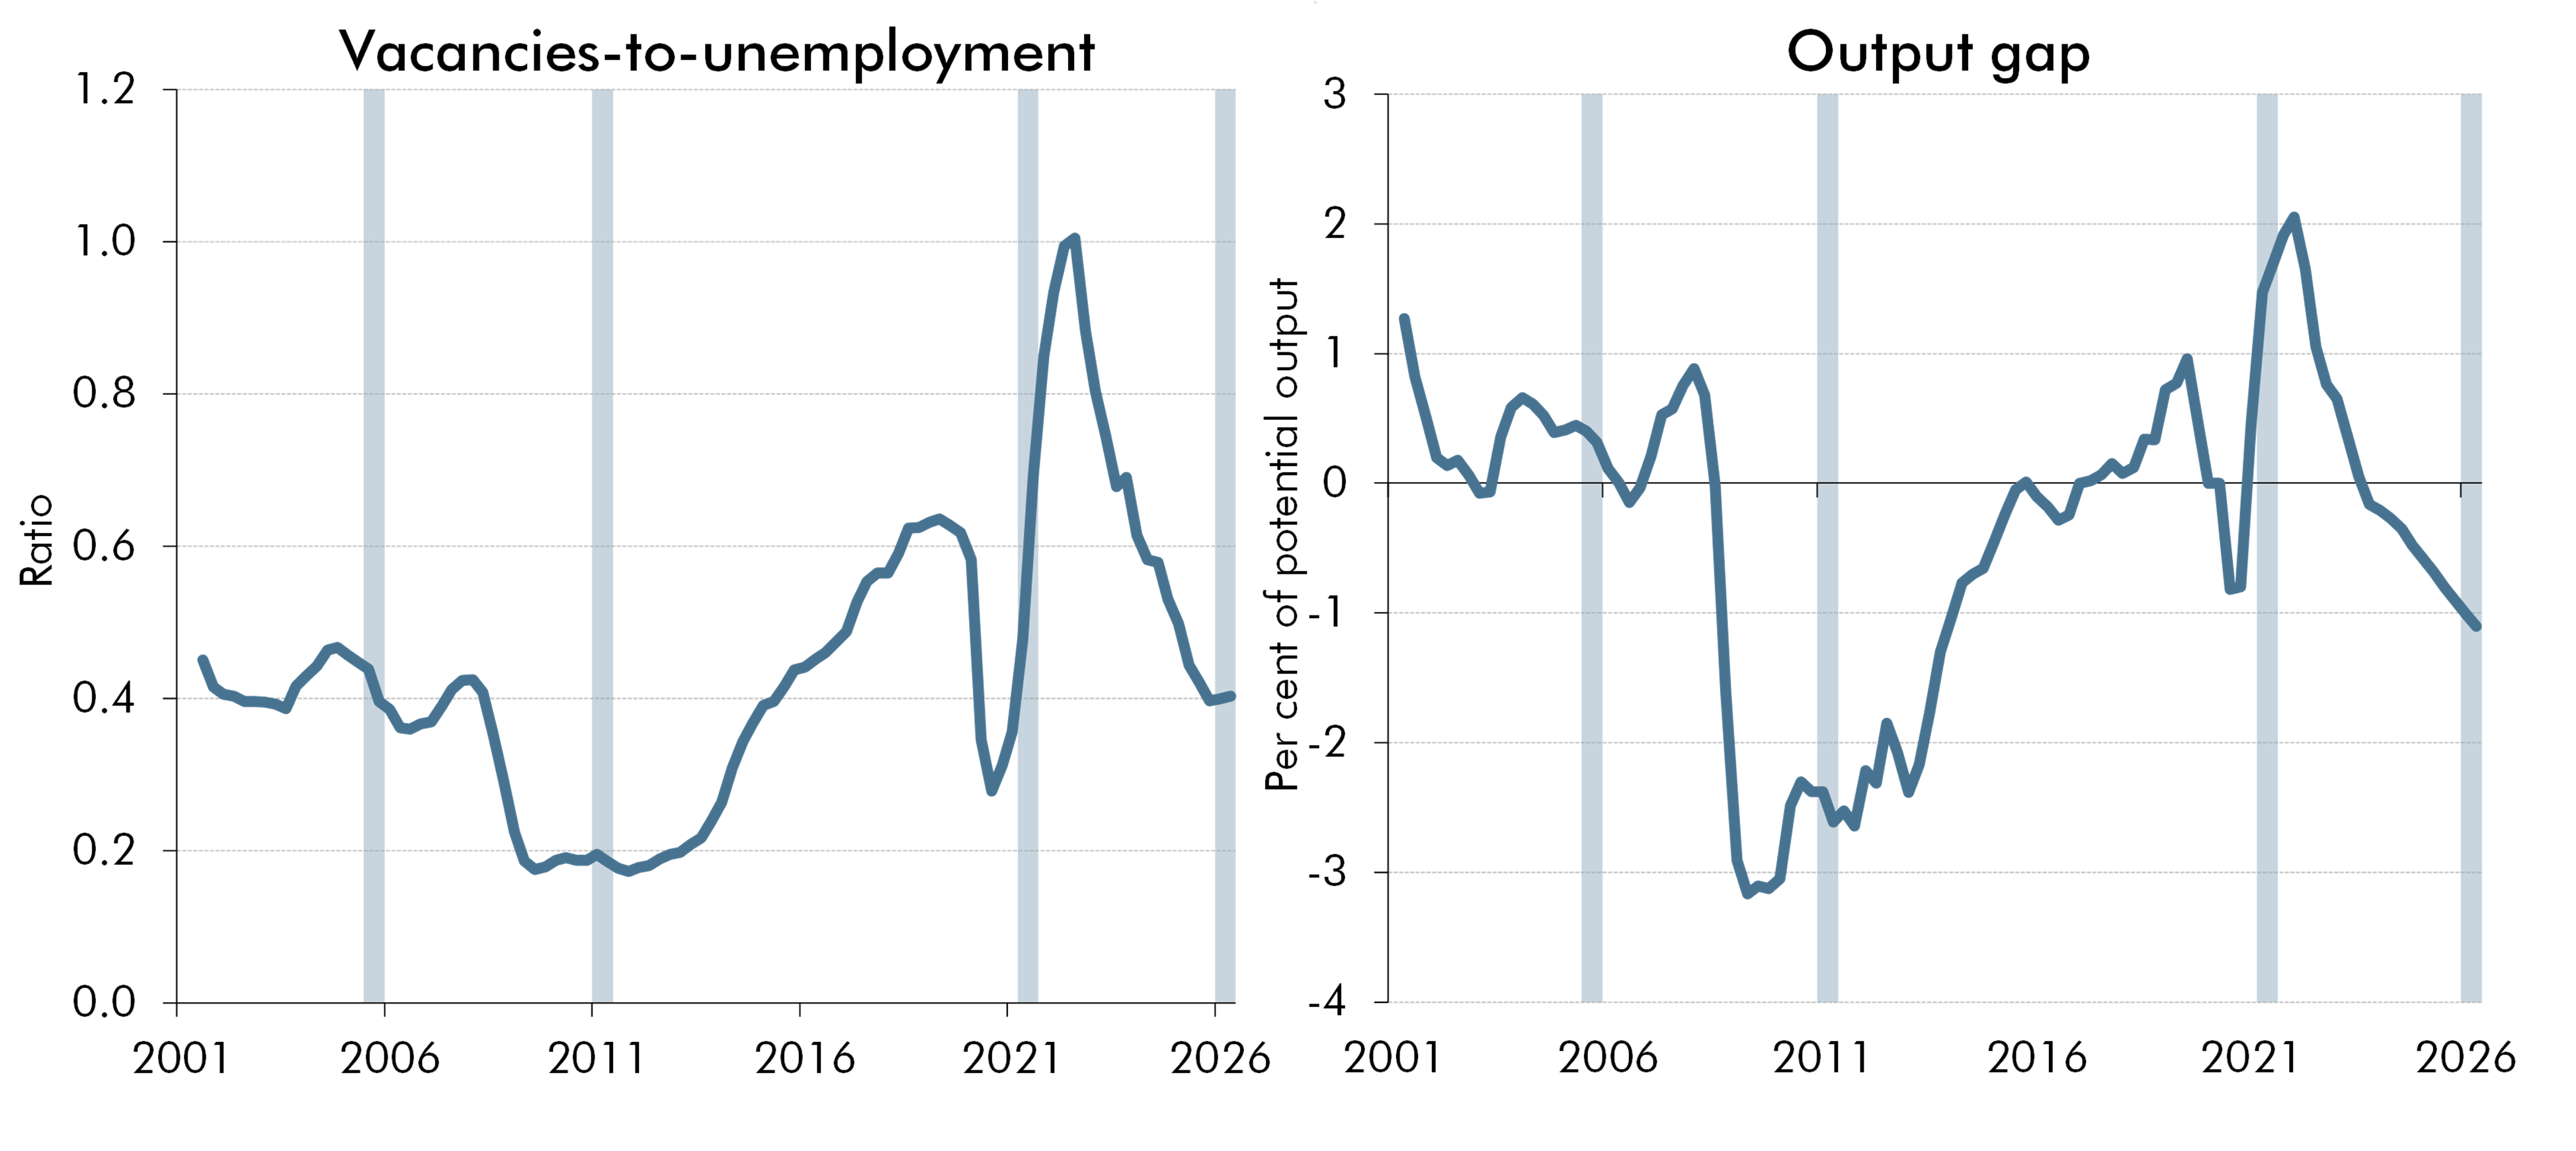
Note: Shaded areas represent the historical energy price shocks from Dhingra, S., Running on empty: Climate risks and the fragility of global energy and food supply chains, Bank of England, June 2026. The vacancies-to-unemployment ratio is a three-month rolling average.
Source: ONS, OBR
As the UK is a net importer of energy, the recent rise in global energy prices represents a negative terms-of-trade shock that will lower real incomes. But this latest shock is smaller than the 2022 episode and there is more spare capacity in the economy, which should reduce the peak and persistence of inflation. The size and limited duration of the shock, declining fossil-fuel exposure, and the decoupling of electricity and gas prices together mean we do not expect a permanent hit to potential output from the energy price paths conditioning our forecast.
a) The year-on-year change in fossil fuel prices in 2022 partly reflects an increase from a lower base after the pandemic.
b) For example, see D’Orazio, A., S. Emiliozzi, F. Ferriani, A. Gazzani, M. Taboga and G. Veronese, Energy markets under chokepoint stress: The 2026 Hormuz shock, VoxEU, CEPR, September 2026.
c) We previously explored these trends in depth in our 2022 and 2023 Fiscal risks and sustainability reports.
d) The market pricing for electricity futures we use to condition our forecast in the near term is likely to account for this decoupling.
e) The proportion of time in which gas sets the wholesale price for electricity is not directly observed and therefore uncertain, but recent government estimates suggest this has fallen from around 90 per cent of the time in the early 2020s, to around 60 per cent today. See McCluskey, K., R. Carmichael, A. Rhodes, R. Gross and W. Blyth, The cost of electricity in the UK: drivers, challenges and opportunities for reform, UK Energy Research Centre, July 2026.
f) See ‘Summary of changes to the energy price cap: 1 October to 31 December 2026’ on Ofgem, Energy price cap (default tariff) levels (accessed October 2026). The wholesale cost share of a consumer’s bill is for direct debit customers and includes Contracts for Difference (CfDs).
g) See Box 3.1 of our October 2023 Forecast evaluation report.
h) For example, see Mann, C., Holding the anchor in turbulent waters, Bank of England, March 2025.
Interest rates
2.9 Chart 2.2 shows that market pricing for Bank Rate and gilt yields has increased significantly since our March forecast:[footnote 1]
-
Our central economy forecast is conditioned on Bank Rate reaching just over 4¼ per cent by mid-2027 and just over 4½ per cent by the end of the forecast. On average, this is just under ¾ of a percentage point higher than our March forecast. In our fiscal forecast, Bank Rate is on average just over a further ¼ of a percentage point higher.
-
Gilt yields have also risen substantially across all maturities since our March forecast. On average, yields are just over ½ a percentage point higher in our economy forecast, and a further ¼ of a percentage point higher in our fiscal forecast.
2.10 Since the start of the conflict in the Middle East, interest rates have fluctuated significantly. Between the onset of the conflict and 20 October, market pricing for Bank Rate in late-2027 has ranged from 3½ per cent to 5 per cent. Gilt yields at the 10-year mark have ranged from around 4½ per cent to 5½ per cent over the same period. The assumptions in our fiscal forecast and the latest market pricing at the time we finalised this report sit close to the top of these ranges.
Chart 2.2: Interest rates
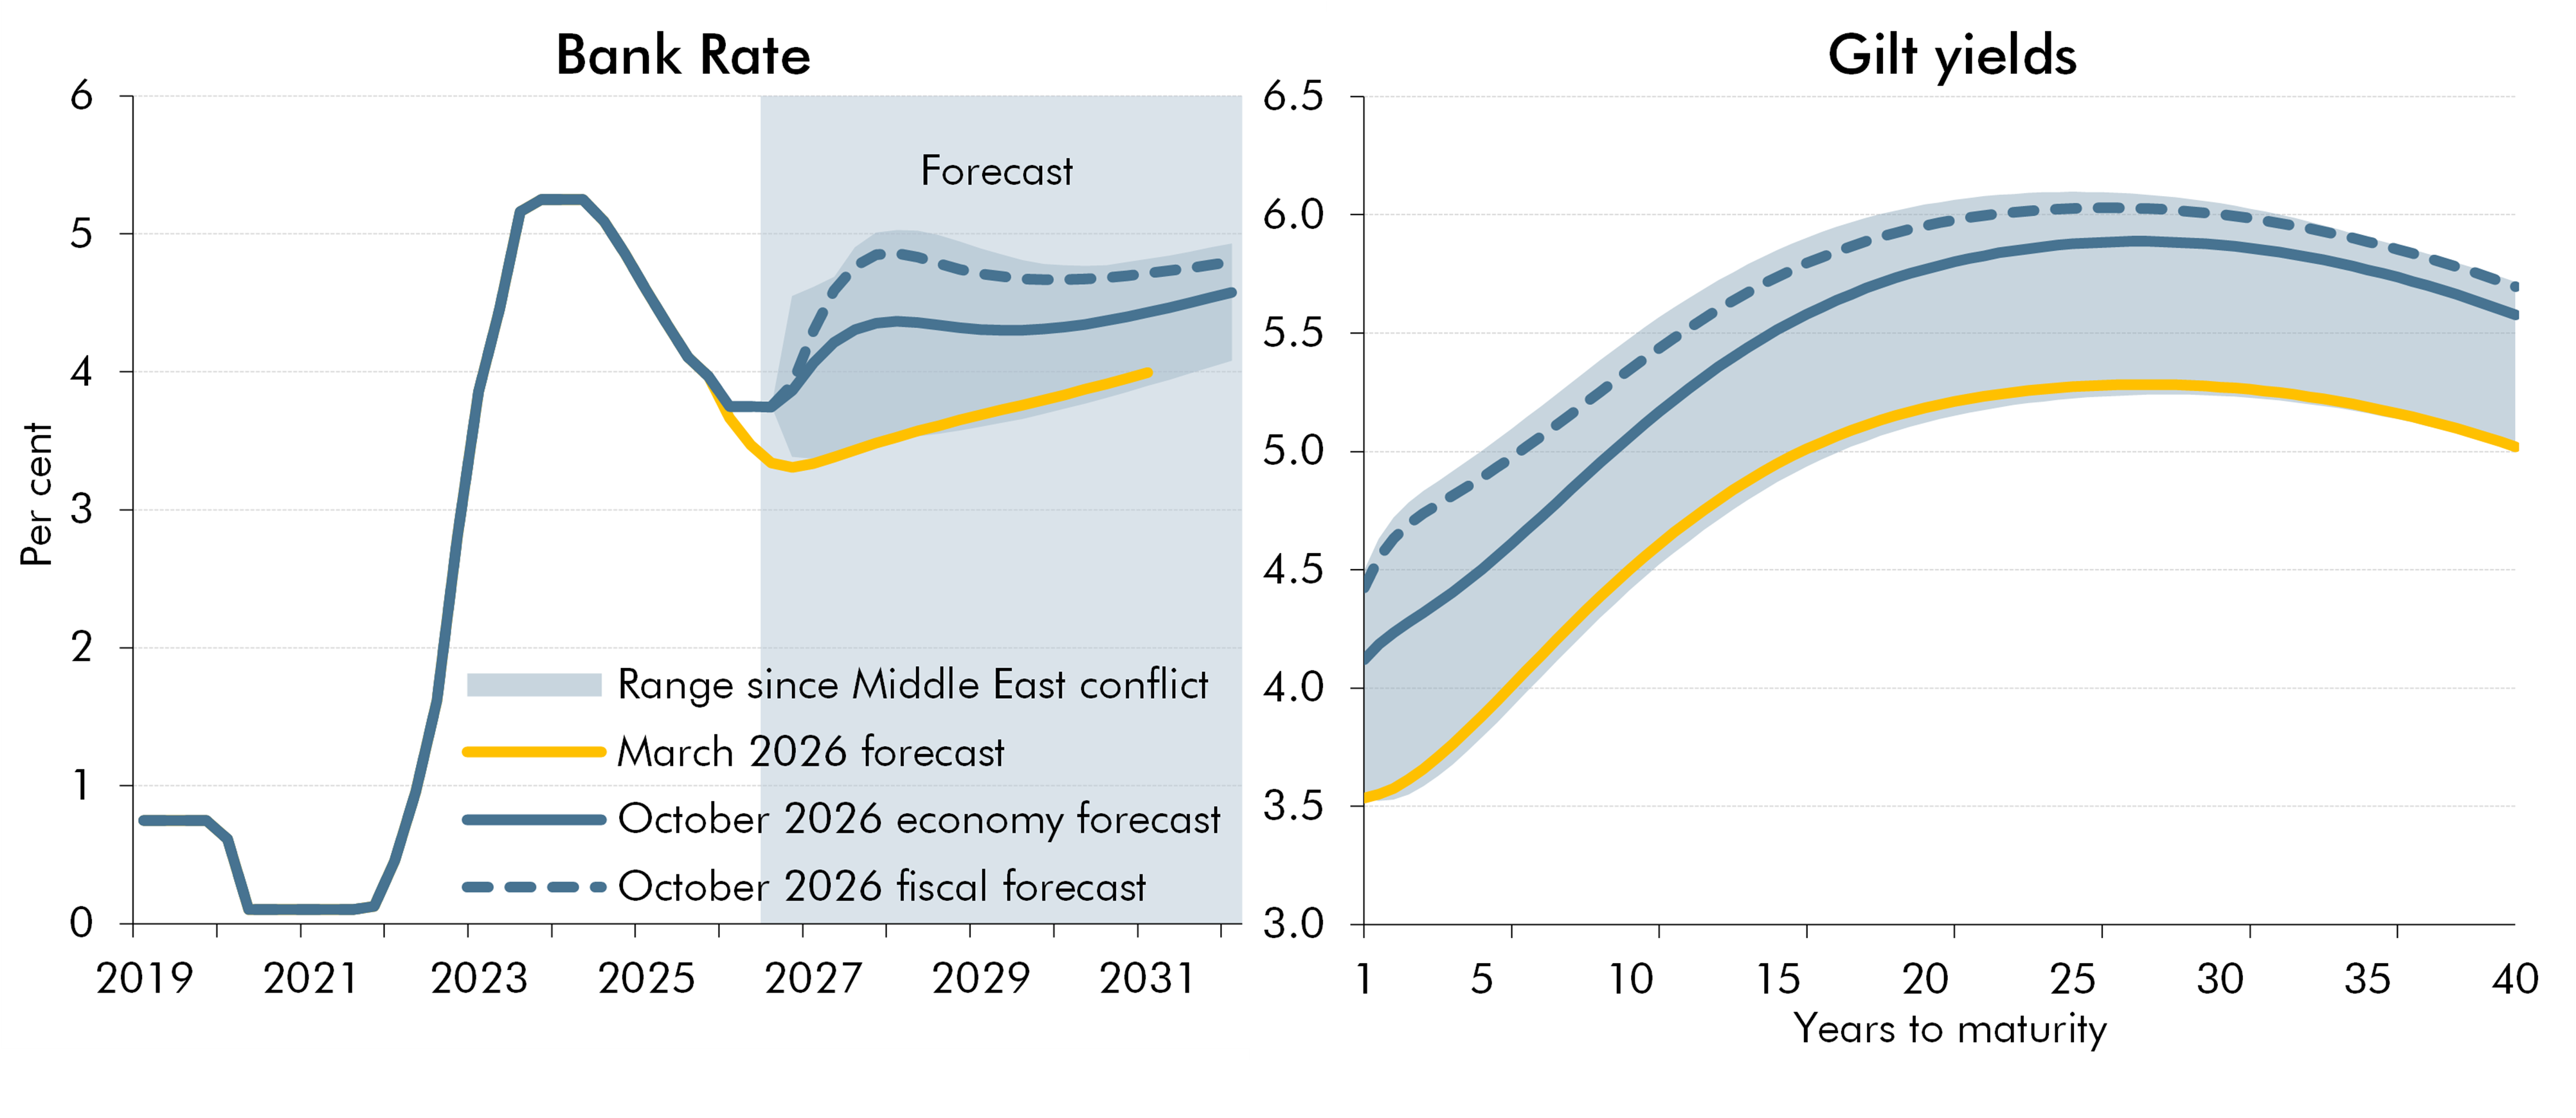
Note: October 2026 economy forecast uses 10 working days to 19 August, October 2026 fiscal forecast uses five working days to 15 September, and March 2026 forecast uses the 10 working days to 22 January. Range since Middle East conflict is range between 2 March and 20 October.
Source: Bank of England, OBR
2.11 Chart 2.3 shows that nominal and real 10-year government bond yields have risen in all G7 economies since March. This is likely to partly reflect the impact of higher energy prices on inflation and on monetary policy expectations, and rises in real yields. Some commentators have also pointed to sustained, large fiscal deficits in many advanced economies and competition for financing from increased AI investment as factors pushing up yields. The increases in UK nominal and real gilt yields since March (around 1¼ and ¾ of a percentage point respectively) are within the range of other G7 economies, suggesting recent UK market movements largely reflect common developments across advanced economies.
Chart 2.3: International comparison of 10-year government bond yields
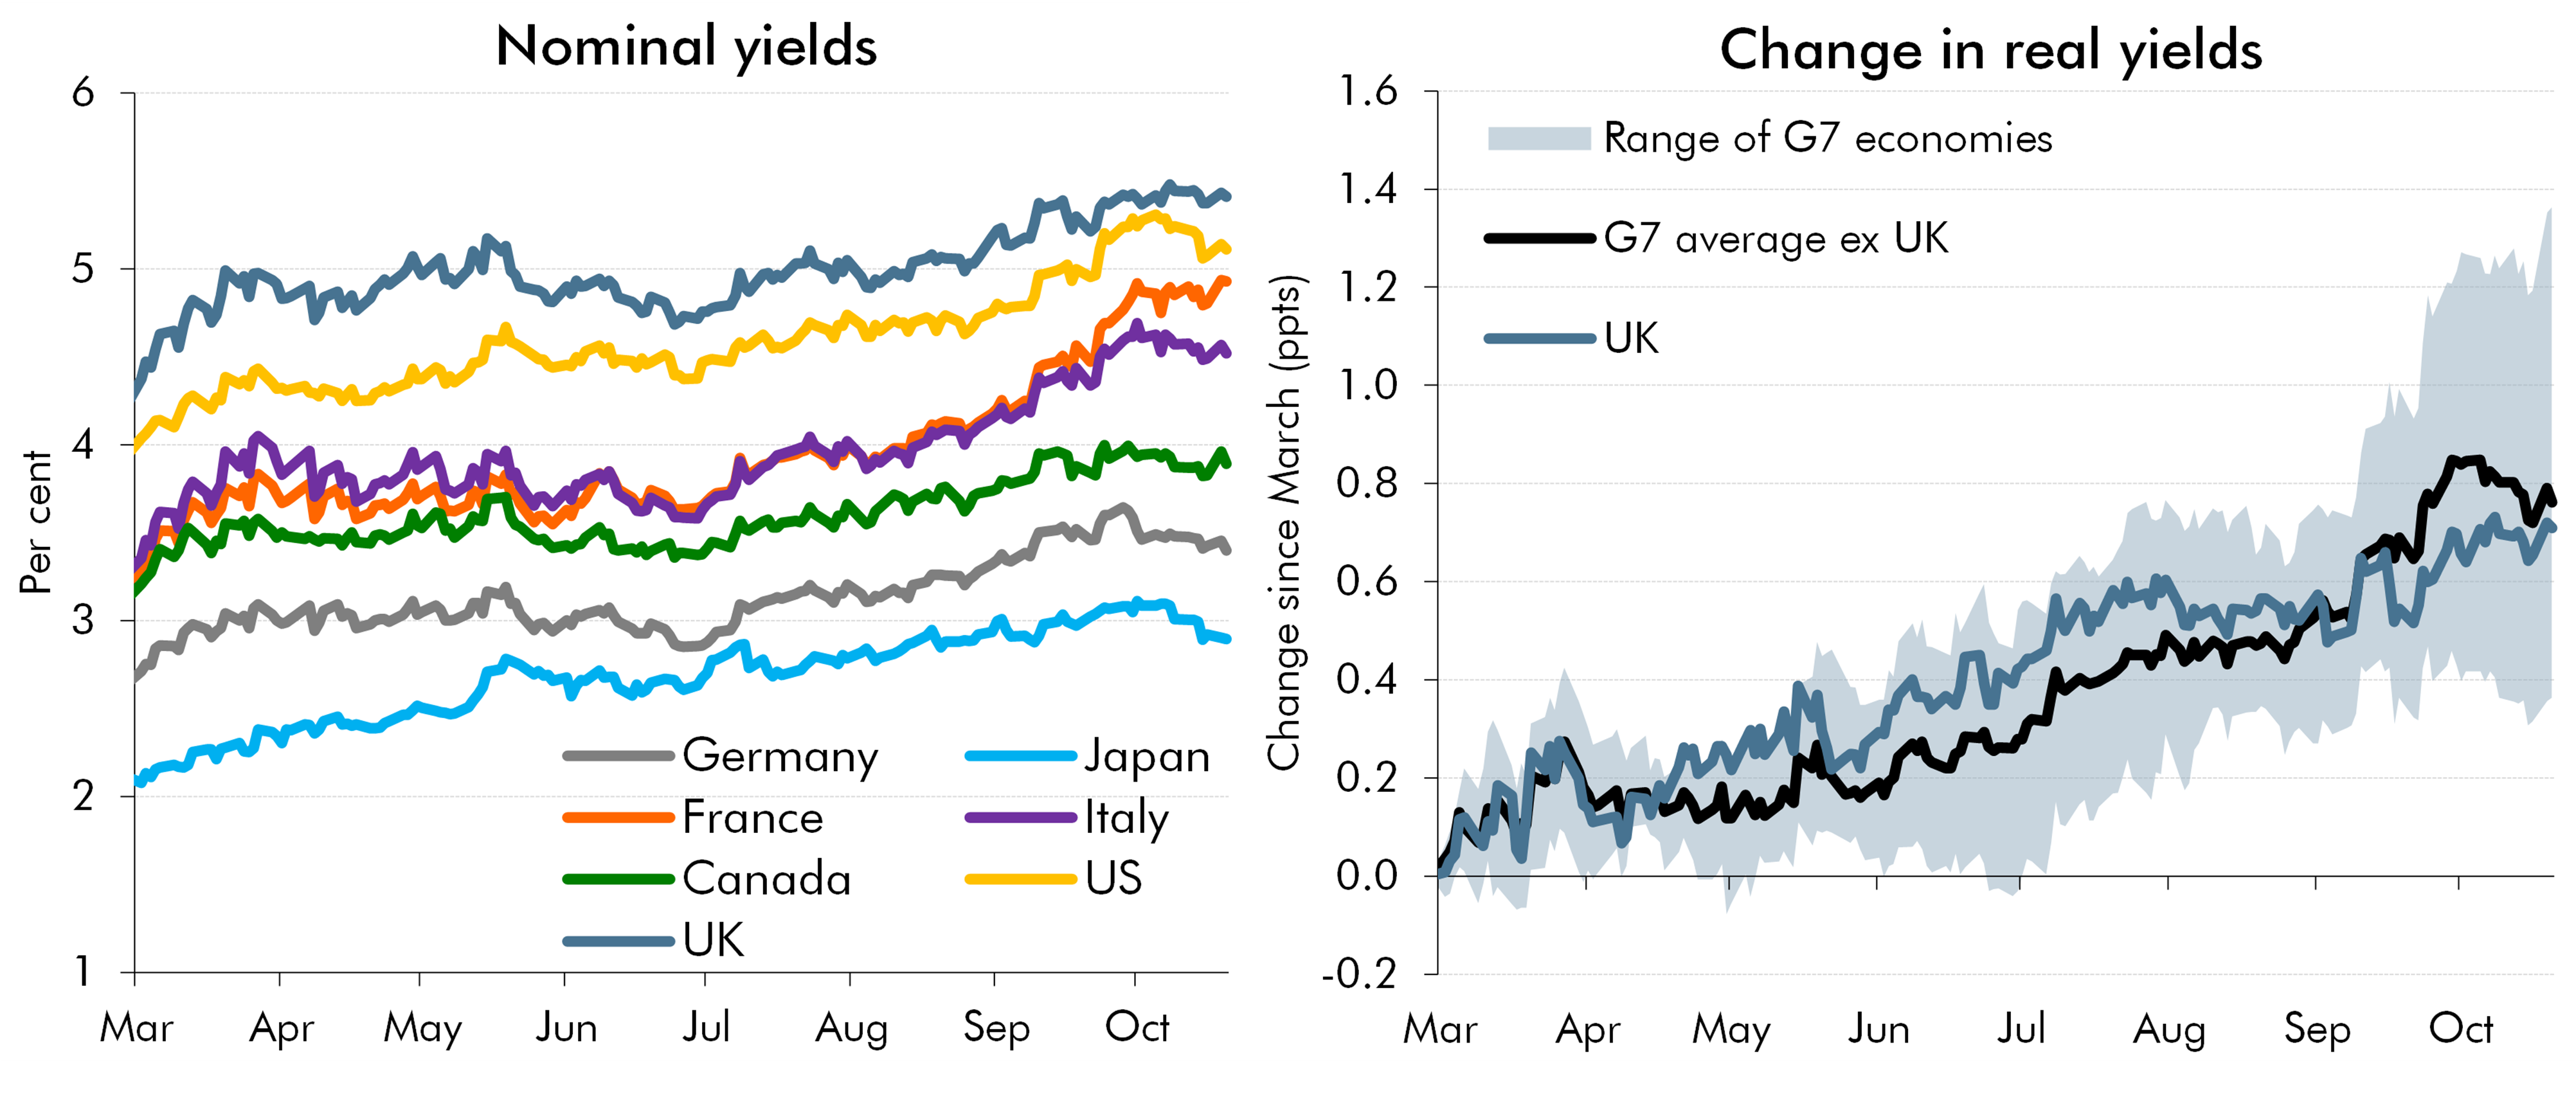
Note: On both charts, the first data point is 27 February 2026, and the last data point is 20 October 2026.
Source: Bloomberg, OBR
2.12 However, interest rates at all maturities in the UK have been consistently among the highest in the G7 since 2022, having been toward the middle of the pack in the decade prior. Drivers of this likely include:
-
Recent episodes of higher and more persistent inflation than in other advanced economies. CPI inflation in the UK averaged 9.1 per cent in 2022, the highest in the G7 versus an average of 6.4 per cent across the rest of the group. UK inflation has remained among the highest in the G7 since then.
-
The UK’s higher level of borrowing resulting in a larger increase in net debt than other advanced economies. Between 2019 and 2025, the UK’s net debt-to-GDP ratio on an internationally comparable basis increased by 19 percentage points, significantly above the 5 percentage point average for other G7 economies.
-
Structural changes in the composition of demand for gilts, as set out in our 2025 Fiscal risks and sustainability report (FRS). The decline of defined benefit pension schemes and the Bank of England’s continued quantitative tightening have reduced gilt holdings of pension funds and of the central bank. We found that expected shifts in gilt demand toward more price-sensitive foreign investors could increase the overall interest rate on UK government debt by close to 1 percentage point over the next 50 years, though markets may already have priced in some of this impact.
2.13 Despite these substantial rises over recent years, interest rates are not high by historical standards. The 2010s, in which Bank Rate was close to the zero-lower bound and quantitative easing reduced longer term gilt rates to multi-decade lows, was historically unprecedented. Current levels are close to historical experience – since 1935, 10-year gilt yields have averaged around 6 per cent.
Equity prices
2.14 Equity prices, measured by the FTSE All-Share index, are around 1½ per cent higher on average than in our March forecast. We assume that equity prices grow in line with nominal GDP over the forecast. Valuations, measured by price-to-earnings (P/E) ratios, remain around historical averages in the UK, while US equity valuations remain elevated. However, as global equity markets are highly correlated, a potential correction in equity valuations elsewhere poses a downside risk to our forecast. We explored the potential impacts of a negative shock to equity prices in our Autumn 2025 EFO.
World economy, trade and the exchange rate
2.15 Our central forecast, based on the IMF’s July 2026 World Economic Outlook Update and April 2026 World Economic Outlook (WEO), is for global GDP to increase by 3.0 per cent this year, down from 3.4 per cent in 2025. This is unchanged from our March forecast. The IMF July WEO Update noted that the impact of tariffs has been more muted than expected, while the energy shock has been partly offset by momentum in the technology sector due to the growth and adoption of AI. Global GDP growth thereafter averages around 3 per cent a year. Global trade is expected to increase by 3½ per cent in 2026 and 4¼ per cent in 2027 before averaging around 3 per cent a year over the rest of the forecast.
2.16 US tariff policy continues to be restrictive compared to recent experience. Changes in US tariff policy since July have reduced the relative advantage previously held by UK exporters. Chapter 3 discusses the potential impacts of recent changes to UK trade policy.
2.17 Since our March forecast, the pound has appreciated ½ per cent against the dollar (to 1.35 dollars per pound) and 2 per cent against the euro (to 1.17 euros per pound). We assume that exchange rates are unchanged over our forecast. As a result, the trade-weighted sterling effective exchange rate remains about 1¼ per cent higher across the forecast period compared to our March forecast.
Fiscal policy
2.18 In the central forecast, public sector net borrowing falls from 4.4 per cent of GDP in 2025-26 to 1.8 per cent of GDP in 2031-32, but is higher than in our March forecast in every year. The primary balance (public sector non-interest revenue minus non-interest expenditure) moves from a deficit of 1.5 per cent of GDP in 2025-26 to a surplus by 2028-29, and reaches a surplus of 1.7 per cent of GDP in 2031-32. The drivers of reduced borrowing over the forecast are discussed in Chapter 6.
2.19 Policy measures increase borrowing modestly as a share of GDP from 2026-27 to 2028-29, and slightly reduce it thereafter. We judge that these changes in borrowing will not have a material impact on real GDP growth that would justify an explicit adjustment to the forecast. This is due to the relatively moderate size and profile of the changes in borrowing, and because some measures were announced prior to the Budget (see paragraph 3.9). The wider impacts of policy measures are discussed in more detail in Chapter 3.
Inflation
2.20 CPI inflation has fallen by less than we expected in March, reaching 3.1 per cent in the third quarter of 2026, 1 percentage point above our March forecast. In the 12 months to September 2026, CPI inflation was 3.5 per cent. Higher-than-expected inflation has largely been driven by the direct effects of higher utilities and fuel prices.
2.21 As illustrated in Chart 2.4, we expect that the recent rise in energy prices will keep CPI inflation above the Bank of England’s 2 per cent target in 2026 and 2027. In our central forecast, CPI inflation increases from around 3.1 per cent in 2026 to 3.4 per cent in 2027, with a quarterly peak of 3.8 per cent in early 2027.[footnote 2] Policy measures reduce CPI inflation by 0.1 percentage points in 2027 and increase it by around the same amount in 2028 – this is discussed in more detail in Chapter 3. We expect inflation to fall back to target halfway through 2028 in our central forecast, as energy prices fall based on the market pricing that our economy forecast is conditioned on.
2.22 The near-term outlook for inflation is significantly higher than in our March forecast, primarily driven by:
-
the direct effect of higher energy prices on fuel prices and utilities – in our forecast the Ofgem energy price cap peaks at around £1,875 in Q1 2027;[footnote 3]
-
the indirect effects of higher energy prices on the production and transportation costs of other goods and services, compounded by broader commodity price pressures – including from elevated fertiliser prices and increases in cereal and metals prices – which could feed through to the price of food and other tradable goods; and
-
some second-round effects from higher inflation through earnings, as workers attempt to protect their real wages – but we assume that these will be smaller than for the 2022 energy shock because the labour market is significantly looser, the rise in energy prices is smaller and market pricing suggests it will be less persistent.
2.23 There is significant uncertainty around our inflation forecast, mainly due to the evolving situation in the Middle East. Our central forecast is conditioned on market pricing for oil and gas from mid-August. We explore scenarios for different energy price paths in Chapter 7. If energy prices are significantly higher than the path assumed in our forecast, we would expect larger direct and indirect effects on CPI inflation, and potentially larger second-round effects. Conversely, an orderly resolution of the conflict could mean that inflation falls more quickly than expected. The extent to which higher energy prices generate second-round effects through wages is also highly uncertain and particularly important for the fiscal forecast, given the high effective tax rate on labour income and that income tax thresholds are currently frozen.
2.24 Other risks to the CPI inflation forecast include the degree to which a particularly strong El Niño phenomenon disrupts global food production and puts upward pressure on food prices. Based purely on past forecast errors, Chart 2.4 suggests there is a one-in-five chance that CPI inflation in 2027 will be above 4½ per cent and a similar probability it will be below 2½ per cent.
Chart 2.4: CPI inflation
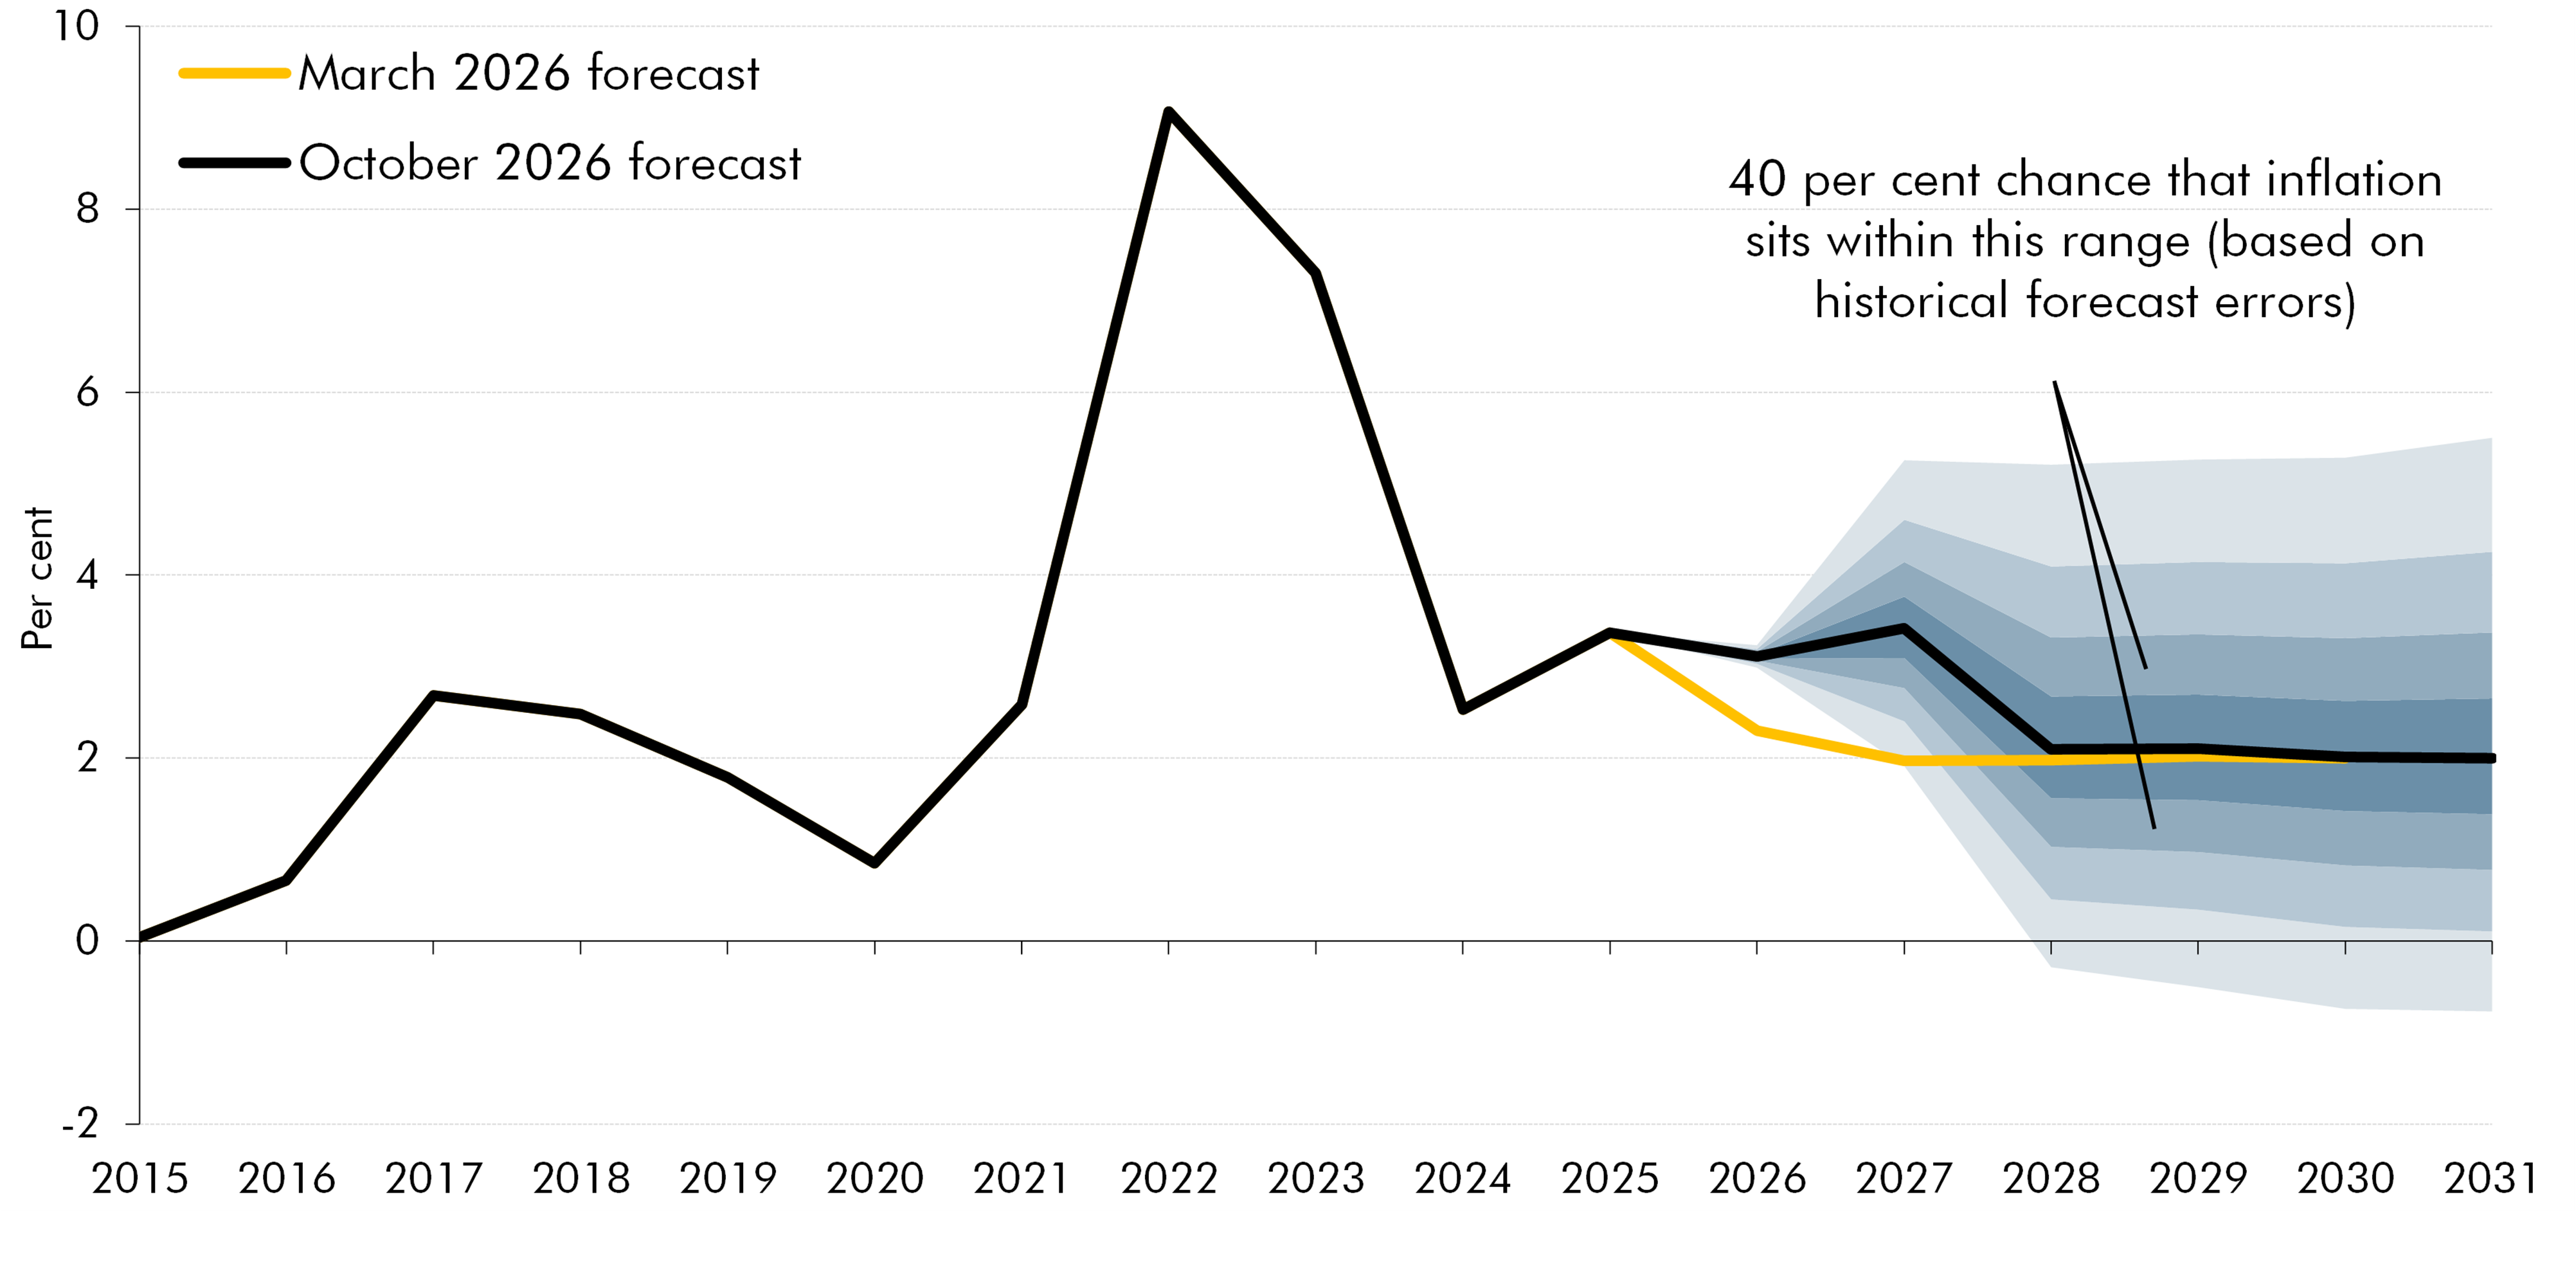
Note: The chart shows annual average CPI inflation. The forecast starts from 2026. The fan chart uses past forecast errors, assumes that these are representative of future errors, and does not take into account the current level of uncertainty. Successive pairs of lighter-shaded areas around our central forecast represent 20 per cent probability bands.
Source: ONS, OBR
2.25 In our central forecast, RPI inflation increases from around 3½ per cent this year to around 4¼ per cent in 2027, before falling back to 3 per cent in 2028, broadly in line with the shape of the CPI inflation path. We then expect RPI inflation to drop to 2¼ per cent in 2030 as the ONS converges the RPI measure to CPIH (see Box 2.3 of our October 2024 EFO for a more detailed explanation of this change).
2.26 We expect the GDP deflator, which measures the price of all domestically produced goods and services, to grow by 3 per cent in 2026. The GDP deflator is affected by energy prices directly to the extent that energy is produced in the UK and indirectly to the extent that energy prices create second-round effects on the price of other goods and services through increased average earnings. We expect the growth in the deflator to fall to around 2¼ per cent in 2027 and around 2 per cent on average from 2028 onward, as energy prices – and, in particular, the second-round effects of those price rises – fall back. Compared to our March forecast, we project that cumulative growth in the GDP deflator between 2025-26 and 2030-31, an important determinant of our receipts forecast, will be around 1 percentage point higher.
Earnings and income growth
Average earnings
2.27 Nominal and real average earnings growth in 2025 has been revised down by around a percentage point by the ONS since our March forecast. In our central forecast, we anticipate that nominal earnings growth will continue to slow in the near term, partly due to looser labour market conditions (left panel of Chart 2.5). But we expect a more gradual slowdown than in March, reflecting a judgement that there will be some second-round effects of higher inflation through wage growth, as workers attempt to protect their real wages. We judge that these effects will be modest relative to the previous energy price spike in 2022, as a significantly looser labour market restricts workers’ capacity to bargain for higher wages. This is reflected in recent survey evidence, with firms increasingly expecting limited upward pressure on wages.[footnote 4] The market pricing underpinning our forecast also suggests that the increase in energy prices will be smaller and less persistent than in 2022, which should further limit the size of second-round effects.
2.28 Second-round effects on wage growth have particularly important fiscal implications, given that income tax thresholds are currently frozen and labour income has the highest effective tax rate of any tax base. The size of these effects is uncertain and will depend on a number of factors including: the size of the energy price shock relative to the market pricing that our forecast is conditioned on; whether workers’ inflation expectations respond more or less than we assume to rising inflation; the monetary and fiscal policy response to the shock; and the degree to which a relatively loose labour market restricts workers’ capacity to bargain for higher wages. We explore the impact of stronger second-round effects in our energy price scenarios in Chapter 7.
2.29 Taken together with our forecast for inflation, this means that we expect lower near-term growth in real earnings than in March. We expect no growth in real earnings in 2027 and 2028. Over the medium term, real wage growth recovers to around ½ a per cent a year by 2030 in our central forecast (right panel of Chart 2.5). This is slightly weaker than growth in output per worker as we expect firms to rebuild profit margins, which allows the rate of return on capital to recover. This, in part, reflects our assessment in our October 2024 forecast – we expect firms to pass on an increasing share of the Autumn Budget 2024 employer NICs increase to workers, rather than absorbing it in lower profits.
Chart 2.5: Nominal and real earnings growth
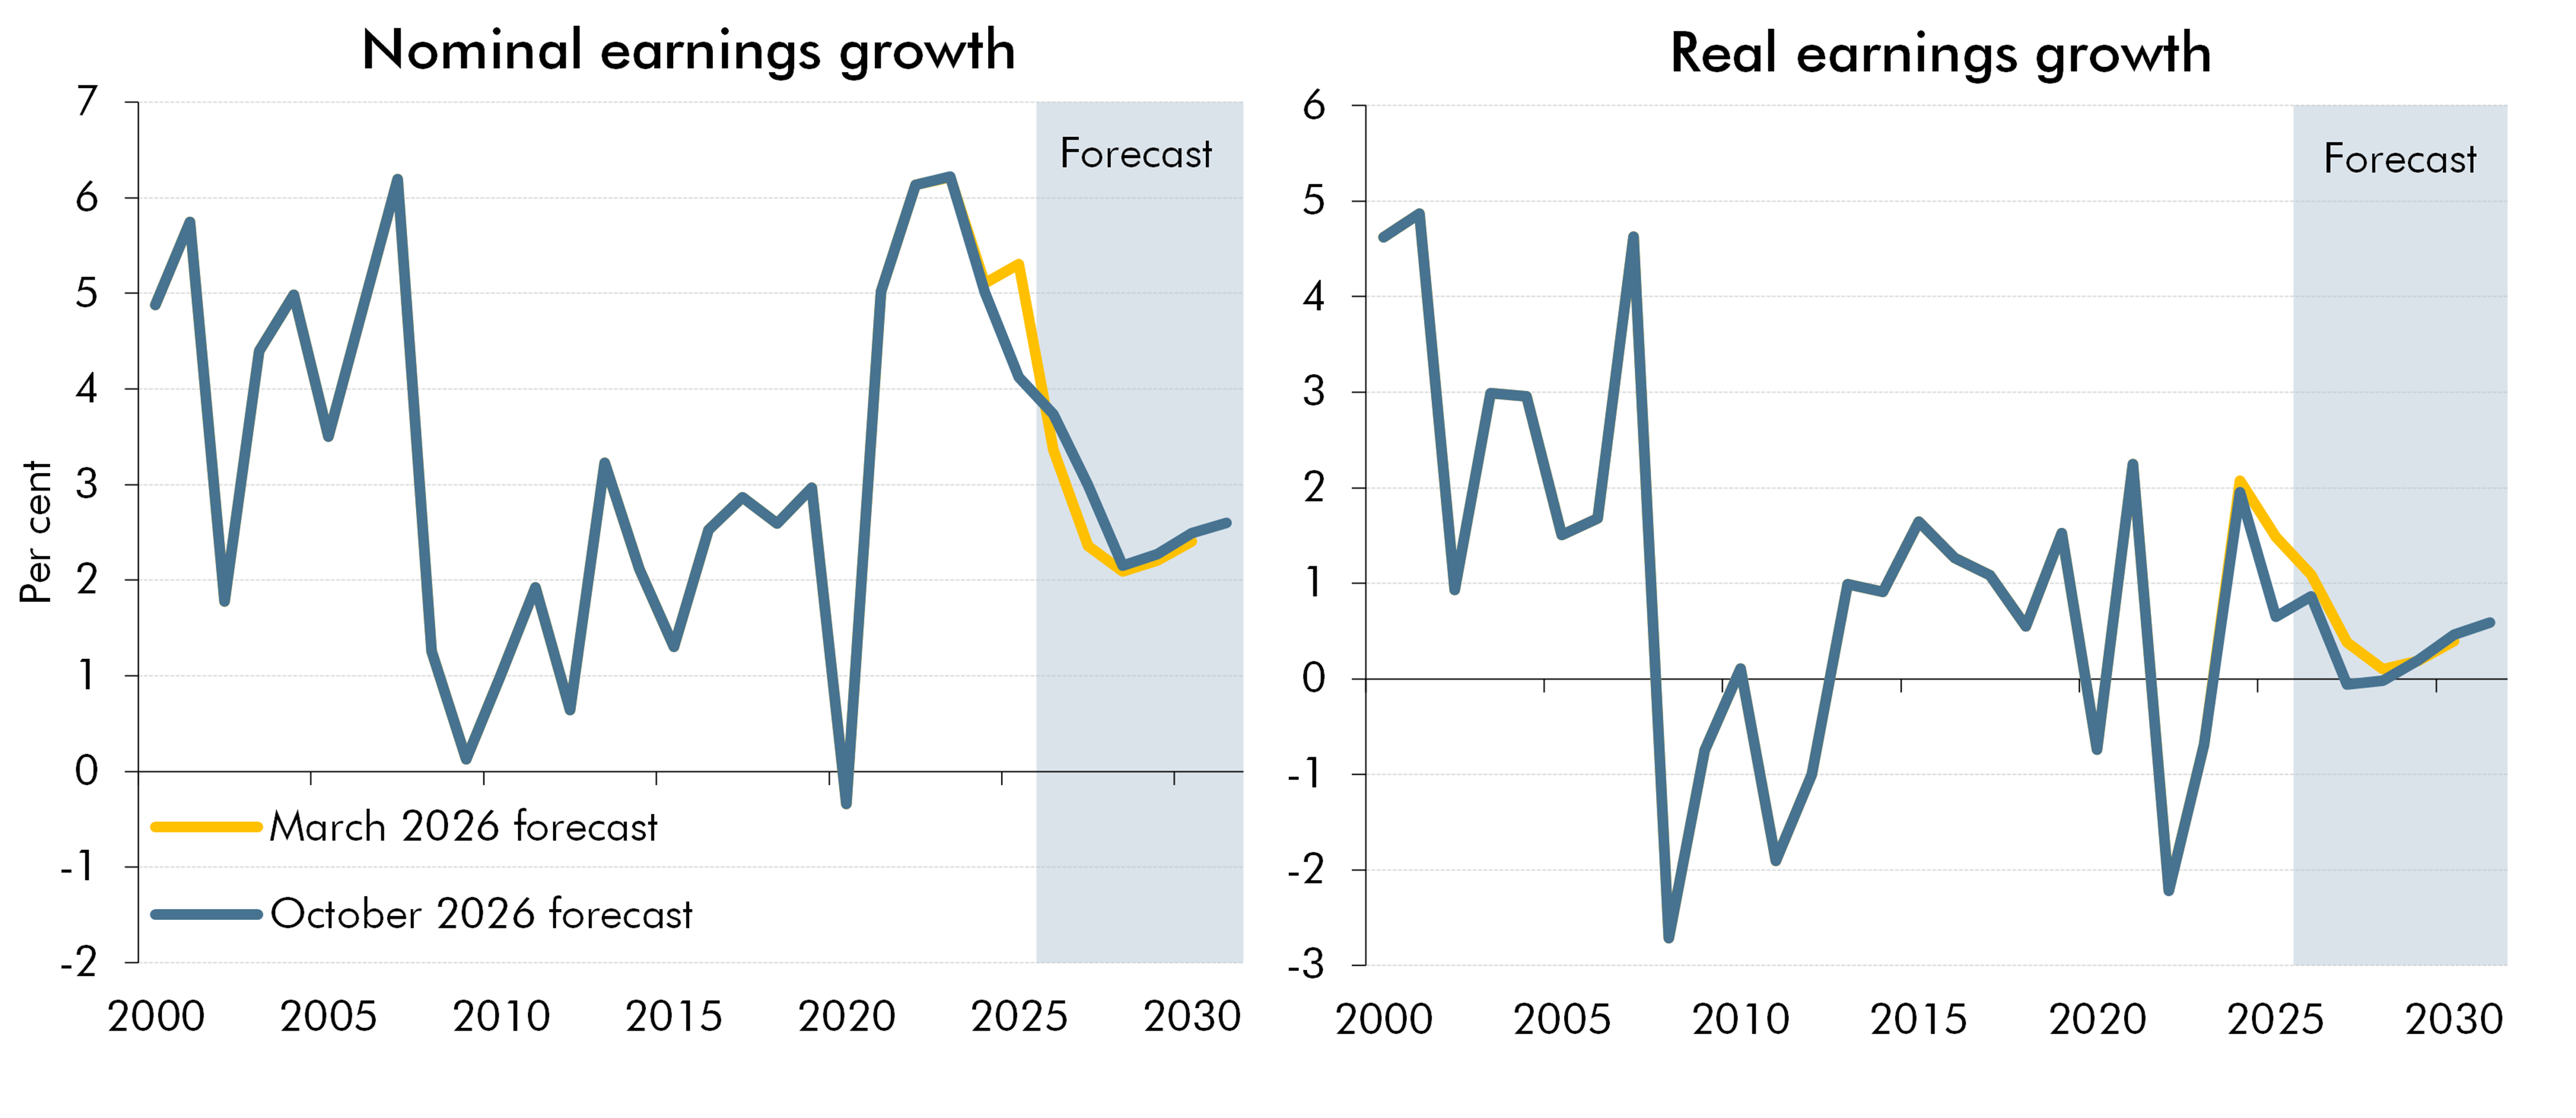
Note: Nominal earnings are wages and salaries divided by the number of employees. Real earnings are deflated using the private consumption deflator.
Source: ONS, OBR
Real household disposable income
2.30 In our central forecast, real household disposable income (RHDI) per person, a useful though incomplete measure of living standards,[footnote 5] falls slightly in the near term. The left panel of Chart 2.6 shows the contributions to growth in RHDI per person, with labour income, non-labour income, and social benefits all boosting income. But across last year and this year, these factors are outweighed by higher prices and taxes on income and wealth. In terms of economic drivers, this near-term weakness is driven by the negative terms-of-trade shock, which pushes down on real wage growth, but up on nominal wage growth. The latter then weighs on RHDI because frozen income tax thresholds increase the degree to which effective tax rates rise as nominal earnings increase.
2.31 In the medium term, the expected fall-back in energy prices means RHDI per person partly recovers. Growth over the last four years of the forecast averages around ¾ of a per cent a year, broadly in line with the average since 2010. But the right panel of Chart 2.6 shows that the level of RHDI per person is forecast to remain more than ¾ of a per cent below the March profile in 2030-31.
Chart 2.6: Real household disposable income per person
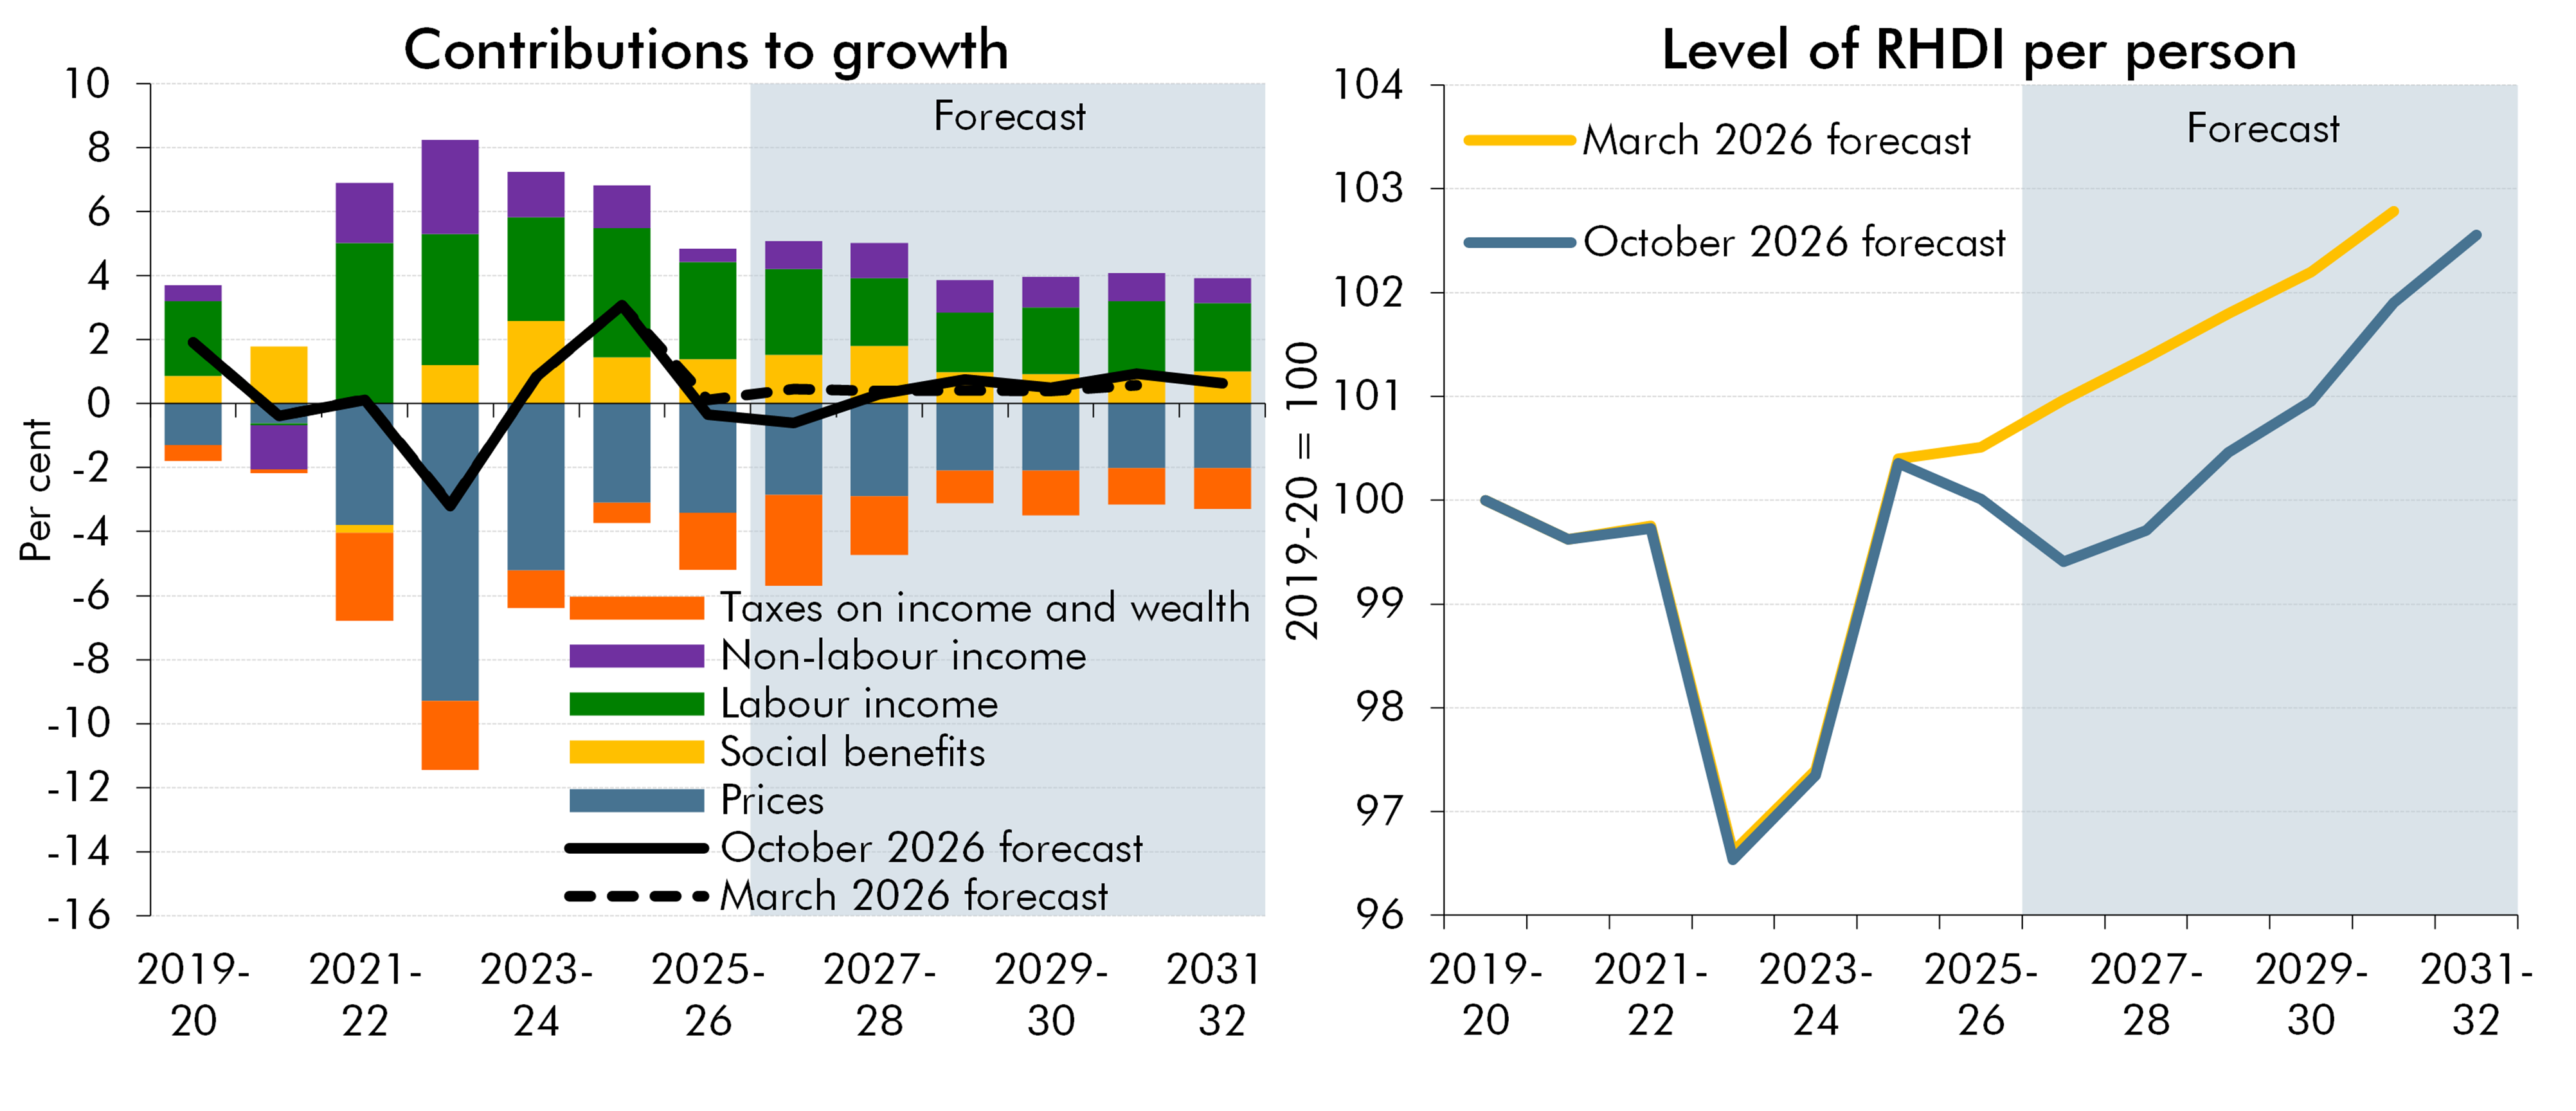
Source: ONS, OBR
2.32 Our central forecast represents a continuation of the historically weak growth in RHDI per person since the global financial crisis. Chart 2.7 shows the rolling 10-year average annual growth in RHDI per person. This slowed significantly in the aftermath of the financial crisis, due to lower growth in productivity and real wages. Growth reached a historic low over the 10 years to 2025-26, averaging just ¼ per cent a year, and we expect it to fall further in the near term. By 2029-30, our central forecast sees growth over the prior 10 years averaging less than 0.1 per cent a year. As a result, 10 years on from the onset of the pandemic, RHDI per person would be just 1 per cent higher than its pre-pandemic level.
Chart 2.7: Rolling 10-year average growth in RHDI per person
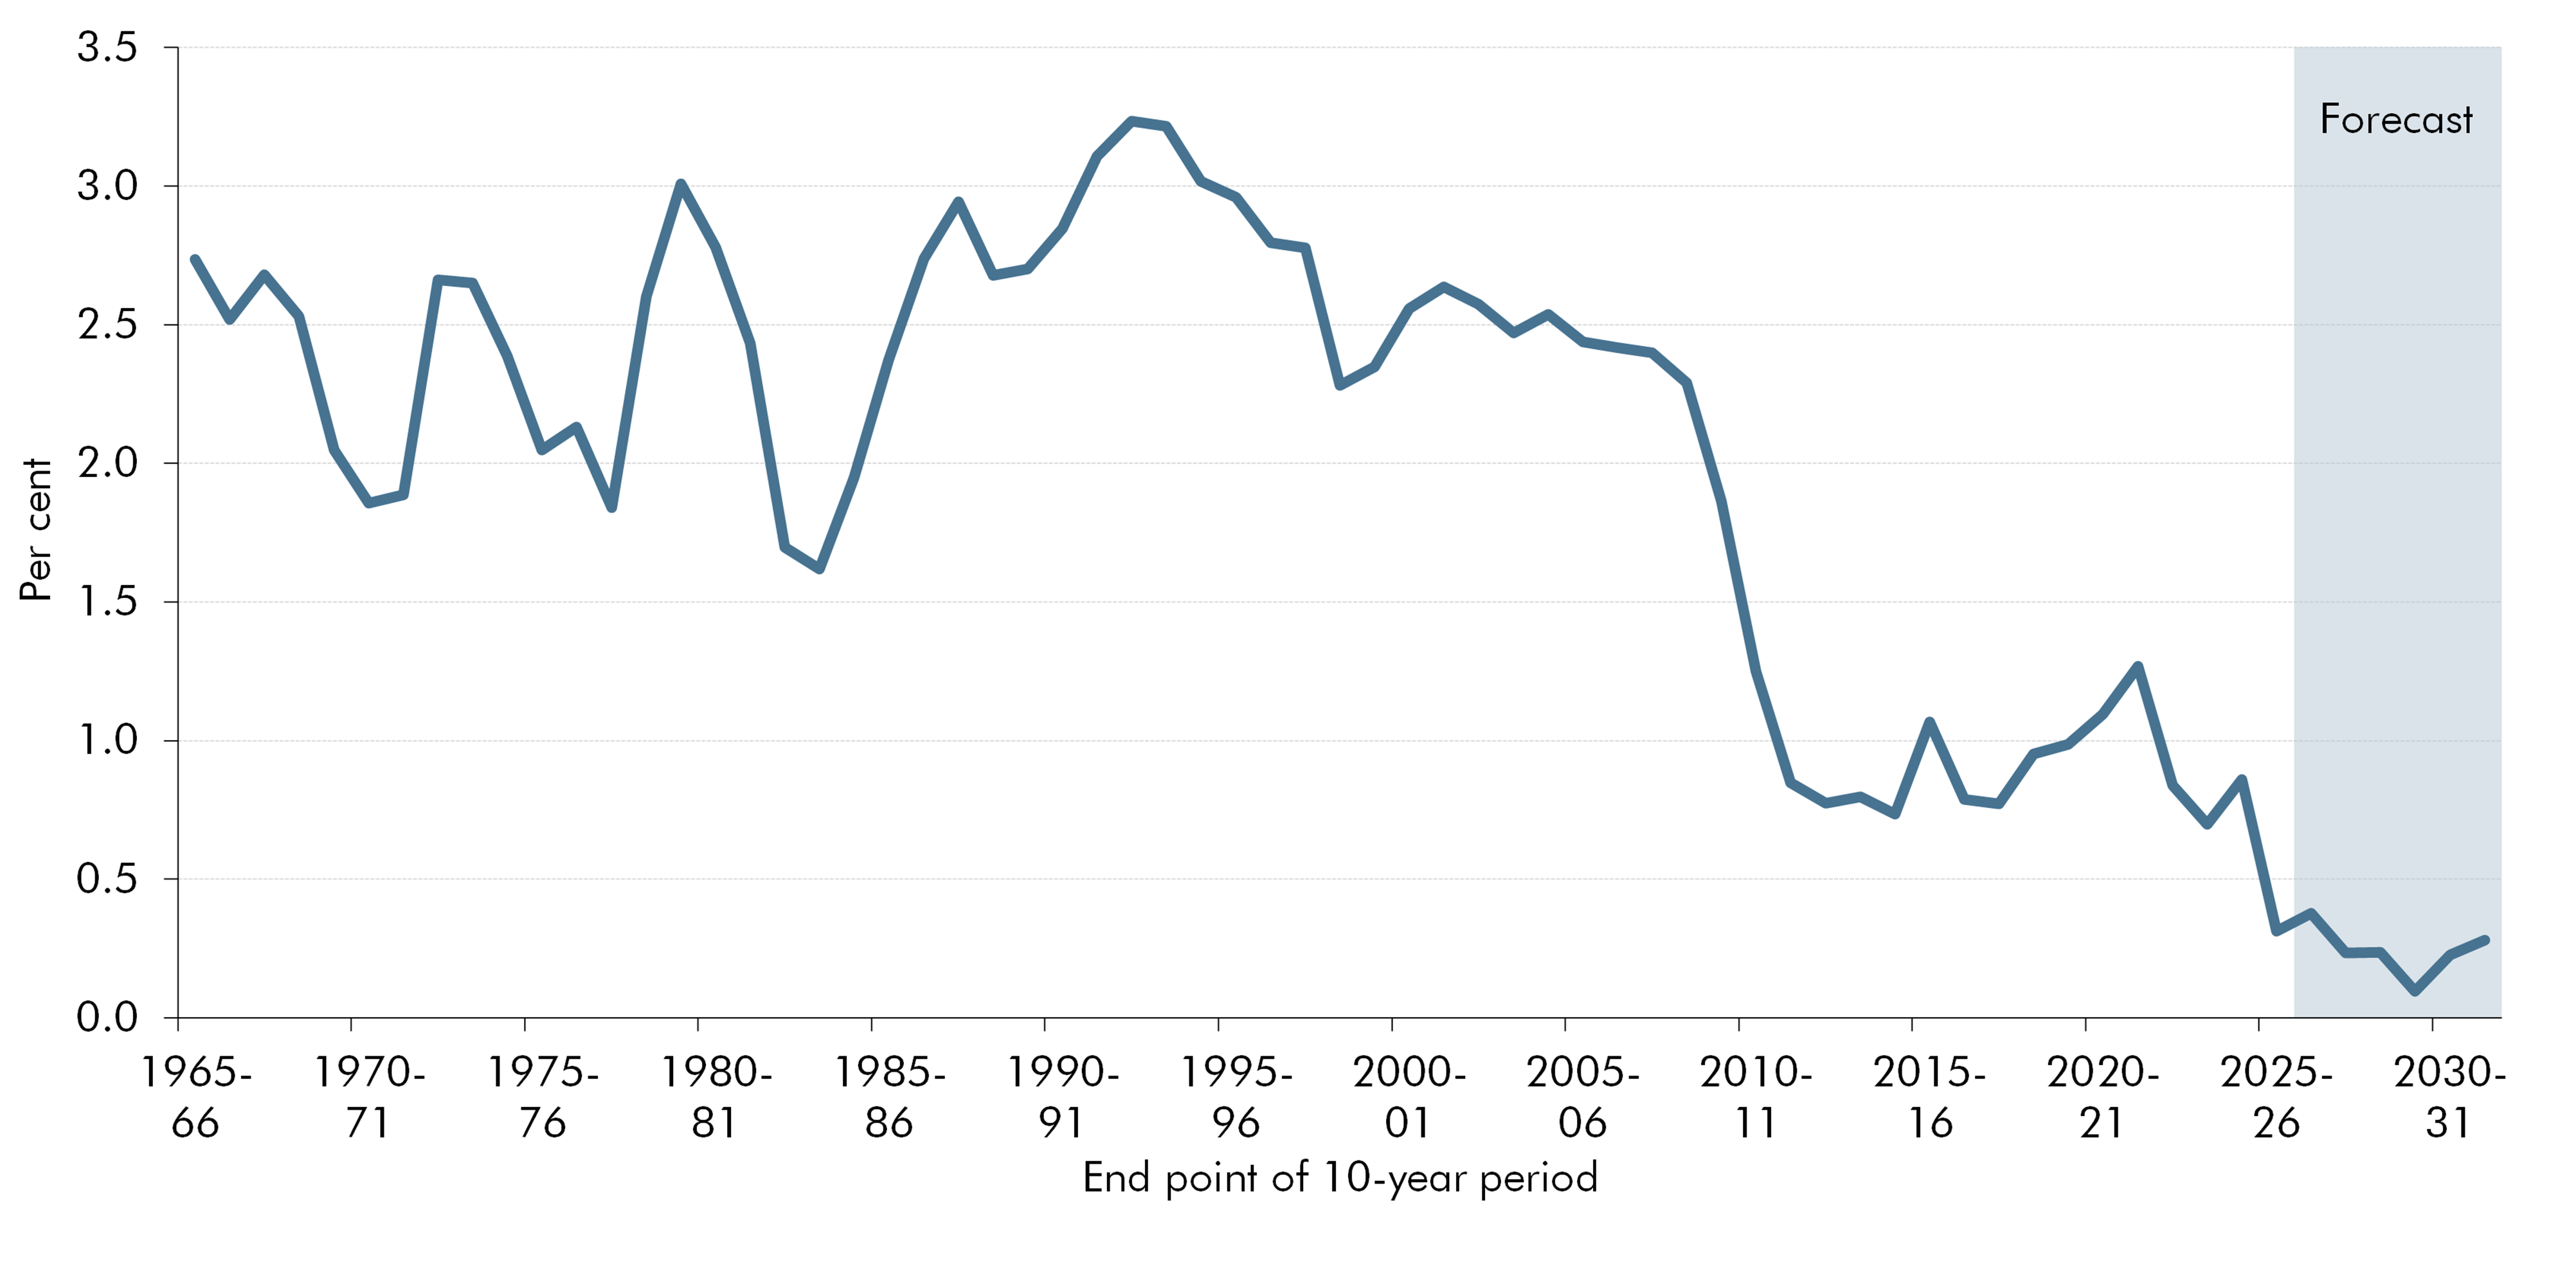
Note: Compound average growth rate over a 10-year period. 2025-26 is the final year of outturn data, with forecast ending in 2031-32.
Source: ONS, OBR
Potential output, productivity and labour supply
2.33 In our central forecast, we expect potential output growth to fall from around 1½ per cent this year to about 1 per cent next year, as higher energy prices weigh on productive potential. We also expect lower net migration to slow population and labour supply growth, but to have little impact on GDP or real incomes per person. Chart 2.8 shows that we expect potential output growth to then rise to around 1½ per cent in the medium term as market pricing implies a fall back in energy prices.
Chart 2.8: Potential output growth
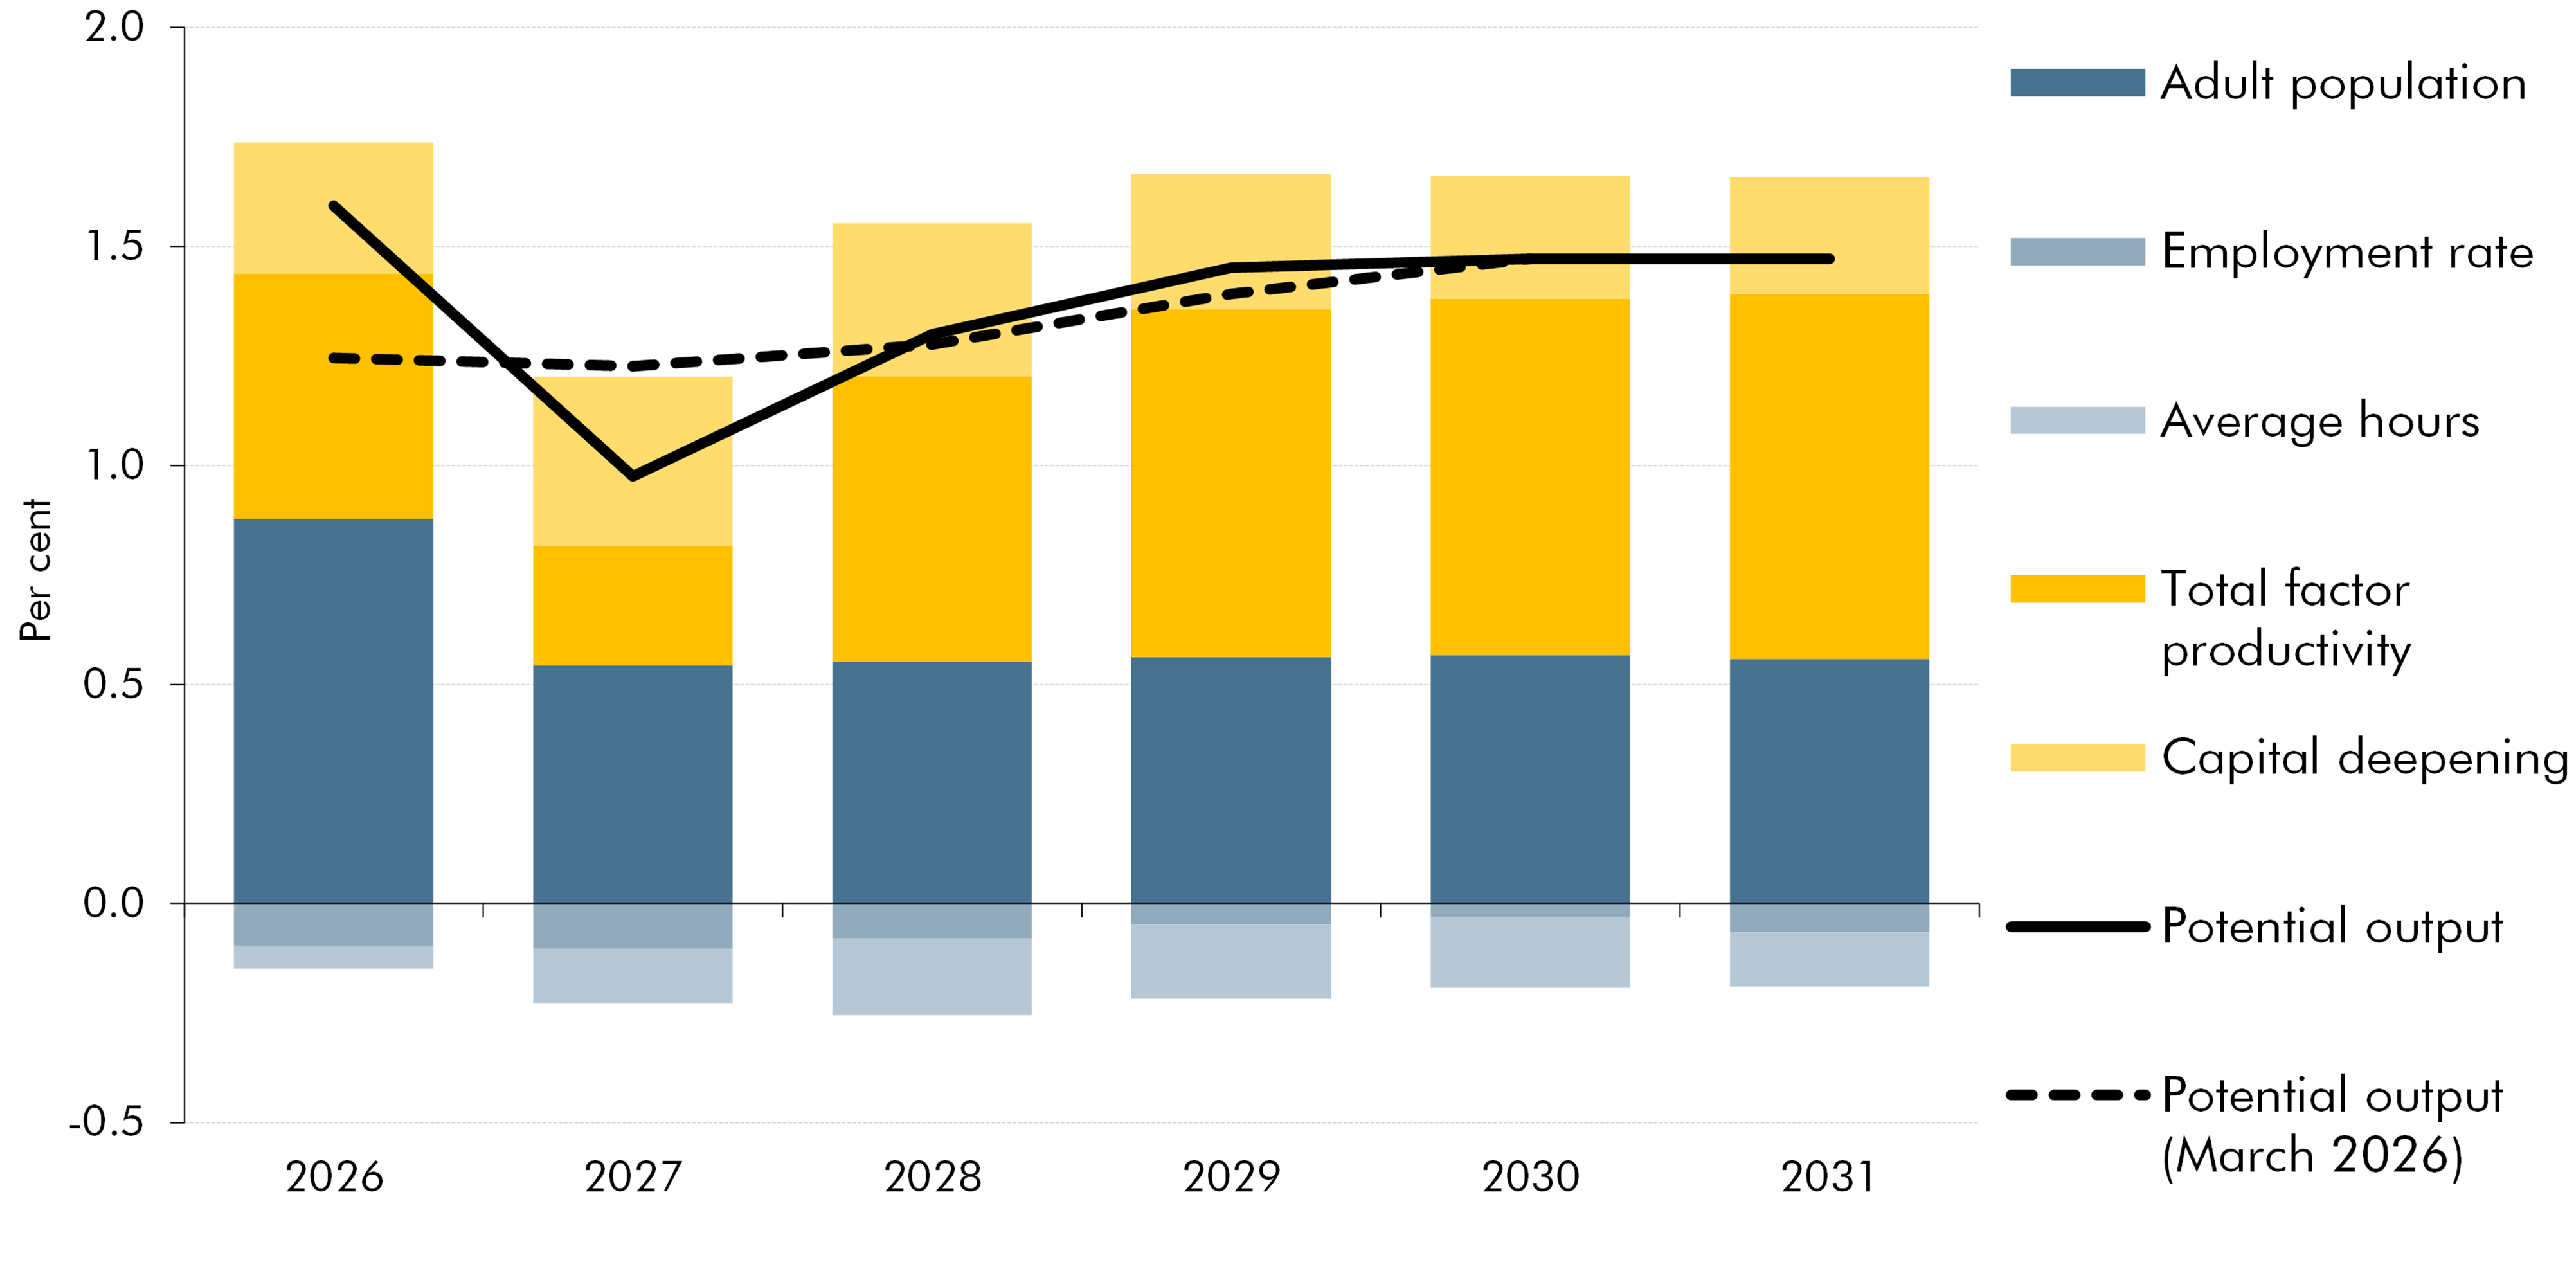
Source: OBR
2.34 Relative to March, our central forecast is for the level of potential output to be broadly unchanged in the medium term. A downward revision to net migration is offset by a higher starting level of potential output driven by strong recent GDP outturns, which we judge to be structural; and a higher forecast for business investment which slightly raises capital deepening. In per adult terms, potential output is expected to be slightly higher in the medium term than in March as the net migration revision has no impact.
Labour supply
2.35 Labour supply growth is expected to slow from around ¾ of a per cent in 2026 to around 1/3 of a per cent a year over the medium term, marginally lower than in March. The slowdown over the forecast reflects net migration falling this year and then remaining more in line with the previous decade’s average over the next few years, alongside the impact of the ageing population on average hours and participation.
Adult population
2.36 Our forecast for the adult population is based on historical data from the Labour Force Survey (LFS), births and deaths from the latest ONS National Population Projections (NPPs), and our own forecast for net migration. [footnote 6] Based on these, the size of the adult population is forecast to rise by around 320,000 people a year (around 150,000 via net migration), from 56.8 million in 2026 to 58.4 million in 2031. The adult population in 2030 is now expected to be around 50,000 lower than in our March forecast, as shown in the left panel of Chart 2.9, reflecting the downward revision to our net migration forecast partly offset by higher-than-expected outturn population data.
Net migration
2.37 Data published since we finalised the March forecast suggest that net migration will be lower than we previously assumed. The ONS estimates that net migration fell from 331,000 in 2024 to 171,000 in 2025, while visa data up to June 2026 continue to show declines across most visa types. Reflecting these latest data, and informed by our migration model, we expect net migration to fall to 120,000 in the year to mid-2026 (right panel of Chart 2.9).[footnote 7] The near-term decline reflects visa restrictions introduced since 2023 alongside higher emigration following past high levels of immigration, especially among students. Net migration is then forecast to rise gradually to 230,000 by the year to mid-2031, in line with the ‘principal variant’ of the latest ONS population projections. This rise largely reflects our assumption that the net outflow of British nationals and EU nationals who arrived under the pre-Brexit immigration regime will gradually lessen. We judge our net migration forecast to be a reasonable central assumption based on recent outturn data, our modelling infrastructure, and current government policy.
Chart 2.9: Adult population and net migration
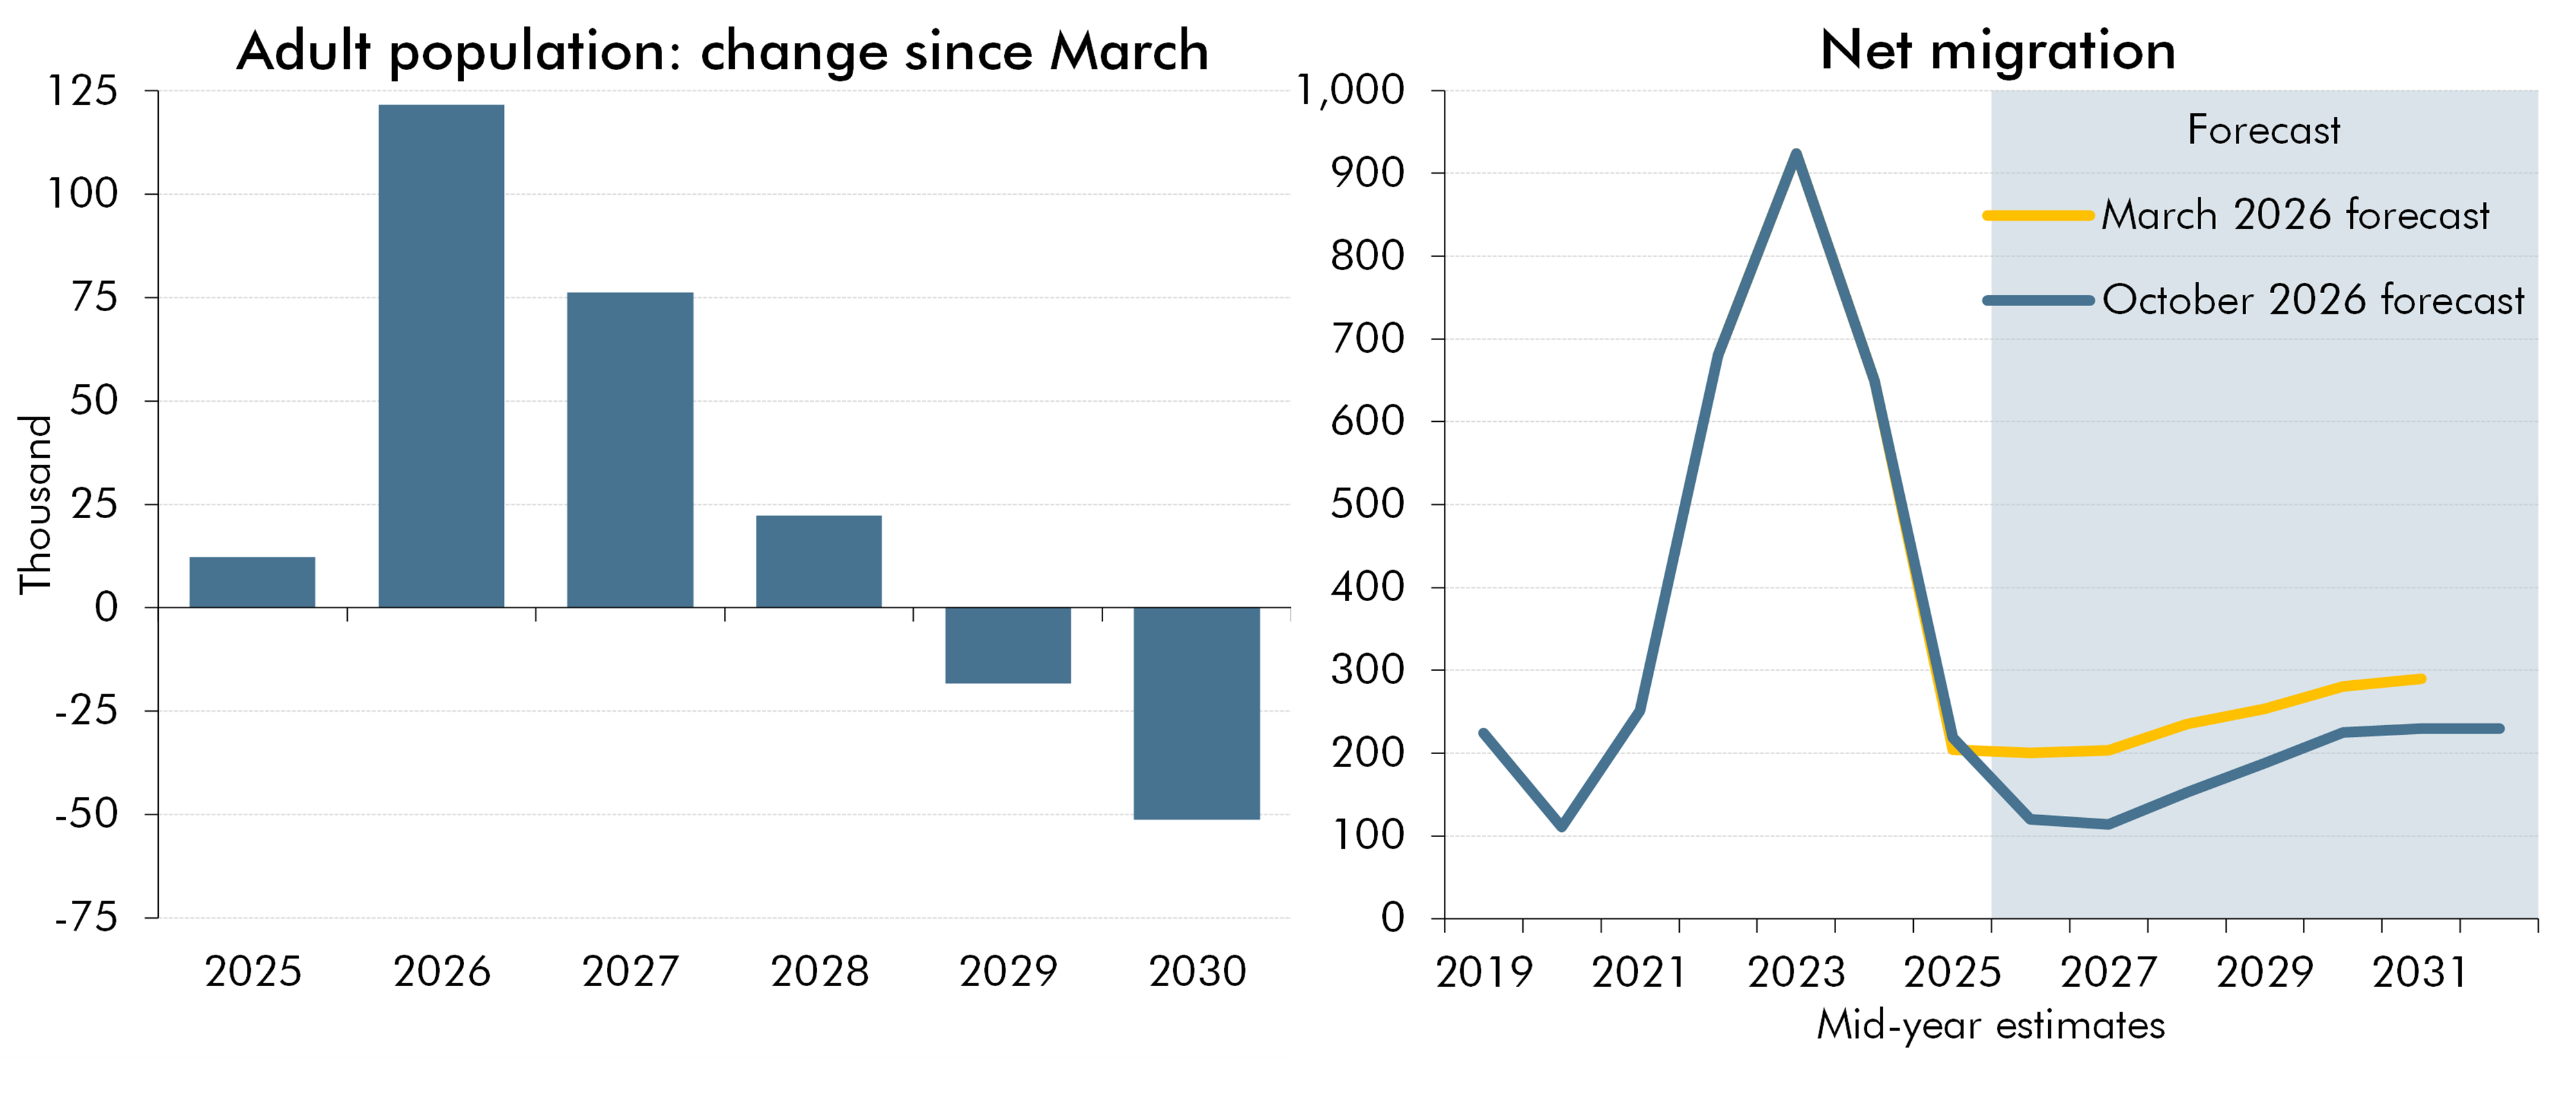
Source: ONS, OBR
2.38 Our net migration forecast is around 70,000 a year lower than in March. This has a small negative impact on the level of GDP and potential output in the medium term – but has no impact on per person incomes. The composition of migration is also important for economic and fiscal outcomes, with the following being important factors:
-
Demographics: on arrival, migrants are generally more likely to be of working age with around 80 per cent of migrants being aged 16-64 – compared to around 60 per cent for the wider UK population – in the principal variant of the ONS 2024-based NPPs.
-
Participation: on arrival, migrants tend to have a lower rate of participation at a given age than the domestic population. This generally offsets the effect of demographics and means that the average migrant tends to have a similar overall participation rate. See Box 2.3 of the March 2024 EFO and Box 2.3 of the November 2023 EFO for more detail on these assumptions.
-
Productivity: we assume migrants have broadly the same average rate of productivity as the domestic population. This judgement is highly uncertain as it depends on a range of factors related to the characteristics of migrants which we explored in more detail in Box 2.1 of the March 2026 EFO.
2.39 We consider all of these factors when assessing the impact on the labour market of revisions to our overall net migration forecast, as the composition of the migrant population will vary significantly across different entry routes.[footnote 8] The downward revision to net migration in this forecast is broad-based across various visa routes so we judge that this revision has no impact on the overall participation rate or level of productivity. This means that we assume that lower net migration will leave GDP per person, an indicator of average living standards, unchanged by the end of the forecast.
2.40 There remains considerable uncertainty around our net migration forecast, including the impact of previous policy changes on the outlook for student visas, the share of humanitarian arrivals from Ukraine that remain in the UK, and the future level of net migration of EU nationals. Potential changes to indefinite leave to remain policy, which are not currently reflected in our forecast as the policy details are not sufficiently certain, and changes to visa salary requirements, the details of which were confirmed after the deadline for inclusion in the economy forecast, may also affect net migration in future. We explored the economic impact of two alternative scenarios of higher and lower medium-term net migration in Box 2.3 of the March 2024 EFO. In these scenarios, we also demonstrated the impacts of using alternative assumptions for migrants’ productivity and participation in the labour force, which are significant.
Participation rate and average hours
2.41 Our forecasts for trend labour force participation and average hours are unchanged from March. The trend labour force participation rate is forecast to fall slightly from 63½ per cent in 2026 to 63¼ per cent in 2030, while trend average hours fall marginally from 32 hours a week in 2026 to 31¾ hours a week in 2030. Both decline because of our assumption that the population will continue to age, and that older people, on average, have lower participation rates and work fewer hours. The decline in average hours is more gradual than had been the case before the financial crisis, as we assume that the weakness in productivity growth since then limits workers’ capacity to use part of their increase in real wages to increase their amount of leisure time. The recent ONS revisions to historical average hours, which were published after we finalised our forecast, suggest that average hours growth has been lower, and output per hour higher, than we had previously thought. We discuss these revisions in detail in Box 2.2.
Productivity
2.42 We assume that trend productivity growth slows in 2027 to 0.7 per cent, largely because of the spike in energy prices.[footnote 9] Productivity growth is then forecast to rise to 1.1 per cent in 2031 as energy prices fall back. We assume the slightly higher medium term fossil fuel prices in financial market pricing do not reduce medium-term productivity, as firms adjust production processes and energy sources (see Box 2.1 for more details).
2.43 The main change to our forecast for trend productivity growth since March is a stronger contribution from capital deepening, largely reflecting a higher path for business investment following consistently stronger-than-expected outturns. This change, combined with slightly higher-than-expected growth in the first half of 2026, leaves the level of trend productivity around 0.2 per cent higher than in the March forecast in 2030. We have not changed our previous judgement that underlying trend total factor productivity growth reaches 0.8 per cent in 2030, which we explained in Briefing paper No.9: Forecasting productivity. The recent ONS revisions to productivity were published after we finalised this forecast, but we discuss them in Box 2.2. We will incorporate the impact of any changes, alongside other developments, in our next forecast.
Alternative measure of productivity
2.44 Labour market data remain a key source of uncertainty for the productivity outlook. Chart 2.10 compares an LFS-based measure of labour productivity with an alternative measure created by the Resolution Foundation, based on HMRC PAYE real time information on employees and administrative data on self-employment. The two measures now suggest similarly weak cumulative growth since the pandemic (shown in the right panel), despite considerably different paths to get there. This demonstrates the uncertainty around even recent trends in productivity growth. We remain cautious about interpreting trends from recent data from relatively short periods and we will continue to regularly review our productivity assumption to consider any new information, such as the component-based data discussed in Box 2.2.
Chart 2.10: Productivity (output per hour)
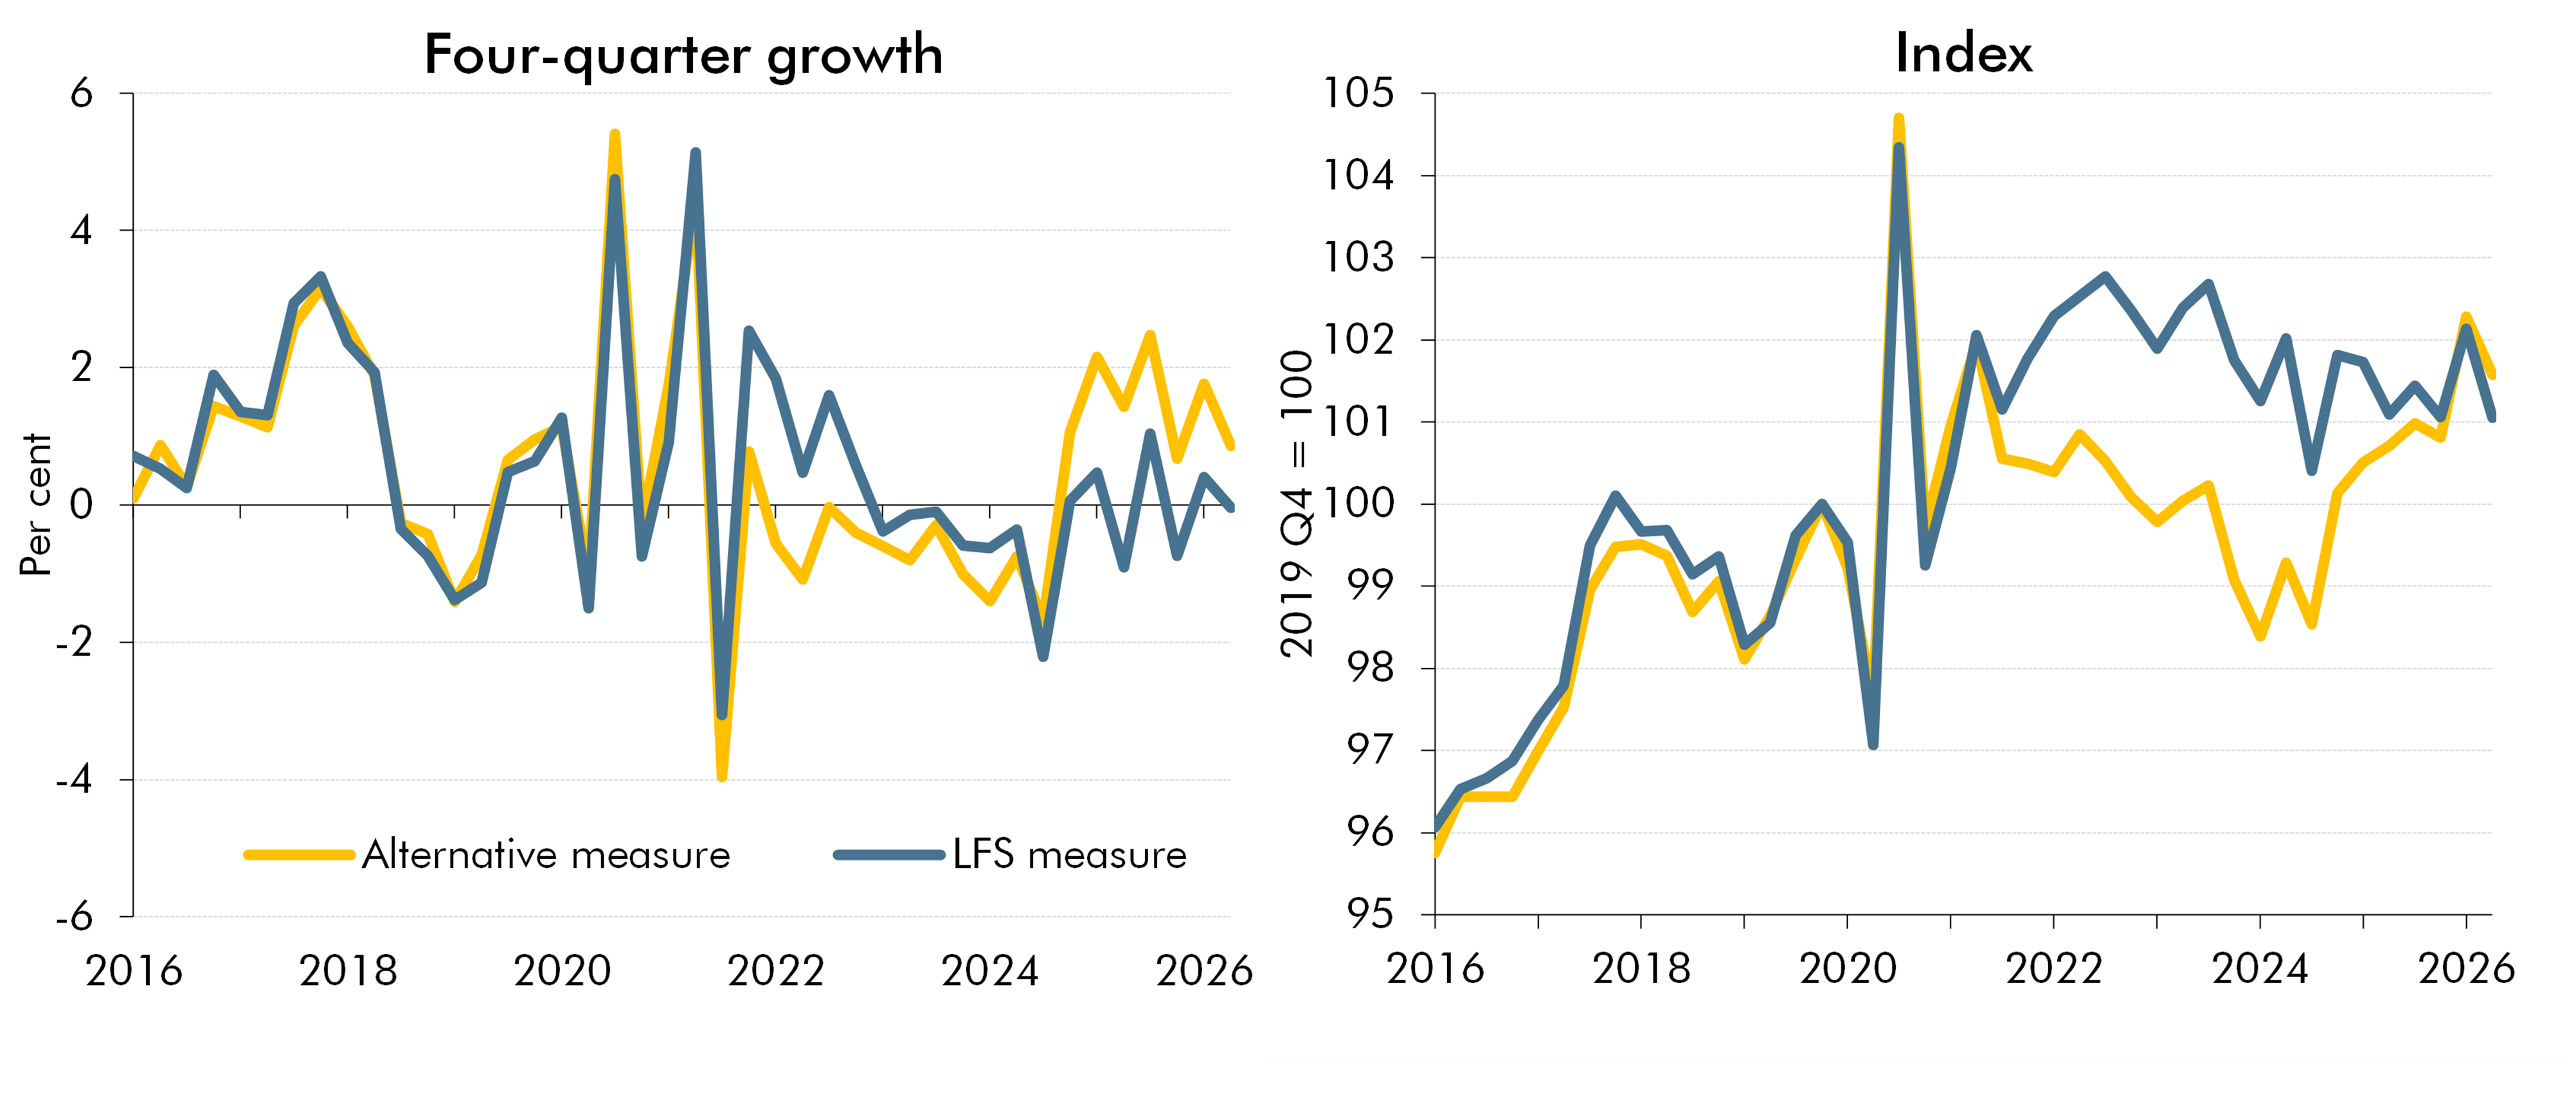
Note: Both measures use real GDP from Quarterly National Accounts published on 30 September. Alternative measure uses administrative employment data constructed by the Resolution Foundation (accessed on 25 September) and average hours data published on 18 August. LFS measures use total hours published on 18 August.
Source: ONS, Resolution Foundation, OBR
2.45 The development and adoption of AI is widely expected to boost future productivity growth, and we previously analysed this in Annex B of Briefing paper No.9: Forecasting productivity. Sectoral data can help to shed light on the degree to which AI is already enhancing UK productivity growth. Initially, it might be expected that ‘AI-producing’ sectors would experience an acceleration in productivity growth, and then over time this would spread to ‘AI-adopting’ sectors. According to the latest ONS Business Insights and Conditions Survey, only 30 per cent of businesses reported using at least one type of AI technology in September 2026, though this is up from 15 per cent two years ago.
2.46 While sectoral data over short periods can be highly volatile, data on output per worker based on administrative sources suggests recent growth in productivity has been broad-based.[footnote 10] Table 2.2 shows that growth between the final quarter of 2024 and the second quarter of 2026 has accelerated compared to previous periods in some of the sectors most associated with the production and use of AI services, such as IT and communications, and professional, scientific and technical services. But productivity growth was relatively strong in these sectors prior to the pandemic, and growth has also accelerated in sectors likely to be currently less affected by AI, such as accommodation and food, and wholesale and retail. We will continue to closely monitor the emerging evidence and how to reflect it in our forecasts for productivity and employment.
Table 2.2: Output per worker growth by sector
| Sector | Average annualised growth over period (per cent) | ||
|---|---|---|---|
| 2016Q1 to 2019Q4 | 2022Q1 to 2024Q3 | 2024Q4 to 2026Q2 | |
| Accelerating productivity growth | |||
| Information and communication | 5.6 | 1.3 | 7.6 |
| Professional, scientific and technical | 1.1 | -0.8 | 3.7 |
| Accommodation and food service activities | 1.1 | -3.3 | 3.2 |
| Transportation and storage | -1.2 | 7.8 | 2.7 |
| Wholesale and retail; repair of motor vehicles | 1.2 | -2.0 | 2.4 |
| Construction | 0.2 | 1.7 | 1.9 |
| Manufacturing | 0.5 | 0.6 | 1.9 |
| Health and social work | -1.6 | -0.5 | 1.5 |
| Slowing productivity growth | |||
| Public administration and defence; social security | 2.7 | 3.2 | 1.5 |
| Finance and insurance | 2.5 | -3.9 | 0.3 |
| Other | -0.6 | -2.2 | -0.9 |
| Administrative and support services | 1.2 | 2.7 | -1.3 |
| Education | 1.8 | -0.8 | -1.7 |
| Note: ‘Other’ includes all other sectors, except real estate which is excluded. Accelerating and slowing productivity growth defined based on the difference between 2024Q4 to 2026Q2 and 2016Q1 to 2019Q4. |
| Source: ONS, Resolution Foundation, OBR |
Box 2.2: Recent ONS revisions to historical economic data
In the period since we closed our forecast to new data,a the ONS has released revised historical National Accounts and hourly productivity data.
Blue Book-consistent Quarterly National Accounts figures
The Blue Book is the ONS’s annual update to the sources and methods used in the UK National Accounts, and the Quarterly National Accounts published on 30 September were consistent with the 2026 Blue Book. Real GDP growth between 1997 and the second quarter of 2026 has been revised upward by an annual average of 0.1 percentage points. Growth in 2025 was revised down by 0.1 percentage points, and growth in the first half of 2026 revised up by the same amount. Blue Book revisions only have a small impact on the starting level of nominal GDP in our forecast – which is important as the denominator for fiscal aggregates – raising it by 0.1 per cent in the second quarter of 2026. There were also relatively limited changes to the composition of GDP. Given these modest revisions to the recent momentum in the economy, and to the starting level and composition of nominal GDP, it is unlikely that incorporating the Blue Book 2026 revisions would have had a material impact on our economy or fiscal forecasts.
Average hours and productivity
Productivity growth is one of the most important, but uncertain, judgements for our economy and fiscal forecasts. One of the sources of uncertainty relates to challenges in accurately measuring both the level of, and growth in, historical productivity.
Our preferred measure of productivity is output per hour worked.b To estimate total hours worked, the ONS previously used a ‘direct approach’ which drew on average hours worked reported in the Labour Force Survey. The ONS will now be moving towards a ‘component approach’ to calculate hourly productivity that draws on a wider range of data sources to construct estimates of labour input, in line with the latest international standards.c Revisions have, so far, been published on a whole-economy basis up to 2024. Previous OECD research finds that countries which rely on average hours taken directly from labour force surveys systematically overestimate labour input and so underestimate hourly productivity.d The ONS published this new approach after we had finalised the pre-measures forecast, so we did not reflect it in the forecast, and it will become the official estimate for hourly productivity from November.
Chart D shows that average hours worked are materially lower under this new methodology and have continued their pre-financial crisis downward trend, falling at an average annual rate of 0.3 per cent between 2010 and 2024. The difference between the direct and component approaches is largely explained by reducing the use of imputation when measuring the amount of annual leave taken, leading to higher measured annual leave and lower hours worked.e The revisions to average hours have not changed output or income, but have significantly changed the working hours required to produce that output.
Chart D: Average hours worked
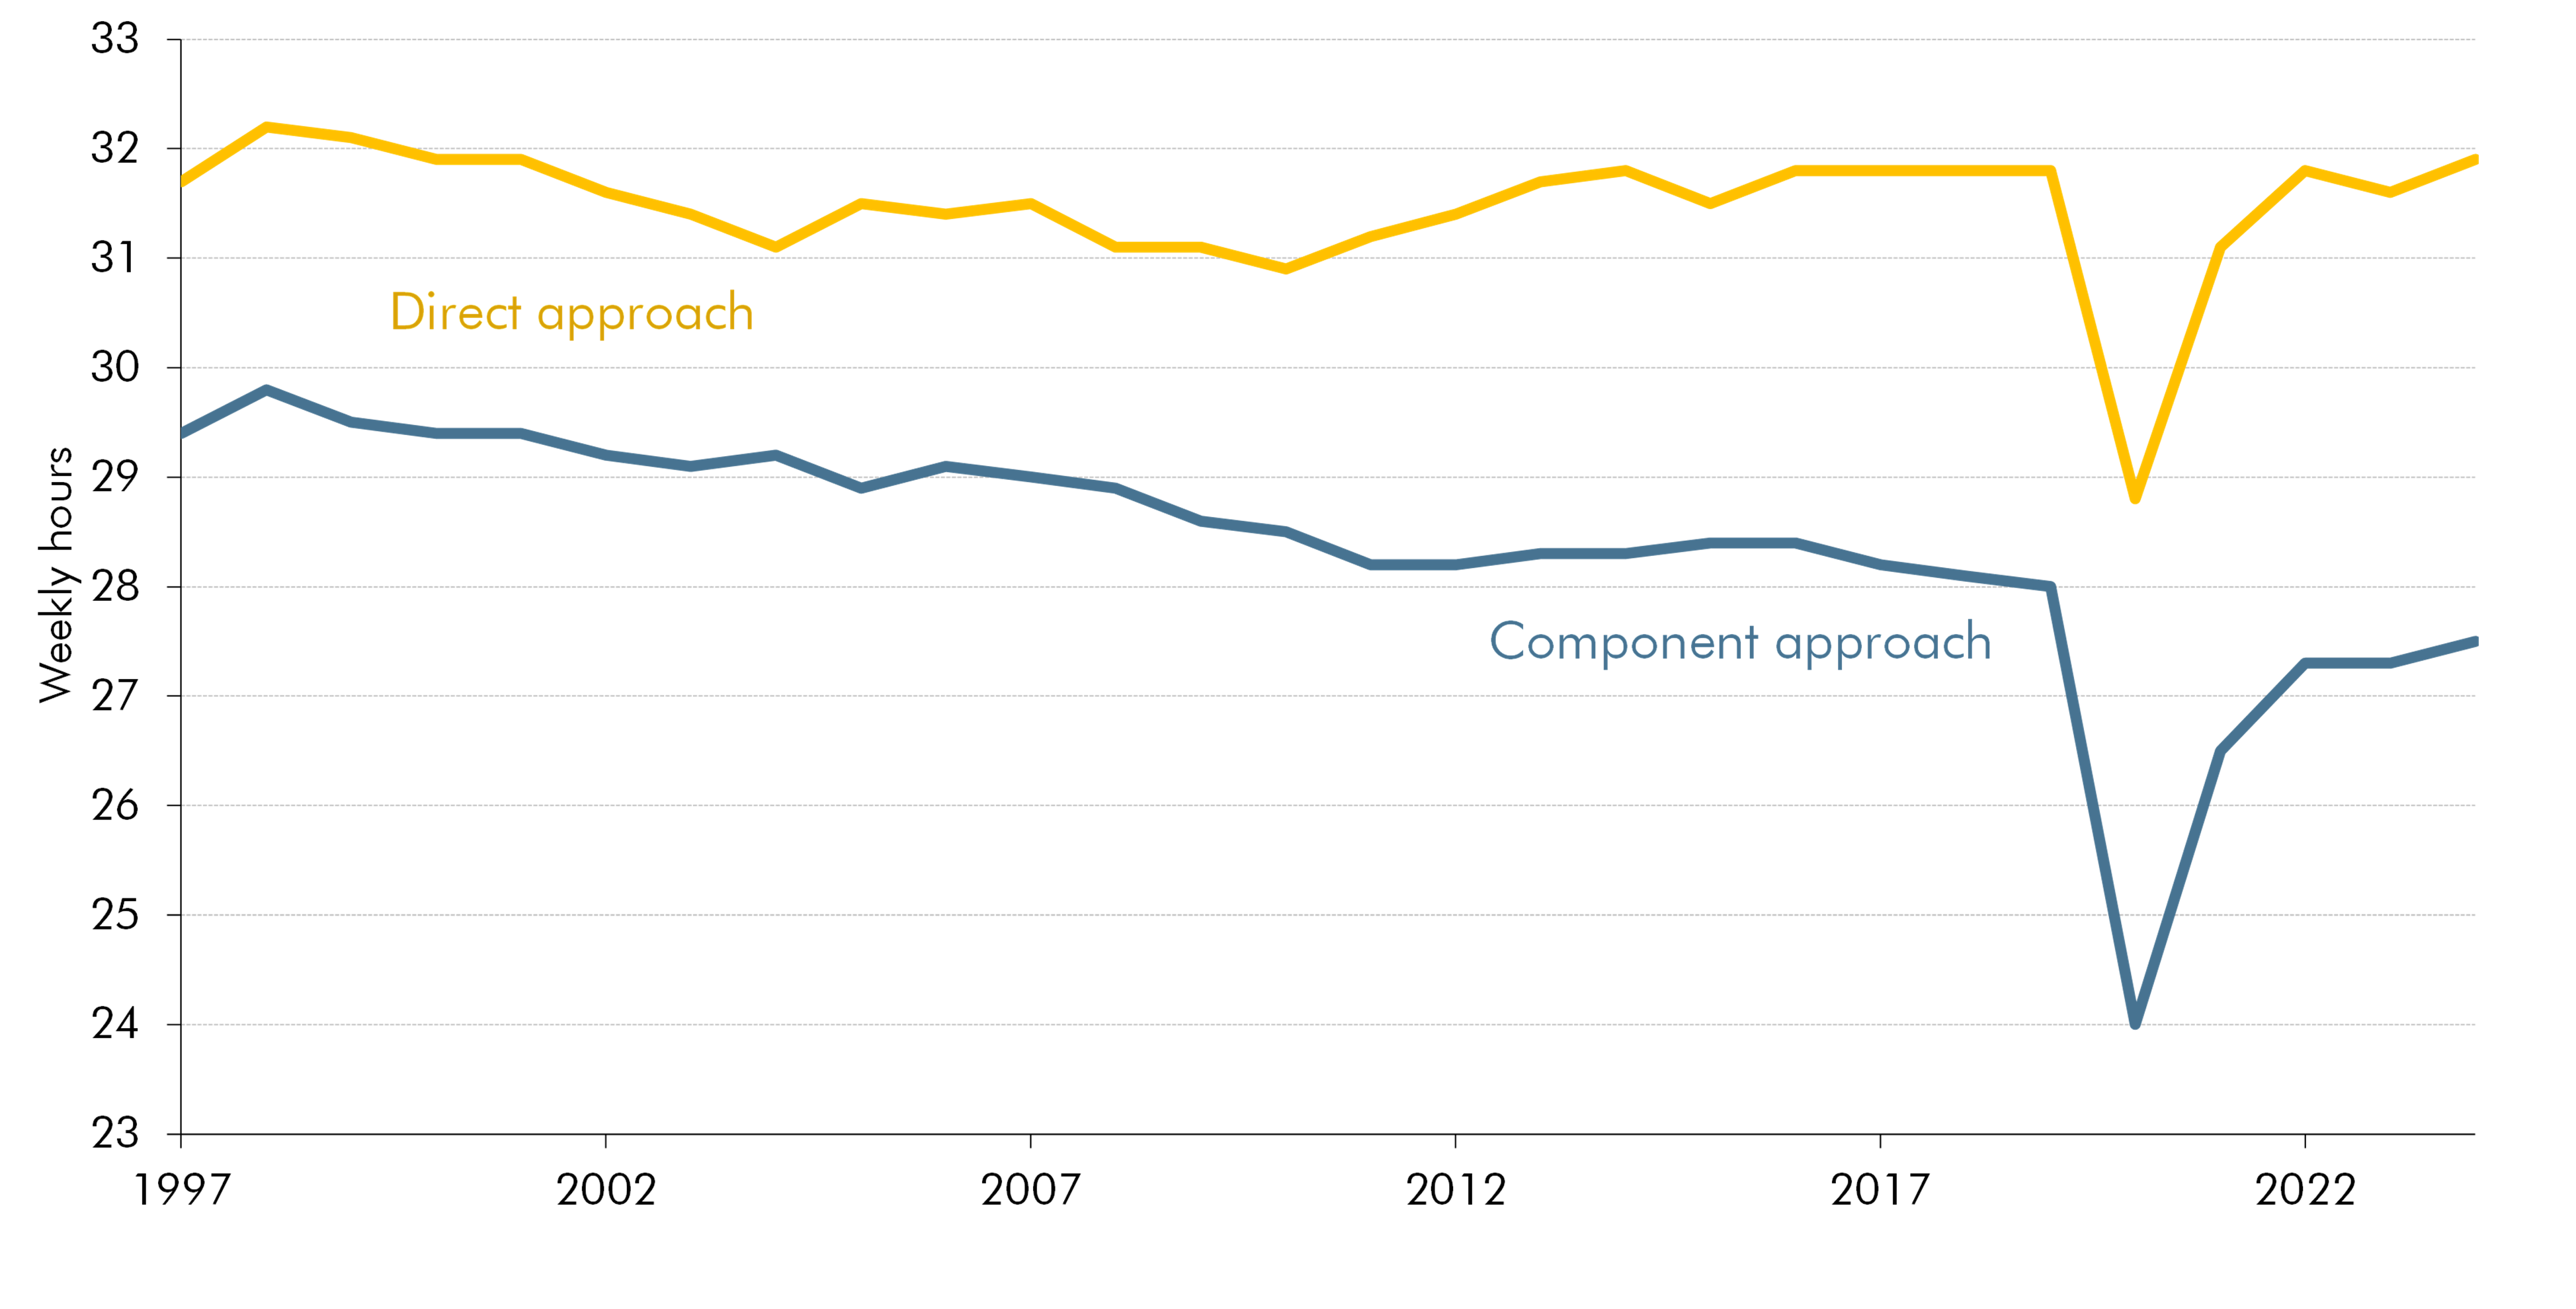
Source: ONS
Table A shows that the reduction in labour input, combined with the slight upward revision to real GDP mentioned above, means that output per hour worked is now estimated to have grown at an average annual rate of 1.0 per cent between 2010 and 2024. This is close to double the previous estimate of 0.4 per cent a year and is just under the 1.1 per cent we expect productivity growth to rise to by the end of our forecast. The small change in the contribution to GDP growth from employment reflects revisions to the number of workers from taking on new data sources, which results in a small change in output per worker.
Table A: Contributions to GDP growth, 2010-2024
| GDP | GDP per hour | GDP per worker | Employment | Average hours | |
|---|---|---|---|---|---|
| Percentage points | |||||
| ONS direct approach | 1.6 | 0.4 | 0.6 | 1.0 | 0.2 |
| ONS component approach | 1.7 | 1.0 | 0.7 | 0.9 | -0.3 |
| Difference(1) | 0.1 | 0.6 | 0.1 | 0.0 | -0.4 |
| 1) Difference in GDP is due to the component approach using updated quarterly national accounts data. Difference in employment is due to the wider range of data sources used to construct jobs estimate under the component approach. |
| Source: ONS, OBR |
The revised data shows a significantly different picture of the slowdown in productivity growth following the global financial crisis. The slowdown still exists but to a lesser degree than previously thought and the new data make our forecasts over this period look less over-optimistic in some years (Chart E, left panel).f The new data also suggest that the UK’s productivity growth performance was closer to that of international comparators in the decade following the crisis, after previously appearing to underperform (Chart E, right panel).
Chart E: Output per hour, UK and the G7
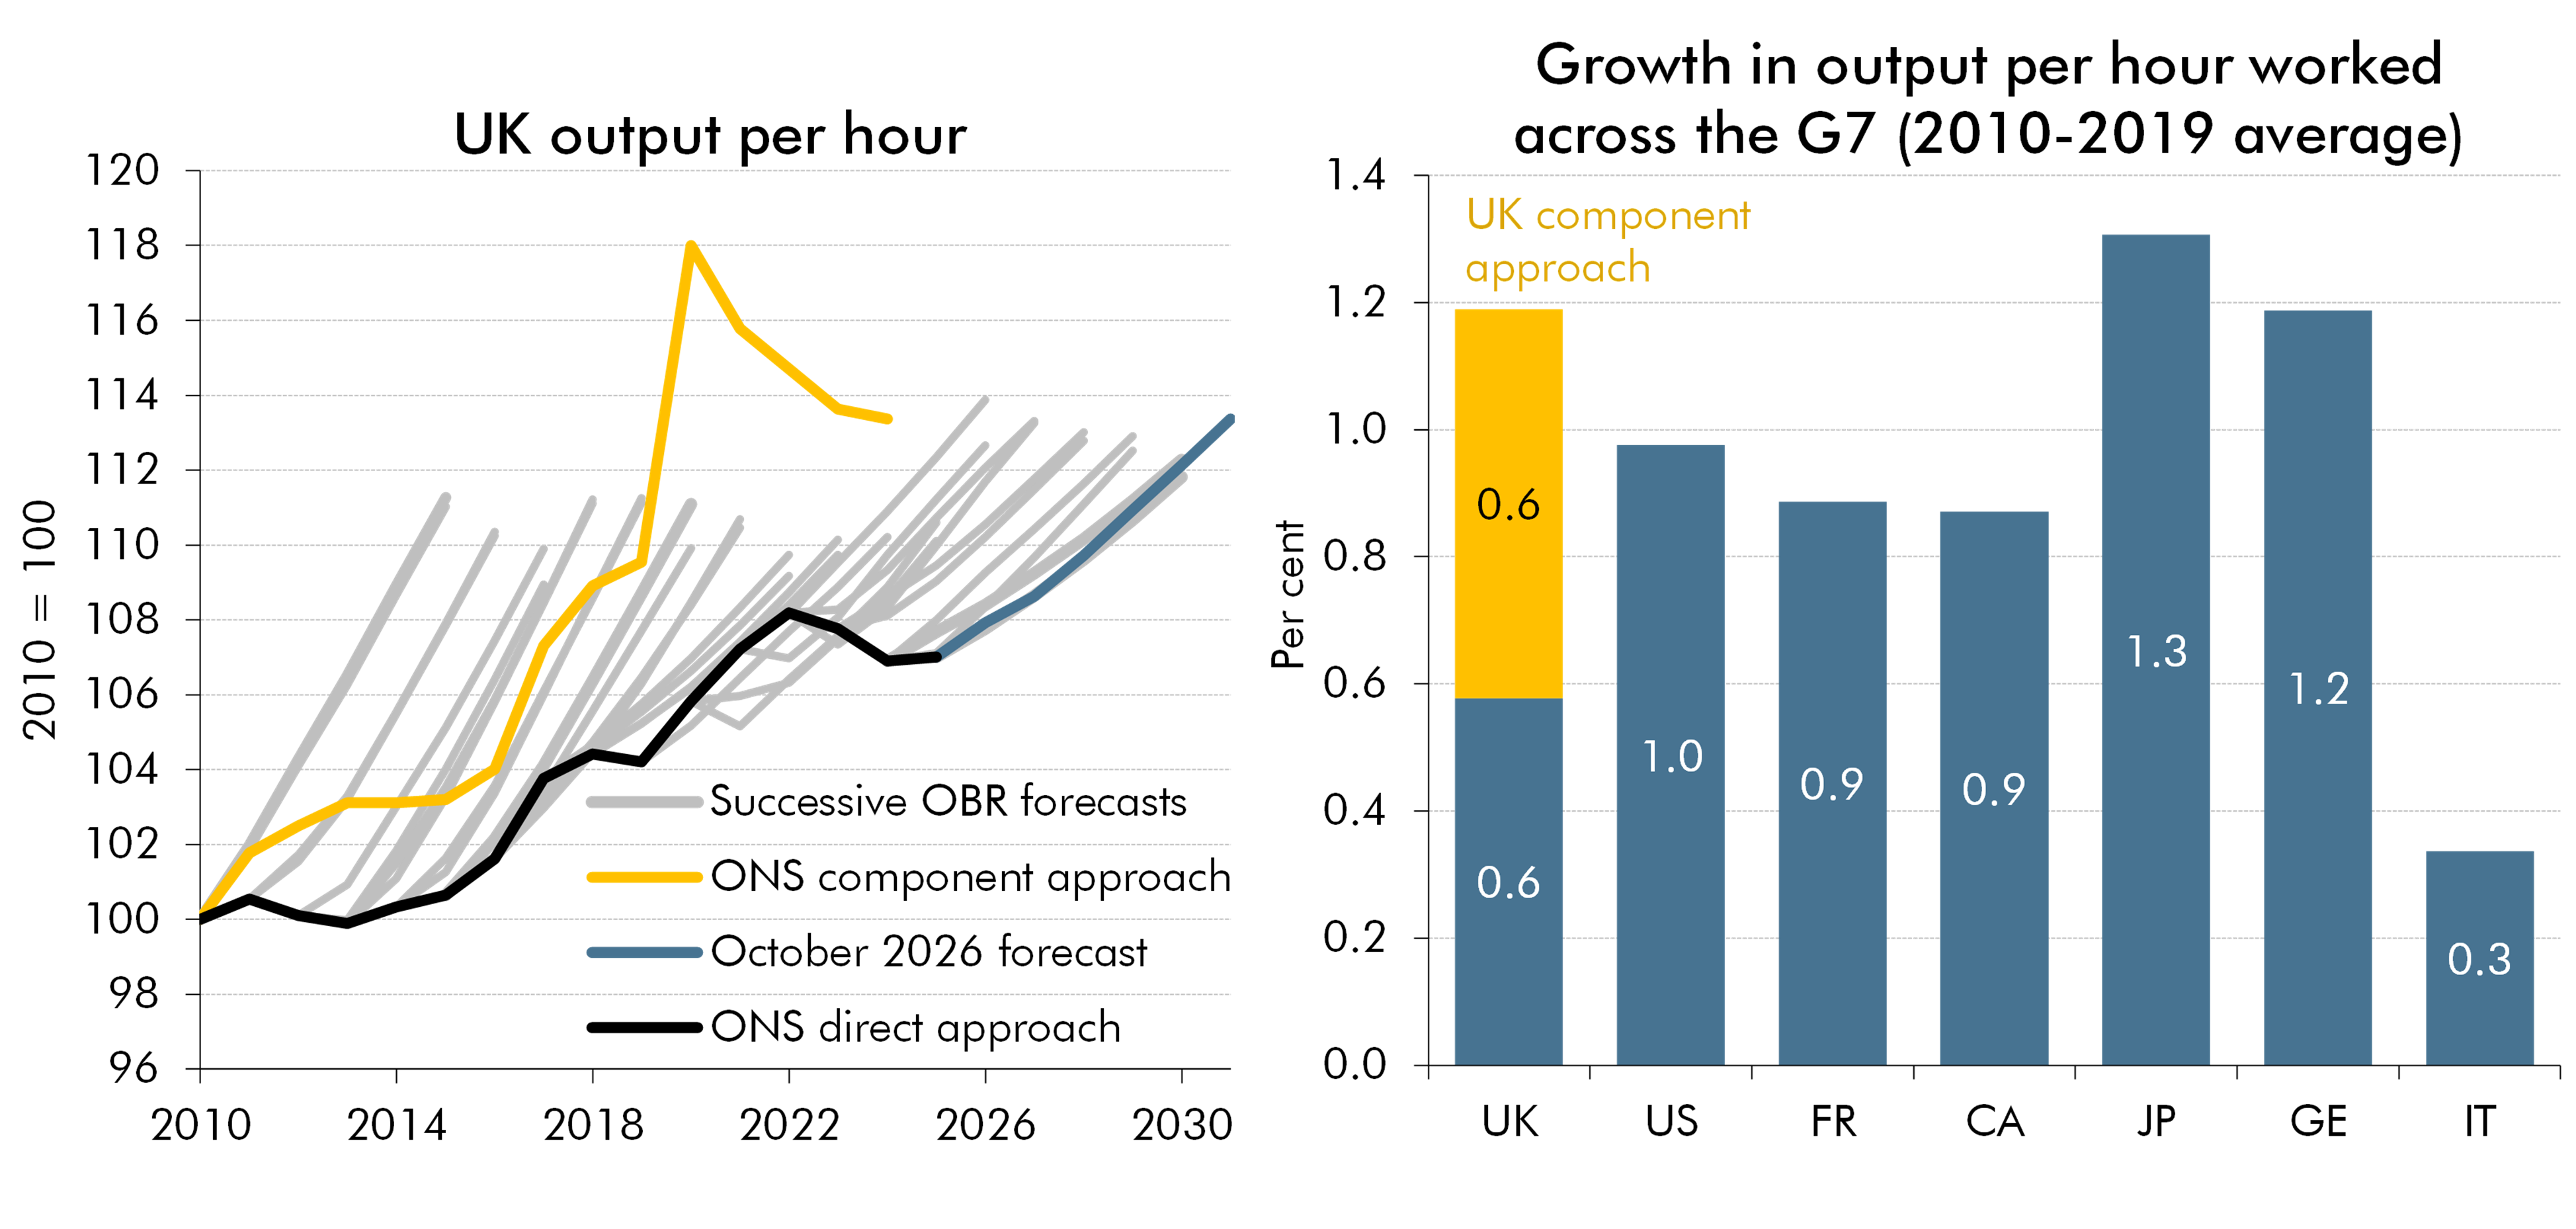
Note: Chain-linked volume measures of GDP are used as the measure of output. UK figures are based on ONS data, whereas internationally comparable OECD figures are used for other G7 countries. Yellow bar in the right panel represents additional growth in output per hour from using the component approach.
Source: OECD, ONS, OBR
Ultimately, what matters for the outlook for potential output, GDP per person, average earnings and, consequently, for the fiscal forecast, is growth in output per worker – which combines forecasts for output per hour and average hours worked. And this set of ONS revisions has little effect on output per worker. After the data becomes the official measure of productivity in November, we will consider whether this, alongside any other developments and analysis, should result in any revisions to our next forecast.
a) See the Foreword for more details on our forecast timetable.
b) See Briefing paper No.9: Forecasting productivity for more information on how we forecast productivity and measurement issues.
c) See ONS, Component approach to measuring labour productivity, UK: 1997 to 2024, September 2026.
d) See OECD, International productivity gaps: Are labour input measures comparable?, December 2018.
e) This is largely driven by an explicit adjustment for annual leave that assumes workers fully utilise their holiday entitlements. While this is a strong assumption, which the ONS are continuing to investigate, they argue that it results in more reasonable estimates of annual leave than under the previous direct approach, which implied for several years that, on average, full-time employees took less annual leave than the statutory minimum. Several other adjustments, such as for sickness absences and parental leave, also lead to lower average hours worked and have remained broadly constant over time.
f) Productivity significantly increased during the Covid pandemic as restrictions led to a marked temporary decline in economy-wide average working hours, as well as low-productivity sectors being shut down and then reopened.
Output gap and real GDP
Output gap
2.47 Our swathe of output gap models, shown in Chart 2.11, points to a widening amount of spare capacity in the economy. The models are based on a variety of methods including statistical filters on GDP, extracting common trends from surveys of capacity utilisation, and structural filters using economic relationships with variables like inflation to make inferences about the output gap. Based on these and other indicators, our central estimate is that GDP is just over 1 per cent below its potential level at the start of the forecast. In the second half of this year, we expect higher energy prices to weigh on aggregate demand to a greater extent than supply, widening the output gap further. Relative to March, higher interest rate expectations also push down on our output gap forecast. As energy prices fall back, as implied by the market pricing that underpins our forecast, we expect a steady cyclical recovery in our central forecast, with the output gap closing by 2031.
Chart 2.11: Output gap
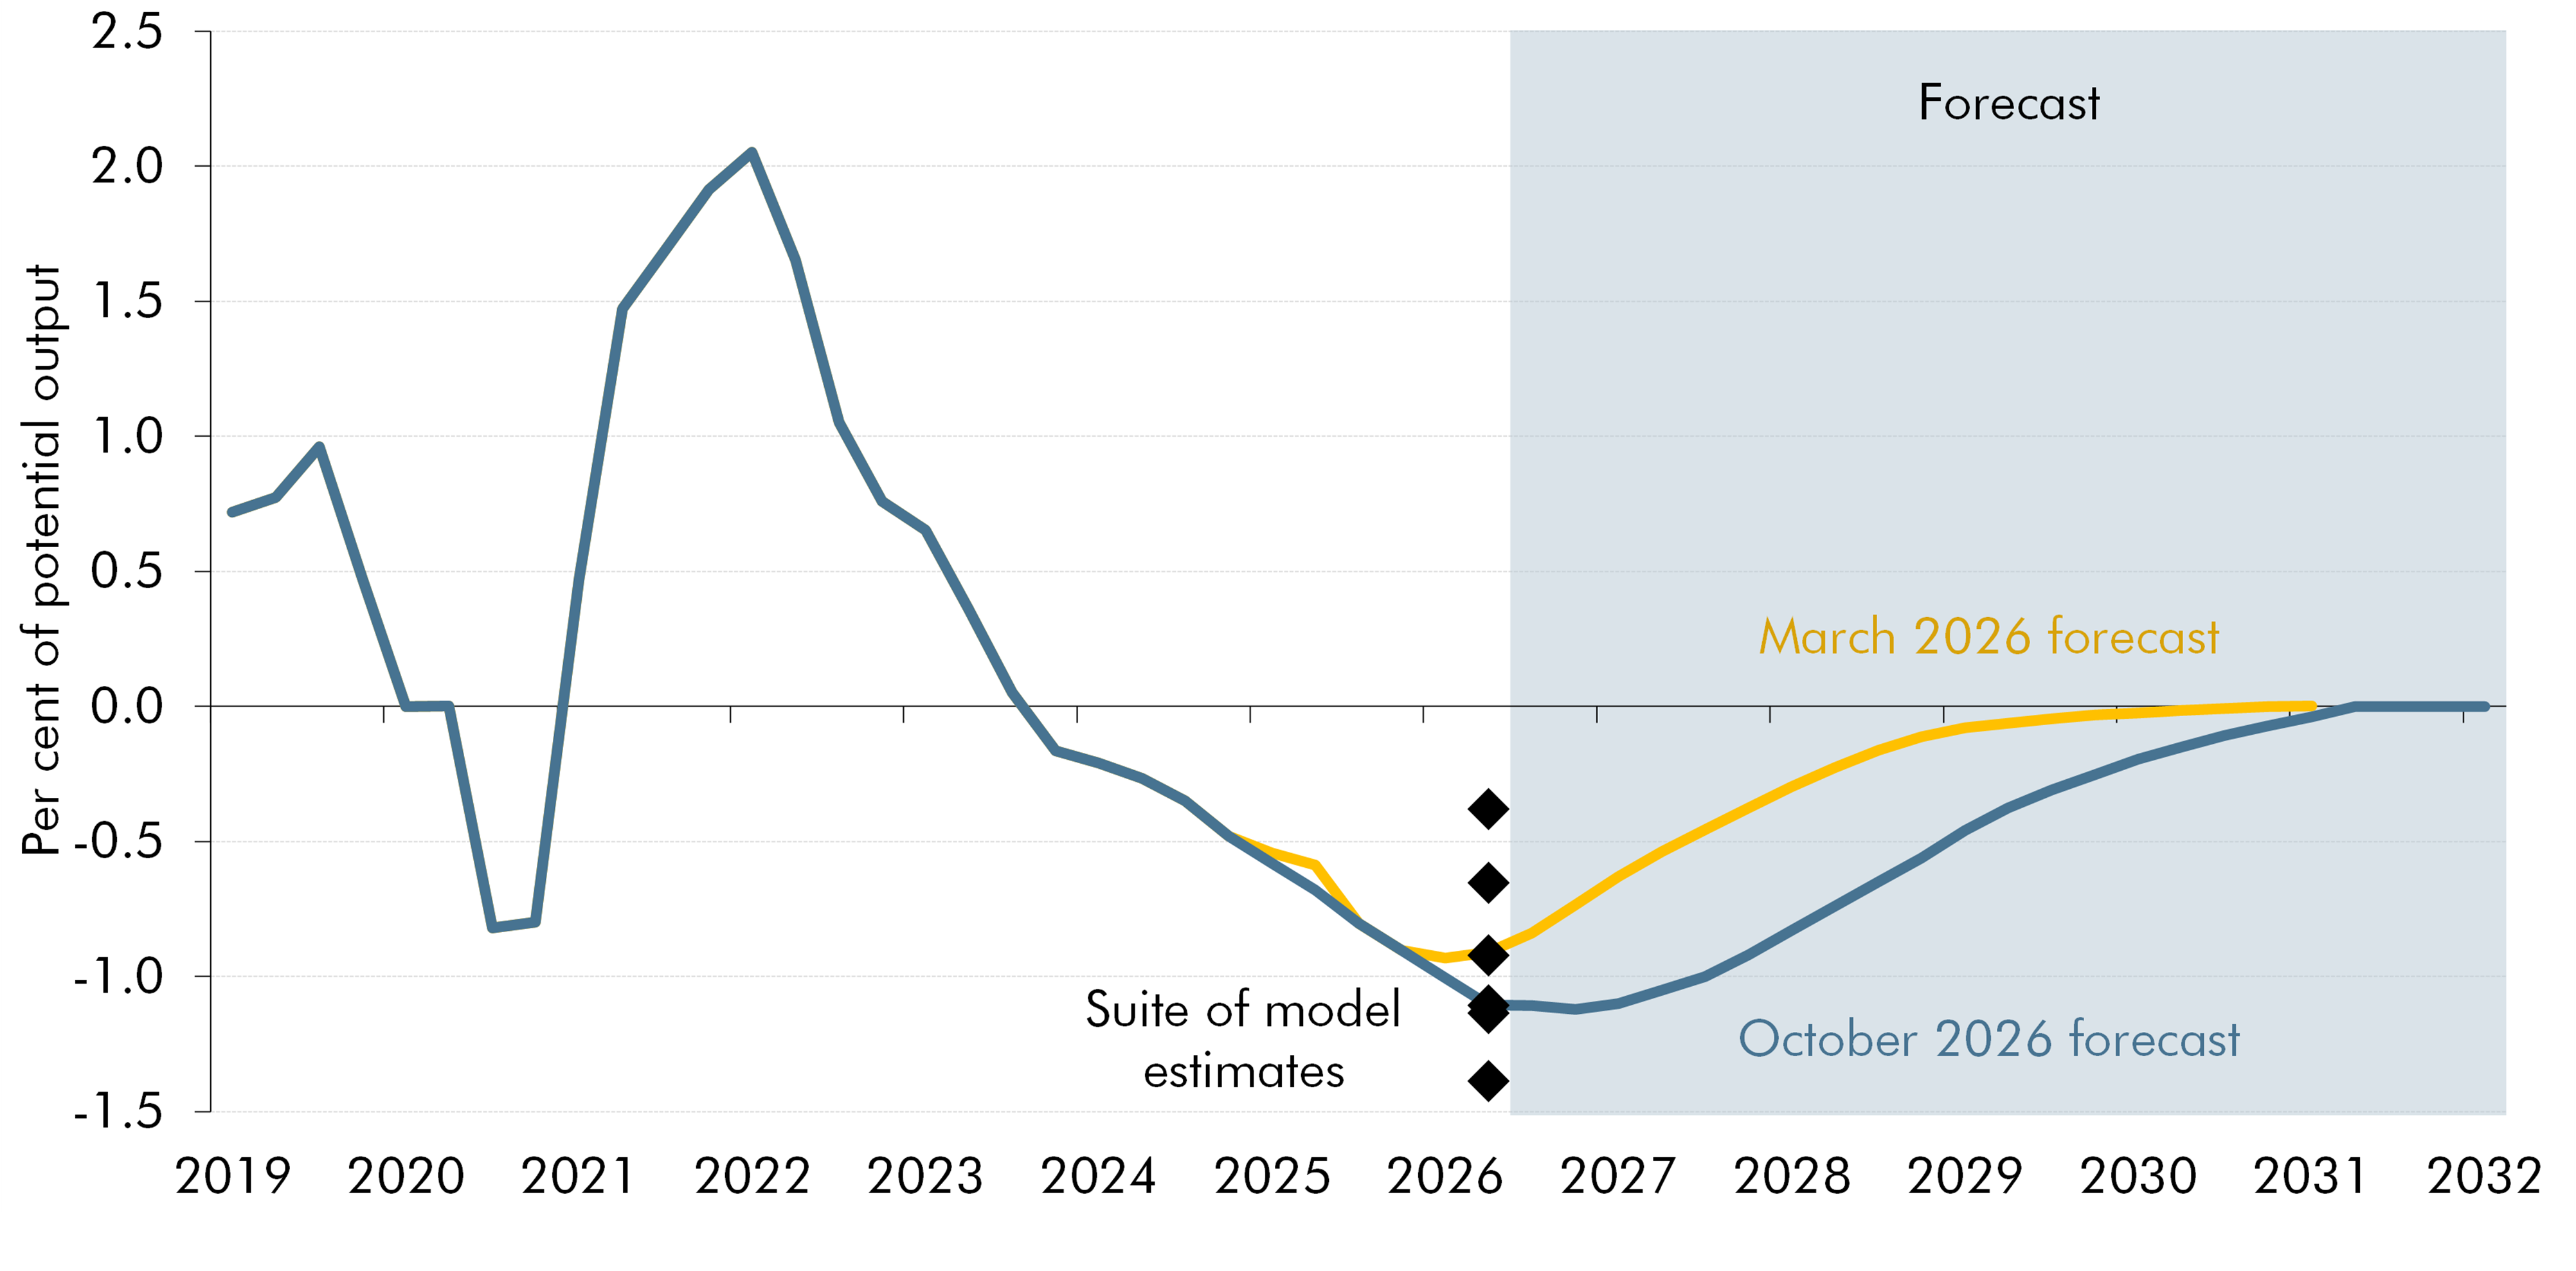
Source: OBR
Real GDP
2.48 Real GDP growth was robust around the start of the Middle East conflict, with quarterly growth of 0.6 per cent in the first quarter of 2026, but we expect higher energy prices to begin to weigh on growth from the second half of 2026. Our central forecast, shown in the left panel of Chart 2.12, is for real GDP growth of around 1¼ per cent in 2026, a slight improvement on our March forecast reflecting significantly higher-than-expected first-quarter growth.[footnote 11] In the second half of 2026 and into 2027, we expect higher global energy prices to feed through to the prices facing consumers and businesses, and higher interest rates to weigh on activity. We have therefore downgraded our central forecast for real GDP growth in 2027 to 1 per cent, 0.5 percentage points below our March forecast. As energy prices are then expected to fall back, our central forecast sees growth pick up to average 1¾ per cent a year over the rest of the forecast period. This leaves the level of GDP in 2030 broadly unchanged from our March forecast.
2.49 We judge that the risks around our central forecast are broadly balanced. The right panel of Chart 2.12 shows that, based on our historical forecast errors, there is a one-in-five chance that real GDP growth in 2027 could be higher than 2¼ per cent and a similar chance that real GDP contracts. In practice, the risks to the forecast will likely be different to those in the past. Upside risks to real GDP growth include a faster reduction in energy prices than we assume and stronger productivity growth, potentially driven by the wider adoption of AI. Downside risks include a larger or more persistent energy shock than implied by market pricing, increased geopolitical uncertainty, more disruption to trade due to uncertainty and the impact of tariffs, and weaker productivity growth. We explore the implications for growth of alternative energy price paths in Chapter 7. There is also a significant risk of wider unexpected shocks hitting the UK economy, with recent examples being the Covid pandemic and Russian invasion of Ukraine. These shocks tend to be larger on the downside than the upside and may result in large differences between forecast and outturn.
Chart 2.12: Real GDP
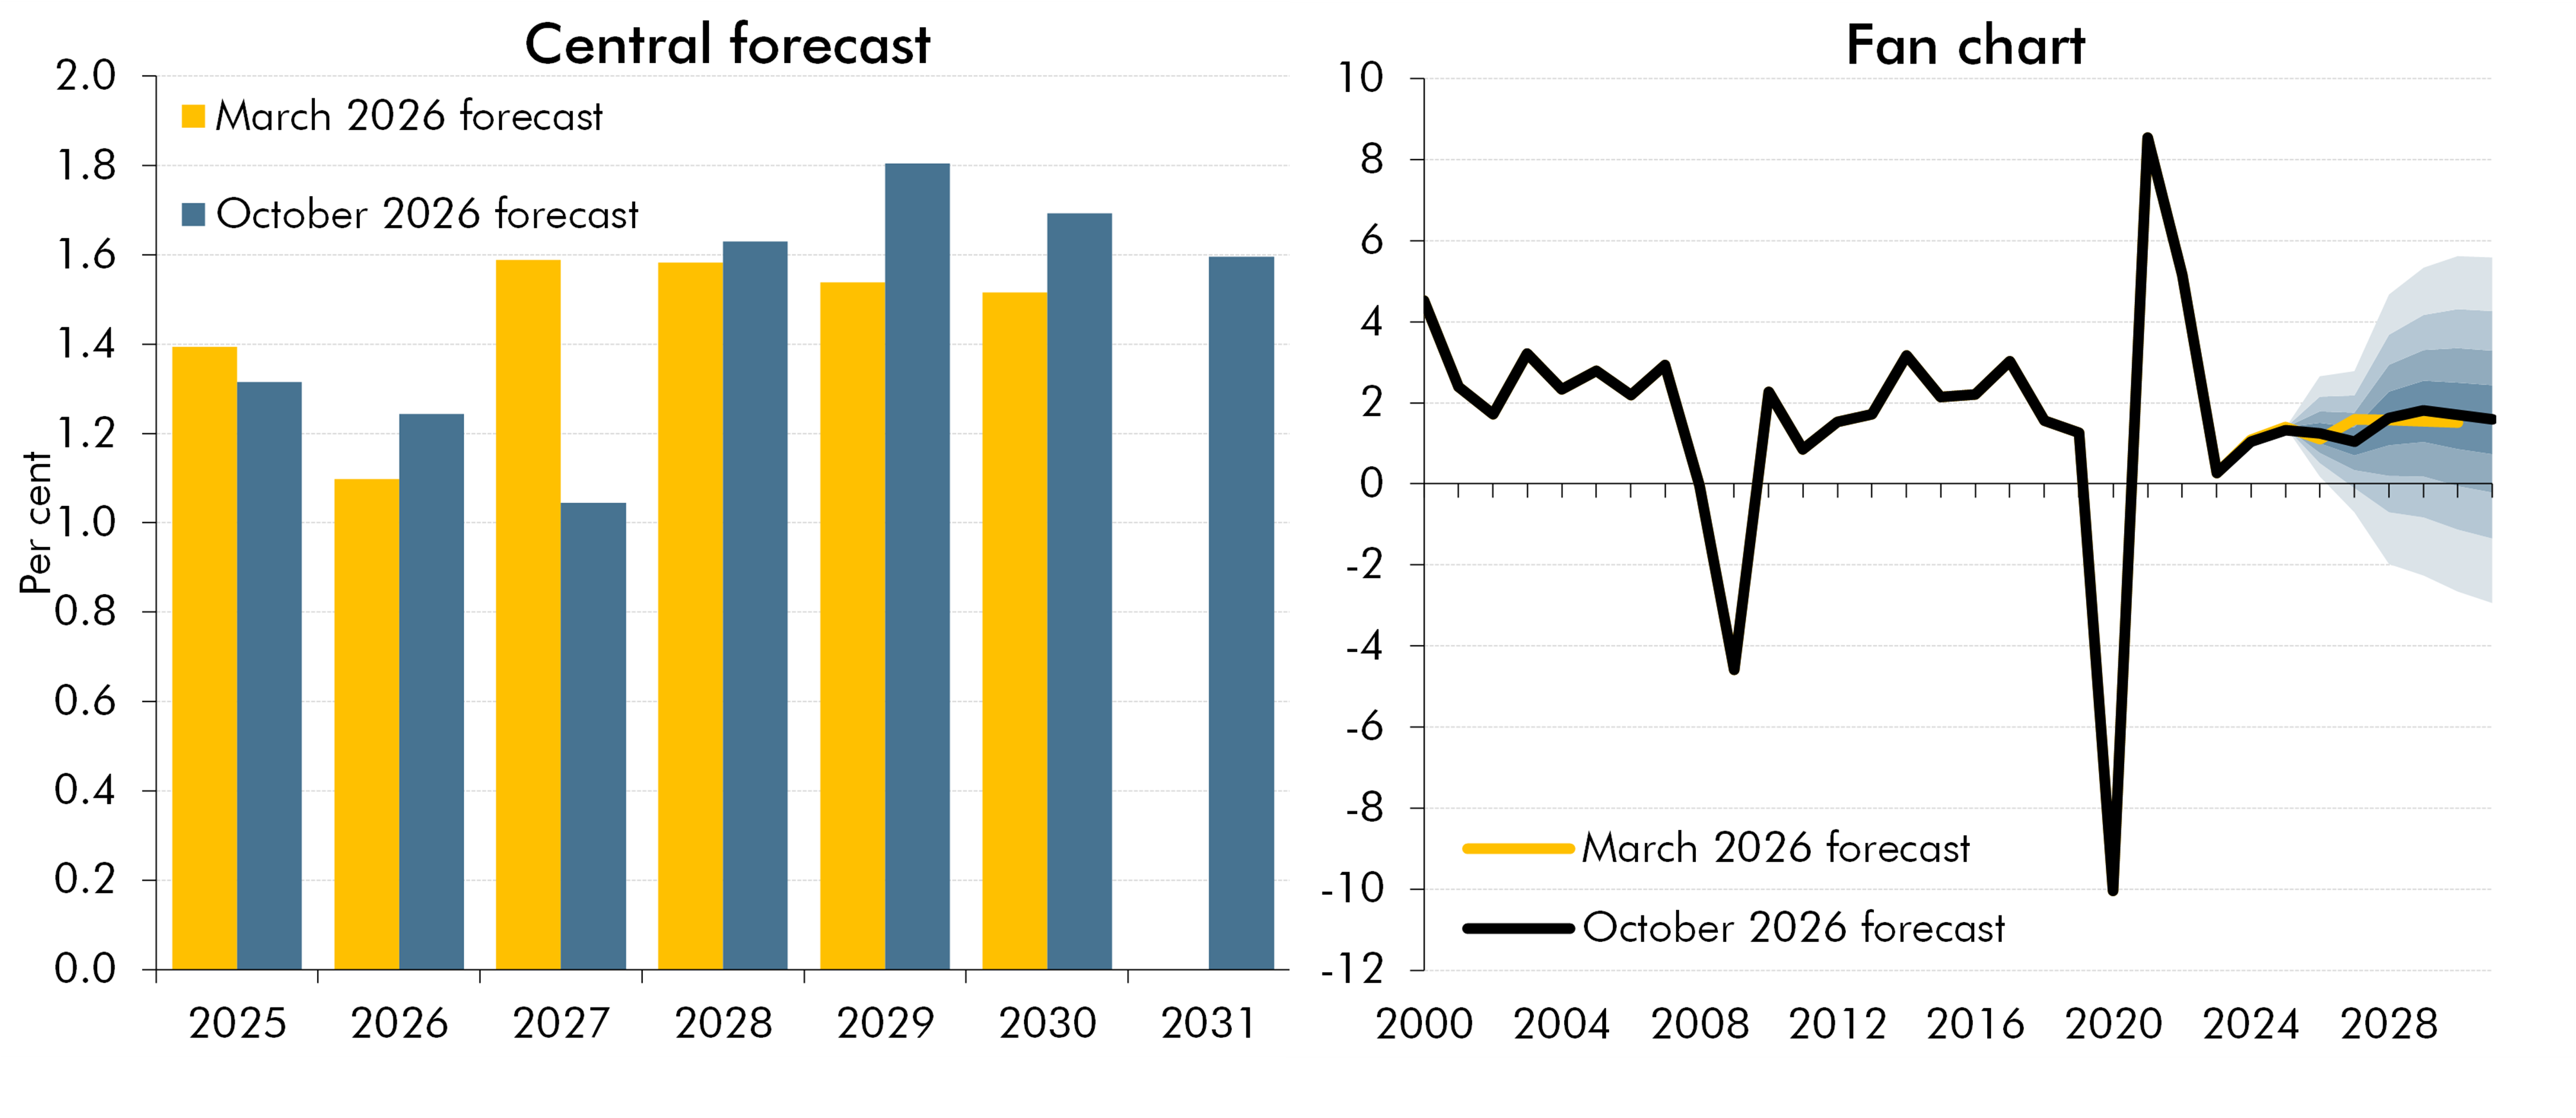
Source: ONS, OBR
2.50 Real GDP per person, an indicator of living standards, is 0.7 per cent higher in 2030 than in our March forecast. This is mainly explained by a higher starting level of potential output, with a small contribution over the forecast from higher growth in capital deepening. The lower forecast for net migration has very little impact on GDP per person as we judge that those net migrants would have had similar labour market characteristics to those of the general population, explained in paragraph 2.38.
Labour market
2.51 Labour market conditions continue to loosen as vacancies and the number of payrolled employees fall, while private sector pay growth has eased. Given the acknowledged issues with data quality within the LFS, we continue to draw on a wide range of evidence in our assessment of labour market conditions, including administrative data and surveys.[footnote 12] This is particularly the case for the participation rate and, consequently, employment growth. The left panel of Chart 2.13 illustrates that non-LFS measures of employment point to a subdued labour market, in contrast to the continued growth in LFS employment. Survey evidence, such as the latest Bank of England Decision Makers Panel, also points to broadly flat employment growth over the past year. HMRC administrative data suggest this continues to be driven by lower inflows into employment rather than higher outflows from employment. We also expect the Employment Rights Act 2025 (ERA) to weigh on the labour market, in addition to previously announced policies including the increases in employer NICs and the National Living Wage. See Chapter 3 for a detailed discussion of the impact of policy measures on the labour market.
2.52 The general trend in the LFS unemployment rate matches this picture of a loosening labour market, rising from its post-pandemic trough of 3.6 per cent in 2022 to 5.2 per cent in the final quarter of 2025 (right panel of Chart 2.13). While the unemployment rate in the LFS fell to 4.9 per cent in the second quarter of 2026, other evidence – such as the number of vacancies, the KPMG and REC UK Report on Jobs, and the employment component of the UK PMI – signal ongoing weakness in labour demand. Given these wider indicators, we expect the unemployment rate to rise marginally from its current level, peaking at just above 5 per cent in the second quarter of 2027, before falling to its estimated equilibrium rate of 4.1 per cent. The peak in unemployment is marginally lower than in our March forecast but comes a year later. We previously explored scenarios with alternative trajectories for the unemployment rate in our March 2026 EFO.
Chart 2.13: Unemployment rate and employment
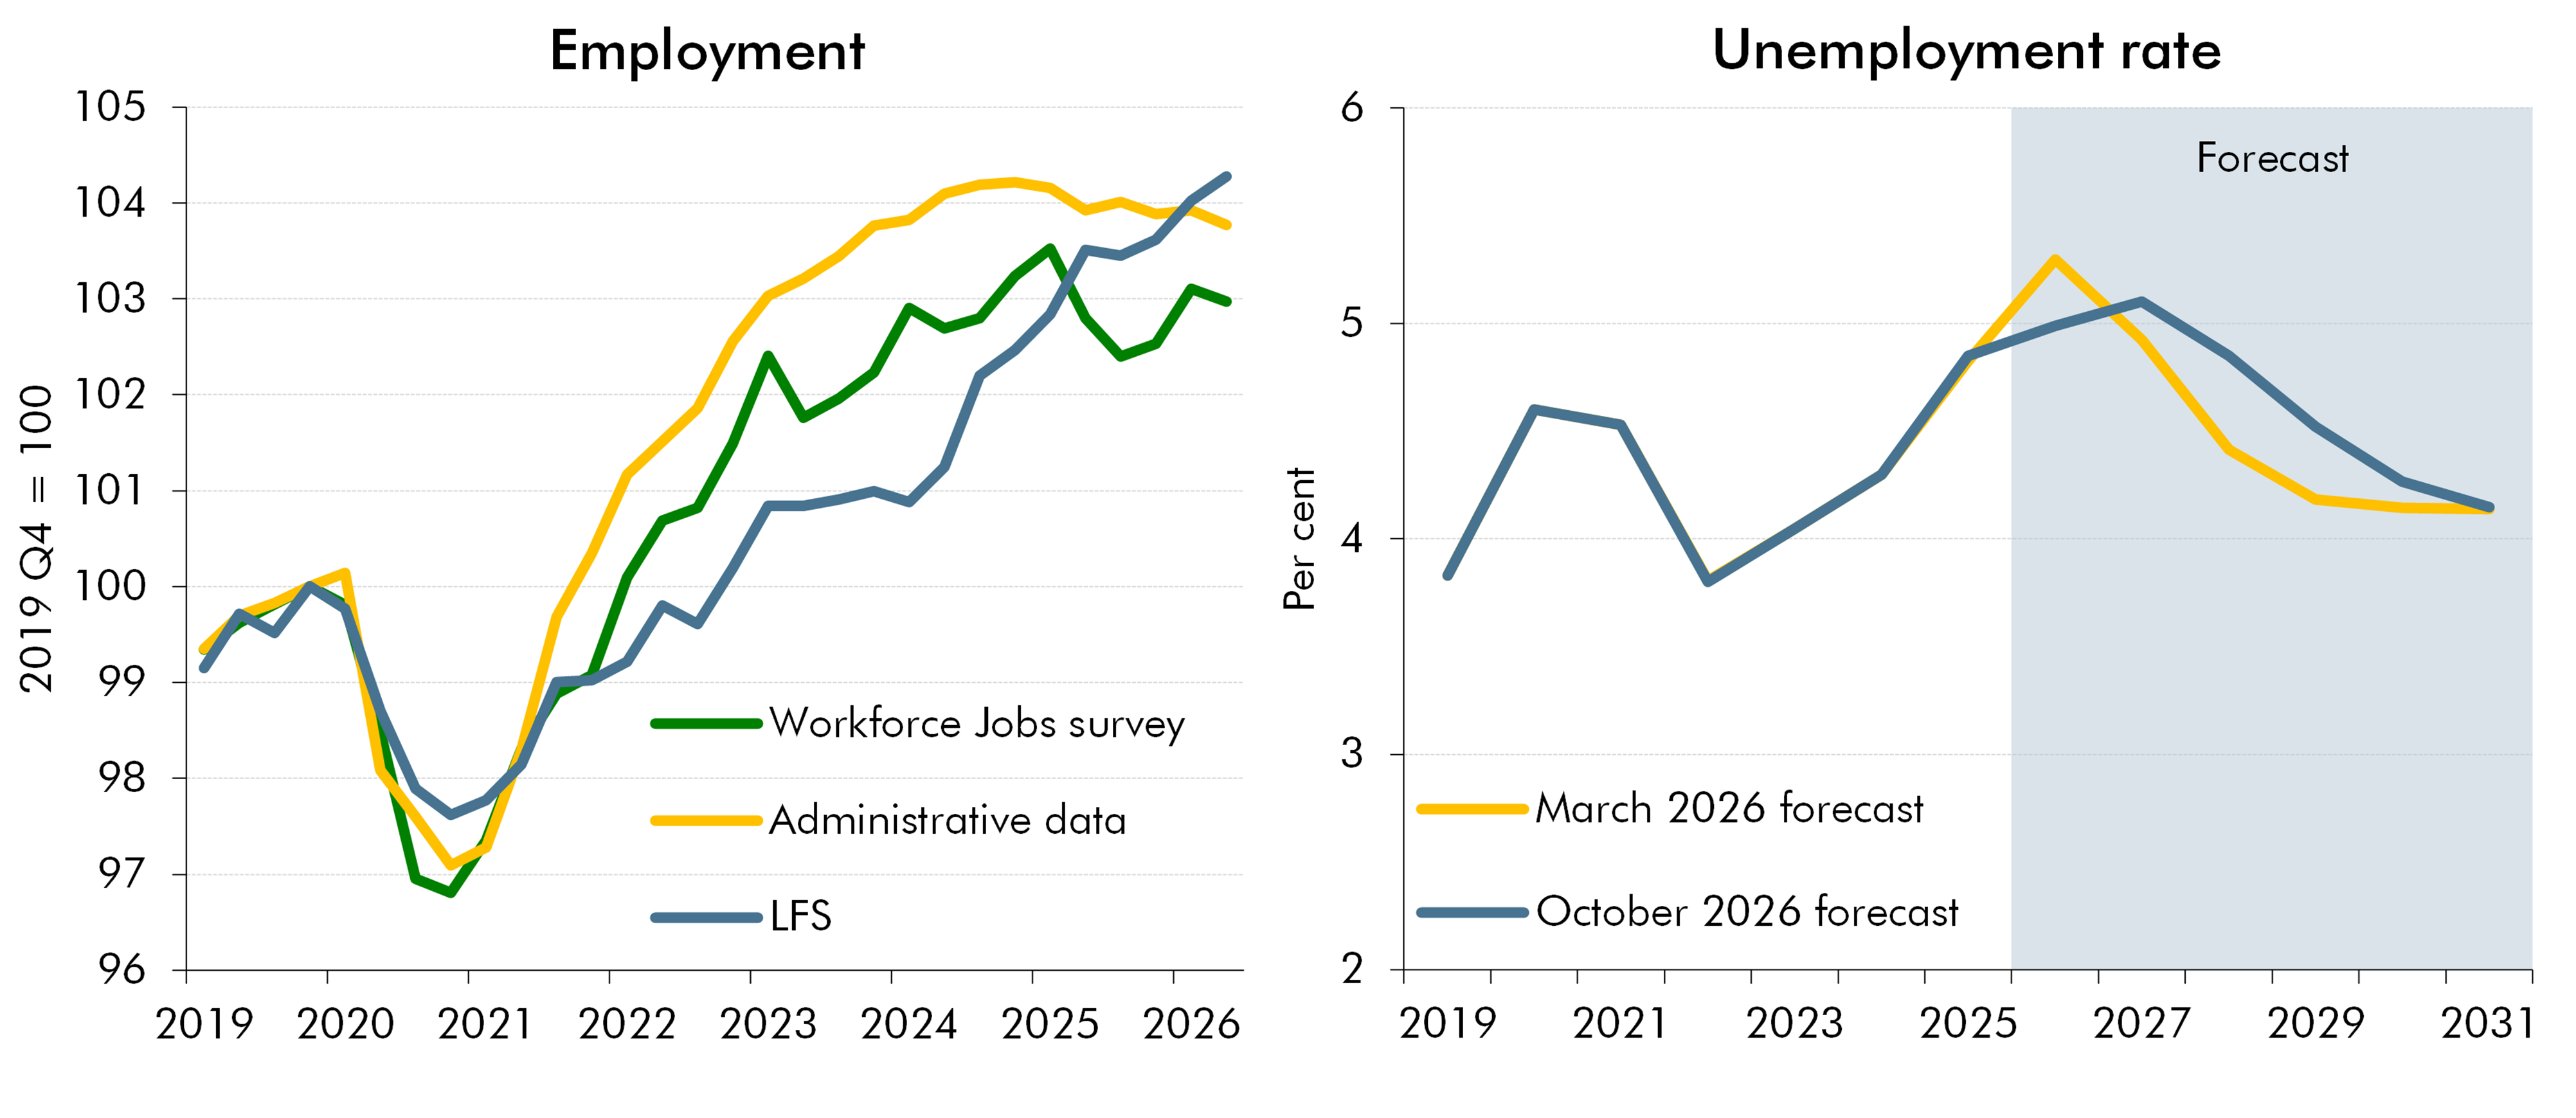
Note: Administrative data is the HMRC RTI payrolls-based estimate from the Resolution Foundation. Workforce Jobs survey data, RTI employees data, and LFS data published on 15 September.
Source: ONS, OBR
Composition of economic activity
Households
Household saving rate
2.53 In our central forecast, the adjusted saving rate, excluding pension valuation effects, falls from around 5½ per cent in 2025 to just over ½ a per cent in 2031 (Chart 2.14). As described in paragraph 2.30, we are forecasting real household disposable incomes to fall slightly in the near term. In the face of this, we expect consumers to gradually reduce saving to smooth their consumption over time. There are significant risks around this forecast. For example, if higher interest rates or general economic uncertainty encourage higher precautionary saving, consumption would be weaker than in our forecast.
Chart 2.14: Household saving rate
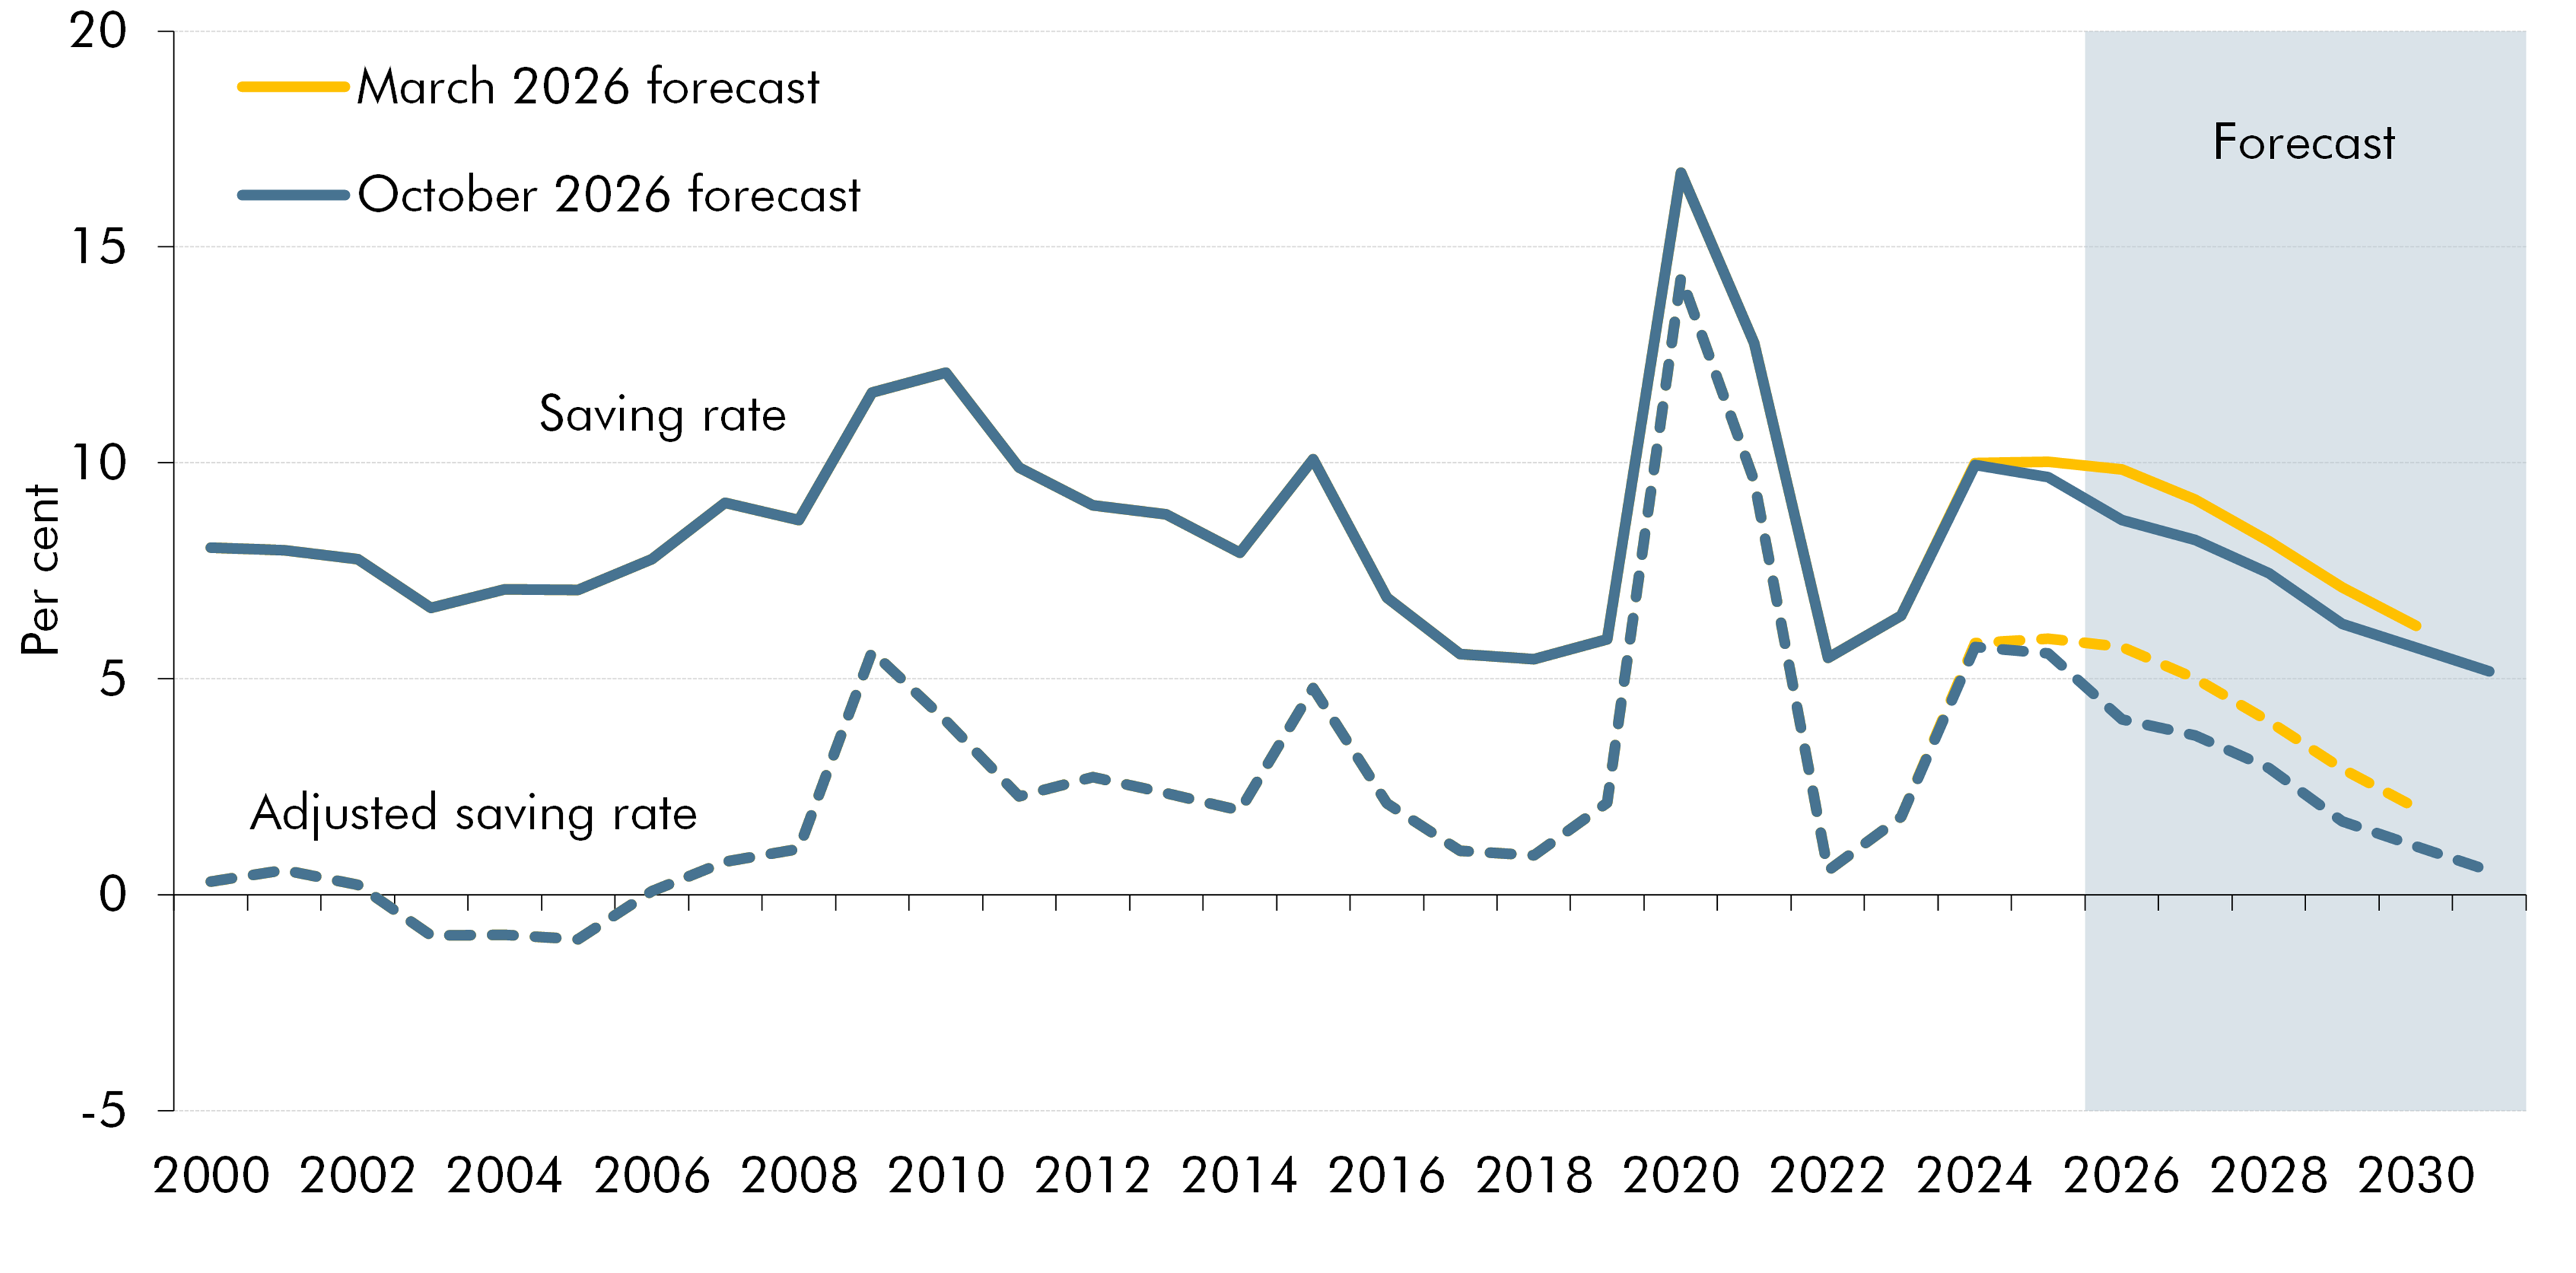
Note: The ‘saving rate’ is defined as one minus the ratio of consumption to disposable income plus the change in net equity in pension reserves. The ‘adjusted saving rate’ is defined as one minus the ratio of consumption to disposable income.
Source: ONS, OBR
Household consumption
2.54 Real household consumption has stagnated since the pandemic, with its level in 2025 only 1 per cent higher than in 2019. We expect real household consumption growth to average ¾ of a per cent in 2026 and 2027, as weak real income growth weighs on spending growth. It then picks up to grow more in line with overall GDP in the medium term, following the recovery in real income growth. This leaves real consumption as a share of GDP at 61 per cent at the end of the forecast, over 2 percentage points below the average level from 2010-2019, and 0.4 percentage points below the level we forecast in March. The relatively weak growth in consumption reflects higher energy prices (and that these constitute a larger shock to real household disposable incomes than real GDP) and a higher share of consumption occurring via government-provided services since the pandemic.
Business sector
Profits
2.55 The rate of return on corporate capital and the profit share of GDP are both currently at low levels relative to recent history (Chart 2.15). After a period when firms have absorbed a range of cost increases into lower profits, including the rises in employer NICs and energy prices, we increasingly expect them to pass these costs on to households and rebuild their profit margins. Increasing real wages by slightly less than productivity growth should push up the rate of return and profit share towards more historically typical levels. The relatively loose labour market is likely to underpin this process by reducing workers’ bargaining power.
Chart 2.15: Rate of return and profit share of income
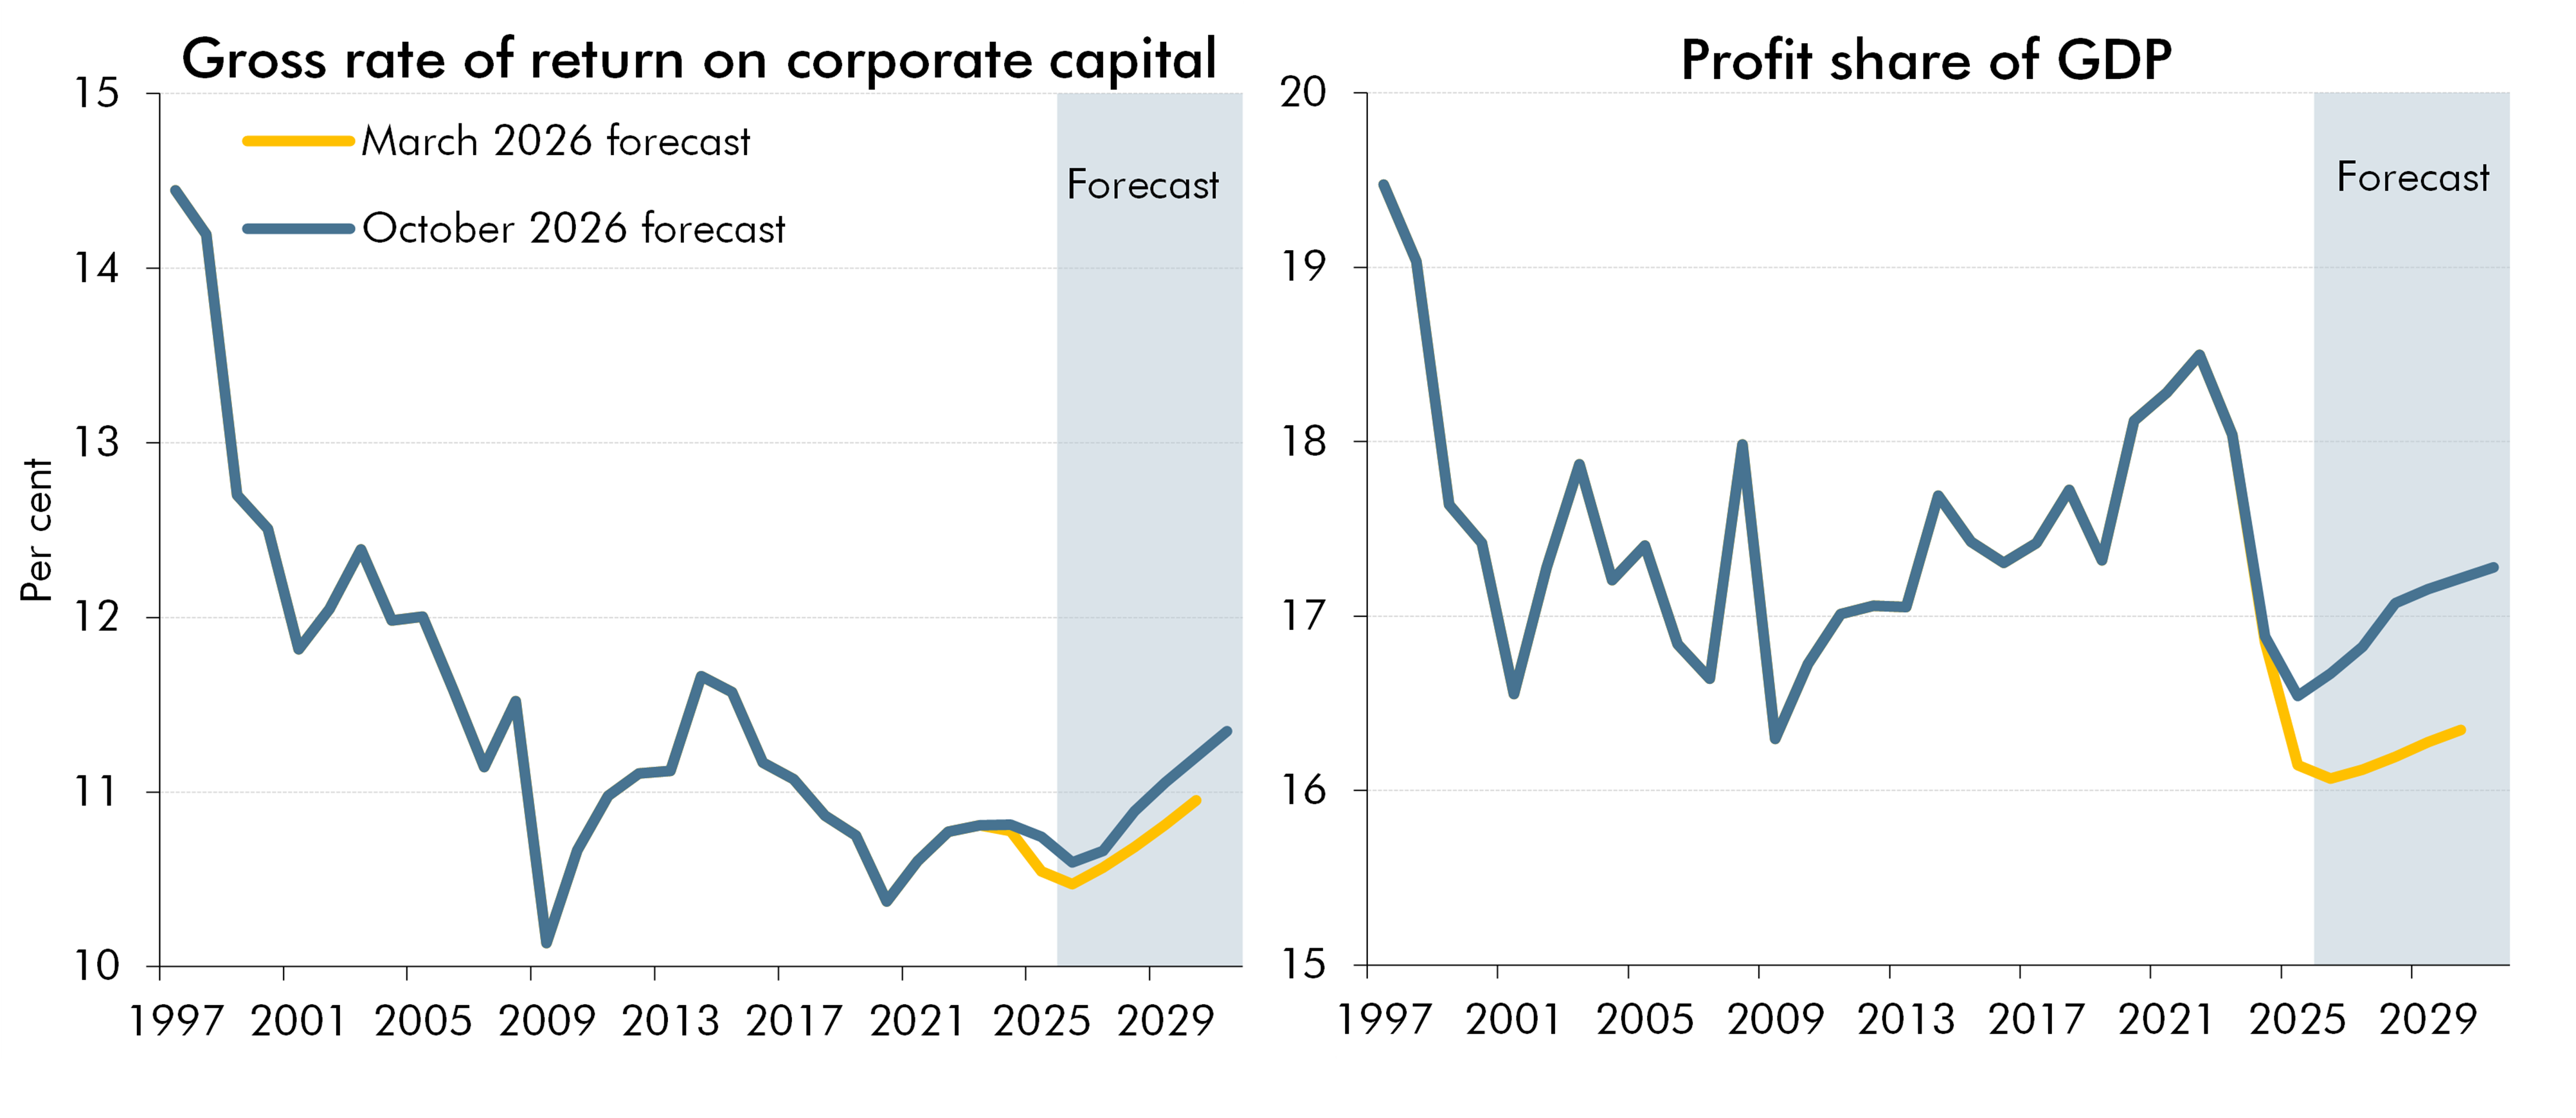
Note: The gross rate of return is calculated as private non-financial corporations’ (PNFC) gross operating surplus divided by their gross capital employed. PNFC gross operating surplus includes their gross trading profits and their rental income from residential and non-residential buildings, but excludes their inventory holding gains. Profit share in the right panel includes only PNFC gross trading profits.
Source: ONS, OBR
Business investment
2.56 Real business investment rose by around 2½ per cent over the first half of 2026, leaving its level 2 per cent above our March forecast by the second quarter of 2026. We expect some of this recent strength to unwind as headwinds from higher energy prices weigh on business activity and investment over 2027. We then expect growth in business investment to pick up, averaging 1¼ per cent a year. By 2030, we expect the level to be ½ a per cent above our March forecast, reflecting both its recent strength and a higher profits forecast.
Government
2.57 Real government spending, the sum of government consumption and investment, is expected to grow by just under 4 per cent in 2026, up from 2 per cent in 2025. Growth then slows to average 1¼ per cent over the remainder of the forecast. Weaker real departmental spending growth in the medium term leaves the level of total government spending around ½ a per cent lower in 2030 relative to our March forecast. Within government spending, consumption rises from 21 per cent of GDP in 2025 to 21¼ per cent in 2026. It then settles at around 21 per cent of GDP by the end of the forecast, significantly higher than the 19½ per cent in 2019. Government investment follows a similar profile, increasing from just under 3½ per cent of GDP in 2025 to nearly 4 per cent in 2027, before falling back to around 3½ per cent by 2031. This is around ¾ of a percentage point above the level in 2019.
Current account and sectoral balances
2.58 We forecast the current account deficit of the balance of payments to narrow from just over 3 per cent of GDP in 2025 to around 2½ per cent by 2030, as export growth outpaces import growth. Chart 2.16 shows how the matching inflow of foreign saving to fund this deficit represents a steady inflow of net lending from the rest of the world. As weak income growth drives a fall in household saving, we expect the household net lending position to fall from a surplus of around 1¾ per cent of GDP in 2026 to a deficit of 1¼ per cent by 2031. The corporate sector moves from a small deficit to a surplus by 2030 as firms rebuild the rate of return and investment falls slightly as a share of GDP. The public sector deficit narrows significantly over the forecast, but the profile remains similar to our March forecast.
Chart 2.16: Sectoral net lending
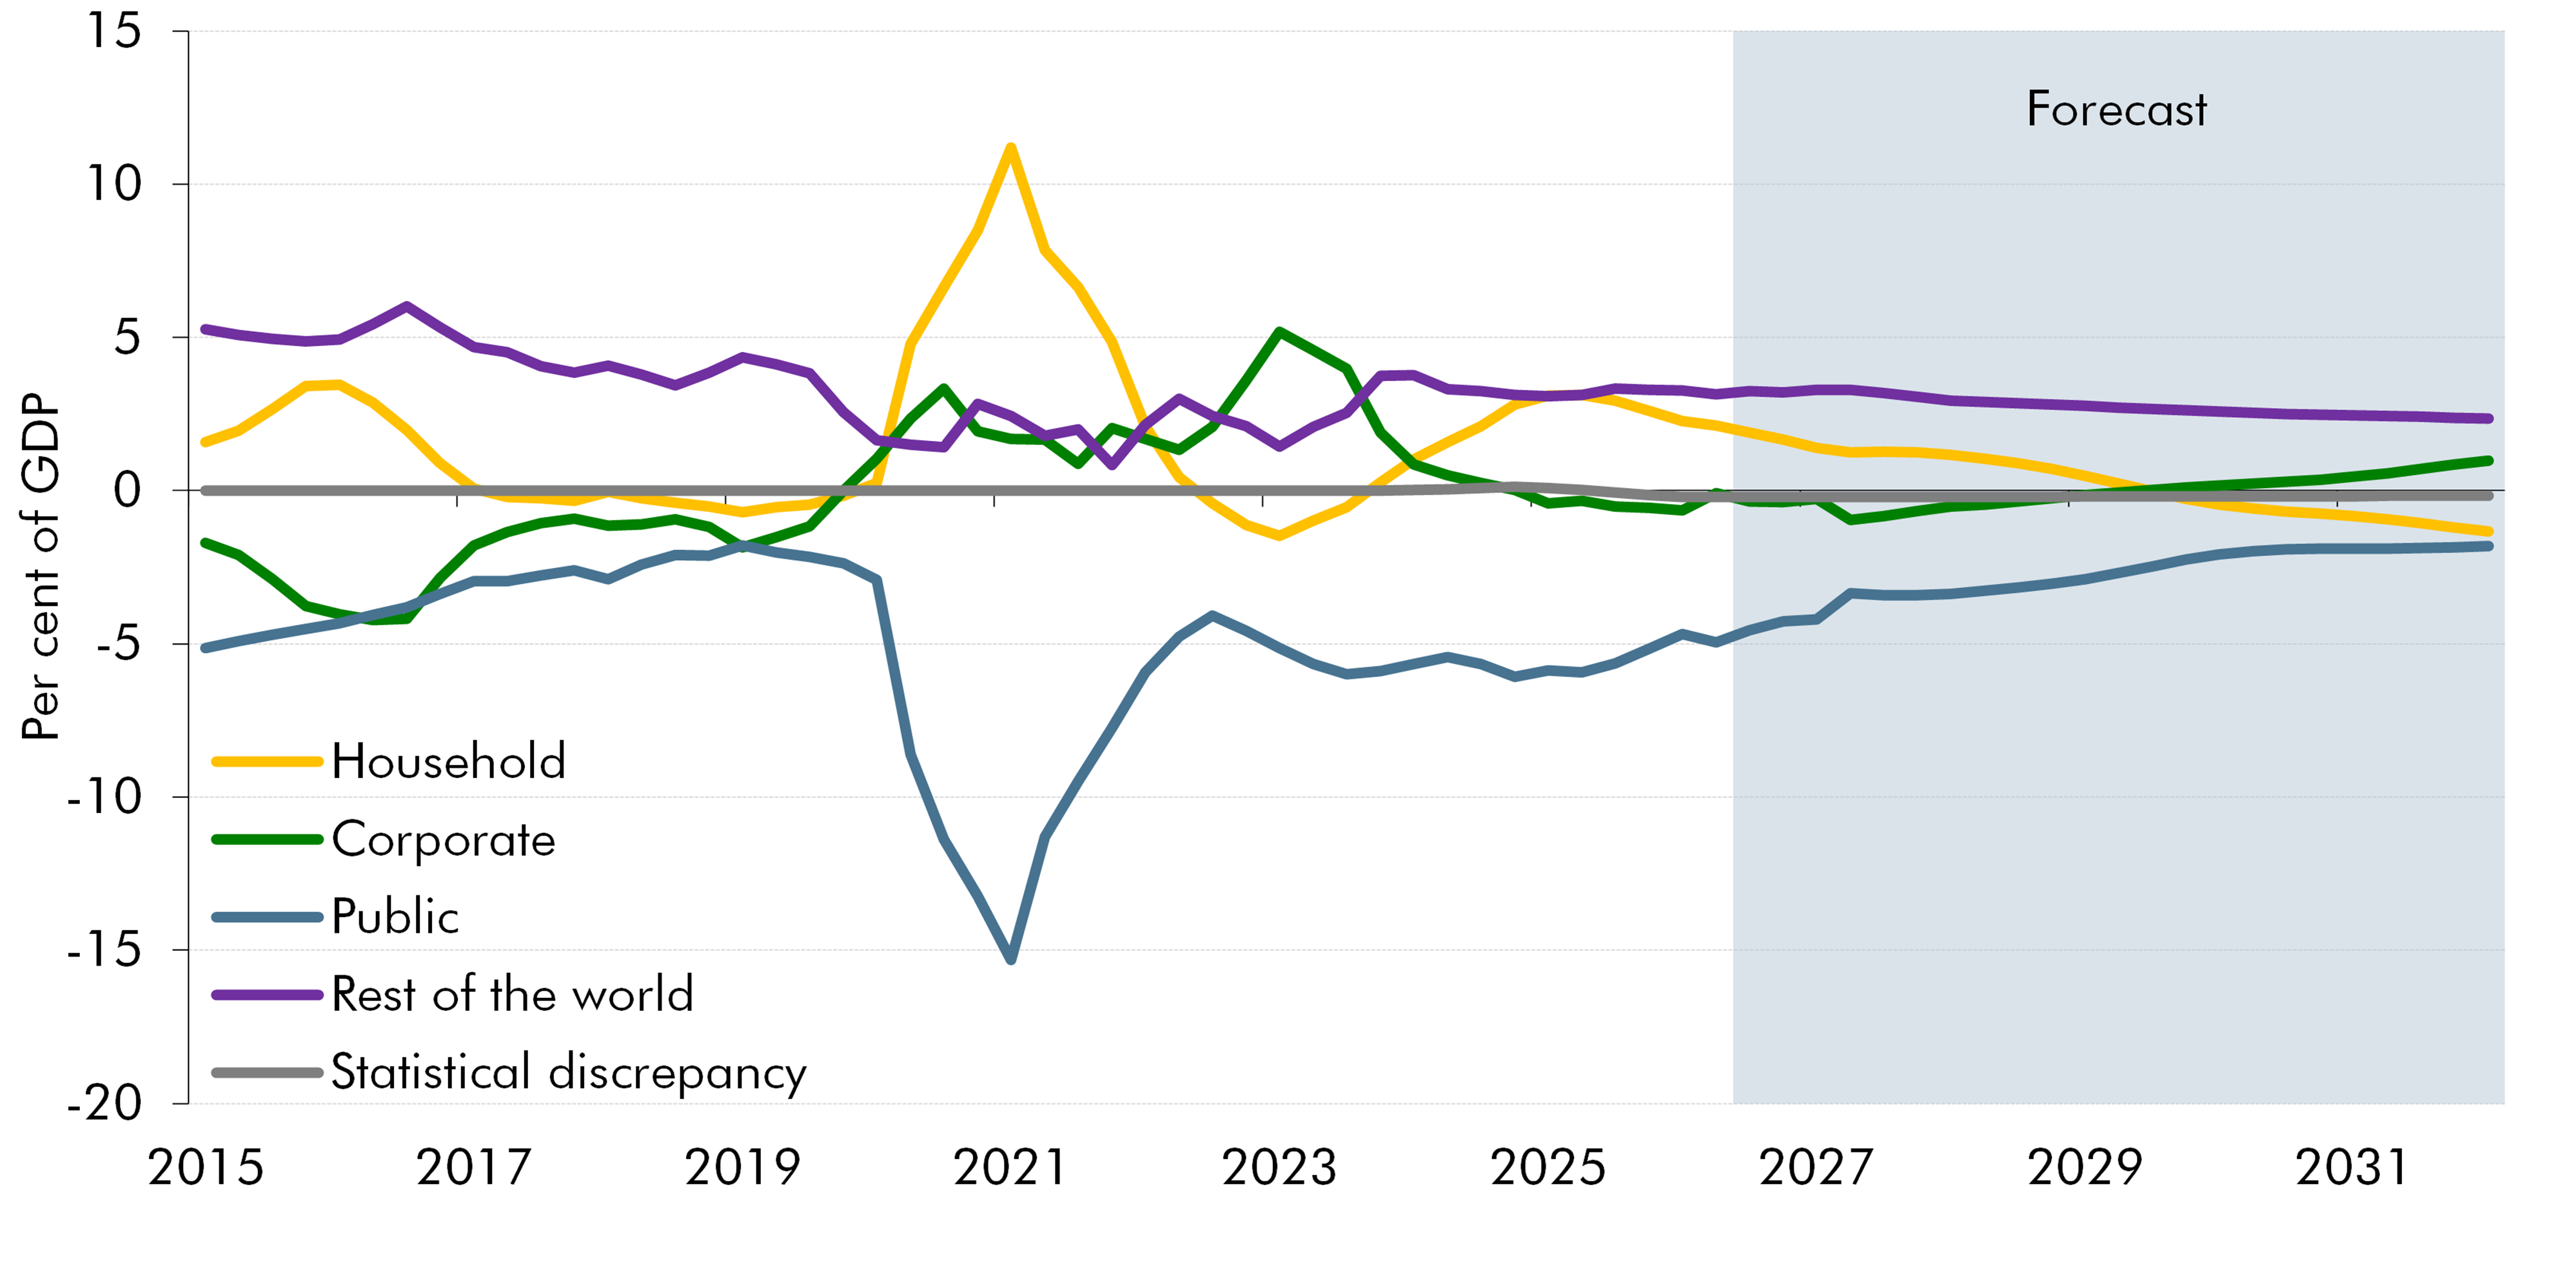
Note: Four-quarter rolling average.
Source: ONS, OBR
The housing market
Mortgage rates
2.59 We expect that the average effective interest rate on the outstanding stock of mortgages will rise from 4 per cent in 2026 to around 5 per cent in 2031. This is due to an upward-sloping yield curve pushing up quoted rates, and people rolling off mortgages that were fixed when rates were lower. As illustrated in the left panel of Chart 2.17, this effective rate is higher than the average since the financial crisis (3 per cent), but significantly lower than over the decades leading up to 2008. The stock of outstanding mortgage debt is around 85 per cent of household disposable income across the forecast period. This is lower than the peak during the financial crisis, but higher than at any time before the early 2000s, when effective mortgage rates were significantly higher. The right panel of Chart 2.17 shows that mortgage payments as a share of household disposable income are expected to rise to reach 4¼ per cent in 2031, the highest since 2009 and more than double the 2021 level of 2 per cent.
Chart 2.17: Mortgage rate and mortgage debt
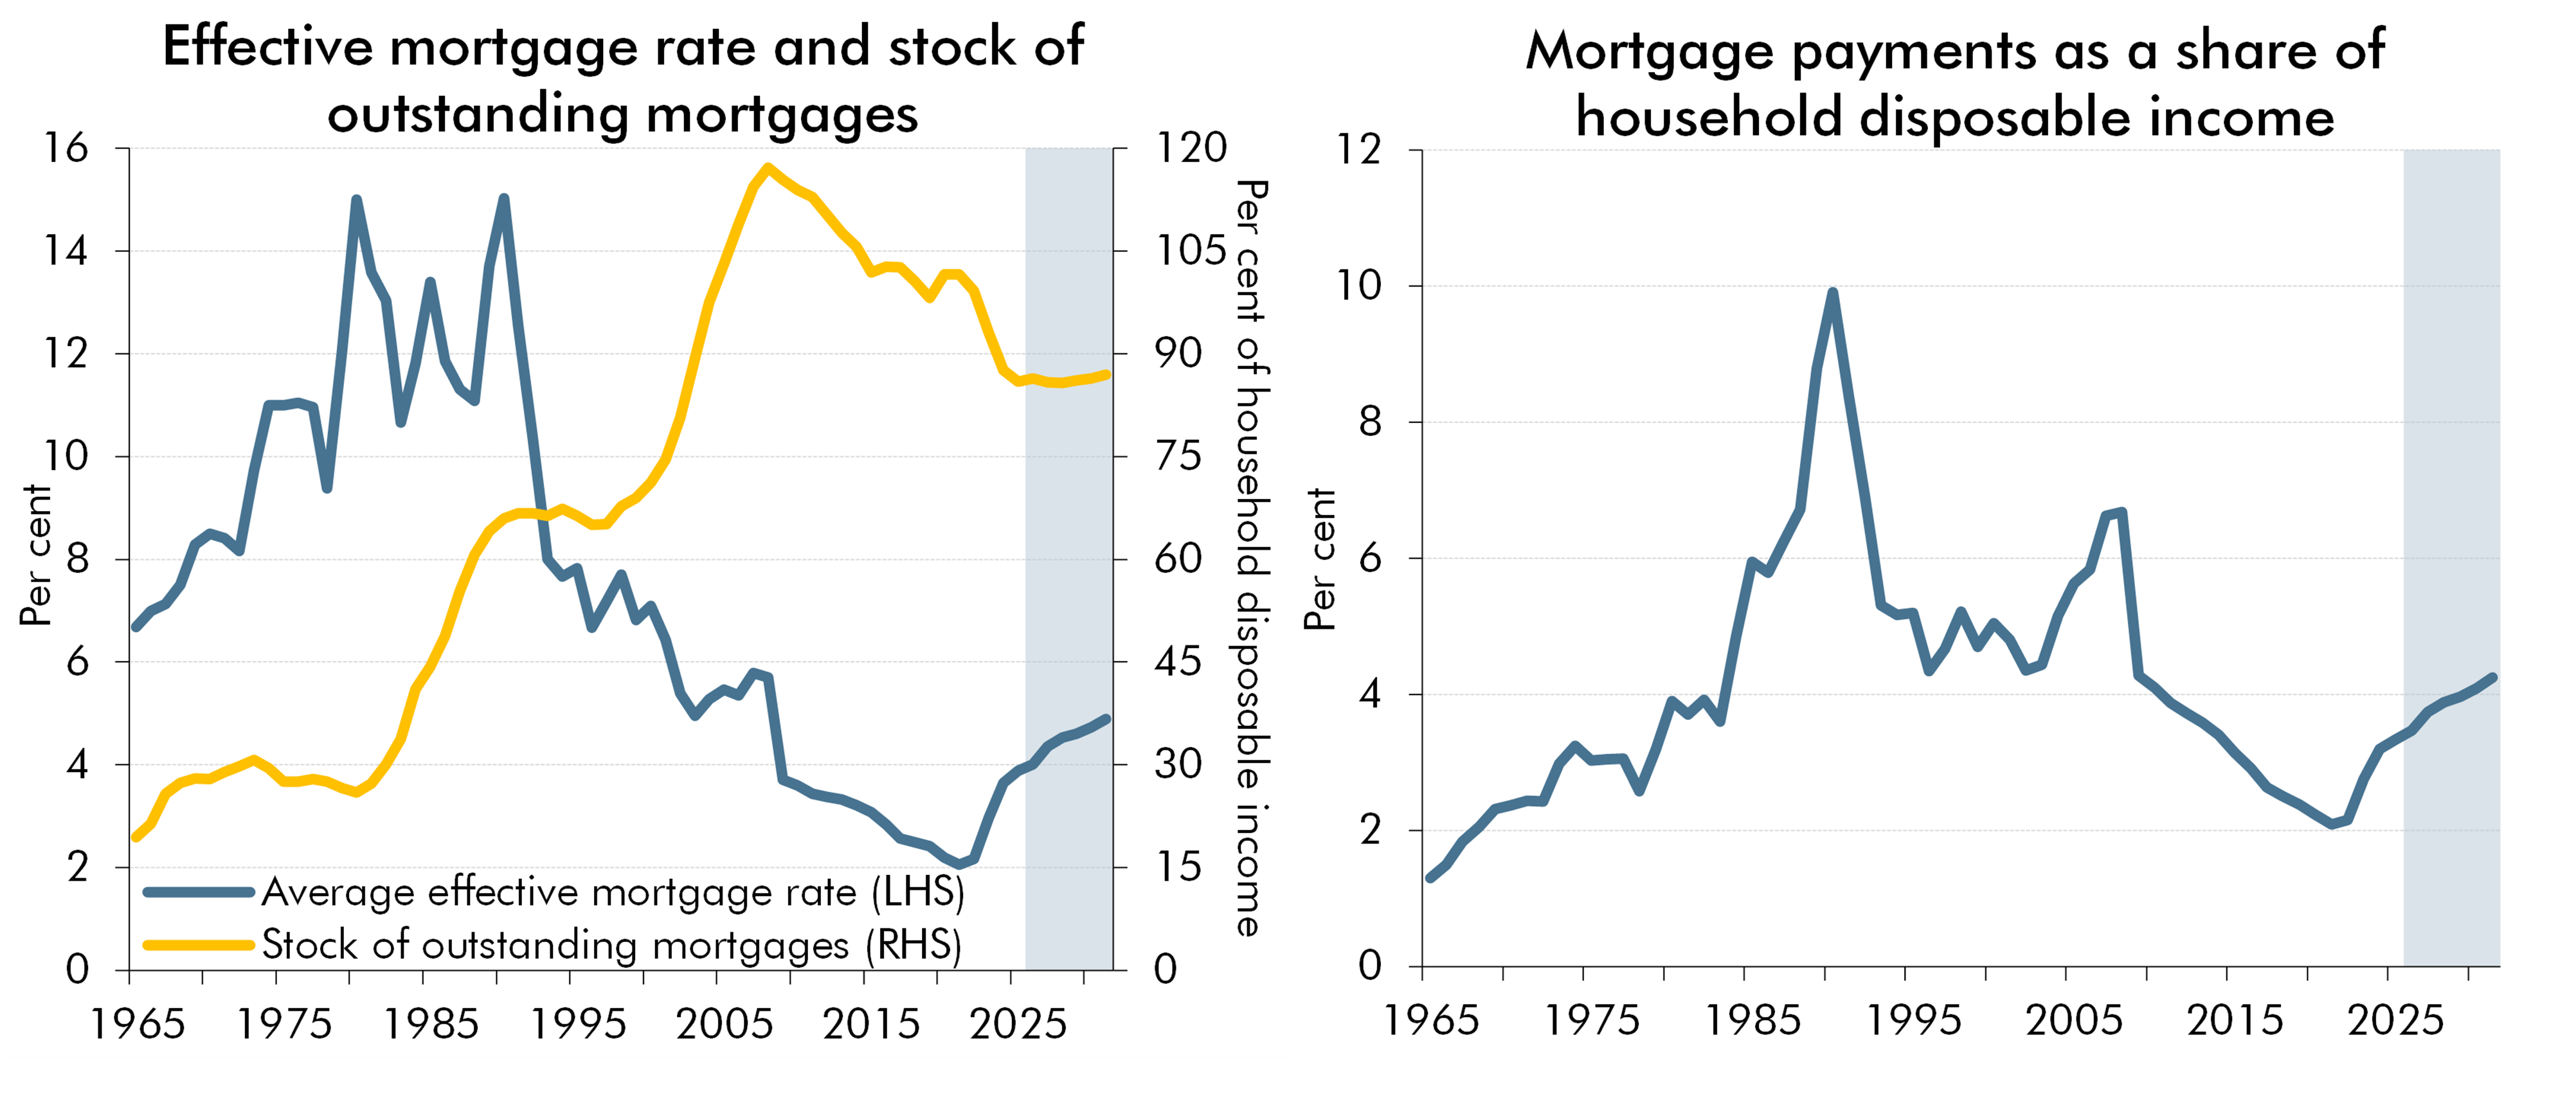
Note: Shaded area marks forecast period. In the right panel, mortgage payments as a share of household disposable income are calculated by multiplying the stock of outstanding mortgages by the average effective mortgage rate.
Source: ONS, OBR
Housing supply
2.60 As shown in Chart 2.18, we expect net additions to the housing stock to fall from around 230,000 in 2025-26 to 220,000 in 2026-27 and 2027-28, before increasing gradually to 260,000 in 2030-31. Compared to the March forecast, we expect 190,000 fewer cumulative net additions over the forecast period. We expect the ’Your First Home‘ equity loan scheme to only have a marginal impact on housing supply given its limited overall size.
Chart 2.18: Net additions to the housing stock
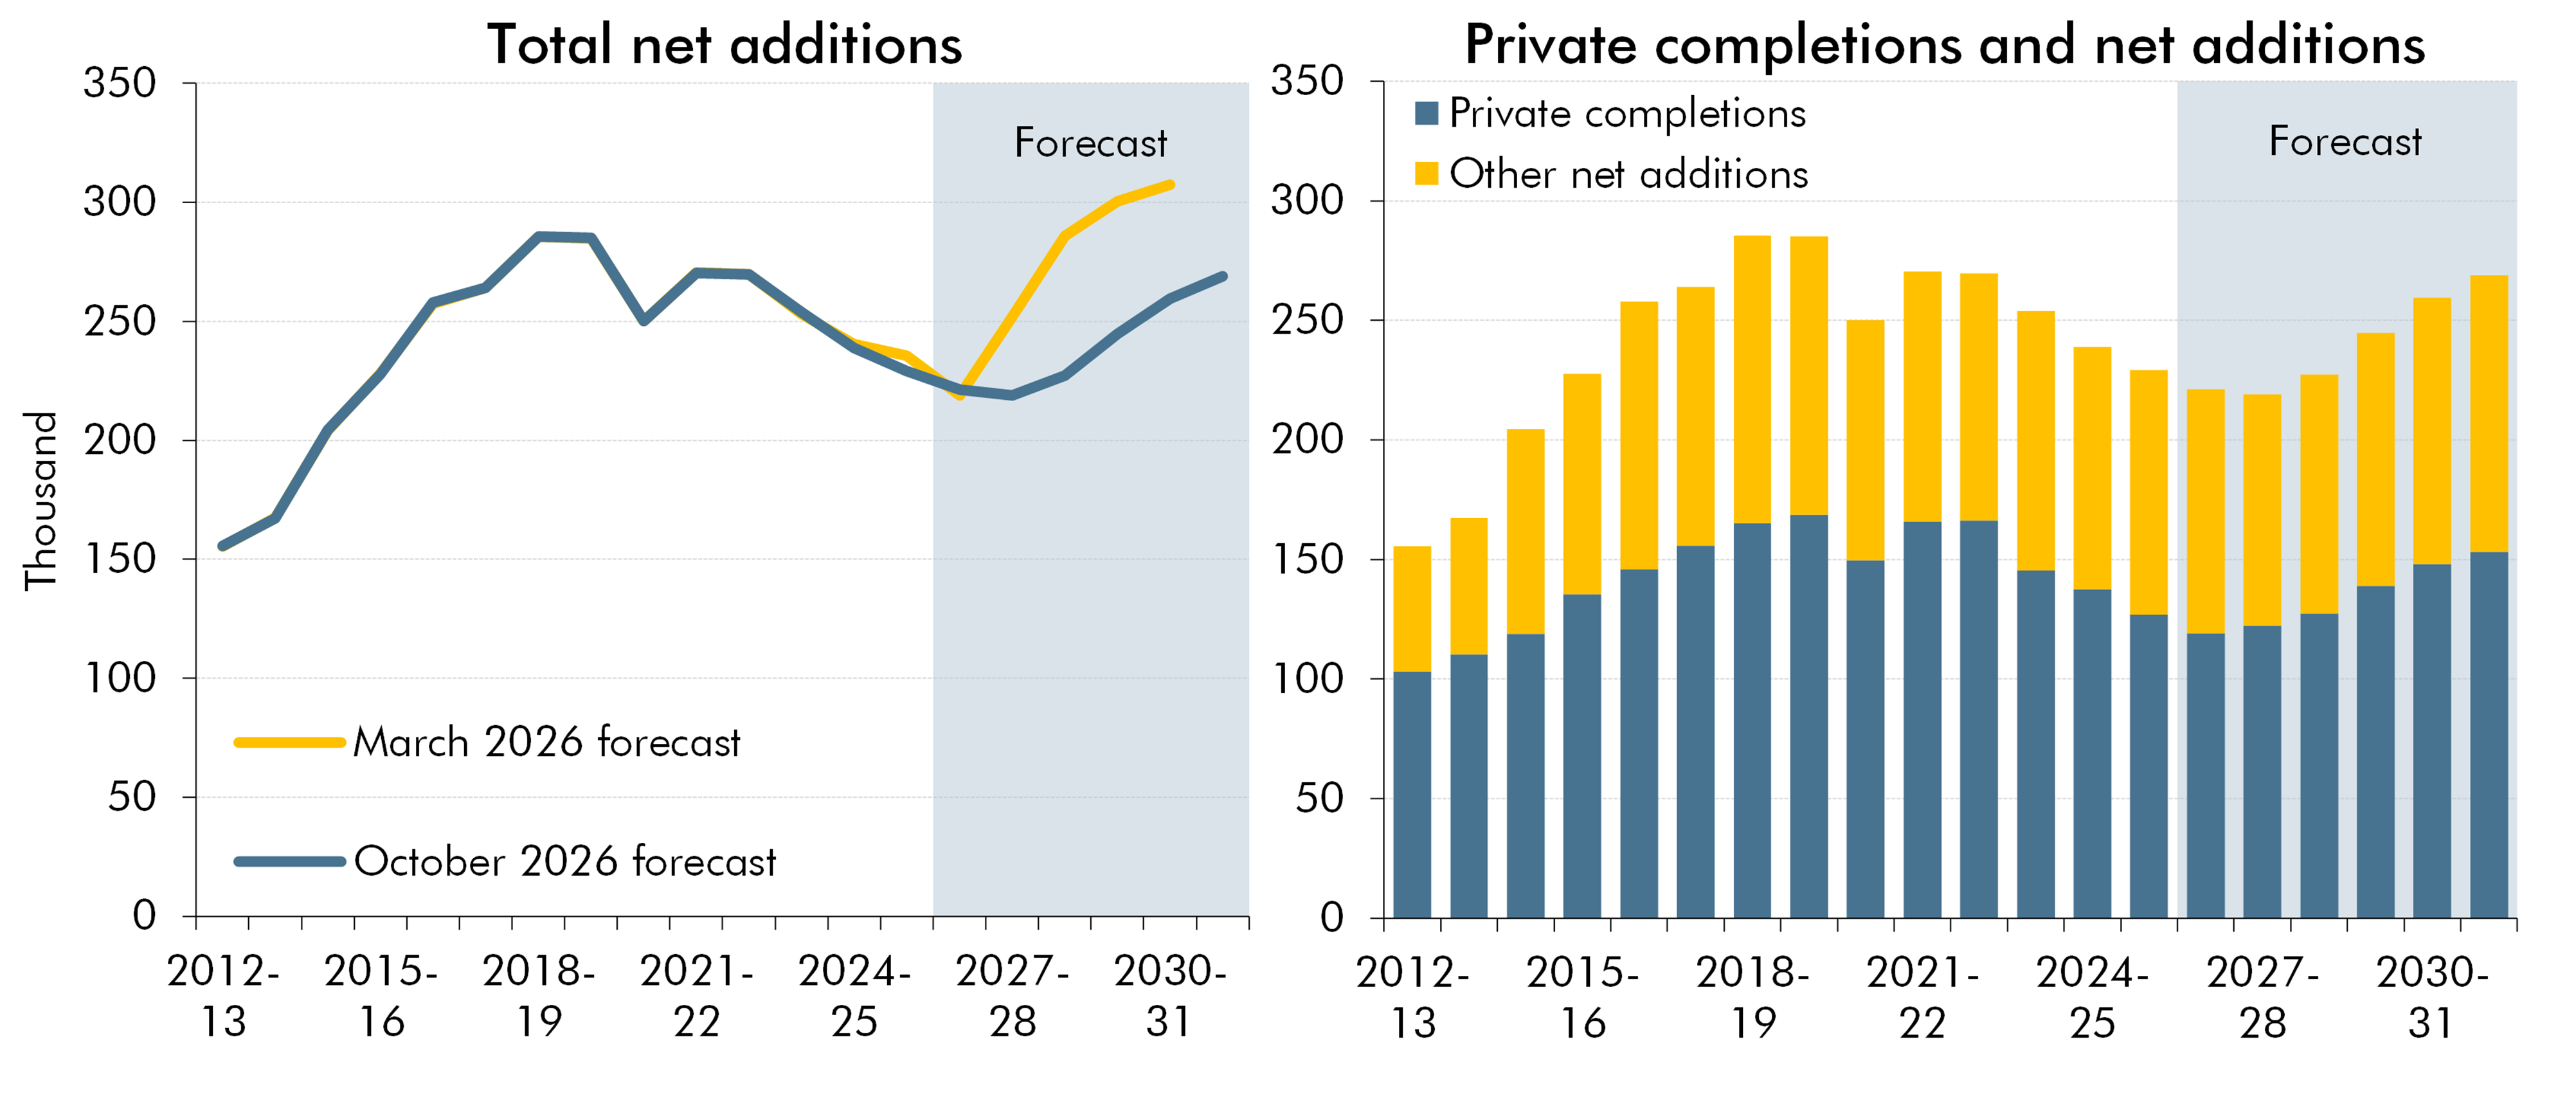
Source: ONS, OBR
2.61 We have not changed our estimate from the March 2025 forecast that the National Planning Policy Framework (NPPF), on its own, would boost housebuilding significantly. But leading indicators, particularly housing permissions, suggest that housing supply will remain substantially weaker than would be consistent with our previous forecasts in the near term (see Chart 2.19). Over the medium term, we judge that the economic environment, including as a result of higher interest rates, and the wider regulatory picture, mean net housing additions are likely to rise more slowly than we previously expected:
-
Higher interest rates since late 2022, alongside other affordability pressures and weak effective demand, have weighed on the commercial viability of residential development. Industry evidence suggests that higher borrowing costs and weaker buyer sentiment have weighed on house price growth, reducing developers’ ability to absorb rising costs.[footnote 13] This points to a flatter near-term profile for net additions, with some medium-term recovery expected as some of these economic conditions improve.
-
The weaker profile for housing supply in the near and medium term also partly reflects the cumulative effect of regulatory and fiscal changes outside the planning system over the last decade, particularly since 2019. These policy developments have increased the cost, complexity, and timescales associated with residential development. These include measures aimed at improving building safety, such as the Building Safety Levy and Building Safety Regulator regime, environmental requirements such as Biodiversity Net Gain and nutrient mitigation schemes, and wider fiscal measures including the residential property developer tax and higher corporation tax rates. Taken together, these measures appear to have weighed on housebuilding activity to a greater extent than we had previously assumed.
Chart 2.19: Housing completions indicated by residential planning permissions
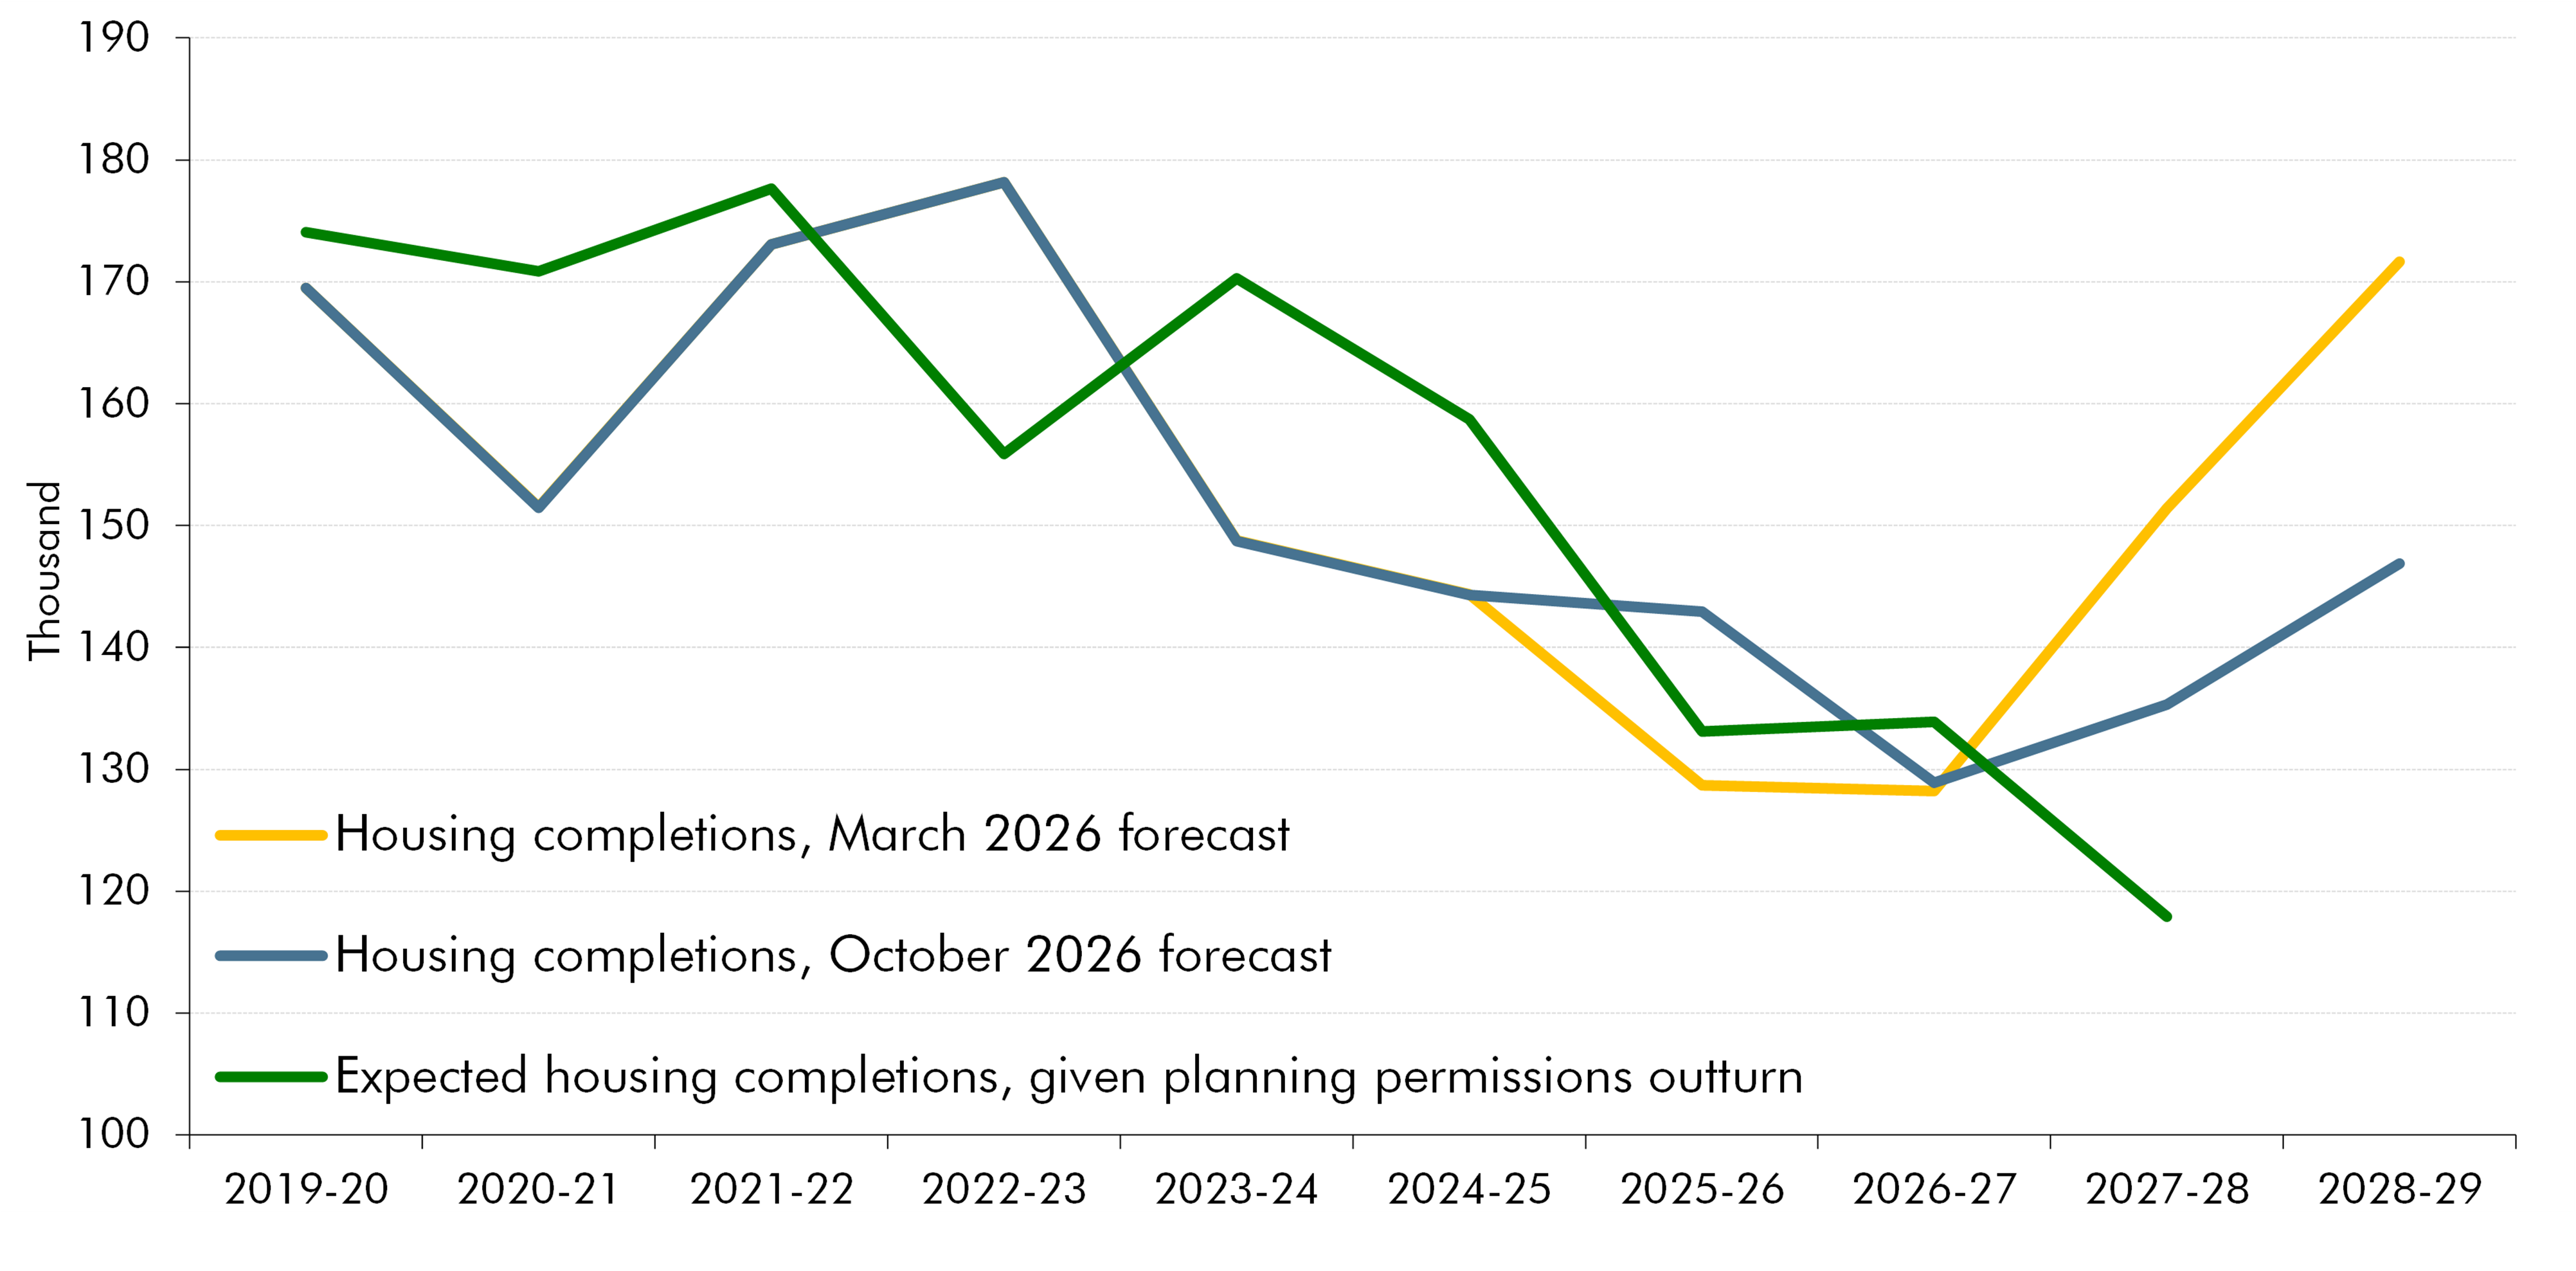
Note: The “Expected housing completions, given planning permissions outturn” line shows the path for housing completions implied by the latest outturn data for residential planning permissions. This is calculated by applying the historical average lag between permissions being granted and homes completed to the residential planning permissions outturn data. The latest residential planning permissions outturn data is from MHCLG analysis of Glenigan data and remains subject to revision.
Source: Glenigan data from 2016 to 2021 Q4, MHCLG analysis of Glenigan data from 2022 Q1 onwards, ONS, OBR
House prices and property transactions
2.62 We estimate that average house prices will grow by around 2 per cent in 2026 and by 2½ per cent in 2027. This would continue the recent trend of house price growth being below CPI inflation, largely driven by higher mortgage rates and stagnating real incomes. We then expect house price growth to average 2¾ per cent from 2028 onwards, as real income growth recovers. Compared to the March forecast, growth in house prices is therefore lower in the near term. The outlook for house prices remains highly sensitive to the path of mortgage rates, the evolution in real incomes, and the impact of planning and regulatory changes on housing supply. The ’Your First Home‘ scheme could marginally raise house prices by stimulating housing demand.
2.63 In our central forecast, property transactions grow from around 1.2 million in 2026 to around 1.3 million in 2031, as the housing market turnover rate returns to its assumed medium-term equilibrium that every house is transacted on average once every 24 years and as the housing stock continues to grow. The number of transactions across the forecast period is around 4 per cent lower than in the March forecast, as higher mortgage rates are expected to weigh on activity, and as we have revised down our forecast for growth in the housing stock.
Residential investment
2.64 Real residential investment (excluding transfer costs) is forecast to rise by 0.5 per cent in 2026, following weaker-than-expected outturns in the first half of the year, 0.2 percentage points lower than in our March forecast.[footnote 14] Growth then picks up to average around 3 per cent a year over the rest of the forecast, around 2 percentage points lower than in our March forecast. This leaves real residential investment 6¾ per cent lower in 2030 than in our March forecast. This weaker outlook is due to lower planned housing completions on new-build investment but is partially offset by diverted investment toward improving the existing stock.
Nominal GDP and its composition
2.65 We expect nominal GDP growth to slow from around 4 per cent in 2026-27 to 3¼ per cent in 2027-28, as growth in both real GDP and the GDP deflator slows. We then expect nominal GDP growth to average around 3¾ per cent a year over the rest of the forecast, as real GDP growth rises and inflation sits at around 2 per cent. Compared to the March forecast, cumulative growth in nominal GDP from 2025-26 to 2030-31 is 1¼ percentage points higher. This difference is driven almost entirely by higher growth in the GDP deflator. Whole-economy inflation is higher due to the second-round effects of the imported energy shock through wages and profits, and a rise in the price of energy produced in the UK.
2.66 This is reflected in stronger cumulative growth in all major components of nominal GDP, both in income and expenditure terms. On the income side, we expect strong growth in nominal corporate profits, a determinant of corporation tax receipts, averaging around 4½ per cent a year over the forecast period. Growth in nominal labour income, including wages and salaries and mixed incomes, averages just over 3 per cent a year over the forecast period. Labour income growth is a key judgement in the forecast given its comparatively high effective tax rate and that income tax thresholds are currently frozen. On the expenditure side, we expect nominal business investment growth to average around 2¼ per cent a year across the forecast, while nominal household consumption growth averages 3¾ per cent a year.
Comparison to external forecasters
2.67 Chart 2.20 compares our forecast for real GDP growth to a range of external forecasts. The interpretation of differences with external forecasters is more complex than usual. Ongoing volatility in financial and energy markets may obscure or exaggerate differences in underlying assumptions about the economic outlook, depending on when the forecast was constructed. Our real GDP forecast over the next two years is slightly lower than the latest short-term external forecasts (published in October), as it does not incorporate the stronger-than-expected GDP growth for July and August. From 2028, our forecast is at the higher end of the range of long-term external forecasts (published in August), with cumulative real GDP growth between 2025 and 2030 ¾ of a percentage point higher than the external average. Our forecast for real GDP growth, both cumulative and year-to-year, is similar to that of the Bank of England in its July Monetary Policy Report.
Chart 2.20: Real GDP: comparison of external forecasts
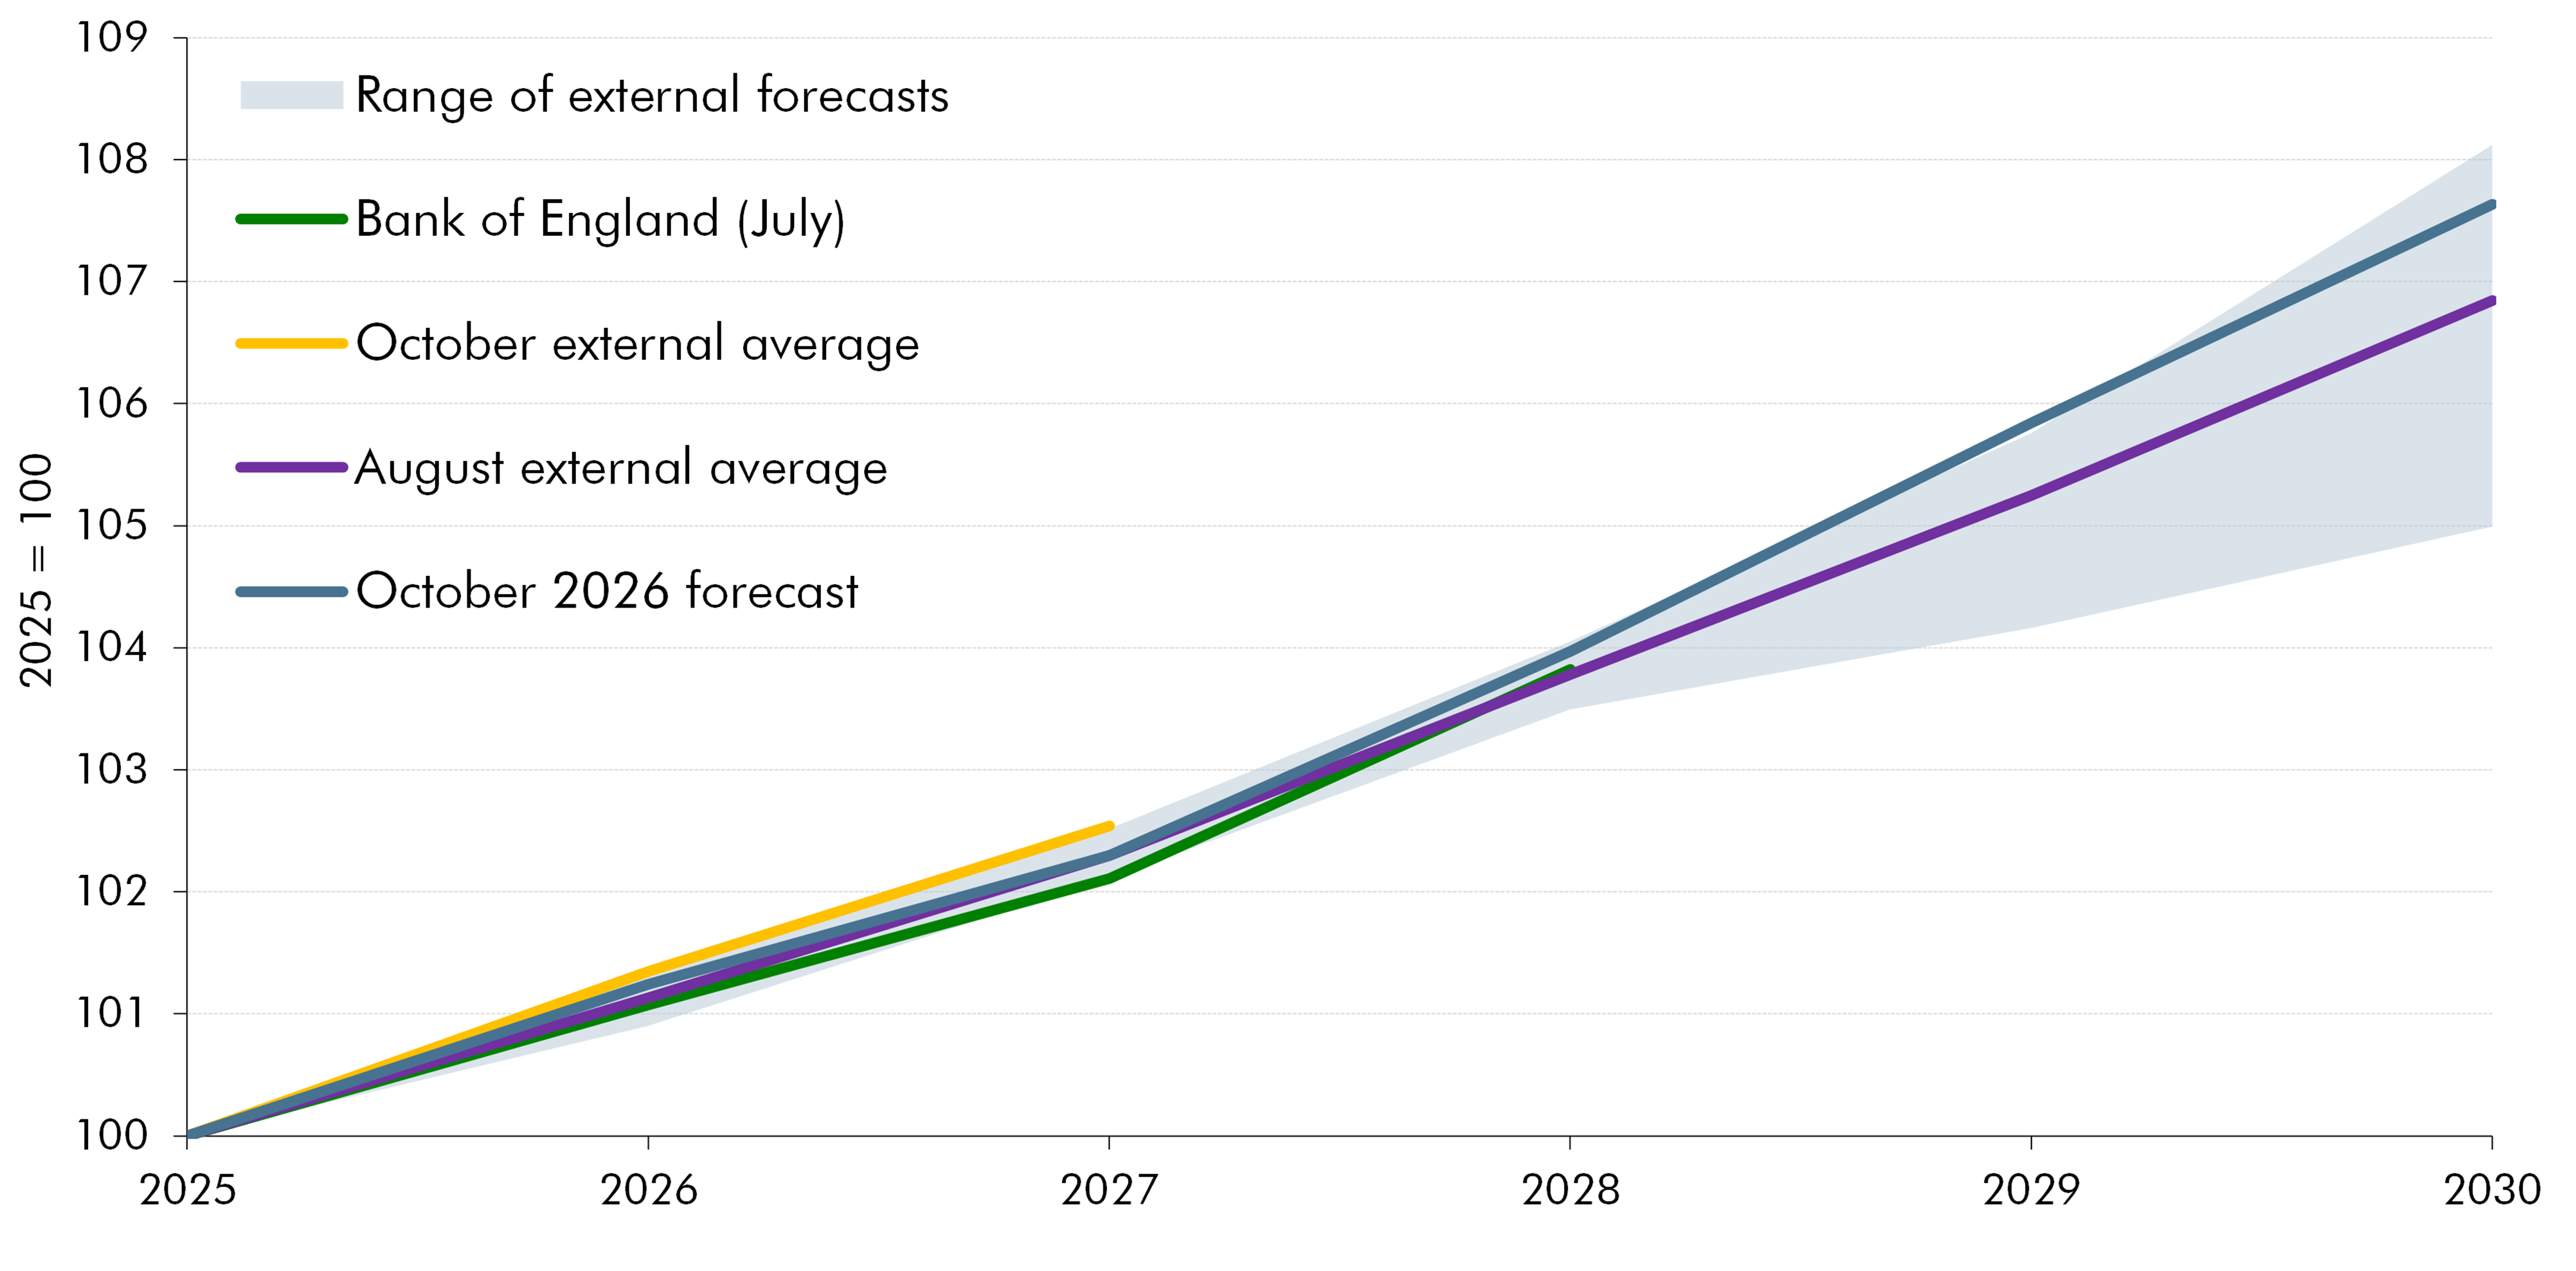
Note: Bank of England is from the July Monetary Policy Report. October external average uses the latest external forecasts for 2026 and 2027 published by HM Treasury in October 2026. The range and August external average are based on the latest five-year forecasts, published in August 2026.
Source: Bank of England, HM Treasury, OBR
2.68 As shown in Table 2.3, our forecast for CPI inflation next year is higher than both the Bank of England and the average of external forecasters. This difference is likely primarily driven by the timing of market determinants used in different forecasts,[footnote 15] the relative importance of import cost pressures for food and other tradable goods, and judgements about the degree of indirect and second-round effects. Our forecast for the unemployment rate is in line with the Bank of England and external forecasters over the next two years, but lower afterward. This is likely driven by different assumptions about the equilibrium rate of unemployment.[footnote 16]
Table 2.3: Real GDP, CPI inflation, and the unemployment rate
| Per cent | |||||
| 2026 | 2027 | 2028 | 2029 | 2030 | |
| GDP growth | |||||
| OBR | 1.2 | 1.0 | 1.6 | 1.8 | 1.7 |
| Bank of England | 1.1 | 1.0 | 1.7 | ||
| External average (August) | 1.1 | 1.2 | 1.4 | 1.4 | 1.5 |
| CPI inflation | |||||
| OBR | 3.1 | 3.4 | 2.1 | 2.1 | 2.0 |
| Bank of England | 3.0 | 2.8 | 1.8 | ||
| External average (August) | 3.1 | 2.7 | 2.2 | 2.1 | 2.0 |
| Unemployment rate | |||||
| OBR | 5.0 | 5.1 | 4.9 | 4.5 | 4.3 |
| Bank of England | 5.0 | 5.3 | 5.2 | ||
| External average (August) | 5.1 | 5.2 | 5.1 | 5.0 | 4.9 |
| Source: Bank of England, HM Treasury, ONS, OBR |
Chapter 3: Policy measures
Introduction
3.1 The Charter for Budget Responsibility states that the responsibility for producing the costings of policy measures lies with the responsible policy department, which is typically HM Revenue and Customs for tax policies and the Department for Work and Pensions for welfare policies. These departments therefore hold the models and datasets that are used to produce these costings. The OBR’s role, as set out in the Charter, is to provide independent scrutiny and certification of these costings.[footnote 17] Requests for further information relating to the methodology and datasets used for costings should therefore initially be directed to the relevant department.
Total effect of Government decisions
The impact of fiscal policy decisions on borrowing
3.2 This forecast incorporates the fiscal implications of policy measures announced in this Budget and since the March forecast, which are summarised in Table 3.1 and Chart 3.1. The direct effect of these measures is to increase borrowing by £7.6 billion in 2026-27, £3.5 billion in 2027-28, and £0.4 billion in 2028-29. The direct effect of policy measures reduces borrowing thereafter by £4.1 billion in 2029-30, £5 billion in 2030-31 and £12 billion in 2031-32.
3.3 Policies that affect public spending are estimated to increase borrowing between 2026-27 and 2030-31 by an average of £3.3 billion, before planned spending reductions are estimated to reduce borrowing by £4.2 billion in 2031-32. This reflects:
-
Funding to support a £100 council tax rebate increases spending this year (2026-27) by £2.6 billion.
-
Funding for the defence investment plan is estimated to increase spending by an average of £1.8 billion a year. The valuation of unfunded public sector pensions increases spending by an average of £1.1 billion a year across the forecast.
-
Reductions in planned capital spending of £0.9 billion a year from 2027-28. The civil service transformation programme is estimated to reduce resource spending by £0.5 billion a year from 2028-29. In 2031-32, a reduction in the pre-measures spending assumption further reduces resource spending by £5.5 billion.
3.4 Changes to tax policy increase borrowing by £1.7 billion in 2026-27, before reducing borrowing by an average of £6 billion over the final four years of the forecast. This reflects:
-
The further freeze to fuel duty and the temporary zero-rating of VAT on domestic electricity reduce receipts in 2026-27 by £1.3 billion.
-
HMRC tax administration, compliance and debt collection measures raise an additional £3.6 billion by 2031-32. The largest of these measures is the introduction of timely payment for self assessment which is estimated to yield an average of £1.6 billion a year from 2029-30.
-
Changes to corporation and bank taxes are estimated to raise an average of £2.2 billion a year across the forecast. The reduction in writing down allowances is estimated to raise approximately £1 billion a year on average from 2027-28, while the temporary increase in the bank surcharge increases receipts by £1 billion in 2027-28.
-
Further increases to tax rates on savings and property income increase receipts by an average of £1 billion a year from 2028-29.
Chart 3.1: Direct borrowing impact of policy decisions included in this forecast
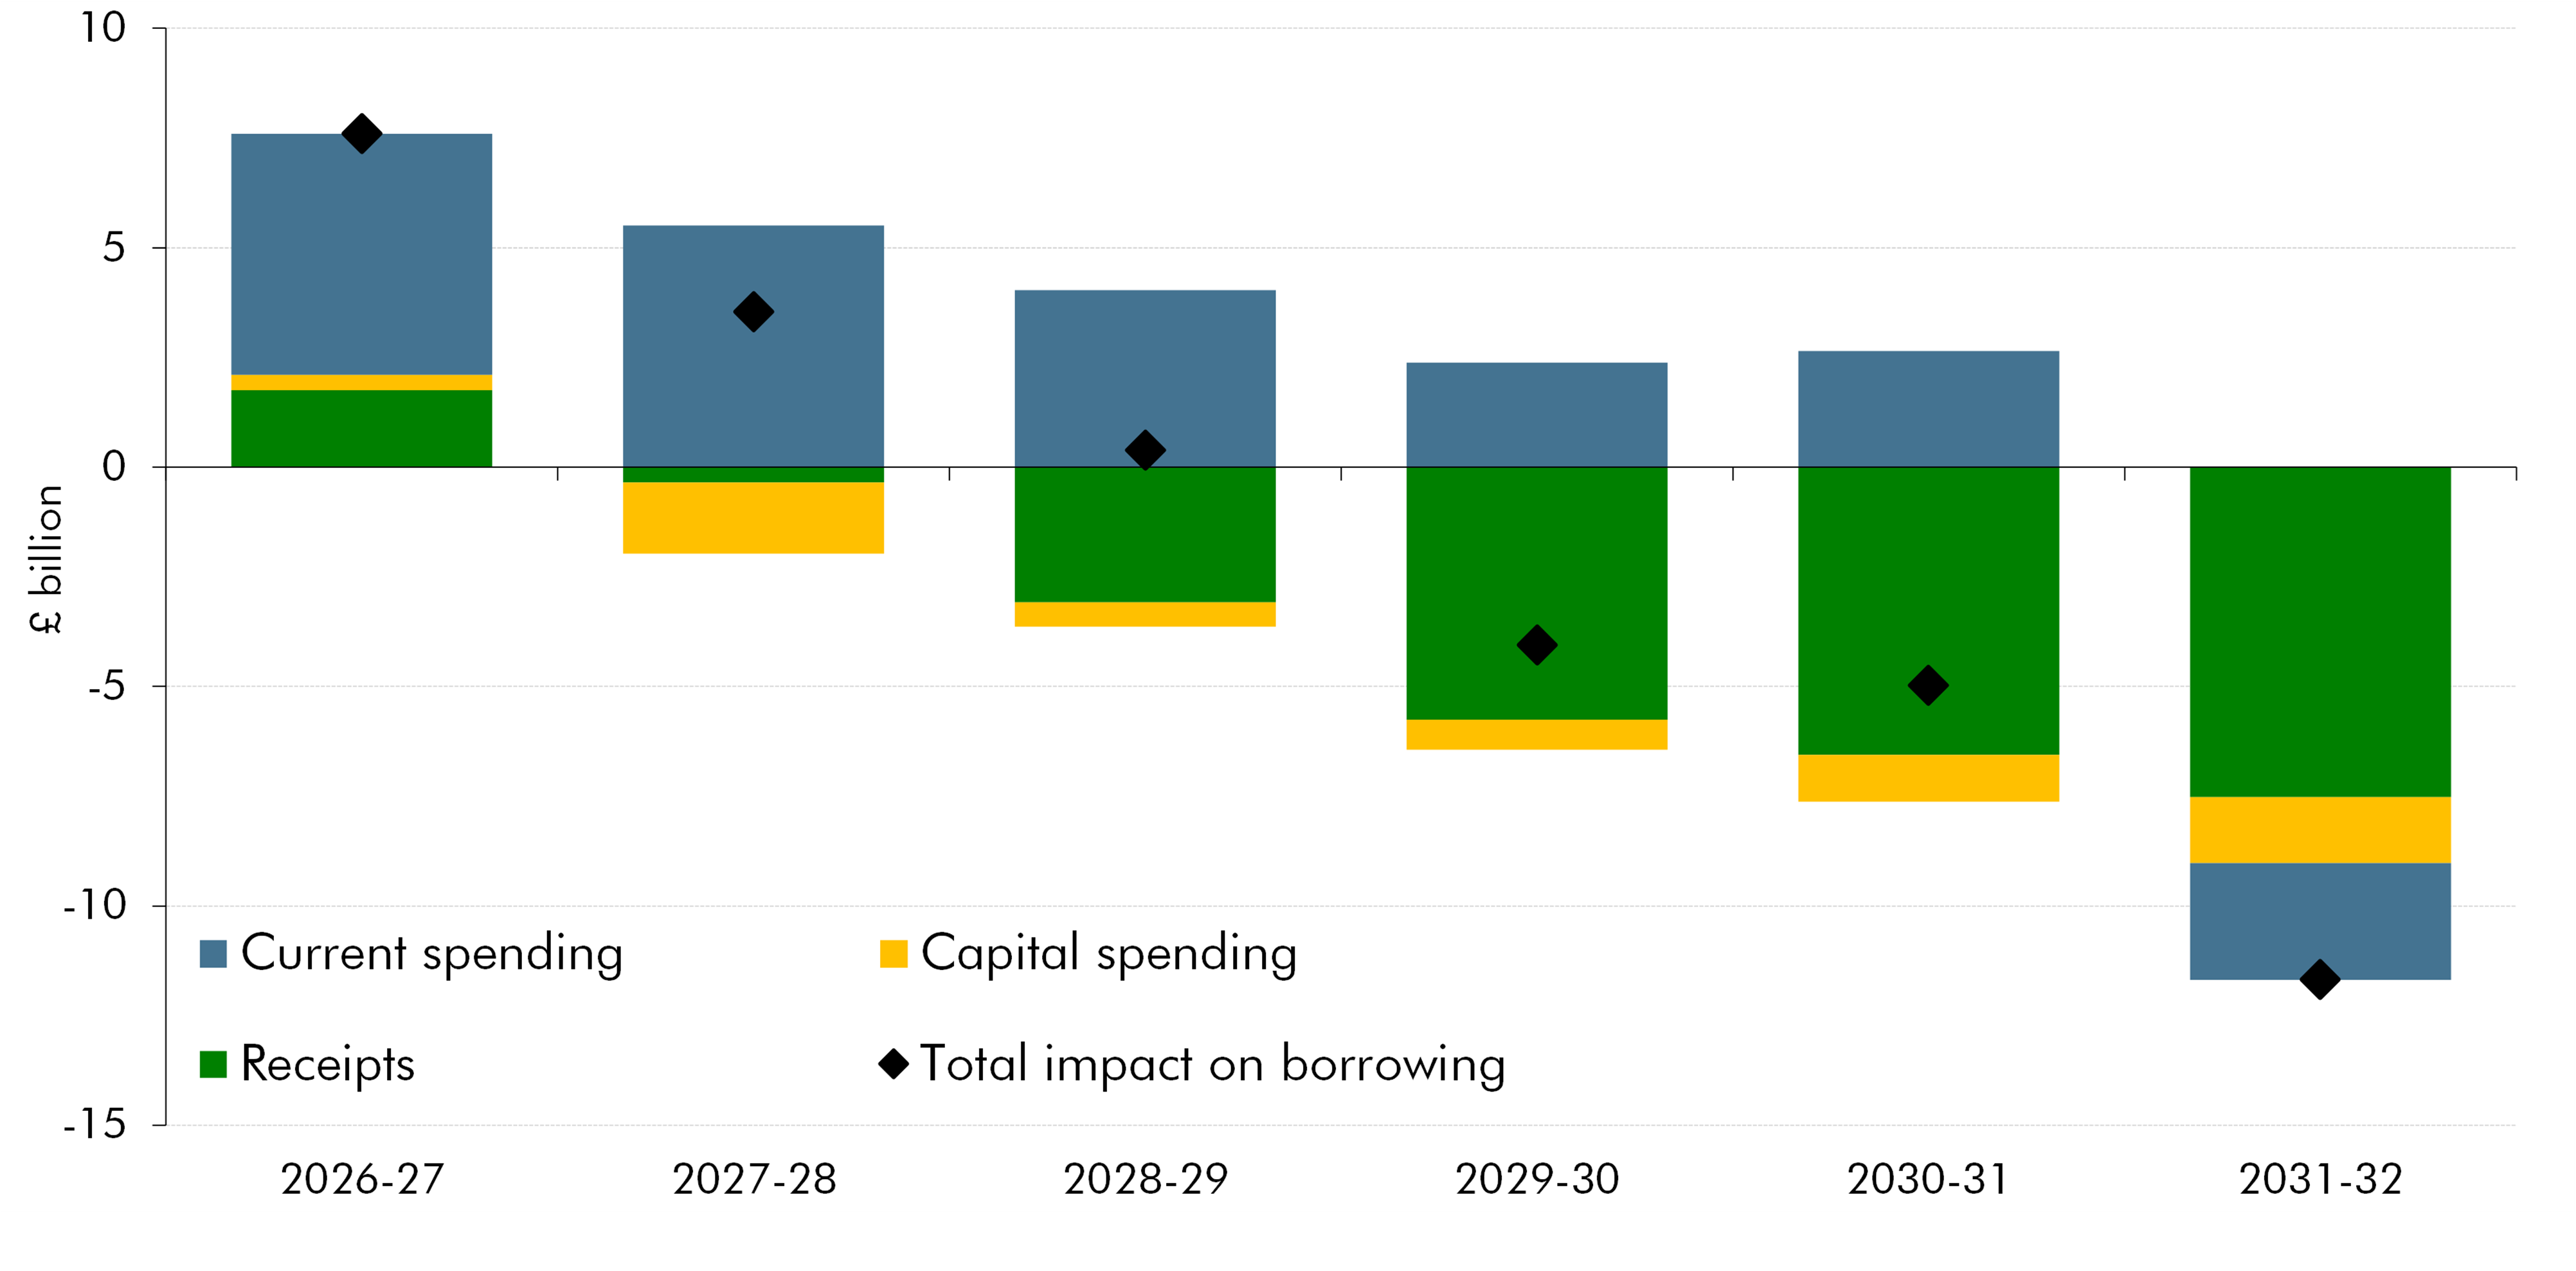
Note: A positive sign implies an increase in borrowing.
Source: HM Treasury, OBR
3.5 Table 3.1 also includes the indirect effects of policies on the public finances via any wider impacts they have on the economy. At this Budget, these indirect effects are relatively small and primarily driven by the impact that policy measures have on inflation (see paragraph 3.10) and by higher near-term borrowing increasing debt interest spending. These also include a £1 billion reduction in estimated departmental underspends against their day-to-day spending plans in 2027-28 due to the impact of spending policy in that year, discussed further in Chapter 5.
Table 3.1: Total effect of Government decisions since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Forecast | ||||||
| 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Total effect of Government decisions | 6.3 | 7.0 | 2.1 | -2.6 | -3.5 | -9.3 |
| of which: | ||||||
| Direct effect of spending measures | 5.8 | 3.9 | 3.5 | 1.7 | 1.6 | -4.2 |
| Direct effect of tax measures | 1.7 | -0.3 | -3.1 | -5.8 | -6.6 | -7.5 |
| Indirect effects of Government decisions | -1.3 | 3.5 | 1.7 | 1.4 | 1.4 | 2.4 |
| Direct effects of Government decisions | 7.6 | 3.5 | 0.4 | -4.1 | -5.0 | -11.7 |
| of which: | ||||||
| Spending measures | 5.8 | 3.9 | 3.5 | 1.7 | 1.6 | -4.2 |
| of which: | ||||||
| Council tax rebate | 2.6 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Other departmental spending changes(1) | 5.4 | 1.2 | 1.5 | -0.1 | -0.2 | -6.0 |
| Net impact of unfunded pensions valuation1,2 | 0.0 | 1.1 | 1.1 | 1.1 | 1.2 | 1.2 |
| Other AME spending decisions | -2.2 | 1.7 | 0.9 | 0.6 | 0.6 | 0.6 |
| Tax measures | 1.7 | -0.3 | -3.1 | -5.8 | -6.6 | -7.5 |
| of which: | ||||||
| Tax administration, compliance and debt collection measures | -0.1 | -0.5 | -0.6 | -2.4 | -2.9 | -3.6 |
| of which: | ||||||
| Timely payment for self-assessment | 0.0 | 0.0 | 0.0 | -1.4 | -1.6 | -1.8 |
| Changes to corporation and bank taxation | -0.5 | -2.3 | -2.2 | -2.2 | -2.2 | -2.3 |
| Changes to savings and property income tax rates | 0.0 | -0.1 | -1.1 | -0.9 | -1.0 | -1.0 |
| Changes to dividend and capital gains taxation | 0.0 | 0.2 | -0.1 | -0.8 | -0.8 | -0.8 |
| Fuel duty freeze and VAT off domestic energy bills | 1.3 | 1.1 | 0.0 | 0.0 | 0.0 | 0.0 |
| Other tax measures | 1.1 | 1.3 | 0.9 | 0.6 | 0.3 | 0.2 |
| Memo: direct effect of decisions on HM Treasury’s October 2026 Budget policy decisions table | 7.6 | 2.5 | -0.7 | -5.2 | -6.1 | -7.3 |
| Memo: direct effect of decisions not on HM Treasury’s October 2026 Budget policy decisions table | 0.0 | 1.1 | 1.1 | 1.1 | 1.2 | -4.3 |
| Memo: total effect of Government decisions on current budget deficit | 6.1 | 8.4 | 2.5 | -2.0 | -2.4 | -7.7 |
| Note: A positive sign implies an increase in borrowing. Our online detailed scorecard contains a measure-by-measure breakdown of every line, alongside our subjective assessment of each costing’s uncertainty. |
| 1) The two decisions not included on HM Treasury’s October 2026 Budget policy decisions table are the £5.5 billion reduction to the 2031-32 pre-measures RDEL spending assumption, and the impacts of the unfunded pensions valuation. |
| 2) The valuation of unfunded pensions has larger, partially offsetting impacts on departmental and annually managed expenditure, which we incorporate in our aggregate spending forecast. |
| Source: HM Treasury, OBR |
3.6 Across the forecast period, this policy package has a broadly neutral absolute average net impact (just 0.02 per cent of GDP, £1.3 billion). As shown in Chart 3.2, between 2010 and 2014 there were a series of events where policy was tightened overall in net terms. After this period, fiscal policy was loosened in net terms at most fiscal events, including at each event from March 2023 to October 2024. Since then, this Budget represents the fourth consecutive event where the absolute average net impact of planned policy measures on borrowing over the forecast has been less than or equal to 0.1 per cent of GDP.
Chart 3.2: Size of fiscal policy packages, 2010 to 2026
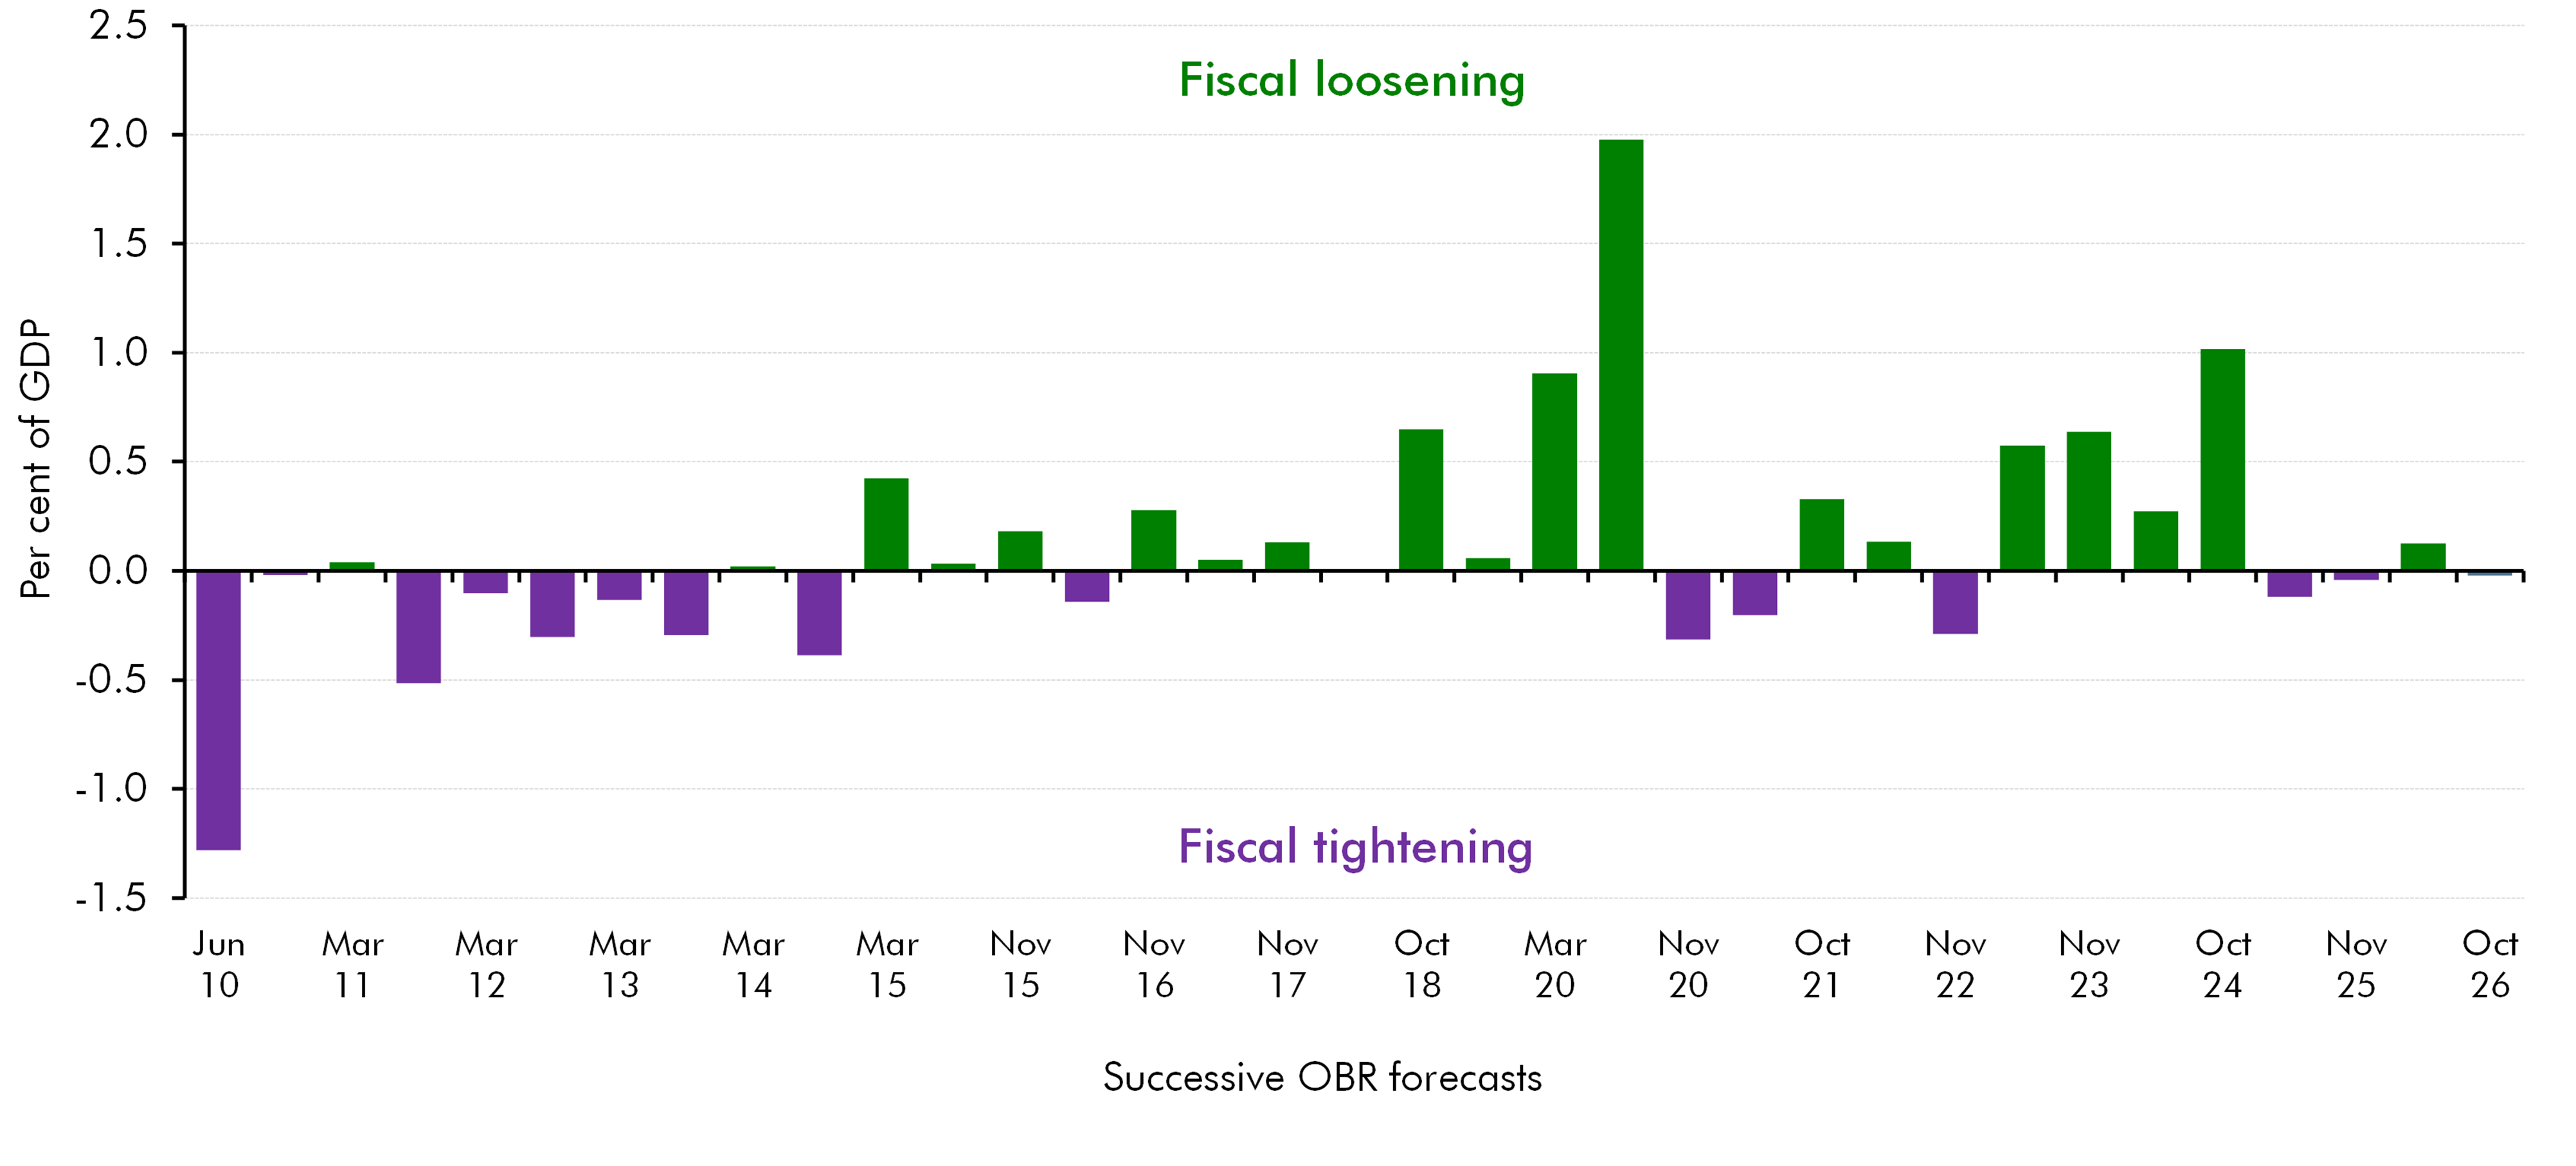
Note: This shows the average annual impact over the five-year forecast period of the direct and indirect effects of policy decisions on borrowing as a share of GDP for each fiscal event, based on our forecast revisions database. June 2010 does not include the fiscal impact of indirect effects. For July 2020, the in-year forecast revision is included in the five-year average.
Source: OBR
3.7 However, this period includes events, such as Budget 2025, which saw significant near-term loosening followed by medium-term tightening. Chart 3.3 compares the profile of the overall fiscal impact of policy at this event, including indirect effects, against other policy events since June 2010. This shows that it follows a typical pattern of short-term policy loosening followed by medium-term planned policy tightening. The in-year policy loosening at this event is above the interquartile range of all other policy events for that year, while the planned tightening in the final two years is broadly in the middle of the range.
Chart 3.3: Impact of planned policy measures on borrowing over the five-year forecast
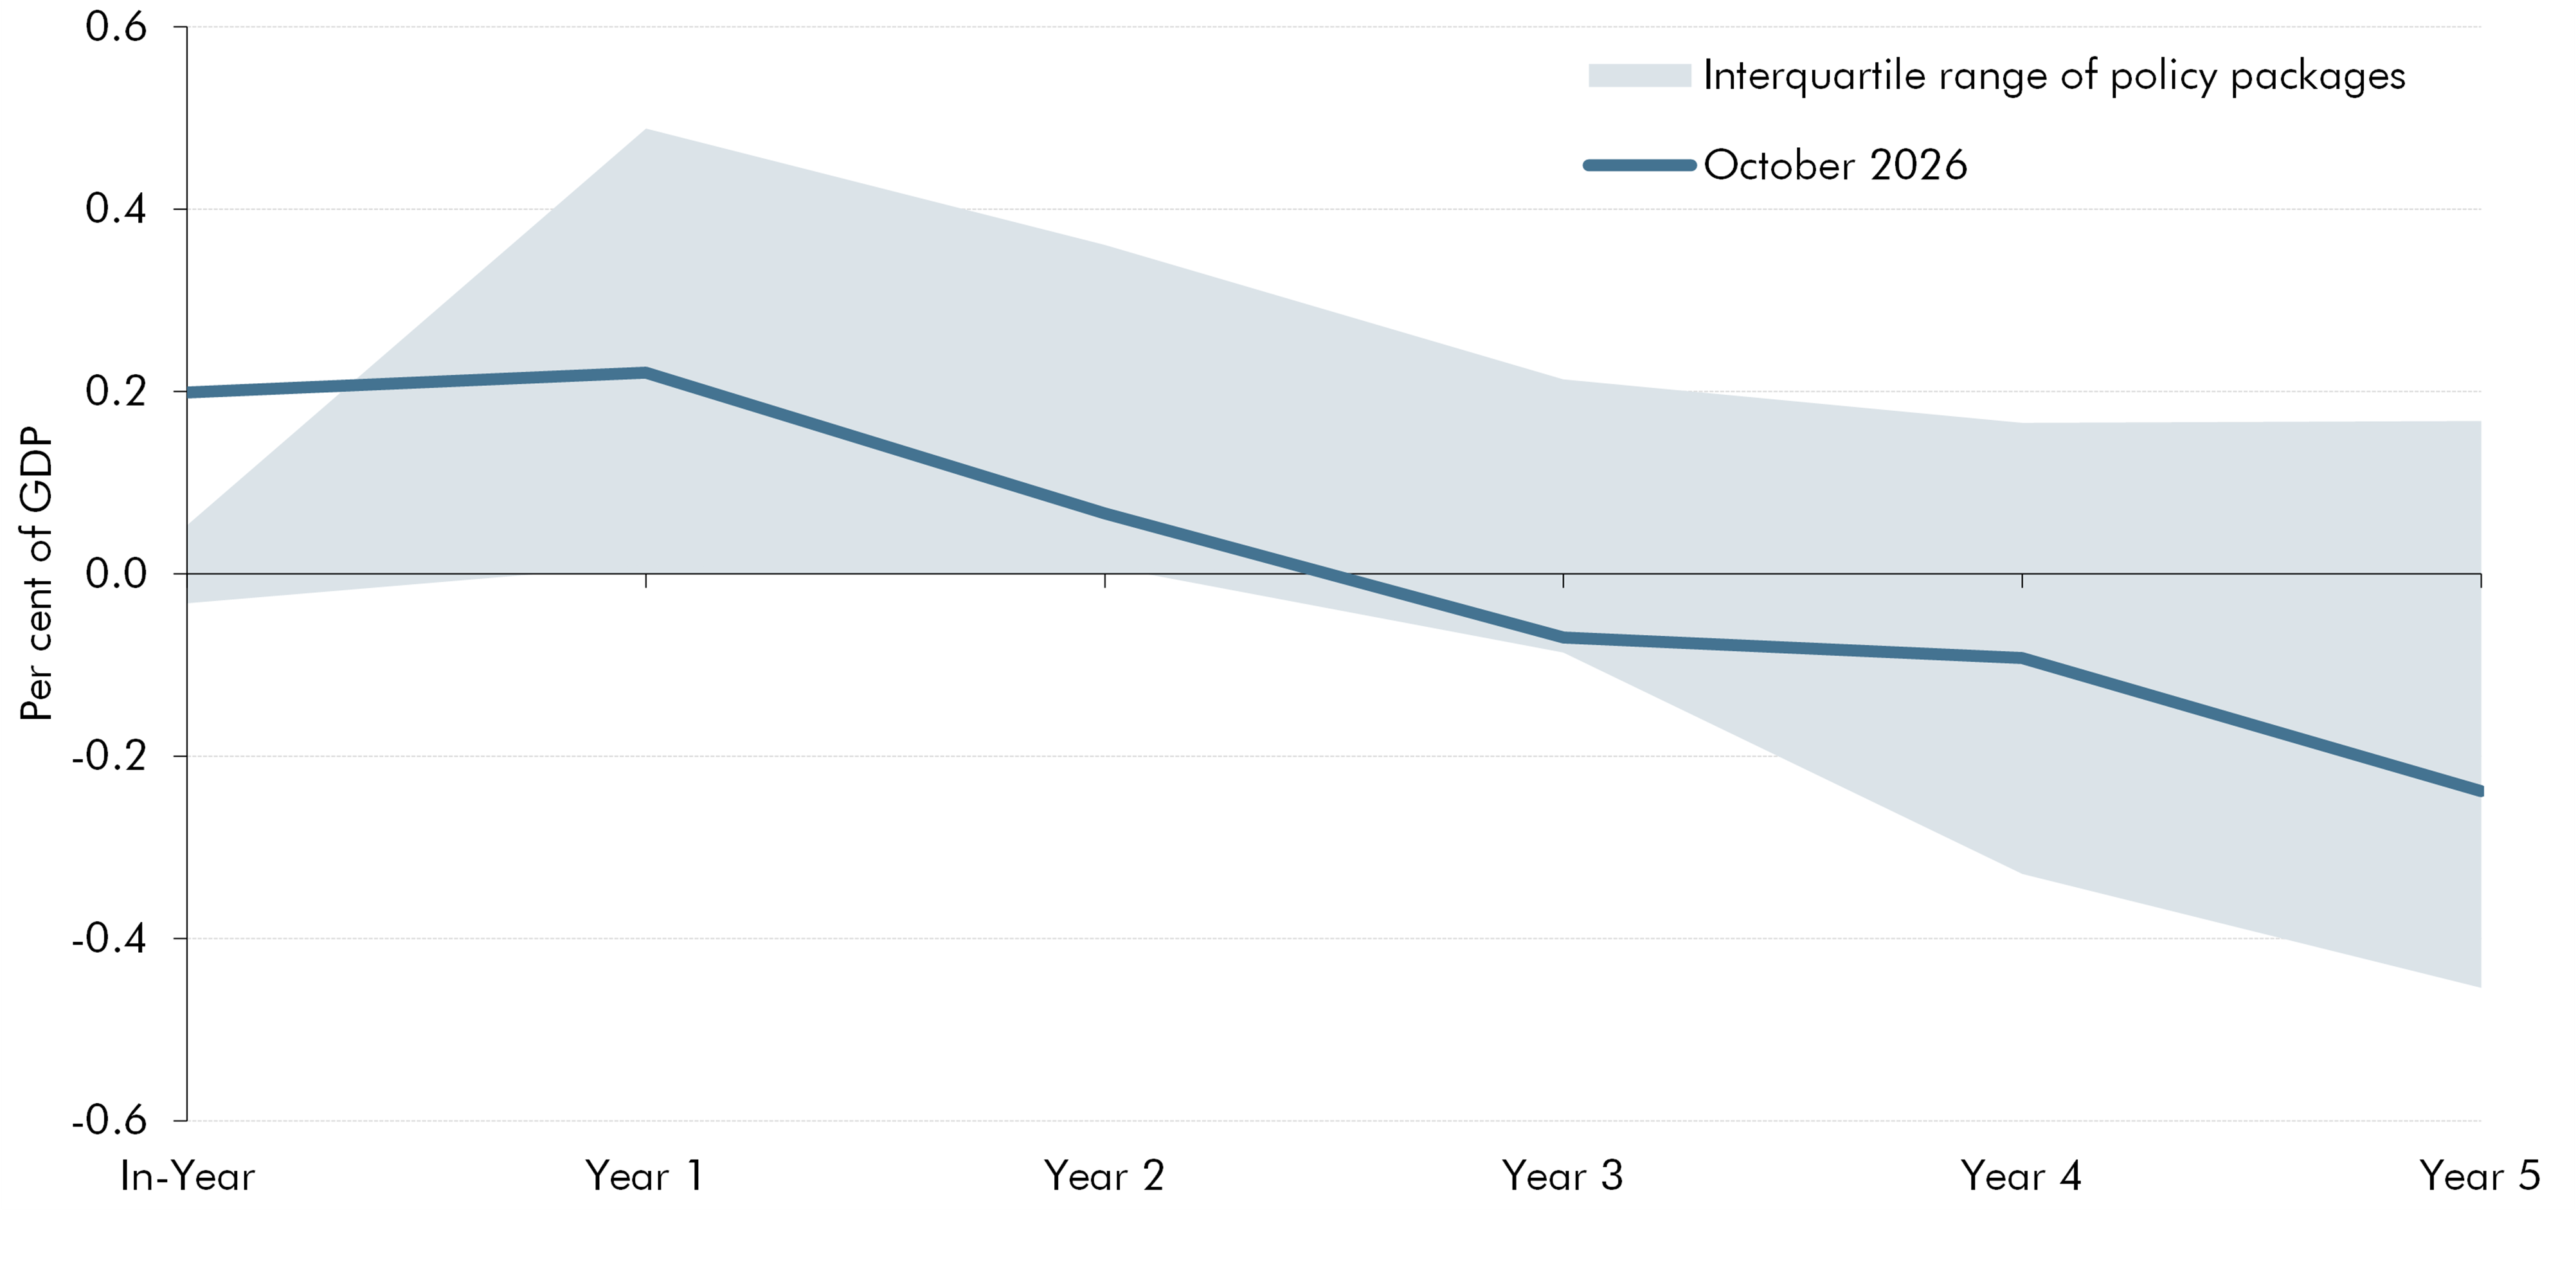
Note: The interquartile range is estimated using our Fiscal forecast revisions database, which goes back to November 2010, and the June 2010 post-Budget forecast.
Source: OBR
Economic effects of policy measures
3.8 Our forecast explicitly accounts for the economic impacts of newly announced government policy where these are material. The impacts of policy on the supply side of the economy are explicitly accounted for in our forecast if credible evidence suggests the measures will have an additional, durable, and significant impact on potential output.[footnote 18] The Government has announced initial details of a range of policies since the March forecast – including at this Budget – which aim to raise GDP over the longer term. We will review the potential impact of such policies, over the medium- and long-term, when final details are confirmed and where sufficient evidence is available – including as part of our annual summer assessments of supply potential. Therefore, in this forecast, we have not made any explicit adjustments to potential output due to policy changes.[footnote 19]
3.9 Our assessment of the demand-side effects of fiscal policy is informed by ‘fiscal multipliers’. We define fiscal multipliers as the impact of a policy package on demand which, at least in the short run, can affect the output gap by changing the level of economic activity relative to potential output. Our standard multipliers are drawn from the empirical literature. However, there is no single multiplier that applies to all policies and at all points in the economic cycle. The multiplier may vary due to macroeconomic conditions and policy instruments. We therefore assess at each forecast what multipliers are appropriate.[footnote 20] We judge that the demand-side impact of this policy package is not sufficiently material to explicitly adjust our real GDP forecast. The overall package is relatively small in fiscal terms and much of the initial fiscal loosening has been pre-announced. Additionally, forward-looking agents may smooth economic activity through the initial fiscal loosening and subsequent fiscal tightening arising from policy.
3.10 The changes to fuel duty and the temporary cut to VAT on domestic electricity bills have small effects on our inflation forecast. They reduce CPI inflation by 0.08 percentage points in 2026-27 and 0.02 percentage points in 2027-28, before raising CPI inflation by 0.04 percentage points in 2028-29. On a quarterly basis, at its peak, these policies reduce CPI inflation by 0.22 percentage points in the second quarter of 2027 and increase CPI inflation by 0.16 percentage points in the second quarter of 2028.[footnote 21],[footnote 22]
Spending measures included in this forecast
Changes to departmental expenditure
3.11 Changes to departmental spending increase borrowing by £5 billion in 2026-27 and £1.2 billion in 2027-28, before reducing borrowing by £6 billion in 2031-32. We discuss changes to departmental spending in greater detail in Chapter 5. The largest changes are:
-
a £100 council tax rebate for properties in bands A to D in England which increases borrowing by £2.6 billion in 2026-27;
-
the defence investment plan, which increases departmental resource spending (RDEL) by £1.8 billion a year on average;
-
a £5.5 billion reduction to the RDEL pre-measures spending assumption in 2031-32; and
-
changes to departmental capital spending, which reduce borrowing by an average of £0.9 billion a year from 2027-28.
Other spending policies
3.12 Other policies contributing to the changes in spending in this forecast include:
-
The valuation of public service pension schemes and consequent reduction in employer contributions, which increases net spending on unfunded pension schemes by an average of £17 billion per year in the medium-term. The Government has decided to reduce departmental resource spending in line with the lower cost of employer contributions, by an average £16 billion from 2027-28 onwards. The overall net effect of these changes is therefore to increase overall spending by an average of £1.1 billion from 2027-28. This net cost arises from the participation of employers in public service pension schemes whose staff costs are not funded through departmental spending, so the lower employer contributions are not offset. This policy is discussed in greater detail in Chapter 5.
-
A package of further measures to address fraud and error in the welfare system is expected to reduce welfare spending by £0.5 billion in 2031-32. This includes the hiring of 2,000 verification assurance officers, 200 additional staff to prevent fraud and error from those living abroad, and 150 additional staff to reduce capital-related fraud and error in pension credit. We discuss the staffing and departmental spending implications of these measures in more detail in paragraphs 3.14 and 3.15.
Receipts measures included in this forecast
Tax administration, compliance, and debt collection measures
3.13 The Government has announced further HMRC tax administration, compliance, and debt collection measures in this Budget which are estimated to raise an additional £3.6 billion by 2031-32. These measures are targeted at the current high levels of tax debt and reducing the overall tax gap through increased HMRC compliance activity, and include:
-
The introduction of timely payment for self assessment, and part reversal of the Budget 2025 measure that mandated coding out via the PAYE system, which brings more payments of self-assessment liabilities forward into the tax year in which income is earned. This measure is estimated to yield an average of £1.6 billion a year from 2029-30 which reflects the timely payment system preventing some debt losses and changing the timing of recovery of debt. The yield is adjusted to account for self-assessment customers reducing their forecast liabilities and additional delayed debt created due to payment pressures in the transition year. Further information on the non-debt cash timing impacts of the measure is detailed in paragraph 3.25.
-
Changes to HMRC’s compliance workforce which are estimated to yield an additional £0.4 billion in 2031-32. This accelerates the recruitment of the previously announced 5,500 additional HMRC compliance officers and funds an additional 670 staff by the end of 2029-30. The recruitment of these compliance officers will be equivalent to a 23 per cent increase to HMRC’s compliance workforce compared to March 2024. The expected yield has been adjusted to account for diminishing returns of additional compliance officers, where marginal yield from additional activity is likely to be below the average yield from business-as-usual compliance activity, disruption impacts, and optimism bias to reflect uncertainty around recruitment, performance of staff, and nature of future non-compliance activity.
-
Other measures which yield £1.4 billion in 2031-32, and include extending HMRC’s powers to directly recover outstanding tax debts; mandating the use of e-invoicing to reduce opportunities for error and other forms of non-compliance; investing to place part of the established stock and future flows of outstanding tax debt with debt collection agencies; and extending the VAT online marketplace liability rules to UK businesses, with a minimum platform threshold at £90,000. The interactions between measures targeted at debt collection have been captured by adjusting the tax bases to capture the reduced revenue available to collect as a result of measures targeting the same customer group or types of debt.
Box 3.1: Compliance policy and the tax gap
In our scrutiny of tax compliance policies, in addition to considering the impact of each measure individually, we also consider the overall impact of the full package of measures on the projected ‘tax gap’. This is the difference between the amount of tax that should, in theory, be paid and the amount received, and so is a measure of overall non-compliance. While most tax liabilities are paid voluntarily through the normal operation of the tax system, other liabilities are only identified or recovered through HMRC compliance activity. HMRC records the additional revenue generated, and losses prevented through this activity as ‘compliance yield’. Other things equal, higher yield from compliance and debt collection activities should reduce the amount of tax that ultimately remains unpaid and, in turn, the tax gap.
HMRC’s latest estimate of the tax gap was £59 billion or 6.4 per cent of total theoretical liabilities in 2024-25 (left-hand side, Chart A).a These estimates suggest the tax gap has risen since the mid-2010s, following a period of decline, although the increase appears to have flattened in recent years.b As shown on the right-hand side of Chart A, small businesses have accounted for a growing share of the tax gap in recent years, rising from around 40 per cent of the total in 2017-18 to more than 60 per cent since 2021-22. Of the compliance measures announced in this Budget, a third of the yield is expected to reduce the tax gap, with the residual reflecting either debt acceleration or payments. Of the 15 measures expected to reduce the tax gap announced this Budget, four target the small business tax gap.
Chart A: Tax gap: recent trends and forecast
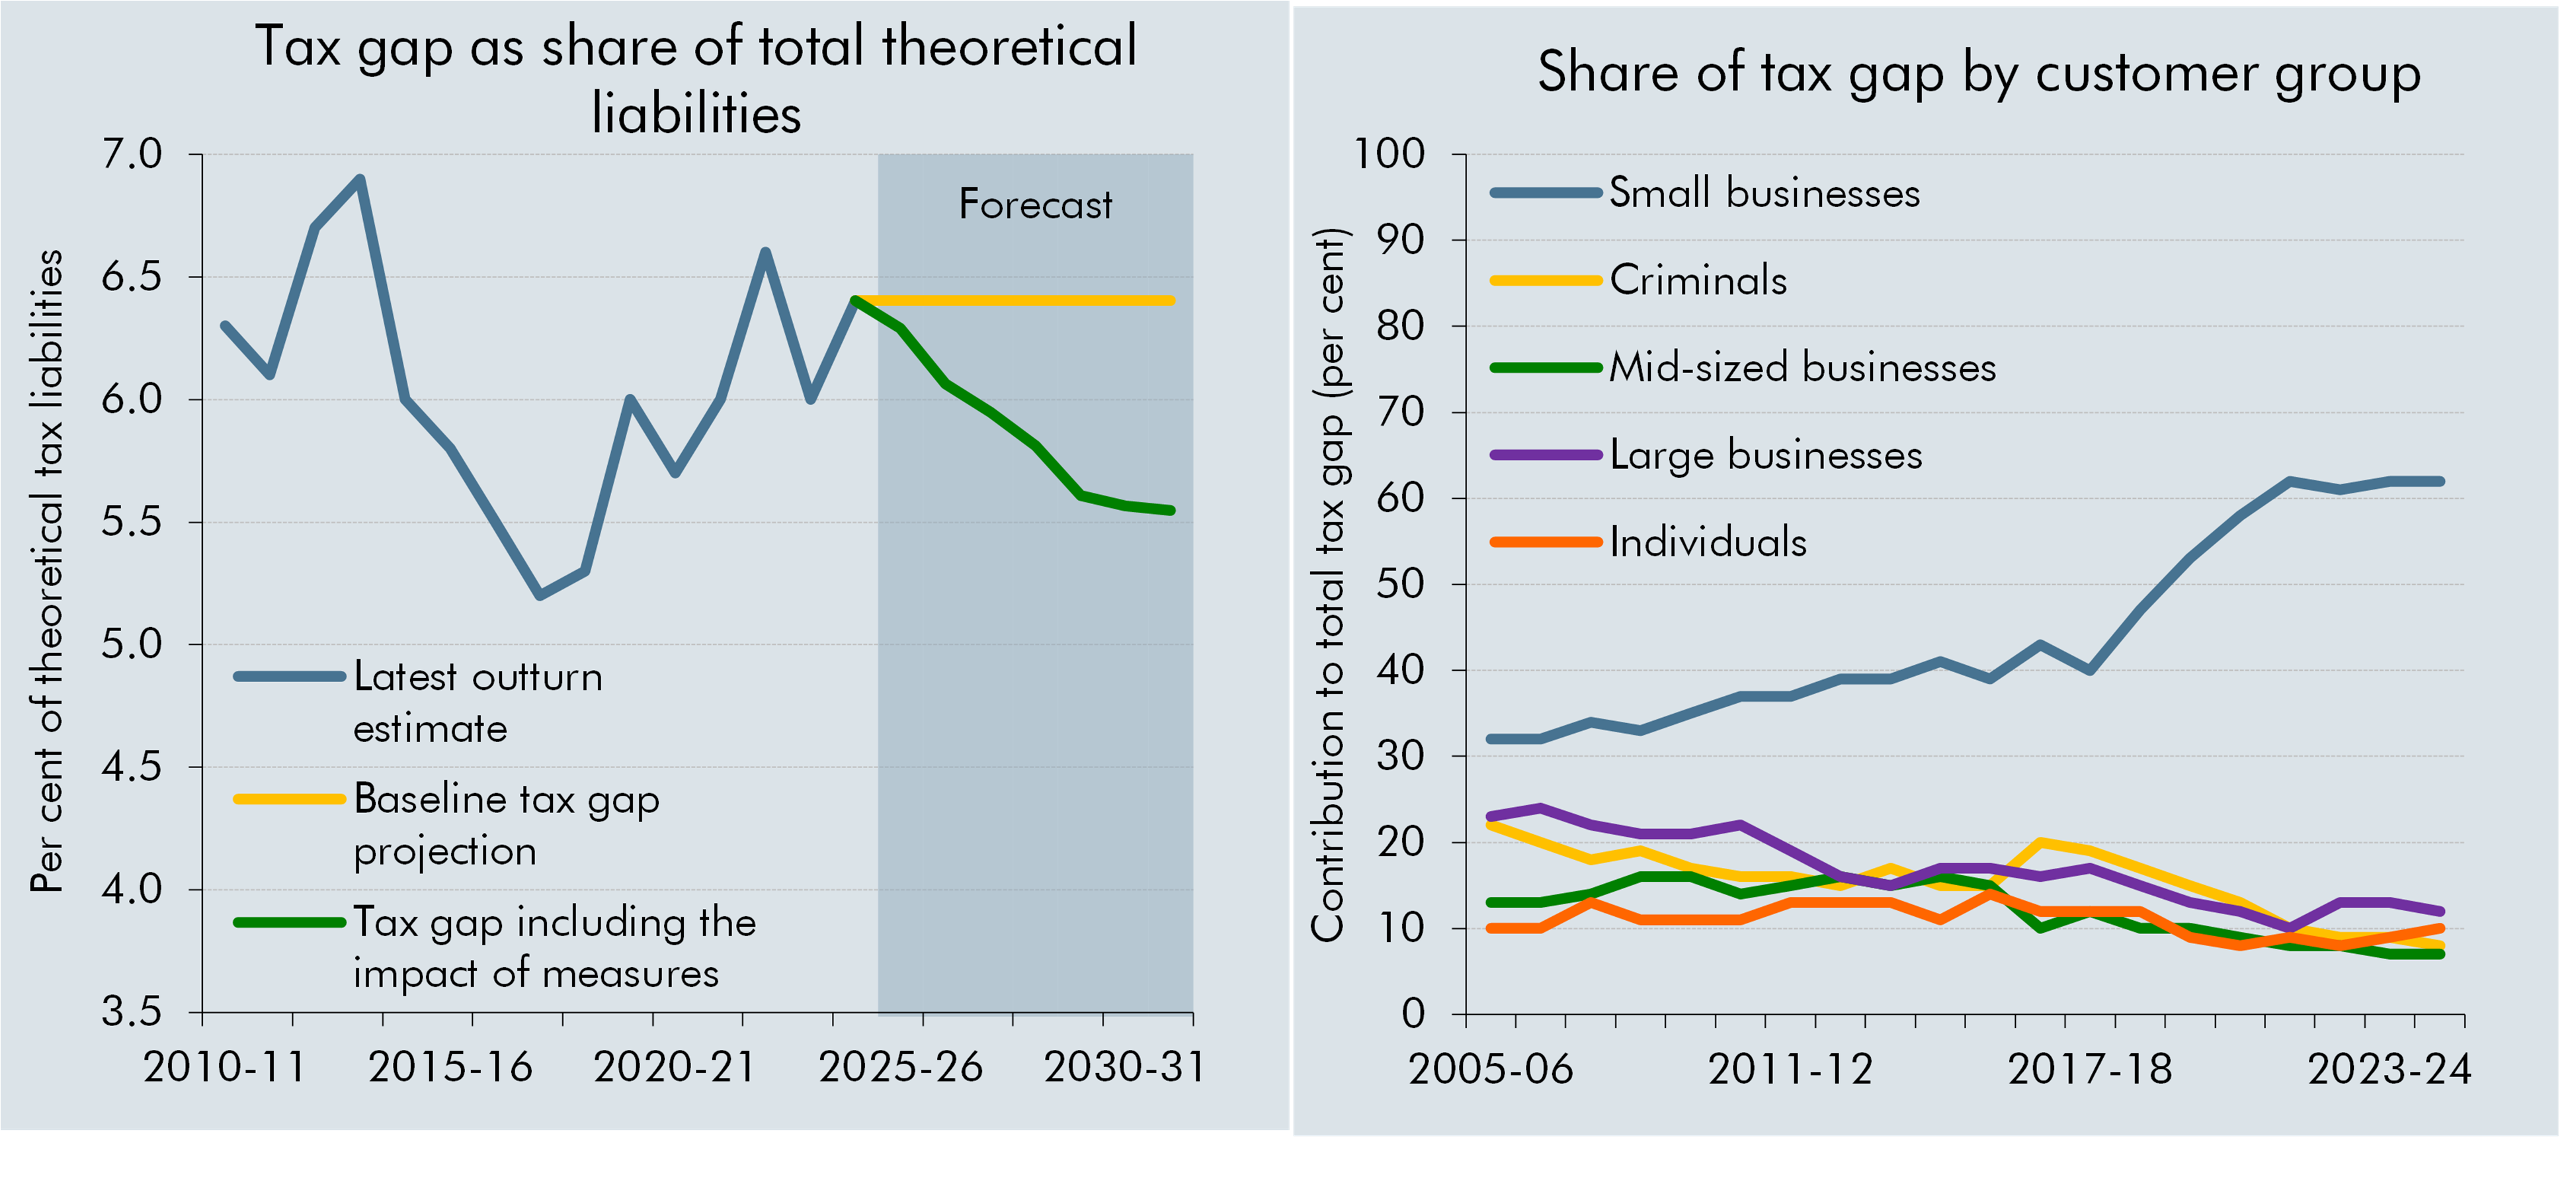
Note: Customer group splits are produced by HMRC, we have simplified these by combining the series for ‘individuals’ and ‘wealthy’.
Source: HMRC, OBR
Recent fiscal events have included large numbers of compliance and debt measures aimed at closing the tax gap. Chart B shows the expected yield from all compliance and debt measures announced at fiscal events since 2014.c Since the start of 2024, around 65 new measures have been announced, which together are estimated to reduce the tax gap by around £8 billion in 2029-30, with just over half of this driven by measures announced at Autumn Budget 2024. This increase in estimated yield from compliance and debt measures in the forecast period partially drives the forecasted decline in the tax gap shown on the left-hand side of Chart A.
Chart B: Estimated yield from compliance and debt measures announced since Spring 2014 impacting the tax gap
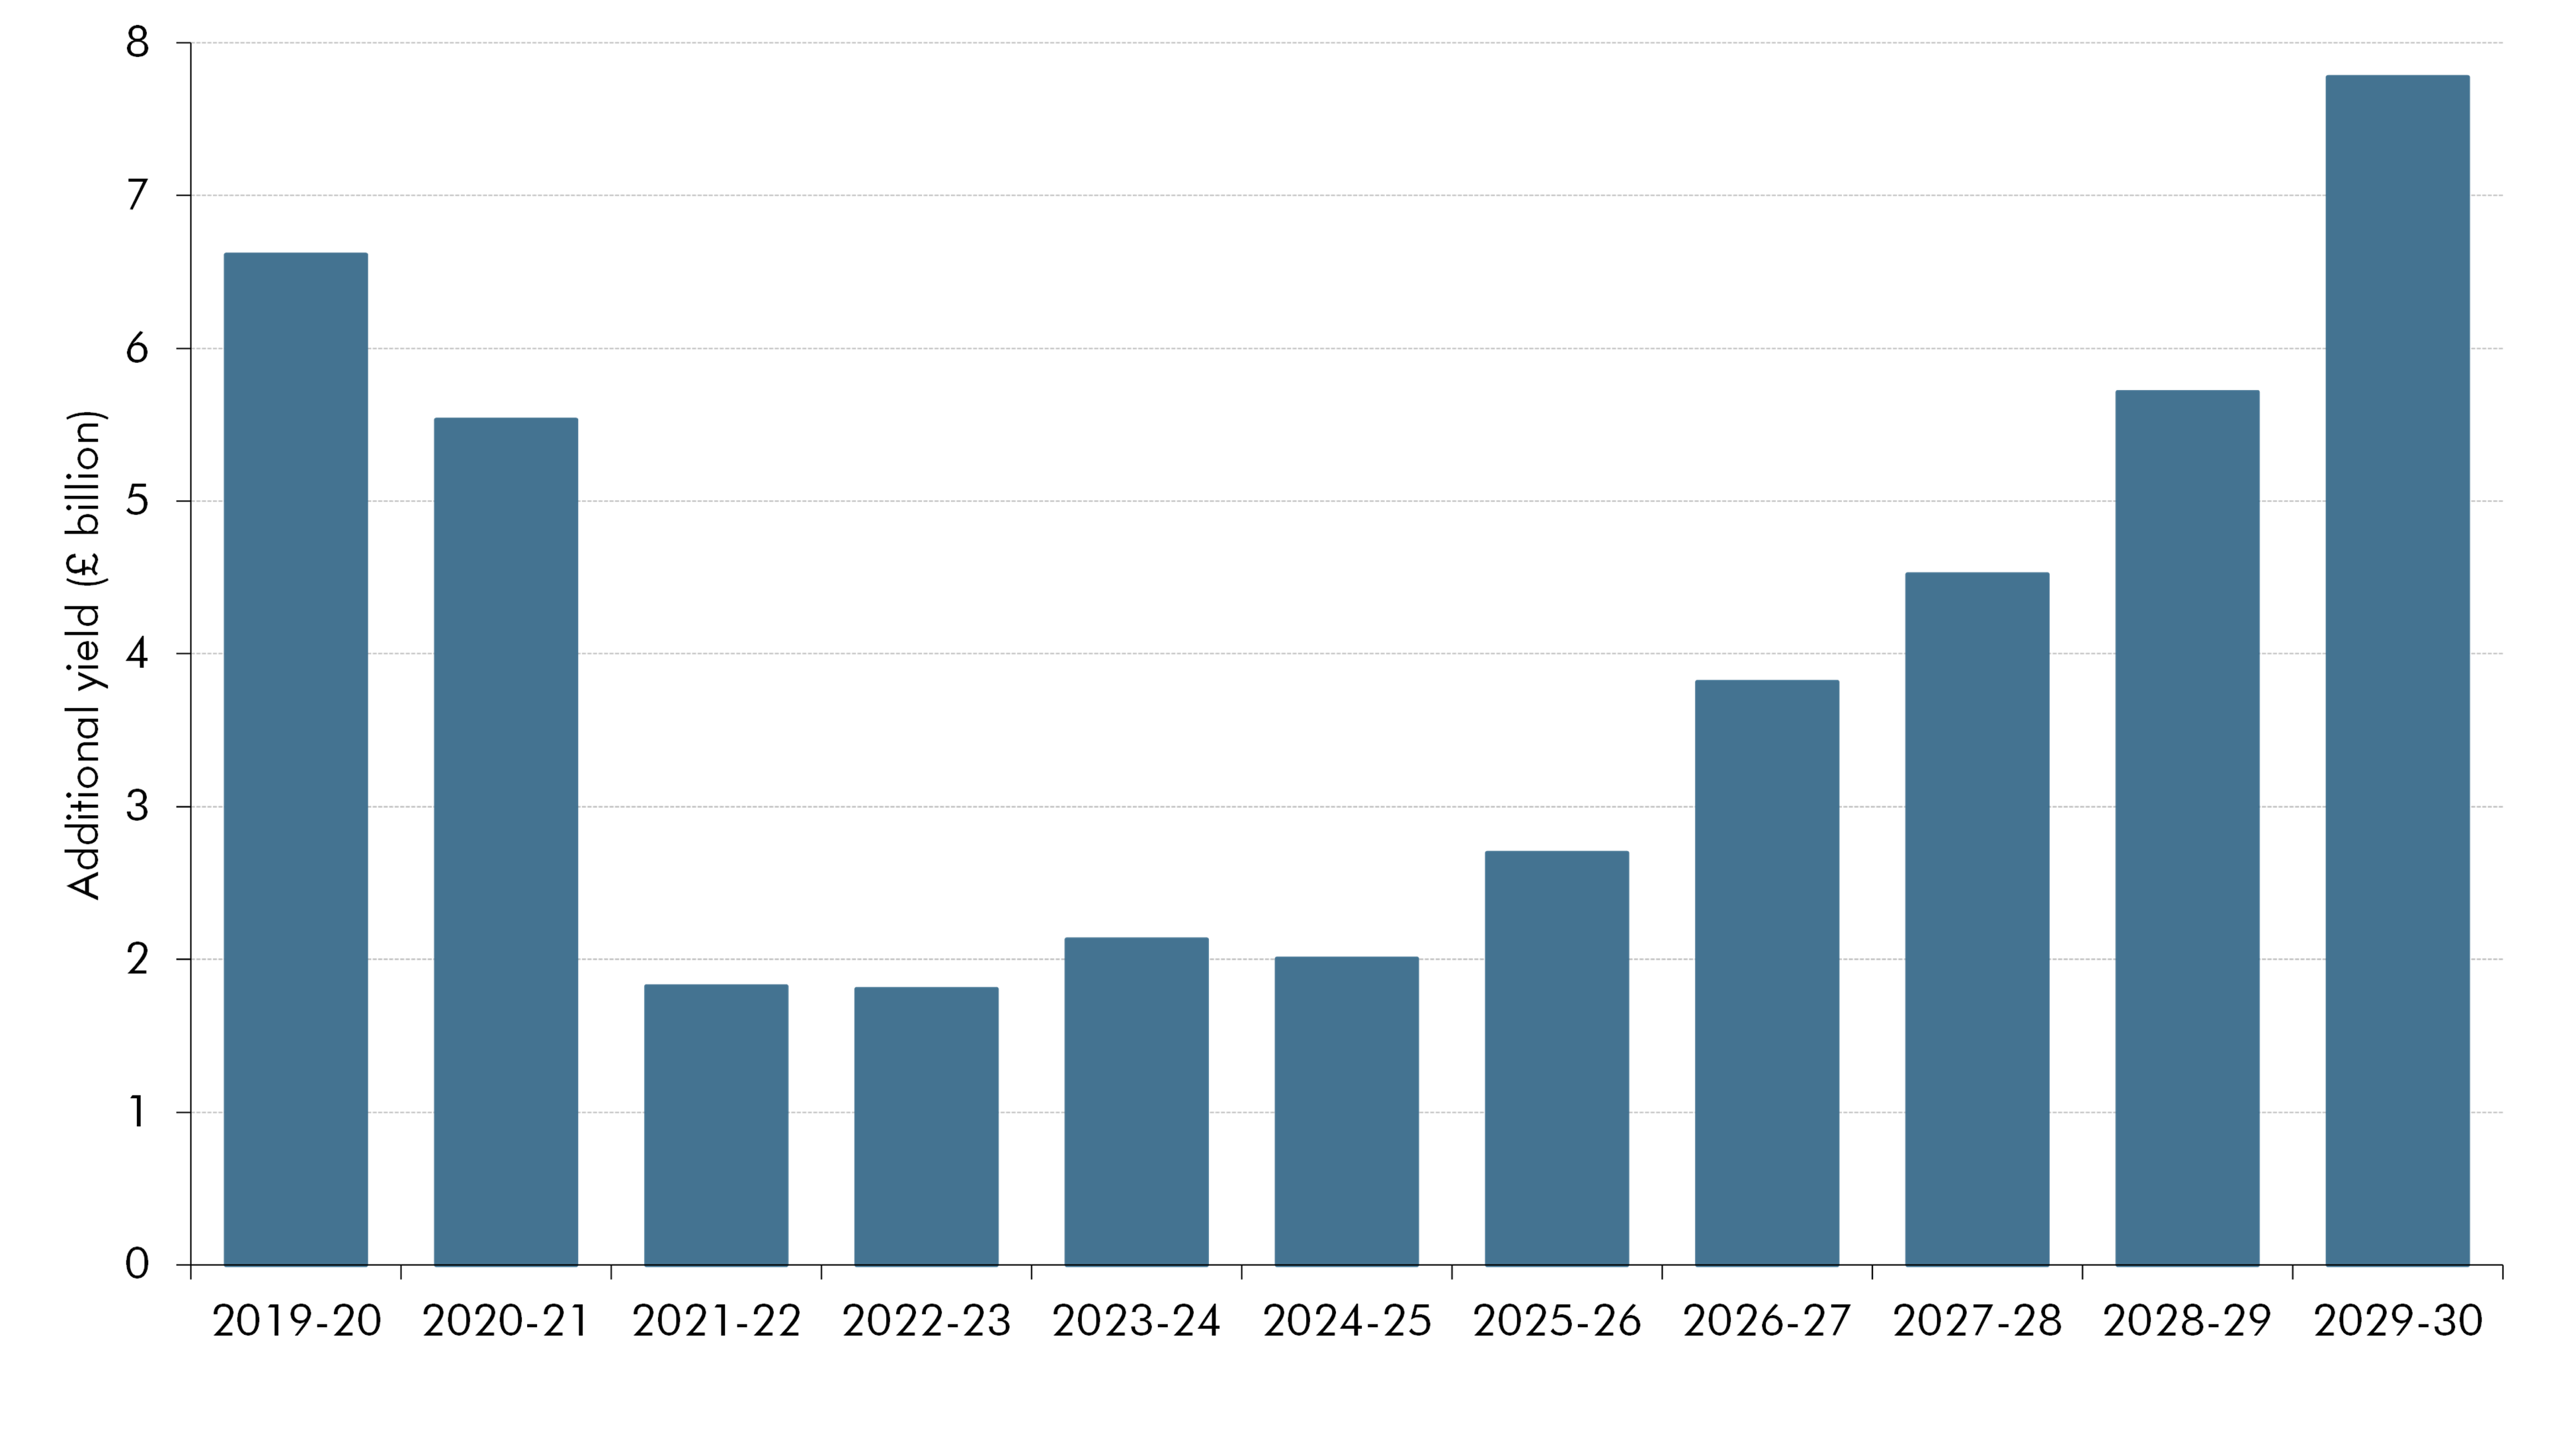
Note: This chart reflects when announced yield is estimated to impact the tax gap. Yield estimates shown here are ‘debt management adjusted’ and therefore differ from total yield. Debt management yield that changes the timing of payments, rather than the amount of tax ultimately collected, is excluded, while yield that reduces amounts otherwise lost through write-offs or remissions is included. HMRC estimates the latter using the age of debt in scope of each measure and the associated estimated impairment rate. The non-adjusted total compliance yield expected from these policies in 2029-30 is around £12 billion.
Source: HMRC, OBR
Estimates of the yield from compliance measures are highly uncertain. This reflects uncertainty around how taxpayers will respond to interventions and around the effectiveness of the operational delivery of such measures. To account for this, we apply a range of adjustments including attrition, which reflects how behavioural responses can erode yield over time, and optimism bias, to reflect the risk that evidence or delivery assumptions overstate yield. These adjustments are intended to produce a central estimate, but the resulting yield will nonetheless remain uncertain.
Looking top-down, the historical and projected future path of the tax gap indicates both upside and downside risk to the forecast. The forecast assumes a significant and sustained decline in the tax gap following a period across which it has been broadly flat. However, there have been previous periods of steeper declines in the tax gap, most significantly in the early 2010s. Given these risks, we will continue to monitor and evaluate the tax gap outturn compared to the estimated yield from compliance and debt measures, and, as set out in the article we published in October 2025, will undertake additional work with HMRC to further improve the approach used to produce these costings, including standardising the bottom-up assumptions we use to arrive at a central estimate of the yield.d
a) HM Revenue and Customs, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025, June 2026. There is a lag in the tax gap publication data and as such the most recent, 2026, estimates cover the 2024-25 financial year.
b) HMRC cautions against interpreting changes in tax gap estimates over time as evidence of underlying trends, given the impact of data revisions, methodological changes and uncertainty around the estimates themselves.
c) This is an illustrative comparison between scored yield and outturn and projected tax gap. Left-hand side of Chart A shows the expected impact of measures on the tax gap which have been re-costed at subsequent events, whereas Chart B shows the original scored yield from compliance and debt measures announced at fiscal events. Both have been adjusted to only capture yield from debt measures which has an impact on the tax gap.
d) Turner, A., and B. Garrett, Estimating the yield from tax compliance policies, 2025.
3.14 These measures aimed at addressing the compliance tax gap and fraud and error in the welfare system will require additional DEL funding across the forecast period. As RDEL settlements for HMRC and DWP have not been agreed beyond 2028-29, we requested additional information from the Government to ensure the activity captured by these measures would be truly additional to HMRC and DWP baseline activity. We also asked the Treasury to provide assurances that HMRC and DWP would receive the funding necessary to achieve the baseline compliance and fraud and error activity implicit in our forecast. The funding provision for baseline HMRC and DWP activity and measures announced at this Budget and Budget 2025 is set out in Table 3.2.
3.15 The Treasury has also agreed, once the full funding allocated to HMRC and DWP has been finalised in the next Spending Review, to undertake a review of the estimated yield from compliance and fraud and error measures announced since Autumn Budget 2024 which will be implemented beyond the current Spending Review period. We will also review the approach to post-Spending Review period measures in future as part of our ongoing work on the compliance tax gap and fraud and error in the welfare system.
Table 3.2: Funding costs of HMRC and DWP baseline and newly announced compliance, debt and fraud and error activity
| £ million | ||||||
|---|---|---|---|---|---|---|
| 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Baseline HMRC compliance and debt funding | 2,715 | 2,994 | 2,940 | 3,123 | 3,177 | 3,226 |
| Budget 2025 additional closing the tax gap funding | 57 | 66 | 35 | 31 | 98 | 57 |
| Budget 2026 additional closing the tax gap funding | 82 | 140 | 137 | 121 | 109 | 153 |
| Total HMRC compliance and debt funding | 2,854 | 3,200 | 3,112 | 3,275 | 3,384 | 3,436 |
| Baseline DWP fraud and error funding | 1,124 | 1,149 | 1,169 | 1,190 | 1,213 | 1,343 |
| Budget 2025 additional fraud and error funding | 36 | 97 | 168 | 103 | 105 | - |
| Budget 2026 additional fraud and error funding | -16 | 188 | 178 | 188 | 210 | 214 |
| Total DWP fraud and error funding | 1,144 | 1,434 | 1,515 | 1,481 | 1,528 | 1,557 |
| Source: HM Treasury |
Changes to corporation and bank taxes
3.16 The Budget includes several changes to corporation and bank taxes, which increase receipts by £2.3 billion in 2031-32. These include:
-
A reduction to the writing down allowance (WDA) main rate from 14 to 12 per cent, alongside an increase in the new first-year allowance introduced in January 2026 from 40 to 50 per cent from April 2027.[footnote 23] This is estimated to raise an average of £1 billion per year from 2027-28.
-
A temporary 3 percentage point increase to the bank surcharge, from 3 to 6 per cent, effective from 1 January 2027 to 31 March 2028. Over the 15 months this is in effect, it is estimated to yield a total of £1.5 billion. This is net of an estimated £190 million reduction in receipts[footnote 24] as some banks are assumed to move profits out of the UK in response to the higher tax rate. The size of this effect is uncertain.
-
Restricting sovereign wealth and overseas public pension funds’ immunity from direct taxes on UK income and gains from January 2029 raises £0.7 billion by 2029-30. This estimated yield includes a behavioural effect which significantly reduces the costing to reflect the affected population restructuring their assets, increasing leverage, and an attrition adjustment. This costing is deemed highly uncertain because of a lack of administrative data on the tax and assets of the affected group, and uncertainty surrounding the degree to which these groups will respond to minimise the impact of these changes.
Increase to tax rates on savings and property income
3.17 This Budget further increases the tax rates on savings and property income. These rates were already set to increase by 2 percentage points in April 2027 following measures announced at Budget 2025. From April 2027, the basic, higher, and additional rates will increase by a further 2 percentage points to 24, 44, and 49 per cent respectively. Together, the measures announced at this Budget are estimated to raise £1.0 billion by 2031-32:
-
The additional 2 percentage point increase in all rates of saving income tax is estimated to yield £0.6 billion a year on average from 2028-29. A behavioural response, primarily reflecting additional usage of other tax advantaged assets, such as Individual Savings Accounts, reduces the yield by around £0.2 billion a year.
-
The further 2 percentage point increase in all rates of property income tax is estimated to raise £0.4 billion a year on average from 2028-29. The costing of this policy includes small behavioural responses, reflecting additional tax-motivated incorporation and higher non-compliance, that reduce the yield by £0.1 billion a year. The potential long-term impact of the increase to property income tax rates and other related measures is discussed in paragraph 3.46.
Changes to dividend and capital gains taxation
3.18 The Budget includes the following changes to the dividend and capital gains tax (CGT) regimes:
-
Changes to the taxation framework for distributions from companies to individuals from April 2028 which is estimated to raise £0.8 billion by 2029-30. This introduces a number of changes to the system which aim to prevent company owners paying tax at lower CGT rates rather than at dividend income tax rates. The costing includes a significant reduction in the estimated yield over time to reflect the targeted tax base’s ability to plan to reduce the additional tax liability.
-
A reduction to the lifetime limit for the business asset disposal relief (BADR) from £1 million to £500,000 from April 2027 increases receipts by £0.3 billion in 2029-30. The introduction of a 10 per cent CGT rate for qualifying founders of high-growth or innovative companies from April 2027 reduces receipts in 2029-30 by £0.3 billion.
Other changes to taxes
3.19 This forecast also incorporates other changes to taxes which raise £1.1 billion in 2026-27, £1.3 billion in 2027-28, before falling to £0.2 billion by 2031-32. These include:
-
The Government has announced the abolition of the carbon price support (CPS) from April 2028 and provided funding for the Low Carbon Contracts Company (LCCC) enabling it to reduce contracts for difference (CfD) levies on billpayers. These measures cost an average £0.4 billion a year from 2027-28 onwards.[footnote 25] These measures are intended to offset the increase in electricity bills for non-energy-intensive-industry consumers due to the British Industrial Competitiveness Scheme (BICS) and an uplift to the Supercharger scheme.
-
In Budget 2025, fuel duty rates were frozen and the reversal of the 5p fuel duty cut delayed until September 2026. The Government has since announced a further freeze to fuel duty rates and delay of the reversal until January 2027, with this Budget extending these until June 2027. According to the latest policy, on 1 July 2027 the temporary five pence cut – first introduced in 2022 – will be reversed in full alongside an uprating of fuel duty rates. If implemented, it would lead to fuel duty rates rising from 52.95 pence per litre to 60.59 pence per litre. This policy costs £0.6 billion in 2026-27 and £0.8 billion in 2027-28. The reversal of the 5p cut has now been delayed five times and fuel duty has not been uprated with RPI since 2011. Paragraph 3.43 and Chapter 7 sets out the fiscal impacts if this latest iteration of fuel duty policy were to again not be implemented.
-
A cut to VAT on domestic electricity from 5 per cent to 0 per cent until April 2027 announced in July, with this Budget extending the cut until July 2027. This is expected to cost £0.7 billion in 2026-27 and £0.3 billion in 2027-28.
-
The Government has announced a package of temporary business rates measures through the remainder of the current valuation period, at a net cost of around £0.5 billion in 2028-29. These measures include a real-terms freeze in business rates liabilities for properties in certain sectors, increased reliefs for pubs and live music venues, and higher eligibility thresholds for small business rates relief. The Budget also extends existing schemes that limit increases in business rates bills following revaluation. The cost of these measures is partly offset by a two-year extension of the 1p transitional relief supplement.
-
The Budget also incorporates mayoral strategic authorities into the business rates retention system on a permanent basis. This increases the share of net business rates revenues flowing into local government by approximately £0.5 billion in 2031-32.[footnote 26] The measure means that a larger share of future growth in business rates revenues accrues to mayoral authorities rather than central government. This policy forms part of the Government’s wider devolution roadmap, which we discuss further in paragraph 3.38.
Measures impacting the Government’s balance sheet
3.20 The Government has increased the funding available for the National Wealth Fund and the British Business Bank (BBB) to invest in financial assets, such as loans and equity. This raises the Government’s financing requirement by £1.9 billion a year on average, and increases debt by £3.9 billion in 2031-32. The new investments are estimated to reduce borrowing by £0.5 billion in 2031-32, reflecting £0.6 billion of additional income, which is only slightly offset by expected losses due to loan write-offs and calls on guarantees. Taken together, the net impact of these measures is to increase debt by £3.4 billion in 2031-32.
3.21 The Government has also announced additional capacity for UK Export Finance (UKEF) to provide guarantees to back the purchases of British exports by foreign buyers. UKEF expects to issue a total of £40 billion of additional guarantees evenly between 2027-28 and 2030-31. This reduces borrowing by £0.2 billion a year over the medium-term but materially increases the public sector’s exposure to geopolitical risk. The £7 billion expansion of the Growth Guarantee Scheme offered by the BBB is expected to increase borrowing by £0.1 billion in 2026-27 and 2027-28 and £0.2 billion thereafter, reflecting the expected calls on the guarantees, which outweigh the fee income earned.
3.22 The ‘Your First Home’ Equity Loan Scheme will provide loans to first-time buyers of newbuild homes totalling £0.7 billion in 2027-28 and of £1 billion from 2028-29 onwards. This increases debt by £0.7 billion in the first year, thereafter the annual increase in debt from new loans is increasingly offset by loan repayments. We expect the scheme to only have a marginal impact on house prices and supply given its limited overall size.
Measures with highly uncertain costings
3.23 We assign an uncertainty rating to all certified policy costings. The measures that we have given a ‘high’ or ‘very high’ uncertainty ratings are set out in Table 3.3.
Table 3.3: Costings of measures with high degrees of uncertainty
| £ million | |||||||
|---|---|---|---|---|---|---|---|
| Head | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | Uncertainty | |
| Modernising overseas sovereign taxation | Tax | -105 | -479 | -688 | -677 | -657 | High |
| Property income tax rate increase | Tax | -2 | -543 | -400 | -411 | -422 | High |
| Direct recovery of debt | Tax | 0 | -2 | -50 | -258 | -323 | High |
| Online marketplace liability changes | Tax | -164 | -318 | -270 | -250 | -264 | High |
| Verification assurance officers | Spend | -20 | -78 | -161 | -255 | -329 | High |
| Company Share Option Plan scheme reform | Tax | 26 | 33 | 47 | 143 | 141 | High |
| E-invoicing mandation | Tax | -10 | -56 | -137 | -158 | -151 | High |
| Note: A positive sign implies an increase in borrowing. See our online detailed scorecard for the full, measure-by-measure breakdown of every costing. |
| Source: OBR |
3.24 The only highly uncertain measure not discussed above is the measure increasing the Company Share Option Plan (CSOP) scheme individual limit and removing the interaction with Enterprise Management Incentives so individuals can benefit from both allowances fully. There are high levels of uncertainty around the level of additional take-up of these schemes and the extent to which additional take-up maximises the increased options allowances.
Classification treatment of policies
3.25 On the advice of Treasury classification experts and pending an ONS decision on classification this section sets out how we are recording the following new Budget transactions:
-
Fees levied on landlords to register with local authorities are recorded as central government taxes and so increase receipts, while fees on developers to participate in the equity loans scheme are recorded as sales of goods and services and so decrease spending. These decisions do not affect borrowing or debt.
-
The introduction of timely payment for self assessment means that affected taxpayers make payments towards both their previous and current year liabilities during the transition year of 2029-30. These overlapping payments, together with the part reversal of the Budget 2025 measure that mandated coding out via the PAYE system, increase cash receipts in 2029-30 by £17 billion. As explained further in Chapter 6 the additional cash receipts reduce the CGNCR and public sector net debt in 2029-30, as both are measured in cash terms. We assume that the ONS will make an extraordinary accruals adjustment in 2029-30 to remove the temporary cash timing effect from these overlapping payments but will not do so in subsequent years.
3.26 The Treasury has also decided to switch the British Business Bank and National Housing Bank from departmental expenditure limits (DEL) to annually managed expenditure (AME).
Update on previous measures
3.27 We cannot review and re-cost all previous measures at each fiscal event, but we do look at those where the original (or revised) costings seem to be under- or over-performing, and costings that were identified as particularly uncertain.
3.28 The yield from the Budget 2025 measure to no longer exempt salary-sacrificed pension contributions from NICs, above an annual £2,000 threshold, has been revised up by an average of £0.4 billion in 2029-30 and 2030-31. This is driven by outturn data suggesting higher usage and average contributions than previously assumed and a stronger nominal earnings forecast.
3.29 In response to underperformance in the delivery model of their targeted case review (TCR) regime, DWP has decided to insource 2,500 FTE staff who were previously working for a third-party contractor to boost their productivity, as well as to hire an additional 900 FTE staff to undertake more case reviews. We included AME savings from this operational expansion in our pre-measures forecast. Despite the Government’s intention for these additional 900 staff to be permanent, we were informed after the closure of our pre-measures forecast that they would not be funding these staff beyond 2028-29. We will review both the resourcing and AME savings of this measure at our next forecast.
Update on previous indirect effects judgements
3.30 Together with the Treasury and departments responsible for implementation of the various policy measures, we have established transparent processes for monitoring and evaluation of the supply-side impacts of policies on potential output. We use these processes to check whether observed outcomes are consistent with the assumptions underpinning our economy forecast. We have made no explicit adjustments to the forecast as a result of monitoring and evaluation at this event. For larger policies, there is not yet evidence that their effects differ materially from those incorporated in our forecast, while policies experiencing delivery issues have relatively small effects in the forecast.
3.31 As set out in Chapter 2, in this forecast we have revised down our projection for new housing supply over the forecast period by 190,000. We have not, however, at this point revised our previous estimates of the positive contribution that the National Planning Policy Framework (NPPF) reforms would make to housing supply over this period. Instead, our assessment is related to the wider regulatory and fiscal environment and to sharp rises in construction costs. This illustrates the challenges associated with assessing the economic effects of regulatory policies, where the full range of relevant regulatory changes affecting any specific sector can be difficult to identify and quantify.[footnote 27] We will keep our NPPF assumption under review. A feasibility study for the evaluation of the NPPF reforms is expected from MHCLG in early 2027.
3.32 We have previously not included an assessment of the potential economic impacts of the Employment Rights Act 2025 (ERA), given it was dependent on ongoing consultations and secondary legislation. We have made an assessment at this event, following the conclusion of most of the consultations and the implementation of various components of the reforms. Our analysis suggests that the ERA will likely have a negative economic impact from negative impacts on businesses, particularly through increased uncertainty, lost flexibility and higher labour related costs, which will more than offset any potential positive impact on worker productivity.
3.33 However, the size of the impact of the ERA is highly uncertain, partly due to the difficulties mentioned above in assessing the economic effects of regulatory policy. It is likely that the negative impact from the final set of reforms is substantially less than the initial policy proposals put forward in 2024 would have been. There is also still some uncertainty about the final policy design of the zero-hour contract related measures. However, overall, we judge there is currently not clear evidence that this negative impact is above our 0.1 per cent potential output threshold, so we have not made an explicit adjustment to our forecast. We will keep this judgement under review.
3.34 The latest evidence on the increase in employer NICs announced at Autumn Budget 2024 does not suggest that its impacts have been materially different from our expectations. Sharper falls in employment among lower-paid sectors are consistent with our judgement that these firms would be most affected by the reduction of the secondary threshold and its interaction with the National Living Wage. That said, it remains too early to draw firm conclusions about the scale of the policy’s impacts relative to our original assumptions, given the wider effects impacting the labour market (see Chapter 2). A full evaluation is expected from HMRC in 2027.
3.35 At previous events we have incorporated estimates of the increase to labour supply from government employment support programmes. The extension to Talking Therapies, which we estimated would increase employment by 10,000 in our November 2023 forecast, was intended to increase both the number of completed treatments and the average number of sessions. However, this extension has not been delivered. Connect to Work, which we assumed – in our 2023 forecasts – would increase employment by around 25,000, aimed to help people with health conditions and disabilities into employment. The number of participants supported is now expected to be around a third lower than we assumed by 2028-29. These examples illustrate the challenges of making explicit adjustments to the economy forecast for departmental spending policies, given that the impacts are highly sensitive to subsequent changes to policy and operational design, possible reprioritisation of funding, delivery challenges, and wider changes to spending programmes which may have offsetting effects.[footnote 28]
3.36 The latest evidence on the expansion of 30 hours free childcare, suggests take-up has been stronger than expected. This was announced at Spring Budget 2023 and, as of June 2026, the number of active users of the offer was 17 per cent above the DfE target. This has increased spending on the policy relative to original expectations. However, higher take-up does not necessarily imply a larger labour supply effect – we originally estimated that this would increase employment by 60,000. Some parents receiving the additional support may have worked similar hours in its absence – particularly those on higher incomes – and it is possible that individuals earning above the £100k cut-off threshold have reduced their hours worked to receive the childcare benefit. The DfE evaluation for this policy is expected in 2027.
Policy risks
3.37 Our legislation requires that our forecasts reflect only current government policy. As such, when the Government sets out ‘policy ambitions’ or ‘intentions’, we ask the Treasury to confirm whether they represent firm policy. We use that information to determine what should be reflected in our forecast. Where they are not yet firm policy, we note them as a source of risk to our central forecast. A full database of risks to this forecast and the changes from previous updates will be available on our website.
3.38 The Government’s devolution roadmap sets out initial details of the transfer of powers and resources in England. This includes policies for local retention of income tax receipts from April 2028 and discretionary power for mayoral and foundation strategic authorities to introduce an Overnight Visitor Levy. We will incorporate any material economic and fiscal impacts of these reforms into our forecast once the detailed policy and implementation arrangements have been finalised.
3.39 The Timms Review of Personal Independence Payment and Milburn Report on youth, health, and employment have both published interim findings with final recommendations expected later this year. We will assess the economic and fiscal impacts of any resulting policy changes once the Government has responded and the policy details are sufficiently clear.
3.40 The Government has announced several future spending commitments following the end of the current Spending Review period. As discussed in paragraphs 5.16 to 5.19, this includes the Government’s commitment to reach 3.5 per cent of GDP spent on defence by 2035 and a commitment to significantly increase council house building. We will incorporate the economic and fiscal impacts of the final announcements made in these areas after the next Spending Review.
3.41 The Government has announced its intention to establish a National Care Service in England and has brought forward the Casey Commission’s recommendation on its design to 2027. The fiscal cost of these reforms is highly dependent on the final design of the reforms and the timing of their introduction. For example, the Health Foundation has previously estimated that reforms to social care could increase spending by between £3.5 billion and £17 billion a year, depending on the generosity and design of the system.[footnote 29] We will incorporate the economic and fiscal impacts once the detailed policy and funding arrangements have been confirmed. Based on the current policy regime, we projected in the 2026 Fiscal risks and sustainability report that adult care spending in the UK would rise as a share of GDP from 1.2 per cent to 1.8 per cent over the next 50 years, largely reflecting demographic pressures associated with the UK’s projected growing old-age population. These spending pressures are expected to be most pronounced in the 2030s as the baby-boom cohort reaches their 80s, given the concentration of adult social care costs towards the end of life.
Extensions of temporary policies
3.42 The Budget includes several extensions to policies that are described as temporary and therefore not included in the forecast beyond the short term. This continues a pattern of such extensions at successive fiscal events. This introduces risk into the medium-term forecast which is produced on the basis of these temporary policies expiring.
3.43 At this Budget, fuel duty rates have again been frozen for a further 10 months until July 2027, from when the ‘temporary’ 5p cut to rates were first introduced at Spring Statement 2022.[footnote 30] The cumulative cost of freezing fuel duty rates between 2010-11 and 2027-28 and the 5p cut, relative to the stated policy that they will increase in line with RPI inflation, has risen to £139 billion. As shown in Table 7.1, if fuel duty were to remain frozen until 2029-30, public sector net borrowing would be £4.3 billion higher.
3.44 Other smaller measures which have been extended through repeated short-term policy decisions include various reliefs for business rates, the universal credit surplus earnings limit – which has been extended for the tenth consecutive year – and tariff suspension extensions.
The long-run impact of government policy
3.45 The Charter for Budget Responsibility requires us to assess the long-term impacts of new government policies, where these are material. We therefore report on new policies with long-run economic and fiscal impacts, especially where these differ from the effects that are expected to have occurred by the five-year timeframe at which we are required to produce our medium-term forecasts.
The long-run economic impact of measures
3.46 The 2 percentage point increase in property income tax rates in this Budget will be implemented on top of the 2 percentage point increase announced at Budget 2025. Both of these measures will come into force from April 2027 and represent a material reduction in returns to private landlords. This follows various measures over the past 10 years that have also reduced private landlord returns.[footnote 31] These measures collectively risk leading to a steady rise in rents through two effects. First, potential landlords are less likely to enter the market, reducing long-run rental supply, which risks a steady long-term rise in rents if demand outstrips supply – which we think is more likely than not. Second, landlords are likely to pass on more of these costs to renters in the long-run through a combination of some current landlords leaving, thereby giving more price setting power to remaining landlords, and greater long-run flexibility to raise rents. Such rises in rents would offset at least some of the reduction in the commercial viability to landlords from the measures introduced in recent years.
3.47 The India-UK Free Trade Agreement could increase real GDP by amounts rising to 0.13 per cent by 2040, according to the Government’s impact assessment.[footnote 32] As these economic benefits are expected to build up gradually over the long-term, we do not make an explicit adjustment in the medium-term forecast. The UK is also currently negotiating with the EU on various policies, including sanitary and phytosanitary measures and alignment between the UK Emissions Trading Scheme and EU Emissions Trading System. The economic impact will depend on the outcome of these negotiations.
The long-run fiscal impact of measures
3.48 In our Fiscal risks and sustainability reports (FRS), we have highlighted the long-term costs of the triple lock policy which, under its current design, uprates the state pension each year by the greater of average earnings growth, CPI inflation, or 2.5 per cent. In the 2026 FRS long-term scenarios, an ageing population – combined with the triple lock – drove a significant projected increase in state pension spending from 5 per cent of GDP in 2025-26 to 9 per cent of GDP in 2075-76. We estimated that the triple lock accounted for around one third of this increase. In the FRS baseline long-term scenario, which assumes pensions are uprated by the triple lock, public sector debt is projected to reach 300 per cent of GDP by 2075. In a scenario where the state pension is instead assumed to be uprated by earnings each year, debt was projected to reach 260 per cent of GDP by 2075.
3.49 Under the adjusted triple lock system, which is expected to take effect from April 2030, the state pension will be uprated by the highest of CPI inflation, 2.5 per cent, or the increase required to maintain its value relative to earnings at 2029-30 levels. As a result, if the value of the state pension moves above its value relative to earnings in 2029-30 (due to periods in which inflation or 2.5 per cent is higher than earnings growth) then in subsequent periods (where earnings growth is higher than inflation or 2.5 per cent) it would converge back toward this relative value. This removes the so-called spending ratchet effect under the current triple lock whereby increases in pension values relative to earnings are permanently retained and compounded over time.
3.50 We have incorporated the adjusted triple lock into our central medium-term forecast from 2030-31 but it does not currently affect state pension costs over the forecast period.[footnote 33] However, the adjusted triple lock is likely to materially reduce the growth of state pension spending over the long term relative to the current triple lock. The exact long-term impact of this change will be highly dependent on the future relationship between earnings growth, inflation, and the 2.5 per cent floor. To illustrate this, Chart 3.4 applies earnings uprating, the current triple lock and the adjusted triple lock to historical outturn data for earnings and inflation since 1990. This shows that:
-
1990-2007: Average earnings growth was typically above both inflation and 2.5 per cent.[footnote 34] As a result, the illustrative pension values under both the current triple lock and adjusted triple lock would have remained very close to those produced by earnings uprating alone.
-
2008-2014: Inflation or 2.5 per cent consistently exceeded earnings growth. As such, pensions under both the current and adjusted triple lock would have been uprated by the same amount each year and seen their value relative to earnings rise.
-
2015-2025: Earnings growth exceeded inflation or 2.5 per cent over seven of the 10 years. These are the years in which the current and adjusted triple lock mechanisms would have produced different pension value outcomes:
-
under the current triple lock, pensions would be uprated by earnings growth in these years, maintaining the gaps with earnings indexation that develop when inflation or the 2.5 per cent targets bind. This illustrates the ratchet effect of the current triple lock, under which this gap can only widen over time.
-
under the adjusted triple lock, pensions would instead have been uprated by inflation or 2.5 per cent in these years, narrowing the gap with earnings indexation. In a scenario where earnings continued to exceed inflation and 2.5 per cent in subsequent years, this gap would eventually close under the adjusted triple lock.
3.51 Over the period from 1990 to 2025, the adjusted triple lock would have produced annual outcomes relative to earnings growth and the current triple lock that varied significantly across the different economic environments described. Averaging over the period as a whole, state pension payments would have been on average 1.4 per cent lower each year than under the current triple lock and 4.4 per cent higher than under earnings uprating.
3.52 This analysis illustrates that while the adjusted triple lock will not eliminate the long-term cost of state pension uprating relative to earnings indexation, it is expected to reduce costs relative to the current triple lock. Provisional analysis based on the historical experience described above suggests that if the next 50 years looked similar to the last 35 years on average, the adjusted triple lock would reduce the projected long-term increase in debt by around 25 per cent of GDP in 2075-76 relative to retaining the current triple lock.[footnote 35] Debt would be around 10 per cent of GDP higher in the long-term than under an earnings uprating scenario, reflecting the likelihood that there would continue to be periods where the inflation or 2.5 per cent uprating mechanisms would bind.
Chart 3.4: The value of the state pension under alternative uprating mechanisms
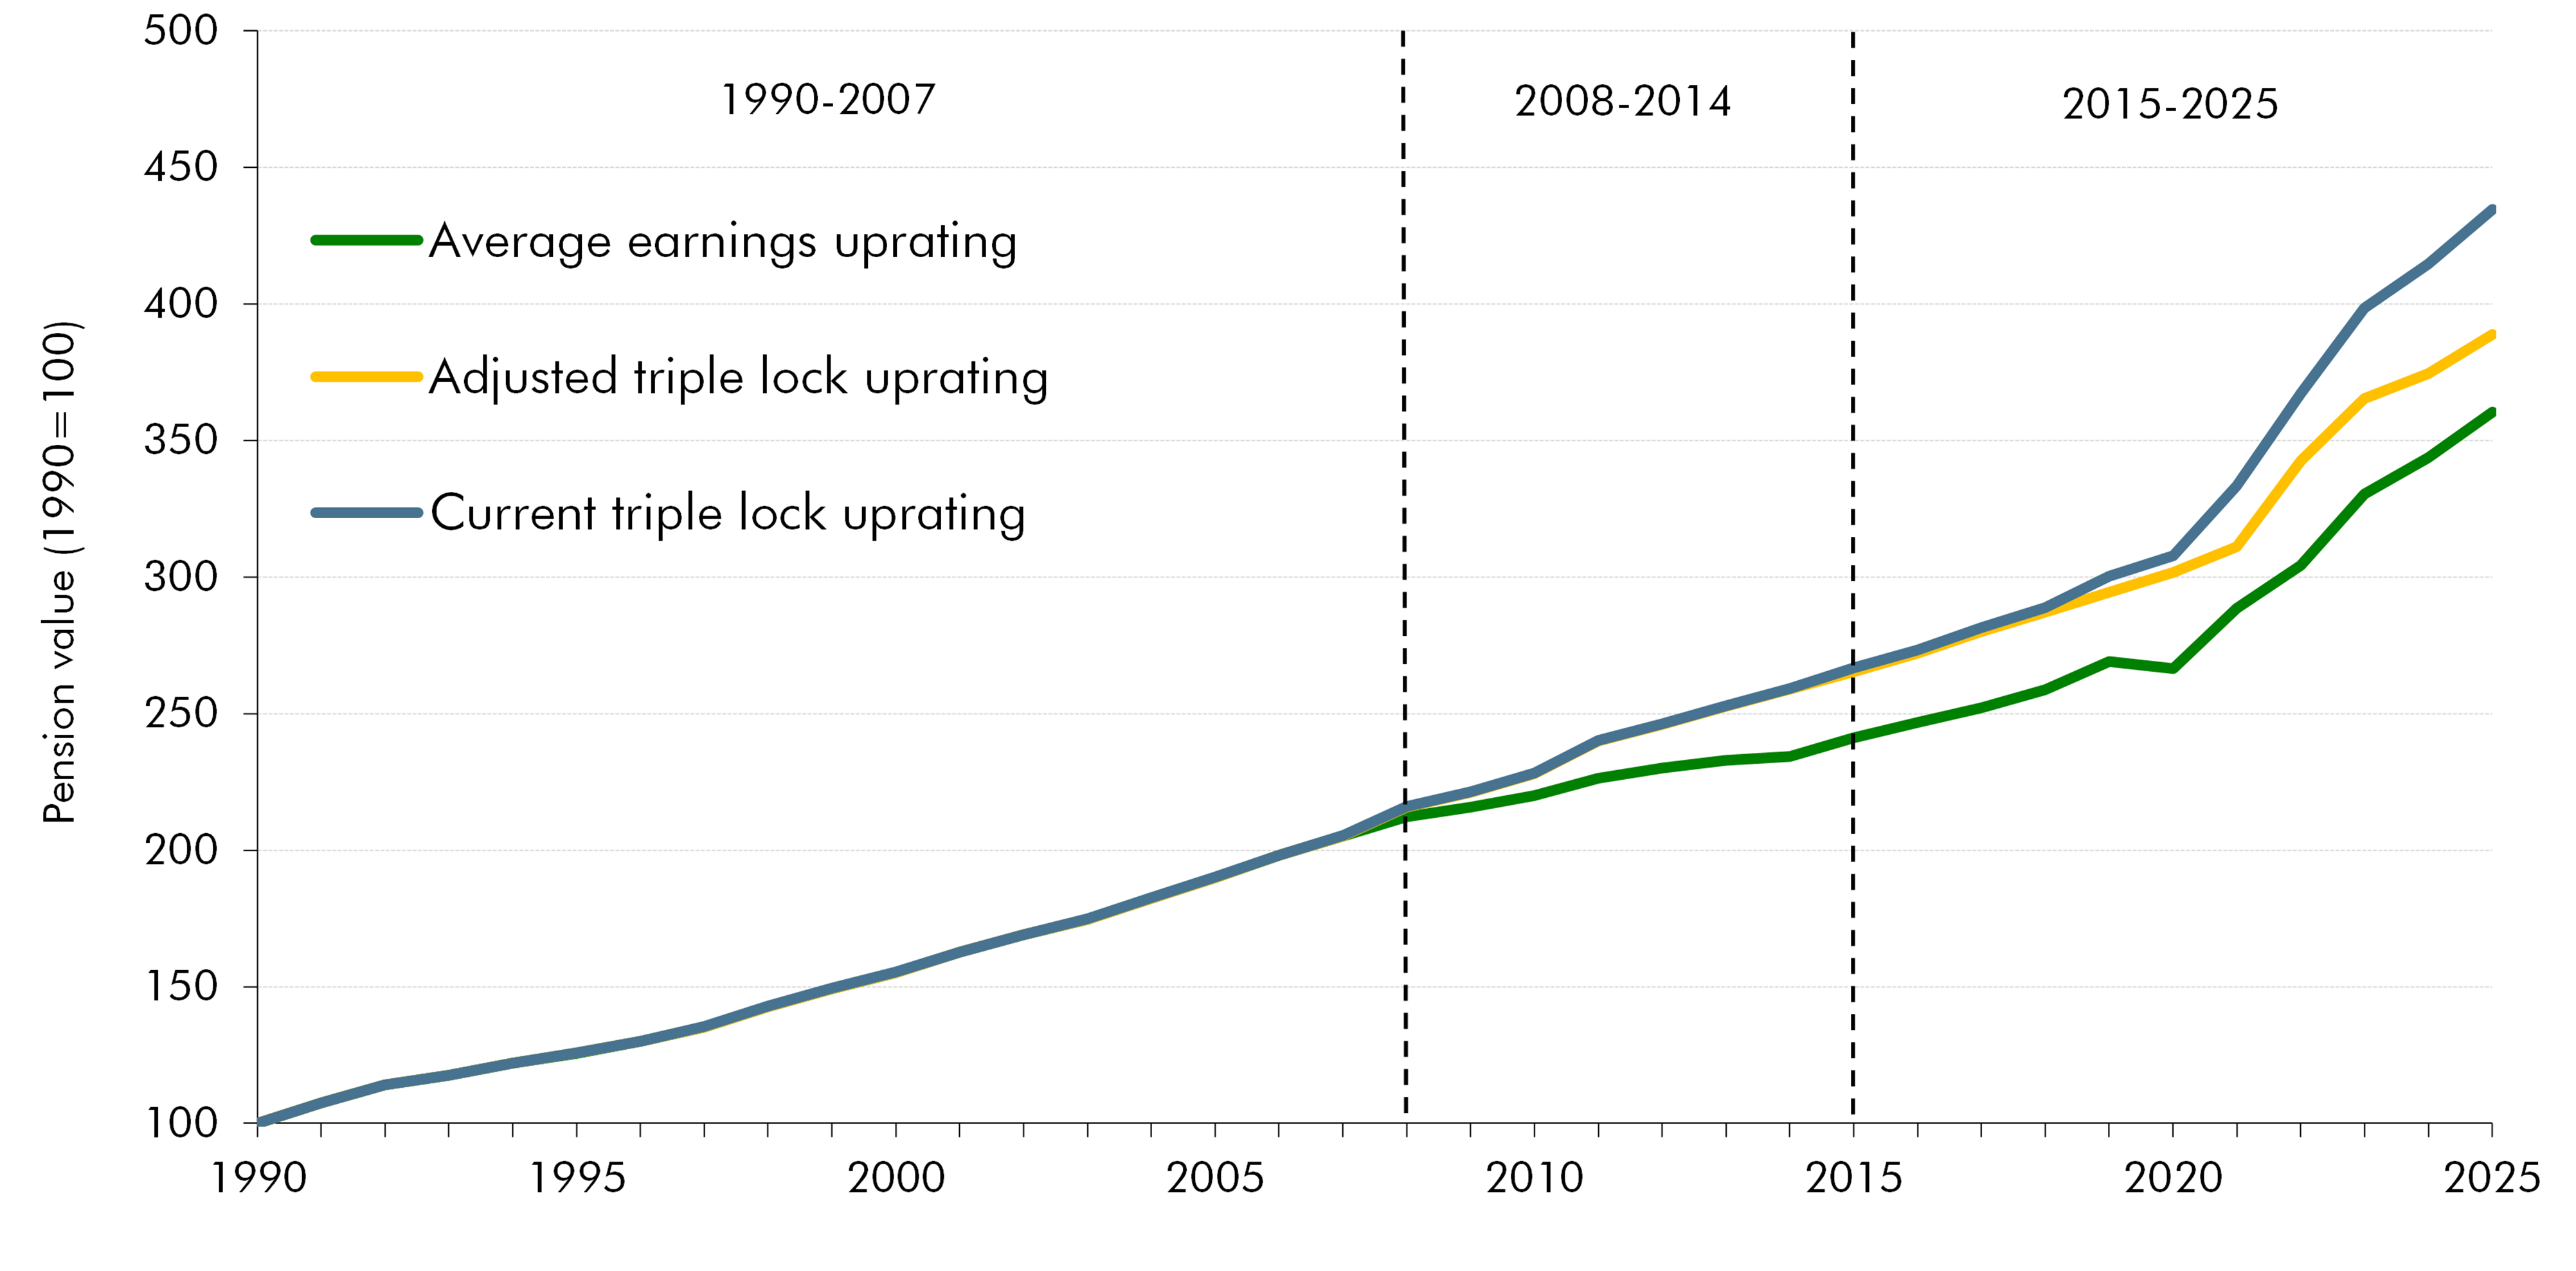
Note: The above reflects illustrative analysis of how pension values would have evolved under alternative uprating mechanisms between 1990 and 2025. It assumes that the adjusted triple lock would be conditioned on maintaining pension value relative to earnings at 1990 levels and that these alternative mechanisms would have bound across all years shown.
Source: OBR
3.53 This is an illustrative estimate of the long-term fiscal impact of the adjusted triple lock. These estimates depend critically on the order, level and covariation of wage growth and inflation over time. We intend to develop our long-term modelling approach ahead of the next FRS so that we can provide a fuller analysis of the adjusted triple lock mechanism and assess its sensitivity to different long-run economic assumptions.
3.54 These initial illustrative estimates suggest that the adjusted triple lock is likely to materially reduce future spending pressures relative to current policy. However, alongside the announced adjustment to the triple lock, the Government stated its intention to expand state provision of social care. The overall impact of these announcements on the long-term public finances therefore depends on the additional cost of the social care reform which, as discussed in paragraph 3.41, depends on the final policy design and the timing of its introduction.
Chapter 4: Public sector receipts
Summary of the receipts forecast
4.1 In the central forecast, total public sector receipts are projected to rise as a share of GDP from 40.1 per cent of GDP (£1.2 trillion) in 2025-26 to 42.9 per cent of GDP (£1.6 trillion) in 2031-32. Within this, as Chart 4.1 shows, National Accounts taxes as a share of GDP (the ‘tax take’) are forecast to increase sharply from 36.0 per cent of GDP in 2025-26 to 37.9 per cent of GDP in 2027-28, surpassing the previous historical high, before then rising more gradually to reach a peak of 38.6 per cent of GDP at the end of the forecast period.[footnote 36] This would be a 5.7 per cent of GDP increase on the pre-pandemic level of 32.9 per cent of GDP in 2019-20.
4.2 Table 4.1 details the main drivers of the expected 2.6 per cent of GDP increase in the tax take from 2025-26 to 2031-32. Increases in personal taxes (income tax and National Insurance contributions) contribute 1.6 per cent of GDP to this increase, reflecting forecast earnings growth, frozen personal tax thresholds until April 2031, and policy measures that raise self-assessment receipts. Capital taxes contribute 0.5 per cent of GDP to the increase due to projected rises in equity prices and the expected impact of inheritance tax and capital gains tax (CGT) policy changes largely announced in Autumn Budget 2024. Onshore corporation tax contributes a further 0.4 per cent of GDP to the increase mainly due to strong expected near-term profits growth.
4.3 Relative to our March 2026 forecast, National Accounts taxes as a share of GDP are forecast to be 0.2 per cent of GDP higher this year and just 0.1 per cent of GDP higher in 2030-31, as higher forecast receipts in nominal terms are almost offset by higher forecast nominal GDP. Of the rise in nominal receipts, around four-fifths of the increase in 2030-31 compared to March is due to changes in the underlying forecast, primarily due to a stronger nominal earnings forecast and higher forecast asset prices and profits. Around one-fifth is accounted for by the tax policy changes announced in this Budget.
Chart 4.1: National Accounts taxes as a share of GDP
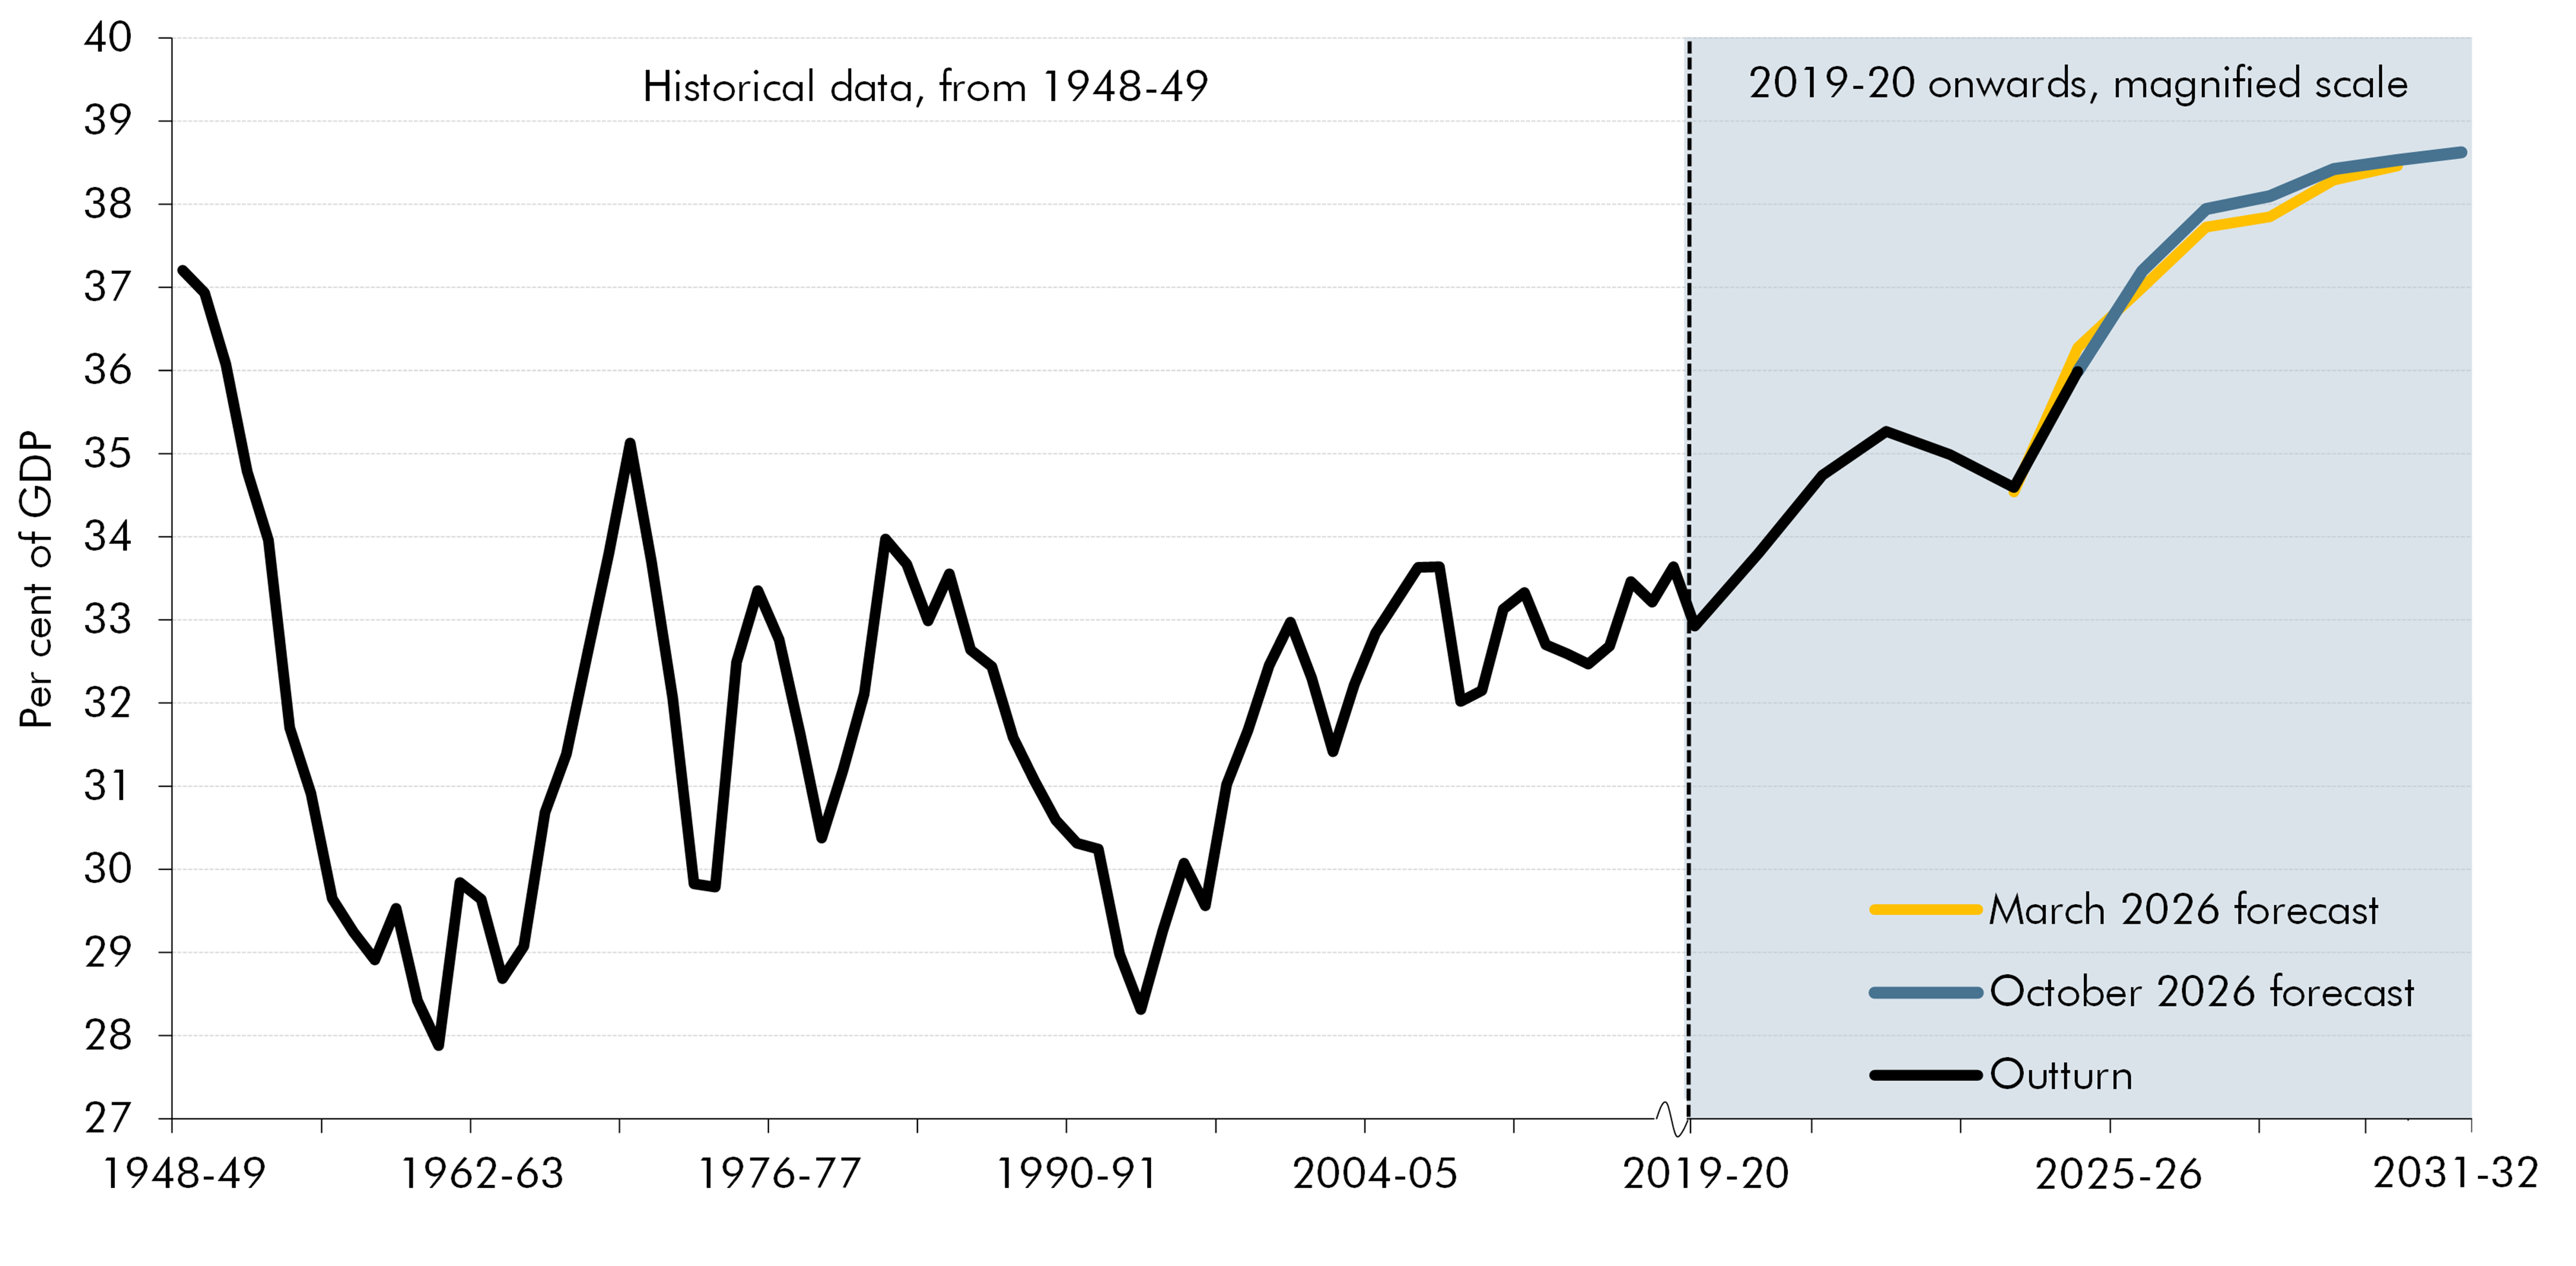
Source: ONS, OBR
Table 4.1: Public sector receipts as a share of GDP
| Per cent of GDP | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Income tax | 10.7 | 11.5 | 11.9 | 11.8 | 12.0 | 12.1 | 12.2 |
| NICs | 6.7 | 6.7 | 6.7 | 6.7 | 6.8 | 6.8 | 6.8 |
| Value added tax | 5.9 | 5.9 | 6.0 | 6.0 | 6.0 | 6.0 | 6.0 |
| Onshore corporation tax(1) | 3.1 | 3.4 | 3.5 | 3.5 | 3.6 | 3.6 | 3.6 |
| Capital taxes(2) | 1.8 | 1.8 | 1.9 | 2.1 | 2.1 | 2.2 | 2.3 |
| Business rates | 1.1 | 1.1 | 1.1 | 1.1 | 1.2 | 1.1 | 1.1 |
| Fuel duties | 0.8 | 0.8 | 0.8 | 0.8 | 0.7 | 0.7 | 0.6 |
| Alcohol and tobacco duties | 0.6 | 0.6 | 0.6 | 0.6 | 0.6 | 0.6 | 0.5 |
| PSNB-neutral taxes(3) | 3.0 | 3.2 | 3.2 | 3.2 | 3.2 | 3.2 | 3.2 |
| Other taxes | 2.2 | 2.3 | 2.3 | 2.3 | 2.2 | 2.2 | 2.2 |
| National Accounts taxes(4) | 36.0 | 37.2 | 37.9 | 38.1 | 38.4 | 38.5 | 38.6 |
| Interest and dividend receipts | 1.3 | 1.4 | 1.5 | 1.5 | 1.4 | 1.4 | 1.4 |
| Public sector depreciation (PSNB-neutral) | 2.4 | 2.5 | 2.5 | 2.5 | 2.5 | 2.5 | 2.5 |
| Other receipts | 0.4 | 0.4 | 0.4 | 0.3 | 0.3 | 0.3 | 0.3 |
| Current receipts | 40.1 | 41.4 | 42.3 | 42.4 | 42.7 | 42.8 | 42.9 |
| 1) Includes Pillar 2 taxes. |
| 2) Includes capital gains tax, inheritance tax, property transaction taxes, and stamp taxes on shares. |
| 3) Includes council tax, VAT refunds, extended producer responsibility, community infrastructure levy, and most environmental levies. |
| 4) Includes all taxes recognised in ONS’s National Accounts and National Insurance Contributions. It is also referred to as the ‘tax take’. |
| Source: ONS, OBR |
4.4 Chart 4.2 shows the contributions to the change in the National Accounts tax-to-GDP ratio, which is forecast to be 5.7 percentage points higher in 2031-32 than it was in 2019-20, just before the Covid pandemic. They are:
-
2019-20 to 2025-26: Nearly all major taxes grew as a share of GDP during this period, adding 3.1 percentage points to the tax-to-GDP ratio by 2025-26. The contribution of income tax rose sharply after 2022-23 due to the freezing of personal tax thresholds combined with the subsequent period of high inflation. NICs receipts fell in 2024-25 due to the reductions to employee and self-employed NICs announced in Autumn Statement 2023 and Spring Budget 2024, but then rose again in 2025-26 due to the employer NICs rises announced in Autumn Budget 2024. The rise in onshore corporation tax was driven by the increase in the main rate from 19 per cent to 25 per cent in April 2023 and resilient profits in higher tax-paying sectors. Oil and gas receipts rose sharply in 2022-23 due to high energy prices and the introduction of the energy profits levy, then fell back as prices declined. Fuel duty was the only major tax to see a persistent fall as a share of GDP after the pandemic because of successive duty rate freezes, the 5p rate cut announced in Spring Statement 2022, and the increasing use of electric vehicles.
-
2025-26 to 2031-32: The further forecast increase in the tax take of 2.6 per cent of GDP over this period is mainly driven by further expected growth in personal taxes, capital taxes and onshore corporation tax, as described in paragraph 4.2. This is expected to be slightly offset by further declines in fuel duty receipts, alongside reductions in receipts from alcohol and tobacco duties. Much of the increase is expected to take place by 2027-28, which is also temporarily boosted compared to 2028-29 by expected one-off receipts from the reforms to the previous non-domiciled tax regime, with more gradual increases then expected from 2028-29 onwards.
Chart 4.2: Contributions to the change in the tax-to-GDP ratio since 2019-20
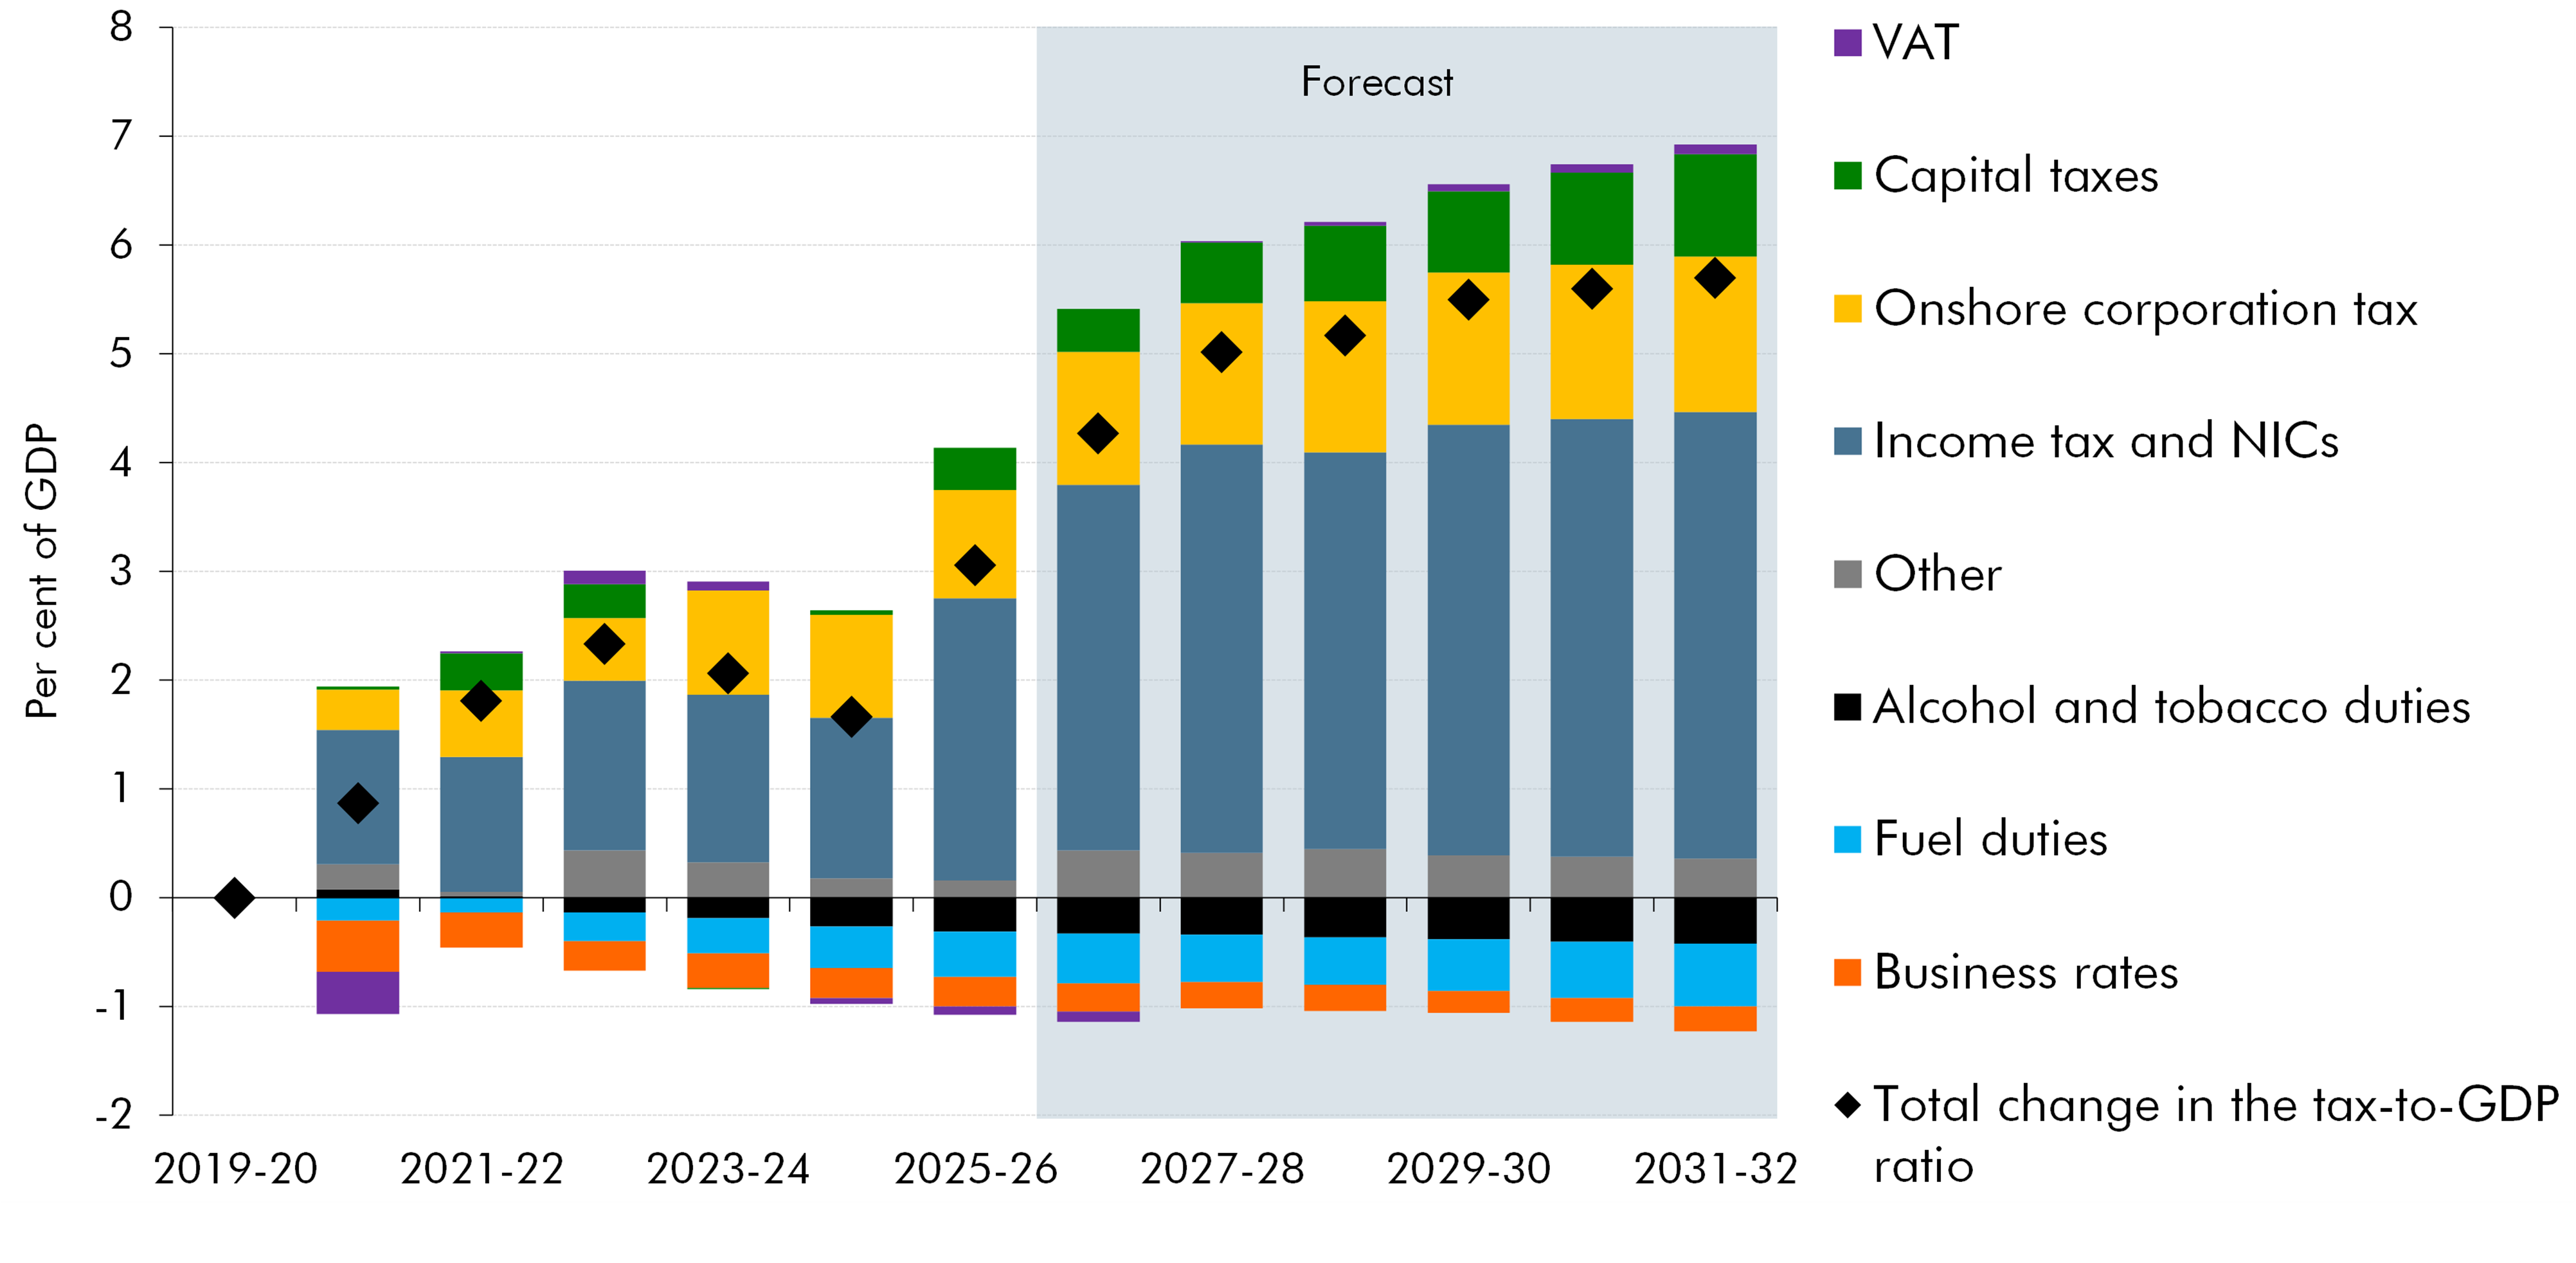
Source: ONS, OBR
4.5 Chart 4.3 shows the same projected 5.7 percentage point rise in the tax-to-GDP ratio from 2019-20 to 2031-32 decomposed into the impact of forecast and policy changes:
-
The inherited tax system adds 0.8 percentage points to the tax-to-GDP ratio over this period. This is the increase in tax revenues that is driven by the structure of the tax system in place at the time of the pre-pandemic Budget in March 2020, combined with the expected evolution of the economy over the period to 2031-32.
-
Underlying forecast changes, including outturn and economy forecast changes, add an expected additional 0.7 percentage points, which is mainly due to higher forecast profits and earnings.
-
The direct impacts of government policy decisions from Spring Budget 2020 to Spring Budget 2024 increase the tax-to-GDP ratio by a further 1.7 percentage points between 2019-20 and 2031-32, primarily through freezes to personal tax thresholds and the increased headline rate of corporation tax.
-
The direct impacts of Government policy decisions from Autumn Budget 2024 onwards add a further 2.5 percentage points to the tax-to-GDP ratio between 2024-25 and 2031-32, including through the measures announced at this Budget that increase it (by 0.2 percentage points).
Chart 4.3: Contributions to the rise in the tax-to-GDP ratio from 2019-20 to 2031-32
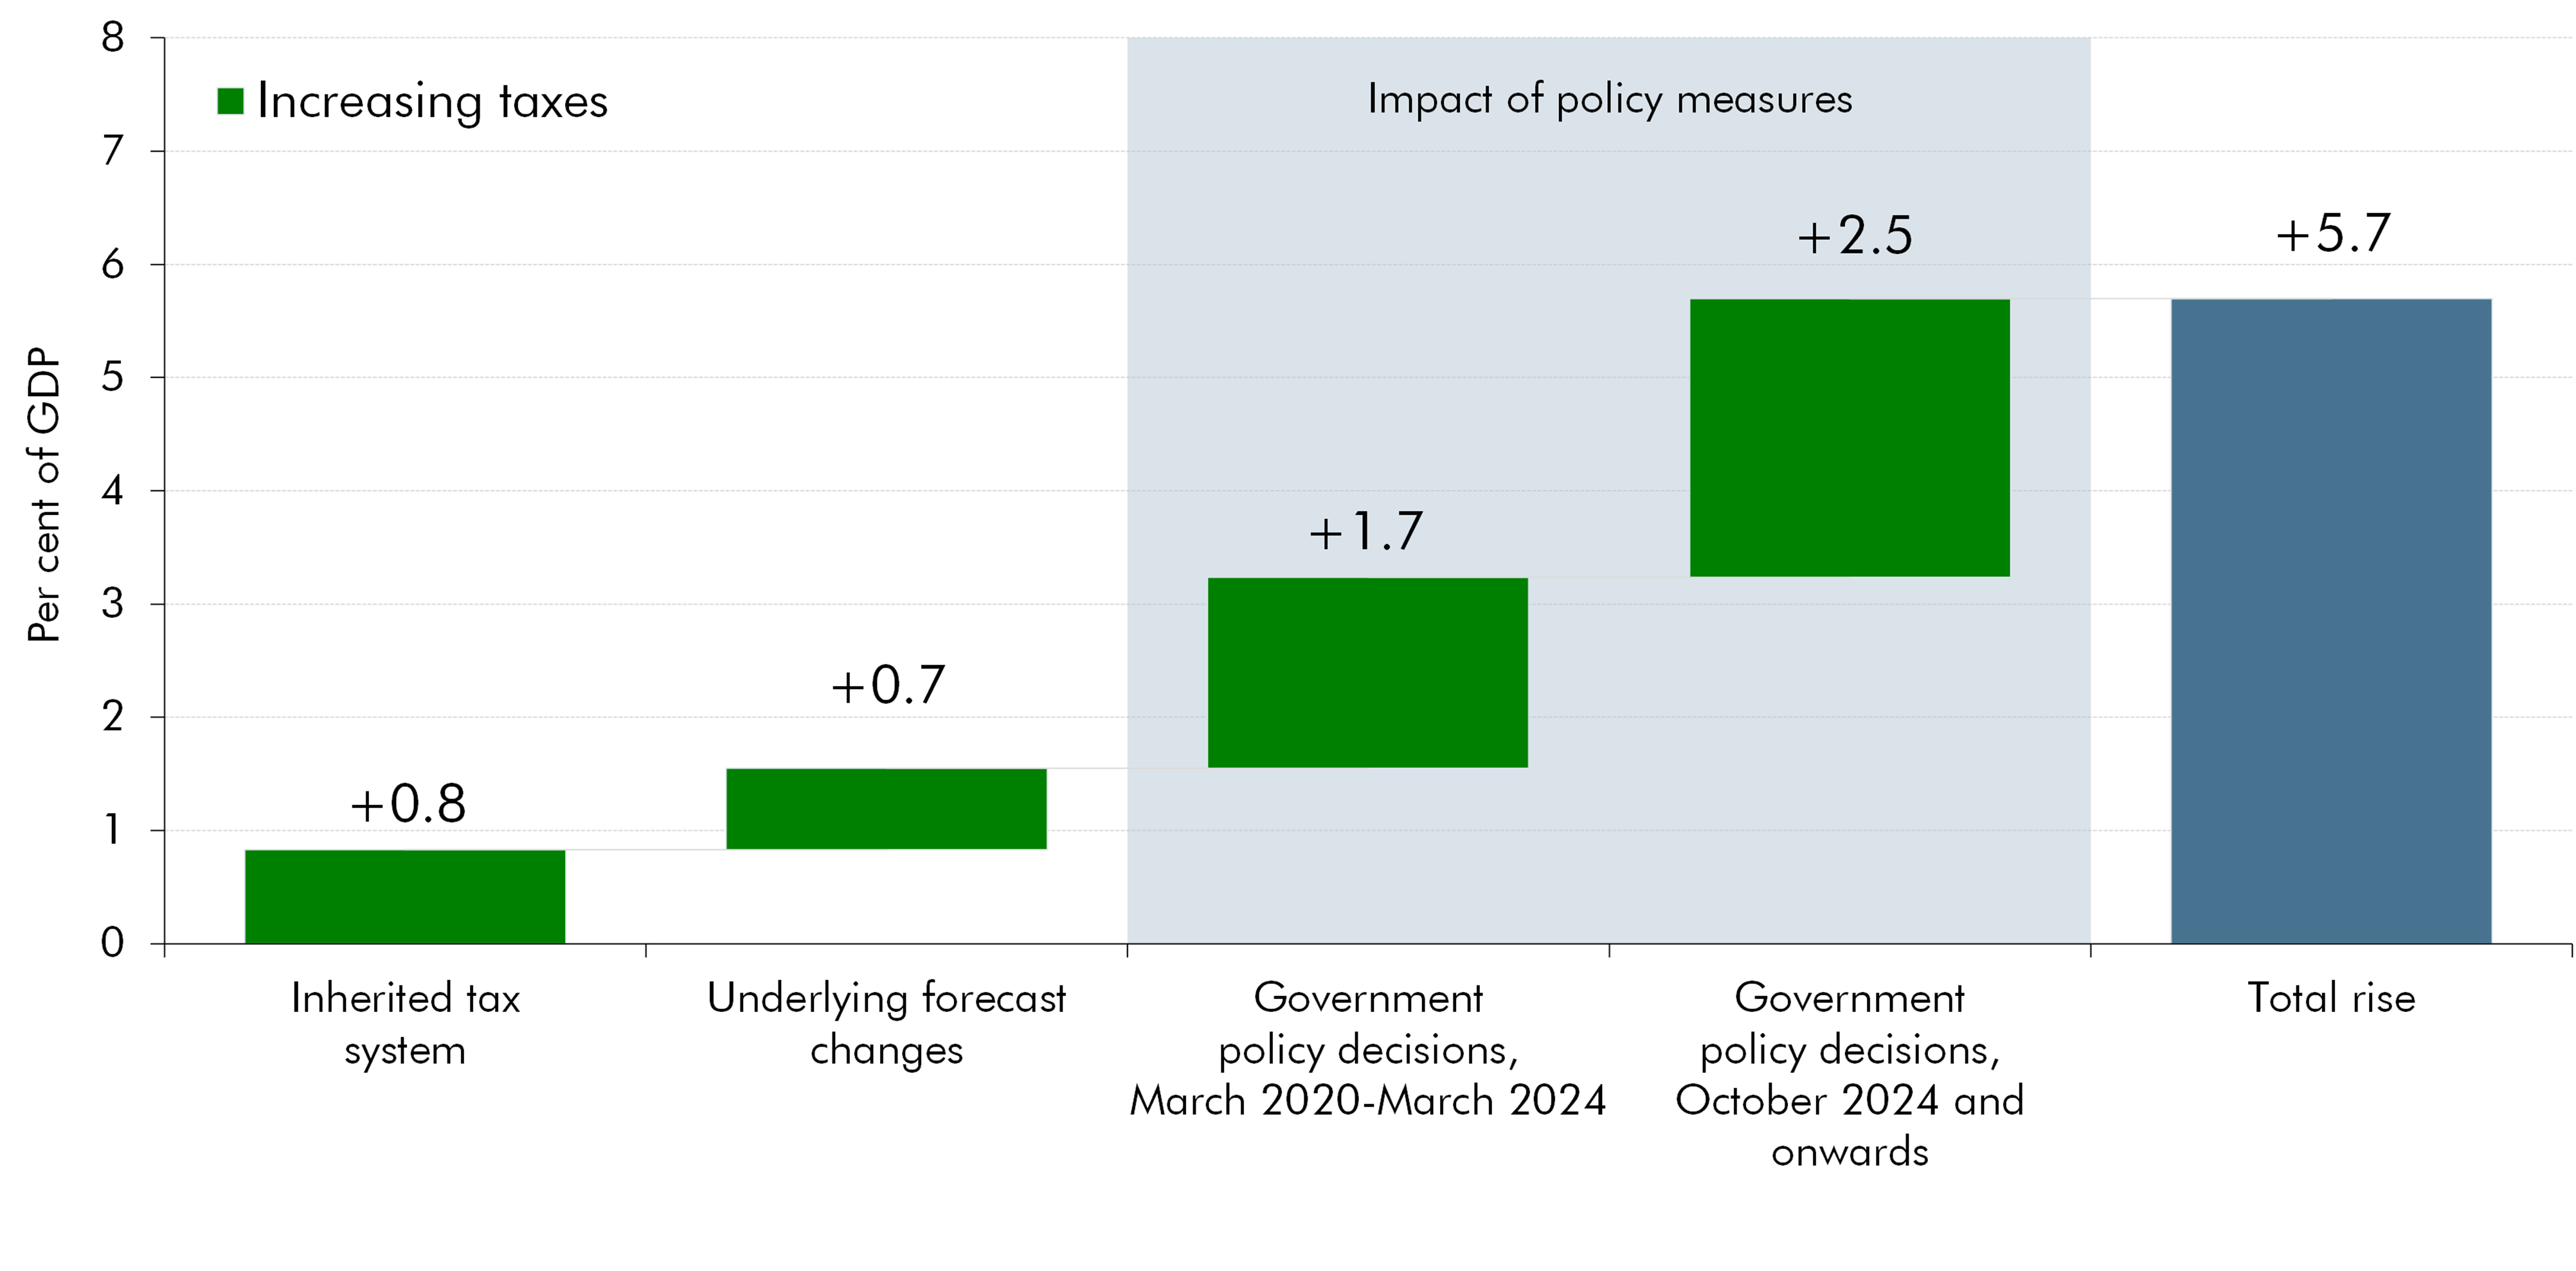
Note: ‘October 2024 and onwards’ incorporates Government policy decisions that were made between March and October 2024.
Source: ONS, OBR
4.6 Chart 4.4 illustrates the sensitivity of the receipts forecast to some of the key drivers of expected receipts growth using ready reckoners. The chart shows the impact of assuming that the level of average earnings, nominal consumption and equity prices are higher or lower than our central forecast by their median absolute forecast difference in each year.[footnote 37] By 2031-32, this would mean the levels of nominal earnings and consumption, two of the largest tax bases, are around 6 per cent higher or lower than in the central forecast, and equity prices around 10 per cent higher or lower. Additionally, we assume in the downside sensitivity that the tax gap remains flat as a share of GDP from 2024-25,[footnote 38] and in the upside sensitivity that it falls as a share of GDP by double the rate in our central forecast.
4.7 The left panel shows the overall impact on public sector receipts of these upside and downside sensitivities relative to the central forecast, and the right panel decomposes this impact by economic and fiscal variables:
-
In the upside sensitivity, receipts are higher by £82 billion (2.2 per cent of GDP) in 2031-32.[footnote 39] The largest driver is the impact of higher nominal earnings on income tax and NICs, boosting receipts by £50 billion in 2031-32, while higher equity prices increase capital taxes, onshore corporation tax, self-assessed income tax and interest and dividend receipts by £12 billion. Higher nominal consumption increases VAT receipts by around £10 billion in 2031-32. The narrowing of the tax gap raises receipts by around £10 billion.
-
In the downside analysis, receipts are lower by a symmetric amount, reducing receipts by £82 billion (2.2 per cent of GDP) in the final year.
Chart 4.4: Sensitivity of receipts to key economic drivers and the tax gap
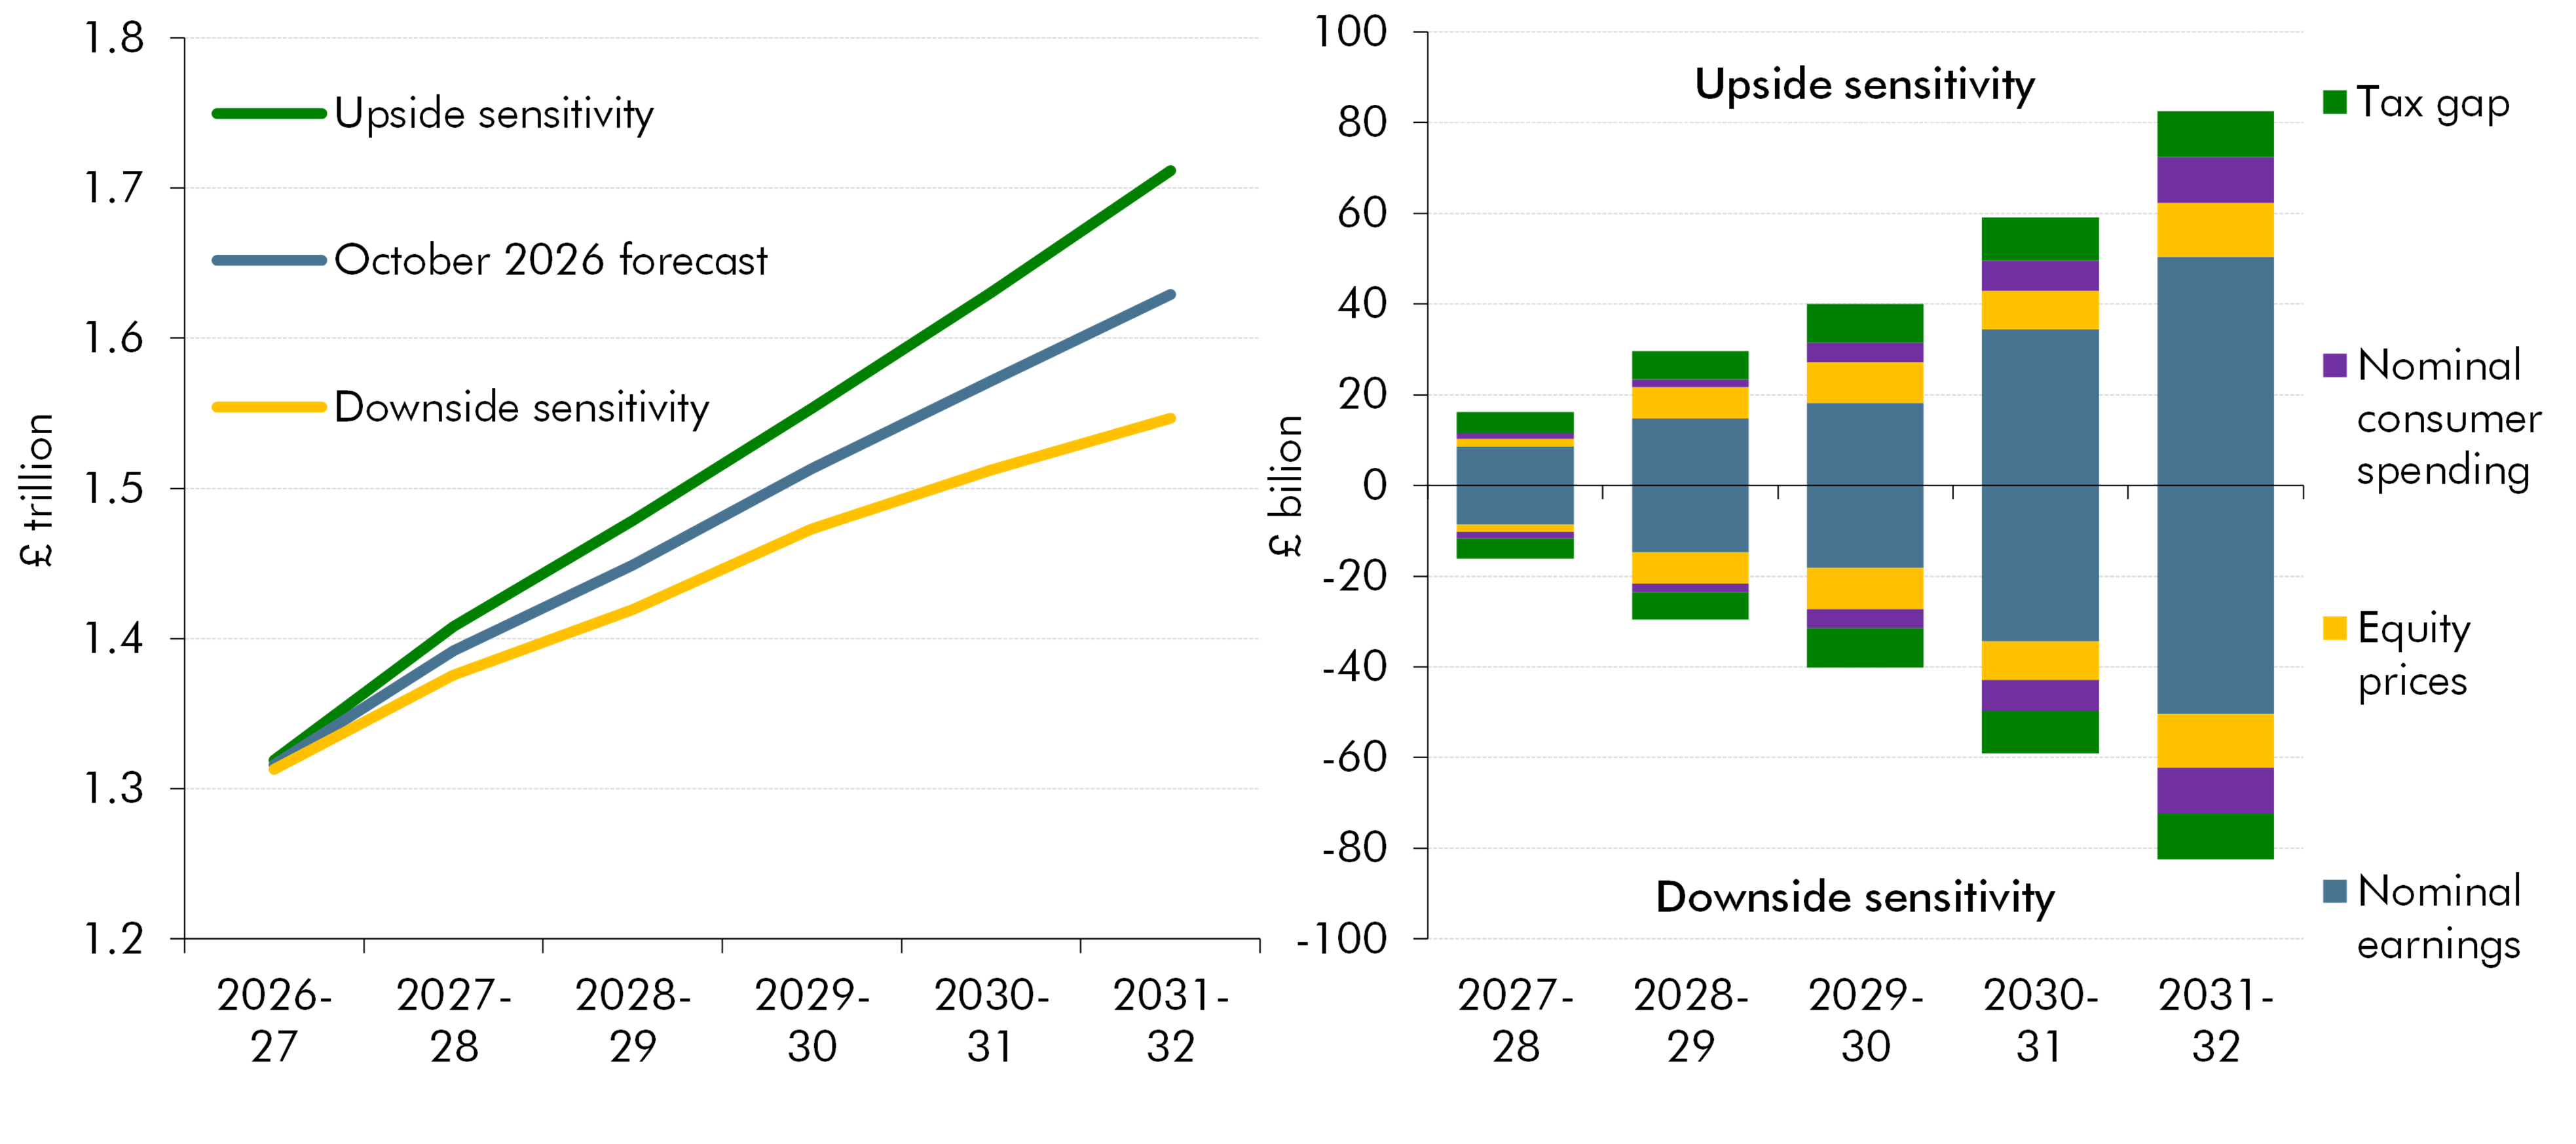
Source: HMRC, ONS, OBR
Changes in receipts since the March 2026 forecast
4.8 Table 4.2 shows that in the central forecast, receipts in nominal terms are expected to be £12 billion higher in 2026-27 than in the March 2026 forecast, with the difference rising to £20 billion in 2030-31. This is primarily driven by:
-
Underlying forecast differences, which increase receipts by £14 billion by 2030-31, due to stronger-than-expected in-year receipts outturn and stronger forecast growth in profits, nominal earnings and equity prices (discussed further in paragraph 4.9 below);
-
PSNB-neutral forecast differences, which are offset in spending, including changes to depreciation, VAT refunds and environmental levies, which increase receipts by £1.4 billion in 2030-31;
-
The direct effect of Government decisions announced since the March 2026 forecast including in this Budget, which reduces receipts by £1.7 billion in 2026-27 but increases receipts by £6.6 billion in 2030-31. This is mostly due to near-term tax reductions on VAT on domestic electricity and business rates, and further delays to the rise in the fuel duty rate, that are later offset by measures boosting self-assessed income tax, including the modernisation of the distributions framework, and the increase to savings and property income tax rates;
-
The indirect effects of Government decisions announced in this Budget, which lower receipts by £2.1 billion in 2030-31, partly due to a small negative effect on nominal GDP including from some measures reducing the GDP deflator.
Table 4.2: Receipts: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| March 2026 forecast | 1,235 | 1,304 | 1,375 | 1,427 | 1,492 | 1,551 |
| October 2026 forecast | 1,231 | 1,316 | 1,392 | 1,449 | 1,513 | 1,571 |
| Difference | -3.9 | 12.2 | 16.6 | 21.5 | 21.2 | 20.0 |
| By policy and forecast differences | ||||||
| of which: | ||||||
| Underlying forecast differences(1) | 0.3 | 14.9 | 17.0 | 17.1 | 14.4 | 14.1 |
| PSNB-neutral forecast differences(2) | -4.3 | -0.7 | 0.9 | 2.5 | 2.5 | 1.4 |
| Direct effect of Government decisions | 0.0 | -1.7 | 0.3 | 3.1 | 5.8 | 6.6 |
| Indirect effects of Government decisions | 0.0 | -0.3 | -1.6 | -1.1 | -1.4 | -2.1 |
| By tax head | ||||||
| of which: | ||||||
| Income tax and NICs | -1.7 | 8.5 | 9.5 | 10.2 | 15.6 | 17.4 |
| Value added tax | -0.6 | -2.3 | -1.6 | -1.3 | -1.5 | -2.2 |
| Onshore corporation tax(3) | -0.3 | 5.8 | 5.1 | 7.6 | 8.3 | 8.1 |
| Capital gains tax | 2.5 | 4.8 | 3.7 | 3.5 | 2.2 | 2.8 |
| Stamp duty land tax | -0.3 | -3.2 | -3.5 | -3.7 | -4.2 | -4.2 |
| Oil and gas revenues(4) | 0.0 | 2.6 | 1.9 | 1.7 | 1.1 | 0.3 |
| Interest and dividend receipts | -0.4 | 0.7 | 3.3 | 3.1 | 0.9 | 0.0 |
| PSNB-neutral receipts | -4.3 | -0.8 | 0.4 | 2.5 | 2.1 | 0.5 |
| Public corporations’ trading surplus | 0.3 | -1.7 | -1.5 | -1.8 | -1.5 | -1.3 |
| Other receipts | 0.8 | -2.2 | -0.6 | -0.2 | -1.8 | -1.2 |
| Memo: changes in receipts ex PSNB-neutral | 0.3 | 12.9 | 16.2 | 19.1 | 19.2 | 19.5 |
| 1) Excludes PSNB-neutral forecast changes. |
| 2) Pre-measures basis, includes depreciation, VAT refunds, most environmental levies, extended producer responsibility, community infrastructure levy, and council tax. |
| 3) Includes Pillar 2 taxes. |
| 4) Offshore corporation tax, petroleum revenue tax, and energy profits levy. |
| Source: ONS, OBR |
4.9 Chart 4.5 shows changes in the nominal receipts forecast compared to March 2026, split into the contributions due to changes to the pre-measures economy forecast, receipts outturn data, and policy changes. Higher forecasts for nominal profits and nominal earnings are the largest drivers – increasing pre-measures receipts by £10 billion and £9 billion, respectively, in 2030-31 compared to the March forecast. Other economic drivers include stronger-than-expected equity price growth which raises the forecast by £3 billion in 2030-31, and slightly weaker expected employee numbers which reduce it by an almost equivalent amount. Stronger-than-expected PAYE income tax and NICs outturn receipts so far this year increase the forecast by £4.2 billion in 2031-32, while weaker outturn for stamp duty land tax reduces it by £3.3 billion.
Chart 4.5: Receipts: drivers of the change since March
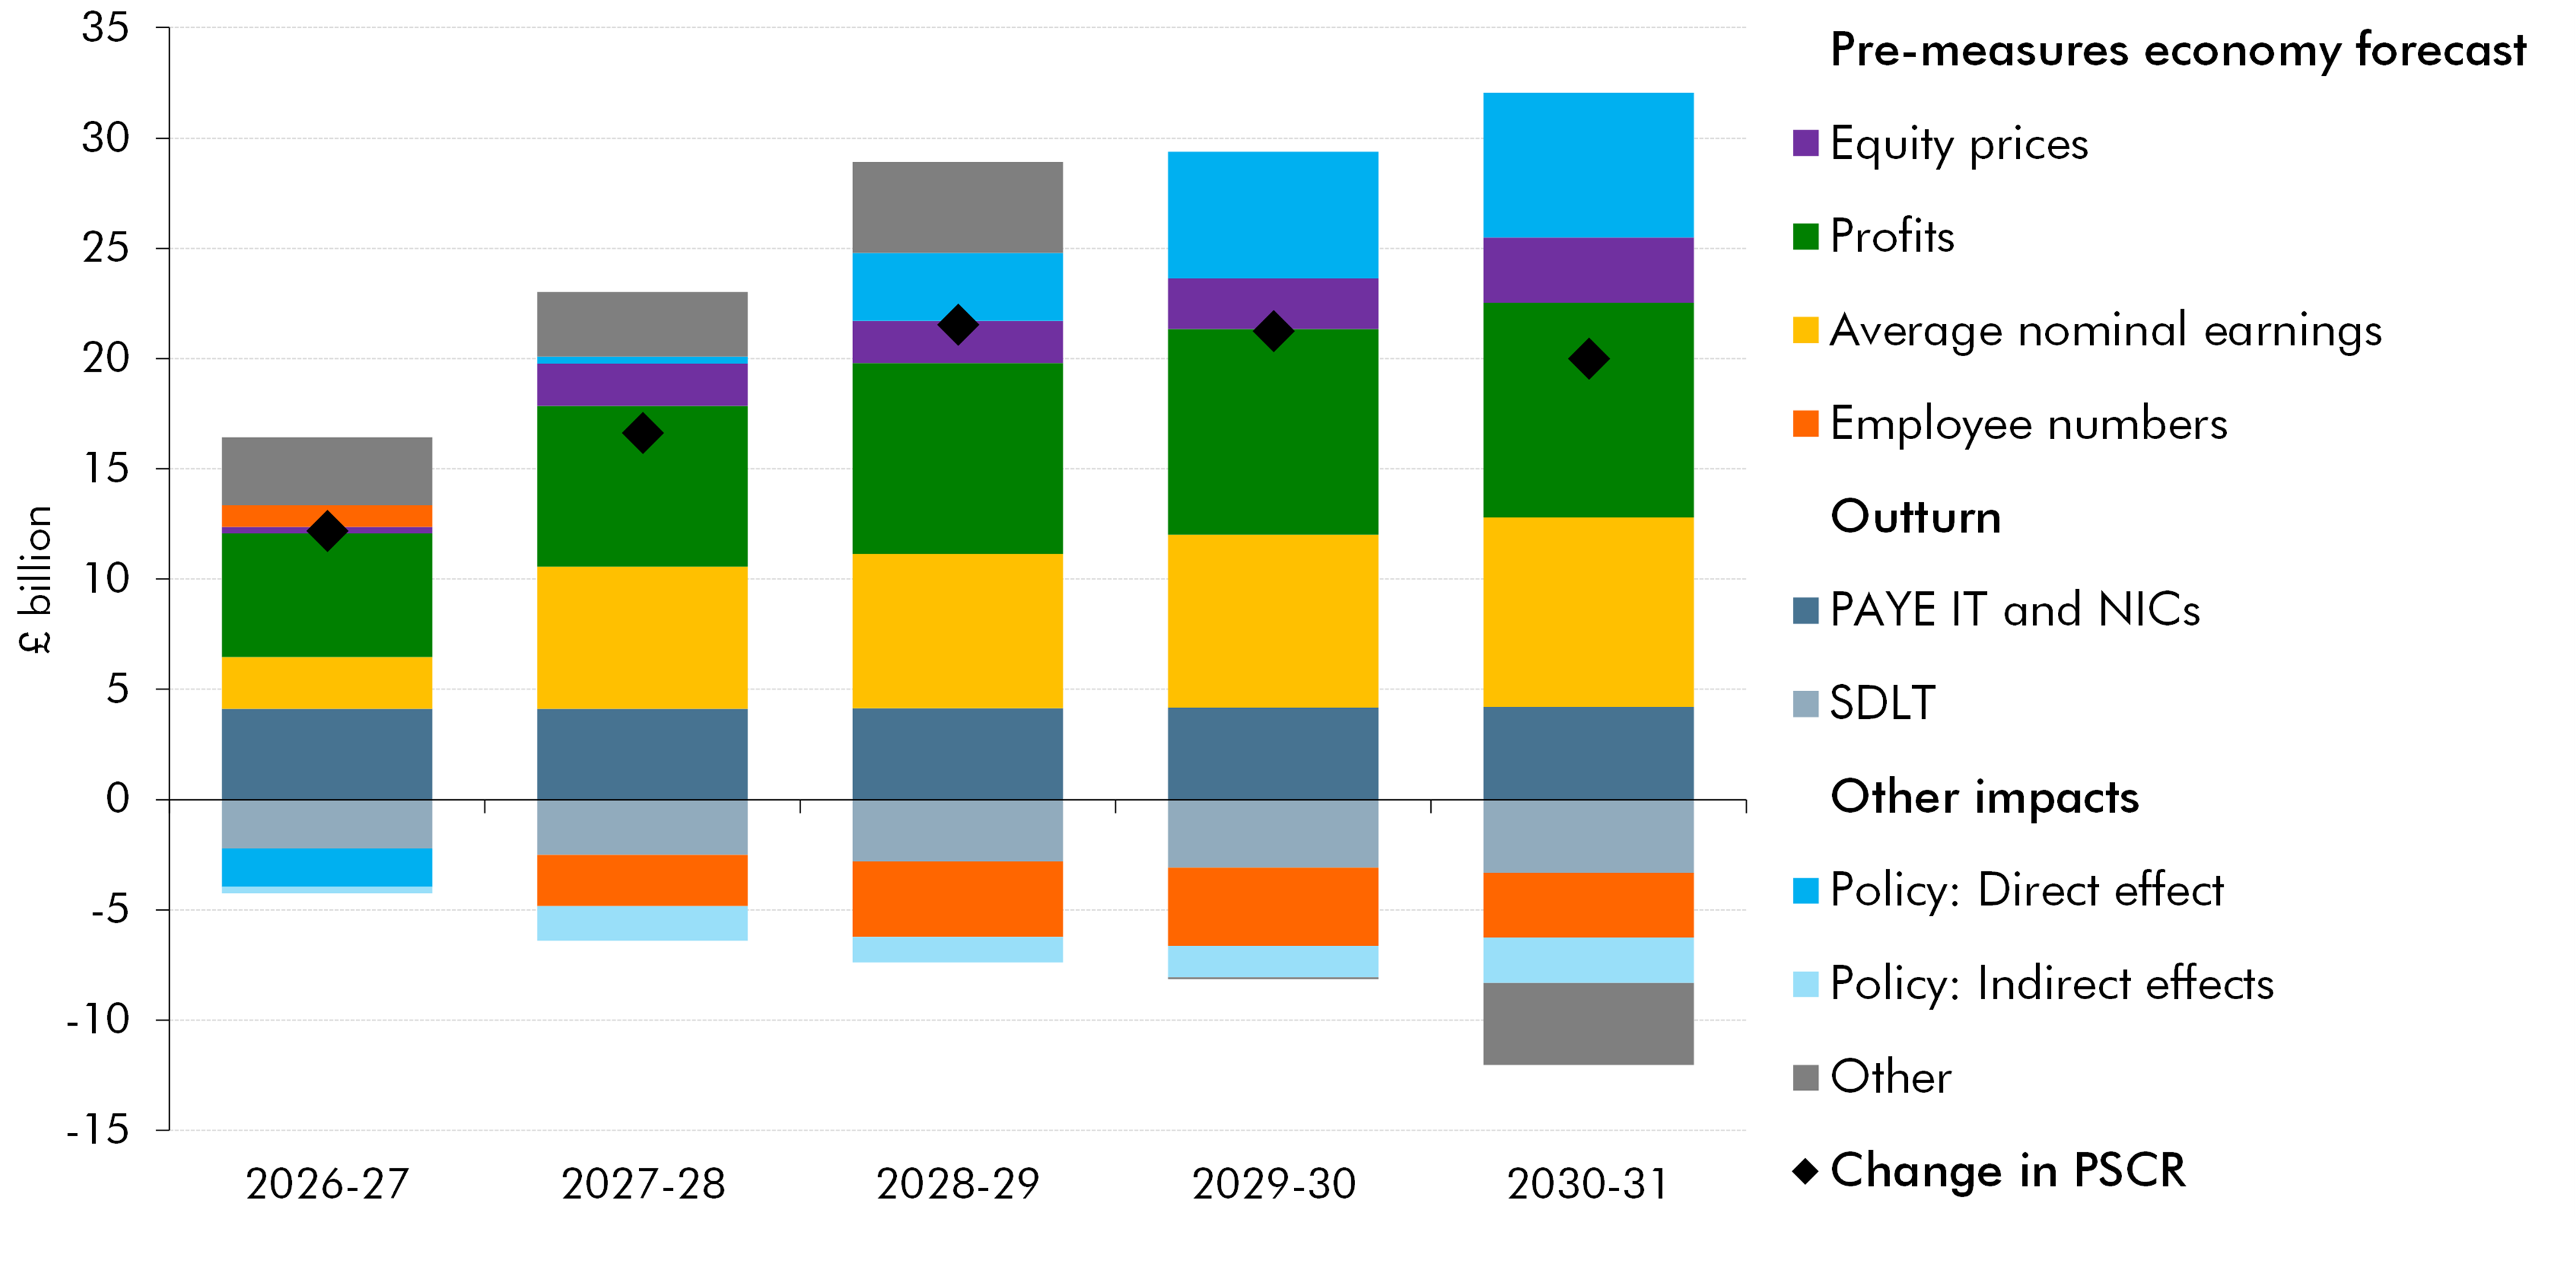
Source: OBR
Note: ‘Pre-measures economy forecast’ refers to changes in economy variables before the impact of policy, discussed further in Chapter 2. ‘Outturn’ refers to the difference against our March 2026 forecast in the final outturn data included in our pre-measures forecast as set out in the Foreword.
4.10 HMRC cash outturn receipts for 2026-27, received up to August 2026 which is the final outturn data included in our pre-measures forecast, were £3 billion above the profile consistent with our March forecast for 2026-27. The latest data up to September 2026 – received after closing the pre-measures forecast – show this has increased to £7 billion against the March profile. This is likely to primarily reflect the stronger-than-expected growth in nominal earnings and profits so far this year.[footnote 40]
4.11 In this forecast we expect public sector current receipts for the full year of 2026-27 to be £12 billion higher than forecast in March, which remains broadly consistent with the latest September cash receipts. Income tax (excluding self-assessed), NICs and onshore corporation tax receipts are expected to remain stronger than in our March forecast through the rest of the year as is the case in the September data. As outlined in Box 4.1, oil and gas revenues, which have been lower than expected up to August, are expected to recover in the remainder of the year due to the higher oil and gas prices. CGT receipts, mainly received in January 2027, are expected to be £5 billion higher than expected in March, reflecting an updated assessment of the strength in receipts seen in 2025-26 (paragraph 4.33). However, CGT receipts are typically volatile from year to year, so this is a particularly uncertain part of the in-year forecast.
4.12 Overall receipts in 2026-27 are expected to be relatively backloaded, with relatively more receipts expected in the final three months of 2026-27 than in a usual year. This is partly due to expected receipts from the Temporary Repatriation Facility introduced alongside reforms to the previous non-domiciled tax regime. As we set out when these reforms were announced, the estimated yield from this policy is highly uncertain.
Tax-by-tax analysis
Income tax (excluding self-assessed) and National Insurance contributions
4.13 Income tax (excluding self-assessed) and National Insurance contributions (NICs) are forecast to raise £520 billion (16.2 per cent of GDP) in 2026-27, a 7.6 per cent increase from 2025-26. This rise is driven by strong nominal earnings growth combining with frozen tax thresholds. Receipts are then forecast to rise to £610 billion (16.5 per cent of GDP) in 2030-31, before remaining broadly flat as a share of GDP in 2031-32 as thresholds return to being uprated by CPI from April 2031. Almost all of this growth comes from higher PAYE income tax because it is a more progressive tax than NICs, and is therefore boosted by the freezes to tax thresholds. A further temporary increase is expected to income tax receipts between 2026-27 and 2028-29 due to the Temporary Repatriation Facility announced as part of previous reforms to the non-domiciled regime.
4.14 Budget 2025 extended the allowances and threshold freezes in income tax and NICs to April 2031, meaning the majority will be frozen for most of the 2020s. This increases the sensitivity of the receipts forecast to nominal earnings changes through ‘fiscal drag’. Using our standard ready reckoners, a 1 percentage point increase in nominal earnings and CPI would raise income tax and NICs receipts by an average of £7 billion a year under the current policy of frozen thresholds to April 2031. This is around £2.5 billion a year higher than if thresholds were increasing with CPI, reflecting the additional fiscal drag generated.[footnote 41] This is also likely to have an adverse effect on financial work incentives by increasing the marginal tax rate on each additional hour of work. Following our standard approach, we have estimated that, taken together, the threshold freezes in income tax and NICs from 2022-23 to 2030-31 could decrease labour supply by 215,000 in average-hours equivalent (AHE) terms by 2030-31.[footnote 42]
4.15 Table 4.3 shows that relative to the March forecast, non-SA income tax and NICs receipts are expected to be £9 billion higher in 2026-27. This reflects the higher-than-expected PAYE receipts received so far this year, which has likely been driven by nominal earnings slowing by less than expected compared with the March forecast. Nominal earnings growth has been particularly strong in the public sector, in part due to the earlier timing of pay awards compared with previous years that may have boosted receipts against our previously assumed profile for receipts in 2026-27. Over the rest of the forecast, receipts are expected to be £8 billion higher, on average, than expected in March. This is driven by the higher outturn this year and a higher forecast for nominal earnings growth next year, which are only partly offset by a weaker forecast for the number of employees and the effects of Government decisions in 2029-30 and 2030-31.
4.16 The main effect of Budget policy decisions is through the measure to introduce timely payment for self-assessment and part reversal of the Budget 2025 measure that mandated coding out via the PAYE system, explained in more detail in paragraph 3.13. This transfers receipts from PAYE to SA IT that were previously associated with the coding out measure. The indirect effects of policy decisions have a very small downward impact on receipts in most years.
Table 4.3: Non-SA income tax and NICs: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| March 2026 forecast | 479.6 | 506.8 | 532.4 | 547.4 | 575.1 | 599.6 |
| October 2026 forecast | 479.7 | 516.3 | 541.0 | 555.2 | 582.3 | 606.2 |
| Difference | 0.1 | 9.4 | 8.5 | 7.8 | 7.2 | 6.6 |
| of which: | ||||||
| Pre-measures forecast changes | 9.5 | 8.8 | 8.1 | 9.8 | 11.7 | |
| of which: | ||||||
| Changes to earnings forecast | 2.3 | 6.4 | 7.0 | 7.8 | 8.6 | |
| Calibration to outturn | 4.1 | 4.1 | 4.1 | 4.2 | 4.2 | |
| Changes to employee numbers forecast | 1.0 | -2.3 | -3.4 | -3.6 | -2.9 | |
| Other | 2.0 | 0.5 | 0.3 | 1.3 | 1.8 | |
| Direct effect of Government decisions | 0.0 | -0.1 | -0.4 | -2.5 | -4.9 | |
| Indirect effects of Government decisions | 0.0 | -0.2 | 0.1 | -0.1 | -0.2 |
| Source: ONS, OBR |
Self-assessed income tax
4.17 Self-assessed income tax (SA IT) is forecast to raise £63 billion in 2026-27 (2.0 per cent of GDP), a 17.2 per cent increase on 2025-26. This sharp increase compared to 2025-26 is driven by the previously announced reforms to the non-domiciled tax regime, which are expected to generate additional receipts from this year onwards, the personal tax threshold freezes, and forecast growth in self-employment and dividend income. Receipts are then forecast to rise to £94 billion (2.5 per cent of GDP) in 2031-32, driven by further expected receipts from the non-domiciled tax regime reforms, the reclassification of carried interest into SA IT from CGT, and policy measures announced at this Budget.
4.18 Table 4.4 shows that compared to March, SA IT receipts are £1.0 billion lower in 2026-27 but higher thereafter by increasing amounts, peaking at £11 billion in 2030-31. The pre-measures forecast changes reflect a stronger profits forecast boosting dividend income, and the impact of higher equity prices on the carried interest forecast. The main effect of Budget policy is through the measure to introduce timely payment for self-assessment. This is estimated to increase accrued SA IT receipts by £3.5 billion in 2029-30 and £6.5 billion in 2030-31. This is partly offset by reductions in PAYE IT receipts, outlined above, which lower the total net yield of the measure by around two-thirds in each year. This measure is expected to increase cash SA IT receipts by around £21 billion in 2029-30, only partly offset by a reduction of around £5 billion in PAYE IT cash receipts. Paragraph 3.25 provides further detail on the accounting treatment of this measure. The modernisation of the distributions framework is estimated to increase SA IT receipts by around £2 billion in 2029-30 and 2030-31, partially offset by the expected reduction in CGT receipts from this measure. The increase to savings and property tax rates is estimated to increase SA IT receipts by an average of £0.8 billion a year from 2028-29.
Table 4.4: SA income tax: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| March 2026 forecast | 55.9 | 64.4 | 71.1 | 74.7 | 76.3 | 77.0 |
| October 2026 forecast | 54.1 | 63.4 | 72.0 | 77.2 | 84.7 | 87.7 |
| Difference | -1.8 | -1.0 | 0.9 | 2.4 | 8.4 | 10.8 |
| of which: | ||||||
| Pre-measures forecast changes | -1.0 | 1.1 | 1.8 | 2.1 | 1.7 | |
| Direct effect of Government decisions | 0.0 | -0.1 | 0.7 | 6.4 | 9.1 | |
| of which: | ||||||
| Timely payment for self assessment | 0.0 | 0.0 | 0.0 | 3.5 | 6.5 | |
| Modernisation of distributions framework | 0.0 | 0.0 | 0.0 | 2.1 | 1.9 | |
| Changes to savings and property tax rates | 0.0 | 0.0 | 1.0 | 0.8 | 0.8 | |
| Other | 0.0 | -0.1 | -0.3 | 0.0 | 0.0 | |
| Indirect effects of Government decisions | 0.0 | 0.0 | -0.1 | -0.1 | -0.1 |
| Source: ONS, OBR |
VAT
4.19 VAT receipts are forecast to raise £186 billion in 2026-27 (5.9 per cent of GDP), a 3.3 per cent increase from 2025-26. Receipts are then expected to rise to £230 billion by 2031-32 (6.0 per cent of GDP). The modest rise in VAT as a share of GDP over the forecast reflects the assumption that non-compliance will reduce over the forecast period, and that temporary VAT policies such as the zero-rating of VAT on domestic electricity will end.
4.20 As shown in Table 4.5, in the pre-measures forecast, receipts have been revised down by £1.2 billion in 2026-27 compared to March. Around a third of this is from an adjustment to reflect the September 2025 Tribunal verdict that locum doctors are VAT exempt and can reclaim overpayments backdated up to four years. Another third reflects reduced receipts due to some private hire vehicle operators (PHVOs) changing their business models outside London since the Budget 2025 decision to charge VAT on PHVOs. Over the rest of the forecast, pre-measures VAT receipts are lower in each year compared to March and are forecast to be £2.9 billion lower by 2030-31, largely due to a reduction in the proportion of goods and services assumed to be paying the standard rate of VAT.
4.21 The direct effect of policy measures announced at this Budget initially reduce VAT receipts by £1 billion over 2026-27, largely from temporary zero-rating of VAT on domestic electricity. From 2028-29 onwards, Budget measures increase VAT receipts by £1.1 billion each year. Of this increase, £0.8 billion is from new measures to increase VAT paid by PHVOs and locum doctors, and the extension of VAT online marketplace liability rules, while the rest is largely from measures aimed at reducing non-compliance and collecting tax debt. Further details are provided in Chapter 3. The indirect effects of Budget policies lower VAT receipts in each year.
Table 4.5: VAT: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| March 2026 forecast | 180.9 | 188.7 | 197.8 | 205.8 | 214.7 | 223.8 |
| October 2026 forecast | 180.3 | 186.4 | 196.2 | 204.5 | 213.2 | 221.6 |
| Difference | -0.6 | -2.3 | -1.6 | -1.3 | -1.5 | -2.2 |
| of which: | ||||||
| Pre-measures changes | -1.2 | -1.5 | -2.0 | -2.2 | -2.9 | |
| of which: | ||||||
| Household and government consumption | 1.6 | 1.2 | 0.5 | 0.1 | -0.5 | |
| Calibration to VAT base outturn(1) | -1.2 | -1.3 | -1.4 | -1.5 | -1.7 | |
| Calibration to receipts outturn | -0.3 | -0.5 | -0.5 | -0.5 | -0.5 | |
| Other | -1.3 | -0.9 | -0.6 | -0.3 | -0.1 | |
| Direct effect of Government decisions | -1.0 | 0.2 | 1.1 | 1.1 | 1.1 | |
| Indirect effects of Government decisions | -0.1 | -0.4 | -0.4 | -0.4 | -0.5 |
| 1) Includes updated data on standard-rated splits and illicit tobacco. |
| Source: ONS, OBR |
Onshore corporation tax
4.22 Onshore corporation tax is expected to raise £107 billion (3.4 per cent of GDP) in 2026-27, an increase of 11 per cent from 2025-26. This increase is driven by higher profits in both the non-financial and financial sectors. Receipts are then forecast to rise to £136 billion (3.6 per cent of GDP) by 2031-32. This is mainly driven by the forecast for profits as a share of the economy increasing slightly over the forecast period.
4.23 Table 4.6 shows that relative to March, onshore corporation tax is expected to be £5.8 billion higher in 2026-27 with higher receipts from the financial sector explaining around three-quarters of the upward revision. This reflects higher-than-anticipated profits from both retail and investment banks so far this year and a delay in the effect on receipts from the Financial Conduct Authority’s motor finance compensation scheme, which raises expected receipts by £1.5 billion in 2026-27 and reduces receipts by £1.2 billion in 2027-28.
4.24 Receipts are expected to be £8 billion higher in 2030-31 than forecast in March. The pre-measures forecast is £5.7 billion higher in 2030-31 due to higher receipts this year and a higher forecast recovery in the profit share relative to March (discussed further in paragraph 2.55). This is only partially offset by decreases to the forecast due to the net effect from company tax data updates and modelling changes to estimates of group relief and capital allowances. Budget policies overall increase receipts by £2.3 billion in 2030-31. This includes £1.1 billion from a reduction in the main rate of writing down allowances, £0.7 billion from restrictions to sovereign wealth funds’ and overseas public pension funds’ immunity from direct tax, and £0.5 billion from tighter rules around companies’ ability to use foreign branch losses against UK profits. Further information on these measures is provided in Chapter 3. The indirect effects of Budget policies lower receipts in each year.
Table 4.6: Onshore corporation tax: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| March 2026 forecast | 96.8 | 101.4 | 108.5 | 113.1 | 117.6 | 123.0 |
| October 2026 forecast | 96.5 | 107.2 | 113.6 | 120.7 | 125.9 | 131.1 |
| Difference | -0.3 | 5.8 | 5.1 | 7.6 | 8.3 | 8.1 |
| of which: | ||||||
| Pre-measures change | 5.9 | 4.4 | 6.1 | 6.2 | 5.7 | |
| of which: | ||||||
| Re-profiling motor finance compensation | 1.5 | -1.2 | 0.0 | 0.0 | 0.0 | |
| Profits forecast | 5.1 | 6.5 | 7.7 | 8.1 | 8.4 | |
| Calibration to outturn | 0.4 | 0.8 | 0.8 | 0.7 | 0.7 | |
| Data and modelling revisions | -0.5 | -0.7 | -1.5 | -2.2 | -3.2 | |
| Other | -0.5 | -1.1 | -0.8 | -0.5 | -0.3 | |
| Direct effect of Government decisions | 0.1 | 1.4 | 2.0 | 2.6 | 2.8 | |
| Indirect effects of Government decisions | -0.2 | -0.7 | -0.5 | -0.4 | -0.4 |
| Note: Onshore corporation tax receipts include Pillar 2 taxes and exclude bank surcharge. |
| Source: ONS, OBR |
4.25 Receipts from the bank surcharge, not included in Table 4.6, are expected to raise £2.4 billion in 2027-28. This is an increase of £1.2 billion from 2025-26 and is £1.1 billion higher than expected in the March forecast. This reflects the announcement at this Budget that the rate of the surcharge will increase from 3 per cent to 6 per cent from January 2027 until March 2028. Receipts are then forecast to fall back to £1.6 billion by 2031-32.
Oil and gas receipts
4.26 Offshore corporation tax, petroleum revenue tax (PRT), and the energy profits levy (EPL) are expected to raise £5.1 billion (0.2 per cent of GDP) in 2026-27, a 25 per cent increase on 2025-26 due to higher oil and gas prices. Oil and gas receipts are then expected to fall over the remainder of the forecast, as the recent rises in energy prices are expected to unwind, down to £1.9 billion by 2028-29. Receipts are then forecast to decline further to £0.3 billion in 2030-31 and close to zero in 2031-32, primarily due to the expiry of the EPL in September 2029 and the expected continued fall in oil and gas production.
4.27 These forecasts are based on the North Sea Transition Authority’s (NSTA) projection for total oil and gross gas production, shown in Chart 4.6. This shows that production has been declining since the start of the 2000s and that this decline is expected to continue at around 10 per cent a year over 2027 to 2031. The projection includes production from currently producing fields (including Jackdaw), and the NSTA’s estimate of production from development of new fields, which includes Rosebank, and from future discoveries.[footnote 43] The forecast annual pace of decline would be around 14 per cent a year if there were no production from any new fields.
Chart 4.6: UK oil and gas production
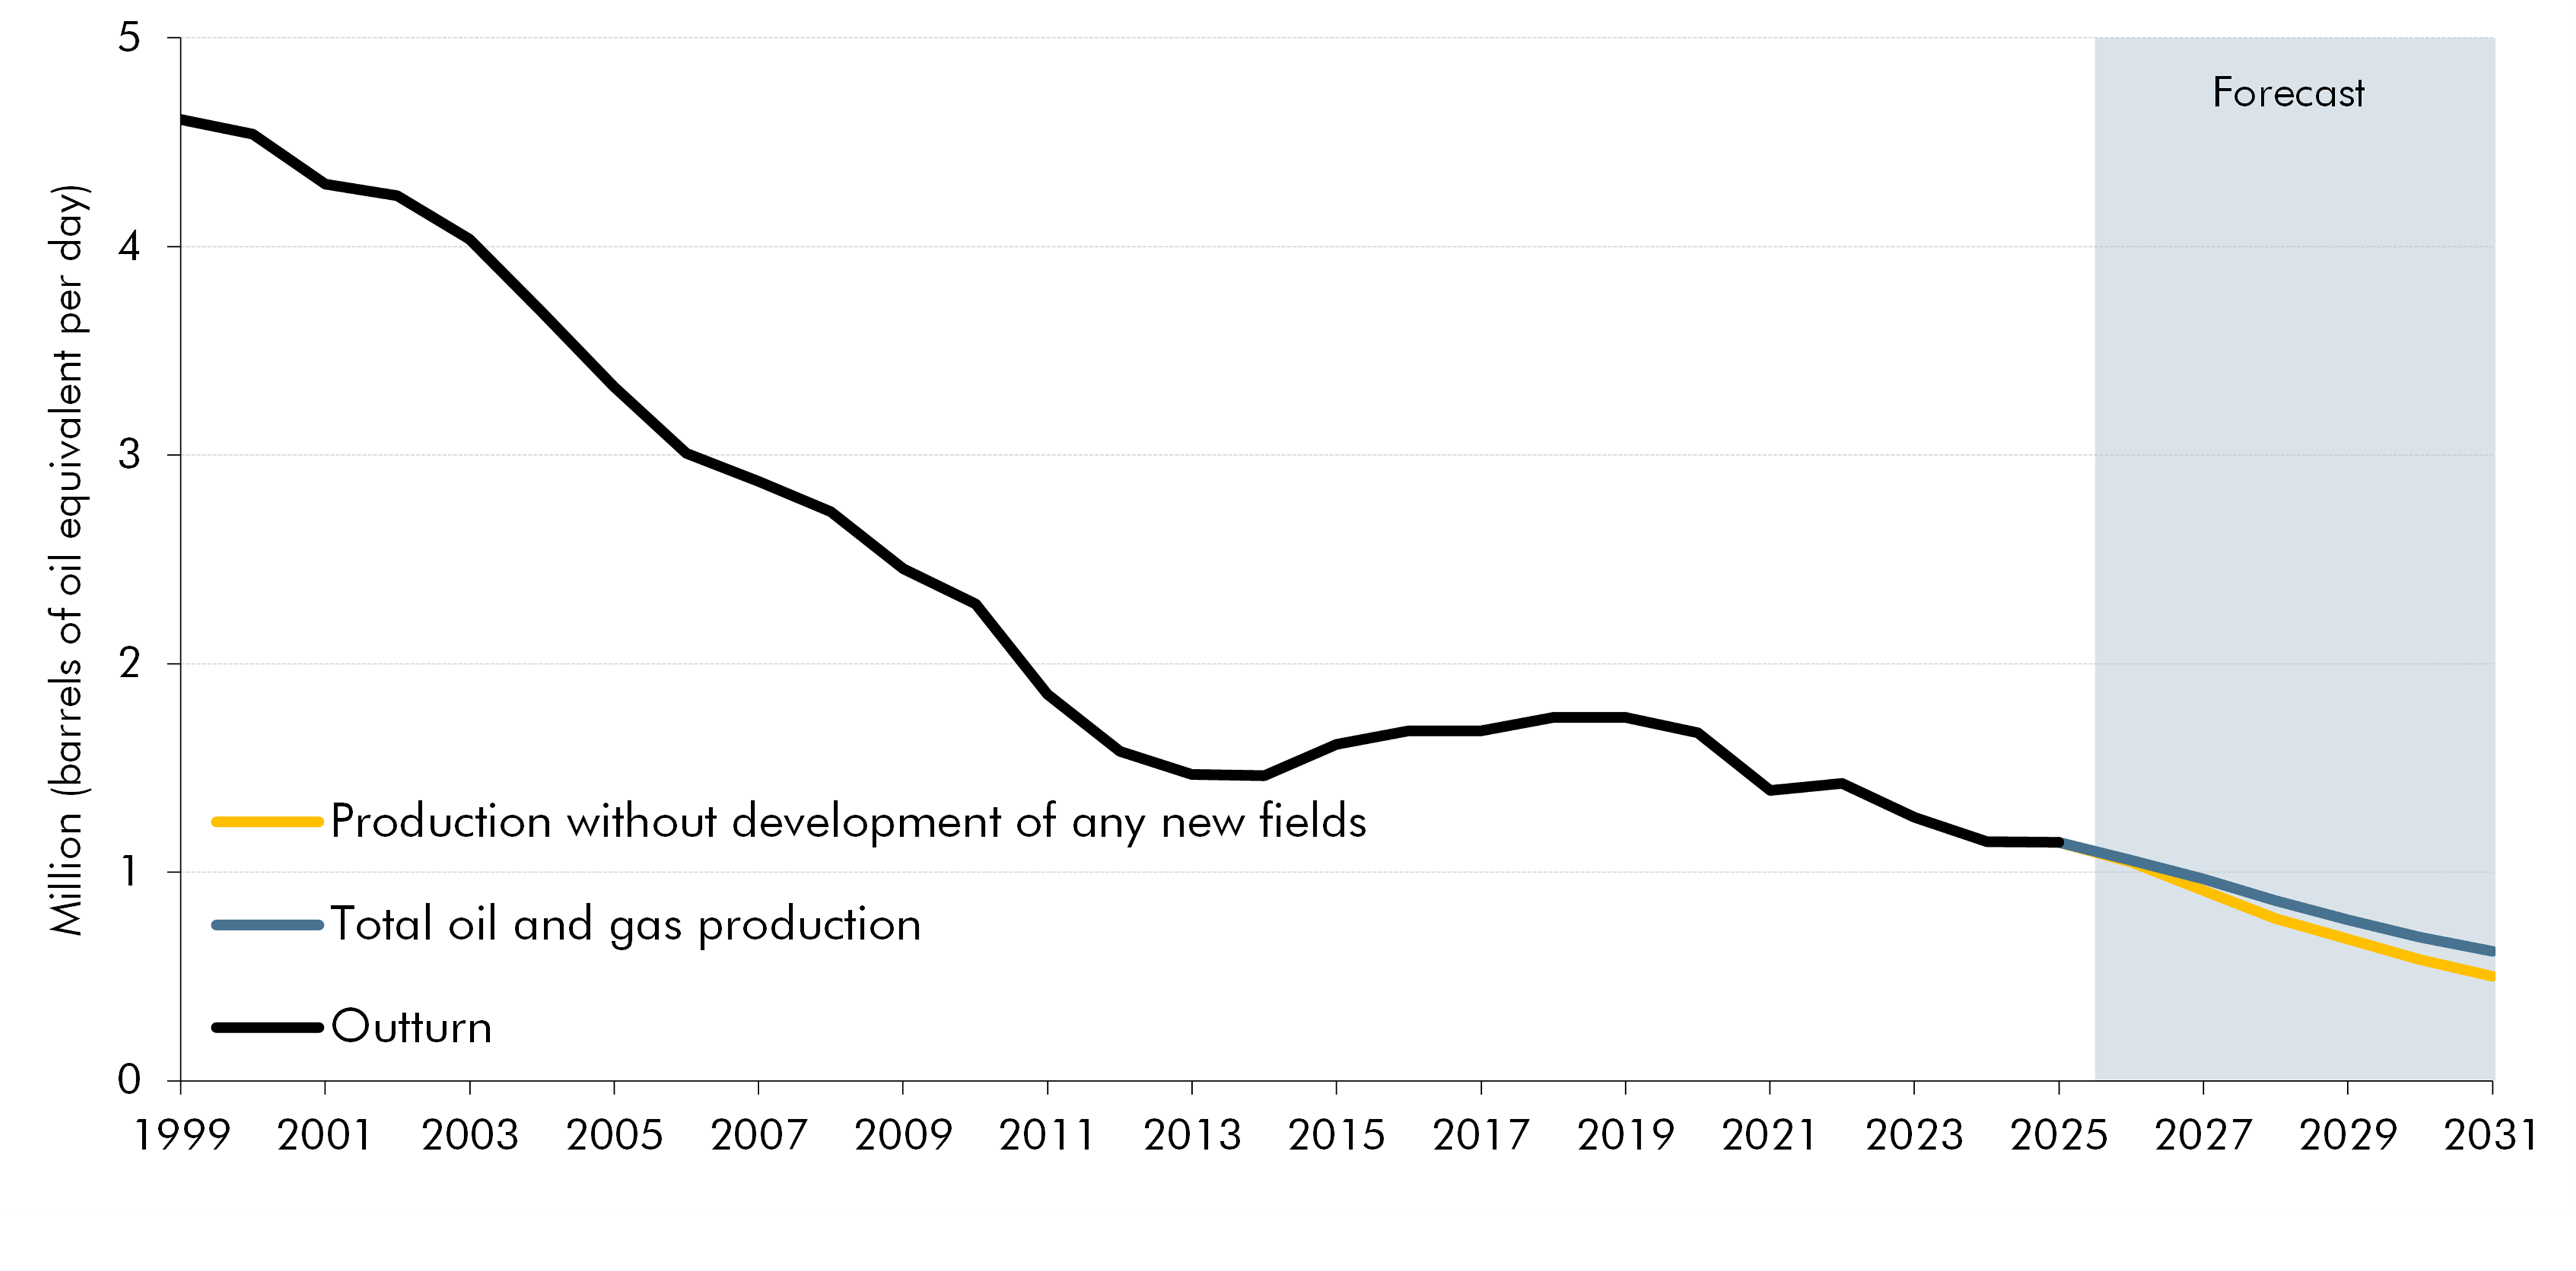
Source: NSTA, OBR
4.28 Relative to our March forecast, oil and gas receipts are expected to be £2.6 billion higher in 2026-27, largely due to significantly higher oil and gas prices. However, the increase has been partly offset by the latest assessment of the impact on receipts of mergers and acquisitions (M&A) activity, described in Box 4.1. Receipts from the energy profits levy are now expected to be £9 billion in total between 2026-27 and 2030-31, up from £2.5 billion at the March forecast. The EPL is now expected to remain in place until September 2029, when the Energy Security Investment Mechanism (ESIM) is expected to trigger based on anticipated average oil and gas prices. This is two years later than in the March forecast.
Box 4.1: The impact of mergers and acquisitions on oil and gas revenues
Recent merger activity by firms operating in the UK continental shelf has resulted in companies with a large stock of tax losses combining operations with tax-paying companies, allowing greater use of losses against taxable profits. The 2021 to 2023 period saw expansion of larger and mid-sized oil and gas companies, outside of the major international groups. Since 2024, several of these companies have merged with portfolios held by major international companies.
The impact of this activity was a key factor behind the downward revision to our November 2025 forecast for offshore corporation taxa and in this forecast has muted the upward impact on receipts this year of higher oil and gas prices. Our tax forecasts are generated by HMRC’s North Sea microsimulation model, which captures M&A activity by combining information on company ownership of fields and tax returns data. The mergers in 2025 and 2026 had a similar pattern of dampening the receipts forecasts in both this and the November 2025 forecast, largely through making the stock of historical losses more readily accessible to profitable companies.
The left panel of Chart A shows the impact on losses used of the mergers incorporated at this forecast. The blue bars show the change in losses used due to recently completed mergers, which increase by a net £2.7 billion between 2026 and 2031. The frontloaded pattern reflects the assumption that, once historical losses become accessible, they are used as quickly as possible. Higher oil and gas prices in the early part of the forecast also generate more profits against which the losses can be used. This frontloading of loss utilisation results in a faster rundown of the stock of outstanding losses, leaving fewer losses available for use in the later years of the forecast.
The forecast also includes an assumption that a further 20 per cent of the stock of losses become accessible from possible future mergers.b The impact of this, shown by the yellow bars, is to increase losses used by £2.2 billion between 2026 and 2031.
The right panel shows the impact on receipts from the greater losses used, which mirrors this pattern, with greater reductions in the early years of the forecast when more losses are available against taxable profits. The net impact between 2026-27 and 2031-32 is a reduction of £1.3 billion from completed mergers and £0.8 billion from the adjustment for future mergers.
Chart A: Impact of M&A activity on losses used and oil and gas receipts
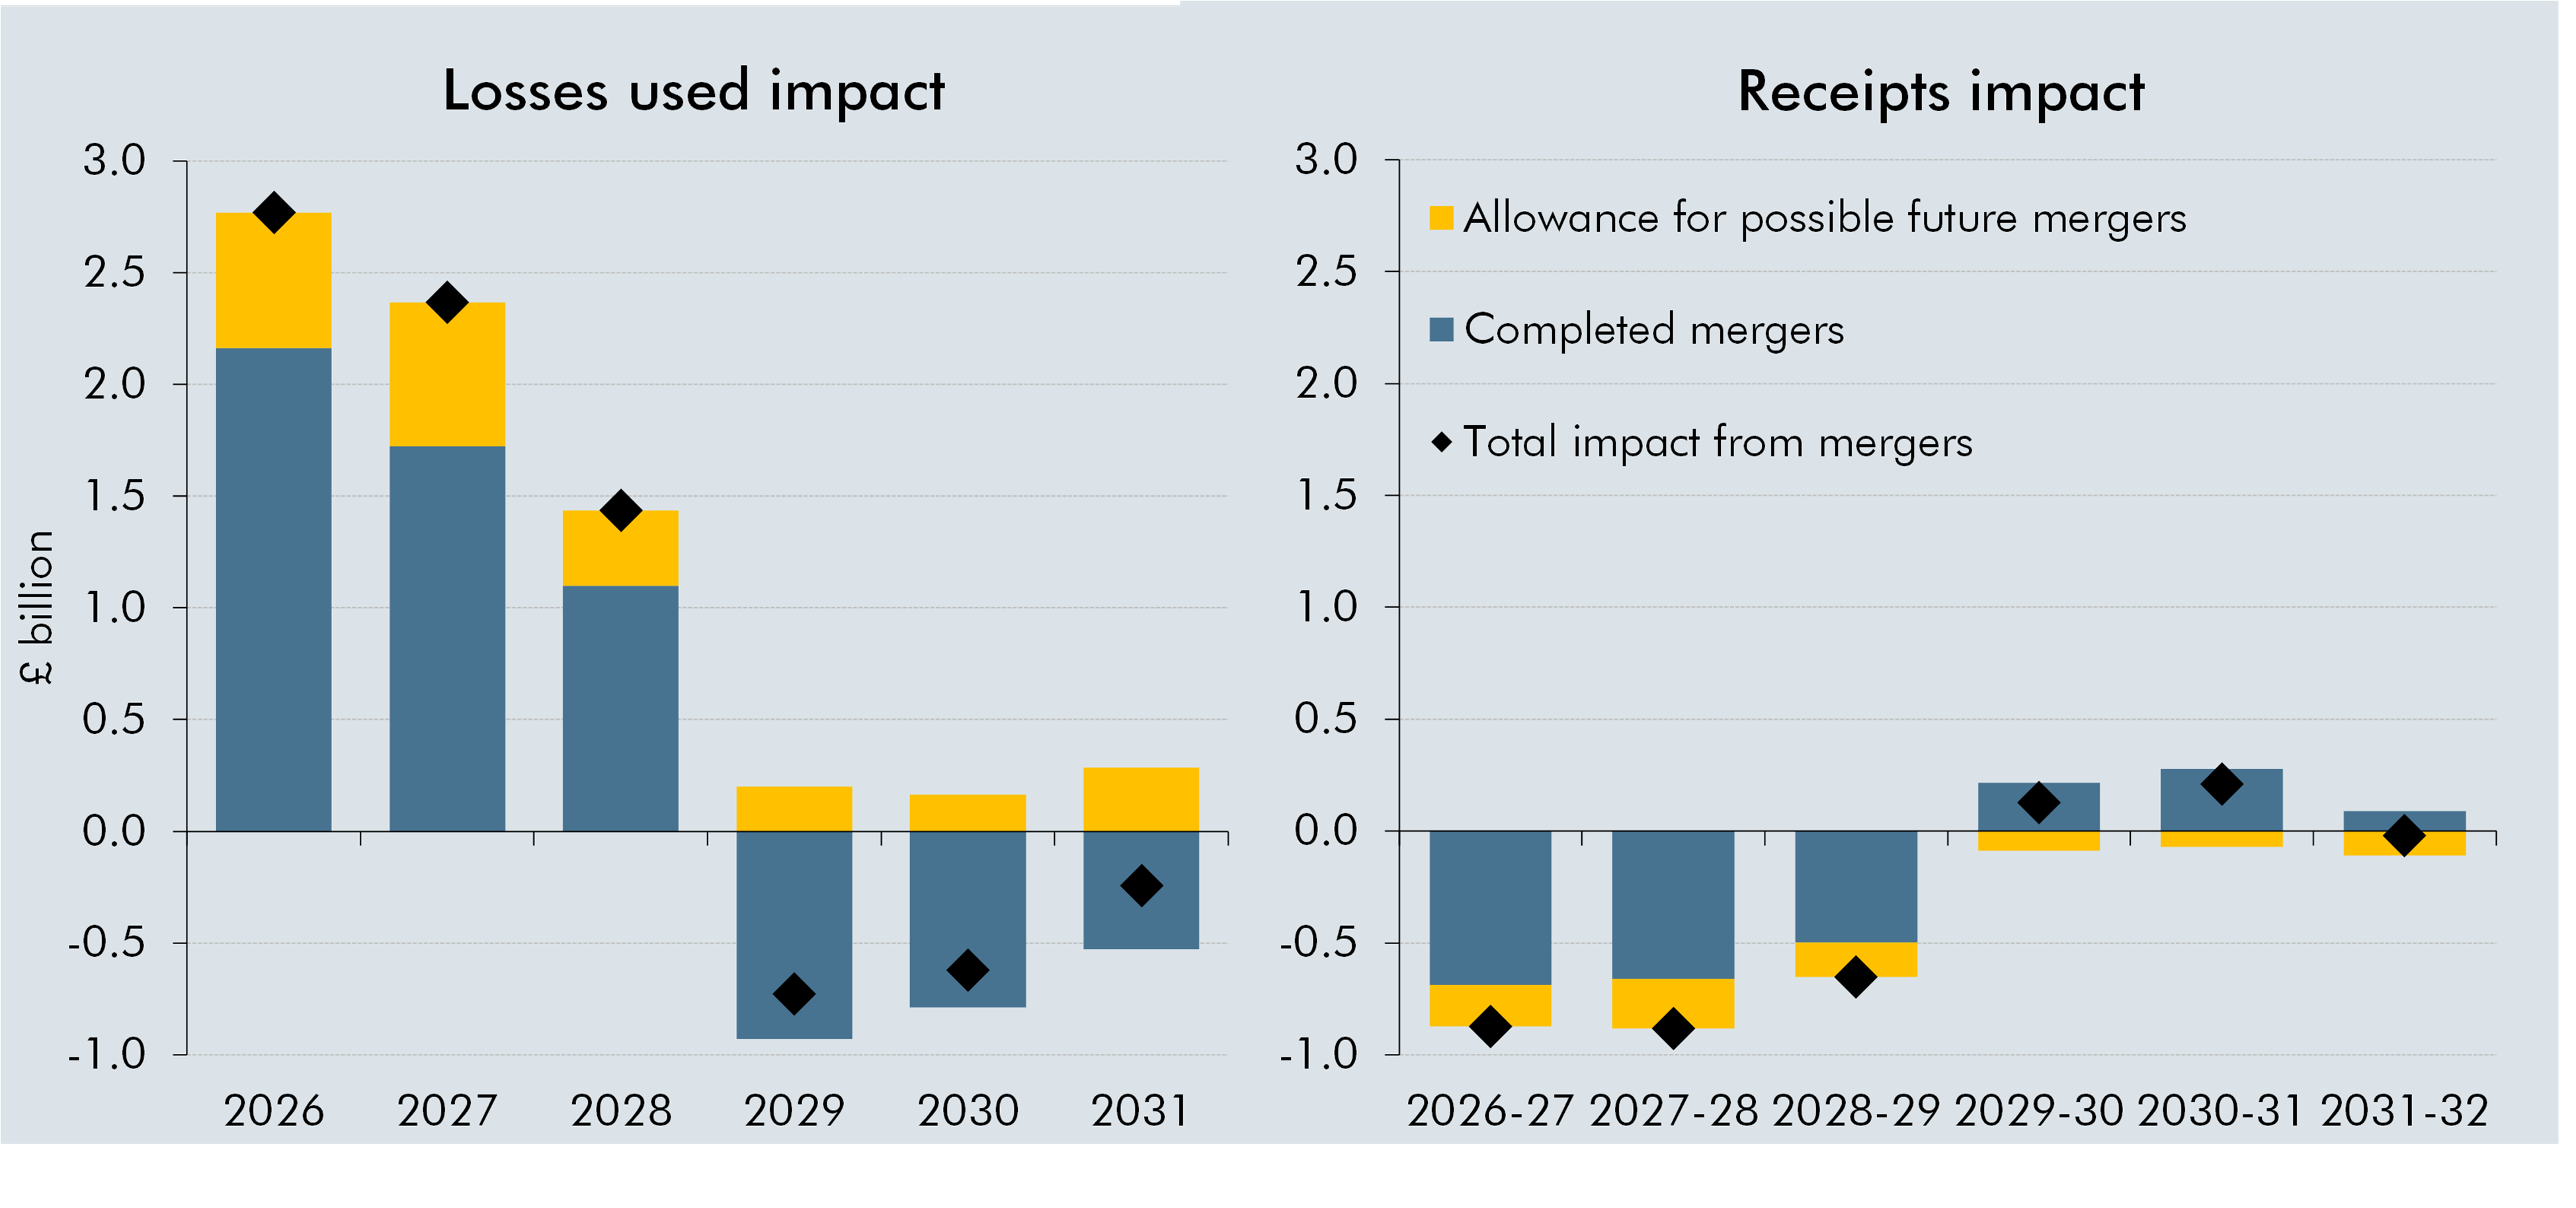
Note: The charts reflect impacts to ring fence corporation tax and the supplementary charge.
Source: HMRC, NSTA, ONS, OBR
a) The affected taxes are ring fence corporation tax (RFCT), the supplementary charge (SC) and petroleum revenue tax (PRT). The energy profits levy does not allow the use of historical losses from the RFCT, SC, and PRT regimes. See the ‘Oil and gas revenues’ Forecast in-depth page on our website for more detail on these taxes.
b) This is a high-level judgment and is not linked to any specific future transactions or groups.
Road taxes
4.29 Fuel duty is expected to raise £24 billion (0.8 per cent of GDP) in 2026-27, which is £0.6 billion less than in 2025-26, largely due to higher pump prices reducing demand. Relative to the March forecast, receipts are expected to be £0.7 billion lower this year mostly due to policy changes and lower demand. In May 2026, the Government announced that fuel duty rates would remain unchanged until January 2027. In this Budget, the Government has announced that rates will remain unchanged until July 2027 at which point the 5p cut first implemented in March 2022 will be unwound and then uprated by RPI. Receipts are then forecast to increase by £1.8 billion (7 per cent) in 2027-28 and by £0.9 billion in 2028-29 assuming this policy is implemented.
4.30 On the assumption that the latest policy is implemented, fuel duty receipts are forecast to peak in nominal terms at £27 billion (0.8 per cent of GDP) in 2028-29 before falling by around £2.1 billion by 2031-32. This reflects the turning point when the additional revenue from the assumed increase in fuel duty rates is forecast to be outweighed by the declining tax base due to a rising electric vehicle (EV) share. Chart 4.7 shows that in practice fuel duty revenues have been consistently lower than forecast. This is largely because despite successive policy commitments to raise fuel duty rates, they have not actually been increased since 2011-12. If the duty rate were to again remain unchanged at its current level throughout the forecast period it would reduce receipts, on average, by £4 billion a year between 2027-28 and 2031-32.
Chart 4.7: Successive fuel duty forecasts and outturn
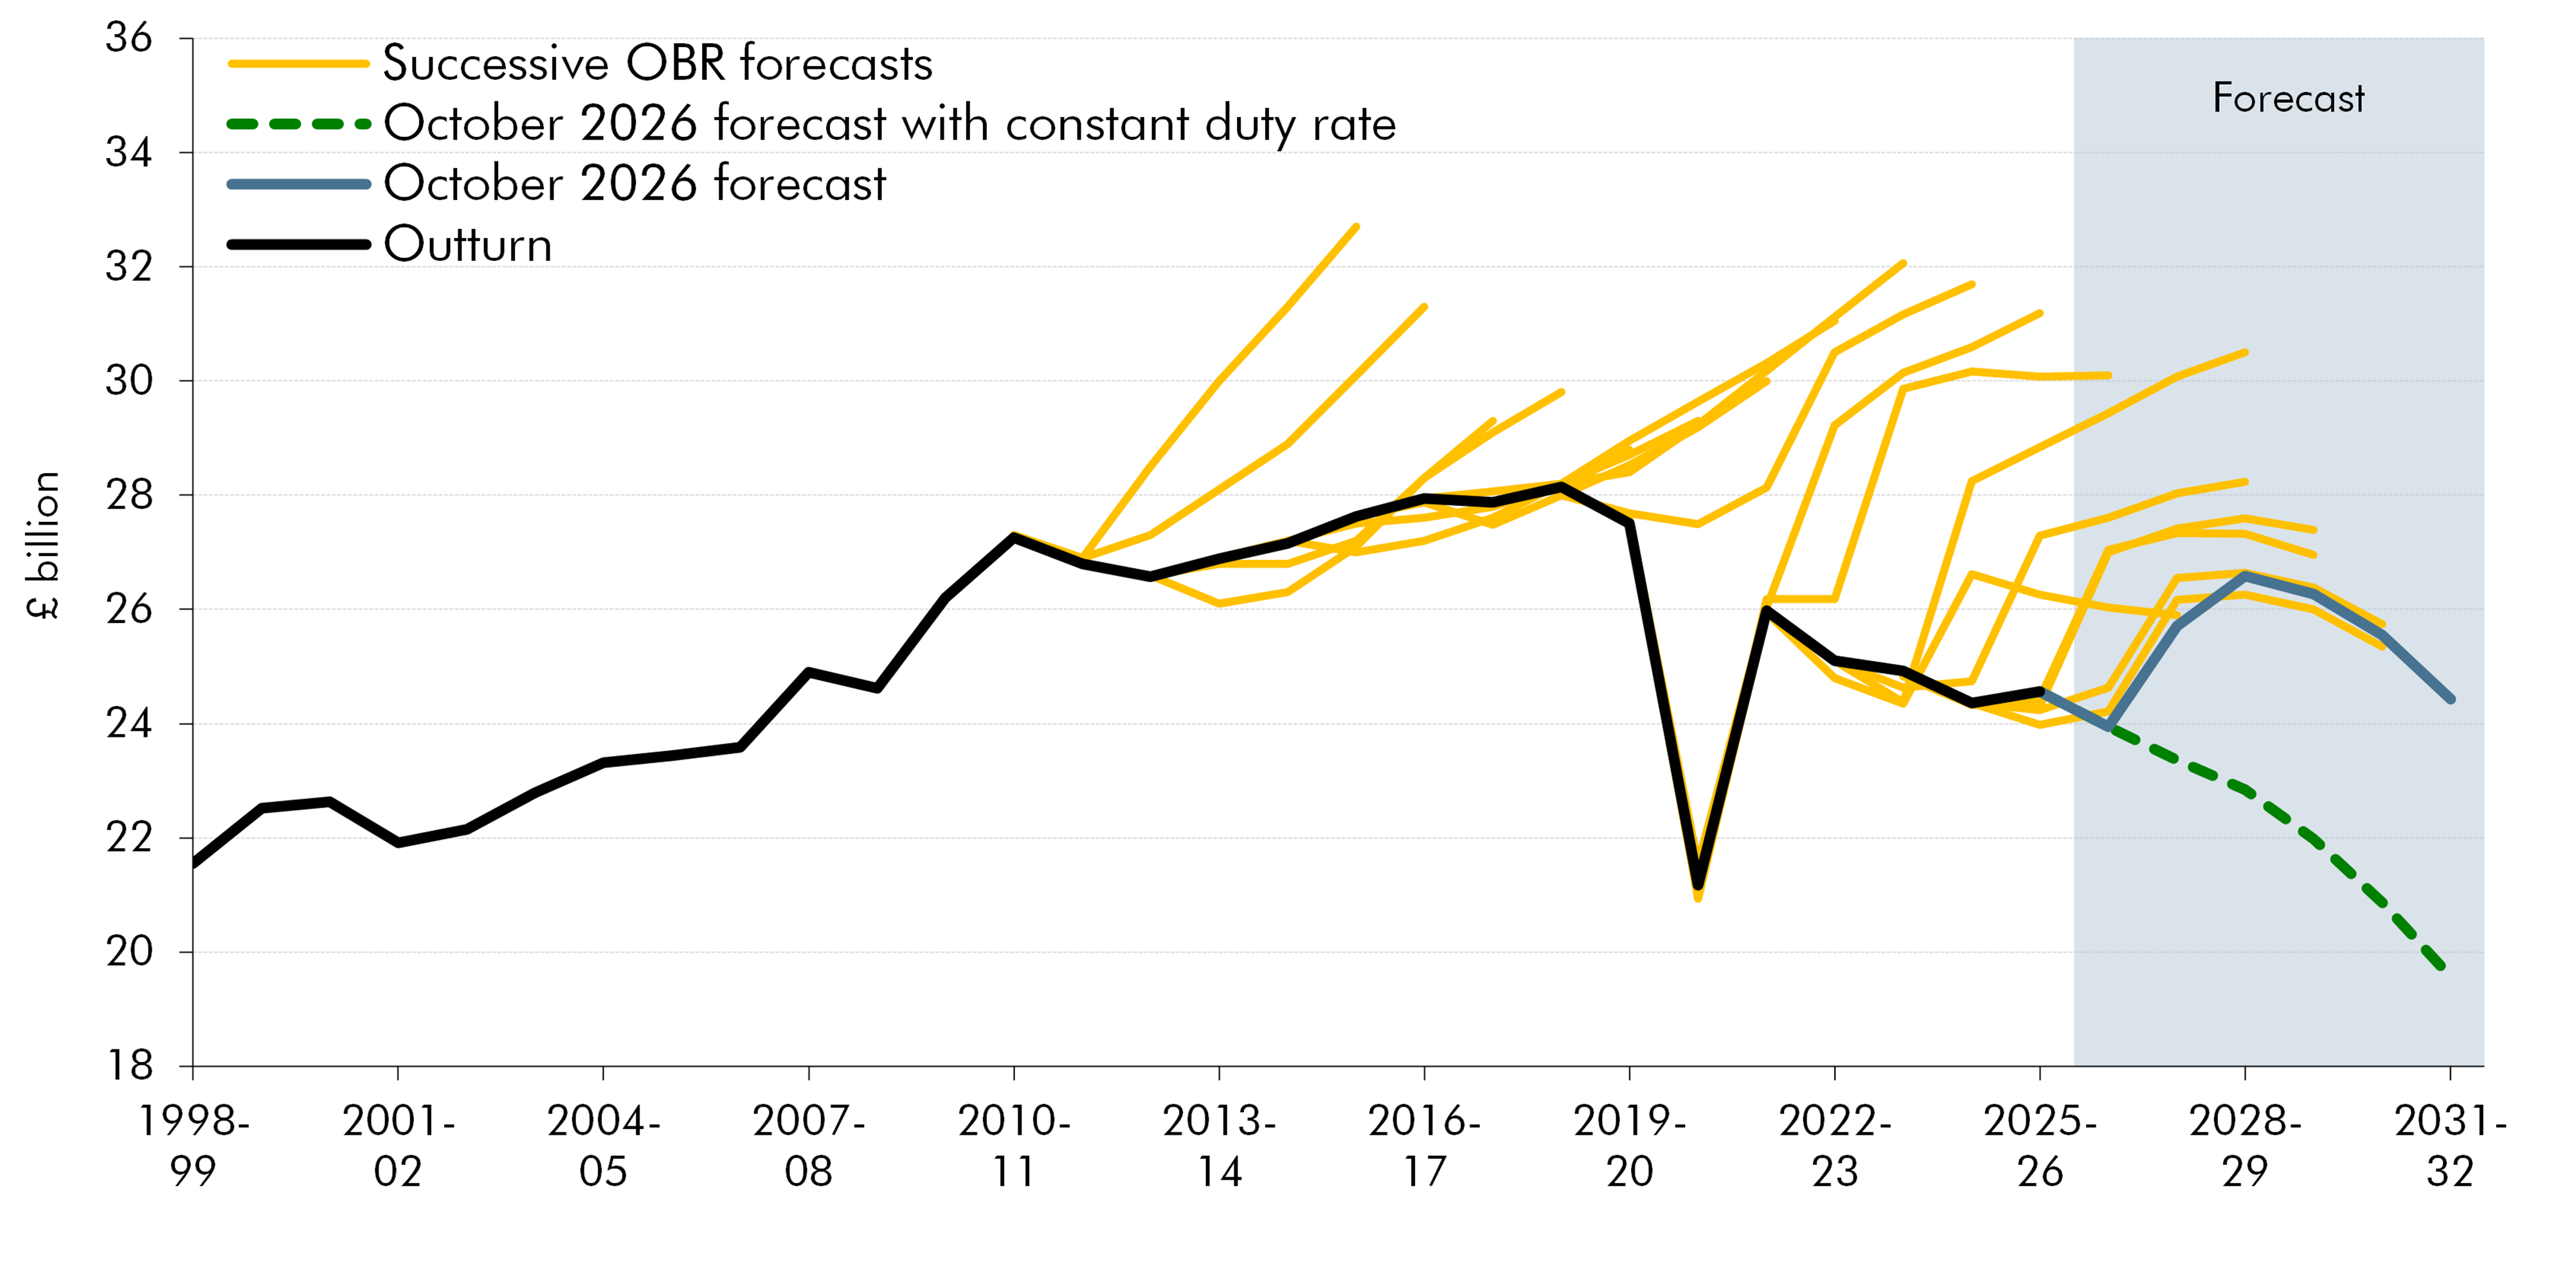
Source: ONS, OBR
4.31 Vehicle excise duty (VED) receipts are expected to be £9 billion (0.3 per cent of GDP) in 2026-27, a 6 per cent increase compared to 2025-26 driven by an increase in vehicle registrations. Across the forecast period, receipts are expected to increase in each successive year, rising to £14 billion by the forecast horizon. The introduction of the electric vehicle excise duty (eVED) from April 2028 adds over £2 billion to VED receipts by 2031-32. Relative to the March forecast, VED receipts are expected to be lower by £0.2 billion on average across the forecast following weaker stock and outturn updates for non-EVs. This has been slightly offset by higher eVED receipts from higher fuel prices inducing faster-than-expected switches to EVs.
Capital taxes
4.32 Capital gains tax (CGT) is forecast to raise £26 billion (0.8 per cent of GDP) in 2026-27, around a 5 per cent increase from 2025-26. Receipts are then forecast to rise to £41 billion in 2031-32 (1.1 per cent of GDP), largely driven by a forecast of rising equity prices.
4.33 Relative to the March forecast, before the impact of policy measures, CGT receipts are expected to be £4.8 billion higher this year largely due to a revised assessment of the forestalling of receipts in 2025-26, which is explained below.[footnote 44] Thereafter, CGT receipts are forecast to be higher than the March forecast by an average of £3.1 billion each year, driven by the 2025-26 receipts reassessment and the impact of higher forecast equity prices. The Budget 2026 policy to reform the taxation framework for distributions from companies to individuals is estimated to reduce CGT receipts by £1.2 billion in 2031-32. However, this is more than offset by the expected increase in SA income tax receipts from this measure. The net impact of the new Founders’ Relief and the lower Business Asset Disposal Relief lifetime limit reduce receipts by an average of £0.1 billion a year from 2027-28.
4.34 CGT receipts for 2025-26, which largely relate to 2024-25 asset disposals, were 78 per cent higher than the previous year. This was partly due to forestalling – an increase in the disposal of assets in 2024-25 ahead of anticipated CGT policy rate increases at Autumn Budget 2024. In the March 2026 forecast, we made a judgement that £4.3 billion of liabilities were brought forward due to this forestalling. This assumption was based on the average magnitude of forestalling seen ahead of anticipated policy changes before Budget 2021 and ahead of rate changes in 2010. We assumed that £1.1 billion of these forestalled liabilities related to transactions that would have taken place later in that same year, resulting in a net £3.2 billion of additional liabilities in the 2024-25 tax year.
4.35 HMRC have since reviewed this forestalling assumption using a more detailed analysis of the pattern of asset disposals across the year.[footnote 45] Compared with a ‘normal’ CGT tax year, the distribution of disposals in 2024-25 suggests that around £5.8 billion of CGT liabilities were brought forward due to forestalling. The analysis also suggests that a higher proportion of these forestalled liabilities than previously assumed were likely to have been brought forward from later in that year (£4.3 billion), because the pattern of disposals later in the year was relatively weak compared to previous years. This suggests there was a net £1.5 billion of additional disposed liabilities in the 2024-25 tax year due to forestalling. The larger in-year unwinding increases the estimate for structural disposals in 2024-25. This, alongside the subsequent lower unwinding, boosts the forecast for disposals and receipts in the next three years compared to March.
4.36 CGT is one of the most volatile and therefore uncertain tax streams. This is reflected in the average size of the difference between CGT forecasts and outturn. Over the last ten forecasts, the one-year ahead CGT average absolute forecast difference was 24.5 per cent of forecast, compared with 4.3 per cent for total public sector current receipts.[footnote 46] Revenues are sensitive to movements in asset prices, in particular equity prices (see Box 3.1 in the March 2026 EFO), which are typically highly volatile from year to year. In addition, receipts are highly sensitive to behavioural decisions made by a relatively narrow group of higher net worth taxpayers, who often have flexibility in choosing when to dispose of assets in response to changes in asset value or to policy changes.
Table 4.7: CGT: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| March 2026 forecast | 21.8 | 20.8 | 25.5 | 28.9 | 32.0 | 34.9 |
| October 2026 forecast | 24.3 | 25.6 | 29.2 | 32.4 | 34.2 | 37.7 |
| Difference | 2.5 | 4.8 | 3.7 | 3.5 | 2.2 | 2.8 |
| of which: | ||||||
| Pre-measures changes | 2.5 | 4.8 | 4.0 | 3.7 | 3.8 | 4.2 |
| of which: | ||||||
| Outturn and forestalling(1) | 2.5 | 4.7 | 3.2 | 2.9 | 2.7 | 2.5 |
| Equity prices and property forecasts | 0.0 | 0.1 | 0.7 | 0.8 | 1.1 | 1.7 |
| Direct effect of Government decisions | 0.0 | 0.0 | -0.2 | 0.0 | -1.4 | -1.2 |
| Indirect effects of Government decisions | 0.0 | 0.0 | 0.0 | -0.2 | -0.2 | -0.2 |
| 1) Includes the impact of the updated unwinding profile, tapered structural strength assumption and other modelling changes. |
| Source: ONS, OBR |
4.37 Property transaction taxes are forecast to raise £17 billion (0.5 per cent of GDP) in 2026-27, a 0.6 per cent decline relative to 2025-26. This is driven by the share of year-to-date receipts in 2026-27 implying a lower annual total for the year compared to 2025.26.The recent fall in house prices in areas of London and the South East, where the level of property prices are higher than the national average, partly informs this judgement. Given the progressivity of the stamp duty land tax system, this has a relatively large effect on overall receipts. Receipts are then forecast to rise gradually to £26 billion (0.7 per cent of GDP) in 2031-32, driven by rising property transactions and house prices over the remainder of the forecast period.
4.38 Relative to the March forecast, property transaction tax receipts are expected to be around £3.2 billion lower in 2026-27 and an average of £3.9 billion a year lower over the rest of the forecast. Changes are largely due to the lower-than-expected in-year receipts for both residential and commercial sectors and reductions to the forecasts for house prices and property transactions.
4.39 Inheritance tax (IHT) receipts are forecast to raise £9 billion (0.3 per cent of GDP) in 2026-27, a 7.2 per cent increase on last year. Receipts are expected to continue to increase over the forecast, reaching £15 billion (0.4 per cent of GDP) in 2031-32, driven by rising equity and house prices, a growing proportion of UK deaths subject to inheritance tax, and the impact of policies announced in Autumn Budget 2024. Relative to the March forecast, IHT receipts are expected to be £0.5 billion lower on average, in every year of the forecast, largely driven by lower in-year outturn which is partly offset by higher equity prices.
4.40 An increasing proportion of IHT revenue is forecast to come from changes to the inheritance tax regime announced at and since Autumn Budget 2024, including taxing inherited pension pots and introducing changes to agricultural and business property reliefs, which account for around one-sixth of total revenue by the end of the forecast. The behavioural responses to these measures and the tax base for inheritable pension wealth are particularly uncertain.
Business rates
4.41 Business rates are expected to raise £35 billion in 2026-27, a 4.5 per cent increase relative to 2025-26. Business rates bills are calculated by multiplying the rateable value by the multiplier (which is typically uprated by CPI inflation) less reliefs for which the property is eligible. Growth in 2026-27 reflects several changes in the business rates system that took effect in April 2026. These include a revaluation in which the rateable values of non-domestic property were updated, a neutral change to multipliers with a lower rate for retail, hospitality and leisure properties and a higher rate for high-value properties and several temporary measures to cap bill increases resulting from the revaluation.
4.42 The 2026-27 estimate for business rates in England is based on forecast information from local authorities which was not available when we finalised the March forecast. This indicates that receipts this year will be £2 billion lower than previously assumed. Over the rest of the forecast period, the higher path for CPI inflation pushes up the multiplier, adding around £1 billion to the business rates forecast by 2030-31. This leaves business rates little changed from our March forecast by that year. In this Budget, the Government has announced a number of further measures which reduce business rates charged on properties in the retail, hospitality and leisure sectors, which lower receipts by £0.4 billion in 2027-28 and £0.6 billion in 2028-29.
Excise duties
4.43 Alcohol duty receipts are expected to raise £13 billion in 2026-27, a 2.7 per cent increase relative to 2025-26. Receipts are then anticipated to increase to £14 billion by 2031-32, driven by increases to the duty rate that offset an assumed average 1 per cent decline in alcohol consumption in each year. Compared to the March forecast, we assume a lower consumption trend, reflecting recent outturns, that reduces forecast receipts by an average of £0.2 billion each year.
4.44 Tobacco duty receipts are expected to raise £7 billion in 2026-27, a 1 per cent decrease relative to 2025-26, as higher duty rates only partly offset falling consumption. Receipts then fall to £6 billion by 2031-32 as consumption continues to decline. Vaping duty, effective from October 2026, raises £0.2 billion in 2026-27 and £0.7 billion by 2031-32. Compared to the March forecast, tobacco receipts are broadly unchanged.
4.45 Betting and gaming receipts are expected to raise £5 billion in 2026-27, a 31 per cent increase relative to 2025-26, driven by the increase to tax rates on remote gambling announced at Budget 2025. Thereafter, receipts are forecast to grow by an average of 3.4 per cent a year to £6 billion in 2031-32. Compared to the March forecast, before the impact of policy measures, receipts are higher by an average of £0.2 billion. This is largely due to stronger-than-expected remote gaming duty receipts, suggesting a slower-than-expected reduction in activity in response to the rate increase. The increase to machine gaming rates announced at this Budget increases receipts by a further estimated £0.1 billion a year from 2027-28.
Other taxes
4.46 VAT refunds are forecast to cost £31 billion in 2026-27, a 2.7 per cent increase from 2025-26. Repayments then grow over the forecast in line with government consumption, reaching £36 billion by 2031-32. Relative to our March forecast, refunds are higher across the forecast period, by £0.1 billion in 2026-27 before rising to £0.5 billion in 2030-31. This is due to strength in outturn data feeding through the forecast, particularly for local authorities. VAT refunds are offset by spending and are neutral for public sector borrowing.
4.47 Environmental levies are expected to total £14 billion in 2026-27, rising to a forecast £16 billion by 2031-32. This is due to an increase in electricity supply and generation in the capacity market and contracts for difference (CfD) forecasts, and an expected £1.1 billion increase from Sizewell C regulated asset base (RAB) levy receipts. Compared to the March forecast, environmental levies are on average £1.2 billion lower each year. This is mostly due to lower CfD receipts reflecting the Government’s decision to provide funding to reduce CfD levies on billpayers (see paragraph 3.19), the near-term rise in wholesale electricity prices, and project delays reducing electricity generation. Receipts relating to the capacity market scheme are lower towards the forecast horizon due to lower-than-expected prices at recent auctions. Most receipts from environmental levies are directly offset in spending because they are used to provide subsidies for energy generators. This means they are generally neutral for public sector borrowing.
4.48 Council tax receipts are expected to raise £54 billion in 2026-27, a 7 per cent increase from 2025-26 driven largely by increases in the rates of council tax in England, Scotland and Wales. Receipts are then forecast to rise to £70 billion by 2031-32 as both council tax rates and the number of households are assumed to grow. Receipts are broadly unchanged from our March forecast. Council tax receipts are directly offset by local authority spending and so they are neutral for public sector borrowing. For more information on the council tax rebate announced at this Budget, see paragraph 3.11 in Chapter 3.
4.49 Home Office fees are forecast to raise £6 billion in 2026-27, a 2.5 per cent increase on 2025-26. Relative to our March forecast, receipts are £0.3 billion lower in 2026-27 due to lower-than-expected immigration health surcharge receipts. Thereafter, overall receipts are on average £0.2 billion higher in every year due to higher projected total in-country work visas, which is partly offset by our lower net migration forecast.
Other receipts
4.50 Interest and dividend receipts are forecast to raise £44 billion in 2026-27, a 7.2 per cent increase on 2025-26. Receipts then rise throughout the forecast, driven mainly by interest received from funded public sector pensions and accrued interest on student loans. Receipts are forecast to be higher than expected in March by around £3 billion in 2027-28 and 2028-29. This reflects higher inflation increasing accrued interest on student loans and higher interest rates boosting returns on public sector assets, deposits and reserves. By 2030-31, receipts return to the level assumed in the March forecast, driven by changes to the assumed rate of return on funded pension assets and inflation subsiding.
4.51 Gross operating surplus (GOS) is the sum of general government depreciation and public corporations’ (PCs’) operating surplus and is projected to reach £86 billion in 2026-27, rising to £105 billion by the forecast horizon. Relative to March, GOS is expected to be an average of £0.6 billion a year higher. General government depreciation is expected to rise from £69 billion in 2026-27 to £87 billion in 2031-32. This is £0.8 billion higher in 2026-27 than expected in March, with the difference rising to £2.7 billion in 2030-31. This is mostly due to higher depreciation rates in outturn, which we assume will persist throughout the forecast. Depreciation is offset by spending and is neutral for public sector borrowing. Changes in PC operating surplus since March largely reflect revisions to the outturn.
Chapter 5: Public sector expenditure
Summary of the expenditure forecast
5.1 As Chart 5.1 shows, in the central forecast, public spending is expected to increase from 44.5 per cent of GDP in 2025-26 to 45.7 per cent of GDP in 2027-28, before gradually declining to 44.7 per cent of GDP by 2031-32. This would be 5.5 percentage points higher than the pre-pandemic level in 2019-20, and 5.0 percentage points higher compared to the pre-financial crisis level of spending in 2006-07.
5.2 As shown in Table 5.1, the change in public spending over the forecast period (2026-27 to 2031-32) is the result of changes in both departmental expenditure limits (DEL), which fall as a share of GDP in every year of the forecast, and annually managed expenditure (AME), which is forecast to peak in 2027-28 before falling gradually until 2030-31:
-
Departmental expenditure limits are expected to rise as a share of GDP from 21.1 per cent in 2025-26 to 21.5 per cent in 2026-27 before gradually falling to 20.0 per cent by 2031-32. The planned fall in the later years of the forecast is explained by decreases in both day-to-day spending (resource DEL or RDEL) from 16.9 per cent of GDP to 16.3 per cent of GDP between 2027-28 and 2031-32, and in capital spending (capital DEL or CDEL) which falls from 4.0 per cent of GDP in 2027-28 to 3.7 per cent of GDP in 2031-32. After the end of the current Spending Review period, these projections are based on assumptions set by the Government for overall total RDEL and CDEL, rather than on detailed departmental spending plans. As set out later in this chapter, there are significant pressures on departmental spending over this period.
-
Annually managed expenditure is expected to rise as a share of GDP from 23.4 per cent of GDP in 2025-26 to 24.9 per cent in 2027-28, then fall to 24.4 per cent by 2030-31, before rising again in 2031-32 to 24.6 per cent. Welfare spending and debt interest spending both rise from 2025-26 to 2027-28, and then are broadly stable until rising slightly again in 2031-32. There are forecast declines from 2027-28 in locally financed expenditure and in other areas of AME spending, as payments from compensation schemes decline and the deficit in unfunded public sector pension schemes falls as a share of GDP.
5.3 Chart 5.1 shows that total public spending as a share of GDP is higher in the near term relative to the March 2026 forecast. The difference then narrows so that the latest forecast is only slightly higher in 2030-31 at 44.6 per cent of GDP, compared to the 44.3 per cent of GDP forecast in March. These near-term increases are mainly driven by higher forecast spending on debt interest and welfare, explained in more detail later in this chapter.
Chart 5.1: Total managed expenditure as a share of GDP
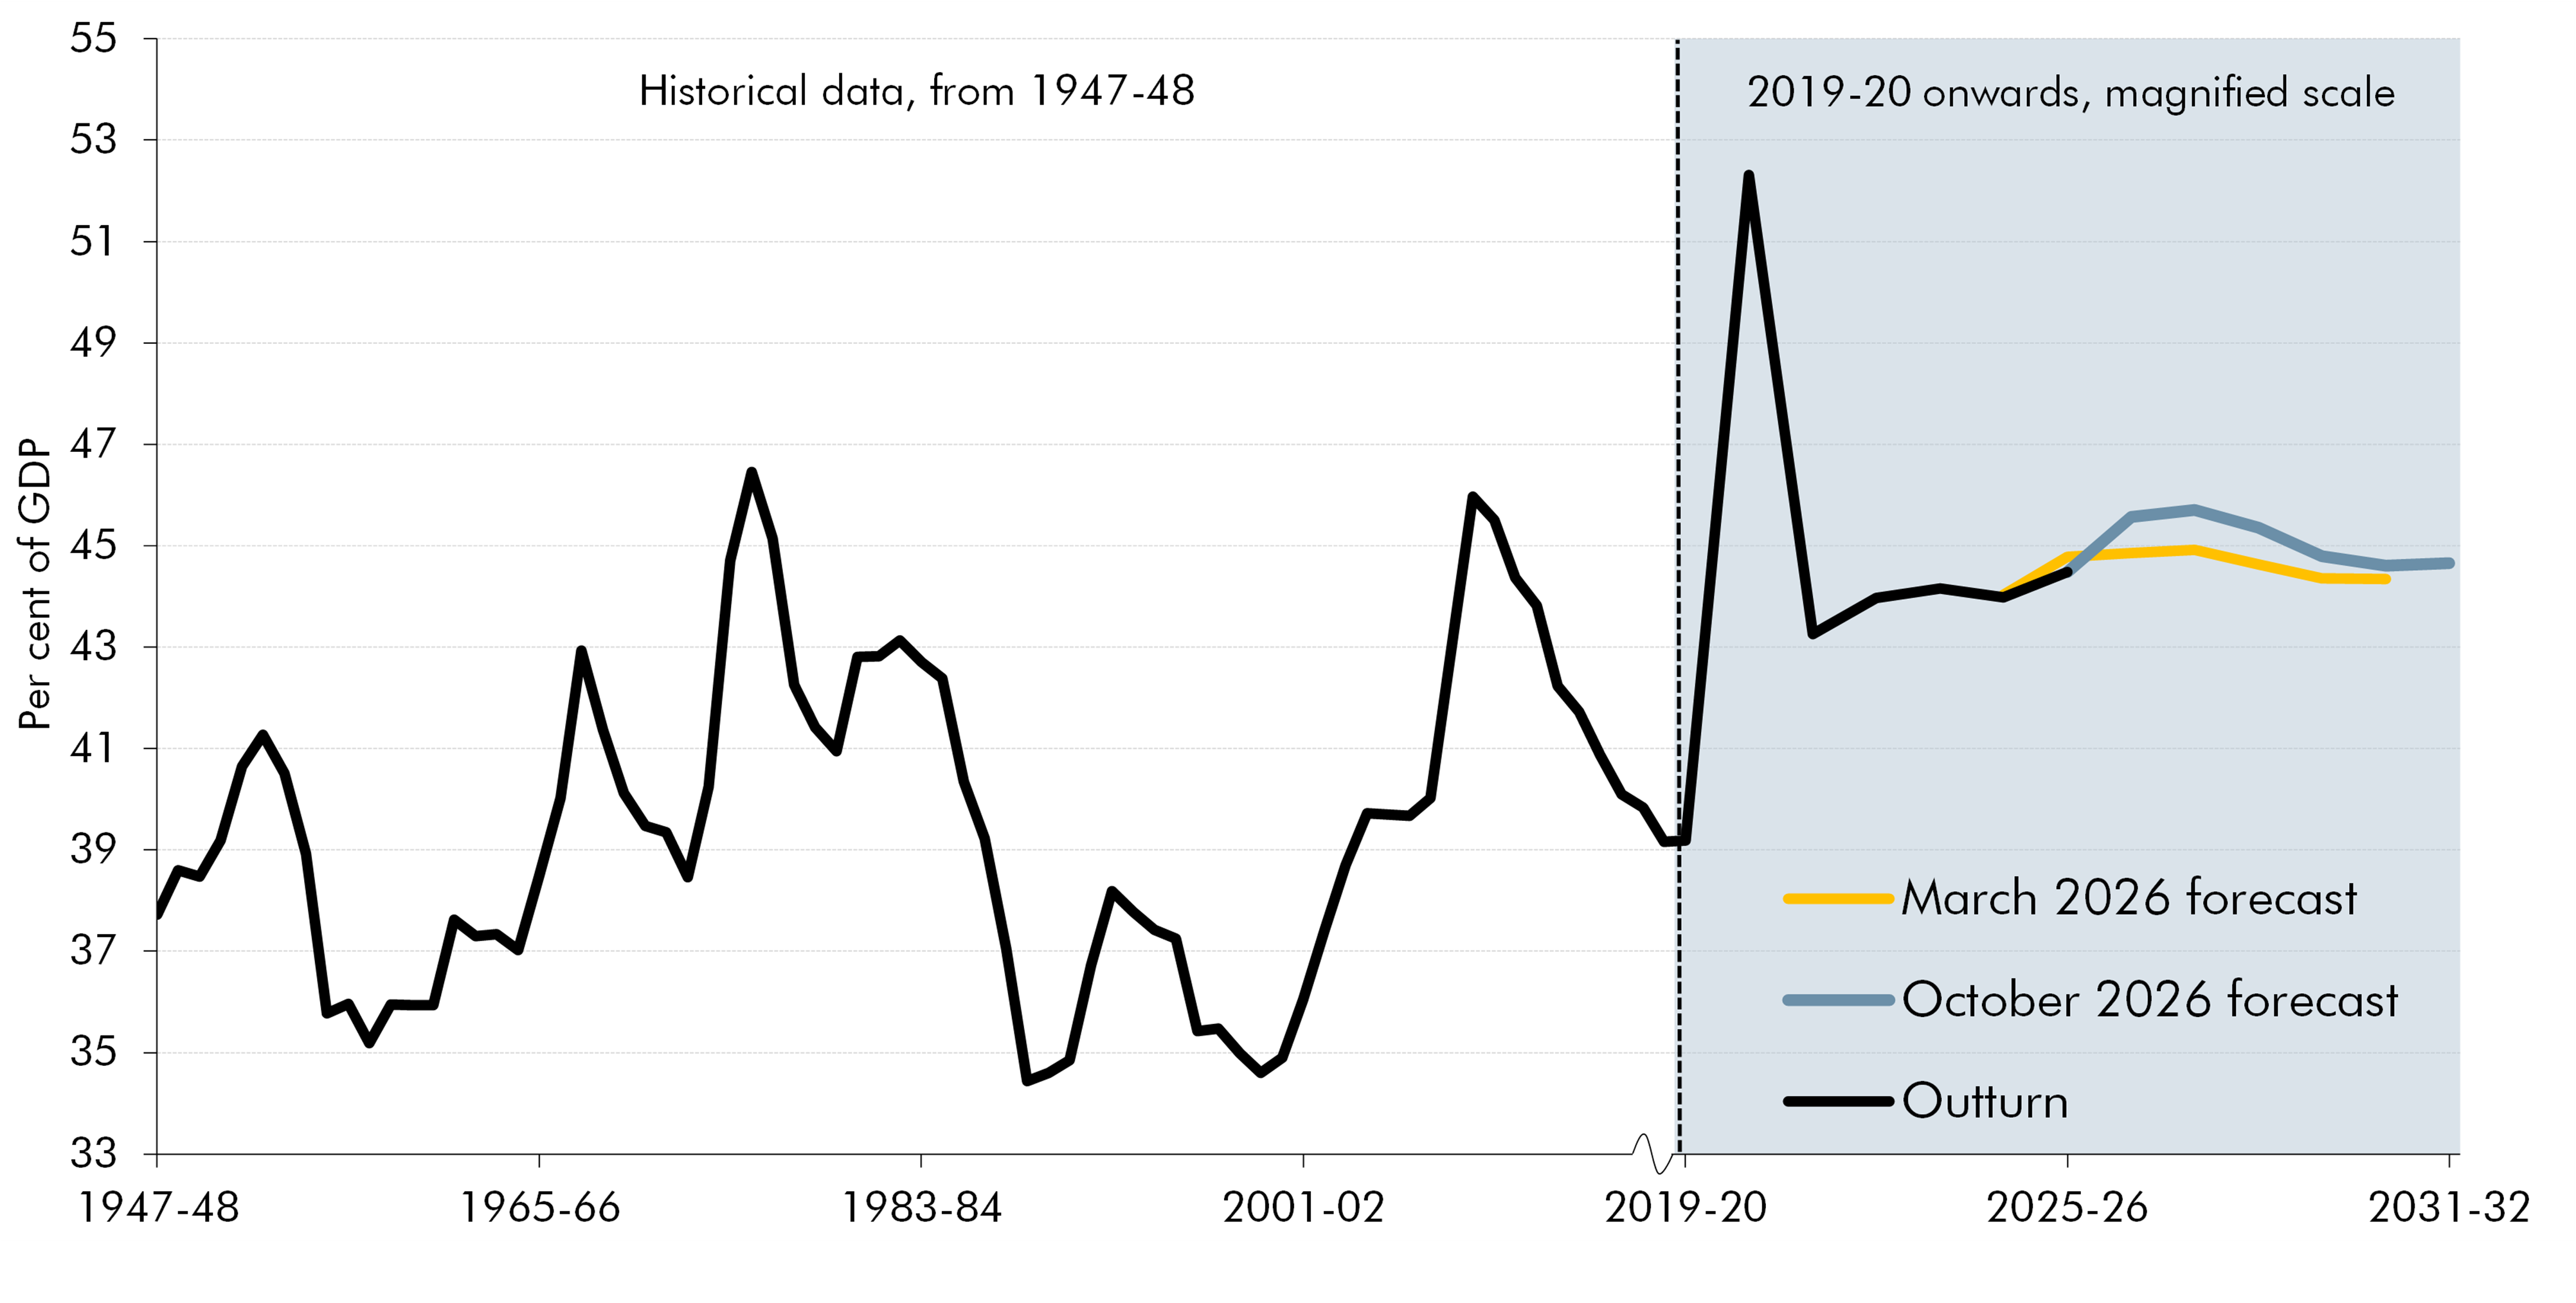
Source: ONS, OBR
Table 5.1: Total managed expenditure as a share of GDP
| Per cent of GDP | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Total managed expenditure | 44.5 | 45.6 | 45.7 | 45.4 | 44.8 | 44.6 | 44.7 |
| of which: | |||||||
| Departmental expenditure limits | 21.1 | 21.5 | 20.8 | 20.6 | 20.3 | 20.2 | 20.0 |
| of which: | |||||||
| Resource DEL | 17.2 | 17.5 | 16.9 | 16.8 | 16.5 | 16.5 | 16.3 |
| Capital DEL | 4.0 | 4.0 | 4.0 | 3.9 | 3.8 | 3.7 | 3.7 |
| Annually managed expenditure | 23.4 | 24.1 | 24.9 | 24.7 | 24.5 | 24.4 | 24.6 |
| of which: | |||||||
| Welfare | 10.9 | 11.1 | 11.2 | 11.2 | 11.2 | 11.2 | 11.3 |
| Debt interest, net of APF | 3.5 | 3.9 | 4.1 | 4.1 | 4.2 | 4.1 | 4.2 |
| Locally financed expenditure | 2.8 | 2.9 | 2.9 | 2.8 | 2.7 | 2.7 | 2.8 |
| Public corporations’ expenditure | 0.5 | 0.5 | 0.5 | 0.5 | 0.5 | 0.5 | 0.5 |
| PSNB-neutral spending(1) | 3.4 | 3.5 | 3.5 | 3.5 | 3.5 | 3.5 | 3.5 |
| Other AME | 2.2 | 2.2 | 2.7 | 2.6 | 2.4 | 2.4 | 2.3 |
| Note: Total managed expenditure can be divided into two components of roughly equal size: departmental expenditure limits (DELs) mostly cover spending on public services, grants and administration (‘resource’ spending), and investment (‘capital’ spending). These items can be planned over multiple years. Annually managed expenditure (AME) covers items less amenable to multi-year planning. |
| 1) PSNB-neutral spending is defined as general government depreciation, current VAT refunds, and environmental levies. This is different to the PSNB-neutral receipts total in Table 3.1 because extended producer responsibility (EPR) is included within the resource DEL line, and council tax and community infrastructure levy (CIL) are included within the locally financed expenditure line. |
| Source: ONS, OBR |
5.4 As Chart 5.1 shows, the spending-to-GDP ratio in 2031-32 is forecast to be 5.5 percentage points above the pre-pandemic level in 2019-20. Over that period there have been significant changes in both the level and composition of public spending as illustrated in Chart 5.2:
-
2019-20 to 2025-26: Spending spiked upward in 2020-21 to 13.1 per cent of GDP above 2019-20 levels, driven by the introduction of temporary pandemic-related income support schemes and loan guarantees, and higher departmental and welfare spending. By 2025-26, while overall public spending had fallen back sharply from this peak it was still 5.3 per cent of GDP higher than in 2019-20, due to higher debt interest, welfare, and departmental spending.
-
2025-26 to 2031-32: Spending is forecast to rise by 1.1 per cent of GDP in 2026-27, primarily due to higher debt interest spending and RDEL. Over the subsequent five years, spending is forecast to fall by 0.9 per cent of GDP, mainly reflecting a decline in RDEL (falling by 1.1 percentage points), but also CDEL and other AME. These declines more than offset a forecast rise in debt interest of 0.3 percentage points and welfare of 0.3 percentage points.
Chart 5.2: Composition of the rise in the spend-to-GDP ratio since 2019-20
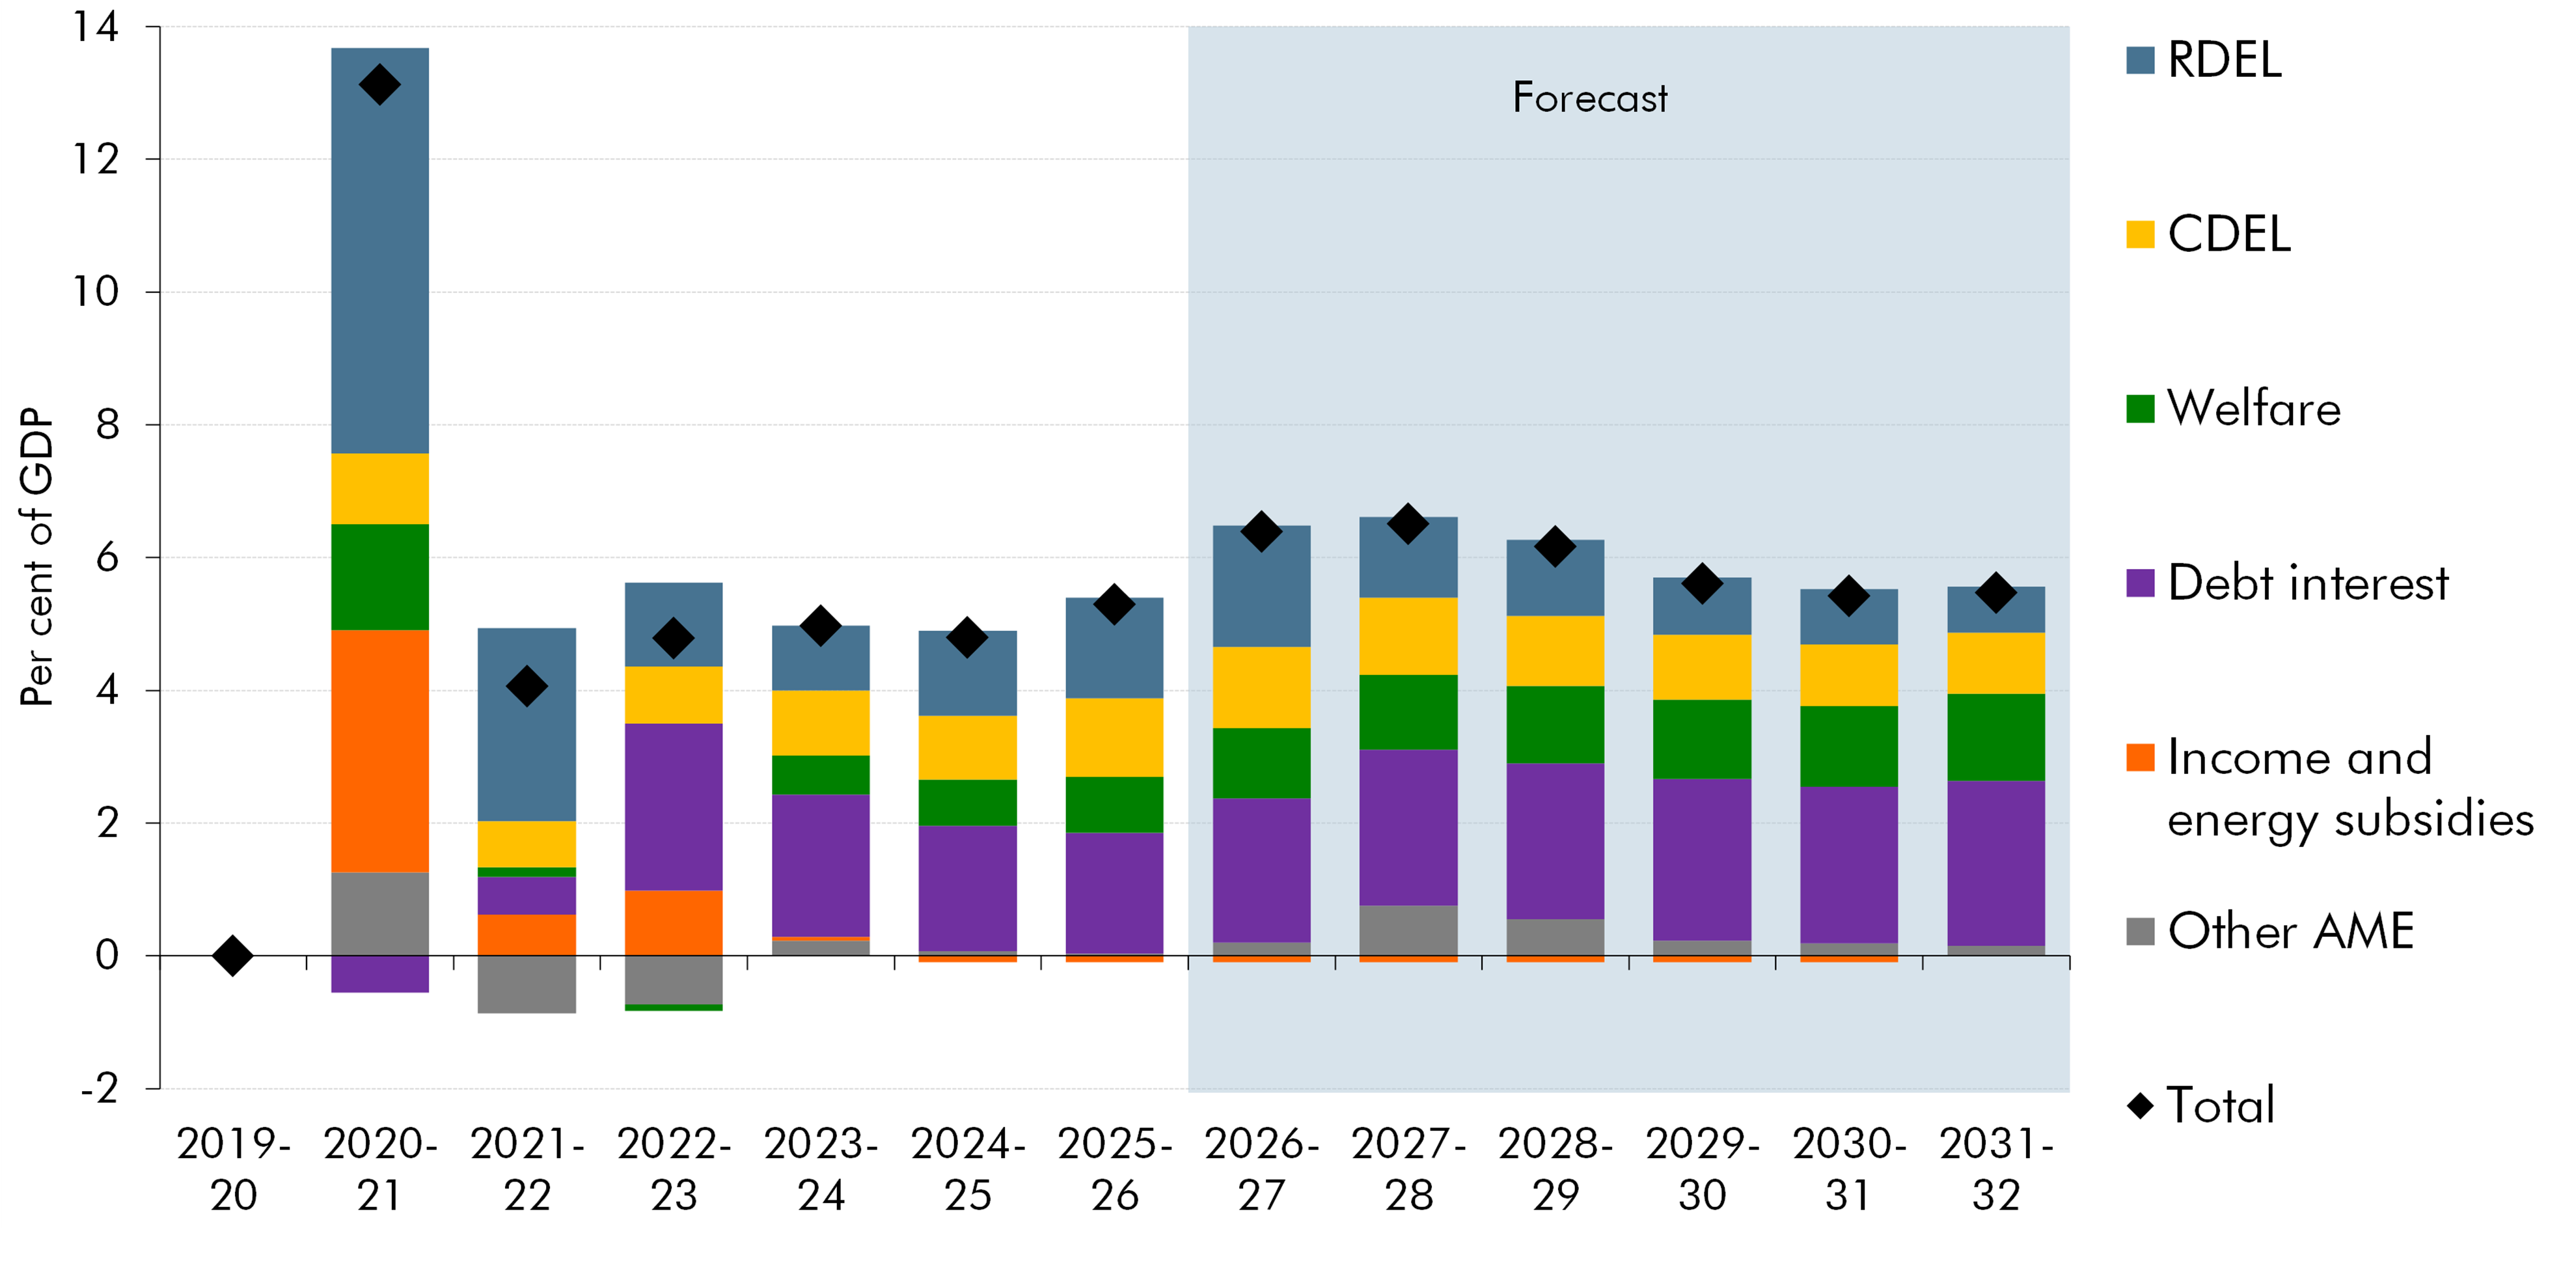
Source: ONS, OBR
5.5 Chart 5.3 shows the same change in the spending-to-GDP ratio between 2019-20 and 2031-32 decomposed into policy and forecast changes. This shows the contributions of:
-
The spending plans in place at the time of the pre-pandemic Budget in March 2020, which would have resulted in the spending-to-GDP ratio falling by 0.8 per cent of GDP over this period.
-
Underlying forecast changes, which raise spending by 3.3 per cent of GDP relative to our pre-pandemic expectations. These are driven mainly by higher debt interest spending (2.8 per cent) which reflects upward revisions to both the amount of debt and the cost of servicing it. Higher other spending primarily reflects higher welfare spending which reflects upward revisions to the forecasts for benefit caseloads and for inflation over this period, which increased welfare spending as governments continued to uprate working age welfare awards by inflation and state pension awards by the triple lock in most years. This is partially offset by falls in other smaller areas of spending.
-
Discretionary spending policy measures announced between Spring Budget 2020 and Spring Budget 2024 raise the spending-to-GDP ratio by 0.7 percentage points, with net increases to both RDEL and CDEL spending.
-
Discretionary spending policy measures from Autumn Budget 2024 onwards are expected to raise spending by 2.2 per cent of GDP in 2031-32, mostly from higher RDEL and CDEL spending.
Chart 5.3: Contributions to the rise in the spend-to-GDP ratio from 2019-20 to 2031-32
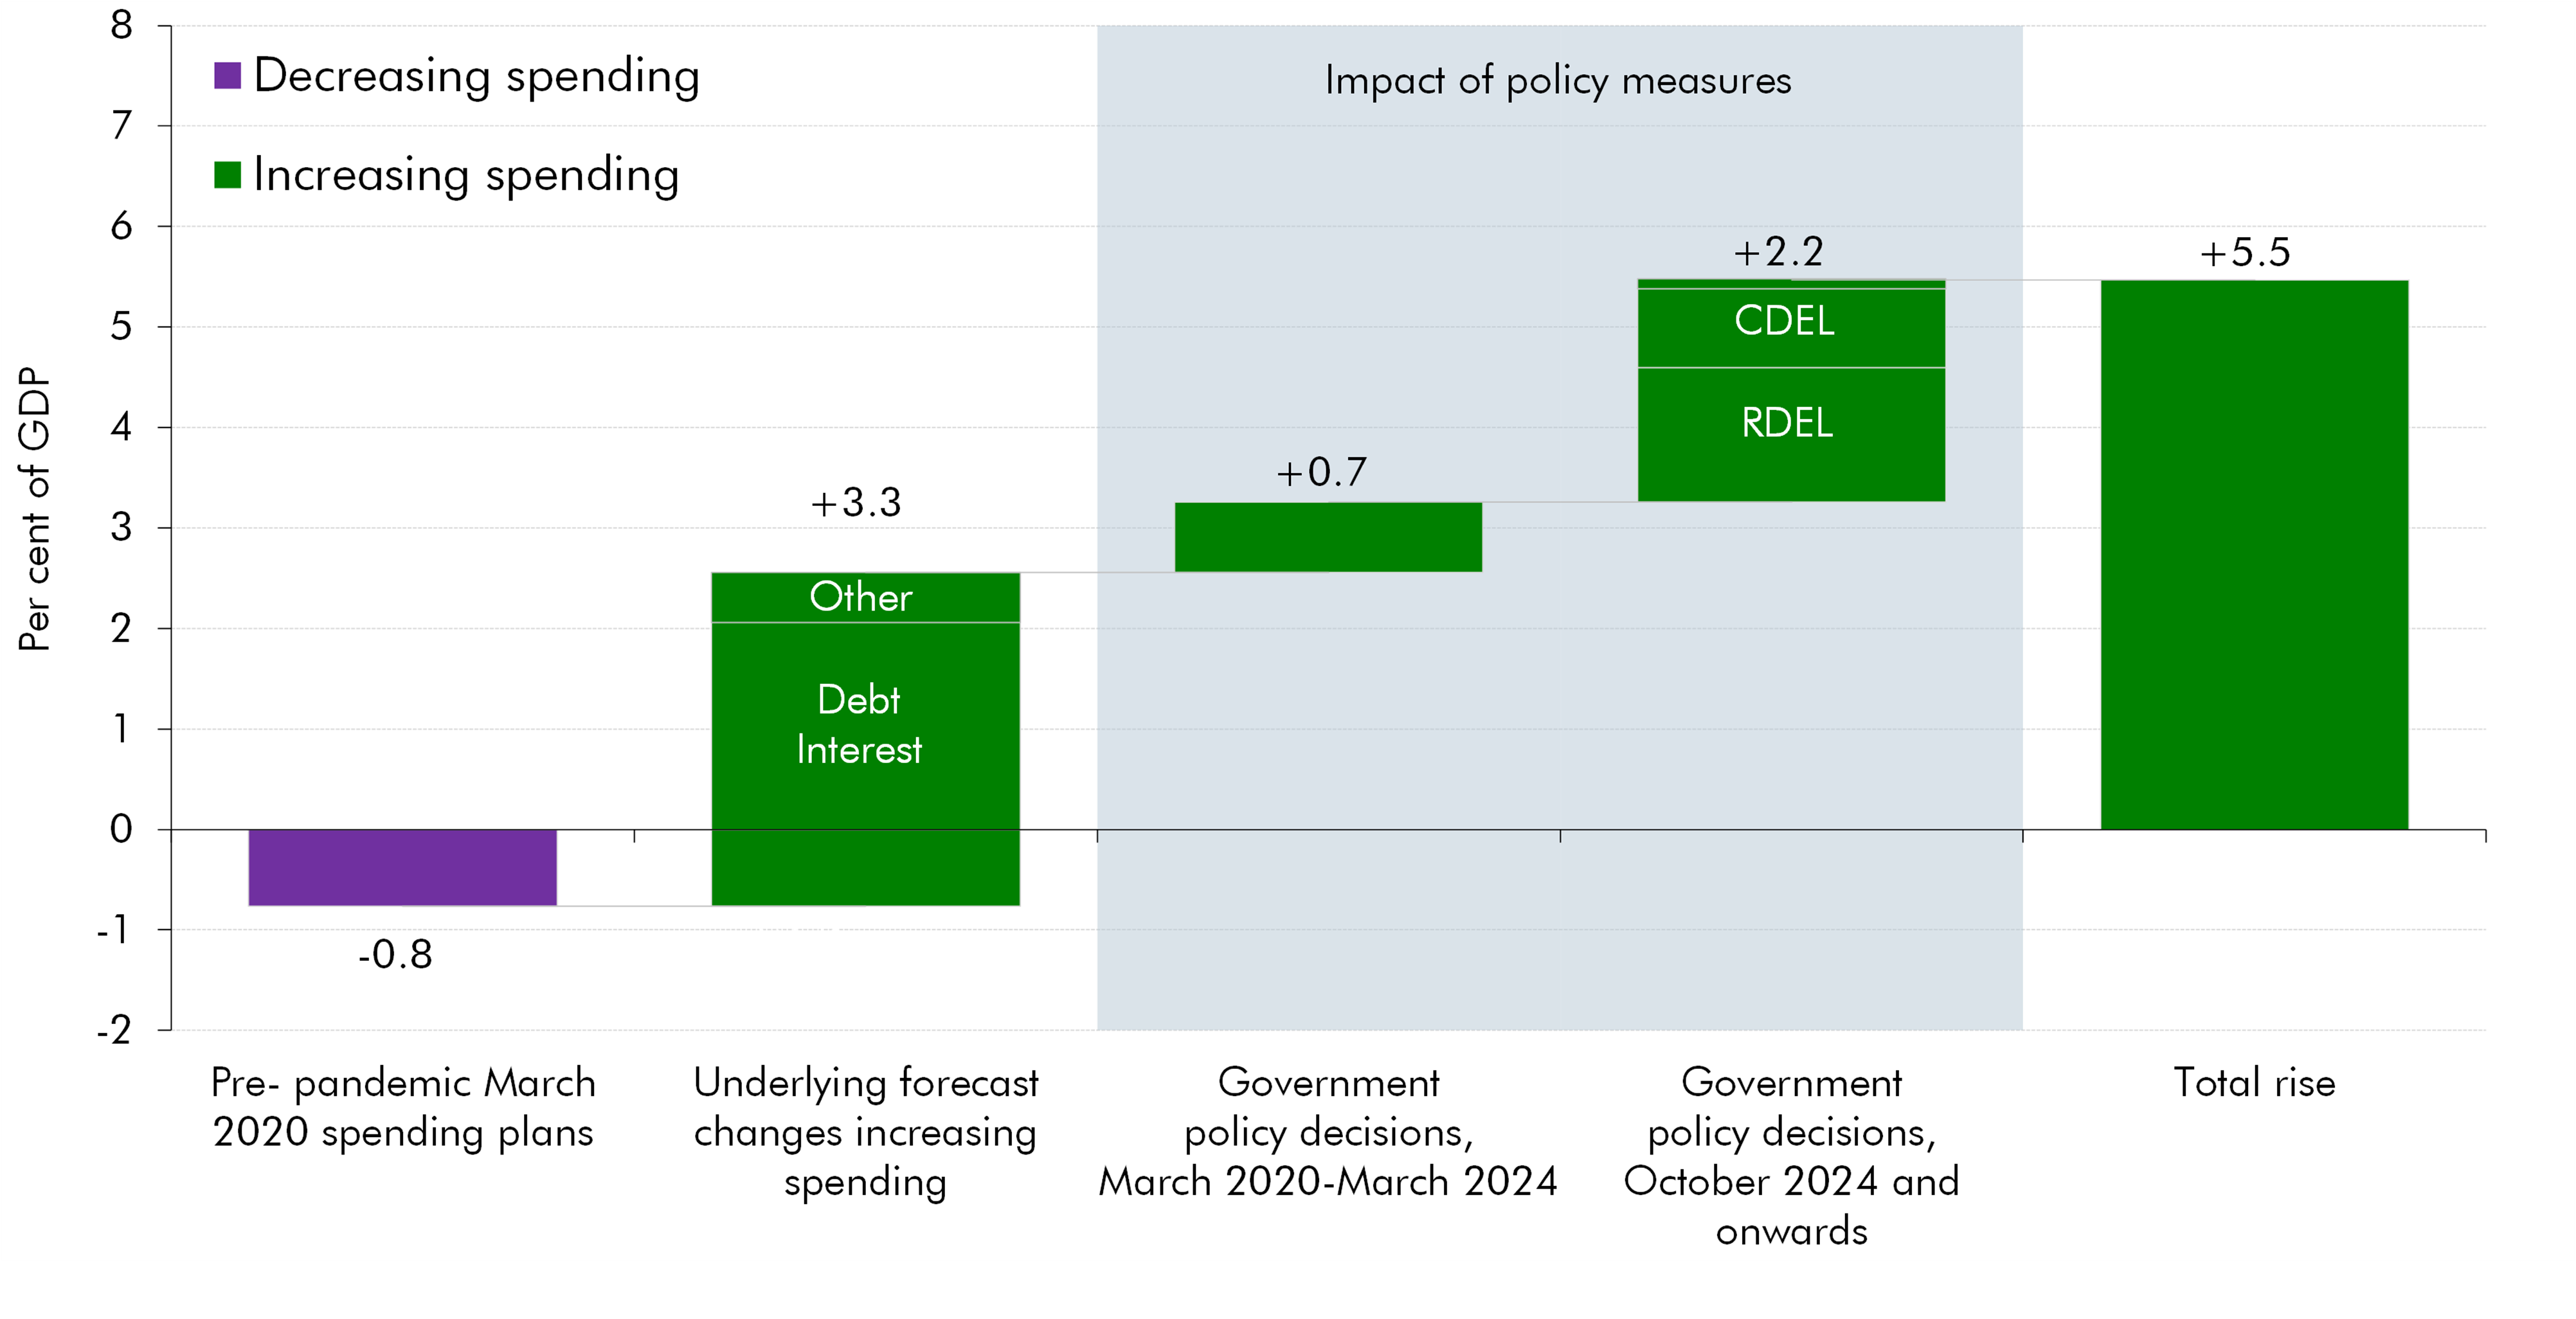
Note: ‘October 2024 and onwards’ incorporates Government policy decisions that were made between March and October 2024.
Source: ONS, OBR
Changes in spending since the March 2026 forecast
5.6 Table 5.2 shows that spending is forecast to rise by £31 billion a year on average over the forecast period compared to the March 2026 forecast. The main drivers of this increase include:
-
Underlying forecast differences, which increase spending by £27 billion a year on average. This is primarily driven by debt interest spending which is £14 billion higher a year on average across the forecast period, largely due to higher Bank Rate and gilt rate expectations. Higher CPI uprating increases welfare spending by £5 billion a year on average. Changes in the local authority net spending and public corporations’ capital expenditure forecasts described in paragraphs 5.26 and 5.32 further increase spending by £4 billion a year on average.
-
PSNB-neutral forecast differences, which are offset in receipts, raise spending by £1.3 billion a year on average.
-
The direct effect of Government decisions announced in this Budget increases borrowing across the first five years of the forecast by £3.3 billion a year on average, driven largely by higher defence spending. The largely offsetting effects on DEL and AME of the unfunded pensions valuation are discussed in more detail in paragraphs 5.8 and 5.32. Spending policy decisions are described in more detail in Chapter 3.
-
The indirect effects of Government decisions announced in this Budget increase spending by £0.1 billion a year on average. This mainly reflects higher debt interest from the near-term increase in borrowing due to policy, and a reduced departmental underspend judgement in 2027-28. These effects are partly offset by lower benefit uprating due to some policy measures slightly reducing inflation.
Table 5.2: Total managed expenditure: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| March 2026 forecast | 1,368 | 1,419 | 1,472 | 1,513 | 1,555 | 1,611 |
| October 2026 forecast | 1,366 | 1,449 | 1,504 | 1,549 | 1,587 | 1,638 |
| Difference | -2.4 | 29.9 | 32.1 | 35.1 | 31.6 | 27.9 |
| By policy and forecast differences | ||||||
| of which: | ||||||
| Underlying forecast differences(1) | 1.9 | 25.6 | 26.3 | 31.0 | 29.9 | 26.9 |
| PSNB-neutral forecast differences(2) | -4.3 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Direct effect of Government decisions | 0.0 | 5.8 | 3.9 | 3.5 | 1.7 | 1.6 |
| Indirect effects of Government decisions | 0.0 | -1.6 | 1.9 | 0.6 | 0.0 | -0.6 |
| By spending category | ||||||
| of which: | ||||||
| Capital DEL | 5.6 | 5.2 | -2.6 | -1.1 | -0.5 | -1.2 |
| Resource DEL | 3.7 | 7.2 | -9.0 | -8.8 | -9.4 | -9.4 |
| of which: | ||||||
| Unfunded pensions valuation change | 0.0 | 0.0 | -15.4 | -15.7 | -15.9 | -16.2 |
| Other | 3.7 | 7.2 | 6.4 | 6.9 | 6.6 | 6.8 |
| Other AME | -11.2 | 2.8 | 18.0 | 18.7 | 17.6 | 18.3 |
| of which: | ||||||
| Unfunded pensions valuation change | 0.0 | 0.0 | 16.5 | 16.8 | 17.1 | 17.4 |
| Other | -11.2 | 2.8 | 1.5 | 2.0 | 0.5 | 0.9 |
| Local government net spending | -1.0 | 0.9 | 2.8 | 2.1 | 1.3 | 0.3 |
| Welfare spending | 0.9 | -0.1 | 4.1 | 8.3 | 7.5 | 6.1 |
| Debt interest, net of APF | -0.9 | 14.5 | 17.3 | 13.0 | 12.7 | 12.4 |
| PSNB-neutral spending(3) | 0.6 | -0.6 | 1.6 | 2.7 | 2.4 | 1.3 |
| Memo: difference ex PSNB-neutral spending | -2.9 | 30.5 | 30.6 | 32.3 | 29.2 | 26.6 |
| 1) Excludes PSNB-neutral forecast changes. |
| 2) Pre-measures basis, includes depreciation, VAT refunds, environmental levies, extended producer responsibility (EPR), community infrastructure levy (CIL), and council tax. |
| 3) Includes general government depreciation, current VAT refunds, and environmental levies, as EPR is included within the resource DEL line, and council tax and CIL are included within the local government net spending line. |
| Source: ONS, OBR |
Analysis of expenditure by category
Spending within departmental expenditure limits (DEL)
5.7 As set out in Table 5.1, spending subject to departmental expenditure limits makes up almost half of all public spending. The current spending review period runs to 2028-29 for resource, and 2029-30 for capital spending. As stated in paragraph 5.2, beyond these years there are no detailed departmental spending plans and so our forecast is based on assumptions for total resource and capital spending that are set by the Government. In line with the Charter for Budget Responsibility, the next spending review will take place in 2027 and set DEL budgets for a minimum of three years. In the rest of this section, ‘RDEL spending’ refers to departmental resource, or day-to-day, spending, and ‘CDEL spending’ refers to departmental capital, or investment, spending.[footnote 47] Total DEL (or TDEL) is the sum of both RDEL and CDEL.
5.8 When analysing spending in real terms (that is, adjusted for the GDP deflator) over the forecast and when comparing real growth rates between this forecast and the last we have made the following adjustments:
-
We have removed from the October 2026 forecast the reductions to RDEL related to the 2024 valuation of unfunded public service pension schemes. The Government Actuary’s Department recommended a lower employer contribution rate in the valuation reports published thus far, primarily because of increases to the discount (‘SCAPE’) rate.[footnote 48] Employer pension contribution rates are reduced from 2027-28, providing savings to departments, and the government has correspondingly reduced RDEL by £16 billion a year. The lower pension contributions act to increase net spending and increase AME by a similar amount to the reduction in RDEL, making these changes broadly neutral for overall spending.[footnote 49] The unfunded pensions forecast is covered in more detail in paragraph 5.32.
-
We have restated the March 2026 forecast for classification changes between DEL and AME made at this forecast. For RDEL, this includes the switch of central government subsidies to public corporations,[footnote 50] and business rates under-indexation compensation and relief grants from AME to DEL,[footnote 51] which increase RDEL by an average of £3.3 billion over the forecast period. For CDEL, the switch of the British Business Bank from DEL to AME decreases CDEL by an average of £0.1 billion over the forecast period. [footnote 52]
5.9 In cash terms, total departmental spending (TDEL) is forecast to rise over the forecast period to reach £762 billion in 2031-32, with RDEL set to reach £621 billion and CDEL £141 billion, as shown in Table 5.4. As shown in Table 5.3 and Chart 5.4 by the dotted line, in real terms and excluding the adjustments above, RDEL spending is set to grow by an average 1.1 per cent over the forecast period, with fastest growth this year at 2.8 per cent. If we include the reduction in RDEL due to the 2024 valuation changes (the solid blue line in Chart 5.4), the real rate of growth of RDEL is on average 0.7 per cent. Real CDEL spending is set to grow at a rate of 0.4 per cent on average over the forecast. Within this there are real-terms reductions forecast in the next three years from 2027-28 to 2029-30, and an assumption of on average 0.9 per cent growth in the final two years of the forecast.
Chart 5.4: Real departmental resource (RDEL) and capital (CDEL) spending
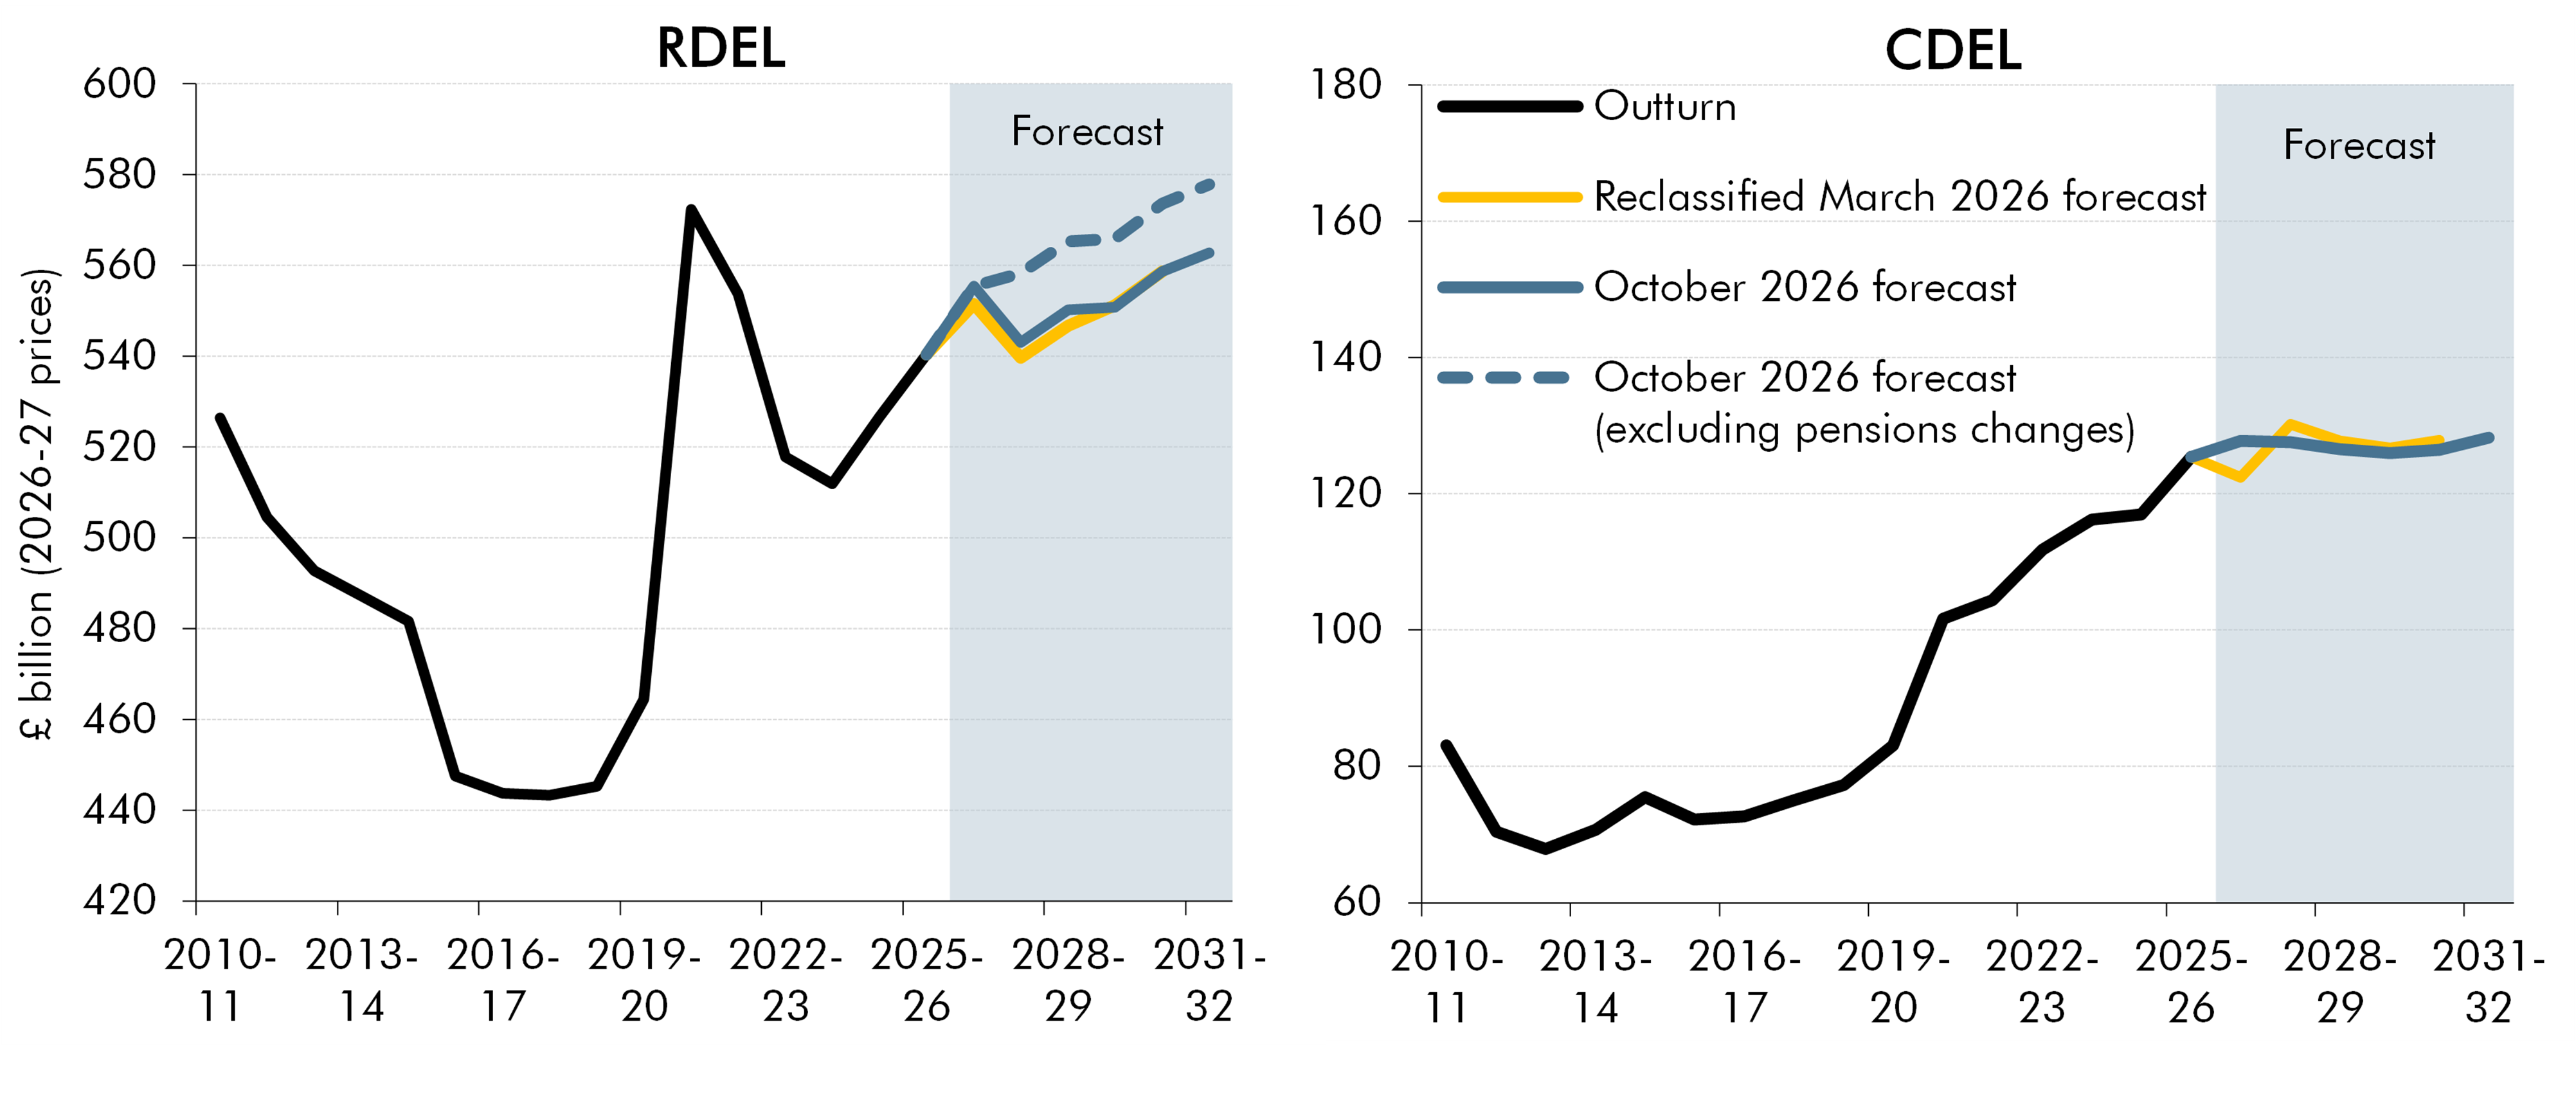
Note: The “Reclassified March 2026 forecast” is the March 2026 forecast adjusted for switches between DEL and AME as detailed in paragraph 5.8. The “October 2026 forecast (excluding pensions changes)” removes the reduction in RDEL from 2027-28 onwards as a result of valuation changes to unfunded pensions (see paragraph 5.8 for more details).
Source: HM Treasury, ONS, OBR
Table 5.3: Departmental spending: real growth rates
| Per cent | ||||||
|---|---|---|---|---|---|---|
| 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Reclassified March 2026 forecast | ||||||
| TDEL real growth rate | 2.9 | 1.7 | 0.6 | 0.5 | 1.2 | |
| of which: | ||||||
| RDEL real growth rate | 2.9 | 0.6 | 1.2 | 0.8 | 1.3 | |
| CDEL real growth rate | 3.0 | 6.4 | -1.9 | -0.8 | 0.8 | |
| October 2026 forecast (excluding changes from pensions valuation change) | ||||||
| TDEL real growth rate | 2.6 | 0.4 | 0.9 | 0.0 | 1.2 | 0.8 |
| of which: | ||||||
| RDEL real growth rate | 2.8 | 0.5 | 1.3 | 0.1 | 1.4 | 0.7 |
| CDEL real growth rate | 1.9 | -0.2 | -0.8 | -0.4 | 0.4 | 1.4 |
| October 2026 forecast | ||||||
| TDEL real growth rate | 2.6 | -1.8 | 0.9 | 0.0 | 1.2 | 0.9 |
| of which: | ||||||
| RDEL real growth rate | 2.8 | -2.2 | 1.3 | 0.1 | 1.4 | 0.7 |
| CDEL real growth rate | 1.9 | -0.2 | -0.8 | -0.4 | 0.4 | 1.4 |
| Note: Classification changes are set out in full in paragraph 5.8. |
| Source: HM Treasury, OBR |
Table 5.4: Departmental spending: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Forecast | ||||||
| 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| March 2026 RDEL | 548.2 | 563.7 | 581.8 | 594.2 | 614.2 | |
| October 2026 RDEL | 555.5 | 554.6 | 573.0 | 584.8 | 604.8 | 620.9 |
| Difference | 7.2 | -9.0 | -8.8 | -9.4 | -9.4 | |
| of which: | ||||||
| Change in underspend | -1.7 | -0.6 | 1.9 | |||
| Forecast | 0.2 | 0.6 | 0.8 | 0.6 | 0.5 | |
| Classification changes | 3.3 | 2.0 | 1.6 | 4.9 | 5.0 | 5.1 |
| Policy | 5.5 | -12.0 | -13.0 | -14.9 | -14.9 | -20.6 |
| of which: | ||||||
| Unfunded pensions valuation change | -15.4 | -15.7 | -15.9 | -16.2 | -16.6 | |
| Other policy | 5.5 | 3.4 | 2.6 | 1.1 | 1.3 | -4.0 |
| Post-measures underspend judgement | 1.0 | |||||
| March 2026 CDEL | 122.5 | 132.8 | 132.8 | 134.2 | 138.1 | |
| October 2026 CDEL | 127.7 | 130.2 | 131.7 | 133.7 | 136.9 | 141.4 |
| Difference | 5.2 | -2.6 | -1.1 | -0.5 | -1.2 | |
| of which: | ||||||
| Change in underspend | 5.2 | -0.8 | -0.3 | 0.3 | ||
| Forecast | 0.2 | 0.6 | 0.5 | 0.4 | 0.5 | |
| Classification changes | -0.1 | -0.1 | -0.1 | -0.1 | -0.1 | -0.1 |
| Policy | -0.1 | -2.3 | -1.2 | -1.1 | -1.5 | -1.9 |
| Memo: October 2026 RDEL underspend assumption | -3.5 | -1.5 | 0.0 | |||
| Memo: October 2026 CDEL underspend assumption | -4.5 | -4.5 | -4.0 | -3.5 |
| Note: The OBR sets underspend (or overspend) assumptions for those years covered by spending reviews. HM Treasury sets underspend assumptions for years beyond spending reviews. |
| Note: Classification changes are set out in full in paragraph 5.8. |
| Source: HM Treasury, OBR |
Departmental spending allocations in 2026-27
5.10 As Table 5.4 shows, RDEL is now forecast to be £555 billion in 2026-27, an increase on our March forecast of £7.2 billion. This difference is made up of:
-
Policy measures which have increased spending by £5.5 billion in 2026-27 – primarily a £2.6 billion council tax rebate and a £2.1 billion increase in defence spending.
-
A set of reclassifications of AME spending into DEL (as set out in paragraph 5.8) have overall increased DEL spending by an estimated £3.3 billion.
-
These are partially offset by our judgement that overall departments will underspend their resource budgets by a larger amount (£3.5 billion) than our previous March forecast (£1.8 billion), based on our assessment of the most recent spending outturn data so far this year.
5.11 The lower panel of Table 5.4 shows that CDEL is now forecast to be £128 billion in 2026-27 which is a £5.2 billion increase on our March forecast. This difference is almost entirely a reduction in our underspend judgement, which increases spending by £5.2 billion. We now expect that departments will underspend their capital budgets by £4.5 billion, compared to the £9.7 billion we estimated in March. Capital underspends were lower than we expected in 2023-24, 2024-25, and 2025-26 and departments have spent a higher-than-average proportion of capital than expected at this point in the year.[footnote 53] Lower underspends may indicate departments have become better able to spend their budgets during periods of fast real growth in capital spending than was the case in the past.[footnote 54]
Departmental spending allocations in the rest of the Spending Review period
5.12 As shown in the top panel of Table 5.4, RDEL is expected to increase by £18 billion over the remaining two years of the Spending Review period (2027-28 to 2028-29), to reach £573 billion by 2028-29. This is £9 billion lower than we expected in the March 2026 forecast, with the main changes due to:
-
Policy changes, including the reduction in RDEL to reflect lower employer pension contributions, which lower RDEL spending by an average of £13 billion a year. Excluding the pension change, RDEL policies increase spending by an average £3.0 billion, primarily reflecting higher defence funding.
-
Classification changes increasing the forecast by an average £1.8 billion.
-
Forecast changes reflecting updated estimates of the composition of DEL, with more included as fiscal spending, further increase spending by an average £0.7 billion.
-
An increase in our underspend judgement in 2028-29 reflecting the spending pressures discussed in more detail below.
5.13 As shown in the lower panel of Table 5.4, CDEL is expected to increase by £6.0 billion over the remaining three years of the Spending Review period for capital spending, to reach £134 billion by 2029-30. Compared to the March 2026 forecast capital spending is on average forecast to be £1.4 billion lower over this period, with the main changes due to:
-
Policy changes which reduce spending by an average of £1.5 billion a year. These are primarily reductions to departmental capital budgets announced as part of the funding for the defence investment plan.
-
Small changes to the underspend judgements on average reduce spending by £0.3 billion to reflect lower pressures on capital budgets, and small classification changes reduce spending by an average of £0.1 billion. Both are offset by forecast updates taking on revised estimates of the composition of DEL, which increase spending by an average £0.5 billion.
Pressures in the Spending Review period
5.14 There are some significant pressures on departmental spending limits over the remainder of the Spending Review. Particular risks include:
-
Higher-than-expected inflation reduces the real spending power of departments as DEL budgets are set in cash terms. Based on the increase in inflation in this forecast compared to the March 2026 forecast, nominal spending would need to be on average £2 billion higher in each year of the Spending Review to maintain the real value of departmental spending plans. Compared to the inflation forecast in March 2025, when the current Spending Review envelope was set, nominal spending plans would need to be on average £7 billion higher in each year than the original Spending Review envelopes to maintain the real value of departmental spending plans.
-
Central government spending on public sector pay makes up around 40 per cent of total RDEL. If all pay settlements were on average 1 per cent higher than expected this would increase public sector pay spending by around £2 billion per year. Higher inflation increases the general risk that there will be pressure for higher pay settlements than anticipated when budgets were set.
-
Efficiency savings: as part of the 2025 Spending Review, the Government published departmental efficiency plans, with the aim of delivering £14 billion in annual efficiency savings by 2028-29.[footnote 55] Some past efficiency programmes have not delivered the initially expected levels of savings.[footnote 56] If this were to be the case again then this would place further pressure on spending envelopes.
-
Other pressures: some specific areas of spending where cost pressures could be significantly higher or lower than expected include:
-
Special educational needs and disabilities (SEND) provision, where the number of children with education, health and care plans (EHCP) increased by 12.5 per cent between January 2025 and January 2026. While data suggests growth in referrals has slowed over the same period, the impact that the reforms announced in February 2026 will have on spending in this area remains very uncertain.[footnote 57] Elsewhere within schools the falling number of pupils in secondary schools could reduce pressures on school spending if it results in a reduction in the number of schools and teachers.[footnote 58]
-
Accommodation for asylum seekers, where the number of asylum seekers in receipt of Home Office support has fallen by 12 per cent between June 2025 and June 2026, and at 90,000 is 25 per cent below the September 2023 peak of 120,000.[footnote 59] The numbers of asylum claims, and detected illegal arrivals, were 5,000 (6 per cent) and 500 (16 per cent) lower in 2025-26 compared to 2024-25, suggesting the number of asylum seekers in receipt of Home Office support will fall further if the Government can maintain the current level of claim processing. The implications for local government spending is discussed in paragraph 5.27.
-
Prisons and wider justice system, where the Government’s response to capacity pressures on prisons through the early prisoner release scheme could increase costs in probation services given existing staffing shortages estimated at 3,150 sentence management staff in 2026-27[footnote 60] mean the marginal cost of expanding these services will be high. There are additional pressures in courts with crown case backlogs standing at around 80,000 and open tribunal cases reaching the highest level since 2012-13 at 860,000.[footnote 61] [footnote 62]
5.15 There is a particular risk to RDEL spending plans in 2028-29 because they are due to be reconsidered in the next spending review. Historically, the real growth of RDEL has typically been higher than originally planned in the final year covered in overlapping Spending Reviews. Based on our assessment of these and wider pressures, at this event we assume that departments will not underspend against existing RDEL plans in 2028-29. This follows the judgement made in our November 2025 forecast to reduce the underspend assumption in 2028-29 to account for pressures from SEND spending. We have kept our underspend assumptions largely unchanged for CDEL.
Departmental spending after the Spending Review period
5.16 Following the end of the Spending Review period, the Government provides an overall assumption for total resource and capital spending for the remainder of the forecast:
-
Total departmental resource spending is assumed to reach £620 billion by the end of the forecast, implying average annual real terms growth of 0.8 per cent over these three years. In the final year of the forecast, the real-terms growth rate is reduced to 0.7 per cent, a reduction of £5.5 billion to the pre-measures spending assumption of keeping RDEL constant as a share of GDP.
-
Total departmental capital spending is assumed to reach £140 billion by 2031-32, implying real terms growth of 0.9 per cent in the final two years of the forecast.
5.17 To illustrate the spending implications of these assumed envelopes, we consider what commitments in some areas of spending imply for growth in spending in areas not covered by commitments, often called ‘unprotected’ spending. In terms of day-to-day departmental spending (RDEL), we assume the following:
-
Spending on the NHS grows at 2.6 per cent a year in real terms after 2028-29, in line with growth rates set at the 2025 Spending Review.
-
Spending on defence is expected to rise from 2.6 per cent of GDP in 2026-27 to 2.7 per cent of GDP in 2029-30, and to then rise to 3.0 per cent of GDP in 2030-31 and to 3.1 per cent of GDP in 2031-32, in line with the Government’s Defence Investment Plan and its commitment announced at this Budget to reach 3.5 per cent of GDP in 2035. The total additional 0.9 per cent of GDP on defence spending in 2035-36 would represent around £35 billion in 2026-27 terms. We assume that the fraction of NATO-qualifying defence spending that is spent on day-to-day expenditure within the RDEL envelope is held constant to that planned in 2029-30.
-
Spending on Official Development Assistance (ODA) grows in line with gross national income (GNI) after 2028-29, in line with the Government’s commitment to spend 0.3 per cent of GNI on ODA by 2027.
-
Underlying spending on special educational needs (SEND) grows by 0.4 per cent a year in real terms reflecting the Treasury’s stated assumption, and spending on the remaining core mainstream schools budget is held flat per pupil in real terms as a policy-neutral baseline.
5.18 Within the assumed envelope for total RDEL spending provided by the Treasury, these assumptions would leave other ‘unprotected’ RDEL spending (accounting for just over a quarter of day-to-day departmental spending) falling by 2.6 per cent a year in real terms in the final three years of the forecast. Spending would have to be £11 billion higher in 2031-32 for unprotected spending not to fall in real terms from 2028-29. As outlined in Box 4.2 in the March 2024 Economic and fiscal outlook (EFO), as spending reviews have approached, governments have increased annual real growth in resource spending over spending review periods by an average 1.1 per cent, equivalent to £6 billion in 2028-29.[footnote 63] Capital spending would need to be an average £2 billion a year higher for the remaining years of the current spending review period to restore its real terms value to that set out in the 2025 Spending Review. These calculations do not include the funding for HMRC and DWP compliance, debt, and fraud and error programs set out in Table 3.2. Including this funding would marginally increase the fall in unprotected departments to 2.7 per cent a year in real terms in the final three years of the forecast.
Chart 5.5: Implied average annual real growth in RDEL spend
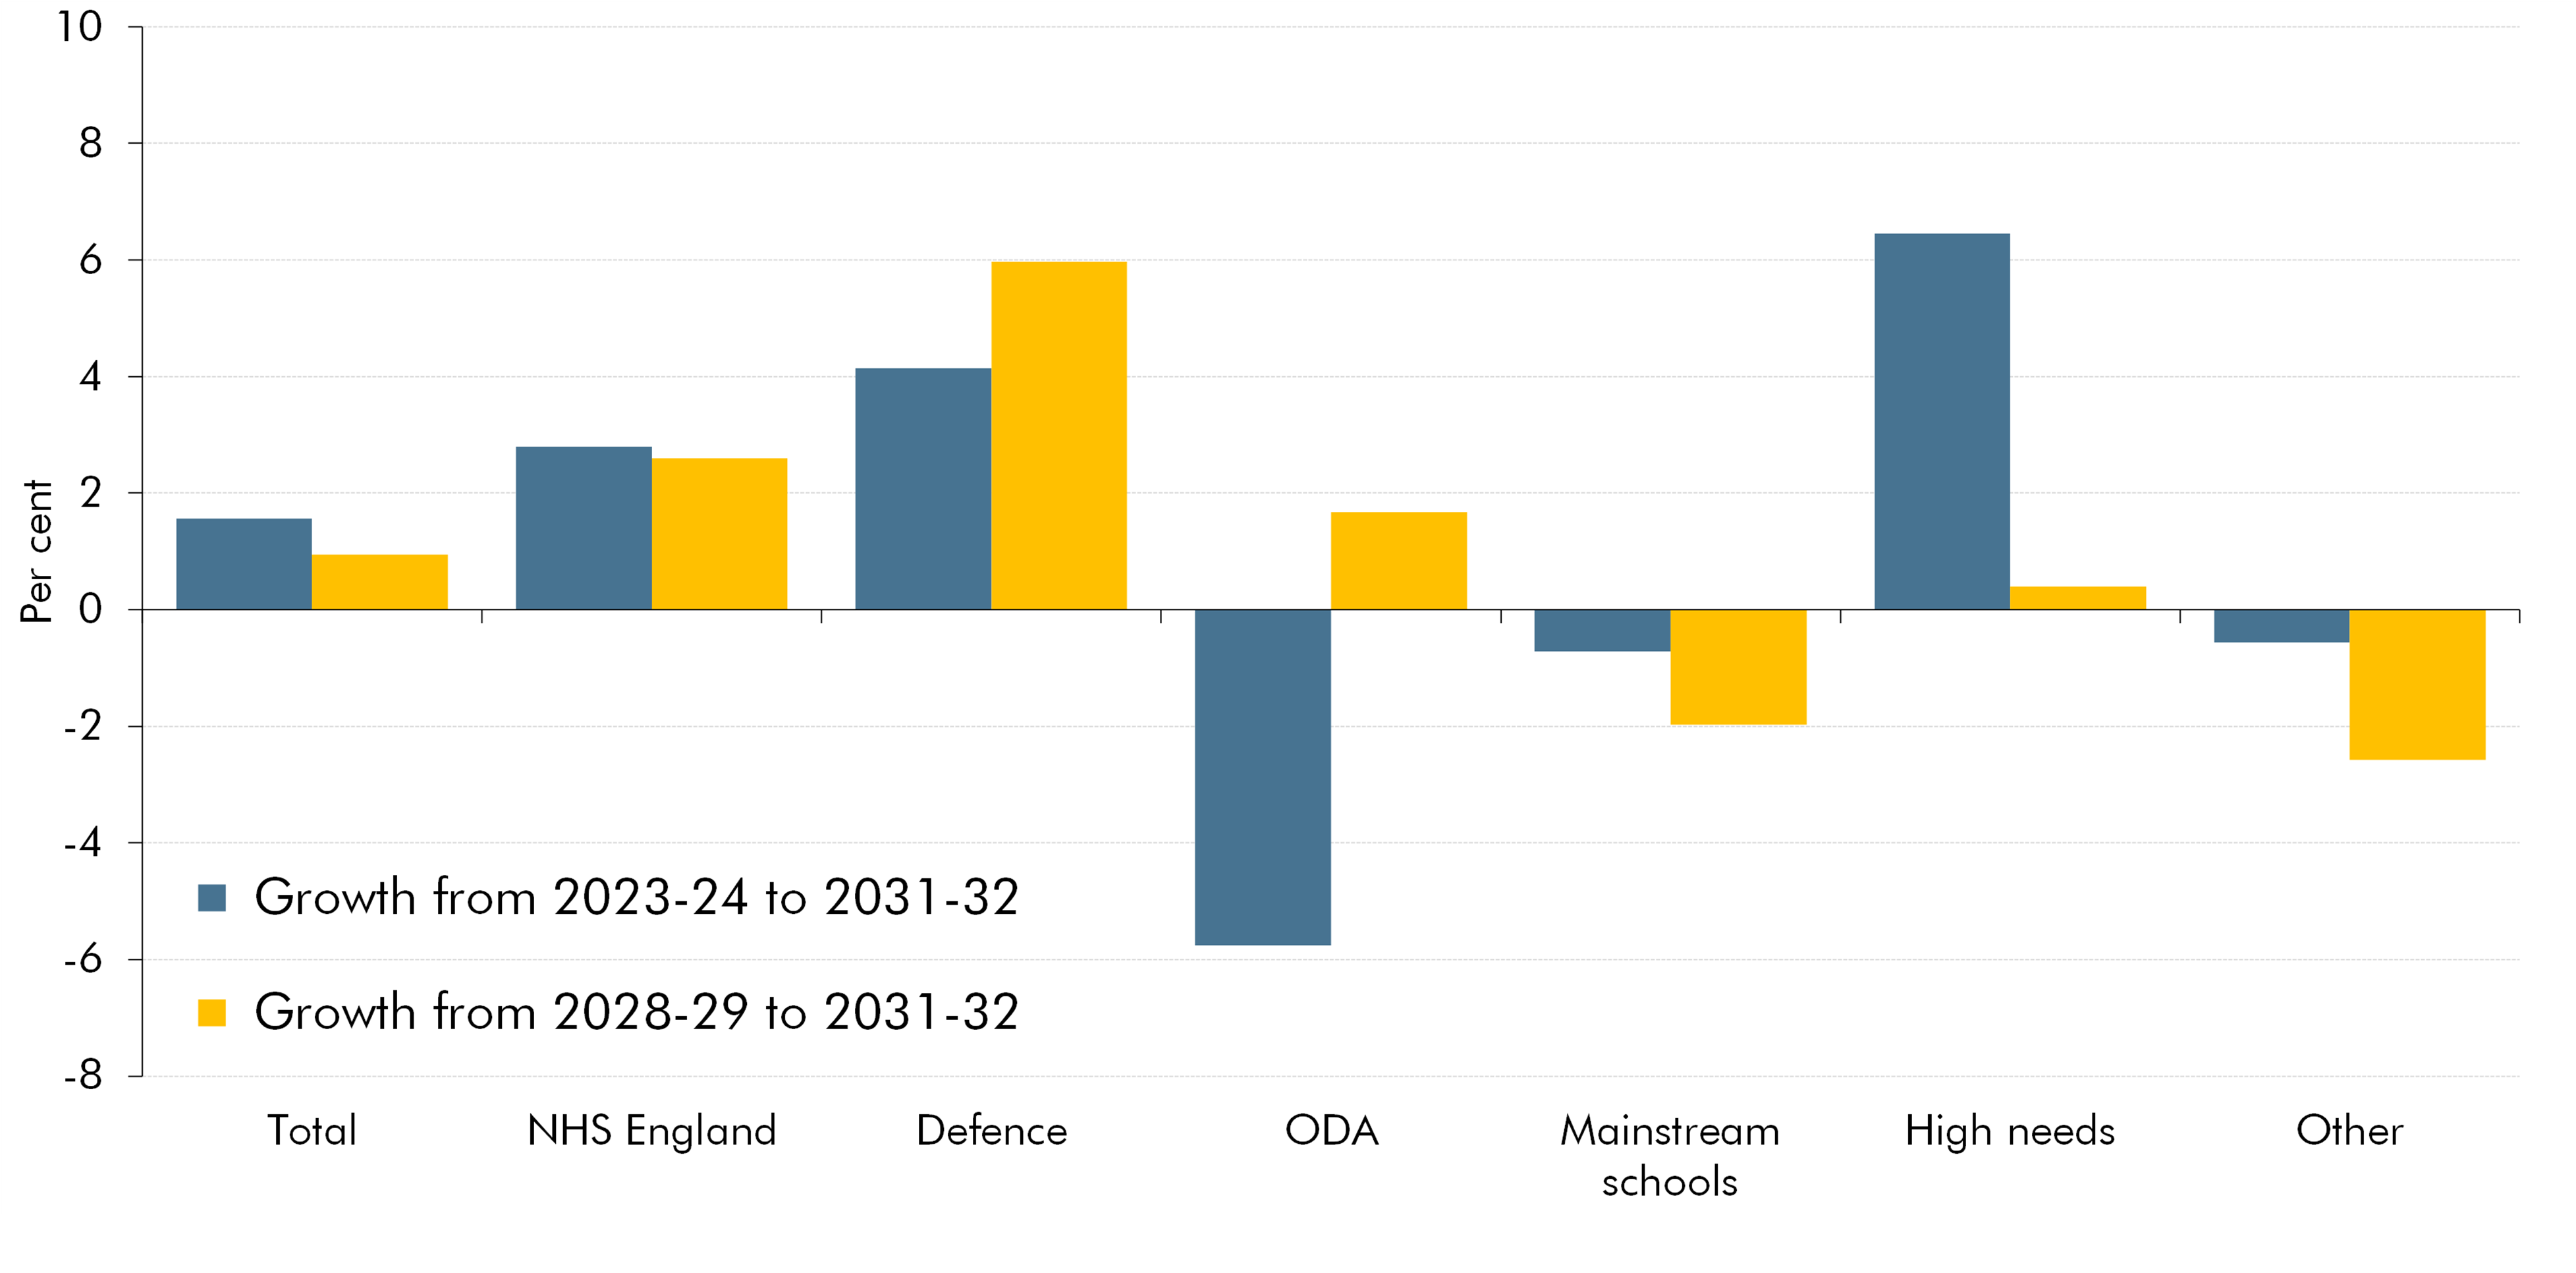
Source: HM Treasury, OBR
5.19 There are other longer-term government policy ambitions which would create further pressure on spending beyond the current spending review period but are not yet possible to fully quantify as policy details have not been finalised. These include:
-
the ambition to carry out the biggest council housebuilding programme “since the post-war boom ended in the early 1980s”,[footnote 64] the cost of which would depend on the final details of the programme and its scale. The capital grant required to cover the cost of building a new property for social rent varies between around £150,000 and £200,000 depending on location. The Government expects the existing Social and Affordable Homes Programme (SAHP) to deliver 180,000 new social homes between 2026 and 2036.[footnote 65] To illustrate the potential costs of this commitment, we assume that to return council housebuilding to 1980s levels would require at least a further 22,000 houses to be built each year in addition to those expected through the SAHP scheme.[footnote 66] If all these additional houses required capital grants, the additional cost would be between £3 billion and £4 billion each year.
-
As discussed further in Chapter 3, the Government intends to reform social care provision and establish a National Care Service in England. Estimates previously produced by the Health Foundation suggest that, depending on the generosity and design of the system, costs could vary between £3.5 billion and £17 billion a year.[footnote 67]
Welfare spending
5.20 Total welfare spending in the forecast refers to AME spending on social security and tax credits. Around half is subject to the Government’s ‘welfare cap’, which excludes the state pension and those payments most sensitive to the economic cycle (we discuss performance against the cap in Chapter 7). The welfare spending forecast is based on the determinants in the latest economy forecast – principally population, unemployment, earnings, and inflation – and informed by the latest outturn data and Department for Work and Pensions (DWP) models.
5.21 Welfare spending is forecast to rise this year by £19 billion (5.7 per cent) to £353 billion or 11.1 per cent of GDP (Table 5.5). It is then forecast to rise in nominal terms by an average of £16 billion (4.4 per cent) a year over the rest of the forecast period, reaching £431 billion or 11.3 per cent of GDP in 2031-32. This would be 1.3 per cent of GDP higher than its pre-pandemic level of 10.1 per cent of GDP in 2019-20, with 0.5 per cent of GDP of this increase occurring between 2025-26 and 2031-32. Chart 5.6 shows that this rise is driven primarily by health-related and pensioner benefit spending, which are forecast to be 0.4 per cent of GDP and 0.3 per cent of GDP higher respectively in 2031-32 than 2025-26, while spending on all other welfare is forecast to fall by 0.2 per cent of GDP over the same period. We explore trends in welfare as a share of GDP further in Box 5.1.
5.22 Health-related benefit caseloads have seen very high rates of growth since the pandemic, with the incapacity caseload growing from 2.5 million to 3.7 million between 2019-20 and 2025-26, and the disability caseload growing from 4.7 million to 6.9 million over the same period.[footnote 68] The extent to which these rates of growth will persist is a highly uncertain component of the forecast. We currently assume that some but not all of the drivers of this growth will persist into the medium term, with health-related spending forecast to grow by an additional 0.4 per cent of GDP over the forecast period on top of the 0.7 per cent of GDP growth observed between 2019-20 and 2025-26. If incapacity and disability caseloads kept increasing at post-pandemic growth rates, spending in 2031-32 would be roughly £25 billion higher than in our central forecast. If growth fell back to pre-pandemic rates, spending in 2031-32 would be roughly £13 billion lower than in our central forecast.
5.23 The latest outturn data on health-related benefit caseloads suggests both downside and upside risks to this judgement. Over the last 18 months, the approval rates at assessment have been falling for both incapacity and child/working-age disability benefits, such that a lower share of new claims receive a benefit award. If this trend were to continue then it could lead to a reduction in future caseloads and expenditure forecasts. Conversely, incapacity off-flow rates have been falling for several years in outturn. If sustained, this could lead to lower off-flows at subsequent forecasts than we are currently expecting, resulting in higher caseloads and expenditure forecasts.
Table 5.5: Welfare spending
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Pensioner spending(1) | 161.4 | 169.8 | 175.3 | 182.4 | 191.2 | 199.9 | 209.8 |
| UC and legacy equivalents(2) | 92.8 | 96.9 | 100.1 | 102.8 | 104.9 | 107.1 | 110.7 |
| Disability benefits(3) | 45.3 | 50.2 | 54.7 | 58.7 | 62.3 | 65.9 | 69.6 |
| Child benefit | 13.4 | 13.7 | 13.9 | 14.1 | 14.0 | 14.0 | 13.9 |
| Other spending(4) | 20.8 | 22.0 | 23.2 | 24.2 | 25.1 | 26.2 | 27.2 |
| Total welfare spending | 333.8 | 352.7 | 367.2 | 382.1 | 397.5 | 413.1 | 431.3 |
| of which: | |||||||
| Inside welfare cap | 170.1 | 180.2 | 188.2 | 196.8 | 204.7 | 212.2 | 220.5 |
| Outside welfare cap | 163.7 | 172.5 | 179.0 | 185.3 | 192.7 | 200.8 | 210.8 |
| Memo: total welfare (per cent of GDP) | 10.9 | 11.1 | 11.2 | 11.2 | 11.2 | 11.2 | 11.3 |
| of which: | |||||||
| Pensioner spending | 5.3 | 5.3 | 5.3 | 5.3 | 5.4 | 5.4 | 5.5 |
| Health and disability benefits(5) | 2.8 | 2.9 | 3.0 | 3.1 | 3.1 | 3.1 | 3.2 |
| Other spending | 2.8 | 2.8 | 2.8 | 2.8 | 2.7 | 2.7 | 2.7 |
| Memo: health and disability benefits | 85.6 | 92.4 | 99.2 | 105.0 | 109.7 | 114.8 | 120.2 |
| of which: | |||||||
| Children | 7.1 | 8.1 | 9.1 | 9.9 | 10.5 | 11.1 | 11.6 |
| Working-age adults | 63.0 | 67.2 | 71.9 | 75.9 | 79.1 | 82.4 | 85.9 |
| Pensioners | 15.5 | 17.1 | 18.2 | 19.2 | 20.2 | 21.4 | 22.7 |
| 1) Pensioner spending includes pensioner housing benefit, pension credit, winter fuel payment, and state pension expenditure. |
| 2) UC and legacy equivalents includes personal tax credits, housing benefit (excluding pensioner part), incapacity benefits (which comprise employment and support allowance, income support for incapacity, severe disablement allowance, and incapacity benefit), income support, and income-based and contributory jobseeker’s allowance. |
| 3) Disability benefits includes disability living allowance, personal independence payment, and attendance allowance. |
| 4) Other spending includes Northern Ireland social security expenditure. |
| 5) Health and disability benefits includes standard allowance and health element expenditure for UC health-related claimants, employment and support allowance, incapacity benefit, severe disablement allowance, income support for incapacity, disability living allowance, personal independence payment, attendance allowance, UC carer’s element expenditure, carer’s allowance, income support for carers, and UC disabled child element expenditure. Excludes Northern Ireland expenditure. A breakdown of the components of this line, along with an alternative definition which excludes carer-related spending, is available in our detailed forecast tables. |
| Source: DWP, HMRC, OBR |
Chart 5.6: Cumulative change in welfare spending compared to 2025-26
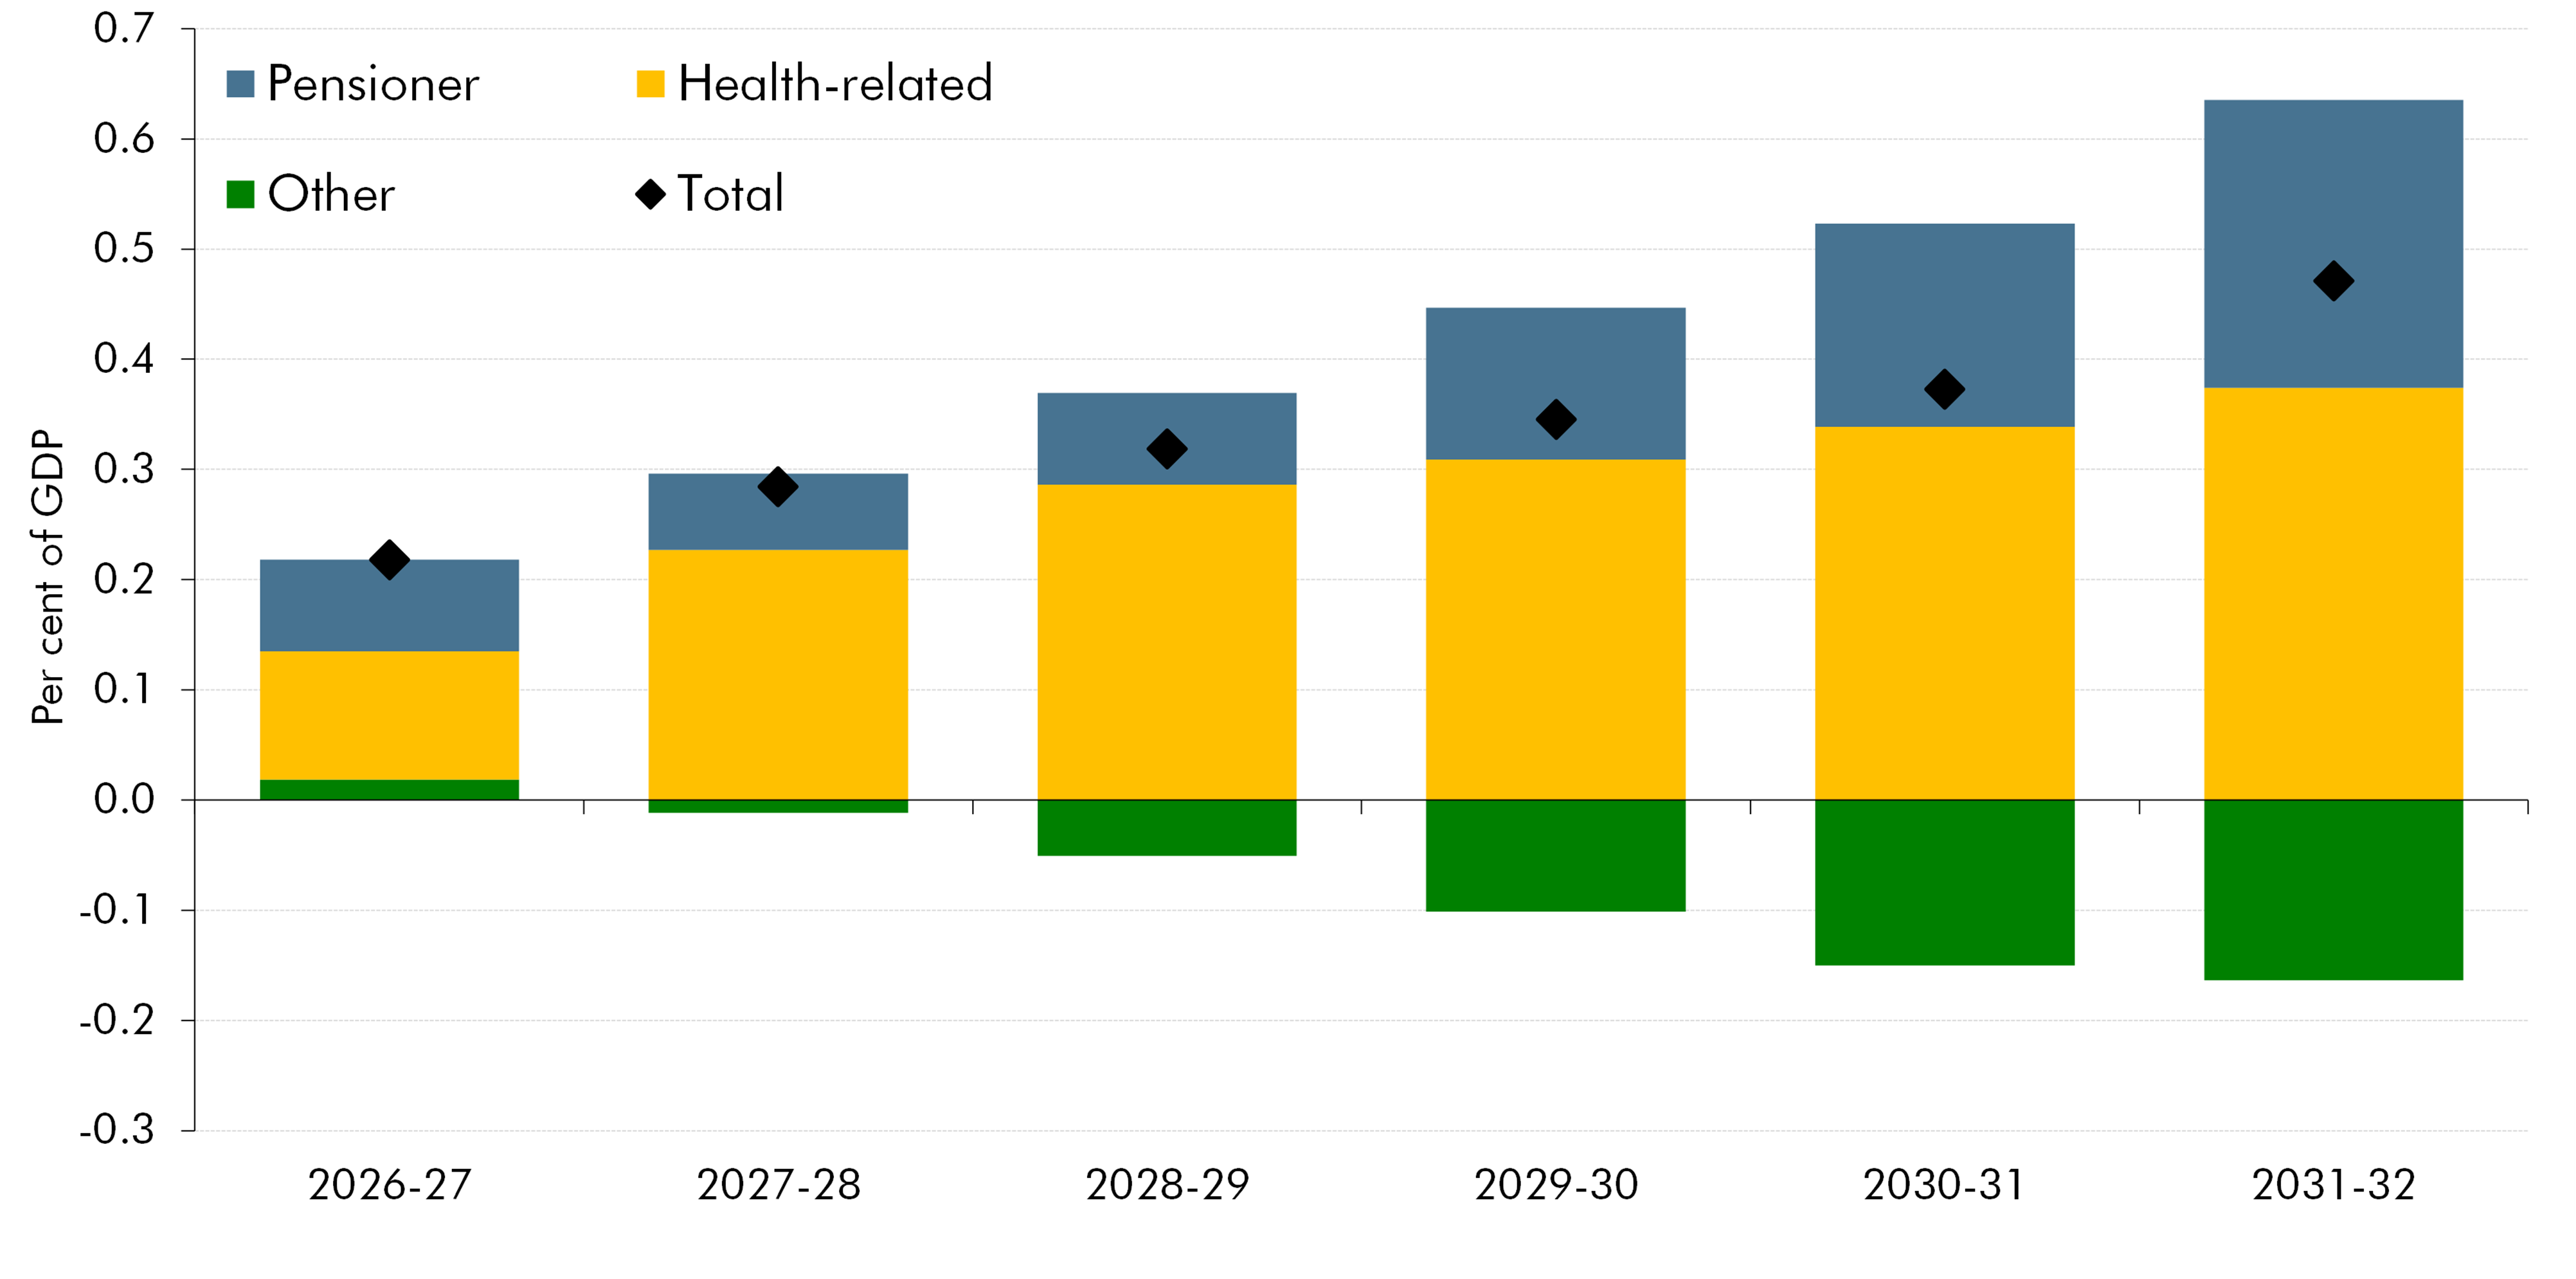
Source: DWP, HMRC, OBR
Box 5.1: Trends in welfare spending
Chart A shows that welfare spending as a share of GDP this year (11.1 per cent) is relatively high by historical standards, though below the 12.3 per cent peak seen in 2012-13 around the height of the labour market downturn following the global financial crisis. The most significant trend since 2019-20 is the rise in health-related welfare spending, which after remaining fairly stable at roughly 2 per cent of GDP between 1993-94 and 2019-20 then rose to 2.8 per cent of GDP by 2025-26, and is forecast to rise to 3.2 per cent of GDP by 2031-32. The 1.0 per cent of GDP forecast rise in health-related welfare spending between 2019-20 and 2031-32 explains over three quarters of the overall rise in welfare spending expected over that period (1.3 per cent of GDP). This rising trend is against a backdrop where in steady state, we would expect welfare spending to be falling as a share of GDP (by roughly 0.1 per cent of GDP each year), as GDP growth per person should outstrip uprating when inflation, earnings growth, and GDP growth are all stable.
Chart A: Welfare spending as a share of GDP over time
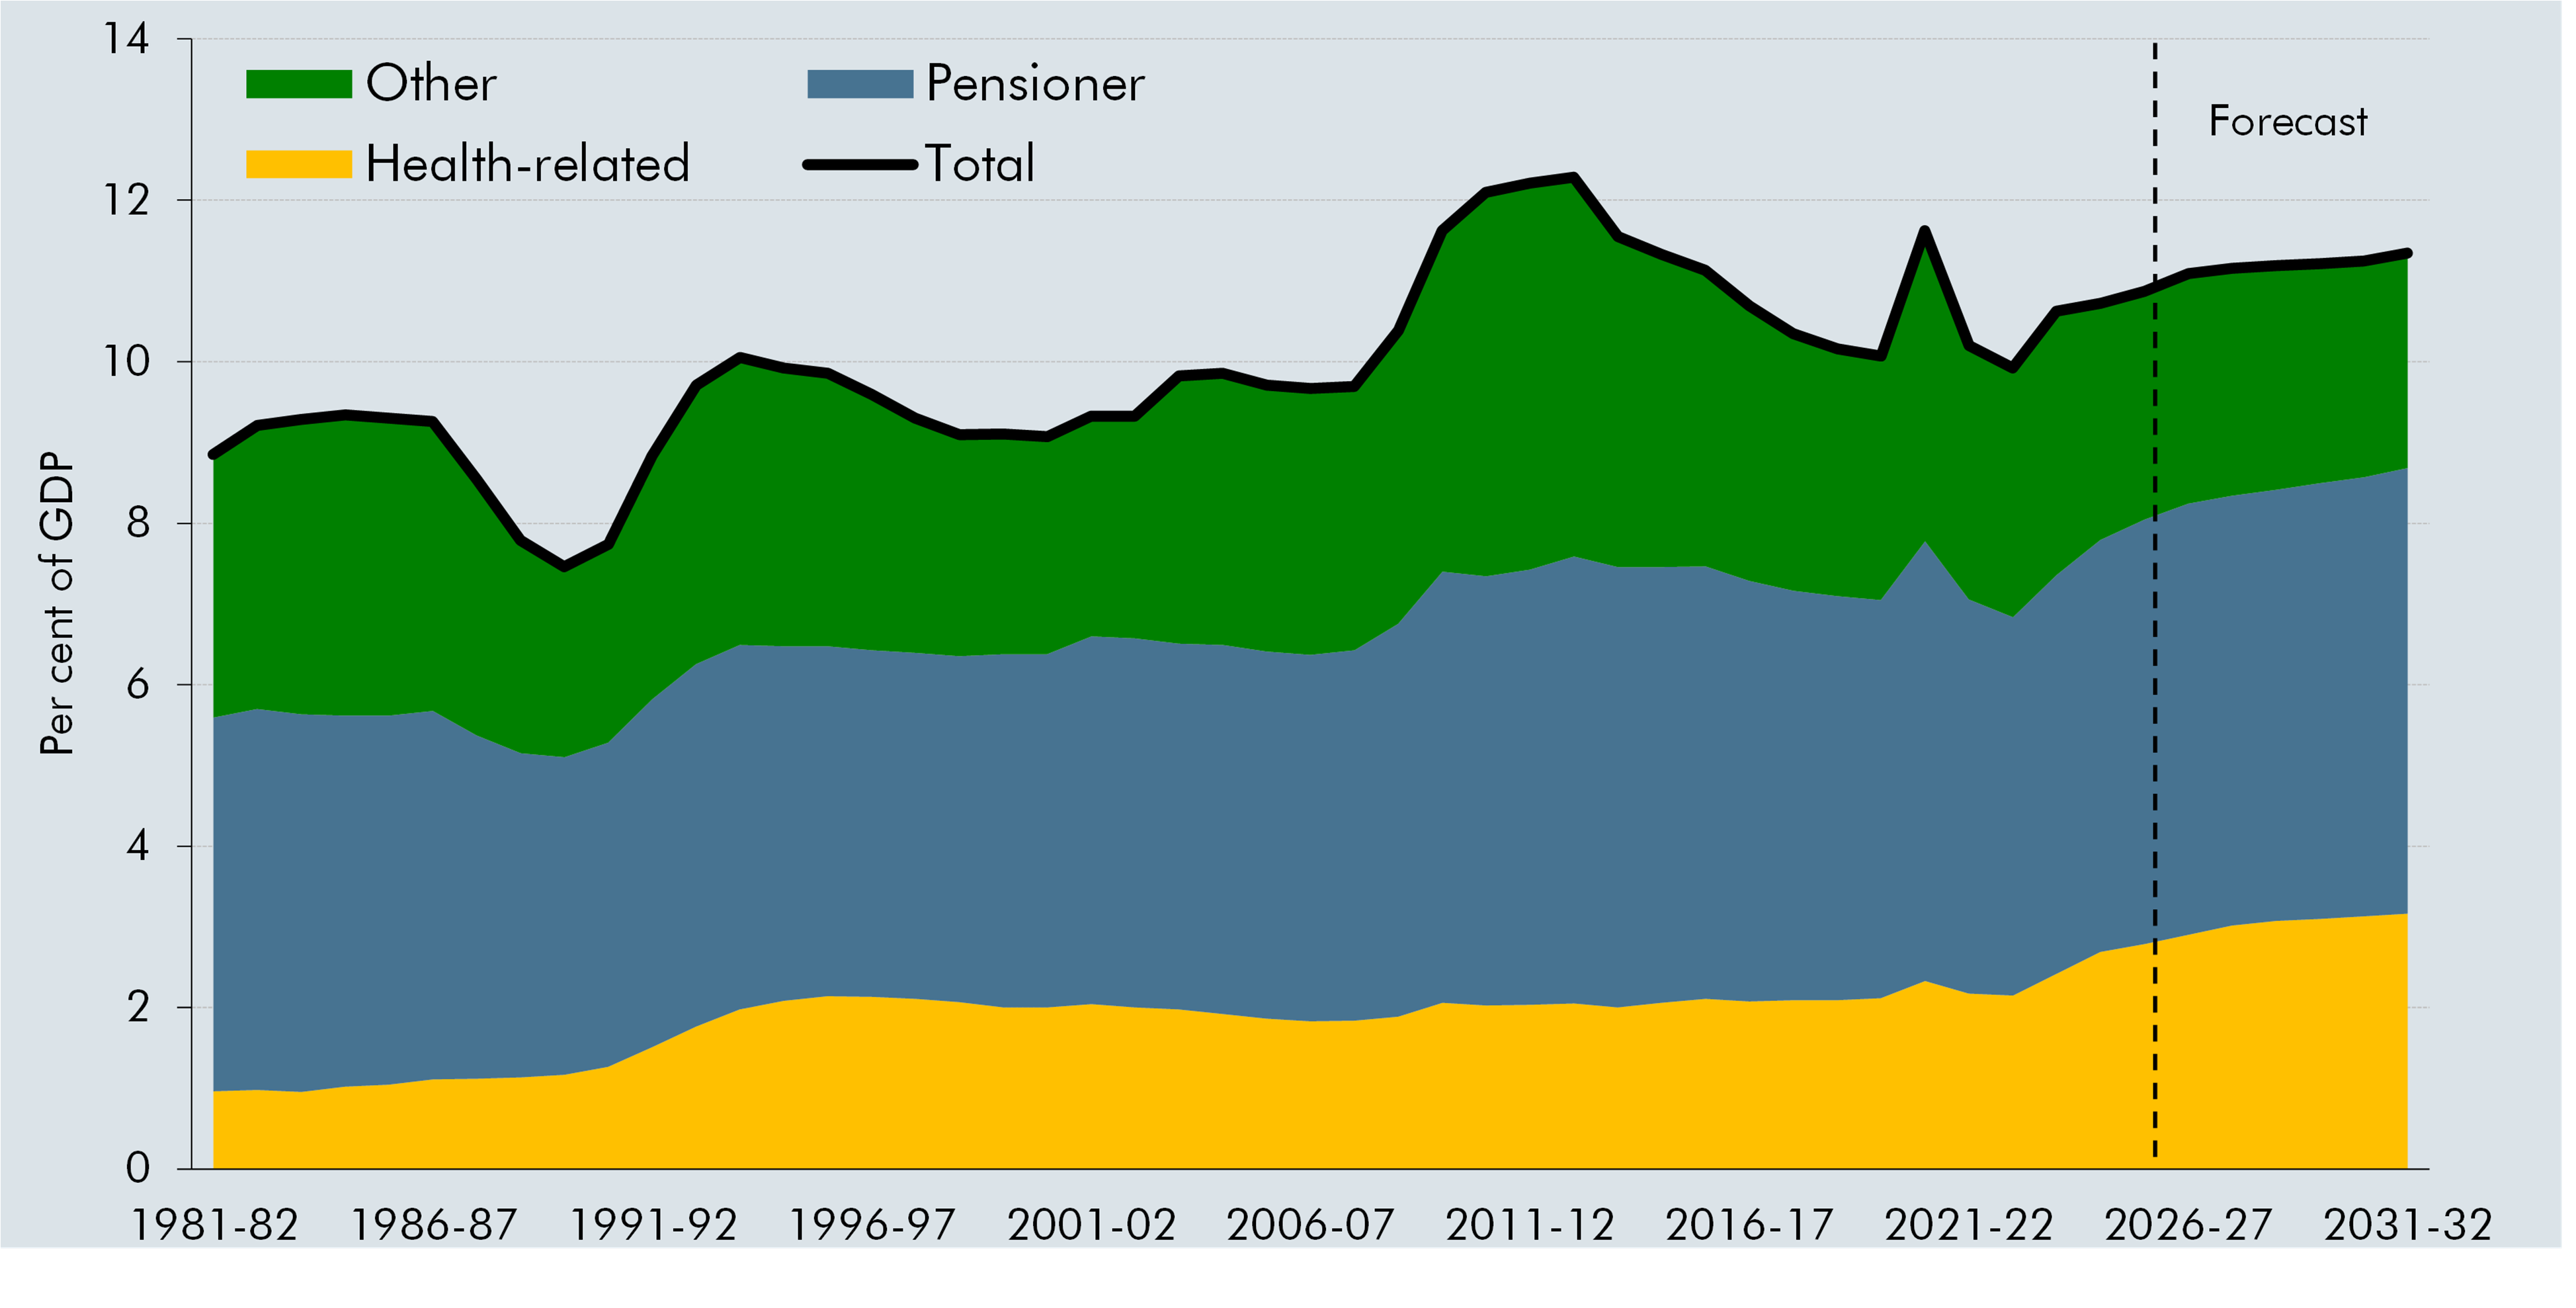
Source: DWP, HMRC, OBR
The left panel of Chart B breaks down the components of the expected annual change in welfare spending as a per cent of GDP across the forecast. The forecast can be split out into three periods:
-
Relatively high growth in 2026-27, where welfare spending rises by 0.2 per cent of GDP. This predominantly reflects growing caseloads for health-related benefits and the cost of uprating benefits by inflation and earnings outstripping growth in GDP per person.a Upwards pressure on pension spending from growth in the 66+ population is offset in this year by the introduction of the state pension age rise to 67 in April 2026, meaning state pension expenditure is largely unchanged as a share of GDP.
-
Lower overall growth is then forecast between 2027-28 and 2030-31. Through this period, a rising 66+ population and rising health-related caseloads continue to push up on welfare spending, but these upward pressures are mostly offset first by the rise in the state pension age reducing state pension spending in 2027-28 and 2028-29, and then by GDP growth per person outstripping the cost of uprating from 2029-30 onwards. Through this period, there is also constant downward pressure from what are expected to be mostly temporary trends – falling forecasts for unemployment and fraud and error, as well as the impact of policy decisions on welfare awards.
-
An increase in growth is then forecast in 2031-32, where welfare spending is expected to rise by 0.1 per cent of GDP. Around half of this increase compared to the previous years is explained by an unwinding of temporary downward pressures, with unemployment and fraud and error expected to be more stable by the final year of the forecast. The rest is largely explained by an uptick in growth in housing-related spending across universal credit and housing benefit. Increases in the pensioner population continue to place upward pressure on the forecast and are no longer offset by the impact of the state pension age rise, a trend which we expect to persist beyond the forecast horizon. Increasing health-related caseloads are also expected to continue to place upward pressure on spending, though by less than in the early years of the forecast.
Chart B: Change in welfare spending as a share of GDP over the forecast
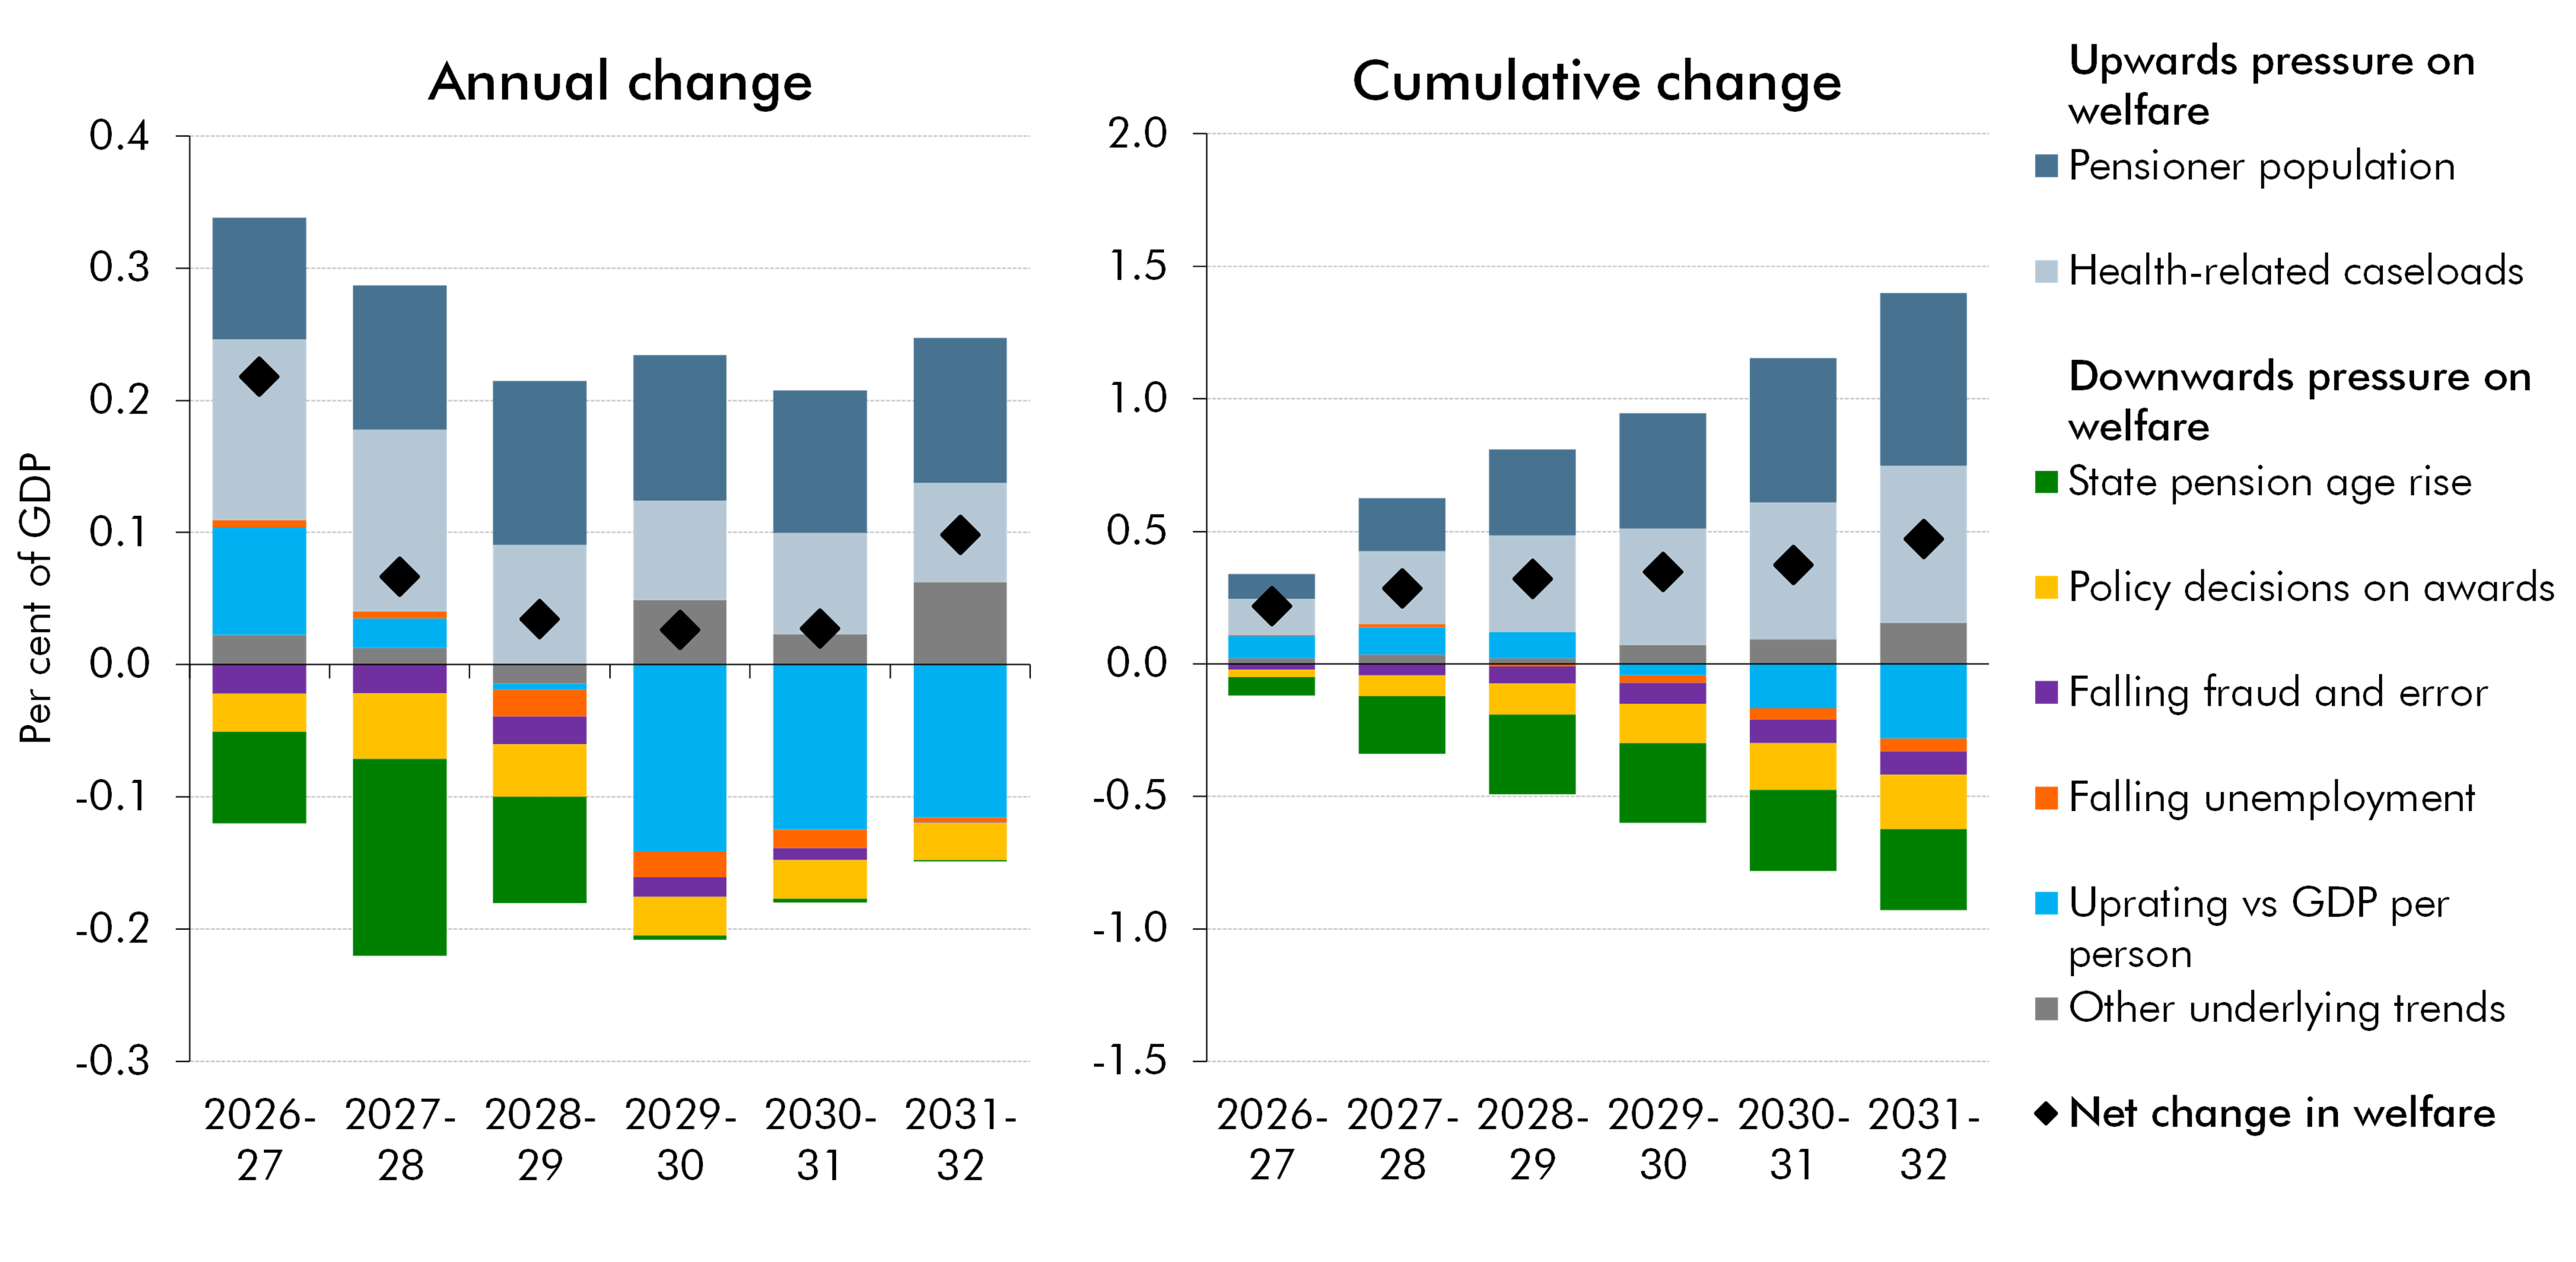
Note: Policy decisions on awards includes the saving from freezing local housing allowance rates compared to keeping them maintained at the thirtieth percentile, the cost of increasing the UC standard allowance at a rate faster than CPI uprating, the saving from halving and freezing of the UC health element for new claims compared to CPI uprating, the saving from legislating that the UC surplus earnings de minimis will return to £300 rather than the current £2,500 threshold, the saving from a nominally fixed benefit cap rather than it rising with CPI inflation, and the saving from nominally fixed high-income child benefit charge (HICBC) thresholds rather than the thresholds rising with CPI inflation.
Source: DWP, HMRC, OBR
-
The right-hand side of Chart B presents the cumulative change in welfare spending as a share of GDP across the forecast compared to 2025-26, which totals a 0.5 per cent of GDP rise between 2025-26 and 2031-32. Upwards pressure from underlying trends in pensioner demography and health-related welfare caseloads together increase spending by 1.2 per cent of GDP over the forecast. This is partially offset by factors including the impact of policy award decisions and the rise in the state pension age from 66 to 67 between 2026 and 2028, which reduces spending by 0.3 per cent of GDP over the forecast.
-
The upward pressures reflect underlying trends in demography which are very likely to persist beyond the medium term, while, as described above, the downward pressure largely reflects temporary or one-off factors that run their course during the forecast period. In particular, the rise in the state pension age will be complete by March 2028, meaning it has no further downward impact on welfare spending from 2029-30 onwards. The next rise in the state pension age is currently expected to occur between 2037 and 2039, meaning the state-pension-age population and therefore pensioner spending is expected to grow significantly until then. The degree to which health-related caseloads continue to place upward pressure beyond the medium term is highly uncertain as set out in paragraph 5.22.
a) Inflation in September 2025, which was used to uprate benefits in 2026-27, was 3.8 per cent, and earnings growth in the three months to July 2025, which was used to uprate pensions, was 4.8 per cent. Both of these are higher than forecast nominal GDP growth per person for 2026-27 (3.4 per cent), which means that inflation and triple lock uprating increase welfare spending this year as a share of GDP
5.24 Relative to the March 2026 forecast, welfare spending is expected to be higher across the forecast by an average of £5 billion a year, and by £6 billion by 2030-31. Table 5.5 shows that this increase is driven by:
-
Higher benefit uprating increases forecast welfare spending by £8 billion in 2030-31. This is mostly driven by higher CPI uprating (£6.1 billion) and higher earnings increasing the triple lock uprating for pensions (£1.5 billion).[footnote 69]
-
Higher forecast health-related universal credit (UC) caseloads increase spending by £3 billion in 2030-31. This is partly driven by the latest outturn data which shows high volumes of new claims for health-related UC in the period since the March forecast.
-
Lower forecast working-age disability benefit onflows decrease spending by £1 billion in 2030-31. New claims for personal independence payment (PIP), the working-age disability benefit, have been higher than expected in 2026, but a much lower proportion of these claims are being awarded the benefit after assessment compared to previous years. The net impact of these two factors reduces the forecast for PIP onflows compared to March.
-
Lower forecast UC fraud and error reduces spending by £2 billion in 2030-31. Following analysis of recent trends in fraud and error in our 2026 Welfare trends report, we have revised down assumptions around the prevalence of fraud and error in UC spending in the forecast period.[footnote 70] The outlook for fraud and error is a particularly uncertain element of the forecast.
Table 5.6: Total welfare spending: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| Welfare spending | ||||||
| March 2026 forecast | 332.9 | 352.8 | 363.1 | 373.8 | 389.9 | 406.9 |
| October 2026 forecast | 333.8 | 352.7 | 367.2 | 382.1 | 397.5 | 413.1 |
| Difference | 0.9 | -0.1 | 4.1 | 8.3 | 7.5 | 6.1 |
| of which: | ||||||
| Uprating(1) | 0.0 | 0.0 | 2.4 | 7.1 | 7.4 | 7.9 |
| UC health-related caseloads | 0.0 | 0.2 | 0.8 | 1.4 | 2.2 | 2.9 |
| Working-age disability onflows | 0.0 | -0.1 | -0.5 | -0.6 | -0.8 | -1.0 |
| UC fraud and error assumptions | 0.0 | 0.1 | -0.2 | -0.8 | -1.4 | -2.1 |
| Direct effect of Government decisions(2) | 0.0 | 0.1 | 0.2 | -0.1 | -0.1 | -0.2 |
| Other | 0.8 | -0.4 | 1.4 | 1.3 | 0.3 | -1.4 |
| 1) This captures the effects of changes to the inflation and earnings forecasts on all benefit uprating linked to CPI, earnings, and the triple lock. |
| 2) This excludes the consequences of decisions for the block grant adjustment. |
| Source: DWP, HMRC, OBR |
Local authority and Housing Revenue Account spending
5.25 Local authority spending is currently an uncertain part of the forecast due to the range of financial pressures across the sector discussed in paragraph 5.27. Reflecting the increased net borrowing related to the Housing and Revenue Account (HRA) in recent years, we have expanded our analysis in this EFO to show HRA spending and borrowing alongside our main local authority forecast, and discuss it in more detail in Box 5.2.
Table 5.7: Local authority and housing revenue account net borrowing and changes since March forecast
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| LA and HRA net borrowing | 17.4 | 16.5 | 16.6 | 11.1 | 10.3 | 10.2 | 9.8 |
| of which: | |||||||
| HRA net borrowing | 6.8 | 6.9 | 6.8 | 6.6 | 6.5 | 6.5 | 6.4 |
| LA net borrowing | 10.5 | 9.6 | 9.7 | 4.5 | 3.8 | 3.7 | 3.4 |
| of which: | |||||||
| SEND deficits | 2.8 | 4.2 | 5.7 | 0.0 | 0.0 | 0.0 | 0.0 |
| EFS | 1.4 | 1.2 | 1.0 | 1.0 | 1.0 | 1.0 | 1.0 |
| Other net current spending | -0.7 | -4.5 | -4.6 | -4.7 | -4.4 | -4.5 | -4.6 |
| Net capital spending | 7.1 | 8.7 | 7.7 | 8.2 | 7.2 | 7.3 | 7.0 |
| Changes since March | |||||||
| LA and HRA net borrowing | -1.0 | 0.9 | 2.8 | 2.1 | 1.3 | 0.3 | |
| of which: | |||||||
| HRA net borrowing | 0.7 | 1.1 | 1.1 | 1.1 | 1.3 | 1.5 | |
| LA net borrowing | -1.7 | -0.2 | 1.6 | 1.0 | 0.0 | -1.2 | |
| of which: | |||||||
| SEND deficits | 0.2 | 0.0 | 0.3 | 0.0 | 0.0 | 0.0 | |
| EFS | 0.0 | -0.1 | 1.0 | 1.0 | 1.0 | 1.0 | |
| Other net current spending | -1.8 | -2.1 | -1.2 | -1.0 | -1.0 | -1.1 | |
| Net capital spending | 0.0 | 2.0 | 1.6 | 0.9 | 0.0 | -1.1 |
| Note: Other net current spending typically includes SEND deficits, EFS, and HRA net borrowing. To increase transparency in this table we present these elements seperately. This is a change from the presentation in the equivalent table in the March 2026 EFO where net current spending included EFS and HRA net borrowing. Other net capital spending is gross capital spending minus grants from within the public sector. 2025-26 outturn uses the latest PSF, released on 22 September. 2025-26 EFS figure is a forecast based on agreements in-principle and historic utilisation of capital redirections. See footnote 25 for a definition of EFS. SEND deficits refer to the financial overspends accumulated by LAs when the cost for Special Educational Needs and Disabilities (SEND) support outstrips the high-needs funding allocated by the central government. |
| Source: DfE, HM Treasury, ONS, OBR |
5.26 Local authority and HRA borrowing has been at elevated levels since the pandemic, averaging £16 billion a year over the past four years compared to an average of £8 billion in the four years preceding the pandemic. We assume that borrowing levels will not fall significantly from these levels in the near term, but from 2028-29 onwards will fall to an average of £10 billion per year largely reflecting responsibility for funding special educational needs (SEND) provision moving to central government. These judgements are largely unchanged from March 2026, with net borrowing now expected to be an average of £1.5 billion higher each year, across the forecast period. The main components of the local authority and HRA borrowing forecast are:
-
HRAs are the ring-fenced financial accounts used by most LAs in England, Scotland, and Wales to manage the income and spending related to the running of council-owned housing stock. HRA net borrowing has risen strongly in the last decade from £0.2 billion in 2015-16 to a forecast £7 billion this year (see Box 5.2). We forecast HRA net borrowing will decline slightly to £6.4 billion by 2031-32. HRA net borrowing is around £1 billion on average higher than in March, driven by evidence that local authorities have not reduced borrowing in the face of higher interest rates to the degree we previously expected.
-
The cost of SEND deficits is forecast to grow from £3 billion in 2025-26 to £6 billion by 2027-28 as the volume and cost of school-aged children in receipt of EHCPs grows. From 2028-29, all SEND spending will be funded from within central government DEL and so local authorities will no longer have to finance this. The estimated cost of SEND deficits is broadly unchanged from March.
-
Spending enabled by Exceptional Financial Support (EFS)[footnote 71] is forecast to stay broadly flat at around £1 billion over the next five years, following a period in which it increased from £0.3 billion in 2021-22 to £1.4 billion in 2025-26. We previously incorporated a forecast for EFS for only one financial year ahead, but given this sustained rise we now assume it will continue in all years of the forecast.
-
We expect other current spending to be in surplus and reduce overall LA borrowing by an average of £4.6 billion each year, over the forecast period. This reflects our assumption that rising council tax revenues, higher central government grants, the ‘fair funding’ reforms, and central government funding of SEND from 2028-29 strengthens the financial position of LAs over the forecast period.
-
Net capital spending is forecast to fall slightly over the forecast period to £7 billion in 2031-32. We assume that the financial pressures facing local authorities and higher interest rates will lead to lower spending on capital projects, but this is highly uncertain. Relative to March, capital borrowing is higher by around £1 billion on average each year over the forecast period, which reflects local authorities not reducing borrowing in the face of higher interest rates by as much as expected.
5.27 The local authority and HRA forecasts are highly uncertain as they reflect decisions that will be taken by individual local authorities in response to the varied social, economic and financial environments that they face. Financial pressures on local authorities have increased in recent years which is shown by the increased numbers of authorities being granted EFS, from one in 2017-18 to 37 to date in 2026-27. In addition to HRA pressures, discussed in Box 5.2, some of the main pressures and risks in the forecast period include:
-
SEND – local authorities will continue to face financial pressures from SEND related spending until it is fully funded by central government from 2028-29, with local authorities now expecting significantly higher deficits up to 2027-28 compared to their own previous estimates.[footnote 72] There is uncertainty around the impact that the recent reforms in February 2026 will have on costs and on the numbers of children that receive support. Further, while the Government has committed to reimburse local authorities for 90 per cent of the deficits they accumulated on SEND spending through to the end of 2025-26,[footnote 73] the Government has made no commitment in relation to deficits accumulated after that point.
-
Temporary accommodation and asylum – English local authority spending on housing support outside of the HRA has grown from £2 billion in 2010-11 to £4 billion in 2025-26, driven by increases in the cost of provision of housing for homeless families and for refugees transitioning out of asylum accommodation. The Government’s ambitions to reduce the level of homelessness and improve the standard of temporary accommodation are likely to increase pressure on local authority spending in this area.
-
Social care – which in 2025-26 accounted for around 30 per cent of local government current expenditure in England – £44 billion – compared with around 20 per cent in 2010-11. Adult social care costs are likely to increase further given the ageing population, rising demand among working-age adults, inflation and the minimum wage. Local authorities in England also spent around £17 billion on social care for children in 2025-26 and the number of children in England looked after by local authorities grew from 64,000 in 2010 to 82,000 in 2025.[footnote 74]
Box 5.2: The financial position of local authority Housing Revenue Accounts
Housing Revenue Accounts (HRAs) are the financial accounts that the majority of local authorities use for the management, maintenance and improvement of around 2 million council homes in England, Scotland and Wales, which is around 7 per cent of the total stock of homes. Over the past decade, the financial position of many HRAs has come under increasing pressure. This reflects constrained rental income growth and rising expenditure costs.
Rental income accounts for around 90 per cent of HRA income and is largely determined by government policy on social rents and the stock of housing. The stock of council housing in England has declined from over 5 million in 1980 to 1.6 million today, largely due to houses purchased under Right to Buy and some large-scale voluntary transfers of homes to private registered housing providers. In parallel, rents have largely not kept up with the rate of inflation in the last decade. Between the late 2000s and mid-2010s, social housing landlords, including local authorities, were generally permitted to increase rents by inflation plus an additional uplift. Policy reform in the 2015 Summer Budget required social rents in England to fall by 1 per cent a year between 2016-17 and 2019-20. Thereafter, rent increases resumed but remained subject to government regulation and have often been capped below prevailing inflation rates. Earlier this year, the government introduced a 10-year settlement from April 2026 to allow social housing landlords to increase rents by CPI+1 percentage point annually.
The cost of construction and maintenance in the housing sector has increased substantially over the past decade, growing by over 40 per cent.a The impact of this is illustrated in the right panel of Chart A, which shows that the total costs of HRA capital works has risen even while the volume of works has fallen. Following the Grenfell Tower fire and subsequent reforms to social housing regulation, social landlords, including councils, have faced further spending pressure to meet the growing obligations to improve the quality and safety of housing, while also meeting separate obligations to improve the energy efficiency of the housing stock.
As a result of these trends, as shown in the left panel of Chart C, the HRA net borrowing position has increased from around £0.1 billion to over £6 billion in the last decade. This reflects that HRA capital expenditure has increased from £5 billion in 2014-15 to £10 billion in 2024-25, and total spending has risen from £10 billion to £18 billion, while in the same period income has only increased from £10 billion to £12 billion.
Chart C: Housing revenue account spending and income
Note: HRA spending and income chart (left chart) covers England, Scotland, and Wales. HRA related capital work by LAs (right chart) covers only England. Net capital spending is capital spending including asset sales.
Source: ONS, MHCLG
Many of the factors that have driven higher spending are likely to persist. While rental revenues are now set to rise above inflation, an ageing housing stock, growing regulatory requirements, and a backlog of repair, remediation and energy efficiency works, will continue to place pressure on expenditure. For example, the Government expects that meeting the new Decent Homes standard, set to be fully enforced by 2035, will cost local authorities around £5 billion.b The financial positions of individual HRAs vary significantly across local authorities, but these pressures are also likely to severely constrain the ability of many local authorities to significantly increase new council house construction.
a) ONS, Construction output price indices, August 2026.
b) Housing, Communities and Local Government Committee, EHS Briefing: Modelling a new Decent Homes Standard, February 2026 and MHCLG, EHS Briefing: Modelling a new Decent Homes Standard, January 2026.
Debt interest spending
5.28 Debt interest spending as a share of GDP is forecast to rise from 3.9 per cent of GDP in 2026-27 to reach 4.2 per cent of GDP in 2031-32 (Chart 5.7). This would be above the previous highs reached in the 1960s and 1980s and more than double the average of the ten years prior to the pandemic. The increase in debt interest costs since the pandemic has been driven by both the rising stock of debt and by the sharp increases in interest rates over that period. However, interest rates are not high by historical standards, as is also shown in Chart 5.7. The effective interest rate[footnote 75] on government debt of around 4 per cent over the forecast period is less than half the 1980s peak, of 10 per cent, and below the average rate over the two decades preceding the 2008 financial crisis of 7.5 per cent.
Chart 5.7: Debt interest spending relative to GDP and effective interest rate
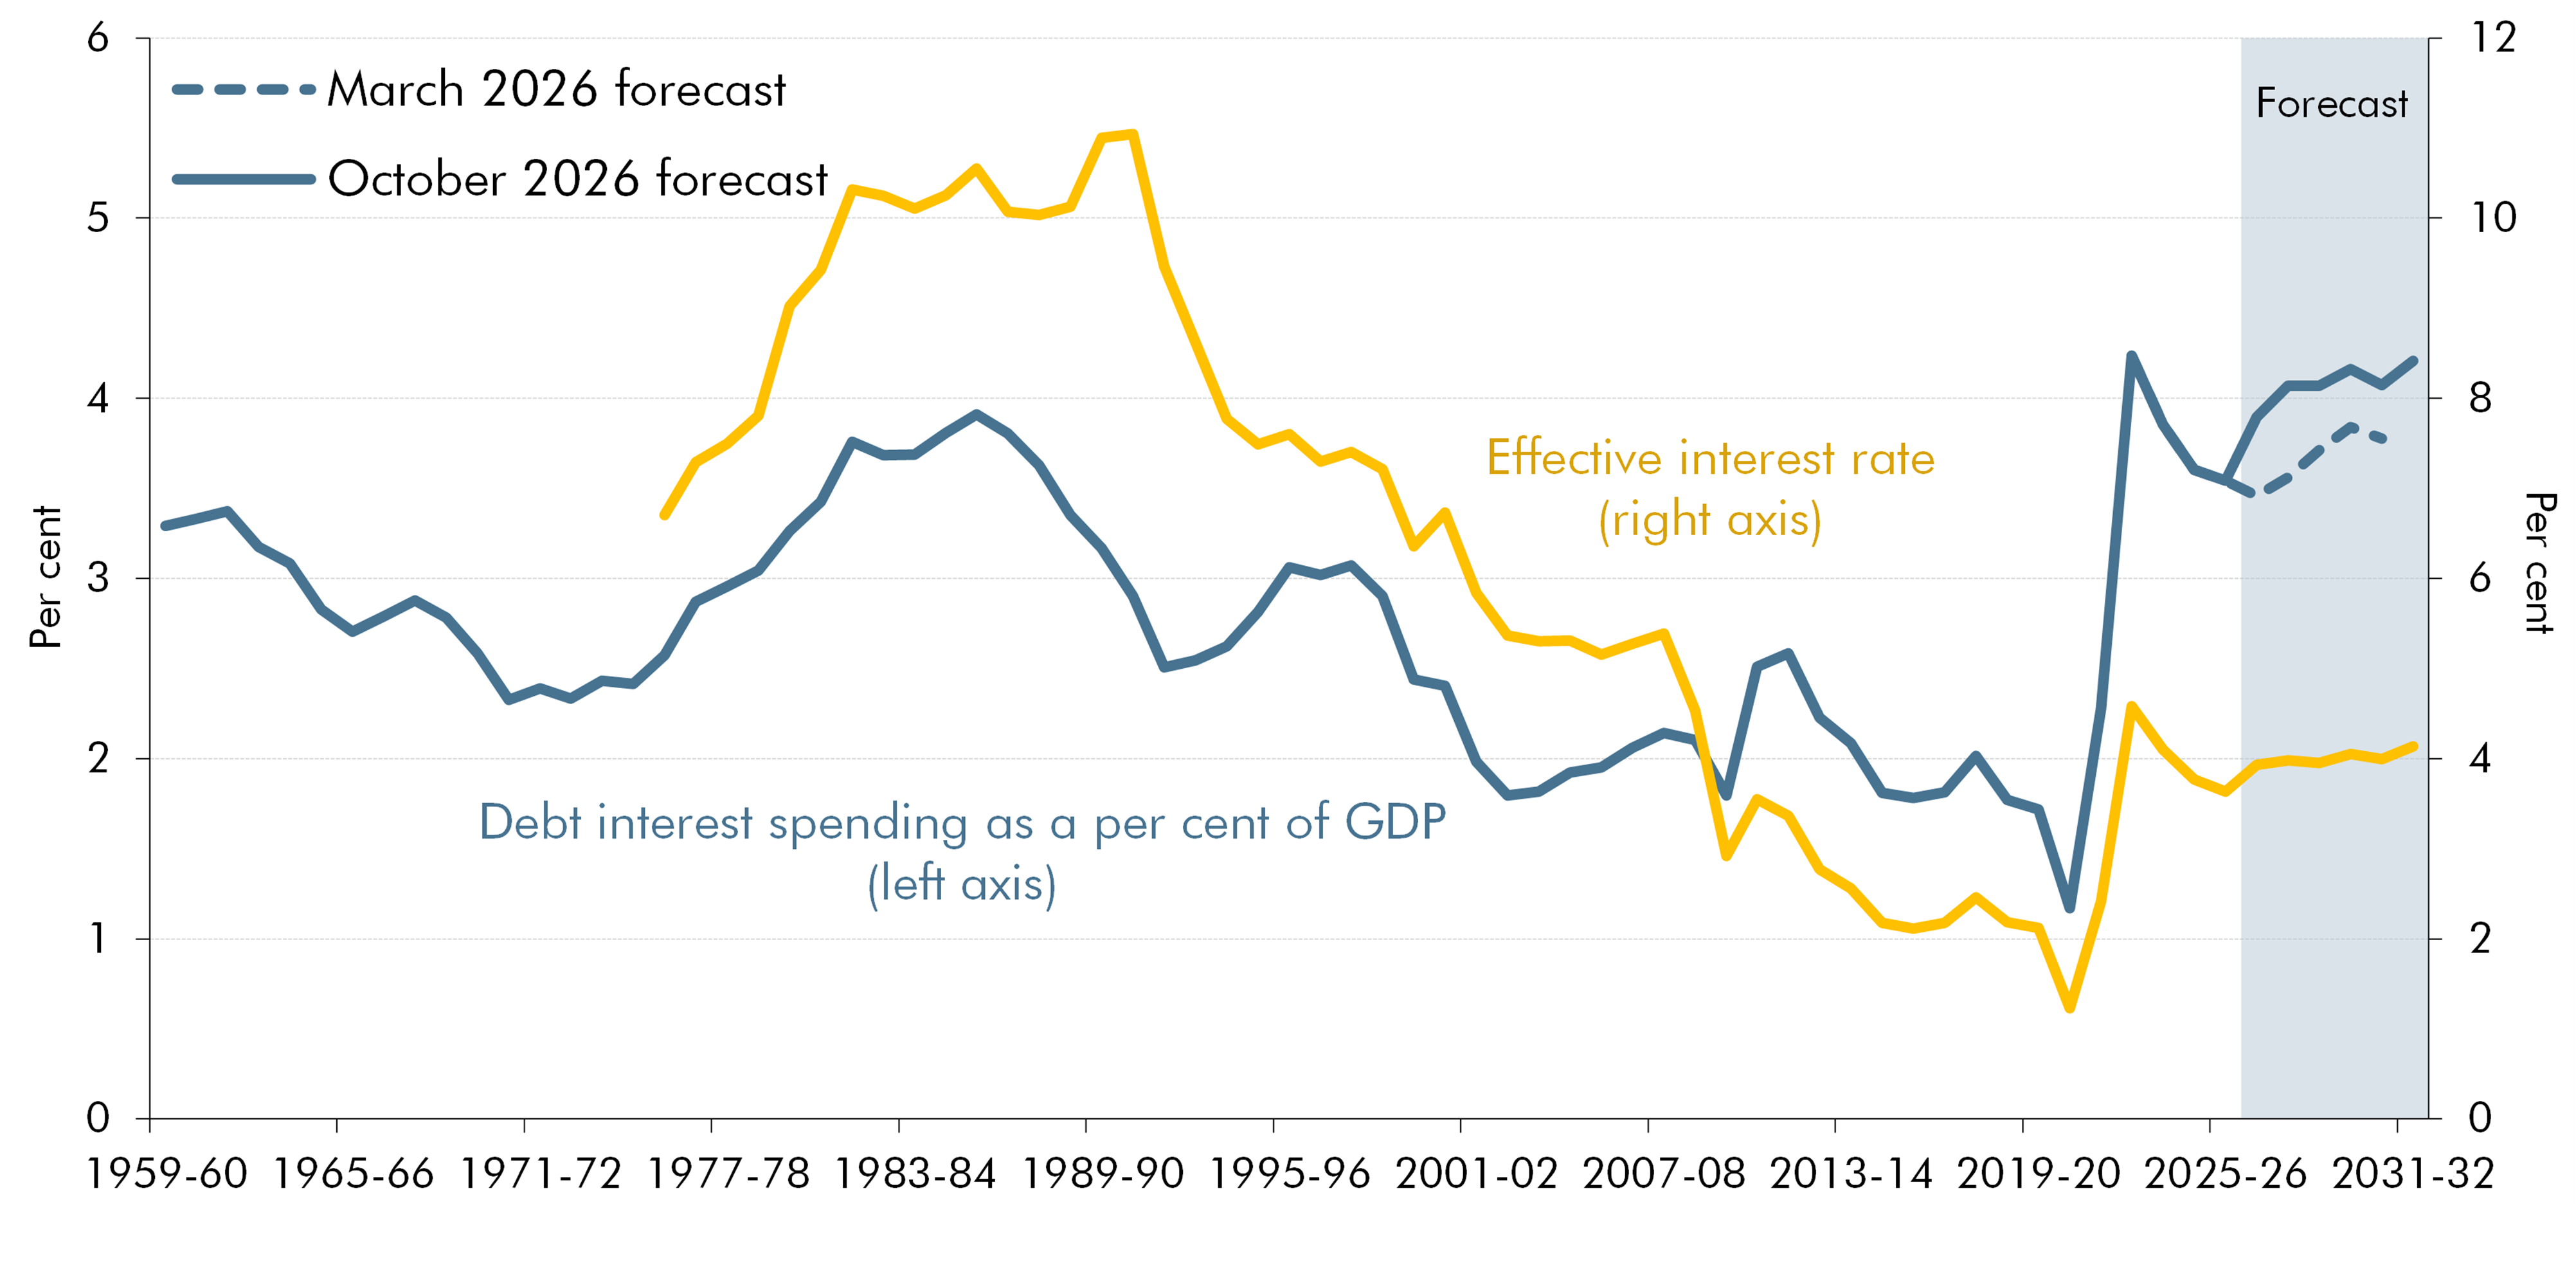
Source: ONS, OBR
5.29 In nominal terms, debt interest spending is forecast to rise from £124 billion in 2026-27 to £160 billion in 2031-32, an average year-on-year increase of around £7 billion. This is driven by new borrowing which increases the stock of debt on which interest accrues each year. In addition, an average of £184 billion of maturing gilts are refinanced each year, typically at higher interest rates than the debt they replaced, which also contributes to the rise in spending. In 2030-31, the year-on-year increase in debt interest spending slows to £2.2 billion because the alignment of RPI with CPIH[footnote 76] reduces RPI growth and therefore the uplift applied to index-linked gilts. In the final year of the forecast, year-on-year growth in debt interest spending returns to the previous trend, increasing by £10 billion, reflecting new borrowing and significant redemptions in that year from the large volume of gilts issued during the Covid period. Chapter 6 has further discussion of the impact of redemptions and the change in the maturity composition of gilt issuance.
5.30 Compared to March, debt interest is forecast to be £14 billion higher on average over the forecast period. This largely reflects higher RPI inflation in the near term and higher Bank Rate and gilt rates expectations in the medium term:
-
Revisions to the RPI inflation forecast increase spending by £12 billion in 2026-27 and £6.5 billion in 2027-28, and then by an average of £1.2 billion until 2030-31.
-
Higher Bank Rate and gilt rates are forecast to increase debt interest costs compared to March 2026 by £3.9 billion in 2026-27 and then by an average of £11 billion a year throughout the forecast period.
-
Financing and other factors are expected to decrease spending in the first two years of the forecast, by an average of £0.9 billion, but then increase it by £0.8 billion in 2030-31.
-
The effects of policy decrease debt interest in 2026-27 by £0.9 billion, which reflects the direct impact on inflation of policy measures this year, and then raises it by an average of £0.8 billion a year thereafter mostly due to increased borrowing.
Table 5.8: Central government debt interest (net of APF): changes since March
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| March 2026 forecast | 109.7 | 109.4 | 116.7 | 125.9 | 134.7 | 137.1 | |
| October 2026 forecast | 108.7 | 123.9 | 134.0 | 139.0 | 147.4 | 149.6 | 160.0 |
| Difference | -0.9 | 14.5 | 17.3 | 13.0 | 12.7 | 12.4 | |
| of which: | |||||||
| Pre-measures changes | 15.4 | 16.0 | 12.0 | 12.0 | 12.1 | ||
| of which: | |||||||
| RPI inflation | 12.3 | 6.5 | 1.3 | 1.1 | 1.2 | ||
| Bank Rate | 3.5 | 8.9 | 7.7 | 5.8 | 4.7 | ||
| of which: | |||||||
| Central government | 0.9 | 3.2 | 3.3 | 2.5 | 2.0 | ||
| APF | 2.6 | 5.7 | 4.4 | 3.3 | 2.7 | ||
| Gilt rate | 0.4 | 1.9 | 3.7 | 5.0 | 5.3 | ||
| Financing and other | -0.8 | -1.2 | -0.6 | 0.1 | 0.8 | ||
| Effects of Government decisions | -0.9 | 1.2 | 1.0 | 0.7 | 0.4 | 0.3 |
| Source: ONS, OBR |
PSNB-neutral spending and other annually managed expenditure
5.31 PSNB-neutral spending includes spending which is offset in receipts and therefore does not affect public sector net borrowing (PSNB). PSNB-neutral spending has increased by £0.9 billion on average since the March 2026 forecast. The main changes are increases in depreciation and VAT refunds, and decreases in environmental levies, which are described in paragraphs 4.46-4.51 of Chapter 4.
5.32 Some of the main other items of AME spending include:
-
Net spending on unfunded public service pensions is forecast to move from a deficit of £1.1 billion in 2026-27 to a deficit of £14 billion in 2027-28. This is primarily due to the 2024 valuation of these schemes, described in more detail in paragraph 5.8, which reduces employer contributions and increases net pension spending by around £16 billion a year from 2027-28 onwards. The lower employer contributions represent a saving for departments, which are offset by a broadly equivalent reduction in RDEL, leaving overall spending around £1.1 billion higher a year. Spending is also around £2 billion higher than in March due to higher forecast inflation and pensioner caseloads. From 2027-28, the deficit is expected to remain largely flat in cash terms at around £15 billion and therefore to fall slightly as a share of GDP.
-
Public corporations excluding the HRA are forecast to spend £8 billion on capital by 2030-31, around £1 billion more than we forecast in March 2026. This is driven by a combination of new outturn data which was around £0.6 billion higher than expected in March and changes to the nominal GDP forecast.
-
The cost of the Post Office redress and Infected Blood compensation schemes is expected to peak at £3.8 billion in 2026-27 before falling to £0.2 billion in 2031-32.[footnote 77] Spending on these schemes was £1.5 billion less in 2025-26 than expected in the March 2026. Given the ongoing rollout of these schemes, there remains uncertainty around the number of eligible claimants, average award amounts and how quickly claims will be processed which could change the total amount of spending and its profile.
-
Capital spending on the construction of the Sizewell C nuclear power station, which is estimated to be £3.7 billion in 2026-27 before rising slightly to £3.9 billion in 2031-32. Compared to the March 2026 forecast, spending is expected to be an average of £0.8 billion higher between 2026-27 and 2029-30 reflecting Sizewell C’s revised plan to frontload more of the total capital spending.
Chapter 6: Fiscal aggregates
Introduction
6.1 This chapter details how changes in our pre-measures forecast, and policy measures since our March 2026 forecast, affect key summary measures of the public finances, including:
-
deficit aggregates, including public sector net borrowing (PSNB), the difference between expenditure and receipts; the current budget deficit, the difference between current (day-to-day) expenditure and receipts; the primary deficit, the difference between non-interest expenditure and receipts; and cyclically adjusted measures of the deficit, which take account of the position of the economy relative to its potential level of output;
-
financial transactions, which capture the effects of public sector net lending, sales or purchases of financial assets, and interventions which affect the Bank of England’s (BoE’s) balance sheet; and
-
balance sheet aggregates, including public sector net debt (PSND), which includes all debt obligations net of liquid financial assets; public sector net financial liabilities (PSNFL), which includes all financial liabilities and financial assets; and public sector net worth (PSNW), which includes all financial and non-financial assets and liabilities.
Deficit aggregates
Borrowing and the current budget deficit
6.2 Chart 6.1 shows that public sector net borrowing increased sharply to 10.2 per cent of GDP in 2009-10 following the financial crisis, before falling in each subsequent year to reach 2.0 per cent of GDP in 2018-19. It then increased again to a record high of 14.7 per cent of GDP in 2020-21 due to the pandemic and the policy response to it, reflecting both the large rise in cash borrowing and the fall in nominal GDP in that year. After the pandemic, borrowing fell to around 5 per cent of GDP in 2021-22 and remained close to that level for the following three years before falling again to 4.4 per cent in 2025-26.
6.3 Chart 6.1 and Table 6.1 show that, in our central forecast, PSNB is expected to fall slightly from 4.4 per cent of GDP (£134 billion) in 2025-26 to 4.2 per cent (£133 billion) in 2026-27. It then declines steadily to reach 1.8 per cent of GDP (£67 billion) in 2030-31 and remains flat as a share of GDP in 2031-32. PSNB is now expected to be higher in each year of the forecast compared to March, by 0.5 per cent of GDP in the near term and 0.2 per cent of GDP in 2030-31.
6.4 Chart 6.1 and Table 6.1 also show that the current budget deficit is forecast to fall from 1.5 per cent of GDP in 2025-26 (£47 billion) to 1.3 per cent (£41 billion) in 2026-27. It is then forecast to improve in each year to reach a surplus of 0.4 per cent of GDP (£15 billion) in 2029-30, rising to 0.6 per cent in 2030-31 (£22 billion) but then falling to 0.5 per cent (£21 billion) in 2031-32. As with PSNB, the forecast for the current budget deficit has seen a moderate deterioration in each year compared to the March.
Chart 6.1: Public sector net borrowing and the current budget deficit
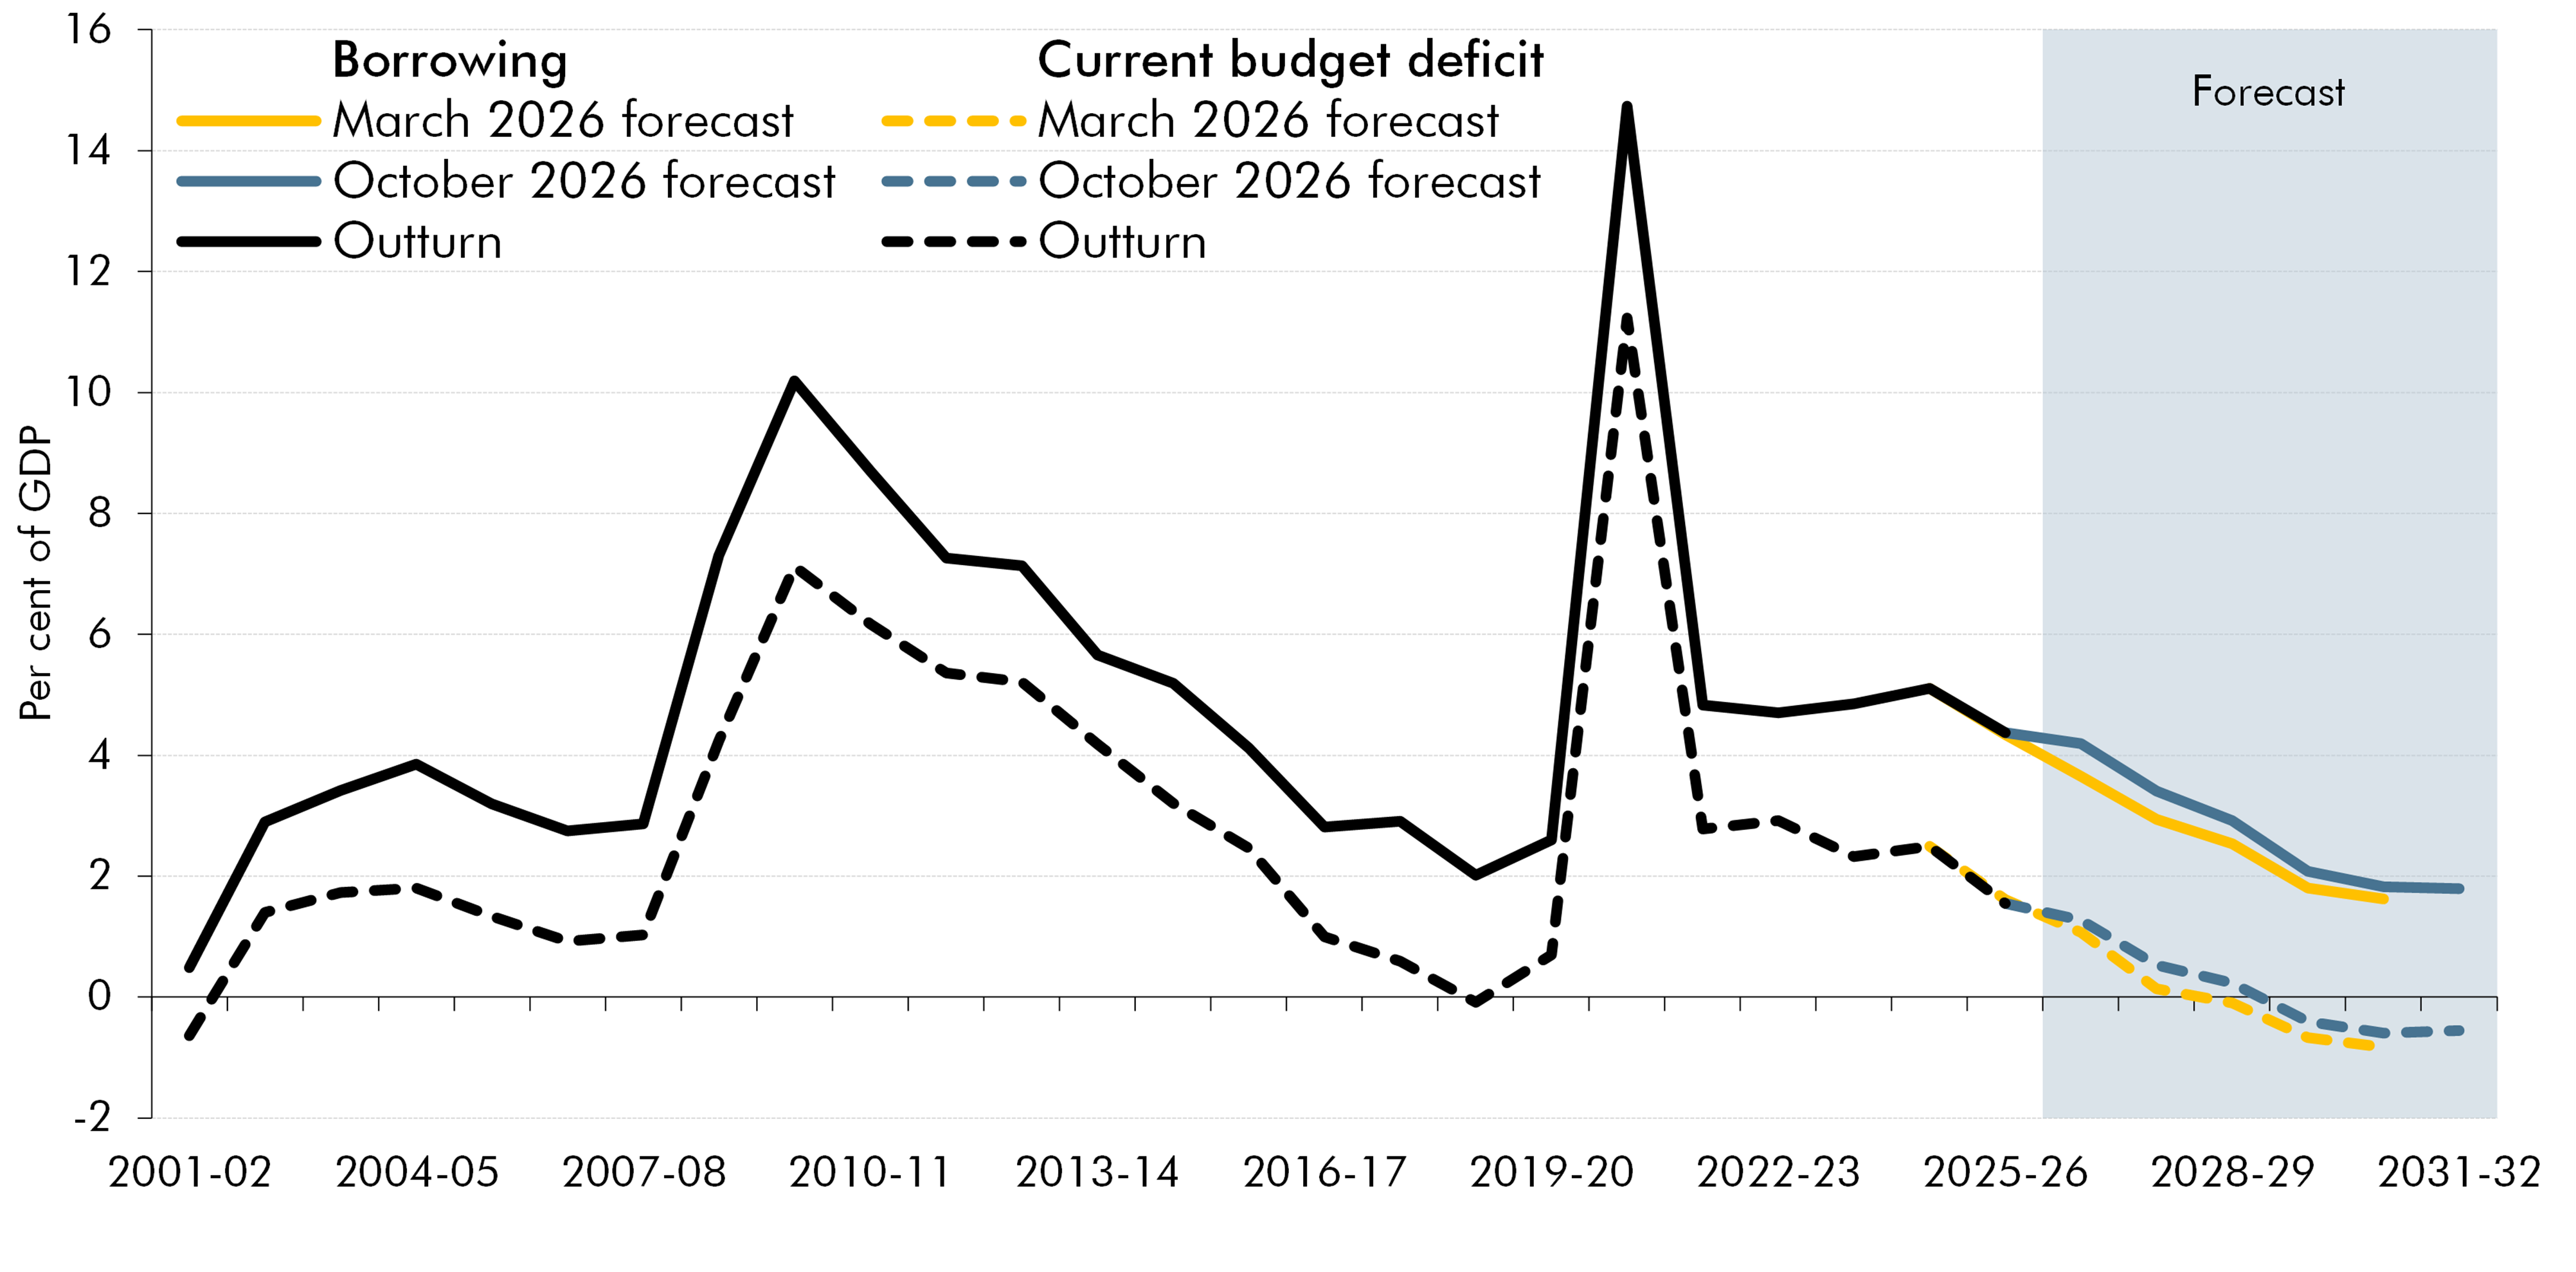
Source: ONS, OBR
Table 6.1: Public sector net borrowing and the current budget deficit
| Per cent of GDP | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| March 2026 PSNB | 4.3 | 3.6 | 2.9 | 2.5 | 1.8 | 1.6 | |
| October 2026 PSNB | 4.4 | 4.2 | 3.4 | 2.9 | 2.1 | 1.8 | 1.8 |
| Difference | 0.0 | 0.5 | 0.5 | 0.4 | 0.3 | 0.2 | |
| March 2026 current budget deficit | 1.6 | 1.1 | 0.1 | -0.1 | -0.7 | -0.8 | |
| October 2026 current budget deficit | 1.5 | 1.3 | 0.5 | 0.2 | -0.4 | -0.6 | -0.5 |
| Difference | -0.1 | 0.2 | 0.4 | 0.3 | 0.3 | 0.2 |
| Source: ONS, OBR |
6.5 Chart 6.2 shows the contributions to the forecast reduction in PSNB between 2026-27 and 2031-32. Of the fall of 2.4 per cent of GDP, around 0.7 per cent is accounted for by the forecast increase in income tax and NICs receipts over this period, with another 0.7 per cent due to the forecast rise in other receipts, mainly capital taxes and corporation tax. The drivers of these receipts forecasts are explained in Chapter 4. The remaining reduction in PSNB reflects a 1.4 per cent of GDP expected decline in departmental spending, which is only partly offset by higher forecast AME, explained further in Chapter 5.
Chart 6.2: The fall in borrowing as a share of GDP from 2026-27 to 2031-32
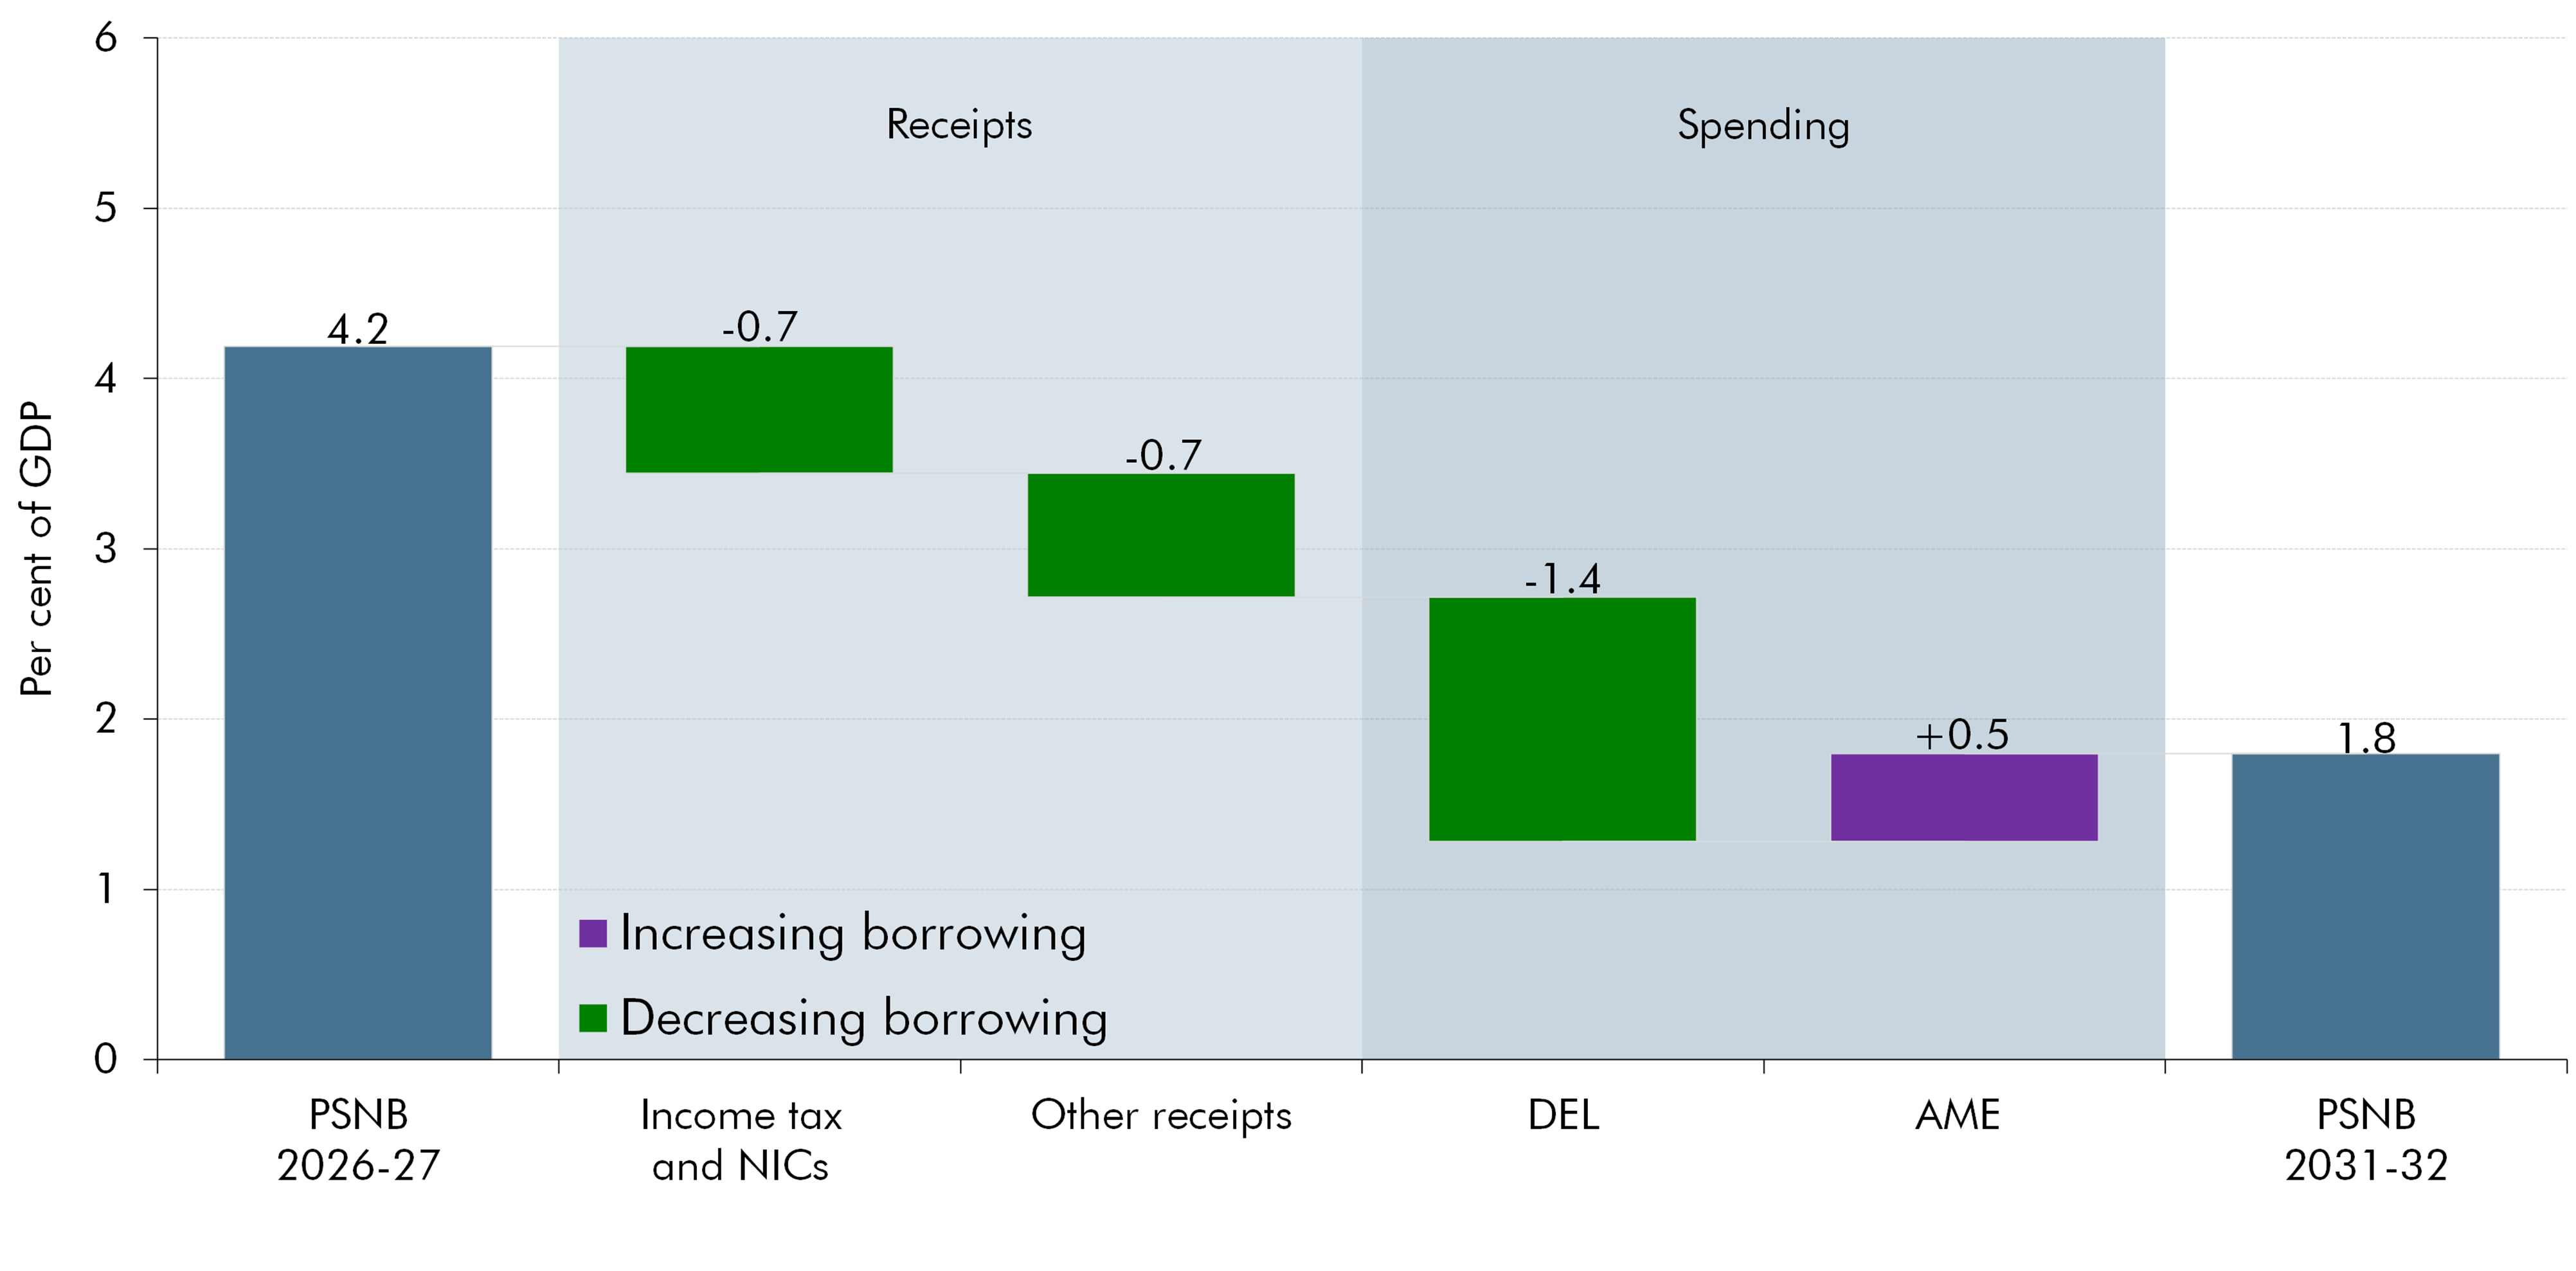
Source: OBR
6.6 Both PSNB and the current budget deficit are expected to fall gradually as a share of GDP over the forecast, but these improvements begin to level off by the end of the forecast period, with PSNB remaining flat and the current budget deficit declining slightly as a share of GDP in 2031-32. Box 6.1 investigates the underlying drivers of this trend in more detail.
Box 6.1: The forecast rise in underlying borrowing from 2030-31 to 2031-32
In the central pre-measures forecast, that is before accounting for the effects of new policy measures, public sector net borrowing falls year on year by around half a per cent of GDP until 2030-31, at which point it is forecast to rise by 0.1 per cent to 2.0 per cent of GDP (Table A). This is an unusual pattern because typically at the end of the forecast – when the economy is usually assumed to be growing at trend and departmental spending is often assumed to be rising in line with nominal GDP – borrowing would be expected to be falling as a share of GDP. This is often driven by ‘fiscal drag’, where tax receipts rise as a share of GDP because earnings are assumed to rise faster than CPI inflation (which is used to uprate personal tax thresholds at the end of the forecast) and by some other areas of underlying buoyancy in the tax regime.
Table A: Pre-measures public sector borrowing
| Per cent of GDP | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Public sector net borrowing (a - b) | 4.2 | 4.0 | 3.2 | 2.8 | 2.2 | 1.9 | 2.0 |
| of which: | |||||||
| Total managed expenditure (a) | 44.5 | 45.4 | 45.4 | 45.1 | 44.6 | 44.5 | 44.7 |
| Public sector current receipts (b) | 40.1 | 41.4 | 42.2 | 42.3 | 42.5 | 42.6 | 42.6 |
| Source: ONS, OBR |
In the current forecast, however, public sector current receipts increase by an average of 0.3 per cent of GDP a year between 2026-27 and 2030-31, but are then flat at 42.6 per cent of GDP in 2031-32. Total managed expenditure falls between 2026-27 and 2030-31, by an average of 0.2 per cent of GDP, but then rises slightly in the final year. So the rise in PSNB in 2031-32 in the pre-measures forecast is driven by flat receipts and slightly rising spending as shares of GDP.
The drivers of these trends relate to the emergence of pressures that we identified in the 2026 Fiscal risks and sustainability (FRS) report and which will intensify over the longer term. Specifically, the upward pressure on pension spending from the ageing population, the reduction in tax revenues from the loss of fuel duty due to the transition to electric vehicles, and the increasing cost of debt interest due to the rising stock of debt. Looking at these components in more detail:
-
Welfare spending is forecast to rise by around 0.1 per cent of GDP in 2031-32. This reflects increasing health-related caseloads and forecast growth in the state pension caseload due to the ageing population. Over previous years of the forecast, the underlying upward trend in pensioner spending is suppressed by the increase to the state pension age between April 2026 and March 2028. This is assessed in more detail in Box 5.1.
-
Fuel duty receipts are forecast to decline slightly as a share of GDP in 2031-32, as the loss of revenue due to the transition to electric vehicles is greater than the increase in revenue from the assumed increase in fuel duty rates at this point. In addition, there are small declines in revenue as a share of GDP from assumed declines in the consumption of tobacco and alcohol, and from declining oil and gas revenues, as discussed in Chapter 4. Overall, the decline in revenues from these sources push up on borrowing by around 0.1 per cent of GDP.
-
Debt interest spending increases borrowing by a further 0.1 per cent of GDP in 2031-32. This is driven by the rising stock of debt and by the rising number of gilts that are forecast to be refinanced at this time horizon at higher interest rates, discussed further in paragraph 5.29.
Overall, in 2031-32, these three effects increase borrowing by around 0.3 per cent of GDP, which more than offsets all the other pre-measures year-on-year changes to tax and spending which are forecast to reduce borrowing in 2031-32 by around 0.2 per cent of GDP. This includes some fiscal drag as earnings are forecast to rise faster than CPI at this time horizon. However, this effect is more muted than in previous years of the forecast where the personal tax thresholds are frozen.
In this Budget, the Government has decided to reduce the pre-measures assumption for the growth in departmental spending in 2031-32, which, combined with policies to increase taxation, helps reduce the forecast for borrowing in this year by 0.2 per cent of GDP. This means that, after the impact of policy, borrowing remains flat between 2030-31 and 2031-32 as a share of GDP. This is an early indication of the additional pressures that the long-term trends highlighted in the 2026 FRS will create for policy-makers aiming to put the public finances on a sustainable path over the coming decades.
Change in forecast borrowing and the current budget deficit since March
6.7 Table 6.2 and Chart 6.3 show that, compared to the March 2026 forecast, PSNB is now forecast to be higher in each year, by £18 billion in 2026-27, £16 billion in 2027-28, and an average of £11 billion each year thereafter. This reflects:
-
Upwards revisions to the pre-measures spending forecast, which increase PSNB by an average of £28 billion per year. This primarily reflects higher debt interest spending, due to higher RPI inflation and interest rates, which increase borrowing by an average of £14 billion each year. Other changes include higher welfare spending largely due to higher CPI inflation, and higher capital spending by departments, described further in Chapter 5.
-
Upwards revisions to the pre-measures receipts forecast which reduce PSNB by an average of £17 billion per year. These are largely driven by a higher forecast for income tax and NICs and corporation tax, reflecting higher forecasts for nominal earnings and profits, described further in Chapter 4.
-
The direct effect of Budget policy measures, which increase PSNB in each year until 2028-29, reflecting policy decisions which reduce receipts in 2026-27 and increase spending in each year. From 2028-29 onwards a set of tax measures reduce borrowing by £7 billion per year on average. A reduction to the pre-measures assumption for total resource departmental spending further reduces borrowing in 2031-32 by £6 billion.
-
The indirect effects of Budget policy measures decrease PSNB in 2026-27 by £1.3 billion, before increasing it by an average of £2.1 billion per year thereafter. This reflects the impact of policies which lower inflation in 2026-27 and in subsequent years the debt interest costs from higher borrowing.
6.8 The lower panel of Table 6.2 shows changes in the forecast for the current budget deficit since March. As with PSNB, the current budget deficit has deteriorated in each year, with a £9 billion reduction in the surplus forecast for 2029-30, the target year for the Government’s fiscal mandate. Differences between the revisions to the forecasts for PSNB and the current budget deficit reflect the increase in capital spending in this forecast compared to March (as set out in Chapter 5 and shown in the green bars in Chart 6.3), partly offset by a higher forecast for depreciation (described in paragraph 4.51). These effects mean that in 2026-27 the deterioration in the current budget deficit is £11 billion less than for PSNB. The net impact of changes to capital spending and depreciation on the current budget deficit reduce over the forecast period until largely cancelling each other out in 2030-31.
Table 6.2: Public sector net borrowing and the current budget deficit: changes since March
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| March 2026 PSNB | 132.7 | 115.5 | 96.5 | 86.0 | 63.4 | 59.0 | |
| October 2026 PSNB | 134.3 | 133.2 | 112.0 | 99.5 | 73.8 | 66.9 | 68.3 |
| Difference | 1.6 | 17.7 | 15.5 | 13.5 | 10.4 | 7.9 | |
| of which: | |||||||
| Underlying differences | 11.4 | 8.5 | 11.4 | 13.0 | 11.4 | ||
| of which: | |||||||
| Spending | 25.6 | 26.3 | 31.0 | 29.9 | 26.9 | ||
| of which: | |||||||
| Debt interest spending | 15.4 | 16.0 | 12.0 | 12.0 | 12.1 | ||
| Capital spending | 11.5 | 6.1 | 5.5 | 5.1 | 3.6 | ||
| Welfare | -0.2 | 4.0 | 8.6 | 7.8 | 6.6 | ||
| Other spending | -1.1 | 0.2 | 5.0 | 5.1 | 4.6 | ||
| Receipts | -14.2 | -17.8 | -19.6 | -16.9 | -15.5 | ||
| of which: | |||||||
| Income tax and NICs | -8.5 | -9.8 | -9.9 | -11.9 | -13.4 | ||
| Onshore corporation tax(1) | -5.9 | -4.4 | -6.1 | -6.2 | -5.7 | ||
| Other receipts | 0.1 | -3.6 | -3.6 | 1.1 | 3.6 | ||
| Direct effects of policy decisions | 7.6 | 3.5 | 0.4 | -4.1 | -5.0 | -11.7 | |
| of which: | |||||||
| Tax decisions | 1.7 | -0.3 | -3.1 | -5.8 | -6.6 | -7.5 | |
| DEL spending decisions(2) | 5.4 | 1.2 | 1.5 | -0.1 | -0.2 | -6.0 | |
| Other spending decisions(2) | 0.4 | 2.7 | 2.0 | 1.8 | 1.8 | 1.8 | |
| Indirect effects of policy decisions | -1.3 | 3.5 | 1.7 | 1.4 | 1.4 | 2.4 | |
| March 2026 current budget deficit(3) | 49.2 | 33.9 | 4.6 | -3.3 | -23.6 | -30.3 | |
| October 2026 current budget deficit(3) | 47.4 | 40.6 | 17.5 | 7.8 | -14.5 | -21.7 | -20.9 |
| Difference | -1.8 | 6.6 | 13.0 | 11.1 | 9.0 | 8.6 | |
| of which: | |||||||
| PSNB | 17.7 | 15.5 | 13.5 | 10.4 | 7.9 | ||
| Capital spending | -11.7 | -4.5 | -4.9 | -4.2 | -2.2 | ||
| Depreciation | 0.7 | 1.9 | 2.4 | 2.9 | 2.9 |
| Note: This table uses the convention that a negative figure means a reduction in PSNB i.e. an increase in receipts or a reduction in spending will have a negative effect on PSNB. |
| 1) Contains Pillar 2 receipts. |
| 2) Only the net effects of the 2024 valuations of unfunded public pensions measure are included within these lines. Those effects which offset between ‘DEL spending decisions’ and ‘Other spending decisions’ are excluded. |
| 3) The current budget deficit in a given year is equal to public sector current receipts minus public sector current expenditure. It can also be derived, for a given year, as PSNB minus capital spending plus depreciation. |
| Source: ONS, OBR |
Chart 6.3: Changes in borrowing and the current budget deficit since March
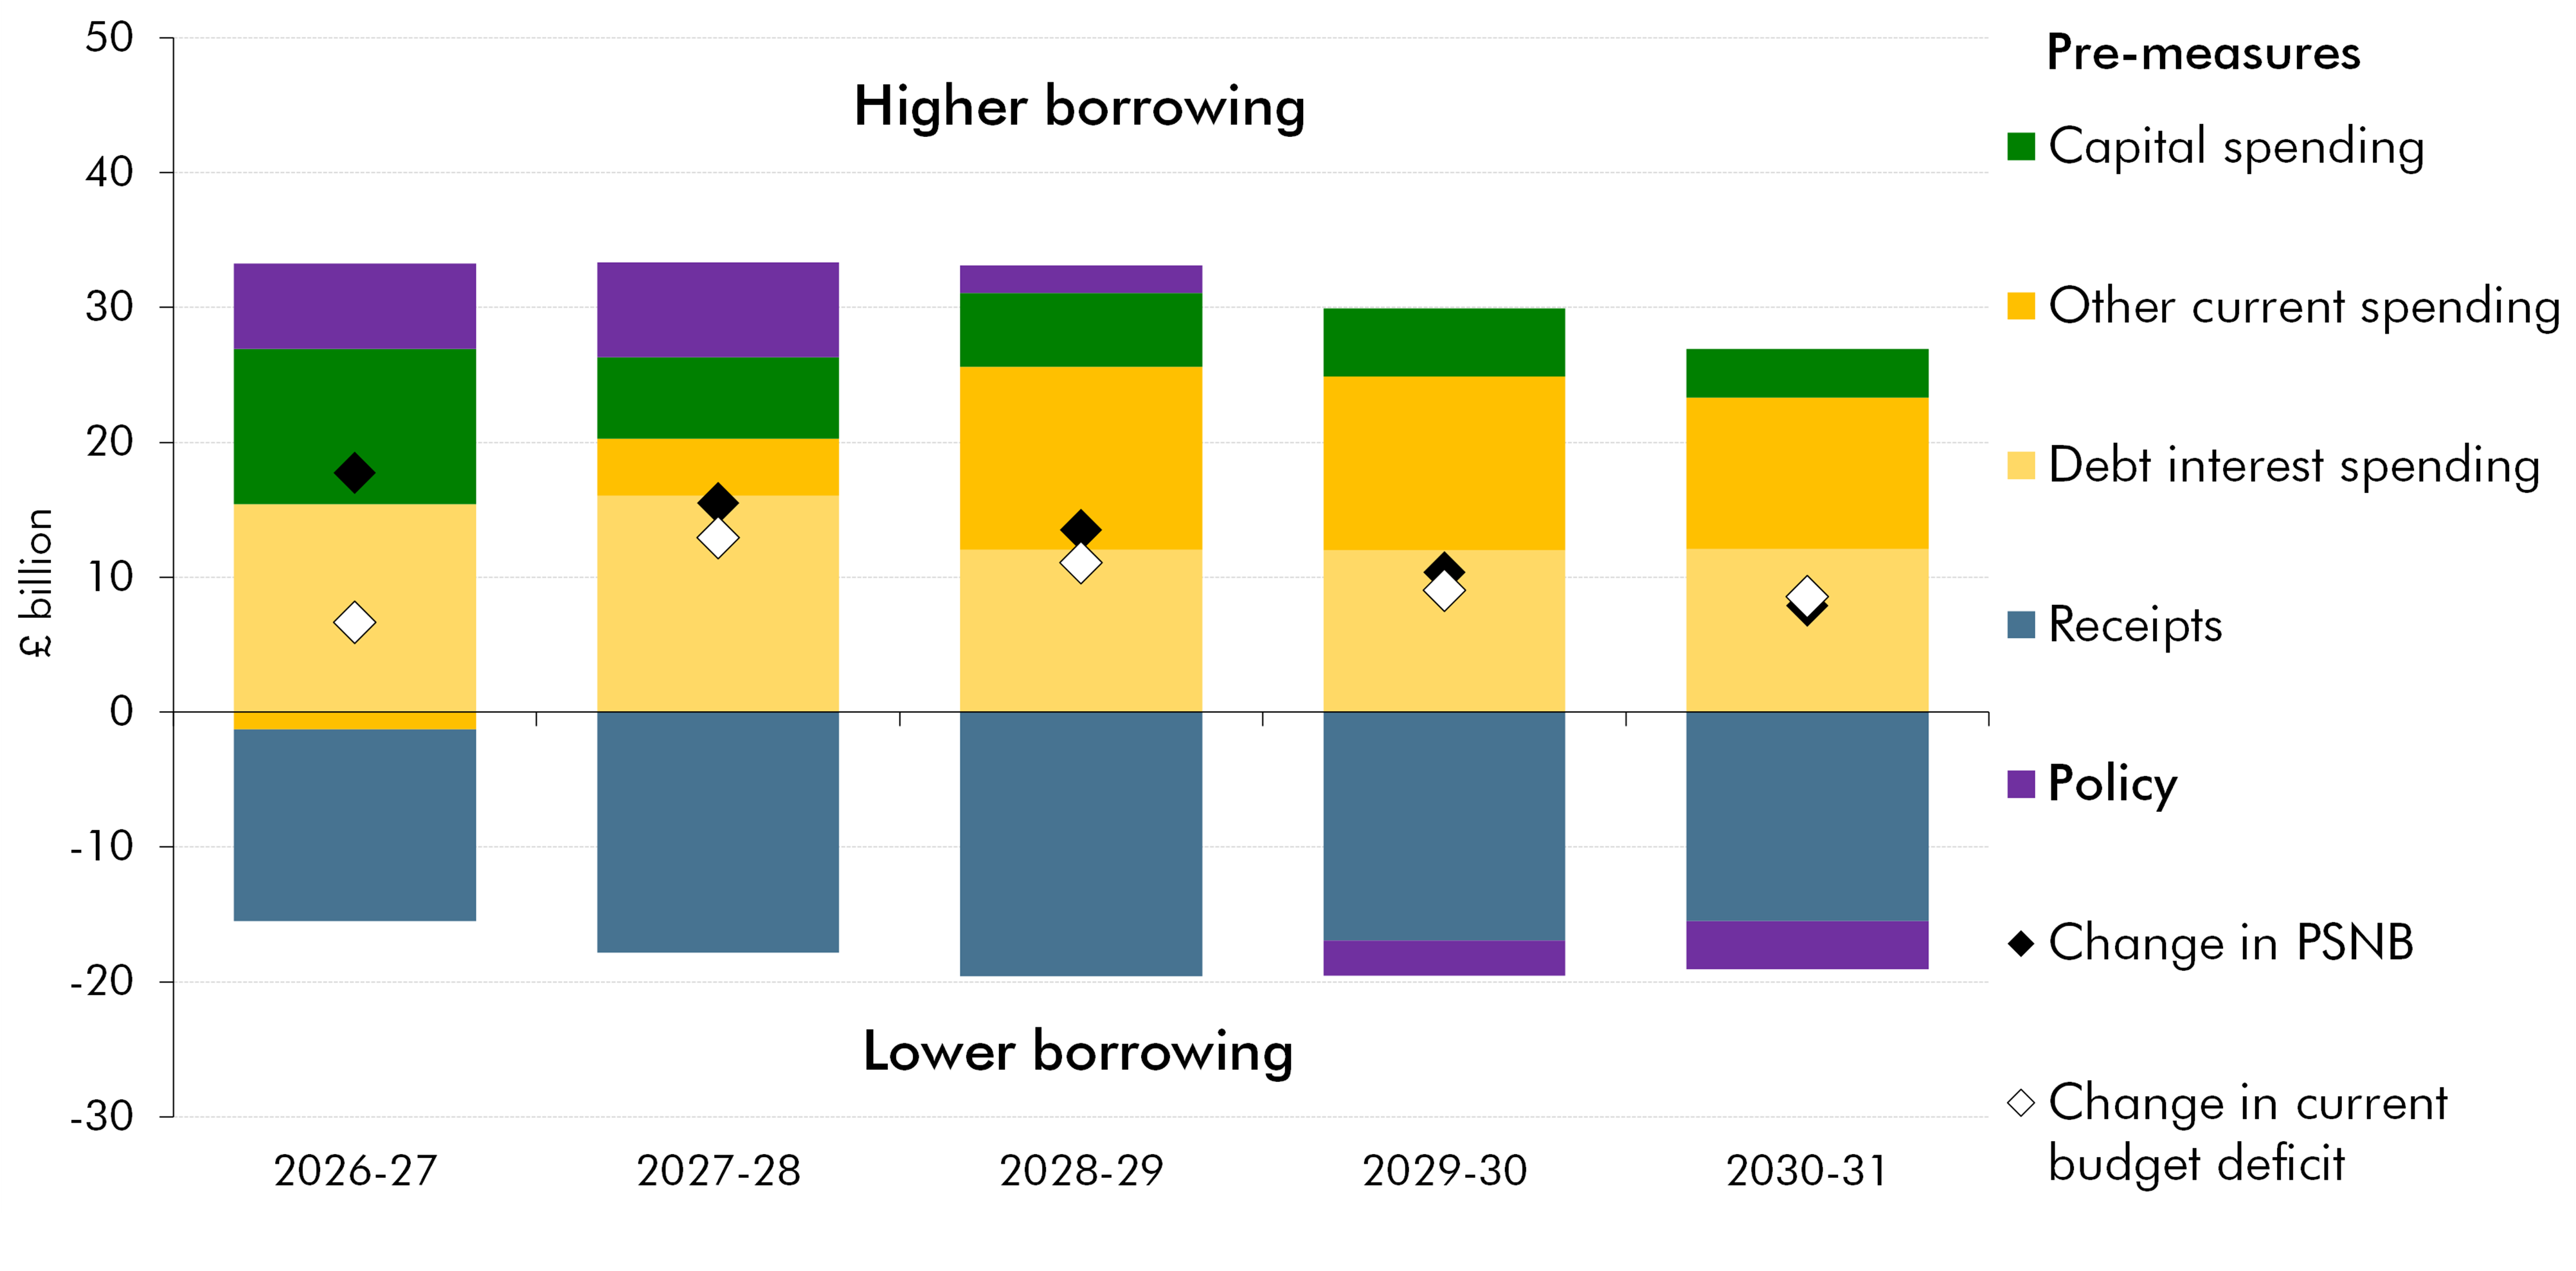
Source: OBR
6.9 The forecasts for deficit aggregates such as PSNB and the current budget deficit are particularly uncertain given that they measure the difference between around £1.5 trillion a year of both receipts and spending by the end of the decade. A small percentage change in the forecast for either can therefore lead to a large percentage change in the forecast for the deficit. For example, in 2029-30 year on year receipts growth is only forecast to be 2 percentage points higher than spending growth, but as a result PSNB is forecast to fall by 26 per cent compared to the previous year.
6.10 Chart 6.4 highlights this uncertainty by showing a range of possible outcomes around the central forecast for PSNB, based on the distribution of historical shocks. It shows a 60 per cent chance of PSNB falling between a surplus of 1.0 per cent of GDP (£38 billion) and a deficit of 4.4 per cent of GDP (£168 billion) in 2031-32. The key current risks and uncertainties around the forecasts for tax, spending and wider fiscal aggregates are assessed in detail in Chapter 7.
Chart 6.4: Fan chart for PSNB
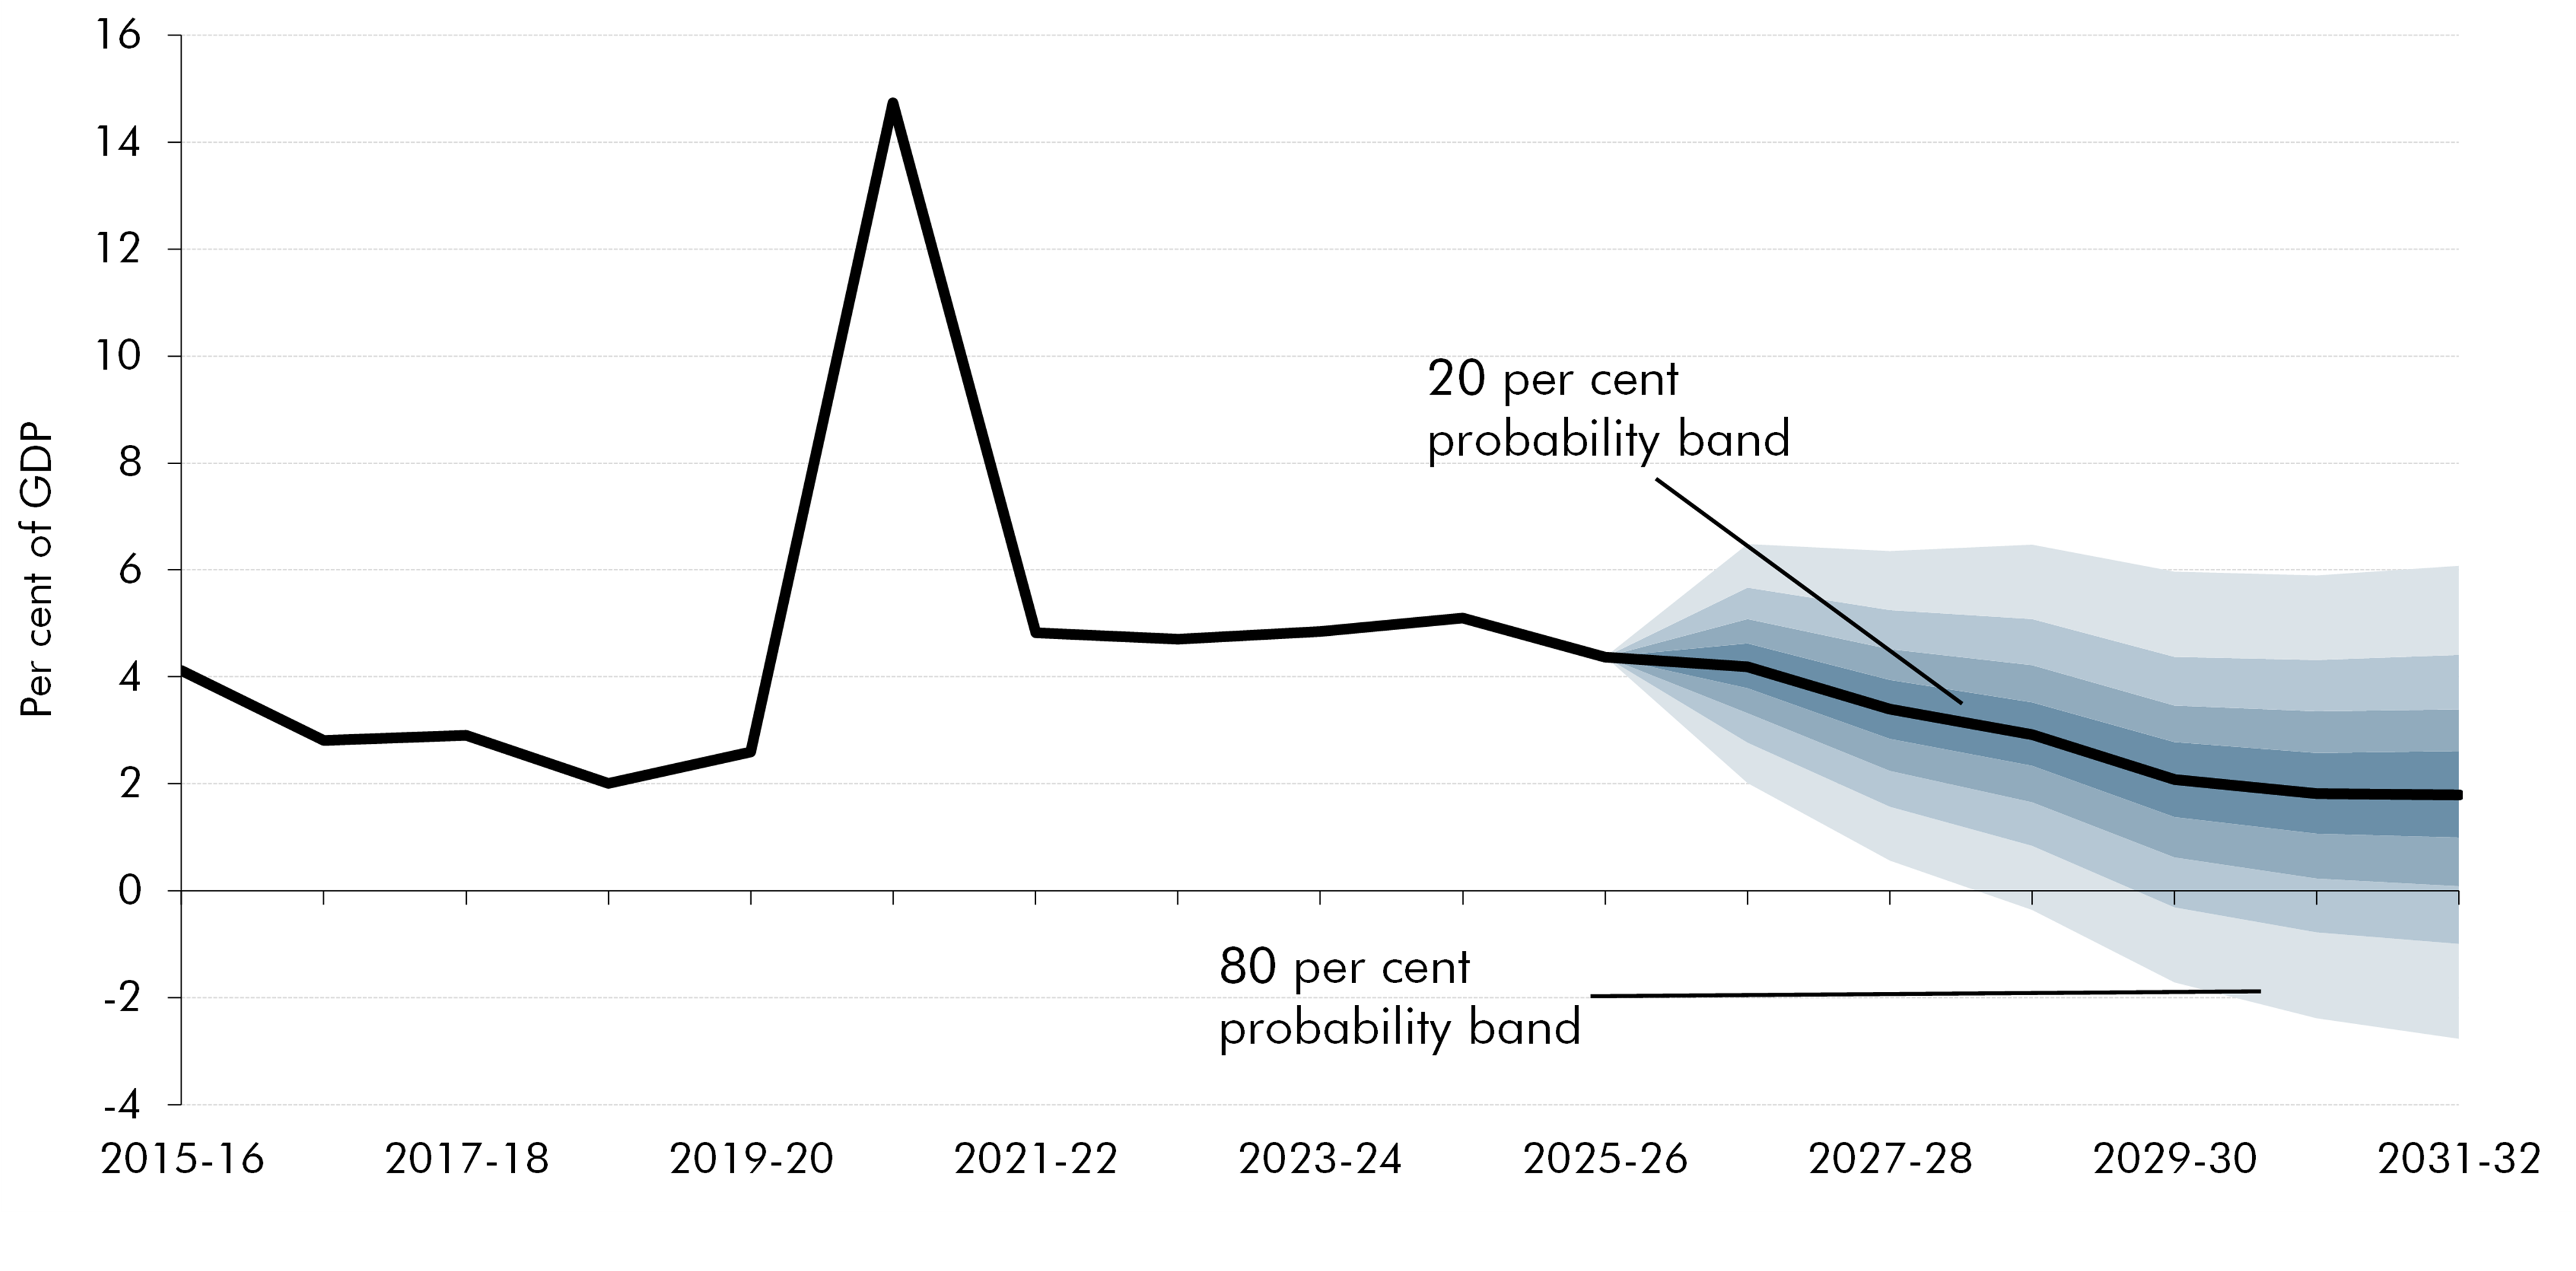
Note: The solid black line shows outturn and our median forecast, with successive pairs of lighter shaded areas around it representing 20 per cent probability bands, with 20 per cent of the distribution outside the fan.
Source: OBR
Other deficit measures
6.11 Other deficit measures also provide relevant information on the state of the public finances. The primary deficit, which excludes net interest spending, is a useful proxy of the extent to which discretionary spending is covered by revenues. All measures of the deficit can be presented in cyclically adjusted terms, correcting for an estimate of the position in the economic cycle, which provides a rough indication of the underlying or structural deficit:
-
The primary deficit moves from 1 per cent of GDP this year to a surplus of 1.7 per cent of GDP in 2031-32. If achieved, this would be the largest primary surplus since 2000-01. Compared to the March forecast the primary deficit is an average of 0.1 per cent of GDP higher in each year until 2029-30, but the same in 2030-31. This reflects that the medium-term deterioration in PSNB compared to March can be seen as driven largely by higher net interest spending, with other changes to spending and receipts broadly offsetting.
-
Cyclically adjusted measures of the deficit are 0.7 per cent of GDP below the unadjusted metrics in 2026-27 and 2027-28. The gap narrows over each of the subsequent years until 2031-32 when it closes. This reflects the negative output gap this year and subsequent closing of the output gap across the forecast.
Financial transactions
6.12 Changes in public sector net debt and wider balance sheet aggregates, including public sector net financial liabilities, are calculated by combining changes in borrowing with changes in financial transactions and valuation effects. Financial transactions capture the effects of public sector net lending, sales or purchases of financial assets, and interventions which affect the Bank of England’s (BoE’s) balance sheet. They also convert the accrued measures of tax and spending which underpin our forecast for borrowing into the cash flows relevant to debt. Valuation effects capture changes in the value of the assets or liabilities held by the public sector which count toward the measure of net debt.
6.13 In nominal terms public sector net debt is forecast to increase in each year from 2026-27 onwards, by an average of £129 billion a year. Table 6.3 breaks down the contribution to the year-on-year increases in PSND from public sector net borrowing, pre-measures financial transactions, policy measures which affect financial transactions, and valuation effects. It shows:
-
Public sector net borrowing is forecast to increase PSND in each year from 2026-27, by an average of £92 billion, as discussed in paragraph 6.7.
- Pre-measures financial transactions increase debt in each year of the forecast, due to:
-
The cost of student loans, which increase debt on average £9 billion a year over the forecast reflecting new lending to students.
-
Repayments to the Bank of England’s Term Funding Scheme (TFS) which reduce debt by £26 billion in 2026-27. The TFS then has no further effect until 2030-31 where it reduces debt by £16 billion due to the expected one-off payment as the scheme comes to an end.
-
Losses on gilts held within the Asset Purchase Facility (APF), incurred when gilts are sold for less than their face value, raise debt by an average of £4.3 billion a year.
-
Net lending and purchases of equity by public financial institutions (PuFins) increase debt by an average of £3.1 billion each year.[footnote 78]
-
-
Cash flow timing effects, which convert the accrued measures of tax and spending in the forecast for borrowing into the cash flows relevant to debt, raise debt by an average of £19 billion a year. Of this, accruals adjustments for taxes contribute an average of £10 billion a year and the removal of modified interest on student loans an average of £9 billion a year.
-
The direct effects of policy measures on financial transactions increase debt in every year of the forecast, apart from 2029-30, by on average of £2.7 billion. This is mainly due to policies which increase the funding for the National Wealth Fund and British Business Bank to invest in financial assets (see paragraph 3.20 for more detail). In 2029-30, the policy to introduce timely payment for self assessment decreases debt by £17 billion due to the additional tax payments brought forward to that year (see paragraph 3.13 for more detail). These cash payments have no effect on accrued measures such as PSNB or PSNFL.
- Valuation effects increase debt by £11 billion in 2026-27 and an average of £1.2 billion thereafter. These largely reflect the consequences of new gilts being issued at a discount to the face value they are recorded at in the public finances, an effect which subsides over the forecast as we assume that a greater proportion of gilts are issued for nearer to face value.
6.14 The bottom panel of Table 6.3 shows that, relative to March, year-on-year growth in debt is forecast to be higher in each year of the forecast, aside from 2029-30 (where the downwards revision reflects the policy to introduce timely payment for self assessment). These upwards revisions are largely driven by higher PSNB, reflecting the factors set out in paragraph 6.7. There is a particularly large upward revision to PSND in 2026-27, of £33 billion, which is driven by revisions to financial transactions and valuation effects which add a combined £16 billion to debt, in addition to the increase to the PSNB forecast in this year. Revisions to underlying financial transactions and valuation effects across the subsequent forecast years are modest, reflecting the offsetting effects of upwards revisions to cash flow timing effects and lower effects from APF sales losses and student loans.
Table 6.3: Public sector net debt: year-on-year changes
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Year-on-year change in PSND | 113.5 | 163.9 | 156.8 | 144.8 | 103.2 | 96.0 | 111.3 |
| of which: | |||||||
| PSNB | 133.2 | 112.0 | 99.5 | 73.8 | 66.9 | 68.3 | |
| Underlying changes in financial transactions(1) | 19.5 | 41.3 | 42.3 | 41.1 | 24.4 | 38.1 | |
| of which: | |||||||
| Student loans net lending | 15.8 | 9.1 | 9.2 | 9.4 | 9.5 | 9.3 | |
| Term funding scheme repayments | -26.4 | 0.0 | 0.0 | 0.0 | -15.5 | 0.0 | |
| Asset Purchase Facility sales losses | 1.5 | 3.7 | 3.8 | 4.6 | 4.5 | 4.6 | |
| Public financial institutions | 6.1 | 5.3 | 3.9 | 2.9 | 2.0 | 1.4 | |
| Cash flow timing effects(2) | 19.1 | 21.3 | 18.7 | 18.9 | 17.6 | 16.8 | |
| Other financial transactions | 3.4 | 2.0 | 6.6 | 5.3 | 6.2 | 5.9 | |
| Effects of policy on financial transactions(3) | -0.1 | 0.8 | 2.1 | -12.4 | 3.9 | 4.0 | |
| Valuation effects2,4 | 11.3 | 2.6 | 0.9 | 0.8 | 0.8 | 1.0 | |
| Changes since March | |||||||
| Year-on-year change in PSND | 33.1 | 18.4 | 16.8 | -4.5 | 9.5 | ||
| of which: | |||||||
| PSNB | 17.7 | 15.5 | 13.5 | 10.4 | 7.9 | ||
| Underlying changes in financial transactions(1) | 6.3 | 0.8 | 1.6 | -2.1 | -1.8 | ||
| of which: | |||||||
| Student loans net lending | 1.3 | -0.7 | -0.7 | -0.7 | -0.4 | ||
| Term funding scheme repayments | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | ||
| Asset Purchase Facility sales losses | -1.7 | -0.4 | -0.5 | -0.4 | -0.9 | ||
| Public financial institutions | 1.7 | 0.3 | -0.1 | 0.3 | 1.5 | ||
| Cash flow timing effects(2) | 4.1 | 4.6 | 3.8 | 1.6 | 0.4 | ||
| Other financial transactions | 0.8 | -3.0 | -0.8 | -3.0 | -2.5 | ||
| Effects of policy on financial transactions(3) | -0.1 | 0.8 | 2.1 | -12.4 | 3.9 | ||
| Valuation effects2,4 | 9.3 | 1.2 | -0.4 | -0.4 | -0.5 |
| 1) Contains impacts of our pre-measures forecast and indirect effects of policy measures, beyond those already captured within PSNB. |
| 2) Excludes the uplift on index-linked gilts which nets out between cash flow timing and valuation effects. |
| 3) Contains the direct effects of policy measures on debt, beyond those already caputured within PSNB. |
| 4) Effects of the premia on gilts held in the APF are subtracted from this line but included as part of the APF sales losses line. |
| Source: ONS, OBR |
Asset Purchase Facility
6.15 The impact of the Bank of England’s Asset Purchase Facility (APF) on fiscal aggregates over the forecast period is dependent on changes in Bank Rate, gilt yields, and the assumed pace at which the stock of gilts held within the APF is unwound. After reducing its gilt holdings by £70 billion in 2025-26, the Monetary Policy Committee decided at its September 2026 meeting that active sales will be paused until April 2027. Thereafter, the MPC stated that the APF will unwind with a constant pace of active sales of £20 billion a year, which results in an average annual reduction in gilts of £53 billion a year over the forecast, when including redemptions (Table 6.4).[footnote 79]
Table 6.4: APF annual runoff
| £ billion | ||||||
|---|---|---|---|---|---|---|
| 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Forecast | ||||||
| Total gilts held within the APF (start of year) | 527.9 | 482.4 | 410.1 | 356.3 | 312.9 | 247.0 |
| Total reduction of gilts held within the APF(1) | 45.5 | 72.3 | 53.8 | 43.4 | 66.0 | 31.1 |
| of which: | ||||||
| Active sales | 10.4 | 20.0 | 20.0 | 20.0 | 20.0 | 20.0 |
| Redemptions | 35.0 | 52.3 | 33.8 | 23.4 | 46.0 | 11.1 |
| Note: This table, now presented on a fiscal year basis, was previously presented on an October to September basis reflecting the MPC’s previous policy to set the unwind for the following 12 months at its September meeting. The MPC’s latest decision corresponds to a multi-year plan of constant active sales beginning in April 2027. |
| 1) The annual reduction of gilts held in the APF is based on values at initial purchase price. |
| Source: Bank of England, OBR |
6.16 The APF’s direct impact on the current budget deficit, the Government’s target measure for its fiscal mandate, is driven only by APF interest losses. APF valuation losses on sales or redemptions do not affect the current budget deficit but do increase cash transfers from central government to the Bank. Both interest losses and valuation losses on sales impact PSND and PSNFL (Table 6.5).
6.17 APF interest losses are forecast to decrease the forecast current budget surplus in 2029-30 by £8 billion. This is £3.3 billion greater than forecast in March due to higher market-implied Bank Rate and the slower pace of the unwind of gilt holdings. APF transactions increase PSNFL and PSND by around £12 billion on average a year over the forecast period. The slower assumed pace of APF unwind reduces sales losses by £0.4 billion by 2029-30 compared to the March forecast. This means that, overall, the impact of APF interest and sales losses on PSNFL is £3.0 billion higher in 2029-30 than we forecast in March.[footnote 80]
Table 6.5: Impact of the Asset Purchase Facility on fiscal aggregates
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Forecast | ||||||
| 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| APF interest losses (a) | 8.6 | 11.0 | 9.5 | 8.1 | 6.4 | 5.4 |
| APF valuation losses on sales (b)(1) | 1.5 | 3.7 | 3.8 | 4.6 | 4.5 | 4.6 |
| Impact on current budget deficit/PSNB (a) | 8.6 | 11.0 | 9.5 | 8.1 | 6.4 | 5.4 |
| Impact on PSNFL/PSND (a + b) | 10.1 | 14.6 | 13.3 | 12.7 | 10.9 | 10.0 |
| Memo: APF valuation losses | 5.2 | 10.6 | 13.0 | 10.1 | 14.5 | 8.1 |
| Changes since March | ||||||
| APF interest losses (a) | 2.6 | 5.7 | 4.4 | 3.3 | 2.7 | |
| APF valuation losses on sales (b)(1) | -1.7 | -0.4 | -0.5 | -0.4 | -0.9 | |
| Impact on current budget deficit/PSNB (a) | 2.6 | 5.7 | 4.4 | 3.3 | 2.7 | |
| Impact on PSNFL/PSND (a + b) | 1.0 | 5.3 | 3.9 | 3.0 | 1.8 | |
| Memo: APF valuation losses | -4.4 | -2.5 | -2.9 | -3.3 | -2.3 |
| Note: This table uses the convention that a positive figure means an increase in fiscal aggregates, i.e. an increase in the current budget deficit or in PSNFL/PSND. For detail on APF cash flows, see the online detailed forecast tables: aggregates. |
| 1) Sales losses are realised when gilts held in the APF are sold below their redemption price, which increases PSND and PSNFL. |
| Source: OBR |
6.18 Chart 6.5 shows outturn and projections for the nominal quarterly income, outlays and cumulative transfers of the APF from 2012 to 2033, when active sales are expected to end under the MPC’s multi-year plan. Based on these projections the estimated cumulative lifetime cost of the APF in net present value terms is £114 billion or in real terms is £140 billion.[footnote 81] As shown in Chart 6.5, the APF income flows which underpin this estimate are very sensitive to the future path of interest rates, which is highly uncertain. A comprehensive assessment of the overall economic impact of the quantitative easing (QE) programme would take account of its effects on, among other things, government financing costs, asset prices and labour and financial markets.[footnote 82] The Bank of England has estimated that reduced debt interest costs due to QE have resulted in fiscal savings of between £50 billion and £125 billion.[footnote 83]
Chart 6.5: Cumulative flows of the APF: outturn and projections to 2033
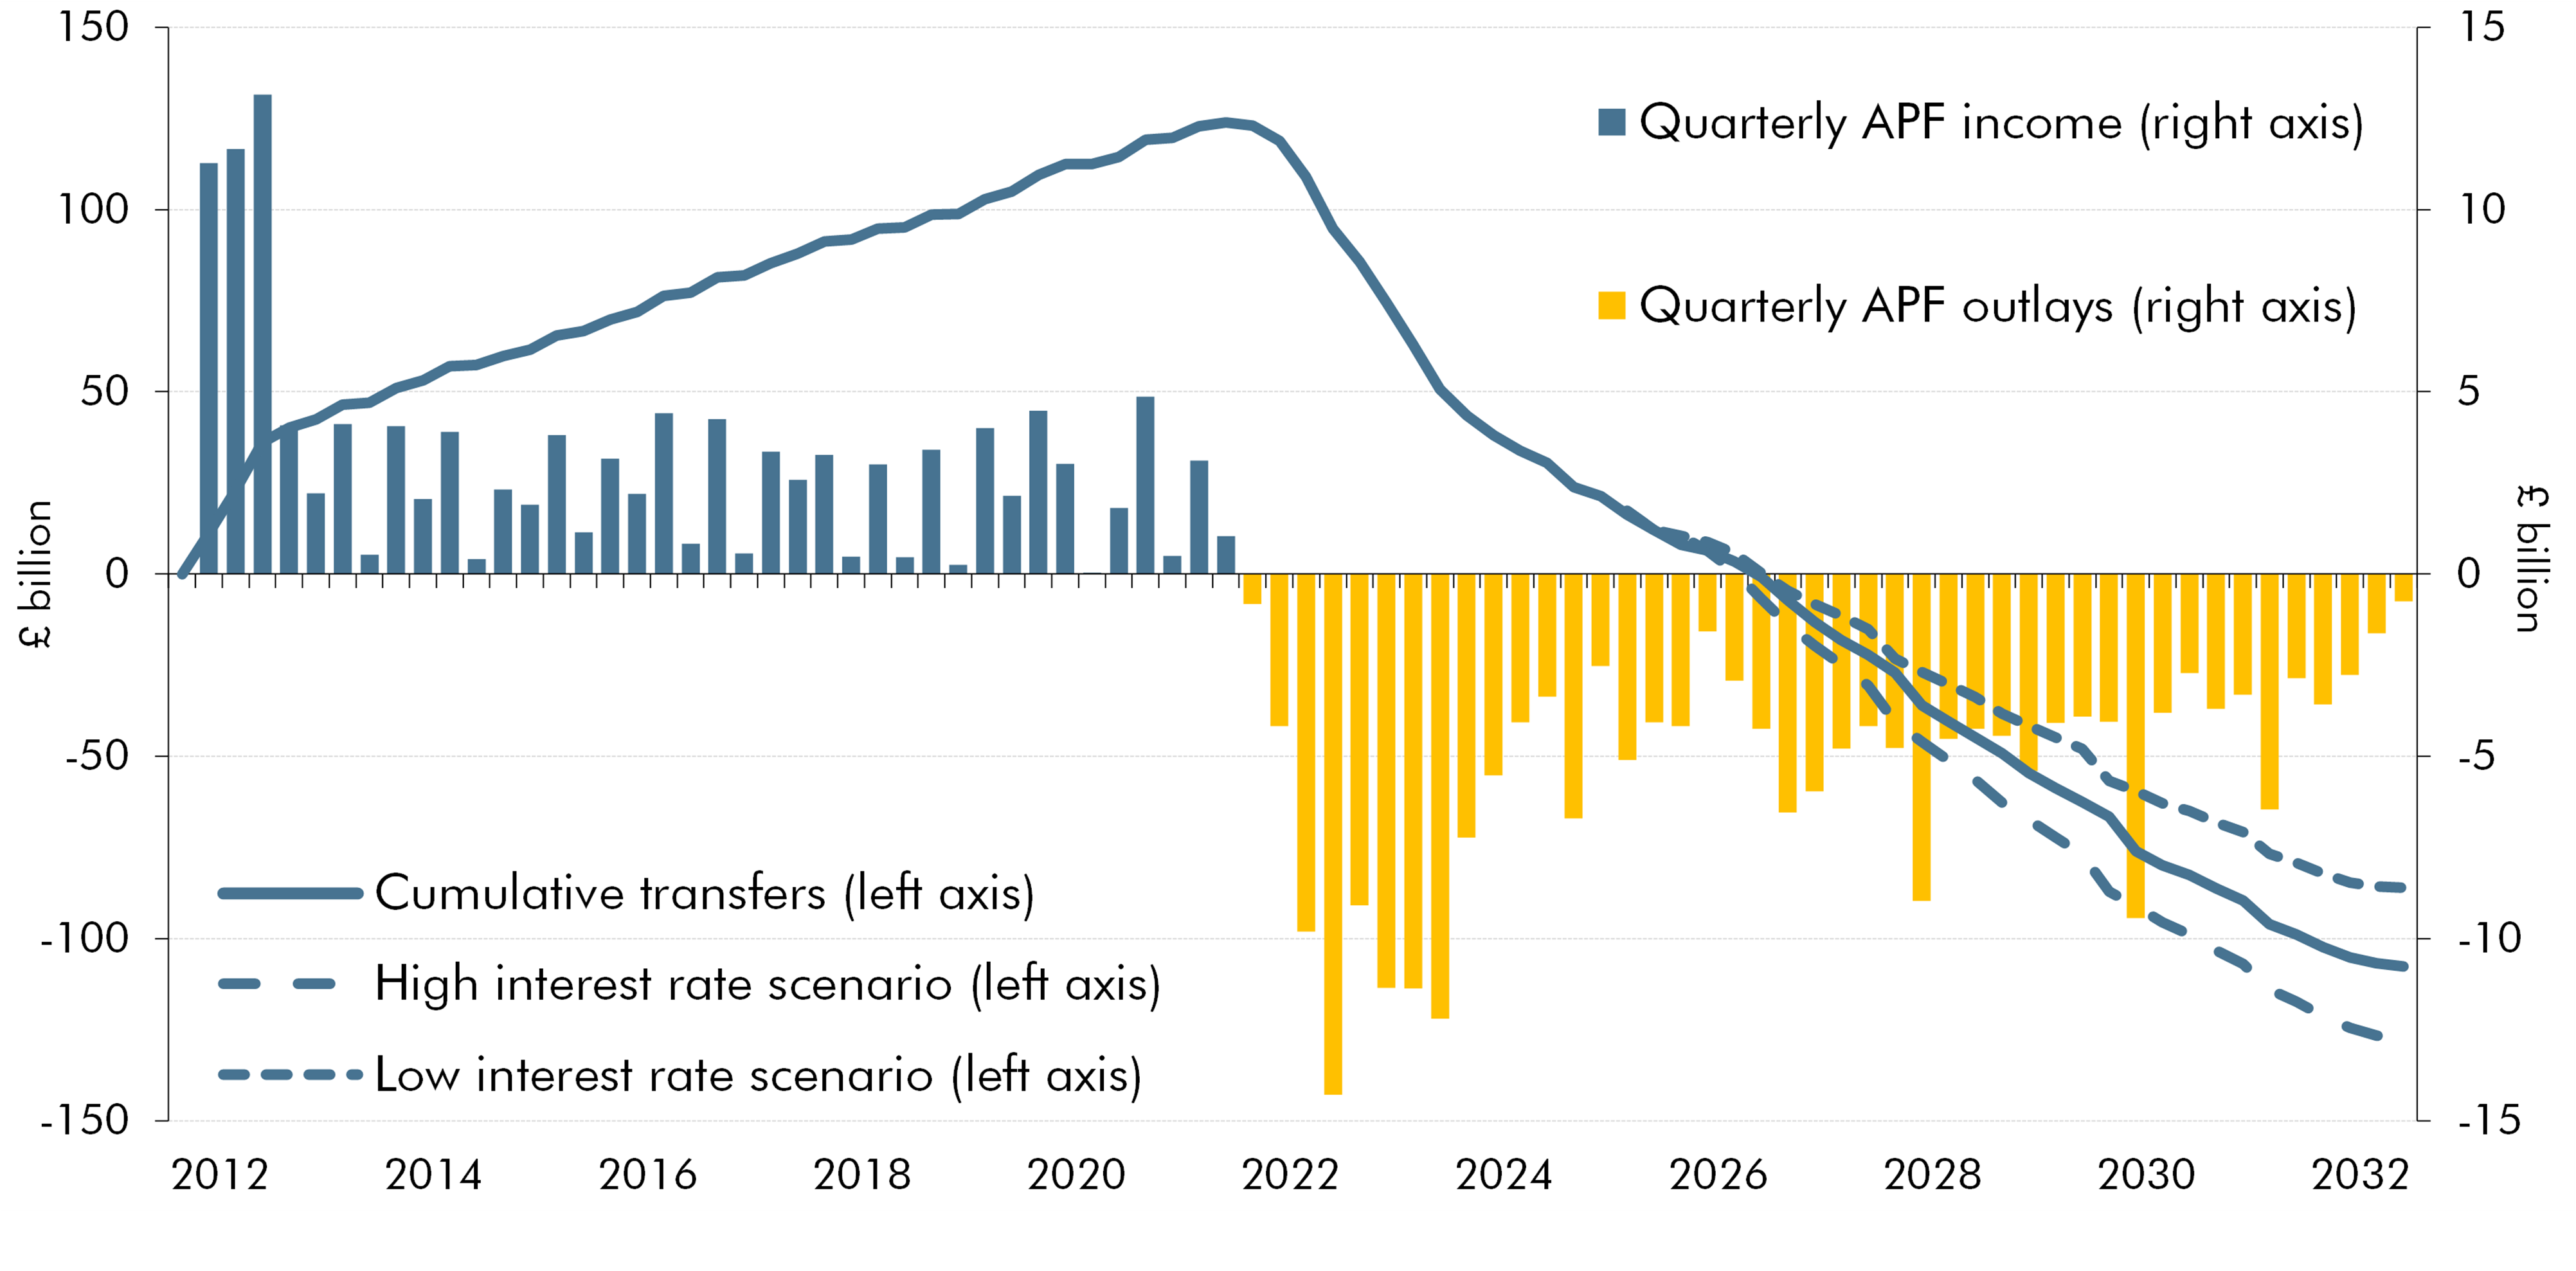
Note: The chart shows the nominal cumulative flows of the APF until the end of active sales in 2033. Beyond this point over £120 billion of gilts will stay within the APF until redemption. The high and low interest rate scenarios show the impact of a 1 percentage point increase and decrease in bank rate respectively.
Source: DMO, OBR
Financing requirement
6.19 Public sector net borrowing is comprised of central government, local government, and public corporations’ borrowing. The central government net cash requirement (CGNCR), which only covers central government and is on a cash basis, forms the basis of the Debt Management Office’s (DMO’s) financing remit and so is the primary driver of the net issuance of gilts.
6.20 Table 6.6 shows the relationship between the CGNCR and PSNB. First, financial transactions are added to borrowing to get the cash requirement of the whole public sector (PSNCR). The cash requirements for non-central government (local authorities, public corporations and Network Rail) are then removed to get to the CGNCR excluding Network Rail (CGNCR ex), which is the measure that feeds directly into the Government’s gilt issuance plans, which also cover the rolling over of maturing debt securities.
6.21 The CGNCR ex is forecast to be £144 billion this year, to peak at £150 billion in 2028-29, and then to fall to £105 billion at the end of the forecast. It is on average £36 billion higher per year than PSNB across the forecast period, which largely reflects the additional financing required for the financial transactions set out in paragraph 6.13. Changes since the March forecast are broadly similar to changes in PSNB in 2028-29 and 2030-31. In 2026-27 and 2027-28, the change in CGNCR ex compared to March is considerably less than the change in PSNB. This is because the inflation driven increases to the cost of index-linked gilts only affects the accrued measures of borrowing and does not need to be financed for many years. In 2029-30, the £17 billion of additional cash payments associated with the policy to introduce timely payment for self assessment (explained in further detail in paragraph 3.13) reduces the CGNCR ex, but does not affect PSNB.
Table 6.6: Reconciliation of PSNCR and CGNCR
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Public sector net borrowing (a) | 134.3 | 133.2 | 112.0 | 99.5 | 73.8 | 66.9 | 68.3 |
| Financial transactions (b) | -99.2 | -7.7 | 39.2 | 56.1 | 13.1 | 31.7 | 36.4 |
| Public sector net cash requirement (PSNCR) (a+b) | 35.1 | 125.5 | 151.2 | 155.7 | 86.9 | 98.6 | 104.7 |
| Less local authorities and public corporations NCR (c) | -100.0 | -19.9 | 11.0 | 4.1 | 1.4 | -17.1 | -1.8 |
| CG net cash requirement (CGNCR) (a+b-c) | 135.1 | 145.5 | 140.2 | 151.6 | 85.4 | 115.8 | 106.5 |
| Less Network Rail NCR (d) | -0.8 | 1.4 | -5.9 | 1.8 | 1.8 | 1.0 | 1.8 |
| CGNCR ex Network Rail (a+b-c-d) | 135.9 | 144.1 | 146.1 | 149.8 | 83.6 | 114.8 | 104.7 |
| Source: ONS, OBR |
6.22 As shown in Chart 6.6, gross gilt issuance by the DMO averages 8.1 per cent of GDP (£287 billion) per year across the forecast period (blue bars). Gross gilt issuance comprises new financing and the refinancing of the gilts which redeem each year. Net gilt issuance (black line) is therefore lower at an average of 2.9 per cent of GDP per year, reflecting the profile of redemptions of gilts (green bars), which average 5.2 per cent of GDP. There is a particularly high volume of redemptions in the final year of the forecast (£229 billion). This reflects the maturity of a significant number of gilts issued during the Covid pandemic – £92 billion of the record volume of gilts issued in 2020-21 and 2021-22 redeem in 2031-32. This is one factor that is pushing up debt interest costs in the final year of the forecast, as explained in paragraph 5.28, as these gilts are expected to be refinanced at higher interest rates.
6.23 More generally, the composition of gilts issued by the DMO in recent years has become skewed toward shorter maturities. As interest rates are lower at shorter maturities this has decreased interest costs for the Government in the near term. However, it increases the value of gilts that are redeemed and require refinancing in future, so increasing sensitivity to changes in rates. This is discussed in more detail in Box 6.1 in the November 2025 EFO.
6.24 As the APF unwinds and sells the gilts that it holds (yellow bars), this adds to the total gilts that must be held by the private sector (orange line),[footnote 84] which contributes to an average of 4.3 per cent of GDP each year over the forecast. This is more than 50 per cent higher than the average annual increase in private sector holdings of gilts between 2000-01 and 2022-23.
Chart 6.6: UK gilt issuance
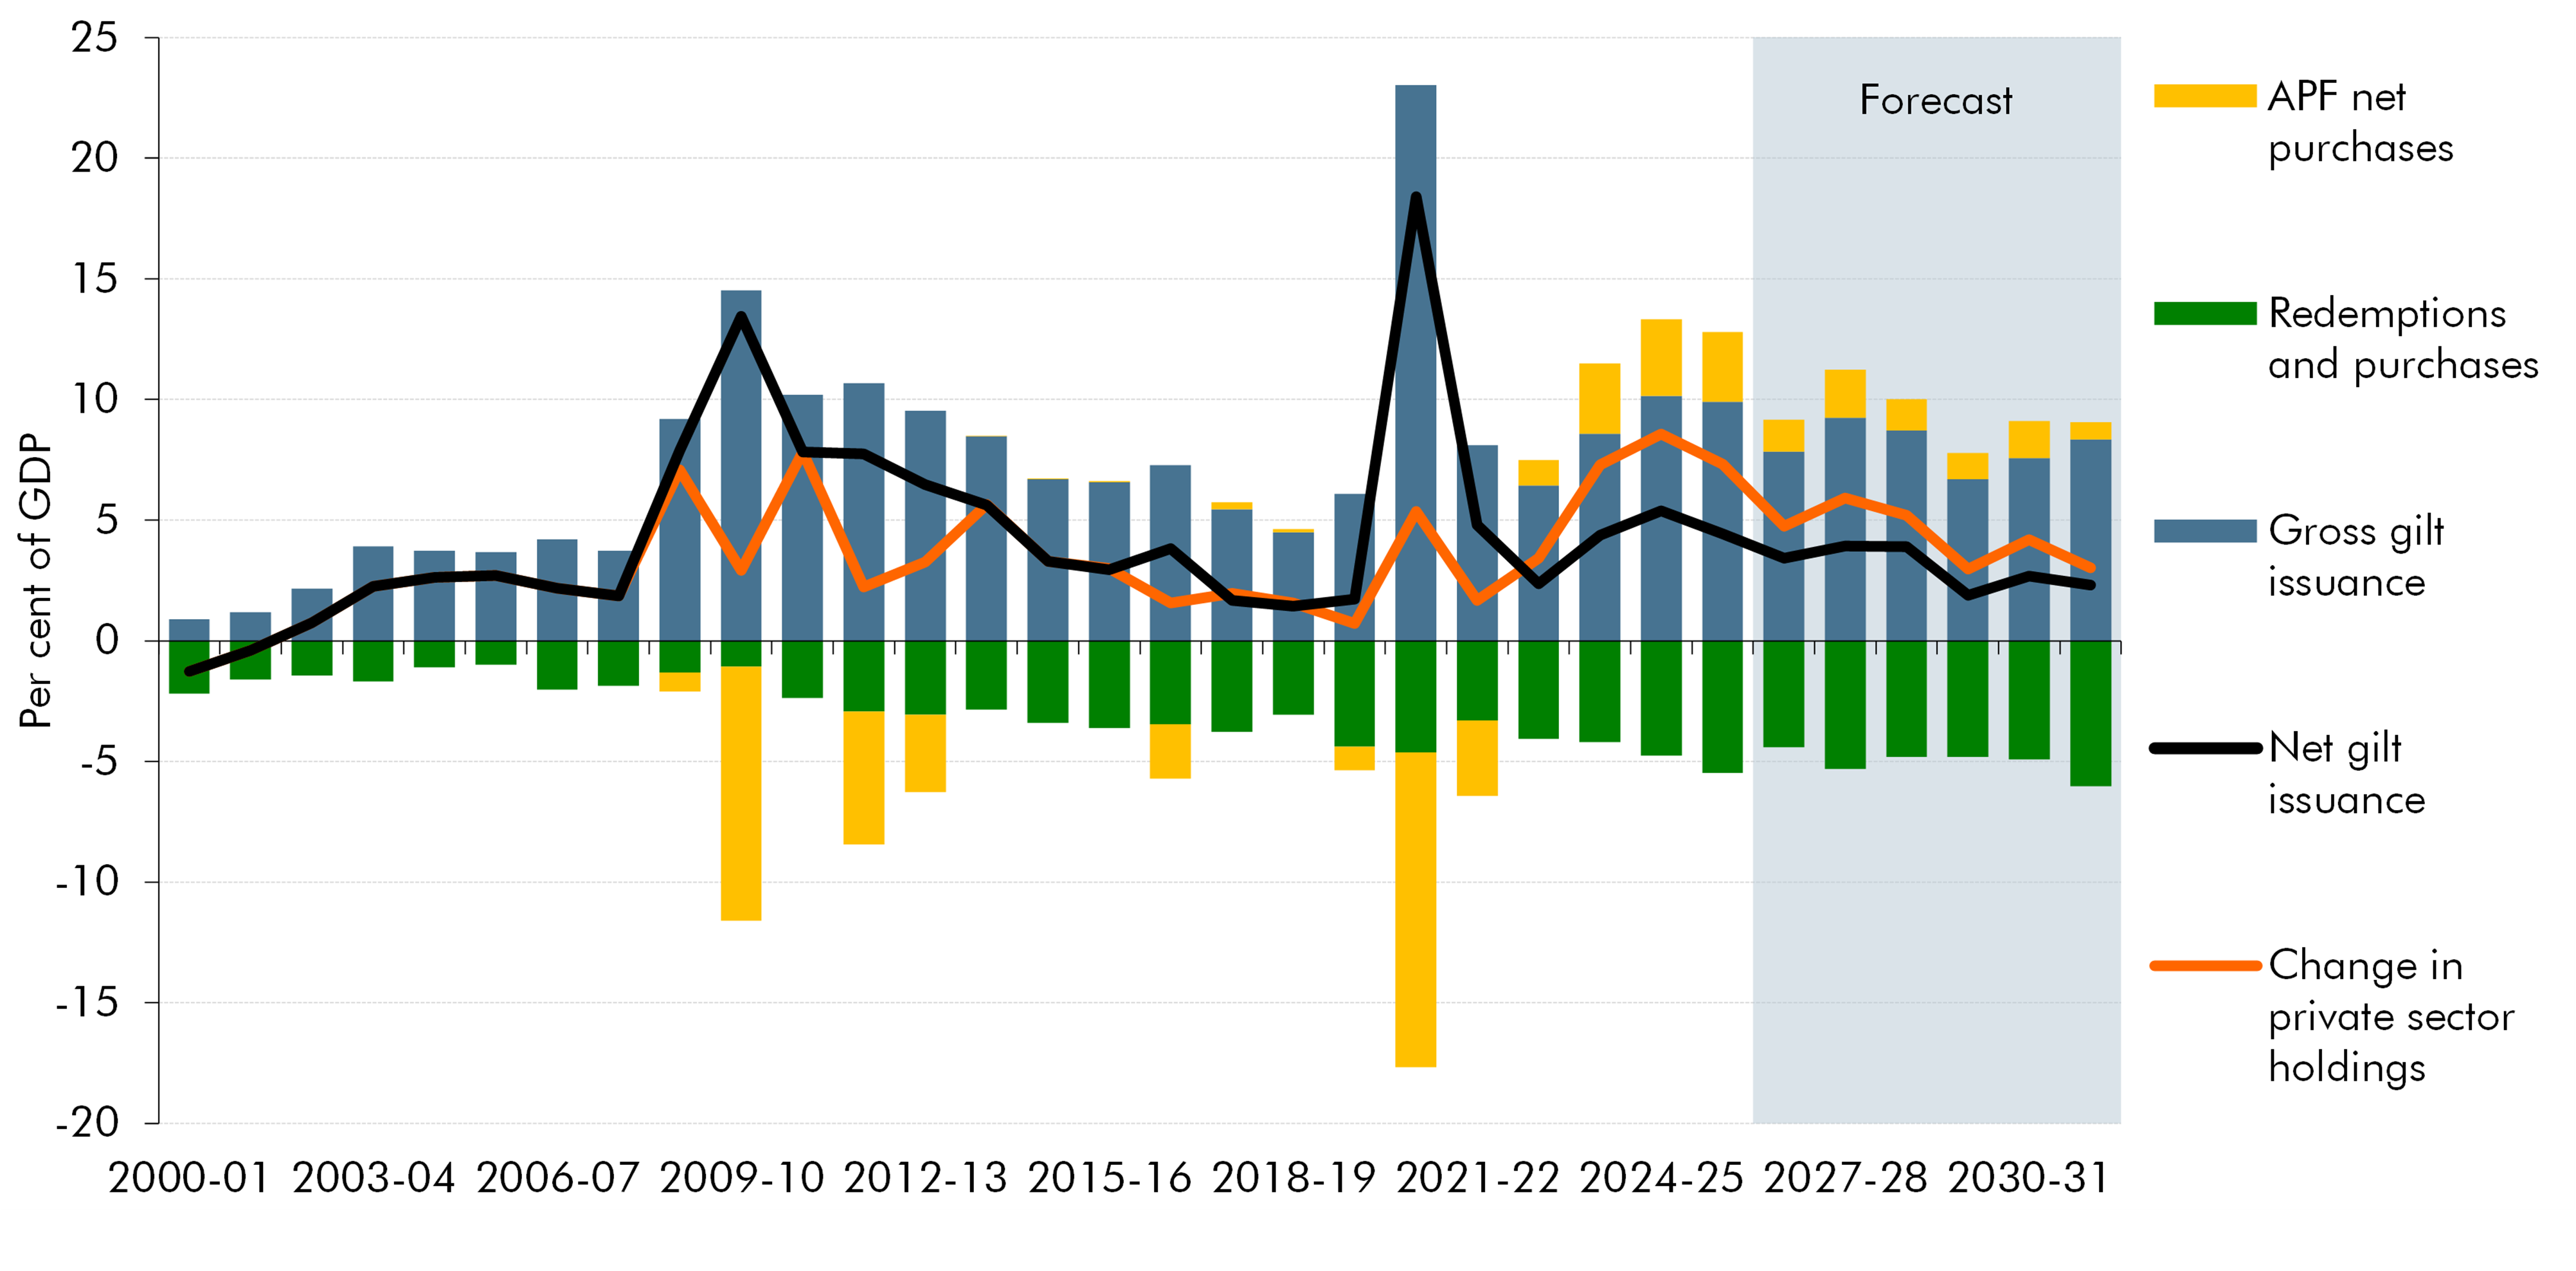
Source: DMO, OBR
Debt and other balance sheet aggregates
Public sector net debt
6.25 Chart 6.7 shows that PSND is forecast to rise from 95.5 per cent of GDP in 2026-27 to 97.3 per cent of GDP in 2028-29, before declining to 95.6 per cent of GDP in the final year of the forecast. The reduction in debt from 2029-30 onwards largely reflects the forecast reduction in PSNB, with a one-off cash flow timing effect from the policy to introduce timely payment for self assessment in 2029-30, and the one-off set of TFS loan repayments to the Bank of England in 2030-31, described in more detail in paragraph 6.13. Compared to our March forecast, net debt is 0.7 percentage points higher this year and on average 0.8 percentage points higher in every year throughout the forecast. This predominantly reflects higher forecast PSNB as explained in paragraph 6.7.
Public sector net debt (excluding the Bank of England)
6.26 Chart 6.7 also shows that public sector net debt excluding the Bank of England (PSND ex BoE) is forecast to rise from 92.4 per cent of GDP in 2026-27 to peak in 2028-29 at 94.7 per cent of GDP, and then to decline to 94 per cent of GDP in the final year of the forecast (right panel of the Chart 6.7). Compared to our March forecast, PSND ex BoE is higher by 0.1 per cent of GDP this year and lower by 0.1 per cent of GDP in 2030-31. Compared to March, PSND ex BoE has not increased as much as PSND, reflecting a downward revision to PSND ex BoE outturn in 2025-26 and the revised APF unwind profile, which raises headline PSND by more than PSND ex BoE. The difference between PSND and PSND ex BoE as a share of GDP narrows from 3.2 percentage points this year to just 1.6 percentage points in 2031-32 due to the winding down of the TFS and APF (see Box 6.2 for more detail).
Chart 6.7: Public sector net debt and public sector net debt ex Bank of England
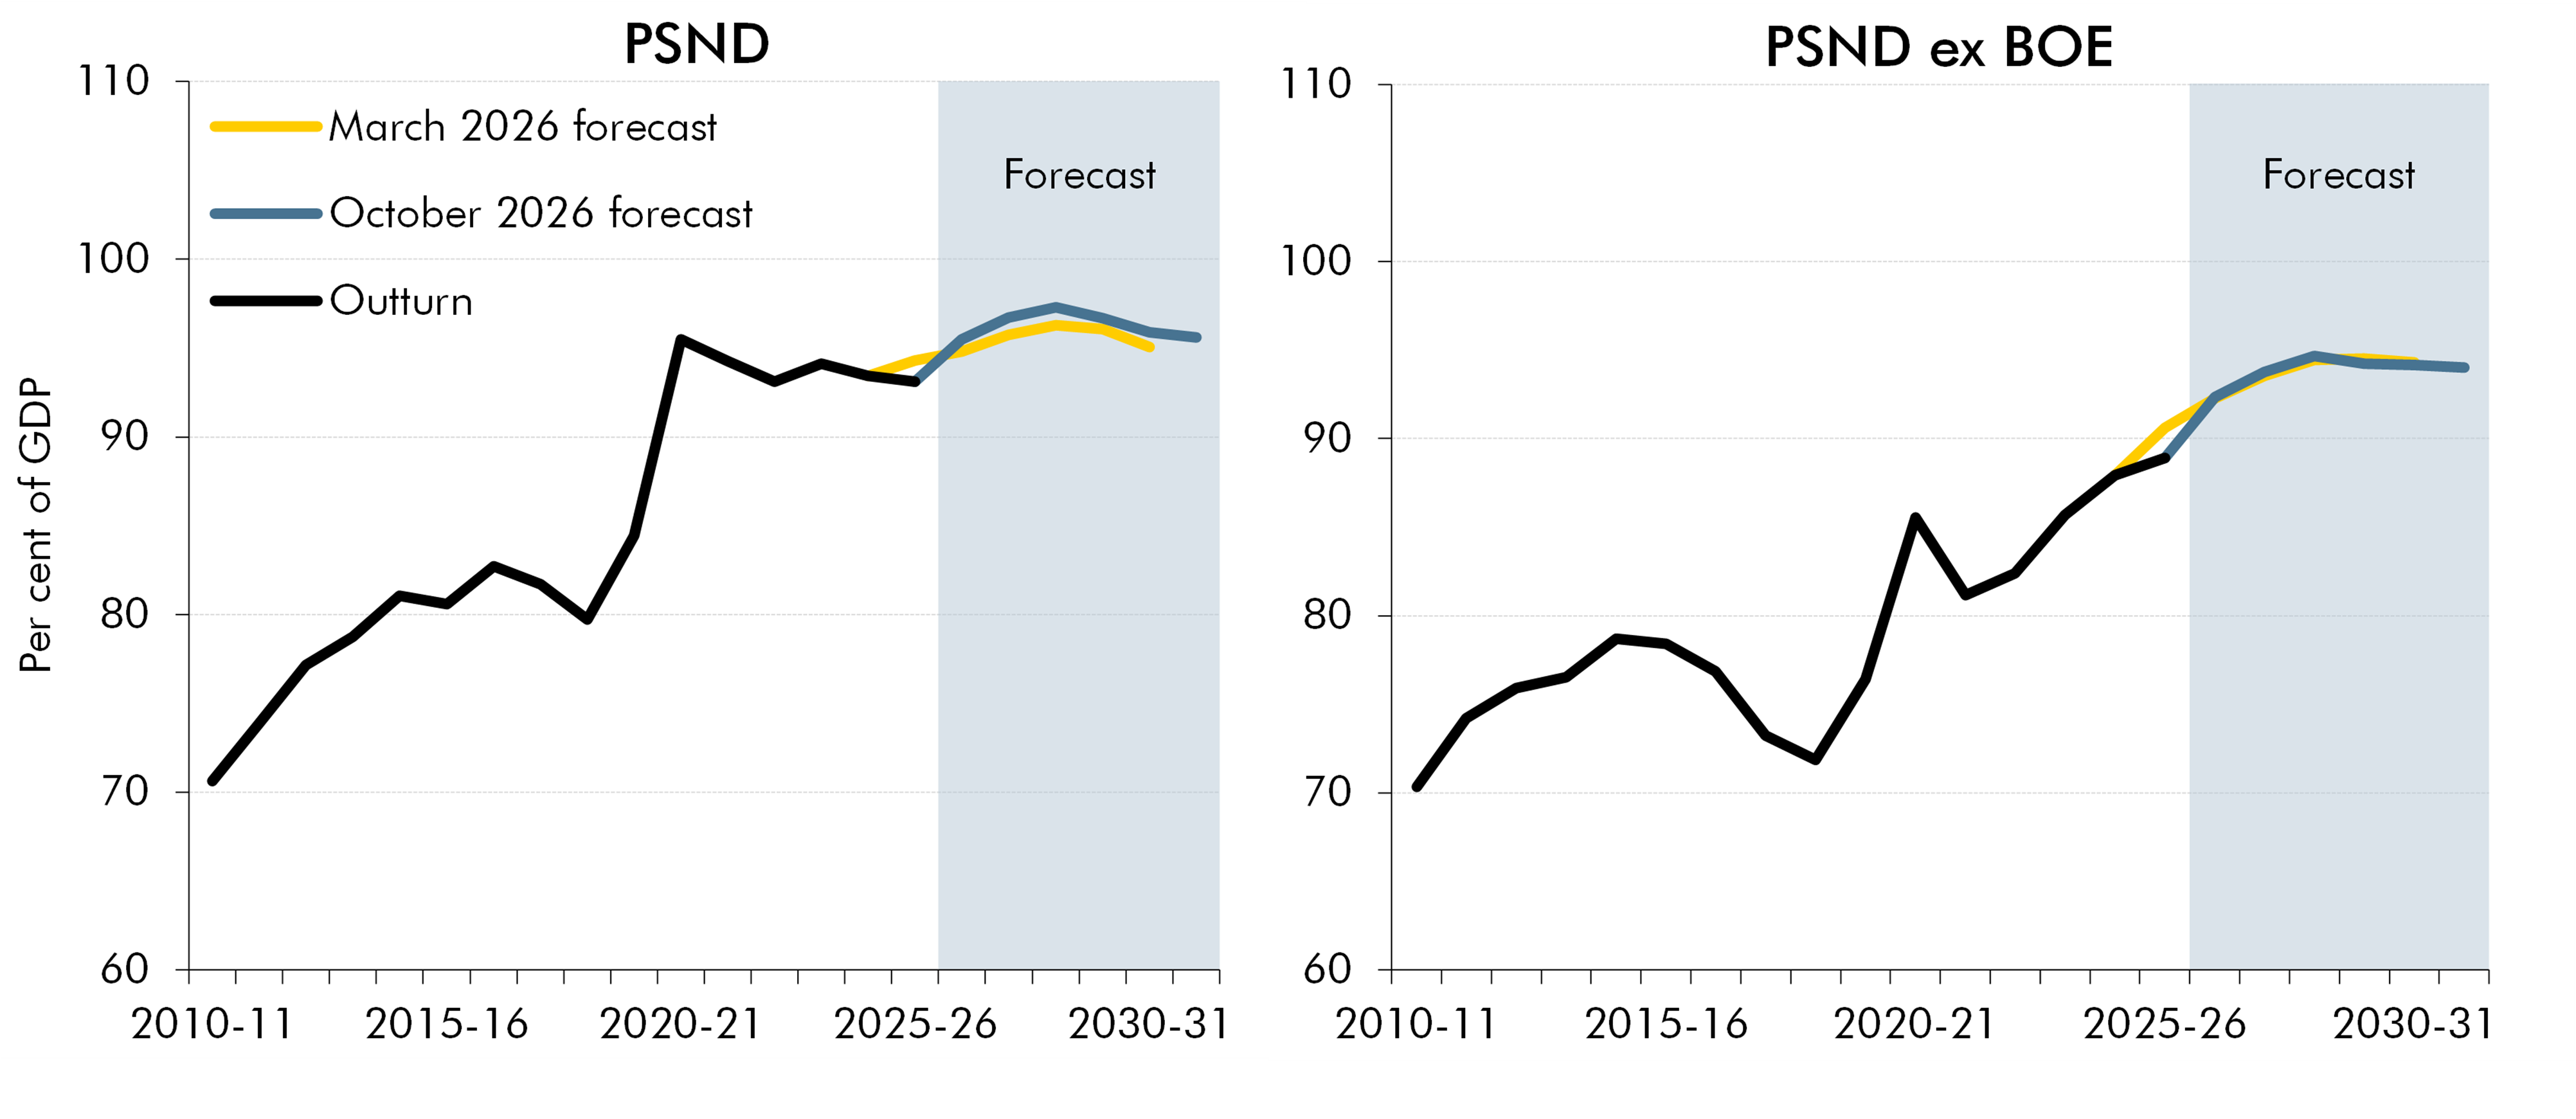
Source: ONS, OBR
Box 6.2: The trajectories of PSND and PSND excluding the Bank of England
Public sector net debt (PSND) is the stock of the public sector’s gross debt liabilities minus its liquid financial assets. In 2016, the ONS also produced a new measure of public sector net debt excluding the Bank of England (PSND ex BoE), which excludes assets and liabilities on the Bank of England’s balance sheet, with a historical series extending back to April 1997. Material differences between the two measures emerged in the 2010s, due to:
-
The Bank’s quantitative easing (QE) programme introduced in 2009. The creation of central bank reserves to purchase assets for QE, held in the Asset Purchase Facility (APF), initially increased PSND as the reserve liabilities came to have a higher value than the assets.a
-
The Term Funding Scheme (TFS), which was introduced by the Bank in 2016 to support bank lending. The loan assets held by the TFS are not counted as liquid assets in PSND, while the reserves created by the Bank for this scheme are liabilities that increase PSND.
These schemes therefore initially increased PSND and not PSND ex BoE. As Chart A shows, this led to a divergence between the two measures which widened as the schemes expanded over the 2010s and early 2020s, with the gap reaching 13.1 per cent of GDP in 2021-22. Subsequently the gap has narrowed as the APF has been unwound and loans on the TFS repaid to reach 4.2 per cent of GDP in 2025-26. We assume this will continue over the forecast period with the gap expected to narrow to 1.6 per cent of GDP in 2031-32. This means that, between 2021-22 and 2025-26, PSND fell marginally as a share of GDP because the unwind of the APF and TFS more than offset the upward pressure on debt from high levels of government borrowing. By contrast, PSND ex BoE rose steadily over this period, though from a lower level, because the APF and TFS effects are excluded. PSND ex BoE therefore provides a better picture of the underlying trajectory of the fiscal position driven by government borrowing over this period.
Chart A: Decomposition of the differences between PSND and PSND ex BoE
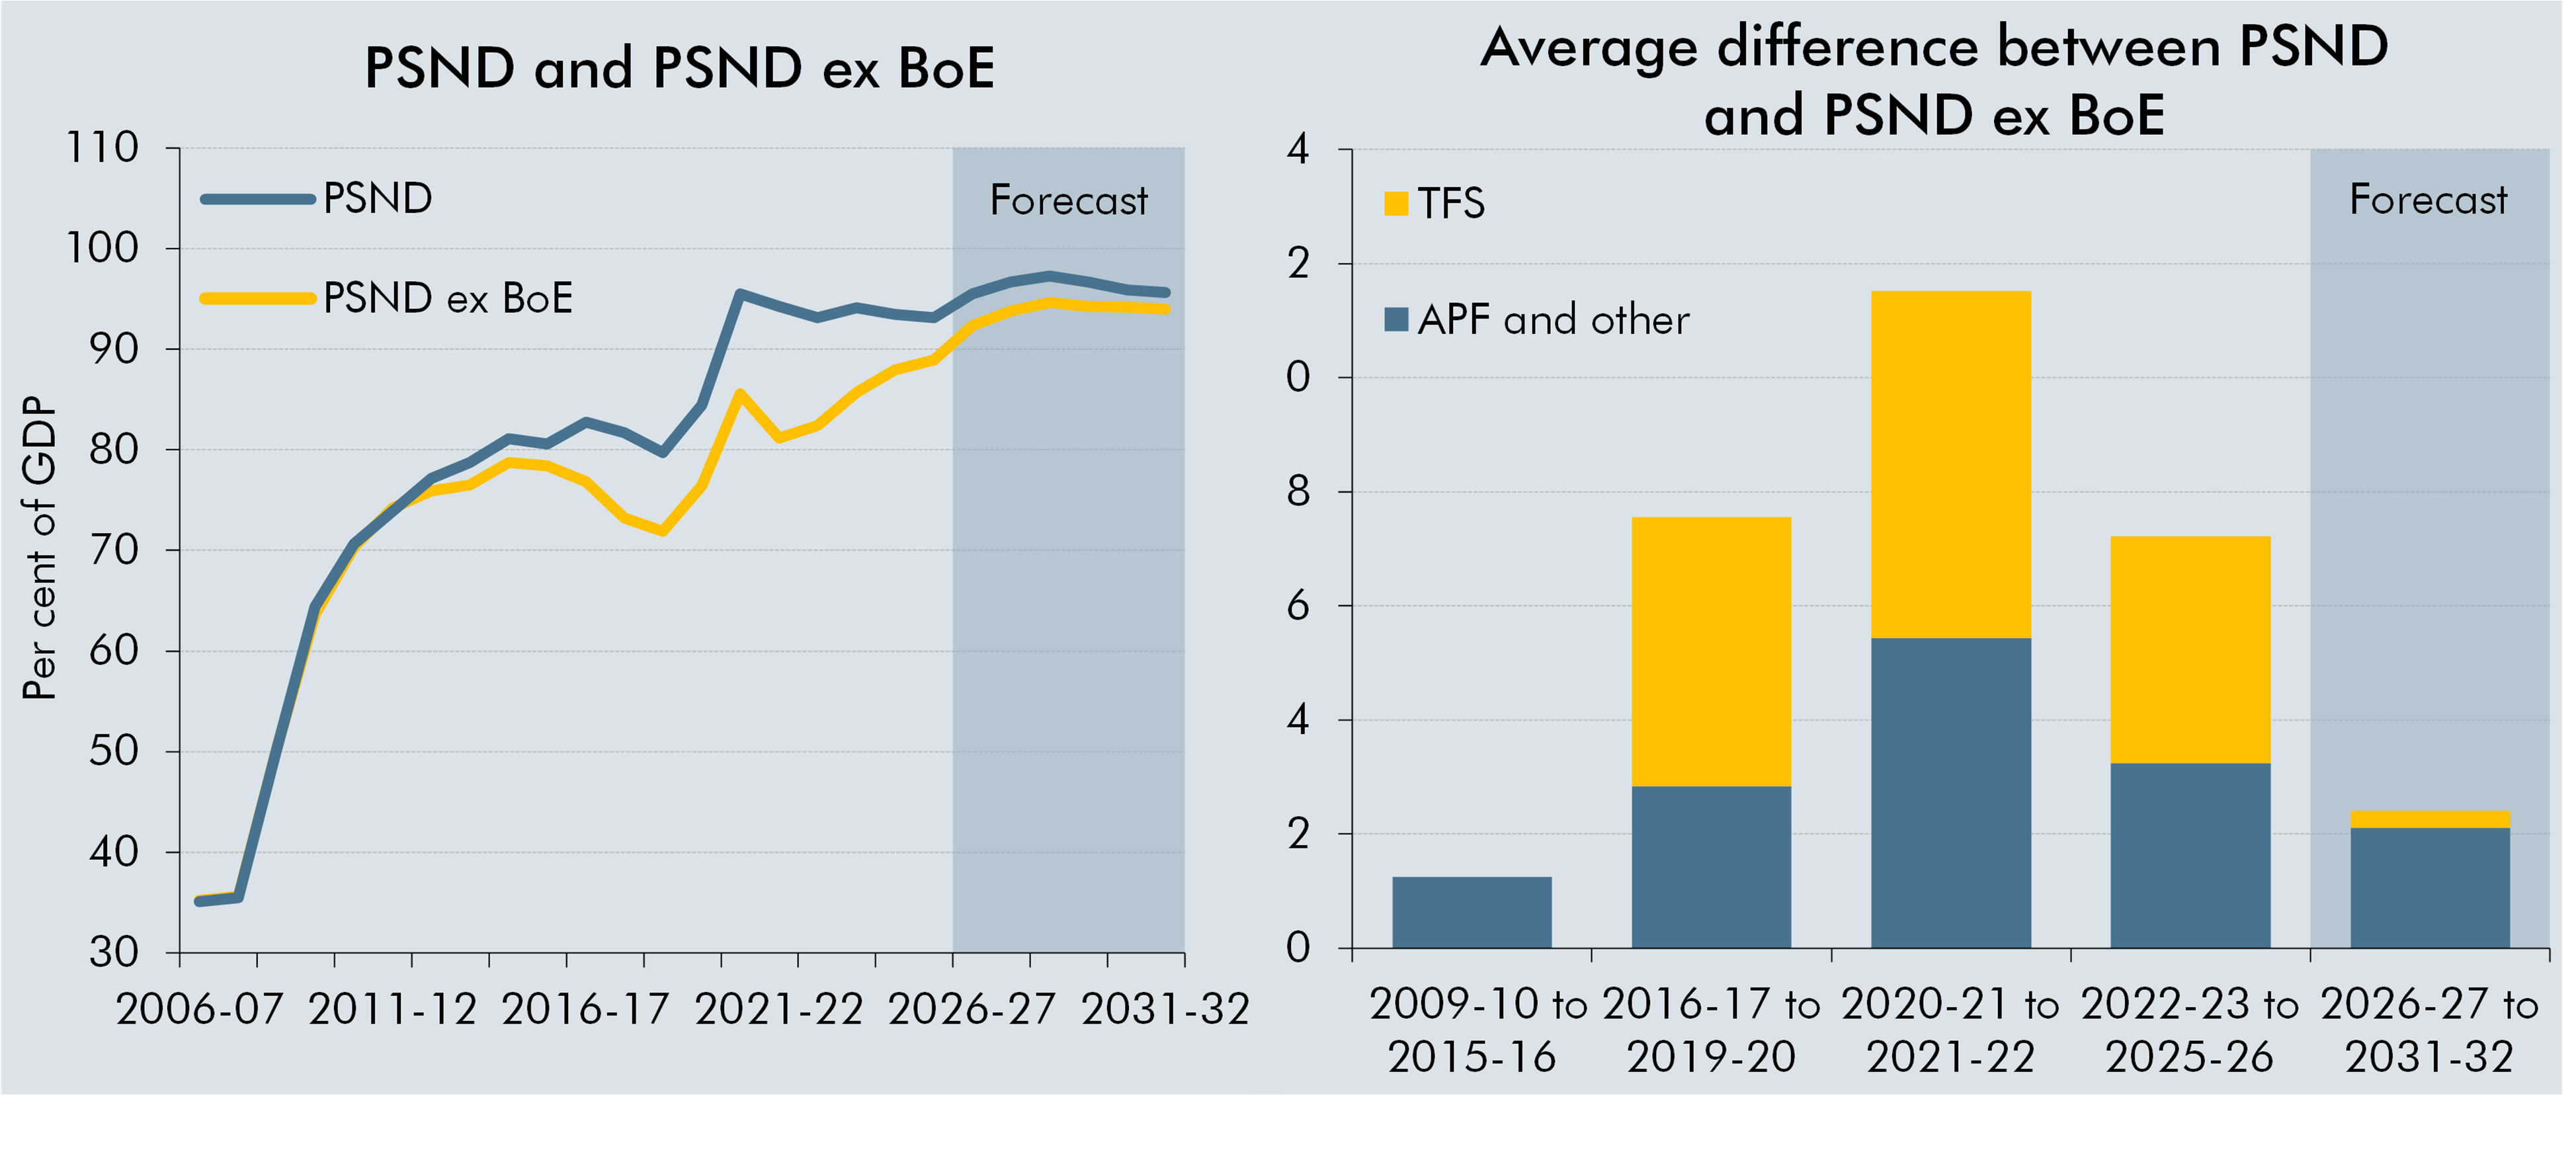
Note: APF and other on the RHS chart predominantly reflects the effects of the APF, with a small proportion reflecting other elements of the Bank of England’s balance sheet.
Source: ONS, OBR
a) The reserves created to finance APF gilt purchases are recorded in PSND as liabilities at their nominal value, while the gilt assets are recorded at their redemption value rather than the market price paid at purchase. As the gilts were purchased at prices above redemption value their valuation in PSND is lower than the valuation of the reserves, which leads to an increase in PSND.
Public sector net financial liabilities
6.27 Public sector net financial liabilities (PSNFL) is the balance sheet measure that is targeted in the Government’s fiscal rules. It includes non-debt liabilities such as funded pensions, and additional illiquid financial assets such as loans (most notably student loans) and equity (including the assets of funded pension schemes). In nominal terms, from a stock of £2.6 trillion in 2025-26, PSNFL is forecast to increase by £133 billion in 2026-27, £83 billion in 2029-30 and by smaller amounts in the following two years. Table 6.7 shows the year-on-year changes in PSNFL are mainly driven by PSNB, as well as:
-
Valuation changes in funded pension schemes, which reduce PSNFL in 2026-27 by £8 billion, but increase it thereafter. This reflects a judgement that equity assets held within the schemes will increase in value faster than the pension liabilities in 2026-27, but that this effect reverses over the remainder of the forecast.
-
Asset Purchase Facility sales losses, incurred when gilts are sold for less than their redemption value. These add to PSNFL by amounts rising year on year until 2029-30 and around £5 billion by 2031-32.
-
The discount on new issuance of central government gilts (gilt premia) pushes up PSNFL by £8 billion in 2026-27 and £2.6 billion in 2027-28. This effect subsides, with smaller increases of £0.9 billion a year on average thereafter, as gilt prices rise and new debt is assumed to issued nearer to face value.
-
Increases in the value of general government equity assets. These capture growth in public sector equity assets not held in funded pension schemes and include the equity holdings of PuFins. They reduce PSNFL by an average of £4.2 billion a year.
-
Reserves and other valuation changes, which increase PSNFL by £2.5 billion in 2026-27 largely due to a reduction in the value of the UK’s foreign reserve assets. They have little effect thereafter as we assume a constant exchange rate.
Table 6.7: Public sector net financial liabilities: year-on-year changes
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Year-on-year change in PSNFL | 154.5 | 132.6 | 122.7 | 107.1 | 83.5 | 78.0 | 80.7 |
| of which: | |||||||
| PSNB | 133.2 | 112.0 | 99.5 | 73.8 | 66.9 | 68.3 | |
| Valuation changes | -0.6 | 10.7 | 7.5 | 9.7 | 11.1 | 12.3 | |
| of which: | |||||||
| Funded pensions | -8.0 | 8.0 | 7.3 | 9.2 | 9.5 | 10.5 | |
| Asset Purchase Facility sales losses | 1.5 | 3.7 | 3.8 | 4.6 | 4.5 | 4.6 | |
| Central government gilt premia | 8.0 | 2.6 | 0.9 | 0.7 | 0.8 | 1.0 | |
| General government equity | -4.7 | -3.6 | -4.5 | -4.8 | -3.8 | -3.7 | |
| Reserves and other | 2.5 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Source: ONS, OBR |
6.28 As shown in Chart 6.8, PSNFL as a share of GDP is forecast to rise to 83.2 per cent in 2026-27 and peak at 83.8 per cent in 2027-28, before falling to 83.1 per cent in 2029-30 and then to 81.7 per cent by 2031-32. Relative to March, as shown in Table 6.8, PSNFL is higher in each year of the forecast, by 0.5 per cent of GDP in 2026-27, rising to 1.1 per cent by 2030-31. This is driven by a higher level of PSNFL in each year, partly offset by stronger nominal GDP growth over the forecast. These cash revisions reflect:
-
Revisions to PSNFL outturn for 2025-26, which lower liabilities in each year of our forecast by £2.0 billion.
-
Upwards revisions to pre-measures PSNB in each year, which add a total of £56 billion to PSNFL by 2030-31.
-
The effect of policy measures on PSNB, which increase PSNFL in each year until 2030-31, but reduce it by £0.1 billion by 2031-32.
-
Valuation changes, which increase PSNFL by a total of £13 billion. This reflects valuation changes in funded pension schemes, which are only partly offset by faster growth in the value of general government equity assets.
Chart 6.8: Public sector net financial liabilities
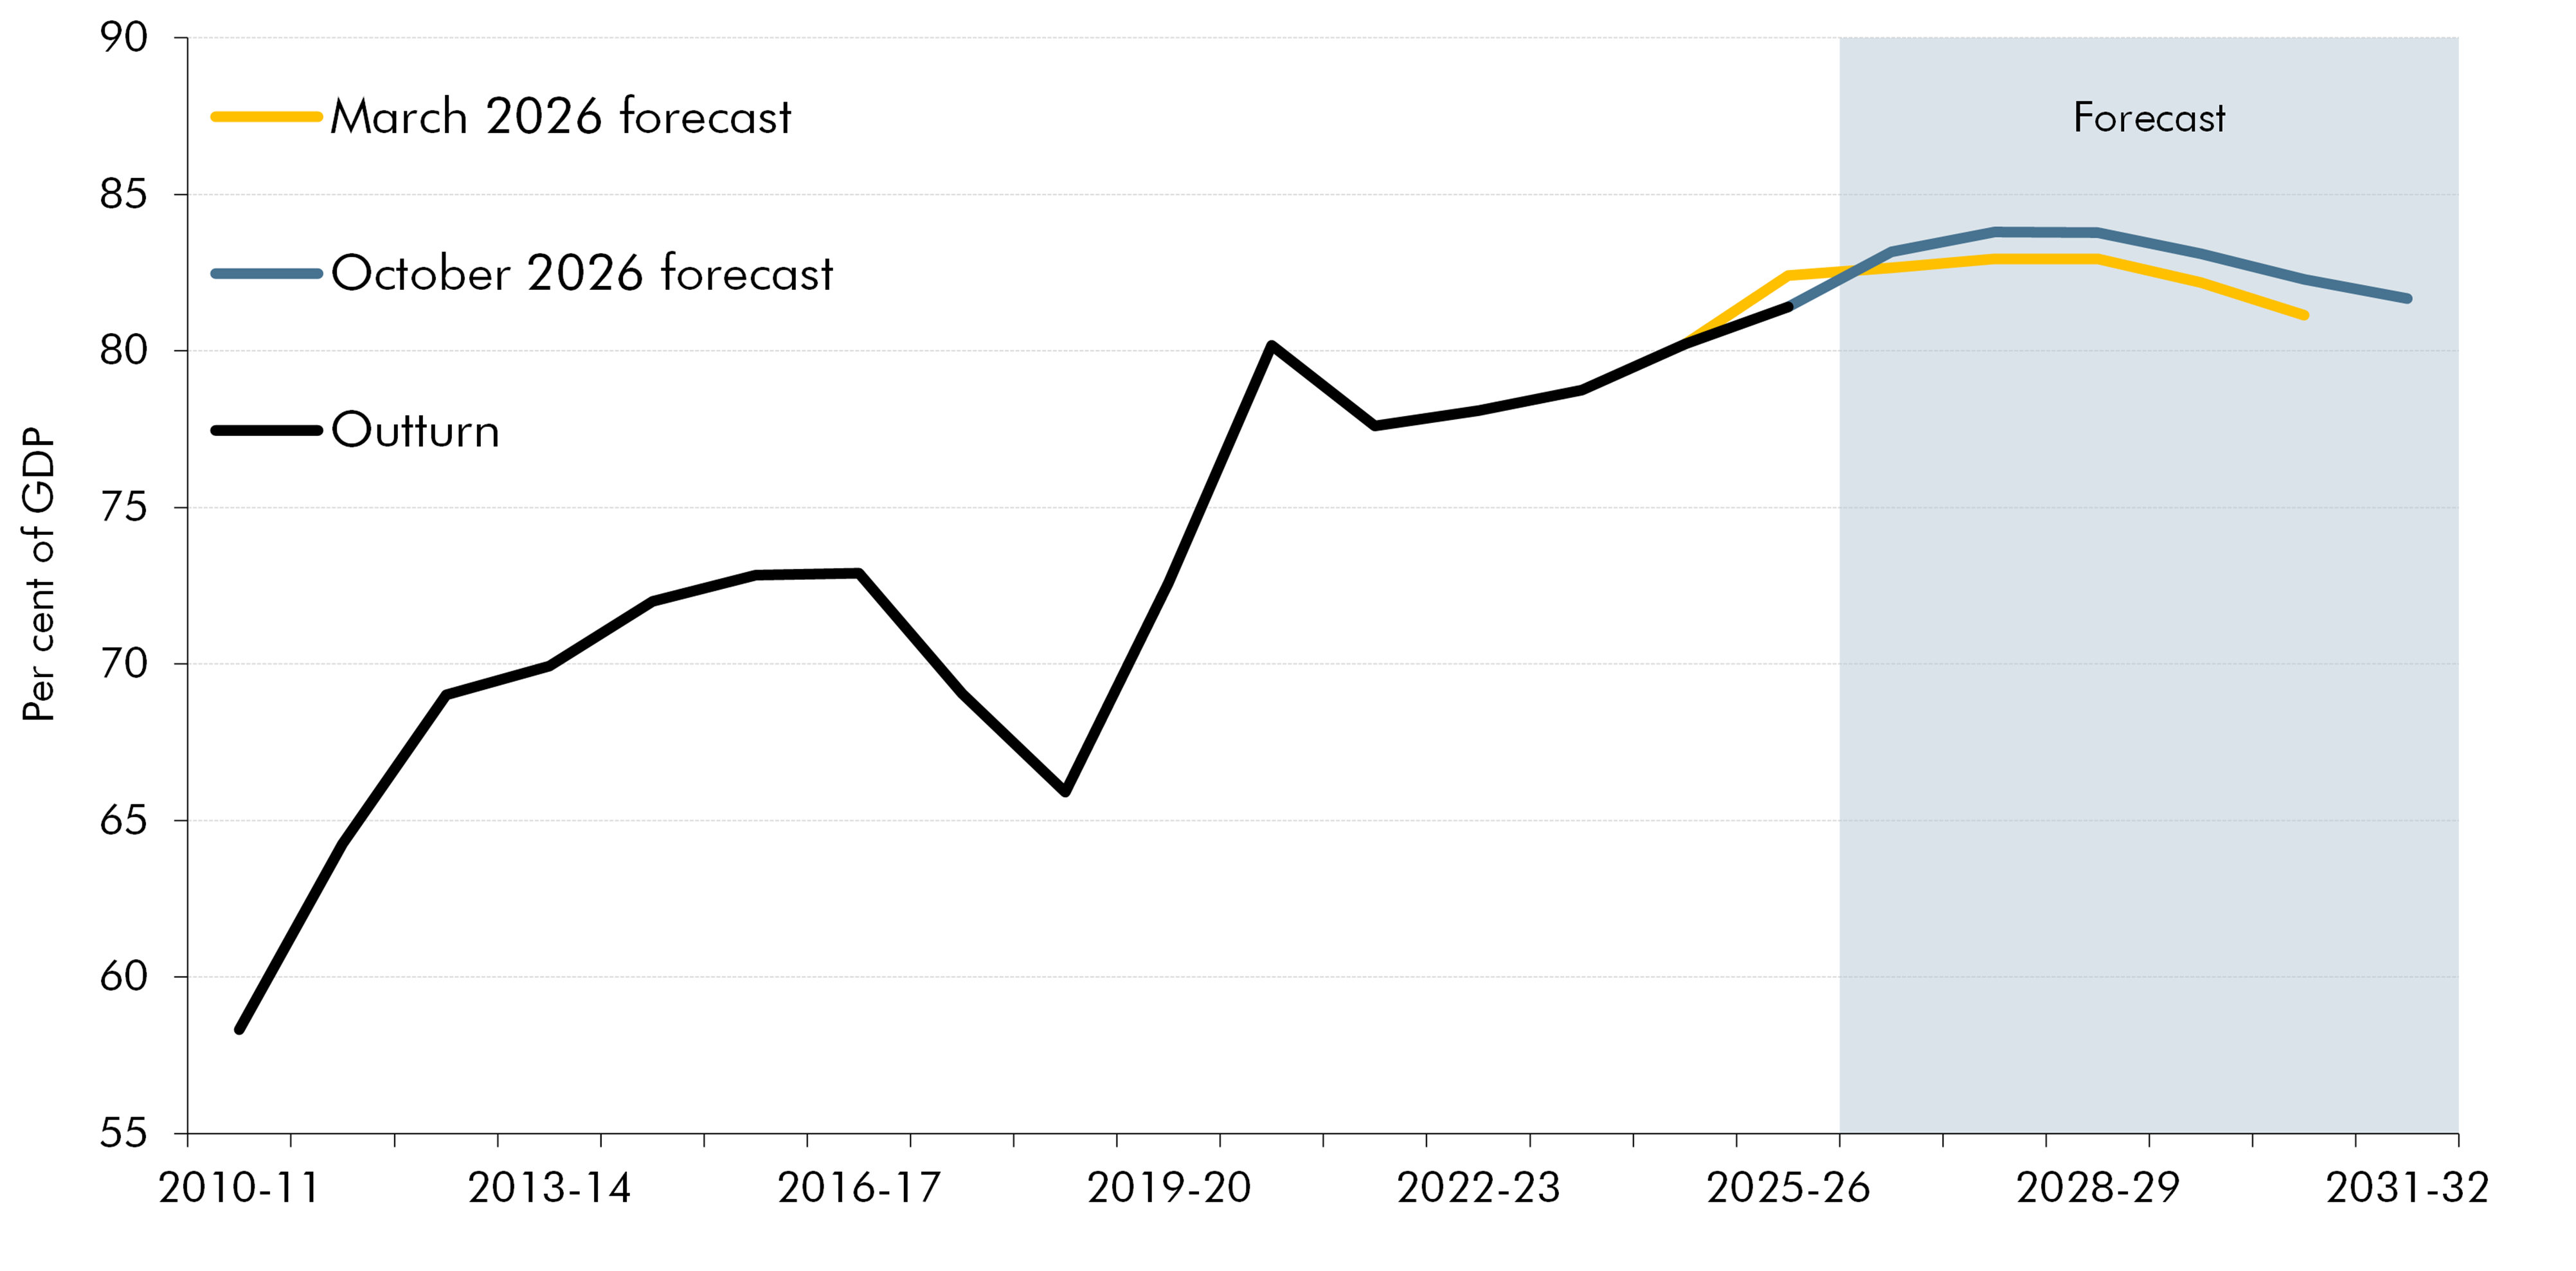
Source: ONS, OBR
Table 6.8: Public sector net financial liabilities: changes since March
| Per cent of GDP | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| March 2026 forecast | 82.4 | 82.6 | 82.9 | 82.9 | 82.2 | 81.1 | |
| October 2026 forecast | 81.4 | 83.2 | 83.8 | 83.8 | 83.1 | 82.3 | 81.7 |
| Difference | -1.0 | 0.5 | 0.8 | 0.8 | 0.9 | 1.1 | |
| of which: | |||||||
| Nominal GDP(1) | -0.2 | -0.4 | -0.7 | -0.9 | -0.9 | ||
| Cash level of financial liabilities | 0.7 | 1.2 | 1.6 | 1.8 | 2.0 | ||
| £ billion | |||||||
| March 2026 forecast | 2,554 | 2,661 | 2,765 | 2,859 | 2,932 | 2,999 | |
| October 2026 forecast | 2,552 | 2,684 | 2,807 | 2,914 | 2,997 | 3,075 | 3,156 |
| Difference | -2.0 | 22.9 | 41.8 | 54.7 | 65.8 | 76.1 | |
| of which: | |||||||
| Revisions to outturn | -2.0 | -2.0 | -2.0 | -2.0 | -2.0 | ||
| Pre-measures PSNB forecast revisions | 11.4 | 19.9 | 31.4 | 44.4 | 55.8 | ||
| Effect of Government decisions on PSNB | 6.3 | 13.3 | 15.4 | 12.8 | 9.2 | -0.1 | |
| Valuation changes | 7.2 | 10.5 | 9.9 | 10.6 | 13.1 |
| 1) Non-seasonally-adjusted GDP centred end-March. |
| Source: ONS, OBR |
Public sector net worth
6.29 Public sector net worth (PSNW) is the broadest measure of the Government’s balance sheet, capturing changes in the value of non-financial assets (NFAs) and the liabilities associated with unfunded pension schemes, in addition to what is included in PSNFL. Inverted PSNW falls by 3.5 per cent of GDP from 63.3 per cent in 2026-27 to 59.8 per cent in 2031-32, driven by a 1.9 per cent of GDP rise in the value of NFAs. Compared to our March forecast, inverted PSNW is 0.3 per cent of GDP lower in 2026-27, largely due to lower-than-forecast outturn for 2025-26. This difference gradually reverses, leaving it 1.4 per cent of GDP higher by 2030-31, reflecting the upwards revisions to our forecast for PSNFL, in combination with faster forecast growth in unfunded pensions liabilities.
6.30 Chart 6.9 shows that all four measures of the balance sheet, as a share of GDP, are currently at high levels relative to the past 50 years. They are all forecast to remain broadly stable at these elevated levels over the forecast period. PSND and PSND ex BoE increase until 2028-29, before declining slightly in each subsequent year. PSNFL and PSNW both rise until 2027-28 and fall slightly in the final four years. PSND, PSND ex BoE and PSNFL are forecast to be higher than their 2025-26 levels at the forecast horizon, while PSNW is forecast to be lower.
Chart 6.9: Four measures of the public sector balance sheet
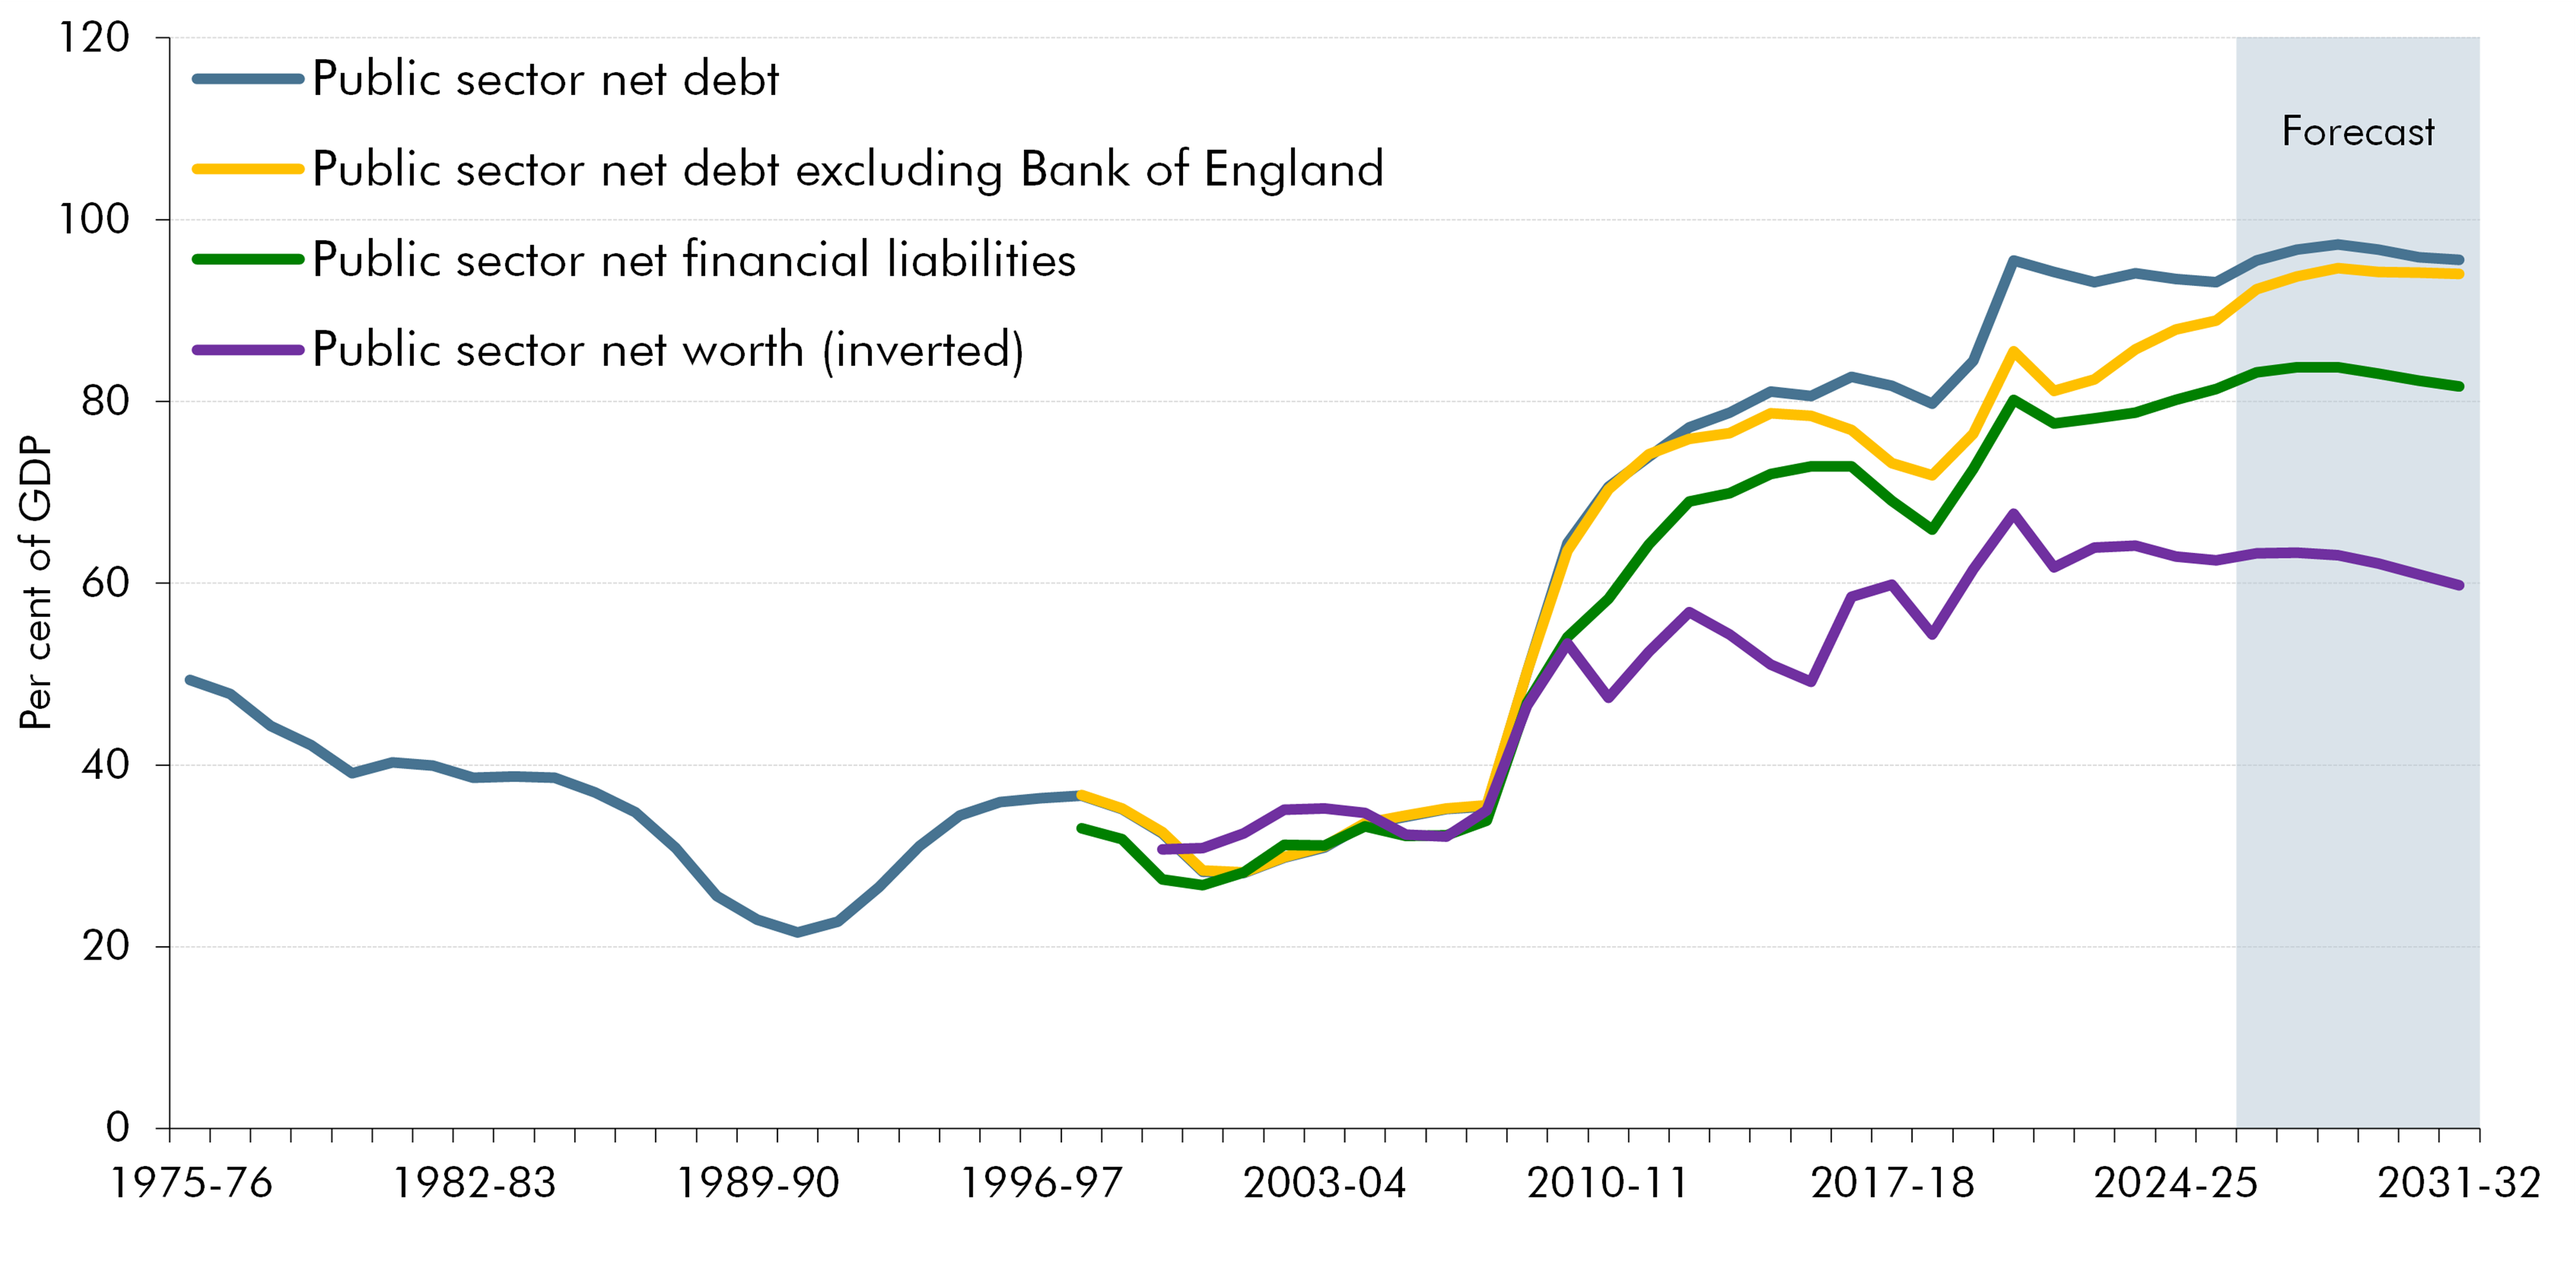
Note: Each of the lines shown begins at the point the ONS first records outturn for that measure, except for PSND which starts at 1974-75.
Source: ONS, OBR
6.31 Box 6.3 discusses the impact of the possible reclassification of water companies for the public sector balance sheets measures and for borrowing and the current budget deficit.
Box 6.3: Potential impact of water companies on the public finances
Water companies in England and Wales have been classified within the private sector since 1989. The Office for National Statistics (ONS), however, is currently reviewing this classification in response to the Water (Special Measures) Act 2025, which increased the degree of government control over the operation of water companies.a,b The Government has also recently announced its intention to further increase public control of the industry, including by removing caps on government share ownership in water firms.c If the ONS were to reclassify, then the relevant assets, liabilities, revenue and expenditure of providers would be incorporated to the public sector.
The 2025 Fiscal risks and sustainability report assessed the potential impact of reclassifying the full water sector on the public sector balance sheet in 2023-24, showing that this could:
-
Increase gross liabilities, which increase PSNFL, by £91 billion (3.3 per cent of GDP), including £66 billion of debt. Borrowing by water companies has increased in recent years with around half (52 per cent) of debt inflation-linked.
-
Increase financial assets, which all reduce PSNFL, by £12 billion (0.4 per cent of GDP). This includes £5 billion in cash held by water companies, the only financial assets which would reduce PSND.
-
Overall, increase PSNFL by £78 billion (2.8 per cent of GDP). PSNW, as the widest measure of the balance sheet, would additionally include the £94 billion of water companies’ physical assets, including water pipelines, treatment facilities, and reservoirs which account for 88 per cent of their total assets.
This increase in PSNFL would be incorporated as a one-off increase to its level at the point of reclassification. Following the initial increase in the level of PSNFL, only the level of borrowing by water companies would directly affect the trajectory of PSNFL, and so affect the Government’s supplementary fiscal target which is for PSNFL to be declining as a share of GDP in the third year of the forecast.
Table B illustrates the potential impact of reclassification on the level of borrowing and the current budget deficit if the revenue and expenditure of providers were to be moved into the public sector, by using data from the outturn years between 2020-21 and 2024-25.d,e Within these years, we estimate that reclassification could:
-
Increase public sector receipts by £13 billion (0.5 per cent of GDP) a year on average. Within this, revenue from consumer bills averaged £12 billion and interest receipts averaged £0.4 billion a year.
-
Increase current spending by £11 billion (0.4 per cent of GDP) a year. Within this, operating costs, mainly comprising of wages and contracted services, averaged £7 billion, and dividend and debt interest payments averaged £3.8 billion.
-
Increase capital spending by £6 billion (0.2 per cent of GDP) a year. Most investment by water companies is on capital additions of property, plant and equipment.
-
Increase the current budget deficit, in most years, by £1.0 billion a year (less than 0.1 per cent of GDP). This is because, in outturn, current spending and depreciation is largely offset by receipts, and most borrowing by water companies is to fund investment.
-
Increase net borrowing by £4.4 billion (0.2 per cent of GDP) a year. The increase in borrowing rises from £0.2 billion in 2020-21 to £7 billion by 2024-25. This is because both capital and current spending have increased by more than receipts over this period.
Table B: Estimated impact of reclassification on net borrowing and the current budget deficit
| £ billion | |||||
|---|---|---|---|---|---|
| 2020-21 | 2021-22 | 2022-23 | 2023-24 | 2024-25 | |
| Receipts (a) | 11.7 | 11.9 | 12.6 | 14.1 | 15.0 |
| Current spending (b) | 7.8 | 9.9 | 12.4 | 12.5 | 13.4 |
| of which: | |||||
| Operating costs | 5.8 | 6.2 | 7.1 | 8.1 | 9.6 |
| Interest payments | 2.0 | 3.7 | 5.3 | 4.4 | 3.8 |
| Depreciation (c) | 2.6 | 2.7 | 2.9 | 3.0 | 3.2 |
| Capital spending (d) | 4.0 | 5.1 | 5.4 | 7.6 | 8.9 |
| Impact on current budget deficit (b+c-a) | -1.2 | 0.7 | 2.7 | 1.4 | 1.6 |
| Impact on net borrowing (b+d-a) | 0.2 | 3.1 | 5.2 | 6.0 | 7.4 |
| Source: Water companies, OBR |
The impact of reclassification on borrowing and the current budget deficit over the forecast period would depend on the business plans of water companies at the time of reclassification, and on any future policy or regulatory changes. Recent outturn data, discussed above, suggests that it could have a small impact on the current budget deficit forecast as receipts largely offset current spending and depreciation in the sector. However, the forecast for borrowing will also reflect capital spending, which is set to remain at an elevated level over the next five years as water companies invest to upgrade their capital stocks. The Ofwat Price Review 2024 has approved £104 billion of expenditure (2022-23 prices) by water companies between 2025-26 and 2029-30.f This would point to higher current and capital spending compared to Table B, averaging around £25 billion a year of total spending in nominal terms over this time period.
a) The Water (Special Measures) Act 2025 implements powers for Ofwat to set rules over performance-related pay, lowers the criminal standard of proof, enables issuance of automatic penalties, and places conditions on companies’ licences, supporting cost recovery by the Government if a company enters a Special Administration Regime (SAR).
b) Office for National Statistics, Forward work plan, October 2026.
c) GOV.UK, Pathway to stronger public control of the water industry revealed, September 2026.
d) Reclassification would not impact CGNCR because the financing of water companies would remain unchanged.
e) The ONS would backdate the point of any reclassification to when the ONS judged that the public sector took sufficient control over water companies.
f) Ofwat, PR24 final determinations: sector summary, September 2024.
Chapter 7: Fiscal context, targets and uncertainty
Introduction
7.1 In this chapter, we assess the Government’s performance against its fiscal rules alongside a wider analysis of fiscal sustainability. This includes an examination of the fiscal context, the main risks to the fiscal outlook, and long-term fiscal pressures. As such, in this chapter we:
-
assess the fiscal context for this Budget, by summarising changes in public sector net borrowing and public sector net debt in the post-war period, comparing the UK fiscal position to that of other advanced economies, and assessing the outlook for longer-term fiscal sustainability in the UK;
-
set out the Government’s fiscal targets and estimate their likelihood of being met under current policy conditions in our central forecast, and assess the fiscal position against wider metrics for fiscal sustainability; and
-
examine key risks and uncertainties around the central forecast using analysis based on: an assessment of specific risks to the central forecast; patterns of shocks to, and variations in, key macroeconomic and fiscal determinants; and analysis of the impact on the fiscal forecast of alternative economic scenarios.
The fiscal context
Current and historical fiscal position
7.2 The left panel of Chart 7.1 shows that over the past two decades, public sector net borrowing (PSNB) as a share of GDP has, on average, been markedly higher than over the preceding 60 years. Borrowing has averaged 5.8 per cent of GDP in the period since the global financial crisis (5.3 per cent of GDP excluding the pandemic-hit year of 2020-21), three times the post-war average of 1.9 per cent of GDP in the period up until 2008.
7.3 Following the Covid pandemic, borrowing remained at around 5 per cent of GDP for four years until 2024-25. In the following two years, it has fallen and is now forecast to reach 4.2 per cent of GDP in 2026-27. In the latest central forecast, under the government’s planned fiscal consolidation, borrowing is expected to fall further to 1.8 per cent of GDP by 2031-32, which, if achieved, would be broadly in line with the post-war, pre-2008 average. The right panel of Chart 7.1 shows that in successive forecasts since the pandemic, governments have typically planned to reduce borrowing to the pre-2008 average of below 2 per cent of GDP. However, in practice over the period since then, there has so far only been a slight decline in borrowing in outturn years to 4.4 per cent of GDP in 2025-26. This has been as a result of the fiscal impact of subsequent economic shocks, weaker-than-expected growth, and discretionary policy decisions to delay consolidation.
Chart 7.1: Public sector net borrowing: historical outturn and recent forecasts
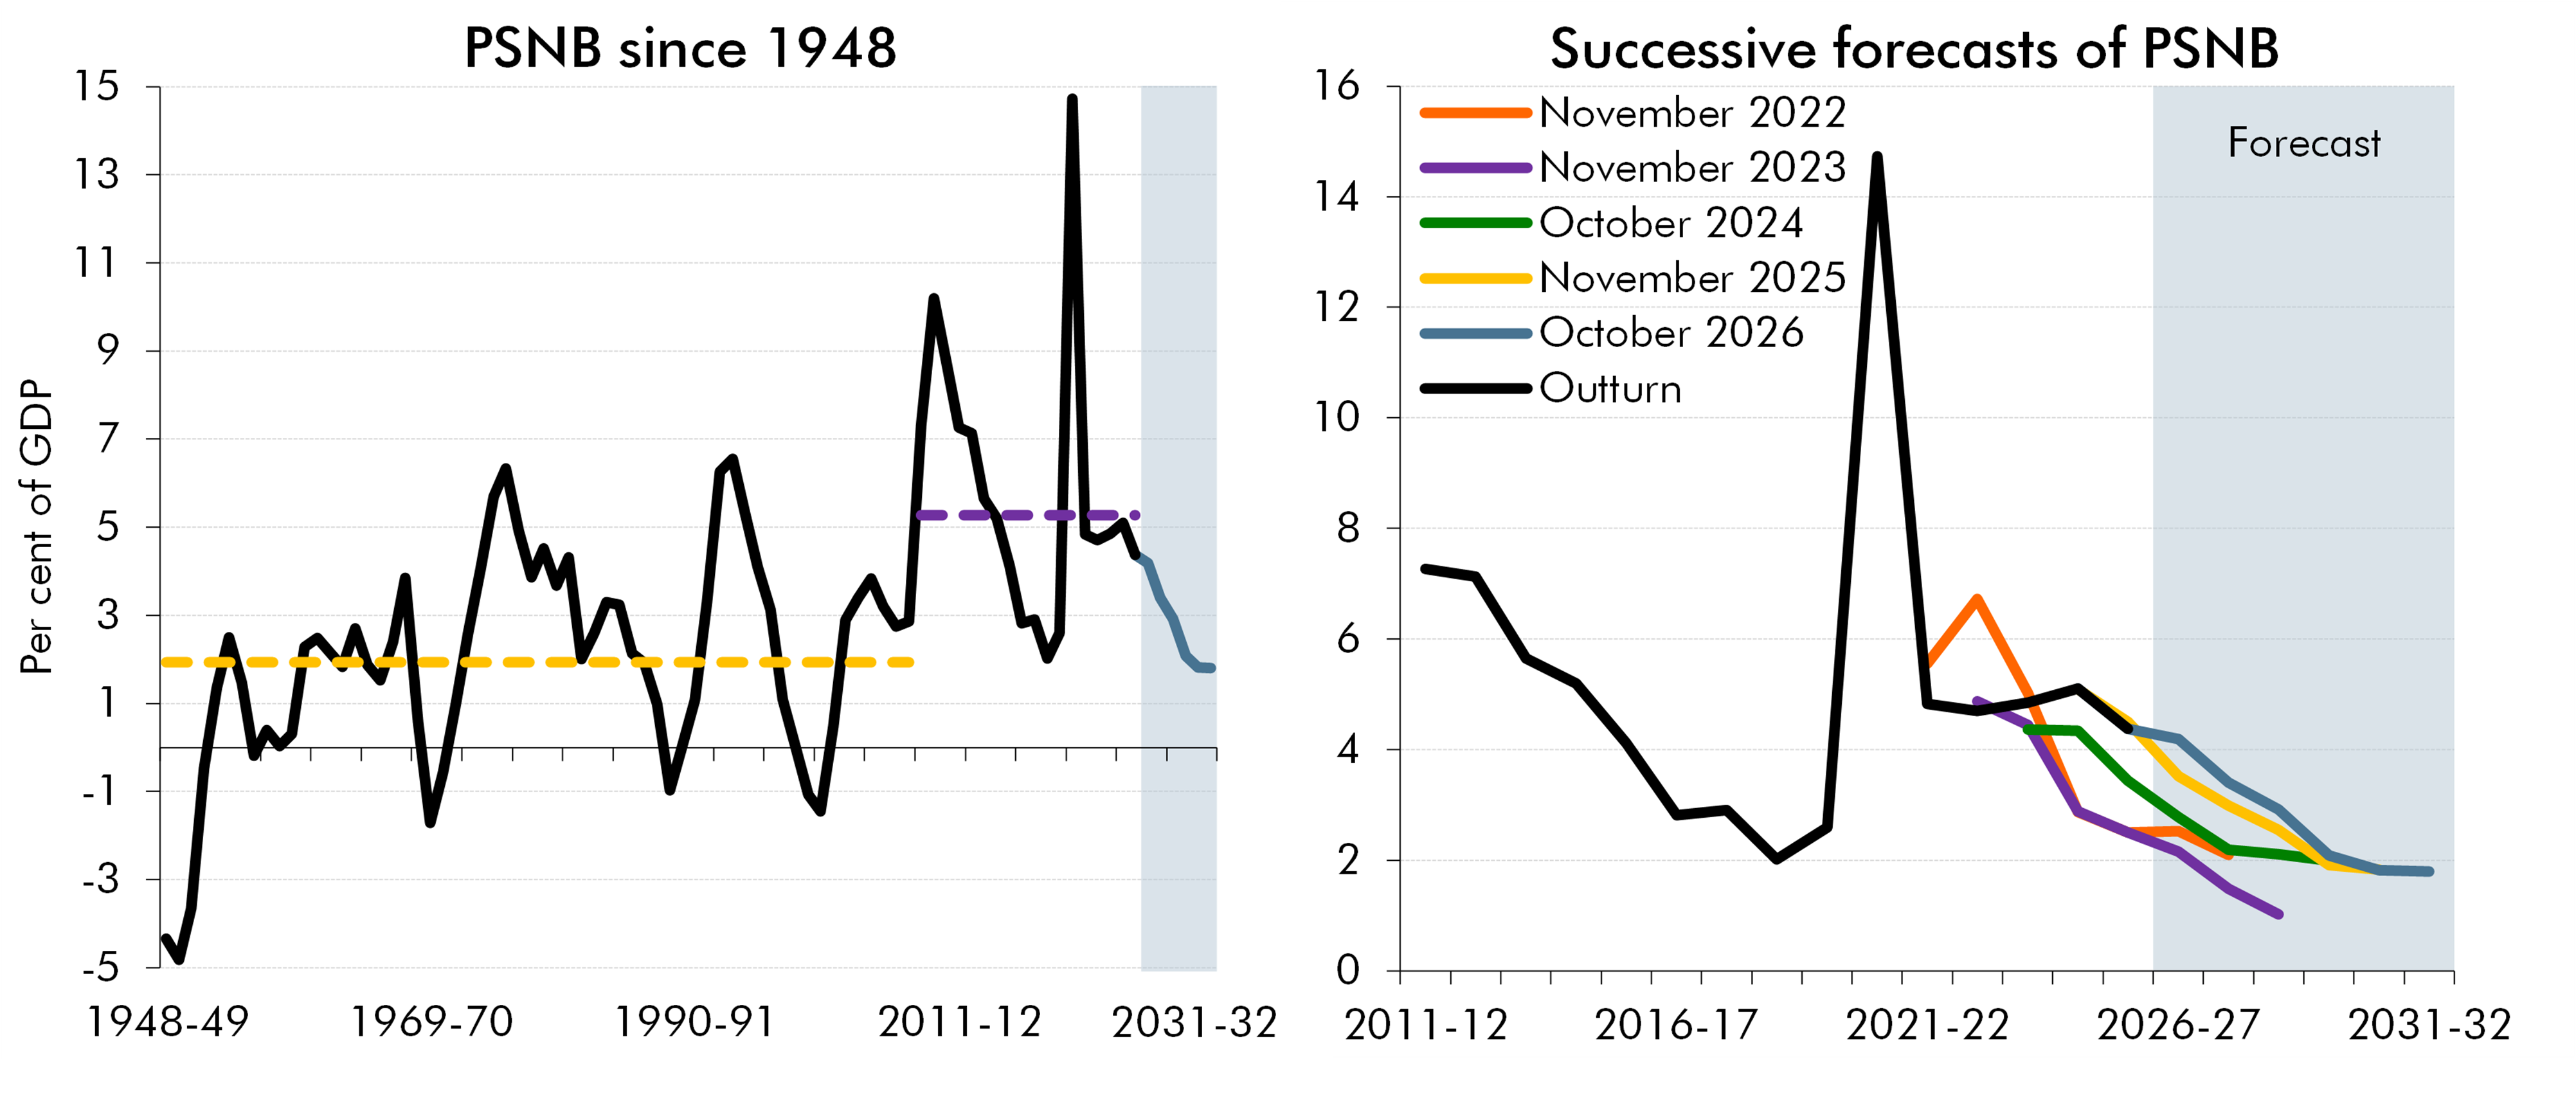
Note: Forecast lines on the right panel are presented as the nominal forecast for PSNB divided by the outturn and forecast for nominal GDP that is consistent with this forecast.
Source: ONS, OBR
7.4 The left panel of Chart 7.2 shows changes in public sector net debt, excluding the Bank of England (PSND ex BoE), also referred to as underlying debt, as a share of GDP since 1948-49. The three decades following the Second World War saw a steady fall from the very high debt level of around 250 per cent of GDP reached immediately after the war. This fall was supported by high real economic growth and a substantial fall in defence spending. From the late 1970s, debt broadly stabilised between 20 and 40 per cent of GDP, and stood at around 36 per cent on the eve of the financial crisis in 2007-08.
7.5 The fiscal impact of the financial crisis led underlying debt to rise sharply to reach a peak of 79 per cent in 2014-15 before then falling slightly in the late 2010s. It then once again rose markedly due to the impact of the pandemic to reach 86 per cent in 2020-21. Following the pandemic, after an initial decline, underlying debt has continued to rise in all years, due to the relatively elevated level of borrowing in this period described above, to reach 92 per cent of GDP in 2026-27. This would be 57 percentage points of GDP higher than the pre-financial-crisis level.
7.6 The right panel of Chart 7.2 compares the forecast changes in underlying debt over the post-pandemic period relative to actual outturn. Successive previous forecasts have expected debt to fall or stabilise over the medium term. In practice, this has yet to occur for the same reasons that the recent forecasts for falling borrowing, described above, have not yet been delivered. In the latest forecast, PSND ex BoE is projected to peak in 2028-29 at 95 per cent of GDP and then subsequently fall slightly. If this were to be achieved, it would still leave the level of debt 7 percentage points of GDP higher in 2031-32 than the November 2022 forecast peak; 5 percentage points higher than the 2025-26 figure of 89 per cent of GDP; and at elevated levels compared to the past 50 years.
Chart 7.2: Underlying public sector net debt: historical outturn and recent forecasts
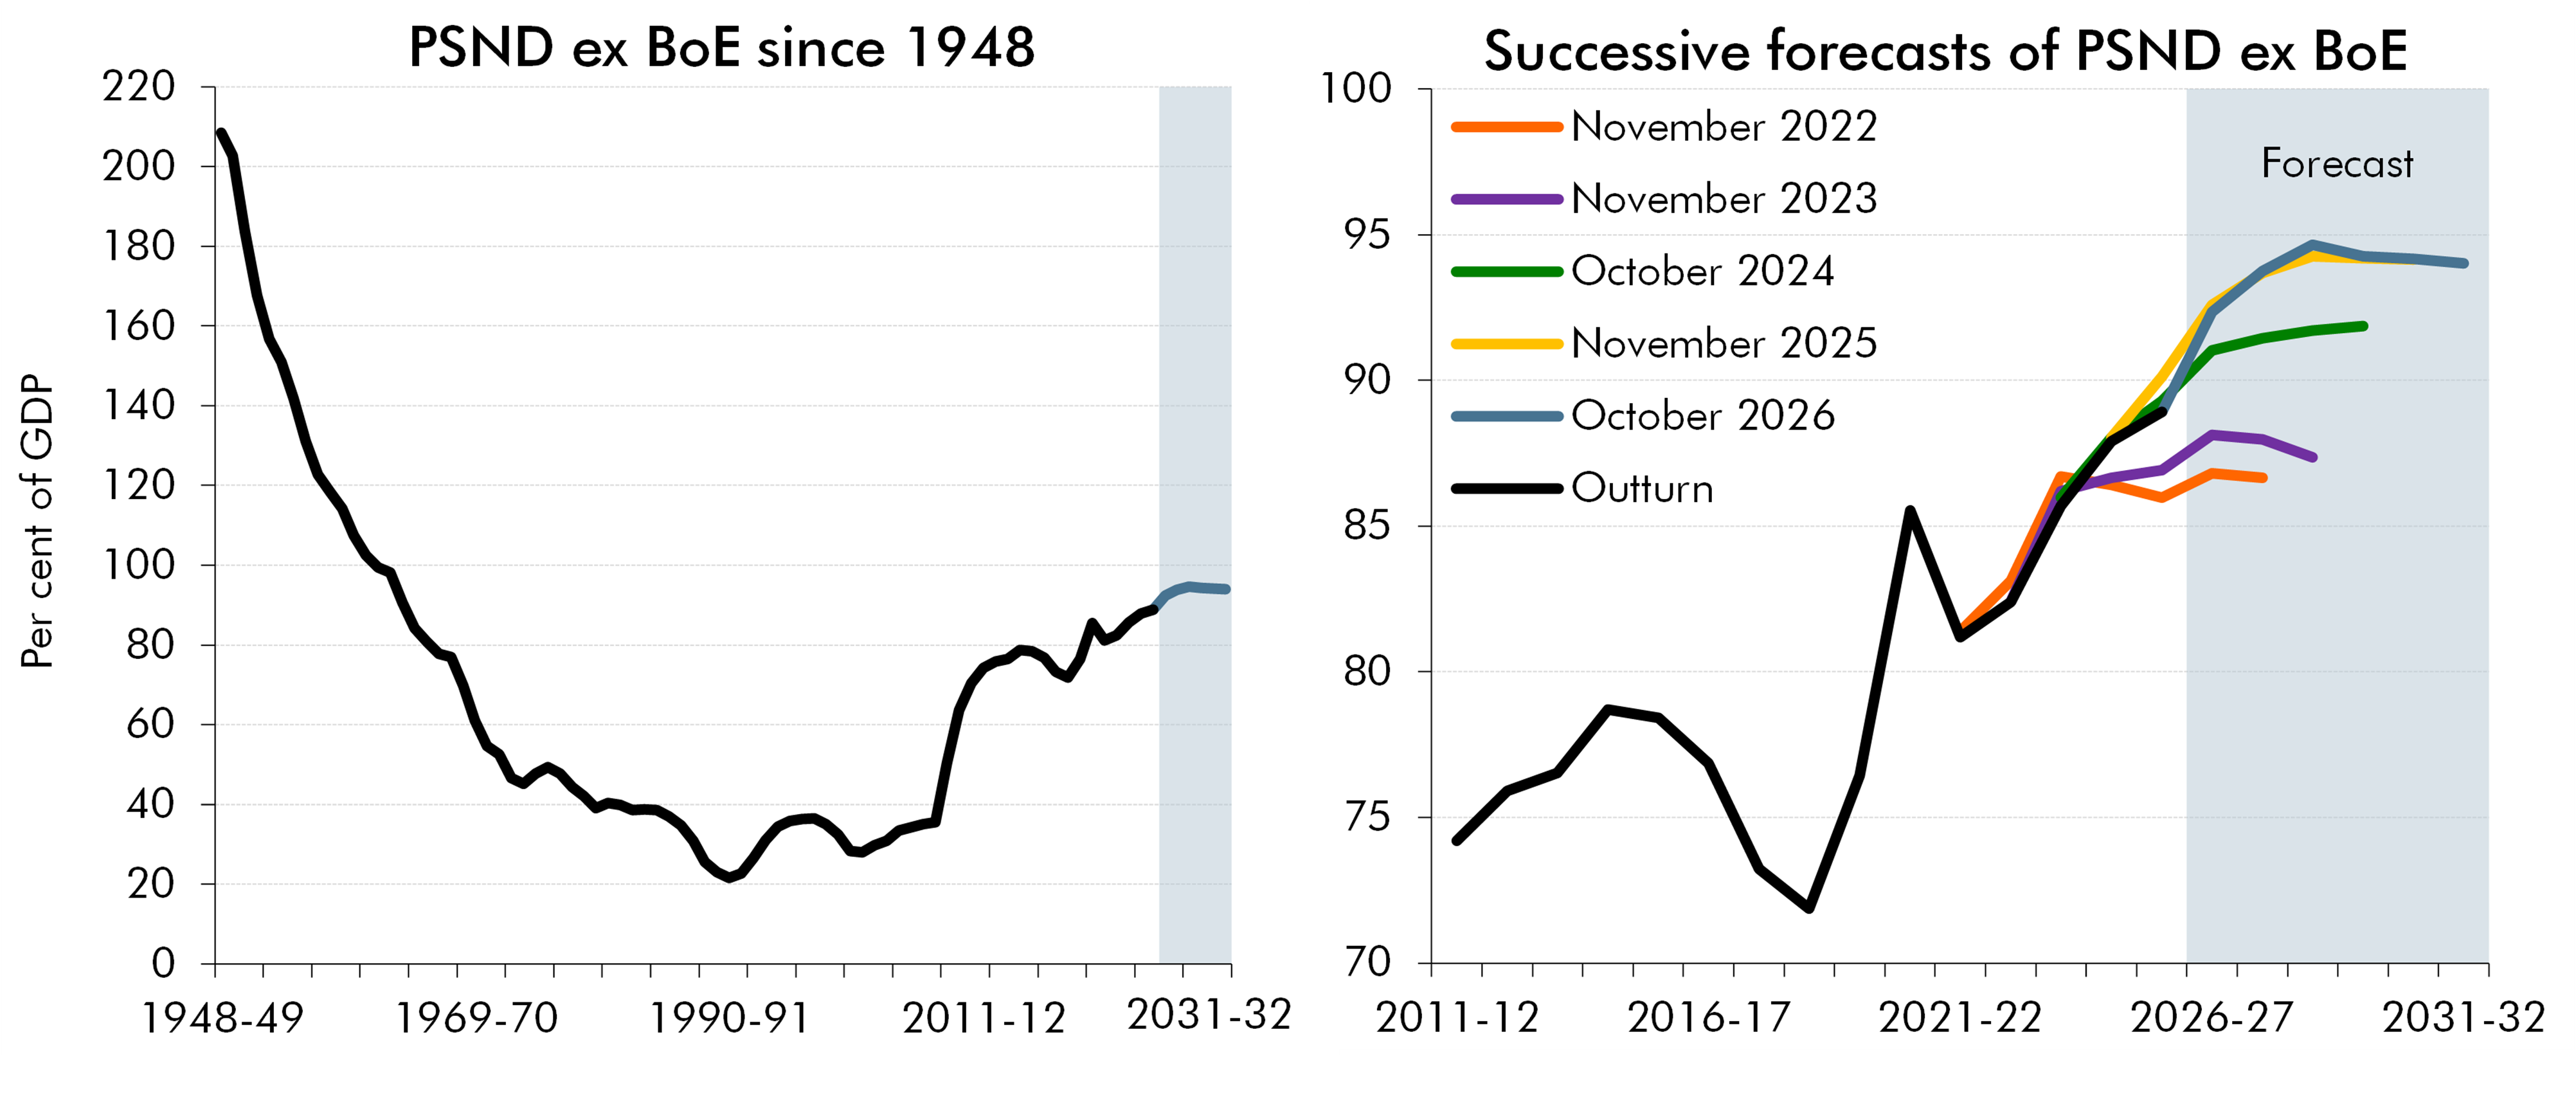
Note: Forecast lines on the right panel are presented as the nominal forecast for PSND excluding the Bank of England divided by the outturn and forecast for March-centred nominal GDP that is consistent with this forecast.
Source: ONS, OBR
International context
7.7 As discussed above, unexpected shocks and low growth have contributed to elevated levels of borrowing and significant increases in public debt in the last two decades. While these factors have affected nearly all advanced economies, the UK has experienced a more significant deterioration in the public finances than most. The left side of Chart 7.3 shows that while general government net borrowing in the UK (blue line) has followed a similar overall trend to other G7 (purple line) and advanced (yellow line) economies since 2006, it has consistently been at a higher level and saw larger spikes in response to shocks. Between 2022 and 2026, UK net borrowing on an internationally comparable basis was 5.1 per cent of GDP, 1.3 percentage points higher than the average for other G7 economies and 3.8 percentage points higher than the average for other advanced economies.
7.8 Based on the IMF forecasts shown in these charts, borrowing in the UK is expected by the IMF to decline by 2.4 per cent of GDP to 1.4 per cent in 2031 – which would be close to the IMF’s forecasts for the average for other advanced economies.[footnote 85] As described in paragraph 7.3, recent similar plans have subsequently been delayed due to economic shocks, weaker-than-expected growth, and changes to government policy.
7.9 The right panel of Chart 7.3 shows that the higher borrowing in the UK than in comparable economies over the previous two decades has contributed to a larger increase in its debt stock over time. General government net debt in the UK as a share of GDP (on an internationally comparable basis) has gone from 8 percentage points higher than the average for other advanced economies in 2006 to 53 percentage points higher in 2026. Over this period among G7 economies, the UK has experienced the largest increase in net debt as a share of GDP, increasing from 25 percentage points below the average of other G7 economies in 2006 to 6 percentage points higher in 2026. Even with the fiscal consolidation planned over the forecast period, the IMF expects UK general government net debt to decline only marginally between 2026 and 2031, to end broadly level with the IMF’s forecasts for the average of other G7 economies, and 54 percentage points higher than its level in 2006.
Chart 7.3: General government net borrowing and net debt in advanced economies
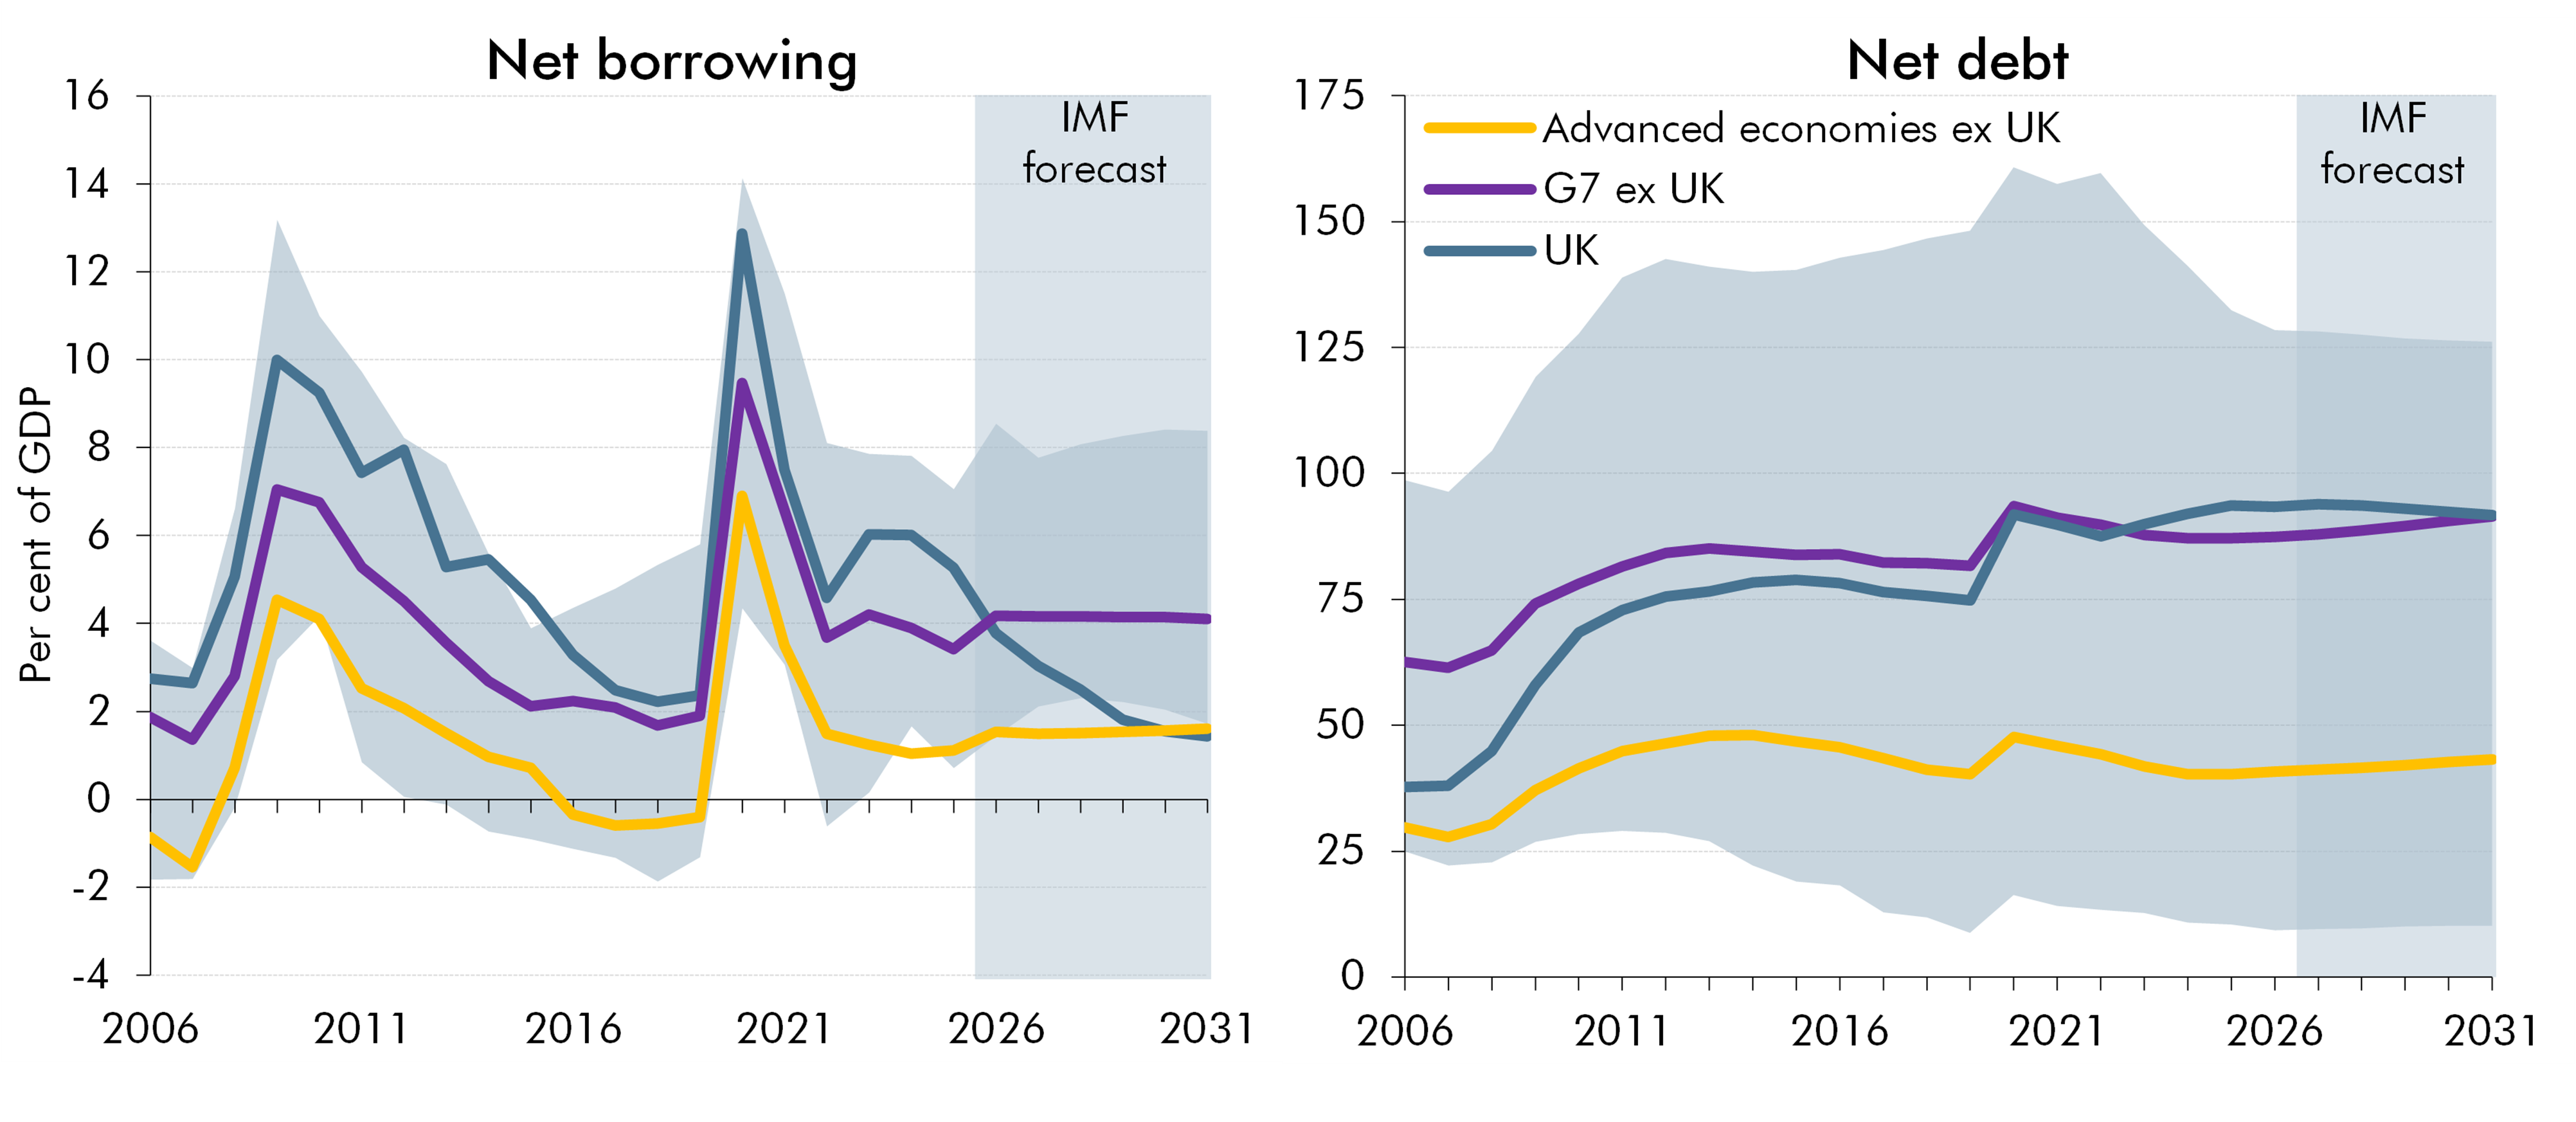
Note: This chart shows IMF outturn (2006-2025) and forecast (2026-2031) for general government net borrowing and net debt which excludes the activity of public corporations. The lines show borrowing and debt for the UK, the unweighted G7 average excluding the UK and the unweighted advanced economy average excluding the UK. The advanced economies included in the average are those detailed in the IMF World economic outlook. The swathe shows the range of borrowing and debt for G7 economies excluding the UK.
Source: IMF, OBR
Long-term sustainability of the public finances
7.10 In the 2026 Fiscal risks and sustainability report, we explored the major sources of long-term fiscal pressure and set out projections for the public finances over the next 50 years. In nearly all of the long-term scenarios we produced, including under several different assumptions for long-term policy settings, demographic and other cost pressures were projected to eventually move borrowing and debt onto an ever-rising trajectory. The blue line in Chart 7.4 shows how the upward trajectory of debt in the FRS baseline long-term scenario starts to accelerate onto an unsustainable path in the 2040s.
7.11 The baseline long-term scenario shown in Chart 7.4 took, as its starting point, the March 2026 forecast for a fiscal consolidation in which the primary balance moves from a deficit of 1.4 per cent of GDP in 2025-26 to a surplus of 1.5 per cent of GDP in 2030-31. However, Chart 7.1 showed that successive recent plans for fiscal consolidation have not yet been delivered. If the long-term projections were instead based on the primary deficit in 2030-31 remaining at its 2025-26 level, the yellow line shows that debt is projected to start to rise onto an unsustainable upward trajectory in the early 2030s. This highlights the importance of early policy action to keep debt on a sustainable trajectory.
7.12 Some of the pressures which drive the increase in debt in the FRS long-term scenarios, such as the impact of an ageing population on state pension caseloads and declining tax revenue from emissions-related taxes, are already starting to affect the fiscal position over the medium term. Box 6.1 explains how some of these factors contribute to the increase in borrowing in the pre-measures forecast between 2030-31 and 2031-32, underlining the importance of early action to address these pressures.
7.13 The Government’s decision to replace the state pension triple lock with an adjusted triple lock from April 2030 should, in itself, reduce some of the long-term upward pressure on the public finances that was identified in the 2026 FRS. Provisional analysis suggests that, if the next 50 years are similar to the previous 35 years, the adjusted triple lock could reduce the projected increase in debt by around 25 per cent of GDP in 2075-76 relative to the current triple lock uprating. However, alongside this announcement the Government also set out an ambition to expand public provision of social care. The overall impact of these announcements on the outlook for long-term fiscal sustainability therefore depends on the costs of the reforms to social care. These issues are discussed further in paragraphs 3.48 to 3.54.
Chart 7.4: Long-term debt scenarios: 2026 Fiscal risks and sustainability report
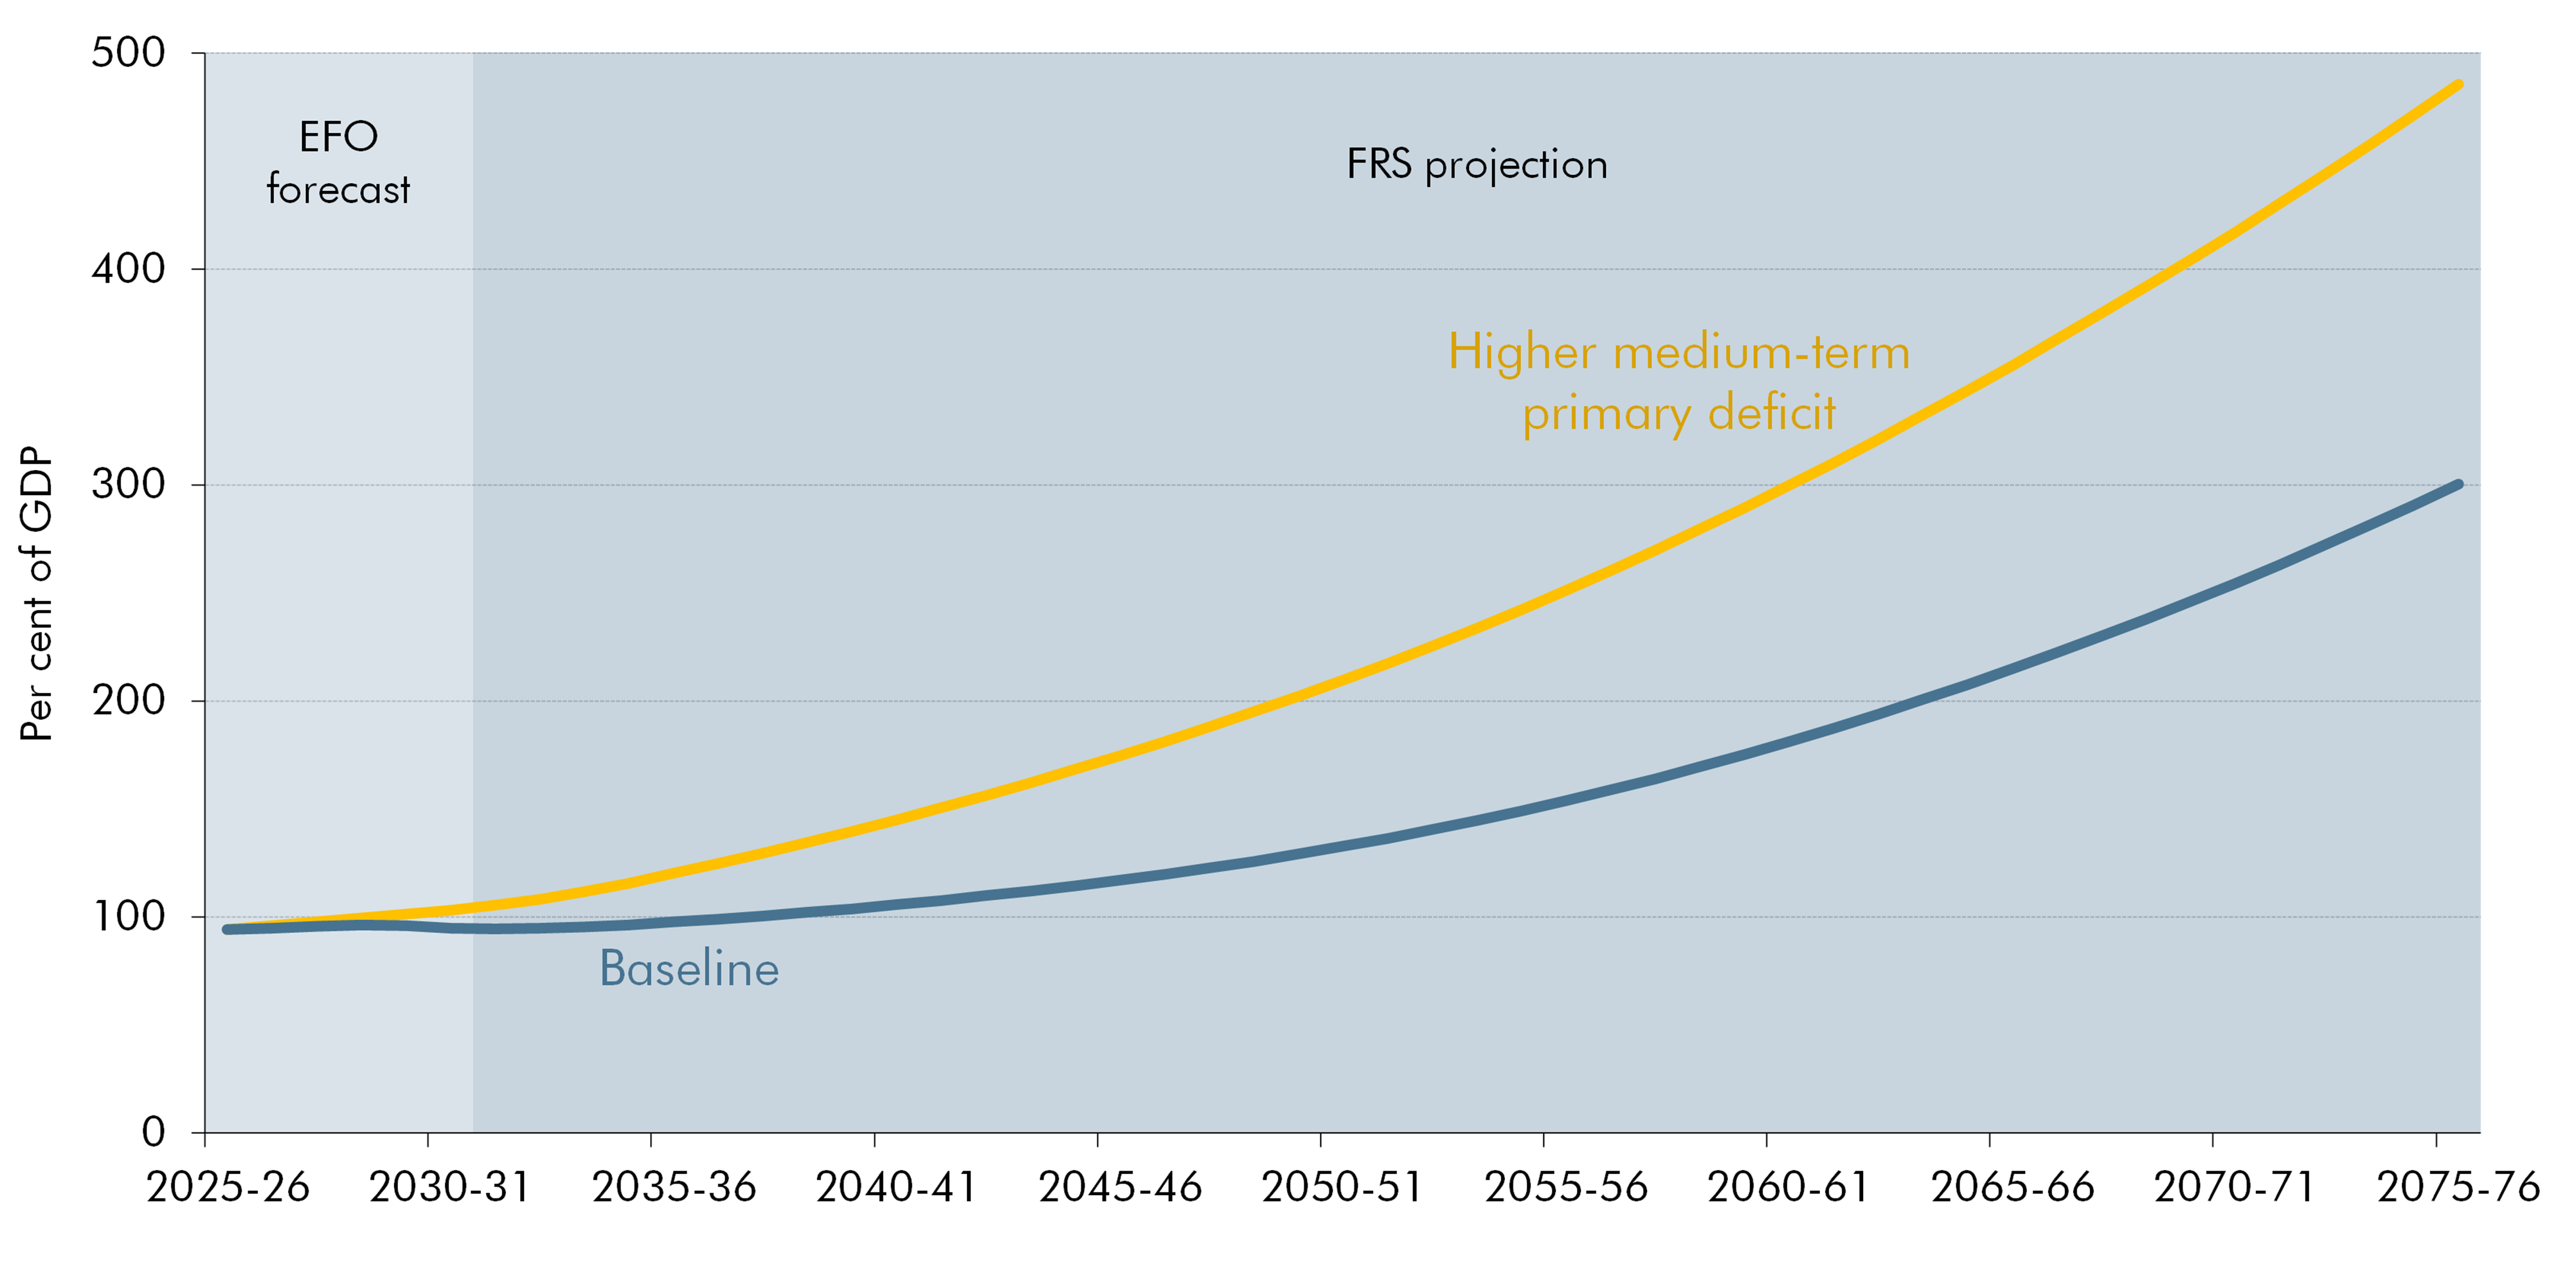
Source: OBR
Fiscal targets and wider indicators of fiscal sustainability
7.14 The Budget Responsibility and National Audit Act 2011 requires the OBR to assess at least once per financial year the extent to which the Government has achieved or is likely to achieve its fiscal mandate under current policy. The Charter for Budget Responsibility states that the fiscal mandate is:
- to have the current budget in surplus in 2029-30, until 2029-30 becomes the third year of the forecast period. From that point, the current budget must then remain in balance or in surplus from the third year of the rolling forecast periods.
7.15 There are also two supplementary targets in the Charter:
-
to have debt, defined as public sector net financial liabilities (PSNFL), falling as a share of the economy in 2029-30, until 2029-30 becomes the third year of the forecast period. Debt should then fall by the third year of the rolling forecast period; and
-
to ensure that expenditure on welfare (excluding the state pension and payments closely linked to the economic cycle) is contained within a predetermined cap and margin. The Charter sets out that the OBR will assess spending against the welfare cap and margin at the first Budget of each new Parliament.
7.16 The Charter also requires the OBR to provide an analysis of the risks surrounding the fiscal outlook, and to consider a wide range of factors and dimensions relating to the sustainability of the public finances. The Charter further states that the Treasury will consider a wide range of indicators in its management of fiscal policy.
Performance against the Government’s fiscal targets in the central forecast
7.17 Based on the central forecast and as shown in Table 7.1, the centres of the distribution of forecast outcomes for the current budget and the PSNFL-to-GDP ratio are such that:
-
The fiscal mandate for the current budget to be in surplus in 2029-30, the third year of the forecast period, is met by a margin of 0.4 per cent of GDP (£15 billion). This compares to a margin of 0.6 per cent of GDP (£22 billion) when performance against the rules was last assessed alongside the November 2025 Budget.
-
The supplementary target, for public sector net financial liabilities (PSNFL) to be falling as a per cent of GDP in 2029-30, is forecast to be met by a margin of 0.7 per cent of GDP (£24 billion), unchanged from a margin of 0.7 per cent of GDP (also £24 billion) at the November 2025 Budget.
-
The welfare cap plus margin, set for 2029-30, is on course to not be met by a margin of £3 billion, as opposed to last November when it was forecast to be met by a margin of £2 billion.
Table 7.1: Performance against the Government’s fiscal targets
| Per cent of GDP | £ billion | Per cent | |
|---|---|---|---|
| Margin | Margin | Probability(1) | |
| Current budget to be in surplus by 2029-30 | |||
| November 2025 forecast(2) | 0.6 | 21.7 | 59 |
| October 2026 pre-measures forecast | 0.4 | 12.5 | 55 |
| October 2026 forecast | 0.4 | 14.5 | 56 |
| Memo: excluding fuel duty rises(3) | 0.3 | 10.2 | |
| Change in public sector net financial liabilities in 2029-30 | |||
| November 2025 forecast(2) | 0.7 | 24.4 | 52 |
| October 2026 pre-measures forecast | 0.6 | 21.8 | 54 |
| October 2026 forecast | 0.7 | 24.4 | 54 |
| Memo: excluding fuel duty rises(3) | 0.6 | 20.3 | |
| £ billion | |||
| Forecast | Margin | ||
| Welfare cap: specified welfare spending in 2029-30 | |||
| November 2025 forecast | 202.3 | 1.9 | |
| October 2026 forecast | 207.0 | -2.8 |
| 1) The probability of meeting the corresponding fiscal target in the mandate year of 2029-30 based on our central forecast. |
| 2) In our November 2025 forecast, the target year was the fourth year of the forecast. In our current forecast, the target is the third year of the forecast. |
| 3) This shows the margin for the target if fuel duty was to remain frozen in cash terms in each year of the forecast. |
| Source: OBR |
Probability of meeting the fiscal targets
7.18 Chart 7.5 presents fan charts, based on stochastic simulations and historic deviations from central forecasts, of the probability distribution around the forecast for the current budget and PSNFL.[footnote 86] These distributions enable us to assess the probability of the Government’s fiscal targets being met based on current policies. They show that currently:
-
The probability of meeting the fiscal mandate to have the current budget in surplus in 2029-30 is now 56 per cent in the post-measures forecast. This is a slight reduction from last November’s 59 per cent. With the shorter horizon to the target year compared to last November, a smaller margin is required to have the same chance of meeting the rules. Despite this, the probability has decreased overall because the reduction in the margin more than offsets the effect of the shorter horizon. For the probability of meeting the fiscal mandate to be increased to reach 60 or 70 per cent, it would require the current budget forecast to be in surplus by around £25 and £50 billion, respectively, in 2029-30, instead of the current forecast margin of £15 billion.
-
The probability of meeting the supplementary target, PSNFL falling as a share of GDP, is now 54 per cent. The estimated likelihood has increased slightly from 52 per cent in November 2025, primarily due to a reduction in the uncertainty around the central forecast for the target year having rolled forward from the fourth to the third year of the forecast. For the probability of the supplementary target to be met by a 60 or 70 per cent chance, it would require PSNFL to be falling by 1.8 or 3.9 per cent of GDP in 2029-30, respectively, instead of the current forecast margin of a fall of 0.7 per cent of GDP.
7.19 Chart 7.5 illustrates the very wide range of possible outcomes around the central forecast for the current deficit and PSNFL. In this forecast, the probability distribution suggests that there is a 60 per cent chance that the current budget deficit falls between a deficit of 2.0 per cent of GDP (around £70 billion) and a surplus of 2.8 per cent of GDP in the target year 2029-30 (around £100 billion). For PSNFL, there is a 60 per cent chance of it lying between 78 per cent of GDP and 90 per cent of GDP in 2029-30. This reflects the uncertainty inherent in any medium-term fiscal forecast given the multiple economic factors that can affect the public finances and the scale of the shocks that can hit the economy over such a period. This is illustrated by the frequency with which large adverse shocks have hit the economy over the last two decades, as outlined earlier in the chapter. These types of downside risks mean that the probability distribution is weighted towards higher levels of borrowing and debt. While risks are skewed to the downside, outcomes above and below the median forecast remain broadly equally likely, based on current stated Government policy.
Chart 7.5: Fan charts for the current budget deficit and PSNFL
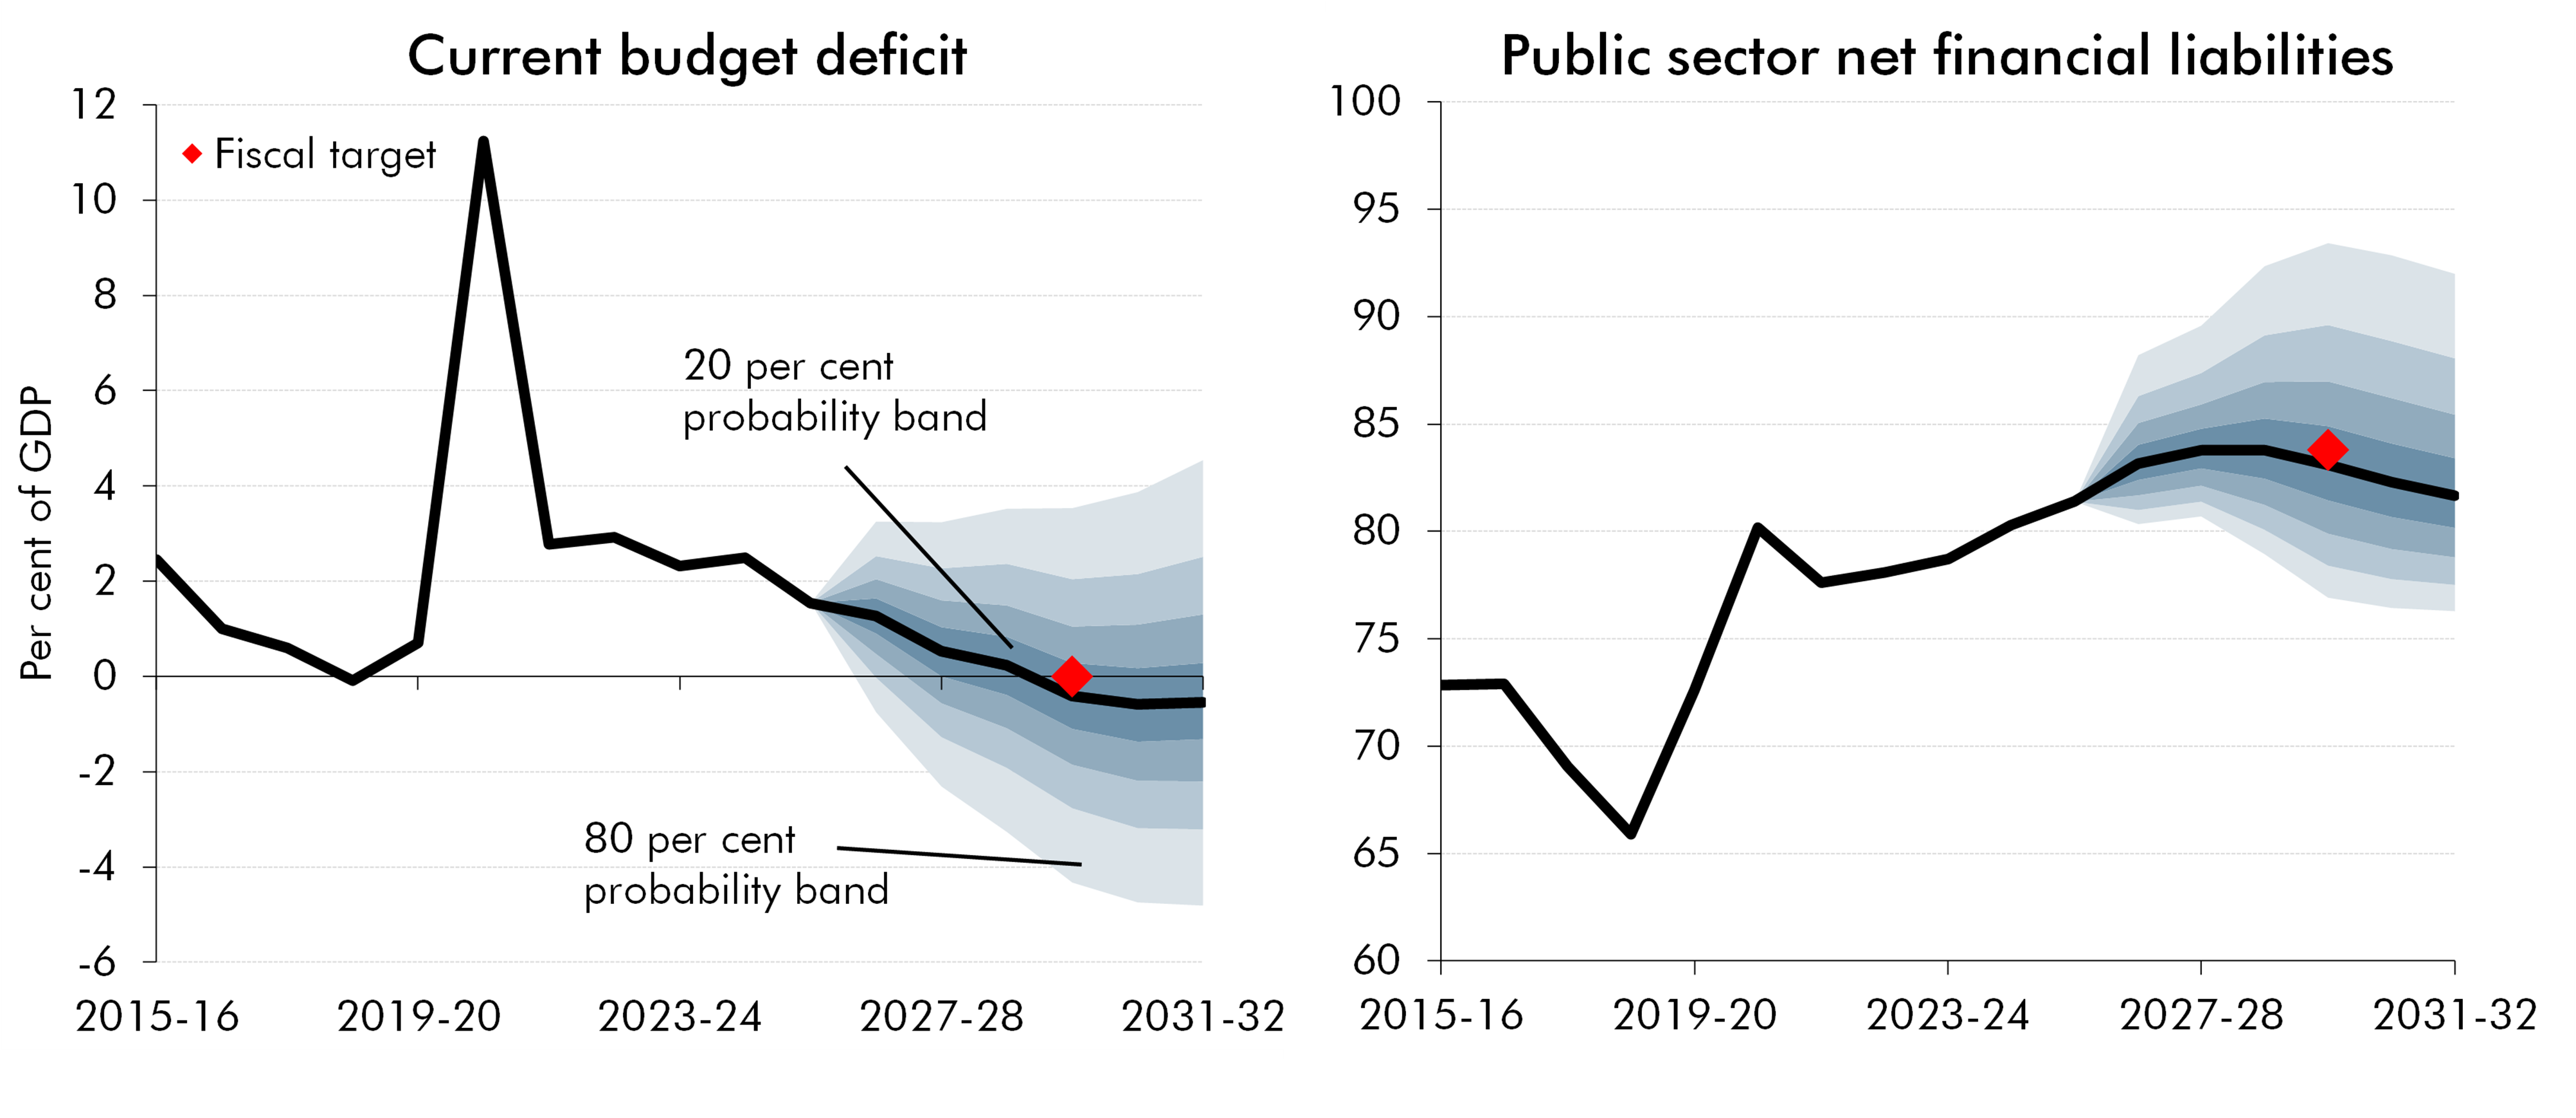
Source: OBR
Change in the margins against fiscal targets
7.20 Chart 7.6 decomposes the change in margins for the current budget and PSNFL targets in the central forecast compared to last November. The current budget has a reduced margin of £7 billion, while PSNFL is unchanged:
-
Underlying pre-measures forecast changes between the Budget 2025 forecast and the March 2026 forecast increased the margin by £8 billion for both the current budget and the net liabilities target.[footnote 87] This was largely driven by upward revisions in March to the receipts forecast due to higher forecast equity prices, and a lower debt interest spending forecast as a result of lower gilt rates and RPI inflation at that time.
-
The effects of policy measures announced between Budget 2025 and the March 2026 forecast lowered the current budget and PSNFL margins by £6 billion.
-
Underlying pre-measures forecast changes since the March forecast have reduced the current budget margin by £11 billion and the PSNFL margin by £5 billion.3 This largely reflects higher debt interest spending, mainly as a result of increased borrowing costs and inflation, and higher welfare spending due to inflation, described further in Chapter 6. The impact of pre-measures forecast changes on PSNFL is lower because of a higher forecast for nominal GDP growth in 2029-30, which lowers PSNFL as a share of GDP.[footnote 88]
-
The effect of policy included in this Budget, as set out in Chapter 3, increases both the current budget and PSNFL margins by £2 billion and £3 billion respectively.
Chart 7.6: Fiscal target margins in 2029-30: changes since November 2025
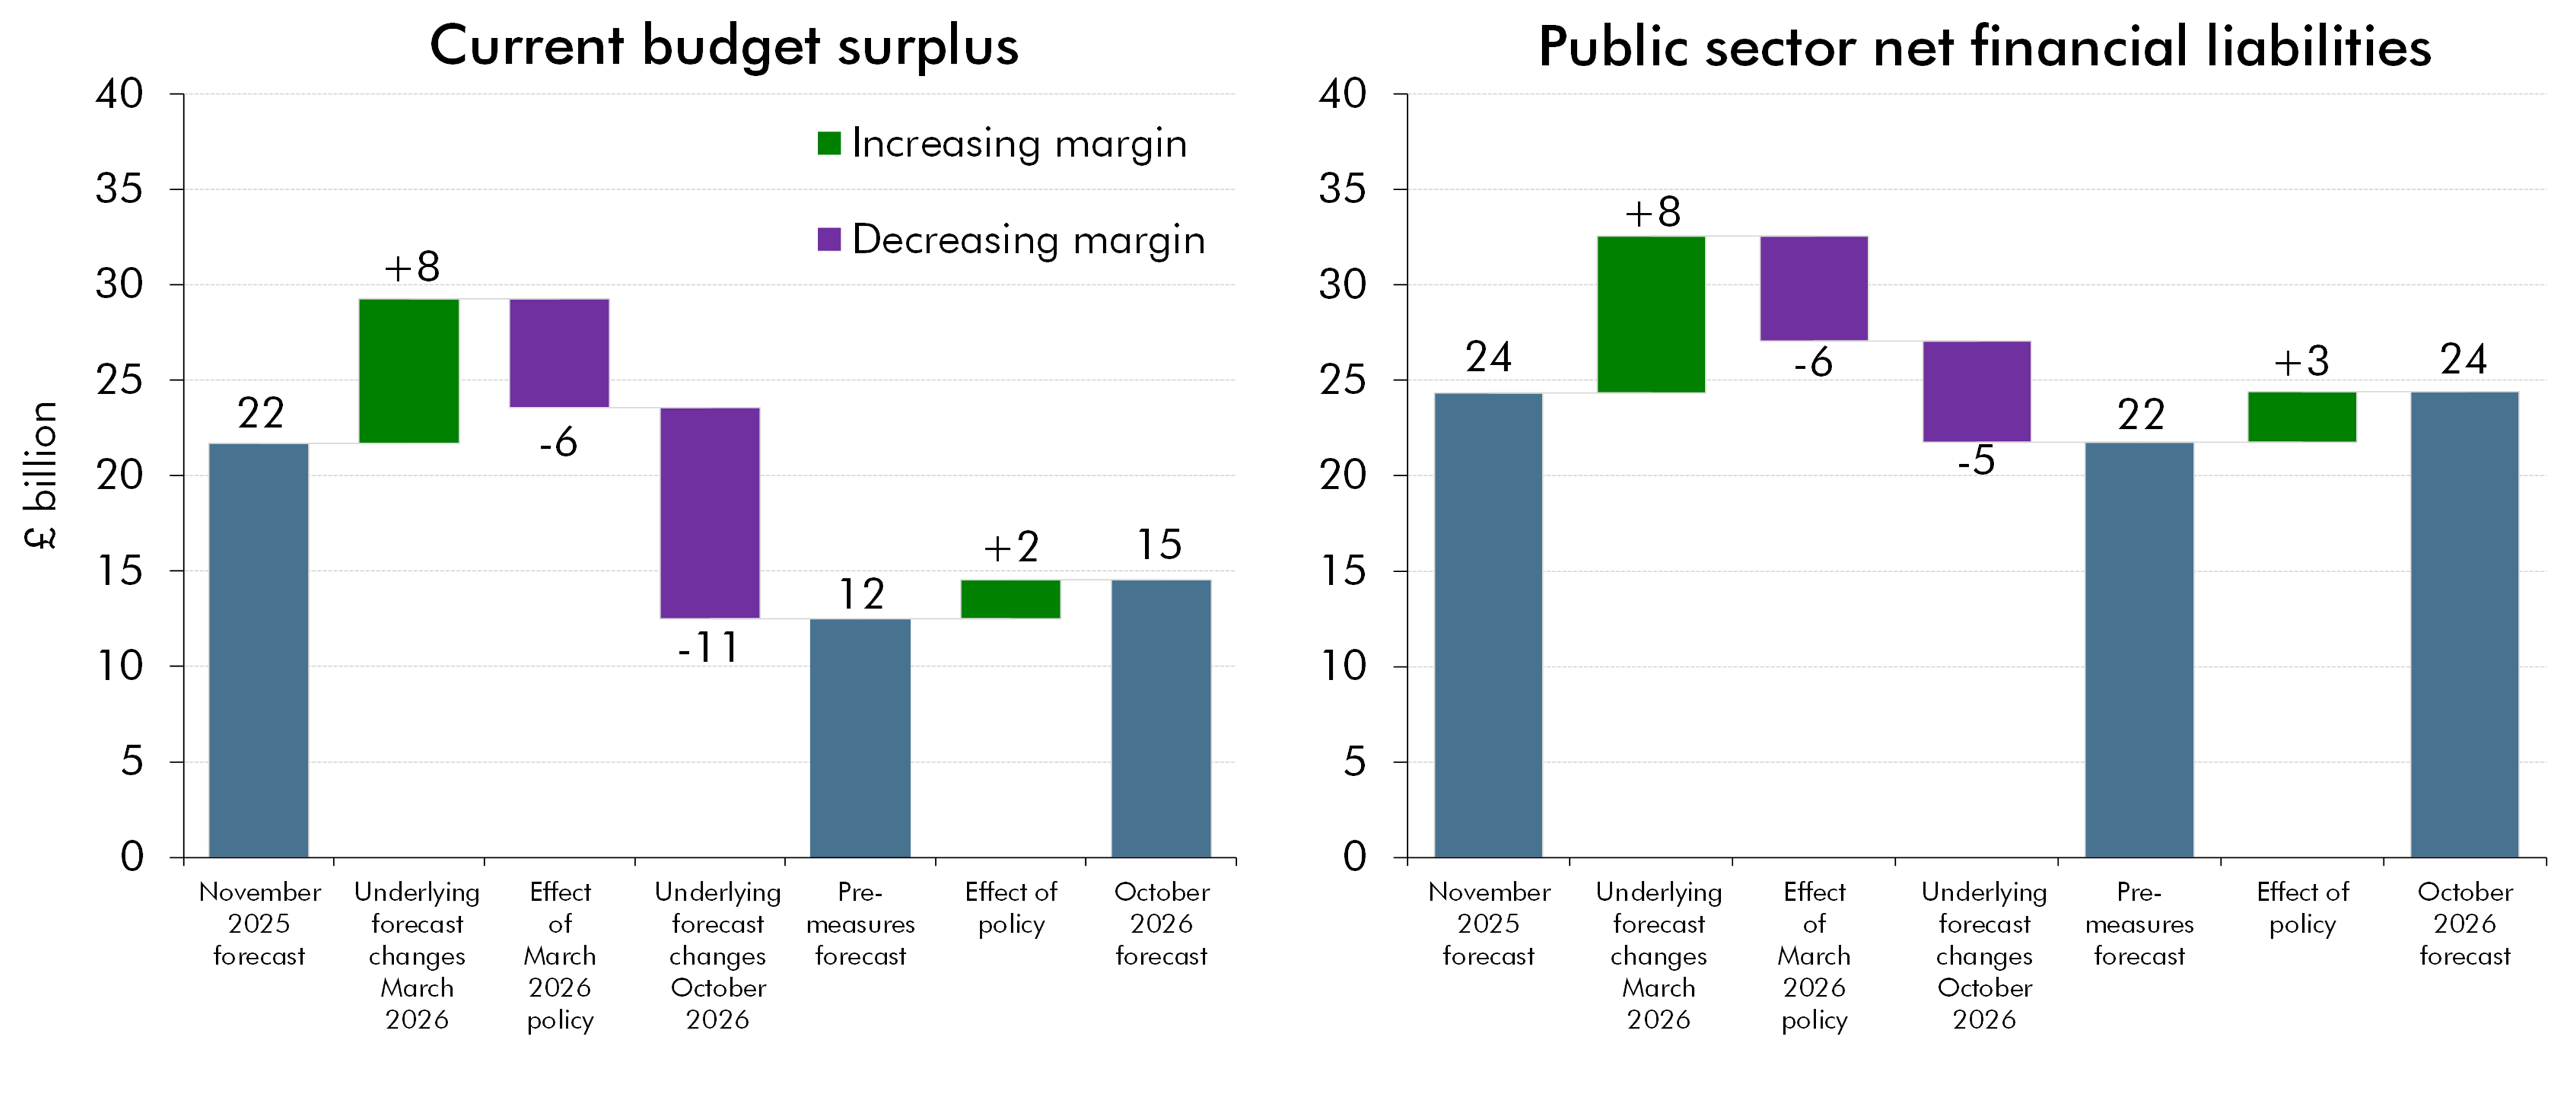
Note: Numbers may not add up due to rounding.
Source: OBR
Margins against successive fiscal mandates
7.21 The margin against the Government’s fiscal mandate of £15 billion is around half of the average margin that previous Chancellors have left against their fiscal mandate since 2010. Chart 7.7 shows that at 56 per cent, the probability of meeting the target is judged to be broadly in line with the mean and median since the pandemic. The £15 billion margin is only slightly lower than the average revision to pre-measures borrowing in the third year of the forecast since the pandemic, which is £18 billion.[footnote 89] It is under half of the median three-year-ahead difference between forecast and outturn, which is £34 billion.[footnote 90]
7.22 The margins shown in Chart 7.7 have often been against rules that targeted the fourth or fifth year of the forecast period. At this forecast, the current Government’s fiscal mandate is now assessed at the third year of the forecast. The Charter also requires the Government to set detailed spending plans for three years ahead at spending reviews every two years. This means that, from the next spending review, the Government will be required to have detailed spending allocations for the year in which the fiscal targets bind. This should reduce the uncertainty, for a given expected margin, around meeting these targets.
Chart 7.7: The probability of hitting the Government’s fiscal mandate (right axis) and successive forecasts of the margin (left axis)
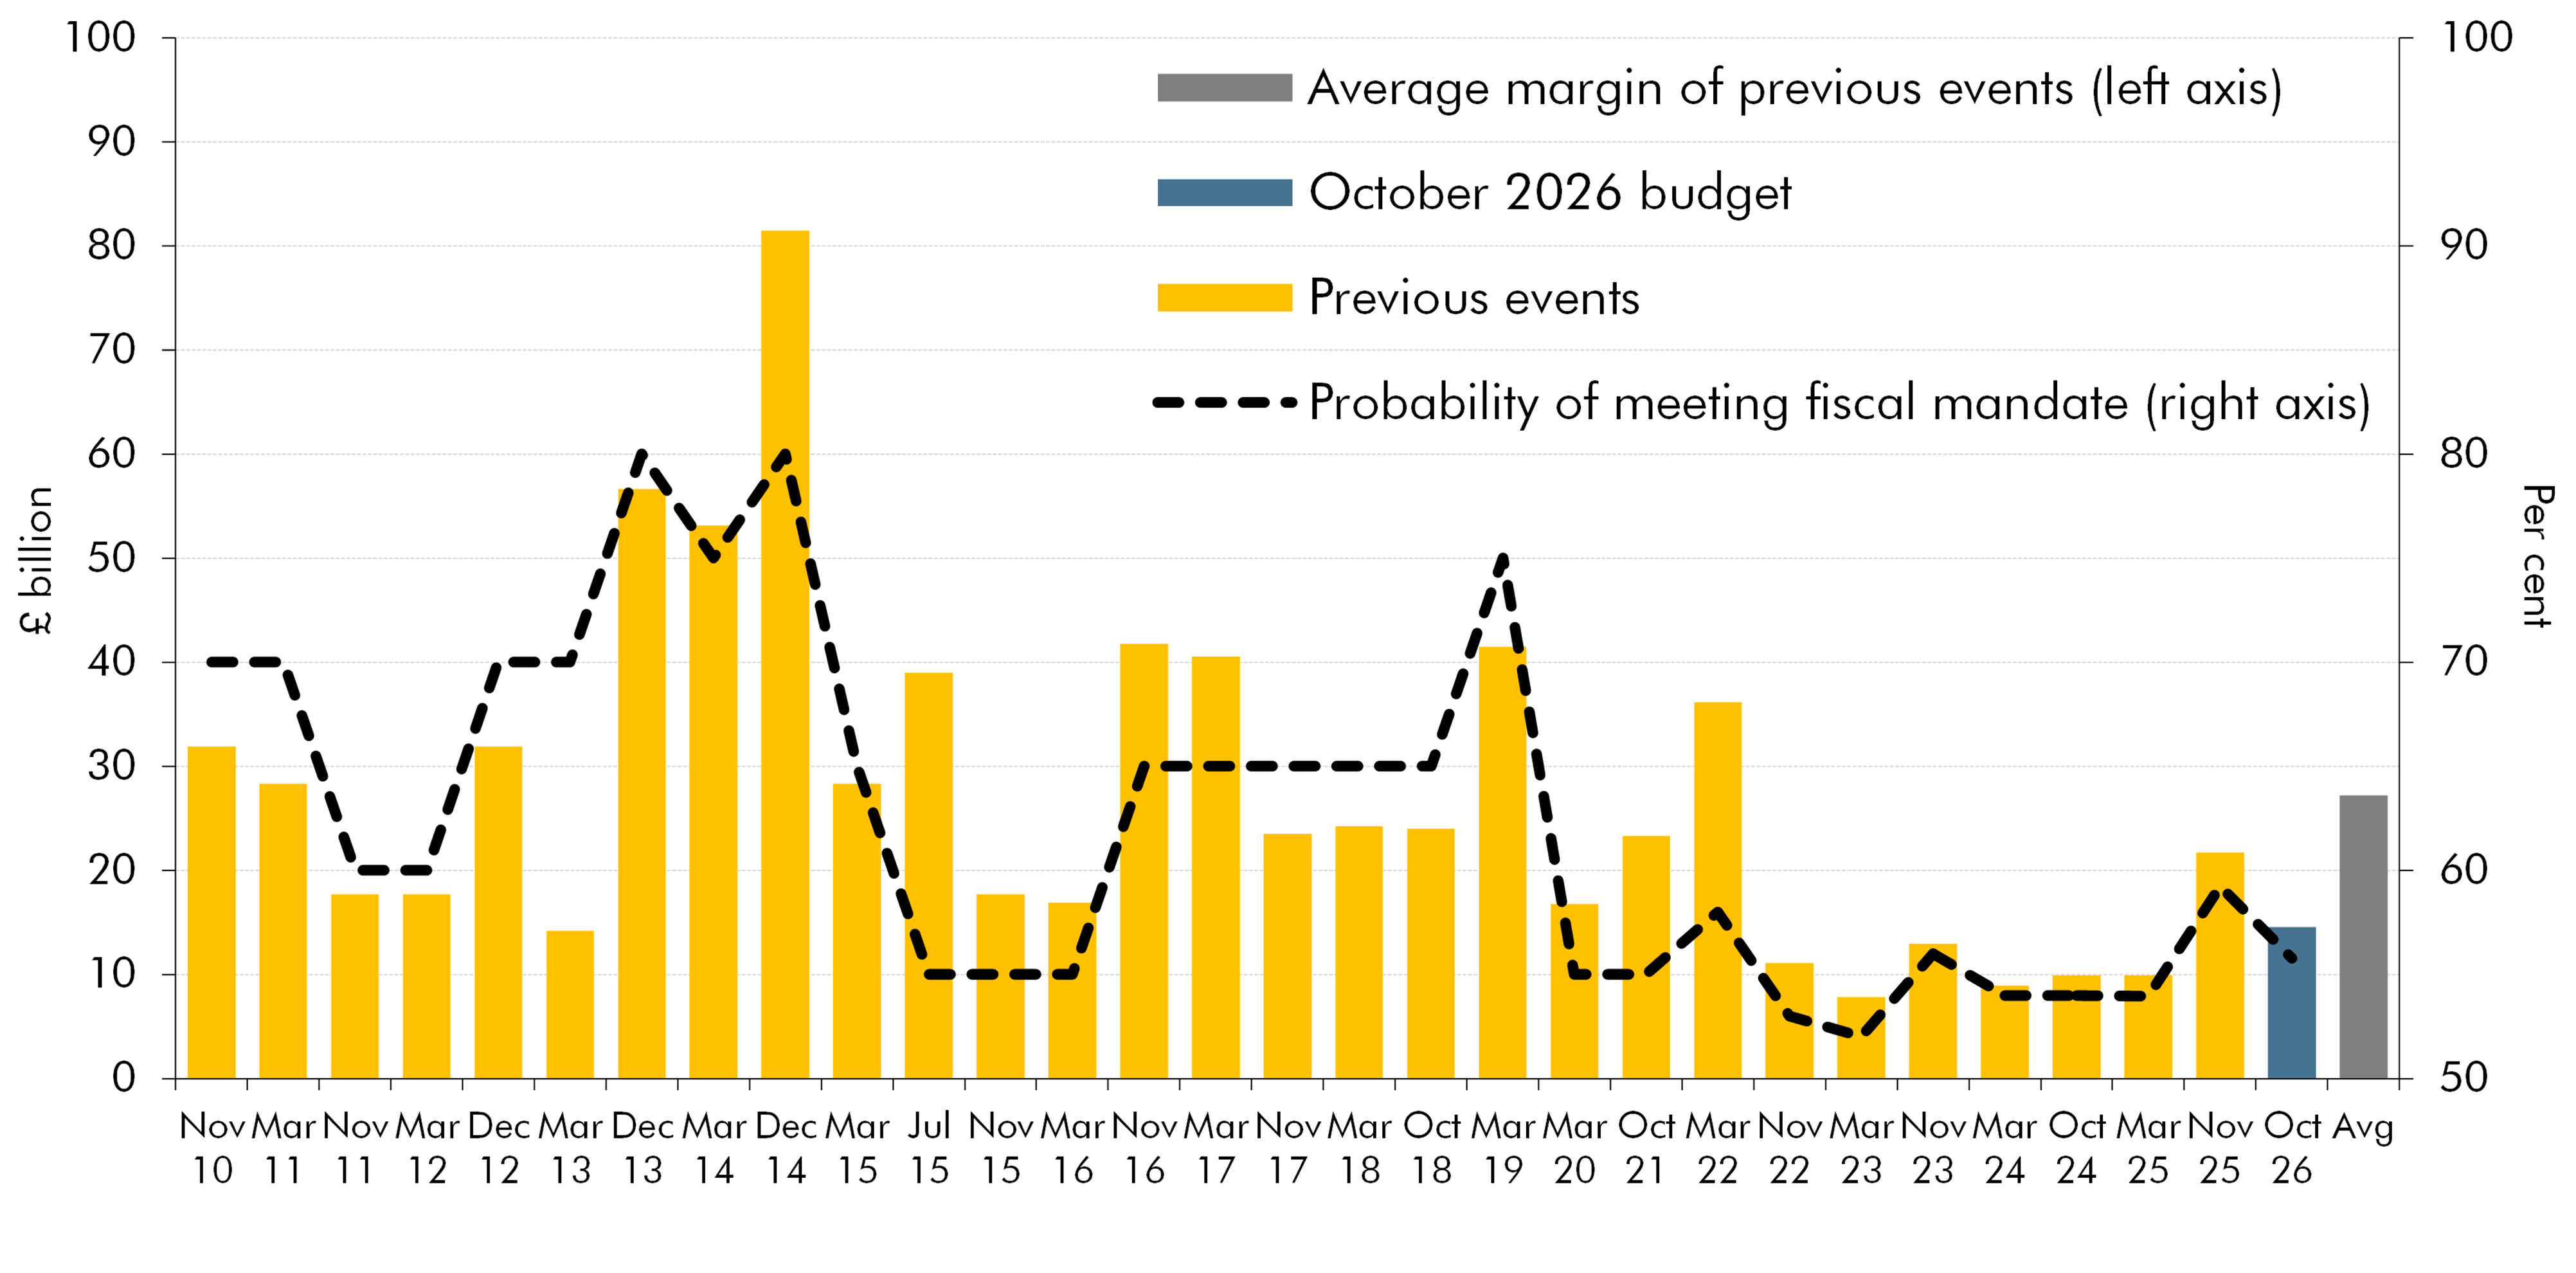
Note: Target metric varies depending on the fiscal mandate, and the date is the EFO at which the rule was assessed. For comparability with headroom against the current fiscal mandate, past margins have been calculated in per cent of GDP as forecast at the time and multiplied by our latest forecast for nominal GDP in 2029-30. For November 2016 and March 2020, we have used the Chancellor’s margin against the proposed fiscal rules at the time.
Source: OBR
7.23 Chart 7.8 shows successive forecasts for the current deficit since it became the target for the fiscal mandate in October 2024. It shows that in successive forecasts, governments have planned to have the current budget in surplus by 2029-30, which is the current target year for the fiscal mandate. However, the year in which the current budget deficit was forecast to move into surplus has been moved back from 2027-28 in the October 2024 and March 2025 forecasts, to 2028-29 in the November 2025 forecast and 2029-30 in the current forecast. This is a similar pattern to the successive delays to plans for the reduction in borrowing shown in Chart 7.1.
Chart 7.8: Successive forecasts for the current budget deficit
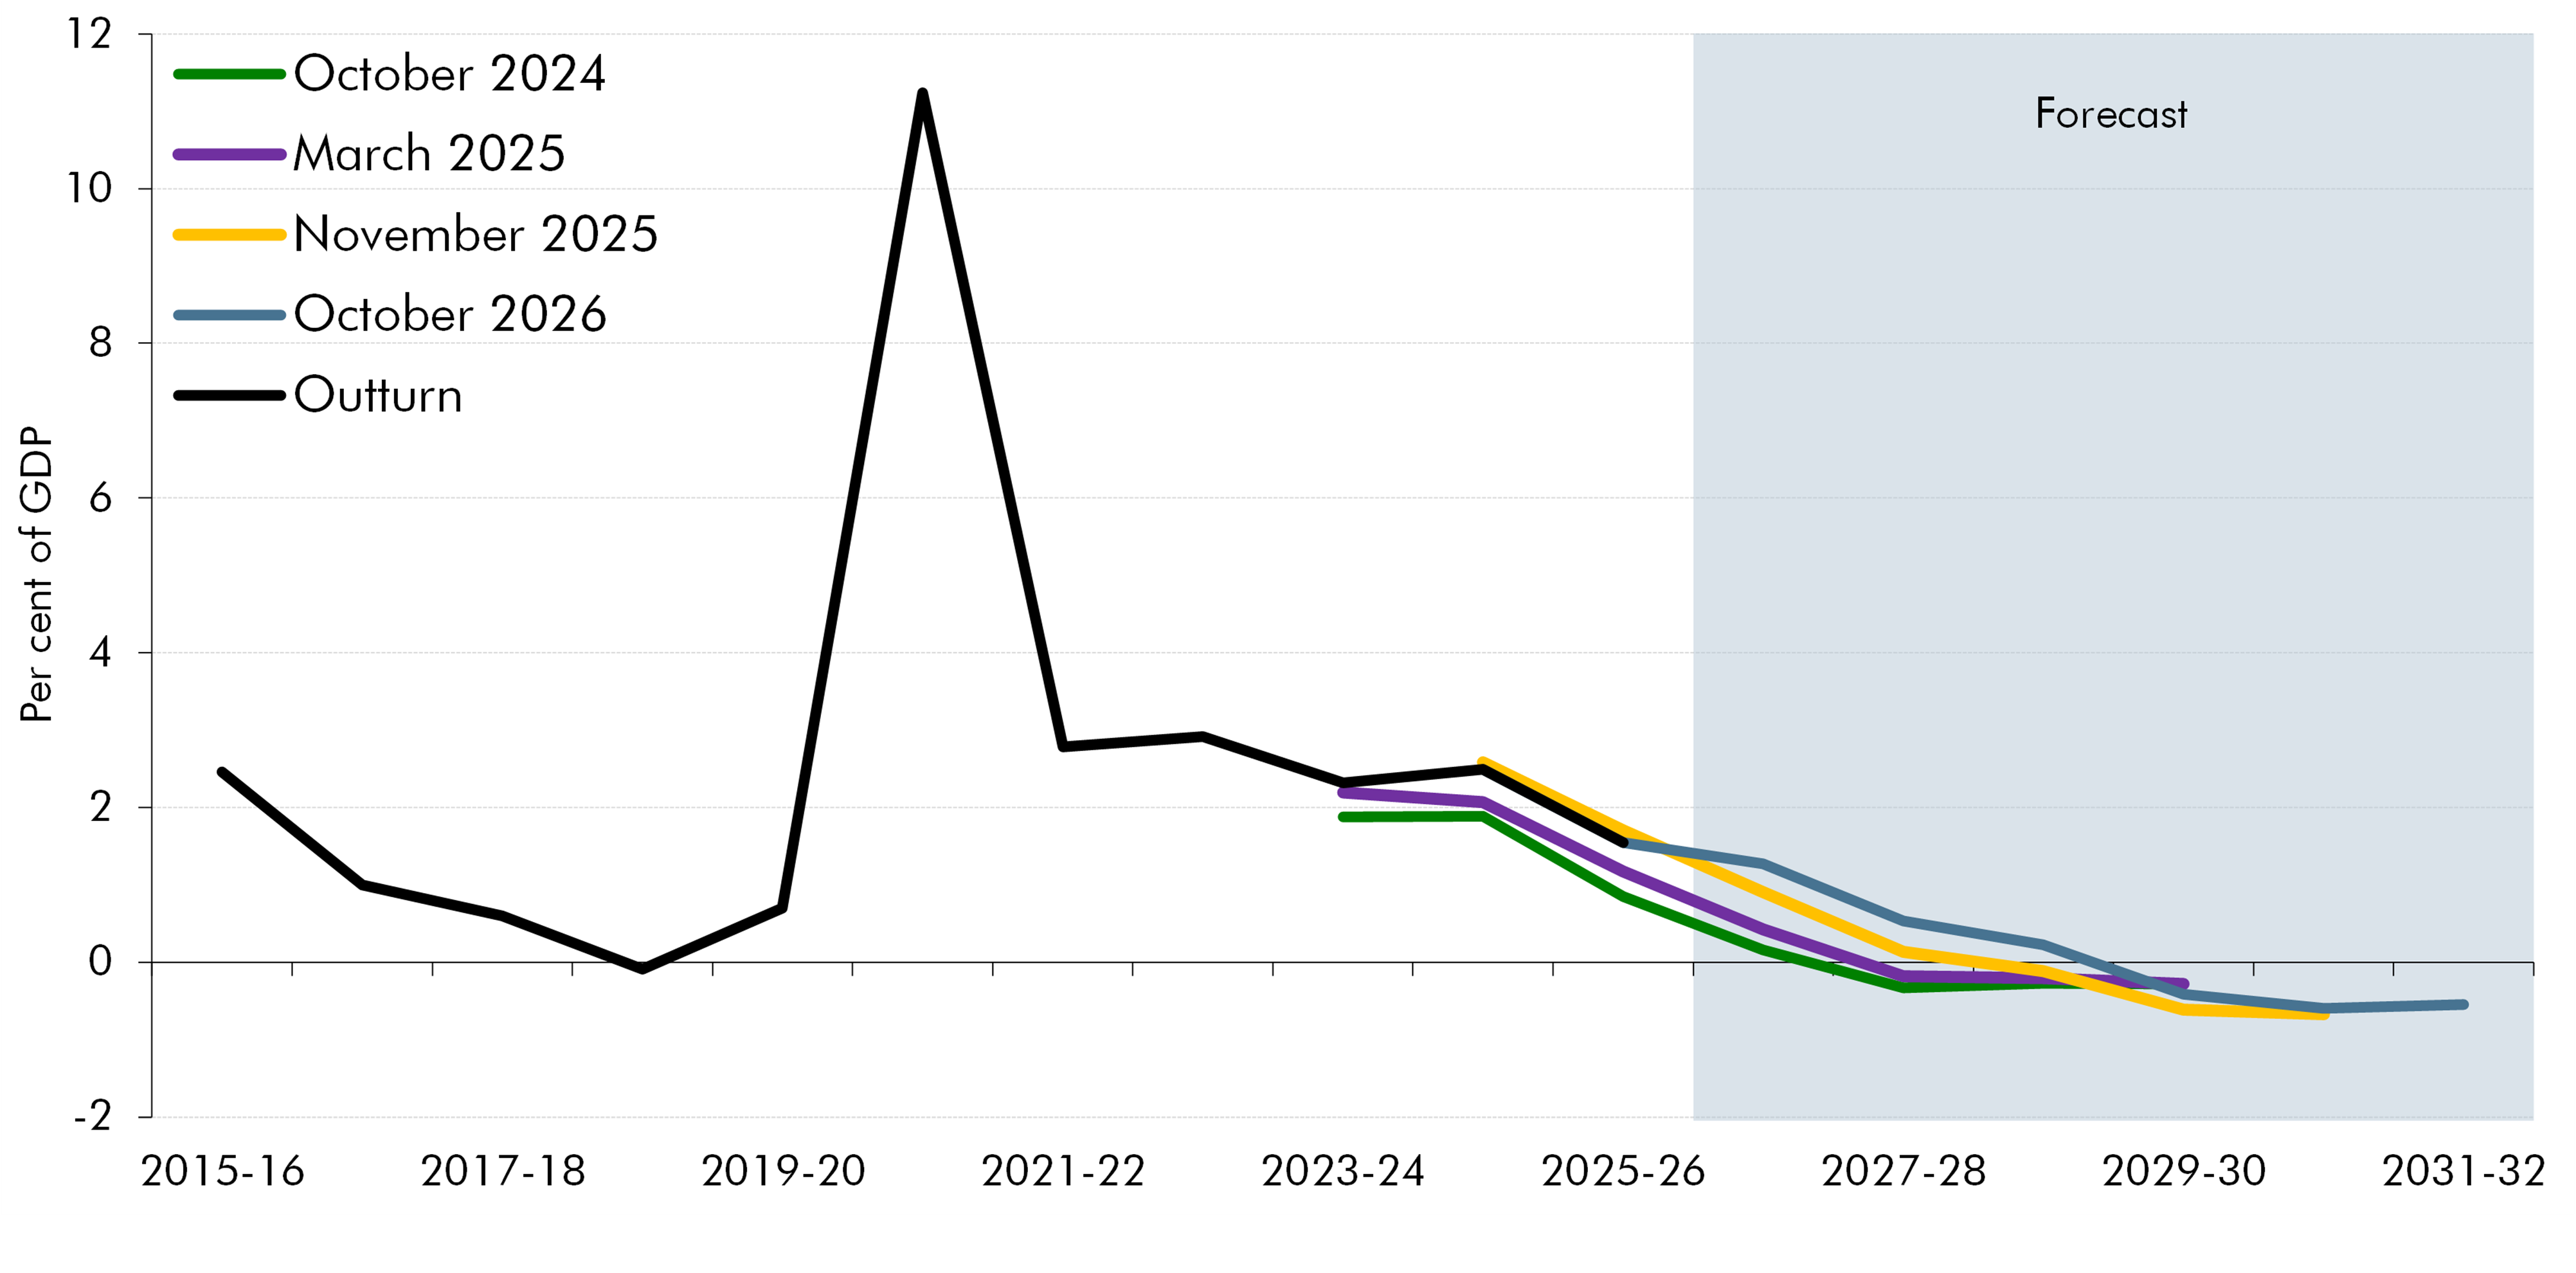
Note: Forecast lines are presented as the nominal forecast for the current budget deficit divided by the outturn and forecast for nominal GDP that is consistent with this forecast.
Source: ONS, OBR
Welfare cap
7.24 The welfare cap is a limit for government spending on certain social security benefits and tax credits in the final year of a given Parliament. Since its introduction in 2014, the welfare cap has been revised upwards frequently to account for inflation and changes in welfare demand. The Charter states that the OBR will make a formal assessment of spending against the welfare cap and margin at the first Budget of each new Parliament, and will monitor welfare spending against the pathway and margin at each Budget before the formal assessment.
7.25 The Government set a welfare cap of £194.5 billion in 2029-30 at the October 2024 forecast, and a margin for the cap that rises each year to reach 5 per cent in 2029-30. Spending against the welfare cap in 2029-30 has risen by £5 billion since the November 2025 forecast, largely due to higher in-work and health-related universal credit caseloads, along with higher spending forecasts for supported housing. This results in the welfare cap being on course not to be met by £3 billion once the margin is included.
Table 7.2: Welfare cap and margin
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | |
|---|---|---|---|---|---|
| £ billion | |||||
| Forecast | |||||
| Welfare cap | 194.5 | ||||
| Pathway | 166.8 | 172.6 | 179.0 | 186.4 | |
| Margin (per cent) | 1.0 | 2.0 | 3.0 | 4.0 | 5.0 |
| Margin | 1.7 | 3.5 | 5.4 | 7.5 | 9.7 |
| Welfare cap and pathway plus margin | 168.5 | 176.0 | 184.4 | 193.8 | 204.2 |
| Latest forecast and update on performance against cap and pathway | |||||
| October 2026 forecast | 170.1 | 180.2 | 188.2 | 196.8 | 204.7 |
| Inflation adjustment | 0.6 | -1.1 | -2.7 | -5.2 | -5.3 |
| Scottish welfare block grant adjustment | 5.8 | 6.3 | 6.8 | 7.3 | 7.7 |
| October 2026 forecast after adjustments | 176.5 | 185.4 | 192.4 | 198.9 | 207.0 |
| Difference from: | |||||
| Cap and pathway | 9.7 | 12.8 | 13.4 | 12.5 | 12.5 |
| Cap and pathway plus margin | 8.0 | 9.4 | 8.0 | 5.0 | 2.8 |
| Memo: cumulative percentage point change in preceding September (Q3) rates of inflation since our October 2024 forecast | -0.4 | 0.7 | 1.6 | 2.9 | 2.8 |
| Source: DWP, HMRC, HM Treasury, OBR |
Balance sheet and fiscal affordability metrics
7.26 The assessment of the Government’s performance against its medium-term fiscal targets provides limited information on the overall sustainability of the fiscal position. In recognition of this, the Charter sets out that the “OBR will consider a wide range of factors and dimensions relating to the sustainability of the public finances”. In this chapter, we have included analysis of the UK’s overall fiscal position compared to the past, provided comparisons of key fiscal indicators in the UK compared to other advanced economies, and summarised some of the key conclusions from our most recent analysis of long-term fiscal sustainability in the 2026 FRS. This section provides a summary assessment of a range of balance sheet, debt affordability and debt stabilisation metrics, which can also be used as indicators of fiscal sustainability.
7.27 Table 7.3 presents this dashboard of metrics that shows: first (top two panels), their levels and how these compare with the medians from 1967-68 to 2006-07 (the four decades preceding the financial crisis) and from 2007-08 to 2018-19; and second (lowest panel), whether they are improving or deteriorating in each year of the forecast. It shows that:
-
Balance sheet stock measures all remain in a significantly worse position than both the pre-2007 and the 2007-2019 medians across the forecast period.
-
The financing and cost of debt measures are also generally in a worse position than the pre-crisis median. The central government net cash requirement remains above the pre-2007 median for the majority of the forecast period. Net interest costs are also above the pre-2007 median as a share of GDP across the forecast period, and close to the pre-2007 median as a share of revenue.
-
The primary balance (non-interest revenue minus non-interest spending) is expected to be in a better position than the pre-financial crisis median from 2028-29 onwards. It is forecast to improve from a 1.5 per cent of GDP deficit (£47 billion) in 2025-26 to a 1.7 per cent of GDP (£65 billion) surplus in 2031-32.
-
However, the debt-stabilising primary balance, which is the level of the primary balance at which debt remains constant as a share of GDP, is forecast to be a surplus which rises across the forecast period. By contrast, in both the pre-financial crisis period and the 2007-2019 period, governments could run deficits of 0.4 per cent of GDP and 1.5 per cent of GDP respectively, and still stabilise debt.
-
The difference between the primary balance and the debt-stabilising primary balance gives the debt stabilisation gap. This gap is positive until 2028-29, which means that debt is forecast to rise up to this year, but becomes negative from 2029-30 onwards due to the forecast improvement in the primary balance, which means that debt is forecast to be marginally falling in this period. The long-term trends and outlook for the debt-stabilising primary balance are discussed further in Box 7.1.
Table 7.3: Dashboard of balance sheet and fiscal affordability indicators
| Pre-2007 median | 2007-2019 median | Level (per cent of GDP, unless otherwise stated) | |||||||
|---|---|---|---|---|---|---|---|---|---|
| 2025-2026 | 2026-2027 | 2027-2028 | 2028-2029 | 2029-2030 | 2030-2031 | 2031-2032 | |||
| Balance sheet metrics | |||||||||
| PSND | 36.4 | 78.0 | 93.1 | 95.5 | 96.7 | 97.3 | 96.7 | 95.9 | 95.6 |
| PSND ex BoE | 36.4 | 73.7 | 88.9 | 92.4 | 93.8 | 94.7 | 94.3 | 94.2 | 94.0 |
| PSNFL | 29.7 | 67.5 | 81.4 | 83.2 | 83.8 | 83.8 | 83.1 | 82.3 | 81.7 |
| PSNW (inverted) | -12.5 | 52.9 | 62.5 | 63.3 | 63.4 | 63.1 | 62.2 | 61.0 | 59.8 |
| Financing and cost of debt metrics | |||||||||
| Central government net cash requirement | 2.6 | 4.4 | 4.4 | 4.6 | 4.3 | 4.4 | 2.4 | 3.2 | 2.8 |
| Net interest costs | 2.8 | 1.9 | 2.8 | 3.2 | 3.2 | 3.3 | 3.4 | 3.3 | 3.5 |
| Net interest costs (per cent of revenue) | 7.9 | 5.3 | 7.1 | 7.7 | 7.7 | 7.7 | 8.0 | 7.8 | 8.2 |
| Per cent of GDP | |||||||||
| Debt stabilisation metrics | |||||||||
| Debt-stabilising primary balance | -0.4 | -1.5 | 0.4 | 1.5 | 1.3 | 1.3 | 0.9 | 1.4 | 1.5 |
| Primary balance | 0.0 | -3.5 | -1.5 | -1.0 | -0.2 | 0.3 | 1.3 | 1.5 | 1.7 |
| Debt stabilisation gap | -1.1 | 1.2 | 2.0 | 2.5 | 1.4 | 0.9 | -0.4 | -0.1 | -0.2 |
| Year-on-year change in ratio to GDP | |||||||||
| Balance sheet metrics | |||||||||
| PSND | -1.4 | 2.2 | -0.3 | 2.4 | 1.2 | 0.6 | -0.6 | -0.8 | -0.3 |
| PSND ex BoE | -1.4 | 1.2 | 1.0 | 3.4 | 1.4 | 0.9 | -0.4 | -0.1 | -0.2 |
| PSNFL | -0.5 | 1.9 | 1.6 | 1.8 | 0.6 | 0.0 | -0.7 | -0.8 | -0.6 |
| PSNW (inverted) | 0.4 | 2.2 | -0.4 | 0.8 | 0.1 | -0.3 | -0.9 | -1.2 | -1.2 |
| Financing and cost of debt metrics | |||||||||
| Central government net cash requirement | 0.0 | -0.8 | -1.7 | 0.2 | -0.3 | 0.2 | -2.0 | 0.7 | -0.3 |
| Net interest costs | -0.1 | 0.0 | 0.0 | 0.3 | 0.1 | 0.0 | 0.1 | -0.1 | 0.2 |
| Net interest costs (per cent of revenue) | -0.1 | -0.1 | -0.1 | 0.6 | 0.0 | 0.0 | 0.3 | -0.2 | 0.4 |
| Note: Pre-2007 median is from 1967-68 to 2006-07. For year-on-year changes, medians are from 1968-69. Metrics are coloured depending on the pre-crisis decile they lie in, with green for the first to fourth decile, yellow and orange for the fifth to eighth decile and red for the ninth and 10th decile. PSNW has been inverted to facilitate comparisons with the other metrics. |
| Source: ONS, OBR |
Box 7.1: Long-term trends in the growth-corrected interest rate, “R-G”
A key indicator of fiscal sustainability is the growth-corrected interest rate, often referred to as ‘R-G’, which is the difference between the cost of servicing debt and the growth rate of the economy.a If the effective nominal interest rate (R) exceeds nominal GDP growth (G), so R-G is positive, then a primary surplus is required to stabilise debt as a share of GDP, all else equal. Conversely, when G exceeds R, and so R-G is negative, governments can, in principle, run a primary deficit without debt as a share of GDP rising. Together with the level of the debt stock and financial transactions, R-G determines the debt-stabilising primary balance.b When debt levels are high, a given positive level of R-G implies a larger debt-stabilising primary balance.
Chart A shows trends in R-G and the debt-stabilising primary balance since the Second World War. Up to the end of the 1970s, growth was consistently higher than the effective interest rate on government debt, and so R-G was negative, which meant that the debt-stabilising primary balance was very low at, on average, -5 per cent. This facilitated the rapid reduction in debt as a share of GDP seen over this period. The 1980s saw nominal growth rates fall below nominal interest rates, and so R-G turned positive. It remained positive for most years up to the financial crisis in 2008, with an average value of 1 per cent over the period. However, a low stock of debt meant the debt-stabilising primary balance averaged close to zero per cent of GDP.
Following the global financial crisis (GFC), the effective interest rate fell to an average of 3 per cent between 2009-10 and 2018-19, the lowest rate since the 1950s. While growth was also weak over much of this period, these very low interest rates meant that R-G turned negative, reaching -1.3 per cent in 2018-19. Despite this, debt levels rose, largely because the primary deficit averaged 2.1 per cent of GDP higher than the level required to keep debt stable.
Since 2022, interest rates have risen sharply and economic growth has remained subdued. As a result, R-G has increased from -3.5 per cent in 2022-23 to -1.1 per cent in 2025-26. Market interest rates are currently higher than the effective interest rate on the stock of debt, so as the debt stock is refinanced over time the effective interest rate will rise towards the market rate. This contributes to the forecast increase in R-G from -0.2 per cent in 2027-28 to 0.4 per cent in 2031-32.
This would be a return to the generally positive levels of R-G seen in the three decades leading up to the financial crisis, even though market interest rates are currently around 1.7 per cent lower than the post-war average. However, the level of debt is now much higher than in the pre-financial crisis period which, along with an increased use of financial transactions, increases the debt-stabilising primary balance for a given level of R-G. The debt-stabilising primary balance is expected to rise from 0.4 per cent of GDP in 2025-26 to 1.5 per cent by 2031-32, 3 percentage points higher than the 2007-2019 median (Table 7.3).
Chart A: Long-run UK debt dynamics: the growth-corrected interest rate and debt-stabilising primary balance
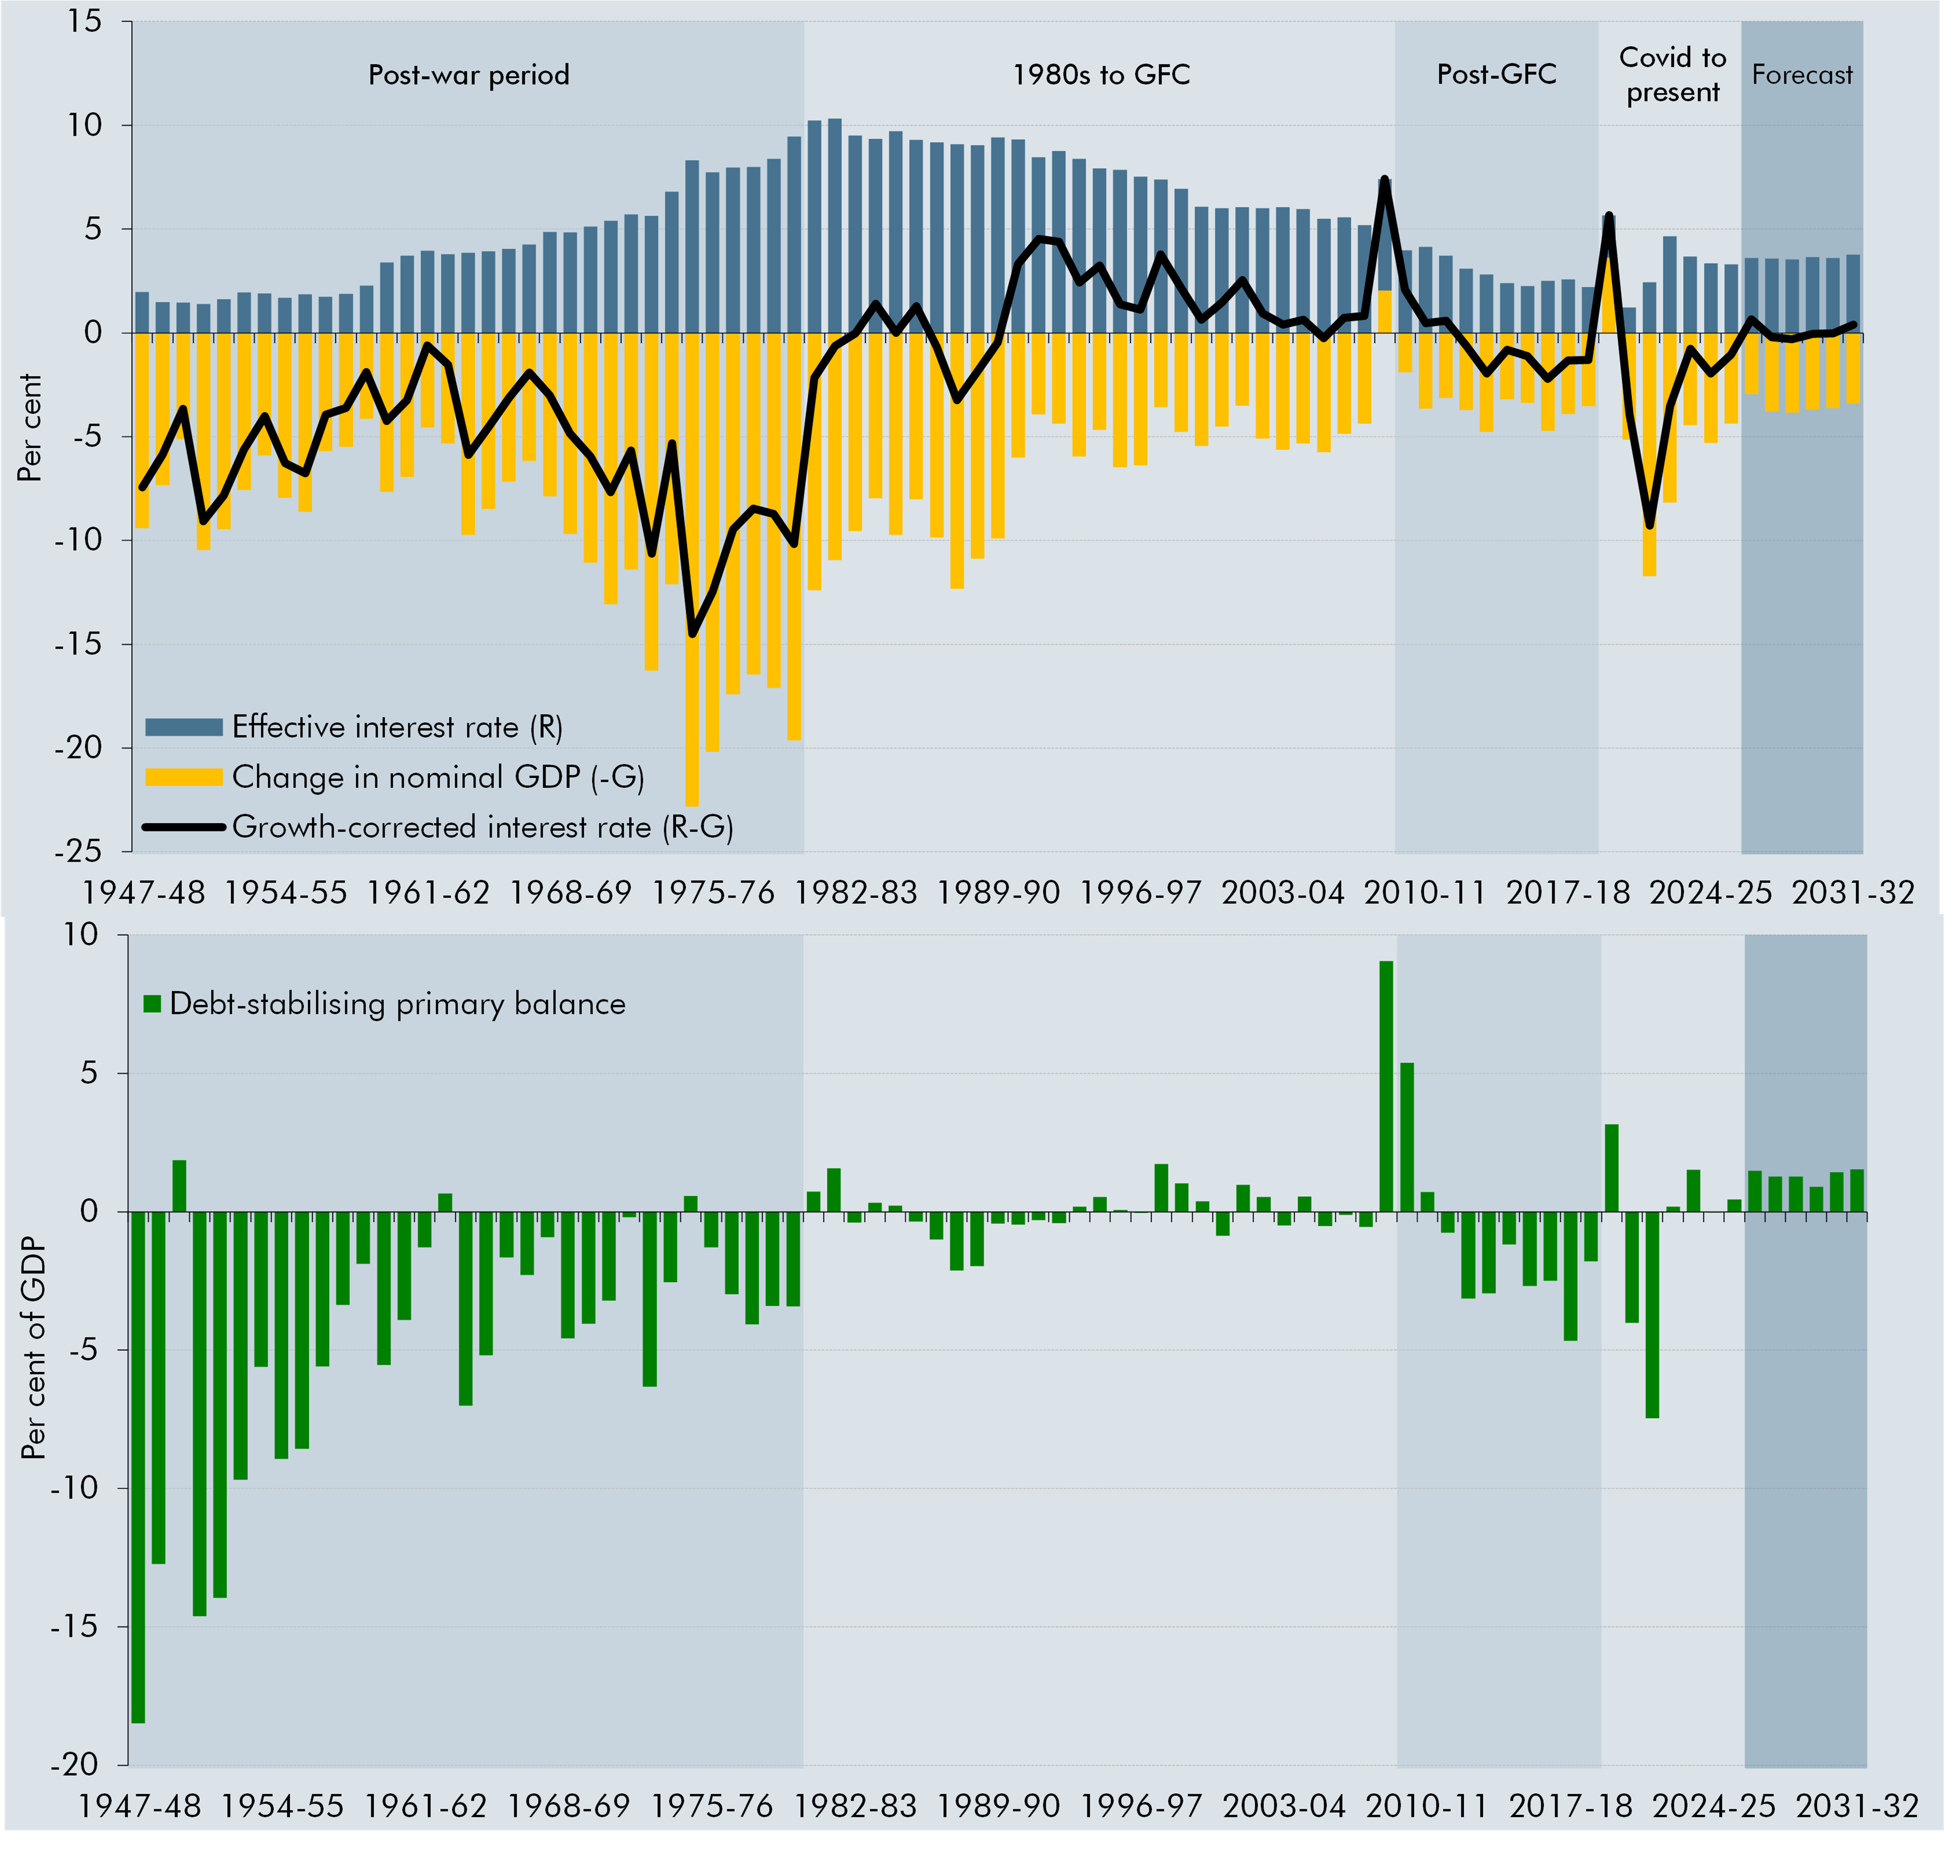
Note: The five periods cover: ‘Post-war’ (1947-48 to 1979-80), ‘1980s to GFC’ (1980-81 to 2008-09), ‘Post-GFC’ (2009-10 to 2018-19), ‘Covid to present’ (2019-20 to 2025-26), and ‘Forecast’ (2026-27 to 2031-32).
Source: ONS, OBR
‘R’ measured as the effective nominal interest rate, – the net interest payments as a percentage of PSND excluding the Bank of England. The year-on-year growth rate ‘G’ is nominal GDP growth on a March-centred basis.
Financial transactions average 0.8 per cent of GDP across the forecast, and partly explain why the UK requires a higher debt-stabilising primary balance than most peers.
Risk and uncertainty
7.28 All economic and fiscal forecasts are inherently subject to significant risk and uncertainty. It is inevitable that unforeseen events will drive economic and fiscal outcomes away from any central forecast. In recent years, large negative shocks, consistently weak GDP growth and significant policy changes have generated substantial revisions to forecasts from one fiscal event to the next. We use a range of tools to highlight this uncertainty and to meet the requirement in the Charter that we provide analysis of the risks surrounding the fiscal outlook. These include:
-
detailing specific risks to our economic and fiscal forecasts, focusing on those which appear most material at the time;
-
fan charts that reflect the chances of shocks of different sizes – through stochastic simulations and past central forecast deviations from outturns – to illustrate the uncertainty around key economic and fiscal variables, including, as set out in paragraphs 7.18 and 7.19, the fiscal aggregates targeted in the Government’s fiscal rules;
-
sensitivity analysis that shows the responsiveness of the path of the current budget deficit to changes in key forecast variables, including gilt yields and nominal GDP growth; and
-
scenarios that illustrate the potential channels through which changes in energy prices could affect the public finances.
Specific risks
7.29 The most important specific sources of risk to the economy forecast include:
-
The evolution of the Middle East conflict, and its implications for interest rates and inflation, which has sharply pushed up energy prices this year and led to disruption to wider international trade flows. Energy markets remain volatile – at the time of finalising this report, oil and gas futures pricing was close to the top of the range observed since the beginning of the Middle East conflict. From paragraph 7.33 onwards, we explain the results of a detailed set of scenarios that illustrate the potential economic and fiscal implications of alternative paths for energy prices. This highlights that the fiscal impact is particularly dependent on changes in financial conditions and the extent of the pass-through of an inflation shock to wages, which would serve to boost nominal tax bases. This is particularly important given that personal tax thresholds are currently frozen. In addition, any inflationary shock would create further pressure on departmental spending by eroding real-terms Spending Review settlements.
-
The outlook for productivity growth, a key driver of the economic and fiscal forecasts, is highly uncertain. The development and adoption of artificial intelligence could have a significant positive effect – our central forecast is for it to boost productivity growth by 0.2 percentage points a year by the medium term – but the scale and timing of any effect is highly uncertain. An additional uncertainty relates to challenges in accurately measuring historical productivity. As discussed in Box 2.2, ONS revisions to historical average hours suggest that UK productivity growth slowed after the financial crisis, but that the magnitude of the slowdown was closer to international comparators than previously suggested. This was driven by average hours growth being materially lower than previously estimated. Any change to the outlook for productivity could have a significant impact on the public finances. In the November 2025 EFO, we illustrated that if annual productivity growth were 0.5 percentage points higher or lower in the medium term than our central forecast, borrowing would be around £50 billion lower or £40 billion higher by 2030-31.
-
The outlook for the labour market, including from the effects of an ageing population and from migration, provides several sources of uncertainty. We assume that the ageing population will have a moderate adverse impact on average hours worked and labour market participation. However, the forecast for average hours worked is particularly uncertain due to recent historical revisions, as outlined above. There are also significant risks around the size and composition of future migration flows, given the post-Brexit change in migration regime and the recent spike and subsequent fall in net migration. In addition, there are risks around the outlook for unemployment. In the March 2026 EFO, we produced scenarios on the fiscal implications of alternative paths for the labour market. These suggested that if unemployment returned to its estimated equilibrium rate two years earlier than the central forecast, borrowing could be £16 billion a year lower on average, or if it instead peaked at a higher 6.8 per cent, borrowing could be an average of £20 billion a year higher than our central forecast.
7.30 There are also an additional set of specific fiscal and policy-related risks:
-
The cost of servicing government debt – which had already increased sharply since 2021 before rising further following the onset of the conflict in Iran. As explained in Chapter 2, UK government borrowing costs have been volatile recently with the 10-year yield ranging from around 4.5 to 5.5 per cent since March. But yields within this range are not unusual by historical standards. As a result of the recent rise in yields, debt interest spending is now forecast to rise to 4.2 per cent of GDP (£160 billion) in 2031-32, compared to 1.7 per cent of GDP (£39 billion) in 2019-20. Paragraph 7.32 sets out that a 1 percentage point change in gilt yields and Bank Rate expectations across the forecast in either direction could lead to an increase or decrease of £16 billion in the current budget deficit in the medium term.
-
There continue to be a wide range of pressures on departmental spending. These include higher inflation since March, which reduces real-terms departmental spending within fixed nominal spending limits, and the risk of higher-than-expected pay settlements. Beyond the current spending review, after accounting for spending commitments in areas including the NHS, defence and schools, the total spending assumptions currently set by the Government for the likely next spending review period imply ‘unprotected’ areas of day-to-day spending could face a 2.6 per cent a year real-terms reduction in the final three years of the forecast. Spending would have to be £11 billion higher in 2031-32 for ‘unprotected’ spending not to fall in real terms from 2028-29. The Government has set out a longer-term ambition to reform social care, which the Health Foundation previously estimated could cost between £3.5 billion and £17 billion a year.[footnote 91] The commitment to increase defence spending to 3.5 per cent of GDP by 2035 would cost around £35 billion in 2026-27 terms.
-
There is significant uncertainty around the outlook for welfare spending, especially on disability- and health-related benefits, where caseloads have increased sharply since the pandemic. We continue to assume that the caseloads will rise in the forecast, but at a slower rate than that seen to date. If caseloads were to continue to grow at their post-pandemic rate, spending in 2031-32 would be roughly £25 billion higher than in our central forecast in 2031-32, but if pre-pandemic rates were restored, then spending could be around £13 billion lower in 2031-32.
-
The forecast rise in the tax-to-GDP ratio accounts for around three-fifths of the current planned medium-term consolidation of the public finances. However, there are several risks around this forecast. Much of the increase is from rising income tax and national insurance contributions which is highly sensitive to growth in nominal earnings, especially with personal tax thresholds frozen until 2030-31. Capital taxes also account for a significant portion of the forecast rise, but they are highly dependent on future equity prices and are sensitive to behavioural responses from affected taxpayers who are more typically a more mobile part of the tax base. Further, the forecast assumes that the indexation of fuel duty and reversal of the 5p cut will be implemented in July 2027. The forecast also assumes the tax gap – a measure of tax compliance – will decline over the forecast period following the recent period where it has remained broadly flat after rising in the 2010s. More broadly, a higher level of tax take increases the risk that incentives within the tax system distort or constrain economic activity by more or less than expected.
7.31 Some steps have been taken to address previously identified fiscal risks. As discussed in more detail in Chapter 3, the Government has announced it will replace the state pension triple lock with an adjusted triple lock from April 2030 which should significantly reduce the projected increase in the cost of the state pension over the long term. Additionally, as set out above, the fiscal mandate now targets the third year of the forecast. This means that, from the next spending review, the Government will be required to have detailed spending allocations for the year in which the fiscal targets bind which should reduce the risks around meeting these targets.
Sensitivities
7.32 Sensitivity analysis estimates how unit changes to key forecast variables would, in isolation, affect the current budget deficit relative to our central forecast.[footnote 92] Chart 7.9 shows that:
-
A 0.1 percentage point reduction in nominal GDP growth from 2027-28 is estimated to increase the current budget deficit by £5 billion in 2029-30 and £9 billion in 2031-32.
-
A 1 percentage point reduction in the effective tax rate from 2027-28 is expected to increase the current budget deficit by £35 billion in 2029-30 and £38 billion in 2031-32, assuming no wider macroeconomic impacts.
-
A 1 percentage point increase in gilt yields on new debt issued and on Bank Rate expectations across the forecast period, directly via its effect on debt interest payments, is expected to increase the current budget deficit by £13 billion in 2029-30 and £16 billion in 2031-32.
-
A 1 percentage point rise in RPI and CPIH inflation in each year of the forecast period, via its effect on accrued interest on index-linked gilts alone, is expected to increase the current budget deficit by £9 billion in 2029-30 and £11 billion in 2031-32.[footnote 93]
Chart 7.9: Sensitivities of the current budget deficit to changes in selected variables
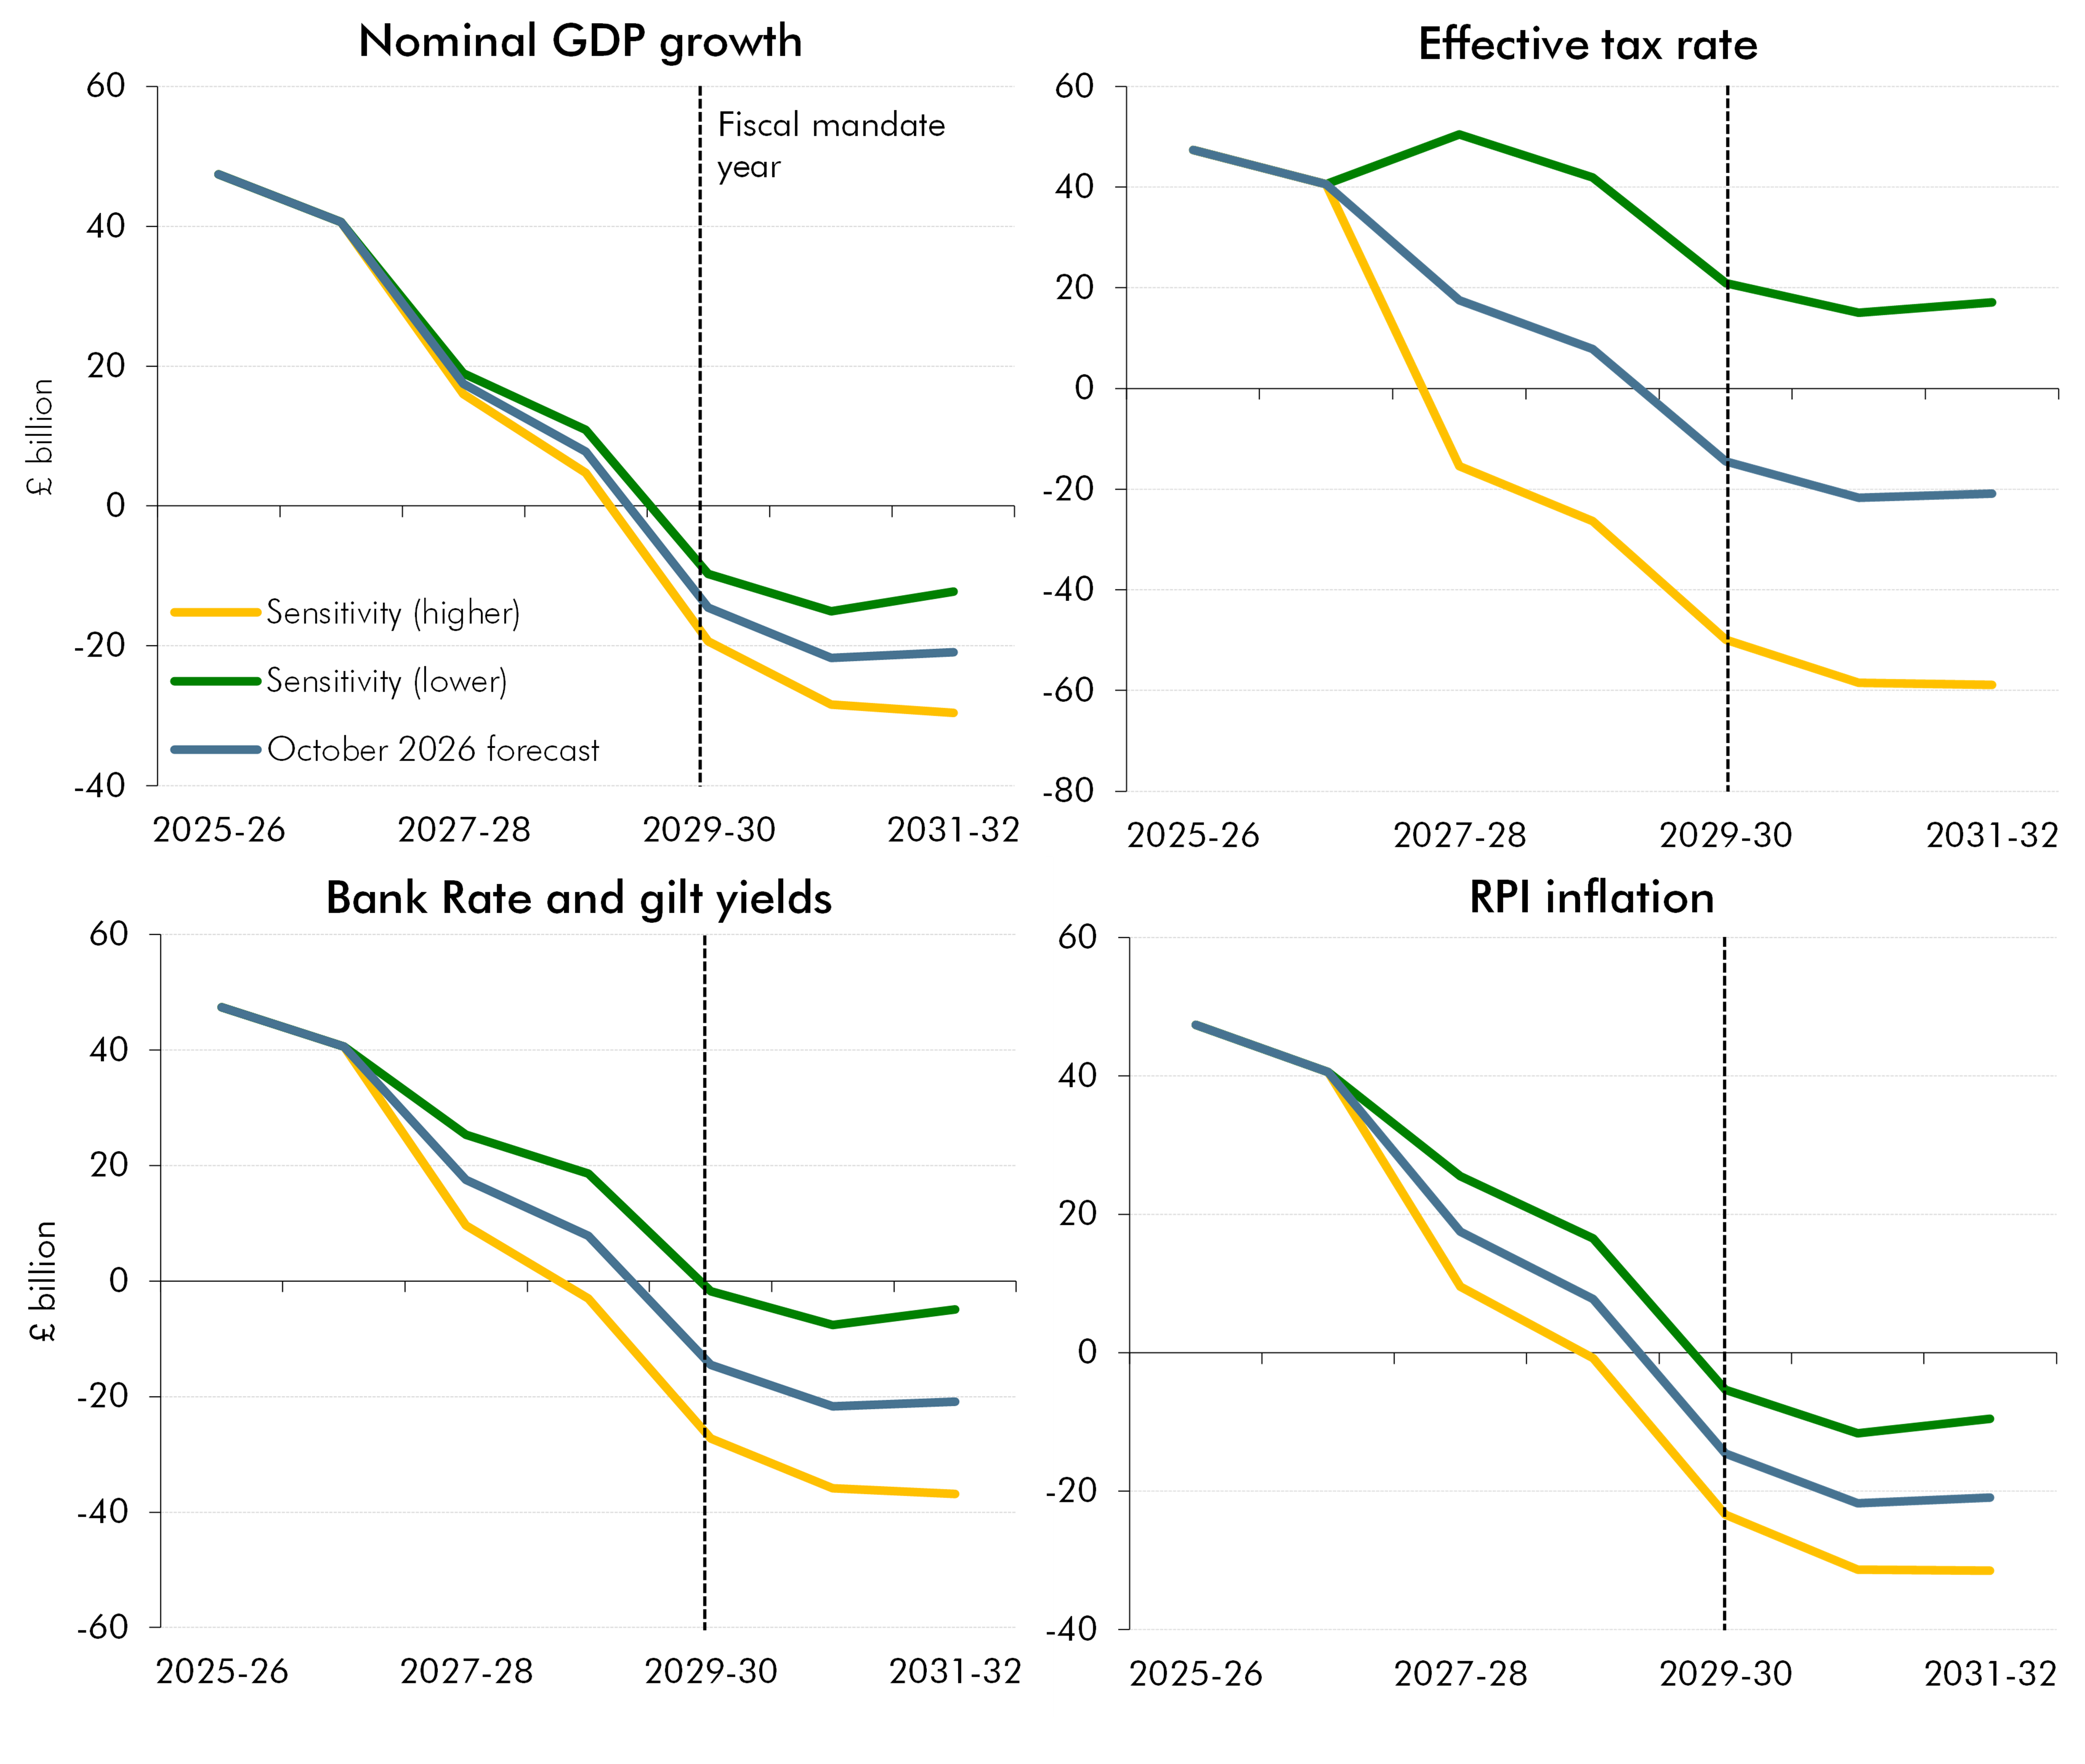
Note: All variables are to a 1 percentage point sensitivity, except nominal GDP growth which is to a 0.1 percentage point sensitivity.
Source: ONS, OBR
Scenarios
7.33 Energy prices have been volatile recently and their future evolution will be important to the economic and fiscal outlook, with significant implications for inflation, interest rates and GDP growth. To explore these factors, we present two alternative scenarios for energy prices, shown in Chart 7.10. The energy price paths are calibrated using an option-implied distribution of market pricing, taking one standard deviation above or below the central path implied by futures in the near term:
-
In our severe shock scenario, oil prices peak at around $115 a barrel in the first half of 2027 and the shock is more persistent than the market pricing in our central forecast, with prices remaining at or above $100 a barrel throughout 2027 and staying elevated until 2031. Gas prices reach a peak of 275 pence a therm, with prices remaining over 150 pence a therm throughout 2027 before gradually returning to the central forecast path. In both cases, the peak is near the highs observed following the 2022 Russian invasion of Ukraine.
-
In our orderly recovery scenario, oil and gas prices fall back more quickly than assumed in our central forecast, and converge on our March 2026 forecast path in the medium term. Oil prices reach a trough of around $55 a barrel in the second quarter of 2027 and gas prices a trough of around 55 pence a therm during the third quarter, and both return to their March 2026 forecast path in 2029.
Chart 7.10: Scenario oil and gas prices
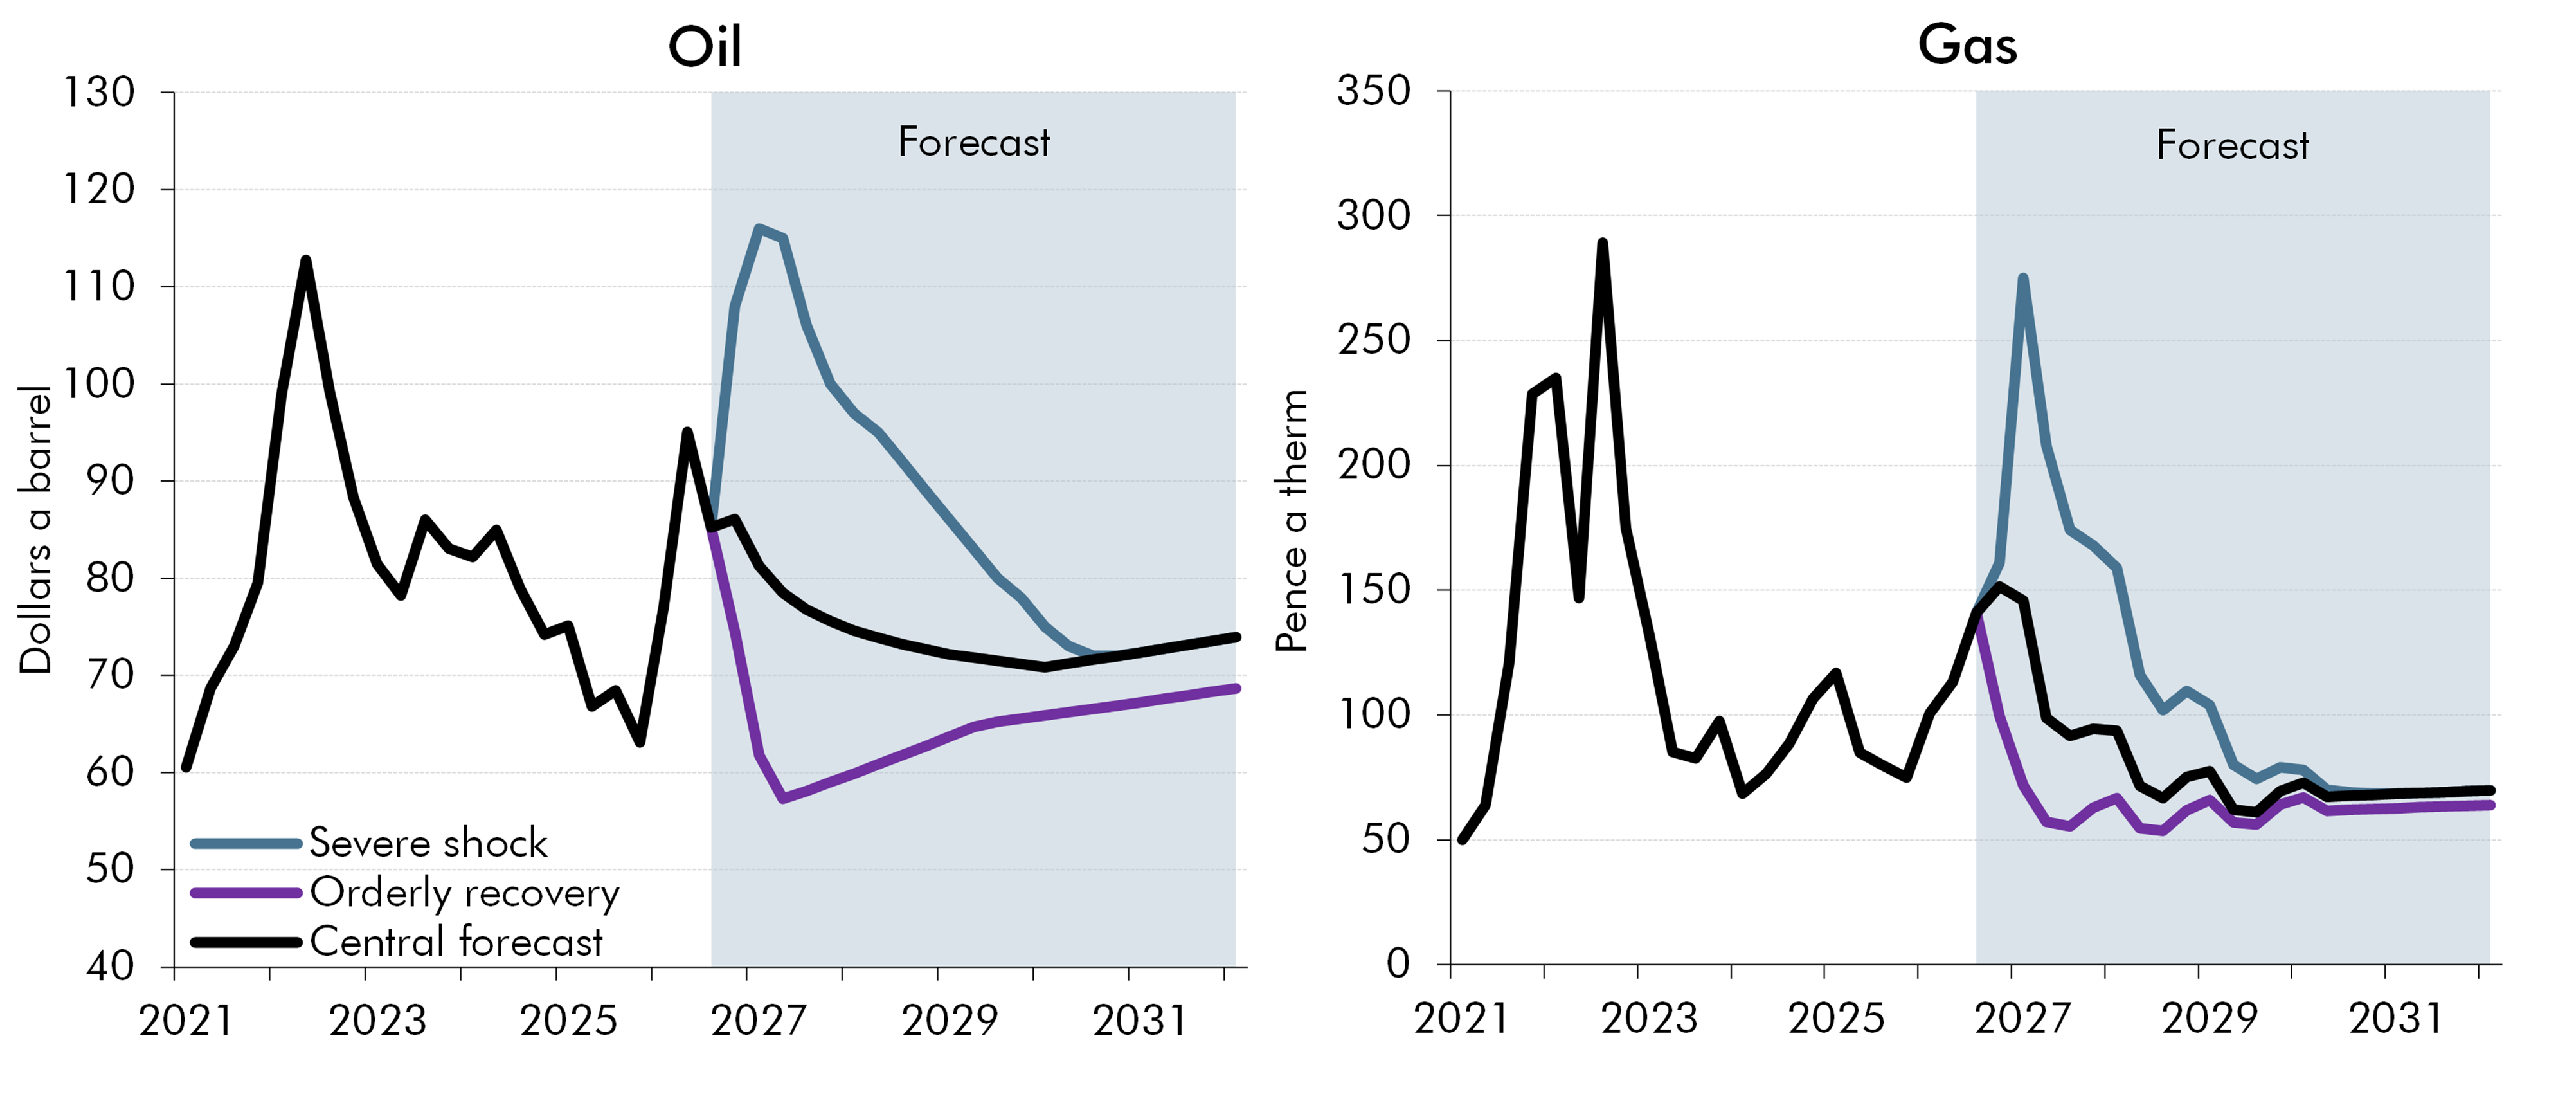
Note: Quarterly data, Q1 2021 to Q1 2032.
Source: Bloomberg, OBR
7.34 We take a layered approach to illustrate the potential channels through which these alternative paths may affect the economic and fiscal outlook, rather than providing a single estimate of the possible impact. In both scenarios, we first set out the potential direct impact on the economy and public finances, and then layer on the potential implications for interest rates and gilt yields. In the severe shock scenario, we set out further potential implications arising from second-round effects in inflation and increased pressures on departmental spending plans arising from higher inflation. The scenarios were informed by the Oxford Economics Global Economic Model, alongside our own judgement.
Severe shock
7.35 We set out four channels of potential impacts on the economy and public finances in the severe shock scenario (for which the key economic implications are shown in Chart 7.11):
-
The pure energy shock leads to a peak in CPI inflation of around 6 per cent next year – about 2¼ percentage points above our central forecast – and a reduction in GDP growth in 2027 to below ½ a per cent – ¾ of a percentage point below our central forecast. In 2031, the level of real GDP is ¼ per cent lower than in our central forecast, though the level of nominal GDP is slightly higher. RHDI per person is persistently lower than our central forecast, and only recovers to its pre-pandemic level after a decade, in 2029-30. By assumption, there is no adjustment in interest rates.
-
We then illustrate a potential tightening in financial conditions resulting from the shock. Relative to our central forecast, we assume an additional upward adjustment to Bank Rate of around 1 percentage point by the second half of 2027, and a persistent increase in gilt yields of around 1 percentage point.[footnote 94] This leads to a further reduction in real GDP growth in 2027.
-
Possible second-round effects increase nominal earnings growth by an average of ½ of a percentage point each year from 2027 to 2029, and CPI inflation by an average ¼ of a percentage point. This results in a further upward adjustment in Bank Rate and gilt yields and increases the size of the nominal economy and key tax bases. But it has little impact on the path of real GDP growth or RHDI per person. Both whether second-round effects emerge and their potential scale are highly uncertain.
-
We also illustrate the implied erosion in real departmental spending power due to the higher inflation. This is the additional spending that would be required to maintain the same real-terms value of departmental spending as in our central forecast. Any adjustment would not happen automatically as departmental spending limits are set in nominal terms and are a discretionary policy choice for the Government.
Chart 7.11: Severe shock scenario CPI inflation and real GDP growth
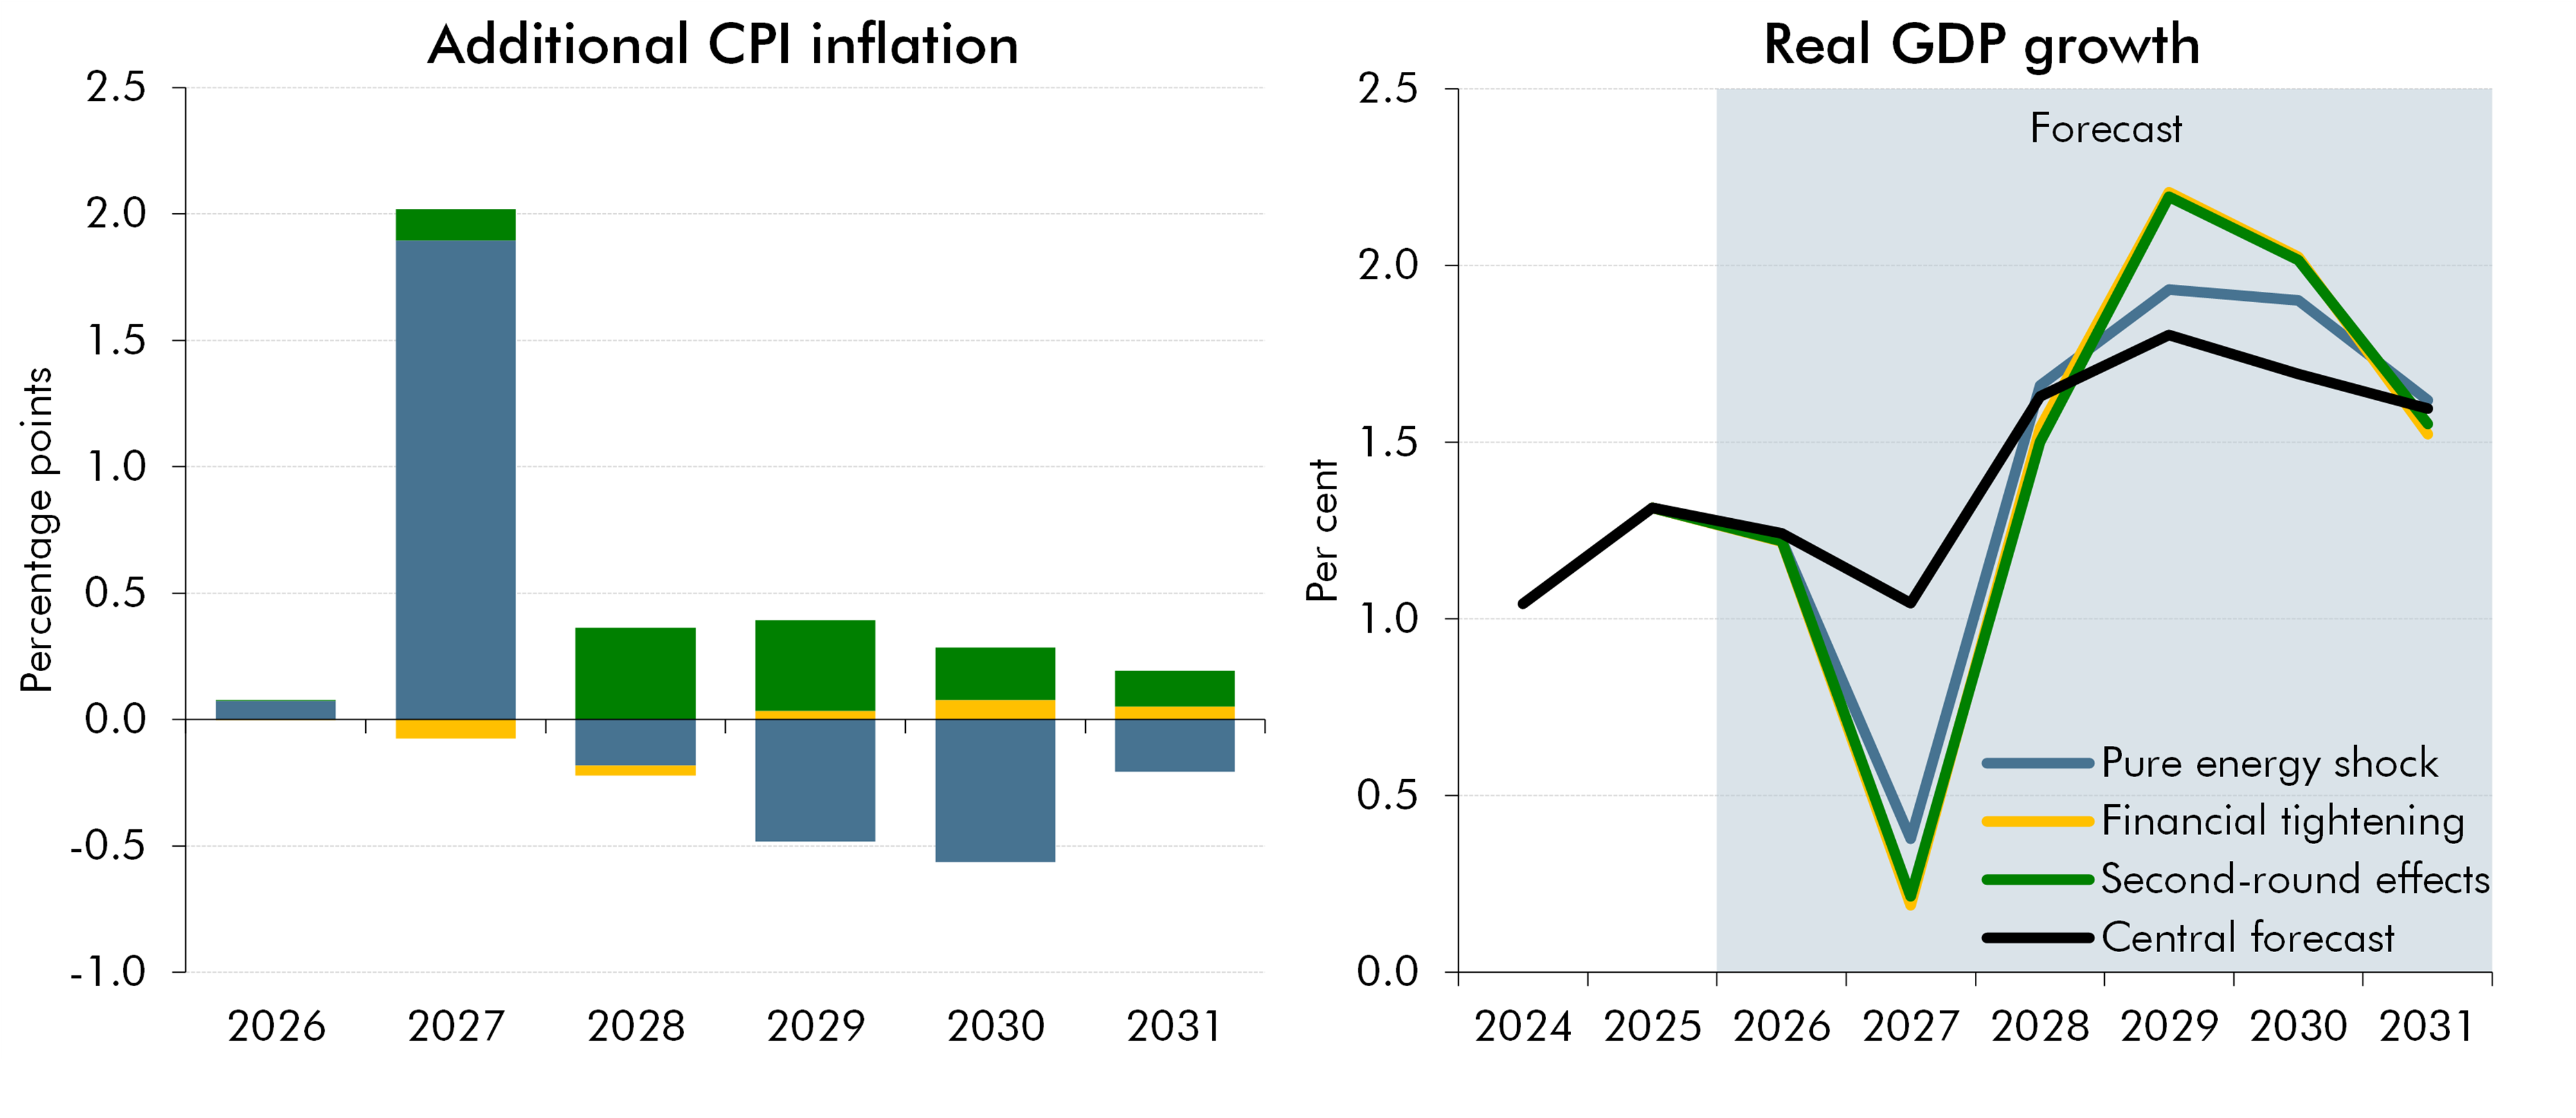
Source: ONS, OBR
7.36 Chart 7.12 shows the potential implications for borrowing from each of these different channels in the severe shock scenario relative to our central forecast:
-
The pure energy shock is estimated to add £7 billion to borrowing in 2027-28, as increased spending on index-linked gilts more than offsets higher oil and gas revenues. It adds £4 billion in 2031-32 as higher welfare spending more than offsets a small increase in receipts arising from a larger nominal economy.[footnote 95]
-
Tightening financial conditions could add a further £11 billion, on average, to borrowing over the forecast, due to higher debt interest costs.
-
Second-round effects could reduce borrowing by increasing amounts, reaching £13 billion in 2031-32, as domestically generated inflation from wages pushes up receipts by more than spending, particularly due to frozen personal tax thresholds.
-
Taken together, all these factors could increase borrowing by around £6 billion in 2031-32 relative to the central forecast. The pressures on the public finances would be compounded by a £13 billion erosion in real-terms departmental spending power.[footnote 96]
Chart 7.12: Severe shock scenario borrowing relative to central forecast
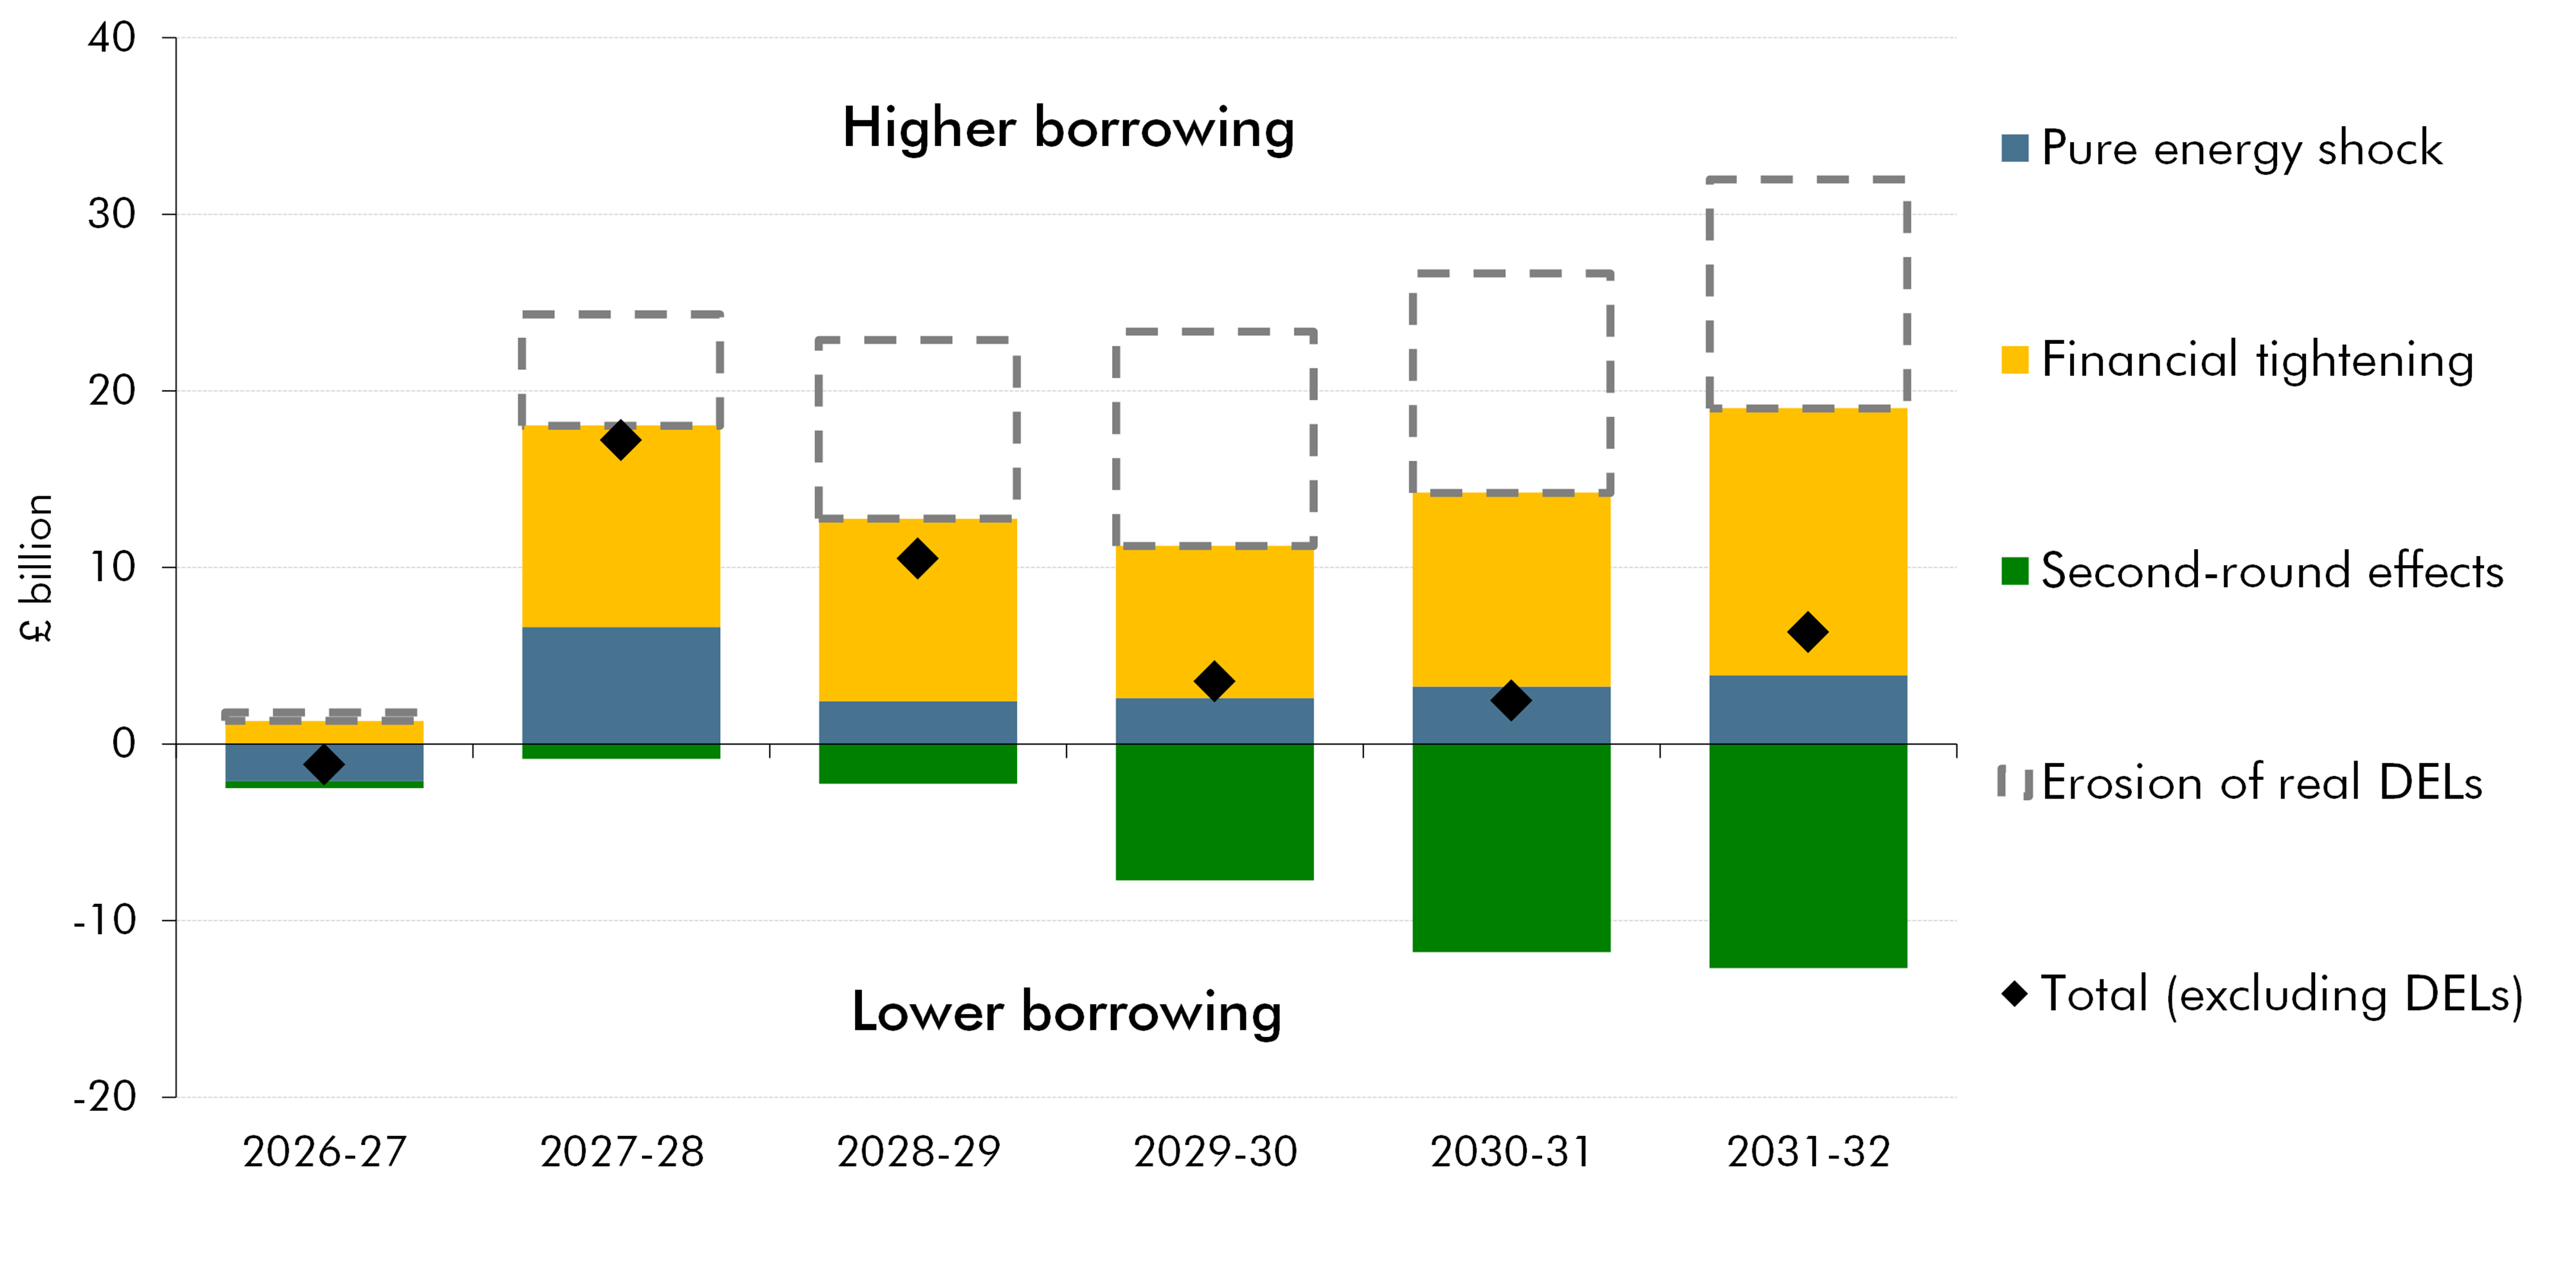
Source: OBR
Orderly recovery
7.37 We set out two channels of impact for the economy and public finances in the orderly recovery scenario.[footnote 97] The implications for CPI inflation and real GDP growth are shown in Chart 7.13:
-
The pure energy price fall results in more rapid disinflation than in our central forecast, with CPI inflation falling to 2¼ per cent in 2027 (1¼ percentage points lower than the central forecast). There is higher real GDP growth of 1½ per cent in 2027 (½ of a percentage point above our central forecast) while the lower inflation largely reverses the near-term decline in RHDI per person seen in our central forecast. By 2031, the level of real GDP is ¼ of a per cent higher than in our central forecast, while the level of nominal GDP is similar. As in the severe shock scenario, there is no adjustment in interest rates by assumption.
-
We assume that there is financial easing as the energy shock subsides, such that Bank Rate remains flat in 2027 before it largely converges with our central forecast by mid-2028.[footnote 98] Gilt yields are lower across the forecast period, as we assume there is around ½ of a percentage point reduction in the risk premium, taking gilt yields around halfway back to the March EFO forecast levels. This has only modest implications for real GDP growth.
Chart 7.13: Orderly recovery scenario CPI inflation and real GDP growth
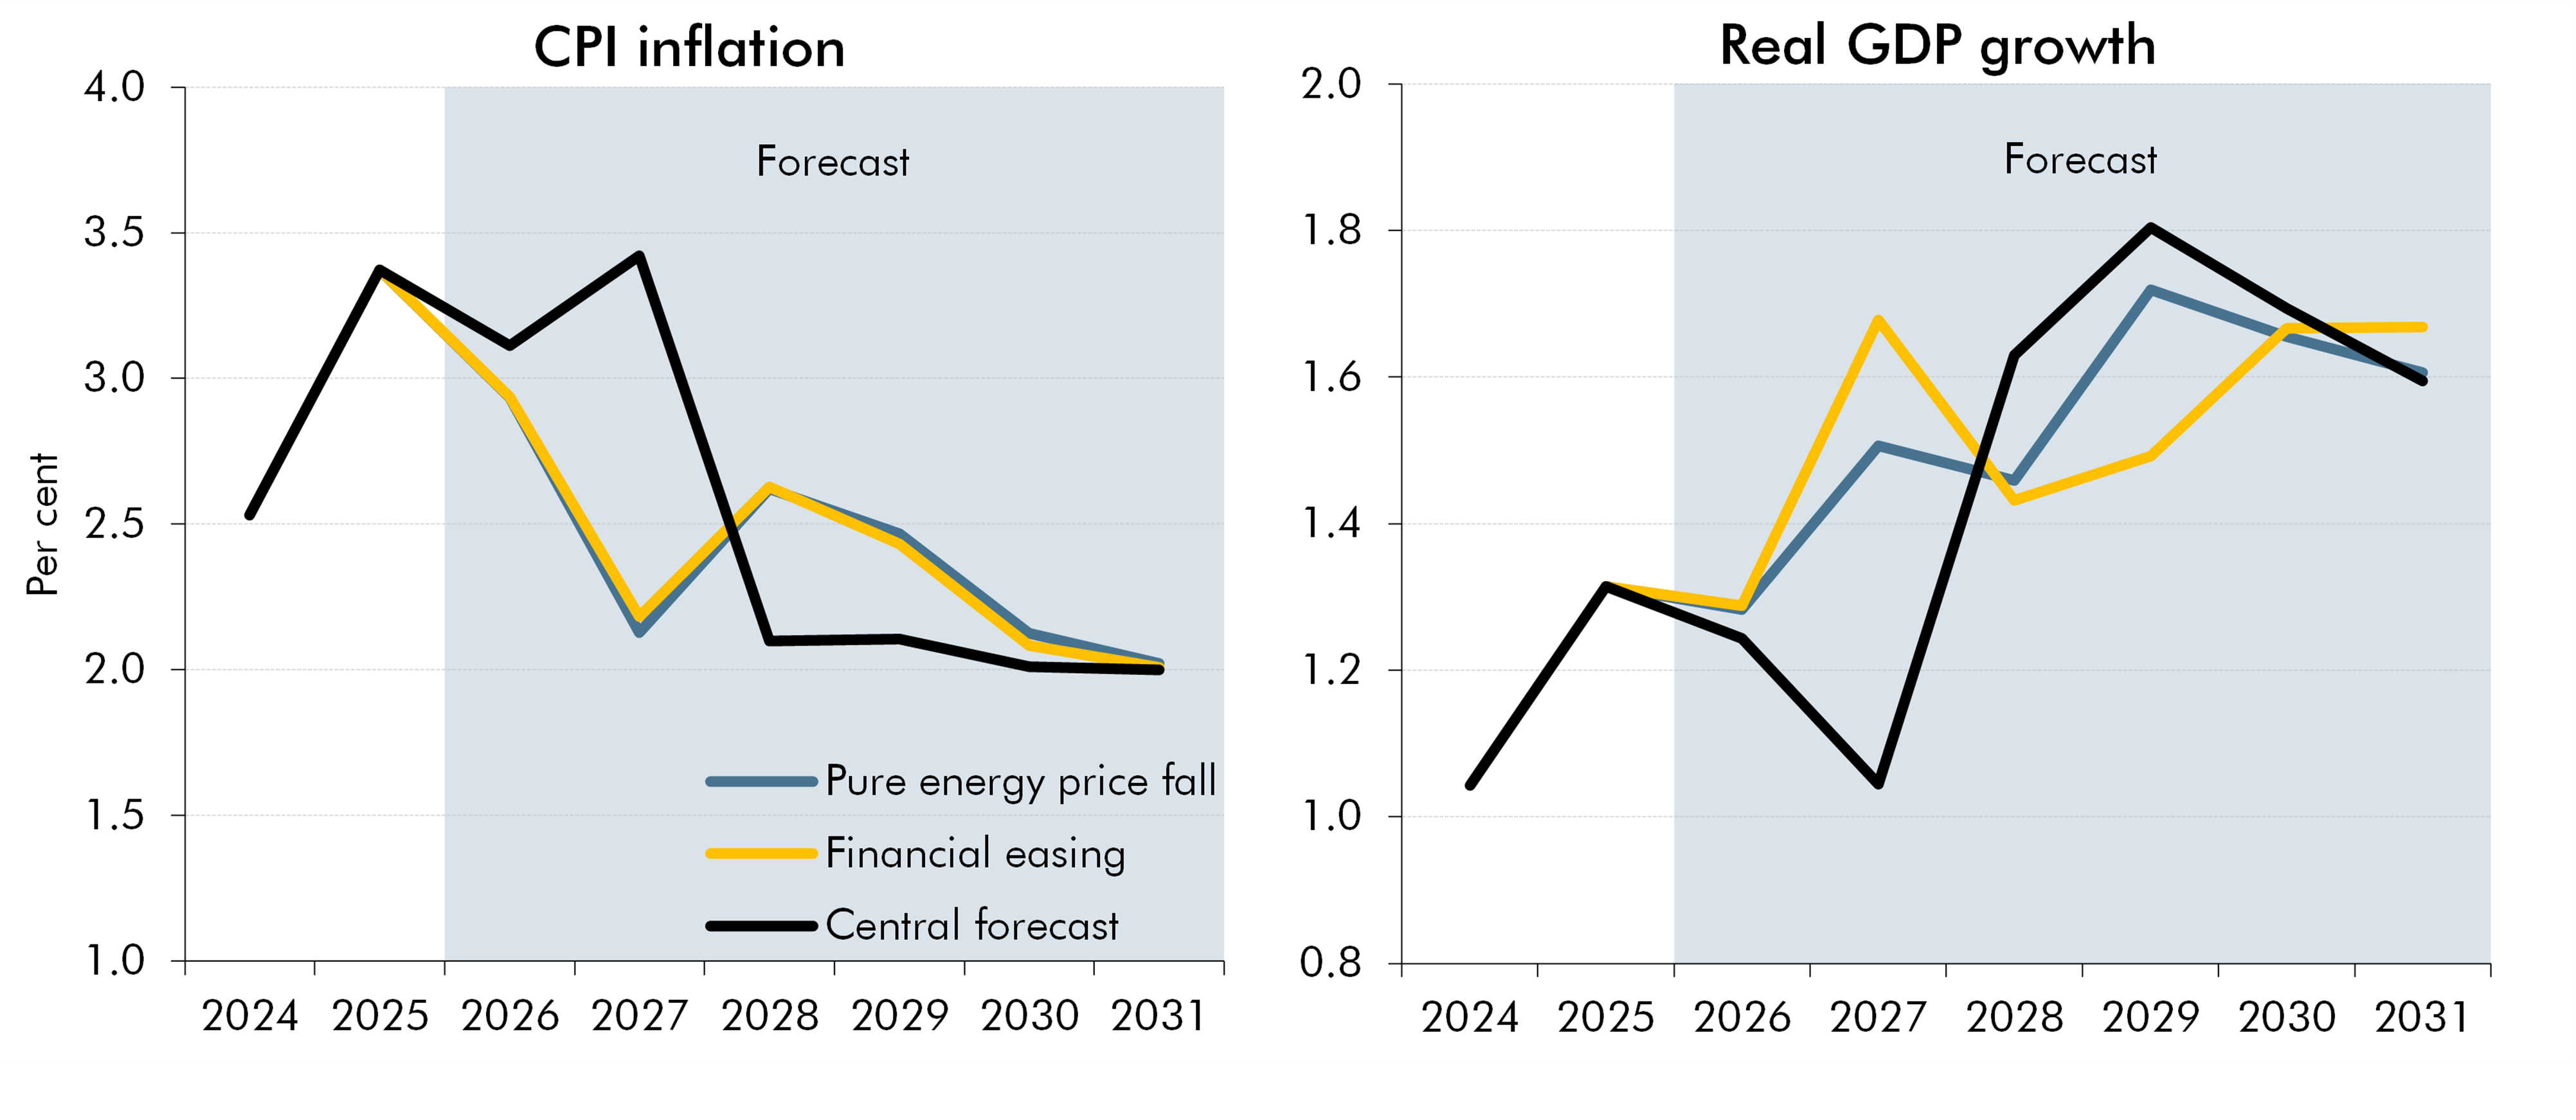
Source: ONS, OBR
7.38 Chart 7.14 shows the implications for PSNB of the orderly recovery scenario relative to our central forecast. These are modest compared to the severe shock scenario, as the near-term change in energy prices is smaller. The fiscal implications of the pure fall in energy prices largely track inflation. Lower inflation reduces debt interest spending on index-linked gilts in 2027-28, but then debt interest spending is marginally higher in the two subsequent years because inflation is slightly higher than in the central forecast. By 2031-32, borrowing is broadly unchanged, as lower welfare spending due to lower inflation offsets lower receipts from a smaller nominal economy. Financial easing further reduces borrowing by £5 billion on average over the forecast period, due to the lower path for Bank Rate and gilt yields.
Chart 7.14: Orderly recovery scenario borrowing relative to central forecast
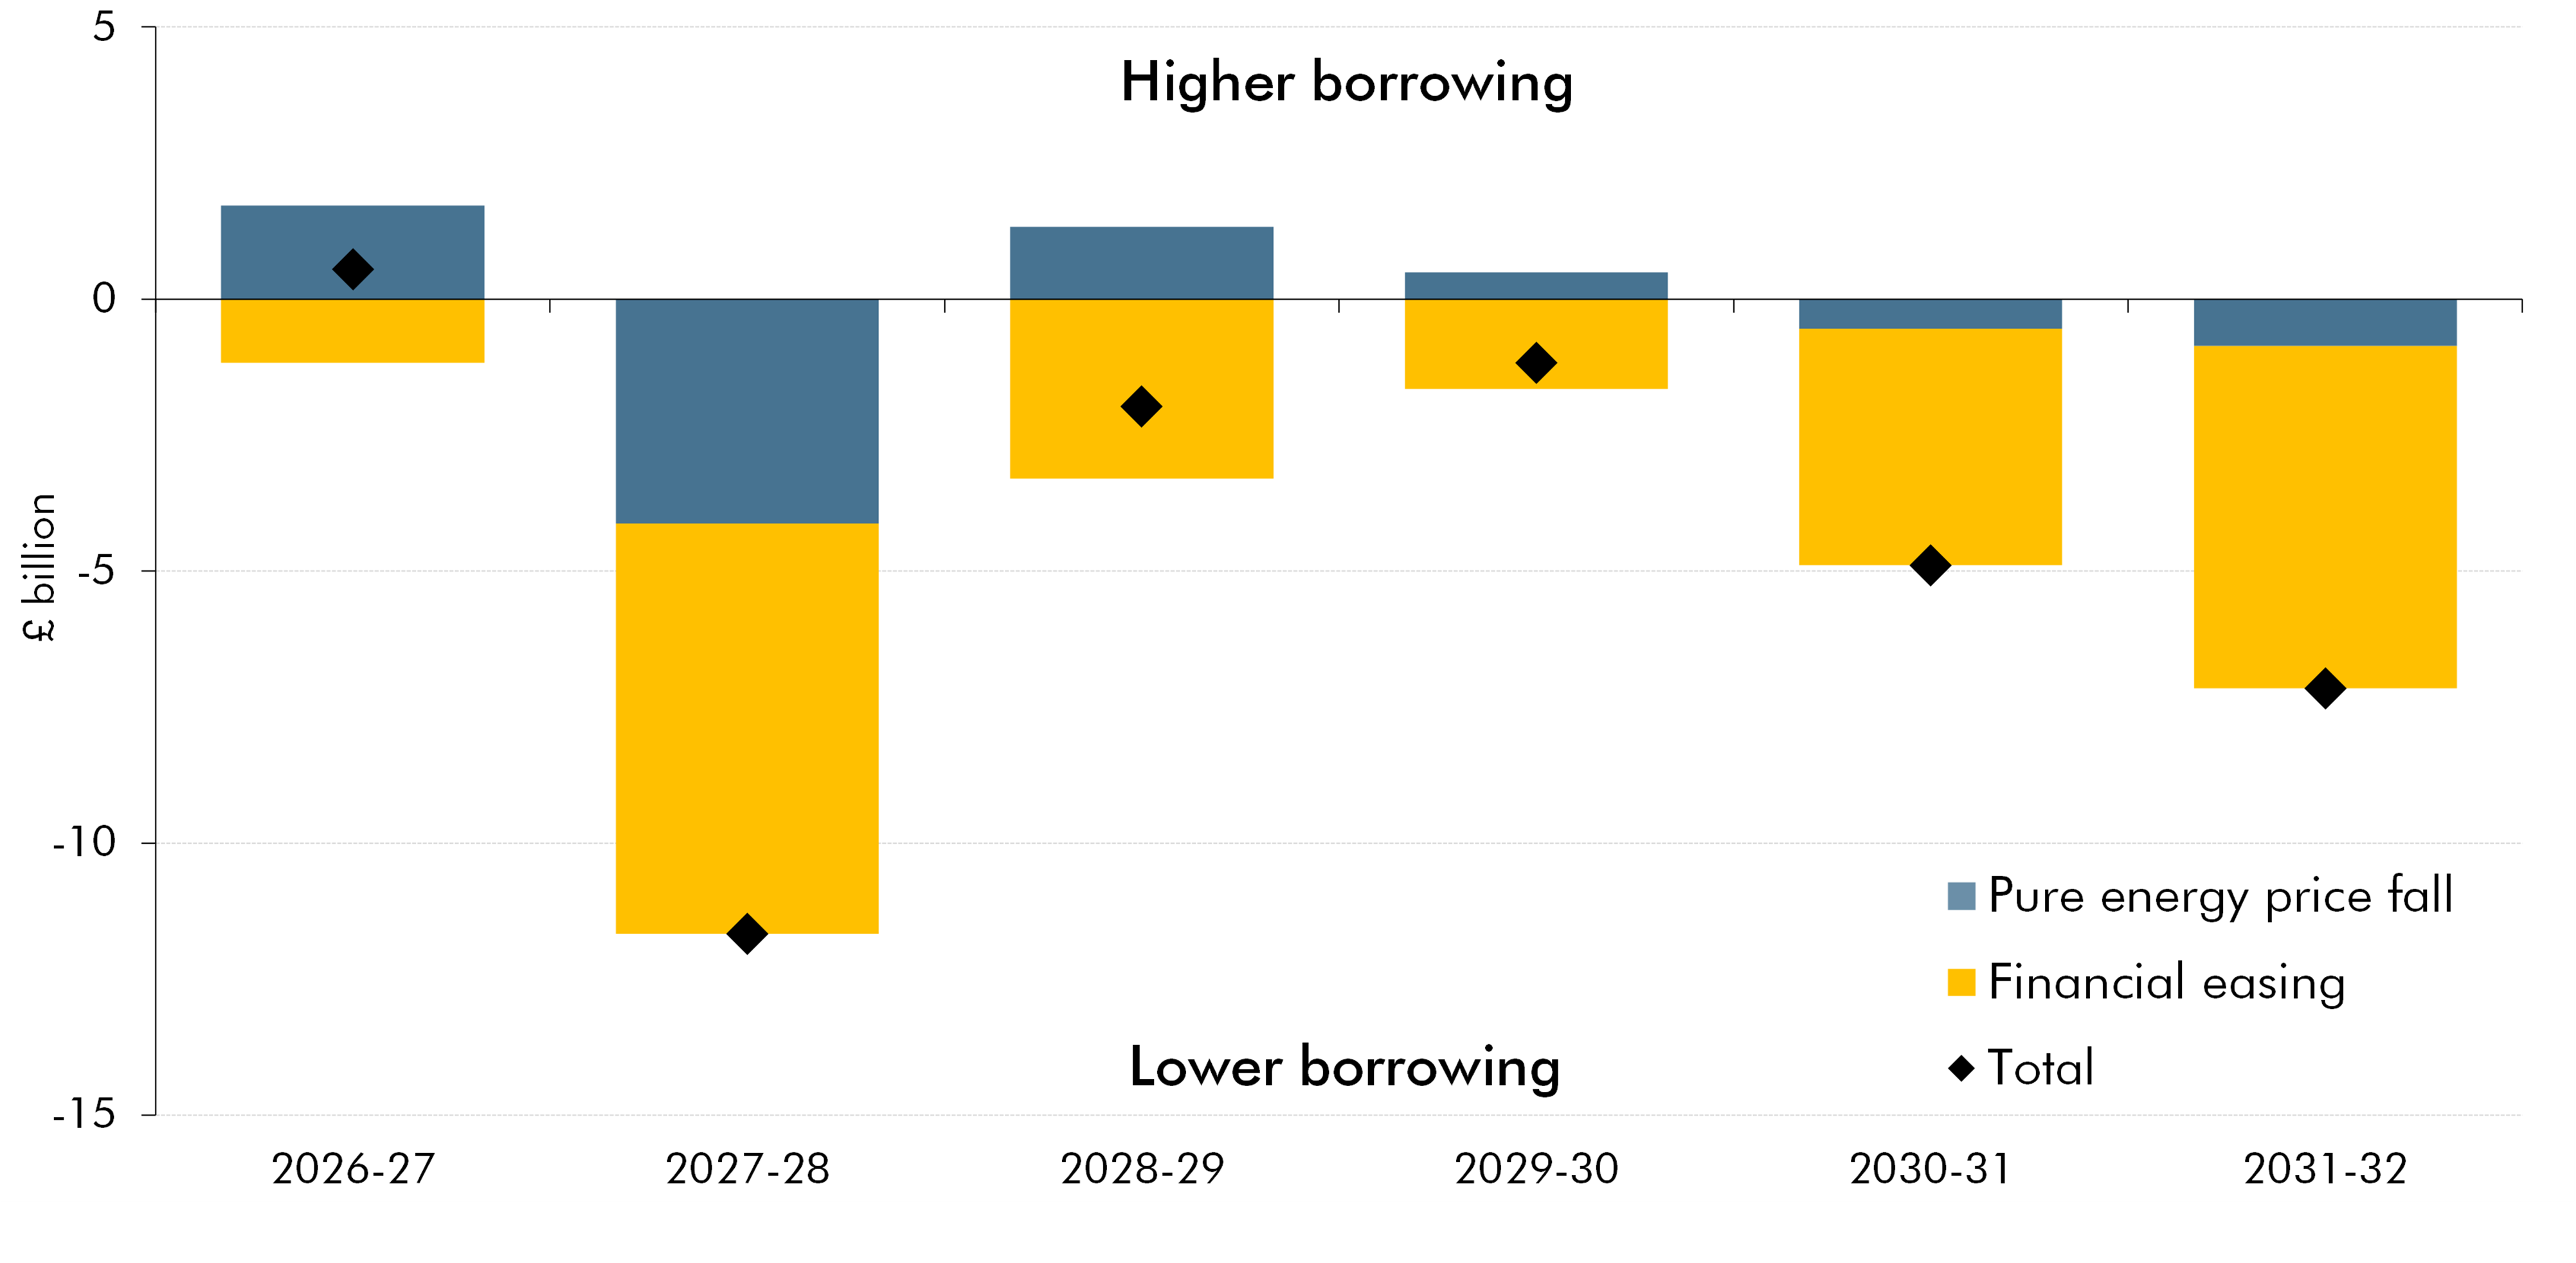
Source: OBR
Annex A: Detailed tables
A.1 This annex contains summary tables providing a detailed breakdown of the economy and fiscal forecasts described in this Economic and fiscal outlook. We also include changes since our March 2026 Economic and fiscal outlook. These tables include:
-
a detailed summary of our economy forecast and key determinants of the fiscal forecast;
-
public sector current receipts and individual taxes;
-
contributions to total managed expenditure;
-
the main fiscal aggregates; and
-
sources of year-on-year changes in balance sheet aggregates.
Table A.1: Economy forecast
| Percentage change on a year earlier, unless otherwise stated | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | |
| Potential output | |||||||
| Trend gross domestic product (GDP) | 1.7 | 1.6 | 1.0 | 1.3 | 1.5 | 1.5 | 1.5 |
| Trend productivity per hour | 0.7 | 0.9 | 0.7 | 1.0 | 1.1 | 1.1 | 1.1 |
| Trend labour supply | 1.1 | 0.7 | 0.3 | 0.3 | 0.3 | 0.4 | 0.4 |
| UK economy | |||||||
| GDP | 1.3 | 1.2 | 1.0 | 1.6 | 1.8 | 1.7 | 1.6 |
| GDP per person | 1.0 | 1.0 | 0.9 | 1.4 | 1.6 | 1.4 | 1.4 |
| GDP level (2019=100) | 105.4 | 106.7 | 107.8 | 109.6 | 111.5 | 113.4 | 115.2 |
| Nominal GDP | 5.0 | 4.2 | 3.2 | 3.6 | 3.8 | 3.7 | 3.6 |
| Output gap (per cent of potential output) | -0.7 | -1.1 | -1.0 | -0.7 | -0.3 | -0.1 | 0.0 |
| Expenditure components of GDP | |||||||
| Household consumption(1) | 1.1 | 1.0 | 0.6 | 1.7 | 2.0 | 1.7 | 1.6 |
| General government consumption | 1.7 | 2.2 | 0.9 | 1.3 | 1.3 | 1.7 | 1.8 |
| Fixed investment, of which: | 4.0 | 2.9 | 1.1 | 0.6 | 1.3 | 1.7 | 1.6 |
| Business | 4.3 | 0.0 | -0.5 | 1.0 | 1.2 | 1.2 | 1.3 |
| General government | 4.2 | 14.6 | 3.6 | -2.4 | -2.2 | -0.2 | 0.1 |
| Private dwellings(2) | 3.6 | 1.5 | 2.4 | 2.1 | 3.9 | 3.9 | 2.9 |
| Change in inventories(3) | -0.1 | 0.1 | -0.1 | 0.0 | 0.0 | 0.0 | 0.0 |
| Exports of goods and services | 1.9 | 1.1 | 1.4 | 1.0 | 1.0 | 1.1 | 1.1 |
| Imports of goods and services | 4.1 | 2.8 | 0.1 | 0.5 | 0.9 | 1.0 | 1.1 |
| Balance of payments current account | |||||||
| Per cent of GDP | -3.1 | -3.2 | -3.1 | -2.9 | -2.7 | -2.5 | -2.4 |
| Inflation | |||||||
| CPI | 3.4 | 3.1 | 3.4 | 2.1 | 2.1 | 2.0 | 2.0 |
| RPI | 4.1 | 3.6 | 4.3 | 3.0 | 3.0 | 2.3 | 2.2 |
| GDP deflator at market prices | 3.6 | 3.0 | 2.2 | 1.9 | 2.0 | 2.0 | 1.9 |
| Labour market | |||||||
| Employment (million) | 34.2 | 34.4 | 34.5 | 34.7 | 34.9 | 35.2 | 35.4 |
| Wages and salaries | 5.9 | 4.2 | 3.1 | 2.5 | 2.8 | 3.1 | 3.1 |
| Average weekly earnings(4) | 4.1 | 3.7 | 3.0 | 2.2 | 2.3 | 2.5 | 2.6 |
| Average hourly earnings | 4.5 | 3.7 | 2.9 | 2.3 | 2.4 | 2.7 | 2.7 |
| LFS unemployment rate (per cent) | 4.8 | 5.0 | 5.1 | 4.9 | 4.5 | 4.3 | 4.1 |
| Unemployment (million) | 1.7 | 1.8 | 1.9 | 1.8 | 1.7 | 1.6 | 1.5 |
| Household sector | |||||||
| Real household disposable income(1) | 0.9 | -0.6 | 0.2 | 0.9 | 0.7 | 1.1 | 1.0 |
| Saving rate (per cent)(1) | 9.7 | 8.7 | 8.2 | 7.4 | 6.3 | 5.7 | 5.2 |
| House prices | 2.6 | 2.1 | 2.4 | 2.8 | 2.8 | 2.7 | 2.7 |
| World economy | |||||||
| World GDP at purchasing power parity | 3.4 | 3.0 | 3.4 | 3.2 | 3.2 | 3.2 | 3.2 |
| 1) Includes households and non-profit institutions serving households. |
| 2) Includes transfer costs of non-produced assets. |
| 3) Contribution to GDP growth, percentage points. |
| 4) Wages and salaries divided by employees. |
Table A.2: Economy forecast changes since March
| Percentage point difference, unless otherwise stated | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | |
| Potential output | ||||||
| Trend gross domestic product (GDP) | 0.0 | 0.3 | -0.3 | 0.0 | 0.1 | 0.0 |
| Trend productivity per hour | -0.1 | 0.2 | -0.2 | 0.1 | 0.1 | 0.1 |
| Trend labour supply | 0.0 | 0.2 | -0.1 | -0.1 | -0.1 | -0.1 |
| UK economy | ||||||
| GDP | -0.1 | 0.1 | -0.5 | 0.0 | 0.3 | 0.2 |
| GDP per person | -0.1 | 0.3 | -0.4 | 0.2 | 0.4 | 0.3 |
| GDP level (per cent)(1) | -0.1 | 0.0 | -0.5 | -0.5 | -0.2 | 0.0 |
| Nominal GDP | -0.1 | 0.9 | -0.3 | 0.1 | 0.4 | 0.2 |
| Output gap | 0.0 | -0.2 | -0.5 | -0.5 | -0.3 | -0.1 |
| Expenditure components of GDP | ||||||
| Household consumption(2) | 0.2 | 0.1 | -0.9 | -0.1 | 0.1 | -0.1 |
| General government consumption | -0.1 | 0.0 | -0.8 | 0.0 | 0.3 | 0.1 |
| Fixed investment, of which: | 0.3 | 0.9 | -1.6 | -1.5 | 0.0 | 0.4 |
| Business | 0.1 | 0.9 | -0.9 | 0.2 | 0.2 | -0.1 |
| General government | 1.8 | 2.4 | -1.1 | -1.6 | -0.5 | -0.5 |
| Private dwellings(3) | 0.2 | -0.5 | -3.8 | -4.6 | 0.3 | 2.0 |
| Change in inventories(4) | -0.1 | 0.1 | -0.2 | 0.0 | 0.0 | 0.0 |
| Exports of goods and services | -0.4 | 1.1 | 1.1 | 0.3 | 0.1 | 0.2 |
| Imports of goods and services | 0.2 | 1.9 | -1.0 | -0.7 | -0.3 | -0.3 |
| Balance of payments current account | ||||||
| Per cent of GDP | -0.7 | -0.8 | -0.1 | 0.2 | 0.3 | 0.4 |
| Inflation | ||||||
| CPI | 0.0 | 0.8 | 1.5 | 0.1 | 0.1 | 0.0 |
| RPI | 0.0 | 0.5 | 1.3 | 0.3 | 0.1 | 0.0 |
| GDP deflator at market prices | -0.1 | 0.8 | 0.2 | 0.1 | 0.1 | 0.0 |
| Labour market | ||||||
| Employment (million) | 0.0 | 0.2 | 0.0 | -0.1 | -0.1 | -0.1 |
| Wages and salaries | -1.2 | 0.7 | 0.2 | -0.3 | 0.0 | 0.2 |
| Average weekly earnings(5) | -1.2 | 0.4 | 0.6 | 0.1 | 0.1 | 0.1 |
| Average hourly earnings | -1.3 | 0.5 | 0.6 | 0.0 | 0.1 | 0.1 |
| LFS unemployment rate | 0.0 | -0.3 | 0.2 | 0.4 | 0.3 | 0.1 |
| Unemployment (million) | 0.0 | -0.1 | 0.1 | 0.2 | 0.1 | 0.0 |
| Household sector | ||||||
| Real household disposable income(2) | -0.1 | -1.3 | -0.5 | 0.2 | 0.0 | 0.2 |
| Saving rate(2) | -0.4 | -1.2 | -0.9 | -0.7 | -0.9 | -0.5 |
| House prices | -0.1 | -0.3 | -0.5 | 0.1 | 0.2 | 0.3 |
| World economy | ||||||
| World GDP at purchasing power parity | 0.1 | -0.1 | 0.2 | 0.0 | 0.0 | 0.0 |
| 1) GDP is indexed to 2019=100. |
| 2) Includes households and non-profit institutions serving households. |
| 3) Includes transfer costs of non-produced assets. |
| 4) Contribution to GDP growth, percentage points. |
| 5) Wages and salaries divided by employees. |
Table A.3: Determinants of the fiscal forecast
| Percentage change on previous year, unless otherwise stated | Growth over forecast | |||||||
|---|---|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | ||
| GDP and its components | ||||||||
| Real GDP | 1.1 | 1.3 | 1.1 | 1.7 | 1.8 | 1.7 | 1.6 | 9.5 |
| Nominal GDP(1) | 4.6 | 3.6 | 3.5 | 3.7 | 3.8 | 3.7 | 3.5 | 23.8 |
| Nominal GDP (£ billion)1,2 | 3,070 | 3,180 | 3,291 | 3,414 | 3,543 | 3,673 | 3,802 | 732 |
| Nominal GDP (centred end-March £bn)1,3 | 3,135 | 3,227 | 3,350 | 3,478 | 3,607 | 3,738 | 3,864 | 729 |
| Wages and salaries | 5.0 | 4.0 | 2.9 | 2.6 | 2.9 | 3.2 | 3.0 | 20.0 |
| Non-oil PNFC profits(4) | 3.4 | 5.3 | 4.3 | 5.2 | 4.4 | 4.1 | 4.0 | 30.5 |
| Consumer spending(4) | 4.6 | 3.8 | 3.7 | 3.9 | 4.1 | 3.7 | 3.6 | 25.2 |
| Prices and earnings | ||||||||
| GDP deflator | 3.4 | 2.6 | 2.1 | 2.0 | 2.0 | 2.0 | 1.9 | 13.2 |
| RPI | 4.2 | 3.8 | 4.0 | 2.9 | 3.0 | 2.1 | 2.2 | 19.4 |
| CPI | 3.4 | 3.3 | 3.1 | 2.0 | 2.1 | 2.0 | 2.0 | 15.4 |
| Average weekly earnings(5) | 3.6 | 3.6 | 2.9 | 2.1 | 2.3 | 2.5 | 2.6 | 17.1 |
| ‘Triple-lock’ guarantee(6) | 4.8 | 3.9 | 3.4 | 2.5 | 2.5 | 2.5 | 2.6 | 18.7 |
| Key fiscal determinants | ||||||||
| Employment (million) | 34.3 | 34.5 | 34.5 | 34.7 | 35.0 | 35.2 | 35.4 | 1.2 |
| Output gap (per cent of potential output) | -0.8 | -1.1 | -0.9 | -0.6 | -0.3 | -0.1 | 0.0 | 0.8 |
| Financial and property sectors | ||||||||
| Equity prices (FTSE All-Share index) | 5,085 | 5,660 | 5,844 | 6,062 | 6,291 | 6,522 | 6,751 | 1,666 |
| HMRC financial sector profits1,7 | 6.9 | 10.0 | 4.4 | 4.5 | 4.2 | 4.2 | 4.1 | 35.7 |
| Residential property prices(8) | 1.9 | 2.4 | 2.6 | 2.8 | 2.7 | 2.7 | 2.7 | 17.1 |
| Residential property transactions (000)(9) | 1,140 | 1,180 | 1,204 | 1,235 | 1,270 | 1,304 | 1,332 | 192 |
| Commercial property prices(9) | 3.2 | -3.7 | 3.8 | 2.0 | 2.0 | 2.0 | 1.9 | 8.0 |
| Commercial property transactions(9) | -0.1 | -0.8 | 1.8 | 1.7 | 1.8 | 1.7 | 1.6 | 8.0 |
| Oil and gas | ||||||||
| Oil prices ($ a barrel)(4) | 68.4 | 85.8 | 78.0 | 73.6 | 71.7 | 71.4 | 72.9 | 4.6 |
| Oil prices (£ a barrel)(4) | 51.9 | 63.7 | 57.7 | 54.4 | 53.0 | 52.8 | 53.9 | 2.1 |
| Gas prices (pence a therm)(4) | 89.2 | 126.6 | 107.7 | 76.8 | 67.6 | 69.0 | 68.9 | -20.3 |
| Oil production (million tonnes)(4) | 31.2 | 28.5 | 26.2 | 23.9 | 21.7 | 19.8 | 18.2 | -13.0 |
| Gas production (billion therms)(4) | 10.1 | 9.3 | 8.4 | 7.3 | 6.2 | 5.4 | 4.7 | -5.4 |
| Interest rates and exchange rates | ||||||||
| Bank Rate (per cent) | 4.0 | 3.9 | 4.8 | 4.8 | 4.7 | 4.7 | 4.8 | 0.8 |
| Market gilt rates (per cent)(10) | 4.4 | 5.1 | 5.4 | 5.6 | 5.7 | 5.9 | 6.0 | 1.6 |
| Euro/sterling exchange rate (€/£) | 1.16 | 1.17 | 1.17 | 1.17 | 1.17 | 1.17 | 1.17 | 0.01 |
| 1) Non-seasonally adjusted. |
| 2) Denominator for receipts, spending, and deficit forecasts as a share of GDP. |
| 3) Denominator for PSND and PSNFL as a share of GDP. |
| 4) Calendar year. |
| 5) Wages and salaries divided by employees. |
| 6) Highest of 2.5 per cent, Q2 earnings growth, and Q3 CPI inflation, which is then used to uprate the state pension in the following year. |
| 7) HMRC Gross Case 1 trading profits; 2025-26 is forecast. |
| 8) Outturn data from ONS House Price Index. |
| 9) Outturn data from HMRC information on stamp duty land tax. |
| 10) Weighted average interest rate on conventional gilts. |
Table A.4: Determinants of the fiscal forecast: changes since March
| Percentage point difference, unless otherwise stated | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| GDP and its components | ||||||
| Real GDP | -0.1 | 0.0 | -0.5 | 0.2 | 0.3 | 0.1 |
| Nominal GDP(1) | 0.5 | 0.0 | -0.1 | 0.3 | 0.4 | 0.1 |
| Nominal GDP (£ billion)1,2 | 15.1 | 15.8 | 14.1 | 23.4 | 36.3 | 41.2 |
| Nominal GDP (centred end-March £bn)1,3 | 36.1 | 7.4 | 16.2 | 30.8 | 39.6 | 41.0 |
| Wages and salaries | -1.0 | 0.8 | 0.0 | -0.2 | 0.1 | 0.3 |
| Non-oil PNFC profits(4) | 2.4 | 2.0 | 0.3 | 1.2 | 0.4 | 0.1 |
| Consumer spending(4) | -0.2 | 0.7 | 0.2 | 0.1 | 0.2 | -0.1 |
| Prices and earnings | ||||||
| GDP deflator | 0.2 | 0.6 | 0.2 | 0.1 | 0.1 | 0.0 |
| RPI | 0.0 | 0.9 | 1.1 | 0.1 | 0.1 | 0.1 |
| CPI | 0.0 | 1.3 | 1.1 | 0.0 | 0.1 | 0.0 |
| Average weekly earnings(5) | -1.0 | 0.4 | 0.7 | 0.0 | 0.1 | 0.1 |
| ‘Triple-lock’ guarantee(6) | 0.0 | 0.2 | 0.9 | 0.0 | 0.0 | 0.0 |
| Key fiscal determinants | ||||||
| Employment (million) | 0.0 | 0.2 | 0.0 | -0.1 | -0.1 | -0.1 |
| Output gap | 0.0 | -0.3 | -0.5 | -0.5 | -0.2 | -0.1 |
| Financial and property sectors | ||||||
| Equity prices (per cent difference in level) | 0.4 | 1.6 | 1.3 | 1.5 | 1.9 | 2.0 |
| HMRC financial sector profits1,7 | 0.0 | 7.7 | -0.2 | 0.0 | 0.0 | 0.0 |
| Residential property prices(8) | -0.2 | -0.5 | -0.3 | 0.1 | 0.2 | 0.4 |
| Residential property transactions (000)(9) | 6.5 | -45.6 | -57.2 | -60.7 | -54.8 | -44.0 |
| Commercial property prices(9) | 0.7 | -6.1 | 2.0 | 0.1 | 0.1 | 0.0 |
| Commercial property transactions(9) | 1.2 | -2.0 | 0.2 | 0.2 | 0.3 | 0.1 |
| Oil and gas | ||||||
| Oil prices ($ a barrel)(4) | 0.0 | 22.8 | 15.4 | 9.8 | 6.6 | 5.0 |
| Oil prices (£ a barrel)(4) | 0.0 | 16.8 | 11.1 | 7.0 | 4.6 | 3.4 |
| Gas prices (pence a therm)(4) | 0.0 | 52.6 | 43.3 | 16.4 | 5.5 | 7.2 |
| Oil production (million tonnes)(4) | -0.1 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Gas production (billion therms)(4) | 0.1 | 0.0 | -0.1 | 0.0 | 0.0 | 0.0 |
| Interest rates and exchange rates | ||||||
| Bank Rate | 0.0 | 0.5 | 1.2 | 1.1 | 0.8 | 0.7 |
| Market gilt rates(10) | 0.0 | 0.6 | 0.7 | 0.6 | 0.5 | 0.5 |
| Euro/sterling exchange rate (€/£) | 0.00 | 0.02 | 0.02 | 0.02 | 0.02 | 0.02 |
| 1) Non-seasonally adjusted. |
| 2) Denominator for receipts, spending, and deficit forecasts as a share of GDP. |
| 3) Denominator for PSND and PSNFL as a share of GDP. |
| 4) Calendar year. |
| 5) Wages and salaries divided by employees. |
| 6) Highest of 2.5 per cent, Q2 earnings growth, and Q3 CPI inflation, which is then used to uprate the state pension in the following year. |
| 7) HMRC Gross Case 1 trading profits; 2025-26 is forecast. |
| 8) Outturn data from ONS House Price Index. |
| 9) Outturn data from HMRC information on stamp duty land tax. |
| 10) Weighted average interest rate on conventional gilts. |
Table A.5: Current receipts
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Income tax(1) | 329.3 | 365.4 | 392.2 | 403.8 | 426.4 | 444.5 | 463.7 |
| of which: Pay as you earn | 280.5 | 302.5 | 316.2 | 329.6 | 347.3 | 362.2 | 375.6 |
| Self assessment | 54.1 | 63.4 | 72.0 | 77.2 | 84.7 | 87.7 | 93.6 |
| Other income tax | -5.2 | -0.4 | 4.0 | -2.9 | -5.5 | -5.5 | -5.5 |
| National Insurance contributions | 204.4 | 214.2 | 220.8 | 228.6 | 240.5 | 249.5 | 257.7 |
| Value added tax | 180.3 | 186.4 | 196.2 | 204.5 | 213.2 | 221.6 | 229.8 |
| Corporation tax(2) | 98.3 | 109.0 | 114.5 | 121.2 | 126.5 | 131.5 | 136.4 |
| of which: Onshore | 96.5 | 107.2 | 113.6 | 120.7 | 125.9 | 131.1 | 136.2 |
| Offshore | 1.8 | 1.8 | 0.9 | 0.5 | 0.6 | 0.5 | 0.1 |
| Petroleum revenue tax | -0.4 | -0.4 | -0.4 | -0.3 | -0.2 | -0.2 | -0.2 |
| Fuel duties | 24.6 | 23.9 | 25.7 | 26.6 | 26.3 | 25.6 | 24.4 |
| Business rates | 33.6 | 35.1 | 36.9 | 38.3 | 41.1 | 42.1 | 43.1 |
| Council tax(3) | 50.4 | 54.0 | 56.8 | 60.4 | 63.7 | 67.2 | 70.7 |
| VAT refunds | 30.5 | 31.3 | 32.8 | 33.3 | 33.9 | 35.2 | 36.3 |
| Capital gains tax | 24.3 | 25.6 | 29.2 | 32.4 | 34.2 | 37.7 | 41.3 |
| Inheritance tax | 8.5 | 9.1 | 10.8 | 12.3 | 13.3 | 14.2 | 15.1 |
| Property transaction taxes(4) | 16.6 | 16.5 | 18.4 | 20.6 | 22.1 | 23.9 | 25.7 |
| Stamp taxes on shares | 4.7 | 5.1 | 5.2 | 5.4 | 5.5 | 5.7 | 5.9 |
| Tobacco duties | 7.5 | 7.4 | 7.3 | 7.1 | 6.8 | 6.5 | 6.3 |
| Alcohol duties | 12.4 | 12.8 | 13.1 | 13.4 | 13.7 | 13.9 | 14.1 |
| Air passenger duty(5) | 4.6 | 4.9 | 5.2 | 5.5 | 5.8 | 6.1 | 6.4 |
| Insurance premium tax | 9.0 | 9.2 | 9.5 | 9.7 | 10.0 | 10.2 | 10.4 |
| Climate change levy | 1.7 | 1.8 | 1.7 | 1.5 | 1.5 | 1.6 | 1.6 |
| Bank levy | 1.5 | 1.6 | 1.6 | 1.6 | 1.6 | 1.6 | 1.6 |
| Bank surcharge | 1.2 | 1.6 | 2.4 | 1.7 | 1.5 | 1.5 | 1.6 |
| Apprenticeship levy | 4.3 | 4.6 | 4.8 | 4.9 | 5.1 | 5.3 | 5.5 |
| Digital services tax | 0.9 | 1.1 | 1.2 | 1.3 | 1.4 | 1.5 | 1.6 |
| Other HMRC taxes(6) | 11.2 | 11.9 | 12.7 | 13.4 | 14.2 | 14.8 | 15.1 |
| Vehicle excise duties | 8.9 | 9.4 | 10.1 | 11.7 | 12.5 | 13.4 | 14.2 |
| Licence fee receipts | 3.9 | 3.9 | 3.9 | 3.9 | 3.9 | 3.9 | 3.8 |
| Environmental levies | 13.7 | 14.3 | 13.7 | 16.1 | 16.0 | 16.2 | 16.0 |
| Emissions trading scheme | 2.1 | 2.8 | 2.8 | 2.6 | 2.2 | 2.1 | 2.0 |
| Energy profits levy | 2.8 | 3.8 | 2.7 | 1.7 | 0.8 | 0.0 | 0.0 |
| Electricity generator levy | 0.0 | 0.6 | 0.2 | 0.0 | 0.0 | 0.0 | 0.0 |
| Other taxes | 13.6 | 15.9 | 16.6 | 17.6 | 17.8 | 18.1 | 18.3 |
| National Accounts taxes | 1,105 | 1,183 | 1,249 | 1,301 | 1,361 | 1,415 | 1,468 |
| Interest and dividends | 40.6 | 43.6 | 48.6 | 50.0 | 50.0 | 51.1 | 51.8 |
| Gross operating surplus | 82.9 | 86.3 | 91.2 | 94.6 | 98.2 | 101.6 | 105.4 |
| Other receipts | 3.1 | 3.2 | 3.5 | 3.6 | 3.6 | 3.7 | 3.7 |
| Current receipts | 1,231 | 1,316 | 1,392 | 1,449 | 1,513 | 1,571 | 1,629 |
| Memo: UK oil and gas revenues(7) | 4.1 | 5.1 | 3.1 | 1.9 | 1.2 | 0.3 | 0.0 |
| 1) Includes PAYE, self assessment, tax on savings income, and other minor components, such as income tax repayments. |
| 2) National Accounts measure, includes Pillar 2 taxes. |
| 3) Includes high-value council tax surcharge. |
| 4) Includes stamp duty land tax, devolved property transaction taxes, and the annual tax on enveloped dwellings. |
| 5) Includes Scottish air departure tax. |
| 6) Consists of landfill tax and aggregates levy (ex devolved), betting and gaming duties, customs duties, diverted profits tax, soft drinks industry levy, residential property developer tax, the carbon border adjustment mechanism, vaping tax, and plastic packaging tax. |
| 7) Consists of offshore corporation tax, petroleum revenue tax, and energy profits levy. |
Table A.6: Current receipts: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| Income tax(1) | -2.1 | 5.8 | 7.6 | 8.2 | 12.6 | 13.7 |
| of which: Pay as you earn | 0.1 | 6.2 | 6.0 | 5.2 | 3.8 | 2.1 |
| Self assessment | -1.8 | -1.0 | 0.9 | 2.4 | 8.4 | 10.8 |
| Other income tax | -0.4 | 0.6 | 0.6 | 0.5 | 0.5 | 0.8 |
| National Insurance contributions | 0.4 | 2.6 | 1.9 | 2.0 | 2.9 | 3.7 |
| Value added tax | -0.6 | -2.3 | -1.6 | -1.3 | -1.5 | -2.2 |
| Corporation tax(2) | -0.5 | 6.6 | 5.4 | 7.8 | 8.7 | 8.4 |
| of which: Onshore | -0.3 | 5.8 | 5.1 | 7.6 | 8.3 | 8.1 |
| Offshore | -0.2 | 0.8 | 0.3 | 0.2 | 0.4 | 0.3 |
| Petroleum revenue tax | -0.1 | -0.2 | -0.2 | -0.2 | -0.1 | -0.1 |
| Fuel duties | 0.3 | -0.7 | -0.8 | -0.1 | -0.1 | -0.2 |
| Business rates | -0.1 | -2.0 | -1.0 | -0.4 | -1.0 | 0.0 |
| Council tax(3) | -0.5 | 0.3 | 0.0 | -0.3 | -0.4 | -0.4 |
| VAT refunds | 0.2 | 0.1 | 0.4 | 0.6 | 0.6 | 0.5 |
| Capital gains tax | 2.5 | 4.8 | 3.7 | 3.5 | 2.2 | 2.8 |
| Inheritance tax | -0.2 | -0.4 | -0.4 | -0.5 | -0.5 | -0.5 |
| Property transaction taxes(4) | -0.3 | -3.2 | -3.5 | -3.7 | -4.2 | -4.2 |
| Stamp taxes on shares | 0.1 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Tobacco duties | -0.2 | -0.1 | 0.0 | 0.0 | 0.0 | -0.1 |
| Alcohol duties | 0.1 | 0.1 | -0.1 | -0.2 | -0.4 | -0.6 |
| Air passenger duty(5) | 0.1 | -0.3 | -0.3 | -0.3 | -0.3 | -0.3 |
| Insurance premium tax | 0.0 | -0.1 | 0.0 | 0.0 | 0.0 | 0.0 |
| Climate change levy | 0.0 | 0.0 | 0.0 | -0.1 | -0.1 | -0.1 |
| Bank levy | 0.0 | 0.2 | 0.2 | 0.2 | 0.2 | 0.2 |
| Bank surcharge | 0.0 | 0.4 | 1.1 | 0.3 | 0.0 | 0.0 |
| Apprenticeship levy | 0.0 | 0.1 | 0.1 | 0.1 | 0.1 | 0.1 |
| Digital services tax | -0.1 | 0.0 | 0.0 | 0.0 | 0.1 | 0.1 |
| Other HMRC taxes(6) | 0.2 | 0.5 | 0.3 | 0.4 | 0.3 | 0.3 |
| Vehicle excise duties | -0.5 | -0.5 | -0.3 | -0.1 | 0.0 | 0.0 |
| Licence fee receipts | 0.0 | -0.1 | -0.1 | 0.0 | -0.1 | -0.2 |
| Environmental levies | -0.3 | -1.6 | -1.6 | 0.1 | -0.7 | -2.3 |
| Emissions trading scheme | -0.5 | -0.2 | -0.6 | -0.6 | -0.9 | -0.8 |
| Energy profits levy | 0.2 | 2.1 | 1.8 | 1.7 | 0.8 | 0.0 |
| Electricity generator levy | 0.0 | 0.6 | 0.2 | 0.0 | 0.0 | 0.0 |
| Other taxes | -1.7 | -0.2 | 0.4 | 0.6 | 0.4 | 0.4 |
| National Accounts taxes | -3.4 | 12.3 | 12.5 | 17.5 | 18.7 | 18.2 |
| Interest and dividends | -0.4 | 0.7 | 3.3 | 3.1 | 0.9 | 0.0 |
| Gross operating surplus | -0.3 | -1.0 | 0.4 | 0.7 | 1.4 | 1.6 |
| Other receipts | 0.1 | 0.2 | 0.3 | 0.3 | 0.3 | 0.2 |
| Current receipts | -3.9 | 12.2 | 16.6 | 21.5 | 21.2 | 20.0 |
| Memo: UK oil and gas revenues(7) | 0.0 | 2.6 | 1.9 | 1.7 | 1.1 | 0.3 |
| 1) Includes PAYE, self assessment, tax on savings income, and other minor components, such as income tax repayments. |
| 2) National Accounts measure, includes Pillar 2 taxes. |
| 3) Includes high-value council tax surcharge. |
| 4) Includes stamp duty land tax, devolved property transaction taxes, and the annual tax on enveloped dwellings. |
| 5) Includes Scottish air departure tax. |
| 6) Consists of landfill tax and aggregates levy(ex devolved), betting and gaming duties, customs duties, diverted profits tax, soft drinks industry levy, residential property developer tax, the carbon border adjustment mechanism, vaping tax and plastic packaging tax. |
| 7) Consists of offshore corporation tax, petroleum revenue tax, and energy profits levy. |
Table A.7: Total managed expenditure
| £ billion | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Public sector current expenditure (PSCE) | |||||||
| PSCE in RDEL | 526.6 | 555.5 | 554.6 | 573.0 | 584.8 | 604.8 | 620.9 |
| PSCE in AME | 679.8 | 723.0 | 772.2 | 797.3 | 824.0 | 851.9 | 890.8 |
| of which: | |||||||
| Welfare spending | 333.8 | 352.7 | 367.2 | 382.1 | 397.5 | 413.1 | 431.3 |
| Locally financed current expenditure | 78.2 | 81.5 | 87.2 | 85.7 | 87.2 | 91.0 | 95.4 |
| Central government debt interest, net of APF(1) | 108.7 | 123.9 | 134.0 | 139.0 | 147.4 | 149.6 | 160.0 |
| Scottish Government’s current AME | 7.4 | 8.0 | 7.6 | 7.7 | 7.7 | 8.4 | 8.8 |
| EU financial settlement | 0.9 | 0.3 | 0.0 | 0.7 | 0.2 | 0.2 | 0.3 |
| Unfunded public service pensions | -0.4 | -1.1 | 14.3 | 14.9 | 14.9 | 14.9 | 15.1 |
| Company and other tax credits | 10.9 | 11.6 | 12.0 | 12.2 | 12.4 | 12.8 | 13.1 |
| BBC current expenditure | 4.3 | 4.4 | 4.2 | 4.3 | 4.3 | 4.3 | 4.4 |
| National Lottery current grants | 1.5 | 1.5 | 1.5 | 1.5 | 1.5 | 1.5 | 1.5 |
| General government imputed pensions | 1.6 | 1.6 | 1.7 | 1.7 | 1.8 | 1.8 | 1.9 |
| Public corporations’ debt interest | 0.5 | 0.5 | 0.5 | 0.5 | 0.5 | 0.5 | 0.5 |
| Funded public sector pension schemes | 19.9 | 18.8 | 19.6 | 20.4 | 21.2 | 22.2 | 23.1 |
| General government depreciation | 64.7 | 69.5 | 73.7 | 77.1 | 80.2 | 83.2 | 86.6 |
| Current VAT refunds | 26.4 | 27.0 | 27.8 | 28.5 | 29.0 | 30.4 | 31.5 |
| Environmental levies | 15.2 | 17.6 | 17.9 | 18.8 | 16.6 | 16.9 | 16.6 |
| Other PSCE items in AME | 9.2 | 2.1 | 2.0 | 1.9 | 1.9 | 1.9 | 2.0 |
| Other National Accounts adjustments | -3.1 | 3.1 | 1.0 | 0.3 | -0.2 | -0.7 | -1.1 |
| Total public sector current expenditure | 1,206 | 1,278 | 1,327 | 1,370 | 1,409 | 1,457 | 1,512 |
| Public sector gross investment (PSGI) | |||||||
| PSGI in CDEL | 122.2 | 127.7 | 130.2 | 131.7 | 133.7 | 136.9 | 141.4 |
| PSGI in AME | 37.0 | 43.0 | 47.0 | 46.5 | 44.4 | 44.8 | 44.6 |
| of which: | |||||||
| Locally financed capital expenditure | 8.4 | 10.8 | 9.8 | 10.4 | 9.3 | 9.5 | 9.2 |
| Public corporations’ capital expenditure | 15.9 | 16.9 | 17.1 | 17.4 | 17.5 | 17.8 | 18.0 |
| Student loans | 8.5 | 1.4 | 8.3 | 8.3 | 8.3 | 8.2 | 8.2 |
| Funded public sector pension schemes | 0.6 | 2.0 | 0.7 | 0.7 | 0.7 | 0.7 | 0.7 |
| Tax litigation | 0.0 | 0.0 | 0.6 | 0.6 | 0.6 | 0.6 | 0.6 |
| Other PSGI items in AME | 3.2 | 9.2 | 7.8 | 6.7 | 5.6 | 5.6 | 5.6 |
| Other National Accounts adjustments | 0.4 | 2.8 | 2.6 | 2.4 | 2.4 | 2.4 | 2.3 |
| Total public sector gross investment | 159.2 | 170.7 | 177.2 | 178.2 | 178.1 | 181.7 | 186.0 |
| Less public sector depreciation | -72.3 | -78.1 | -82.7 | -86.5 | -89.8 | -93.1 | -96.8 |
| Public sector net investment | 86.9 | 92.6 | 94.5 | 91.7 | 88.3 | 88.6 | 89.2 |
| Total managed expenditure | 1,366 | 1,449 | 1,504 | 1,549 | 1,587 | 1,638 | 1,698 |
| 1) Includes increases in debt interest payments due to the APF. |
Table A.8: Total managed expenditure: changes since March
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| Public sector current expenditure (PSCE) | ||||||
| PSCE in RDEL(23) | 3.7 | 7.2 | -9.0 | -8.8 | -9.4 | -9.4 |
| PSCE in AME | -8.8 | 10.9 | 36.7 | 39.0 | 36.8 | 35.1 |
| of which: | ||||||
| Welfare spending | 0.9 | -0.1 | 4.1 | 8.3 | 7.5 | 6.1 |
| Locally financed current expenditure(2) | -0.5 | -5.9 | -3.0 | -2.6 | -3.0 | -2.7 |
| Central government debt interest, net of APF(1) | -0.9 | 14.5 | 17.3 | 13.0 | 12.7 | 12.4 |
| Scottish Government’s current AME | -0.2 | 0.2 | -0.2 | -0.6 | -0.8 | -0.3 |
| EU financial settlement | 0.0 | -0.6 | -0.4 | -0.1 | 0.2 | 0.2 |
| Unfunded public service pensions(3) | -0.9 | 1.9 | 17.7 | 19.2 | 19.2 | 20.0 |
| Company and other tax credits | 0.0 | 0.0 | 0.1 | 0.1 | 0.1 | 0.2 |
| BBC current expenditure | 0.1 | 0.1 | -0.1 | 0.0 | -0.1 | -0.1 |
| National Lottery current grants | 0.1 | 0.2 | 0.3 | 0.3 | 0.2 | 0.2 |
| General government imputed pensions | -0.4 | -0.4 | -0.4 | -0.4 | -0.4 | -0.4 |
| Public corporations’ debt interest | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Funded public sector pension schemes | 0.1 | -2.0 | -2.2 | -2.4 | -2.7 | -3.0 |
| General government depreciation | 0.1 | 0.8 | 1.9 | 2.3 | 2.7 | 2.7 |
| Current VAT refunds | 0.2 | -0.2 | -0.3 | 0.0 | 0.0 | 0.1 |
| Environmental levies | 0.3 | -1.2 | -0.1 | 0.4 | -0.3 | -1.5 |
| Other PSCE items in AME | -0.5 | -0.2 | -0.4 | -0.6 | -0.8 | -1.0 |
| Other National Accounts adjustments | -7.0 | 3.9 | 2.2 | 2.0 | 2.2 | 2.2 |
| Total public sector current expenditure | -5.1 | 18.2 | 27.6 | 30.2 | 27.4 | 25.7 |
| Public sector gross investment (PSGI) | ||||||
| PSGI in CDEL | 5.6 | 5.2 | -2.6 | -1.1 | -0.5 | -1.2 |
| PSGI in AME | -2.9 | 6.5 | 7.1 | 5.9 | 4.7 | 3.4 |
| of which: | ||||||
| Locally financed capital expenditure | -1.2 | 1.8 | 1.4 | 0.7 | -0.2 | -1.3 |
| Public corporations’ capital expenditure | 3.7 | 3.0 | 2.9 | 3.0 | 3.0 | 3.2 |
| Student loans | 0.0 | -1.7 | 0.2 | 0.1 | 0.0 | -0.1 |
| Funded public sector pension schemes | -2.0 | 0.2 | 0.1 | 0.1 | 0.1 | 0.1 |
| Tax litigation | -0.4 | -0.4 | 0.2 | 0.2 | 0.2 | 0.2 |
| Other PSGI items in AME | -2.1 | 2.4 | 1.5 | 1.0 | 0.9 | 0.7 |
| Other National Accounts adjustments | -0.9 | 1.2 | 0.9 | 0.8 | 0.7 | 0.6 |
| Total public sector gross investment | 2.7 | 11.7 | 4.5 | 4.9 | 4.2 | 2.2 |
| Less public sector depreciation | 0.6 | -0.7 | -1.9 | -2.4 | -2.9 | -2.9 |
| Public sector net investment | 3.3 | 11.1 | 2.6 | 2.4 | 1.3 | -0.7 |
| Total managed expenditure | -2.4 | 29.9 | 32.1 | 35.1 | 31.6 | 27.9 |
| 1) Includes increases in debt interest payments due to the APF. |
| 2) Changes include the move of business rate under-indexation compensation grants and reliefs paid to local authorities from AME to DEL. |
| 3) Changes include the 2024 valuation of unfunded public service pension schemes. |
Table A.9: Fiscal aggregates
| Per cent of GDP | |||||||
|---|---|---|---|---|---|---|---|
| Outturn | Forecast | ||||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Receipts and expenditure | |||||||
| Public sector current receipts (a) | 40.1 | 41.4 | 42.3 | 42.4 | 42.7 | 42.8 | 42.9 |
| National Accounts taxes | 36.0 | 37.2 | 37.9 | 38.1 | 38.4 | 38.5 | 38.6 |
| Total managed expenditure (b) | 44.5 | 45.6 | 45.7 | 45.4 | 44.8 | 44.6 | 44.7 |
| Public sector current expenditure (c) | 39.3 | 40.2 | 40.3 | 40.1 | 39.8 | 39.7 | 39.8 |
| Public sector net investment (d) | 2.8 | 2.9 | 2.9 | 2.7 | 2.5 | 2.4 | 2.3 |
| Depreciation (e) | 2.4 | 2.5 | 2.5 | 2.5 | 2.5 | 2.5 | 2.5 |
| Fiscal mandate and supplementary target | |||||||
| Current budget deficit (c+e-a) | 1.5 | 1.3 | 0.5 | 0.2 | -0.4 | -0.6 | -0.5 |
| Public sector net financial liabilities(1) | 81.4 | 83.2 | 83.8 | 83.8 | 83.1 | 82.3 | 81.7 |
| Other deficit measures | |||||||
| Public sector net borrowing (b-a) | 4.4 | 4.2 | 3.4 | 2.9 | 2.1 | 1.8 | 1.8 |
| Cyclically adjusted net borrowing | 3.9 | 3.5 | 2.7 | 2.4 | 1.8 | 1.7 | 1.8 |
| Cyclically adjusted current budget deficit | 1.0 | 0.6 | -0.2 | -0.3 | -0.7 | -0.7 | -0.6 |
| Primary deficit | 1.5 | 1.0 | 0.2 | -0.3 | -1.3 | -1.5 | -1.7 |
| Cyclically adjusted primary deficit | 1.0 | 0.3 | -0.5 | -0.8 | -1.6 | -1.6 | -1.7 |
| Financing | |||||||
| Central government net cash requirement | 4.4 | 4.6 | 4.3 | 4.4 | 2.4 | 3.2 | 2.8 |
| Public sector net cash requirement | 1.1 | 3.9 | 4.6 | 4.6 | 2.5 | 2.7 | 2.8 |
| Alternative balance sheet metrics | |||||||
| Public sector net debt(1) | 93.1 | 95.5 | 96.7 | 97.3 | 96.7 | 95.9 | 95.6 |
| Public sector net debt ex Bank of England(1) | 88.9 | 92.4 | 93.8 | 94.7 | 94.3 | 94.2 | 94.0 |
| Public sector net worth (inverted)(1) | 62.5 | 63.3 | 63.4 | 63.1 | 62.2 | 61.0 | 59.8 |
| International comparisons(2) | |||||||
| General government net borrowing (GGNB) | 5.4 | 4.5 | 3.9 | 3.5 | 2.7 | 2.4 | 2.1 |
| Cyclically adjusted GGNB | 4.9 | 3.8 | 3.2 | 3.0 | 2.4 | 2.2 | 2.1 |
| General government gross debt | 102.4 | 102.3 | 103.9 | 104.8 | 104.4 | 104.0 | 103.6 |
| £ billion | |||||||
| Current budget deficit | 47.4 | 40.6 | 17.5 | 7.8 | -14.5 | -21.7 | -20.9 |
| Public sector net investment | 86.9 | 92.6 | 94.5 | 91.7 | 88.3 | 88.6 | 89.2 |
| Public sector net borrowing | 134.3 | 133.2 | 112.0 | 99.5 | 73.8 | 66.9 | 68.3 |
| Cyclically adjusted net borrowing | 118.7 | 110.2 | 89.1 | 82.8 | 64.5 | 63.1 | 67.6 |
| Cyclically adjusted current budget deficit | 31.8 | 17.5 | -5.4 | -9.0 | -23.8 | -25.5 | -21.6 |
| Public sector net financial liabilities | 2,552 | 2,684 | 2,807 | 2,914 | 2,997 | 3,075 | 3,156 |
| Public sector net debt | 2,918 | 3,082 | 3,239 | 3,384 | 3,487 | 3,583 | 3,695 |
| Public sector net debt ex Bank of England | 2,787 | 2,981 | 3,140 | 3,293 | 3,400 | 3,520 | 3,633 |
| Net debt interest | 87.5 | 100.8 | 106.7 | 111.1 | 120.3 | 122.4 | 133.0 |
| Non-interest receipts | 1,191 | 1,272 | 1,343 | 1,399 | 1,463 | 1,520 | 1,578 |
| Memo: output gap (per cent of GDP) | -0.8 | -1.1 | -0.9 | -0.6 | -0.3 | -0.1 | 0.0 |
| 1) Position at end-March; GDP centred on end-March. |
| 2) Calendar year basis. |
Table A.10: Fiscal aggregates: changes since March
| Per cent of GDP | ||||||
|---|---|---|---|---|---|---|
| Outturn | Forecast | |||||
| 2025-26 | 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| Receipts and expenditure | ||||||
| Public sector current receipts (a) | -0.3 | 0.2 | 0.3 | 0.3 | 0.2 | 0.1 |
| National Accounts taxes | -0.3 | 0.2 | 0.2 | 0.3 | 0.1 | 0.1 |
| Total managed expenditure (b) | -0.3 | 0.7 | 0.8 | 0.7 | 0.4 | 0.3 |
| Public sector current expenditure (c) | -0.4 | 0.4 | 0.7 | 0.6 | 0.4 | 0.3 |
| Public sector net investment (d) | 0.1 | 0.3 | 0.1 | 0.1 | 0.0 | 0.0 |
| Depreciation (e) | 0.0 | 0.0 | 0.0 | 0.1 | 0.1 | 0.1 |
| Fiscal mandate and supplementary target | ||||||
| Current budget deficit (c+e-a) | -0.1 | 0.2 | 0.4 | 0.3 | 0.3 | 0.2 |
| Public sector net financial liabilities(1) | -1.0 | 0.5 | 0.8 | 0.8 | 0.9 | 1.1 |
| Other deficit measures | ||||||
| Public sector net borrowing (b-a) | 0.0 | 0.5 | 0.5 | 0.4 | 0.3 | 0.2 |
| Cyclically adjusted net borrowing | 0.0 | 0.4 | 0.1 | 0.0 | 0.1 | 0.1 |
| Cyclically adjusted current budget deficit | -0.1 | 0.0 | 0.1 | 0.0 | 0.0 | 0.1 |
| Primary deficit | 0.1 | 0.2 | 0.1 | 0.2 | 0.1 | 0.0 |
| Cyclically adjusted primary deficit | 0.1 | 0.0 | -0.2 | -0.2 | -0.2 | -0.1 |
| Financing | ||||||
| Central government net cash requirement | -0.4 | 0.2 | 0.0 | 0.3 | -0.3 | 0.2 |
| Public sector net cash requirement | -2.4 | 0.3 | 0.3 | 0.4 | -0.2 | 0.2 |
| Alternative balance sheet metrics | ||||||
| Public sector net debt(1) | -1.2 | 0.7 | 1.0 | 1.0 | 0.6 | 0.8 |
| Public sector net debt ex Bank of England(1) | -1.7 | 0.1 | 0.2 | 0.2 | -0.3 | -0.1 |
| Public sector net worth (inverted)(1) | -1.7 | -0.3 | 0.1 | 0.2 | 0.5 | 1.4 |
| International comparisons(2) | ||||||
| General government net borrowing (GGNB) | -0.1 | 0.2 | 0.3 | 0.2 | 0.1 | 0.1 |
| Cyclically adjusted GGNB | -0.2 | 0.1 | 0.0 | -0.1 | -0.1 | 0.0 |
| General government gross debt | 0.0 | -0.6 | 0.0 | 0.2 | -0.4 | -0.4 |
| £ billion | ||||||
| Current budget deficit | -1.8 | 6.6 | 13.0 | 11.1 | 9.0 | 8.6 |
| Public sector net investment | 3.3 | 11.1 | 2.6 | 2.4 | 1.3 | -0.7 |
| Public sector net borrowing | 1.6 | 17.7 | 15.5 | 13.5 | 10.4 | 7.9 |
| Cyclically adjusted net borrowing | 0.8 | 12.1 | 4.5 | 2.0 | 2.8 | 4.5 |
| Cyclically adjusted current budget deficit | -2.6 | 1.0 | 2.0 | -0.4 | 1.5 | 5.2 |
| Public sector net financial liabilities(1) | -2.0 | 22.9 | 41.8 | 54.7 | 65.8 | 76.1 |
| Public sector net debt | -3.9 | 29.3 | 47.7 | 64.5 | 60.0 | 69.5 |
| Public sector net debt ex Bank of England | -20.3 | 9.7 | 22.4 | 35.8 | 27.1 | 34.0 |
| Net debt interest | -2.6 | 11.8 | 11.7 | 7.5 | 9.0 | 9.5 |
| Non-interest receipts | -3.5 | 11.5 | 13.3 | 18.4 | 20.3 | 20.0 |
| Memo: output gap (per cent of GDP) | 0.0 | -0.3 | -0.5 | -0.5 | -0.2 | -0.1 |
| 1) Position at end-March; GDP centred on end-March. |
| 2) Calendar year basis. |
Table A.11: Source of year-on-year changes in balance sheet aggregates
| £ billion | ||||||
|---|---|---|---|---|---|---|
| Forecast | ||||||
| 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | 2031-32 | |
| Public sector net borrowing (a) | 133.2 | 112.0 | 99.5 | 73.8 | 66.9 | 68.3 |
| PSNFL valuation changes (b) | -0.6 | 10.7 | 7.5 | 9.7 | 11.1 | 12.3 |
| Asset purchase facility | 1.5 | 3.7 | 3.8 | 4.6 | 4.5 | 4.6 |
| Central government gilt premia | 8.0 | 2.6 | 0.9 | 0.7 | 0.8 | 1.0 |
| Reserve assets | 3.3 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Funded pensions | -8.0 | 8.0 | 7.3 | 9.2 | 9.5 | 10.5 |
| Other | -5.5 | -3.5 | -4.5 | -4.8 | -3.8 | -3.7 |
| Public sector net financial liabilities (a+b) | 132.6 | 122.7 | 107.1 | 83.5 | 78.0 | 80.7 |
| Remove valuation of assets not in PSND (c) | 13.5 | -4.4 | -2.8 | -4.4 | -5.7 | -6.8 |
| Funded pensions | 8.0 | -8.0 | -7.3 | -9.2 | -9.5 | -10.5 |
| Other | 5.5 | 3.5 | 4.5 | 4.8 | 3.8 | 3.7 |
| Net acquisition of financial assets (d) | -2.2 | 18.3 | 20.5 | 20.7 | 5.8 | 20.8 |
| DEL net lending | 2.4 | 2.8 | 4.1 | 4.3 | 4.7 | 4.5 |
| Student loan outlays | 22.5 | 16.4 | 17.3 | 18.3 | 19.3 | 20.1 |
| Student loan repayments | -6.7 | -7.5 | -8.3 | -9.1 | -9.9 | -10.9 |
| Central government public financial institutions | 5.4 | 4.2 | 4.4 | 5.0 | 4.7 | 4.7 |
| Public corporation public financial institutions | 1.2 | 1.4 | 0.8 | 0.3 | 0.5 | 0.6 |
| Term funding scheme | -26.4 | 0.0 | 0.0 | 0.0 | -15.5 | 0.0 |
| Other | -0.5 | 1.0 | 2.2 | 2.0 | 2.0 | 1.8 |
| Cash flow timing effects (e) | 20.0 | 20.2 | 20.1 | 3.4 | 18.0 | 16.6 |
| Student loan interest | 7.5 | 9.3 | 9.4 | 8.7 | 8.8 | 8.4 |
| Other receipts | 12.0 | 9.9 | 10.4 | -5.0 | 10.8 | 10.2 |
| Funded public pension schemes | 0.8 | 2.1 | 1.9 | 1.7 | 1.3 | 1.0 |
| Gilt accruals | 1.8 | 1.7 | 1.2 | 1.0 | 0.2 | 0.2 |
| Guarantee schemes write offs | 0.7 | 0.5 | 0.2 | 0.1 | 0.0 | 0.0 |
| Other expenditure | -2.9 | -3.1 | -3.0 | -3.0 | -3.1 | -3.1 |
| Public sector net debt (a+b+c+d+e) | 163.9 | 156.8 | 144.8 | 103.2 | 96.0 | 111.3 |
Table A.12: Source of year-on-year changes in balance sheet aggregates: changes since March
| £ billion | |||||
|---|---|---|---|---|---|
| 2026-27 | 2027-28 | 2028-29 | 2029-30 | 2030-31 | |
| Public sector net borrowing (a) | 17.7 | 15.5 | 13.5 | 10.4 | 7.9 |
| PSNFL valuation changes (b) | 7.2 | 3.3 | -0.6 | 0.7 | 2.4 |
| Asset purchase facility | -1.7 | -0.4 | -0.5 | -0.4 | -0.9 |
| Central government gilt premia | 6.1 | 1.2 | -0.4 | -0.5 | -0.5 |
| Reserve assets | 3.2 | 0.0 | 0.0 | 0.0 | 0.0 |
| Funded pensions | 0.6 | 4.3 | 2.9 | 4.3 | 5.3 |
| Other | -1.1 | -1.8 | -2.6 | -2.8 | -1.5 |
| Public sector net financial liabilities (a+b) | 24.9 | 18.9 | 12.9 | 11.1 | 10.3 |
| Remove valuation of assets not in PSND (c) | 0.5 | -2.5 | -0.3 | -1.5 | -3.8 |
| Funded pensions | -0.6 | -4.3 | -2.9 | -4.3 | -5.3 |
| Other | 1.1 | 1.8 | 2.6 | 2.8 | 1.5 |
| Net acquisition of financial assets (d) | 2.8 | -1.4 | -0.9 | -0.2 | 2.2 |
| DEL net lending(1) | 1.7 | 1.9 | 1.1 | -0.2 | 0.2 |
| Student loan outlays | 1.3 | -0.9 | -0.9 | -0.9 | -0.8 |
| Student loan repayments | 0.1 | 0.0 | 0.0 | 0.1 | 0.3 |
| Central government public financial institutions(1) | 1.8 | 0.9 | 0.8 | 1.7 | 2.6 |
| Public corporation public financial institutions(2) | -2.0 | -2.8 | -2.0 | -1.0 | -0.1 |
| Term funding scheme | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Other | 0.0 | -0.5 | 0.1 | 0.1 | 0.0 |
| Cash flow timing effects (e) | 5.0 | 3.5 | 5.1 | -13.9 | 0.8 |
| Student loan interest | -0.1 | 1.5 | 1.9 | 0.7 | -0.2 |
| Other receipts | 3.1 | 0.5 | 1.6 | -15.7 | 0.2 |
| Funded public pension schemes | 1.0 | 0.8 | 0.7 | 0.7 | 0.6 |
| Gilt accruals | 0.9 | 0.6 | 0.7 | 0.2 | 0.0 |
| Guarantee schemes write offs | -0.2 | -0.1 | 0.0 | 0.0 | 0.0 |
| Other expenditure | 0.3 | 0.2 | 0.2 | 0.2 | 0.2 |
| Public sector net debt (a+b+c+d+e) | 33.1 | 18.4 | 16.8 | -4.5 | 9.5 |
| 1) Our March forecast for each of these lines has been restated on a like-for-like basis, to reflect the movement of the National Housing Bank and British Business Bank from ‘DEL net lending’ to ‘Central government public financial institutions’. |
| 2) This forecast now contains British International Investment, so we have recalculated the March forecast it compares against on a like-for-like basis. |
-
(1) There is some evidence that the UK OIS curve we use to condition our forecast for Bank Rate may be less risk-free than usual. For example, see Lengyel, A. and D. Walker, Bank Rate expectations in the UK curve following the war in Iran, Bank of England Insights, July 2026. As is set out in Forecasts in-depth: Conditioning assumptions on our website, we condition our forecasts on the expected values implicit in market pricing. Since these reflect the collective views of a large number of investors in each market, it is unlikely that a forecast could systematically outperform these values. ↩
-
(2) We recently published more information on our CPI inflation modelling framework, in line with the recommendations from our 2025 external review to share more transparently our analytical infrastructure. See Cavallero, J., The OBR’s CPI inflation modelling, OBR articles, August 2026. ↩
-
(3) External forecasts based on more recent readings of energy market pricing suggest that the Ofgem energy price cap could rise to around £2,150 in Q1 2027. This figure represents the simple average of estimates from the forecasting services of EDF, British Gas, and E.ON Next available as of 21 October 2026. ↩
-
(4) See Bank of England, Decision Maker Panel survey, September 2026. ↩
-
(5) RHDI measures the purchasing power of households’ monetary income. It does not account for changes in household wealth due to asset prices, changes in the quantity and quality of the provision of goods and services by the Government, the state of the environment, or factors that may change quality of life such as leisure time. For details, see ONS, Understanding real household disposable income per head, November 2025. ↩
-
(6) Current LFS data are based on an older vintage of National Population Projections (NPPs), which assumed a higher level of net migration. Since March, we have taken on the April 2026 ONS NPPs, which imply higher inflows into the adult population and marginally fewer deaths than the previous NPPs. As such, LFS outturn for the adult population in the second quarter of 2026 was 145,000 higher than we expected in March. ↩
-
(7) We recently published more information on how we forecast net migration, including our migration model, in line with the recommendations from our 2025 external review to share more transparently our analytical infrastructure. See Robson, E., Forecasting net migration, OBR articles, September 2026. ↩
-
(8) For example, migrants arriving on work visas tend to have a higher participation rate than the domestic population, while dependants and migrants on humanitarian visas tend to have lower participation rates. ↩
-
(9) We have updated the model described in Box 3.2 of our 2022 FRS in line with the latest data available at the time of finalising our pre-measures forecast for the intermediate consumption of fossil fuels in the UK economy. ↩
-
(10) We use sectoral GVA published on 30 September divided by sectoral employment. Sectoral employment is calculated using RTI employees and WFJ self-employment (both published on 15 September), scaled to align to the total aggregate employment measure constructed by the Resolution Foundation. Output per hour worked is our preferred measure of labour productivity, but limitations with the LFS make it challenging to examine trends at a sectoral level. Output per worker is also less likely to be significantly impacted by the change to the new ‘component’ approach discussed in Box 2.2. ↩
-
(11) Although in recent experience real GDP growth has tended to be stronger in the first half of the year, ONS analysis has not found evidence of residual seasonality in quarterly or monthly GDP data. See ONS, How the ONS assesses statistical outputs for residual seasonality, May 2026. ↩
-
(12) This is in line with an ONS recommendation to use the LFS as part of a suite of labour market indicators. See ONS, Labour market overview, UK, September 2026. ↩
-
(13) The RICS national sales-to-stock ratio has fallen since late 2022, indicating weaker demand relative to the stock of properties available for sale. At the same time, residential construction costs have risen more rapidly than house prices over this period, putting further pressure on development viability. ↩
-
(14) Transfer costs are additional costs associated with buying housing, such as stamp duty land tax and estate agents’ and solicitors’ fees. ↩
-
(15) Our latest economic forecast is conditioned on the average of market determinants over the 10 working days to 19 August. The central projection in the Bank of England’s July Monetary Policy Report is conditioned over the 15 working days to 20 July. ↩
-
(16) There are conceptual differences in how the OBR and the Bank of England consider spare capacity and equilibrium in the economy. See Box 3.1 in the March 2014 EFO. ↩
-
(17) We have certified the costings for all but one measure in this forecast. Small changes were made to the policy parameters of the fuel duty policy announced in the Budget following the costings certification deadline. As a result, we could not certify the final version of the relevant costing but have used the Government’s estimates in this forecast and will finalise the certification for our next forecast. We do not expect this will have a material impact on the costing we have used. ↩
-
(18) We define ‘significant’ as when a measure, or package of measures, changes the level of potential output by at least 0.1 per cent by the fifth year of our forecast. See Briefing Paper No. 10: Accounting for the supply-side effects of policy. ↩
-
(19) We have not included an assessment of changes to visa salary requirements announced at this Budget, as the final policy was confirmed after the deadline for including it in the economy forecast. We will consider the impacts of these changes in our next forecast. ↩
-
(20) See Chapter 2 in our June 2026 Forecast evaluation report. ↩
-
(21) The fuel duty policy confirmed in the Budget is slightly different to that reflected in our economy forecast as the Government informed us of the final policy after the relevant deadline. Incorporating the final policy would have had less than a 0.1 percentage point impact on our quarterly inflation forecast. ↩
-
(22) While other policy measures may also impact CPI inflation, their impacts are not material enough to warrant an explicit adjustment to our inflation forecast. ↩
-
(23) The measure applies to both corporation tax and income tax populations. The WDA rate change affects expenditure that receives main rate WDAs, including existing pooled expenditure and new qualifying expenditure. The FYA rate change applies only to new main rate expenditure, including plant or machinery for leasing but excludes second-hand assets and cars. ↩
-
(24) The behavioural response reflects some banking companies shifting profits outside of the UK in response to the higher tax rate and includes the impact of this profit shifting on both corporation tax and the bank surcharge. ↩
-
(25) This measure also increases annually managed expenditure by £0.8 billion in 2027-28 as firms eligible for BICS and the Supercharger uplift receive backdated support relating to 2026-27. This increases the total cost of the scheme to £0.5 billion a year for 2027-28 onwards. ↩
-
(26) This net annually managed expenditure flowing into local authorities captures retained rates and safety net payments, offset by top-up and tariffs, and levy payments. ↩
-
(27) For example, the full range of relevant regulatory changes affecting any specific sector can be difficult to identify and quantify, making it difficult to form a baseline of regulation against new policy is assessed. See paragraph 4.13 of our “Briefing paper 10: Accounting for the supply-side effects of policy”. ↩
-
(28) See paragraph 4.12 of our “Briefing paper 10: Accounting for the supply-side effects of policy”. ↩
-
(29) Health Foundation Report 2024. The Health Foundation figures are for the extra costs of healthcare over and above current spending in 2035-36 and cover a range of different reform options. For example, the low figure estimates only cover some costs for those recipients living at home. The higher figures correspond to wider schemes e.g. including the costs of residential care. ↩
-
(30) As described in paragraph 3.19, this includes the four-month freeze announced in May, and the further six-month freeze announced at this Budget. ↩
-
(31) For example, changes to mortgage interest relief, the stamp duty land tax surcharge and capital gains tax allowances, and the introduction of the Renters’ Rights Act. ↩
-
(32) See Department for Business and Trade, Impact assessment of the Free Trade Agreement between the UK and India, 2025. The agreement came into effect in 15 July 2026. ↩
-
(33) This is because in our current medium-term forecast an uprating of 2.5 per cent would apply under both the previous and adjusted version of the triple lock in both 2030-31 and 2031-32. ↩
-
(34) Average earnings growth exceeded CPI or 2.5 per cent in all years between 1990 and 2007 apart from 1995 when CPI was 0.1 percentage point above average earnings growth. ↩
-
(35) This provisional estimate assumes that the average percentage difference between pension values under earnings uprating and the adjusted triple lock observed over 1990 to 2025 persists over the next 50 years. It applies this average uplift to our long-term earnings-uprated state pension projection and compounds savings as a proportion of GDP each year to produce an illustrative estimate of the resulting effect on debt. These resulting debt impact estimates are not directly comparable with those produced as part of our FRS reports which have some methodological and data input differences. ↩
-
(36) National Accounts taxes include all taxes recognised in the ONS’s National Accounts and National Insurance Contributions. Public sector current receipts further include public sector interest and dividend receipts (driven by the interest received from funded public sector pensions and the accrued interest on student loans), public sector gross operating surplus and a small amount of other non-tax receipts. ↩
-
(37) We take the median of the absolute level differences at each forecast horizon between outturns and the central forecasts. We use data from all spring forecasts since 2011 and all autumn forecasts since 2013. The median value is used as it is less skewed by shocks such as the Covid pandemic. These differences broadly increase each year over the forecast period. The median absolute level difference in the final year is 6.4 per cent for nominal earnings, 5.9 per cent for nominal consumption, and 10.3 per cent for equity prices. ↩
-
(38) The tax gap is the difference between the amount of tax that should, in theory, be paid to HMRC (‘theoretical tax liability’), and the amount that is actually paid. See Box 3.1 in Chapter 3 for more detail. 2024-25 is the latest year for which HMRC publishes estimates, see HMRC, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025, June 2026. ↩
-
(39) These indicative scenarios assume that the nominal GDP denominator is unaffected by the changes to the economic determinants that drive changes in receipts. ↩
-
(40) Nominal earnings are the main driver of income tax and NICs receipts, with frozen tax thresholds until April 2031 amplifying the impact of nominal earnings growth on receipts (paragraph 4.14). Higher-than-expected inflation means that, despite stronger nominal earnings, real earnings are lower than our March forecast in 2026-27, as discussed in paragraph 2.29. ↩
-
(41) Estimates are based on our standard ready reckoners consistent with our pre-measures forecast. They solely capture the direct effect of a 1 percentage point increase in nominal earnings and CPI on income tax and NICs receipts, including on self-assessed income tax. They exclude any wider effects on other receipts, spending, or the broader economy. ↩
-
(42) See Box 3.2 in the March 2024 Economic and fiscal outlook for details on our estimation approach. We used a similar approach in the 2026 Fiscal risks and sustainability report. ↩
-
(43) The NSTA’s oil and gas projections are based on the informed judgement, which is guided by survey data, comparisons with other forecasts (including forecasts by the International Energy Agency, Wood Mackenzie and National Grid Gas) and assumptions around factors which could impact the output from fields. More information is available from the Data and Insights section of the North Sea Transition Authority website. ↩
-
(44) This also includes the impact of recent analysis of 2025-26 SA receipts which suggests that CGT receipts were £2.5 billion stronger than assumed at the March forecast, some of which was offset by a reallocation which reduced SA IT receipts by £1.8 billion. ↩
-
(45) HMRC extracted asset-level information from taxpayer returns and constructed a counterfactual path of asset disposals across the tax year using 2023-24 data. This was compared to the actual level of asset disposals in 2024-25 to estimate the impact of forestalling. ↩
-
(46) The average absolute forecast difference is calculated by taking the average of the absolute values of differences between outturns and the central (point) forecasts, ignoring whether the differences are positive or negative. This indicates the absolute size of forecast differences and therefore is a measure of how accurate the forecasts are. ↩
-
(47) More formally, unless otherwise stated these terms refer, respectively, to public sector current expenditure (PSCE) in RDEL and public sector gross investment (PSGI) in CDEL, which is the spending within DELs that is recorded within the National Accounts measure of total managed expenditure. ↩
-
(48) The Superannuation Contributions Adjusted for Past Experience (SCAPE) rate is the discount rate used by unfunded public service pension schemes to place a current value on expected future pension payments. HMT increased the SCAPE rate from CPI+1.7% per year to CPI+2.0% per year in May 2026. ↩
-
(49) The 2024 valuation is not entirely fiscally neutral because some employers participate in public service pension schemes whose staff costs are not funded through RDEL (for example, teachers at independent schools or at some universities which use the public service Teachers’ Pension Scheme). This means there is an increase in net pension spending with no offsetting RDEL reduction. This results in an average £1.1 billion increase in spending between 2027-28 and 2031-32. ↩
-
(50) Central government subsidies to public corporations – mainly payments to train-operating-companies – are now classified as part of fiscal DEL rather than AME. This was not captured in our March 2026 AME forecast and so adjusting for this increases TME by around £1.5 billion a year. ↩
-
(51) The government have moved business rate under-indexation compensation and relief grants from AME to DEL. This was not fully captured in our March 2026 AME forecast and so adjusting for this decreases TME by around £0.2 billion a year. ↩
-
(52) The government has moved spending on British Business Bank expected guarantees and write-offs from DEL to AME. This was captured in our March 2026 forecast and so has no effect on TME. ↩
-
(53) Between April and July, departments spent 28 per cent of their total forecasted PSGI in CDEL for 2026-27. The average is around 26 per cent. ↩
-
(54) We had based our previous capital underspend judgements on an assessment of previous periods of fast real growth in capital spending when departments typically underspent plans by a significant amount. This is discussed further in the Forecast evaluation reports 2025 (in paragraph 3.26) and 2026 (in paragraph 3.28), and in paragraph 5.20 in the November 2025 EFO. ↩
-
(55) HM Treasury, Departmental Efficiency Plans. June 2025 ↩
-
(56) See NAO, The Efficiency Programme: A second review of progress, February 2007 and NAO, Efficiency and reform in government corporate functions through shared service centres, March 2012. In October 2026, the Government published 2025-26 Departmental efficiency and savings performance which reports £16 billion of efficiencies and savings in 2025-26. This does not split out cash-releasing and non-cash-releasing savings and so the implications for future spending plans and pressures are not clear. A more detailed assessment will be published by large departments in their 2026-27 Annual Reports and Accounts. ↩
-
(57) Department for Education, Education, health and care plans. September 2026 ↩
-
(58) Between 2019 and 2026 primary schools in England reduced the number of teachers and classes, but not schools, in response to falling primary school pupils. The outlook on school funding in England, Institute for Fiscal Studies. September 2026 ↩
-
(59) Immigration Service Statistics, Home Office. June 2026 ↩
-
(60) NAO, Building an effective and resilient probation service, October 2025, the NAO estimates that 3,150 extra probation service staff undertaking sentence management are needed in 2026-27. ↩
-
(61) Criminal court statistics quarterly: April to June 2026, all open cases in the crown court in England and Wales in 2025-26 are estimated at 79,706. ↩
-
(62) Tribunal statistics quarterly, September 2026. 2025-26 has an open caseload of 860,491 compared to 898,100 in 2012-13. ↩
-
(63) Calculation is based on Spending Reviews between 2000 and 2021, excluding pandemic affected Spending Reviews in 2019 and 2020. ↩
-
(64) MHCLG, The Social and Affordable Homes Programme and the reinvigoration of council housebuilding. August 2026 ↩
-
(65) MHCLG, Launching the Social and Affordable Homes Programme. November 2025 ↩
-
(66) We assume that half of the 180,000 social homes will be built by councils and the rest built by housing associations. ↩
-
(67) 2035-36 estimates by the Health Foundation, Social care funding reform in England. June 2026 ↩
-
(68) Incapacity caseloads here refer to claimants in Great Britain on either employment and support allowance, the universal credit health journey, or both. Disability caseloads refer to claimants in England and Wales on disability living allowance, personal independence payment, or attendance allowance. ↩
-
(69) The forecast assumes CPI uprating of 3.1 per cent in 2027-28. After our forecast was finalised, CPI inflation outturn for September 2026 was published which, if incorporated into our forecast, would have increased CPI uprating for 2027-28 to 3.5 per cent. This would have increased welfare spending by an average of £0.9 billion from 2027-28 onwards. ↩
-
(70) See paragraphs 3.10 and 3.11 in our 2026 Welfare Trends Report. ↩
-
(71) EFS is a mechanism offered by central government to local authorities that would otherwise be at risk of being unable to meet their statutory requirement to balance their budget. It is primarily provided through capitalisation directions, which allow local authorities to use capital resource, including borrowing and capital receipts, to fund spending. A smaller proportion is typically delivered through additional council tax flexibilities. ↩
-
(72) A survey of 89 local authorities found here: Society of County Treasurers and Association of Local Authority Treasurer Societies and County Councils Network., Overview of the 2026 SEND Deficits Survey, October 2026. ↩
-
(73) The one-time transfer was previously estimated to be valued at £6 billion in 2026-27 and is neutral for PSNB but does have implications for the central government net cash requirement as discussed in paragraph 5.17 of our March 2026 EFO. ↩
-
(74) DfE, Children looked after in England including adoptions, 26 November 2025 ↩
-
(75) The effective interest rate is central government interest payments, net of the APF, as a share of central government gross debt. ↩
-
(76) From February 2030, the ONS RPI measure will be aligned to CPIH. See Box 2.3 of our October 2024 EFO for a more detailed explanation of this change. ↩
-
(77) The Post Office redress schemes refer to the following redress schemes: Horizon Shortfall Scheme, HSS Appeals, Overturned Convictions, Horizon Convictions Redress Scheme, Group Litigation Order, Capture Redress Scheme, Family Members Redress Scheme. ↩
-
(78) These illiquid financial assets acquired by the PuFins are not counted within public sector net debt, which therefore only records the gilts issued to finance their acquisition. But the assets are included within public sector net financial liabilities, which are described from paragraph 6.27. The interest payable on the gilts issued to finance the activities of the PuFins is captured within our forecast for central government debt interest spending, the income on the assets is mostly recorded within the interest receipts forecast, and the losses on the assets are recorded as capital spending. For more information on how PuFins affect the public finances and the associated risks and uncertainties see Lockwood, I., M. Hanson and T. Baiju, Forecasting public financial institutions, OBR articles, August 2026. UK Government Investments produces experimental estimates of the performance of the assets of PuFins relative to financing costs in its Financial Investment Report 2026. ↩
-
(79) Bank of England, Monetary Policy Summary and Minutes, September 2026. The Bank has stated that it will retain £120 billion of the longest-dated gilts held within the APF. Of the remaining £368 billion, it has stated that £222 billion will unwind passively and £146 billion will be sold following the MPC’s intended annual sales pace of £20 billion starting in April 2027. This means the APF will not be fully unwound until 2071. ↩
-
(80) A full estimation of the APF’s impact on the public finances requires consideration of central government financing. Interest losses and valuation losses impact the financing requirement, which is largely met through gilt sales. ↩
-
(81) The lifetime cost on a net present value basis is discounted by weighted-average gilt yields. The real terms estimate is deflated by CPI. We have used these approaches given the extended lifetime of the APF following the Bank’s announcements in September. These estimates are therefore not directly comparable with the cash estimates produced in previous EFOs. ↩
-
(82) The Bank of England’s, Asset Purchase Facility Quarter 2 2026 report notes that the difference in the pace of unwind across various scenarios have a minimal impact on the respective cumulative lifetime net present value. ↩
-
(83) Figures, in net present value terms, from Bank of England, Asset Purchase Facility Quarterly Report, Quarter 3 2025. ↩
-
(84) The forecast assumes that the active sales of gilts held within the APF are made directly to the private sector. The Bank of England and HM Treasury are considering a new model from April 2027, under which the DMO would instead purchase gilts sold by the APF, with these gilts subsequently cancelled and the purchases financed by a corresponding amount issued by the DMO. If implemented, this would shift the associated increase in private sector gilt holdings from APF sales to gross gilt issuance, while keeping overall private sector holdings unchanged. A final decision on whether to proceed with this change has not been taken and so it is not reflected in our forecast. See HM Treasury, Update on the Asset Purchase Facility (APF), September 2026. ↩
-
(85) See IMF, World economic outlook, October 2026. The IMF fiscal projection is based on our March 2026 forecast, adjusted for differences in assumptions. ↩
-
(86) The probability distributions for the current budget deficit are based on stochastic simulations, which generate thousands of potential outcomes whose chances of occurring are based on randomly selected shocks drawn historical outturn. We use historical deviations from previous forecasts to generate the probability distributions for PSNFL. We only began forecasting PSNFL in 2016 so there would be a limited sample from which to generate stochastic simulations, and from a period which has seen relatively high variation in borrowing and debt. More detail can be found in the October 2024 EFO and in Steel, D., OBR Working Paper No. 17: Evaluating forecast uncertainty with stochastic simulations, December 2021. ↩
-
(87) Underlying forecast changes include the effects of new outturn data, changes in the economic forecast, revisions to forecasting judgements and assumptions, and methodological changes. It excludes the effects of new policies announced since our March 2026 forecast. ↩
-
(88) The supplementary target requires PSNFL as a share of GDP to fall between 2028-29 and 2029-30. Higher nominal GDP growth in 2029-30 will, other things equal, reduce PSNFL as a share of GDP in that year and therefore increase the degree by which it falls in that year. ↩
-
(89) This absolute average is based on forecasts since October 2021. This calculation is made on a borrowing basis. ↩
-
(90) This absolute median is based on all OBR forecasts exclusive of the current forecast. This calculation is made on a borrowing basis. ↩
-
(91) See Health Foundation, Social care funding reform in England, June 2025. These figures are for the extra costs of healthcare over and above current spending. ↩
-
(92) Sensitivities are estimated using elasticities (for nominal GDP growth and the effective tax rate sensitivities) and our debt interest ready reckoner (for the Bank Rate and gilt yield and inflation sensitivities). See our ready reckoner available on our website. ↩
-
(93) From February 2030, the ONS RPI measure will be aligned to CPIH. ↩
-
(94) In these scenarios, we model the Bank Rate adjustment using the “contemporaneous Taylor-type rule (headline inflation)” from the Bank of England April MPR, and assume this converges to the Bank Rate path in our central forecast in the medium term. In practice, changes to Bank Rate are based on the collective judgement of the Monetary Policy Committee. We model the adjustment in gilt yields assuming a one percentage point increase in the risk premium alongside an estimate of the present value of changes in the Bank Rate, and use the 10-year mark as a proxy for the curve given the average maturity of UK public debt. ↩
-
(95) We do not make an explicit adjustment for the measure to temporarily remove VAT on domestic electricity bills. But we do not believe this would substantially change the results. ↩
-
(96) This is estimated by uprating departmental spending with the additional growth in the GDP deflator in the second-round effects scenario relative to our central forecast. Absent second-round effects, additional GDP deflator growth is around three-quarters lower in the medium term. As this is illustrative, we do not account for the impacts of higher departmental spending on debt interest spending, or on the wider economy. ↩
-
(97) We do not model additional disinflationary second-round effects from a faster recovery of oil and gas prices, which we would expect to be modest. We also do not illustrate an implied easing of DEL pressure, as the changes in the GDP deflator in this scenario are relatively small. ↩
-
(98) Like in the severe shock scenario, this is based on the “contemporaneous Taylor-type rule (headline inflation)” from the Bank of England’s April MPR, which we then assume converges to the Bank Rate path in our central forecast in the medium term. ↩