National Loans Fund Annual Report and Account 2025-26
Published 12 November 2026

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/publications/national-loans-fund-account-2025-to-2026/national-loans-fund-annual-report-and-account-2025-26
1. Performance Report
The performance report includes:
- Performance overview which outlines the purpose, activities of the National Loans Fund (NLF).
- Performance Analysis which provides a more detailed look at the expenditure, assets and liabilities of the NLF during 2025-26.
1.1 Overview
Purpose and activities of the National Loans Fund
The National Loans Fund (NLF) was established on 1 April 1968 by the National Loans Act 1968. The Fund accounts for government borrowing and lending which were previously included in the Consolidated Fund (CF).
The CF was first established in 1787 as a single fund for all government income and spending: ‘One fund into which shall flow every stream of public revenue, and from which shall come the supply for every service’.
Since the creation of the NLF, the CF has accounted for government revenue and expenditure, while the NLF has accounted for government borrowing and lending. The accounts for the CF and NLF are published separately.
Both the CF and NLF are administered by HM Treasury with the bank accounts maintained at the Bank of England.
The NLF’s main role is to meet the financing needs of the CF where taxation and other government receipts are insufficient to cover the CF’s outgoings. The NLF therefore borrows to fund any CF deficits, while any CF surpluses are transferred to the NLF to reduce borrowing requirement or to increase the amount it can lend. The NLFs key relationships are shown on page 8.
The NLF closes each day with a nil balance in its bank account because any cash surpluses or deficits are offset by transfers to or from the Debt Management Account (DMA) at the Bank of England, administered by the Debt Management Office (DMO), and closely connected to the NLF.
Much of the NLF’s borrowing requirement is met indirectly through borrowing undertaken on its behalf by the DMO and National Savings and Investments (NS&I).
The DMO carries out the government’s debt management policy on behalf of HM Treasury. Its objective is to minimise long-term financing costs, while taking account of risk. It also manages the government’s day-to-day cash needs by minimising the cost of balancing cash flows over time, within the risk appetite set by ministers. The DMO carries out these cash management activities through the DMA.
As the government’s debt manager, the DMO plays a central role in issuing of gilt-edged securities, or gilts. Gilts are UK government sterling-denominated listed bonds. The two main types issued from the NLF and sold to the market are:
- conventional gilts - bonds that pay a fixed rate of interest at regular intervals and repay the principal amount at maturity
- index-linked gilts - bonds where both the interest payments and principal are adjusted in line with movements in the of the Retail Price Index (RPI).
The DMO also issues Treasury Bills through the DMA and undertakes other money market operations to meet the government’s daily cash requirements. Treasury Bills are short-term government securities, typically with a term of up to one year. They are issued at a discount, make no regular interest payments and are repaid at face value on maturity. Further details are set out in the Debt Management Report 2025-26.
The NLF may also borrow temporarily from other government bank accounts where surplus funds are available. This reduces the amount the NLF needs to borrow externally. No interest is payable on balances already classified as Exchequer funds, although the NLF generally pays interest on other borrowing. Where the interest paid by the NLF exceeds the interest it receives, the shortfall is met by a transfer from the CF.
The Exchange Equalisation Account (EEA) was established in 1932 to provide a fund that could be used, when necessary, to regulate the exchange value of sterling. It holds the UK’s reserves of gold, foreign currency assets and International Monetary Fund (IMF) Special Drawing Rights (SDRs). Together with the UK’s Reserve Tranche Position (RTP) with the IMF, these assets comprise the UK’s official holdings of international reserves. The RTP is an asset of the NLF. The Bank of England manages the EEA on a day-to-day basis as agent for HM Treasury.
The NLF provides finance to both the DMA and the EEA. As a result, any surpluses or deficits of these accounts are recorded as income and expenditure of the NLF, and their net assets are assets of the NLF.
The NLF also lends to various statutory public sector bodies and provides the funding used by the Public Works Loan Board (PWLB) to make loans to prescribed bodies, mainly local authorities. In addition, the profits of the Issue Department of the Bank of England are paid to the NLF under section 9(1) of the National Loans Act 1968. The Issue Department is solely concerned with the issue of banknotes and the assets backing them.
NS&I’s savings products are liabilities of the NLF.
As the vast majority of the NLF’s assets comprise advances to, and net assets of, the DMA and EEA, and advances to the PWLB, the NLF is not exposed to significant credit risk. Further information on the management of credit risk is provided in Note 16, Financial risks related to the NLF.
Under section 19(1) of the National Loans Act 1968, the net liabilities of the NLF are a liability of the CF. The servicing and redemption of the NLF’s liabilities are expected to be met over the long term mainly through future tax receipts. Although receipts in any year may be affected by tax policy decisions and the wider UK economic position, the government can continue to meet expenditure, including debt servicing costs, through the issuance or reissuance of debt. Demand for UK government debt remains robust.
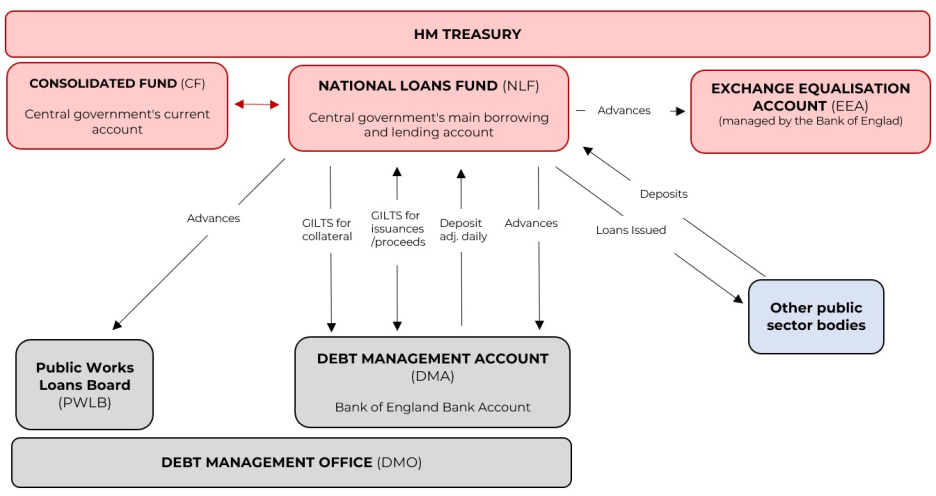
Key relationships of the NLF
This diagram sets out the principal relationships of the NLF with other organisations and funds. It is intended for illustrative purposes only
Key issues and risks
The key issues and risks facing the NLF are considered in the Governance Statement. In addition, the financial risks related to the NLF are separately disclosed in Note 16, Financial risks related to the NLF.
1.2 Performance analysis
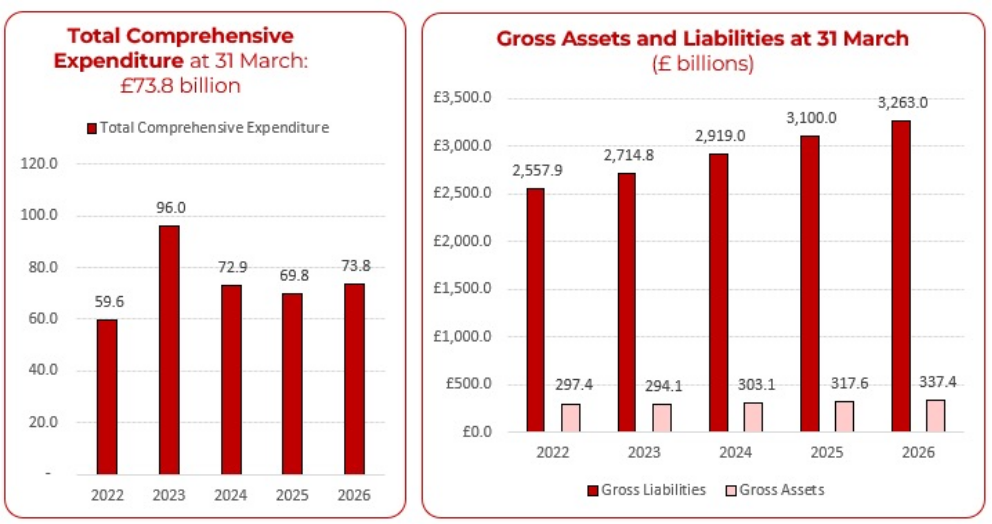
2025-26 Total Comprehensive Expenditure as at 31 March 2026 was £73.8 billion £4.0 billion higher than 2024-25 (2024-25: £69.8 billion) primarily due to an £11.1 billion increase in finance costs of borrowing partially offset by a £6.9 billion increase in income.
Outturn for 2025-26
| Note | 2025-26 £m | 2024-25 £m | |
|---|---|---|---|
| Total comprehensive net expenditure | 73,816 | 69,763 | |
| EEA total comprehensive net (income)/expenditure | 5 | 14,492 | 8,353 |
| DMA total comprehensive net (income)/expenditure | 5 | 1,618 | 443 |
| Profits of the Bank of England Issue Department | 5 | 3,772 | 4,792 |
| 93,698 | 83,351 |
Assets
The NLF’s total gross assets increased by £19.8 billion from £317.6 billion at 31 March 2025 to £337.4 billion at 31 March 2026.
Assets at 31 March 2026 £’bn
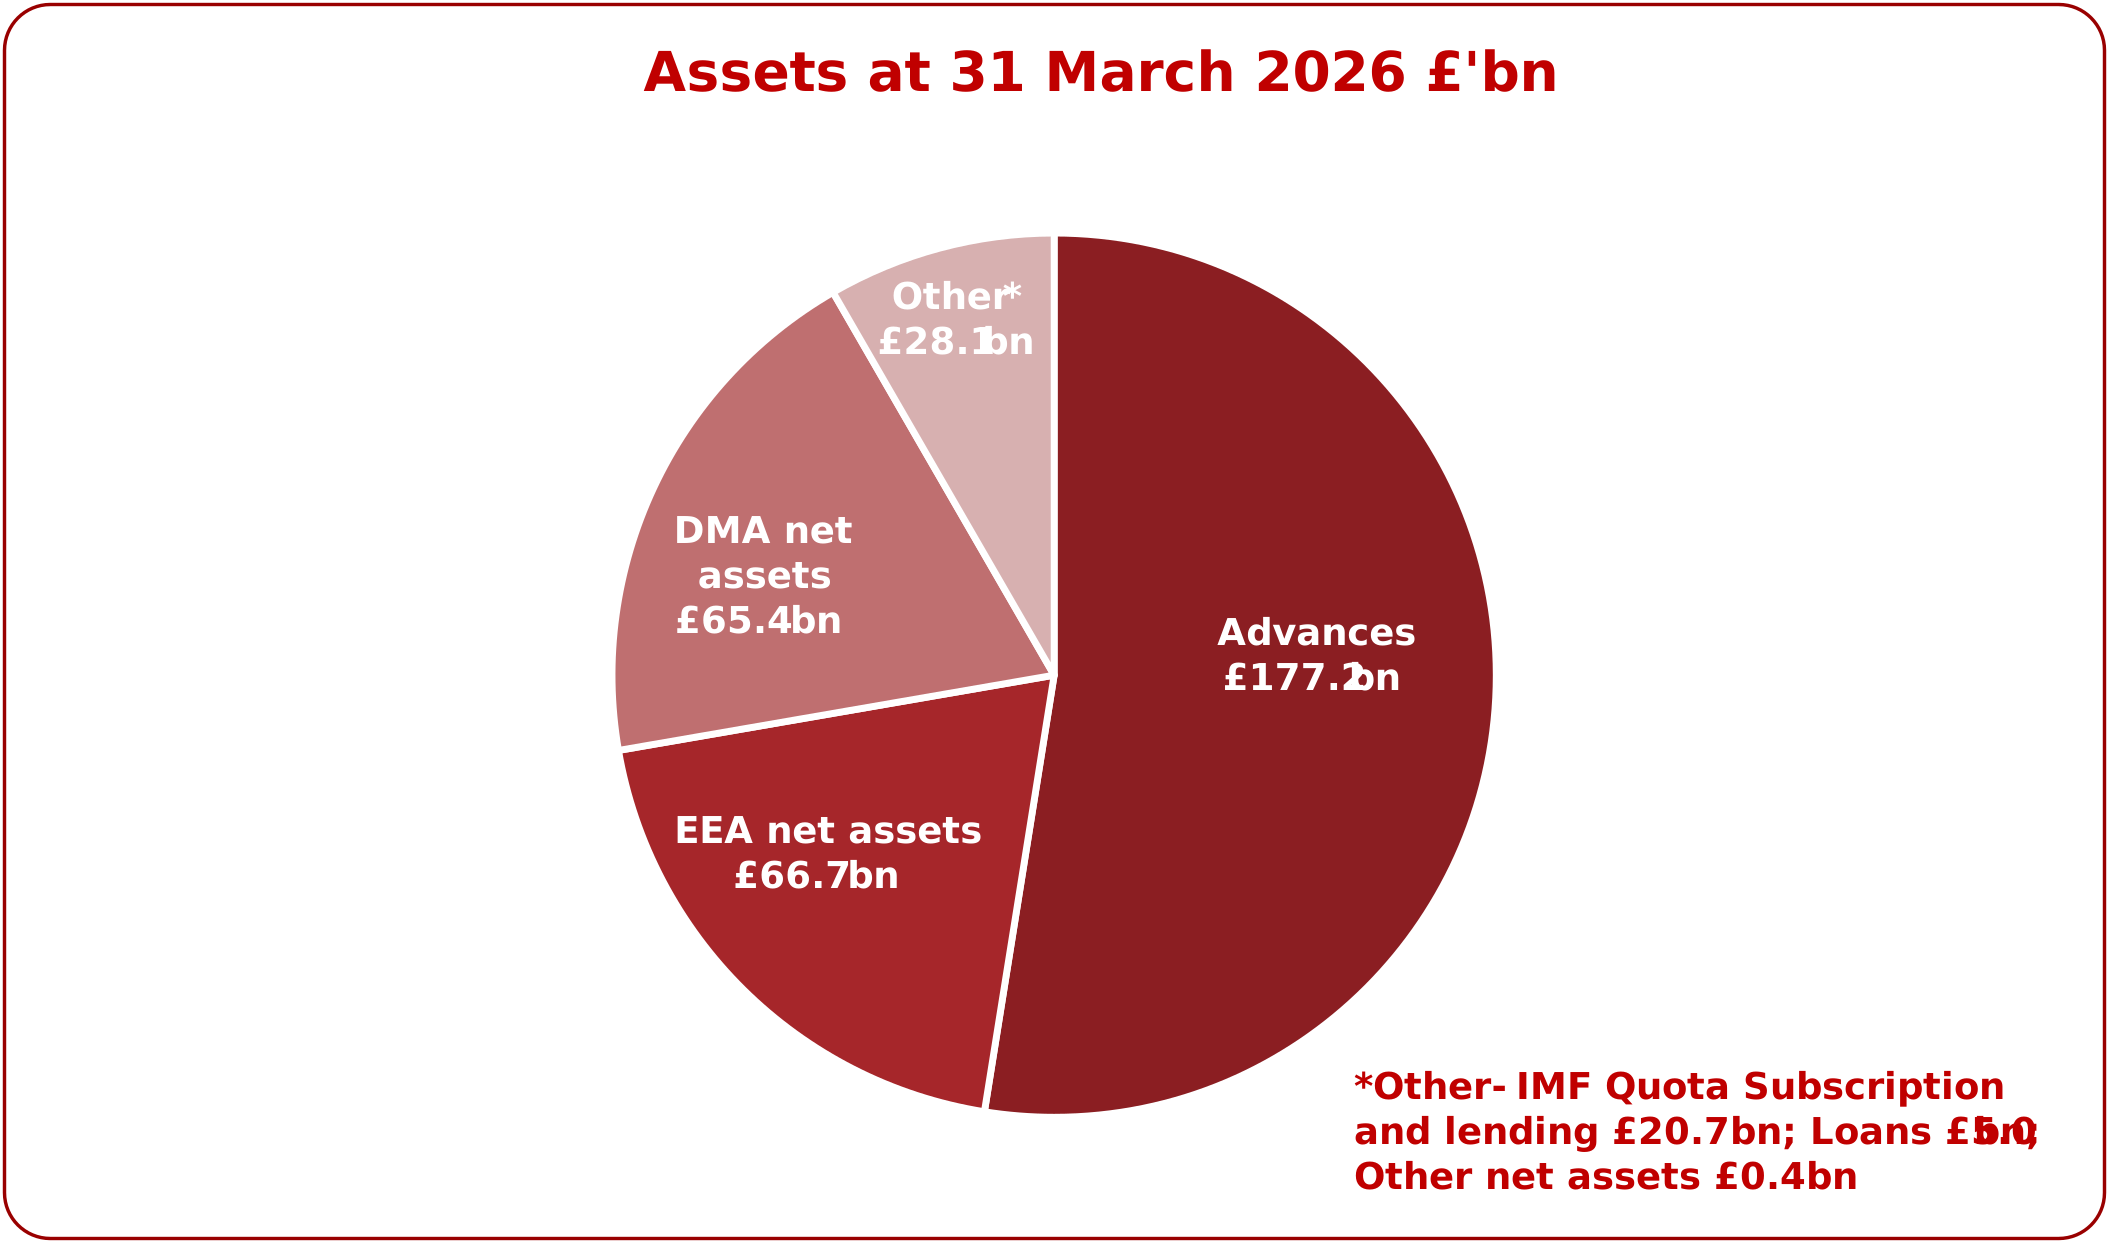
This was driven by higher advances and other assets. Advances increased by £3.6 billion, mainly due to a £6.1 billion increase in advances to the PWLB, where lending exceeded repayments during the year, partly offset by a £2.5 billion reduction in the advance to the EEA. Other assets increased by £15.9 billion, including a £14.5 billion increase in the net assets of the EEA, mainly reflecting higher gold prices, net interest income and fair value and exchange-rate gains on financial assets. DMA net assets also increased by £1.6 billion. (See Note 6 Advances and Note 8 Other Assets)
Liabilities
The NLF’s total gross liabilities increased by £163.0 billion from £3,100.0 billion at 31 March 2025 to £3,263.0 billion at 31 March 2026.
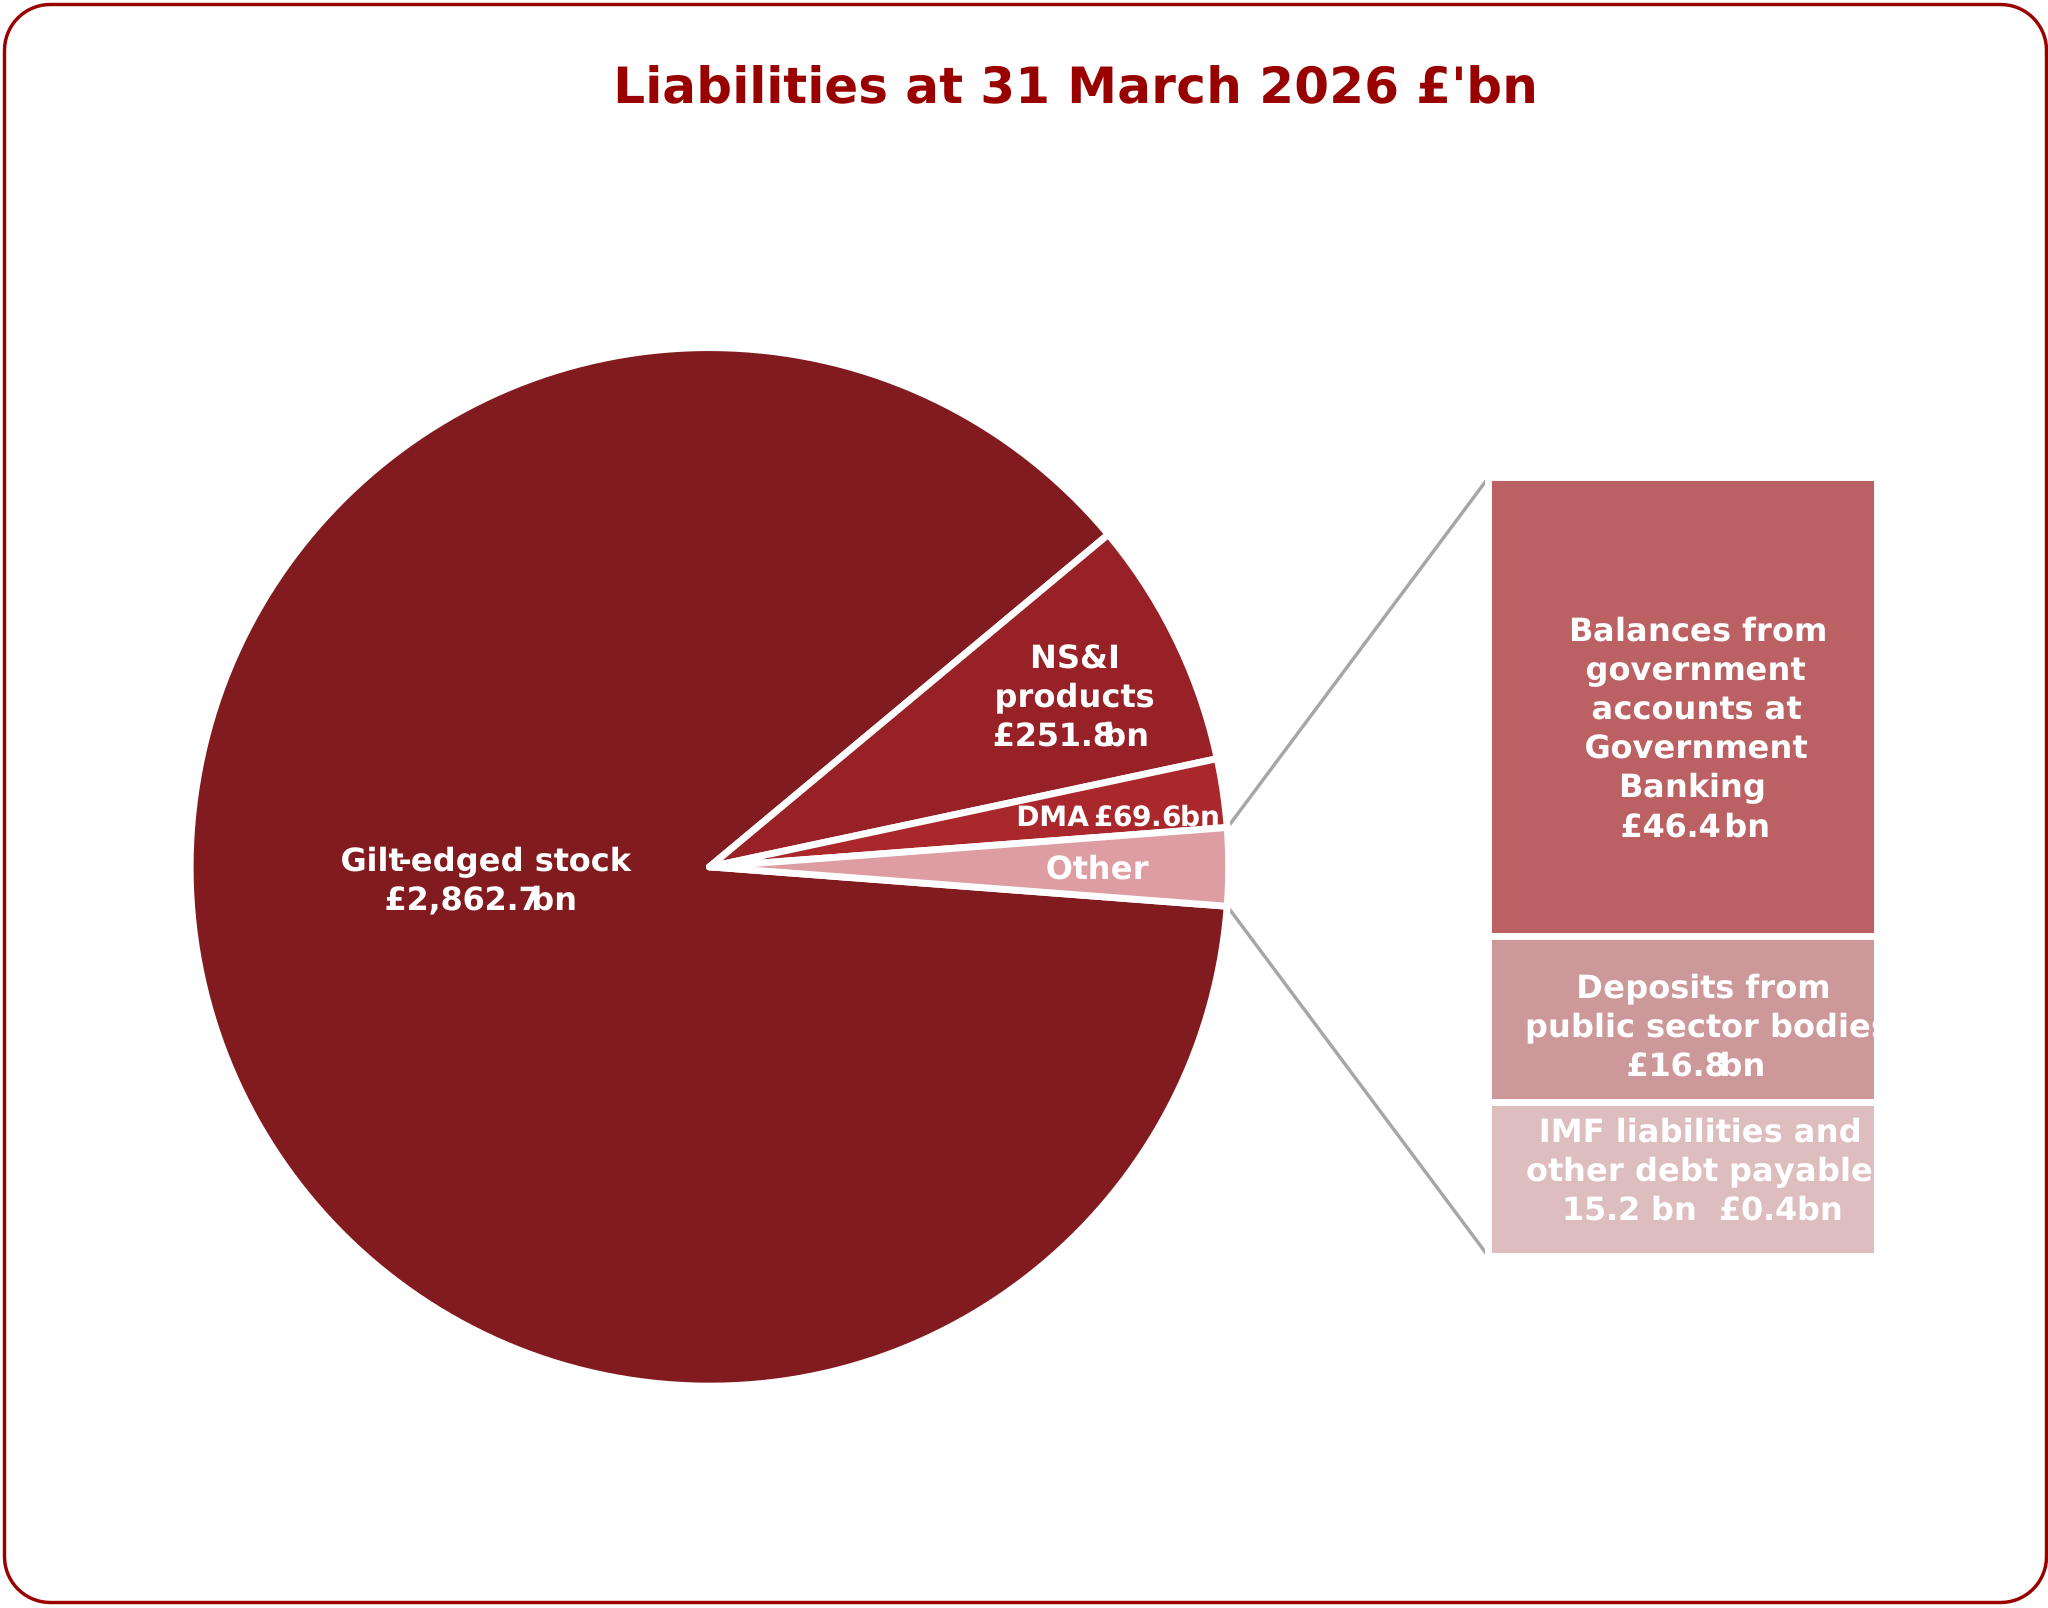
The increase was mainly due to a £163.7 billion increase in Gilt-edged securities (Note 10, Gilt-edged stock), reflecting the net effect of gilt issuance and redemptions during the year, together with non-cash movements including indexation and the amortisation of issuance premiums and discounts. NS&I products increased by £11.6 billion, as deposits and accrued financing costs exceeded repayments. This was partly offset by a £12.0 billion decrease in other debt, mainly comprising an £8.7 billion decrease in the DMA deposit and a £2.7 billion decrease in balances held at Government Banking. (Note 12. Other debt payable).
Public Sector Net Debt
As a result of the increase in liabilities exceeding the increase in assets, the net liabilities of the Fund increased by £143.1 billion, from £2,782.5 billion in 2024-25 to £2,925.6 billion in 2025-26. This is matched by a corresponding claim on the CF under section 19(1) of the National Loans Act 1968.
The NLF both lends to, and borrows from, other parts of the public sector. For example, it makes advances to the PWLB and borrows directly from a range of public sector bodies, as set out in Note 12, Other debt payable. In addition, some gilts issued by the NLF are held within the public sector, including by the DMA for use as collateral in its money market activities and by the Bank of England through the Asset Purchase Facility.
The DMA also has significant advances to and from the NLF. The NLF’s net liabilities are not the same as Public Sector Net Debt (PSND), which measures the net debt of the public sector as a whole after eliminating balances between public sector bodies. PSND figures are published jointly by HM Treasury and the Office for National Statistics in the monthly Public Sector Finances Statistical Bulletin, available on the ONS and GOV.UK websites.
International Support
The UK continued to support the International Monetary Fund (IMF) through the NLF in 2025-26, in line with our commitments as an IMF member. This support is provided through the UK’s quota subscription and other lending arrangements. The UK’s quota commitment to the IMF is currently fixed at SDR 20.2 billion (£20.7 billion at the 31 March 2026 exchange rate[footnote 1]).
The UK also supports the Fund’s New Arrangements to Borrow (NAB) and Bilateral Borrowing Agreements (BBAs). These provide supplementary resources that the IMF can call on if quota resources are exhausted, and which serve as the second and third lines of defence respectively. The UK’s commitments under these arrangements are SDR 19.0 billion (£19.5 billion) for the NAB and SDR 4.0 billion (£4.1 billion) for the BBAs.
Overall, the UK’s commitment to the IMF’s general resources, comprising quota, NAB and BBAs stands at SDR 43.1 billion (£44.3 billion). This has been unchanged since 1 January 2021.
The International Monetary Fund’s 16th General Review of Quotas (GRQ) concluded in December 2023 with agreement on a 50% increase in members’ quotas. The changes have not yet taken effect, and the deadline for members to consent to their quota increases has been extended to 15 November 2026[footnote 2]. If the required conditions are met, the UK’s quota subscription will increase by SDR 10.1 billion to SDR 30.2 billion (£31.0 billion), alongside the full rollback of the Bilateral Borrowing Agreements and a partial rollback of the New Arrangements to Borrow from SDR 19.0 billion to SDR 15.9 billion. The UK’s total commitment to the IMF’s general resources would then increase to SDR 46.1 billion (£47.3 billion), a net increase of SDR 3.0 billion (£3.1 billion).
The NLF’s net exposure to the IMF of £5.5 billion at 31 March 2026 (2024-25: £5.2 billion) is described in Note 9, IMF quota subscription and lending. The IMF maintains precautionary balances of retained earnings to absorb any losses it may incur. As at 31 March 2026, any losses that may be incurred by the IMF on loans to its member countries are not expected to result in losses to the NLF.
Bank of England Asset Purchase Facility Fund
The Bank of England Asset Purchase Facility Fund (BEAPFF) is a wholly owned subsidiary of the Bank of England that was set up in 2009. The BEAPFF is authorised to purchase assets financed by the issuance of central bank reserves (a process known as ‘quantitative easing’).
As at 31 March 2026 £456.1 billion (2024-25: £548.7 billion) of gilts (on an amortised cost basis) from the NLF were held by the Bank of England for quantitative easing. Under an indemnity agreement between HM Treasury and the Bank of England, any excess funds held in the facility, are transferred to HM Treasury to be paid to the CF as Extra Receipts, while cash shortfalls are covered by HM Treasury via quarterly payments.
Since 2012 the BEAPFF has made net transfers of £21.3 billion to HM Treasury (2024-25: £38.0 billion) from coupon payments on purchased gilts net of interest and realised profit or losses upon the sale and redemption of gilts as quantitative easing unwinds, a process known as quantitative tightening. On 17 September 2026 the Monetary Policy Committee at the Bank of England set out several changes to quantitative tightening, including a multiyear strategy for unwinding the BEAPFF. More information on the scheme can be found on the Bank of England’s website and in HM Treasury’s Annual Report and Accounts.
Long-term expenditure trends
Since the function of the NLF is to account for government borrowing and lending, it has no long-term expenditure trends. Historical total comprehensive expenditure is shown in the Performance Analysis.
Sustainability reporting
Operationally, the NLF forms part of HM Treasury and has no separate staff, estate or buildings. Its direct environmental impact is therefore captured within HM Treasury’s wider departmental sustainability reporting. Further information on environmental performance, climate change adaptation and how sustainability considerations are embedded in decision-making and assurance processes is provided in the Performance Report of HM Treasury’s Annual Report and Accounts.
James Bowler
Accounting Officer
HM Treasury
5 November 2026
2. Accountability Report
The Accountability Report has been prepared in accordance with the Government Financial Reporting Manual (FReM), to the extent that its requirements are relevant to the National Loans Fund (NLF). The NLF is administered by HM Treasury and does not have a separate board, workforce, estate or voted Estimate. Where disclosures are not applicable to the NLF, this is explained in the relevant section.
- Corporate governance report which explains the governance framework for the NLF, including the Statement of Accounting Officer’s responsibilities, the Governance Statement, and the arrangements for risk management, internal control and assurance.
- Remuneration and staff report which explains why separate remuneration and staff disclosures are not applicable to the NLF and signposts to HM Treasury’s Annual Report and Accounts for departmental staffing information.
- Parliamentary accountability and audit report which includes key Parliamentary accountability information on regularity of expenditure, losses and special payments, fees and charges, gifts, remote contingent liabilities and the Certificate and Report of the Comptroller and Auditor General to the Houses of Parliament.
2.1 Corporate governance report
The NLF is administered by HM Treasury and does not have its own workforce. All staff involved in administering the Fund are employees of HM Treasury.
Conflicts of interest
HM Treasury requires all employees to disclose any actual or perceived conflict of interest. Conflicts of interest may be financial and can also stem from the interests of household members or other associates; all potential conflicts must be declared and assessed to ensure they do not undermine integrity, reputation or decision-making of HM Treasury.
Staff receive clear guidance on how to identify and manage conflicts, and what to do if one arises. There is a strong process in place for declaring, reviewing, approving, mitigating and recording both actual and perceived conflicts. With proportionate measures put in place to manage them and sanctions (up to contract termination) for failure to declare or comply, whether intentional or not. The declarations process utilises a digital system, which has enhanced both the efficiency and accessibility of declaring conflicts across the department
In 2025-26, no material conflicts of interest have been noted by the senior management overseeing the NLF (2024-25: none).
Personal data related incidents
The NLF does not hold any protected personal data.
Statement of Accounting Officer’s responsibilities
Under section 21(1) of the National Loans Act 1968, HM Treasury is required to prepare an account relating to the National Loans Fund for each financial year in the form and on the basis considered set out in the Accounts Direction. The Account is prepared on an accruals basis and should give a true and fair view of the state of affairs of the Fund and of its Comprehensive Net Expenditure and cash flows for the financial year.
In preparing the Account the Accounting Officer should:
- observe the relevant accounting and disclosure requirements of the FReM in so far as they are relevant to the Account and apply suitable accounting policies on a consistent basis
- make judgements and estimates on a reasonable basis
- prepare the accounts on a going concern basis as defined in the FReM
- confirm that the annual report and accounts as a whole, are fair, balanced and understandable and take personal responsibility for the annual report and accounts and the judgements required for determining that they are fair, balanced and understandable.
As HM Treasury’s Principal Accounting Officer, I am the Accounting Officer for the NLF. The responsibilities of an Accounting Officer, including responsibility for the propriety and regularity of the public finances for which the Accounting Officer is answerable and for keeping proper records, are set out in Managing Public Money.
Statement regarding the disclosure of information to auditors
As Accounting Officer, I have taken all the steps that I ought to have taken to make myself aware of any relevant audit information and to establish that the NLF’s auditors are aware of that information. So far as I am aware, there is no relevant audit information of which the auditors are unaware.
I also confirm that the annual report and accounts are fair, balanced, and understandable and I take personal responsibility for judgements required for determining that they are fair, balanced and understandable.
Audit arrangements
The NLF accounts are audited by the Comptroller and Auditor General (C&AG) under the requirements of the National Loans Act 1968. The National Audit Office (NAO) performs the external audit on behalf of the C&AG and bears the cost of all external audit work performed on the NLF. No non-audit work was undertaken by the NAO in relation to the NLF in 2025-26.
2.2 Governance Statement
Governance overview
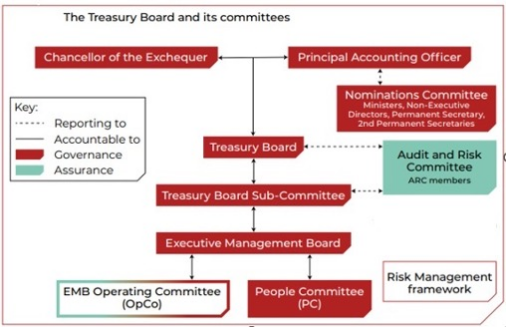
The NLF is managed within HM Treasury’s wider governance, risk management and internal control framework. This framework is set out in HM Treasury’s Annual Report and Accounts 2025-26 and includes HM Treasury Board’s assessment of compliance with the Corporate Governance Code for central government departments.
The Chancellor of the Exchequer, as Minister in charge of HM Treasury, is responsible and answerable to Parliament on all the policies, decisions and actions of HM Treasury, and ultimately of the NLF.
As Accounting Officer for the NLF, I am personally responsible and accountable to Parliament for the organisation and quality of management of the NLF, including its use of public money and the stewardship of its assets, in line with those responsibilities assigned to me in Managing Public Money.
This statement explains how that departmental framework applies to the NLF, how NLF-specific risks and controls are managed by the Exchequer Funds and Accounts team, and how assurance is provided to me as Accounting Officer.
Audit and Risk Committee (ARC)
1.1 HM Treasury’s Audit and Risk Committee provides independent advice and challenge to the Treasury Board, the Permanent Secretary as Principal Accounting Officer, and HM Treasury’s additional Accounting Officers on risk, internal control, governance and financial reporting. Its remit includes oversight of the integrity of the financial statements for the Consolidated Fund, National Loans Fund, Contingencies Fund, Exchange Equalisation Account, HM Treasury’s Annual Report and Accounts and Whole of Government Accounts.
The Committee oversees the work of the Government Internal Audit Agency (GIAA) and the NAO, considers the adequacy of the assurance available to the Board and Accounting Officers, and holds pre-meeting discussions with the NAO and GIAA where needed. Representatives from both organisations attend meetings as appropriate.
Internal audit forms a key part of HM Treasury’s governance, risk management and internal control framework. It provides objective assurance to the Principal Accounting Officer on whether controls are properly designed and operating effectively. The Committee approves the annual Internal Audit Plan, which is risk based, forward looking and aligned to the department’s strategic objectives.
HM Treasury recognises the importance of maintaining an appropriate balance of skills, experience and capacity across its governance structures. In line with the ARC Handbook, the ARC will consider the adequacy of skills, experience and capacity across the Committee and will undertake a formal skills audit in 2026-27 to assess whether any capability gaps exist and to inform future Committee composition.
Members of the Committee are appointed by the Chair along with the Principal Accounting Officer. The Committee met six times during 2025-26. Membership of the committee at included:
| Committee member | Role | Attended |
|---|---|---|
| Edward Twiddy[footnote 3] | Chair of the Audit and Risk Committee | 4/4 |
| Sir Edward Braham | Member of the Audit and Risk Committee | 5/6 |
| Catherine Vaughan[footnote 3] | Member of the Audit and Risk Committee | 4/4 |
| Former committee members leaving in year | ||
| Jane Hanson CBE (to 31/12/2025)[footnote 3] | Member of the Audit and Risk Committee | 4/4 |
| Zarin Patel[footnote 3] (to 31/07/2025) | Chair of the Audit and Risk Committee | 2/2 |
The Committee has a robust Conflicts of Interest Policy, which requires members to excuse themselves from discussions where potential conflicts may occur. Members are required to inform me about any potential conflicts and highlight these at the start of each meeting as appropriate.
Internal Audit
Internal audit for the NLF is provided by GIAA as part of its wider work on the HM Treasury group. During 2025-26, GIAA reviewed the governance, accuracy and completeness of NLF transactions and found no errors. A substantial opinion was issued, providing assurance on the adequacy and effectiveness of the risk management, control and governance arrangements relevant to the Fund.
During 2025-26, internal audit work undertaken by GIAA across business continuity and resilience, including cyber related dependencies, confirmed that core controls are in place and operating effectively while identifying opportunities to further strengthen elements of the control framework.
HM Treasury is taking forward actions to support continuous improvement. This is consistent with the department’s wider approach to governance, risk management and internal control, as set out in HM Treasury’s Annual Report and Accounts.
Management of the National Loans Fund
The NLF is managed by the Treasury Accountant and the Exchequer Funds and Accounts (EFA) team within HM Treasury, overseen by the Group Finance Director. Any matters concerning the NLF are reported directly to me.
Reporting to HM Treasury’s Boards
The NLF operates within HM Treasury’s wider governance and risk management framework. Departmental risk reporting to HM Treasury’s Boards covers strategic and operational risks across the department. Risks specific to the administration and operation of the NLF are identified, assessed and managed through EFA’s control and risk management processes.
HM Treasury’s risk management framework supports the identification and management of risks to the department’s strategic objectives. Directors, specialist Risk Groups and the Operating Committee and the Executive Management Board (EMB) are responsible for monitoring, challenging and reporting on performance against risks and HM Treasury’s objectives.
HM Treasury’s approach to risk management is compliant with the principles set out in The Orange Book. In accordance with this guidance, risk management is embedded in the department’s governance, leadership, and activities. HM Treasury’s ARC supports the Accounting Officers in overseeing the Risk Management Framework.
Organisational risks that exceed the department’s risk appetite are escalated to senior managers via quarterly risk reporting and, where necessary for appropriate action. The EFA’s control and risk management processes feed into this.
In 2025-26, the department undertook comprehensive work to review and strengthen its risk and crisis management frameworks. This resulted in streamlined reporting, clear lines of accountability and escalation, and refreshed business continuity arrangements. This will enable the department to respond more effectively to the crystallisation of acute risks in the future.
Following the publication of the updated 2025 National Risk Register in January 2026, the department continues to own four risks under the Lead Government Department Model. Updates on these four risks are included in the Quarterly risk note.
Throughout 2025-26 the HM Treasury Operating Committee held discussions on the risk landscape and undertook deep dives into high-priority risks flagged through the quarterly reporting system. These processes have produced tangible recommendations for teams to improve the department’s resilience. Risks assessed this year include cyber security, departmental oversight of Arm’s Length Body (ALB) governance arrangements and impacts from the voluntary exit scheme on workforce planning. EMB has also addressed varied risks through its regular meetings.
National Loans Fund Risk Management
EFA manages NLF-specific risks within HM Treasury’s overall risk management framework. These risks relate principally to the administration of the Fund, the regularity and accuracy of very high-value transactions, business continuity, information security, reliance on key systems and delivery by operational partners.
The Treasury Accountant has day-to-day responsibility for risk management of the funds managed by EFA, ensuring that my financial, regularity and propriety responsibilities as Accounting Officer for the NLF are met. Key operational staff involved in the NLF are trained and equipped to manage risks within their roles.
Risk management underpins all EFA processes, including business continuity resilience planning for the public funds for which EFA is responsible. Business continuity arrangements are regularly tested, both within EFA and business partners, and lessons learned are used to strengthen and improve these arrangements.
Cyber security and information resilience form an integral part of this overall control environment. The administration of the NLF relies on HM Treasury systems, infrastructure and cross government partners to support critical financial operations. These arrangements are supported by established security controls, resilience measures and incident response processes, underpinned by ongoing monitoring, assurance activity and alignment with cross-government standards. Business continuity planning explicitly considers disruption scenarios, including those arising from cyber incidents and wider system dependencies
The Treasury Accountant also chairs the Public Finance Business Continuity group, a network that brings together relevant teams across HM Treasury, the Bank of England, Debt Management Office, NAO, HMRC and Government Banking. The Group helps ensure business continuity risks are identified, managed and addressed in a consistent and coordinated manner across all operational partners involved in the stewardship of Exchequer funds. Annual certificates of assurance are obtained from all member organisations.
The risk management strategy includes periodic horizon scanning to identify any changes in risk exposure, to evaluate their potential impact and to determine appropriate mitigating actions. Significant risk issues are recorded in a risk register and are assessed by likelihood and impact. Each risk has an appointed risk owner, who is responsible for its management. The risk register is reviewed quarterly by EFA management and is provided to me alongside the quarterly risks and controls report.
The system of internal control
As Accounting Officer, I am responsible for maintaining a sound system of internal control that supports the achievement of the NLF’s policies, aims and objectives, whilst safeguarding the public funds and assets for which I am personally responsible, in accordance with the responsibilities assigned to me in Managing Public Money.
The system of internal control is designed to manage risk to an acceptable level, balancing the impact of potential risks with the resources required to manage them, rather than eliminate all risk. It can therefore only provide reasonable and not absolute assurance of effectiveness. The system of internal control is based on an ongoing process designed to identify and prioritise the risks to the achievement of the NLF’s policies, aims, and objectives; to evaluate the likelihood of those risks being realised and the impact should they be realised; and to manage them efficiently, effectively and economically.
The system of internal control has been in place throughout the year ended 31 March 2026 and up to the date of approval of the financial statements and accords with HM Treasury guidance. During the year there were no significant changes to the control environment.
Risk profile
The NLF is managed generally within the framework of HM Treasury’s system of internal control. Within that broader framework, EFA identifies and manages the principal risks specific to the administration and operation of the NLF. This includes resourcing the administration of the NLF, security, and the management of risks across HM Treasury’s business.
The key operational and control risks specific to the NLF, together with the main controls and sources of assurance in place to mitigate them, are set out in the table below. These risks should be read alongside, rather than as a substitute for, HM Treasury’s wider departmental risk reporting.
| Risk area | Description | Key controls and assurance | Status |
|---|---|---|---|
| Regularity and accuracy of transactions | Risk that NLF payments or receipts are made incorrectly, unlawfully or fraudulently, leading to financial loss, misstatement or reputational damage. | Segregation of duties is enforced through system permissions and payment approval arrangements. Payment instructions are generated from underlying transaction records, reducing manual input risk. The NAO Exchequer Section approves the regularity of payments in advance and reconciles NLF transactions daily, providing additional assurance to Parliament. | Stable |
| Financial reporting and accounting | Risk of material misstatement in the accounts arising from system error, incorrect inputs, incomplete reconciliations or misapplication of accounting requirements. | Application controls support the recording and processing of NLF transactions. Monthly management accounts and reconciliations are reviewed by EFA management, with oversight by the Treasury Accountant and Accounting Officer. Internal audit and external audit provide further assurance over the financial reporting control environment. | Stable |
| Systems resilience | Risk that failure of HM Treasury systems, infrastructure or communication channels prevents the processing of payments or access to critical financial data. | HM Treasury’s network infrastructure is supported by resilience arrangements, including failover capability. Business continuity arrangements cover critical systems and dependencies and are subject to periodic testing and review. | Stable |
| Business continuity and operational resilience | Risk that EFA operations are unable to continue effectively during adverse circumstances, including cyber incidents, system disruption or wider business continuity events. | Key EFA staff are cross trained to support operational resilience. Business continuity arrangements are tested through HM Treasury-wide structures and through the Public Finance Business Continuity group. Lessons learned are used to strengthen processes and controls. | Stable |
| Counterparty and partner delivery | Risk that principal counterparties or operational partners fail to deliver essential services or meet agreed performance standards, resulting in operational disruption, delay or weakened controls. | Service level agreements and established working arrangements set out responsibilities, monitoring arrangements and escalation routes. Annual certificates of assurance are obtained from relevant partner organisations. | Stable |
| Information and cyber security | Risk that confidential, sensitive or operational information is lost, disclosed, altered or accessed without authorisation, with legal, financial or reputational consequences. | Information risk is managed through HM Treasury policies and controls, including access management, encryption, physical security, IT security and incident response processes. EFA’s Data Handling Policy is reviewed periodically. | Stable |
| Financial risks arising from linked accounts | Risk that financial performance or exposures in the DMA or EEA affect the NLF’s reported results. | Financial risks inherent in the DMA and EEA are managed through the risk and control frameworks of those accounts and their Accounting Officers. The impact on the NLF is monitored through financial reporting and account preparation processes. Further information is provided in Note 16. | Stable |
Review of effectiveness
In line with HM Government guidance, set out within the Corporate Governance Code for central government departments, I have reviewed the effectiveness of the system of internal control.
My review is informed by the work of GIAA, which provided positive assurance over the management and control of the NLF in 2025-26; by EFA management, which is responsible for maintaining the NLF control framework; by the operation of key controls and risk reporting throughout the year; and by comments made by the external auditors in their management letter and other reports.
I have also taken account of the oversight provided by HM Treasury’s Audit and Risk Committee, including its review of assurance over risk management, internal control and financial reporting. The Committee considered the 2025-26 accounts in draft and provided its views before I formally signed the accounts. Further information on HM Treasury’s overall system of governance, including board effectiveness, attendance, compliance with the Corporate Governance Code and the quality of management information reviewed, is reported in HM Treasury’s Annual Report and Accounts.
No significant internal control issues, including data-related incidents, were identified in 2025-26. No significant new risks specific to the operational management and performance of the NLF were identified during the year, and no ministerial directions relating to the NLF’s operations were given in 2025-26.
Based on the evidence described above, including the operation of the control framework, the management of NLF-specific risks, the assurance provided by GIAA, and the oversight of the Audit and Risk Committee, I am satisfied that the system of internal control was effective throughout the financial year and remains so on the date I sign this report.
2.3 Remuneration and staff report
The NLF does not have employees, directors, board members or remuneration arrangements of its own. It is administered by HM Treasury, and all staff involved in administering the Fund are employees of HM Treasury. Staff costs, remuneration disclosures and related workforce information are therefore reported through HM Treasury’s Annual Report and Accounts rather than separately in this Account.
2.4 Parliamentary accountability and audit report
The Parliamentary accountability disclosures in this section are subject to audit where indicated. The Certificate and Report of the Comptroller and Auditor General sets out the auditor’s responsibilities in relation to the financial statements, regularity and the parts of the Accountability Report subject to audit.
Regularity of expenditure (audited)
The expenditure and income of the NLF were applied to the purposes intended by Parliament.
The borrowings, investments and lending of the NLF were applied to the purposes intended by Parliament.
Losses and special payments (audited)
Currency losses from transactions with the IMF are disclosed within the financial statements. There were no other losses or special payments in the year (2024-25: nil).
Fees and charges (audited)
The NLF does not have any fees or charges.
Gifts (audited)
The NLF did not make any gifts during the financial year.
Remote contingent liabilities (audited)
The NLF is required to disclose liabilities for which the likelihood of a transfer of economic benefit in settlement is too remote to meet the disclosure requirements of IAS 37.
These disclosures are required by Managing Public Money and are related to parliamentary accountability. All contingent liabilities must be reported to Parliament by a departmental minute so that Parliament has the opportunity to debate the merits of the item and to bind the government to honour the obligation. To meet the relevant disclosure requirements the NLF is required to provide a brief description of the nature of each contingent liability and where practical, an estimate of its financial effect.
In many cases, entering into arrangements that create a contingent liability has a distinct policy advantage; as they allow the government to intervene where it deems necessary, whilst not requiring an injection of government funding. While the risk of settlement may be remote, if they did crystallise there is a possibility that the government may have to distribute funds.
A remote contingent liability represents the maximum potential exposure assuming trigger events occur, and the maximum exposure crystallises. If any of the contingent liabilities detailed below were to crystallise and HM Treasury was required to settle an obligation this would be achieved through the normal Supply Estimates process. The NLF has two such liabilities outlined below.
Bank of England Issue Department
Under the National Loans Act 1968 section 9(3), the NLF has a contingent liability to the Bank of England Issue Department in respect of that part of the assets backing the note issue that is not represented by government securities. The note issue refers to the process by which the Bank of England Issue Department creates and distributes banknotes (physical currency) for use in the UK economy. The value of these banknotes in circulation is backed by assets which typically include government securities and other approved assets.
This liability would only crystallise if government securities were insufficient to meet demand from holders of notes to exchange them for another instrument. The contingent liability was £95.9 billion at 31 March 2026 (£90.1 billion at 31 March 2025). No obligations crystallised or expired in 2025-26 (2024-25: nil).
Commissioners for the Reduction of the National Debt
The NLF has a contingent liability to the Commissioners for the Reduction of the National Debt (CRND) in respect of unclaimed dividends received in previous years. This represents historic uncleared amounts surrendered by the gilts registrar to CRND and then onto the NLF and stood at £30.0 million at 31 March 2026 (£32.0 million at 31 March 2025). This contingent liability would crystallise if holders of gilts requested amounts owed to them in excess of an amount for settlement retained by CRND. No obligations crystallised or expired in 2025-26 (2024-25: nil).
Functional Standards (not subject to audit)
Operationally, the NLF forms part of HM Treasury and does not have separate functional standards arrangements of its own. Further information on HM Treasury’s application of the Government Functional Standards is provided in the Parliamentary accountability and audit report in HM Treasury’s Annual Report and Accounts.
James Bowler
Accounting Officer
HM Treasury
5 November 2026
2.5 The Certificate and Report of the Comptroller and Auditor General to the Houses of Parliament
Opinion on financial statements
I certify that I have audited the financial statements of the National Loans Fund for the year ended 31 March 2026 under the National Loans Act 1968.
The financial statements comprise the National Loans Fund’s
- Statement of Financial Position as at 31 March 2026;
- Statement of Comprehensive Net Expenditure, Statement of Cash Flows and Statement of Changes in the Liability of the Consolidated Fund to the National Loans Fund for the year then ended; and
- the related notes including the significant accounting policies.
The financial reporting framework that has been applied in the preparation of the financial statements is applicable law and the UK adopted International Accounting Standards.
In my opinion, the financial statements:
- give a true and fair view of the state of the National Loans Fund’s affairs as at 31 March 2026 and its total comprehensive Expenditure for the year then ended; and
- have been properly prepared in accordance with the National Loans Act 1968 and HM Treasury directions issued thereunder.
Opinion on regularity
In my opinion, in all material respects, the income and expenditure recorded in the financial statements have been applied to the purposes intended by Parliament and the financial transactions recorded in the financial statements conform to the authorities which govern them.
Basis for opinions
I conducted my audit in accordance with International Standards on Auditing (UK) (ISAs UK), applicable law and Practice Note 10 Audit of Financial Statements and Regularity of Public Sector Bodies in the United Kingdom (2024). My responsibilities under those standards are further described in the Auditor’s responsibilities for the audit of the financial statements section of my certificate.
Those standards require me and my staff to comply with the Financial Reporting Council’s Revised Ethical Standard 2024. I am independent of the National Loans Fund in accordance with the ethical requirements that are relevant to my audit of the financial statements in the UK. In applying the Ethical Standards, I have considered the potential implications for my audit arising from extending a loan staff arrangement with the Office of Value for Money within HM Treasury, to November 2025. The loan staff arrangement concerned one of my directors (unconnected with our audit of the National Loans Fund Accounts prepared by HM Treasury) and was for an initial period of 12 months from September 2024. The arrangement was extended by a further two months so that the secondee was able to support the completion of the Office for Value for Money’s work. I am satisfied that appropriate safeguards have been implemented to protect my and the NAO team’s independence and objectivity throughout the audit. My staff and I have fulfilled our other ethical responsibilities in accordance with these requirements.
I believe that the audit evidence I have obtained is sufficient and appropriate to provide a basis for my opinion.
Conclusions relating to going concern
In auditing the financial statements, I have concluded that the National Loans Fund’s use of the going concern basis of accounting in the preparation of the financial statements is appropriate.
Based on the work I have performed, I have not identified any material uncertainties relating to events or conditions that, individually or collectively, may cast significant doubt on the National Loans Fund’s ability to continue as a going concern for a period of at least twelve months from when the financial statements are authorised for issue.
My responsibilities and the responsibilities of the Accounting Officer with respect to going concern are described in the relevant sections of this certificate.
The going concern basis of accounting for the National Loans Fund is adopted in consideration of the requirements set out in HM Treasury’s Government Financial Reporting Manual, which requires entities to adopt the going concern basis of accounting in the preparation of the financial statements where it is anticipated that the services which they provide will continue into the future.
Other information
The other information comprises information included in the Annual Report but does not include the financial statements and my auditor’s certificate and report thereon. The Accounting Officer is responsible for the other information.
My opinion on the financial statements does not cover the other information and, except to the extent otherwise explicitly stated in my certificate, I do not express any form of assurance conclusion thereon.
My responsibility is to read the other information and, in doing so, consider whether the other information is materially inconsistent with the financial statements or my knowledge obtained in the audit, or otherwise appears to be materially misstated.
If I identify such material inconsistencies or apparent material misstatements, I am required to determine whether this gives rise to a material misstatement in the financial statements themselves. If, based on the work I have performed, I conclude that there is a material misstatement of this other information, I am required to report that fact.
I have nothing to report in this regard.
Opinion on other matters
In my opinion the part of the Remuneration and Staff Report to be audited has been properly prepared in accordance with HM Treasury directions issued under the National Loans Act 1968.
In my opinion, based on the work undertaken in the course of the audit:
- the parts of the Accountability Report subject to audit have been properly prepared in accordance with HM Treasury directions issued under the National Loans Act 1968; and
- the information given in the Performance Report and Accountability Report for the financial year for which the financial statements are prepared is consistent with the financial statements and is in accordance with the applicable legal requirements.
Matters on which I report by exception
In the light of the knowledge and understanding of the National Loans Fund and its environment obtained in the course of the audit, I have not identified material misstatements in the Performance Report and Accountability Report.
I have nothing to report in respect of the following matters which I report to you if, in my opinion:
- adequate accounting records have not been kept by the National Loans Fund or returns adequate for my audit have not been received from branches not visited by my staff; or
- I have not received all of the information and explanations I require for my audit; or
- the financial statements and the parts of the Accountability Report subject to audit are not in agreement with the accounting records and returns; or
- the Governance Statement does not reflect compliance with HM Treasury’s guidance.
Responsibilities of the Accounting Officer for the financial statements
As explained more fully in the Statement of Accounting Officer’s Responsibilities, the Accounting Officer is responsible for:
- maintaining proper accounting records;
- providing the C&AG with access to all information of which management is aware that is relevant to the preparation of the financial statements such as records, documentation and other matters;
- providing the C&AG with additional information and explanations needed for his audit;
- providing the C&AG with unrestricted access to persons within the National Loans Fund from whom the auditor determines it necessary to obtain audit evidence;
- ensuring such internal controls are in place as deemed necessary to enable the preparation of financial statements to be free from material misstatement, whether due to fraud or error;
- preparing financial statements which give a true and fair view in accordance with HM Treasury directions issued under the National Loans Act 1968;
- preparing the annual report, in accordance with HM Treasury directions under the National Loans Act 1968; and
- assessing the National Loans Fund’s ability to continue as a going concern, disclosing, as applicable, matters related to going concern and using the going concern basis of accounting unless the Accounting Officer anticipates that the services provided by the National Loans Fund will not continue to be provided in the future.
Auditor’s responsibilities for the audit of the financial statements
My responsibility is to audit, certify and report on the financial statements in accordance with the National Loans Act 1968.
My objectives are to obtain reasonable assurance about whether the financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue a certificate that includes my opinion. Reasonable assurance is a high level of assurance but is not a guarantee that an audit conducted in accordance with ISAs (UK) will always detect a material misstatement when it exists. Misstatements can arise from fraud or error and are considered material if, individually or in the aggregate, they could reasonably be expected to influence the economic decisions of users taken on the basis of these financial statements.
Extent to which the audit was considered capable of detecting non-compliance with laws and regulations, including fraud
I design procedures in line with my responsibilities, outlined above, to detect material misstatements in respect of non-compliance with laws and regulations, including fraud. The extent to which my procedures are capable of detecting non-compliance with laws and regulations, including fraud is detailed below.
Identifying and assessing potential risks related to non-compliance with laws and regulations, including fraud
In identifying and assessing risks of material misstatement in respect of non-compliance with laws and regulations, including fraud, I:
- considered the nature of the sector, control environment and operational performance including the design of the National Loans Fund’s accounting policies.
- inquired of management, the National Loans Fund’s head of internal audit, and those charged with governance, including obtaining and reviewing supporting documentation relating to the National Loans Fund’s policies and procedures on:
- identifying, evaluating and complying with laws and regulations;
- detecting and responding to the risks of fraud; and
- the internal controls established to mitigate risks related to fraud or non-compliance with laws and regulations including the National Loans Fund’s controls relating to the National Loans Fund’s compliance with the National Loans Act 1968 and Managing Public Money;
- inquired of management, the National Loans Fund’s head of internal audit, and those charged with governance whether:
- they were aware of any instances of non-compliance with laws and regulations; and
- they had knowledge of any actual, suspected, or alleged fraud;
- discussed with the engagement team regarding how and where fraud might occur in the financial statements and any potential indicators of fraud.
As a result of these procedures, I considered the opportunities and incentives that may exist within the National Loans Fund for fraud and identified the greatest potential for fraud in the following areas: revenue recognition, posting of unusual journals, complex transactions and bias in management estimates. In common with all audits under ISAs (UK), I am required to perform specific procedures to respond to the risk of management override.
I obtained an understanding of the National Loans Fund’s framework of authority and other legal and regulatory frameworks in which the National Loans Fund operates. I focused on those laws and regulations that had a direct effect on material amounts and disclosures in the financial statements or that had a fundamental effect on the operations of the National Loans Fund. The key laws and regulations I considered in this context included the National Loans Act 1968 and Managing Public Money.
Audit response to identified risk
To respond to the identified risks resulting from the above procedures:
- I reviewed the financial statement disclosures and testing to supporting documentation to assess compliance with provisions of relevant laws and regulations described above as having direct effect on the financial statements;
- I enquired of management, the Audit and Risk Committee and in-house legal counsel concerning actual and potential litigation and claims;
- I reviewed minutes of meetings of those charged with governance and the Board and internal audit reports; and
- I addressed the risk of fraud through management override of controls by testing the appropriateness of journal entries and other adjustments; assessing whether the judgements on estimates are indicative of a potential bias; and evaluating the business rationale of any significant transactions that are unusual or outside the normal course of business.
I communicated relevant identified laws and regulations and potential risks of fraud to all engagement team members and remained alert to any indications of fraud or non-compliance with laws and regulations throughout the audit.
A further description of my responsibilities for the audit of the financial statements is located on the Financial Reporting Council’s website. This description forms part of my certificate.
Other auditor’s responsibilities
I am required to obtain sufficient appropriate audit evidence to give reasonable assurance that the expenditure and income recorded in the financial statements have been applied to the purposes intended by Parliament and the financial transactions recorded in the financial statements conform to the authorities which govern them.
I communicate with those charged with governance regarding, among other matters, the planned scope and timing of the audit and significant audit findings, including any significant deficiencies in internal control I identify during my audit.
Report
I have no observations to make on these financial statements.
Gareth Davies
Comptroller and Auditor General
9 November 2026
National Audit Office
157-197 Buckingham Palace Road
Victoria
London, SW1W 9SP
3. Financial Statements
3.1 Statement of Comprehensive Net Expenditure
For the year ended 31 March 2026
| Note | 2025-26 | 2024-25 | |
|---|---|---|---|
| £m | £m | ||
| Financing costs of borrowing | 2 | 98,049 | 86,949 |
| Income from lending operations | 3 | (3,710) | (3,716) |
| Losses / (gains) on foreign exchange transactions | 4 | 4 | 121 |
| Other expenditure | 5 | 6 | 22 |
| Other income | 5 | (20,533) | (13,613) |
| Total comprehensive net expenditure | 73,816 | 69,763 |
The Notes to the Account form part of this Account.
3.2 Statement of Financial Position
As at 31 March 2026
| Note | At 31 March 2026 £m | At 31 March 2025 £m | |
|---|---|---|---|
| Assets | |||
| Advances | 6 | 177,228 | 173,636 |
| Other assets: | 8 | ||
| EEA net assets | 66,664 | 52,172 | |
| DMA net assets | 65,418 | 63,800 | |
| Other assets | 2,441 | 2,625 | |
| IMF Quota Subscription & Lending | 9 | 20,713 | 20,696 |
| Loans | 7 | 4,975 | 4,635 |
| Total assets | 337,439 | 317,564 | |
| Liabilities | |||
| Gilt-edged stock | 10 | 2,862,715 | 2,699,047 |
| National Savings and Investments products | 11 | 251,771 | 240,146 |
| Other debt: | 12 | ||
| DMA deposit | 69,637 | 78,386 | |
| Balances from government accounts in Government Banking: | 46,448 | 49,178 | |
| Deposits from public sector bodies | 16,818 | 17,343 | |
| Other debt payable | 378 | 385 | |
| Liabilities to the IMF | 9 | 15,239 | 15,545 |
| Total liabilities | 3,263,006 | 3,100,030 | |
| Net liabilities | 2,925,567 | 2,782,466 | |
| Liability of the Consolidated Fund to the National Loans Fund | |||
| 2,925,567 | 2,782,466 |
The Notes to the Account form part of this Account.
James Bowler
Accounting Officer
HM Treasury
5 November 2026
3.3 Statement of Cash Flows
For the year ended 31 March 2026
| 2025-26 £m | 2024-25 £m | |
|---|---|---|
| Cash flows from operating activities | ||
| Interest received | 4,017 | 3,641 |
| Other receipts | 3,771 | 4,785 |
| Interest paid | (70,351) | (63,307) |
| Other outflows | 522 | 449 |
| Transfer from the Consolidated Fund for the cost of debt servicing | 62,041 | 54,432 |
| Net cash flow from operating activities | - | - |
| Cash flows from investing activities | ||
| Net advance to the Public Works Loans Board (issued)/repaid | (6,408) | (7,384) |
| Net loans (issued)/repaid | (339) | (11) |
| Net advance to the Exchange Equalisation Account (issued)/repaid | 2,509 | 1,566 |
| Net cash (outflow) / inflow from investing activities | (4,238) | (5,829) |
| Cash flows from financing activities | ||
| Net issuance of government stock | 140,173 | 141,079 |
| Net receipt of cash from National Savings | 8,092 | 5,425 |
| Net increase / (decrease) in other sterling borrowing | (11,853) | 10,604 |
| Net transfers of IMF non-interest-bearing securities | (848) | (94) |
| Net transfers to the Consolidated Fund | (131,326) | (151,185) |
| Net cash inflow / (outflow) from financing activities | 4,238 | 5,829 |
| Net change in cash and cash equivalents | - | - |
| Cash and cash equivalents at beginning and end of year | - | - |
The Notes to the Account form part of this Account.
3.4 Statement of Changes in the Liability of the Consolidated Fund to the National Loans Fund
For the year ended 31 March 2026
| 2025-26 £m | 2024-25 £m | |
|---|---|---|
| Liability of the Consolidated Fund to the National Loans Fund at 1 April | 2,782,466 | 2,615,950 |
| Net cash paid to the Consolidated Fund | 131,326 | 151,185 |
| Payment from the Consolidated Fund for the cost of debt servicing during the year | (62,041) | (54,432) |
| Total comprehensive net expenditure | 73,816 | 69,763 |
| Liability of the Consolidated Fund to the National Loans Fund at 31 March | 2,925,567 | 2,782,466 |
The Notes to the Account form part of this Account.
4. Notes to the Account
4.1 1. Statement of accounting Policies
The following notes form an integral part of these financial statements, providing additional detail and explanation of the reported figures. They set out the accounting policies applied, key judgements and estimates where applicable, and further analysis of material balances.
1.1 Basis of presentation
These financial statements have been prepared in line with the Government Financial Reporting Manual (FReM) 2025-26 to the extent that its requirements are relevant to the National Loans Fund and in accordance with the issued Accounts Direction, see Appendix B. The accounting policies contained in the FReM apply International Financial Reporting Standards (IFRS) as adapted and interpreted for the public sector. Where the FReM permits a choice of accounting policy, for the purpose of giving a true and fair view, the accounting policy which is judged to be the most appropriate to the circumstances of the NLF has been selected. The polices adopted by the NLF are described below and included throughout.
The NLF is the government’s main borrowing and lending account. By the nature of government financing, it is expected that the NLF will show a net liability. By virtue of section 19(1) of the National Loans Act 1968, the net liabilities of the NLF are a liability of the CF.
1.2 Accounting convention
The account presents the results and transactions of the NLF. The Statement of Financial Position is presented in order of liquidity.
1.3 Going Concern
The servicing and redemption of the NLF’s liabilities are expected to be met over the long term mainly through future tax revenue receipts. Whilst the level of receipts in any year is subject to tax policy changes and, relatedly the UK’s economic position, the level of debt required to meet government expenditure, including the servicing of debt, can be maintained by the issuance or reissuance of further debt.
Therefore, in accordance with the FReM, it has been concluded as appropriate to adopt the going concern basis of preparation for the NLF Accounts.
1.4 Standards in issue but not yet effective
Several new accounting standards have been issued but are not yet effective. The NLF will apply new and revised standards once they have been adopted by the public sector as set out in the FReM. Dates for adoption by the public sector of IFRS 18 Presentation and disclosure of financial statements and IFRS 19 Subsidiaries without public accountability: Disclosures have not yet been published.
IFRS 18 Presentation and Disclosure in Financial Statements
IFRS 18 Presentation and Disclosure of Financial Statements was issued in April 2024 and applies to annual reporting periods beginning on or after 1 January 2027. IFRS 18 sets out general and specific requirements for the presentation and disclosure of information in general purpose financial statements.
The objective of IFRS 18 Presentation and Disclosure of Financial Statements is to improve comparability of financial performance between organisations applying IFRS. Once effective, it will replace IAS 1 Presentation of Financial Statements. The impact of adopting this standard is still being assessed. The NLF does not intend to early adopt IFRS 18 Presentation and Disclosure of Financial Statements.
IFRS 19 Subsidiaries without Public Accountability: Disclosures
IFRS 19 Subsidiaries without Public Accountability: Disclosures was issued in May 2024 and applies to annual reporting periods beginning on or after 1 January 2027. The Standard permits certain eligible subsidiaries to apply reduced disclosure requirements when preparing their financial statements.
The NLF does not have subsidiaries and therefore this standard is not expected to impact the financial statements.
There are no other IFRS or IFRIC interpretations that are not yet effective that would be expected to have a material impact on the NLF.
1.5 Significant judgements and estimates
The NLF’s accounting policy for impairment losses arising on financial assets is described below. No impairment losses have been recognised in the year. There are no other areas of the financial statements which are reliant on management’s judgement in the process of applying the Fund’s accounting policies.
Fair values are included for disclosure purposes only and their calculation is described in Note 14, Fair Values. The majority of the NLF’s financial assets have a fixed return. For those products that have a variable return, the current rate applicable to that product is used in the calculation of the finance income or cost. Note 16 applies various assumptions to demonstrate the sensitivity of NLF’s assets and liabilities to changes in interest rates, inflation and foreign currency exchange rates.
1.6 Recognition of finance income and costs
Premium Bond prizes are recognised in the accounts in the period they relate to. Other interest income and financing costs are spread over the expected life of the related financial asset or liability using the effective interest rate method. The method calculates a consistent interest rate that reflects the expected future cashflows of the asset or liability, including any premiums, discounts, and contractual terms. In simple terms, it ensures that interest income and costs are recognised fairly over time rather than all at once.
The majority of the NLF’s financial assets and liabilities have a fixed return. For those that have a variable return, the current rate applicable to that product is used in the calculation of the finance income or cost. Gilts with the same maturity and coupon rate are sometimes issued in separate tranches. Each tranche may be issued with a different premium or discount because of market conditions and therefore with a different effective interest rate. However, once issued, gilts with the same maturity and coupon rate are indistinguishable from each other and so are accounted for as one issue using a weighted average effective interest rate.
1.7 Recognition of finance income – Special Drawing Rights (SDR)
The IMF remunerates the UK in SDRs on its Reserve Tranche Position (RTP) for balances in excess of SDR 0.7 billion and on its bilateral loans. Under section 3(2) of the Exchange Equalisation Act 1979 any SDRs received by the Government must be treated as assets of the EEA, therefore all SDR income is accounted for in the EEA and not the NLF.
1.8 Financial assets and liabilities
The assets and liabilities of the NLF are all accounted for as financial assets and liabilities except for those arising from the net assets of the EEA and the DMA which are accounted for as explained below. In accordance with IFRS 9, Financial Instruments all financial assets and liabilities are initially recognised at fair value.
Assets
The NLF’s financial assets are designated as debt instruments at amortised cost as defined in IFRS 9, Financial Instruments. The classification is based on both the entity’s business model for managing the financial assets (determined as held to collect contractual cashflows) and the contractual cash flow characteristics of the financial assets (being solely payment of principal and interest). Subsequent measurement is therefore at amortised cost using the effective interest rate method.
Liabilities
The NLF’s financial liabilities are not held for trading and are therefore also subsequently measured at amortised cost using the effective interest rate method in accordance with IFRS 9, Financial Instruments. If gilts are issued by a syndication process, the syndication fees are borne by the NLF and are netted off from gross issuance proceeds as part of the calculation of amortised cost. Other directly related issue costs for assets and liabilities are negligible and are written off as incurred.
The distinction between loans and advances derives from the legislation that governs the operation of the NLF. Interest on loans must be charged at a rate that at least covers the cost that the Fund would have to bear if it were to borrow the same sum for the period of the loan, in addition to HM Treasury’s own administration costs. There is no such requirement for advances, although interest is charged at the Bank Rate on advances to the DMA. No interest is charged on advances to the EEA. The NLF does not charge interest on its advances to PWLB but interest on loans by the PWLB to local authorities financed by NLF advances is paid to the NLF under section 3(3) of the National Loans Act 1968.
As required by IFRS 7 Financial Instruments: Disclosures, the fair values of the financial assets and liabilities are disclosed in Note 14. They are calculated by reference to market prices where instruments are traded on an active quoted market or, where this is not the case, as the net present value of future cash flows.
i. Impairment of financial assets
In accordance with IFRS 9, Financial Instruments, impairment of financial assets held at amortised cost is based on an expected credit loss (ECL) model. Each financial asset is categorised as ‘stage 1’, ‘stage 2’ or ‘stage 3’ depending on whether there has been a default event or a significant increase in credit risk since initial recognition. See the diagram below for further information:
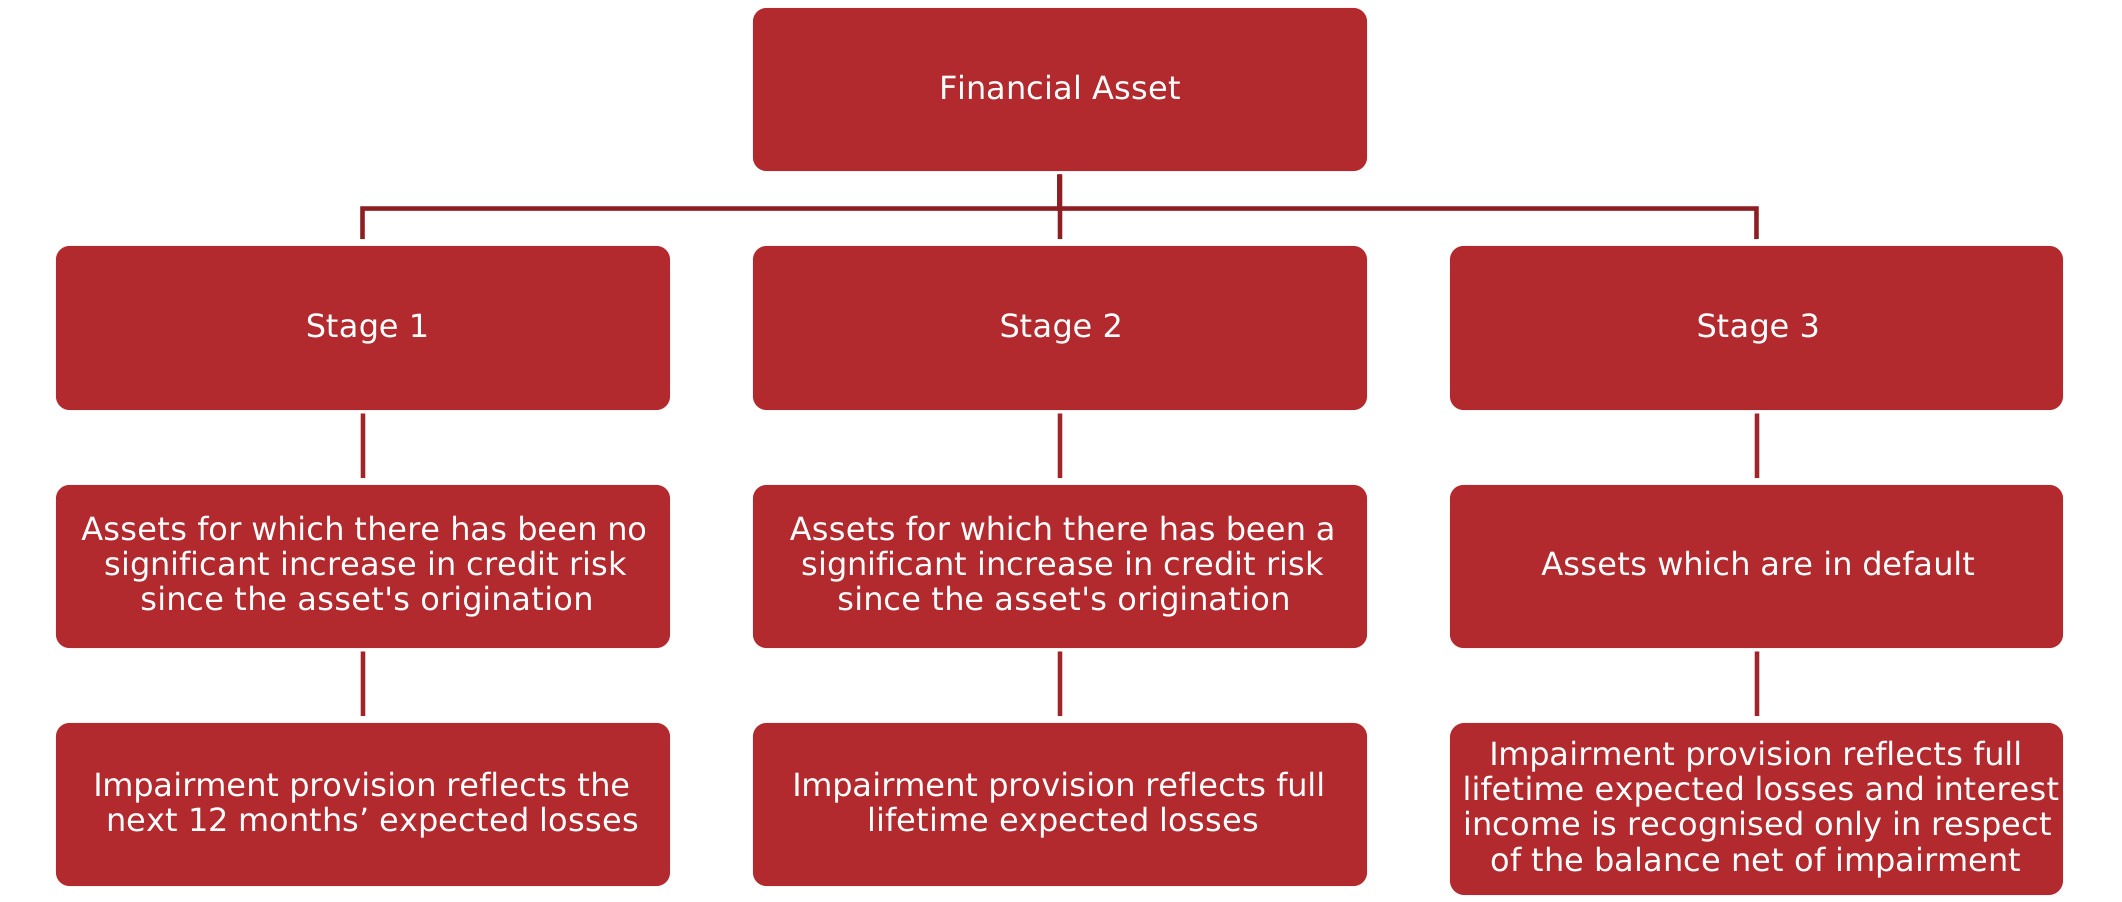
The FReM includes an exemption from recognising stage 1 and stage 2 losses on balances with other government Exchequer funds or government departments and on assets held by government Exchequer funds (which includes the NLF) where repayment is ensured by primary legislation.
For assets not covered by the exemptions above, the NLF assesses at the end of each reporting period, whether there is objective evidence of a deterioration of credit risk since initial recognition in line with IFRS 9, Financial Instruments. This assessment includes consideration of indicators such as financial difficulty experienced by the borrower or a breach of loan conditions, including default or delinquency in interest or principal payments. No impairment losses have been recognised during the year.
ii. Foreign currencies
The financial statements of the NLF are presented in sterling, being the currency of the primary economic environment in which it operates. Transactions denominated in foreign currencies are recorded at the rate of exchange applicable to the transaction.
Monetary assets and liabilities denominated in foreign currencies at the end of the reporting period are reported at the rates of exchange prevailing at that date. Liabilities to the IMF are denominated in sterling but are subject to a revaluation adjustment reflecting movement in the SDR to sterling exchange rate.
iii. Administration expenditure
These financial statements reflect activity through, and the financial position of, the NLF. The costs of gilts registration, listing fees and foreign currency debt issuance are met by the NLF. Administration costs such as departmental staff costs and bank charges are borne by the appropriate body and accounted for through their respective accounts.
iv. EEA and DMA
Under section 11 of Schedule 5A to the National Loans Act 1968, any excess of the assets of the DMA over its liabilities shall be a liability of the DMA to the NLF.
Over time, the NLF has advanced sterling to the EEA to finance the UK’s reserves of gold, foreign currency assets and IMF SDRs. As a result, having been derived from initial NLF financing, the EEA’s net assets are ultimately due to the NLF. Annual financial statements are prepared for both the DMA and the EEA.
The net assets of the DMA and EEA are reported in Note 8, Other Assets and the total comprehensive net expenditure or income recognised in the Statement of Comprehensive Net Expenditure as Note 5, Other Expenditure or Other Income). These NLF assets and net income or expenditure are the result of activity in the EEA and DMA during the year and the various accounting policies applied by them to that activity.
4.2 2. Financing costs of borrowing
| £m | 2025-26 | 2024-25 |
|---|---|---|
| Gilt-edged stock | 85,332 | 71,595 |
| National Savings and Investments products | 8,600 | 9,316 |
| Other finance costs | 4,117 | 6,038 |
| Total finance costs of borrowing | 98,049 | 86,949 |
Costs include the payment of interest on Gilts along with interest and prize payments related to Premium bonds administered by National Savings and Investments (NS&I).
4.3 3. Income from lending operations
| £m | 2025-26 | 2024-25 |
|---|---|---|
| Interest on loans advanced by the NLF to: | ||
| Public corporations | 18 | 23 |
| Central government bodies | 127 | 114 |
| 145 | 137 | |
| Interest on loans by the PWLB financed by NLF advances | 3,565 | 3,579 |
| Total income from lending operations | 3,710 | 3,716 |
4.4 4. Gains and losses on foreign exchange transactions
| £m | Note | 2025-26 | 2024-25 |
|---|---|---|---|
| Loss / (gain) on Reserve Tranche Position at the IMF | 9 | 4 | 121 |
| Net loss / (gain) on foreign currency transactions | 4 | 121 |
4.5 5. Other income and expenditure
| £’m | 2025-26 | 2024-25 |
|---|---|---|
| Other expenditure | ||
| Expenditure in respect of depreciation of Issue Department Assets | 2 | 18 |
| Miscellaneous expenditure | 4 | 4 |
| Total: Other expenditure | 6 | 22 |
| Other income | ||
| EEA total comprehensive net income | (14,492) | (8,353) |
| DMA total comprehensive net income[footnote 4] | (1,618) | (443) |
| Profits of the Bank of England Issue Department | (3,772) | (4,792) |
| Written off gilt-edged stock | (645) | - |
| Miscellaneous receipts | (5) | (14) |
| Income in respect of appreciation of Issue Department Assets | (1) | (11) |
| Total: Other income | (20,533) | (13,613) |
| Net total | (20,527) | (13,591) |
EEA total comprehensive net income
The EEA made a £14.5 billion gain (2024-25: £8.4 billion gain). Of the £14.5 billion net income from the EEA, £0.4 billion (2024-25: £0.2 billion) relates to interest income from the IMF Reserve Tranche Position and bilateral loans to the IMF. Further detail is provided in the EEA Accounts.
Bank of England Issue Department profit and appreciation/deprecation of assets
Under section 9 of the National Loans Act 1968, the profits of the Issue Department are paid into the NLF. In addition, the Bank of England Issue Department is required by the Currency and Bank Notes Act 1928 to hold investments equal to the value of bank notes in issue. These investments are revalued to market value quarterly. If the market value is less than the value of notes in issue, legislation requires the NLF to pay an amount equal to the deficiency to the Issue Department to finance the purchase of additional investments. Conversely, if the market value of the assets exceeds the value of notes in issue, the Issue Department sells investments to the value of the surplus and pays the proceeds to the NLF.
Written off gilt-edged stock
Other income includes £645 million arising from the cancellation of a gilts held in the Commissioners for the Reduction of the National Debt (CRND) Donations and Bequests Account. The account is used to receive donations and bequests intended to reduce the national debt and gilts held in the account are cancelled for that purpose.[footnote 4]
4.6 6. Advances
| £’m | Public Works Loan Board | Exchange Equalisation Account | Total | |||
|---|---|---|---|---|---|---|
| 2025-26 | 2024-25 | 2025-26 | 2024-25 | 2025-26 | 2024-25 | |
| Principal outstanding at 1 April | 110,627 | 103,243 | 61,781 | 63,347 | 172,408 | 166,590 |
| Advances issued | 18,540 | 14,642 | 800 | 5,461 | 19,340 | 20,103 |
| Advances repaid | (12,131) | (7,258) | (3,309) | (7,027) | (15,440) | (14,285) |
| Principal outstanding at 31 March | 117,036 | 110,627 | 59,272 | 61,781 | 176,308 | 172,408 |
| Accrued interest | 920 | 1,228 | - | - | 920 | 1,228 |
| Total advances outstanding | 117,956 | 111,855 | 59,272 | 61,781 | 177,228 | 173,636 |
4.7 7. Loans and commitments to lend
| Loans | 2025-26 | 2024-25 | ||||
|---|---|---|---|---|---|---|
| £’m | Public Corporations | Central Government | Total | Public Corporations | Central Government | Total |
| Principal outstanding at 1 April | 297 | 4,315 | 4,612 | 366 | 4,235 | 4,601 |
| Loans advanced | 111 | 781 | 892 | 240 | 439 | 679 |
| Loans repaid | (161) | (392) | (553) | (309) | (359) | (668) |
| Principal outstanding at 31 March | 247 | 4,704 | 4,951 | 297 | 4,315 | 4,612 |
| Accrued interest | 4 | 20 | 24 | 4 | 19 | 23 |
| Total loans outstanding | 251 | 4,724 | 4,975 | 301 | 4,334 | 4,635 |
Commitments to lend
| At 31 March 2026 | At 31 March 2025 | |||||
|---|---|---|---|---|---|---|
| £’m | Public Corporations | Central Government | Total | Public Corporations | Central Government | Total |
| Undrawn commitments to lend | 36 | 250 | 286 | 25 | 250 | 275 |
Commitments to lend are agreements to lend to a customer in the future subject to certain conditions. Such commitments are made either for a fixed period or have no specific maturity but are cancellable by the NLF. In addition to the above, the NLF has a loan commitment to the IMF, which is explained in Note 9, IMF Reserve Tranche Position and Lending to the IMF.
4.8 8. Other assets
| £m | At 31 March 2026 | At 31 March 2025 |
|---|---|---|
| Exchange Equalisation Account net assets[footnote 5] | 66,664 | 52,172 |
| DMA net assets[footnote 6] | 65,418 | 63,800 |
| Cash held by National Savings and Investments | 2,388 | 2,571 |
| Sterling balances at Bank of England advanced to IMF | 53 | 54 |
| Total other assets | 134,523 | 118,597 |
4.9 9. IMF Reserve Tranche Position and Lending to the IMF
The United Kingdom’s financial relationship with the International Monetary Fund (IMF) is accounted for in the NLF and the EEA. The UK’s quota subscription to the IMF, 20,155 million Special Drawing Rights (SDRs) - equivalent to £20.7 billion[footnote 7] at 31 March 2026 (£20.7 billion at 31 March 2025) - was paid from the NLF and is recognised as an NLF asset.
Part of the subscription is deposited by the IMF in the NLF in return for sterling non-interest-bearing securities (NIBS) which totalled £15.0 billion at 31 March 2026 (£15.8 billion at 31 March 2025). NIBS represent a liability of the NLF to the IMF. There is a remaining small liability of £0.05 billion (£0.05 billion at 31 March 2025) against which an equal amount of sterling cash is made available in an account at the Bank of England for drawdown by the IMF.
The difference between the gross quota subscription and the NLF’s sterling liability to the IMF is the UK’s reserve tranche position (RTP). Under the arrangements for membership of the Fund, valuation adjustments are made between the IMF and NLF annually to reflect any changes in value in SDR terms of the NLF’s sterling liability to the IMF. An annual settlement payment is made between the NLF and the IMF, normally in May. The cumulative valuation adjustment at 31 March 2026 was £0.2 billion gain (£0.4 billion gain at 31 March 2025). The table below sets out the composition of the RTP and the make-up of changes over the year.
NLF Assets and Liabilities: Composition of the Reserve Tranche Position and Lending[footnote 8] to the IMF
| Asset | Liabilities | Reserve Tranche Position | ||||
|---|---|---|---|---|---|---|
| £m | IMF Quota Subscription | Non-interest-bearing securities | Other quota liability | Valuation adjustment | Total liabilities | |
| Balances at 31 March 2025 | 20,696 | (15,847) | (54) | 356 | (15,545) | 5,151 |
| Exchange rate losses for the year on the Quota subscription | 17 | - | 17 | |||
| Change in year-end valuation adjustment | (543) | (543) | (543) | |||
| Change in loan notes as a result of the valuation settlement | 521 | 521 | 521 | |||
| Change in cash on No 1 account | 1 | 1 | 1 | |||
| Cash subscribed to the IMF | - | - | - | |||
| Net increase in loan notes | 327 | 327 | 327 | |||
| Balances at 31 March 2026 | 20,713 | (14,999) | (53) | (187) | (15,239) | 5,474 |
| Lending to the IMF | £m | |||||
| Lending as at 31 March 2025 | - | |||||
| Lending as at 31 March 2026 | - | |||||
| IMF Quota Subscription and Lending | 20,713 |
The RTP is a net asset of the NLF. It represents an SDR asset that can be drawn on by the UK if needed and is considered part of the UK’s foreign exchange reserves. Sterling transactions by the IMF impact on the level of non-interest-bearing securities (NIBS) and hence on the RTP.
Under current policy, changes in the RTP lead to adjustments in the composition of other reserve assets (held in the EEA) in order to keep the portfolio composition of the reserves in line with plan. Interest is payable by the IMF on the RTP balance in excess of SDR 0.7 billion. This interest is retained in the EEA.
Separately, the EEA also holds the UK’s allocation of SDRs (SDR 29.5 billion at 31 March 2026) as a liability to the IMF and retains an asset in the form of the UK’s holdings of SDRs (SDR 30.3 billion at 31 March 2026).
During 2025-26 the IMF deposited a net amount of £0.3 billion into the NLF in return for NIBs (2024-25: £0.3 billion), representing a net repayment of amounts provided in support of IMF funding programmes.
Aside from the UK’s quota subscription to the IMF of 20.2 billion Special Drawing Rights (SDRs) - equivalent to £20.7 billion at 31 March 2026, the UK partakes in two IMF borrowing arrangements which increase the NLF’s overall exposure to the IMF:
- The New Arrangements to Borrow (NAB): The NAB acts as a second line of defence to IMF resources should quotas be exhausted. It requires creditor consent to activate, by an 85% supermajority based on total NAB shareholdings. The UK’s NAB commitment is SDR 19.0 billion (£19.5 billion as of 31 March 2026 exchange rate). This agreement is due to expire in December 2030.
- Bilateral Borrowing Agreements (BBAs): BBAs serve as a third line of defence after quotas and the NAB. The UK’s bilateral borrowing agreement is SDR 4.0 billion (£4.1 billion at the 31 March 2026 exchange rate). The UK’s BBA agreement was due to expire in December 2024. At the IMF’s request, the UK agreed to extend its BBA agreement until the 16th GRQ has come into effect.
The UK’s total commitments to borrowed resource (NAB and BBA) therefore stands at SDR 22.9 billion (£23.5 billion at the 31 March 2026 exchange rate). The UK also supports the IMF outside of the NLF, through the channelling of Special Drawing Right (SDR) assets held in the Exchange Equalisation Account (EEA) to IMF trusts, specifically the Poverty Reduction and Growth Trust (PRGT) and Resilience and Sustainability Trust (RST). Further detail is provided in the EEA Accounts.
UK’s total commitment to the IMF’s general resources
| At 31 March 2026 | At 31 March 2025 | |||||
|---|---|---|---|---|---|---|
| Total commitment | Total drawn | Total undrawn | Total commitment | Total drawn | Total undrawn | |
| Quota SDRm) | 20,155 | 5,327 | 14,828 | 20,155 | 5,017 | 15,138 |
| Loans SDRm) | 22,912 | - | 22,912 | 22,912 | - | 22,912 |
| Total (SDRm) | 43,067 | 5,327 | 37,740 | 43,067 | 5,017 | 38,050 |
| Quota (£m) | 20,713 | 5,474 | 15,239 | 20,696 | 5,151 | 15,545 |
| Loans (£m) | 23,546 | - | 23,546 | 23,527 | - | 23,527 |
| Total (£m) | 44,259 | 5,474 | 38,785 | 44,223 | 5,151 | 39,072 |
Changes to the UK’s quota subscription and loans to the IMF are subject to Parliamentary-approved limits.
4.10 10. Gilt-edged stock
| £m | Conventional | Index-Linked | Total |
|---|---|---|---|
| At 31 March 2025 | 2,008,489 | 690,558 | 2,699,047 |
| Receipts from gilt issuance | 273,014 | 31,080 | 304,094 |
| Payments for gilt redemption | (162,160) | (21,209) | (183,369) |
| Net issuance of DMA gilts | 19,448 | - | 19,448 |
| Amortisation of premiums and discounts | 348 | 3,761 | 4,109 |
| Change in accrued interest | 2,027 | 17,359 | 19,386 |
| At 31 March 2026 | 2,141,166 | 721,549 | 2,862,715 |
The NLF issues gilts directly to the DMA for use by the DMO in its money market activities managing the Exchequer’s daily cash requirement. These gilts do not contribute directly to Exchequer financing. All other gilts are sold into the primary gilt market to meet government financing needs.
Syndication fees are borne by the NLF and are netted off from gross issuance proceeds as part of the calculation of amortised cost. Other directly related issue costs for assets and liabilities are negligible and are written-off as incurred. Total syndication fees for the year were £81.0 million (2024-25: £99.9 million). The analysis below shows two large holdings of the gilt liability by UK public sector entities, the DMA and Bank of England[footnote 9].
| £m | At 31 March 2026 | At 31 March 2025 |
|---|---|---|
| Debt Management Account (DMA) | 181,247 | 164,021 |
| Bank of England (for quantitative easing) | 456,138 | 548,695 |
| Other investors | 2,225,330 | 1,986,331 |
| Total gilt-edged stock | 2,862,715 | 2,699,047 |
4.11 11. National Savings and Investments products
| £m | 2025-26 | 2024-25 |
|---|---|---|
| Principal outstanding at 1 April | 238,496 | 228,889 |
| Cash repayments from the NLF | (53,647) | (50,380) |
| Principal cash received in the NLF | 61,739 | 55,805 |
| Capitalised interest and other returns to savers | 3,752 | 3,948 |
| Change in cash holdings for principal | (204) | 234 |
| Principal outstanding at 31 March | 250,136 | 238,496 |
| Accrued interest and other returns to savers | 1,635 | 1,650 |
| Total principal and accrued interest outstanding | 251,771 | 240,146 |
NS&I provides more detail on this liability in a set of Product Accounts which are published with the NS&I resource accounts.
4.12 12. Other debt payable
| £m | At 31 March 2026 | At 31 March 2025 |
|---|---|---|
| Debt Management Account | 69,637 | 78,386 |
| Bank of England Issue Department | 371 | 371 |
| Balances from government accounts at Government Banking | 46,448 | 49,178 |
| Deposits from public sector bodies | 16,818 | 17,343 |
| Other | 7 | 14 |
| Total other debt payable | 133,281 | 145,292 |
The third item reflects the transfer to the NLF of any temporary cash surpluses on other government accounts held at Government Banking. Deposits from public sector bodies represents deposits by public sector bodies which are directly held with the NLF. “Other” comprises mostly residual certificates of tax deposit held by the NLF and not yet reclaimed following the scheme closure.
At 31 March 2026, there was no foreign currency debt outstanding in the NLF (2024-25: nil).
4.13 13. Reconciliation of liabilities arising from financing activities
| £m | Liability at 1 April 2025 | Interest paid (cashflow from operating activities) | Cashflow from financing activities | Finance costs of borrowing (Note 2) | Exchange rate gains (Note 9) | Gilt write offs (Note 5) | Movement in cash held by third parties on behalf of the NLF | Liability at 31 March 2026 |
|---|---|---|---|---|---|---|---|---|
| Gilt-edged stock | 2,699,047 | (61,192) | 140,173 | 85,332 | - | (645) | - | 2,862,715 |
| National Savings & Investments products | 240,146 | (4,884) | 8,092 | 8,600 | - | - | (183) | 251,771 |
| Other debt | 145,292 | (4,275) | (11,853) | 4,117 | - | - | - | 133,281 |
| Liabilities to the IMF | 15,545 | - | (848) | – | 543 | - | (1) | 15,239 |
| Total | 3,100,030 | (70,351) | 135,564 | 98,049 | 543 | (645) | (184) | 3,263,006 |
4.14 14. Fair Values
Carrying Value and Fair Value of NLF assets and liabilities
| At 31 March 2026 | At 31 March 2025 | |||
|---|---|---|---|---|
| Carrying Value | Fair Value | Carrying Value | Fair Value | |
| Assets | £m | £m | £m | £m |
| Advances: | ||||
| PWLB | 117,036 | 92,043 | 110,627 | 86,565 |
| Debt Management Account | - | - | - | - |
| Exchange Equalisation Account | 59,272 | 59,272 | 61,781 | 61,781 |
| Accrued interest | 920 | 920 | 1,228 | 1,228 |
| Loans: | ||||
| Principal | 4,951 | 4,351 | 4,612 | 4,160 |
| Accrued interest | 24 | 24 | 23 | 23 |
| Other assets | 134,523 | 134,523 | 118,597 | 118,597 |
| IMF quota subscription & lending | 20,713 | 20,713 | 20,696 | 20,696 |
| Total assets | 337,439 | 311,846 | 317,564 | 293,050 |
| At 31 March 2026 | At 31 March 2025 | |||
|---|---|---|---|---|
| Carrying Value | Fair Value | Carrying Value | Fair Value | |
| Liabilities | £m | £m | £m | |
| Gilts | 2,862,715 | 2,349,235 | 2,699,047 | 2,204,901 |
| National Savings & Investments | ||||
| Principal | 250,136 | 250,034 | 238,496 | 238,483 |
| Accrued interest | 1,635 | 1,634 | 1,650 | 1,650 |
| IMF liabilities | 15,239 | 15,239 | 15,545 | 15,545 |
| Other Debt | ||||
| Debt Management Account | 69,637 | 69,637 | 78,386 | 78,386 |
| Issue Department of Bank of England | 371 | 371 | 371 | 371 |
| Government balances | 46,448 | 46,448 | 49,178 | 49,178 |
| Deposits from public sector bodies | 16,818 | 16,818 | 17,343 | 17,343 |
| Foreign currency debt | - | - | - | - |
| Other | 7 | 7 | 14 | 14 |
| 3,263,006 | 2,749,423 | 3,100,030 | 2,605,871 |
With the exception of gilts, which are classified as level 1, all assets and liabilities are classified as level 2 in the fair value hierarchy defined by IFRS 7.
The NLF’s assets are classified as financial assets except for the net assets of the EEA £66.7 billion, (2024-25: £52.2 billion) and DMA £65.4 billion (2024-25: £63.8 billion), reported in Note 8, Other Assets. The carrying value of financial assets is £205.4 billion (2024-25: £201.6 billion) and their fair value is £179.8 billion (2024-25: £177.1 billion).
All the NLF’s liabilities are financial liabilities. In instances where the fair value differs from the carrying value, the fair value has been calculated by reference to market prices where instruments are traded on an active quoted market or, where this is not the case, as the net present value of future cash flows.
The fair value of advances to the PWLB is calculated as the net present value of future cash flows. Loans by the PWLB are usually at a fixed rate of interest and so their fair value increases or decreases according to changes in the difference between the fixed rate of interest earned on the loan and current market values. Differences between the fair and book value will not be realised as the PWLB loans are not traded by the NLF.
The fair value of gilts is calculated by reference to their market prices. They will generally be redeemed at their book values so any difference between their fair value and book value will not normally be realised in the NLF accounts.
4.15 15. Maturity of assets and liabilities
The following table shows the split between current and non-current assets and liabilities based on contract date of maturity or expected maturity if there is no contract date.
| At 31 March 2026 | At 31 March 2025 | |||||
|---|---|---|---|---|---|---|
| Current | Non-current | Total | Current | Non-current | Total | |
| £m | £m | £m | £m | £m | £m | |
| Assets | ||||||
| Advances | 13,815 | 163,413 | 177,228 | 11,506 | 162,130 | 173,636 |
| Loans | 468 | 4,507 | 4,975 | 465 | 4,170 | 4,635 |
| Other assets | 2,444 | 132,079 | 134,523 | 2,625 | 115,972 | 118,597 |
| IMF quota subscription (SDR) & lending | - | 20,713 | 20,713 | - | 20,696 | 20,696 |
| Total assets | 16,727 | 320,712 | 337,439 | 14,596 | 302,968 | 317,564 |
| Liabilities | ||||||
| Gilts | ||||||
| Conventional | 163,003 | 1,978,163 | 2,141,166 | 174,836 | 1,833,653 | 2,008,489 |
| Index-linked | 963 | 720,586 | 721,549 | 21,536 | 669,022 | 690,558 |
| Gilt-edged stock | 163,966 | 2,698,749 | 2,862,715 | 196,372 | 2,502,675 | 2,699,047 |
| National Savings and Investments | 236,066 | 15,705 | 251,771 | 224,221 | 15,925 | 240,146 |
| IMF liabilities | - | 15,239 | 15,239 | - | 15,545 | 15,545 |
| Other debt payable | 133,281 | - | 133,281 | 144,792 | 500 | 145,292 |
| Total liabilities | 533,313 | 2,729,693 | 3,263,006 | 565,385 | 2,534,645 | 3,100,030 |
All National Savings and Investments products are payable on demand and therefore classified as current liabilities except for investments in Guaranteed Bonds made on or after 1 May 2019 and Green Savings Bonds, which repay at maturity.
The following table shows an analysis of current and non-current assets and liabilities by type of counterparty.
| At 31 March 2026 | At 31 March 2025 | |||||
|---|---|---|---|---|---|---|
| Current | Non-current | Total | Current | Non-current | Total | |
| £m | £m | £m | £m | £m | £m | |
| Assets | ||||||
| Balances with: | ||||||
| Other central government bodies | 16,635 | 299,786 | 316,421 | 14,488 | 282,024 | 296,512 |
| NHS Trusts | - | - | - | - | - | - |
| Public corporations and trading funds | 92 | 213 | 305 | 108 | 248 | 356 |
| Total intra government balances | 16,727 | 299,999 | 316,726 | 14,596 | 282,272 | 296,868 |
| Balances with bodies external to government | - | 20,713 | 20,713 | - | 20,696 | 20,696 |
| Total assets | 16,727 | 320,712 | 337,439 | 14,596 | 302,968 | 317,564 |
| Liabilities | ||||||
| Balances with: | ||||||
| Other central government bodies | 131,495 | 171,851 | 303,346 | 142,742 | 156,040 | 298,782 |
| NHS Trusts | 10,444 | - | 10,444 | 9,901 | - | 9,901 |
| Public corporations and trading funds | 37,825 | 431,233 | 469,058 | 80,354 | 482,288 | 562,642 |
| Total intra government balances | 179,764 | 603,084 | 782,848 | 232,997 | 638,328 | 871,325 |
| Balances with bodies external to government | 353,549 | 2,126,609 | 2,480,158 | 332,389 | 1,896,316 | 2,228,705 |
| Total liabilities | 533,313 | 2,729,693 | 3,263,006 | 565,386 | 2,534,644 | 3,100,030 |
4.16 16. Financial risks related to the NLF
The Government’s debt management objective is set out in the annual Debt and Reserves Management Report:
‘To minimise, over the long term, the costs of meeting the government’s financing needs, taking into account risk, whilst ensuring that debt management policy is consistent with the aims of monetary policy.’
This is achieved by:
- meeting the principles of openness, transparency and predictability
- developing a liquid and efficient gilt market
- issuing gilts that achieve a benchmark premium
- adjusting the maturity and nature of the government’s debt portfolio, primarily by means of the maturity and composition of debt issuance and potentially by other market operations including switch auctions, conversion offers and buy-backs
- offering cost-effective savings instruments to the retail sector through National Savings & Investments.
For cash management, the aggregate balance on government accounts is swept daily to the NLF and then to the DMA. The DMO deals with the financial markets to manage the daily cash surplus or deficit on the DMA relative to its target overnight balance, lending when there is a surplus and borrowing when there is a deficit.
The NLF’s liabilities include conventional and index-linked gilt-edged securities, NS&I product liabilities, certificates of tax deposit, deposits from other public sector accounts and liabilities to the IMF. There is a wide spread of maturities.
NLF assets include advances to the DMA, PWLB and EEA, loans to UK public bodies, net assets of the DMA and EEA, NS&I product-related cash holdings and the UK’s gross Quota Subscription and lending to the IMF, denominated in SDRs.
Set out below are certain risk factors that could affect the NLF’s operations.
Interest rate and inflation risk
The NLF is exposed to cash flow interest rate risk on its floating rate borrowing and lending due to the risk that future interest rates will fluctuate. It is not exposed to fair value interest rate risk as its financial assets and liabilities are measured at amortised cost and not fair value. Some of the NLF’s assets and liabilities have no associated interest income or expense (are “zero-rated”) and are therefore not exposed to changes in interest rates.
Inflation risk arises because interest and redemption amounts paid on index-linked gilts vary monthly in line with changes in the UK Retail Prices Index (RPI) since the initial issue of each stock.
The table below analyses the NLF’s interest rate and inflation risk by indicating the timeframe in which the risk could crystallise. Assets and liabilities are included at carrying amount and are shown at the earlier of contractual re-pricing or maturity dates.
Interest rate and inflation risk analysis as at 31 March 2026
| Up to 1 month/ repayable on demand | 1-12 months | 1-5 years | Over 5 years | Zero-rated | Total carrying value | Fixed rate | Floating rate | |
|---|---|---|---|---|---|---|---|---|
| £m | £m | £m | £m | £m | £m | £m | £m | |
| Assets | ||||||||
| Advances | 845 | 11,911 | 26,551 | 77,590 | 60,331 | 177,228 | 116,897 | - |
| Loans | - | 443 | 1,497 | 3,011 | 24 | 4,975 | 4,951 | - |
| Other assets | - | - | - | - | 134,523 | 134,523 | - | - |
| IMF quota subscription | - | - | - | - | 20,713 | 20,713 | - | - |
| Total | 845 | 12,354 | 28,048 | 80,601 | 215,591 | 337,439 | 121,848 | - |
| Liabilities | ||||||||
| Gilts | ||||||||
| Conventional | - | 148,000 | 559,185 | 1,418,978 | 15,003 | 2,141,166 | 2,126,163 | - |
| Index-linked | 720,714 | - | - | - | 835 | 721,549 | - | 720,714 |
| Gilt-edged stock | 720,714 | 148,000 | 559,185 | 1,418,978 | 15,838 | 2,862,715 | 2,126,163 | 720,714 |
| National Savings and Investments | 216,009 | 26,626 | 7,442 | - | 1,694 | 251,771 | 35,256 | 214,821 |
| IMF liabilities | - | - | - | - | 15,239 | 15,239 | - | - |
| Other debt payable | 85,554 | 13,213 | - | - | 34,514 | 133,281 | 16,679 | 82,088 |
| Total | 1,022,277 | 187,839 | 566,627 | 1,418,978 | 67,285 | 3,263,006 | 2,178,098 | 1,017,623 |
| Period gap | 1,021,432 | 175,485 | 538,579 | 1,338,377 | (148,306) | 2,925,567 | ||
| Cumulative gap | 1,021,432 | 1,196,917 | 1,735,496 | 3,073,873 | 2,925,567 |
Interest rate and inflation risk analysis as at 31 March 2025
| Up to 1 month/ repayable on demand | 1-12 months | 1-5 years | Over 5 years | Zero-rated | Total carrying value | Fixed rate | Floating rate | |
|---|---|---|---|---|---|---|---|---|
| £m | £m | £m | £m | £m | £m | £m | £m | |
| Assets | ||||||||
| Advances | 602 | 8,771 | 20,582 | 79,766 | 63,915 | 173,636 | 109,721 | - |
| Loans | 10 | 432 | 1,447 | 2,723 | 23 | 4,635 | 4,612 | - |
| Other assets | - | - | - | - | 118,597 | 118,597 | - | - |
| IMF quota subscription | - | - | - | - | 20,696 | 20,696 | - | - |
| Total | 612 | 9,203 | 22,029 | 82,489 | 203,231 | 317,564 | 114,333 | - |
| Liabilities | ||||||||
| Gilts | ||||||||
| Conventional | - | 161,860 | 490,771 | 1,342,882 | 12,976 | 2,008,489 | 1,995,513 | - |
| Index-linked | 689,758 | - | - | - | 800 | 690,558 | - | 689,758 |
| Gilt-edged stock | 689,758 | 161,860 | 490,771 | 1,342,882 | 13,776 | 2,699,047 | 1,995,513 | 689,758 |
| National Savings and Investments | 208,758 | 19,695 | 9,998 | - | 1,695 | 240,146 | 30,603 | 207,848 |
| IMF liabilities | - | - | - | - | 15,545 | 15,545 | - | - |
| Other debt payable | 93,255 | 13,389 | 500 | - | 38,148 | 145,292 | 17,177 | 89,967 |
| Total | 991,771 | 194,944 | 501,269 | 1,342,882 | 69,164 | 3,100,030 | 2,043,293 | 987,573 |
| Period gap | 991,159 | 185,741 | 479,240 | 1,260,393 | (134,067) | 2,782,466 | ||
| Cumulative gap | 991,159 | 1,176,900 | 1,656,140 | 2,916,533 | 2,782,466 |
Foreign currency risk
The NLF is exposed to foreign exchange risk through transactions with the IMF as the reserve tranche position (quota subscription less UK liability) and lending to the IMF are denominated in SDRs (Note 9, IMF Reserve Tranche Position and Lending to the IMF). In addition to the risk of unrealised revaluations of the assets and liability, foreign exchange gains and losses are realised as the NLF transacts with the IMF on the UK liability and loans. As it is not possible to predict the size and timing of these transactions with any certainty it has not been deemed cost-effective to attempt to mitigate this risk through hedging arrangements.
Sensitivity analysis
The following analysis, required by IFRS 7 Financial Instruments: Disclosures, is intended to illustrate the sensitivity of the NLF’s financial assets and liabilities to changes in UK interest rates, the UK Retail Prices Index (RPI)and the SDR to sterling exchange rates. The sensitivity analysis has been calculated on the basis that the components of financial assets and liabilities, the number of instruments held at fixed, floating and zero interest rates and the amount of instruments held in SDRs are all constant and are as at the end of the reporting period.
The following assumptions have been made in calculating sensitivity:
- All sensitivities impact the Statement of Comprehensive Net Expenditure (SoCNE) and thereby the net liability of the CF to the NLF
- Finance income and costs and the net liability of the CF to the NLF will be affected by changes in interest rates on floating rate instruments
- to changes in fair value as a result of interest rate changes
- No sensitivity is provided for interest accruals where these are based on pre-agreed interest rates and are therefore not susceptible to further rate changes
- 100 basis points and 10 percent have been used as a basis for a reasonably possible change in interest, RPI and FX rates at the end of the reporting period. This is not a forecast.
Using the above assumptions, the following table shows the illustrative impact on the SoCNE that would result from an increase in UK interest rates and the UK Retail Prices Index and if the SDR to sterling exchange rate was to strengthen.
| 2025-26 | 2024-25 | |
|---|---|---|
| Statement of Comprehensive Net Expenditure | Statement of Comprehensive Net Expenditure | |
| £m | £m | |
| UK interest rates + 100bp expense | 2,969 | 3,763 |
| UK Retail Prices Index + 100bp expense | 7,207 | 6,898 |
| SDR exchange rate + 10% income | (547) | 1,070 |
An equal, but opposite effect would result if there were a decrease in UK interest rates and the UK RPI, and if the SDR to sterling exchange rates was to weaken.
Liquidity risk
Liquidity risk is the risk that the NLF will encounter difficulty in meeting obligations associated with financial liabilities. Its exposure to liquidity risk arises because of its fundamental purpose of being the Government’s main borrowing account.
NLF liabilities carry a wide range of maturities, spreading funding requirements for redemption payments, and thus liquidity risk, across a wide time period into the future. The longest stock in existence at 31 March 2026 matures in 2073.
Deposits in the NLF have a shorter maturity profile since they can change on demand. However, in practice, balances change only slowly due to re-investment. By virtue of section 19(1) of the National Loans Act 1968, the net liabilities of the NLF are a liability of the Consolidated Fund. The servicing and redemption of the NLF’s liabilities are expected to be met over the long term mainly through future tax revenue receipts. Whilst the level of receipts in any year is subject to tax policy changes and, relatedly the UK’s economic position, the level of debt required to meet government expenditure, including the servicing of debt, can be maintained by the issuance or reissuance of further debt.
Therefore, in accordance with the FReM, it has been concluded as appropriate to adopt the going concern basis of preparation for the NLF Accounts. Most of the NLF’s borrowing needs are met through borrowing on its behalf by the DMO and NS&I.
Contractual undiscounted cash flows of financial liabilities
The following table shows the contractual undiscounted cash flows of the NLF’s liabilities. The amounts shown are the cash flows arising from the NLF’s financial liabilities during the period up to and including maturity. This contrasts with the basis on which the Statement of Financial Position amounts are calculated. As described in Note 1, Accounting Policies, items on the Statement of Financial Position (SoFP) are valued at fair value upon initial recognition and subsequently held at amortised cost. Therefore, totals in the following table will not agree to the SoFP.
The treatment of coupon payments is of particular significance. The table includes contractual coupon payments for the period to maturity based on coupon rates and, in the case of index-linked gilts, the Retail Prices Index at 31 March 2026.
The table below reports coupon cash flows of £869.8 billion (£808.1 billion at 31 March 2025) reflecting the large number of coupon payments due on longer dated gilts. By contrast, the gilts liability in the SoFP includes coupon accruals to the end of the reporting period of £16.0 billion (£13.9 billion at 31 March 2025).
The cash flows reported in the table will be funded by replacement debt issues, the proceeds of assets or by finance from the Consolidated Fund.
Contractual cash outflows as at 31 March 2026
| 0-12 months | 1-2 years | 2-5 years | Over 5 years | Undated | Total | |
|---|---|---|---|---|---|---|
| Liabilities | £m | £m | £m | £m | £m | £m |
| Conventional Gilts: | ||||||
| Principal | 148,095 | 161,184 | 394,667 | 1,439,904 | - | 2,143,850 |
| Coupons | 62,988 | 59,527 | 152,865 | 533,487 | - | 808,867 |
| Index-Linked Gilts: | - | |||||
| Principal | - | 29,679 | 67,132 | 575,967 | - | 672,778 |
| Coupons | 4,516 | 4,516 | 11,988 | 39,926 | - | 60,946 |
| Total Gilts | 215,599 | 254,906 | 626,652 | 2,589,284 | - | 3,686,441 |
| National Savings and Investments | 244,414 | 3,150 | 4,148 | - | 58 | 251,770 |
| IMF | 15,239 | - | - | - | - | 15,239 |
| Temporary Deposits | 16,480 | - | - | - | - | 16,480 |
| Other debt payable | 116,965 | - | - | - | - | 116,965 |
| 608,697 | 258,056 | 630,800 | 2,589,284 | 58 | 4,068,895 |
The maturity of liabilities after five years is:
| 5-10 years | 10-20 years | 20-30 years | 30-40 years | Over 40 years | Total | |
|---|---|---|---|---|---|---|
| £m | £m | £m | £m | £m | £m | |
| Conventional Gilts: | ||||||
| Principal | 505,157 | 410,159 | 344,246 | 123,275 | 57,067 | 1,439,904 |
| Coupons | 188,072 | 209,081 | 101,698 | 29,368 | 5,268 | 533,487 |
| Index-Linked Gilts: | ||||||
| Principal | 131,258 | 210.177 | 144,395 | 62,543 | 27,594 | 575,967 |
| Coupons | 15,054 | 15,832 | 7,883 | 1,044 | 113 | 39,926 |
| 839,541 | 845,249 | 598,222 | 216,230 | 90,042 | 2,589,284 |
Contractual cash outflows as at 31 March 2025
| 0-12 months | 1-2 years | 2-5 years | Over 5 years | Undated | Total | |
|---|---|---|---|---|---|---|
| Liabilities | £m | £m | £m | £m | £m | £m |
| Conventional Gilts: | ||||||
| Principal | 162,160 | 146,800 | 343,104 | 1,352,824 | - | 2,004,888 |
| Coupons | 52,790 | 50,605 | 131,286 | 515,518 | - | 750,199 |
| Index-Linked Gilts: | - | |||||
| Principal | 20,409 | - | 79,269 | 536,584 | - | 636,262 |
| Coupons | 4,000 | 3,975 | 11,130 | 38,786 | - | 57,891 |
| Total Gilts | 239,359 | 201,380 | 564,789 | 2,443,712 | - | 3,449,240 |
| National Savings and Investments | 230,806 | 5,012 | 4,283 | - | 45 | 240,146 |
| IMF | 15,546 | - | - | - | - | 15,546 |
| Temporary Deposits | 17,045 | - | - | - | - | 17,045 |
| Other debt payable | 127,950 | 501 | - | - | - | 128,451 |
| 630,706 | 206,893 | 569,072 | 2,443,712 | 45 | 3,850,428 |
The maturity of liabilities after five years is:
| 5-10 years | 10-20 years | 20-30 years | 30-40 years | Over 40 years | Total | |
|---|---|---|---|---|---|---|
| £m | £m | £m | £m | £m | £m | |
| Conventional Gilts: | ||||||
| Principal | 419,828 | 407,026 | 321,401 | 127,452 | 77,117 | 1,352,824 |
| Coupons | 168,989 | 204,622 | 102,838 | 32,355 | 6,714 | 515,518 |
| Index-Linked Gilts: | ||||||
| Principal | 119,586 | 173,516 | 135,879 | 68,790 | 38,813 | 536,584 |
| Coupons | 14,135 | 15,080 | 8,035 | 1,378 | 158 | 38,786 |
| 722,538 | 800,244 | 568,153 | 229,975 | 122,802 | 2,443,712 |
Credit risk
The NLF makes loans to UK public corporations and central government entities, advances to other UK central Exchequer Funds and subscribes to the IMF. The NLF also lends to the IMF. As a result, the NLF is not exposed to significant credit risk. Details of this can be found in Notes 6, 7 and 9. Total loans and advances stand at £182.2 billion (2024-25: £178.3 billion) and gross IMF exposure stands at £20.7 billion (2024-25: £20.7 billion).
In respect of loans financed by the NLF, the financial relationship with the borrower is managed by the department responsible for the relevant public corporation. The sponsoring department performs due diligence on the borrower and proposes the loan. HM Treasury reviews the proposal and, if the proposal is approved, the NLF will make the loan. The NLF is not allowed to accept losses on its loans. Any such losses can only be written off by primary legislation; however, in 1990 HM Treasury gave an undertaking to the Public Accounts Committee that it would not seek Parliament’s approval to such a course except as part of a reconstruction of the borrower’s finances prior to privatisation. In other cases, HM Treasury would look to the borrower’s sponsor department to cover any losses from its resource account.
In the case of advances to the PWLB for loans to Local Authorities, the PWLB manages the financial relationship with the borrower though the credit risk is ultimately borne by the NLF.
In the context of NLF loans issued to trading organisations at market rates, under HM Treasury’s Commercial Lending policy, the terms and interest rates are designed to reflect the terms on which a private sector lender, such as a commercial bank would lend to the borrower if the borrower were a wholly private sector body rather than a government body.
Ceilings on total lending from the NLF to specific bodies are prescribed in the statutes governing each loan. The PWLB is allowed to lend up to an aggregate amount of £135 billion[footnote 10]. For short-term lending to public bodies, the maximum exposure of the NLF is determined by prescribed credit ceilings appropriate for the circumstances of the body.
The IMF maintains precautionary balances (comprising retained earnings) as prudential cover to ensure the continued security and liquidity of its members’ claims. Other factors that help safeguard the Fund’s resources include the conditionality associated with lending by the IMF and the IMF’s status as a creditor with preferential right to receive payment.
None of the NLF’s financial assets are past due or impaired.
Derivatives and hedging
The NLF itself does not use derivatives or undertake hedging. However, some of the risks on the NLF are offset by the activities of the EEA. The Exchange Equalisation Account Act 1979 constrains how the EEA may borrow from outside government. Where the EEA’s foreign currency reserves are financed by foreign currency borrowing, the debt is issued by and is an obligation of the NLF. The foreign currency raised is sold by the NLF to the EEA for sterling. While the NLF remains exposed to the interest and exchange rate risks from the foreign currency debt it has issued, in practice these risks are offset through the EEA’s programme of asset management and swaps. There was no foreign currency debt outstanding in the NLF at 31 March 2026.
4.17 17 Related Parties
HM Treasury is the ultimate controlling party of the NLF. There have been no direct transactions between HM Treasury and the NLF in 2025-26. As at 31 March 2026 £0.5 billion proceeds of debt issuance from Treasury Group are deposited with the NLF (2024-25: £0.5 billion).
The main related parties of the NLF are the CF, DMA, EEA, PWLB, Bank of England and NS&I. The relationship between the NLF and CF is explained in the Overview within the Performance report. The NLF has provided finance in the year to the DMA, EEA, PWLB and to various statutory public sector bodies. The NLF has also transacted with the Bank of England and NS&I. Transactions with these bodies are all disclosed in these accounts. The NLF has also had a significant number of transactions with other government bodies via its temporary borrowing of balances in various Government Banking bank accounts.
During the year, there have been no transactions between key management personnel at HM Treasury and the NLF.
4.18 18 Events after the Reporting Period
There are no events after the reporting period to report.
4.19 19 Date of Authorisation for Issue of Account
These financial statements have been authorised for issue by the Accounting Officer on the same date as the Comptroller and Auditor General’s Certificate and Report.
5. Appendix A – Glossary
| Consolidated Fund | A fund used by HM Treasury to collect certain receipts and make payments to government bodies. |
|---|---|
| Contingencies Fund | A fund used by HM Treasury to support emergency spending in advance of approval by Parliament. |
| Exchange Equalisation Account (EEA) | Holds the UK’s reserves of gold, foreign currency assets, and International Monetary Fund (IMF) Special Drawing Rights (SDR). The Bank of England acts as HM Treasury’s agent in the day-to-day management of the EEA. |
| Financial Reporting Manual (FReM) | A technical guide for producing the accounts of public bodies. |
| Managing Public Money | A publication produced by HM Treasury which is concerned with regularity and propriety and sets out the main principles for dealing with resources used by public sector bodies. |
| National Audit Office (NAO) | Office of the Comptroller and Auditor General, which audits accounts of government bodies and carries out value for money inspections within the bodies it audits |
| Net Cash Requirement | The limit voted by Parliament reflecting the maximum amount of cash that can be released from the Consolidated Fund to a department in support of expenditure in its Estimate. In the case of a negative net cash requirement, the department must generate a surplus of at least that amount. |
| Poverty Reduction and Growth Trust (PRGT) | IS the IMF’s main vehicle for providing concessional financing (currently at zero interest rates) to low-income countries (LICs). Poverty Reaction and Growth Trust |
| Reserve Tranche Position (RTP) | The difference between the IMF’s holdings of sterling and the UK’s subscription (or quota) to the IMF. It is in effect, the amount of the UK’s subscription the IMF has called. RTP is a reserve asset as in the event of need, the UK could exchange sterling for useable foreign currencies up to the value of its RTP. |
| Resilience and Sustainability Trust (RST) | The IMF’s Resilience and Sustainability Trust (RST) helps low-income and vulnerable middle-income countries build resilience to external shocks and ensure sustainable growth, contributing to their longer-term balance of payments stability. |
| Special Drawing Rights (SDRs) | International reserve asset created by the IMF in 1969 as a supplement to the then existing reserve assets. It is currently valued in terms of a weighted basket of five currencies (US dollar, sterling, yen, euro, and renminbi). |
6. Appendix B – Accounts Direction
National Loans Fund - Accounts Direction given by the Treasury
- The Treasury shall prepare accounts for the National Loans Fund for the year ending 31 March 2025 and each subsequent financial year, that give a true and fair view of the state of affairs of the National Loans Fund at the reporting date and of its cash flows for the year then ended.
- The accounts shall be prepared in accordance with the requirements of the relevant version of the Government Financial Reporting Manual (FReM).
- Compliance with the requirements of the FReM will, in all but exceptional circumstances, be necessary for the accounts to give a true and fair view. If, in these exceptional circumstances, compliance with the requirements of the FReM is inconsistent with the requirement to give a true and fair view, the requirements of the FReM should be departed from only to the extent necessary to give a true and fair view. In such cases, informed and unbiased judgement should be used to devise an appropriate alternative treatment which should be consistent with both the economic characteristics of the circumstances concerned and the spirit of the FReM. Any material departure from the FReM should be discussed in the first instance with the Treasury.
- The Statement shall be transmitted to the Comptroller and Auditor General for the purpose of his examination and report by a date agreed with the Comptroller and Auditor General and the Treasury to enable compliance with the administrative deadline for laying the audited accounts before Parliament.
- This accounts direction shall be reproduced as an appendix to the accounts.
Charlotte Goodrich
Deputy Director, Government Financial Reporting, Public Spending Group
HM Treasury
25 November 2025
-
The GBP/SDR exchange rate at 31 March 2026 was 0.973061 (31 March 2025: 0.97385) ↩
-
The deadline maybe subject to further extension by the IMF Executive Board, as needed. ↩
-
Zarin Patel retired from her post as Non-Executive Board member and Chair of the Audit and Risk Committee on the 31 July 2025. Jane Hanson CBE’s term ended on 31 December 2025, after it was extended for four months for continuity of experience during a period of change. Catherine Vaughan has also joined the Audit and Risk Committee. Edward Twiddy took on the role of Chair from 1 January 2026. ↩ ↩2 ↩3 ↩4
-
DMA Annual Report & Accounts can be viewed on the UK Debt Management Office website ↩ ↩2
-
HMT central funds, Exchange Equalisation Account ↩
-
The GBP/SDR exchange rate at 31 March 2026 was 0.973061 (31 March 2025: 0.97385) ↩
-
Lending includes both loans made under the New Arrangements to Borrow (NAB) and the bilateral loan facility ↩
-
This analysis is based on the proportion of the total nominal value of each gilt held by the respective entities. Figures will differ from the value shown in the accounts of the other entities if an alternative valuation method is applied by those entities. ↩