Draft legislation (accessible version)
Published 6 October 2026
© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/consultations/draft-legislation-plastic-packaging-tax-chemical-recycling-and-adoption-of-a-mass-balance-approach/draft-legislation-accessible-version
The Plastic Packaging Tax (Chemical Recycling Certification Schemes) Regulations 2027
The Commissioners for His Majesty’s Revenue and Customs make these Regulations in exercise of the powers conferred by sections 49(10), 49A(1)(c), (3)(c) and (6)(b), 49B, 63(1) and 84(1) and (2) of the Finance Act 2021 [footnote 1].
Part 1: Introductory
Citation and commencement
- 1 These Regulations may be cited as the Plastic Packaging Tax (Chemical Recycling Certification Schemes) Regulations 2027 and come into force on *** 2027.
Interpretation
- 2 In these Regulations—
- ‘the Act’ means the Finance Act 2021;
- ‘attribution’ means an attribution of recovered material [footnote 2] under section 49A(2)(c) of the Act;
- ‘scheme’ means a chemical recycling certification scheme [footnote 3];
- ‘site’ means the whole area under the control of a certified person [footnote 4] where a mass balance process [footnote 5] is operated by that person, and for this purpose 2 or more areas under the control of the same person and separated only by a road, railway or inland waterway are to be treated as one whole area;
- ‘writing’ includes electronic communications.
Part 2: Conditions for the attribution of recovered material
Methodology of attribution
- 3—(1) An attribution must meet the conditions in paragraphs (2) to (4).
- (2) The weight of recovered material that may be attributed within a balancing period is the sum of—
- (a) the amount obtained by multiplying the weight of qualifying input material [footnote 6] added to the mixture during that period by the conversion factor,
- (b) the weight of any recovered material that was available for attribution under this paragraph in the preceding balancing period but was not attributed in that period, and
- (c) any material available for attribution as a result of regulation 4(1).
- (3) The proportion of consumed fuel to which recovered material is attributed during a balancing period must be the same as the proportion of the mixture (before it is processed) that is qualifying input material.
- (4) For the purposes of attributing recovered material, all mass balance processes operated at a single site are to be treated as if they were a single mass balance process.
- (5) In this regulation —
- ‘balancing period’ means—
- (a) the 3 month period starting with the day on which a certified person is granted a certificate under provisions of a scheme required by regulation 9, and
- each successive period of 3 months.
- ‘conversion factor’ is the percentage calculated in accordance with the formula—
- ‘balancing period’ means—
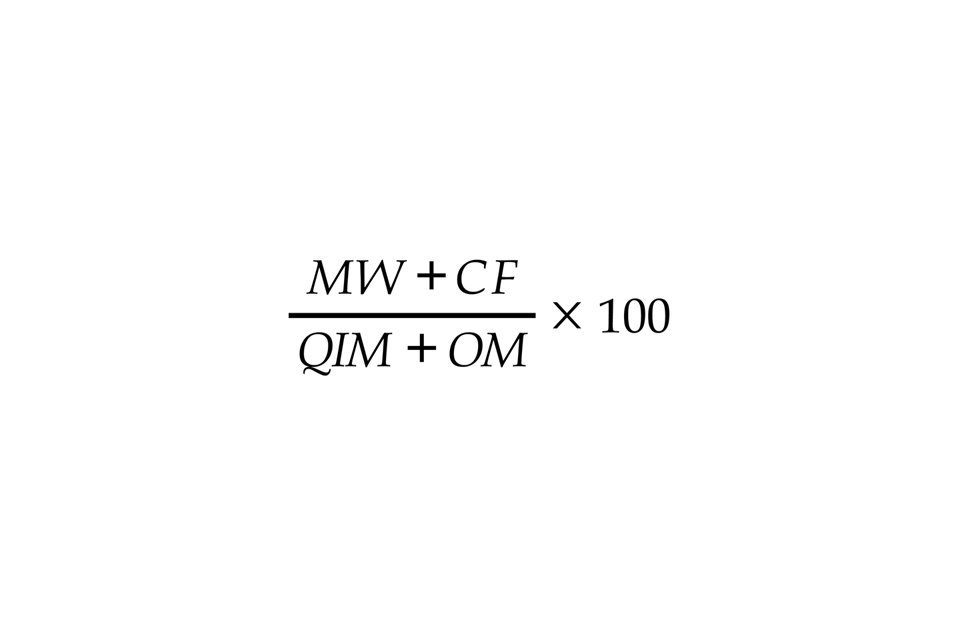
- where, in relation to a mass balance process, during a balancing period—
- MW is the weight of material withdrawn from the mixture after processing (see section 49A(2)(c)(i) of the Act),
- CF is the weight of consumed fuel,
- QIM is the weight of qualifying input material, and
- OM is the weight of other material added to that mixture (see section 49A(2)(a) of the Act) [footnote 7].
Transfer of recovered material credit
- 4—(1) Where recovered material is available for attribution under a mass balance process (‘transferring process’) other than the mass balance process under which an attribution is made (‘receiving process’), it may instead be attributed under the receiving process provided that the conditions in paragraphs (2) to (6) are met.
- (2) The quantity of recovered material available for attribution under the transferring process must be reduced by an amount equal to any amount attributed under the receiving process.
- (3) Material attributed under the receiving process may only be attributed to material constituting output products that could have been produced under the transferring process.
- (4) The certified person operating the transferring process must be either—
- (a) the same undertaking that operates the receiving process, or
- (b) an undertaking in relation to which the certified person operating that process is a group undertaking.
- (5) The sites at which the receiving process and the transferring process take place must be connected by a pipeline that meets the requirements specified in a notice published by the Commissioners.
- (6) The attribution must meet any further requirements set out in a notice published by the Commissioners.
- (7) In paragraph (4), ‘undertaking’ and ‘group undertaking’ have the same meaning as in section 1161 of the Companies Act 2006 [footnote 8].
Material not to be regarded as withdrawn fuel
- 5—(1) Material to which this regulation applies is not to be regarded as withdrawn fuel [footnote 9] for the purposes of section 49A(3)b) of the Act.
- (2) This regulation applies to so much of the material withdrawn from the mixture after processing that constitutes an output product as is given by the result of the calculation—
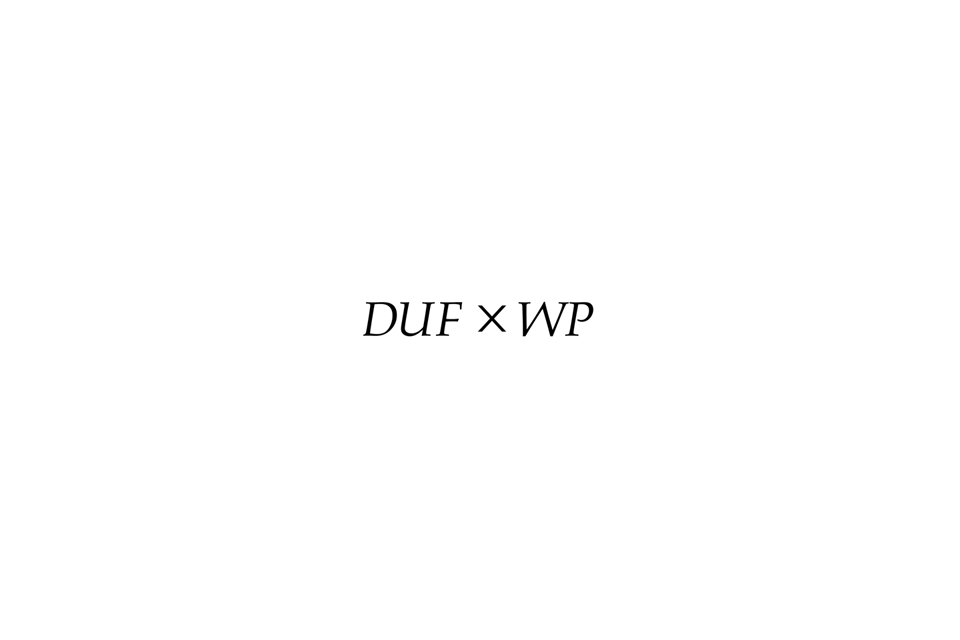
- where—
- DUF is the Dual Use Factor, and
- WP is the weight of that output product.
- (3) For the purposes of paragraph (2), the ‘dual use factor’ is a number between 0 and 1 inclusive that—
- (a) is determined in accordance with the methodology set out in the Dual Use Output Products Document, and
- (b) for which a certified person has sufficient evidence to satisfy the Commissioners that the attribution accords with that methodology.
- (4) The Commissioners must prescribe in a notice what constitutes sufficient evidence for the purposes of paragraph (3)(b).
- (5) In this regulation, ‘Dual Use Output Products Document’ means the document titled ‘Dual-use factors for refinery and petrochemical output products’, version [ ** ], dated [ ** ] [footnote 10].
Part 3: Conditions for chemical recycling certification schemes
Interpretation of part 3
- 6 In this Part—
- ‘attribution declaration’ has the meaning given by regulation 12;
- ‘certificate’ means a certificate issued under provision required by regulation 9(1)(c);
- ‘certification body’ means a body responsible for certification of certified persons under a scheme;
- ‘minimum standards’ has the meaning given by regulation 9(1)(a);
- ‘scheme operator’ means a body responsible for the administration of a scheme including—
- (a) making provision in relation to a scheme under this Part,
- (b) keeping records of certified persons in accordance with regulation 15.
Conditions for chemical recycling certification schemes
- 7 For the purposes of section 49A(1)(c) of the Act, a chemical recycling certification scheme must contain provision made by a scheme operator complying with this Part.
Accreditation
- 8—(1) A scheme must contain provision—
- (a) setting out the standards that a certification body must meet in order to be accredited to administer certification under that scheme, and
- (b) requiring that a certification body is accredited by an accrediting body as meeting those standards.
- (2) An accrediting body is a body that—
- (a) is a full member of Global Accreditation Cooperation Incorporated, a New Zealand Incorporated Society with incorporation number 50223540 [footnote 11], and
- (b) meets the standards set out in a notice published by the Commissioners.
- (3) A notice under paragraph (2)(b) may make provision by reference to technical standards that an accreditation body must meet, including by reference to standards produced by international bodies.
Certification bodies
- 9—(1) A scheme must contain provision—
- (a) requiring that persons may only be certified persons under that scheme where they meet the standards set out in a notice published by the Commissioners (‘minimum standards’);
- (b) under which the assessment of whether those standards are met is to be carried out by a certification body;
- (c) under which the meeting of those standards must be evidenced by a certificate in writing issued by that certification body.
- (2) A notice under paragraph (1)(a) may make provision, including by reference to technical standards produced by national and international bodies, relevant to demonstrating that a certified person is competent to meet any relevant standards or requirements relating to a mass balance process.
- (3) The Commissioners may publish a notice specifying further requirements for which the scheme must provide in relation to certification including—
- (a) the information that must be included in a certificate,
- (b) the maximum period for which a certificate can be valid,
- (c) requirements relating to the process for application, issue and renewal of certificates, including requirements as to time, and
- (d) persons or descriptions of persons who must be certified under a scheme.
Audit
- 10—(1) The provision that is required in relation to assessment under regulation 9(1)(b) includes provision requiring—
- (a) a certification body to conduct an audit of any person applying for the issue or renewal of a certificate (‘applicant’);
- (b) that any audit is to—
- (i) assess the ability of the applicant to comply with the minimum standards;
- (ii) include an inspection of all sites at which a mass balance process operated by the applicant takes place;
- (c) the certification body to produce a report setting out the results of the audit;
- (d) the certification body to comply with any further matters relating to the audit that may be specified in a notice published by the Commissioners.
- (2) The matters that may be specified in a notice under paragraph (1)(d) include—
- (a) requirements for a certification body to carry out risk assessments relating to an applicant, including the timing of, and criteria to be applied in, such assessments;
- (b) requirements as to the timing and frequency of audits;
- (c) further provision about circumstances in which the inspection of a site may be required;
- (d) requirements as to—
- (i) the information that must be included in a report under paragraph (1)(c);
- (ii) the persons to whom copies of such a report must be sent.
Monitoring and enforcement
- 11—(1) A scheme must include provision under which a certification body is required to—
- (a) monitor the compliance of certified persons with the minimum standards;
- (b) investigate any cases where it reasonably suspects that those standards are not being met;
- (c) undertake any further requirements relating to monitoring that may be specified in a notice published by the Commissioners.
- (2) The matters that may be specified in a notice under paragraph (1)(c) include—
- (a) prescribing indications of non-compliance that must be investigated;
- (b) prescribing risk criteria relating to monitoring of certified persons.
- (3) The scheme must provide for a process under which, if the certification body considers that a certified person has failed to meet the minimum standards, it must—
- (a) give the certified person a reasonable period in which to rectify any such failure,
- (b) if the certified person fails to rectify the failure within that period, issue a notice to the certified person suspending the validity of the certificate until such time as the failure is rectified, and
- (c) when it is satisfied that the failure has been rectified, issue a notice to the certified person confirming that the suspension has ended.
- (4) The scheme must provide for a process under which, if the certification body considers that there has been a significant, deliberate or repeated failure to meet the minimum standards by a certified person, it must—
- (a) withdraw that certified person’s certificate, and
- (b) issue a notice confirming that withdrawal
- (5) Provision made in accordance with paragraphs (3) and (4) must include provision for a process under which a person is entitled to appeal against the suspension or withdrawal of a certificate, and for the determination of such appeals.
Attribution declarations
- 12—(1) A scheme must include provision requiring that any attribution is accurately recorded by the certified person making it in a document in writing (an ‘attribution declaration’) that includes the information specified in a notice published by the Commissioners.
- (2) The Commissioners must publish a notice under paragraph (1).
Chain of custody
- 13.—(1) A scheme must include provision under which, wherever a certified person is operating a mass balance process in which they receive material falling within section 49A(4)(b) of the Act from another person (‘supplier’)—
- (a) the certified person is required to obtain from the supplier—
- (i) a copy of all attribution declarations relating to that material, and
- (ii) copies of all certificates showing that the person or persons who made those attribution declarations were, at the time the declarations were made, certified persons;
- (b) the certified person is required to—
- (i) conduct appropriate due diligence checks in relation to the information received from the supplier, and
- (ii) report any suspected non-compliance with the requirements of the scheme by a supplier to the scheme operator.
- (a) the certified person is required to obtain from the supplier—
- (2) Where—
- (a) a certified person has complied with provision required under paragraph (1) in relation to a supplier, and
- (b) the supplier’s certificate is subsequently suspended or withdrawn in accordance with provision required by or under regulation 11,
- the suspension or withdrawal is to be disregarded in determining whether material is qualifying input material for the purposes of section 49A(4)(b) of the Act.
Records
- 14—(1) A scheme must include provision requiring that a certified person keep a record in writing of—
- (a) all attribution declarations—
- (i) made by them, or
- (ii) supplied to them under provision complying with regulation 13(1)(a)(i);
- (b) any certificate—
- (i) issued to them, or
- (ii) supplied to them under provision complying with regulation 13(1)(a)(ii);
- (c) such other records demonstrating that the requirements of a scheme have been met as may be specified in a notice made by the Commissioners.
- (a) all attribution declarations—
- (2) The scheme must provide that any records required to be kept under any provision complying with these Regulations must be retained for a period of not less than 6 years from the date that the record was created.
Database
- 15—(1) A scheme must make provision for a scheme operator to establish and maintain a database containing—
- (a) the full names and addresses of persons certified under the scheme;
- (b) the products that are produced under the mass balance process to which the certificate relates;
- (c) copies of certificates issued by any certification body including the numbers and validity dates of those certificates;
- (d) any further information that the Commissioners specify in a notice.
- (2) The database must —
- (a) be available to the public;
- (b) be searchable by reference to the criteria specified in paragraph (1);
- (c) comply with any further requirements the Commissioners may specify in a notice.
- (3) Provision under paragraph (1) must require a record of any issue of a certificate under provision complying with regulation 10, or suspension or withdrawal under provision complying with regulation 11 (‘relevant event’) to be added to the database by the scheme operator within one week of the relevant event taking place.
Part 4: Amendment of the Plastic Packaging Tax (General) Regulations 2022
Amendment of the Plastic Packaging Tax (General) Regulations 2022
- 16.—(1) The Plastic Packaging Tax (General) Regulations 2022 [footnote 12] are amended as follows.
- (2) In regulation 6 (provision of evidence that plastic is recycled plastic)—
- (a) in the heading, at the end insert ‘or attributed recycled plastic’[footnote 13];
- (b) in paragraph (1), after ‘recycled plastic’, insert ‘or attributed recycled plastic’.
- (3) In regulation 7 (chargeable plastic packaging component: method of calculation of recycled plastic content)—
- (a) in the heading, after ‘recycled plastic’ insert ‘and attributed recycled plastic’;
- (b) in paragraph (3), in the text following the formula—
- (i) in the definition of X, for ‘proportion of recycled plastic’ substitute ‘combined
- (ii) in the definition of A, for ‘weight of recycled plastic’ substitute ‘total weight of recycled plastic and attributed recycled plastic’; proportion of recycled plastic and attributed recycled plastic’;
- (c) in paragraph (6)(a), for ‘weight of recycled plastic’ substitute ‘total weight of recycled plastic and attributed recycled plastic’;
- (d) in paragraph (7)(a)(iii), for ‘weight of the recycled plastic’ substitute ‘total weight of the recycled plastic and attributed recycled plastic’.
- (4) In regulation 23 (measurement of weight: application and interpretation), for paragraph (3) substitute—
- (3) This Chapter does not apply to—
- (a) the estimation of the weight of finished plastic packaging components for the purposes of section 55(2)(a) of the Act (liability to register: producers and importers),
- (b) regulation 20(2)(i), or
- (c) any measurement of weight provided for by the Plastic Packaging Tax (Chemical Recycling Certification Schemes) Regulations 2027.’.
- (3) This Chapter does not apply to—
EXPLANATORY NOTE
(This note is not part of the Regulations)
These Regulations make provision for the operation of the chemical recycling attribution regime introduced by sections 49A and 49B of the Finance Act 2021 (inserted by the Finance Act 2026) for the purposes of Plastic Packaging Tax.
Part 1 of the Regulations provides for citation, commencement and general interpretation.
Part 2 sets out the conditions that must be met before recovered material arising from a chemical recycling mass balance process may be attributed to plastic packaging components. It establishes the methodology for calculating the quantity of recovered material that may be attributed, permits transfers of attributable material between certain connected mass balance processes, and makes provision for the treatment of specified dual-use output products.
Part 3 prescribes the requirements that must be included in a chemical recycling certification scheme. These include requirements relating to the accreditation of certification bodies, the certification, audit and monitoring of participants, record-keeping, supply chain due diligence and the maintenance of a public database of certified persons and certificates. The purpose of these requirements is to ensure that claims that plastic is attributed recycled plastic are supported by independently verified certification arrangements.
Part 4 amends the Plastic Packaging Tax (General) Regulations 2022 (S.I. 2022/117) to reflect the introduction of attributed recycled plastic. The amendments make provision about the evidence required to demonstrate that plastic is attributed recycled plastic, amend the calculation of recycled content for Plastic Packaging Tax purposes, and disapply certain existing measurement provisions in relation to measurements made under these Regulations.
The reference document entitled ‘Dual-use factors for refinery and petrochemical output products’ version [1.00] dated [Y] is available electronically from [gov.uk address]. A person unable to access the document electronically may access it by inspection free of charge at HMRC, 100 Parliament Street, London SW1A 2BQ.
A notice published under a power in these Regulations will be available at the website on [www.gov.uk/X]. A person unable to access a notice electronically may access it by inspection free of charge at HMRC, 100 Parliament Street, London SW1A 2BQ.
A Tax Information and Impact Note (TIIN) covering this instrument was published on 26 November 2025 alongside the budget on GOV.UK. It remains an accurate summary of the impacts that apply to this instrument.
-
2021 c. 26 (‘the Act’). Section 49(10) was amended by, and sections 49A and 49B were inserted by, section 105 of the Finance Act 2026 (c. 11) (‘FA 2026’). ↩
-
’Recovered material’ is defined in section 49(4) of the Act, as amended by section 106(a) of FA 2026. ↩
-
‘Chemical recycling certification scheme’ is defined in section 49A of the Act. ↩
-
’Certified person’ is defined in section 49A(5) of the Act. ↩
-
A ‘mass balance process’ is defined in section 49A(2) of the Act. ↩
-
’Qualifying input material’ is defined in section 49A(3) of the Act. ↩
-
’Mixture’ has the meaning given by section 49A(2), and ‘consumed fuel’ has the meaning given by section 49A(5) of the Act. ↩
-
c. 46. Section 1162 of that Act defines ‘parent undertaking’ and ‘subsidiary undertaking’ for the purposes of these definitions. ↩
-
’Withdrawn fuel’ has the meaning given by section 49A(5) of the Act. ↩
-
This document is available online at [ ** ]. A hard copy is available for inspection at [ ** ]. ↩
-
A full member is a body providing accreditation that has been accepted by Global Accreditation Cooperation Limited (‘Global ACI’) as a signatory to the Global ACI Mutual Recognition Arrangement. Details of current full members, as well as the Constitution of Global ACI and other relevant documentation, are available at https://global-aci.org/en/home. ↩
-
S.I. 2022/117. ↩
-
’Attributed recycled plastic’ is defined in accordance with section 49(2A) of the Act. Section 49(7A) provides that plastic is not to be taken as attributed recycled plastic unless it is shown that it is attributed recycled plastic. ↩