Mortgage and landlord possession statistics: April to June 2026
Updated 19 August 2026
Applies to England and Wales

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/statistics/mortgage-and-landlord-possession-statistics-april-to-june-2026/mortgage-and-landlord-possession-statistics-april-to-june-2026
1. Main Points
This publication presents quarterly mortgage and landlord possession statistics up to April to June 2026. In general, we have compared figures to the same quarter in the previous year. Should users wish to compare against previous years, they can do so using the accompanying statistical tables. For technical detail, please refer to the accompanying supporting document published alongside each quarterly publication here: Mortgage and landlord possession statistics - GOV.UK
| All mortgage actions have decreased. | Compared to the same quarter in 2025 there were decreases in mortgage possession claims from 6,539 to 5,232 (20%) and orders from 4,421 to 3,651 (17%), warrants from 3,804 to 3,101 (18%) and a decrease in repossessions by county court bailiffs from 1,166 to 1,008 (14%). |
| Landlord possession claims increased and orders remained stable, while warrant actions and repossessions decreased. | When compared to the same quarter in 2025 there were increases in landlord possession claims from 22,352 to 23,635 (6%), orders remained stable and there were decreases in warrants from 10,349 to 9,715 (6%), and repossessions from 6,767 to 6,560 (3%). |
| Mortgage claims have decreased across most regions, whilst Landlord claims have increased. | Increases in landlord possession claims have been recorded across most regions compared to last quarter. Meanwhile, decreases have been recorded across most regions for mortgage possession claims over the same period. |
| Median timeliness for mortgage repossessions has increased. | The median average time from claim to mortgage repossession has increased to 49.1 weeks, up from 42.9 weeks in the same period in 2025. The median average time from claim to warrant has increased to 39.4 weeks, up from 34.0 weeks in the same period in 2025. |
| Median timeliness for landlord repossessions has decreased. | The median average time from claim to landlord repossession has decreased to 27.1 weeks, down from 27.9 weeks in the same period in 2025. |
A data visualisation tool has also been published that provides further breakdowns in a web-based application. The tool can be found here.
We are currently experiencing technical issues with the data visualisation tool, we will republish the tool as soon as possible.
For feedback related to the content of this publication and visualisation tool, please contact us at CAJS@justice.gov.uk
2. Statistician’s Comment
There have been decreases in both mortgage and landlord repossessions when compared to the same quarter in 2025. While the number of new mortgage claims have decreased in the same period, the number of landlord claims issued increased.
The median timeliness for mortgage claims to repossessions has increased by more than 6 weeks when compared to the same period in 2025 and is the highest since Q4 2023. The median timeliness for landlord claims to repossession has decreased slightly, by less than one week overall, although private landlord repossessions have seen the largest decrease, by just under 3 weeks compared to the same period last year.
3. Overview of Mortgage Possession
Mortgage possession claims, orders, warrants and repossessions have decreased.
Compared to the same quarter in 2025, mortgage possession claims (5,232) are down 20%, mortgage orders for possession (3,651) are down 17%, warrants issued (3,101) are down 18% and repossessions (1,008) are down 14%.
Figure 1: Mortgage possession actions in the county courts of England and Wales, April to June 2021 to April to June 2026 (Source: Table 1)
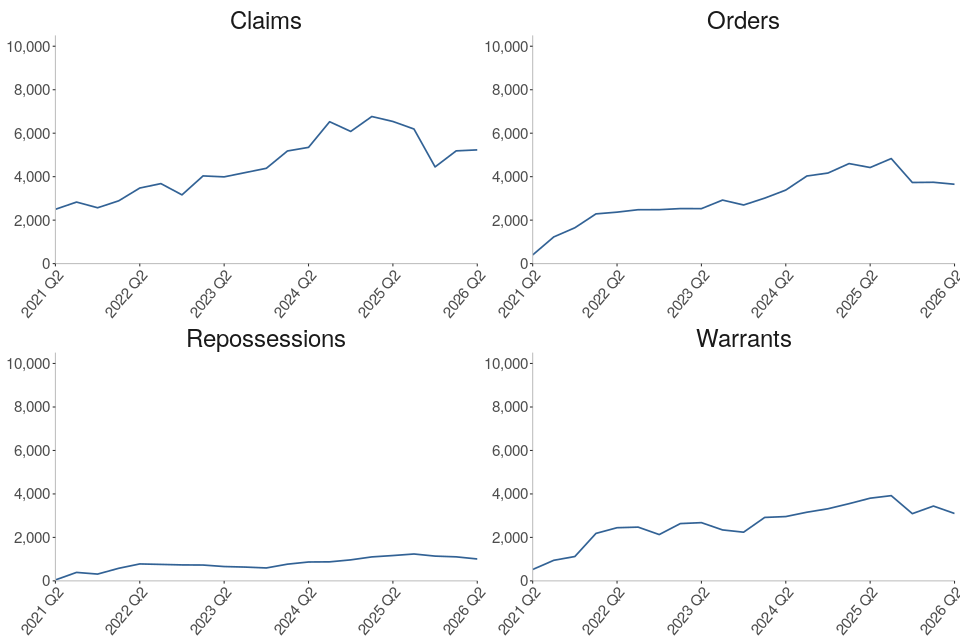
Following Covid-19, mortgage possession claims have generally risen since Q2 2021. However, in the most recent quarter, Q2 2026, there were 5,232 claims for possession, down 20% from the same quarter in 2025.
Orders and warrants for possession have followed a similar trend to mortgage claims. Compared to the same quarter in 2025, orders are down 17% to 3,651 and warrants are down 18% to 3,101 in Q2 2026. This data shows early signs of decreases but it is not yet known if this trend will continue. We will monitor this closely over the next quarters.
4. Mortgage Possession Action Timeliness
Claim to warrant median timeliness has increased by 5.4 weeks while claim to repossession median timeliness has increased by 6.3 weeks compared to the same quarter last year. Median timeliness for claim to order has remained stable.
The median average time from claim to repossession has increased to 49.1 weeks, up from 42.9 weeks in the same period in 2025.
Figure 2: Average timeliness of mortgage possession actions, April to June 2021 to April to June 2026 (Source: Table 3)
Number of weeks taken from initial mortgage claim to…
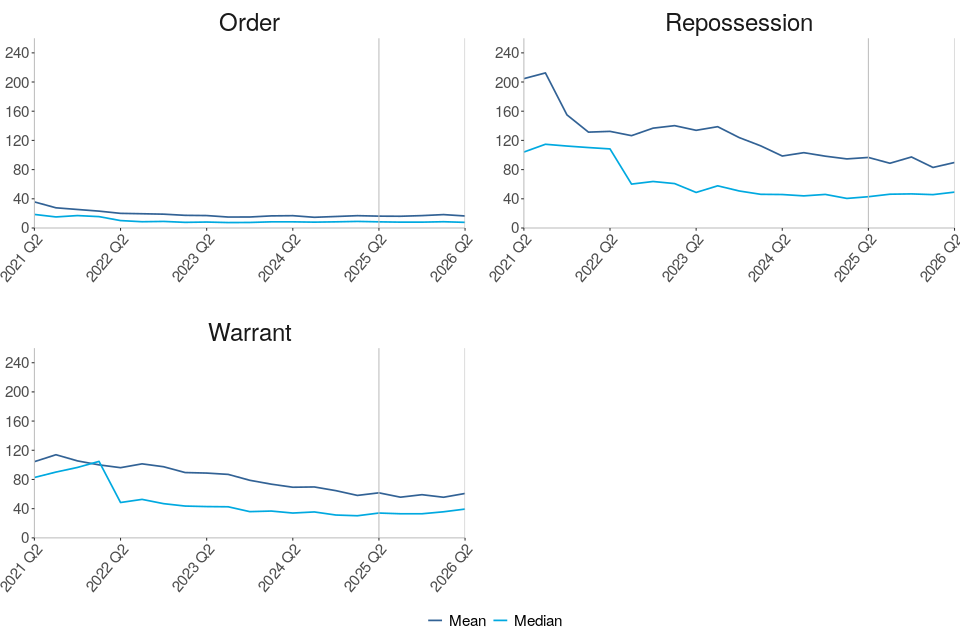
Median time taken to complete mortgage actions has remained relatively stable for claims to orders. Claims to warrants and claims to repossession median timeliness have increased compared to the same quarter in 2025. This quarter;
-
Claims to order median timeliness is currently 7.7 weeks, down from 8.4 weeks in the same period in 2025.
-
Claims to warrant median timeliness has increased to 39.4 weeks, up from 34.0 weeks in the same period in 2025.
-
Warrants to repossession median timeliness has increased to 10.1 weeks, up from 9.6 weeks in the same period in 2025.
-
Claims to repossession median timeliness has increased to 49.1 weeks, up from 42.9 weeks in the same period in 2025.
The trend for mortgage possession timeliness is driven by outright orders, which make up more than two thirds of all cases. In the most recent quarter, the median time taken from claim to repossession was 45 weeks for outright orders (an increase of 5.3 weeks), and 120.7 weeks for suspended orders (a decrease of 22.4 weeks).
The above charts distinguish between the timeliness of possession claims at different stages of a case. Average time taken from claim to warrant or claim to repossession can fluctuate and is affected by various factors. For example, the final two charts take account of the amount of time between the court order being issued and the claimant, such as the mortgage lender, applying for a warrant of possession.
Median figures are generally considerably lower than mean figures, demonstrating that progression from claim to successive stages can be positively skewed by outlying cases.
5. Overview of Landlord Possession
The number of landlord possession claims have increased compared to the same quarter of last year, while orders have remained stable, and warrants and repossessions have decreased compared to the same quarter of last year.
Claims (23,635) have increased by 6% whilst orders remained stable compared to the same quarter in 2025. Warrants (9,715) and repossessions (6,560) have decreased by 6% and 3% respectively in the same period.
Figure 3: Landlord possession actions in the county courts of England and Wales, April to June 2021 to April to June 2026 (Source: Table 4)
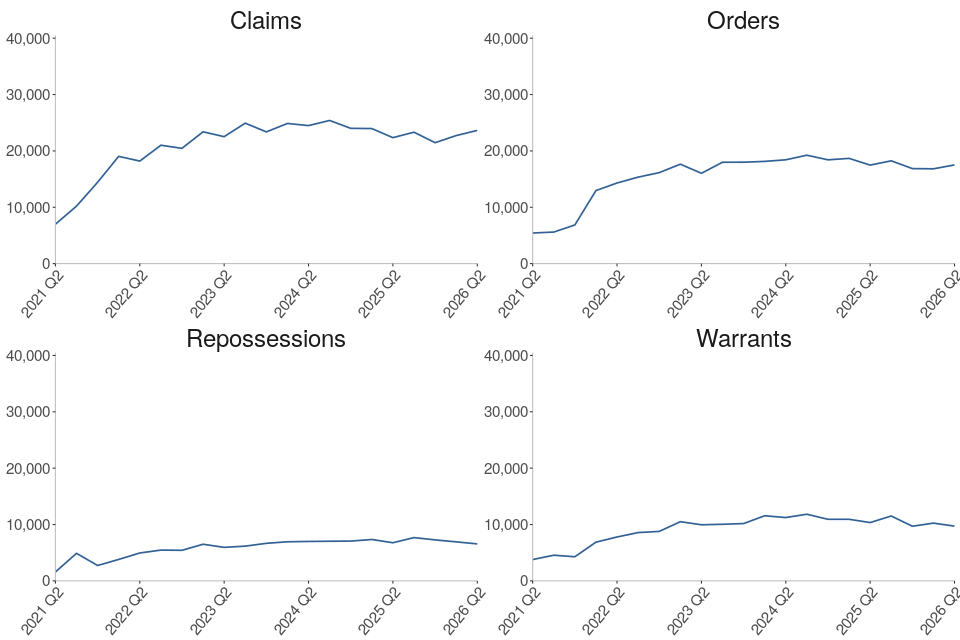
Landlord possession claims showed a general increase from Q2 2021 peaking in Q3 2024 at 25,402. These have fallen overall and are currently at 23,635. Within the landlord possession actions, accelerated claims are up 16%, private landlord claims are up 5% and social landlord claims are down 3% compared to the same quarter in 2025.
In Q2 2026, 32% (7,449) of all landlord possession claims were social landlord claims, compared to 32% (7,617) private landlord claims and 36% (8,569) accelerated claims.
The fall in claim and orders volumes is observed in courts across most geographical regions. As in previous quarters, a concentration was seen in London, with 7,793 landlord claims and 5,440 landlord orders at London courts in Q2 2026, accounting for 33%, and 31% each of the respective totals. In London, there was a increase of 2% (from 7,610 in Q2 2025) for landlord claims and a increase of 2% for landlord orders (from 5,356 in Q2 2025).
The 6% decrease in landlord warrants compared to Q2 2025, was driven by a decrease in London. The largest regional number (2,993) was again found in London, making up 31% of all landlord warrants. There was a decrease of 20% for landlord warrants in London (from 3,744 in Q2 2025).[footnote 1]
The Housing Loss Prevention Advice Service (HLPAS) provides advice to tenants and homeowners as soon as they are served with a written notice asking them to leave their home. Individuals who require the service do not need to meet legal aid financial eligibility rules as the service is not means tested but they are required to show evidence that they are at risk of losing their home. More information can be found here.
The Renters Right Act came into force on 1st May 2026 and this quarter’s data, which covers from April to June, reflects two months of activity following the Act’s implementation. It’s not clear whether the overall fall in landlord possession claims or changes in other types of claims can be attributed to commencement of the Act, but we will continue to closely monitor trends over the next quarters. Further information on the act can be found here: Guide to the Renters’ Rights Bill - GOV.UK.
6. Landlord Possession Timeliness
Median timeliness figures for landlord claims to orders and warrants have remained relatively stable compared to the same period of 2025, while repossession timeliness decreased by 0.7 weeks over the same period.
The median average time from claim to repossession has decreased to 27.1 weeks, down from 27.9 weeks in the same period of 2025.
Figure 4: Average timeliness of landlord possession actions, April to June 2021 to April to June 2026 (Source: Table 6)
Number of weeks taken from initial landlord claim to…
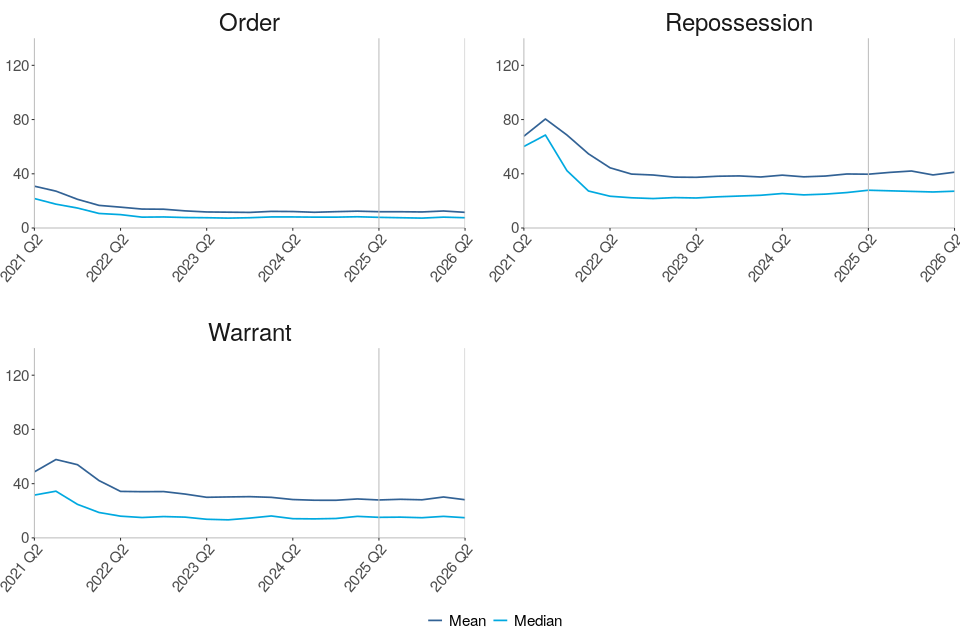
The median time taken to complete landlord actions increased for warrants and repossessions this quarter.
-
Claims to order median timeliness is currently 7.6 weeks, down from 7.9 weeks in the same period in 2025.
-
Claims to warrant median timeliness is currently 14.9 weeks, down from 15.1 weeks in the same period in 2025.
-
Warrants to repossessions median timeliness has decreased to 9.4 weeks, down from 10.1 weeks in the same period in 2025.
-
Claims to repossessions median timeliness has decreased to 27.1 weeks, down from 27.9 weeks in the same period in 2025.
As shown in Figure 4, median figures are generally considerably lower than mean figures, demonstrating that progression from claim to successive stages can be positively skewed by outlying cases.
7. Regional Possession Claims
Westminster had the highest overall rate of mortgage claims at 344 per 100,000 households owned by a mortgage or loan.
Private landlord claims were highest in Enfield with 579 per 100,000 households owned by a private landlord.
Social landlord claims were highest in Lewisham with 453 per 100,000 households owned by a social landlord.
Since Q4 2022, the methodology used for calculating the rates of possession claims[footnote 2] and repossessions has been modified to take into account the variation in proportions of tenure[footnote 3] types in each local authority (LA) as measured by the 2021 census. More information on this change is provided in the accompanying guide to this publication here.
The Isles of Scilly and the City of London have very small populations (ranked 309th and 308th out of 309 respectively for population size) therefore rates may be less robust.
There have been two boundary code changes for Barnsley and Sheffield (Yorkshire and the Humber) and due to technical issues, these boundaries will be updated in Figures 5 to 10 as soon as possible, however the data for these local authorities is available within the Map CSV.
Figure 5: Mortgage possession Claims per 100,000 households owned by a mortgage or loan, April to June 2026 (Source: map.csv; see supporting guide)
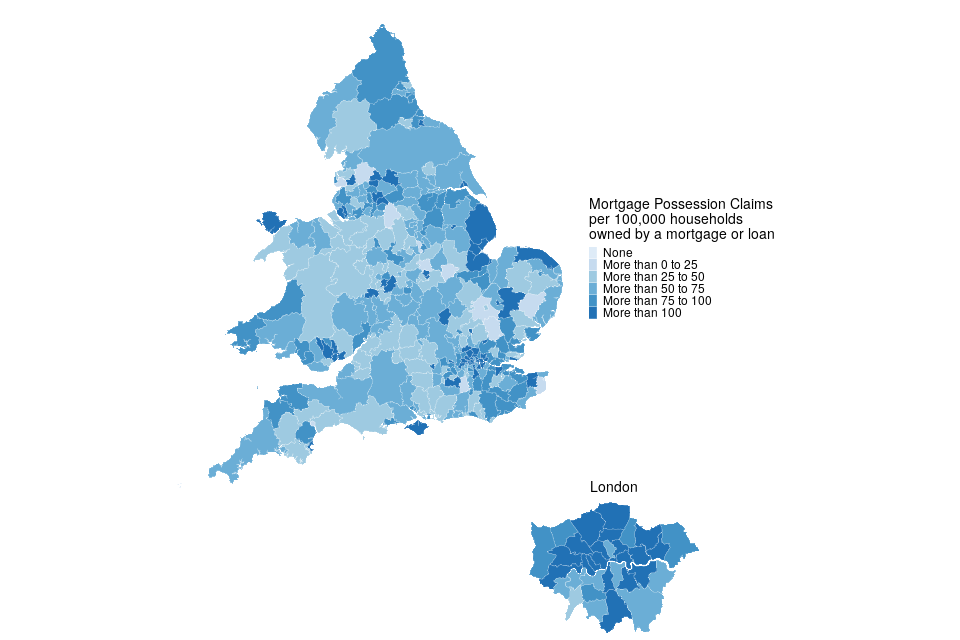
| Local Authority | Rate (per 100,000 households owned by a mortgage or loan) | Actual number |
|---|---|---|
| Westminster | 344 | 37 |
| City of London | 294 | <10 |
| Greenwich | 197 | 56 |
London boroughs accounted for 8 of the 10 local authorities with the highest rate of mortgage claims. Westminster, in the London region, had the highest rate of mortgage possession claims at 344 per 100,000 households owned by mortgage or loan, followed by City of London (London region) and Greenwich (London region); with 294 and 197 claims per 100,000 respectively.
One local authority had no mortgage possession claims during this period. Excluding these Fylde had the lowest rate of mortgage claims (9.5 per 100,000 households owned by a mortgage or loan).
Figure 6: Private landlord possession Claims per 100,000 households owned by a private landlord, April to June 2026 (Source: map.csv; see supporting guide)
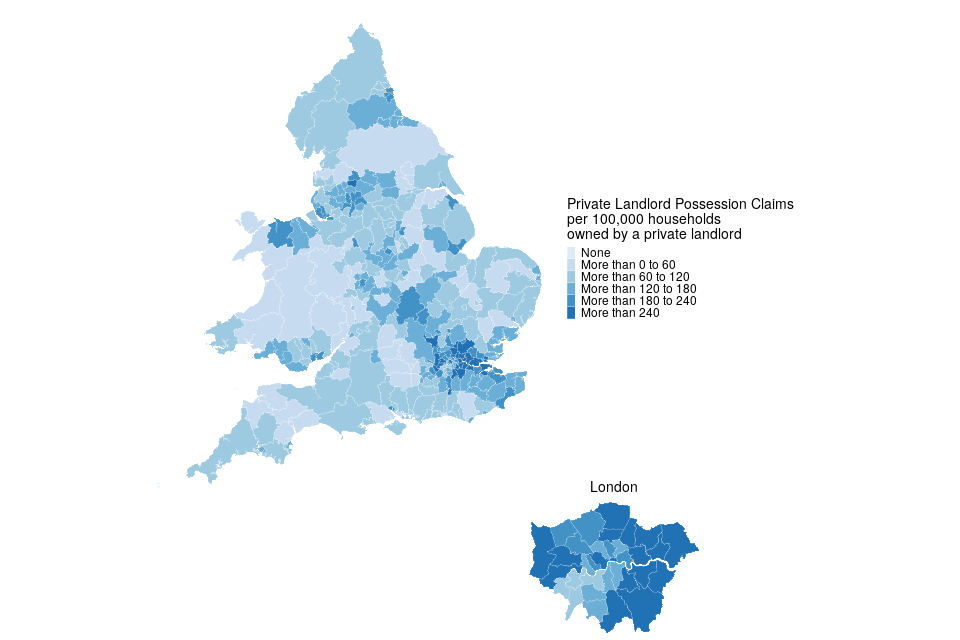
| Local Authority | Rate (per 100,000 households owned by a private landlord) | Actual number |
|---|---|---|
| Enfield | 579 | 205 |
| Barking and Dagenham | 542 | 97 |
| Newham | 481 | 214 |
London boroughs accounted for 8 of the 10 local authorities with the highest rate of private landlord claims. Enfield (London region) had the highest rate for private landlord claims (579 per 100,000 households owned by a private landlord), followed by Barking and Dagenham (London region) and Newham (London region) with 542 and 481 claims per 100,000 households owned by a private landlord respectively.
One local authority had no private landlord claims during this period. Excluding these, Torridge had the lowest rate of private landlord claims (16.3 per 100,000 households owned by a private landlord).
Figure 7: Social landlord possession Claims per 100,000 households owned by a social landlord, April to June 2026 (Source: map.csv; see supporting guide)
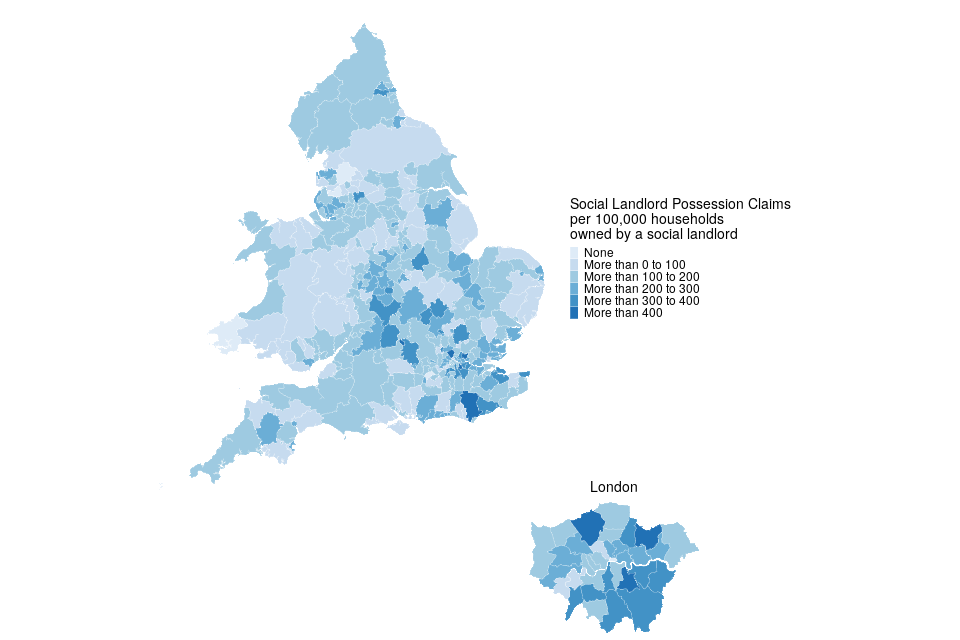
| Local Authority | Rate (per 100,000 households owned by a social landlord) | Actual number |
|---|---|---|
| Lewisham | 453 | 162 |
| Oxford | 441 | 51 |
| Barnet | 419 | 84 |
London boroughs accounted for 5 of the 10 local authorities with the highest rate of social landlord claims. Lewisham (London region) had the highest social landlord possession claim rate with 453 per 100,000 households owned by a social landlord. This was followed by Oxford (South East region) and Barnet (London region) with 441 and 419 per 100,000 households owned by a social landlord respectively.
Six local authorities had no social landlord claims during this period. Excluding these, New Forest had the lowest rate of social landlord claims (12 per 100,000 households owned by a social landlord).
8. Regional Repossessions (by County Court Bailiffs)
Westminster had the highest overall rate of mortgage repossessions at 65 per 100,000 households owned by a mortgage or loan.
Private landlord repossessions were highest in Barking and Dagenham with 352 per 100,000 households owned by a private landlord.
Social landlord repossessions were highest in Reading with 211 per 100,000 households owned by a social landlord.
The Isles of Scilly and the City of London have very small populations (ranked 309th and 308th out of 309 respectively for population size) therefore rates may be less robust.
Figure 8: Mortgage repossessions per 100,000 households owned by a mortgage or loan, April to June 2026 (Source: map.csv; see supporting guide)
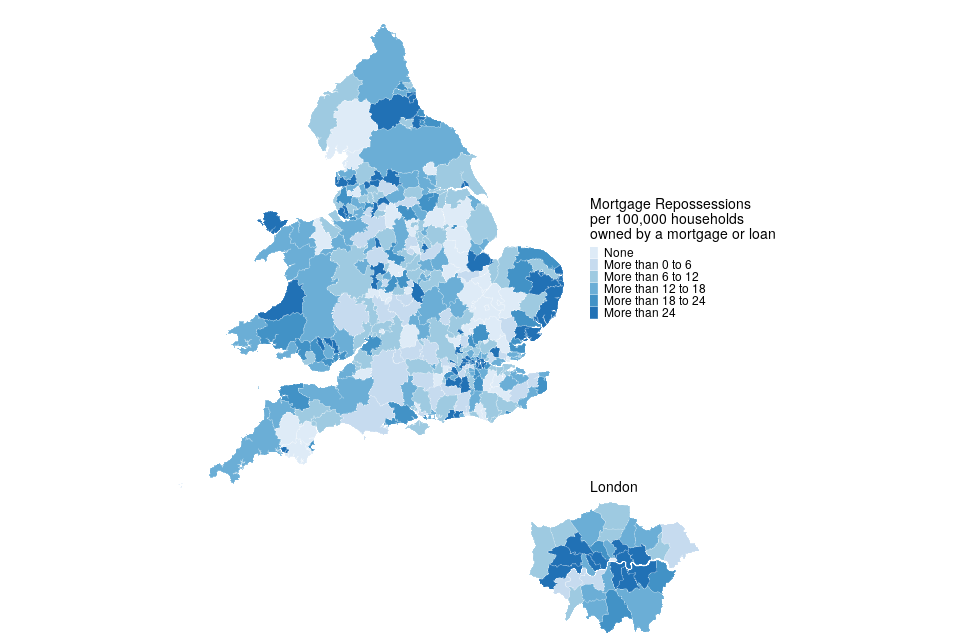
| Local Authority | Rate (per 100,000 households owned by a mortgage or loan) | Actual number |
|---|---|---|
| Westminster | 65 | <10 |
| Merthyr Tydfil | 57 | <10 |
| Slough | 46 | <10 |
Local authorities in London account for 3 of the 10 boroughs with the highest rate of mortgage repossessions.
No repossessions by county court bailiffs were recorded during this period in 47 local authorities out of a total of 318.
Figure 9: Private landlord repossessions per 100,000 households owned by a private landlord, April to June 2026 (Source: map.csv; see supporting guide)
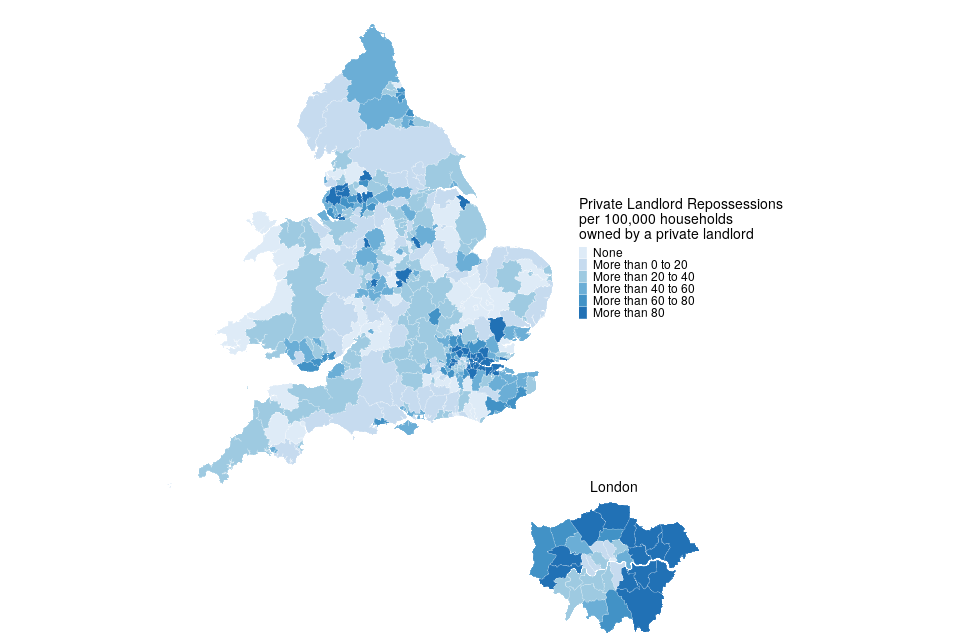
| Local Authority | Rate (per 100,000 households owned by a private landlord) | Actual number |
|---|---|---|
| Barking and Dagenham | 352 | 63 |
| Newham | 225 | 100 |
| Gravesham | 201 | 16 |
London local authorities account for 6 of the 10 boroughs with the highest rate of private landlord repossessions.
47 local authorities had no private landlord repossessions by county court bailiffs in Q2 2026.
Figure 10: Social landlord repossessions per 100,000 households owned by a social landlord, April to June 2026 (Source: map.csv; see supporting guide)
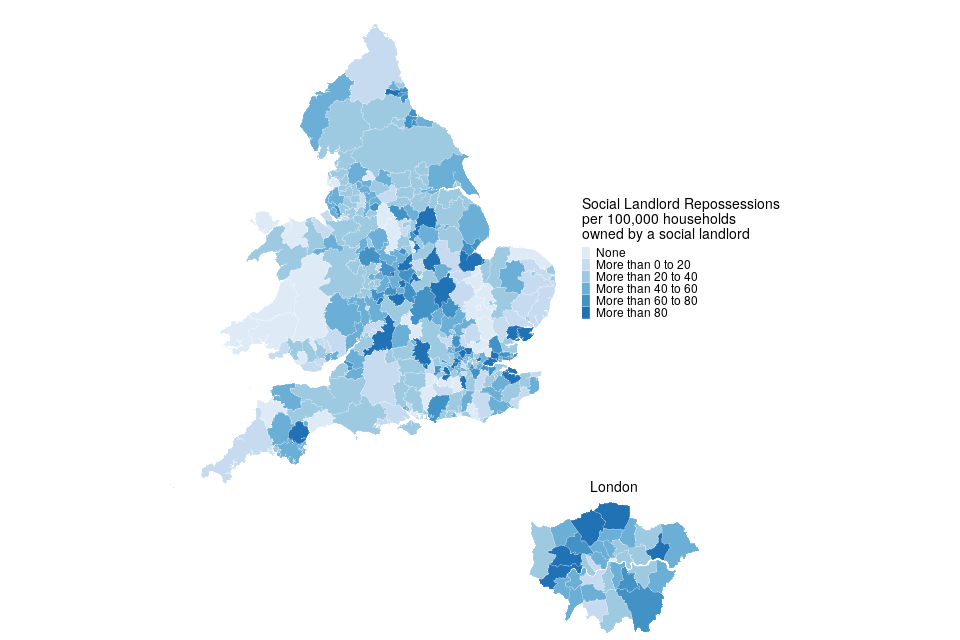
| Local Authority | Rate (per 100,000 households owned by a social landlord) | Actual number |
|---|---|---|
| Reading | 211 | 23 |
| Nuneaton and Bedworth | 184 | 15 |
| South Holland | 142 | <10 |
South East local authorities accounted for 2 of the 10 boroughs with the highest rate of social landlord repossessions.
37 local authorities had no social landlord repossessions by county court bailiffs in Q2 2026.
As with claims, it should be noted that for some of these areas the rates are based on a small number of repossessions.
9. Further information
The statistics in the latest quarter are provisional and revisions may be made when the next edition of this bulletin is published. If revisions are needed in subsequent quarters, these will be annotated in the tables.
9.1 Accompanying files
As well as this bulletin, the following products are published as part of this release:
-
A supporting guide providing further information on how the data is collected and processed, including a guide to the csv files, as well as legislation relevant to mortgage possessions and background information.
-
A set of overview tables (also available in accessible format), covering key sections of this bulletin.
-
CSV files of the map data and the possession action volumes by local authority and county court.
-
A data visualisation tool which provides a detailed view of the Mortgage and Landlord statistics. We welcome feedback on this tool to help improve it in later editions and to ensure it meets user needs.
These can be found here: https://www.gov.uk/government/statistics/mortgage-and-landlord-possession-statistics-april-to-june-2026
9.2 National Statistics status
National Statistics are accredited official statistics (https://osr.statisticsauthority.gov.uk/accredited-official-statistics/) that meet the highest standards of trustworthiness, quality and public value.
Accredited official statistics are called National Statistics in the Statistics and Registration Service Act 2007. These accredited official statistics were independently reviewed by the Office for Statistics Regulation in September 2021. They comply with the standards of trustworthiness, quality and value in the Code of Practice for Statistics and should be labelled ‘accredited official statistics’.
It is the Ministry of Justice’s responsibility to maintain compliance with the standards expected for National Statistics. If we become concerned about whether these statistics are still meeting the appropriate standards, we will discuss any concerns with the Authority promptly. National Statistics status can be removed at any point when the highest standards are not maintained, and reinstated when the standards are restored. These statistics have been audited and re-accredited as National Statistics. The most recent compliance check completed by the Office of Statistics Regulation can be found here.
9.3 Future publications
Our statisticians regularly review the content of publications. Development of new and improved statistical outputs is usually dependent on reallocating existing resources. As part of our continual review and prioritisation, we welcome user feedback on existing outputs including content, breadth, frequency and methodology. Please send any comments you have on this publication including suggestions for further developments or reductions in content.
9.4 Contact
Press enquiries should be directed to the Ministry of Housing, Communities and Local Government press office:
email: newsdesk@communities.gov.uk
Other enquiries and feedback on these statistics should be directed to the Courts and People unit of the Ministry of Justice:
Leanne Crew - email: CAJS@justice.gov.uk
Next update: 12 November 2026
© Crown Copyright
Produced by the Ministry of Justice
-
These regions are based on the court that handled the possession claim not the region of the defendant postcode. ↩
-
Please note rates for private and social landlord possession claims and repossessions do not include accelerated claims. This is because accelerated claims are recorded onto the case management system at point of entry so do not specify the tenure type. ↩
-
Tenure - Office for National Statistics ons.gov.uk. ↩