MOD supported employment estimates 2024/25
Published 20 August 2026
© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/statistics/mod-supported-employment-estimates-202425/mod-supported-employment-estimates-202425
The Finance and Economics Statistical Bulletin series provides figures on the composition and scope of the Department’s expenditure, information on the impact of defence spending on the wider economy, and compares Ministry of Defence (MOD) spending to that of other departments and countries.
This publication presents the number of direct and indirect jobs supported by MOD in 2024/25 by UK region and industry group. Statistics on MOD expenditure are published separately, please find them in the MOD Regional Expenditure with Industry bulletin.
Note: Revision
Revisions have been made across multiple years in the time series due to changes in underlying data on MOD expenditure, UK employment, and Input-Output Analytical Tables (IOATs) from which job estimates are calculated.
The combined effects have revised total UK direct jobs by up to 2% fewer in 2021/22 to 2023/24, and indirect jobs by up to 17% fewer in 2022/23 and 2023/24.
Therefore, the time series presented in this release should be used over any previous editions where figures will differ. The cause of these changes to the underlying data are discussed further within the Accuracy section below.
1. Key Points
| 274,000 | Total number of direct and indirect jobs supported through MOD expenditure with UK industry. |
| This is comprised of 164,000 direct jobs and 110,000 indirect jobs, up from a combined total of 248,000r in 2023/24. | |
| 1 in 100 | Proportion of all direct and indirect jobs in the UK which are supported as a result of MOD expenditure with UK industry. |
| This is an increase from the 1 in 110r in the previous year. | |
| 462,000 | The total number of UK jobs supported when combining jobs supported in industry with MOD civilian and UK Regular Armed Forces personnel based in the UK. |
| The equivalent of 1 in every 60 UK jobs. | |
| 53% | The rise in the number of direct jobs per 100,000 people in FTE employment supported by MOD expenditure in Yorkshire and The Humber compared to the previous year. |
| This equates to 260 direct jobs per 100,000 people in FTE employment. | |
| 5,900 | Total number of direct jobs supported by MOD expenditure in the Weapons and Ammunition industry. |
| This accounts for an additional 2,000 jobs compared with the previous year. This increase is largely as a result of a 344 million increase in spending in this sector from the previous year, when accounting for inflation. Note that that the Weapons and Ammunition industry group includes the manufacture of weapons, ammunition and military fighting vehicles. | |
| 32,800 | Total number of industry wide indirect jobs supported as a result of MOD direct expenditure on Shipbuilding and Repairing. |
| MOD direct expenditure on Shipbuilding and Repairing supported more indirect jobs than any other single industry. |
Responsible statistician: Analysis-Expenditure Head of Branch
Telephone: 0303 378 6554
Further information/mailing list: Analysis-Expenditure-PQ-FOI@mod.gov.uk
Background quality report: Background Quality Report
Would you like to be added to our contact list, so that we can inform you about updates to these statistics and consult you if we are thinking of making changes? You can subscribe to updates by emailing Analysis-Publications@mod.gov.uk.
2. Introduction
This publication provides estimates on the number of direct and indirect full-time equivalent (FTE) jobs supported in the UK by MOD expenditure. Tables and figures present statistics for the most recent financial year and comparisons will be made in the narrative to previous financial years where appropriate. Detailed statistics can be found in the supporting data tables.
The number of direct and indirect jobs are estimated using MOD regional expenditure data, external data such as employment and turnover data from the Business Register and Employment Survey (BRES) and the Annual Business Survey (ABS), and additional supply and use data from the Office for National Statistics (ONS).
Direct jobs will be presented in the following ways:
-
by International Territorial Level (ITL) 1 regions (for clarity these will be referred to as regions in text).
-
as the number of FTE jobs supported for every 100,000 people in FTE employment in each region. This measure considers the employment levels of each region and will make these figures more directly comparable.
-
by industry group.
Indirect jobs will be presented by industry group only. No reliable regional split can currently be given as there are no regional Input-Output Analytical Tables available from the Office for National Statistics (ONS) from which these estimates are derived. The limitations of this are discussed further in the Methodology and Background Quality Report.
2.1 Context
Estimates on direct and indirect jobs have been produced in recent years within the MOD supported employment estimates bulletin series. Direct jobs are the jobs supported within companies receiving payments for goods and services directly from MOD. Indirect jobs are those that occur further down the supply chain through sub-contracting or via suppliers to the direct contractor.
Prior to this, estimated jobs figures were published as part of the UK Defence Statistics (UKDS) publication and included both direct and indirect jobs. This was followed by the MOD Regional Expenditure with UK Industry and Supported Employment bulletin which was ceased after the 2021/22 release.
2.2 Comparisons over time: overall
Jobs statistics are derived from MOD expenditure estimates which are based on MOD contract information and display natural variability. Thus, we would expect total jobs to fluctuate year-on-year due to yearly variations in total expenditure with large value contracts starting and ending across different financial years or large one-off payments occurring. MOD Direct Expenditure figures published up until 2009 in UK Defence Statistics showed a similar amount of variation between years to the figures presented in the rest of this bulletin.
2.3 Comparisons over time: by region and industry group
Contract payment data can fluctuate naturally across years due to occurrences of large payments and therefore, comparison of longer term trends in jobs estimates which are derived from MOD contract information is preferential to year-on-year comparisons which should be used with caution.
2.4 Comparisons over time: to other published statistics
Please note that these statistics are broadly similar to estimates published in UK Defence Statistics, but should not be directly compared due to methodological differences. Since estimates of employment were previously produced, output per FTE has increased across most industries. Output per FTE is calculated as an industry’s total output divided by its number of FTE employees and can be used as an indicator of how much output is generated for each FTE employee in the industry.
If MOD expenditure in an industry remains the same and output per FTE employee increases, then we see greater productivity per FTE employee and witness a reduction in the number of jobs estimated. This is of particular relevance in industries where MOD expenditure is high such as Shipbuilding and Aircraft manufacturing and repair. In addition, earlier estimates also included expenditure and jobs supported as a result of exports.
ADS (a trade organisation for Aerospace, Defence and Security) publish annual estimates of the number of direct jobs supported in the Defence Sector in their annual Industry Facts and Figures publication. ADS estimates are based on a specific definition of what constitutes the defence sector and also include estimated employment as a result of defence exports. In contrast, the estimates produced in this publication are based on all MOD expenditure with industry and include elements of spending that wouldn’t necessarily be considered as ‘defence’, such as financial services, so the two estimates are not directly comparable.
The Joint Economic Data Hub (JEDHub), based in the UK Defence Solutions Centre (UKDSC), is a collaborative initiative to improve understanding of the defence sector’s contribution to the UK economy. UKDSC has worked with MOD, other government departments (OGDs), Defence Growth Partnership (DGP) companies, trade bodies and academics to develop the JEDHub. A key part of this work has been collecting and aggregating data from defence companies through an annual survey.
The JEDHub Annual Economic Report is published annually, it includes estimates of turnover and employment in the defence sector. Employment data in the report was based on companies responding to the JEDHub survey. This data is not directly comparable to the MOD estimates, due to it just being based on survey responses from specific companies and the survey using a specific definition of the defence sector rather than including all elements of MOD spending with industry.
2.5 Accuracy
Several assumptions have been made during analysis of this data. In addition, revisions have been made across multiple years in the time series due to changes in the underlying data on MOD expenditure, UK employment, and Input-Output Analytical Tables (IOATs) from which job estimates are calculated. Therefore, the time series presented in this release should be used over any previous editions where figures will differ:
-
MOD expenditure - Figures for 2020/21 to 2024/25 have been revised due to a review of location of work codes used to classify expenditure as either UK or overseas. This was to address an issue where six contracts had been incorrectly allocated a location wholly overseas or had defaulted to using supplier headquarter locations instead of known worksites. The revision has uplifted total UK spending across these years by up to 1%. This has further impacted breakdowns by region and industry.
-
UK employment - For 2024/25, BRES data for Northern Ireland is currently unavailable. ABS turnover and BRES employment figures used in the calculation of both direct and indirect jobs are based on Great Britain data only. It is estimated that using ABS and BRES data for Great Britain rather than the United Kingdom data that has been used in previous years has an impact of approximately 1% fewer total industry jobs.
-
UK turnover - In previous bulletins only the 2019 Input-Output Analytical Tables (IOATs) had been used for the years 2019/20 onwards, as this was the most recently available IOAT that had been unaffected by the COVID-19 pandemic. For 2024/25, the more recent 2022 and 2023 IOATs are used. This has a notable effect on the estimation of the indirect jobs for the 2022/23 and 2023/24 years. Growth in the economy has led to increases in turnover and total output. Indirect jobs are calculated by dividing intermediate demand by output at basic prices per FTE. As the output at basic prices per FTE is now greater for 2022/23 and 2023/24 the MOD’s spend with industry now represents a smaller proportion of this overall figure, which in turn has led to the total estimated indirect jobs being lower. The effect of using these updated IOATs is that indirect jobs have been revised by up to 17% fewer in 2022/23 and 2023/24.
For further information on these, and for more detailed explanations of the applications and limitations of this data, please refer to the Background Quality Report.
Official Statistics publication
Our statistical practice is regulated by the Office for Statistics Regulation (OSR). OSR sets the standards of trustworthiness, quality and value in the Code of Practice for Statistics that all producers of official statistics should adhere to.
You are welcome to contact us directly with any comments about how we meet these standards. Please contact us at Analysis-Publications@mod.gov.uk. Alternatively, you can contact OSR by emailing regulation@statistics.gov.uk or via the OSR website.
3. Direct and Indirect Jobs Supported by MOD Expenditure with UK Industry
This section outlines the number of direct and indirect jobs supported by MOD expenditure with UK industry. Both direct and indirect jobs are presented by financial year and direct jobs are presented by region. Only direct jobs can be presented by region as the underlying data does not support this breakdown for indirect jobs. This section does not include jobs supported by MOD direct public sector employment such as civilian personnel employed by the MOD or those serving in the armed forces.
The total number of jobs supported by MOD expenditure with industry in 2024/25 has increased by 26,000 to 274,000.
Full-Time Equivalent employment
Full-time equivalent (FTE) employment is a figure that allows part-time workers’ hours to be put into the same units as full-time workers. This publication often uses the term jobs to mean full-time equivalent employment.
UK turnover per Full-Time Equivalent employment
This shows how much money an industry takes for each person in FTE employment. It therefore allows us to estimate the number of jobs supported by MOD expenditure by dividing expenditure with UK industry by turnover per FTE employment for that industry.
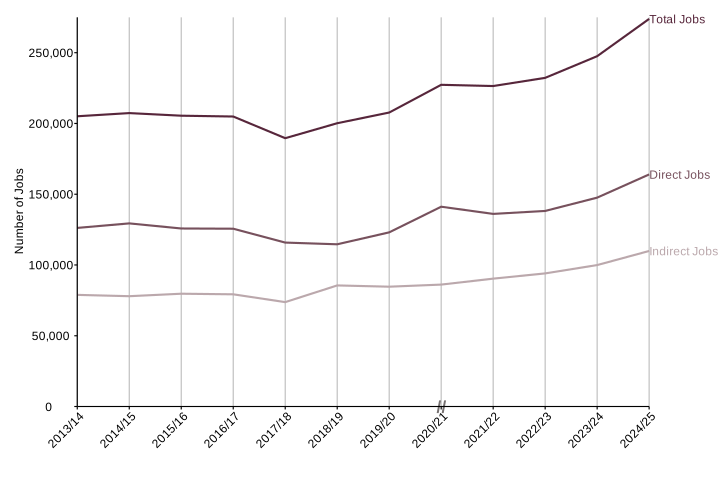
The estimated 274,000 FTE jobs supported by MOD expenditure is the equivalent to 1 in every 100 jobs. This figure includes both direct and indirect jobs so accounts for employment through direct supplier payments as well as jobs arising through the supply chain. The increase in total jobs in 2024/25 was driven by an increase of 16,000 in the number of direct jobs and an increase of 10,000 in the number of indirect jobs, as a result of increased MOD direct expenditure with industry and greater supply chain demand.
Total direct MOD expenditure with UK industry and commerce in 2024/25 was £31.9 billion, an increase of 6% from 2023/24 when accounting for inflation. Supported job estimates are derived from expenditure data and the increase in expenditure data is reflected by an 11% increase in direct jobs and a 10% increase in indirect jobs. Please note that a given expenditure percentage increase in a certain industry may not necessarily equate to an equal percentage increase in the number of jobs in that industry due to factors such as the type of spending, potential inefficiencies in spending and the overall economic climate at the time.
Figure 1: Direct and Indirect Jobs Supported by MOD Expenditure with Industry from 2013/14 to 2024/25[footnote 1]
Source: Analysis Directorate (MOD), ONS Input-Output Tables, ONS Supply-Use Tables, BRES employment figures and ABS turnover figures
Figure 1 shows a line graph of jobs supported by Defence expenditure with UK industry over time since 2013/14. The total number of jobs reached 274,000 in 2024/25, an increase of 11% when compared to the previous financial year.
Direct jobs have increased by over 32% in London, making it the first time since 2020/21 where direct jobs in this region have exceeded 10,000 FTE employees.
West Midlands was the only region where the number of direct jobs decreased, reducing from 8,100r to 7,900 due to a 12%r decrease in Technical, Financial and Other Business Services industry jobs in this region. Spend in the West Midlands in this industry had stayed consistent and hereby the drop is a result of higher turnover per full-time equivalent (FTE) employment in 2024/25.
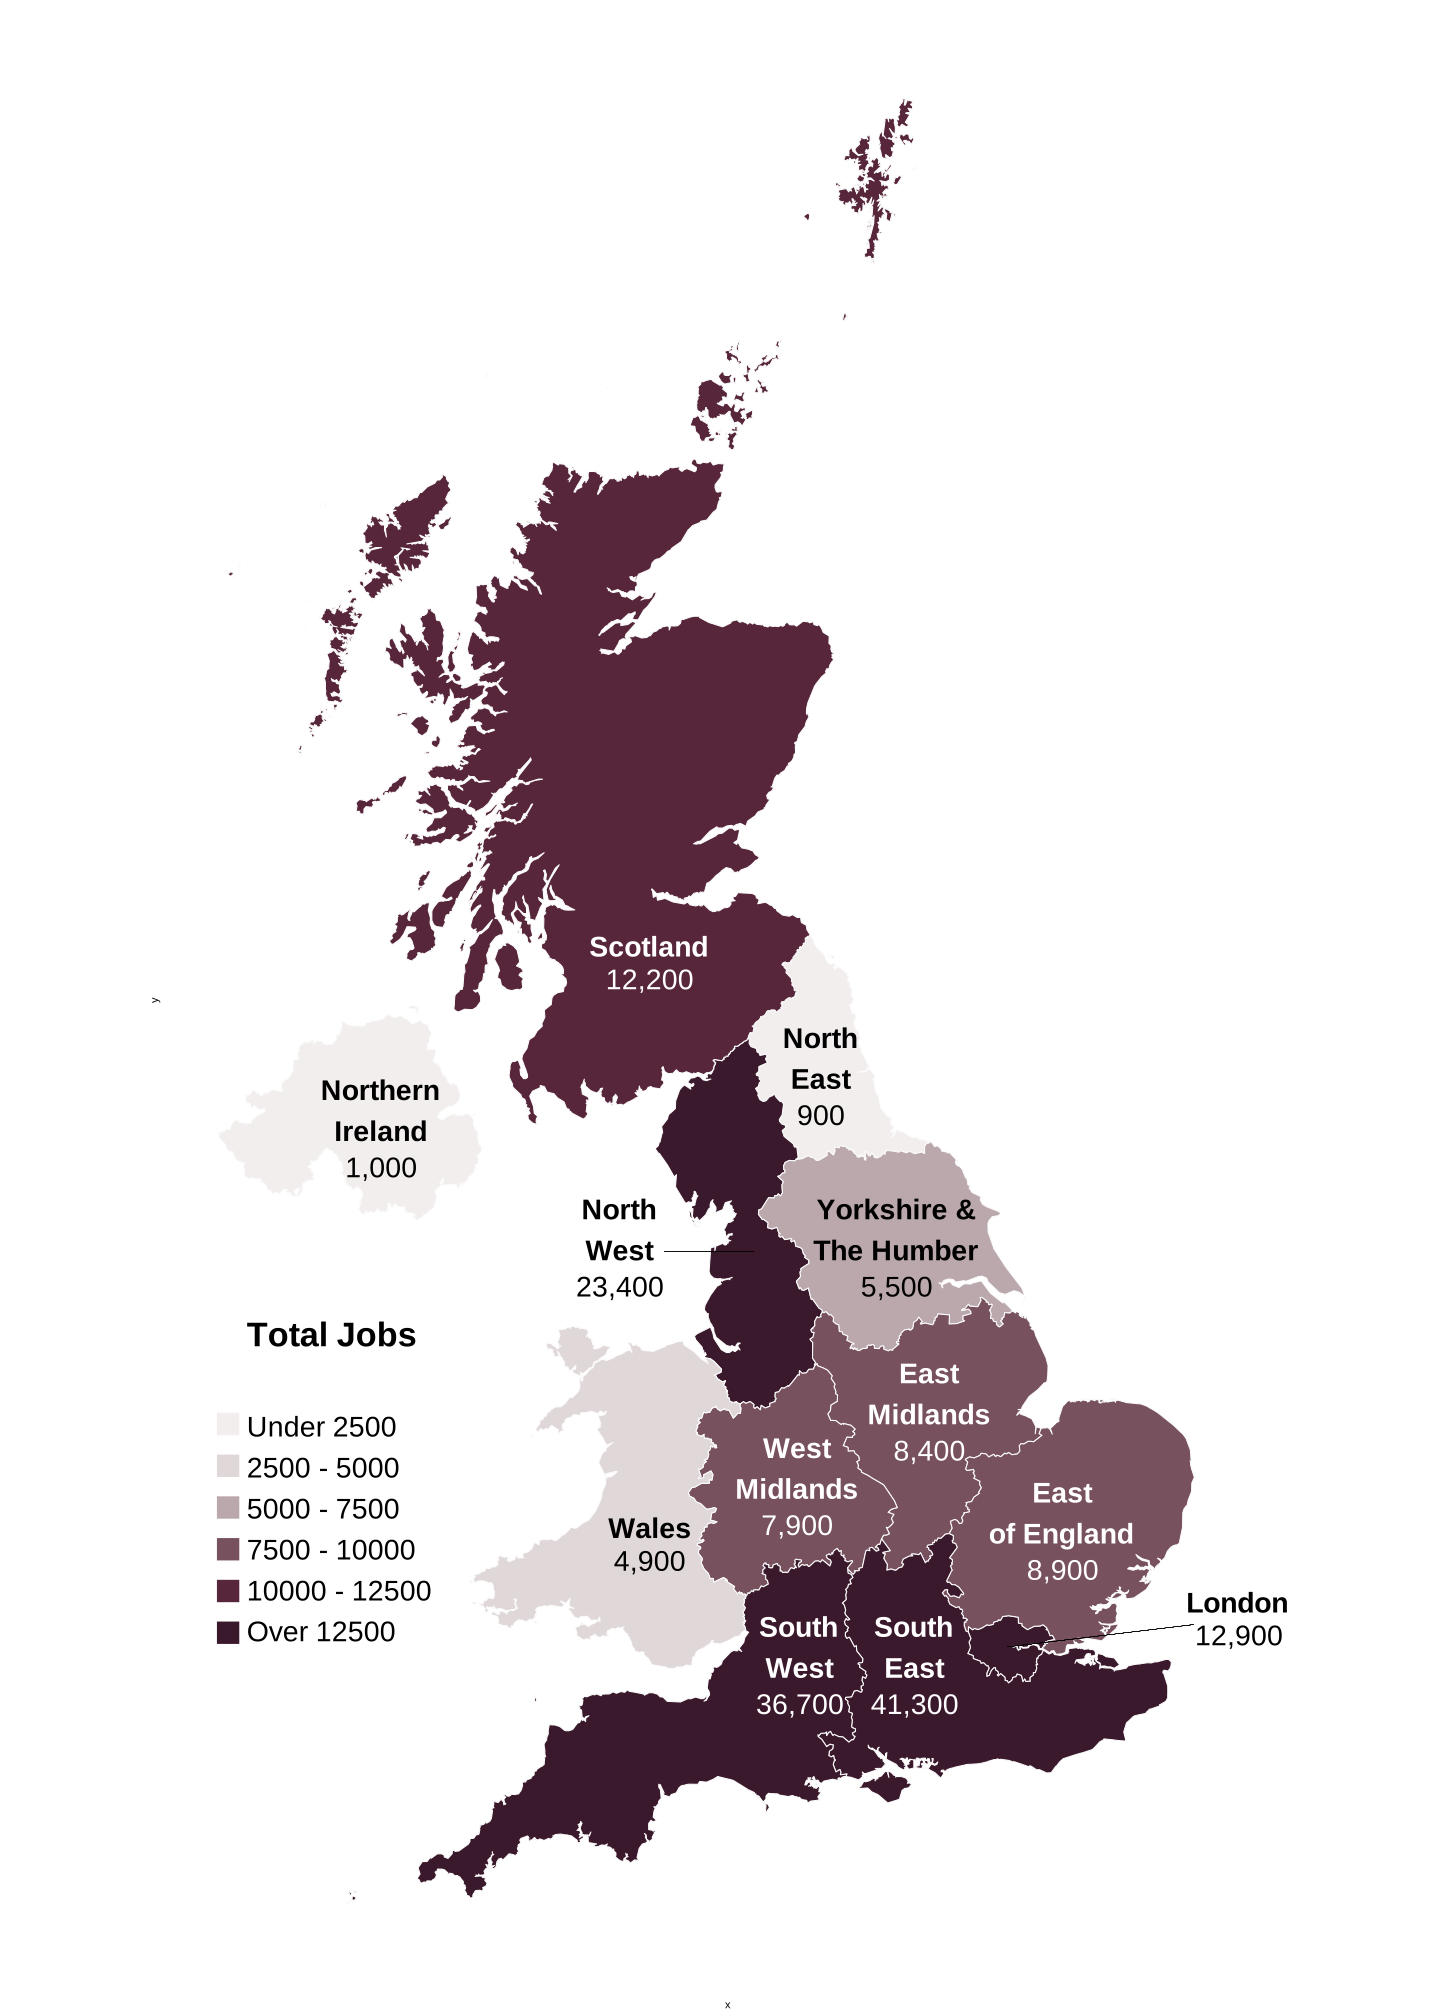
Figure 2: Total Number of Direct Jobs Supported by MOD Expenditure with Industry by Region 2024/25
Source: Analysis Directorate (MOD), BRES employment figures and ABS turnover figures.
Figure 2 shows a heat map of the number of direct jobs supported by MOD expenditure with UK industry by region in 2024/25. The region with the highest number of direct jobs was the South East (41,300).
4. Total MOD Supported Jobs: Industry, Civilian and Military Jobs
This section outlines the total number of jobs supported by the MOD over the years and by region, through direct and indirect expenditure with industry as well as direct public sector employment.
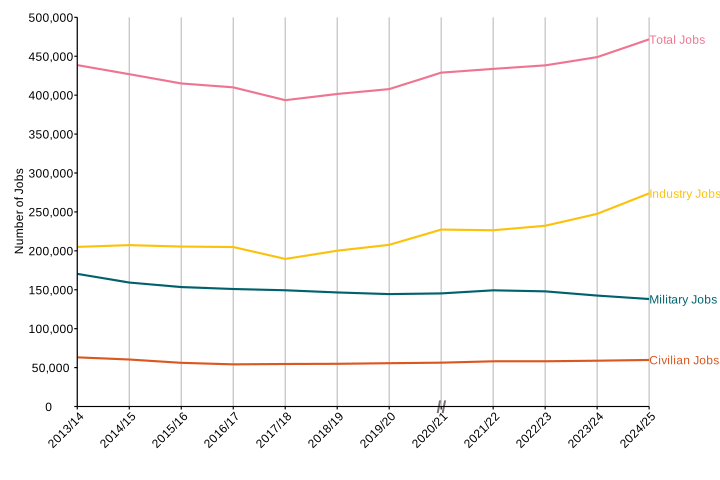
Total number of MOD supported UK jobs (including direct, indirect, civilian and military jobs) in 2024/25 has increased by 23,000 to 462,000.
Figures published by the MOD show that in April 2024 the MOD employed 60,000 civilian personnel and 138,000 service personnel, of which 55,000 civilians and 132,000 service personnel were based in the UK. This shows that through direct expenditure, indirect expenditure, and direct public sector employment the MOD supported 462,000 jobs in the UK in 2024/25. This is equivalent to 1 in every 60 jobs.
Figure 3: Total MOD Supported Jobs from 2013/14 to 2024/25[footnote 1]
Source: Analysis Directorate (MOD), ONS Input-Output Tables, ONS Supply-Use Tables, ABS turnover figures, BRES employment figures and Annual Location Statistics.
Figure 3 shows a line graph showing number of jobs supported by MOD through both expenditure with industry and direct public sector employment since 2013/14. The total number of UK jobs reached 462,000 in 2024/25, an increase of 5% when compared to the previous financial year.
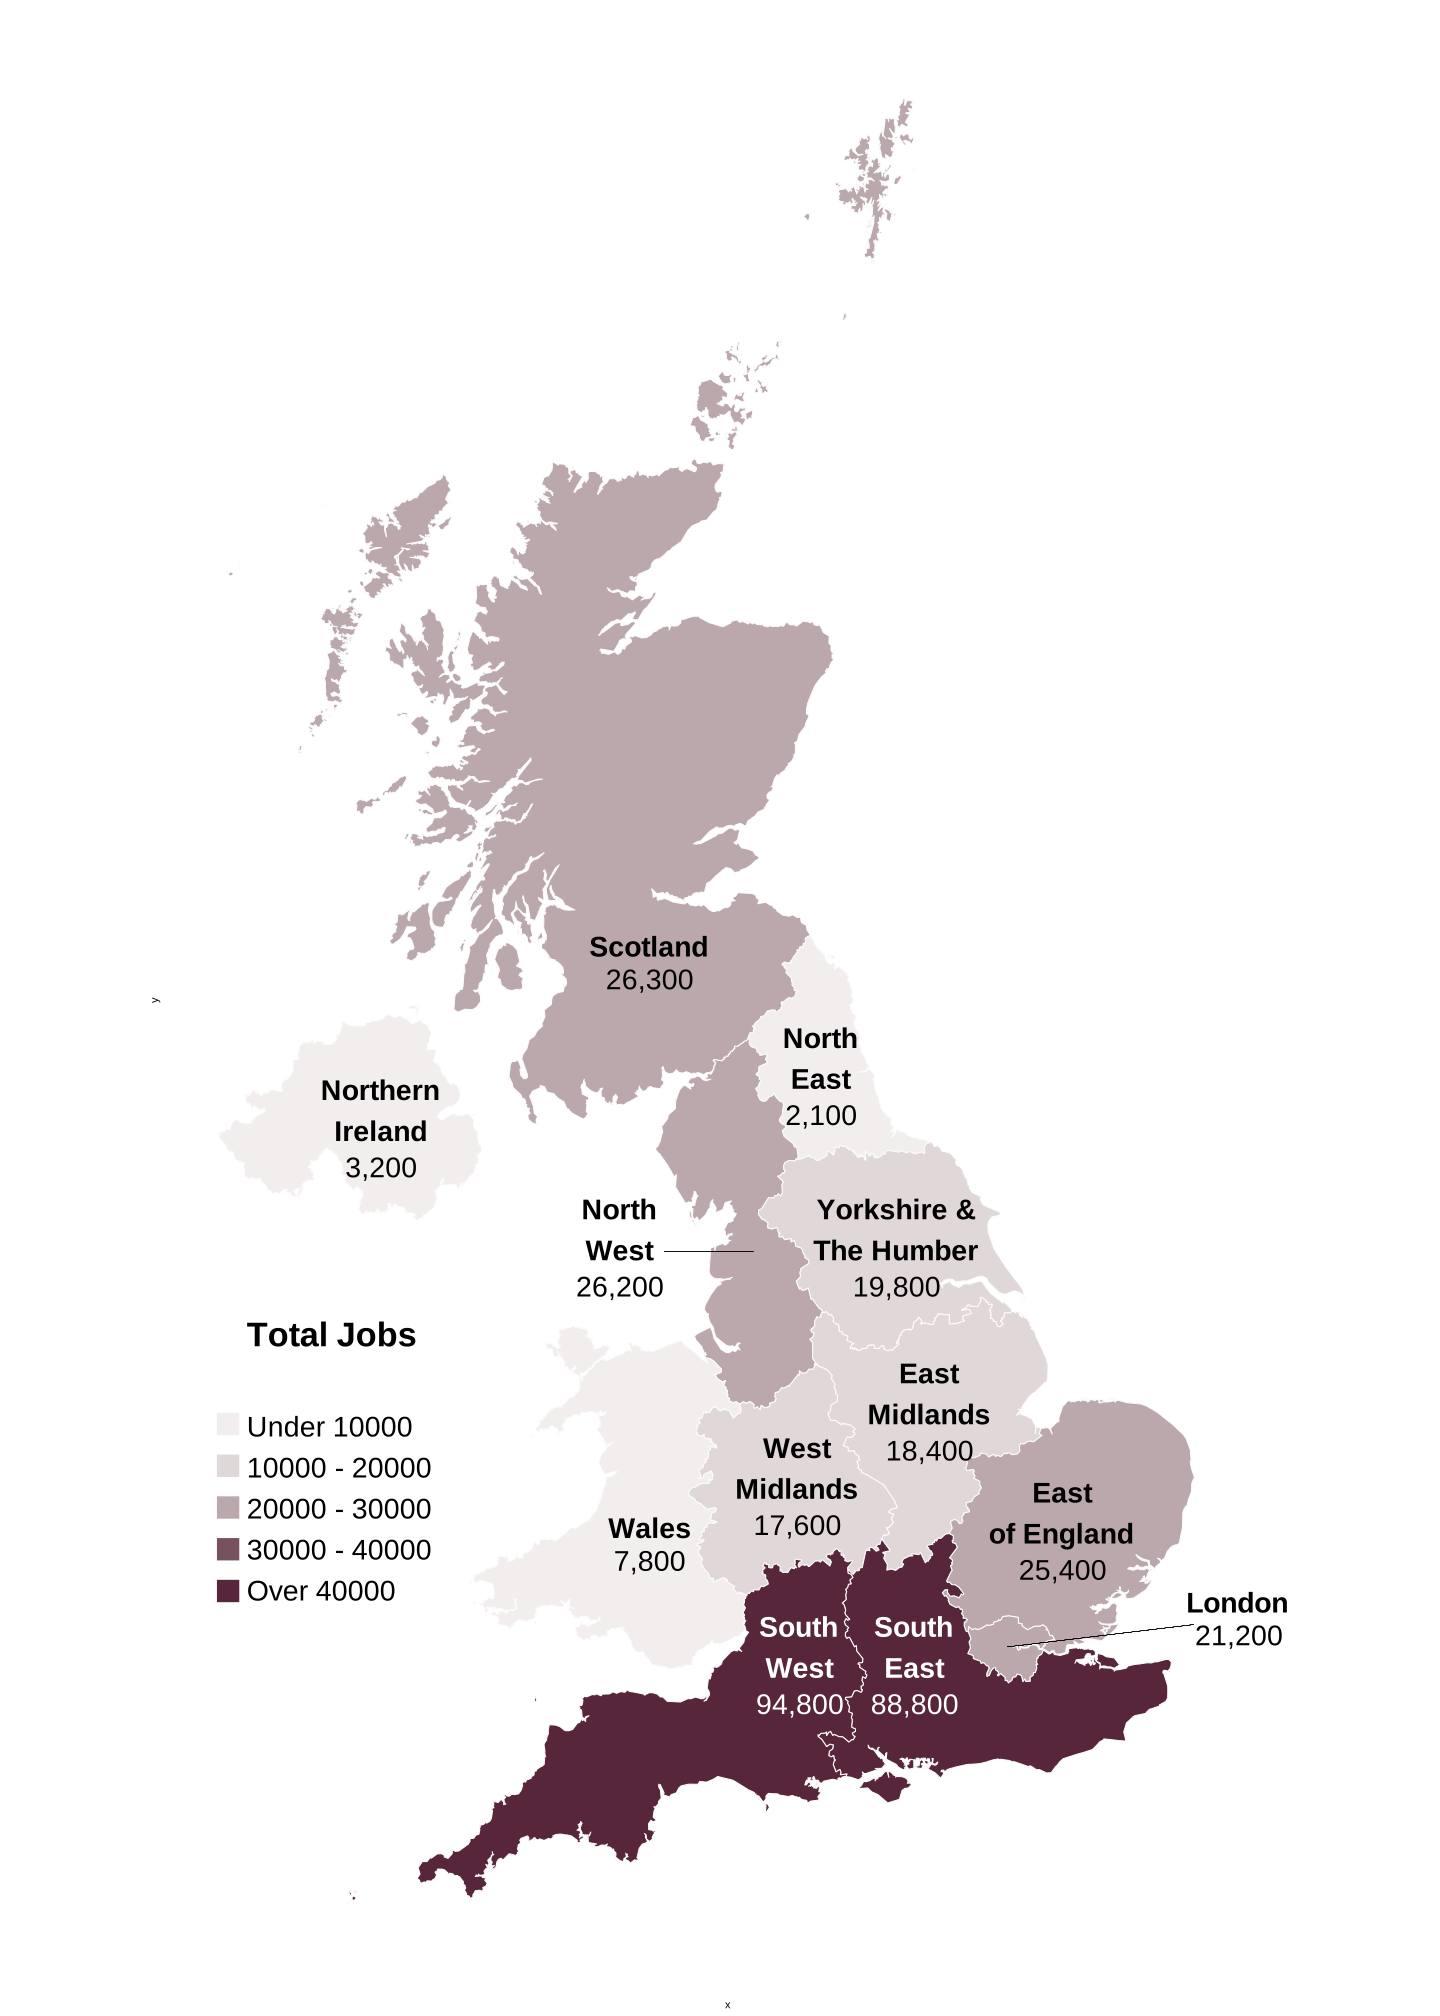
The total number of MOD supported jobs in 2024/25 can be further broken down by region, as shown in Figure 4. It excludes indirect jobs with industry as regional data is not available.
Figure 4: Total MOD Supported Direct, Civilian and Military Jobs by Region 2024/25
Source: Analysis Directorate (MOD), ONS Input-Output Tables, ONS Supply-Use Tables, ABS turnover figures, BRES employment figures and Annual Location Statistics
Figure 4 shows a heat map of the combined total of direct, civilian and military jobs supported by MOD by region. The region with the highest number of jobs in 2024/25 was the South West (94,800).
52% of MOD employment was in the South of England in 2024/25, which is a slight decrease from 54%r in 2023/24. This high concentration of employment is primarily because the headquarters of all three branches of the armed forces are located in the South East (Andover, Portsmouth and High Wycombe) and a high number of civilian jobs in the South West, due to significant MOD sites such as Bristol’s Abbey Wood.
Scotland has remained the region with the third most MOD supported direct, civilian and military jobs in 2024/25 although the difference between Scotland and the next highest region, the North West, is now only 100 jobs.
The North East has remained the region with the lowest number of MOD supported jobs with half of the region’s 2,100 jobs being armed forces personnel.
5. Direct Jobs per 100,000 FTE Employment Supported by MOD Expenditure with UK Industry by Region
This section outlines the number of direct jobs supported by MOD expenditure with UK industry for every 100,000 people in FTE employment by region. Only direct jobs can be presented by region as the underlying data does not support this breakdown for indirect jobs.
MOD expenditure in 2024/25 supported 590 direct jobs per 100,000 FTE employment in the UK which is up from 540r jobs per 100,000 in the previous financial year.
Jobs per 100,000 FTE Employment
To compare the number of jobs supported by MOD expenditure across regions we have calculated jobs supported per 100,000 people in full-time equivalent (FTE) employment in each region. This adjusts the figures for the population and employment levels of the regions.
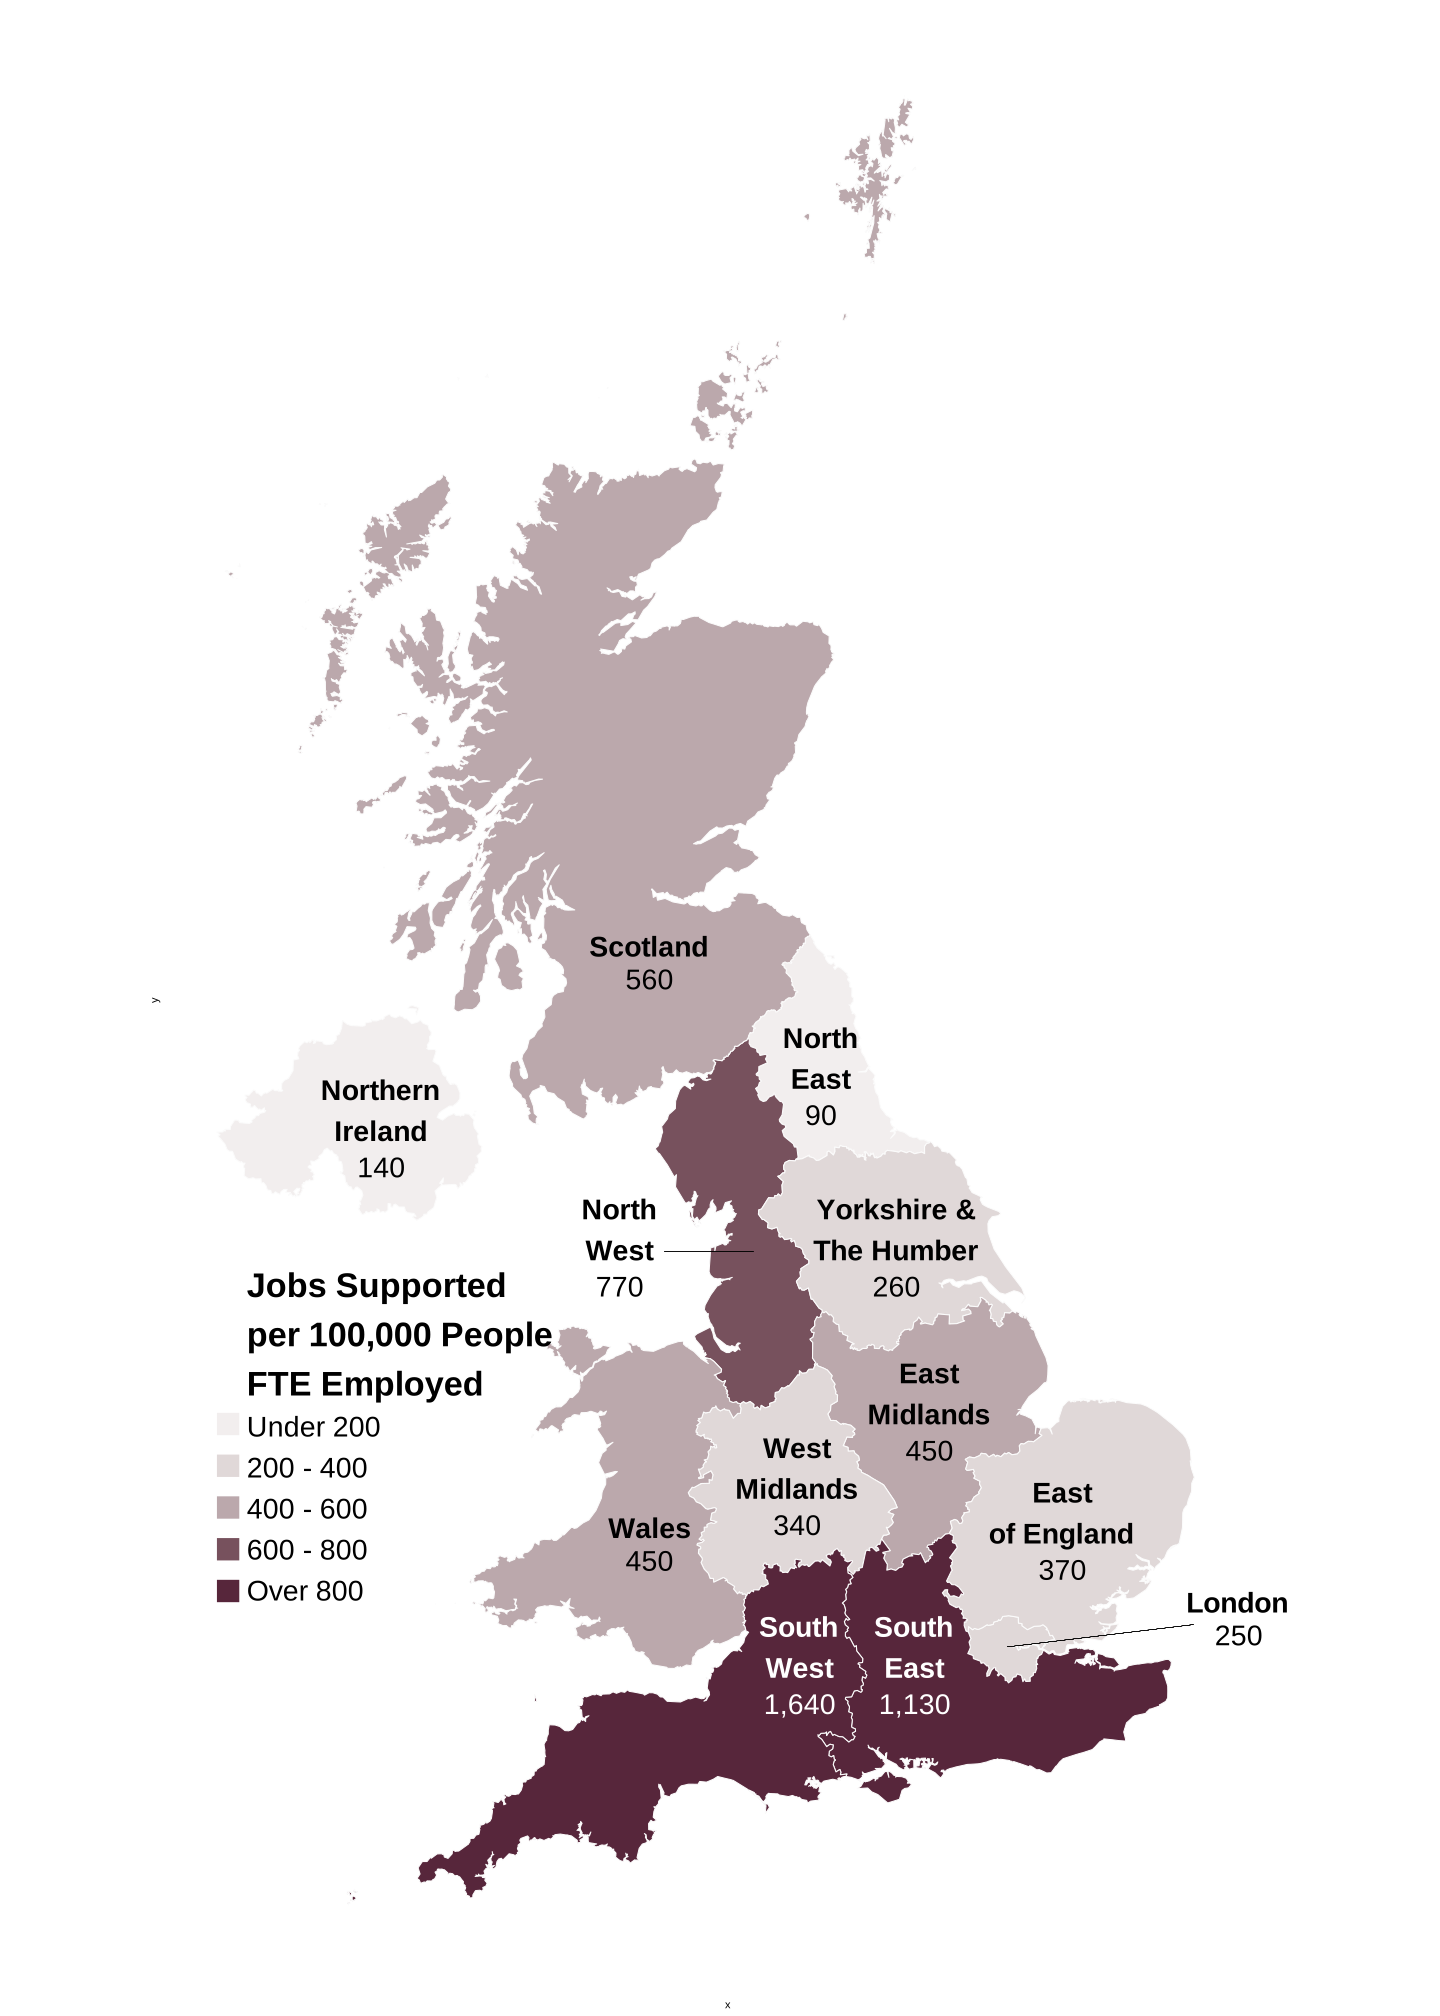
Figure 5: Number of Direct Jobs Supported Through MOD Expenditure for Every 100,000 People in FTE Employment by Region 2024/25
Source: Analysis Directorate (MOD), ONS Mid-Year Population Estimates, ABS turnover figures and BRES employment figures
Figure 5 shows a heat map of the number of direct jobs supported by MOD expenditure with UK industry in 2024/25, for every 100,000 people in FTE employment by region. The regions with the highest number of direct jobs per 100,000 FTE employment were the South West (1,640) and the South East (1,130).
The South West tops the number of direct jobs per 100,000 FTE and has done so every year since data was first compiled in 2013/14, though the number for 2024/25 is unchanged on last year. The East of England (370), East Midlands (450), North West (770) and Yorkshire and The Humber (260) all had their highest figure since 2013/14.
The largest change in direct jobs per 100,000 people in FTE employment was observed in Yorkshire and The Humber, with a 53% increase.
Direct jobs per 100,000 people in FTE employment increased by 25% in London, up to 250 per 100,000 people in FTE employment, and by 29% in Wales, up to 450 per 100,000 people in FTE employment.
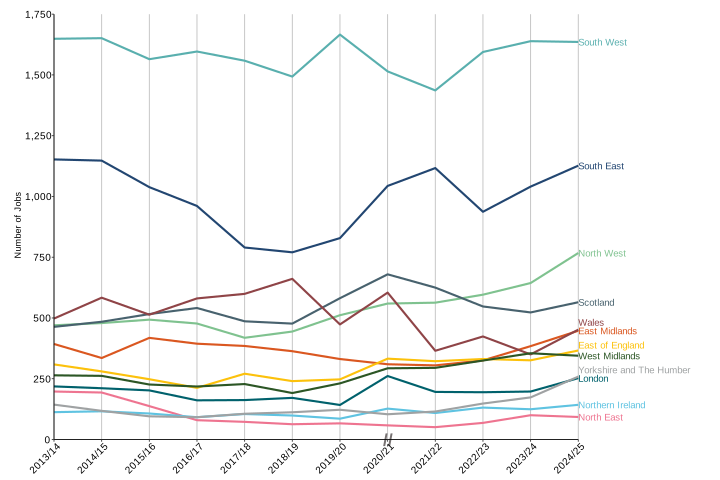
Figure 6: Number of Direct Jobs Supported Through MOD Expenditure for Every 100,000 People in FTE Employment by Region 2013/14 to 2024/25[footnote 1]
Source: Analysis Directorate (MOD), ONS Mid-Year Population Estimates, ABS turnover figures and BRES employment figures
Figure 6 shows a line graph showing the number of direct jobs per 100,000 people in FTE employment supported by Defence expenditure by region since 2013/14. The highest change in the number of jobs in 2024/25 compared to the previous financial year was observed in Yorkshire and The Humber (a 53% increase).
The North West has seen the largest absolute increase in direct jobs per 100,000 FTE when compared with the previous year, increasing from 640r to 770 FTE jobs per 100,000, and is the third successive year the region has seen increases in the number of direct jobs per 100,000 FTE.
The number of direct jobs in the North East remained unchanged between 2023/24 and 2024/25. However, a rise in employed individuals within the region over this same period means that MOD now supports fewer jobs per 100,000. This has caused the North East to see a drop from 100r to 90 FTE jobs per 100,000.
6. Direct Jobs Supported by MOD Expenditure with UK Industry by Industry Group
This section outlines the number of direct jobs supported by MOD expenditure with UK industry broken down by industry group.
Direct jobs supported in the Weapons and Ammunition industry increased to 5,900 in 2024/25.
Using Standard Industrial Classification (SIC) codes we can estimate how many direct jobs are supported in each industry group by dividing MOD expenditure in each group by turnover per FTE employment.
The Weapons and Ammunition SIC group includes the manufacture of weapons, ammunition and military fighting vehicles.
The Technical, Financial and Other Business Services sector remains in top position with 63,300 direct jobs supported in 2024/25, this is largely unchanged from the 62,900r direct jobs supported last year. Given the large difference in the number of jobs between this sector and the other sectors, only defence-specific industry groups are presented in the figure below to ensure changing trends in those groups are clearly visible.
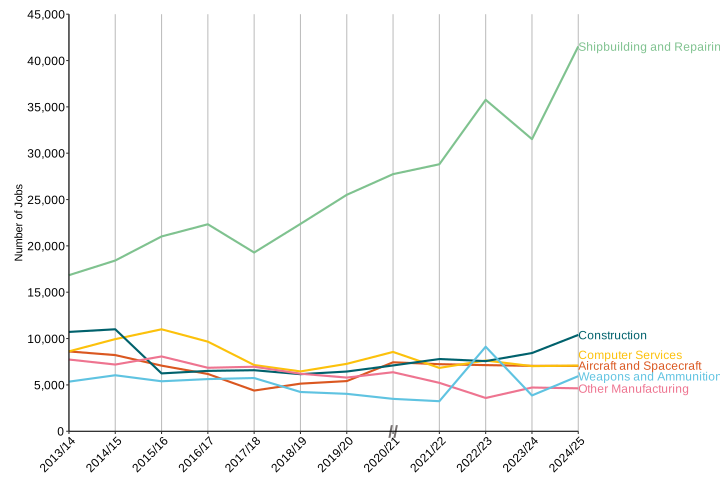
The Weapons and Ammunition industry saw the largest percentage increase (51%) in direct jobs supported by MOD expenditure from the previous year, increasing from 3,900 in 2023/24 to 5,900 in 2024/25. This is because of a 21% increase in expenditure in this sector when accounting for inflation, the largest increase in spending in any sector this year. This can be attributed to a £200 million increase in payments to OCCAR this year for the BOXER project.
The largest absolute increase of direct jobs was in the Shipbuilding and Repairing industry, increasing from 31,500r to 41,500 between 2023/24 and 2024/25. This was due to nominal regional increases of over 1,500r direct jobs in this industry in each of the East Midlands, London, North West and the South West. This increase was primarily due to contracts for the design and production of three Fleet Solid Support (FSS) vessels for the Royal Fleet Auxiliary (RFA) with Navantia as well as contracts for the production of the Dreadnought submarines with BAE Systems.
Figure 7: Number of Direct Jobs Supported Through MOD Expenditure by Defence-Specific Industry Group, 2013/14 to 2024/25[footnote 1]
Source: Analysis Directorate (MOD), ABS turnover figures and BRES employment figures.
Figure 7 shows a line graph showing the number of direct jobs supported by Defence expenditure by industry group since 2013/14. The highest percentage change in the number of jobs in 2024/25 compared to the previous financial year was observed for the Weapons and Ammunition industry.
Note: ‘Other Manufacturing’ excludes Weapons and Ammunition, Electronics, Precision Instruments, Shipbuilding and Repairing, and Aircraft and Spacecraft.
7. Indirect Jobs Supported by MOD Expenditure with UK Industry by Industry Group
This section outlines the number of indirect jobs supported by MOD expenditure with UK industry broken down by industry group.
MOD expenditure on Shipbuilding and Repairing supports the most industry-wide indirect jobs.
Using ONS Input-Output Tables, ONS Supply-Use Tables and known direct MOD expenditure against each industry, we can estimate the indirect effect of MOD expenditure in the supply chain. From the demand on goods and services arising from MOD expenditure, the number of indirect jobs supported in each industry group is estimated by dividing the demand in each group by its respective output per FTE employment.
MOD supported 110,000 indirect jobs through industry expenditure in 2024/25, an increase of 10,000 on the previous year due to greater demand in the supply chain. Indirect jobs make up 40% of total jobs, this has remained constant from 2023/24r.
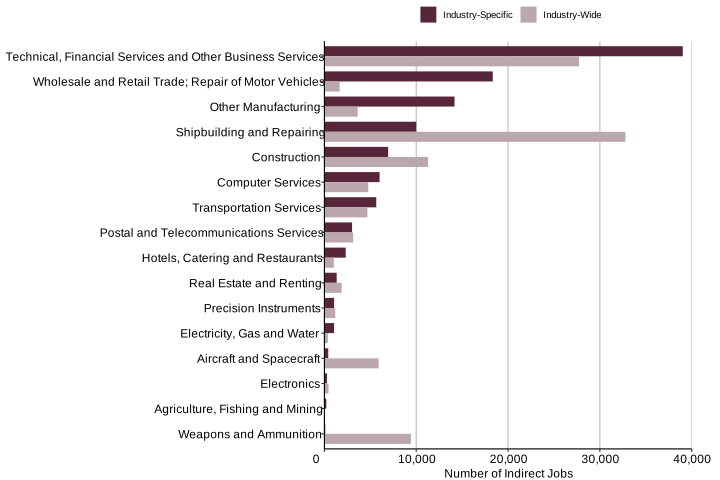
Industry-wide indirect jobs represent the total number of indirect jobs across all industry sectors supported by MOD expenditure in a specific sector. When viewed in terms of industry-wide indirect jobs, it is expenditure on Shipbuilding and Repairing that comes out on top for indirect employment.
In 2024/25, MOD expenditure on Shipbuilding and Repairing supported 32,800 jobs throughout the supply chain, more indirect jobs than in any other single industry.
In 2024/25, £6.9 billion was spent in the Shipbuilding and Repairing industry which supported 41,500 direct jobs in the same industry group and a further 32,800 indirect jobs across all industry sectors. This represents 30% of all indirect jobs supported within MOD’s supply chain. It should be clearly noted that these indirect jobs are not necessarily further jobs in the Shipbuilding and Repairing industry but rather made up of all industry components that are required to deliver end products and services in this sector.
The Technical, Financial Services and Other Business Services sector dominates industry-specific indirect jobs supported by MOD expenditure.
Industry-specific indirect jobs represent the total number of indirect jobs in a specific industry sector supported by MOD expenditure across all industry groups (irrespective of the direct industry group expenditure).
When viewed in terms of industry-specific indirect jobs, the highest number of jobs indirectly supported through MOD expenditure in 2024/25 was in the Technical, Financial Services and Other Business Services sector with 39,000 jobs. This sector had the largest absolute increase of industry wide indirect jobs supported by MOD Expenditure with an additional 3,000 jobs compared to the previous year.
Since 2013/14, it has supported over double the number of jobs than the next ranked industry group. Combined with Wholesale and Retail Trade; Repair of Motor Vehicles, these two industry groups accounted for 52% of all indirect MOD supported employment in 2024/25.
The Shipbuilding and Repairing industry has had the largest percentage increase in industry wide indirect jobs supported by MOD expenditure, with a 22% increase from the previous year.
Figure 8: Number of Indirect Jobs Supported Through MOD Expenditure by Industry Group 2024/25
Source: Analysis Directorate (MOD), ONS Input-Output Tables, ONS Supply-Use Tables, BRES employment figures and ABS turnover figures.
Figure 8 shows a horizontal bar chart showing the number of indirect jobs supported by MOD expenditure by industry group in descending order in 2024/25. MOD expenditure supported the highest number of industry-specific indirect jobs in the Technical, Financial Services and Other Business Services industry (39,000).
Note: ‘Technical, Financial Services and Other Business Services’ includes Financial Services, Business Services, Education, Health and other Service Activities.
‘Other Manufacturing’ excludes Weapons and Ammunition, Electronics, Precision Instruments, Shipbuilding and Repairing, and Aircraft and Spacecraft.
8. Methodology
This section sets out the data requirements and processes used to create the tables and charts in this bulletin. More detailed explanations of data sources, assumptions and methodologies used in this publication can be found in the Background Quality Report.
8.1 Sources
As well as using MOD expenditure and location data identified by MOD’s Contracting, Purchasing and Finance (CP&F) system and information from individual MOD project teams, additional input is required from data released by the ONS.
-
Supply-Use Tables (SUTs) are produced annually to show estimates of industry inputs and outputs, product supply and demand, and gross value added for the UK. SUTs for 1997 to 2023 are consistent with the UK National Accounts 2025 Blue Book.
-
Input-Output Analytical Tables (IOATs) are produced semi-regularly and are derived from the SUTs. They highlight how products are used to produce further products and satisfy final demand across ONS industry codes.
-
NOMIS annual data on regional employee and employment count.
-
Annual UK population estimates produced by the ONS.
-
Data on UK employment and turnover by MOD SIC group is produced by the ONS as a subset of the Business Register and Employment Survey (BRES) and Annual Business Survey (ABS).
-
Annual Location Statistics produced by the MOD present figures on the national and international locations of all UK Regular Forces personnel and MOD Civilian personnel.
8.2 Assumptions and Limitations
Various assumptions have had to be made throughout the process when concrete or reliable information was not available. These assumptions are listed in the Background Quality Report.
8.3 Estimating Direct Jobs Supported by MOD Expenditure
Turnover per full-time equivalent (FTE) employment for the UK is calculated by dividing turnover figures obtained from the ABS, by employment figures from the BRES. We can then divide MOD expenditure for each region and industry group by its respective industry’s turnover per FTE employment figure. This provides an estimate of how many direct jobs are supported by MOD expenditure in each region as well as in each industry group. This information is also presented as the number of direct jobs supported for every 100,000 people in FTE employment in the area, which is calculated using employment figures from the BRES and NOMIS.
8.4 Estimating Indirect Jobs Supported by MOD Expenditure
To estimate the number of indirect jobs supported in the UK by MOD expenditure, we use direct MOD expenditure with UK industry as a measure of MOD’s demand for products and services across the UK economy. By aggregating the ONS Input-Output Table from the IOATs to match the SIC groups used by MOD, we can use this table to show total UK wide demand and output (including intermediate products) arising from this initial MOD demand. Subtracting MOD final demand from this leaves just the intermediate demand (meaning that which occurs throughout the supply chain).
An estimate of UK output per FTE employment is calculated using the ONS Supply of Products Table in the SUTs and BRES employment data. The amount of UK output generated from MOD intermediate demand is then divided by output per FTE employment to determine the number of indirect jobs supported by MOD expenditure. Due to the method employed in their derivation, as well as showing the overall total, these estimates can be presented by industry group.
9. Glossary
Annual Business Survey (ABS) is the main business survey carried out by the ONS. It is used to collect financial information on a large proportion of the UK economy and includes figures such as turnover, employment costs and capital expenditure.
Business Register and Employment Survey (BRES) is a survey carried out by the ONS that provides information on employee and employment estimates by location and industry.
Contracting Purchasing and Finance (CP&F) provides a single online end to end procurement system for all MOD procurement activity. All other processes, especially paper-based systems, will be either replaced or subsumed.
Direct Jobs are defined as those supported within companies receiving payments for goods and services directly from MOD.
Full-Time Equivalent (FTE) Employment is a figure that allows part-time workers’ hours to be put into the same units as full-time workers.
Indirect Jobs are generated as a result of supporting and supplying goods and services to those in direct employment. It is therefore a measure of jobs that occur further down the supply chain through sub-contracting or via suppliers to the direct contractor.
Industry is defined as an economic activity concerned with the procurement and processing of raw materials into finished products.
Industry Groups are 22 groups based on the Standard Industrial Classification (SIC) 2007 guidelines maintained by the Office for National Statistics (ONS). Industry groups combine SIC codes that are related to similar types of activity. A breakdown of which SIC codes belong in each industry group can be found in the accompanying data tables to this publication.
Input-Output Analytical Tables (IOATs) are produced semi-regularly by the ONS and are derived from the Supply-Use Tables. They highlight how products are used to produce further products and satisfy final demand across ONS industry codes. These tables were historically produced once every five years due to the time it takes to compile additional data requirements yet due to the increased demand for their use this has been reviewed to become more timely. At point of release, the latest detailed tables are those from 2023.
Input-Output Table (IOT) is one of the main tables from the Input-Output Analytical Tables. It shows which products go to produce other products as intermediate production.
Intermediate Demand is demand for goods and services that occurs throughout the supply chain.
International Territorial Levels (ITL) Level 1 Regions are 12 UK regions used in the production of statistics.
Leontief Inverse Matrix shows how much of each industry’s output is needed to produce a unit of a given industry’s output. It is calculated from the ONS Input-Output Analytical Tables (IOATs).
Ministry of Defence (MOD) is the United Kingdom government department responsible for implementation of government defence policy.
MOD Vector of Final Demand is in-year MOD expenditure for a given financial year broken down by SIC groups.
NOMIS is a service provided by the Office for National Statistics (ONS) to give free public access to detailed and up-to-date UK labour market statistics from official sources. It contains readily accessible data from the Business Register and Employment Survey (BRES).
Office for National Statistics (ONS) is responsible for the production of a wide range of independent economic and social statistics. The statistics are there to improve understanding of the United Kingdom’s economy and society, and for planning the proper allocation of resources, policy-making and decision-making. It is the executive office of the UK Statistics Authority, a non-ministerial department which reports directly to Parliament. ONS is the UK Government’s single largest statistical producer.
Other Government Departments (OGDs) refers to government departments outside the MOD that the MOD spends money with.
Standard Industrial Classification (SIC) Codes classify business establishments and other statistical units by the type of economic activity in which they are engaged. The classification is maintained by the ONS.
Supply-Use Tables (SUTs) are produced annually by the ONS and show estimates of industry inputs and outputs, product supply and demand, and gross value added for the UK.
10. Further information
10.1 Symbols
Figures marked with p are provided as provisional estimates.
Figures marked with r are revised from the previous edition.
Data visualisations marked with “//” indicate there is a break in the data series. Surrounding commentary will declare the impact on the figures and whether the break in series arises from a data issue, or a change in methodology or process.
10.2 Rounding
Where rounding has been used, totals and sub-totals have been rounded separately and so may not equal the sums of their rounded parts. Total expenditure figures have been rounded to the nearest £ million, and per person expenditure figures have been rounded to the nearest £10. Total estimates for jobs supported by MOD expenditure have been rounded to the nearest 1,000, the number of jobs supported by MOD expenditure by region or industry group have been rounded to the nearest 100, and the number of jobs supported per 100,000 in FTE employment have been rounded to the nearest 10.
10.3 Revisions
Corrections to the published statistics will be made if errors are found, or if figures change as a result of improvements to methodology or changes to definitions. When making corrections, we will follow the Ministry of Defence Statistics Revisions and Corrections Policy. All corrected figures will be identified by the symbol r, and an explanation will be given stating the reason and size of the revision. Corrections which would have a significant impact on the utility of the statistics will be corrected as soon as possible, by reissuing the publication.
10.4 Contact Us
The Analysis Directorate welcomes feedback on our statistical products. If you have any comments or questions about this publication, or about our statistics in general, you can contact us as follows:
Analysis Directorate (Analysis-Expenditure)
Telephone: 0303 378 6554
Email: Analysis-Expenditure-PQ-FOI@mod.gov.uk
If you require information which is not available within this or other available publications, you may wish to submit a Request for Information to the Ministry of Defence under the Freedom of Information Act 2000.
If you wish to correspond by mail, our postal address is:
Analysis Directorate (Analysis-Expenditure)
Ministry of Defence
Teak, Level 1, Wing 3
MOD Abbey Wood North
Bristol
BS34 8QW
For general MOD enquiries, please call: 020 7218 9000
-
The break in series highlighted from 2020/21 is the result of a change in the methodology used to produce the regional expenditure estimates which impacted on the number of jobs supported by this expenditure. Comparisons across financial years 2019/20 and 2020/21 should not be made but longer term comparisons across the timeseries should still be valid. More details can be found in the Background Quality Report. ↩ ↩2 ↩3 ↩4