Wholesale Digital Markets Champion - First report
Published 13 July 2026

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/publications/wholesale-digital-markets-champion-first-report/wholesale-digital-markets-champion-first-report
1. Foreword
This is the first of two reports to the Chancellor in my role as Wholesale Digital Markets Champion.
The aim of this first report is to provide a framework towards how the UK develops a tokenised wholesale financial markets system, and steps towards the sector’s implementation of the Government’s Wholesale Financial Markets Digital Strategy.
Put simply, tokenised markets are fundamental to the future of financial services.[footnote 1] What the UK does here determines our right to be at the heart of the next generation of financial markets. The work of the Digital Markets Champion Industry Taskforce and this report is not simply an opportunity to participate in a growing market. It is an opportunity for the UK to help shape the future infrastructure of global finance.
Tokenised markets offer a significant opportunity to the UK in terms of efficiency, the potential for innovation, and to defend our global position in established markets. The prize is very large – estimates put the tokenised real-world assets (RWA) market at $88 trillion by 2035, dwarfing the current crypto and stablecoin market of $3 trillion. Beyond the fast-growing size of the market, there are significant productivity and cost efficiencies. All of this could translate into a sizeable economic benefit for the UK – an estimated up to £33 billion increase in annual economic output and £14 billion in annual tax revenue by 2035.[footnote 2]
The UK remains the global financial trading centre for much of the world. We have markets built on centuries of trust, deep pools of liquidity, and a Government with a track record of embracing innovation. However, tokenised markets are also a network game. Our place in that game is not guaranteed. Like all network games, it is a race and one where the UK needs to move at the speed of the most agile players if we want to ensure we have a stake in developing the approach for international markets. As outlined in TheCityUK’s report chaired by Dame Anne Richards, there is No Time to Lose.
As well as the UK’s deep heritage, this report is also founded on the work already done by Mark Austin CBE and Andrew Douglas as well as hundreds of participants across the market. There is a depth and breadth of progress being made across the market through initiatives like the Digital Gilt Instrument (DIGIT) Pilot, the Great British Tokenised Deposit (GBTD), the Tokenised Funds Blueprint and many more industry innovations.
HM Treasury and the Authorities[footnote 3] play a central role in providing a framework for innovators to operate with confidence, including the work already delivered on clearance.
I therefore welcome the recent call for input made jointly by the Bank of England and the Financial Conduct Authority (FCA).[footnote 4] This call for input comes alongside the Bank of England sterling-denominated systemic stablecoins policy statement,[footnote 5] the FCA cryptoasset regime policy statements,[footnote 6] the Authorities’ approach to joint regulation of systemic stablecoin issuers,[footnote 7] and the Digital Securities Sandbox update.[footnote 8]
As champion, my role is to present the voice of industry, but also be a bridge to the Government and the Authorities. In the course of compiling this report, I have undertaken extensive engagement including over seventy meetings with established and new firms, focused roundtables with international standard-setting bodies,[footnote 9] dialogue with financial market trade associations representing a broad cross-section of the sector, and two meetings of the full Taskforce with over eighty members and observers drawn from across the industry and the Authorities. This has also been supported by written submissions and wider engagement across the ecosystem.
The key challenges for the market for the coming year will be turning the many excellent individual initiatives into a broad, strategic approach to tokenisation and wholesale digital markets as a whole. The aim of the work of this report will be to encourage, embrace and unblock. As an industry, we need to innovate as pragmatically and swiftly as possible, including where we can drive innovations without the need for regulatory or legislative change.
As outlined in the following pages, the UK needs to adopt an approach to a number of key issues, including how much interoperability is needed within the UK and internationally, and how the necessary level of interoperability can be achieved. We need to have a clear, joined-up vision for the necessary conditions for the growth of tokenised markets, including the supporting arrangements in law and tax.
In addition to all this, the UK needs to be confident in articulating its value to the world. As is too often the case, significant steps have been taken by UK market participants, HM Treasury, and the Authorities with stereotypical modesty, but other countries have been much more voluble. Whilst pushing to do more, more quickly, the UK – industry, Authorities and Government together – need to have a clear, confident message: that when it comes to digital markets, the UK is open for business. Open to innovation. Open to investment. And determined to remain at the forefront of global financial markets.
The publication of this report is also an opportunity to engage even more widely. I am particularly keen to hear views from those firms with whom I have yet to engage. I would also welcome views on the contents of this report by Friday 4 September 2026 to ensure the proposed programme of work reflects the priorities of the sector as a whole.
Finally, thanks are due to the many people who have contributed to this first report. Thanks in particular to the more than fifty firms providing members of the Taskforce from across industry, those wise people who have helped me via my informal steering group[footnote 10] and the incredibly committed and helpful colleagues from across HM Treasury and the Authorities who have been generous with their time. Thank you too to the dozens of firms and organisations who have already submitted their thoughts and those that have taken the time to meet me.
Special thanks go to Chris Hayward, Policy Chairman of the City of London Corporation for his support, and to Jenny Young and her City of London Corporation colleagues for running the secretariat alongside support from TheCityUK, the Investment Association, UK Finance and Innovate Finance. Last but not least, thank you to Tim Maloney and his colleagues from HM Treasury who have been a constant source of support and advice. This report would simply not have happened without all of you.
This has only been the beginning – I look forward to working with everyone in the year ahead.
Christopher Woolard CBE
Wholesale Digital Markets Champion
2. Executive Summary and a look forward to the second report
The UK is a leading global liquidity provider in wholesale capital markets, processing over £4 trillion worth of securities on average per day[footnote 11] and is well placed to take advantage of digitalisation. Tokenised assets represented only a marginal 0.01% of investable assets in 2025 ($30 billion globally), but value grew by 300% in 2025. This could reach $88 trillion, or around 16% of global investable assets, by 2035.[footnote 12] Without a clear national roadmap, there is a risk that standards, infrastructure and regulatory frameworks evolve offshore, eroding the UK’s role as an open and global financial centre.
The UK has already made some significant progress. Plans for the DIGIT Pilot would make the UK the first country in the G7 to issue Government debt securities. The Digital Securities Sandbox (DSS) is the most sophisticated public live financial markets facility in the world. UK Authorities have recently confirmed that DSS firms can now apply to use specific stablecoins as a settlement asset.[footnote 13] Dozens of firms across the UK market have piloted approaches to digital assets.
A coordinated approach between Government, the Authorities, and industry will enable clear legal, regulatory, and tax treatment of tokenised and digitally native assets. This will position the UK as the leading jurisdiction for digital market activity and innovation, attracting new asset classes, anchoring key infrastructure onshore, and reinforcing the UK’s position as a global hub for open, safe and efficient capital markets. Firms need the confidence to make the material private investments needed in tokenisation.
We need practical, pragmatic actions to unlock that investment. Our focus needs to be on action. Action in the short-term to prove concepts and build confidence, action to lay long-term pathways, and action to ensure the world understands the UK’s global capability and ambition. By seizing the opportunity of digitally native asset classes alongside the ongoing tokenisation of traditional global liquidity, the UK can digitalise at scale, future-proof its financial ecosystem, and solidify its position as an open and global financial centre.
Early focus on the UK’s strengths across fixed income, international Foreign Exchange (FX), equities, derivatives and trusted financial intermediaries will help accrue benefits and skew the economic outcomes towards more winners than losers. Focusing specifically on secondary markets as well as post-trade and settlement infrastructure will prioritise liquidity, transparent price formation, efficient capital utilisation, capital mobility, cross-border flows and scalability. These are necessary conditions to unlock the full economic and competitive benefits of tokenised and digitally native assets.
This report sets out the current state of play, including the innovation landscape and what has been achieved to date, before making the case for tokenisation and the benefits that can be gained. It then explores several policy considerations, as well as the approaches from other jurisdictions and the impacts of cross-border issuance and international interoperability.
Facilitating the transition to tokenised markets requires clear prioritisation; this report outlines the immediate industry priorities and supporting actions for HM Treasury and the Authorities, as summarised in Table 1 below.
The Digital Markets Champion Industry Taskforce (“the Taskforce”) will drive these actions over the next 12 months to deliver the UK’s vision. Structurally, we are adopting a cross-sectoral approach to digitalising specific use cases, starting with an end-to-end repo transaction.
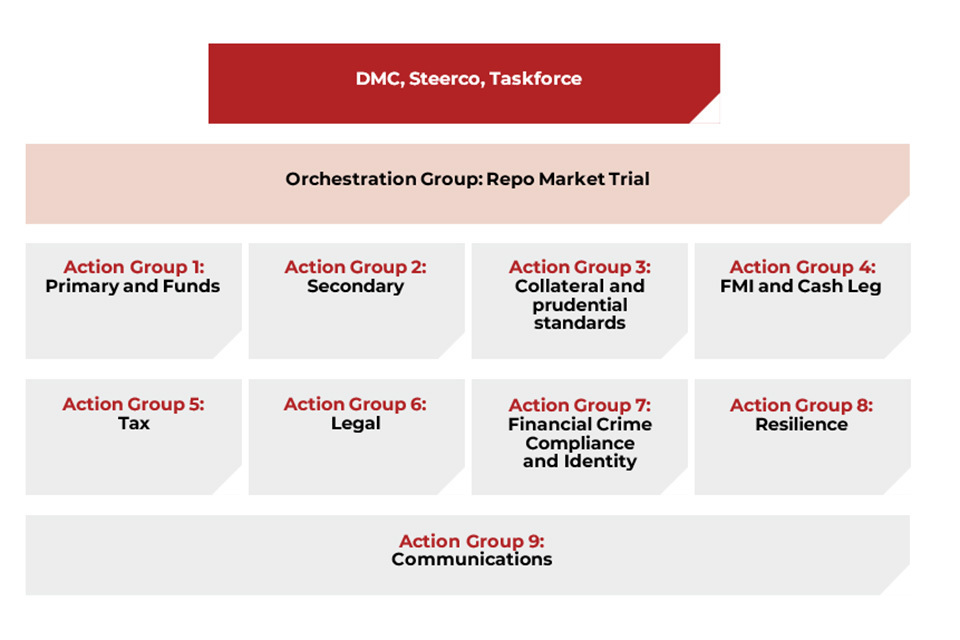
To achieve this, the Taskforce is setting up Action Groups (AGs) across nine specific areas to convene industry experts. They will be guided by the ten key priorities outlined in Table 1 below, and further details on the appointment of these Action Groups will be set out by September. To reinforce and guide their efforts, a Digital Markets Champion-led Orchestrator Group (OG) will coordinate the practical delivery of the end-to-end repo use case on blockchain, ensuring ecosystem-wide interoperability and cross-border testing.
The key priorities identified in this report have been summarised in Table 1, including Industry Actions, supporting actions from the Government and Authorities, and the Action Groups in the Taskforce assigned to their delivery.
Table 1: Summary of Priorities, Recommendations, Industry Actions and their responsible Action Groups
| Priority | Industry/Actions | Supporting Actions from Government and Authorities | Action Groups |
|---|---|---|---|
| 1. Clear direction towards scalable, live tokenised markets that drive industry investment | • Build on the DIGIT pilot to develop the market towards an ecosystem for digital securities, leveraging sector issuances. • Beyond DIGIT, develop the standards for open, interoperable platforms to broaden investor access. • Taskforce to deliver and validate end-to-end tokenisation use cases focusing on three priority areas: repo, fixed income and uncleared over-the-counter (OTC) derivatives. |
• Work with the Taskforce to assess how the regulatory framework for central securities depositories (CSDs) should evolve to support the wider adoption of tokenisation. • Build on the success of the DSS and other initiatives by building more predictable pathways from these foundations to full authorisation, market launch and scale. • Prioritise an immediate pilot issuance of DIGIT no later than Q1 2027 and the development of further DIGIT issuances over the medium term. Working with the sector these should demonstrate successful live secondary market trading of those instruments and encourage investment in infrastructure by industry. |
OG, AGs 1, 2 |
| 2. Tokenised collateral to support the development of tokenised markets | • Build collaborative wider ecosystem solutions from existing bilateral use cases. • Taskforce to deliver and validate end-to-end repo use case to support scaling, using DIGIT and/or privately issued assets depending on availability and suitability. |
• The Bank of England should be prepared to accept DIGIT as collateral in the Sterling Monetary Framework. • The Bank of England should consider broader acceptability of tokenised collateral in the market, for example for the use in central counterparties (CCPs). |
AG 3 |
| 3. Establishment of a tokenised funds market | • Through the Investment Association’s (IA’s) Investment Fund 3.0 (IF3) Lab, develop funds use cases to: • Establish common operational and market practices. • Demonstrate scalability. |
• Maintain close engagement with industry through the City Minister’s Investment Management Taskforce to ensure they keep pace with evolving market developments in the asset management sector. • Provide guidance as needed based on evidence emerging from implementation |
AG 1-3 |
| 4. Wholesale payment rails that support tokenised markets | • Continue to build GBTD at scale. • Build end-to-end tokenisation use cases that work across both existing and new payment rails. • Develop shared token standards, common Application Programming Interfaces (APIs) and data models (including through the Common Domain Model) to deliver interoperability. |
• Ensure infrastructure and regulatory policy supports settlement of tokenised assets using different forms of money (including stablecoins and tokenised deposits). • Develop models to allow settlement directly in central bank money via real-time gross settlement (RTGS), such as through Synchronisation. |
AG 4 |
| 5. Legal certainty and best practice to remove perceived and real obstacles | • Develop best practice frameworks including for contracts under English Law (for example through International Capital Markets Association’s (ICMA’s) digital Bond Data Taxonomy). • Identify issues that are blocking industry development and raise with the Authorities. • Promote that English law accommodates innovation and, where needed, develop myth-busting narratives where there are misconceptions. |
• Support industry where it requires greater legal certainty. | AG 6 |
| 6. Regulatory standards that support tokenised markets | • Collaborate with HM Treasury and the Authorities to identify pinch-points. | • Ensure that the UK’s regulatory regime provides comprehensive support for digital innovation, including its integration with traditional markets, without extending the regulatory envelope. | AG 3 |
| 7. Standards that support domestic and international interoperability and convergence | • Lead on the development of domestic interoperability standards that support transaction flows, including APIs, common messaging protocols, reference data models, and data standards. Produce governance frameworks to oversee the development, adoption and maintenance of these standards (including through the Common Domain Model). • Where shared industry standards are not possible, adopt other solutions (e.g. interoperability layers, orchestrators) to allow distributed ledger technology (DLT)-based ledgers to interact with existing settlement infrastructure and each other. |
• Adopt a proportionate and technology neutral principle-based approach that supports, where appropriate, the introduction of new services by existing financial market infrastructures (FMIs), or new entrants to become FMIs, to drive further innovation in the sector. • Support industry-led functional standard setting for interoperability, in line with established regulatory expectations. |
AG 1-4 |
| 8. Effective Financial Crime Compliance (FCC) and digital identity | • Develop solutions and best practice to close the ‘lag’ of any tokenised asset’s compliance data moving between platforms and its associated asset (KYC, AML, sanctions screening). • Develop and test interoperable compliance frameworks, including benchmarking standards across jurisdictions, and propose mechanisms such as safe harbours. • Support digital verification by building on pre-existing industry-led initiatives that leverage trusted standards for identity credentials and data quality. |
• Ensure domestic and global regulations on financial crime are fit for DLT. • Support the development of industry standards on digital verification and identity. |
AG 7 |
| 9. A technology neutral approach to tax | • Contribute to the development of technologically neutral tax frameworks by considering relevant accounting standards, including any insights from end-to-end tokenisation use cases, and through existing industry working groups. | • Embed tech-neutrality for tax treatment of digital assets into legislation and guidance. | AG 5 |
| 10. Resilience through collaboration between industry and the Authorities | • Deliver a coordinated testing and resilience programme for cross-network components. | • Adapt existing principles, consistent with their statutory objectives, to underpin resilience in tokenised markets, as part of a broader set of standards and practices applied by firms. | AG 8 |
The Action Groups (AGs) are as follows:
- AG1–AG4: focussed on primary issuance, secondary markets, collateral, and FMI/cash infrastructure, developing interoperable platforms, token standards, smart contracts, and settlement processes.
- AG5–AG8 providing horizontal support across tax, legal, financial crime compliance, and resilience, producing best practice guidance and undertaking stress testing of the end-to-end use case.
- A ninth Action Group will be tasked with coordinating the promotion of the UK as a digital assets centre, including myth-busting where needed.
Figure 1 below provides a visual representation of the structure of the Taskforce across the Action Groups and the Orchestration Group. Annex G provides further detail on the specific work of the Action Groups and expected outputs.
Figure 1: Visual of Digital Markets Champion Industry Taskforce and Action Group Architecture
3. Baseline
3.1 Wholesale capital markets today
Wholesale capital markets are interconnected and mostly institutional in nature, allowing participants to raise short-term finance and long-term capital to fund growth; undertake domestic and international trade; manage financial and other risks; and pursue investment opportunities.[footnote 14]
The UK is a leading global liquidity provider in wholesale capital markets, processing over £4 trillion worth of securities on average per day.[footnote 15] We lead in FX, Over-the-Counter (OTC) derivatives, repurchase agreement (repo) and funding markets, and are a major booking centre for international banks. That position reflects not only market scale and liquidity, but also the depth of the UK’s legal, regulatory, infrastructure, and professional services ecosystem.
3.2 Role of firms
Established firms are key enablers of tokenisation in the existing UK framework.[footnote 16] They provide regulated infrastructure, tokenised sterling deposits, market connectivity and institutional-grade risk management. They will likely remain the main source of liquidity in tokenised markets and be a key trust anchor for the scaling of tokenisation. They will devote capital expenditure and scale when regulatory and end-game certainty is achieved.[footnote 17]
Recent entrants have differentiated themselves through their speed of innovation and development of novel product and market models, including tokenised equities, funds, and collateral products. They are building native systems, with a focus on enabling continuous markets, new forms of ownership like fractionalising, and expanded asset universes.
Some firms across the ecosystem are designing solutions that work with existing infrastructure and enable collaboration between established firms. In these so-called hybrid models, functions such as settlement, custody, liquidity provision, and risk management rely on established systems.[footnote 18] In parallel, other firms are experimenting with approaches that move elements of existing FMIs on chain, while preserving core roles such as centralised clearing, custody and collateral management. As a result, DLT-based and legacy systems could potentially operate alongside one another.[footnote 19]
There is evidence of convergence between established and recent entrants, driven by acquisitions,[footnote 20] established firms‘ own innovation efforts,[footnote 21] and increasing collaboration between recent and established firms.[footnote 22] As this convergence accelerates, established financial institutions are expected to remain system operators, with new entrants either competing directly or partnering strategically to deliver tokenised products and services.
3.3 The innovation landscape
The global innovation landscape for DLT is moving away from pilots and experimentation, and towards scaled market infrastructure and live deployment across use cases such as collateral, payments, bonds and stablecoins.[footnote 23]
Whilst DLT designs have become technically more advanced, governance, resilience, integration with existing infrastructure, and access to central bank money remain key constraints on wider adoption.[footnote 24]
In addition, compliance and due diligence costs associated with assessing new technologies create barriers to entry. Regulated firms often face resource constraints in assessing and onboarding new technology offerings, creating friction for DLT-based innovation in wholesale financial markets.[footnote 25] A key policy consideration, reflected in the Bank of England and FCA Digital Securities Sandbox Guidance, is that supervisory and regulatory requirements should be proportionate to risk, scale and technology, rather than applying a uniform institutional-grade compliance framework to early-stage DLT initiatives.[footnote 26]
3.4 What has been achieved to date
Industry has been working at pace to innovate through tokenisation within the existing UK regulatory framework.
Case study:
In July 2025, Lloyds Banking Group, Aberdeen Investments, and Archax completed a UK-first initiative, using tokenised money market fund units and tokenised UK gilts as collateral for foreign exchange trades. Lloyds noted that the initiative proved digital assets can be used in regulated financial markets under existing legal frameworks.[footnote 27]
Case study:
In September 2025, London Stock Exchange Group (LSEG) launched its Digital Markets Infrastructure platform for private funds and facilitated its first transaction, covering the full asset lifecycle from issuance and tokenisation through to post-trade settlement, including support for secondary market transfers – all within its existing permissions.[footnote 28]
These live, institutional-scale transactions demonstrate that the current rules already accommodate meaningful tokenisation in UK capital markets. Regulated firms are operating in tokenised markets today under permissions that already exist, across trading, clearing, custody, banking, prime brokerage, payments and asset management. Further examples of this are set out in Annex B, however, there remains a need for GBP-denominated stablecoins to be developed then issued at scale and pace. Establishing a robust and domestic stablecoin ecosystem will be critical to strengthen the UK’s competitiveness and operational resilience, safeguarding its strategic position in an increasingly complex geopolitical environment.
Advances in legislation, policy, and regulation, including through the Digital Securities Sandbox (DSS) and the FCA Regulatory Sandbox cohort have helped establish stronger foundations for tokenisation. However, this progress has yet to translate into significant live issuance and adoption at scale – an outcome that currently remains limited across jurisdictions. In addition, the possibility of international participants in the DSS should be evaluated to further enhance its impact.
The UK’s overarching ambition for digital wholesale financial markets was set out in the Wholesale Financial Markets Digital Strategy, published in July 2025.[footnote 29] UK Authorities have committed to supporting the growth of tokenisation in wholesale financial markets, including through the commitments the Bank of England and FCA have recently set out in their joint Call for Input.[footnote 30]
The UK has established initiatives, including the DIGIT Pilot and the DSS, to deepen the tokenised finance ecosystem, signalling a transition from exploration to experimentation to implementation. Notable initiatives and their timelines are set out in Annex C.
3.5 Interaction with other Government initiatives to digitise the economy
Within the Wholesale Financial Markets Digital Strategy, DLT is deployed alongside artificial intelligence (AI) and quantum technologies.[footnote 31] These are generally complementary but hold characteristics of their own that interact with DLT, entailing impact on regulation, uptake, risk, and sequencing. For example, agentic AI operating on DLT infrastructure introduces new accountability gaps that current frameworks are not yet fully developed to mitigate. Quantum introduces strength in fast, complex modelling, but also vulnerabilities from quantum-enabled cyber-attacks.
Regulations and initiatives, such as the DSS, only address each technology individually, but the overlaps between them present uncertainty. Identifying the most prevalent and impactful crossovers and engaging with the Authorities and infrastructure providers will help enable these distinct but related initiatives to work together. This will also support delivery of the UK’s National Payments Vision, ensuring that emerging technologies are adopted within a coherent framework that promotes innovation, resilience, and interoperability across wholesale financial markets and payment infrastructures.[footnote 32]
4. The case for tokenisation and digitalisation
4.1 Drivers of tokenisation
The move to tokenisation is driven by several reinforcing forces:
- the economics of token-based networks;
- a client environment that is becoming increasingly digital and operationally sophisticated;
- a regulatory landscape that is gradually opening across major jurisdictions; and
- rising competitive pressure as exchanges, market infrastructures, and digital-native firms seek to capture value in emerging market structures.[footnote 33]
Crucially, these market dynamics are underpinned by an economic rationale as the structural shift toward digital assets unlocks substantial commercial value and capital efficiencies.
These drivers have implications far beyond operational efficiency. By successfully scaling its digital asset activity, the UK will be better positioned to attract capital, liquidity, talent, and innovation. Fostering a strong digital asset ecosystem will be important not only for maintaining competitiveness, but also for reinforcing its position as a leading global financial centre as market activity increasingly moves onto digital rails.
4.2 Economic and competitive benefits
The case for tokenisation is technological, economic, and strategic. If implemented at scale, tokenisation could improve the efficiency of wholesale markets, free up capital for growth investment, support new sources of revenue, and strengthen the UK’s competitive position. Over time, tokenisation can broaden access to capital markets by lowering distribution costs, enabling fractional ownership, and increasing participation in productive assets. In 2025, financial and professional services in the UK contributed £323 billion in economic output and £110 billion in taxes.[footnote 34] Analysis by Barclays and PwC suggests that tokenisation could increase this output on annual basis by up to £33 billion in economic value and by £14 billion in fiscal revenues by 2035, provided the UK is one of the leading jurisdictions for tokenisation, tokenisation scales globally, and UK domestic adoption increases in line with major peers.[footnote 35]
4.3 Capital efficiency
Tokenisation can improve collateral mobility, capital efficiency, and risk management by making assets easier to identify, move, substitute, and reuse across venues and workflows. This reduces trapped collateral, excess buffers, failed trades, and friction in collateralised funding and treasury activity. Faster settlement and greater transparency over asset location and ownership can also reduce operational, counterparty, and liquidity risk.[footnote 36] Capital freed up from more efficient collateral and treasury functions can be redeployed into higher-value activity. The projected 1–2% improvement in collateral efficiency would generate hundreds of millions of pounds of annual economic value for an average wholesale bank and contribute up to 4% uplift in return on equity. Fractionalised ownership alone would unlock 10-20% of additional capital for an average real estate fund.[footnote 37]
Case study:
In February 2026, Digital Asset, alongside a working group of leading financial institutions, completed a groundbreaking cross-border intraday repo with tokenised Gilts. This set of transactions was also executed using tokenised Gilts against non-GBP tokenised deposits, making it the first cross-currency transaction of its kind.[footnote 38]
4.4 Cost reduction
Shared records and programmable workflows can reduce reconciliation, manual intervention, and fragmented processing across issuance, reporting, and post-trade activities.[footnote 39] These benefits appear credible, although many will only be fully realised after a transition period in which firms run digital and legacy systems in parallel.[footnote 40][footnote 41]
4.5 Revenue opportunities
Tokenisation in wholesale markets creates revenue opportunities across the whole value chain. Banks, brokers, and asset managers can grow fee earning by broadening access to previously hard-to-access assets (such as private markets) and new digital assets (such as fractionalised real-world assets). The access case should be framed with care, as participation in many tokenised products remains limited to eligible investors.[footnote 42] Nevertheless, these instances of broadening access to previously closed markets reflect a small proportion of the examples of innovation providing new services to the market. As the range of new services expands, revenue sources will follow in turn, yielding stronger revenue opportunities from innovation as they expand and deepen.
Case study:
In June 2026, Baillie Gifford launched the UK’s first fully tokenised investment fund ($BAGEY), partnering with BNY. This corporate fund is issued natively on the Ethereum and Solana blockchains, featuring innovative stablecoin redemption and peer-to-peer transfer capabilities. It pays eligible investors a yield of approximately 7%, and is denominated in dollars.[footnote 43]
Research suggests that for existing services, asset managers are expected to see a 15–30% revenue uplift from the improved capture, mix, and scalability of the existing asset base (excluding new clients and alpha).[footnote 44] Trading venues, CSDs, CCPs and new platforms can monetise issuance, trading, settlement, and custody via transaction fees, connectivity charges and data and analytics derived from richer, near real-time on chain information.
4.6 Strategic and ecosystem benefits
Beyond the direct economic benefits, tokenisation may also reshape competitive positioning in wholesale markets. Annex D analyses what change could look like for firms in the UK. The key issue is not whether tokenised securities displace business models outright, but whether institutions can retain control of high-value activities as they migrate onto digital rails.
For the UK, more efficient capital markets can improve the allocation of capital, support business funding, and contribute to economic growth. A credible domestic market would also give UK banks, asset managers, custodians, exchanges, technology providers, and fintechs a stronger platform for innovation. A trusted UK market could also attract international issuers, investors, and intermediaries, supporting high-value jobs, investment, and innovation across the wider UK financial services ecosystem. With tokenisation, the UK can also both leverage and further bolster English common law’s global reputation for trustworthiness, predictability, and adaptability.
5. Policy considerations
5.1 Understanding network effects
Network effects arise when each additional user or asset increases the value of a platform to existing and prospective users by enhancing liquidity, price discovery and collateral availability. Network effects are present in all traditional payment and settlement infrastructure and will continue to shape hybrid wholesale markets, where firms will issue, trade, or collateralise tokenised assets but settle through traditional FMIs.[footnote 45]
In fully tokenised wholesale markets, the ledger, or set of interoperable ledgers that host the most assets and liquidity, may progressively become more attractive to new issuers, intermediaries, and investors. Initially, this could lead to fragmented market structures or “walled gardens” with different ledgers or sets of interoperable ledgers operating in parallel. Once a ledger or standard reaches scale first, other ledgers or sets of standardised ledgers could find it difficult to compete.[footnote 46] Understanding these effects and their impact on market structures is essential.
5.2 The need for pace
The UK could emerge as a trusted hub for governance and intermediation in cross-border transactions and tokenised markets. Until recently, the UK regulatory regime was seen as developing more slowly than the US, EU, UAE, and Singapore in authorising digital asset firms and finalising its crypto regime. A lack of pace would bring fundamental risks to the UK’s influential position as a global leading financial services hub. These risks include the movement of liquidity offshore, being a standards taker rather than standards setter, and the concentration of new market infrastructure in jurisdictions outside of the UK. The picture today is now more nuanced and the UK is better placed to avoid these risks. On stablecoins, the UK and US are on similar timelines, both targeting full regimes in 2027. With its final cryptoasset framework published by the FCA, the UK is structurally further advanced than the US, where comprehensive federal legislation remains pending. Compared with the EU, Markets in Crypto-Assets Regulation (MiCA) gives Europe a lead in retail crypto regulation, but the UK has moved faster on wholesale tokenisation policy. The FCA will open applications for authorisation on 30 September 2026 ahead of the implementation of the regime in October 2027. Nevertheless, there remains some industry concerns that the UK authorisation processes remain slower than in other jurisdiction, e.g. the US.
The UK has already laid important groundwork. Live wholesale omnibus accounts now enable DLT networks to settle in risk-free central bank money, while work continues to facilitate the future settlement of tokenised assets in central bank money (including synchronisation and moving towards 24/7 settlement). This sits alongside the DSS, the FCA’s Wholesale Data Market Study, and the recent joint Bank of England and FCA call for input. At the same time, there is a broader global dynamic: the importance of clear, consistent signals from the Authorities in enabling market participants to move from pilots and announcements into live operation. If core wholesale activities such as trading and settlement, collateral management, and funding increasingly migrate onto digital rails, jurisdictions that move faster to support scalable tokenised markets are likely to capture a greater share of activity, liquidity, and standard-setting power. This is true for the whole value chain: issuing a tokenised security has limited value for the secondary market if it (i) cannot be traded, (ii) used as collateral to obtain financing or (iii) used in a repo transaction for the secured borrowing and lending of cash.[footnote 47]
Case study:
In 2025, Standard Chartered became the first global systemically important bank to launch an institutional crypto trading desk in London, offering spot trading in Bitcoin (BTC) and Ethereum (ETH) to institutional clients. Through its UK-headquartered ventures, Zodia Custody and Zodia Markets, the Bank has also helped build the custody, trading, and settlement infrastructure underpinning institutional digital asset adoption, reinforcing the UK’s position as a leading centre for digital asset innovation.[footnote 48]
For the UK, the value of getting this right means strengthening UK’s role in the next generation of wholesale markets, capturing efficiency gains, and helping retain high-value activity onshore rather than seeing it migrate offshore. Moreover, traditional advantages such as the UK’s strategic time-zone position may diminish in a 24/7 financial market. Maintaining competitiveness will therefore require legal, regulatory, and technical standards that enable tokenised markets to develop safely and at scale.
5.3 Maintaining the integrity of UK policy
Alongside what may be technically possible and commercially desirable, policymakers will need to consider the maintenance of the integrity of wider number of issues including UK monetary and securities policy. This may manifest itself in a large number of issues in the development of tokenised markets and the Taskforce. The Authorities should specifically acknowledge these issues in their work together and look for practical solutions.
5.4 Liquidity
Deep pools of liquidity are essential for the functioning of all secondary markets. While the UK possesses these deep pools, concern exists that tokenisation could induce market fragmentation as pools form around particular tokenised chains. Although a degree of minor fracturing may be inevitable during an initial experimentation phase, this risk underscores the critical necessity of cross-chain interoperability. Consequently, existing FMIs and exchanges will play a pivotal role in anchoring this transition, serving as vital bridges alongside emerging digital means of exchange. This could include permissionless chains providing the common liquidity with permissioned institutional layers built on top.
5.5 Fostering innovation
Many of the digital assets in scope of this report already exist in current markets, so conversion at scale is likely to involve established players. However, we have seen deep innovations in many markets driven by newer firms, particularly native digital asset issuers and fintech innovators. Crucially, this includes a comprehensive regulatory regime for stablecoins, which alongside tokenised deposits, are emerging as vital components for on-chain settlement. Other technology companies have been developing supporting technologies for clearance, secure custody, and interoperability. We should also not forget that some of the most promising developments have come from established players partnering with innovators. As the Taskforce progresses, ensuring that there is the opportunity for new technologies, new players and new infrastructure to emerge will be an essential part of the UK’s development.
5.6 Permissioned and permissionless networks
DLT is broadly categorised into permissioned and permissionless (or public) networks. In the first phase of this work, almost all the networks of any scale being considered will be permissioned – meaning they will be between a known group of interlocutors, pre-authorised to operate. However, as markets progress, the UK, HM Treasury and the Authorities should remain open to the competitive benefits of permissionless networks. A full approach towards permissionless networks should be developed in the medium-term.
Permissionless DLT offers significant benefits including market maturity and liquidity, decentralisation and resilience, transparency and auditability supporting blockchain forensics, and a broad ecosystem of custodians, liquidity providers and risk management infrastructure. A technology-neutral, outcomes focussed approach would allow the benefits of permissionless networks to be realised while ensuring that financial stability and resilience objectives are met.
While permissionless networks are a natural evolution within the uptake of DLT, they introduce fresh challenges compared to traditional models of intermediaries. For example, as transactions and value move on-chain, there are fewer opportunities to confirm identity (as opposed to the more numerous opportunities in traditional financial markets infrastructure, e.g. correspondent banks), which holds implications for compliance with identity-based requirements like anti-money laundering (AML) and Know Your Customer (KYC) obligations. Emerging on-chain identity solutions attempt to incorporate identity verification onto the chain itself, however, these solutions are still in their early stages, as are the accompanying regulations and legal requirements to promote compliance. Moving forward industry and the Authorities alike will need to treat onboarding controls and on-chain identity standards as essential to ensure the compliance architecture matures at a similar pace to the technology it serves.
Enabling regulated financial institutions to interact with public blockchains in a proportionate manner, paired with institution-grade risk management and clear supervisory standards, can reduce systemic risk by improving transparency and keeping activity within the regulated sector. The Authorities and international standard setters should work with industry to leverage evolving safeguards, governance practices, and mitigants to some of the risks associated with permissionless DLT and reflect those in the regulatory framework. The addition of risk management, for example permissioned layers on top of permissionless networks, will make the distinction between permissioned and public blockchains less binary.
Case study:
In 2024, BlackRock launched its BlackRock USD Institutional Digital Liquidity Fund (“BUIDL”), which is issued on Ethereum (a permissionless, public network) but with a permissioned layer on top provided by Securitize. Investor onboarding, compliance, and share issuance are handled in a permissioned environment, and the resulting fund shares are issued as tokens on Ethereum. This creates a hybrid model between traditional finance compliance and on-chain infrastructure.[footnote 49]
Settlement on permissionless networks is also an area of consideration. In many permissionless DLTs, settlement risk exists where a confirmed transaction could in theory be reversed by a chain reorganisation – a problem that has not needed to be addressed to date by traditional infrastructure or regulations.[footnote 50] The law should be calibrated to account for this risk, but overcoming these novel challenges will require industry and regulatory collaboration to carefully design and develop systems, accountability frameworks, and mechanisms to reassure participants and support confidence in permissionless market infrastructure.
5.7 Settlement Finality
Settlement finality is critical in UK wholesale markets for both securities transactions and the movement of collateral. It ensures that, once processed through a designated payment or securities settlement system,[footnote 51] transfers of funds and securities are irrevocable and cannot be reversed in insolvency of a participant in the system. This reduces systemic risk, supports market stability, and gives participants certainty over their positions and liquidity. However, the UK’s existing settlement finality regime was built around traditional payment and securities settlement systems and has not yet been fully adapted to cover systems for tokenised assets and DLTbased settlement in a clear, consistent way. The DSS currently makes provisions for the designation of such systems in its scope of securities settlement. Further clarity around other tokenised assets would encourage accelerated adoption and scaling of DLTbased infrastructure.
5.8 Buy-side considerations
Tokenised wholesale markets will not scale without active participation from both the buy-side and the sell-side. While the sell-side plays a critical role in issuance, market-making and infrastructure provision, the buy-side ultimately determines whether tokenised assets achieve meaningful adoption through capital allocation decisions, liquidity provision and product design. As highlighted throughout this report, liquidity is the key test of success for tokenisation, and fragmentation across issuers and platforms remains a constraint in early-stage markets. Without clear buy-side demand, including from asset managers, pension funds and insurers, tokenised products risk remaining confined to pilots or niche use cases rather than developing into deep, scalable markets. Industry experience, including insights from the UK–Singapore Project Guardian, underscores that buy-side requirements must be embedded early in market design. These include clarity on custody, client asset protection, valuation, fund accounting, and integration into existing portfolio management and risk frameworks.[footnote 52]
Buy-side firms are less concerned with the underlying technology than with whether tokenised assets deliver equal or better economics than traditional instruments, while still fitting into existing trading, financing, and risk-management processes. This reinforces the need for tokenisation initiatives to move beyond issuance and address the full lifecycle, particularly secondary markets, collateral usability and interoperability, to ensure assets are investible at scale. For example, initiatives like DIGIT have highlighted the need to support the development of secondary markets within the case for fixed-income applications.
This lesson extends beyond tokenisation. For several years, the Investment Association (IA) has championed the electronification of equity IPOs and secondary placings, reflecting buy-side demand for more efficient, resilient and transparent capital markets that evolve alongside market innovation. In 2024, a position paper calling for the electronification of Initial Public Offering (IPO) order placement was published and has since worked with market participants, the Authorities and the FIX Trading Community to develop practical solutions and common standards.[footnote 53] This experience has reinforced an important principle: successful market innovation depends not only on new technology, but on active buy-side participation, interoperability, and a clear value proposition for investors.
Durable market change cannot be delivered by issuers, infrastructure providers, or intermediaries acting alone. Success requires coordinated action across the investment value chain, with products, standards, and market practices designed collaboratively and aligned to the operational, liquidity, and investment needs of end users. Without such coordination, there is a risk that liquidity, investment activity, and operational efficiencies become fragmented across platforms rather than contributing to the development of deep and scalable markets. A co-ordinated approach from participants from across the value chain is therefore essential to avoid disjointed development. In practice, this means co-designing tokenised products and aligning standards (for example, on data models and reporting).
6. International approach
6.1 International comparison
Annex E contains a comparative analysis of the developments in the EU, Hong Kong, Luxembourg, the Middle East, Singapore, Switzerland and the US. Digital financial markets are evolving in all these jurisdictions, but they do not provide a single consistent approach to follow. The US has shown the importance of private sector scale and institutional adoption. Hong Kong has created live proof points through Government-led digital bonds and regulated platform linkages, but has not demonstrated broad private sector cross-border issuance at scale. Singapore has used Project Guardian to test cross-border functionality and international interoperability. Switzerland has built legal certainty and regulated infrastructure, with real activity concentrated in digital bonds and settlement connectivity. The EU has created a harmonised Distributed Ledger Technology Pilot Regime, but uptake remains limited. In the Middle East, activity is concentrated in licensed financial centres, sandboxes and controlled settlement experiments. The common lesson is that jurisdictions are moving from policy design into staged implementation, but market-wide scale remains limited.
Crucially, many international frameworks have two structural limitations that impede cross-border interoperability: they blur private law and regulatory requirements, effectively locking firms into a single legal structure, and they do not adequately accommodate DLT systems governed under foreign legal regimes. As the UK develops its approach, it should avoid these constraints and instead adopt a more flexible framework that recognises and can interface with a range of international legal systems.
6.2 Cross-border issuance
Cross-border issuance could strengthen the position of the UK as an international financial centre, particularly where it deepens liquidity in the UK secondary market and reduces frictions that are specific to international activity. However, the UK’s openness must be calibrated carefully with the terms of access shaped by material risks around divergent regulatory standards and legal certainty.
6.3 International interoperability and convergence
International interoperability presents a significant challenge for cross-border issuance into the UK, operating at three interacting levels: legal, regulatory, and technological. At the legal level, overseas-issued tokenised assets may carry uncertain status for UK investors. As the Bank for International Settlements (BIS) has identified, the legal and regulatory status of a tokenised asset may differ across jurisdictions, particularly where some adopt token-specific legal frameworks while others apply existing law, raising questions as to whether such assets reflect a legal claim or property right.[footnote 54] At the regulatory level, unconditional inbound issuance could introduce divergent standards into UK markets; where overseas standards are lower or less rigorous, increasing risks to UK investors, introducing compliance challenges for UK firms, and giving rise to regulatory arbitrage risks.[footnote 55] In addition, while the UK Prudential Regulation Authority’s (PRA) 2026 “Dear CEO” letter[footnote 56] defers a consultation on the permanent prudential capital and risk management rules for these holdings until at least 2028, the PRA has announced interim expectations for their prudential treatment. The PRA’s deferral of the permanent framework reflects international, rather than domestic timelines, as the Authorities await the outcome of the Basel Committee’s targeted review of cryptoassets.[footnote 57]
However, this delay risks slowing the convergence of international prudential standards and increasing regulatory fragmentation, as national digital assets frameworks and market infrastructure continue to develop at different speeds. Addressing these gaps calls for a clearer understanding of the respective roles that Governments, the Authorities, standard-setting bodies, and private firms should play across different functional lenses, including asset ownership, securities trading, and payment settlement. The next step will involve exploring how to align these international frameworks.
7. Priorities, recommendations and roadmap
7.1 Vision for the UK
The UK’s growth opportunity extends far beyond simply migrating existing financial instruments onto the new technological infrastructure. Real added value lies in the emergence of digitally native asset classes and programmable assets, rather than tokenised versions of traditional bonds, equities, or funds, alongside innovative market models and new customer segments.[footnote 58] By pairing digitally native and programmable assets with the ongoing digitalisation of traditional global liquidity and digital money, the UK can tokenise at scale, future-proof its financial ecosystem, and solidify its position as an open and global financial centre. Consideration of the differences between digitally native and tokenised assets will be needed to ensure both are designed for explicitly.
Effective prioritisation will be a key driver of success in formulating a national roadmap and catalysing the transition to tokenised markets. An early focus on the UK’s existing strengths, including fixed income, FX and commodity trading, wholesale settlement, asset management, repo and collateral management, custody, and audit and compliance tooling, would allow benefits to accrue quickly and skew economic outcomes towards more winners than losers. If progress is fast, equities should also be brought into scope.
Within these markets, prioritising secondary markets and their supporting infrastructure would target the benefits that matter most: deeper liquidity, transparent price formation, efficient capital utilisation, capital mobility, cross-border flows, issuance, and scalability. Together, these are necessary to unlock the full economic and competitive benefits of tokenisation in the UK’s internationally connected markets.
To deliver on priorities at pace, the UK needs coordinated action across HM Treasury, the Bank of England, the FCA and industry, underpinned by a time-bound roadmap with clear delivery ownership, priority use cases, milestones and success metrics, and a visible link to market development and competitiveness.
Not all parts of wholesale markets will go through that transformation at the same speed. New and legacy infrastructures will inevitably meet in wholesale market lifecycles. The Government and Authorities’ priorities should therefore align closely with the industry’s priorities to ensure that efforts to deliver this transformation, yield the greatest returns and minimise frictions.
7.2 The role of the Wholesale Digital Markets Champion and Taskforce
Over the next 12 months, the members of the Taskforce will seek to deliver the actions outlined below in Section 7.3. These actions have been identified in collaboration with the Taskforce and are designed to target the key priorities that will deliver the overall vision for the UK. These priorities will also require the Government and Authorities to act, and we have set out recommendations for them to support delivery.
At the heart of the Taskforce’s work will be four Action Groups representing the transaction value chain: primary issuance and funds, secondary markets, collateral and prudential standards, and FMI and the cash leg. Inevitably there will be horizontal overlaps between these Action Groups.
To ensure a practical approach that reflects commercial priorities, these actions will help feed an end-to-end repo transaction use case. An Orchestration Group chaired by the Digital Markets Champion will oversee the development of the use case and commission its key components from the Action Groups.
In addition, four Action Groups will be responsible for supporting, cross-cutting issues: tax, legal, financial crime compliance and identity, and resilience. They will support the other Action Groups and deliver best practice guides in parallel. The ninth Action Group on communications will be tasked with coordinating the promotion of the UK as a digital assets centre.
The Action Group structure will be kept under review and adjusted as needed to minimise overlap, ensure coordination, address new issues as they arise. The full Taskforce will also continue to meet periodically. Further detail on the Taskforce architecture, delivery model, members and ways of working can be found in Annex G.
7.3 Priorities, Recommendations and Industry Actions
See Table 1 in the Executive Summary for the table of priorities mapped to the Taskforce Action Groups that will deliver the industry actions.
Clear direction towards scalable, live tokenised markets that drives industry investment
The Authorities, HM Treasury, and industry in the UK have already made a number of significant steps towards this vision, and undertaken a range of pilots and other activities. Now, there is a need to move towards scalable, live markets. Greater certainty and clarity will be critical. HM Treasury, the Authorities and Taskforce should work together to develop a comprehensive roadmap of actions, including challenging interdependent timelines as needed.
The DSS, DIGIT, the Synchronisation Lab and industry initiatives like the GBTD project are strong foundations. Building on the Bank of England’s commitments to deliver a permanent live Synchronisation service and a clear regulatory glidepath out of the DSS, the next step is ensuring a clear route out of live sandboxes and testing grounds into at-scale, regulated activity under lasting, permanent regulatory regimes. It also includes the UK Authorities setting out a plan to ensure that the steady-state CSD settlement regime takes into account the rapid pace of innovation and settlement.
A number of firms have specifically mentioned the perception that US “no action letters” seem more positive and sweeping than the DSS. Whilst this is partly true in terms of scope, US “no action letters” last three years so are not any more permanent. Additionally, the mechanism cannot be directly replicated under UK law, as UK Authorities cannot waive statutory requirements or remove liabilities through “no action” letters.[footnote 59] Instead, formal legislative modifications are required to alter legal frameworks, which is the mechanism used for the DSS. However, “no action“ letters offer a distinct advantage as they allow firms to launch immediately with live products in the active market rather than building exclusively for a live test environment. This dynamic can fundamentally shift the business proposition, lowering the barrier to entry and changing how a business commits capital and resources to innovation.
Significant market developments like the Private Intermittent Securities and Capital Exchange System (PISCES) have been developed and run in a sandbox environment. However, HM Treasury and the Authorities should explore whether the scope of the DSS could be expanded either to give greater scope or greater participation. It would also be interesting to test the appetite of HM Treasury and the Authorities to invite specific organisations, firms or technology providers into the DSS, for example in the way the Depository Trust and Clearing Corporation (DTCC) plays a role now in the US. There are sound reasons for limiting participation to the DSS to firms established in the UK. However, consideration should be given to permitting the participation of overseas firms operating through a UK branch in certain circumstances. For example, there would be value in a firm’s inclusion where they currently undertake a significant volume of the transactions in the UK, and tokenised versions of those transactions are being tested in the DSS.
Conditions required for adoption at scale are often beyond those that are needed for a successful pilot. On DIGIT, for example, technical and operational readiness are potentially sufficient for an initial issuance, but broader investor participation will depend on clarity around long-term commitment to further issuance, supporting market infrastructure and market conventions.
Industry actions:
- Build on the DIGIT pilot to develop the market towards an ecosystem for digital securities, leveraging sector issuances.
- Beyond DIGIT, develop the standards for open, interoperable platforms to broaden investor access.
- Taskforce to deliver and validate end-to-end tokenisation use cases focusing on three priority areas: repo, fixed income and uncleared OTC derivatives.
- Take forward delivery of these use cases through Action Groups, with repo to be the main focus over the next year.
- Build on DIGIT to establish a digital ecosystem for fixed-income, especially through private sector bond issuances.
- Develop the standards for open, interoperable platforms to broaden investor access to trading.
Supporting Actions from Government and Authorities:
- Work with the Taskforce to assess how the regulatory framework for CSDs should evolve to support the wider adoption of tokenisation.
- Build on the success of the DSS and other initiatives by building more predictable pathways from these foundations to full authorisation, market launch and scale.
- Prioritise an immediate pilot issuance of DIGIT no later than Q1 2027, and the development of further DIGIT issuances over the medium term. Working with the sector, these should demonstrate successful live secondary market trading of those instruments and encourage investment in infrastructure by industry.
Tokenised collateral to support the development of tokenised markets
The UK needs to deliver the scaling of priority use cases to build confidence and develop industry-wide expertise. Extensive industry engagement including with the Taskforce has clarified that repo is a clear candidate. It is a foundational element for scaling tokenisation in secondary markets and provides the greatest scope for improved efficiencies. The potential gain is significant, as set out in Section 4.2 of this report.
Bilateral repo transactions have already taken place on-chain, but the next step to scale the use case is end-to-end, ecosystem-wide transactions involving FMIs, and full lifecycle management is needed to enable the benefits of secondary market digitalisation. To scale, key building blocks include recognition of tokenised assets as collateral under the UK regulatory framework, and greater clarity on the use of public blockchain networks for regulated repo transactions.
Industry actions:
- Build collaborative wider ecosystem solutions from existing bilateral use cases.
- Taskforce to deliver and validate end-to-end repo use case to support scaling, using DIGIT and/or privately issued assets depending on availability and suitability.
Supporting Actions from Government and Authorities
- The Bank of England should be prepared to accept DIGIT as collateral in the Sterling Monetary Framework.
- The Bank of England should consider broader acceptability of tokenised collateral in the market, for example for the use of CCPs.
Establishment of a tokenised funds market
Building a sustainable tokenised market requires not only institutional adoption but credible pathways linking fund architecture and end investors. Tokenising investment funds can broaden market access through fractionalisation, flexible product design, and digital distribution channels – lowering investment thresholds and opening new asset classes to those of small means. However, these benefits will only materialise if wholesale market infrastructure is designed with distribution and end-investor access in mind from the outset.
The UK is uniquely positioned to leverage its global strength in fund management and retail distribution to bridge this gap. This is no longer a purely conceptual exercise; pioneering industry initiatives, such as Baillie Gifford’s launch of a fully native, UK-regulated on chain fund,[footnote 60] have proven that live deployment is available today. The next critical step for the wider market is to move beyond these initial, standalone implementations and establish broad operational scalability.
The IA’s ongoing Investment Fund 3.0 (IF3) work, alongside the City Minister’s Investment Management Taskforce, underscores the need for existing norms to evolve into scalable, industry-wide models. To drive this next phase, the industry must develop a broader range of live use cases through the IA’s IF3 Lab. This targeted execution will establish the common operational and market practices required to demonstrate true scalability across the ecosystem. This work will show how tokenised assets can practically integrate into day-to-day portfolio management, risk frameworks, and standard fund distribution networks.
Industry actions:
Through the IA’s IF3Lab, develop funds use cases to:
- Establish common operational and market practices.
- Demonstrate scalability.
Supporting Actions from Government and Authorities
- Maintain close engagement with industry through the City Minister’s Investment Management Taskforce to ensure they keep pace with evolving market developments in the asset management sector.
- Provide guidance as needed based on evidence emerging from implementation.
Wholesale payment rails that support tokenised markets
The transfer of digital assets will need to be matched with a corresponding, secure payment leg. Without payment rails, tokenisation at scale will simply not succeed.
The Bank of England’s modernised RTGS service is central to this, enabling real-time settlement in central bank money – the ultimate risk-free settlement asset.
Industry engagement points towards accelerating a multi-money, multi-currency and multi-asset ecosystem in the UK, in which central bank money continues to anchor settlement finality and financial stability. Like most international jurisdictions, this diverse approach includes tokenised deposits as well as stablecoins.
Within this model, future arrangements must ensure interoperability across different forms of money, and a solution for cash-leg settlement in central bank money via RTGS. This includes tokenised deposits, stablecoins, and other emerging instruments, depending on the use case. Achieving this interoperability will be critical to unlocking end-to-end tokenised transactions.
The Bank of England is enhancing RTGS and its access frameworks to support this transition, including through:
- Omnibus Accounts launched in 2022, enabling tokenised central bank money for wholesale settlement;
- Planning to launch a synchronisation service in 2028;[footnote 61]
- Consulting on extending RTGS and CHAPS settlement to near 24/7 operation; and
- Ongoing experimentation to build practical evidence on how new technologies and market designs can inform its infrastructure.
Together, these initiatives provide a pathway towards more flexible, near-continuous settlement in central bank money, supporting a range of use cases.
Alongside this, commercial banks are developing tokenised deposits through the Great British Tokenised Deposit (GBTD). This latter initiative is exceptionally important to the UK.
Supporting a multi-money, multi-asset ecosystem will also need greater regulatory certainty on payments, including on the role of stablecoins as a wholesale capital market settlement tool and its role in cross-border trade in particular. The FCA’s final rules on UK stablecoins and the Bank of England’s June 2026 Policy Statement on sterling-denominated systemic stablecoins provides a path towards this.[footnote 62]
Industry actions:
- Continue to build GBTD at scale.
- Build end-to-end tokenisation use cases that work across both existing and new payment rails.
- Develop shared token standards, common APIs and data models (including through the Common Domain Model) to deliver interoperability.
Supporting Actions from Government and Authorities:
- Ensure infrastructure and regulatory policy supports settlement of tokenised assets using different forms of money (including stablecoins and tokenised deposits).
- Develop models to allow settlement directly in central bank money via RTGS, such as through Synchronisation.
Legal certainty and best practice to remove perceived and real obstacles
The UK starts from a strong legal foundation,[footnote 63] and should build on this to clarify how tokenisation of securities, collateral treatment, custody arrangements, and settlement outcomes will hold up in practice. The priority should therefore be to translate this broad legal certainty into a greater level of awareness of work already carried out in the legal sector and operational certainty.
Some of this can be achieved by industry in developing best practice to support the transition. Time and again in the Taskforce we heard firms were uncertain if they can act, only for another firm to reveal they were delivering solutions and the legal tools already existed.
Industry Actions:
- Develop best practice frameworks, including for contracts under English Law (for example through the ICMA’s digital Bond Data Taxonomy).[footnote 64]
- Identify issues that are blocking industry development and raise with the Authorities.
- Promote that English law accommodates innovation and, where needed, develop myth-busting narratives where there are misconceptions.
Supporting Actions from Government and Authorities:
- Support industry where it requires greater legal certainty.
Regulatory standards that support tokenised markets
There is also a big agenda for policy makers in this space. Running through the whole theme of legal certainty are regulatory standards. We expect these to be tackled by the respective Action Group chairs.
As a matter of priority, industry requires greater clarity regarding collateral treatment and settlement finality in relation to tokenised assets. Improved understanding is also needed on prudential treatment, custody and client asset treatment, the interaction with the various UK reporting regimes and the legal status of tokenised securities.
In addition to legal and regulatory clarity, adoption will need to be supported by the development of market practice notes, standardised documentation and pragmatic guidance tools that help firms translate legal certainty into operational implementation during the transition.[footnote 65]
Industry Actions:
- Collaborate with HM Treasury and the Authorities to identify pinch-points.
Supporting Actions from Government and Authorities:
- Ensure that the UK’s regulatory regime provides comprehensive support for digital innovation, including its integration with traditional markets, without extending the regulatory envelope.
Table 2: Areas in need of greater legal and regulatory certainty
| Policy area/instrument | Responsible authority |
|---|---|
| Dematerialisation of securities, primarily the tokenisation of equities (miscellaneous legislative amendments). | HM Treasury (HMT) |
| Clarify the eligibility of tokenised assets as collateral in the Sterling Monetary Framework (SMF). | BoE |
| Review CSD Regulation to take account of the rapid pace of innovation, addressing new risks and allowing for new business models where appropriate. | HMT, BoE, FCA |
| Settlement Finality Regulations – amend where needed to ensure technological neutrality and if not dealt with separately under the DSS. | HMT, BoE |
| PRA Framework for prudential treatment of firms exposures to crypto assets. | PRA |
| Finalise the remaining elements of the stablecoin regime.[footnote 66] | HMT, BoE, FCA |
| Finalise policy in relation to custody of digital assets. | HMT, FCA |
| Crypto resolution regime. | FCA |
Standards that support domestic and international interoperability and convergence
Interoperability, the seamless interaction between institutions, platforms, and infrastructure, continues to be recognised as a critical constraint to scaling the tokenisation ecosystem.
It is essential for enabling the efficient flow of trades, data, collateral and payments across on- and off-chain environments without friction or duplication.
This is also critical for collateral mobilisation, given that market participants are likely to hold collateral across multiple DLT platforms.
The role and function of some of these infrastructures – trading venues, central counterparties, CSDs, custodians, payment systems - may evolve as the transition progresses. However, the underlying requirement for seamless connectivity remains. Without connectivity underpinned by common specifications and rules, “walled gardens” can emerge.
This can jeopardise liquidity, fungibility, scalability and efficiency, particularly where transactions transition between on- and off-chain systems.
There is strong consensus across the industry that standards, rather than any particular technology, are key to achieving interoperability. The standards are shaped and enforced across several layers of governance in the financial services ecosystem. These include global and national standardsetting bodies, financial market infrastructures, regulatory and supervisory authorities, and firmlevel implementation frameworks.
Achieving interoperability depends on common messaging standards, identifiers, Application Programming Interfaces (APIs), and data model standards that support connectivity. Yet, fragmentation is already emerging in these areas.[footnote 67] Bridging solutions can provide a short-term remedy, but these can introduce additional operational, technological and cyber risks. Addressing these challenges requires a broad and coordinated approach.
International
International cooperation is essential to unlock the full potential of digital assets, which depend on deep, cross-border liquidity only achievable in an interconnected digital economy. Without global interoperability, capital flows risk being constrained and liquidity fragmented.[footnote 68]
We have found that international standard setters are lagging behind market developments.[footnote 69] The UK has an opportunity to develop effective standards specifically across legal recognition, settlement finality, custody, compliance, messaging, data and tokenised cash settlement to support its domestic ambition for secondary markets and international interoperability.
Industry actions:
- Lead on the development of domestic interoperability standards that support transaction flows, including APIs, common messaging protocols, reference data models,[footnote 70] and data standards.[footnote 71] Produce governance frameworks to oversee the development, adoption and maintenance of these standards (including through the Common Domain Model).
- Where shared industry standards are not possible, adopt other solutions (e.g. interoperability layers, orchestrators) to allow DLT-based ledgers to interact with existing settlement infrastructure and each other.
Supporting Actions from Government and Authorities:
- Adopt a proportionate and technology neutral principle-based approach that supports, where appropriate, the introduction of new services by existing FMIs, or new entrants to become FMIs, to drive further innovation in the sector.
- Support industry-led functional standard setting for interoperability, in line with established regulatory expectations.
Effective Financial Crime Compliance (FCC) and digital identity
Financial Crime, Anti-Money Laundering (AML), Sanctions Compliance and Know Your Customer (KYC)
Current implementation of KYC, AML, and sanctions compliance obligations, which are national and, in some instances, extraterritorial, is presenting structural challenges for some UK firms that can create frictions for cross-border activity.[footnote 72] Issues include the untimely verification of compliance data delaying the transfer of an asset, a lack of cross-platform and cross-border compliance procedures, and little guidance for firms implementing DLT-oriented procedures. This creates demand for novel interventions that support the industry’s compliance efforts. Whilst technological solutions developed by industry, including digital identity and programmable compliance, are fast evolving, compliance remains complex. Development in digital verification frameworks, for example, offer a pathway to address FCC compliance challenges by enabling reusable, trusted identity credentials that can be leveraged across institutions, reducing duplication in KYC processes and improving data quality.[footnote 73] A coordinated Digital Verification Service could also support interoperability across jurisdictions, helping to streamline onboarding, lower compliance costs, and reduce cross-border transaction frictions.
Fostering trust between firms and avoiding forced identity checks at every layer of infrastructure should be a key objective when developing interoperable compliance frameworks. Industry should progress this work through existing structures - for example by tasking the UK Finance Money Laundering Advisory Panel (MLAP) with coordinating an Action Group. Where feasible, these efforts should be supported through the DSS or sandbox testing. Findings should then inform engagement with the Financial Action Task Force (FATF), the Authorities and HM Treasury to ensure regulatory implementation supports innovation while minimising frictions.[footnote 74]
Industry Actions:
- Develop solutions and best practice to close the ‘lag’ of any tokenised asset’s compliance data moving between platforms and its associated asset (KYC, AML, sanctions screening).
- Develop and test interoperable compliance frameworks, including benchmarking standards across jurisdictions, and propose mechanisms such as safe harbours.
- Support digital verification by building on pre-existing industry-led initiatives that leverage trusted standards for identity credentials and data quality.
Supporting Actions from Government and Authorities:
- Ensure domestic and global regulations on financial crime are fit for DLT.
- Support the development of industry standards on digital verification and identity.
A technology neutral approach to tax
A clear and consistent tax framework to support the digitalisation of wholesale financial markets is essential, considering how quickly digitalised assets and markets are developing. The UK needs a transparent system which handles complexity directly, rather than case-by-case guidance and support which is time-consuming and provides little transparency for other participants.
Given the pace of change in tokenisation, achieving clarity in tax requires a collaborative, phased approach between Government, Authorities and industry. Much clarity could be gained by embedding the principle of technological neutrality in the tax treatment of financial assets in legislation and guidance.
International
Whilst the Government must address the domestic need, it should also collaborate with global peers to ensure domestic and international reporting and taxation requirements do not create dual obligations for firms or reduce efficiency. Industry can also assist in identifying those risks as they arise.
Industry actions:
- Contribute to the development of technologically neutral tax frameworks by considering relevant accounting standards, including any insights from end-to-end tokenisation use cases, and through existing industry working groups.
Supporting Actions from Government and Authorities:
- Embed tech-neutrality for tax treatment of digital assets into legislation and guidance.
Resilience through collaboration between industry and the Authorities
Cyber-attacks, outage scenarios, and fragmented liquidity represent significant operational risks. As digital asset infrastructure becomes increasingly critical to financial markets, ensuring their resilience as plausible targets for malign actors, including hostile states, and as exposed to market shocks demands novel responses to fresh challenges that Authorities are not accustomed to.[footnote 75] [footnote 76]
Industry action should address these risks by driving the design of proportionate regulation, industry-led standards to avoid gaps between principles and their application, supervisory capability and international cooperation without slowing market development.
Coordinated work should focus on testing protocols and responsiveness to threats, creating certainty around default management frameworks, and building a resilience programme to evaluate cross-network preparedness and close critical gaps.
Industry Action:
- Deliver a coordinated testing and resilience programme for cross-network components.
Supporting Actions from Government and Authorities:
- Adapt existing principles, consistent with their statutory objectives, to underpin resilience in tokenised markets, as part of a broader set of standards and practices applied by firms.
7.4 Conclusion and roadmap for delivery
There is plenty to be done, and as this report has outlined, a need for pragmatic and practical action at pace.
Work has already commenced to assemble the Action Groups across industry, with Action Group members and their Chairs in the process of confirmation. Their membership and precise tasks will be finalised in September 2026. Each group will have a detailed timeline and specific deliverables with identified milestones. The full Taskforce will assemble periodically over the course of the year, to allow for collaboration across the Action Groups and knowledge-sharing.
Feedback and comments on this report are very welcome from industry, especially from those who have not been engaged in this work to date, to ensure the proposed programme of work accurately reflects the priorities of the sector. All feedback should be sent to DigitalMarketsChampion@cityoflondon.gov.uk by 4 September 2026.
We expect the Action Groups to make meaningful progress by the end of 2026. Many of the immediate use cases and actions may skew towards fixed income as an area of the market that is advanced in its thinking and scale for the UK. We will consider the possibility of exploring additional asset classes, such as commodities, across the course of the year.
We will also establish the repo use case, with an aim of completing as much as possible to test and ideally run a live trial by spring 2027.
The Taskforce will provide regular updates on its progress on www.theglobalcity.uk/digital-markets-champion.
The second report will focus on delivery, setting out what will have been achieved over the next year, and how industry, Authorities and Government can capitalise on this progress.
The opportunity is clear, the foundations are in place, and now the task is to move from pilots to scale, from ambition to action, and from participation to leadership.
8. Annex A: Definitions
Tokenisation will likely transform all parts of the wholesale capital markets value chain and life cycle activities for existing financial assets by harnessing DLT. New classes of digitally native assets will also emerge. Table 3 below sets out definitions of forms of tokenisation and related technologies.
Table 3: Definitions of common terms
| Term | Definitions |
|---|---|
| Tokenisation | Digital representation of assets using distributed ledger technology (DLT).[footnote 77] |
| Tokenised deposits | Digital representation of traditional commercial bank money. They retain the trust and regulatory protections of conventional deposits, while offering benefits such as enhanced speed and fraud protection.[footnote 78] |
| Tokenised funds | A fund where shares or units in the fund, or a feeder fund for it, are digitally represented and can be traded and recorded using DLT or blockchain. It uses code to mimic the functionalities of a traditional fund and replaces shares or units with tokens. It is not a form of uncertificated security recorded by the fund itself, but by the DLT ledger. May also be known as a digital fund or a BTF (blockchain-traded fund).[footnote 79] |
| Tokenised markets | Tokenised markets refer to segments of financial markets in which assets, including securities, funds, deposits, or settlement instruments. |
| Tokenised securities | Digital representation of existing traditional securities, as well as securities issued only on DLT that have new features (such as programmability) and that are dependent on the design of each token.[footnote 80] |
| Regulated stablecoins | The term stablecoin commonly refers to a cryptoasset which is backed by a mixture of bank deposits and other highly liquid assets in order to maintain value at par with other forms of money (a ‘fiat stablecoin’, or ‘qualifying stablecoin’ in UK regulations). While only fiat stablecoins typically fall in-scope of regulations, a stablecoin issuer can also employ algorithmic or other means to stabilise or impact its market value by, for example, automatically adjusting its supply in response to changes in demand.[footnote 81] |
| Central bank digital currency (CBDC) | A central bank digital currency (CBDC) is money that a country’s central bank can issue in digital (or electronic) form, rather than as physical money, such as cash and coins. For example, in the UK this digital money (a “digital pound”) would be issued by the Bank of England. It would hold the same value as physical money and could be used in similar ways as money stored in a bank account and be used for everyday payments.[footnote 82] |
| Delivery-versus-Payment (DVP) | A DVP mechanism links a funds transfer (payment) system and a securities transfer (delivery) system to ensure delivery occurs if and only if payment occurs. Currently, by linking the delivery of securities and payments of funds in a CSD, securities and funds move simultaneously.[footnote 83] |
| Distributed ledger technology (DLT) | Distributed ledger technology is the infrastructure and protocols (rules) that allow independent computers (nodes) in different locations to propose and validate transactions. DLT systems and processes allow computers to update records in a synchronised way across a DLT network. A distributed ledger is a common record of information that is shared across multiple locations. DLT is formed of a network of independent computers – if a record is updated on one of those computers, then the records across all the computers that are part of the network also get updated. DLT allows information, including records of transactions, to be stored securely using cryptography. The protocols are the rules of the distributed ledger. They define how records are added, validated and synchronised. Protocols also validate the rights of a digital asset.[footnote 84] |
9. Annex B: Examples of regulated activity today
Regulated firms are already operating in these markets today, under permissions that already exist, across trading, clearing, custody, banking, prime brokerage, payments and asset management.
Trading and clearing venues
Crypto Facilities Ltd (Kraken) - FCA-authorised investment firm (FRN 757895); the first FCA-authorised crypto multilateral trading facility (MTF) (2020); launched crypto derivatives for UK professional clients in May 2025.
GFO-X – the first FCA-authorised, centrally cleared MTF for digital-asset derivatives, cleared through LCH; live since May 2025, with ABN AMRO Clearing, Nomura International and Standard Chartered as founding clearing members.
Banks and FSMA regulated firms, under existing permissions
Standard Chartered Bank - institutional spot Bitcoin (BTC) and Ethereum (ETH) trading from its UK branch (launched July 2025, within the FX division), under its banking authorisation; also registered as a cryptoasset firm. Group entities Zodia Custody and Zodia Markets are separately registered.
BlackRock International – registered cryptoasset firm (April 2025), acting as arranger for its iShares crypto exchange-traded products.
Hidden Road / Ripple Prime – holds both an FCA investment-firm licence and FCA cryptoasset registration, covering spot and derivatives across FX and digital assets.
Interactive Brokers (UK) – FSMA-authorised firms that also carry cryptoasset registration.
Payments and cryptoasset permissions on a single regulated entity
Coinbase / CB Payments (e-money institution plus cryptoasset registration)
PayPal UK (e-money, consumer credit and cryptoasset registration) Revolut (e-money institution plus cryptoasset registration)
ClearToken Depository (Authorised Payment Institution under the Payment Services Regulations 2017, plus cryptoasset registration)
Fnality’s live wholesale settlement asset which uses the Bank of England’s Omnibus account.
The wider population
Over 50 firms hold live cryptoasset registrations under the Money Laundering Regulations, spanning exchanges, custodians, brokers and asset managers – most migrating to full Part4A authorisation by October 2027.
10. Annex C: Notable tokenisation initiatives in the UK
Digital Gilt Instrument (DIGIT) pilot
The Digital Gilt Instrument (DIGIT) programme will see the Government’s pilot issuance of a sovereign digital debt instrument using DLT within the Digital Securities Sandbox (DSS). This positions the UK as a global leader, and the first G7 country to tokenise sovereign debt.
Digital Securities Sandbox (DSS)
The DSS, a joint initiative by the Bank of England and the FCA, enables firms to test and adopt DLT for digital securities in a controlled live setting. To date, commercial deployment of digital wholesale financial assets in the UK remains limited. While 16 firms are currently participating in the DSS, they have only entered the testing stage (“Gate 1”). Firms must progress to “Gate 2” before carrying out live business under initial limits. Authorities have committed to delivering a pathway for firms outside of the DSS, for firms who wish to become permanently authorised FMIs.[footnote 85]
The DSS is complementary to a number of other BoE initiatives, such as the Synchronisation Lab. The Lab provides a route for DSS firms to test settlement of digital-security transactions in sterling central bank money. The GBTD project is also an approved participant in the Synchronisation Lab.
Great British Tokenised Deposit (GBTD)
The GBTD is a new private sector-led platform enabling different banks’ tokenised deposits to interact – ensuring that programmable commercial bank money is able to support a range of wholesale and retail use cases.
Tokenised Fund Blueprint; FCA Fund Tokenisation Policy Statement
In late 2023, the Investment Association and the asset management industry developed a blueprint for tokenising investment funds. After the first tokenised UK open-ended investment company (OEIC) launched, this evolved into detailed industry guidance which ultimately informed the FCA’s Fund Tokenisation Policy Statement (PS 26/7).[footnote 86] An optional settlement mechanism, Direct 2 Fund (D2F), was introduced to enable settlement without the Authorised Fund Manager acting as an intermediary. The IA’s IF3 Lab is progressing fund tokenisation use cases while simultaneously working on the tech-powered future retail investment journey via the City Minister’s Investment Management Taskforce.
Digitisation Taskforce
The Digitisation Taskforce (2022–25), established by HM Treasury and chaired by Sir Douglas Flint, aimed to fully digitise the UK’s shareholding system by removing paper certificates and strengthening the intermediated ownership model. The Government has accepted its recommendations in full and is moving to implementation. While focused on equity infrastructure, the Digitisation Taskforce forms a core part of the UK’s wider capital markets modernisation agenda, laying the foundations for digital communication, payment systems, and ownership records to support future market developments.
Dematerialisation Market Action Taskforce
The Dematerialisation Market Action Taskforce (DEMAT), established by HM Treasury and chaired by Mark Austin CBE, has been tasked with taking forward and implementing the recommendations of Sir Douglas Flint’s Digitisation Taskforce. It is focused on delivering the transition from paper-based to fully electronic shareholdings through detailed standards, timelines, and market processes. While centred on equity markets, DEMAT is intended to embed these reforms within the UK’s broader capital markets modernisation agenda, supporting the move to fully digital communication, payment mechanisms, and ownership records for future market developments.
In July 2026, the DEMAT published a report to the Chancellor recommending 4 January 2028 as the date from which paper share certificates will cease to be legal proof of ownership and will be replaced by digital registers for shareholders who wish to hold shares directly. It also provides a practical roadmap for implementing this transition. In parallel, work has started with market participants on the next phases of shareholding reform, and the report outlines initial observations and issues that will be examined further in DEMAT’s second report next year.
Digital Markets Taskforce
Andrew Douglas chaired the industry-led Digital Markets Taskforce (DMT), a group created to develop single, coherent “Digital Vision” for the UK. Looking out at a 10-year horizon, the group mapped what the UK wholesale market should look like by 2036. The membership brings together a mix of traditional finance, decentralised finance, and trade associations, reflecting the need to bridge legacy infrastructure with emerging technologies. In 2026 the Taskforce was merged into the new Digital Markets Champion Industry Taskforce.
Accelerated Settlement Taskforce
The Accelerated Settlement Taskforce (AST) was formed in December 2022, established by HM Treasury and chaired by Charlie Geffen, to explore the potential for faster settlement of securities trades in the UK. The taskforce’s report was published in 2024 committing to move from a T+2 to a T+1 settlement cycle. The Government has accepted all the recommendations and appointed Andrew Douglas to chair the Technical Group to take forward the next phase of work.
Legal
The UK has engaged through the Law Commission,[footnote 87] [footnote 88] [footnote 89] Parliament,[footnote 90] [footnote 91] HM Treasury,[footnote 92] the FCA and Bank of England,[footnote 93] UK Jurisdiction Taskforce94 and industry bodies,[footnote 95] actively laying the legal and regulatory foundations for tokenised markets.[footnote 96]
Importantly, this certainty has largely been achieved through principles-based and common law-led approach.
The UK has adopted primary legislation to empower HM Treasury and the Authorities to clarify how the financial services regulatory perimeter applies to digital assets, to provide for stablecoins as a digital settlement asset, to establish financial market infrastructure sandboxes, to enable the digitalisation of trade documents, and to provide legal certainty that digital assets are not prevented from attracting property rights.[footnote 97]
HM Treasury, the FCA and the Bank of England have also set out an extensive set of secondary legislation, rules and guidance aimed at establishing the regulatory perimeter for digital assets, setting out regimes for admissions, disclosures, market abuse, an AML framework, prudential and conduct requirements, adapting legislation to allow for a digital sovereign bond, plus rules and guidance to enable use of DLT by authorised funds.[footnote 98]
The Law Commission has spearheaded research into smart contracts, digital asset ownership, insolvency, private international law and has built up a body of materials to inform industry activity. The Law Commission found that the current legal framework in England and Wales is clearly able to facilitate and support the use of smart legal contracts, without the need for statutory law reform. It also made recommendations including on ways to take security over tokenised securities.[footnote 99]
The UK Jurisdiction Taskforce has issued a Legal Statement on how English law enables the issuance of tokenised securities, and published reports on how the concept of control applies in practice to help ascertain ownership of digital assets and on the insolvency law implications of digital assets under English law.[footnote 100]
National Payments Vision
The UK Government’s National Payments Vision (“the Vision”) sets out a strategy to deliver a trusted, world-leading payments ecosystem built on next generation technologies. It aims to support economic growth by strengthening payments infrastructure, reducing regulatory fragmentation, promoting innovation and competition, and maintaining high standards of consumer protection. The Vision highlights the transformative potential of technologies such as DLT, artificial intelligence, and enhanced data sharing, while supporting initiatives such as Open Banking, account-to-account payments, and exploration of a digital pound CBDC. It will be implemented through close collaboration between Government, HM Treasury and the Authorities, and industry.[footnote 101]
11. Annex D: Opportunities and threats
Within the new tokenised landscape, we can already see that new opportunities and threats are emerging. The following annex gives a broad sense of the scale of these.
DLT, and particularly its application to tokenised financial markets, has engendered new firms with newly defined roles within that ecosystem. Some of these firms have already been phenomenally successful and stand to gain more, although challenges still exist, as outlined in Table 4 below.
Table 4: Opportunities and threats to the FinTechs and Crypto infrastructure
| Sector | Opportunities | Threats |
|---|---|---|
| Digital Asset Financial Markets Infrastructure | • Lower cost models designed for crypto, extended to stablecoins and now onboarding tokenised financial products • Global connectivity and, often, both retail and wholesale liquidity by design |
• Lower trust and scale in traditional products may slow growth as existing markets infrastructure adopts tokenised products • With some exceptions, low growth in retail participation may limit adoption in wholesale markets |
| Digital Asset Custodians | • Optimised models for digital assets custody with the necessary emphasis on technology and key management • First mover, scaled advantage and regulatory requirements support the need for third party custody |
• Self-custody solutions may increasingly scale as viable, regulatory compliant alternatives • Existing custodians with institutional trust could extend to digital assets |
| Digital Asset Infrastructure (Blockchains / Oracles) | • Significant growth opportunities as usage grows with tokenisation | • Significant competition means likely not all firms will win and there will be consolidation or a smaller number of platforms operating as walled gardens where there are network effects • Innovation continues at pace and new, more effective protocols will emerge |
| Broader (Financial Markets Relevant) Crypto Firms | • Other specialised firms such as crypto cyber security specialists, staking providers and DeFi protocols have a critical role to support trust and efficiency in wholesale markets. Developing this expertise in the UK creates opportunities for UK Fintechs |
Within the financial services sector, there are a number of dynamics which will create threats and opportunities to market participants, outlined in Table 5 below.
Table 5: Opportunities and threats to Fintechs and Crypto infrastructure
| Sector | Opportunities | Threats |
|---|---|---|
| Asset & Wealth Managers | • Operational efficiencies in settlement speed and cost from blockchain • Broader secondary market access to private markets • Composable finance with the opportunity to customise portfolio compositions for clients with algorithmic / programmable investment strategies • Greater value ascribed to qualified advice and market analysis where consumers look for trust |
• Disintermediation and an imperative to innovate to maintain margin given customers may increasingly adopt direct access to investments • Potential for banks or other financial services firms to increasingly embed asset management capabilities to avoid deposit flight • Lower barriers to entry by AI-powered challengers |
| Retail banks | • Faster, cheaper cross-border payments • More automated, programmable 24/7 banking • Transparent, cost-effective lending and deposit mobility • Potential for universal banks which offer brokerage and investment services to enhance customer experience and create more sticky client relationships |
• More mobile money runs the risk of deposit flight over time or, in a crisis, as a more pronounced bank run • Implication of deposit flight on the potential provision of credit and Net Interest Margin (NIM) dynamics for a traditional bank business |
| Commercial banks | • Faster and cheaper global transaction banking using digital payment rails and an ability to ‘own’ the transition through integrated traditional and tokenised payment rails • Greater collateral mobility offering funding and liquidity benefits • Operational efficiencies and balance sheet velocity enhancements from tokenised lending and securitisations allowing better risk recycling • Programmable treasury and options for enhanced customer engagement on supported services |
• Similar challenges to retail banks on corporate deposits if yield-bearing, low-risk rapidly liquidatable products are accessible in tokenised form • Potential disintermediation from agile challenger banks and technology-supported in-house strategies by clients • Greater price competition where increased transparency enables more mobile client money and decision making |
| Investment banks | • Collateral mobility frees up funding and liquidity, allowing greater credit provision and use of resources • Opportunities to extend market connectivity to tokenised credit and equities with new venues, liquidity sources and different volatility dynamics driving growth • Reduced settlement risk • Increased retail participation in capital markets providing more liquidity • Potential for future automation of derivative contracts with programmable payments reducing operational overheads • Different options and market dynamics for equity capital markets (ECM) / debt capital markets (DCM) extending advisory services |
• Threat of disintermediation by challengers adopting a low cost, tokenised product-only model • Firms may opt to self-service DCM / ECM activities leveraging similar models to ICOs (Initial Coin Offerings) • Dangers of market dislocations where liquidity is fragmented across multiple venues and product formats |
| Exchanges | • Opportunity to extend product coverage • Natively tokenised equities would need well governed, supporting exchange infrastructure • Potential broadening of international coverage and easier listing of natively tokenised stock |
• Threat of migration of activity to digital asset native exchanges and decentralised exchanges who can compete at lower cost in tokenised markets • Intensified international competition between exchanges |
| Payment intermediaries | • Effective integration of tokenised payment rails will provide new competition and cement providers as critical interfaces • Usage of digital money may provide operational efficiencies for parts of the payment value chain reducing cost |
• Threat of disintermediation by challengers, banks or other firms using their own digital money solutions • Threat of competition from outside financial services with corporates, for example ecommerce, internalising tokenised payments solutions and moving volume outside traditional networks |
| Clearing and settlement | • Growth of tokenised term product clearing as repo / derivative markets mature • Likely continued important role for FX and other settlement agents given the netting and compression provided |
• New entrants will challenge existing firms • Faster on-chain settlement may remove the need for settlement intermediaries in many asset classes |
| Private equity | • Tokenised markets provide a route to easy admission of funds to secondary markets and associated price transparency / liquidity • Potential for easier incorporation of funds and structuring of solutions |
• Greater competition and market compression with lower barriers |
12. Annex E: International state of play
EU
The EU has adopted one of the most developed supranational regulatory frameworks for tokenisation internationally but has pursued a regulatory harmonisation model centred on market integration rather than commercial deployment. Through the DLT Pilot Regime, the EU has sought to establish a common framework for tokenised securities markets and DLT based market infrastructure across Member States.[footnote 102] Tokenisation has therefore been positioned less as a discrete market initiative and more as part of broader efforts towards capital market integration and competitiveness under the Capital Markets Union agenda.
At present, activity under the EU DLT Pilot Regime remains largely experimental and has not yet reached scale, either domestically or cross-border. While the regime was explicitly designed to facilitate cross-border DLT market infrastructure and market integration across Member States, adoption has thus far remained comparatively limited with only three DLT market infrastructures authorised under the scheme as of 31 May 2025.[footnote 103]
Ultimately, barriers to a more mature tokenisation structure include continued market fragmentation, interoperability constraints and the absence of sufficiently integrated market infrastructure across Member States. Echoing wider industry concerns, the Association for Financial Markets in Europe (AFME) has similarly argued that the EU tokenisation framework remains constrained by restrictive settlement caps, fragmented liquidity pools, interoperability limitations and the continued reliance on legacy settlement architectures, creating a risk that the regime remains a “niche sandbox” rather than evolving into scalable market infrastructure.[footnote 104]
Hong Kong
Hong Kong has followed a model of controlled scaling rather than open market liberalisation. The Hong Kong Monetary Authority (HKMA) and the Securities and Futures Commission (SFC) have enabled activity across tokenised securities, tokenised SFC-authorised investment products, secondary trading of tokenised products, stablecoins, digital bonds and tokenised deposit settlement. Access remains channelled through licensed firms, prior regulatory engagement and specific safeguards. Hong Kong is therefore a useful comparator for the UK because it shows how a jurisdiction can move from policy intent to live initiatives while keeping close control over market access.
The strongest evidence of real commercial activity is in digital bonds. The HKMA’s Project Evergreen followed Project Genesis in 2021 and supported real money Government green bond issuances from 2023. The first issuance tested DLT across the bond lifecycle, including primary issuance, secondary trading settlement, coupon payment and maturity redemption. It also shortened the primary settlement cycle from the typical T+5 to T+1. In 2024, Hong Kong issued around 6 billion HKD-equivalent of digital green bonds across HKD, Renminbi (RMB), USD and EUR, attracting global investors. In November 2025, the Government priced around 10 billion HKD -equivalent of digital green bonds, which the HKMA described as the largest digital bond issuance in the world to date. This is a real proof point, but one which involves Government-led issuance rather than private sector cross-border issuance at scale.
The main cross-border mechanism involves shared liquidity, not full interoperability. In November 2025, the SFC allowed licensed virtual asset trading platforms (VATPs) to integrate order books with affiliated overseas platforms, creating a shared liquidity pool. This seeks to bring global liquidity into Hong Kong while keeping client access inside the domestic regulatory perimeter. The conditions are stringent. Overseas affiliate platforms must be appropriately regulated, orders must be fully prefunded, settlement must follow delivery versus payment principles, compensation arrangements must be in place and market surveillance must cover the shared order book. Hong Kong is therefore not making every token usable everywhere but rather importing liquidity through controlled platform linkages.
Beyond the scope of this report, Hong Kong has also opened the perimeter for tokenised funds and investment products to retail investors. As of March 2026, 13 tokenised products were offered to the public in Hong Kong, with assets under management of tokenised classes increasing around sevenfold to HKD 10.7 billion over the previous year. In April 2026, the SFC confirmed requirements for secondary trading of tokenised SFC authorised investment products by the public on licensed VATPs. This moved the policy question from issuance to tradability. The framework continues to uphold high standards: product providers must consult the SFC, maintain ownership records, manage operational risks and support fair pricing, market making and liquidity monitoring. The SFC also highlights risks around thin trading, price deviation from net asset value, price fragmentation and reliance on market makers.
Luxembourg
Luxembourg has pursued a commercially-oriented model centred on incremental integration rather than wholesale market redesign. Through successive blockchain laws, Luxembourg has progressively embedded tokenisation within its existing investment fund, securities and asset servicing ecosystem, which covers a mix of retail/institutional and wholesale use cases, providing legal certainty around tokenised fund units and DLT based ownership structures. Tokenisation has therefore been positioned less as a standalone market infrastructure initiative and more as an extension of Luxembourg’s established fund ecosystem, reinforcing its role as a cross-border asset servicing centre.
At present, Luxembourg’s adaptive approach to tokenisation is increasingly viewed internally as a source of strategic strength. As noted by Laurent Marochini, Chief Executive Officer of Standard Chartered Luxembourg, the “legislative arsenal put in place by Luxembourg ensures a true competitive advantage”.
As such, while tokenisation initiatives are not yet at scale, we are seeing firms exploring how to integrate digital assets into Luxembourg’s existing cross-border fund distribution ecosystem, potentially preserving Luxembourg’s status as a leading domicile for European asset managers into a digitalised future. Clear evidence of this can be seen via international asset managers, including Franklin Templeton exploring tokenised fund structures within Luxembourg vehicles alongside initiatives such as FundsDLT that embeds tokenisation within existing cross-border fund distribution infrastructure. Having said this, Luxembourg’s adoption progress remains selective, with the principal constraints related to ecosystem integration, interoperability and the need for industry players to adapt legacy systems accordingly.
Middle East
The United Arab Emirates (UAE) is a relatively developed market for digital assets, but its framework is split across Dubai, the Dubai International Financial Centre (DIFC), Abu Dhabi Global Market (ADGM) and the federal Capital Market Authority (CMA). The activities enabled include virtual asset issuance, exchange, custody, transfer and settlement, fiat referenced tokens, staking and trading facilities for tokenised securities. The CMA’s April 2026 Virtual Assets Framework expanded regulated activities from three to eight and included an Alternative Trading System (ATS) module covering multilateral trading facilities for virtual assets and tokenised securities.[footnote 105] Dubai’s Virtual Assets Regulatory Authority (VARA) has tightened requirements on token distribution, margin trading and collateral wallet arrangements. ADGM’s Financial Services Regulatory Authority (FSRA) has also expanded its framework, with over 20 regulated firms licensed for virtual assets or fiat referenced tokens as of December 2025.[footnote 106]
The strongest evidence of UAE tokenisation activity is sandbox-led rather than scaled issuance. The Dubai Financial Services Authority (DFSA) launched its Tokenisation Regulatory Sandbox in March 2025 and received 96 expressions of interest from firms across the UAE, UK, EU, Canada, Singapore and Hong Kong.[footnote 107] Proposed use cases included tokenised bonds, including sukuk, fund units, trading and safe custody. Some firms were invited into the Innovation Testing Licence (ITL), while others were considered suitable for full authorisation under existing rules. This is a useful proof point for market demand, including cross-border interest, but it remains controlled testing rather than evidence of private sector cross-border issuance at scale.
Qatar has focused on legal foundations rather than market scale. The Qatar Financial Centre (QFC) Digital Assets Framework 2024 establishes the basis for tokenisation, property rights in tokens and underlying assets, custody, transfer, exchange and smart contracts.[footnote 108] Companies can apply for licences to perform token service provider activities, while the QFC Digital Assets Lab has accepted 24 participants to develop use cases including trade finance, real world asset tokenisation and carbon credit tokenisation.[footnote 109] Bahrain provides a narrower platform example. ATME, a Central Bank of Bahrain (CBB) licensed digital assets exchange, launched in October 2024 and announced a regulated model in October 2025 allowing brokers and asset managers to issue and trade investment products directly on its platform.[footnote 110] Its first product comprised fixed income securities issued as digitally native tokens with secondary market access. This is a concrete market example, but there is not yet sufficient activity to point to broad secondary liquidity.
Saudi Arabia remains the regional exception, as it does not yet have a dedicated digital asset issuance regime. The main official example is Project Aber, launched by the Saudi Central Bank (SAMA) and the Central Bank of the UAE (CBUAE), which tested a wholesale central bank digital currency (CBDC) for domestic and cross-border interbank settlement using distributed ledger technology.[footnote 111] The CBDC was used only by the two central banks and participating banks as a settlement unit.
Across the region, the pattern is licensed market infrastructure, sandbox testing and controlled settlement experiments, rather than full interoperability or scaled cross-border tokenised issuance.
Singapore
Singapore has emerged as one of the most developed implementation-focused jurisdictions for institutional tokenisation internationally, pursuing a model centred on cross-border interoperability and wholesale market experimentation. The assets in scope of Project Guardian include tokenised funds, fixed income, foreign exchange, stablecoins and bank liabilities. Through Project Guardian, the Monetary Authority of Singapore (MAS) has sought to explore how tokenised financial assets and DLT based market infrastructure can support cross-border trading and asset servicing within institutional wholesale markets. In this respect, tokenisation has been positioned less as a purely domestic regulatory initiative and more as a vehicle for the development of interoperable cross-border financial market infrastructure and international market connectivity.[footnote 112]
Project Guardian has moved beyond pure conceptual experimentation through a series of live industry pilots, including trials for foreign exchange and Government bond transactions, reflecting its evolution from an exploratory initiative into a practical testbed for tokenised financial market infrastructure. Relative to comparable initiatives, the most notable characteristic of Project Guardian is its emphasis on cross-border market functionality and international interoperability, as evidenced by its collaboration with international policymakers through the Project Guardian Policymaker Group, including the FCA.[footnote 113] The MAS is also linking this commercialisation agenda to the Global Layer One initiative, which is intended to support compatible market infrastructures for cross-border tokenised asset activity. MAS has said it will work with the Bank for International Settlements (BIS) to incorporate a compliance by design approach into the Global Layer One architecture.[footnote 114] This aligns with BIS and Committee on Payments and Market Infrastructures (CPMI) analysis that token arrangements can reduce frictions where disparate systems are needed for issuance, trading and settlement, but that benefits depend on sound governance and risk management.[footnote 115] Separately to Project Guardian, the MAS has issued guidance on the application of existing securities laws to tokenised capital markets products and developed operational frameworks for tokenised funds and fixed income markets.[footnote 116]
Switzerland
Switzerland has followed a legal certainty and regulated infrastructure model. The Federal Act on the Adaptation of Federal Law to Developments in Distributed Ledger Technology (DLT Act) came fully into force on 1 August 2021 and enables securities to be issued on blockchain and trading venues to be licensed for that purpose. The Swiss Financial Market Supervisory Authority (FINMA) authorised SIX Digital Exchange (SDX) in 2021 as a stock exchange and CSD for digital securities, aimed at supervised financial institutions. FINMA then licensed BX Digital in March 2025 as the first DLT trading facility, permitting multilateral trading of DLT securities under the dedicated DLT route. The Capital Markets and Technology Association Token (CMTAT) provides an open smart contract framework for equity, debt and structured products. Switzerland has therefore enabled issuance, trading, settlement and custody through regulated infrastructure, with standardisation tools developing alongside it.
The strongest evidence of real activity is in digital bonds. In May 2024, SDX announced that digital asset issuances facilitated on its platform would surpass 1 billion Swiss francs (CHF) with the settlement of the World Bank’s CHF 200 million digital bond. Issuers included the World Bank, UBS, the City of Lugano, the Canton of Zurich, the Canton of Basel City, the City of St. Gallen and SIX Group. The World Bank transaction is the clearest international issuer proof point. It was the first CHF digital bond by an international issuer, settled using Swiss franc wholesale central bank digital currency (wCBDC) provided by the Swiss National Bank (SNB), listed on both SDX and the traditional SIX Swiss Exchange, and connected to conventional settlement systems through SIX SIS, Euroclear and Clearstream. This is production activity rather than sandbox testing. The evidence of scale sits mostly in bonds and regulated infrastructure, rather than broader private sector cross-border issuance across asset classes.
Switzerland’s interoperability work is focused on settlement connectivity rather than full token portability. Under Project Helvetia, the SNB has provided wCBDC on SDX since the end of 2023 and has extended the pilot until at least mid-2027. The SNB is also connecting BX Digital to the Swiss Interbank Clearing (SIC) payment system to test settlement of tokenised assets with traditional central bank money. BX Digital’s model uses a public blockchain for settlement and delivery versus payment (DvP) through a smart contract linked to SIC. Project Jura tested cross-border settlement of tokenised assets and foreign exchange between French and Swiss banks using euro and Swiss franc wCBDCs, with payment versus payment (PvP) and DvP. These initiatives show practical progress on the cash leg and infrastructure links. However, they do not yet show deep secondary market liquidity or freely portable Swiss digital securities across jurisdictions.
United States
The United States has largely relied on private-sector innovation to drive the development of tokenised financial markets, although recent regulatory developments indicate a move towards greater legal clarity. In March 2025, the SEC confirmed that tokenised securities remain subject to the same federal securities laws as their traditional counterparts[footnote 117] and the imminent SEC Innovation Exemption will allow some temporary sandboxing, exempting tokenised issuers from parts of the SEC regulatory framework.
Outside of formal sandboxes, the SEC under President Trump has taken significant steps to enable firms to experiment with tokenisation and support tokenised asset issuance. In particular, in December 2025 the SEC issued a no-action letter permitting the Depository Trust Company (DTC) to operate a three-year pilot to tokenise DTC-custodied assets on supported blockchains, subject to operational restrictions[footnote 118] (for example, that the pilot applies to a defined set of highly liquid assets). The importance of the no-action letter lies not just in the fact that it permits large-scale experimentation with tokenisation, but that it does so in a way that may have significant long-term market structure implications. Enabling an organisation that has historically operated as a monopolist provider of its services to spearhead innovation and experimentation in this space provides a potential solution to the market structure and fragmentation risks covered above, and one which other jurisdictions may seek to follow. At the very least, the DTC’s pilot will inform the design of future models for tokenised securities and allow for real-world testing of key operational and supporting process questions, including interoperability, the use of smart-contracts, and atomic settlement.
Prior to the SEC’s 2025 clarification, the United States had already emerged as one of the most commercially active jurisdictions for institutional tokenisation. A prominent example is BlackRock’s institutionally-oriented BUIDL Fund, the first tokenised fund issued on a public blockchain.[footnote 119] While not designed as an explicit cross-border initiative, the scale of products such as BUIDL illustrate how US tokenisation activity may acquire cross-border significance through market scale rather than coordinated international frameworks. Having grown to approximately $2.5 billion in assets under management, BUIDL demonstrates how US leadership in tokenisation can emerge organically from the depth, liquidity, and global attractiveness of US capital markets. More broadly, the tokenised US Treasury market has expanded to over $10 billion: a relative drop in the ocean given the size of the Treasury market, but a positive early experiment which is likely to scale significantly over time.
From 28 June 2026 the US stock market has moved closer towards 24-hour trading as the National Securities Clearing Corporation, which processes every US equity trade, has begun operating on a 24/5 schedule. The clearing house now operates from Sunday evening through to Friday evening eastern, which has the potential to create a foundational infrastructure step that moves the US one step closer to near-continuous US stock trading. The NYSE, Nasdaq and Cboe have announced similar plans to extend hours between late 2026 and 2027 as part of a shift driven by European and Asian investors.
These developments suggest that existing strengths in US capital markets may increasingly shape the development of tokenised financial markets and their associated infrastructure. More broadly, the depth and global reach of US capital markets position the United States as a natural centre for digital financial asset issuance and distribution, with potential implications for the future concentration of market activity. However, regulatory uncertainty and supervisory fragmentation continue to shape the competitive landscape. Emerging research suggests that these factors may influence the location of issuance activity across jurisdictions, with some evidence of digital asset activity migrating from the United States towards Europe.[footnote 120] This highlights the increasingly competitive dimension of tokenised financial markets, in which both market scale and regulatory design may influence where issuance, liquidity, and market infrastructure ultimately concentrate.
The CLARITY Act is the core vehicle for addressing uncertainty and fragmentation for firms operating in the US. Previous hopes that it could be finalised by 4 July 2026 are now unlikely, but if it can be delivered prior to the midterm elections in November 2026, then this legislative framework would provide a more durable and dependable basis for activity than regulatory policy or interpretation.
13. Annex F: Review of existing standards initiatives
Table 6 below provides an overview of key standard setters in the UK and internationally, and any work done on tokenisation standards.
Table 6: Work to date by standard setters
| Actor | Output on tokenisation |
|---|---|
| Financial Stability Board (FSB) | 2023: High-level Recommendations for the Regulation, Supervision, and Oversight of Global Stablecoin |
| Basel Committee | December 2022: Prudential Treatment of Cryptoasset Exposures – Basel Framework SCO60 July 2024: Final disclosure framework for banks’ cryptoasset exposures and amendments to crypto asset standard. |
| Bank for International Settlements (BIS) | Project Agora, Helvetia; standards-forming venues rather than standards themselves. |
| International Organisation for Standardisation (IOSCO) | July 2022: Application of the Principles for FMI to stablecoin arrangements November 2023: Policy Recommendations for Crypto and Digital Asset Markets; standards applied to 2025 Final Report on Tokenisation of Financial Assets. December 2023: Policy Recommendations for Decentralised Finance (DeFo); standards applied to 2025 Final Report on Tokenisation of Financial Assets. |
| Committee on Payments and Market Infrastructures (CPM) | 2023: Harmonised ISO20022 data requirements for enhancing cross-border payments |
| ISO |
ISO Technical Committee 307 – Blockchain and Distributed Ledger Technologies 2025: ISO 24165-1:2025 Digital Token Identifier – Registration, Assignment and Structure |
| SWIFT | ISO 20022 – de-facto data standard tokenised payments operate with. 2023 interoperability experiments with Chainlink CCIP, a dozen FMIs and banks (Euroclear, Clearstream, DTCC, etc), reusing existing SWIFT architecture across public and private chains. 2024: Sandbox project enabling interoperability between CBDCs, with 38 participating institutions. September 2025: announcement to add a blockchain-based shared ledger to its technology infrastructure; completed in March 2026 and the next development is to enable interoperability between banks’ tokenised deposits, with live transactions planned by EOY. |
| Int’l Swaps and Derivatives Assoc. (ISDA) |
Common Domain Model – machine-executable standards which was open-sourced into FINOS in February 2023 (see also ICMA, ISDA, ISLA, and FINOS). January 2019: Legal Guidelines for Smart Derivatives Contracts January 2023: Standard Definitions for Digital Asset Derivatives May 2024: Tokenised Collateral Guidance |
| Int’l Securities Lending Association (ISLA) | Collaborated on the Common Domain Model (above) |
| Int’l Capital Market Assoc. (ICMA) | May 2023: Common Domain Model - repo and bonds June 2025: lead of Project Guardian Fixed Income Workstream |
| Clearing houses LCH SA, Euroclear, DTCC, Clearstream | September 2023: Digital Assets Securities Control Principles – joint publication by DTCC, Euroclear, and Clearstream April 2024: LCH SA receives regulatory approval from French Supervisors, and ESAs to clear cash-settled Bitcoin index future and options contracts; “LCH DigitalAssetClear will operate a fully segregated clearing service – including… a dedicated set of clearing rules.” |
| European Central Bank (ECB) / European Securities and Markets Authority (ESMA) |
Pontes: operational offering that builds on interoperability to settle DLT-based wholesale transactions in central bank money already in the short term. Appia: the ‘long term track’ analytical and exploratory initiative that investigates possibilities for a futureready, innovative and integrated European financial DLT-based ecosystem, developing common standards, policies and functional building blocks. DLT Pilot Regime– facilitating the set-up of new types of market infrastructure including DLT multilateral trading facility, DLT settlement system, DLT trading and settlement system. |
| Monetary Authority of Singapore (MAS) |
June 2025: takes on ICMA as lead of Project Guardian Fixed Income Workstream From June 2024: Global Layer One aims to foster the development of open, interoperable, shared ledger infrastructures for hosting and executing transactions, as well as to encourage the development of internationally accepted common principles, policies, and standards. June 2023: Project Orchid white paper proposes a common protocol for interacting with different forms of medium of exchanges August 2023: MAS finalises stablecoin regulatory framework |
| US actors SEC, CFTC, Fed, Treasury, Congress |
May 2019: FinCEN Guidance consolidating FinCEN regulations around convertible virtual currencies October 2021: OFAC Sanctions Guidance for Virtual Currency Industry July 2025: GENIUS Act – federal payment-stablecoin framework September 2025: CLARITY Act – market structure |
14. Annex G: Digital Markets Champion Industry Taskforce
Delivery of the Wholesale Digital Markets Champion’s objectives will be led by the Digital Markets Champion Industry Taskforce, mobilised over the next 12 months to implement the priorities set out in Section 7.
An Orchestration Group led by the Digital Markets Champion will coordinate delivery of a practical end-to-end repo use case on blockchain, ensuring ecosystem-wide interoperability and enabling cross-border testing. The Orchestration Group will align activity across Action Groups, facilitate knowledge sharing, and commission cross-cutting input (including legal and tax).
Delivery will be driven by nine Action Groups (AGs), aligned to ten priorities.
- AG1–AG4 (value chain delivery) focus on primary issuance, secondary markets, collateral, and FMI/cash infrastructure, developing interoperable platforms, token standards, smart contracts, and settlement processes.
- AG5–AG8 (cross-cutting) provide horizontal support across tax, legal, financial crime compliance, and resilience, producing best practice guidance and undertaking stress testing of the end-to-end use case.
- AG9 will be tasked with coordinating the promotion of the UK as a digital assets centre.
The structure will remain flexible, evolving over time to ensure delivery remains commercially relevant, executable, and scalable. See a visual of this structure below in Figure 2.
Figure 2:
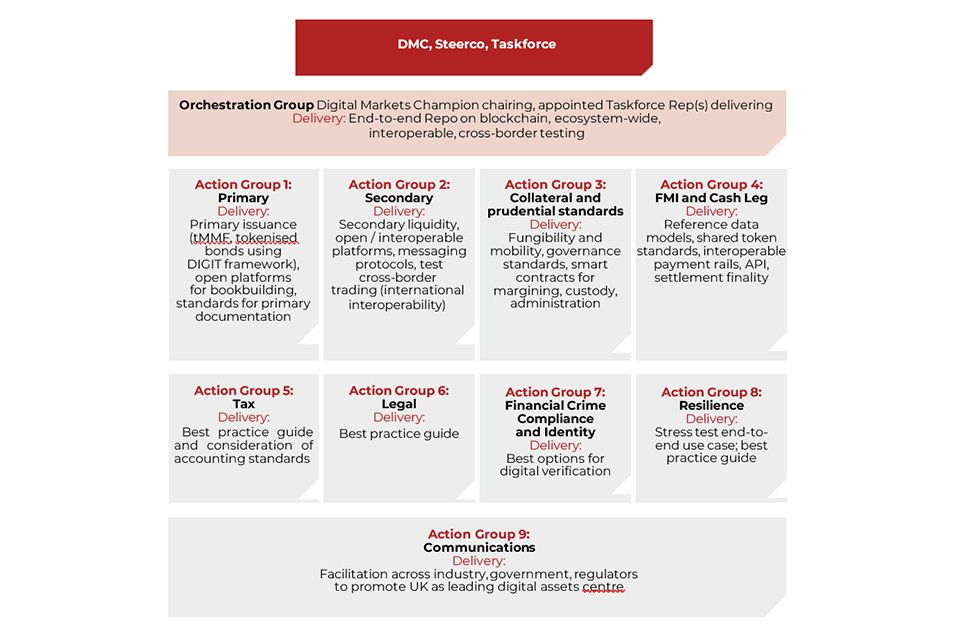
Taskforce Members as of the date of this report:
Ava Labs
Aviva Investors Baillie Gifford Barclays BlackRock Bloomberg BNP Paribas BPX
Calastone Cboe Chainalysis Circle
Citadel Securities Citi
ClearBank Clearstream ClearToken Coinbase Ctrl Alt
Deutsche Bank
Digital Asset / Canton DTCC
Euroclear UK & International (CREST) Fidelity International Fireblocks
Fnality GFO-X
Goldman Sachs HSBC
Intercontinental Exchange (ICE) Invesco
Jane Street
J.P. Morgan
Kinexys by J.P. Morgan Kraken (Payward) Legal & General Asset Management
Lloyds Banking Group
LME Clear LSEG and LCH Mobius Montis Digital
Morgan Stanley Northern Trust Optiver
Ripple Schroders SLIX
Standard Chartered State Street Tokenovate Tradeweb
UBS
Ubyx Wintermute
Steerco Members as of the date of this report:
Andrew Douglas Margaret Harwood-Jones Mark Austin CBE
Michael Voisin
Michelle Scrimgeour CBE Sasha Mills
Simon Walls
Tom Duff Gordon
Contributors to this report:
City of London Corporation UKFinance
TheCityUK
The Investment Association EY
Flint Global Deloitte PwC
Hogan Lovells Stephenson Harwood
-
See Annex A for definitions of commonly used terms in this report. ↩
-
Barclays and PwC. Rewiring Finance: Tokenisation as a Catalyst for UK Growth. (London: Barclays, 2026) ↩
-
Authorities refers collectively to the Bank of England, the Prudential Regulation Authority, and the Financial Conduct Authority. ↩
-
Bank of England and Financial Conduct Authority. The Future of Tokenisation – a joint vision from the authorities for UK wholesale financial markets (London: Financial Conduct Authority, 2026) ↩
-
Bank of England. Sterling-denominated systemic stablecoins policy statement and consultation on draft Code of Practice (London: Bank of England, 2026). ↩
-
Financial Conduct Authority. Overview of our cryptoasset regime policy statements (London: Financial Conduct Authority, 2026) ↩
-
Bank of England. Bank of England and Financial Conduct Authority’s approach to joint regulation of systemic stablecoin issuers. (London: Bank of England, 2026) ↩
-
Bank of England. Digital Securities Sandbox Dashboard. (London: Bank of England, 2026) ↩
-
International Capital Market Association (ICMA), International Swaps and Derivatives Association (ISDA), International Securities Lending Association (ISLA), and Institute of Chartered Accountants in England and Wales (ICLAEW). ↩
-
Thanks to Andrew Douglas, Margaret Harwood-Jones, Mark Austin CBE, Michael Voisin, Michelle Scrimgeour CBE, Sasha Mills, Simon Walls, and Tom Duff Gordon. ↩
-
Bank for International Settlements: Financial market infrastructures and critical service providers (Basel: Bank for International Settlements, 2024) ↩
-
Christian Schmid, Inderpreet Batra, and Roy Choudhury. The Future of Digital Assets. (New York: Boston Consulting Group, 2026) ↩
-
Bank of England. Digital Securities Sandbox Dashboard. (London: Bank of England,2026) ↩
-
Financial Conduct Authority. Wholesale Financial Markets: Overview (London: Financial Conduct Authority, 2026), pg.1 ↩
-
Bank for International Settlements. Financial Market Infrastructure and Critical Service Providers (Basel: Bank for International Settlements, 2024). ↩
-
Financial Conduct Authority. The future of tokenisation: a joint vision from the authorities for UK wholesale financial markets (London: Financial Conduct Authority; Bank of England, 2026), pg 9. ↩
-
City of London Corporation interviews with market participants for Digital Sprint, January – April 2026 ↩
-
City of London Corporation interviews with market participants for Digital Sprint, January – April 2026 ↩
-
City of London Corporation interviews with market participants for Digital Sprint, January – April 2026 ↩
-
See acquisitions such as Ripple’s $1.25 billion purchase of prime broker Hidden Road. ↩
-
See for example HSBC’s deployment of its DLT platform HSBC Orion for digital bonds. ↩
-
See Lloyds Bank’s use of its own ledger combined with Canton’s synchronization layer for tokenised deposits, and white-labelling arrangements including Santander UK’s use of Ripple’s blockchain for cross-border payments. ↩
-
Julio Suarez. DLT-Based Capital Market Report – September 2025 (London/Brussels/Frankfurt: Association of Financial Markets in Europe, 2025). ↩
-
Bank of England. DLT Innovation Challenge 2025: Final Report (London, Bank of England, 2026), pg 5-6. ↩
-
Financial Conduct Authority. PS24/12: Digital Securities Sandbox Joint Policy Statement and Final ↩
-
ibid ↩
-
Lloyds Banking Group. Aberdeen Investements, Lloyds Banking Group and Archax complete UK-first use of digital assets (Edinburgh: Lloyds Banking Group, 2025). ↩
-
London Stock Exchange Group. LSEG launches Digital Markets Infrastructure platform for private funds, and facilitates first transaction (London: London Stock Exchange Group, 2025). ↩
-
HM Treasury. Wholesale Financial Markets Digital Strategy (London: HM Treasury, 2025). ↩
-
Bank of England and Financial Conduct Authority. The Future of Tokenisation – a joint vision from the authorities for UK wholesale financial markets (London: Financial Conduct Authority, 2026). ↩
-
HM Treasury. Wholesale Financial Markets Digital Strategy (London: HM Treasury, 2025). ↩
-
HM Treasury..A. National Payments Vision (London: HM Treasury, 2026). ↩
-
UK Finance and Oliver Wyman. Tokenised Securities in the UK (London: UK Finance and Oliver Wyman, (unpublished) 2026). ↩
-
City of London Corporation. City statistics briefing. (London: City of London Corporation 2025) ↩
-
Barclays and PwC. Rewiring Finance: Tokenisation as a Catalyst for UK Growth. (London: Barclays, 2026) ↩
-
Evidence of these benefits is becoming more tangible. Broadridge reported capital efficiency gains of 20-30% through more efficient repo and collateral mobility, with its digital repo platform processing $368 billion in average daily repo transactions in April 2026, equivalent to nearly $8 trillion over the month. Survey evidence points in the same direction. A 2025 ISSA survey found an 11.6% reduction in collateral buffering requirements, a 13.4% reduction in settlement failures, and that 94% of surveyed firms expect tokenisation to improve collateral mobility ↩
-
Chris Schmid; Inderpreet Batra; Roy Choudhury. The Future of Digital Assets (New York: Boston Consulting Group, 2026). ↩
-
Canton Network. Canton’s Industry Working Group Advances Cross-Border Collateral Mobility on Canton (Switzerland: Canton, 2026). ↩
-
Market examples are encouraging: Hong Kong’s HK$800 million tokenised green bond in 2023 settled on T+1 using tokenised securities and cash tokens; SGX / Marketnode reported a 60% reduction in bond settlement time, from T+5 to T+2, through its DLT-enabled direct-to-depository service; the European Commission estimated potential annual reporting savings of up to €4billion under full automation assumptions. ↩
-
Hong Kong Monetary Authority. HKMA announces the new phase of Project Ensemble to support real-value transactions in tokenised deposits and digital assets (Hong Kong: Hong Kong Monetary Authority, 2025). ↩
-
UK Finance. Unlocking the Power of Securities Tokenisation (London: UK Finance, 2023), pg4. ↩
-
Hamilton Lane. Hamilton Lane and Securitize to Tokenize Fund, Expanding Access to Private Markets for a Broader Set of Investors (New York: Hamilton Lane, 2022). ↩
-
Ali Lyon. Baillie Gifford launches UK’s first ever tokenised fund (London: CityAM, 2026). ↩
-
Chris Schmid; Inderpreet Batra; Roy Choudhury. The Future of Digital Assets (New York: Boston Consulting Group, 2026). Pg 41 ↩
-
Bank for International Settlements. Tokenisation in the Context of Money and other assets: concepts and implications for central banks (Basel: Bank for International Settlements, 2024), p.16 ↩
-
Bank for International Settlements. Tokenisation in the Context of Money and other assets: concepts and implications for central banks (Basel: Bank for International Settlements, 2024), p.16. ↩
-
UK Finance and Oliver Wyman. Unlocking the Power of Securities Tokenisation (London: UK Finance, 2023), pg 17. ↩
-
Standard Chartered. Standard Chartered launches digital assets trading for institutional clients (London: Standard Chartered, 2025). ↩
-
BusinessWire. Securitize, BlackRock Launches Its First Tokenized Fund, BUIDL, on the Ethereum Network (BusinessWire: 2024). ↩
-
Bank for International Settlement. Novel Risks, Mitigants and Uncertainties with Permissionless Distributed Ledger Technologies (Basel: Bank for International Settlement, 2024), pg.4. ↩
-
The Bank of England designates payment and settlement that are systemic under the Financial Markets and Insolvency (Settlement Finality) Regulations 1999. ↩
-
Financial Conduct Authority et al. Bridging the Adoption Gap: Aligning Digital Asset Offerings with Buy-Side Requirements. Insights from Singapore and the UK. (London: The Investment Association, 2025), pg. 7. ↩
-
The Investment Association. The IA Position Paper on the Automation of IPOs and Placing “Block Trades” (London: The Investment Association, 2024). ↩
-
Bank for International Settlements. Tokenisation in the context of money and other assets: concepts and implications for central banks (Basel: Bank for International Settlements, 2024), pg17. ↩
-
Organisation for Economic Cooperation and Development. The Tokenisation of Assets and Potential Implications for Financial Markets (Paris: Organisation for Economic Cooperation and Development, 2020), pg. 7. ↩
-
Bank of England PRA. Dear CEO: Prudential Treatment of Tokenised Assets, Stablecoins, and other Cryptoasset Exposures (London: Bank of England, 2026). ↩
-
Bank for International Settlements. Basel Committee continues to prioritise Basel III implementation, approves final principles on third-party risks and agrees to expedite targeted review of cryptoasset standard (Basel: Bank for International Settlements, 2025). ↩
-
Tokenised assets represented only a marginal 0.01% of investable assets in 2025 ($30 billion globally), but value grew by 300% in 2025. This could reach $88 trillion, or around 16% of global investable assets, by 2035. See: Boston Consulting Group. The Future of Digital Assets (New York: Boston Consulting Group, 2026). Pg 19. ↩
-
Albeit the FCA does provide a “no action letter” in relation to regulatory enforcement action but this is a narrower scope. ↩
-
Ali Lyon. Baillie Gifford launches UK’s first ever tokenised fund (London: CityAM, 2026). https://www. cityam.com/baillie-gifford-launches-uks-first-ever-tokenised-fund/ ↩
-
Synchronisation refers to the instantaneous conditional settlement of assets on an external ledger – including those based on DLT – against central bank money held in RTGS accounts. This is currently being tested by 18 participants in the Bank’s Synchronisation Lab. ↩
-
Bank of England. Sterling-denominated systemic stablecoins policy statement and consultation on draft Code of Practice (London: Bank of England, 2026). ↩
-
See Annex C: Notable tokenisation initiatives in the UK – Legal ↩
-
International Capital Markets Association. Bond Data Taxonomy Working Group (Zurich: International Capital Market Association, n.d.). ↩
-
E.g. ICMA Bond Data Taxonomy, ISDA Common Domain Model. ↩
-
HM Treasury has said that it will consult on changes to payment services and consulted in the meantime on removing stablecoin payments firms from the dealing and arranging licensing requirement (they may still be required to obtain a safeguarding permission). ↩
-
The International Organisation of Securities Commission. Tokenization of Financial Assets (Madrid: the International Organisation of Securities Commissions, 2025), pg.51, 55. ↩
-
Bank for International Settlements. Finternet: The financial system for the future (Basel: Bank for International Settlements, 2024), pg. 29. ↩
-
See Annex F: Work to date by international and national standard setters ↩
-
Organisation for Economic Cooperation and Development. Tokenisation of Assets and Distributed Ledger Technologies in Financial Markets (Paris: Organisation for Economic Cooperation and Development, 2025), pg.19. ↩
-
The Call for Input notes that protocols like IEEE 3205-2023 for cross-chain communication are already emerging and becoming widely adopted. see here: Financial Conduct Authority. The Future of Tokenisation – a joint vision from the authorities for UK wholesale financial markets (London: Financial Conduct Authority, 2026), pg.9. ↩
-
Financial Conduct Authority and Bank of England. The Future of Tokenisation – a joint vision from the authorities for UK wholesale financial markets (London: Financial Conduct Authority, 2026) pg.13. ↩
-
City of London Corporation. Securing growth – the digital verification opportunity (London: City of London Corporation, 2025), pg.9. ↩
-
Financial Action Task Force. Outcomes FATF Plenary, 11–13 February 2026 (Mexico City: Financial Action Taskforce (FATF), 2026). ↩
-
Financial Stability Board. Thematic Review on FSB Global Regulatory Framework for Crypto-asset Activities (Basel: Financial Stability Board, 2025), page 16-17. ↩
-
International Organisation of Securities Commissions. Tokenizsation of Financial Assets (Madrid: International Organisation of Securities Commissions, 2025), pg.7. ↩
-
UK Finance and Oliver Wyman. [Unlocking the Power of Securities Tokenisation]Unlocking the power of securities tokenisation.pdf (London: UK Finance, 2023), pg.4. ↩
-
UK Finance. Tokenised sterling deposit.(London: UK Finance, n.d.). ↩
-
The Investment Association. Tokenised funds series Paper 1 – What, why and how (London: The Investment Association, 2020), pg.2. ↩
-
UK Finance and Oliver Wyman. Unlocking the power of securities tokenisation (London: UK Finance, 2023), pg. 4. ↩
-
Amended slightly to include stablecoins can also be backed by bank deposits and what is/isn’t in scope of definition of a ‘regulated’ stablecoin. see here: Financial Stability Board. Regulation, Supervision, and Oversight of ”Global Stablecoin” Arrangements (Basel: Financial Stability Board, 2020), pg.5. ↩
-
Information Commissioner’s Office. Tech Horizons Report 2024 (London: Information Commissioner’s Office, 2024), pg.57. ↩
-
Association of Financial Markets in Europe. Post Trade explained – the role of post-trade service in the financial sector. (London, Association of Financial Markets in Europe, 2015), pg.4. ↩
-
TheCityUK et al. Digital Currency Glossary (London: TheCityUK et al, 2024), pg.6. ↩
-
Bank of England. Modernising money and markets – speech by Sarah Breeden (London: Bank of England, 2026). ↩
-
Financial Conduct Authority. PS26/7: Progressing Fund Tokenisation (London: Financial Conduct Authority, 2026). ↩
-
The Law Commission. Digital Assets. (London: the Law Commission, 2024). ↩
-
The Law Commission. Smart Contracts (London: The Law Commission, 2021). ↩
-
The Law Commission. Digital Assets and Electronic Trade Documents in Private International Law (London: The Law Commission, 2025). ↩
-
UK Legislation. Property (Digital Assets etc) Act 2025 (London: UK Legislation, 2025). ↩
-
UK Legislation. The Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026 (London: UK Legislation, 2026). ↩
-
HM Treasury. New crypto rules to unlock growth and protect customers (London: HM Treasury, 2025). ↩
-
In the Bank/FCA Call for Input, BoE: 1) published a Dear CEO Letter confirming that for PRA regulated banks, building societies, and designated investment firms tokenised assets should, in general, receive the same prudential treatment as their non-tokenised equivalents, where legal rights are identical and underlying risks are comparable; 2) committed to working to enable tokenised equivalents of already eligible assets to be used as collateral both at central counterparties and in the Bank’s central operations. See here: Bank of England and Financial Conduct Authority. The Future of Tokenisation – A joint vision from the authorities for UK wholesale financial markets (London: The Financial Conduct Authority; Bank of England, 2026). Pg. 19. ↩
-
HM Treasury. Cryptoassets Taskforce: Final Report (London: HM Treasury, 2018). ↩
-
The Bank of England is leveraging its regulatory and supervisory responsibilities to support the adoption of tokenisation. As set out in the joint call for input, the Bank is working to enable tokenised equivalents of traditional assets by focusing on: establishing a clear glidepath, ensuring operational certainty, and supporting interoperability. ↩
-
Financial Services & Markets Act 2023; Electronic Trade Documents Act 2023; Property (Digital Assets etc) Act 2025 and (once brought fully into force) the Digital Assets (Scotland) Act 2026. ↩
-
See the Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026; the PRA Dear CEO letters setting out updated guidance on the Prudential treatment of tokenised assets, stablecoins, and other crypto asset exposures and Innovations in deposits, e-money and stablecoins. ↩
-
Law Commission Documents Template, Digital assets and electronic trade documents in private ↩
-
Report on Control of Digital Assets – LawtechUK (March 2026). In addition, s.5 of the Digital Assets (Scotland) Act 2026 sets out criteria for control of a digital asset. ↩
-
HM Treasury. National Payments Vision (London: HM Treasury, 2026). ↩
-
European Securities and Markets Authority. DLT Pilot Regime (Paris: European Securities and Markets Authority, N.D.). ↩
-
European Securities and Markets Authority. ESMA Report on the Functioning and Review of the DLT Pilot Regime - Pursuant to Article 14 of Regulation (EU) 2022/858. (Paris: European Securities and Markets Authority, 2025). pg13. ↩
-
Association of Financial Markets in Europe. N.A. AFME Urges EU to Raise DLT Cap to EUR 50bn and Pursue Bolder Reforms to Avoid Initiative Failing (Brussels: Association of Financial Markets in Europe, 2026). ↩
-
Emirates News Agency. Capital Market Authority issues Virtual Assets Framework (Abu Dhabi: Emirates New Agency-Wam, 2026). ↩
-
ADGM. ADGM FSRA Presents Key Enhancements to its Digital Assets Framework at Abu Dhabi Finance Week 2025 (Abu Dhabi: ADGM, 2025). ↩
-
Tokenisation Regulatory Sandbox, Reinforcing its Commitment to Responsible Innovation in the DIFC (Dubai: Dubai Financial Services Authority, 2025). ↩
-
Qatar Financial Centre. Qatar Financial Centre Issues QFC Digital Assets Framework 2024 (Doha: Qatar Financial Centre, 2024). ↩
-
Qatar Financial Centre. 24 Participants Kickstart the Innovation Journey at the QFC Digital Assets Lab (Doha: Qatar Financial Centre, 2024). ↩
-
BusinessToday. ATME and Arabian Gulf Capital Unveil MENA’s First Regulated Tokenized Investment Model (Dubai: Business Today, 2025). ↩
-
Central Bank of the UAE. Aber (Abu Dhabi: Central Bank of the UAE, 2025). ↩
-
Monetary Authority of Singapore. Guardian (Singapore: Monetary Authority of Singapore, 2025). ↩
-
Financial Conduct Authority. FCA welcomes Project Guardian’s first industry report on tokenisation (London: Financial Conduct Authority, 2024). ↩
-
Monetary Authority of Singapore. MAS Announces Plans to Support Commercialisation of Asset Tokenisation (Singapore: Monetary Authority of Singapore, n.d.) ↩
-
Bank for International Settlements. Tokenisation in the context of money and other assets (Basel: Bank for International Settlements, 2024). pg.17. ↩
-
Monetary Authority of Singapore. Guide on the Tokenisation of Capital Markets Products (Singapore: Monetary Authority of Singapore, 2025). ↩
-
Securities and Exchange Commission. SEC Clarifies the Application of Federal Securities to Crypto Assets (Washington D.C.: Securities and Exchange Commission, 2026). ↩
-
U.S. Securities and Exchange Commission. Tokenization Trending: Statement on the Division of Trading and Market’s No-Action Letter Related to DTC’s Development of Securities Tokenization Services (Washington D.C.: Securities and Exchange Commission, 2025). ↩
-
Securitize. BlackRock Launches Its First Tokenised Fund, BUIDL, on the Ethereum Network (New York, NY: Securitize, 2024). ↩
-
ArXivLabs. Regulatory Migration to Europe: ICO Reallocation Following U.S. Securities Enforcement (N.L: ArXivLabs, 2026). ↩