The economic benefits of touring and impact of EU exit
Published 27 August 2026
© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/publications/the-economic-benefits-of-touring-and-impact-of-eu-exit/the-economic-benefits-of-touring-and-impact-of-eu-exit
This report was authored by Dr Ricky Lawton, Jack Philips, Abigail Lyons and Alistair Davey at Ipsos UK, Dustin Chodorowicz, Louis Underwood and Balvinder Chowdhary at Nordicity.
Executive summary
The Department for Culture, Media and Sport (DCMS) commissioned Ipsos and Nordicity to assess how UK touring activity in the EU has changed since EU exit. Using a mixed methods approach, the research estimates, for the first time, the impact of new regulatory, administrative and economic barriers on the scale and value of touring, and on artists, crews, promoters, venues and local economies in both the UK and EU.
This analysis employs two approaches. First, micro-level artist revenue data from the music sector, including data from PRS for Music,[footnote 1] is used to model the net annual economic impact of post-EU exit regulations on Gross Value Added (GVA) and employment in both the UK and EU. Secondly, qualitative evidence across the wider touring ecosystem from in-depth interviews with industry representatives and cultural institutions, alongside existing literature and sector surveys, is used to contextualise and deepen the understanding of the impacts identified through the economic modelling.
The findings indicate that reduced touring activity by UK performers in the EU between 2022 and 2024 is associated with clear negative economic consequences for both the UK and EU, highlighting the interconnected nature of the UK-EU cultural ecosystem.
Headline findings
-
Between 2022 and 2024, the UK is estimated to have lost £208.0 million in GVA and 2,490 full-time equivalent (FTE) jobs within the touring sectors covered by this study, including both direct and indirect/induced effects.
-
Reduced touring by UK musicians after EU Exit is estimated to have resulted in losses of approximately £1.04 billion in GVA and 17,010 FTE jobs across the included EU host countries.[footnote 2]
-
Smaller and mid-scale touring activity has been found to be disproportionately affected, particularly performances at general live music venues.
-
Stakeholders reported that immigration, customs, transport, taxation and social security requirements interact cumulatively, increasing costs, complexity and operational uncertainty for touring activity.
-
Evidence suggests that reduced touring activity has implications for workforce sustainability, cultural exchange, audience development and future export growth across both the UK and EU.
The evidence also suggests that reducing current touring barriers, through policy or regulatory changes, could generate a range of economic and cultural gains for both sides.
Scope and nature of EU touring between 2017 and 2024
-
Overall EU touring by UK-based music artists remains below pre-EU exit, pre-COVID-19 levels, with overall performance numbers in 2024 being 21% below 2019 levels. PRS for Music data and interviews with industry representatives indicate reduced live performances, festival earnings and event numbers since 2019. While demand at larger venues (defined as stadium and arena tours) appears to have recovered following the COVID-19 pandemic, music performances at smaller venues (defined as general live music venues) have not returned to pre-2019 levels.
-
Distribution of EU performance activity across EU member states by UK-based artists has remained broadly consistent following EU exit, with Germany, the Republic of Ireland, France and the Netherlands continuing to account for a large share of performances.
Barriers to EU touring caused by EU exit
-
Lack of guaranteed visa and work-permit free travel has created significant operational challenges for movement of artists and crew between the UK and EU. The operation of the 90/180-day Schengen rule, alongside differing visa and work permit requirements across member states, increases complexity and uncertainty. Navigating multiple national systems within a single tour creates additional administrative costs and planning requirements, particularly for tours involving several countries or extended schedules. These requirements also reduce flexibility to accommodate short-notice touring opportunities, including festival appearances and additional dates.
-
Customs procedures and temporary admission requirements have increased the cost and complexity of moving touring equipment between the UK and EU. Additional fees, security bonds, detailed documentation requirements and inconsistent implementation at borders contribute to delays, uncertainty and additional compliance costs.
-
Transport and haulage restrictions present significant barriers for touring activity. Cabotage and cross-trade restrictions affecting UK-registered vehicles operating within the EU reduce flexibility for multi-country touring schedules.[footnote 3] Workarounds - such as using EU-based hauliers, dual-registered fleets or cross-border trailer swaps - were acknowledged to often increase logistical complexity and are not feasible for all organisations, particularly where specialist vehicles or touring infrastructure are involved.
-
Merchandise sales were also identified as an area of growing operational complexity following EU exit. This is due particularly to import VAT, customs declarations and differing tax requirements across member states. While variations in national regimes pre-dated EU exit, import VAT at first point of EU entry - together with divergent VAT and Withholding Tax (WHT) rules across member states - has, in some cases, led to a shift towards EU-based stock or third-party fulfilment models, reducing profit margins.[footnote 4]
-
WHT and social security administration create additional financial pressures and cashflow challenges. Delays in reclaiming WHT and VAT across multiple jurisdictions can leave substantial sums tied up for extended periods. Delays associated with A1 social security forms in some cases have led European promoters to withhold part of fees.
Estimated economic impacts of EU exit on EU touring (2022 to 2024)
Economic implications for UK Touring sectors
-
Key touring sectors: Between 2022 and 2024, the UK’s exit from the EU is estimated to have reduced the contribution of UK live music touring, orchestra, theatre, dance, and visual arts organisations to the UK economy. This decline in economic value is estimated to directly account for over 920 full-time equivalent jobs and £95.6 million in direct GVA. Including indirect and induced impacts, the total impact reaches 2,490 FTEs and £208.0 million.[footnote 5] Within this overall estimate:
-
Music: The decline in live music performances is associated with a direct economic loss of £81.6 million in GVA.[footnote 6] Including indirect and induced impacts, this totals £180.2 million,[footnote 7] largely driven by the impact on musicians performing at smaller general live music venues.
-
Orchestra, theatre, dance and visual arts: Sectors associated with orchestra, theatre, dance and visual arts are estimated to have experienced a direct loss of £14.1 million in GVA and over 230 FTEs. Factoring in indirect and induced impacts elevates the total estimates to £27.8 million in GVA and 440 FTEs.[footnote 8] Orchestras notably saw the largest declines in international touring.
Economic implications for the EU
-
Reduced touring by UK musicians after EU exit has led to an estimated total loss of approximately £1.04 billion in GVA for the included EU host countries. This total loss includes £367.9 million in direct GVA losses, with the remainder from wider indirect and induced effects.
-
Germany experienced the largest impact, with estimated losses reaching nearly £290 million in GVA and an estimated 4,000 FTE jobs.
-
Outside of Germany (£289m), Denmark (£152.4m), France (£114.8m), Italy (£105.1m), and the Netherlands (£96.8m) felt the greatest GVA impacts from the reduction of UK musicians touring in the EU.
-
Losses were distributed across all venue sizes, with smaller venues (general live music venues) accounting for a slightly greater share, with direct GVA losses of £195.3 million (rising to £545.4 million with wider effects). A reduction in UK musicians touring in smaller venues is estimated to have had the greatest negative impact on Denmark (£54.2m), Germany (£40.1m), Italy (£17.4m), France (£16.1m), and the Netherlands (£19.6m).
-
Larger venues (stadium and arena tours) saw direct GVA losses of £172.5 million (rising to £491.8 million with wider effects), with Germany (£59.7m), France (£21.1m), Italy (£16.5m), Ireland (£18.9m), and the Netherlands (£19.1m) being the most negatively impacted based on total GVA lost.
Wider impacts
-
Small and mid-scale artists and companies, freelancers, and crews and hauliers have been disproportionately impacted. Emerging artists in particular face reduced opportunities to build audiences, develop professional networks, and sustain career progression, with implications for diminished future export growth and international market development.
-
Declining touring activity is linked to a combination of financial pressures, with tours no longer financially viable for a considerable proportion of artists. Many professionals who previously worked in the EU are experiencing reduced booking opportunities and lower income.[footnote 9] [footnote 10] Average touring costs have risen markedly, while demand for UK-based performers and crews has fallen, with the steepest effects on lower earning and emerging artists.
-
In some cases, work previously undertaken by UK hauliers, production houses and merchandise providers have shifted in part to EU-based hubs and manufacturers. This risks a long-term transfer of significant value-adding activity from the UK to EU economies.
-
Pressures are impacting the structure of tours, with dynamism and flexibility reduced. Touring schedules have become shorter, more segmented, or regionally-focused where existing fan bases are more established. Last-minute additions to accommodate opportunities such as festival slots have reduced due to increased requirements and the risk of delays.
-
There are also emerging detrimental workforce impacts across parts of the sector. Survey evidence from Musicians’ Union[footnote 11] indicates that some professionals would consider relocating to the EU, while a notable share is contemplating leaving the sector altogether, raising concerns about potential long-term skills losses.[footnote 12]
-
Increased stress and burnout amongst administrative staff, managers and crews was identified. This was linked to prolonged uncertainty, additional travel on rest days to remain compliant, and anxiety around visas and border processes.
-
There are reduced opportunities for artistic diversity, cultural exchange and audience development across UK and EU cultural sectors. This is due to the presence of fewer UK acts touring the EU.
Conclusions
Overall, evidence shows that post-EU exit rules have reduced the volume and viability of UK touring in the EU, especially for smaller-scale activity and emerging talent. The impacts described by stakeholders extend beyond performers themselves, affecting supply chains, workforce sustainability and cultural exchange across both the UK and EU. The full long-term impacts of post-EU exit touring arrangements may continue to emerge over time.
These findings suggest that reduced touring activity has led to measurable economic losses for both the UK and EU, highlighting the interconnected and mutually beneficial nature of the UK-EU cultural ecosystem. The evidence also points to the possibility that easing current barriers could help restore lost value and support long-term sector sustainability.
While data limitations remain in some areas of international touring activity, this research is the first of its kind and provides one of the most detailed assessments to date of the economic and operational impacts associated with changes to UK-EU touring since EU exit. It also establishes an evidence base that future research can build upon as touring models and international arrangements continue to evolve.
Introduction
The ability to tour internationally is a core feature of the UK’s creative economy, underpinning income generation, skills development and cultural exchange. For many artists and creative businesses, the European Union (EU) and the former EEC (incorporated in the EU in 1993) has historically been the most accessible and commercially significant international market, with a supportive framework that enabled relatively frictionless movement of people, goods and services.
Since the UK’s exit from the EU, the operating environment has changed materially. While the UK-EU Trade and Cooperation Agreement established the basis of the post-exit relationship, it did not include specific provisions for touring. As a result, touring in Europe for performers - as well as accompanying professionals and industries - has become more complex, costly and administratively burdensome owing to the introduction of new mobility, customs and transport requirements. Key developments shaping this landscape include:
-
June 2016 – EU referendum: UK votes to leave the EU.
-
31 January 2020 – UK formally leaves EU: Transition period begins; practical rules for touring (visas, customs, cabotage) still follow EU membership norms until the end of 2020.
-
24 December 2020 – EU-UK Trade and Cooperation Agreement (TCA): The deal is agreed. No dedicated provisions for touring artists.
-
19 May 2025 – inaugural UK-EU Summit: A set of shared commitments (the “Common Understanding”) was agreed between the European Commission and the UK to strengthen cooperation between the European Union and the United Kingdom.
Despite evidence suggesting significant impacts on artists’ livelihoods and the wider UK music industry, there is limited comprehensive data quantifying the value of EU touring. DCMS commissioned this research to fill the evidence gap, primarily by quantifying the economic value of EU touring for UK artists and the UK, assessing the extent and nature of barriers faced by touring artists post-EU exit, and associated costs to performers and the wider touring economy (i.e. promoters, venues).
Scope of research
This research examines the economic importance of EU touring for UK artists, and explores the barriers they face when touring in Europe following the UK’s exit from the EU. The scope of this research is covered below:
-
Quantify the economic value of EU touring for UK artists to the UK, and European Countries;
-
Assess the extent and nature of barriers faced by touring artists post-EU exit, including associated costs to performers and the wider touring economy such as promoters and venues. This includes the following scope of touring professionals:
-
Exhibiting artists (visual arts) and producing artists (i.e., music/theatre/film producers, curators);
-
Performing Artists (including music, theatre, circus, spoken word and magic/illusionists);
-
Outdoor arts (including street theatre, pyrotechnics & light shows);
-
Theatre productions;
-
Musicians (across all genres, including classical music such as orchestras);
-
Support staff of touring artists (e.g. technical staff, drivers).
The specific research questions set out by DCMS at the inception of this research include:
-
Research Question 1: What has the scope and nature of UK and EU touring artist activity (between the UK and EU) been since 2019?
-
Research Question 2: Since 2019, what has the overall economic impact of UK artists touring in the EU for the artist and the UK generally been, including how this has changed year-on-year?
-
Research Question 3: Since 2019, what has the overall economic impact of UK artists touring in EU member states been to the EU more broadly, including benefits to local venues, promoters?
-
Research Question 4: What is the economic impact of EU exit on touring, specifically quantifying its estimated value, and what is the estimated potential value of mitigating or removing barriers and challenges faced by UK artists touring in the EU, including their relative financial and operational impacts?
Methodology
The analysis of the impact of the UK’s departure from the EU on UK artists touring the EU uses a mixed-methods approach. This combines the following sources of evidence:
1. Rapid evidence review
A review was undertaken of the existing data and publications relating to EU touring following EU exit. The review included 33 sources, published mainly since 2021, with a concentration from 2023–2025. The evidence base is drawn from a mix of sector surveys, research reports, policy briefs, econometric and empirical analyses, parliamentary submissions, and analytical commentaries. Contributors included industry bodies and professional associations, unions, research consultancies, university-led policy and evidence centres, European cultural networks, and parliamentary research services. Examples of key studies used include 2024 survey of EU touring by Musicians’ Union[footnote 13], the Association of British Orchestras’ State of the UK’s Orchestras report[footnote 14] and Best for Britain analysis of EU festivals[footnote 15].
2. In-depth interviews
Interviews were carried out by the research team with industry representatives and cultural institutions selected to give a breadth of insight across different types of culture, crew and impacts on the supply chain. In total, 13 in-depth interviews lasting 1-hour were carried out which explored:
-
Trends in EU touring activity
-
Benefits of touring in the EU
-
Barriers to touring the EU
-
Administrative and financial impacts to cultural institutions, performers and crew due to changes to touring since EU exit
-
Mental and physical impacts of changes to touring since EU exit
-
Impact of COVID-19
The number of interviews provides indicative evidence of the impacts of EU exit on touring activity, costs and operations across artists, crews, promoters and venues. However, because the sample is not representative or large, findings should be treated with caution.
Economic impact assessment methodology
The economic impact of exiting the EU is estimated through the loss of revenue derived from EU touring post-EU exit in terms of jobs, labour income and GVA. Full details of the economic modelling methodology can be found in Annex 1.
To estimate the ‘additional’ impact attributable to EU exit, a counterfactual scenario is created comparing UK touring activity in the EU to the USA, assuming a parallel growth pattern in the EU had EU exit related barriers not been introduced. While indicative, this approach aligns with interview evidence that EU-specific frictions (visas, carnets, cabotage) have altered EU routing and scheduling in ways not observed for non-EU markets.
The analysis quantifies the share of box office revenue retained by UK artists and promoters, providing a basis to evaluate the economic loss for the UK economy post-EU exit. This metric highlights the financial implications directly associated with reduced touring in the EU. Because US touring was not subject to these regulatory changes, US data provide the baseline comparator, increasing the reliability of the estimates. However, the EU and US are not perfectly comparable, making it difficult to attribute trend differences solely to introduced barriers. Alternative factors, such as differing economic and cultural trends, could also be responsible (see Annex 1 for a discussion of this method’s strengths and limitations).
Beyond the loss in revenue for UK artists and promoters, UK musicians performing in the EU generate significant local benefits through audience spending on travel, accommodation and hospitality as part of attending a concert[footnote 16]. These revenue impacts to the UK and EU member states are converted into jobs and GVA using a bespoke version of Nordicity’s in-house MyEIA™.
It should be noted that displacement is not considered within the analysis. Displacement considers that economic activity such as jobs or spending may shift from one sector to another and therefore a loss of jobs or economic output in the performance sector does not mean an overall loss of jobs or output in the wider economy.
How to read this report
The report incorporates interviews and economic modelling supported by review of the existing literature, to form an overall assessment of the impact on EU Touring from EU exit using the following structure:
1. Scope and Nature of EU Touring between 2017 and 2024:
-
Examines the breadth and evolution of UK performers touring within the EU since 2017.
-
Includes data on touring artists, annual changes, and size of performances and their support teams.
-
Presents analysis of PRS for Music data supplemented by interview and survey findings.
2. Barriers to EU Touring caused by EU exit
-
Identifies challenges to EU touring post-EU exit using expert interviews and literature review.
-
Details the tangible impacts and costs of EU exit barriers, including administrative, financial, and health-related costs.
-
Highlights reduced opportunities and decisions to limit or cease EU touring.
3. Impacts of barriers to touring in the EU
-
Explores how the barriers to touring caused by EU exit translate into impacts to the UK and EU member states.
-
Evidence sources include findings from interviews supported by selected existing literature.
4. The economic value of removing the barriers from EU exit
-
Estimate the direct, indirect and induced impacts of barriers caused by EU exit.
-
Provides economic impacts in terms of GVA and FTEs for EU member states and the UK.
The conclusion section summarises the insights developed from these different sources of evidence, by directly applying the findings to the four research questions.
A more detailed description of the economic modelling methodology, sensitivity analysis and additional tables are included in the annexes[footnote 17].
Key definitions and scope
Population covered
-
Artists and companies: performing and exhibiting artists across commercial music (including pop, rock, electronic, jazz, folk and other genres), classical music and orchestras, theatre, dance, opera and outdoor arts
-
Producers/curators: producing artists (e.g., music/theatre producers, curators) where relevant to touring.
-
Support staff: touring crews and technical staff (e.g., tour managers, sound/lighting technicians), drivers/haulage, and administrative staff directly supporting tours.
-
Wider stakeholders: promoters, venues, and supply-chain firms linked to touring (e.g., haulage/logistics, production services, merchandise).
Who is ‘UK-based’
-
Individuals or organisations with principal residence or tax base in the UK in the reference year.
-
Includes England, Scotland, Wales and Northern Ireland.
What counts as ‘EU touring’
-
Live performances, exhibitions, or productions by UK based performers delivered in EU member states, including one-off events (for example, festivals) and multi-date runs. Not all EU member states are included in the economic estimates due to lack of data.
-
Revenues, employment and supply-chain activity linked to these EU performances.
Geography
-
The analysis of the impact of UK musicians touring the EU in the post-EU exit period attempts to account for as many EU member state host markets as possible. However, full coverage of all member states is not possible due to data constraints.
-
PRS for Music did not provide data for Cyprus, Iceland, Liechtenstein, Luxembourg, Malta or Norway.
-
In addition, while present within the PRS dataset, further methodological constraints meant Nordicity’s in-house economic impact model could not generate estimates for Finland or the Baltic States (Estonia, Latvia and Lithuania).
-
As a result, these countries are excluded from the economic modelling estimates presented in this report.[footnote 18]
-
The United States is used as a non-EU comparator for counterfactual trends in music analysis.
-
Non-EU territories are out of direct scope of impact estimates.
Time period
-
Descriptive trend window: 2017 to 2024 (to show pre- and post-EU exit patterns).
-
Impact estimation window: 2022 to 2024 (post-reopening). Years 2020 to 2021 are excluded from impact estimates due to COVID-19 disruptions overlapping with regulatory changes (as standard in analysis of this type).
-
Interviews conducted Jan to Feb 2026.
-
The rapid literature review focuses on evidence from 2021 to 2025.
Scale thresholds and activity types
-
General live venues (small/mid-scale).[footnote 19]
-
Stadium and arena tours[footnote 20] (large-scale).[footnote 21]
Units and metrics
-
Performances: PRS performance counts per artist and territory used as activity indicators.
-
Revenue/box office: gross ticket sales inferred from PRS royalties and EU tariffs, split between artist/promoter and venue/ticketing.
-
Gross Value Added (GVA): the contribution of each sector to the economy after subtracting intermediate inputs.
-
Full Time Equivalents (FTE): full-time equivalent employment.
-
Economic impacts: estimated (FTE), labour income, and GVA.
-
Direct impact: The FTE employment, labour income and GVA generated directly within the industry or organisation that is the subject of an economic impact analysis.
-
Indirect impact: The employment, labour income and GVA generated within the directly impacted industry or organisation’s supply chain. It occurs when the directly impacted industry or organisation purchases supplies and other intermediate inputs.
-
Induced impact: The employment, labour income and GVA generated when workers employed due to direct and indirect impacts re-spend their income within a local, provincial or national economy through consumer purchases.
Scope and nature of EU touring between 2017 and 2024
This section provides an analysis of UK performers’ tours across EU member states from 2017 to 2024 to identify the shifts that have occurred since the UK’s exit from the EU. The analysis is primarily drawn from PRS for Music data, which includes performance counts reported by PRS members (songwriters, composers and music publishers) and live performance royalties received from its affiliate collecting societies across the EU.[footnote 22]
PRS data provides a useful proxy for UK music touring activity in the EU because performances by artists playing (even in part) their own music will be captured through this metric. However, the dataset does not capture all UK musicians performing in the EU. Some performers may not be PRS members, while others may have their rights administered through collecting societies outside the UK. In addition, although most PRS members are UK-based, PRS membership is also open to songwriters and composers based overseas. The findings should therefore be interpreted as an indicator of broader touring trends rather than as a comprehensive record of all UK music performances in the EU. However, PRS data remains one of the most comprehensive and consistent sources available for assessing changes in UK music touring activity over time and provides a robust basis for analysing changes in touring patterns over time.
Due to the lack of data for different types of performances (for example, theatre, outdoor arts) the analysis focuses on musicians. In places, this quantitative evidence is supported by findings from the interviews and rapid existing research identified through the literature review which provides further insight on touring trends.
Frequency of touring activity
Between 2017 and 2024, the volume of EU touring activity by UK-based artists fluctuated substantially. Performances in 2021 were 85% lower than in 2019, and although there was a recovery in 2024, overall activity remained 21% below 2019 levels.
Figure 1: Total Number of performances of UK artists In the EU
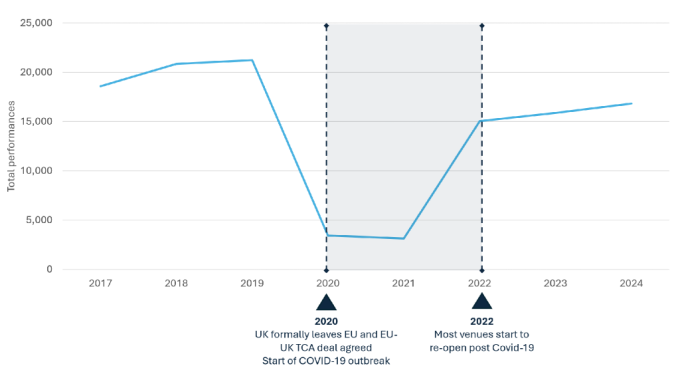
Figure 1.1 is a line chart, displaying the total number of performances of UK artists in the EU over time. The chart highlights a dip between 2020, when the UK formally leaves the EU and the start of the COVID-19 outbreak, and 2022, when most venues reopened after COVID-19.
Source: PRS for Music
Smaller versus larger artists
Findings from the interviews suggest that the reduction in EU touring compared with pre-EU exit and pre-COVID-19 levels has been felt most acutely by small acts, mid-career artists and niche genres. For smaller theatre production companies (for example those represented by the Independent Theatre Council), the impact has been described as ‘really devastating’ and has ‘really stopped a lot of touring’ (ID3).
In contrast, evidence from interviews indicates that larger and mid-sized companies and artists have generally maintained their EU touring activities, thanks to their greater organisational capacity and resources. However, some sector representatives noted that the constraints on EU touring remain ‘quite striking,’ even for these larger acts.
Figure 2 shows PRS data with the number of performances on EU tours, for general live music venues, and stadium and arena tour venues. COVID-19 coincided with the introduction of EU exit rules, which had a severe negative impact on EU touring. Note that the underlying data for the Stadium and Arena Tours category underwent a definition change in 2020; see Annex 1 for further detail.
Artists performing in smaller-capacity venues (general live music venues) saw their performance numbers fall by 85% between 2019 and 2021, recovering somewhat in 2022, but by 2024 they were still 22% below 2019 levels. In contrast, large venues (stadium and arena tours) saw a 97% drop in performances in 2021 compared to 2019, but by 2024 had rebounded to 56% above their 2019 levels, indicating a possible build-up of pent-up demand for larger-scale performances in the post-COVID19 period (and have remained above 2019 levels).
It should be noted that whilst the trend data shows an increase in performances at large venues since COVID-19, this does not indicate a causal estimate of impact of EU exit and COVID-19 as it does not account for what would have happened in the absence of EU exit. To understand the causal impact, these trends must be compared against a counterfactual (explored in later chapters).
Figure 2: Number of performances given by UK performers during tours in EU countries, 2017 to 2024 (stadium and arena tours and general live music venues)
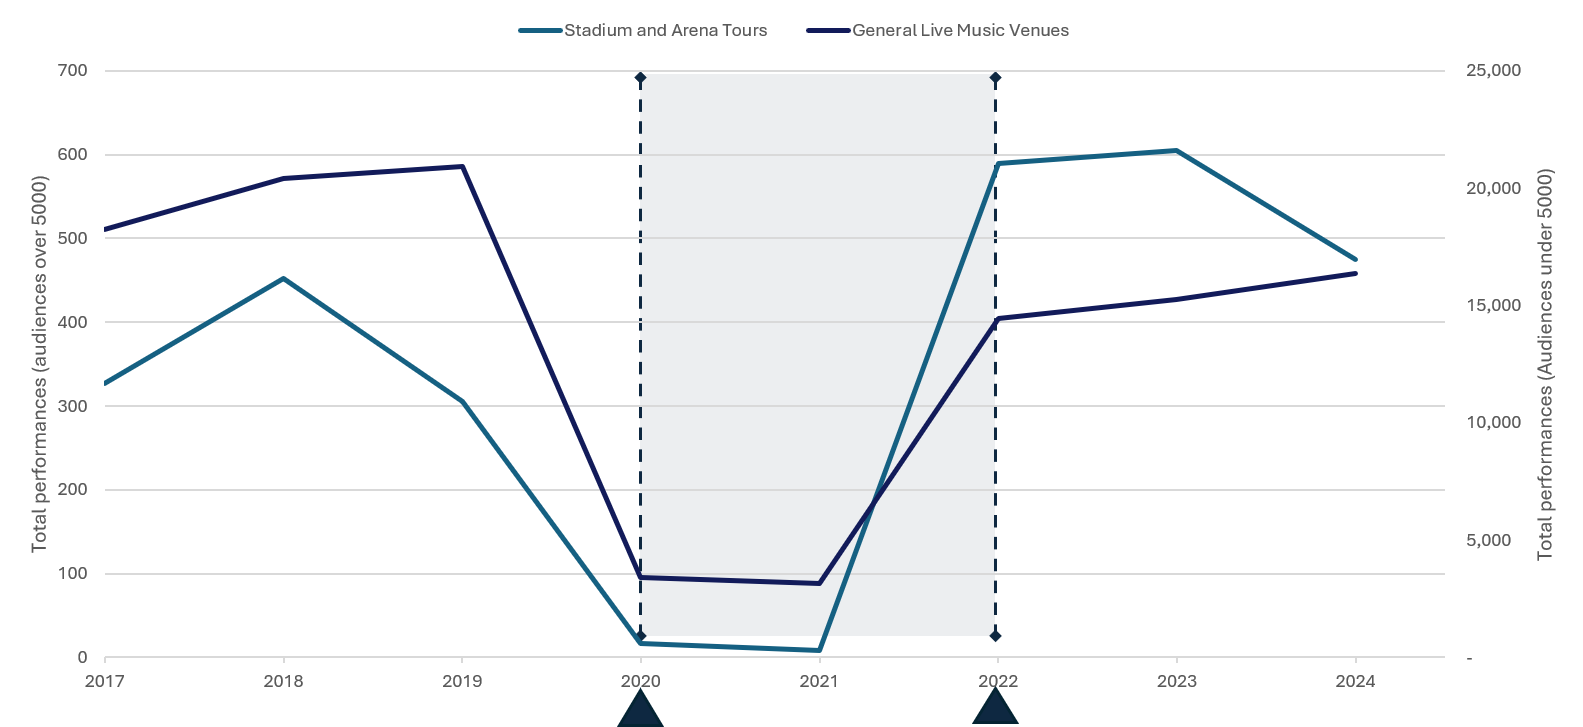
Figure 2 is a line chart, displaying the total number of performances of UK artists in the EU over time, split between stadium and arena tours and general live music venues. The chart highlights a dip between 2020, when the UK formally leaves the EU and the start of the COVID-19 outbreak, and 2022, when most venues reopened after COVID-19.
Source: PRS music
Figure 3 below also supports these findings. It presents proxy measures of average tour length (measured as the average number of performances per artist), which indicate an overall downward trend in performances following the UK’s formal exit from the EU and the onset of COVID-19, before rising again in 2022 as venues reopened.
Average tour length for smaller-capacity venues (general live music venues) remained relatively stable during COVID-19, possibly reflecting a less steep decline in overall performances in these spaces. Larger venues, by contrast, experienced a sharp drop to around one performance per artist in 2021. Following COVID19, however, stadium and arena tours have rebounded strongly, rising to more than seven average performances per artist – above 2019 levels – while smaller venues have remained relatively flat. As above, this may indicate a build-up of demand for larger-scale performances in the post-COVID19 period.
Figure 3: Average number of performances per artist, by audience size (stadium and arena tours and general live music venues)
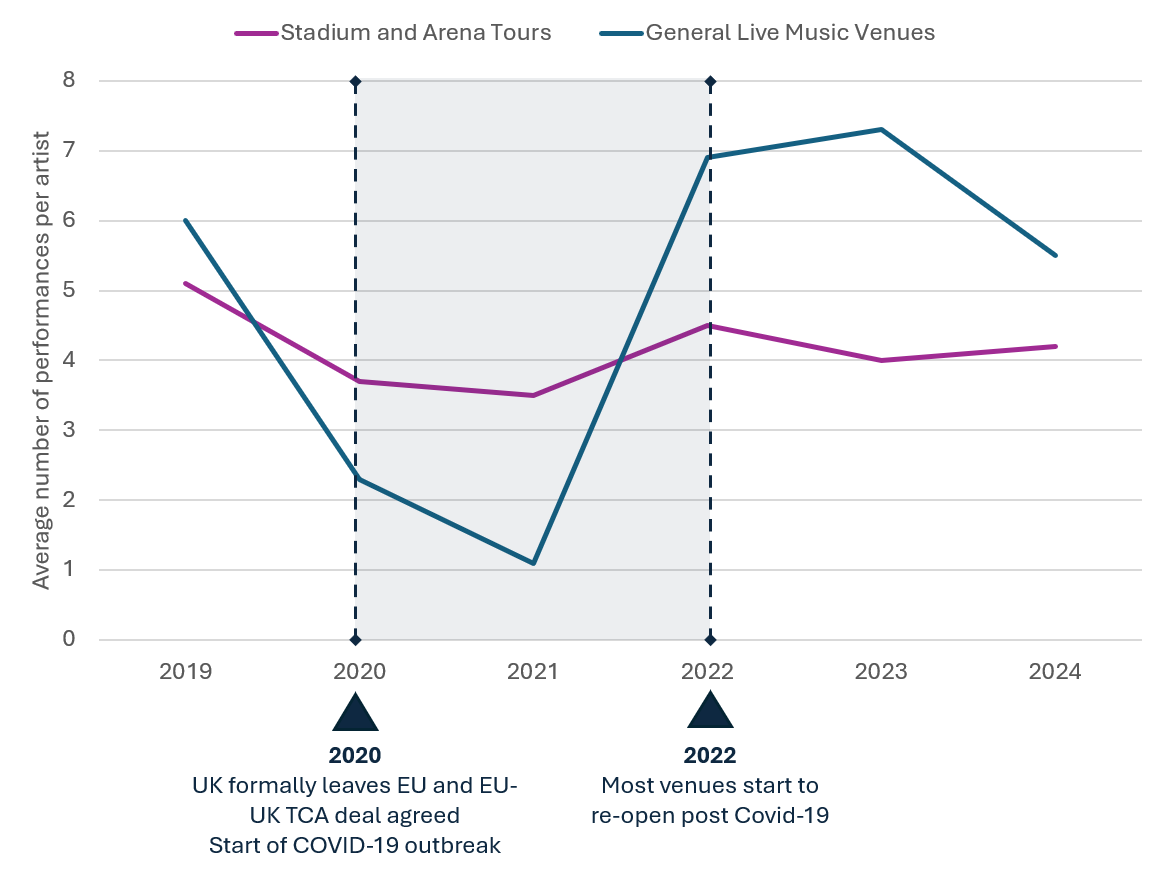
Figure 3 is a line chart, displaying the average number of performances per artist, graphing audiences at stadium and arena tours and general live music venues. The chart highlights a dip between 2020, when the UK formally leaves the EU and the start of the COVID-19 outbreak, and 2022, when most venues reopened after COVID-19.
Source: PRS Music
Geographic spread
PRS for Music data shows that Germany, the Republic of Ireland, France and the Netherlands continue to account for a large share of performances. However, the overall number of performances has fallen, including in some of these key markets. Germany and the Republic of Ireland saw the largest absolute declines in performances from UK artists between 2019 and 2024, with Germany losing over 17,000 performances and the Republic of Ireland over 8,600. However, these headline figures mask different trends by venue size as described below.
Smaller venues (general live music venues)
Germany experienced the largest absolute loss, with over 1,400 fewer performances. Spain also saw a sharp decline, losing around 33% of performances (almost 700), and the Republic of Ireland lost about 30% (around 700). Other countries were less affected; for example, Italy recorded only a small 2% decline over the same period.
Larger venues (stadium and arena tours)
In contrast, performances at larger venues (stadium and arena tours) increased between 2019 and 2024. Germany and the Republic of Ireland saw rises of 93% and 84% (63 and 32 additional performances), respectively. Italy recorded a particularly large increase of 520%, and Spain saw a 123% increase (26 and 16 additional performances), although these percentage changes are from a relatively small starting base.
Note that the above distribution reflects changes in absolute number of performances between countries between 2019 and 2024. Whilst this analysis provides insight on the overall distribution, the findings differ from those found in the economic modelling, where modelling assesses changes in GVA and FTE numbers against a counterfactual scenario.
Figure 4: UK artists’ EU tour performances (Left: General live music venues, Right: Stadium and arena tours)
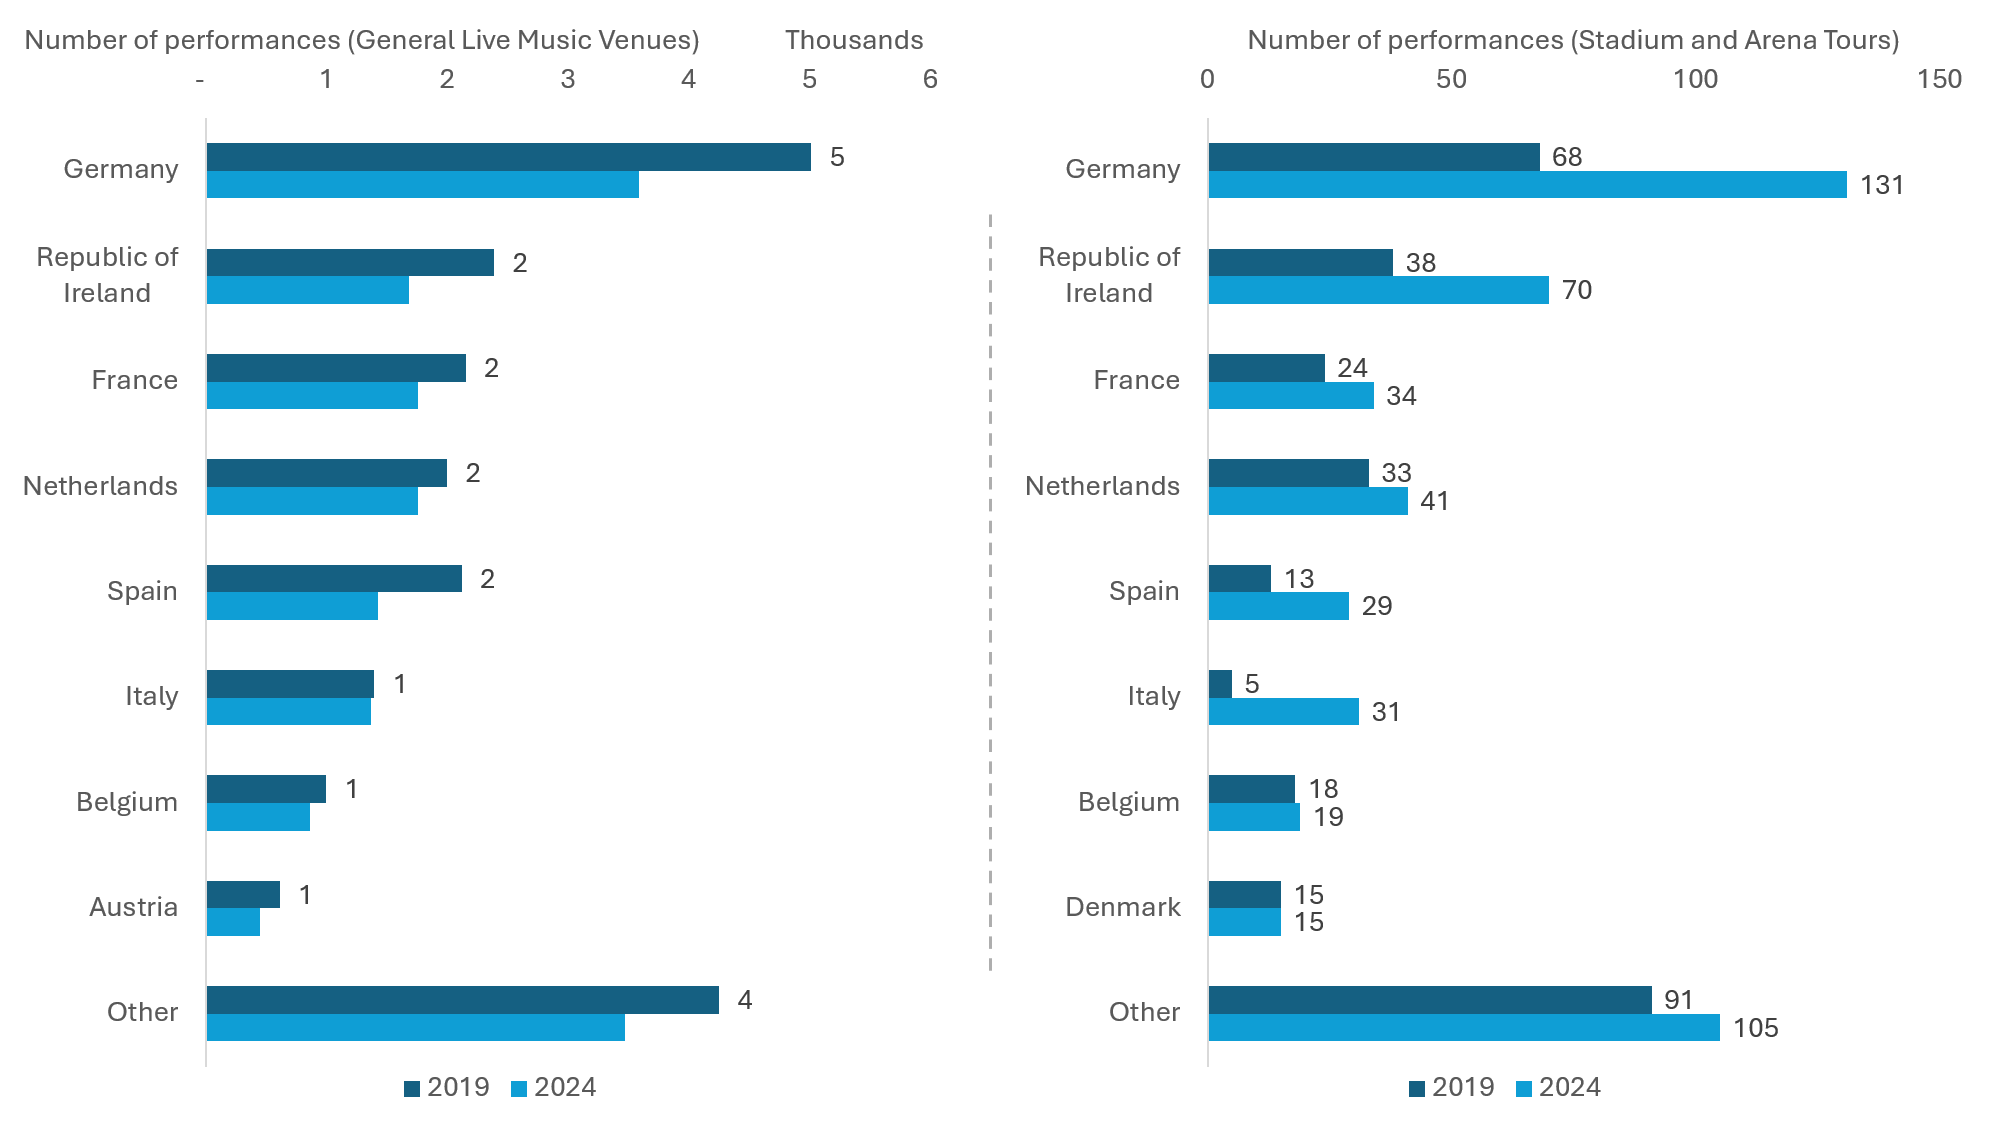
Number of performances (General live music venues, in thousands)
| 2019 | 2024 | |
|---|---|---|
| Germany | 5.0 | 3.6 |
| Republic of Ireland | 2.4 | 1.7 |
| France | 2.2 | 1.8 |
| Netherlands | 2.0 | 1.8 |
| Spain | 2.1 | 1.4 |
| Italy | 1.4 | 1.4 |
| Belgium | 1.0 | 0.9 |
| Austria | 0.6 | 0.4 |
| Other | 4.3 | 3.5 |
| Germany | 68 | 131 |
| Republic of Ireland | 38 | 70 |
| France | 24 | 34 |
| Netherlands | 33 | 41 |
| Spain | 13 | 29 |
| Italy | 5 | 31 |
| Belgium | 18 | 19 |
| Denmark | 15 | 15 |
| Other | 91 | 105 |
Section summary
Frequency of touring activity
-
EU touring activity by UK artists has not fully recovered since EU exit and COVID-19, with overall performance numbers in 2024 remaining 21% below 2019 levels.
-
Performances fell sharply during the pandemic period, reaching levels 85% below 2019 in 2021, before partially recovering between 2022 and 2024.
Smaller vs larger artists
-
Quantitative data shows that performances to small and medium-sized audiences have been negatively impacted and remained 22% below 2019 levels in 2024. This is reinforced by qualitative evidence showing that the downturn has been felt most acutely by smaller and mid-career artists, niche genres, and small theatre companies.
-
Performances to large venues (stadium and arena tours) showed a more substantial rebound after COVID-19 to 56% above their 2019 levels, suggesting pent-up demand for large-scale shows. Qualitative evidence suggests that larger and mid-sized artists and organisations have generally been better able to sustain EU touring activity, supported by greater organisational capacity, established audiences and resources to manage additional administrative and operational requirements.
Geographic Spread
-
PRS for Music data suggests that the overall geographic distribution of UK touring activity across EU member states has remained broadly consistent following EU exit, with Germany, the Republic of Ireland, France and the Netherlands continuing to account for a significant share of performances by UK artists.
-
However, the scale of change since 2019 varies considerably between countries and venue sizes. Smaller-venue touring activity declined significantly in a number of key markets, including Germany, Spain and the Republic of Ireland, while performances at larger venues increased in several countries.
Barriers to EU Touring caused by EU exit
This section draws on in-depth interviews with sector experts and industry representatives, supported by existing literature, to assess how EU exit has changed the operating environment for UK touring in Europe.[footnote 23] The impacts vary depending on sector, scale of operation, touring model and the nember states involved.
The UK’s departure from the EU, Single Market and Customs Union, alongside the end of freedom of movement, has changed the framework within which UK touring activity operates. As a result, UK artists, crews, hauliers and equipment are now subject to a range of immigration, customs, transport, tax and social security requirements. Stakeholders described these as increasing compliance burdens and operational risk.
EU touring was consistently described as having become more administratively complex, financially demanding and uncertain, and less operationally flexible following EU exit. While some requirements existed prior to EU exit, the cumulative effect of these systems has created additional costs, increased administrative pressures and reduced flexibility. Touring was frequently characterised as dependent on simultaneous compliance across multiple interconnected regimes; meaning challenges arising in one area can create wider disruption across schedules, staffing, transport and performances.
Reduced predictability emerged as a consistent theme across all areas of touring activity. This can be particularly challenging for touring activity operating within tightly coordinated schedules and narrow financial margins, where uncertainty can have wider operational and commercial consequences. Stakeholders described rules and processes as changing with limited notice, being interpreted differently across countries, and applied inconsistently at borders or by local authorities. This creates additional risk for performers and touring companies, where minor administrative issues can lead to delays, refusals or financial penalties.
Movement of people
Following EU exit, British performers and support crew no longer benefit from freedom of movement and must instead navigate a combination of EU-level short stay arrangements and Member State specific rules, often within a single tour. UK nationals have been granted permission to travel within the Schengen area for up to 90 days in any 180-day period without a visa for short-stays, but this does not include an automatic right to undertake paid work. Requirements governing paid activity continue to vary between member states, including in relation to eligibility, permitted activities, duration, supporting documentation and application processes.[footnote 24][footnote 25] Interviewees reported that countries can also differ in their interpretation of what constitutes an “artist” or cultural professional, while some require evidence of financial means such as proof of steady income or savings.
Inconsistency in the way that these rules are applied in practice is also identified as a challenge by stakeholders. They described receiving conflicting advice from different authorities and instances where border officials have varied in their interpretation of requirements. This lack of clarity is increasing the administrative burden on organisations and creating a risk of refusals, delays or disruption at the border, even where requirements appear to have been met.
The lack of predictability…different customs offices can give conflicting information. So it’s a lot riskier for them now.
Trade association for theatres, ID3
Visa and work-permit regimes are identified as a major source of additional cost, associated with further administrative burdens and operational uncertainty. Procuring the right documentation often entails fees and requires in-person embassy appointments and time away from rehearsals or production activity.
Additional administrative requirements were also reported in relation to monitoring time spent within the Schengen area and managing crew rotations across tours to avoid exceeding permitted limits. Interviewees noted that touring activity often depends on operational flexibility and the ability to respond rapidly to changing circumstances, including replacing personnel at short notice, extending or shortening tours, and rerouting schedules. Stakeholders reported that the need to remain compliant with Schengen time limits can reduce this flexibility and increase the administrative burden associated with tour planning and delivery.
Smaller organisations and independent artists often lack the administrative and legal expertise necessary to navigate complex compliance requirements. Stakeholders noted that these hurdles impose significant burdens, leading to increased operational costs, heightened stress, and diminished profitability.
There is a disproportionate impact on freelancers, individuals and … smaller companies, … because of the administrative burden and the cost.
Organisation representing dance sector, ID7
Movement of goods and customs
Stakeholders reported that the movement of touring equipment and merchandise between the UK and EU has become more administratively demanding following EU exit, increasing compliance requirements, financial exposure and operational risk.
Temporary movement of goods:
Many organisations now rely on ATA Carnets, an international customs document that allows goods to be temporarily imported without paying duties, provided they are re-exported within a set period.[footnote 26] While carnets provide a recognised framework for temporary admission, stakeholders described the process as administratively burdensome, financially demanding and operationally inflexible. This is particularly for tours involving multiple countries, large volumes of equipment or changing inventories.
Interviewees reported that obtaining and managing carnets can involve substantial upfront costs, including issuing fees and security bonds or deposits linked to the value of the transported goods. The cost of a carnet in the UK is approximately £270 to £444 (including VAT) plus a security deposit of 30 to 40% of the value of the goods/equipment listed. These requirements can place particular pressure on cash flow for smaller organisations, freelancers and emerging artists. Preparing carnet documentation was also described as time-intensive, requiring detailed inventories of equipment, serial numbers and values, with paperwork needing to remain accurate across multiple border crossings and throughout the duration of the tour.
Even minor administrative errors or inconsistencies in documentation can result in significant operational disruption. Cases were reported involving delays at the border, additional charges or financial penalties or, in some cases, the seizure of equipment. The consequences of paperwork errors can be disproportionate, particularly where touring schedules are tightly planned and delays risk knock-on impacts for performances, staffing and venue arrangements. One interviewee explained that if a carnet is not properly discharged, promoters or production companies can face heavy penalties, in some cases reportedly reaching up to 40% of the carnets declared value.
Convention on International Trade in Endangered Species of Wild Fauna and Flora (CITES)
Stakeholders also identified challenges associated with the movement of instruments and equipment containing protected materials covered by the Convention on International Trade in Endangered Species of Wild Fauna and Flora (CITES), including certain woods, ivory and animal products commonly found in musical instruments and bows. Prior to EU exit, movement of these items between the UK and EU did not require the same border processes now associated with third-country movements. It was reported that touring organisations and musicians may now require Musical Instrument Certificates (MICs) or other supporting documentation when travelling internationally with qualifying instruments.
It was reflected that the operation of designated CITES points of entry and exit, alongside differing levels of awareness and enforcement at borders, can create additional uncertainty and administrative requirements for touring artists and organisations. These issues were highlighted as particularly significant for orchestras and musicians travelling with older or specialist instruments. Concerns were also raised regarding the availability and accessibility of designated CITES points of entry and exit on key touring routes. Ultimately it was suggested that this can reduce flexibility for musicians travelling with qualifying instruments and may require alternative travel arrangements or additional planning.
Merchandise
Merchandise was identified by stakeholders as a particular pressure point because of its importance to the financial viability of touring. While VAT and tax arrangements differed between member states prior to EU exit, merchandise transported for sale is now treated as a commercial import into the EU customs territory, rather than moving within the EU single market. As a result, moving goods from the UK into the EU customs territory was reported to create additional administrative and cashflow pressures.
Stakeholders explained that import VAT and, in some cases, customs duties are to be paid when merchandise first enters the EU. Businesses transporting merchandise for sale may need to obtain an Economic Operators Registration and Identification (EORI) number and comply with customs formalities on both sides of the border, with declaration thresholds diverging between the UK and EU. Consignments valued at more than £2,500 generally require a full export declaration before leaving the UK, while commercial goods valued at more than €1,000 must typically be declared when entering the EU. Although these costs can often be reclaimed, industry reports that reimbursement processes can vary significantly between member states and can involve lengthy and unpredictable delays. Industry representatives noted that funds can remain tied up for extended periods, creating cashflow pressures for touring organisations operating on narrow margins. Merchandise income was frequently described as critical to the commercial sustainability of touring activity, particularly for emerging artists and smaller-scale tours.[footnote 27]
Some interviewees reported that, in response to these pressures, artists and touring companies are increasingly using EU-based stock or third-party fulfilment providers to avoid repeatedly moving merchandise across borders. However, stakeholders noted that these approaches can reduce profit margins, increase reliance on intermediaries and limit flexibility to respond to changing demand during tours.
Merch can be the difference between a tour losing money or breaking even for smaller artists.
Organisation representing musicians, ID8
Day-to-day administration of merchandise has also become an issue, particularly where declaration thresholds diverge between the UK and EU. For example, consignments that may qualify for simplified treatment in the UK can require full customs declarations when entering parts of the EU.[footnote 28] This means that consignments that are routine at home can require full declarations when entering the EU.
Disparity in implementation and enforcement
More broadly, customs processes and enforcement practices were reported to vary across member states and points of entry. Interviewees highlighted differences in documentation requirements and local interpretation of the rules, creating operational uncertainty for touring organisations operating across multiple countries.
Requirements are not always applied consistently between locations and may change over time, making it difficult for touring organisations to plan with confidence. Interviewees reported that practices relating to customs declarations, merchandise procedures and the stamping or discharge of ATA carnets can differ between ports, customs offices or individual officials, even where the underlying rules are the same. This variability can lead to longer lead times, higher brokerage costs and increased risk of delays where goods are held at the border pending additional checks or clarification of requirements. Inconsistent enforcement means a minor paperwork mismatch can also translate into withheld fees at settlement or an on-the-spot penalty at the port.
Some described cases where relatively minor discrepancies in paperwork or inconsistencies between accompanying documents and vehicle details resulted in delays, financial penalties or additional checks at the border.
One haulage company stakeholder suggested that customs rules designed for freight hauliers and containerised goods are increasingly being applied to touring vans and smaller-scale touring operations, creating disproportionate administrative burdens.
Transport and haulage
Haulage arrangements have also been affected by the UK’s exit from the EU and were identified as a significant operational challenge. Under the EU-UK TCA, Cabotage and cross-trade restrictions limit the number of movements that UK-registered vehicles can make within the EU, reducing the flexibility for touring logistics. While Cabotage and cross-trade rules are not new and also apply to EU operators in certain circumstances, UK operators now face more restrictive conditions as third-country hauliers.
Table 1.1 Difference between cabotage and cross-trade provisions pre and post TCA
| Movement | Before TCA | After TCA |
|---|---|---|
| Cross-trade: (haulage of goods between two countries by a foreign-registered vehicle) | Unlimited movements | 1 movement (if also conducting cabotage) OR 2 (if not conducting cabotage) |
| Cabotage: (paid loading and unloading of goods in one country by a foreign-registered vehicle in a 7 day period) | 3 movements (within a Member State) | 1 (if also conducting cross-trade) OR 0 (if operator performs 2 cross-trade movements) |
In practice, UK-registered vehicles are limited to up to two additional movements within the EU after an initial international delivery from the UK, before needing to return. This reduces flexibility for multi-stop tours, where equipment would previously have been transported between multiple EU countries as part of a continuous schedule.
In response, some companies have adopted workarounds such as using EU-based hauliers or swapping trucks/trailers at borders. The UK introduced the ‘dual registration’ measure in 2022 as a targeted measure to support specialist events hauliers.[footnote 29] However, not all parts of the sector are able to benefit from this measure. Own account operators, such as an orchestra operating its own specialist vehicle and some specialist coach operators, may not meet the eligibility criteria for reasons such as they are not operating on a hire-and-reward basis.
Many touring organisations rely on specially adapted vehicles designed around the technical and operational requirements of touring productions, meaning that approaches such as vehicle-swapping or outsourcing logistics are not always practical. Interviews with sector representatives suggest these workarounds have knock-on effects; splintering logistics, complicating crew scheduling, and reducing the short-notice flexibility on which touring depends.
The only way to still provide that service to global artists and UK artists into Europe—because live touring is critical to revenue and merch sales—has been for us to set up in the EU as logistics companies so we can operate like any EU haulier for cabotage. Otherwise, a tour simply wouldn’t work in EU countries because of scheduling.
Events Haulage company, ID11
Social security and taxation
Administrative processes for income tax and social security have also contributed to or introduced additional complexity and cashflow pressures for touring artists and organisations. It was reported that these requirements can create significant administrative burdens, particularly where touring activity spans multiple jurisdictions with different systems and timelines.
A1 certificates and social security
Social security coordination requirements apply to touring activity within the EU. A1 certificates, which confirm where an individual pays social security contributions when working across borders, are required for touring staff undertaking temporary overseas work. Delays in obtaining A1 certificates were reported to affect touring timelines and create operational uncertainty, particularly where processing times are unpredictable or where documentation is required before payments are released.
Administrative delays on A1 certificates[footnote 30] and associated documentation have seen European promoters withhold a proportion of fees (sometimes up to 20%) until paperwork was completed and requirements satisfied. These delays result in strained cashflow, increased reliance on advances or bridging finance, and pressure on payroll for performers and crew.
Withholding tax and VAT:
Income earned in the EU may be subject to WHT, meaning that a proportion of earnings is deducted in the country where the activity takes place. While these sums can usually be reclaimed or offset, interviewees reported that the process is often slow and complex, with refunds taking several months across different jurisdictions.
In some cases, delays to these processes and payments have been substantial, with some stakeholders describing waiting several months for tax refunds. Refunds can take many months or even years to be issued with significant cash flow challenges: at the time of interview, one orchestra reported approximately €290,000 (circa. £250,000) in outstanding German WHT refunds dating back to tours since March 2023, alongside a further c. £50,000 pending from a 2024 tour. In some instances the refund processing times were approaching two years.
Withholding tax and VAT obligations were longstanding features of EU touring prior to EU exit. However, these requirements now interact with additional processes, increasing administrative complexity and cashflow pressures for touring organisations across the landscape. Overall, it was reported that delays associated with tax refunds, VAT recovery and administrative documentation can place significant pressure on cashflow management, particularly for organisations undertaking frequent international touring activity.
Section summary: Barriers to EU Touring caused by EU exit
Mobility of people
UK artists and crew must navigate multiple immigration systems with differing rules for short-term paid work. For longer tours, activity is often constrained by the 90/180-day Schengen rule, sometimes requiring separate visas or work permits across multiple member states. Stakeholders reported that this increases administrative burden, costs and operational uncertainty, particularly for multi-country tours.
Temporary movement of goods
Touring productions now rely on ATA Carnets or temporary admission procedures to move instruments and equipment between the UK and EU, creating additional paperwork, fees and compliance requirements.
CITES
Touring with instruments and equipment containing protected materials can require additional certification and compliance processes for affected items, alongside the use of designated points of entry and exit. Stakeholders highlighted particular operational concerns regarding commonly used touring routes.
Merchandise
Merchandise sales are also subject to customs and VAT processes, reducing a valuable revenue stream, particularly for smaller artists and independent touring activity.
Transport and Haulage
Under the EU-UK TCA, UK hauliers are subject to cabotage and cross-trade restrictions, reducing flexibility for multi-country touring schedules and increasing operational costs. Stakeholders also highlighted additional complexity relating to specialist touring vehicles, adapted buses and driver requirements.
Social security and taxation
Performance income in many member states is subject to WHT, while touring activity also requires compliance with social security processes such as A1 certification. Although double taxation agreements exist, reclaim and compliance processes vary across jurisdictions and can be administratively burdensome, creating delays and cashflow pressures.
Cumulative impacts
Interviewees consistently emphasised that these barriers rarely operate in isolation. Touring activity often requires simultaneous compliance across immigration, customs, transport, tax and social security systems, meaning that costs, administrative burdens and operational risks compound across a single tour.
Impacts of barriers to touring in the EU
This section explores how the barriers associated with EU exit translate into economic, operational and cultural impacts to the UK and EU member states. The findings are predominantly informed by interviews, supported by findings from existing literature.
Work opportunities and labour mobility
Evidence suggests that barriers associated with post-EU exit touring arrangements have altered patterns of recruitment and labour mobility, reducing opportunities for UK professionals in the touring workforce. Passport status, visa eligibility and Schengen time-limit rules were described as becoming increasingly important considerations in recruitment and touring decisions, particularly for touring crew and freelance workers undertaking repeated or extended activity within the EU. Possession of an EU-qualifying passport was described as increasingly shaping employability in parts of the sector, where employers are seeking to reduce administrative complexity and compliance risk.
UK workers without an EU passport were reported to be increasingly disadvantaged, routinely losing roles to those who have one. The 90/180-day Schengen rule was identified as a particular challenge for touring crew and freelance workers undertaking extended or repeated touring activity within the EU. One interviewee told us that some EU orchestras initially restricted applications from UK-based applicants outright.
There may be certain band members or tour managers they can’t work with because of the 90/180-day rules (e.g., an 80 to 90 day rule constraint).
Organisation representing musicians, ID2
Existing sector research supports these findings on the loss of opportunities. Analysis from the Independent Society of Musicians (2023)[footnote 31] finds 47.4% of respondents now have less EU work while 27.8% report having no EU work at all.[footnote 32]
Promoters and organisers were also described as becoming more risk-averse when scheduling touring activity requiring rapid cross-border movement. Tight turnaround schedules between UK and EU performances, previously common within festival circuits, were described as carrying greater operational risk due to the potential for border delays, transport disruption or administrative complications. One promoter stated that managers will no longer book a UK artist to perform at an EU festival the day after they perform at a UK festival, reducing opportunities especially for emerging talent.
It used to be common - play a major UK festival on Friday, get in the van, into Europe for a Saturday festival. Now the risk of not making it is too high… So we’re already seeing reduced lower-level activity.
Network for artists, ID8
In line with the interview evidence in this study, existing research also points to reduced UK representation at EU festivals. One study found that EU festival line-ups now feature around 26% fewer UK artists than pre-EU exit.[footnote 33] Border controls, equipment detention, and visa delays have driven cancellations for UK artists, with grassroots acts hit hardest (King’s College London, 2024).[footnote 34] In the orchestral sector, the Association of British Orchestras (2025)[footnote 35] recorded a c.9% drop in overseas performances versus 2019.
Some anecdotal evidence specific to orchestras noted that parts of the sector have adapted operationally over time and suggested that initial reluctance to engage UK-based performers may have eased in certain areas. However, the majority of evidence indicates that additional administrative requirements and operational considerations continue to shape recruitment and touring decisions across the creative and cultural industries.
At the start, lots of EU orchestras weren’t actually kind of offering their roles to UK musicians. You know, they would have disclaimers on their applications that say it was only for EU residents. That’s changed a bit recently. I think it’s got better…
Organisation representing musicians, ID9
Financial viability and earnings
Stakeholders report reduced volume and viability of EU touring since EU exit for UK artists and crews, reducing the earnings repatriated to the UK and impacting employment in touring supply chains. UK Music’s survey of 1,461 creators finds that 30% report that their earnings have been affected by EU exit. Among those affected, 82% say their income has decreased, and 43% say EU touring is no longer viable, citing higher costs, visas/work permits and red tape (UK Music, 2023). [footnote 36]
A lot of our members who spent up to half—or two thirds—of their work in the EU… suddenly the curtain came down.
Trade union representing theatre and entertainment, ID4
For some performers and crew, EU exit has caused them to stop touring Europe altogether after concluding it is no longer financially viable. Depending on the performance type, this represents irreplaceable revenue; opportunities lost within the EU cannot always be replaced domestically due to venue saturation in the UK. Opera sector representatives reported in interviews that the UK scene alone does not have sufficient performance opportunities to sustain/support emerging talent without international touring activity due to the limited number of opera houses.
For some people it marked the end of their career… it’s no longer financially viable to be a touring musician and they’ve just given up… They don’t have the funds.
Organisation representing musicians, ID9
Touring models and delivery
Evidence suggests that barriers associated with post-EU exit touring arrangements have altered the structure, organisation and geographical pattern of touring activity.
Findings suggest that tour design has shifted from traditionally longer and flexible tours across the EU, to shorter and more segmented runs. Artists are increasingly curtailing itineraries or breaking them into discrete blocks, often with returns to the UK between legs. This is because every schedule now needs to be anchored to a hard end date against the 90/180-day rule. Interviewees described this as reducing flexibility within touring schedules and increasing the operational consequences of delays or disruption. They reported that administrative delays, transport disruption or border issues can create knock-on effects across tightly coordinated touring schedules that previously would have been more manageable. This has made short notice or ‘in-and-out’ work such as festival scheduling significantly more difficult and operationally risky than before EU exit.
Interviewees reported that this constraint reduces slack, for example a paperwork delay or travel disruption can trigger knock-on effects, forcing rescheduling or re-routes that would previously have been absorbed. This means that EU-based festivals have become notably harder to integrate with a quick ‘in-and-out’ weekend, becoming more complicated and riskier than before.
It’s impacting how they tour—curtailing, making tours shorter, or having to break it up.
Membership organisation for theatres, ID3
Evidence suggests that touring routes have also become more regionalised. Rather than undertaking the broad, multi-country tours they previously would have, performers are now more commonly focusing on specific sub-regions (for example, Nordic and German-speaking markets). This allows them to target areas with established audience demand while managing logistics, customs, and freight more efficiently within tighter operational windows. This choice is specific to the touring artist and the relationship they have with their audiences: where there is a geographic concentration, there are efficiencies and the opportunity to reduce cross-boundary frictions. Overall, it was reported that these changes reduce the number of markets that can be reached during a single touring cycle and limit opportunities to respond flexibly to late-breaking invitations or commercial opportunities.
In the past, new talents toured many different countries and played a lot of shows; now it’s more focused. They might play [Nordic markets]… or focus on the [German-speaking region]… [southern EU countries] have a higher drop of performances of UK acts than [a large EU market].
Music festival, ID15
Impact on EU member states
Evidence suggests that UK performers remain an important component of live music and cultural programming across parts of the EU. UK performers are acknowledged as being amongst the most popular with European audiences, regularly anchoring club, venue and festival programming. This means that when access to UK performers tightens and touring activity reduces, the effects are felt economically and culturally within EU member states.
Interviewees reported that when barriers reduce the ease or viability of UK touring activity, the effects are felt across EU cultural and local economies. Stakeholders stated that promoters and venue operators can face programming gaps, reduced ticket sales and lower associated revenues where UK acts become more difficult or operationally risky to book. It was consistently emphasised that audience demand for UK performers within the EU remains strong, but that increased administrative complexity and touring costs have made some touring activity more difficult to sustain.
Some UK bands are bigger in parts of Europe than at home; they built those audiences when it was easy—now it’s harder to service them.
Organisation representing musicians, ID10
Interviewees highlighted that a substantial proportion of the economic value generated by touring remains within host economies. Alongside direct promoter and venue revenues, stakeholders identified significant spillover effects, such as local crew and equipment hire. Furthermore, larger artists stimulate ‘music tourism,’ driving considerable audience spending on transport and accommodation within the wider visitor economy. (This broader economic impact is quantified in Chapter 5.) Consequently, when UK artists cannot service demand in EU regions where they have concentrated fanbases, the host cities suffer: venues lose revenue, promoters face programming gaps, and local businesses miss out on predictable peaks of trade.
Cultural impacts associated with reduced touring activity were also identified as being substantial. Live performances from UK performers are seen as a key channel through which styles, production techniques and ideas circulate and are learned. One interviewee identified an often-cited example of The Lion King in Madrid, which reportedly spurred a resurgence of musical theatre audiences there, illustrating how touring works can seed new habits, build sectors and expand the cultural offer for residents. While limited quantitative evidence is currently available to assess these cultural impacts directly, interviewees consistently described touring activity as contributing to broader cultural exchange and creative development across EU cultural ecosystems. Thus, it is expected that EU cities would lose some of the catalytic effect of UK touring.
Career development and exposure
Interviewees consistently described EU touring as an important mechanism for audience development, international visibility and long-term career progression, particularly for emerging artists. Touring activity was also described as supporting broader commercial opportunities, including radio appearances, press coverage, label engagement, streaming growth and future bookings. It was suggested that when those tours do not happen, artists lose immediate income and the follow-on gains resulting in fewer invitations, slower audience growth, and reduced leverage with agents, labels and media. EU touring was identified as an important opportunity for collaborations between the UK and EU music industries, where UK artists are perceived to bring something distinctive and valued.
EU touring was seen by those interviewed as an important component for building awareness and engagement, particularly for emerging talent.
You go into a market, you play some shows. While you’re there, you’re doing radio, press, and other things with local label people on the ground. You’re raising your profile—sales, streams, airplay—all of those things. So, if you’re having difficulty getting into those markets early on, the economic impact is not just the direct impact on your touring, it’s the knock-on impact on all these other things as well.
Organisation representing musicians, ID2
Findings suggest a reduction in international opportunities is squeezing the talent pipeline, making it harder for early-career artists to build sustainable livelihoods from a UK base alone, and risking long-term damage to the arts ecosystem in the UK. The consequences of reducing the talent pipeline are both economic and cultural. If fewer UK artists can access these formative experiences, the UK is likely to lose export revenue and the creative renewal that comes from cross-border exchange. A narrower pipeline would potentially reduce the diversity of voices reaching stages and audiences at home.
One interviewee highlighted how this impact is felt acutely in fields like outdoor arts, which play a vital role in community engagement, transforming public space and reaching underserved audiences through free or low cost events. These diminished development pathways mean fewer companies and practitioners are able to create, scale and tour work internationally. The illustrative analysis of streaming figures below explores the importance of touring in the EU for artists specifically using localised Spotify streaming data.
Illustrative case study analysis of streaming figures (non-causal analysis)
Interview responses suggested that touring in the EU provides important opportunities for performers to grow their market and build a returning audience. To analyse this further, three bands were selected that are either growing their audience or have recently broken into the mainstream. Spotify listenership data from Chartmetric[footnote 37] was analysed to assess how tours have impacted engagement in the area local to the performances. It is reasonable to assume that an increase in listenership might lead to a direct increase in revenue, as well as a strengthening in brand awareness. This data is not causal and there could be a range of reasons why streaming trends change over time. The graphs show monthly listenership between March 2025 and March 2026 for the chosen case study cities, with the indications of when local performances took place. Note, these findings are illustrative with associative patterns only.
Case Study 1: British Lion
British Lion are an English hard rock band formed by Steve Harris, best known as the bassist for Iron Maiden. As part of a short tour in 2025 they played 3 nights in Spain including a night in Barcelona. The number of Spotify listeners in Barcelona peaks around the time of the event suggesting an uptick due to the tour date.
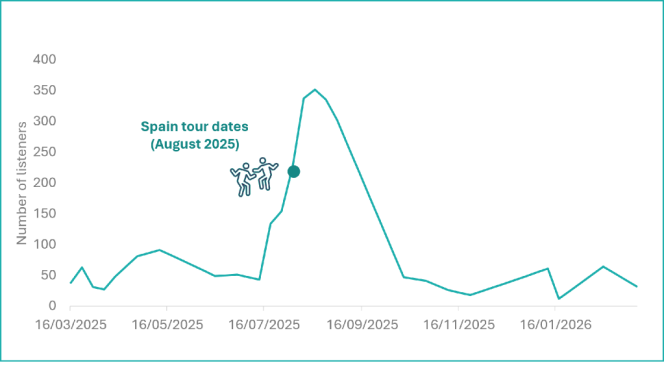
This figure is a line chart that displays the number of listeners of British Lion in Spain, across the nine-month period from March 2025 to January 2026. As mentioned in the text above, there is a spike in line with the 3 nights the band played in Barcelona in August of 2025.
Case Study 2: The Lottery Winners
The Lottery Winners are an Indie pop band from England formed in 2008, who have broken through into the mainstream since 2019. As part of their ‘KOKO’ tour in 2025 - which included the UK and several EU member states - they played one performance in Vienna on 12th July and another on 14th September. Although the September date does not seem to have caused an increase in streaming numbers, the July data saw a considerable spike in local streaming.
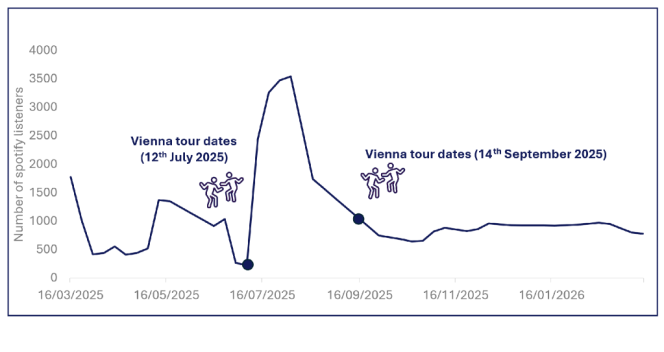
This figure is a line chart that displays the number of listeners of The Lottery Winners in Austria across the nine-month period from March 2025 to January 2026. As mentioned in the text above, there is a spike in line with the July 2025 date played in Vienna.
Case Study 3: Skinny Lister
Skinny Lister are a folk band formed in London in 2009. As part of a European tour at the end of 2025 which included France, Belgium, Netherlands, amongst other countries, Skinny Lister performed in Munich on the 27 November. Monthly listeners on Spotify increased in the period following the performance, suggesting a positive impact on engagement although this does not appear to have been sustained.
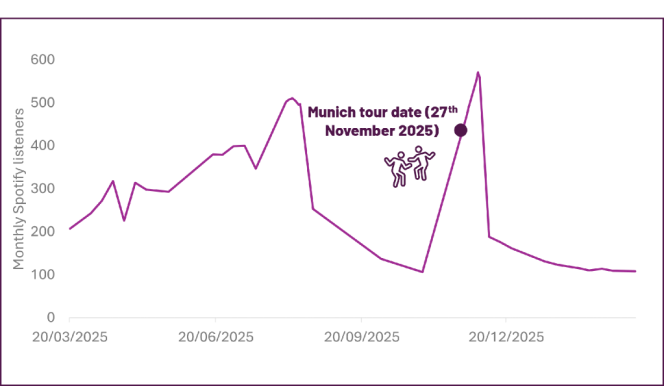
This figure is a line chart that displays the number of listeners of Skinny Lister in Germany across the nine-month period from March 2025 to January 2026. As mentioned in the text above, there is a spike in listeners in line with the November 2025 tour date.
Cultural exchange and soft power
Cultural exchange has been cited as a key impact of touring in the EU. Touring was reported to support collaboration, professional networking, artistic development and audience exchange across borders, allowing performers to engage with different artistic traditions and audiences. This can take the form of dialogue with peers and audiences, creating networking opportunities, co-creation, and the chances to place work in a broader context. Artists can test their performances, learn how different audiences respond, and learn from other performers in ways that feed back into artistic growth.
Meeting and connecting and exchanging ideas with other artists. That networking has huge, huge value.
Organisations representing dancers, ID6
The underlying importance of cultural exchange was the subject of an open letter coordinated by Musicians’ Union, the Association of British Orchestras, LIVE, Pearle, the Independent Society of Musicians, and UK Music, to the EU-UK Summit on 19 May 2025 in London. The letter was signed by over 550 organisations and individuals, including the European Festivals Association.[footnote 38]
Put simply, the current arrangements are not working. Which means audiences, artists and venues in the EU and UK are missing out on the enormous benefits which closer cultural exchange would bring.
Open letter to the EU-UK Summit, 19 May 2025[footnote 39]
The European Commission and the United Kingdom recognise the value of travel and cultural and artistic exchanges, including the activities of touring artists. They will continue their efforts to support travel and cultural exchange.
Common Understanding: A renewed agenda for European Union – United Kingdom cooperation, 19 May 2025[footnote 40]
This has led to the launch of the Culture Exchange Coalition in March 2026 which is intended to take forward the commitment made in the Common Understanding agreement and bring UK and EU policy makers together with live performance organisations.[footnote 41]
Impacts on cultural exchange may in turn affect the UK’s soft power. Touring, cultural exchange and international collaboration have historically been key channels for projecting soft power, helping the UK build international influence through its culture and ideas.[footnote 42] One interviewee set out the benefits of performing arts, particularly dance and opera, as distinctive UK exports with strong EU demand.
The other benefit [is] soft power…a large-scale production like War Horse out – it was a world tour, but there was a substantial European leg – the huge accolades that production won and the kind of soft power that it brought to UK PLC… they couldn’t repeat that tour as they’d done it back then under current regulations, requirements, restrictions. They just simply could not do it. I think they’d exhaust their 90/180.
Trade union for theatre and entertainment, ID4
Wellbeing and workforce sustainability
Evidence suggests that the additional administrative and operational requirements associated with EU touring are placing increased pressure on parts of the touring workforce, particularly within roles responsible for compliance, logistics and tour coordination.
Stakeholders described increased workloads associated with managing visa processes, customs procedures, tax administration and touring logistics across multiple jurisdictions. These pressures were identified as particularly acute for tour managers, production managers, administrative staff and freelance workers operating within tightly coordinated schedules and limited staffing structures.
One CFO of a major merchandise company described the cumulative administrative burden associated with increased compliance requirements as having significant implications for staff workload and wellbeing, with administrative stress triggering sick days and time off.
it[s] pushing people to… breaking point.
Organisation representing musicians, ID2
Additional compliance and travel requirements were also described as increasing stress levels during tour planning and delivery. It was highlighted that the cumulative demands associated with coordinating visa approvals, managing cross-border logistics and maintaining compliance with Schengen time limits across extended touring periods are causing significant strain.
Compressed schedules and additional travel requirements were associated with increased fatigue and reduced opportunities for rest and recovery. In some cases, crew members were described as needing to return to the UK during scheduled breaks or between tour segments in order to remain compliant with Schengen limits, increasing travel demands and reducing downtime during tours. Some interviewees also noted that time spent in the EU for professional activity under the 90/180-day rule can reduce flexibility for personal travel within Europe, particularly for workers undertaking repeated or extended touring activity.
Taken together, evidence suggests that these pressures caused by EU exit are having wider implications for workforce sustainability and retention across parts of the sector due to the material impact on wellbeing.
Connected industries and supply chains
Qualitative evidence suggests a pronounced impact on sectors connected to touring activity, including specialist haulage, merchandise, production and technical support services. Stakeholders reported that some touring productions increasingly rely on EU-based logistics, storage and transport providers to reduce exposure to cabotage restrictions, customs requirements and border-related delays.
Evidence suggests that associated logistical touring crew, technicians and haulage companies are increasingly moving to those based in the EU. According to the haulage company interviewed, before EU exit UK firms handled most contemporary music haulage in Europe for performers from the UK and places like the US. However, they suggested that much of this work has moved to EU based companies.
Some larger companies are also considering moving their storage bases to the EU.
Trade association for theatre, ID3
[We] have built and kept sets in the EU to avoid having to bring them in and out of the UK to tour in the EU.
Organisations representing dancers, ID6
Netherlands is becoming a hub for storing and transportation for European tours.
Trade union for theatre and entertainment, ID4
The choice of merchandise providers appears to be following a similar trend as haulage with interviewees suggesting that EU member states are benefitting at least in part from a move towards EU-based providers.
Companies which specialise in moving sets, backline and merchandise now face fewer EU bookings as productions choose EU-based carriers to avoid cabotage limits, extra border days, and customs friction. One interviewee noted that some international US acts that previously began European tours in the UK as their gateway are now starting touring activity within the EU and sourcing crew and logistics support locally, rather than using UK crews and haulage providers.
Agents used to schedule first/last shows in [a UK city/arena]; now many start in [an EU country] and pick up crew there, then tour around—only coming into the UK for one or two days.
Music agency, ID14
If these trends become more widespread over time, they could reduce demand for UK-based touring infrastructure and support services, including specialist fleets, technical crews and logistics providers, and potentially raise the risk that tours either skip the UK entirely or compress UK dates. Annex 5 includes further analysis of impact on UK haulage based on start and end dates of US touring artists with inconclusive findings.
There is also some evidence to suggest that merchandise supply chains may increasingly be shifting towards EU-based manufacturing, storage and fulfilment. Persistent frictions mean many touring artists are now advised to manufacture or hold stock within the EU. While this change would likely reduce friction during EU tours, it shifts value-add away from the UK with fewer orders for UK printers, finishers, warehousing and fulfilment, and less associated tax revenue and employment. In aggregate, these changes would reallocate work and spend from UK firms to EU counterparts, narrowing the UK’s share of the touring economy. Evidence in this area remains largely anecdotal and no robust industry-wide data was identified to quantify the scale of these changes. As such, these effects are not included within the economic modelling estimates presented in this report.
Dealing with the import and export of merchandise is so complicated that people have kind of recommended just getting it manufactured and printed in Europe.
Membership of musicians, ID9
Environmental impact
Some stakeholders raised concerns about the environmental implications associated with reduced touring efficiency following EU exit. Increased administrative and transport constraints can contribute to more fragmented routing, duplicated journeys and less efficient logistics planning. It was reported that, in some cases, artists, crew and equipment now undertake additional return journeys between the UK and EU that may previously have been avoided through longer continuous touring schedules or more flexible intra-EU routing. Examples provided by interviewees included artists and crew flying back to the UK during gaps between performances because of scheduling constraints or cost pressures, alongside specialist haulage vehicles making additional journeys or operating less efficient routes in response to cabotage restrictions. Some stakeholders also reported increased reliance on parallel logistics arrangements, subcontracting or duplicated equipment movements across jurisdictions.
While these impacts were not quantified within the research, the suggestion was that these changes may increase transport emissions and reduce the overall environmental efficiency of touring activity compared to pre-EU exit operating models.
Wider collaborations and partnership
Although not a barrier to touring itself, the UK’s withdrawal from Creative Europe has had an impact on collaborations, partnerships and funding. Creative Europe had previously invested €89.5 million in 376 UK organisations and supported 190 UK films between 2014 to 2018.[footnote 43] One interviewee suggested that UK partners and budgets previously underwrote the scale and touring reach of many EU-led projects.
People really miss [Programme]. Not only the funding opportunities that flowed from it, but the networking to create collaborations and business relationships that then led to [Region] partners coming back to [Home Country] and collaborating. That was fruitful and positive and is spoken about by some of our smaller members as a significant loss.
Organisation representing theatres, ID3
Section summary: Impacts of barriers to touring in the EU
Overall, evidence suggests that barriers associated with post-EU exit touring arrangements have increased costs, reduced operational flexibility and affected the viability of some UK touring activity within the EU. Stakeholders described impacts extending beyond performers to wider cultural ecosystems, supply chains and associated industries across both the UK and EU.
Work opportunities and labour mobility
Barriers associated with EU touring have reduced work opportunities and increased operating costs across parts of the touring sector. Stakeholders reported reduced hiring flexibility and fewer touring opportunities.
Financial viability and earnings
Interviewees report increasing financial pressures for artists, crew and touring organisations, with disproportionate impacts on freelancers, smaller operators and emerging talent.
Touring models and delivery
Touring schedules have become shorter, more segmented and increasingly regionally focused in response to operational risks and compliance requirements. Stakeholders described reduced flexibility to respond to short-notice opportunities, including festival bookings and additional tour dates.
Impacts on EU member states
Reduced UK touring activity also creates economic and cultural impacts within EU member states. Stakeholders reported that UK artists remain significant audience draws for venues and festivals across parts of the EU, supporting wider economic activity through hospitality, accommodation and visitor spending.
Career development and audience growth
EU touring is important for audience development, international visibility and long-term career progression. Interviewees suggested that reduced access to touring opportunities may limit opportunities for emerging artists to build international audiences, establish industry networks and develop sustainable touring careers.
Cultural exchange and soft power
Touring activity is an important mechanism for cultural exchange, collaboration and artistic development between the UK and EU. Stakeholders also highlighted the role of touring and international cultural activity in supporting the UK’s international cultural influence and soft power.
Wellbeing and workforce sustainability
Increased stress, fatigue and administrative pressures are associated with EU touring, particularly for administrative staff, managers and touring crew. Interviewees suggested that these pressures may have implications for workforce sustainability and retention across parts of the sector.
Connected industries and supply chains
Impacts extend beyond performers to sectors supporting touring activity, including haulage, logistics, merchandise, technical production and storage. Stakeholders reported evidence of some touring-related activity increasingly shifting towards EU-based providers and infrastructure.
Wider collaboration and partnership
Several interviewees highlighted wider impacts on collaboration, professional networks and cultural partnerships following the UK’s withdrawal from Creative Europe, although these impacts extend beyond touring activity specifically.
The economic value of removing the barriers from EU exit
This section estimates the economic costs to the UK and EU member states associated with additional barriers to EU touring following the UK’s exit from the EU. In doing so, it provides indicative evidence of the potential associated benefits that could be realised through reducing these barriers. The findings are shared in terms of revenue, GVA and FTEs based on the methodology set out in Annex 1.
To estimate the impacts associated with EU exit, the analysis compares changes in UK touring activity in the EU with touring activity in comparable international markets that were not subject to the same changes following EU exit.
-
For live music: UK touring activity in the EU is compared with touring activity in the US using PRS for Music data.
-
For orchestras, theatre, dance and visual arts: the analysis compares organisations that toured in the EU prior to EU exit with organisations that toured internationally in non-EU markets, using Arts Council England National Portfolio Organisation (ACE NPO) data.
These comparator markets were selected because consistent data was available and because touring patterns followed similar trends before EU exit.
-
Before EU exit, the EU and US showed a similar trend in UK music touring suggesting that the parallel trends assumption holds[footnote 44] (Annex 1, Figure A.7). Within the ACE NPO data, pre-EU exit touring trends were parallel amongst internationally touring organisations, both to the EU and non-EU markets (Annex 1, Figure A.8).
-
Interview evidence suggests that EU-specific frictions (visas, carnets, cabotage) have altered EU routing and scheduling in ways not observed for non-EU markets.
The findings should be treated as indicative estimates based on the available data. With more detailed data, future research could apply more sophisticated approaches to estimate these impacts further, as discussed in the conclusions section.
The quantitative estimates for live music draw on PRS for Music data, while estimates for orchestras, theatre, dance and visual arts use ACE NPO financial data and proxies. Live music results are not extrapolated to the rest of the cultural sector, which means that GVA estimates are therefore partial and likely conservative of the economic impacts to the cultural sector more widely.
Economic impact estimates
The economic impact estimates presented in this section of the report are calculated using Nordicity’s MyEIA™. It provides estimates of direct, indirect and induced impacts on employment, labour income and GVA. Labour income is part of total GVA estimates.
Types of economic impact
Direct impact: The employment, labour income and GVA generated directly within the industry or organisation that is the subject of an economic impact analysis.
Indirect impact: The employment, labour income and GVA generated within the directly impacted industry or organisation’s supply chain. It occurs when the directly impacted industry or organisation purchases supplies and other intermediate inputs.
Induced impact: The employment, Compensation of Employees (COE) and GVA generated when workers employed due to direct and indirect impacts re-spend their income within a local, provincial or national economy through consumer purchases.
Total impact: The sum of the direct, indirect and induced impacts.
For more information and a detailed model specification, please see Annex 1.5.
Music
UK economy
Based on the methodology described in Annex 1, the economic impact of EU exit on the UK economy associated with changes for touring musicians is presented below.
General live performance
In the general live category, the total estimated loss in box office revenue was £173.1 million in the post-EU exit period (2022 to 2024)[footnote 45].
Box office receipts are typically split between the host venue and the artist and promoter. The venue claims a share based on staging costs and ticketing fees with the remainder going to the artists and promoters. Applying the share of box office receipts retained by artists and promoters (48%)[footnote 46] yields an estimated loss of £83.1 million in revenue for the UK economy between 2022 and 2024.
Based on the change in total EU performances relative to the USA, and the assumptions developed by the Music Managers Forum (MMF) and Office for National Statistics (ONS) data[footnote 47], this decline corresponds to an estimated reduction of 370 direct FTEs over the same period. These findings are supported by the interviews, which described reduced hiring and a movement towards hiring crew with EU passports due to the 90/180-day rule. Musicians’ Union and ISM surveys also suggest difficulty replacing lost EU work elsewhere.
The total economic impact extends beyond the direct effects generated within the UK’s live music sector. Additional impacts arise from two sources: indirect impacts from supply chain businesses providing goods and services to the sector, and induced impacts created by the spending of wages by those employed within the live music sector and its supply chain across the wider economy. (Refer to Annex 1.5 for a detailed explanation of indirect and induced impacts.)
This corresponds to an estimated loss of 1,110 total FTEs, including indirect and induced employment[footnote 48]. The decline in EU touring at general live music venues also resulted in a loss of just under £97.3 million in GVA for the UK economy, including £46.1 million in labour income and including £44.0 million in direct GVA. Interview evidence indicates these impacts fall disproportionately on freelancers and SMEs who lack in-house admin capacity. Respondents described rota changes to stay within 90/180-day limits and outsourcing compliance, alongside reported stress/burnout among managers and crews.
Table 1.2: Economic impact of general live performance, UK economy, 2022 - 2024
| Direct Impact | Indirect Impact | Induced Impact | Total Impact | |
|---|---|---|---|---|
| Employment (FTEs) |
370 | 420 | 310 | 1,110 |
| Labour Income (£m) |
16.6 | 18.9 | 10.6 | 46.1 |
| Gross value added (£m) |
44.0 | 33.8 | 19.4 | 97.3 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding. Modelled estimates; not casual. See Annex 1 for assumptions
Stadium and Arena Tours
In the stadium and arena tours category, the total estimated loss in box office revenue was £147.6 million in the post-EU exit period (2022 to 2024).
Applying the share of box office receipts retained by artists and promoters (48%) yields an estimated loss of £70.8 million for the UK economy between 2022 and 2024. Based on the change in total EU performances relative to the USA, and ONS data in conjunction with the assumptions developed by the Music Managers Forum, this decline corresponds to an estimated reduction of nearly 320 direct crew FTEs over the same period.
This corresponds to an estimated loss of more than 940 total FTEs, including indirect and induced employment, generating £39.3 million in labour income. The decline in EU touring for stadium and arena tours also resulted in a loss of just under £82.9 million in GVA for the UK economy, including £39.3 million in labour income and £37.5 million in direct GVA.
Table 1.3: Economic impact of stadium and arena tours, UK economy, 2022 to 2024
| Direct Impact | Indirect Impact | Induced Impact | Total Impact | |
|---|---|---|---|---|
| Employment (FTEs) |
320 | 360 | 270 | 940 |
| Labour income (£m) |
14.2 | 16.1 | 9.1 | 39.3 |
| Gross value added (£m) |
37.5 | 28.8 | 16.5 | 82.9 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding. Modelled estimates; not causal. See Annex 1 for assumptions.
Total economic impact of live music, UK economy
Across both general live performance and stadium and arena tours, i.e., all musicians performing at venues in the EU who submit set lists to PRS, the total estimated loss in box office revenue was £320.7 million in the post-EU exit period (2022 to 2024).
Applying the share of box office receipts retained by artists and promoters yields an estimated loss of £153.9 million for the UK economy between 2022 and 2024. Based on the change in total EU performances relative to the USA, and the assumptions developed by the MMF alongside data from ONS, this decline corresponds to an estimated reduction of 690 direct FTEs over the same period.
This corresponds to an estimated loss of more than 2,050 total FTEs, including indirect and induced employment. The decline in EU touring also resulted in a loss of just under £180.2 million in GVA for the UK economy, including £85.4 million in labour income and £81.6 million in direct GVA.
Table 1.4: Total economic impact of musicians touring the EU, UK economy, 2022 to 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
690 | 780 | 580 | 2,050 |
| Labour income (£m) |
30.8 | 35.0 | 19.7 | 85.4 |
| Gross value added (£m) |
81.6 | 62.7 | 35.9 | 180.2 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding. Modelled estimates; not causal. See Annex 1 for assumptions.
Orchestras, theatre, dance and visual arts
This section reports the estimated loss in internationally earned income attributable to EU touring as detailed in the methodology derived from the Difference-in-Differences (DiD) modelling[footnote 49], followed by tables detailing how that translates to the economic impact generated by these figures (jobs and GVA), all broken down by sub-sector.
Based on the DiD modelling of orchestras in the ACE NPO survey dataset, grossed up to account for the whole of the UK, UK orchestras have lost an estimated £10.3 million in touring revenue across the post-EU exit period.
This translates into an economic loss of 180 FTEs, £7.1 million in labour income and over £11 million in GVA for the UK economy between 2022 and 2024.
Table 1.5: Estimated economic impact on EU exit on UK Orchestras, 2022 - 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
90 | 50 | 30 | 180 |
| Labour income (£m) |
4.0 | 1.9 | 1.2 | 7.1 |
| Gross value added (£m) |
5.7 | 3.4 | 2.2 | 11.2 |
Source: Estimates based on data from ACE, ONS and ABO. Modelled estimates; not causal. See Annex 1 for assumptions.
Theatre
Modelling results indicate that UK touring theatre companies have lost an estimated £7.0 million in touring income over the post-EU exit period relative to touring theatre companies unaffected by the EU exit.
This translates into an economic loss of 120 FTEs, £4.8 million in labour income and over £7.5 million in GVA for the UK economy between 2022 and 2024. This economic impact found support in the interviews, which pointed to a reduction in co-productions and shorter EU tours.
Table 1.6: Estimated economic impact of EU exit on UK Theatres, 2022 - 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
60 | 30 | 20 | 120 |
| Labour income (£m) |
2.7 | 1.3 | 0.8 | 4.8 |
| Gross value added (£m) |
3.8 | 2.3 | 1.5 | 7.6 |
Source: Estimates based on data from ACE and ONS. Modelled estimates; not causal. See Annex 1 for assumptions.
Dance
Estimates suggest that the EU exit has resulted in touring Dance organisations, including Ballets, losing an estimated £4.5 million in international income between 2022 and 2024.
This revenue loss translates into a loss to the UK economy of 80 FTEs, £3.1 million in labour income and £4.9 million in GVA. Interviewees’ descriptions of fewer residencies and region-focused routing are reflected in these estimates.
Table 1.7: Estimated economic impact of EU exit on UK dance organisations, 2022 - 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
40 | 20 | 20 | 80 |
| Labour income (£m) |
1.7 | 0.8 | 0.5 | 3.1 |
| Gross value added (£m) |
2.5 | 1.5 | 0.9 | 4.9 |
Source: Estimates based on data from ACE and ONS. Modelled estimates; not causal. See Annex 1 for assumptions.
Visual arts
Finally, visual arts organisations, namely museums and galleries, have lost an estimated £3.8 million in revenue between 2022 and 2024 as a result of the UK’s exit from the EU.
This loss in income equates to an estimated loss to the UK economy of 60 FTEs, £2.6 million in labour income and just over £4 million in GVA.
Table 1.8: Estimated economic impact of EU exit on UK visual arts organisations, 2022 - 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
30 | 20 | 10 | 60 |
| Labour income (£m) |
1.4 | 0.7 | 0.4 | 2.6 |
| Gross value added (£m) |
2.1 | 1.2 | 0.8 | 4.1 |
Source: Estimates based on data from ACE and ONS. Modelled estimates; not causal. See Annex 1 for assumptions.
Total economic impact – orchestra, theatre, dance and visual arts organisations
Across the wider arts and culture touring ecosystem, the UK’s exit from the EU is associated with an economic loss of 440 FTEs, £17.5 million in labour income and £27.8 million in GVA to the UK economy between 2022 and 2024, taking into account the estimated loss in international income earned from EU touring attributable to EU exit.
Table 1.9: Estimated economic impact of EU exit on UK orchestra, theatre, dance and visual arts organisations, 2022 - 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
230 | 120 | 90 | 440 |
| Labour income (£m) |
9.9 | 4.7 | 2.9 | 17.5 |
| Gross value added (£m) |
14.1 | 8.3 | 5.4 | 27.8 |
Source: Estimates based on data from ACE, ONS and ABO. Modelled estimates; not causal. See Annex 1 for assumptions.
Total economic impact – all groups of touring artists
Taking into consideration all groups of touring artists analysed in this section – defined as all live UK music touring and UK orchestra, theatre, dance and visual arts organisations - the total economic impact losses to the UK economy between 2022 and 2024 totalled an estimated 2,490 FTEs, £102.9 million in labour income and £208.0 million in GVA, including indirect supply chain and induced impacts. Within these totals, an estimated 920 FTEs and £95.6 million in GVA was lost directly within music, orchestra, theatre, dance and visual arts organisations as a result of the UK’s exit from the EU.
Table 1.10: Estimated economic impact of EU exit for the UK economy, all subsectors, 2022-2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
920 | 900 | 660 | 2,490 |
| Labour income (£m) |
40.6 | 39.7 | 22.6 | 102.9 |
| Gross value added (£m) |
95.6 | 71.0 | 41.3 | 208.0 |
Source: Estimates based on data from PRS, ONS, MMF, NITO, CEBR, ACE and ABO. Modelled estimates; not causal. See Annex 1 for assumptions.
EU member states spillover impacts
General live performance
Direct Impacts
In the general live category, or for musicians performing at general live music venues, the total estimated loss in box office revenue was £173.1 million in the post-EU exit period (2022 to 2024).
The decline in UK touring following the EU exit is estimated to have resulted in a total loss of £562.6 million in consumer spending within the EU. This figure is based on an estimated £90.0 million in lost box office revenue retained in the EU, which accounts for 52% of the total box office revenue (with the remaining 48% retained by UK artists and promoters, based on US ticket revenue splits).
Indirect impacts
Considering that a ticket is assumed to represent 16% of a consumer’s total spend at a live music event, the overall estimated loss in ‘spillover’ spend in the EU-the spending beyond the ticket price was £472.6 million in the post-EU exit period.
This impact includes attendee spending on retail, accommodation, hospitality and travel, beyond the ticket price, which generates economic benefits for host areas. These impacts can be termed ‘high-street’ or local spend, as local businesses like retail stores and hotels benefit from additional footfall when live music events are held.
Geographic distribution of impacts
Based on market size analysis derived from PRS royalty data, GVA losses associated with declines in musicians touring in smaller venues have been greatest in Denmark (£135.8 million), both in absolute terms and intensity, as proxied by loss in revenue per capita. There were also significant absolute impacts in Germany (£81.3 million), France (£39.7 million) and Italy (£44.2 million), as well as in Ireland (£34.0 million), where the loss was also highly intensive.
Figure 5: Estimated loss in absolute spillover revenue in the EU, General Live Performance, 2022 to 2024
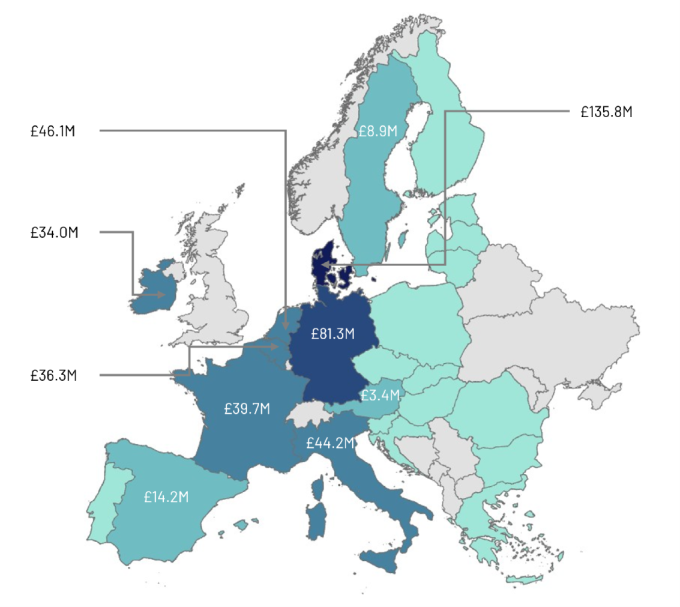
Figure is a map of Europe, without Türkiye or Iceland, showing the estimated loss in absolute spillover revenue for General Live Performance for individual countries. The biggest loss was in Denmark, with one hundred and thirty-five million pounds in lost revenue. The smallest recorded loss was in Austria, with three point four million pounds in lost revenue.
Source: Estimates based on data from PRS
Note: Some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
Western Europe is estimated to have lost the most in spillover revenue post-EU exit, with the exception of the Iberian Peninsula, where losses were more in line with impacts in Eastern Europe than neighbouring member states. Ireland (£6.40 per capita), Belgium (£3.10 per capita) and the Netherlands (£2.60 per capita) stand out as seeing particularly intensive losses on a per capita basis, alongside Denmark (£22.80 per capita), as do the Baltic states albeit to a lesser extent.
Figure 6: Estimated loss in spillover revenue per capita in the EU, General Live Performance, 2022 to 2024
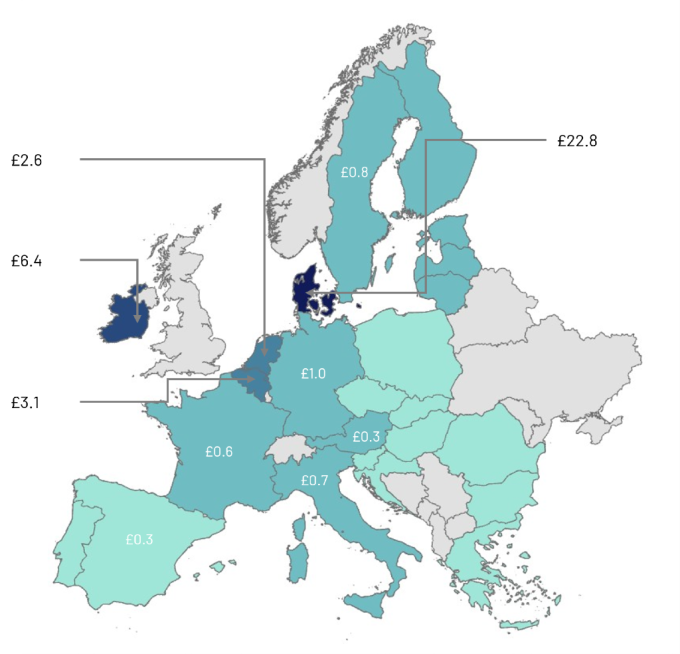
Figure 6 is a map of Europe, without Türkiye or Iceland, showing the estimated loss in absolute spillover revenue per capita for General Live Performance for individual countries. The biggest loss was in Denmark, with one hundred and over twenty-two pounds per capita, and the smallest recorded loss was in Austria and Spain with thirty pence per capita
Source: Estimates based on data from PRS and Eurostat
Note: Some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
On a country-by-country basis, Denmark (£137.6 million), Germany (£116.0 million), Italy (£54 million), France (£49.6 million) and The Netherlands (£49.1 million) all saw estimated losses of over £49 million in GVA as a result of the decline in UK touring musicians. This aligns with the interview evidence, which suggested touring in the EU has become more region-focused (e.g., Nordic and German-speaking markets), while PRS performance indicators showed bigger drops in Spain and Ireland; together this aligns with uneven host-market impacts.
Table 1.11: Economic impact of general live performance spillover impacts, EU member states, 2022 to 2024
| Country | Direct FTEs | Total FTEs | Direct labour income (£m) |
Total labour income (£m) |
Direct GVA (£m) |
Total GVA (£m) |
|---|---|---|---|---|---|---|
| Denmark | 1,140 | 1,870 | 47.0 | 95.3 | 54.2 | 137.6 |
| Germany | 800 | 1,570 | 25.1 | 66.8 | 40.1 | 116.0 |
| Italy | 630 | 1,190 | 10.7 | 29.5 | 17.4 | 54.0 |
| France | 440 | 750 | 12.9 | 32.4 | 16.1 | 49.6 |
| Netherlands | 530 | 890 | 11.0 | 26.4 | 19.6 | 49.1 |
| Ireland | 300 | 410 | 10.7 | 15.4 | 15.3 | 39.2 |
| Belgium | 300 | 520 | 7.0 | 19.5 | 13.0 | 37.1 |
| Spain | 210 | 500 | 4.4 | 14.5 | 6.4 | 23.7 |
| Sweden | 100 | 170 | 2.8 | 6.0 | 3.7 | 11.9 |
| Austria | 70 | 130 | 2.4 | 5.6 | 3.5 | 9.2 |
| Poland | 120 | 210 | 0.8 | 2.1 | 1.5 | 4.8 |
| Czechia | 70 | 110 | 0.7 | 1.5 | 1.1 | 3.5 |
| Romania | 60 | 100 | 0.5 | 1.1 | 0.8 | 2.4 |
| Hungary | 60 | 110 | 0.4 | 1.2 | 0.7 | 2.2 |
| Portugal | 30 | 70 | 0.4 | 1.2 | 0.7 | 2.0 |
| Greece | 30 | 60 | 0.3 | 0.8 | 0.4 | 1.2 |
| Croatia | 20 | 40 | 0.2 | 0.5 | 0.4 | 1.0 |
| Slovakia | 20 | 30 | 0.1 | 0.3 | 0.2 | 0.7 |
| Bulgaria | 10 | 10 | 0.1 | 0.1 | 0.1 | 0.1 |
| Total | 4,940 | 8,740 | 137.4 | 320.2 | 195.3 | 545.4 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, Eurostat, NITO and CEBR
Figures may not sum due to rounding, some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
The loss in spillover revenue in the EU, from UK artists touring general live music venues is estimated to have generated a loss of almost 5,000 direct FTEs between 2022 and 2024. When supply chain employment and induced employment is included, this total reduction in spillover spend of £472.6 million translates into an estimated loss of 8,740 total FTEs. The decline in EU touring at general live music venues also resulted in an estimated loss of £545 million in GVA for the included EU member states. This figure encompasses £195 million in direct GVA and £320.2 million in labour income and £195 million in direct GVA. Interviews from sector representatives reported that they had been told by stakeholders in venues and festivals that there is weaker box office when UK acts are harder to secure and reduced audience spend on hospitality and travel; it was suggested that UK acts are strong draws whose absence dampens local trade.
Table 1.12: Economic impact of general live performance spillover impacts, EU member states, 2022 - 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
4,940 | 2,080 | 1,700 | 8,740 |
| Labour income (£m) |
137.3 | 101.8 | 81.1 | 320.2 |
| Gross value added (£m) |
195.3 | 196.6 | 153.5 | 545.4 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, Eurostat, NITO and CEBR
Note: Figures may not sum due to rounding, some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
Stadium and arena tours
In the stadium and arena tours category, the total estimated loss in box office revenue was £147.6 million in the post-EU exit period (2022 to 2024).
Based on the assumptions outlined in the methodology (Annex 1) and market size analysis of PRS data, the total estimated loss in spillover spend in the EU as a result of the decline in UK stadium and arena touring was £402.9 million in the post-EU exit period[footnote 50]. This includes spending on retail, accommodation, hospitality and travel. Interviewees’ accounts of audience travel, accommodation and food and drink around shows support the presence of sizable non-ticket spend. Interviewees reported that promoters had seen reduced ‘music tourism’ due to less UK acts touring in the EU.
Displaying a similar pattern to the general live performance category, this loss in spillover revenue was concentrated in Western Europe, with significant losses in Germany (£121.2m), France (£52.2m), Italy (£41.8m), the Netherlands (£44.8m) and Ireland (£42.0m). The most significant losses in the stadium and arena tours category were in Germany.
Figure 7: Estimated loss in absolute spillover revenue in the EU, stadium and arena tours, 2022 to 2024
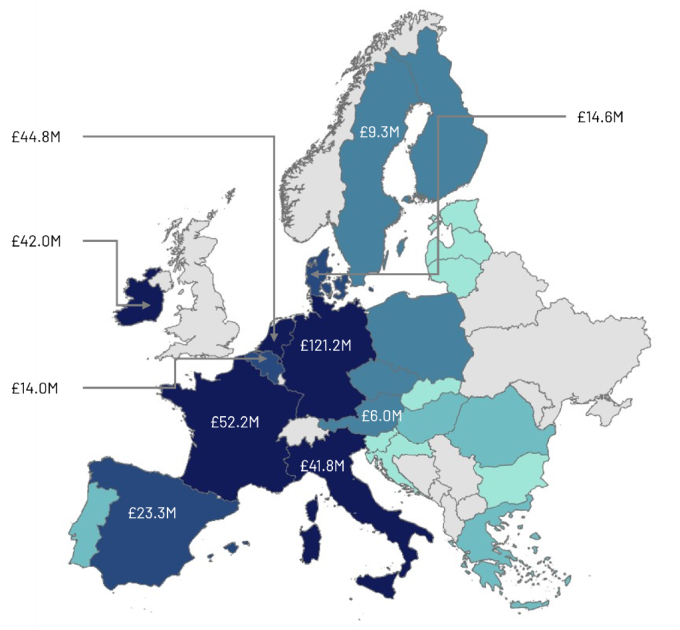
Figure 7 is a map of Europe, without Türkiye or Iceland, showing the estimated loss in absolute spillover revenue for stadium and arena tours for individual countries. The biggest loss was in Germany, with just over one hundred and over twenty-one million pounds, and the smallest recorded loss was in Austria with six million pounds.
Source: Estimates based on data from PRS
Note: Some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
The most intensive losses on a per capita basis resulting from a decline in UK artists touring EU stadium and arena tours were in Ireland (£7.80 per capita), Denmark (£2.50 per capita) and the Netherlands (£2.50 per capita).
Figure 8: Estimated loss in spillover revenue per capita in the EU, stadium and arena tours, 2022 to 2024
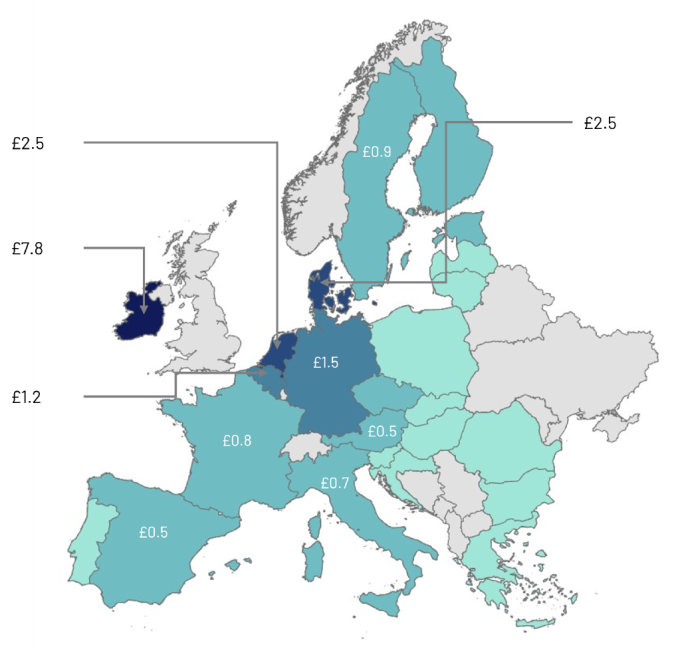
Figure 8 is a map of Europe, without Türkiye or Iceland, showing the estimated loss in absolute spillover revenue per capita for stadium and arena tours for individual countries. The biggest loss was in the Republic of Ireland, with over seven pounds per capita, and the smallest recorded loss was in Austria and Spain with fifty pence per capita.
Source: Estimates based on data from PRS and Eurostat
Note: Some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
On a country-by-country basis, Germany, France, Italy, Ireland and the Netherlands all saw estimated losses of over £47 million in GVA as a result of the decline in UK touring musicians performing at stadium and arena tours.
Table 1.13: Economic impact of stadium and arena tours performance spillover impacts, EU member states, 2022 to 2024
| Country | Direct FTEs | Total FTEs | Direct labour income (£m) |
Total labour income (£m) |
Direct GVA (£m) |
Total GVA (£m) |
|---|---|---|---|---|---|---|
| Germany | 1,190 | 2,340 | 37.4 | 99.6 | 59.7 | 173.0 |
| France | 580 | 980 | 16.9 | 42.6 | 21.1 | 65.2 |
| Italy | 590 | 1,120 | 10.1 | 27.9 | 16.5 | 51.1 |
| Ireland | 380 | 500 | 13.2 | 19.0 | 18.9 | 48.4 |
| Netherlands | 520 | 860 | 10.7 | 25.7 | 19.1 | 47.7 |
| Spain | 340 | 660 | 7.2 | 18.3 | 10.5 | 29.5 |
| Denmark | 120 | 200 | 5.1 | 10.3 | 5.8 | 14.8 |
| Belgium | 110 | 200 | 2.7 | 7.5 | 5.0 | 14.3 |
| Sweden | 110 | 180 | 2.9 | 6.2 | 3.9 | 12.4 |
| Poland | 200 | 350 | 1.3 | 3.6 | 2.5 | 8.0 |
| Austria | 50 | 100 | 1.8 | 4.2 | 2.7 | 6.9 |
| Czechia | 120 | 190 | 1.2 | 2.7 | 1.9 | 6.2 |
| Portugal | 60 | 120 | 0.8 | 2.1 | 1.4 | 3.7 |
| Romania | 70 | 110 | 0.5 | 1.2 | 0.9 | 2.7 |
| Hungary | 60 | 110 | 0.4 | 1.2 | 0.7 | 2.2 |
| Greece | 50 | 100 | 0.4 | 1.2 | 0.7 | 1.9 |
| Croatia | 30 | 60 | 0.3 | 0.9 | 0.6 | 1.6 |
| Slovakia | 40 | 60 | 0.3 | 0.7 | 0.5 | 1.5 |
| Bulgaria | 20 | 30 | 0.1 | 0.4 | 0.2 | 0.7 |
| Total | 4,640 | 8,270 | 113.4 | 275.3 | 172.5 | 491.8 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, Eurostat, NITO and CEBR
Figures may not sum due to rounding, some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
This corresponds to an estimated loss of 8,270 total FTEs and £275.3 million in labour income, including indirect supply chain and induced employment and associated earnings. Of this total, 4,640 FTEs and £113.4 million in labour income were due to direct losses to the EU-member state venues and music industry. The decline in EU touring on stadium and arena tours resulted in a loss of £491.8 million in GVA in EU member states economies, including £172.5 million in direct GVA, or GVA directly attributable to the UK live music sector.
Table 1.14: Economic impact of stadium and arena tours performance spillover impacts, EU member states, 2022 to 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
4,640 | 1,880 | 1,750 | 8,270 |
| Labour income (£m) |
113.4 | 82.3 | 79.6 | 275.3 |
| Gross value added (£m) |
172.5 | 166.4 | 152.9 | 491.8 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, Eurostat, NITO and CEBR
Figures may not sum due to rounding, some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
Total economic impact of live music, EU economy
Across both general live and stadium and arena tours categories, for all musicians performing at venues in the EU, the total estimated loss in box office revenue was £320.7 million in the post-EU exit period (2022 to 2024).
The total estimated loss in spillover spend in the EU as a result of the decline in UK touring was £875.5 million in the post-EU exit period. This includes spending on retail, accommodation, hospitality and travel.
Across all live performance venue sizes, Germany (£202.5 million) represented the EU member state with the highest estimated loss in revenue resulting from the decline in EU touring of UK musicians. Losses in Denmark (£150.4 million), France (£92.0 million), Italy (£86.0 million) and the Netherlands (£90.9 million) were where the next largest losses were estimated.
Figure 9: Estimated loss in absolute spillover revenue in the EU, 2022 to 2024
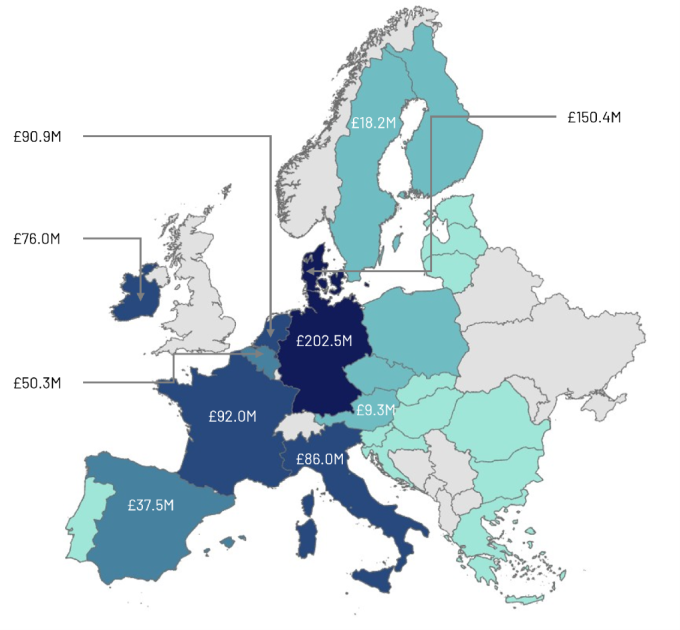
Figure 9 is a map of Europe, without Türkiye or Iceland, showing the estimated loss in absolute spillover revenue for individual countries. The biggest loss was in Germany, with over two-hundred and two million pounds, and the smallest recorded loss was in Austria with over nine million pounds.
Source: Estimates based on data from PRS
Note: Some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
On a per capita basis, Denmark (£25.2 per capita) and Ireland (£14.2 per capita) saw the most intensive losses in revenue. The Iberian Peninsula and most of the included member states in Eastern Europe saw less intensive losses on a per capita basis.
Figure 10: Estimated loss in spillover revenue per capita in the EU, 2022 to 2024
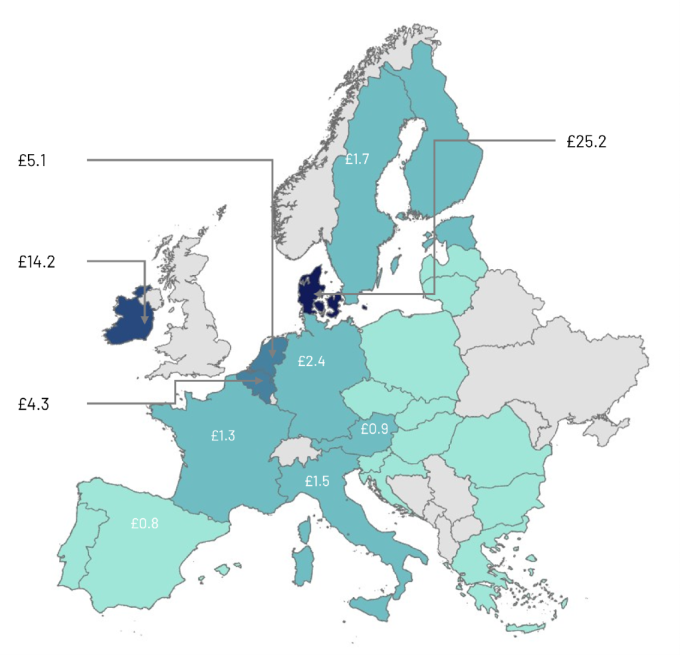
Figure 10 is a map of Europe, without Türkiye or Iceland, showing the estimated loss in absolute spillover revenue per capita for individual countries. The biggest loss was in Germany, with over twenty-five pounds per capita, and the smallest recorded loss was in Spain with eighty pence per capita.
Source: Estimates based on data from PRS and Eurostat
Note: Some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
On a country-by-country basis, Germany saw the largest impact, with a direct loss of almost 2,000 FTEs and £100 million in GVA (and 4,000 FTEs and around £290 million in GVA when indirect and induced impacts are included) between 2022 and 2024. Denmark, France, Italy, the Netherlands and Ireland all saw large estimated direct losses of over £30 million (or £80 million in GVA once indirect and induced impacts are included). This results due to a decline in UK touring musicians, based on PRS royalty data as a proxy for market share.
Table 1.15: Economic impact of UK musicians touring the EU, spillover impacts, EU member states, 2022 to 2024
| Country | Direct FTEs | Total FTEs | Direct labour income (£m) |
Total labour income (£m) |
Direct GVA (£m) |
Total GVA (£m) |
|---|---|---|---|---|---|---|
| Germany | 1,990 | 3,910 | 62.5 | 166.3 | 99.8 | 289.0 |
| Denmark | 1,260 | 2,070 | 52.1 | 105.6 | 60.1 | 152.4 |
| France | 1,020 | 1,730 | 29.8 | 75.0 | 37.2 | 114.8 |
| Italy | 1,220 | 2,310 | 20.8 | 57.5 | 33.9 | 105.1 |
| Netherlands | 1,050 | 1,750 | 21.6 | 52.1 | 38.7 | 96.8 |
| Ireland | 680 | 910 | 23.8 | 34.4 | 34.3 | 87.7 |
| Spain | 550 | 1,160 | 11.6 | 32.8 | 16.9 | 53.3 |
| Belgium | 410 | 720 | 9.6 | 27.1 | 18.1 | 51.3 |
| Sweden | 210 | 350 | 5.8 | 12.2 | 7.6 | 24.3 |
| Austria | 120 | 230 | 4.2 | 9.9 | 6.2 | 16.1 |
| Poland | 320 | 560 | 2.1 | 5.7 | 4.0 | 12.8 |
| Czechia | 190 | 300 | 1.9 | 4.2 | 3.0 | 9.7 |
| Portugal | 90 | 190 | 1.2 | 3.3 | 2.1 | 5.7 |
| Romania | 130 | 210 | 1.0 | 2.4 | 1.6 | 5.1 |
| Hungary | 120 | 220 | 0.9 | 2.3 | 1.4 | 4.5 |
| Greece | 80 | 160 | 0.7 | 2.0 | 1.1 | 3.1 |
| Croatia | 50 | 100 | 0.5 | 1.4 | 1.0 | 2.6 |
| Slovakia | 60 | 90 | 0.4 | 1.1 | 0.7 | 2.2 |
| Bulgaria | 30 | 40 | 0.2 | 0.5 | 0.3 | 0.8 |
| Total | 9,580 | 17,010 | 250.8 | 595.5 | 367.8 | 1037.2 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, Eurostat, NITO and CEBR. Figures may not sum due to rounding, some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions
This corresponds to an estimated loss of over 17,000 total FTEs, including indirect supply chain and induced employment. The decline in EU touring from UK musicians also resulted in a loss of £1.04 billion in GVA in EU member states economies, including £595.5 million in total labour income and £368 million in direct GVA, or GVA generated by the UK live music sector.
Table 1.16: Economic impact of UK musicians touring the EU, spillover impacts, EU member states, 2022 to 2024
| Direct impact | Indirect impact | Induced impact | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
9,580 | 3,960 | 3,450 | 17,010 |
| Labour income (£m) |
250.8 | 184.1 | 160.6 | 595.5 |
| Gross value added (£m) |
367.9 | 363.0 | 306.3 | 1037.2 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, Eurostat, NITO and CEBR
Figures may not sum due to rounding some EU member states excluded. Modelled estimates; not causal. See Annex 1 for assumptions.
Section summary: The economic value of removing the barriers from EU exit
Economic modelling finds that reduced UK touring activity after EU exit is associated with significant modelled losses to the UK. Live music—especially smaller-scale tours in general live music venues—bears the brunt of these losses. Other touring art forms, including orchestras, theatre, dance and visual arts, saw additional but smaller declines, with orchestras most affected. These reductions in UK touring also generated substantial losses for EU host countries, concentrated in Western Europe and particularly affecting Germany, Denmark, France, Italy, the Netherlands and Ireland.
Impact to the UK
Taking into consideration all groups of touring artists analysed in this section, all live UK music touring and UK orchestra, theatre, dance and visual arts organisations, the direct economic impact losses to the UK economy between 2022 and 2024 totalled an estimated 920 FTEs and £95.6 million in GVA, (totalling 2,490 FTEs and £208.0 million with indirect supply chain and induced impacts included).
Music
This analysis found that in the UK, including both the general live performance and the stadium and arena tours categories, EU exit is estimated to correspond to an estimated reduction of almost 700 FTEs and over £81.6 million in GVA directly from the UK’s live music sector. When the impact of businesses providing supply chain products and services to the sector, as well as the induced impacts are included, the total economic impact is estimated to have exceeded 2,000 FTEs and £180.2 million between 2022 and 2024.
Modelled results are largely driven by the decline in those musicians touring to general live music venues, a finding that is in line with qualitative evidence from research interviews that highlighted how the barriers created by the EU exit have disproportionately affected smaller scale UK touring musicians.
Other sectors, orchestras, theatre, dance and visual arts organisations
The UK’s exit from the EU had a total direct economic impact across orchestra, theatre, dance and visual arts of £14 million in GVA, and a loss of 230 FTEs between 2022 and 2024 (totalling £27.8 million in GVA and 440 FTEs when indirect and induced impacts are included). Orchestras saw the largest estimated declines in international touring.
Impact to the EU
This decline in UK touring activity also impacts the EU. Live music concerts generate significant activity for a local area, as ticket costs only represent a small proportion of an attendee’s total expenditures. This is referred to as high-street spillover spend and encompasses the decline in spending on accommodation, retail and travel associated with attendance to a concert.
Economic modelling indicates that the direct spillover impacts to EU host countries totalled £368 million in GVA, and £1.04 billion in total GVA when indirect and induced impacts are included.
This impact was highest in Germany, largely driven by declining performances at larger venues (stadium and arena tours) from UK musicians. However, when looking at smaller scale artists performing at general live music venues, Denmark saw the largest declines in spending and associated economic impact. In total, economic modelling finds that economic impacts in the EU were concentrated in Western Europe, with France, Italy, the Netherlands and Ireland all also seeing an estimated total GVA impact in excess of £80 million between 2022 to 2024.
Conclusions
Research Question 1: What has been the scope and nature of UK and EU touring artists?
This research provides consistent evidence that EU touring activity by UK artists has become more constrained since 2019, particularly for smaller-scale performers. Whilst overall music performance data showed recovery in 2024, this remained 21% below 2019 levels.
There are some significant differences in trends between large- and small-scale music tours post-EU Exit and COVID-19. Large-scale touring (stadium and arena tours) has largely recovered and, in some cases, expanded. This suggests that better-resourced artists and promoters are more able to overcome new frictions. However, this recovery in performance numbers after COVID-19 and EU exit should be treated with caution. As shown in subsequent conclusions, when these observed performance levels are compared to a counterfactual trajectory (i.e. the levels that would have been expected had pre-2019 trends continued without EU exit), performances are estimated to be lower than would otherwise have been.
In contrast, small and mid-scale touring (general live music venues) has not recovered fully post COVID-19. As of 2024, performances by UK artists in EU general live music venues remain materially below 2019 levels, and interviews consistently report that smaller acts, niche genres and independent companies have experienced the steepest loss of viability.
Geographically, UK artists are still touring broadly the same EU markets – with Germany, the Republic of Ireland, France and the Netherlands remaining key destinations. However, the evidence points to a structural shift towards shorter, more segmented and regionally focused tours, with less scope for spontaneous festival bookings or multi-country runs.
Research Question 2: What is the economic impact of UK artists touring in the EU for the artist and the UK generally?
The UK’s departure from the EU is modelled as having a negative economic effect on both UK artists and the wider UK economy, though headline performance metrics have partially rebounded since the combined impacts of EU exit and COVID-19.
Between 2022 and 2024, the UK’s exit from the EU is estimated to have diminished the economic contribution of UK live music touring, along with UK orchestra, theatre, dance, and visual arts organisations. This potential reduction in economic value is calculated to correspond to a loss of 920 direct FTEs and £95.6 million in direct GVA. When indirect and induced impacts are factored in, the total estimated impact rises to 2,490 FTEs and £208.0 million.
This overall estimate includes impacts on the UK music sector. Between 2022 and 2024, UK music artists and promoters are estimated to have suffered a loss in direct employment and GVA of 690 direct FTEs and £81.6 million respectively (or 2,050 FTEs and £180.2 million GVA when indirect and induced impacts are included).
The impact extends to orchestras, theatre, dance, and visual arts, which collectively incurred direct estimated losses of £14.1 million in GVA and 230 FTEs. When including indirect and induced effects, these losses rise to an estimated £27.8 million and 440 FTEs.
The economic impacts are uneven across venue sizes and artist tiers. Small and mid-scale music performances (general live music venues) account for an estimated loss of over 370 direct FTEs and £44.0 million in direct GVA, while large-scale shows (stadium and arena tours) account for a loss of nearly 320 direct FTEs and £37.5 million in direct GVA.
Interviews and sector surveys support these findings. Core frictions such as 90/180-day Schengen limits, country-specific visas/work permits, ATA carnets, cabotage rules and divergent VAT/withholding-tax regimes raise fixed and uncertainty costs and strain cash flow. Tours have shifted toward shorter, segmented and more region-focused runs with less last-minute flexibility, while administrative load and added travel contribute to stress and burnout risks, particularly for freelancers and SMEs. Some logistics and merchandise work appears to have moved to EU providers to navigate cabotage and border frictions (not quantified in the modelling).
It should be noted that the above findings are indicative and correlational. Economic modelling relies on utilising a non-EU (US) counterfactual to estimate the lost revenue and infer box office from PRS royalties and tariffs. The findings also exclude most non-ticket revenues and added operating costs unless reflected as fewer performances.
Research Question 3: What is the economic impact to EU member states of UK artists touring?
The evidence suggests that reduced UK touring activity following the UK’s departure from the EU has had a measurable negative economic impact across a number of EU member states. These impacts extend beyond ticket revenues to wider local economic activity associated with live events, including hospitality, accommodation, transport, local production services and music tourism.
Quantitative analysis estimates that reduced UK touring activity has resulted in approximately £367.9 million in lost direct GVA across EU host markets. When indirect and induced effects are included, the total estimated impact rises to approximately £1.04 billion.
The impacts are distributed across both large and small venues, though general live music venues account for a slightly greater share of losses. Estimated direct GVA losses associated with smaller venues total £195.3 million, rising to £545.4 million when indirect and induced impacts are included, compared with £172.5 million direct GVA losses for larger venues, increasing to £491.8 million including wider economic effects.
Impacts vary by region and are particularly concentrated in Western European markets. Germany records the largest absolute loss, with almost £100 million direct GVA and ~1,990 direct FTEs, rising to almost £290 million GVA and almost 4000 FTEs once indirect and induced impacts are included. Denmark, France, Italy, the Netherlands and Ireland also show significant impacts in GVA losses, with Denmark and Ireland registering the highest losses per capita.
These geographic patterns align with PRS for Music data showing uneven declines in UK performances across EU markets, particularly at general live music venues, alongside qualitative evidence indicating that UK acts remain significant drivers of audience demand within European live music markets whose absence has negative implications for local economies.
These estimates reflect the findings from the interviews, which suggest reduced access to UK performers following EU exit is linked to lower event attendance and spending across Europe. Stakeholders reported that UK artists are often regarded as commercially important programming draws, generating wider spending linked to hospitality, retail and travel. Interviewees suggested that reduced touring activity has therefore had wider spillover effects for local economies connected to live events.
Stakeholders reported that promoters now perceive booking UK acts as more administratively complex and financially risky due to additional requirements relating to immigration processes, social security coordination, customs procedures and temporary movement of goods. Interviewees suggested that these additional frictions can increase operational uncertainty and reduce flexibility in tour scheduling, contributing in some cases to more regionally concentrated route decisions or reduced bookings in certain markets. Some promoters also switch to EU alternatives, causing programming gaps. Impacts are uneven, with more region-focused routing (e.g., Nordic/German markets) and sharper declines in places like Spain and Ireland.
The supply-chain picture is more mixed. While reduced UK touring activity may lower demand for some local crews and suppliers associated with touring productions, interviewees also identified areas where EU-based logistics, storage and merchandise providers may have benefited from productions relocating elements of their operations within the EU in response to cabotage restrictions and border frictions. The Netherlands was cited by some stakeholders as an emerging hub for storage and transport activity linked to touring operations. These potential supply-chain effects relating to EU providers (for example, haulage, storage, merchandise) are qualitative observations from stakeholder interviews and are not incorporated into the quantitative estimates presented in this report.
Interviewees also identified wider cultural impacts associated with reduced touring activity. Stakeholders suggested that a reduced UK touring presence may limit opportunities for cultural exchange, co-production, skills development and audience exposure to UK artistic work, narrowing repertoire diversity and potentially reducing the collaborative and creative benefits traditionally associated with international touring activity across Europe.
Research Question 4: What is the value of mitigating or removing barriers and challenges faced by UK artists touring in the EU?
Mitigating or removing the barriers introduced or exacerbated post-EU exit could plausibly deliver substantial economic and cultural value for artists, organisations and host markets across both the UK and the EU. Interview evidence identified a consistent set of barriers that stakeholders considered to have the greatest impact on touring viability, operational flexibility and market access.
Stakeholders highlighted a number of areas where targeted policy or administrative changes could reduce friction and improve touring conditions.
These included simpler and more predictable mobility arrangements (including Schengen 90/180-day rules and streamlined multi-country visa/work-permit routes for short-term touring); simplified, more consistent and lower-friction carnet and customs processes; targeted mitigations relating to cabotage restrictions for cultural touring; standardised and faster VAT/WHT treatment; improved A1 processing, and accessible, authoritative guidance via a one-stop advisory service. These measures would be especially transformative for those in the sector most disproportionately impacted such as SMEs, freelancers and emerging artists, who are less able to absorb additional administrative costs, cashflow pressures and operational risks.
The quantitative analysis indicates that the potential economic gains associated with reducing current barriers could be substantial. In music alone, UK artists and promoters are estimated to have experienced direct losses of around 690 FTEs and £81.6 million in GVA (rising to 2,050 FTEs and £180.2 million when indirect and induced impacts are included). Across other touring art forms - such as orchestras, theatre, dance and visual arts - reduced EU touring is associated with a further £14.1 million in direct GVA losses and over 230 FTEs (or £27.8 million and 440 FTEs including indirect and induced effects).
The analysis also suggests that the impacts of reduced UK touring extend beyond the UK economy. Across EU member states, reduced UK touring activity is associated with estimated losses of approximately £367.9 million in direct GVA, rising to £1.04 billion when indirect and induced impacts are included. These impacts are concentrated particularly in Western European markets. Germany records the largest absolute losses, with an estimated £100 million in direct GVA impact, rising to nearly £290 million with wider economic effects. Denmark, France, Italy, the Netherlands and Ireland each face estimated direct GVA losses of over £30 million, rising to approximately £80 million including indirect and induced impacts. Denmark in particular experiences substantial impacts, with losses of £60 million in direct GVA, rising to £152 million including indirect and induced effects.
Taken together, these results suggest that reducing current frictions to UK–EU touring could plausibly unlock hundreds of millions of pounds in recoverable value, safeguard and create thousands of jobs, and revitalise cultural exchange.
While the estimates presented in this report are indicative and based on correlational modelling approaches including comparison against US and non-EU counterfactuals as set out in Annex 1, the overall evidence points consistently towards a shared economic and cultural benefit associated with reducing barriers to UK-EU touring activity. The findings suggest that targeted improvements relating to mobility, customs, transport, taxation and administrative guidance are likely to yield significant, shared benefits and could support both economic activity and wider cultural exchange across the European touring landscape.
Suggested future research
This research has combined the available quantitative evidence with primary qualitative data collection to analyse and estimate the economic benefits of EU touring and associated costs that EU exit has had. While the analysis provides an important evidence base, a number of data and methodological limitations remain. Addressing these limitations would support more robust future analysis of touring activity, economic impacts and long-term sectoral change.
Improving the available data
-
A key limitation identified through this research is the absence of a harmonised longitudinal dataset covering UK touring activity across different creative subsectors and international markets.
-
Development of a harmonised, longitudinal dataset of UK touring across all performance types would help improve the economic modelling and trend analysis. The analysis has relied primarily on the PRS for Music data which provides detailed coverage for music touring activity, but does not extend across other touring art forms. Arts Council England Data has therefore been used to understand the impacts for other artists. However, this data does not separate touring revenue from touring in the EU from wider international touring.
-
More granular event-level data, including ticket volumes, ticket pricing, venue size and ancillary audience spending by market, would support improved understanding not only of changes in touring frequency, but also changes in the economic value and commercial profile of touring activity over time.
-
Improved access to administrative data would also strengthen future analysis. This includes data relating to visas and work permit applications, A1 processing, ATA carnet issuance/discharge, border incidents, VAT and withholding tax administration including refund lags, and cabotage/dual-registration usage. While this research has incorporated available industry estimates and stakeholder evidence, more comprehensive administrative datasets would improve the precision and reliability of economic modelling.
-
Further evidence from logistics providers, hauliers, production companies and merchandise suppliers would also support better understanding of supply-chain adjustment and the extent to which elements of touring activity may be relocating or reconfiguring within the EU.
Future research priorities
This study also points to several avenues that warrant further investigation:
-
Distributional impacts on small and mid-scale operators, freelancers, grassroots organisations and emerging artists.
-
Long-term workforce impacts, including workforce wellbeing, retention and skills pipelines.
-
The scale and permanence of EU-based relocation or restructuring within touring supply chains such as logistics/merchandise re-shoring to the EU.
-
Specific changes in EU festival programming, audience behaviour and “music tourism” patterns across EU markets.
-
Longer-term impacts on career development, international audience growth and cultural exchange opportunities.
Future work could also explore differences in touring impacts between EU member states in greater depth, particularly where national administrative systems, labour market rules or border processes appear to shape touring viability differently across Europe.
Improved data enabling a more sophisticated counterfactual approach
The economic modelling presented in this report reflects the most appropriate analytical approach possible using currently available data. However, improvements in data availability could support the use of more sophisticated counterfactual modelling approaches in future research projects.
To enhance causal interpretation and strengthen robust testing, a synthetic-control counterfactual might be considered to replace the current single-country comparator approach. By constructing a synthetic control from a weighted basket of non-EU markets-such as the US, Canada, Australia, Japan, Switzerland, and Norway-and validating it through pre-trend matching, this method offers a more precise comparison than relying solely on the US. Such an improvement facilitates closer trend matching and mitigates the risk of bias stemming from market-specific shocks or unique recovery patterns in any individual country. Ultimately, this approach might more effectively isolate the specific impacts of post-EU exit touring frictions from broader global variables, including inflation, exchange-rate fluctuations, shifts in consumer demand, and varied COVID-19 recovery trajectories.
Delivering this type of analysis would require more detailed event level or tour-level international touring data on UK artist activity, alongside comparable macroeconomic and sector indicators across different markets, including inflation, exchange rates, labour market conditions, tourism flows, live-events pricing and pandemic policy timelines.
Annex 1: Detailed methodology of the economic modelling
The extent to which EU exit has influenced UK touring varies by sub-sector and scale of operation, with the barriers faced and the ability to mitigate or absorb the costs accrued as a result of these also varying significantly. This provides a challenging context in which to design a methodology to quantify the economic impact of EU exit. In addition, the data held by the sub-sectors of interest also varies substantially in terms of quality, reliability and comprehensiveness. There is a lack of long-term datasets on touring activity generally, and EU touring. This is a familiar challenge in any economic analysis of the culture sector but still serves to limit the ability to robustly quantify the total impact an event like EU exit has had.
As a result, the methodology was designed based on the data, which was available at the time of writing. The methodology follows two separate lines of enquiry.
-
The quantification of the impact of EU exit on musicians touring in the EU relies on data from PRS. This is a rich database of artist performance counts and royalties collected through local EU collecting societies, available with country-by-country breakdowns and split into general live (below 5,000 capacity) and stadium and arena tours (above 5,000 capacity). In 2020, the definition for artists categorised under stadium and arena tours within the underlying PRS for Music data was modified, shifting from venues with a capacity over 1,500 to those over 5,000. Although the data necessary to fully analyse the impact of this definition change was unavailable, we do not expect it to have a substantial effect on the analysis presented in this report.
-
The economic impact of EU exit on EU touring for theatre, dance, and visual arts organisations was estimated using the Arts Council England (ACE) National Portfolio Organisations (NPO) Survey. The NPO Survey provided a detailed, longitudinal dataset of NPO activity and financial information, despite lacking specific data points on EU touring. Proxies and assumptions derived from stakeholder consultations were applied to this ACE dataset to quantify the impact.
Both methodologies focus on estimating the loss of revenue derived from EU touring post-EU exit and model the economic impact of this revenue loss in terms of jobs, labour income and GVA. Specific quantification of the individual barriers identified previously in this report is simply not possible to robustly present in most cases due to a lack of data and the fact that the extent to which these barriers are felt varies on an almost case-by-case basis. However, where reasonable assumptions can be made, estimates are provided. It should also be noted that displacement is not considered within the analysis. Displacement considers that economic activity such as jobs or spending may shift from one sector to another and therefore a loss of jobs or economic output in the performance sector does not mean an overall loss of jobs or output in the wider economy.
Scope of the economic modelling
The boundaries of the economic modelling are set out below to articulate what the numbers do and do not capture, and where interview and literature evidence point to potential additional impacts which are not quantified.
Outcomes included in the economic modelling
-
Artist/promoter share of EU box office inferred from PRS royalties market size analysis and EU tariffs (artist/promoter vs venue/ticketing splits applied).
-
UK economic impacts estimated via Nordicity’s model (GVA, labour income, FTEs, see Annex 1 for more detail). Direct crew FTEs are linked to performance counts using sector-elicited assumptions (average crew size and tour length) and ONS SIC (Standard Industrial Classification) level data.
-
EU member state outcomes based on box office revenue.
-
Spillover spending by attendees in EU member states (hospitality, travel, retail) inferred from a ticket-to-total-spend ratio (ticket assumed to be a fraction of total event spend), converted into EU GVA and FTEs and allocated across member states using PRS royalty distributions.
-
EU exit attributable losses in income earned internationally through EU touring for additional UK arts and cultural subsectors, namely orchestra, dance, theatre and visual arts organisations.
-
UK economic impacts estimated via Nordicity’s model (GVA, labour income, FTEs, see Annex 1 for more detail) for additional UK arts and cultural subsectors.
Outcomes not included in the economic modelling
-
Revenues and effects outside of box office for UK musicians and touring artists.
-
Streaming/sales uplifts linked to touring, publishing/recording spillovers, sponsorship are not quantified.
-
Domestic or international substitution (for example, replacing EU dates with UK or non-EU dates) is not modelled.
-
Visa/legal fees and time, carnet issuance fees and bonds, customs brokerage, A1 processing delays, and VAT/WHT cash-flow lags are not directly costed (although where they result in fewer performances, they would appear indirectly as reduced activity). As a result, this report does not provide scenario estimates for the potential impact of removing any of the specific barriers identified via the literature review and interviews.
-
Reported supply chain re-location, comprising shifts of haulage, storage, technical services and merchandise production to EU providers are identified anecdotally through interview research but not quantified. If there has been any associated GVA or employment effects on the UK or EU member states, they are outside the headline figures.
-
Shorter/segmented runs, additional buffers/layovers, and reduced last-minute flexibility are only indirectly reflected (to the extent they reduce performance counts); the extra operating costs of these adaptations are not modelled.
Music
As described above, the data available for the music sub-sector is the most detailed and applicable to the research questions and so is presented as a separate line of analysis, using a different methodology. Fortunately, touring musicians represent the largest sub-sector of touring activity from the UK.
The economic impact for the music industry is derived from data provided by PRS. The PRS data provides one of the most detailed micro-level datasets on artist revenue, specifically focusing on the music sub-sector. PRS for Music collects comprehensive data on artist performance counts and royalties over multiple years, offering valuable insights into revenue trends by analysing the delta between the UK and other territories like the USA, which serves as a useful counterfactual. This dataset’s granularity allows for a robust quantification of the economic impacts of post-EU exit changes on UK musicians, making it a critical component of this report.
PRS define two distinct classifications of music tour:
-
General live
-
Stadium and arena tours[footnote 51]
As a result, the data allows for some direct quantification of impacts by scale of activity. However, the general live category in particular obscures a large amount of the nuance between the scale at which touring musicians operate.
Counterfactual model
PRS holds data on the number of performances by UK artists in each year in EU member states and the USA. For this analysis, the USA represents the counterfactual, under the assumption that touring activity of UK artists in the EU would have grown at the same rate as it did in the USA, where artists did not face the introduction of barriers that were experienced in Europe post-EU exit. The growth in the total number of performances in these two jurisdictions was indexed to 2020 with the difference between the two growth lines (after controlling for economic growth in general) serving as a proxy for the loss in EU touring activity.
Figure A1.1 Performance count, 2018 to 2024, EU vs USA
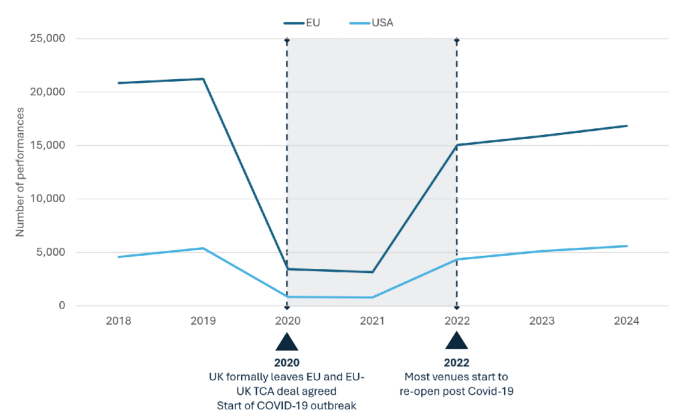
Figure A1.1 is a line chart, displaying the total number of performances of UK artists in the EU vs the USA over time. The chart highlights a dip between 2020, when the UK formally leaves the EU and the start of the COVID-19 outbreak, and 2022, when most venues reopened after COVID-19.
Source: PRS
GVA modelling assumptions
PRS collects data on the amount of royalties it receives from affiliate organisations across the EU for live performances of its members’ music. Collecting societies apply a tariff to licensees to calculate royalties, usually as a percentage of box office revenue. The tariffs charged by local societies to venues were then used to ‘reverse engineer’ and estimate the gross box office revenue generated by UK musicians touring the EU, annually and by Member State.
While songwriter royalties are one of the only metrics available to estimate box office takings by UK performers, there are limitations to the data. Royalties will contain some stadium and arena tours where not reported separately by many societies, and also other tariffs including theatre, live classical, and smaller non-ticketed live events where royalties come from licence fees rather than ticket sales.
The growth delta between the USA and EU was then applied to the annual box office estimates to estimate the amount of box office revenue lost as a result of EU exit. The post-EU exit period is defined as 2022, 2023 and 2024, excluding 2020 and 2021 (standard practice in time series analysis to avoid conflating observed effects with the negative impacts of COVID-19 social distancing measures).
The box office revenue generated by live music performances is generally split between the performing act, the promoter of the live event and the venue itself. Based on research into box office receipts in the USA[footnote 52] (in lieu of equivalent data for EU venues), artists and promoters retain on average 48% of ticket receipts at live music concerts. This share was applied to the estimated loss in box office revenue to estimate the amount of revenue retained by UK artists and promoters, or the loss to the UK economy as a result of EU exit. This figure was then converted into jobs and GVA through Nordicity’s in-house model, MyEIA™.
Direct FTE jobs, or direct crew jobs lost as a result of a decline in EU touring are estimated based on assumptions collected from the Music Managers Forum. The assumption used is that every ‘performance’ claimed for in the PRS data equates to 11 shows per artist, and each artist (individual) brings an average of 11 off-stage crew with them on tour. Assuming the average tour length is 3 months, these assumptions are applied to the estimated decline in the number of performances to estimate the direct FTEs lost as a result of EU exit.
As well as direct crew jobs lost as a result of performance decline, there are also impacts felt by artists, promoters and activities supporting touring. Based on ratios from the ONS’ Business Register and Employment Survey (BRES), ratios for Compensation of Employees (COE, which refers to the total remuneration, including wages, salaries, and other benefits earned by workers in a sector) and Gross Value Added (GVA, which measures the contribution of a sector, industry, or sub-sector to the overall economy) are applied to the revenue loss, in a top-down approach. Average salary in the relevant Standard Industry Classification (SIC) codes in the ONS’ Annual Survey of Hours and Earnings (ASHE) is used to estimate the employment loss.
The remaining 52% of box office revenue covers stage set up and general venue costs (30%) and ticketing fees (22%). The former can be considered value that is retained by the EU jurisdiction in which the concert is held, whereas it is reasonable to assume that ticketing platforms are run by international tech firms based outside the jurisdiction in most cases.
Beyond the loss in revenue for UK artists and promoters, UK musicians performing in the EU generate significant local benefits through audience spending on travel, accommodation and hospitality as part of attending a concert[footnote 53]. Research into UK concert attendee consumer behaviour indicates that the ticket costs represent only 16% of the total cost of attending, with further spillover spend on accommodation and food and drink (37%), retail (22%) and travel (15%) generated as a result. This spend can be considered additive to the EU jurisdictional economy.
This EU ‘left behind’ spend, or lost economic activity in the EU as a result of declining UK touring was distributed between EU jurisdictions based on PRS royalty data distributions and converted into jobs and GVA using a bespoke EU version of Nordicity’s in-house MyEIA™ model. The only EU member states with royalty revenue reported in the PRS data that are not included in modelling results are Estonia, Finland, Latvia and Lithuania.
Orchestras, theatre, dance and visual arts
As described above, data for other sub-sectors does not capture and track the number of touring performances or exhibitions in the EU, so an alternate methodology was developed to estimate the impact of EU exit on EU touring on Orchestras, Theatres, Dance and Visual Arts organisations.
The methodology uses the Arts Council England Annual Survey of National Portfolio Organisations (NPOs), 2013/14 to 2023/24. The National Portfolio is a regular funding programme for arts organisations, museums and libraries across England. Arts Council England NPOs are required to provide data on financial, audience, staff and activity metrics annually. Nordicity collated these annual datasets for analysis, resulting in a longitudinal database featuring over 7,000 observations across over 1,000 unique organisations.
The dataset contains variables tracking income earned internationally, and a range of metrics used to ascertain whether or not an organisation toured in the EU in a given year. However, this incidence of EU touring is not collected uniformly across the annual surveys, so this particular variable of interest, a binary indicator of EU touring activity in a given year, is only indicative of whether the organisation toured the EU at all, rather than where in the EU the tour took place. Similarly, the NPO survey makes no distinction between income earned internationally through touring activity and other international revenue streams. As a result, an organisation’ share of income from their core activity out of their total income was used as a proxy for international touring income, under the assumption that the organisation’s international activity is reflective of its domestic activity.
Furthermore, the NPO survey also does not disaggregate international income by specific location, so the extent to which this proxy for touring income can be attributed to EU touring specifically is based on whether an organisation toured the EU in a given year.
Using this longitudinal data, difference-in-differences with organisational and yearly fixed effects models were run on these variables, by sub-sector between 2018 and 2024. Therefore, the modelling controls for organisational differences (for example, size) and external shocks (e.g. COVID-19). In order to confirm the suitability of these models, parallel trend assumptions were tested, to check whether the treatment and control groups were on similar paths prior to the UK’s exit from the EU.
Figure A1.2: Pre-EU exit trends, treated vs control
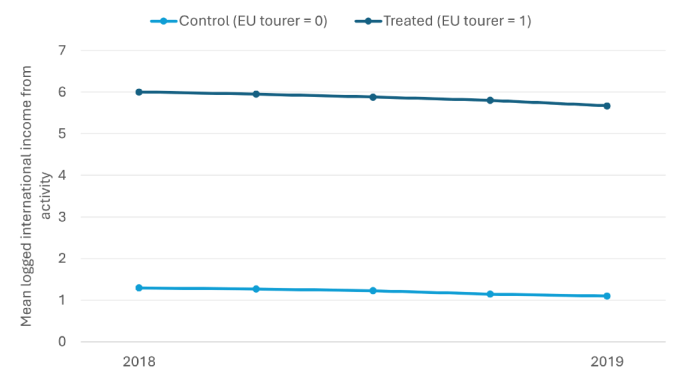
Figure A1.2 is a line chart, displaying the mean logged international income from activity, the activity being touring in the EU or not touring in the EU, between the years of 2018 and 2019. These two tracked activities are used to model and estimate the income, with the Treated, i.e. the EU tourer categories, being higher. This data is in reference particularly to pre-EU exit trends.
Source: Nordicity and Ipsos estimates based on data from ACE
Using organisations that tour internationally, but not to the EU pre-EU exit, as the control group, these models produced estimates for the organisational average difference in income generated from EU touring post-EU exit, for similar organisations, relative to the counterfactual group. This average organisational effect was applied to the international income earned in Europe from touring of the ACE NPO sample. This annualised loss was extrapolated out to the post-EU exit period, 2022 to 2024.
As the ACE data only includes NPOs from England, these results were grossed up, first to account for the non-NPO organisations in England, namely the national museums and galleries and West-End theatres. These England wide estimates were then grossed up to the whole of the UK, based on England’s share of UK wide SIC employment. This is the same gross up method applied in the 2026 report by Ipsos, Nordicity and Saffery, The Cultural Tax Reliefs Impact Review.
These estimates of lost revenue could then be converted into jobs and GVA using Nordicity’s in-house economic impact model.[footnote 54]
Methodological limitations
There are a number of limitations of the methodological approach used in this research, detailed below.
Limitations with use of US as counterfactual:
-
Geographic proximity and touring economics: The EU is geographically closer to the UK, historically enabling lower-cost, multi-stop touring circuits. US touring typically involves longer distances, higher transport costs, and different logistical models. However, this structural difference existed both before and after EU exit, meaning it should not drive post-2019 divergence in trends.
-
Market maturity and audience preferences: The US and EU markets differ in genre preferences, venue infrastructure, and audience behaviours. For example, festival culture varies significantly between regions. Again, these differences are structural and pre-date EU exit, so they are unlikely to explain the post-2019 divergence observed in the data.
-
Currency and exchange rate effects: Fluctuations in GBP/EUR and GBP/USD exchange rates could affect the relative attractiveness of touring in different markets. Analysis of exchange rate movements during the study period indicates that while GBP depreciated against both currencies following the 2016 referendum, the relative movements do not explain the divergent touring patterns observed specifically from 2020 onwards.
-
Potential confounding factors: Differential COVID-19 recovery patterns: The US and EU experienced different pandemic trajectories, vaccination rollouts, and reopening timelines. To address this, the analysis excludes 2020 and 2021 from impact estimation, focusing on 2022 to 2024 when both markets had substantially reopened. Furthermore, the US live music market faced its own COVID-related disruptions, meaning any residual recovery effects would, if anything, bias estimates towards underestimating the EU-specific impact of Brexit barriers.
-
US market growth drivers: The US live music market experienced strong growth in the post-pandemic period, driven by factors including pent-up demand and the growth of large-scale touring. If US-specific growth factors inflated the counterfactual baseline, this could overstate the estimated impact of EU exit. However, interview evidence consistently identifies EU-specific regulatory barriers (visas, carnets, cabotage) as driving changes in EU routing and scheduling that are not observed for US touring, supporting the interpretation that divergence reflects EU exit effects rather than US-specific growth.
-
Validation of parallel trends assumption: The parallel trends assumption—that UK touring in the EU would have followed a similar trajectory to UK touring in the US absent EU exit—is supported by Figure A1.1, which shows broadly similar growth patterns between 2017 and 2019. While the pre-treatment period is limited to two full years (2018 to 2019), this reflects data availability constraints. The similar trajectories during this period, combined with the absence of any identified structural change in the EU-UK touring relationship other than EU exit, support the use of the US as a reasonable counterfactual.
-
Overall assessment: On balance, while no counterfactual is perfect, the US provides the most appropriate available comparator. The identified differences between markets are primarily structural and pre-date EU exit, meaning they should not drive post-2019 divergence. The consistency between quantitative findings and qualitative interview evidence—which identifies EU-specific regulatory barriers as the primary driver of changed touring behaviour—provides additional confidence in the validity of the estimates. Nonetheless, users of this report should interpret the quantified impacts as indicative estimates of the magnitude of effect, rather than precise causal measurements.
Data coverage and availability
-
Not all EU/EEA countries are included in the economic estimates due to lack of data (e.g. Cyprus, Iceland, Liechtenstein, Luxembourg, Malta, Norway, and, for modelling purposes, Finland and the Baltic States).
-
PRS for Music data only cover musicians, and Arts Council England data for other artforms do not separate EU touring revenue from other markets.
-
Limited availability of event-level data (ticket volumes, prices, ancillary spend) restricts the ability to analyse changes in the quality and value of touring, not just volumes.
-
There is a time-lag between performances occurring and being reported to PRS. Subsequently the performance counts are always a snapshot rather than final and will increase as time progresses. Around 90 to 95% of performances are reported within the same year or following year, with a small percentage submitted at a later date. For this reason, data from 2025 is not included.
-
There are gaps in administrative data (e.g. visas/work permits, A1s, carnets, border incidents, WHT/VAT, cabotage/dual registration), meaning some parameters rely on partial data or sector estimates.
-
Firm-level data on hauliers, production and merchandise providers are incomplete, limiting quantification of supply-chain relocation and knock-on effects.
Modelling constraints:
-
The analysis uses the best available approach given current data but cannot employ more sophisticated methods (such as a synthetic-control counterfactual using multiple non-EU markets) that would better isolate EU-exit-specific effects and strengthen causal claims.
-
As a result, the quantified impacts should be interpreted as indicative estimates of the likely scale and direction of effects, rather than precise causal measurements.
MyEIA™
Nordicity’s MyEIA™ Model is an in-house model to estimate the economic impact of organisations, industries, and government programmes and policies. The MyEIA™ Model used in this analysis is based on ONS’s supply and use tables, and 2024 median wages available in the ONS ASHE. It provides estimates of direct, indirect and induced impacts on employment, COE, GVA and tax revenue.
GVA analysis is reported in two steps: inputs to the model (consumer spend) and GVA outputs (economic impact and jobs created).
Types of economic impact
-
Direct impact: The employment, COE and GVA generated directly within the industry or organisation that is the subject of an economic impact analysis.
-
Indirect impact: The employment, COE and GVA generated within the directly impacted industry or organisation’s supply chain. It occurs when the directly impacted industry or organisation purchases supplies and other intermediate inputs.
-
Induced impact: The employment, COE and GVA generated when workers employed due to direct and indirect impacts re-spend their income within a local, provincial or national economy through consumer purchases.
Detailed Specification of MyEIA™ Model
The following section provides a detailed specification of the construction of the MyEIA™ Model as a tool for estimating indirect, induced and total economic impact, both in the UK and in individual EU member states.
Direct impact
Calculation of direct GVA
The GVA ratio (ai) was calculated for each of the SIC based on data found in the ONS I-O tables. These ratios were calculated as:
ai = GVAi / zi
GVAi is the value of GVA generated in industry i as per the I-O tables
zi is the total value of output in industry i as per the I-O tables
The total direct GVA impact across all industries (g*) was calculated in the following manner:
g* = a’y
Where:
a is a 4 x 1 vector of ai
y is a X x 1 vector of yi (gross spend)
Calculation of direct COE
The COE ratio (bi) was calculated for all industries based on data found in the ONS I-O tables. These ratios were calculated as:
bi = COEi / zi
where:
COEi is the value of COE generated in industry i as per the I-O tables
zi is the total value of output in tourism industry i as per the I-O tables
The total direct COE impact across all industries (w*) was calculated in the following manner:
w* = b’y
Where:
b is a X x 1 vector of bi
y is a X x 1 vector of yi (gross spending)
Estimation of direct employment
The number of direct jobs (measured in FTEs) was estimated by dividing the COE impact in each industry (wi) by the average FTE cost in each industry (mi).
qi = wi / mi
where:
wi is the total wage impact (measured in £) in industry i
mi is the average FTE cost in industry i
Total direct employment (q*) was arrived at by summing the employment impacts (qi) across industries.
q* = ?qi
i
Indirect impact
Indirect impacts are estimated using Nordicity’s MyEIA™ Model. This model utilises the I-O tables published by ONS, along with other economic data (e.g. median wages) to estimate how increased purchases of goods and services translate into incremental employment, COE and GVA.
Construction of input-purchases vector
Data collected through primary and secondary research was used to prepare a profile of input purchases in each sub-sector and value chain segment. After removing expenditures on sources of value added (i.e. COE, mixed income), the remaining expenditures are mapped to a 62 x 1 vector (x) of industries (corresponding with the products listed in the input-output tables published by ONS).
Estimation of indirect output
The Leontief inverse matrix (L) for the UK economy was derived from the input-output tables published by ONS. The following formula was then used to estimate a 1 x 62 vector (y) containing the changes in output, yi, in each industry as a result of the input purchases arising from each sector.
y = x’L
Where:
y is a 1 x 62 vector of changes in output (yi)
x is 62 x 1 vector of input-purchase expenditures (by receiving industry)
L is the 62 x 62 Leontief inverse matrix
Calculation of indirect GVA
The GVA ratio (ai) was calculated for each of the 62 industries listed in the ONS I-O tables and L. These ratios were calculated as:
ai = GVAi / zi
where:
GVAi is the value of GVA generated in industry i as per the I-O tables
zi is the total value of output in industry i as per the I-O tables
The total indirect GVA impact across all industries (g*) was calculated in the following manner:
g* = a’y
Where:
a is a 62 x 1 vector of ai
y is a 62 x 1 vector of yi
Calculation of indirect COE
The COE ratio (bi) was calculated for each of the 62 industries listed in the ONS I-O tables. These ratios were calculated as:
bi = COEi / zi
where:
COEi is the value of COE generated in industry i as per the I-O tables
zi is the total value of output in industry i as per the I-O tables
The total indirect COE impact across all industries (w*) was calculated in the following manner:
w* = b’y
Where:
b is a 62 x 1 vector of bi
y is a 62 x 1 vector of yi
Estimation of indirect employment
The number of indirect jobs (measured in FTEs) was estimated by dividing the COE impact in each industry (wi) by the average FTE cost in each industry (mi).
qi=wi / mi
where:
wi is the total wage impact (measured in £) in industry I
mi is the average FTE cost in industry I
Total indirect employment (q*) was arrived at by summing the employment impacts (qi) across the 62 industries.
q* = ?qi
i
Induced impact
Nordicity’s MyEIA™ Model also provides estimates of induced impact. For the UK, these estimates are not based directly on ONS’s I-O tables. Instead, they are based on the average ratio of Type II and Type I output multipliers in the UK economy (?), published by ONS.
? = ?TYPE II / ?TYPE I
Where:
?TYPE I is the arithmetic average of Type I multipliers across all industries
?TYPE II is the arithmetic average of Type II multipliers across all industries
Estimation of induced output
The values of direct and indirect output were summed to arrive at an estimate of Type I output.
yTYPE I = yDIRECT + yINDIRECT
The Type I output was then multiplied by ? to arrive at an estimate of Type II output.
yTYPE II = ? (yTYPE I)
yINDUCED = yTYPE II - yTYPE I
Estimation of induced GVA
The total value of induced impact GVA was estimated by multiplying the economy-wide GVA-to-output ratio (as per the I-O tables) by the estimate of Type II output.
gINDUCED = (a*)·(yINDUCED)
Where:
a* is the GVA-to-output ratio across all industries (0.53)
Estimation of induced COE
The total value of induced impact COE was estimated by multiplying the economy-wide COE-to-output ratio (as per the I-O tables) by the estimate of yINDUCED.
wINDUCED = (b*)·(yINDUCED)
Where:
b* is the COE-to-output ratio across all industries (0.29)
Estimation of induced employment
The number of induced impact FTEs (qINDUCED) was estimated by dividing the estimate of induced COE (wINDUCED) by the average FTE cost across the UK economy (m*).
qINDUCED = wINDUCED / m*
Where:
m* is the median full-time wage (excluding overtime) in the UK economy in 2024.
Annex 2: Annual economic impact
Annual economic impact estimates between 2022 and 2024 are based on yearly changes in box office loss derived from the counterfactual market trends analysis of PRS royalty data. Results suggest a compounding effect over time, whereby the economic impact of the EU exit has grown over time.
Music – General live performance
Table A2.1 Annual direct economic impact of general live performance, UK economy, 2022 to 2024
| 2022 | 2023 | 2024 | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
8 | 170 | 194 | 372 |
| Labour income (£m) |
0.4 | 7.6 | 8.6 | 16.6 |
| Gross value added (£m) |
1.0 | 20.2 | 22.9 | 44.0 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding
Table A2.2 Annual total economic impact of general live performance, UK economy, 2022 to 2024
| 2022 | 2023 | 2024 | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
24 | 507 | 576 | 1,110 |
| Labour income (£m) |
1.0 | 21.1 | 24.0 | 46.1 |
| Gross value added (£m) |
2.1 | 44.5 | 50.6 | 97.3 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding
Music – Stadium and arena tours
Table A2.3 Annual direct economic impact of stadium and arena tours, UK economy, 2022 to 2024
| 2022 | 2023 | 2024 | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
8 | 113 | 196 | 317 |
| Labour income (£m) |
0.4 | 5.1 | 8.7 | 14.2 |
| Gross value added (£m) |
1.0 | 13.4 | 23.2 | 37.5 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding
Table A2.4 Annual total economic impact of stadium and arena tours, UK economy, 2022 to 2024
| 2022 | 2023 | 2024 | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
24 | 337 | 583 | 944 |
| Labour income (£m) |
1.0 | 14.0 | 24.3 | 39.3 |
| Gross value added (£m) |
2.2 | 29.6 | 51.2 | 82.9 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding
Music – Total economic impact
Table A2.5 Annual direct economic impact of live music, UK economy, 2022 to 2024
| 2022 | 2023 | 2024 | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
16 | 283 | 389 | 689 |
| Labour income (£m) |
0.7 | 12.7 | 17.4 | 30.8 |
| Gross value added (£m) |
1.9 | 33.6 | 46.1 | 81.6 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding
Table A2.6 Annual total economic impact of live music, UK economy, 2022 to 2024
| 2022 | 2023 | 2024 | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
48 | 844 | 1,159 | 2,052 |
| Labour income (£m) |
2.0 | 35.2 | 48.3 | 85.4 |
| Gross value added (£m) |
4.3 | 74.2 | 101.8 | 180.2 |
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding
Orchestra, theatre, dance and visual arts organisations
The econometric analysis of the ACE NPO data yielded an average annual impact of the effect of the EU exit between 2022 and 2024, at the organisation level. As such, the total results are annualised, rather than presenting the variation in impact in each year.
Table A2.7 Annual direct economic impact of orchestras, theatre, dance, visual arts, UK economy, 2022 to 2024
| 2022 | 2023 | 2024 | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
78 | 78 | 78 | 234 |
| Labour income (£m) |
3.3 | 3.3 | 3.3 | 9.9 |
| Gross value added (£m) |
4.7 | 4.7 | 4.7 | 14.1 |
Source: Estimates based on data from ACE, ONS and ABO
Figures may not sum due to rounding
Table A2.8 Annual total economic impact of orchestras, theatre, dance, visual arts, UK economy, 2022 to 2024
| 2022 | 2023 | 2024 | Total impact | |
|---|---|---|---|---|
| Employment (FTEs) |
146 | 146 | 146 | 439 |
| Labour income (£m) |
5.8 | 5.8 | 5.8 | 17.5 |
| Gross value added (£m) |
9.3 | 9.3 | 9.3 | 27.8 |
Source: Estimates based on data from ACE, ONS and ABO
Figures may not sum due to rounding
Annex 3: Sensitivity Analysis
Sensitivity analysis is used to explore whether the overall quantitative findings are sensitive to the main assumptions and inputs showing how much the estimates would change with a +/-20% change in inputs.
Music
While the modelling of the impact of EU exit within the music sector was based on several assumptions, the sensitivity analysis focuses on two key assumptions, which are, arguably, subject to the highest degree of uncertainty.
-
UK artists’ and promoters’ retained portion of the estimated total box office for EU performances
-
Audiences’ high-street spending multiplier (i.e. the average euros spent by audiences outside venues for every euro spent inside the venue.)
UK economy impacts
In order to explore the sensitivity of the estimates for the impact of the EU exit on touring musicians for the UK economy, the assumption that 48% of box office revenue is retained by UK artists and promoters has been varied by +/-20%. This assumption was subject to a sensitivity analysis due to a lack of alternate data on the splits of box office receipts, and the fact that the other inputs to the model are far less arbitrary.
Based on this adjustment of the 48% assumption, the revenue lost from the UK economy over the post-EU exit period is estimated to total between £123.1 million and £184.7 million between 2022 and 2024, across both general live performance and stadium and arena tours categories.
The effect this adjustment has on the economic impact generated by lost revenue for the UK economy is presented below in figures A3.1 and A3.2. While the estimated loss of revenue from UK touring musicians over the post-EU exit period is estimated to translate into 2,050 total FTEs and £180.2 million in total GVA, sensitivity analysis suggests that these figures could range from 1,640 and 2,460 total FTEs and £144.2 million and £216.3 million in total GVA.
Figure A3.1 UK economy employment estimates, sensitivity analysis
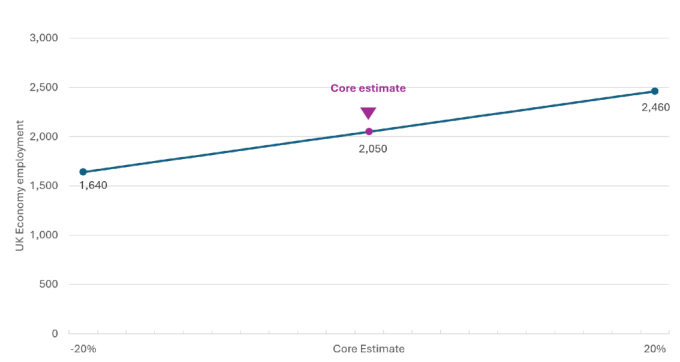
Figure A3.1 is a line chart, displaying estimated impact on UK economy employment. The core estimate is that two-thousand and fifty FTEs will be lost, the sensitivity analysis suggests a range, as mentioned in the text above.
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figures may not sum due to rounding
Figure A3.2 UK economy GVA estimates, sensitivity analysis
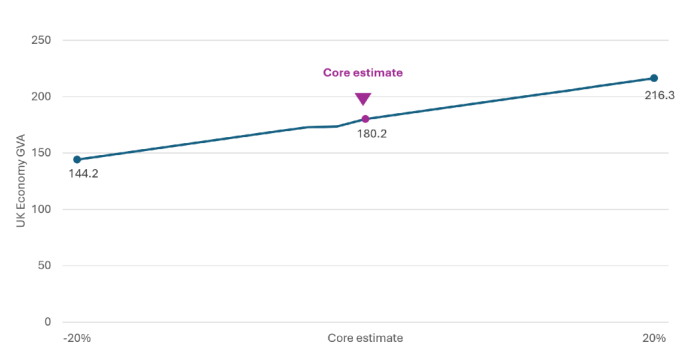
Figure A3.2 is a line chart, displaying estimated impact on UK economy employment. The core estimate is that one hundred and eighty million pounds in GVAs will be lost, the sensitivity analysis suggests a range, as mentioned in the text above.
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
EU economy impacts
The second strand of analysis presented in this report considered the impact that this loss in touring activity in the EU by UK musicians equates to in terms of lost ‘high-street’ spend in host countries, or the spend by audiences outside the venue. These figures are based on the assumption that a ticket to a live music event constitutes 16% of an attendee’s total spend, with the rest going towards expenses including travel, accommodation and retail. This assumption was also subject to sensitivity analysis, again varied by +/-20%. Taking the upper and lower bounds of lost box office revenue within the EU (i.e. total box office loss – box office revenue retained by UK artists and promoters) and applying the lower and upper bounds of the adjusted ticket to additional spend ratio results in a range of between £572.2 million and £1.35 billion. In other words, while the total estimated lost high-street spillover spend within EU member states between 2022 and 2024 is estimated to total £875.5 million, it could plausibly be between £572.2 million and £1.35 billion.
How this translates into economic impact is presented below in tables A3.3 and A3.4. The total FTE impact is estimated to range from 11,280 to 25,880 and the total GVA impact from £668.0 million to £1,58 billion.
Figure A3.3: EU economy employment estimates, sensitivity analysis
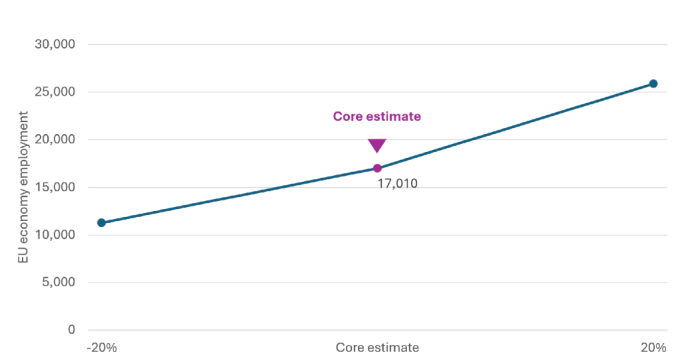
Figure A3.3 is a line chart, displaying estimated impact on EU economy employment. The core estimate is that seventeen thousand FTEs will be lost, the sensitivity analysis suggests a range, as mentioned in the text above.
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Figure A3.4: EU economy GVA estimates, sensitivity analysis
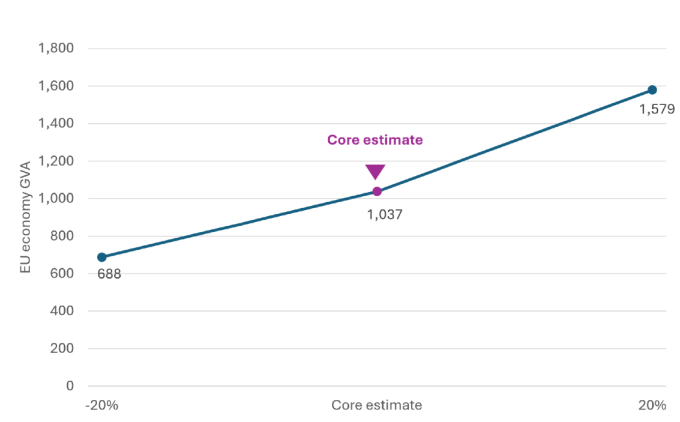
Figure A3.4 is a line chart, displaying estimated impact on UK economy employment. The core estimate is that one and a half billion pounds in GVAs will be lost, the sensitivity analysis suggests a range, as mentioned in the text above.
Source: Nordicity estimates based on data from PRS, ONS, MMF, NITO and CEBR
Orchestras, theatre, dance and visual arts
Results presented in section 5 are based on the central estimate of a 59.95% decline in international income earned from EU touring per organisation, on average, in the post-EU exit period. This estimate is derived from the logged dependent variable, international income earned from core activity, used as a proxy for EU touring income as described in the methodology section. The results of the DiD modelling were significant at the 95% level, therefore sensitivity analysis is explored at the 95% confidence level. Sensitivity analysis at the 95% confidence interval suggests the effect could range from 16.5% to 80.79%.
When translated into economic impact using the same methodology as applied to calculate the core estimate, the total employment impact of the EU exit on these subsectors ranges from 120 to 590 total FTEs between 2022 and 2024. Similarly, the total GVA impact ranges from £7.6 million to £37.4 million. See tables 20 to 22 for more detailed breakdowns of economic impact.
Figure A3.5: Orchestras, theatre, dance and visual arts employment impact, sensitivity analysis
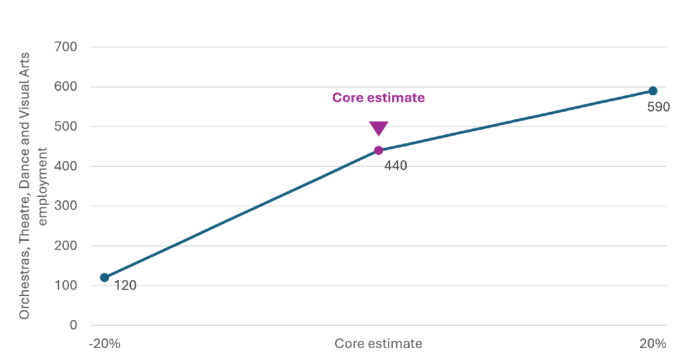
Figure A3.5 is a line chart, displaying estimated employment impact on Orchestras, Theatre, Dance and Visual Arts employment. The core estimate is that four hundred and forty FTEs will be lost, the sensitivity analysis suggests a range, as mentioned in the text above.
Source: Estimates based on data from ACE and ONS
Figure A3.6: Orchestras, theatre, dance and visual arts GVA impact, sensitivity analysis
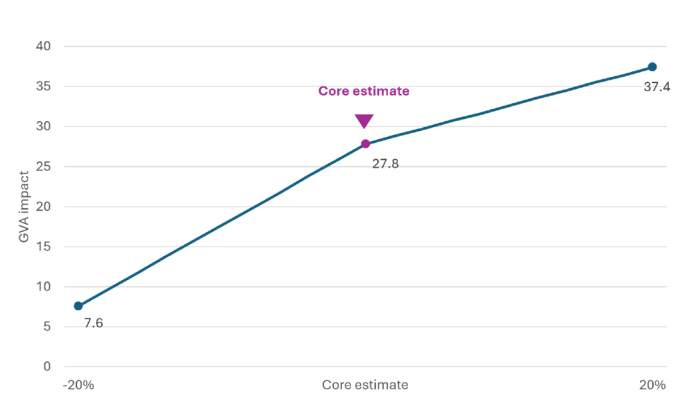
Figure A3.6 is a line chart, displaying estimated GVAs impact on Orchestras, Theatre, Dance and Visual Arts employment. The core estimate is that over twenty-seven GVAs will be lost, the sensitivity analysis suggests a range, as mentioned in the text above.
Source: Estimates based on data from ACE and ONS
Annex 4: Additional tables
Table A4.1: Number of performances reported by PRS members during tours in EU countries, 2017 to 2024 (General live music and stadium and arena tours)
| Year | General live music | Stadium and arena tours |
|---|---|---|
| 2017 | 18,249 | 327 |
| 2018 | 20,401 | 452 |
| 2019 | 20,934 | 305 |
| 2020 | 3,418 | 16 |
| 2021 | 3,131 | 8 |
| 2022 | 14,462 | 590 |
| 2023 | 15,266 | 605 |
| 2024 | 16,354 | 475 |
Table A4.2: Average number of performances per artist, by audience size (stadium and arena tours vs general live music)
| Year | General live music | Stadium and arena tours |
|---|---|---|
| 2019 | 5.1 | 6.0 |
| 2020 | 3.7 | 2.3 |
| 2021 | 3.5 | 1.1 |
| 2022 | 4.5 | 6.9 |
| 2023 | 4.0 | 7.3 |
| 2024 | 4.2 | 5.5 |
Table A4.3: Number of performances by country, by year (General live music)
| Country | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 |
|---|---|---|---|---|---|---|
| Germany | 5015 | 968 | 650 | 3315 | 3440 | 3588 |
| Republic of Ireland | 2388 | 293 | 362 | 1769 | 1958 | 1680 |
| France | 2153 | 381 | 412 | 1517 | 1526 | 1759 |
| Netherlands | 2000 | 284 | 276 | 1529 | 1540 | 1757 |
| Spain | 2119 | 286 | 203 | 1165 | 1441 | 1424 |
| Italy | 1398 | 187 | 214 | 967 | 1148 | 1366 |
| Belgium | 997 | 124 | 130 | 692 | 710 | 863 |
| Austria | 613 | 92 | 106 | 473 | 488 | 448 |
| Poland | 533 | 101 | 114 | 413 | 393 | 475 |
| Denmark | 559 | 97 | 121 | 368 | 339 | 463 |
| Czechia | 555 | 81 | 54 | 393 | 402 | 443 |
| Portugal | 506 | 70 | 65 | 348 | 313 | 379 |
| Sweden | 387 | 66 | 85 | 328 | 310 | 348 |
| Greece | 193 | 54 | 42 | 199 | 202 | 277 |
| Hungary | 242 | 76 | 36 | 173 | 226 | 181 |
| Finland | 349 | 71 | 22 | 190 | 140 | 157 |
| Croatia | 294 | 46 | 68 | 151 | 167 | 161 |
| Romania | 154 | 18 | 32 | 82 | 113 | 177 |
| Slovakia | 129 | 22 | 23 | 72 | 101 | 107 |
| Luxembourg | 81 | 22 | 21 | 85 | 81 | 82 |
| Bulgaria | 100 | 19 | 22 | 78 | 48 | 69 |
| Lithuania | 52 | 42 | 45 | 37 | 37 | 37 |
| Estonia | 50 | 14 | 10 | 42 | 57 | 59 |
| Slovenia | 44 | 1 | 14 | 50 | 56 | 27 |
| Latvia | 23 | 3 | 4 | 26 | 30 | 27 |
| Total | 20934 | 3418 | 3131 | 14462 | 15266 | 16354 |
Table A4.4: Number of performances by country, by year (Stadium and arena tours)
| Country | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 |
|---|---|---|---|---|---|---|
| Germany | 68 | 0 | 1 | 136 | 152 | 131 |
| Republic of Ireland | 38 | 3 | 3 | 59 | 68 | 70 |
| France | 24 | 2 | 0 | 94 | 58 | 34 |
| Netherlands | 33 | 4 | 0 | 48 | 50 | 41 |
| Spain | 13 | 0 | 0 | 32 | 39 | 29 |
| Italy | 5 | 0 | 0 | 39 | 58 | 31 |
| Belgium | 18 | 3 | 0 | 31 | 23 | 19 |
| Denmark | 15 | 1 | 2 | 18 | 25 | 15 |
| Poland | 12 | 1 | 0 | 22 | 19 | 21 |
| Austria | 19 | 1 | 0 | 18 | 22 | 10 |
| Sweden | 12 | 1 | 0 | 17 | 21 | 9 |
| Portugal | 11 | 0 | 0 | 15 | 18 | 9 |
| Czechia | 10 | 0 | 0 | 9 | 12 | 10 |
| Hungary | 4 | 0 | 0 | 13 | 9 | 11 |
| Finland | 5 | 0 | 0 | 7 | 5 | 8 |
| Romania | 3 | 0 | 0 | 5 | 6 | 6 |
| Lithuania | 2 | 0 | 0 | 4 | 2 | 5 |
| Croatia | 2 | 0 | 0 | 6 | 5 | 4 |
| Bulgaria | 3 | 0 | 0 | 3 | 1 | 3 |
| Latvia | 3 | 0 | 0 | 5 | 4 | 1 |
| Estonia | 3 | 0 | 0 | 2 | 2 | 2 |
| Greece | 0 | 0 | 2 | 2 | 3 | 2 |
| Slovakia | 2 | 0 | 0 | 3 | 1 | 3 |
| Slovenia | 0 | 0 | 0 | 2 | 2 | 1 |
| Total | 305 | 16 | 8 | 590 | 605 | 475 |
Annex 5: Analysis of impact on UK haulage based on start and end dates of US touring artists
To explore this further, additional analysis was undertaken to examine where major European tours start and end. However, this indicative analysis did not identify clear evidence of a major shift away from the use of the UK as a hub for US artists entering Europe (note this is indicative only, based on a small sample).
Further analysis of major European Tours by US artists, start and end locations
To explore the anecdotal qualitative evidence that large US tours were moving base locations for EU tours away from the UK since EU exit, we have analysed the largest tours from US artists in 2015 and 2025 using published set lists to see if there has been a notable change assuming where tours start and end are aligned with where tours arrive and leave. Although the sample is small and should therefore be treated with caution, the findings of this indicative analysis suggested that there was no conclusive difference in the propensity to use the UK as a starting point for tours in Europe.
Tours of EU by US artists, 2015
| Started | Ended | |
|---|---|---|
| Ariana Grande | Paris | Barcelona |
| Taylor Swift | Cologne | Dublin |
| Linkin Park | Brussels | Rome |
| Crosby, Stills and Nash | London | Oslo |
| Fifth Harmony | Madrid | Paris |
| Fall Out Boy | Dublin | Saint Petersburg |
| Maroon Five | Paris | Amsterdam |
Tours of EU by US artists, 2025
| Started | Ended | |
|---|---|---|
| Beyonce | London | Paris |
| Billie Eilish | Stockholm | Dublin |
| Kendrick Lamar | Cologne | Stockholm |
| Usher | London | Berlin |
| The Weeknd | Paris | Madrid |
| Luke Combs | London | Oslo |
-
PRS for Music is the UK’s collective management organisation representing over 190,000 songwriters, composers and music publishers. It licenses over 45 million musical works worldwide, ensuring its members receive royalties whenever their songs are streamed, downloaded, broadcast, performed live and played in public. ↩
-
Countries with full economic assessment include Austria, Belgium, Bulgaria, Croatia, Czechia, Denmark, France, Germany, Greece, Hungary, Ireland, Italy, Netherlands, Poland, Portugal, Romania, Slovakia, Slovenia, Spain and Sweden. ↩
-
Cabotage: paid loading and unloading of goods in one country by a foreign registered vehicle in a seven day period; cross-trade: haulage of goods between two countries by a foreign-registered vehicle. ↩
-
EU-based stock means holding merchandise in a warehouse within an EU member state, with import VAT (and any duty) settled on entry. Third-party fulfilment refers to outsourcing storage and distribution to an EU logistics provider that holds the stock and handles pick/pack/ship to venues or customers. Both approaches reduce cross-border paperwork and delays when touring, but add storage/handling fees and may require EU VAT registration, which can reduce margins. ↩
-
Sensitivity analysis suggests that these figures could range from 1,760 and 3,050 total FTEs and £151.8 million and £253.7 million in total Gross Value Added. ↩
-
GVA is a measure of how much value a sector creates in the economy: summed across sectors, it underpins national GDP. ↩
-
Sensitivity analysis suggests that these figures could range from 1,640 and 2,460 total FTEs and £144.2 million and £216.3 million in total Gross Value Added. ↩
-
Sensitivity analysis suggests that these figures could range from 120 and 590 total FTEs and £7.6 million and £37.4 million in total Gross Value Added. ↩
-
ABO (2025) KEY FACTS: THE STATE OF THE UK’S ORCHESTRAS April 2025 Report ↩
-
Musicians’ Union (2024) Touring in the EU Post Brexit: Key Findings and Next Steps From the MU’s Recent Survey ↩
-
Musicians’ Union & Incorporated Society of Musicians (2021) Survey Reveals Brexit Paperwork is a ‘Complete Nightmare’ For Musicians ↩
-
Note that this impact has not been quantified in this report ↩
-
Musicians’ Union (2024) Touring in the EU Post Brexit: Key Findings and Next Steps From the MU’s Recent Survey ↩
-
ABO (2025) KEY FACTS: THE STATE OF THE UK’S ORCHESTRAS April 2025 Report ↩
-
Best for Britain (2025) British acts playing EU festivals down 26% on pre-Brexit ↩
-
UK Government (2011), UK Music publishes study into the economic contribution of live music. Note that this study focuses on the impact in the UK, but demonstrates the economic impacts of music tourism. ↩
-
Sensitivity analysis is used to explore whether the overall quantitative findings are sensitive to the main assumptions and inputs showing how much the estimates would change with a +/-20% change in inputs. ↩
-
Countries with full economic assessment include Austria, Belgium, Bulgaria, Croatia, Czechia, Denmark, France, Germany, Greece, Hungary, Ireland, Italy, Netherlands, Poland, Portugal, Romania, Slovakia, Slovenia, Spain and Sweden. ↩
-
This category may include some events and festivals with a larger capacity that are not part of stadium and arena tours. ↩
-
‘Stadium and arena tours’ is used in this report in place of PRS’ unique term ‘Major Live Concert Service’ or ‘MLCS’. The underlying data for the Stadium and Arena Tours category underwent a definition change in 2020; see Annex 1 for further detail. ↩
-
The qualifying criteria for Stadium and arena tour events changed from 1,500 attendance to 5,000 in 2020. See Annex 1 for further detail. ↩
-
There is a time-lag between performances occurring and being reported to PRS. Subsequently the performance counts are always a snapshot rather than final and will increase as time progresses. Around 90-95% of performances are reported within the same year or following year, with a small percentage submitted at a later date. For this reason, data from 2025 is not included. ↩
-
Rapid literature review is used to support the interview analysis, including details of government policy and regulation to ensure accuracy. ↩
-
UK government (2023), Working, performing and touring in Europe: guidance for musicians and accompanying staff. ↩
-
UK government (2021), Visa-free short term touring allowed in 20 member states. ↩
-
An ATA Carnet is an international customs document allowing the holder to temporarily export goods to countries that are members of the ATA Carnet system: ATA Carnet - Carnet Countries ↩
-
UK Music (2025) This is Music 2025. HMRC also states that a simple online declaration can be used for goods valued at less than £2500 and less than 1000kg in weight. ↩
-
Department for Culture, Media and Sport (2021) Working, performing and touring in Europe - guidance for musical artists and accompanying staff ↩
-
Dual registration provides an opportunity for GB hauliers with the necessary resources to set up an international base in addition to their GB one and not be subject to Vehicle Excise Duty (VED) on their foreign-registered vehicle(s) whilst the vehicle is temporarily operating on their GB operating licence. ↩
-
An A1 certificate is a document used in the EU (and some associated countries) to prove which country’s social security system is paid into when working abroad temporarily. ↩
-
Independent Society of Musicians (2023) Current survey findings, 2021 to 2023 ↩
-
In addition, Musicians’ Union (2024) reports that, among those who previously worked in the EU, 75% now have fewer bookings, 79% have been unable to replace lost EU work elsewhere, 59% say EU touring is no longer financially viable, and 72% report decreased EU income (with 22% down by 75% and no longer working there). ↩
-
Best for Britain (2025) British acts playing EU festivals down 26% on pre-Brexit ↩
-
King’s College London (2024) Touring Today: the impact on young and emerging artists across the EU and UK ↩
-
ABO (2025) KEY FACTS: THE STATE OF THE UK’S ORCHESTRAS April 2025 Report ↩
-
UK Music (2023) Eight Out of Ten Brexit-hit Music Creators Say Their Earnings Have Plunged Since UK Left EU – UK Music Survey Reveals ↩
-
European Festivals Association (2025) UK–EU Cultural and Artistic Exchanges ↩
-
The summit resulted in a Common Understanding agreement, which set out shared commitments and addressed the cultural exchange issue specifically. ↩
-
EU-UK Summit, 19 May 2025, Common Understanding agreement, Point 15. ↩
-
Press release, (2026) ]EU and UK High-Level Policymakers Share the Values of Cultural Cooperation at Culture Exchange Coalition Inaugural Event, Brussels](https://www.pearle.eu/news/eu-and-uk-high-level-policymakers-share-the-values-of-cultural-cooperation-at-culture-exchange-coalition-inaugural-event), 27 March 2026. ↩
-
UK Music (2026) UK Minister Ian Murray Pledges “Full Commitment” of UK Government To Tear Down Barriers To Touring EU and UK - UK Music ↩
-
UK Parliament, Written evidence submitted to the Culture, Media and Sport Committee inquiry: A Creative Future (2023). ↩
-
Parallel trends is a key underlying assumption for attribution analysis. It assumes that absent the policy change, the outcome for the ‘treated’ group and the comparison group would have continued to move in line with each other. If pre-EU exit trends are parallel, then a post-EU exit divergence between the two series can be attributed to EU exit rather than wider shocks common to both. If pre-trends are not parallel, attribution is weaker because the groups were already on different trajectories. ↩
-
Nordicity and Ipsos estimates based on data from PRS and ONS, see Annex 1 for more details ↩
-
Based on analysis from National Independent Talent Organization (NITO) ↩
-
FTEs are estimated based on assumptions on the number of on and off-stage performers and support crew per performance developed by the MMF and ONS median salary data, see Annex 1 for detailed methodology ↩
-
See Annex 1.5 for detailed model specifications of direct, indirect and induced economic impact ↩
-
Difference-in-Differences (DiD) is a quasi-experimental method that estimates the effect of a change by comparing how outcomes evolve over time for a ‘treated’ group (e.g., organisations touring the EU) versus a similar comparison group not exposed to that change (organisations that toured internationally but only to non-EU markets). ↩
-
£147.6 million x 52% = £76.7 million, £70.6 million / 16% = £479.7 million, £479.7 million – 76.7 million = £402.9 million. ↩
-
PRS use the term Major Live Concert Service (MLCS) internally. Note, in 2020, the definition for artists categorised under Stadium and Arena Tours within the underlying PRS for Music data was modified, shifting from venues with a capacity over 1,500 to those over 5,000. Although the data necessary to fully analyse the impact of this definition change was unavailable, we do not expect it to have a substantial effect on the analysis presented in this report. ↩
-
Source: NITO ↩
-
CEBR Research (2024), UK Secondary Ticket Market Contributes $940M To Local Economies. Note the link to the research report is not available ↩
-
Where relevant, estimates were converted from Euros to £’s using the average exchange rate between 2022 to 24 (1 Euro = £0.78). ↩