Rural Payments Agency annual report and accounts 2025 to 2026
Updated 25 August 2026
Applies to England

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/publications/rural-payments-agency-annual-report-and-accounts-2025-to-2026/rural-payments-agency-annual-report-and-accounts-2025-to-2026
Rural Payments Agency annual report and accounts 2025-26
Accounts presented to the House of Commons pursuant to section 7 of the Government Resources and Accounts Act 2000
Annual Report presented to the House of Commons by Command of His Majesty
Ordered by the House of Commons to be printed on 9 July 2026
HC 299
© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at www.gov.uk/official-documents.
Any enquiries regarding this publication should be sent to us at newsdesk@defra.gov.uk.
ISBN: 978-1-5286-6446-2
E03597423 07/26
Chief Executive and Accounting Officer’s statement
I am pleased to present the Rural Payments Agency’s (the agency’s) annual report and accounts for 2025-26, my first since joining the agency in January 2026. It is an honour to lead an organisation that plays such a vital role in supporting farmers, land managers and rural businesses across England.
The 2025-26 financial year began with real operational pressure, and we did not consistently deliver the standard of service our customers have a right to expect. Delays, uncertainty and inconsistent information caused frustration for farmers and land managers, and at times placed additional burden on them. We have been candid about where we fell short, and we have made changes to stabilise delivery and improve performance as the year progressed. I am grateful to Neil Hornby, who provided continuity and steady leadership as Interim Chief Executive Officer (CEO) during this period of pressure.
This has also been a year of organisational transition. The departure of the previous CEO, Paul Caldwell, and several executive directors, combined with 146 colleagues leaving through the voluntary exit scheme, brought change to our leadership and structure while creating an opportunity to refresh roles and clarify priorities. I would like to thank all those who have left the agency during this year for their service, and to recognise the professionalism of colleagues who stepped up to maintain delivery during this period. Paul Caldwell, who completed 8 years as CEO before stepping down in June 2025, ably guided the agency through some of its most significant periods of change, including the transition to domestic agricultural policy. I would like to place on record my, and the agency’s, gratitude.
Against this backdrop, operational performance improved as the year progressed and we made visible progress against our core objectives, delivering outcomes that matter to the customers we serve. This improvement has been delivered alongside a strong focus on stewardship, governance and accountability, recognising their importance in sustaining confidence in our management of public funds. Performance improved materially in the December Countryside Stewardship (CS) and Environmental Stewardship (ES) payment window compared with the previous financial year, with more than 25,000 CS payments and over 5,000 ES payments made in the first month, providing earlier certainty for customers. We will continue to focus on sustaining these improvements, while recognising that there is more to do.
However, the transition since 2021 from legacy subsidy schemes to more complex domestic grant schemes has increased the inherent risk in what we deliver. New environmental land management schemes and greater options for customers have meant more complex rules, processes and system requirements. For farmers and land managers, that complexity can make compliance harder. It has also contributed to increased irregularity levels and the National Audit Office’s qualified regulatory opinion in relation to estimated irregular grant expenditure, driven primarily by non-compliance by grant recipients either by genuine error or knowingly overstating delivery. Together with colleagues in our parent department, the Department for Environment, Food and Rural Affairs (Defra), we are taking a disciplined approach to managing these risks, whilst continuing to deliver at scale and pace.
We are making it easier for customers to stay compliant by being clearer about what is required, engaging earlier when something may be going wrong, and using geospatial tools to spot issues and put them right sooner. We are implementing short-term technical solutions to stabilise services, improving data quality and assurance processes, and ensuring risks are clearly understood, transparently reported and actively managed.
As we progress, we are responding to customer and stakeholder feedback and learning lessons from scheme closures, including the Sustainable Farming Incentive (SFI) Expanded Offer closure and subsequent reopening, in a challenging delivery landscape. We are also addressing feedback from colleagues and customers on outdated systems and lengthy, prescriptive guidance that can be difficult to follow. Our focus is on simplifying the customer journey end-to-end, reducing avoidable errors and improving how quickly we resolve issues when they arise.
The launch of SFI 2026 represents a major operational focus for the agency and is expected to place increased demands on our delivery capability. We are working closely with Defra colleagues on scheme design to ensure a more simplified offer for customers, with a streamlined set of actions and reduced complexity at the point of application. Meeting this challenge will require resilient digital services, effective planning, and close collaboration across the Defra group to ensure scheme design and delivery operate as intended. Digital transformation is therefore central to how we build resilience, simplify processes and enhance customer service. As demand grows and resources tighten, our ability to automate routine activity, provide clearer guidance, improve data flows and reduce manual workarounds will be important in sustaining high-quality delivery and ensuring the agency remains fit for the future.
Our people remain at the heart of this work. Throughout this year, colleagues have adapted to change with professionalism and commitment, delivering the agency’s services while also helping to shape the systems and processes that will underpin our future. We will continue to invest in building capability, strengthening leadership capacity, and providing the support needed to navigate the changes ahead.
In closing, I would like to thank our partners across the Defra group, farming and environmental organisations, and the many customers who work with us and provide invaluable feedback. This report sets out the progress we have made against our objectives and how we are modernising processes and systems to improve the service we offer the nation’s farmers. It’s a really big challenge, but we are certainly up for it.
Oliver Munn
Chief Executive and Accounting Officer
7 July 2026
Chair’s report
This year has been both challenging and rewarding for the agency. Against the backdrop of continued pressures across the agricultural sector, the agency’s performance strengthened as the year progressed and remained firmly focused on supporting farmers, land managers and rural communities. I am proud of the professionalism, commitment and resilience demonstrated by colleagues across the agency.
Having joined as Chair in June 2025, I have greatly valued the warm welcome and constructive engagement from the agency’s staff, customers and partners across the Defra group. This has provided a valuable opportunity to listen, learn and develop a strong understanding of the agency and its operating context.
A significant milestone during the year was the establishment of the new Rural Payments Agency Board (RPA Board). Since March 2026, we have had a stable and fully constituted RPA Board, bringing together a broad range of skills and experience to provide clear strategic direction and effective oversight. Importantly, this includes members with backgrounds in arable farming and horticulture, alongside wider commercial, public sector and governance expertise. This diversity of perspective strengthens our understanding of the sector and enhances the quality of challenge and advice provided to the executive team.
There have also been important developments in executive leadership. I would like to place on record my sincere thanks to Paul Caldwell, who stepped down as CEO in June 2025 after 8 years of dedicated service. His leadership through periods of significant change has been invaluable to the agency.
Following Paul’s departure, Neil Hornby served as Interim CEO until January 2026. I am grateful to Neil for his guidance and direction whilst maintaining continuity during this transitional period.
In January 2026, we were pleased to welcome Oliver Munn as the new CEO. Under his leadership, the executive team is beginning to take shape, with work underway to build the capability and cohesion required for the agency’s next phase. Together with the establishment of a diverse and experienced RPA Board, this provides a strong platform of leadership and governance, positioning the agency well to deliver its priorities and achieve long term success.
Throughout the year, the RPA Board has placed strong emphasis on being a listening board. Members have visited several agency offices, meeting colleagues across a range of functions to understand their work, challenges and ideas for improvement. These engagements have deepened our insight into the agency and reinforced the dedication and professionalism of its staff.
Listening to customers has been equally important. A roundtable with farmers in the South West provided valuable insight into the pressures they face and what they need from the agency. We also visited a diversified arable farm near York where the government’s grant support has helped strengthen and diversify the business. These conversations took place as farmers continued to operate in a highly challenging environment, with recent global geopolitical developments contributing to rising input costs and increased uncertainty. A consistent message from customers was the need for schemes that are clearer, simpler and more predictable, including improvements to application windows and accessibility.
We have worked closely and constructively with Defra throughout the year, building a more open and collaborative relationship. This has supported clearer shared priorities, better communication and stronger alignment on the challenges and opportunities facing the sector. This partnership remains essential as the agency continues to evolve.
Looking ahead, the RPA Board’s priority is to support the executive team as it begins the transformation of the agency, establishing the foundations for a more modern, resilient and customer focused organisation, underpinned by stronger capability, clearer accountability and systems that are fit for the future.
The RPA Board will continue to work closely with the executive team and Defra to ensure the agency is well placed to meet future challenges and seize new opportunities.
Adrian Belton
Non-Executive Chair, Rural Payments Agency Board
7 July 2026
Purpose and objectives
Rural Payments Agency’s purpose and vision
-
Purpose - to grow environmentally and economically sustainable businesses across the country by delivering services that promote economic growth, boost food security and restore nature.
-
Vision - great people providing great services and delivering great outcomes.
-
People - work alongside partner organisations to deliver for customers and stakeholders.
-
Values - visible, engaging, respectful, inclusive, trusted, accountable and supportive.
Rural Payments Agency’s objectives
The Rural Payments Agency (the agency) was created in 2001 as an executive agency of the Department for Environment, Food and Rural Affairs (Defra) with dispersed teams based in offices across England. The agency plays an important role in delivering Defra’s food and farming agenda by supporting the growth of environmental and economically sustainable businesses.
The agency’s strategy is focused on improving services and developing people to drive outcomes aligned with government objectives. This will be achieved by simplifying schemes, processes and guidance, modernising outdated technology, data and operating models and enabling innovation, in collaboration with the whole of the Defra group, responding to customer feedback on the improvements that are needed.
The agency has responsibility for making competed and non-competed grant payments to farmers and rural businesses in England. Responsibilities include:
-
Operational delivery of environmental land management, including the Sustainable Farming Incentive (SFI), the evolution of Countryside Stewardship (CS), capital grants, other grant schemes (some described throughout this report), and new grant offers to help make agriculture more productive and environmentally sustainable.
-
Livestock identification and traceability through the British Cattle Movement Service.
-
An assurance programme which focuses on maintaining the highest standards of animal health and welfare, food quality and environmental outcomes.
-
The provision and integrity of English land data.
-
A customer contact centre providing a range of services on behalf of the Defra group.
Agency directorates and corporate services
Each of the agency’s executive team directors lead on a business area within the agency and these are listed below:
-
Chief Operating Officer
-
Customer Experience
-
Data and Innovation
-
Grants Services
-
Service Delivery
The agency’s corporate services comprise communications, human resources, finance, estate management, legal services, and information technology, all of which are centralised within the Defra group.
Defra group strategy
The Defra group drives economic growth, enhances nature, strengthens food security and protects animals, people and property from disease and flooding. The impact of Defra extends beyond national borders, sharing expertise and shaping policies globally.
The Defra outcomes framework represents what the Defra group aims to achieve, articulating its key role in the government’s Plan for Change and its missions through the agency’s priority outcomes. The outcomes framework reflects the priorities of the Defra group to restore nature, reform our water system, back the British farming and food industry and reset trading relationships. This is alongside the resilience and security responsibilities of Defra and the environmental outcomes outlined in the Environmental Improvement Plan.
Managing significant challenges in 2025-26
Level of irregularity
During 2025-26, the agency continued to manage the significant challenge of scheme irregularity arising from the transition from relatively simple land-based subsidy schemes to more complex agricultural environment schemes, including SFI and CS. While these schemes are designed to deliver more ambitious and targeted environmental outcomes, their inherent complexity increases the risk of irregularity.
As expenditure has continued to shift towards these more complex agricultural environment schemes, estimated irregularity has also increased, reaching 4.23% or £73.41 million in 2025-26, compared with 2.87% or £40.32 million in 2024-25. The agency recognises that this reflects a systemic risk arising primarily from scheme design, customer understanding and delivery complexity, and anticipates that qualification for irregularity will continue for several years. Further detail is provided in the Parliamentary accountability and audit report below.
During the year, the agency strengthened its understanding of the root causes of irregularity through analysis of scheme data, engagement with field officers and stakeholders, and scrutiny by the executive and the Audit and Risk Assurance Committee. This work identified key drivers including aspects of scheme design, measurement and mapping challenges, customer misinterpretation of requirements, and limited mechanisms for customers to proactively declare under-delivery.
In response, the agency agreed and began implementing a prioritised set of mitigations alongside the development of SFI 2026. A core element of this response is the simplification of schemes, working closely with Defra to reduce unnecessary complexity. This includes using operational evidence to inform decisions on the action offer, clarify requirements, and avoid introducing complexity that does not deliver proportionate environmental benefit.
These simplification efforts are supported by clearer guidance, targeted communications on accuracy and compliance, the introduction of tolerances at individual agreement level, and changes to processes to make it easier for agreement holders to declare under-delivery. In parallel, the agency continued to enhance its longer-term approach to preventing irregularity through improved monitoring, intelligence-led analysis and continued close working with the National Audit Office on the measurement of fraud and error.
While the impact of these measures will take time to be fully realised, the actions taken during 2025-26 represent a shift towards a more preventative, proportionate and evidence-led approach to managing irregularity, while balancing environmental ambition, value for money and protection of public funds.
SFI 2024 closure and reopening
On 12 May 2025, a written ministerial statement was made remaking the decision to close the SFI 2024 scheme. This scheme was closed to new applications on 11 March 2025 following full allocation of the available budget. At the point of closure, there were more than 37,000 live agreements in place, all of which continued to be paid in line with scheme rules, alongside the processing of eligible applications that had already been submitted.
The immediate closure, combined with high customer demand, resulted in increased volumes of enquiries and complaints, particularly from customers who had started but not submitted applications.
An error was made, which caused customers who had started, but not yet submitted, an application to be shown 2 messages when saving their application. 1 of these messages was shown in error due to a technical issue where the message from the online application used for the SFI 2023 offer was carried over unintentionally to the SFI 2024 offer. The message gave a legitimate expectation that customers with an application in progress, initiated within the previous 2 months, would be provided with 6 weeks’ notice to complete their applications. This resulted in a ministerial decision to allow a limited reopening of SFI 2024 for defined applicant groups. There were approximately 3,000 such applicants who were allowed a 6-week window to complete their applications.
This required the agency to implement revised eligibility criteria, targeted customer communications and time-limited application windows at pace, while maintaining effective financial control and assurance over a capped budget leading to delivery challenges.
This matter reinforced the importance of close alignment between policy decisions, digital service design and operational readiness. Lessons learned are informing improvements to application messaging, closure processes and contingency planning for future schemes with high demand variability.
Financial, resource and leadership pressures
During 2025-26, the agency operated under sustained financial and workforce pressure while continuing to deliver a large and complex portfolio of services. Demand remained high, with over 100,000 live environmental land management agreements and annual scheme payments exceeding £2 billion, alongside the delivery of legacy schemes, capital grants and statutory livestock services. This demand was managed within a constrained resource envelope and against a backdrop of resource intensive application windows.
Organisational capacity was further affected by workforce reductions during the year, including the departure of 146 colleagues through the Voluntary Exit Scheme supporting workforce reshaping to align capacity and cost with the agency’s future delivery priorities and funding envelope. In parallel, the agency experienced significant leadership instability, with 3 different chief executive officers in post over the course of the financial year, alongside numerous changes at non-executive and executive director level. While continuity arrangements ensured that statutory obligations and payment performance were maintained, the frequency of senior leadership changes reduced overall management capacity and increased pressure on remaining leaders, particularly during periods of operational peak and scheme change.
To mitigate these pressures, the agency prioritised frontline delivery, constrained non-essential activity and undertook a reprioritisation of transformation work to focus on a smaller number of high impact initiatives. Maintaining financial control and delivery performance under these conditions required careful governance and close coordination with Defra. While these actions supported continued service delivery during the year, financial, workforce and leadership stability remain critical dependencies for sustaining performance and resilience into 2026-27.
Going concern statement
The agency plays an important role in delivering significant funds to the rural economy and enhancing environmental outcomes. The agency expects to continue to deliver agricultural support payments in line with Defra’s strategy and government commitments, including on-going delivery of multi-year projects and grant agreements using funding provided by Defra. The government makes decisions about Defra’s funding through HM Treasury’s Spending Review process. This process sets funding for all government departments. The most recent Spending Review was completed in June 2025 and set departmental revenue funding through to 2028-29 and capital funding to 2029-30. The agency expects to continue to provide services within the funding envelope provided and has therefore prepared these financial statements on a going concern basis. The Rural Payments Agency Board considered this issue and agreed that the going concern basis is appropriate and consistent with the Financial Reporting Manual 2025-26.
Performance report
The Rural Payments Agency’s (the agency’s) purpose is to grow environmentally and economically sustainable businesses by improving services and developing people, helping farmers, landowners and traders achieve economic growth, boost food production and restore nature.
Following a challenging start to the financial year, the agency has delivered an improving year of operational performance, making visible progress against core objectives and delivering outcomes that matter to the agency’s customers. This has been achieved while maintaining a strong emphasis on stewardship, governance and accountability, which are critical to creating and sustaining confidence in the agency’s management of public funds.
The year has not been without its challenges. The ongoing transition since 2021 from legacy subsidy schemes to more complex domestic grant schemes has introduced greater flexibility and clearer policy intent, but also a higher inherent risk profile. For farmers and land managers, this has brought added complexity that makes compliance with scheme requirements more difficult. The agency recognises that clearer guidance and earlier dialogue are essential to help customers comply.
The ongoing transition has contributed to increased estimated irregularity levels and the National Audit Office’s qualified regulatory opinion in relation to estimated irregular grant expenditure, driven primarily by non-compliance by grant recipients either by genuine error or knowingly overstating delivery. These factors are not expected to be resolved in the short term because the agency is committed to delivering these schemes for several years to come.
The agency is working closely with colleagues in the agency’s parent department, the Department for Environment, Food and Rural Affairs (Defra) to manage the risks responsibly while continuing to deliver at scale and pace. The agency is moving towards making it easier for farmers to stay compliant by being clearer about the requirements and using geospatial tools to spot issues earlier.
Performance overview
Key performance indicators are regularly reviewed and updated from previous years. The key performance indicators for 2025-26 were:
Objective: Timely processing and payment of grant schemes
| Key performance indicator | What the agency did |
|---|---|
| 95% of Sustainable Farming Incentive payments made in the due month | 88.2% of Sustainable Farming Incentive payments made in the due month[footnote 1] |
| 90% of 2025 Countryside Stewardship revenue claims paid by 31 March 2026 | 98.2% of 2025 Countryside Stewardship revenue claims paid by 31 March 2026 |
| 95% of Countryside Stewardship capital claims paid within 60 working days | 97.4% of Countryside Stewardship capital claims paid within 60 working days |
| 90% of Environmental Stewardship payments made by 31 March 2026 | 98.8% of Environmental Stewardship payments made by 31 March 2026 |
| 95% of Farming Transformation Fund claims paid within 30 calendar days | 97.7% of Farming Transformation Fund claims paid within 30 calendar days |
| 95% of eligible Farming and Equipment Technology Fund 2024 claims paid by 20 June 2025 | 98.1% of eligible Farming and Equipment Technology Fund 2024 claims paid by 20 June 2025 |
Objective: Maintain accurate records of cattle in Great Britain
| Key performance indicator | What the agency did |
|---|---|
| 96% of notified cattle births, deaths and movements recorded within 5 working days of receipt | 99.6% of notified cattle births, deaths and movements recorded within 5 working days of receipt |
| 96% of cattle passports for valid applications and online issued within 5 working days | 99.8% of cattle passports for valid applications and online issued within 5 working days |
Objective: Timely processing and payment of trader schemes
| Key performance indicator | What the agency did |
|---|---|
| 98% of import licences issued within 5 working days | 100% of import licences issued within 5 working days |
| 100% of Fruit and Vegetables claims paid by 15 October 2025 | 100% of Fruit and Vegetables claims paid by 15 October 2025 |
| 100% of valid School Milk claims paid within 90 calendar days | 99.8% of valid School Milk claims paid within 90 calendar days |
Performance in numbers
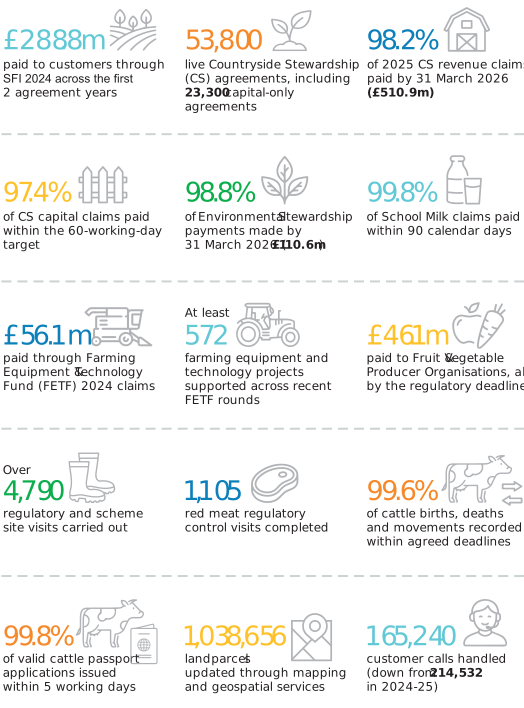
An infographic (simple artwork of fences, tractors, produce and other farming related items) of 2025-26 performance statistics included in this performance section of the document.
- £288.8m paid to customers through SFI 2024 across the first two agreement years
- 53,800 live Countryside Stewardship agreements, including 23,300 capital only agreements
- 98.2% of 2025 CS Revenue claims paid by 31 March 2026 (£510.9m)
- 97.4% of CS Capital claims paid within the 60 working day target
- 98.8% of Environmental Stewardship payments made by year end (£110.6m)
- 99.8% of School Milk claims paid within 90 calendar days
- £56.1m paid through Farming Equipment & Technology Fund (FETF) 2024 claims
- 572+ farming equipment and technology projects supported across recent FETF rounds
- £46.1m paid to Fruit & Vegetable Producer Organisations, all by the regulatory deadline
- Over 4,790 regulatory and scheme site visits carried out
- 1,105 red meat regulatory control visits completed
- 99.6% of cattle births, deaths and movements recorded within agreed deadlines
- 99.8% of valid cattle passport applications issued within 5 working days
- 1,038,656 land parcels updated through mapping and geospatial services
- 165,240 customer calls handled (down from 214,532 in 24–25)
Performance analysis
The values in this performance analysis section relate to paid claims on a cash basis and accordingly will not reconcile to expenditure reported in Note 5 of the financial statements which includes net movements in accrued and prepaid amounts.
Sustainable Farming Incentive (SFI)
SFI is a scheme that pays farmers to adopt environmentally friendly farming practices whilst maintaining food production. Participants select specific actions that align with defined standards and focus on practical evidence-based activities that deliver measurable environmental benefits.
Performance against the agency’s timeliness metric for all SFI payments is set out in the performance overview above. Performance was affected by the early-stage operation of a large-scale scheme. Supporting systems, processes and guidance continued to be refined and embedded during the year alongside the development of subsequent scheme launches. Lessons from this experience are being applied to future scheme implementation.
SFI 2024
Following the success of the SFI 2023 scheme, the SFI 2024 Expanded Offer was launched in June 2024, where customers were invited to apply through an expression of interest exercise, similar to SFI 2023. Once the scheme was opened, 18,080 applications were submitted by 11 March 2025 when the scheme was closed to further applications. Since the original application window was closed there have been 3 extensions to allow customers unable to apply during the first window to submit their applications. At 31 March 2026, 20,804 applications have been received, 19,914 of which were accepted and 99.9% of those accepted are live agreements. £288.8 million has been paid out to customers over the first 2 agreement years (Year 1: £270.2 million, Year 2: £18.6 million).
SFI 2023
At 31 March 2026 there were 25,150 current live SFI 2023 agreements. £928.5 million has been paid out to customers over the 3 agreement years (Year 1: £508.6 million, Year 2: £411.9 million, Year 3: £8.0 million).
SFI Pilot
The SFI Pilot concluded according to the pilot agreement terms, money paid to customers for their involvement reached £40.3 million (Year 1: £13.2 million, Year 2: £13.5 million, Year 3: £13.6 million).
SFI in action
Farmer Will Lacey hosted the agency’s Chief Executive Officer Oliver Munn at Lacey’s Family Farm in Buckinghamshire in March 2026. This visit included showing some of the benefits the SFI scheme has enabled on his land. As well as extending the farm’s hedgerows, they also planted wild bird cover, and they have seen a real benefit to the wildlife on the farm including red kites and yellowhammers.
Paula from the SFI Delivery Team said
I work in the team where we process SFI agreements for farmers just like Will up and down the country. Will’s agreement included the winter bird food action, so by helping Will we help support farmland bird populations, strengthen local ecosystems and play an important part in nature recovery.
Countryside Stewardship (CS)
CS schemes provide funding to farmers and land managers to improve their local environment.
As of January 2026 (for the 2025 scheme agreement year), there were 53,800 live CS agreements. This total includes 23,300 capital only agreements and 30,500 revenue agreements, of which just over 18,100 also include capital options. Approximately 10,800 new capital agreements were received and issued for the 2025 scheme agreement year, of which 8,467 (78.4%) were core capital grants. The agency expects the number of agreements with revenue options to reduce year on year, as agreements expire, and anticipates a continued increase in capital grant agreements.
Performance against the agency’s CS payment metrics is set out in the performance overview above.
CS higher tier
CS higher tier involves more complex environmental management schemes which offer significant benefits to high-priority areas. Since January 2025, 2,852 farmers and landholders have been invited to complete the pre-application advice process for CS higher tier. 1,855 have responded to the invitation or progressed past this stage. 840 have completed the pre-application advice process, of which 778 have been invited to apply. At 31 March 2026 610 applications are active.
CS mid-tier extensions
CS mid-tier pays farmers and land managers to undertake multi-year environmental improvements and capital projects. The agency offered customers who had a CS mid-tier agreement that was due to expire by December 2025 the option of extending their agreement for a further year. 5,390 CS mid-tier extensions were offered to customers, and of those who responded, 4,204 chose to extend their agreements at a value of £58.8 million.
CS capital grants
CS capital grants provide funding for specific capital items to improve the local environment, water quality, and woodland management. Since 1 April 2025 to 31 March 2026, the agency received over 15,488 CS capital claims. 14,511 valid claims were paid totalling £220.8 million. This is an increase of 759 claims and £8.1 million, compared to last year. As shown in the performance overview table above, CS capital claims performance exceeded the target in 2025-26.
CS revenue claims
In 2025-26, the agency received over 31,379 eligible CS revenue claims. By 31 March 2026, the agency had issued 30,801 payments, equating to £510.9 million. This was a decrease of around 1,095 claims by volume and an increase of £27.2 million by value compared with the previous year. As shown in the performance overview table above, this represented 98.2% of eligible claims paid by year end, exceeding the target.
CS in action
Educational access
Educational access (ED1) is an option within the CS scheme where farmers allow organised groups, usually school pupils or care-farming participants, to visit their land and learn about farming and the countryside. The visits usually include a guided tour where the farmer explains links between farming, conservation and food production. The aim is to help their visitors understand how food is produced and how the environment is managed while also encouraging engagement with rural landscapes. Farmers receive payment from the agency for each eligible visit.
Ash from the CS Delivery Team said
Working in the CS processing team, you see options such as ED1 claimed regularly each year. This is not only beneficial financially for farmers, but it also aims to teach, engage and inspire the next generation through farm visits.
Environmental Stewardship (ES)
ES is the responsible use, management, and protection of natural resources to ensure ecosystems remain healthy, resilient, and productive for future generations. The agency has introduced measures each year to improve the administration and efficiency of the ES scheme. Under previous rules agreed with the European Commission, the agency was only able to offer 1-year extensions and on a rolling basis. From January 2023, under domestic regulations, the agency was able to give existing agreement holders greater certainty and clarity by offering them extensions up to 5 years. This means that the agreements for most ES customers have been extended until 2028.
From 1 April 2023, all ES scheme expenditure transactions under the Rural Development Programme for England (RDPE) are recognised and presented in the agency’s annual report and accounts and are now entirely domestically funded. Prior to 1 April 2023, the ES RDPE programme was entirely EU funded, and all expenditure and income was reported in the annual report and accounts of the agency’s parent department, Defra.
As shown in the table below, the agency’s ES payment performance continues to improve year on year.
| Payments made as a % of eligible claims received | Scheme year | Performance |
|---|---|---|
| ES final payment | 2023 | 89.8% |
| ES final payment | 2024 | 97.3% |
| ES final payment | 2025 | 98.8% |
At 31 March 2026, the agency made a total of 5,368 (98.8%) payments equating to £110.6 million.
Trader operations
Trader operations support commercial businesses, the education sector and horticultural producer organisations (POs) across the UK.
Some of the successes during 2025-26 were:
-
The agency issued over 39,000 licences (made up of import licences, tariff rate quota licences and various forms of export certification to help the movement of goods in and out of the UK). All licences were issued within 5 working days, exceeding the target of 98%.
-
Over £46.1 million of financial support was provided to fruit and vegetable POs across the UK, with all POs receiving their 2024 annual payments by the regulatory deadline of 15 October 2025. The agency is currently on track to make all 2025 payments by the regulatory deadline of 15 October 2026. There will be no further horticulture payments once the 2025 scheme year payments have been made.
-
£4.3 million was paid by the School Milk subsidy scheme in the 2025-26 financial year, with 99.8% of all claims being paid within 90 calendar days. This helped over 13,500 schools across the UK to provide subsidised milk, yoghurt and yoghurt products to their students.
Annual grants
The agency is responsible for delivering various grants, decided by ministers, in delivering the farming and countryside programme objectives. This includes the Farming Investment Fund (FIF) and other grants including the water restoration fund, targeted silo replacement scheme and the smaller abattoir fund (including game handling establishments).
The FIF provides grants to farmers, foresters and growers, including contractors to these sectors, so they can invest in the equipment, technology and infrastructure they need to improve farm productivity and enhance the natural environment. FIF is made up of 2 schemes, the Farming Equipment and Technology Fund and the Farming Transformation Fund.
Farming Equipment and Technology Fund (FETF)
FETF provides grants across 3 themes to improve productivity, manage slurry and improve animal health and welfare. FETF 2025 launched in May 2025. Up to 31 March 2026, 5,891 claims have been received at a total value of £40.6 million. FETF 2026 launched in February 2026 with the application window closing on 12 May 2026.
FETF 2025 case studies
E C & S J Alton – FETF productivity funding
North Yorkshire cereals farm E C & S J Alton secured FETF 2025 productivity funding to invest in 2 pieces of equipment designed to improve how they manage irrigation.
They installed an irrigation sensor to monitor soil moisture levels, helping them see exactly when crops need watering. They also bought an irrigation controller for their rain guns, which automates watering schedules and ensures the right amount of water is applied at the correct pressure and time.
Together, this equipment helps the farm make more informed decisions about when, and how much, to irrigate. By targeting water use more precisely, the equipment reduces unnecessary watering while supporting crop growth, helping the farm to use water more efficiently and manage costs.
Mr Alton says
The equipment has improved water efficiency, resulting in reduced costs and a lower environmental impact. It also minimises nutrient leaching caused by over-application and supports regenerative agriculture practices.
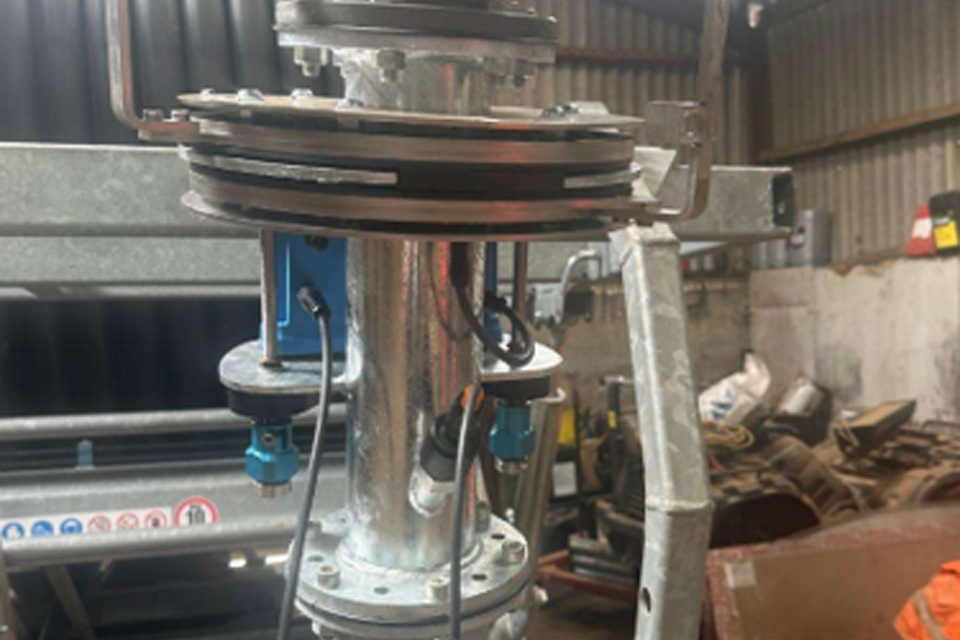
Irrigation sensor at E C & S J Alton’s farm
N L Pugh and Co – FETF Animal Health and Welfare funding
Shropshire-based livestock farm N L Pugh and Co secured FETF 2025 Animal Health and Welfare funding to improve their sheep management and animal welfare. Funding under the continual improvement in farm animal health and welfare supported the purchase of 3 pieces of equipment:
-
An automatic weighing and drafting crate, which quickly and accurately weighs sheep before sorting them into groups based on weight, sex or age.
-
An electronic identification gun, which reads ear tags and triggers the correct dose of treatment based on each animal’s weight.
-
A snacker feeder for mobile supplementary feeding in the field helping to reduce ground damage that can occur with traditional trough feeding.
Investment into the equipment has improved both flock management and farm efficiency.
Mr Pugh says
The FETF grant has enabled us to acquire equipment the business wouldn’t have been able to purchase on its own. Having this equipment has made handling much easier and has improved the way we farm.
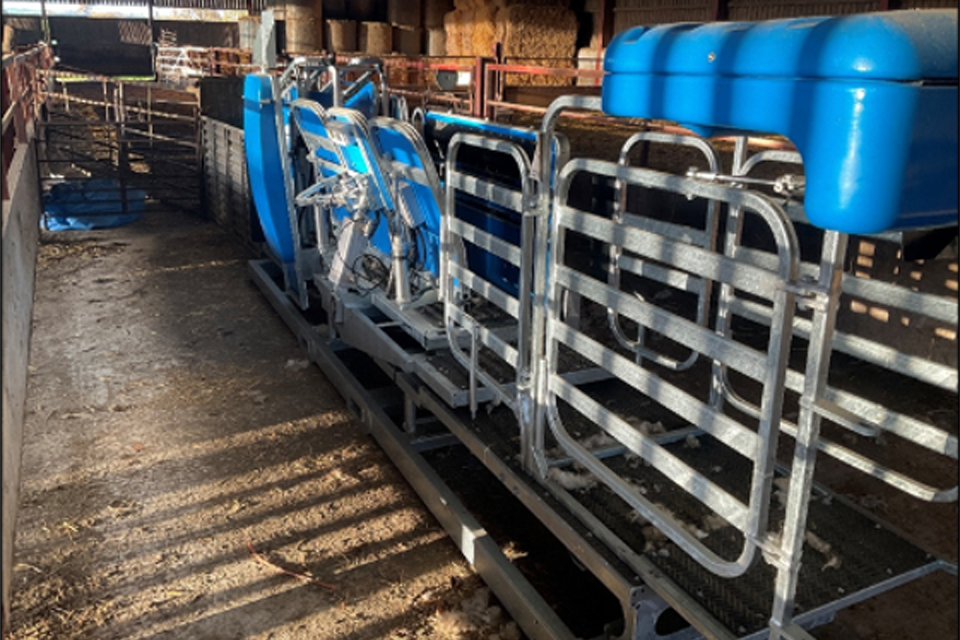
Automatic weighing and drafting crate at N L Pugh and Co’s farm
Farming Transformation Fund (FTF)
The FTF provides grants towards large capital items to help businesses improve productivity, profitability, and environmental sustainability. It includes the following:
-
FTF Water Management: This grant is to fund items to improve using water for irrigation, and to secure water supplies for crop irrigation. The agency has contracted 77 projects across 2 rounds. Round 2 closed in October 2024, with a total committed value of £13.2 million. Of this, £8.8 million has been paid to 31 March 2026. The remaining value of £4.4 million reflects projects that are still live and will deliver over multiple years, with funding drawn down following validation in line with agreed milestones and claim schedules.
-
FTF Improving Farm Productivity: This grant is for innovative farming equipment that increases productivity and improves the environment. There have been 2 rounds with Round 2 closing in July 2025. To 31 March 2026, 408 projects have been contracted worth £32.7 million, with £15.7 million paid out in claims received and validated. At 31 March 2026 there were 112 Round 2 project applications being assessed, with a total value of £8.5 million.
-
FTF Adding Value: This grant is for farm buildings, machinery or equipment that adds value to crops or livestock by increasing productivity and improving the environment. Round 1 closed in January 2024 and received 155 applications requesting £22.0 million in grant funding. To 31 March 2026, 109 projects have been contracted worth £16.0 million, with £12.2 million paid out in claims following validation.
-
FTF Calf Housing for Health and Welfare: This grant is to build new, or upgrade existing, buildings to house calves to deliver health and welfare benefits. Round 1 closed in November 2023. It received 136 applications requesting £10.2 million. To 31 March 2026, 27 projects were contracted worth £2.3 million, and 3 claims were paid following validation, totalling £0.1 million. At 31 March 2026, a further 28 applications were under review, worth £2.4 million.
-
FTF Laying Hen Housing for Health and Welfare: This grant is to upgrade, replace or provide a veranda to existing laying hens housing or pullet housing to deliver health and welfare benefits. Round 1 closed to online applications in September 2024. The agency invited 88 applicants requesting £29.3 million to progress to the next stage of the application process, which required completed full applications to be submitted by 28 April 2026. At 31 March 2026, 8 applications were received, worth £3.5 million.
-
FTF Slurry Infrastructure: This grant is to improve or expand slurry storage. Round 1, closed in June 2024, received 108 applications requesting £15.5 million. To 31 March 2026, 89 projects had been contracted worth £12.2 million, with £5.1 million paid out in claims following validation. At 31 March 2026 6 projects were under review, worth £0.8 million. A second round closed in September 2024. To 31 March 2026, 94 projects were contracted worth £12.1 million, with £1.7 million paid out in claims following validation. At 31 March 2026, there were a further 225 projects at different stages of review, worth £33.4 million.
FTF case study
Mount Pleasant Farm robotic milking
Mount Pleasant Farm is a long-established dairy enterprise that has been operating since 2000. The business has sought ways to modernise its operations and improve efficiency. With support from the FTF Improving Farm Productivity grant, Round 2, the farm invested in 3 voluntary robotic milking systems.
The robotic milking systems enable the cows to have the freedom to choose when they are milked, reducing stress and improving overall wellbeing. The precision of the systems also contributes to improved milk quality with more consistent milking routines. The robots monitor individual cow behaviour and health indicators including better udder health monitoring. The data outputs have become a valuable management tool, enabling more informed decision making and supporting long-term herd health planning.
As well as the welfare of the cows, this has had a huge impact on the physical labour required for daily milking routines. The robots have helped Mount Pleasant Farm address labour shortages and improve work-life balance for their staff. With the introduction of the robotic milkers, they have future-proofed their business, positioning themselves for long-term sustainability, the farmer says
From a business perspective, the process is very straightforward. It has improved efficiency and enabled us to produce more output with less labour.
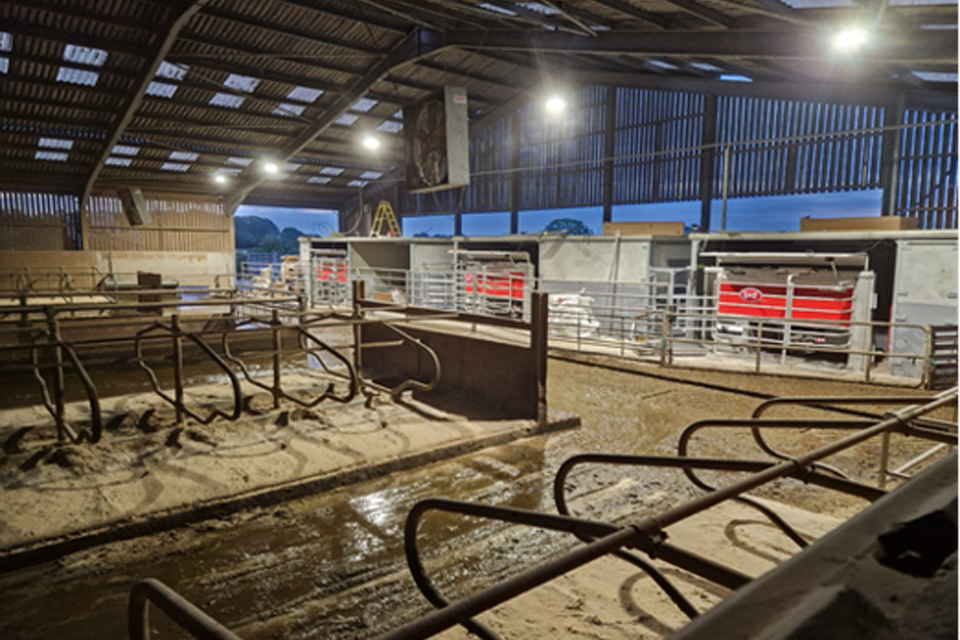
Mount Pleasant Farm robotic milking system
Cattle records
The agency maintains an online database to record cattle births, deaths and movements across England and Wales. This underpins disease control and food traceability, supporting the safe operation of the food chain. The British Cattle Movement Service (BCMS) achieved all key performance indicators with 99.6% of cattle births, deaths and movements completed within agreed deadlines.
The overall volume of non-electronic transactions reduced to 468,000 (2024-25: 490,000), but reductions in non-electronic death transactions were offset by increases in birth and movement transactions. Further effort is required to shift customers to digital channels and achieve operational efficiencies.
The people working in BCMS continued to provide the front-line service for the Livestock Information Service (LIS). LIS is the traceability service (for sheep, goats and deer) and the ear tagging service (for cattle, sheep, goats, and deer). This multi-species service has been and will be developed by Defra’s Livestock Information Transformation Programme. During 2025-26 the agency administered these services on behalf of Defra with Livestock Information Ltd acting as a supplier of the 2 information technology systems that underpin the LIS.
Regulatory and advice service
The agency’s visit programme remains central to assuring compliance with scheme rules and safeguarding public funds while supporting delivery of animal health, welfare and environmental outcomes.
During 2025-26, the agency delivered over 4,790 visits across grant schemes and regulatory controls. This included cattle identification inspections, sheep and goat inspections (with support from the Animal and Plant Health Agency), and regulatory controls visits across the red meat sector.
The agency also implemented new regulatory requirements, including the new Sheep Carcase Classification regulations and the first full year of the Management of Hedgerows (England) Regulations 2024 under which the agency delivered 63 visits based on referrals, processed 263 referrals and processed 1,423 self-declaring notifications for derogation from the cutting period during August to allow for cutting hedges due to sowing oilseed rape or grass.
The agency continues to work collaboratively with officers from the Scottish Government Rural Payments and Inspections Division, and the Department of Agriculture, Environment and Rural Affairs Northern Ireland, along with the Food Standards Agency and their National Food Crime Unit to deliver improved transparency, efficiencies and outcomes throughout the red meat supply chain.
The agency is seeking to expand the use of remote sensing and data to target interventions more effectively. This will enable more proportionate use of field resources, reduce burden on customers, and support earlier identification of risks.
Geospatial services
The agency ensures land data remains current and reliable by focusing on data that hasn’t been reviewed within the last 3 years. This is achieved through a combination of customer notifications via the rural land change online service, field officer reports captured in the field, and desk-based mapping assessments carried out by digitising suppliers using the latest aerial photography (proactive mapping). This approach enables the agency to update approximately 1 million land parcels annually, while carefully avoiding disruptions to scheme application and payment deadlines. It ensures the agency does not amend land already updated by customers or field officers unnecessarily. The agency’s land data supports accurate scheme payments and serves the needs of the Defra group and the wider public sector. For example, it is used by the Animal and Plant Health Agency in their disease control work, by local councils for Rights of Way enforcement, and by the Ministry of Housing, Communities and Local Government in identifying suitable land for housing developments.
To drive efficiency the agency is live testing an artificial intelligence ‘no change’ model developed by Ordnance Survey, which uses 5 independent models to analyse imagery and predict whether parcels require further assessment.
In 2025-26 the agency delivered map updates on 1,038,656 land parcels. These are a mixture of changes submitted by customers, field officers, and those proactively changed or verified as needing no change using the latest aerial imagery.
The geospatial team maintained all spatial data used across the agency, from Ordnance Survey and aerial photography to datasets from other Defra bodies, which are critical to scheme eligibility and validation. The agency produced the Crop Map of England for external use and spatial versions of CS agreements for sharing with public sector partners.
The agency deployed a bare soil marker nationally to support fraud and error prevention by predicting parcels that are bare when green cover is expected, strengthening the agency’s capacity to monitor compliance and support field operations.
Expanding this capability, the geospatial analytics service, expected in Autumn 2026, will deliver area-wide monitoring. Multiple markers will be deployed across land covers within a parcel, improving the quality of the agency’s analytical outputs. Data will be available for widescale monitoring and to join with existing datasets to build an intelligence picture. This service will be transformative for agency scheme monitoring and will deliver key insights to underpin improvements in scheme design and environmental outcomes.
The agency’s hedgerow and tree product developed in association with Forest Research will be published in 2026 by Defra’s Natural Capital and Ecosystem Assessment programme for habitat reporting.
Customer Contact Centre
Demand for the agency’s customer contact centre was successfully reduced year on year, with 165,240 calls handled (2024-25: 214,532[footnote 2]and 138,435 items of correspondence processed (2024-25: 156,5021). This reflects steps that have been taken to increase the use of digital services, improved guidance, and greater uptake of self-service options.
Defra’s general helpline received 12,316 calls (2024-25: 18,392), with 11,878 calls answered (96.4%) during 2025-26 (2024-25: 97.2%). Performance exceeded the service level agreement, with 84.4% of calls answered within 1 minute against a target of 80% (2024-25: 80.6%).
The remaining helplines received 160,380 calls (2024-25: 205,145[footnote 3], with 153,362 calls answered (95.6%) during 2025-26 (2024-25: 95.9%). The agency answered 79.6% of calls within 2 minutes, close to the service level agreement target of 80% (2024-25: 77.9%).
To improve customer experience the agency continues to invest in digital capability, including expanded online forms and enhanced use of customer insight. This has improved data quality, reduced avoidable follow up, and supported a more responsive service.
The agency’s Digital Confidence Programme has supported thousands of customers through personalised one-to-one sessions, helping them build the skills and confidence needed to self-serve effectively.
The agency’s enhanced Natural Language Processing capability offers greater insight into customer contact themes and root causes, enabling more personalised responses and supporting increased use of self-service. This marks a significant shift in how customers access and resolve enquiries, improving first contact resolution through clearer, more responsive guidance.
The agency accesses feedback through customer listening posts which are now an established and integral part of the customer journey, providing richer insight across all customer contact channels and enabling more targeted service improvements compared with previous years.
Complaints
Complaint volumes increased in 2025-26, primarily due to the closure of CS capital and SFI scheme rounds. Delays associated with the completion of historic land actions to support customer applications were also experienced. Plans to mitigate in the future include proactive scheme preparation communication and budget utilisation transparency.
Complaints relating to CS and SFI schemes accounted for 36% and 44% of the total, respectively. The average number of days to resolve complaints was 28.6 days, within the 30-day key performance indicator.
Despite this increase, complaint handling performance improved. The agency resolved more complaints than the number of complaints received, reducing the number outstanding at year end, and increasing the proportion resolved to 94% (2024-25: 89%), demonstrating improved efficiency and capacity in complaints handling.
| Complaints handled | 2025-26 | 2024-25 |
|---|---|---|
| Prior year complaints unresolved | 49 | 46 |
| New complaints received | 546 | 391 |
| Complaints resolved, withdrawn or cancelled | 557 | 388 |
| Complaints unresolved at 31 March | 38 | 49 |
During 2025-26 there were 4 complaints to the Parliamentary Ombudsman of which 2 remained open at the end of the year. The 2 closed were found in favour of the agency. Outcomes from closed cases are reviewed to identify learning and drive service improvements.
| Scheme | 2025-26 | Closed | Outstanding |
|---|---|---|---|
| Countryside Stewardship | 2 | 1 | 1 |
| Sustainable Farming Incentive Expanded Offer | 1 | 1 | - |
| Sustainable Farming Incentive application (linked complaint) | 1 | - | 1 |
Appeals
The agency received fewer appeals during 2025-26, 61 compared to 77 in 2024-25.
A total of 65 appeals were resolved during the year. Of those concluded (excluding withdrawals), 29.8% were upheld or partially upheld. The outcomes provide an important indicator of areas where decision making or guidance can be strengthened. The agency is using these insights to refine processes, improve clarity of scheme requirements, and reduce the likelihood of future appeals.
The Independent Agricultural Appeals Panel continues to provide external scrutiny, ensuring that decisions are consistent with scheme rules and legislation, with final decisions made by the agency’s parent department, Defra, ministers.
| Independent Agricultural Appeals Panel | 2025-26 | 2024-25 |
|---|---|---|
| Prior year appeals unresolved | 26 | 23 |
| Appeals received | 61 | 77 |
| Of which: | ||
| Customer appeals upheld | 15 | 25 |
| Customer appeals partially upheld | 2 | 7 |
| Agency decision upheld | 40 | 36 |
| Appeals withdrawn | 8 | 6 |
| Total appeals resolved | 65 | 74 |
| Appeals unresolved at 31 March | 22 | 26 |
Anti-corruption and anti-bribery matters
The agency has zero tolerance for instances of bribery and corruption involving employees, including permanent, fixed-term and contingent staff. All employees are required to act with honesty and integrity and to comply with the Rural Payments Agency Conduct and Propriety Policy, the Civil Service Code, and all relevant policies and procedures. Any suspected instances are taken seriously and investigated in line with established procedures, with appropriate and proportionate action taken where they are substantiated.
The agency is committed to protecting public funds, assets and information from fraud across operations, including scheme expenditure. All suspicions and referrals of fraud are taken seriously and assessed and investigated in line with established procedures. The agency recognises that fraud risk cannot be eliminated and applies a risk-based approach, with proportionate controls designed to prevent, detect and respond to fraud. This remains a key area of focus for ongoing improvement, particularly in relation to scheme expenditure and estimated levels of irregularity, the agency recognises the need to continue strengthening its control framework.
Financial review
Preparation of the annual report and accounts
The annual report and accounts are prepared in accordance with Section 7(2) of the Government Resources and Accounts Act 2000, the Accounts Direction issued by HM Treasury and the Financial Reporting Manual published by HM Treasury.
Financial performance review
The agency considers its financial performance in 2 categories, running expenditure representing monies needed to provide the service required of the agency’s parent department, the Department for Environment, Food and Rural Affairs (Defra), and scheme expenditure related to the funds the agency administers.
Gross running expenditure this year of £221.1 million is lower than the previous year (2024-25: £230.2 million). Total staff expenditure has risen year-on-year by £9.1 million due in part to permanently employed staff receiving average pay awards up to 3.25% effective from 1 July 2025, see Note 2. This has been offset by a reduction in other, non-staff, running expenditure of £18.2 million mainly due to a reduction in the corporate overhead recharge from Defra, see Note 3.
Net running expenditure was £219.1 million (2024-25: £228.2 million) after allowing for income. Running cost income remained similar at £1.9 million in 2025-26 (2024-25: £2.0 million), this consisted almost entirely of income for work on the British Cattle Movement Service on behalf of Defra of £1.9 million (2024-25: £1.9 million), see Note 4.
Overall net scheme expenditure under schemes administered by the agency in 2025-26 was £1,735.5 million (2024-25: £914.5 million). The primary schemes making up this expenditure were Countryside Stewardship – revenue £533.3 million (2024-25: £566.0 million), and Sustainable Farming Incentive (SFI) £737.5 million (2024-25: £315.5 million), see Note 5 for details. Other significant scheme expenditure in 2025-26, included capital grants £242.3 million (2024-25: £244.5 million) and Environmental Stewardship amounting to £111.2 million (2024-25: £95.9 million), see Note 5.
The overall rise in net scheme expenditure was driven principally by the increase in SFI grant expenditure described above, and the absence this year of one-off recognition of negative expenditure in relation to delinked payments which were processed in 2024-25 to reflect a change in the expected position for future payment rates (2024-25: (£487.1 million)), see Note 5.
Financial position
Non-current assets of the agency have decreased overall in the year to 31 March 2026. £21.1 million of assets were transferred from Defra (2024-25: £21.5 million) however depreciation and amortisation totalled £22.5 million (2024-25: £21.0 million).
Trade and other receivables have increased by £66.6 million compared to 31 March 2025. This is largely due to SFI prepayments increasing by £63.2 million to £235.5 million at 31 March 2026 (31 March 2025: £172.3 million), see Note 7.
The cash and cash equivalent balance held at 31 March 2026 of £50.0 million represents a decrease of £113.4 million compared to 31 March 2025. The 31 March 2026 balance was in line with normal cash management arrangements whereby a balance is maintained to cover any urgent payment requirements or funding requests. The 31 March 2025 balance was unusually high due to the inclusion of the receipt of final EU funding. The cash and cash equivalent balance include securities received from traders, see Note 8.
Trade and other payables due within 1 year have decreased by £304.1 million compared to 31 March 2025. This is mainly due to the settlement of the delinked payments accrual of £265.0 million recognised at 31 March 2025, this was paid during 2025-26, see Note 9.
Whilst there has been no material movement in the delinked payments provisions balance, £21.7 million has been recognised as current at 31 March 2026 for the payments that are expected to be made during 2026-27, see Note 10.
Financial risk
Whilst the agency is not exposed to any significant external financial market risks in administering scheme payments, scheme complexity and demand-led design does represent a financial management challenge. More on this risk is set out under Managing significant challenges in 2025-26 section above.
The agency actively manages the risks of non-compliance with scheme rules especially since in many cases these will reflect a loss to the taxpayer, and irregular spend within the meaning of HM Treasury’s Managing Public Money. The Governance statement below describes the agency’s approach to risk in this area, and the Parliamentary accountability and audit report, provides transparency on the extent of non-compliance.
Sustainability report
The agency’s commitment to net zero
Sustainability is central to the agency’s core purpose as an organisation, which is to grow environmentally and economically sustainable businesses. It is also important internally in reducing the agency’s environmental footprint and work towards net zero. From the schemes administered to the offices worked in and the equipment used, from travel to procurement, from governance to behaviours, all of these have sustainability ambitions at the heart of them.
The Department for Environment, Food and Rural Affairs (Defra) group provide the agency’s corporate services (including estates and information technology) which means many of the areas covered by the Greening Government Commitments are centrally managed by it. However, the agency has a dedicated sustainability team which engages with colleagues across the Defra group to ensure the agency is supporting the delivery of sustainability ambitions by using both central government and departmental policies to enhance the agency’s approach. The agency is doing this by:
-
Establishing sustainability alongside people, finance and customers as key topics when considering the impacts of decision making.
-
Decarbonising business travel and encouraging more sustainable commuting to work towards net zero.
-
Improving capability and strengthening the link between operations and environmental outcomes.
-
Improving the use of resources and services to reduce waste and develop a circular economy approach.
Examples of how the agency is achieving these include:
-
Decarbonising business travel. The agency’s lease car fleet now consists solely of plug-in vehicles, with over 80% of these being fully electric.
-
Strengthening governance. All new strategies and process changes must document their sustainability impacts before approval.
We are making excellent progress towards the target to electrify our fleet of lease cars by the end of 2027. Changes to our lease car scheme have increased the uptake in electric vehicles and it is interesting to note that our fleet size has increased in size despite the field and meat technical scheme teams decreasing in size. This indicates that use of private vehicles by travelling officers has declined considerably, which will drive operational efficiencies as well as decarbonising our business travel.” – Paul Moody, Regulatory and Advice Service.
The agency also encourages its people to play their part in helping us become more sustainable through their individual behaviours.
Key performance indicators
| Key performance indicators | Change against 2017-18 baseline |
|---|---|
| Mitigating climate change working towards net zero by 2050 | Reduced emissions by 65% |
| Water consumption | Reduced by 42% |
| Percentage of waste recovered or reused | Increased by 5.5% |
The agency has achieved improved performance against the baseline year of 2017-18, with overall emissions reduced by over 65% and water consumption reduced significantly. The agency continues to maximise hybrid working, rationalise its estate and decarbonise business travel, all of which have positively contributed to a significant reduction in emissions.
Greenhouse gas emissions
Non-financial indicators (tonnes CO2)
| 2025-26 | 2024-25 restated3 | 2023-24 | 2022-23 | 2017-18 baseline | |
|---|---|---|---|---|---|
| Scope 1 emissions (direct) | 204.10 | 290.93[footnote 6] | 385.70 | 532.53 | 716.67 |
| Scope 2 emissions (indirect) | 165.91 | 269.47 | 367.24 | 332.67 | 724.50 |
| Scope 3 emissions (direct travel) | 210.19 | 329.25{^6] | 253.94 | 393.48 | 220.30 |
| Total emissions | 580.20 | 889.65 | 1,006.88 | 1,258.68 | 1,661.47 |
| Direct carbon from buildings | 140.75 | 219.65 | 291.39 | 335.73 | 229.44 |
| Carbon from UK flights | 0.51 | - | 0.13 | 0.69 | 5.06 |
| Carbon from international travel | 3.08 | 0.66 | - | 1.50 | No data[footnote 4] |
Related energy consumption (KWh)
| 2025-26 | 2024-25 | 2023-24 | 2022-23 | 2017-18 baseline | |
|---|---|---|---|---|---|
| Electricity | - | - | - | - | 2,060,820[footnote 5] |
| Electricity renewable | 897,605 | 1,301,436 | 1,806,707 | 1,727,564 | No data[footnote 5] |
| Gas | 769,442 | 1,277,320[footnote 4] | 1,591,226 | 1,836,978 | 1,245,754 |
| Biomass | - | - | - | - | 1,182 |
Financial indicators (£)
| 2025-26 | 2024-25 | 2023-24 | 2022-23 | 2017-18 baseline | |
|---|---|---|---|---|---|
| Electricity – expenditure | 320,039 | 457,321 | 585,357 | 294,301 | No data[footnote 4] |
| Gas – expenditure | 39,281 | 79,332 | 74,809 | 138,802 | No data[footnote 4] |
| Total expenditure in energy | 359,320 | 536,653 | 660,166 | 433,103 | 240,052 |
| Expenditure on official business travel | 981,156 | 1,806,383 | 1,247,411 | 1,374,620 | 2,121,107 |
Waste Management
Recovered or recycled (tonnes)
| 2025-26 | 2024-25 | 2023-24 | 2022-23 | 2017-18 baseline | |
|---|---|---|---|---|---|
| Reused or recycled | 40.73 | 53.87 | 41.01 | 55.24 | 161.37 |
| Composted | 4.71 | 2.69 | 0.32 | 0.36 | 6.09 |
| Incinerated with energy recovery | 16.42 | 30.49 | 18.16 | 20.97 | 49.12 |
| Total recovered or reused | 61.86 | 87.05 | 59.49 | 76.57 | 216.58 |
Not recovered or recycled (tonnes)
| 2025-26 | 2024-25 | 2023-24 | 2022-23 | 2017-18 baseline | |
|---|---|---|---|---|---|
| Incinerated without energy recovery | - | 0.56 | 0.18 | 0.75 | - |
| Landfill | - | 0.73 | 2.86 | 4.77 | 11.90 |
| Total waste | 61.86 | 88.34 | 62.53 | 82.09 | 228.48 |
| % recovered or reused | 100.00 | 98.54 | 95.15 | 93.30 | 94.79 |
Total waste costs have not been captured historically. However, it is estimated that for 2025-26 the agency’s share of Defra group waste costs approximated £35k, and chiefly comprised of costs for recycling, incineration, landfill, and hazardous waste disposal (2024-25: £40k).
Finite Resource Consumption
| 2025-26 | 2024-25 | 2023-24 | 2022-23 | 2017-18 baseline | |
|---|---|---|---|---|---|
| Direct water consumption (m3)[footnote 7] | 6,994 | 5,614 | 6,042 | 7,896 | 11,983 |
| Direct water supply costs (£)[footnote 8] | 46,760 | 48,259 | 51,401 | 47,676 | 47,408 |
Other target areas
Travel – car fleet
| 2025-26 | 2024-25 | 2023-24 | 2022-23 | 2017-18 baseline | |
|---|---|---|---|---|---|
| Percentage of ultra-low emission vehicles | 17.2% | 26.9% | 44.9% | 36.0% | -[footnote 9] |
| Percentage of zero emission vehicles | 82.8% | 61.1% | 20.6% | 15.3% | -[footnote 9] |
Taskforce for Climate-related Financial Disclosures (TCFD)
Principal risk assessment and compliance statement
The agency has assessed climate related risks in line with HM Treasury’s TCFD aligned guidance. Based on the agency’s risk profile, the agency does not consider climate change to be a principal risk. This is because:
-
The majority of climate related exposures affecting the agency’s operations (for example estate and digital resilience) arise through Defra group corporate services.
-
The shared risks are actively managed through Defra’s risk systems, policies and reporting cycles.
-
The response to a potential requirement to deliver emergency schemes is well established operationally.
-
The agency’s own operational climate exposures are managed under the risk strategy, systems and processes and as such are visible to the Audit and Risk Assurance Committee (ARAC).
-
The agency administers schemes that contribute to Defra’s environmental and climate objectives (including Environmental Land Management schemes). While overall risks relating to delivery of environmental outcomes sit with Defra policy leads, delivery performance, including regularity and operational effectiveness may influence the extent to which these schemes contribute to intended environmental outcomes.
Extent of compliance with mandatory TCFD disclosures
As required for bodies not identifying climate as a principal risk, the agency reports against governance, risk management and emission metrics and targets.
| TCFD disclosure requirement | Extent of compliance | Explanation and forward actions |
|---|---|---|
| Governance – board oversight | Partially compliant | Oversight defined via executive team and sub-committees and has also been reported to ARAC. Work underway to integrate scheduled reporting and formal Rural Payments Agency Board (RPA Board) monitoring. |
| Governance – management’s role | Partially compliant | Senior responsible owner and climate responsibilities identified. Further clarity on reporting channels will be implemented in 2026. |
| Risk management – identification and assessment | Partially compliant | Processes aligned to Defra and the agency’s Risk Strategy; the agency will enhance identification tools and embed climate trigger assessments. |
| Risk management – managing risks | Partially compliant | Controls described; work planned to map climate related mitigations to functional risk registers. |
| Risk management – integration | Fully compliant | Climate risks embedded in corporate risk framework and escalation routes. |
| Metrics and targets – emissions | Fully compliant | Scope 1, 2 and relevant Scope 3 reported through Greening Government Commitments processes, methodology improvements ongoing as part of Defra group. |
Governance - RPA Board and committee oversight
Whilst climate related activity is overseen by the agency’s Finance, Assurance and Risk Committee (FARC), a sub-committee of the executive team, strategic risks (including any climate related risks arising from the agency’s operational areas) are reported via the most appropriate sub-committee.
Later in 2026, sustainability considerations will be embedded alongside people, finance and customer as one of the agency’s strategic pillars. As part of this step change:
-
Climate related risks will be included in quarterly reviews to FARC.
-
Annual updates will be provided to the executive team summarising climate related trends and the implications for operational planning.
-
Escalation to Defra group’s risk governance will occur where risks exceed the agency’s agreed tolerance.
Management’s role
The agency’s Business Strategic Management Director serves as the Senior Responsible Officer for climate related risk management.
Operational climate risks (for example disruption to services, workforce impacts, fleet, supply chain) are monitored by functional leads across estates, digital, people and operations. These risks are:
-
Recorded in functional risk registers.
-
Reviewed monthly.
-
Escalated through the corporate risk framework depending on impact and likelihood.
-
Aligned with both the Defra group and the agency’s risk strategy and climate related guidance.
A more detailed internal review of reporting flows will be completed in 2026 to enhance integration of climate considerations across management functions.
Risk management
Processes for identifying and assessing climate related risks
The agency uses both the Defra group and the agency’s Risk Strategy to identify climate related risks. This includes:
-
Horizon scanning for physical risks (for example extreme heat, flooding, storm events) and transition risks (policy, technology, supply chain).
-
Monitoring reliance on Defra corporate services for estate management and information technology resilience, where most climate exposure sits.
-
Assessing relevance using the corporate risk scoring framework (likelihood × impact).
-
Determining whether climate risk drivers influence existing operational risks.
Processes for managing climate related risks
Where climate related risks arise within the agency’s operational areas (for example operational delivery, staff wellbeing during heatwaves, regional service disruption), risks are:
-
Mitigated through business continuity and adaptation controls (remote working, flexible operations).
-
Managed by the relevant functional lead.
-
Reviewed monthly and assessed using standard risk tolerances.
-
Escalated to Defra group where impacts relate to shared assets (estate and information technology).
Defra manages large scale climate related risks linked to buildings, energy systems and infrastructure. The agency aligns its controls to Defra’s group policies and resilience planning.
Integration into the agency’s overall risk framework
Climate related risks are integrated into the existing corporate risk management cycle. This includes:
-
Recording risks in functional and corporate registers.
-
Regular reviews by risk owners.
-
Annual executive team review of climate related impacts.
-
Periodic review by the RPA Board of all elements of strategic risk.
-
Escalation into Defra group risk reporting where necessary.
Metrics and targets
The agency’s greenhouse gas emissions are reported through the Greening Government Commitments (GGC), including:
-
Scope 1: agency direct fuel combustion and fleet emissions.
-
Scope 2: purchased electricity.
-
Scope 3 (relevant categories): business travel and transmission / distribution emissions.
These metrics are compiled quarterly and published annually in this report. They follow Defra and GGC reporting methodologies and will evolve over time as Defra develops more granular, building-specific consumption and emissions allocations.
The agency’s emissions contribute to Defra group’s net zero and decarbonisation plans, which provide the overarching targets under which the agency operates.
The agency’s figures form part of the Defra group’s decarbonisation work to deliver on the GGC.
Oliver Munn
Chief Executive and Accounting Officer
7 July 2026
Accountability report
Corporate governance report
This section describes the governance, risk management and internal control arrangements for the Rural Payments Agency (the agency) and how the agency’s processes have evolved in response to a changing business environment and set of risks over 2025-26.
Directors’ report
Governance framework
The Department for Environment, Food and Rural Affairs (Defra) Secretary of State has overall responsibility for the agency and is accountable to Parliament for all matters concerning the agency. Ministerial responsibility for the agency has been assigned to the Minister of State.
Tamara Finkelstein, Defra’s Permanent Secretary, served as the Principal Accounting Officer and principal adviser to the Secretary of State on matters affecting Defra, including resource allocation and ensuring high standards of financial management. She stepped down from the role in June 2025, after which David Hill served as Interim Permanent Secretary. Paul Kissack was subsequently appointed and took up the post on 13 October 2025.
At the start of 2025-26, Paul Caldwell was the agency’s Chief Executive Officer (CEO) and designated Accounting Officer. He stepped down on 11 June 2025 and formally left the agency on 31 July 2025. Neil Hornby joined the agency on 2 June 2025, taking over as Interim Chief Executive Officer and Accounting Officer after Paul Caldwell stepped down, until Oliver Munn joined the agency as Chief Executive Officer and Accounting Officer on 12 January 2026. Neil Hornby formally left the agency on 31 January 2026. Overlapping dates reflect planned handover and transition arrangements ensured via formal written letters and by multiple direct meetings and discussions.
The Accounting Officer must be satisfied that the agency has adequate risk management, financial systems, and procedures in place to support the efficient and economical conduct of its business, safeguard financial propriety and regularity, ensure business continuity and safeguard the agency’s reputation. The CEO is line managed by the Defra Director General for Food, Farming and Biosecurity, Emily Miles.
Significant business interests
Details of company directorships and other significant interests held by directors of the agency, which may conflict with their management responsibilities, are disclosed in the related party transactions note to the financial statements, Note 15.
The Rural Payments Agency Board (RPA Board)
Chaired by a non-executive director, the RPA Board is responsible for strategic oversight of the agency’s performance, advising and challenging the CEO, and escalating issues to Defra and ministers as appropriate. It provides leadership in the delivery of statutory corporate and business responsibilities, ensures that risks are effectively identified and managed, encourages improvements in performance across the agency and ensures effective governance and control is in place for the agency.
Key business at RPA Board meetings in 2025-26 included:
-
Scrutiny of scheme delivery and performance against agreed targets.
-
Assessment and management of the agency’s financial position.
-
Assurance on health and safety, including compliance with statutory responsibilities, incident reporting and actions taken to mitigate risk and support staff wellbeing.
-
Oversight of people and capability, including workforce planning, skills and organisational resilience.
-
Review of strategic risk and risk appetite.
The Audit and Risk Assurance Committee (ARAC)
Chaired by a non-executive director, who is also a member of the RPA Board, ARAC’s purpose is to provide independent support and advice to the Accounting Officer and the RPA Board on:
-
Effectiveness of governance, risk management and internal control arrangements.
-
Integrity of financial reporting.
-
Effectiveness of assurance arrangements (internal and external).
-
Management of audit and risk within the agency.
-
Adequacy of arrangements to prevent and detect fraud, bribery and error.
The agency’s ARAC Chair is also a member of Defra’s Audit and Risk Assurance Committee.
Key business at ARAC meetings in 2025-26 included:
-
Qualified regulatory opinion: continued scrutiny of the annual report and accounts’ qualification arising from irregularity in agricultural environmental grant schemes.
-
Risk management: reset of RPA Board and committee risk roles, with development of a strategic risk register and review of risk and escalation frameworks.
-
Assurance and reporting: strengthening of year end assurance arrangements and improved coherence and leadership of the annual report and accounts.
-
Systems oversight: risk-based deep dives into critical IT systems.
The RPA Board and ARAC’s non-executive members are recruited and paid in line with public appointments guidance set by the Cabinet Office.
Membership and attendance
| Name | Title | ARAC attendee | Meetings attended | RPA Board attendee | Meetings attended |
|---|---|---|---|---|---|
| Adrian Belton | Non-Executive Board Chair (from 2 June 2025) | - | - | Chair | 4 of 4 |
| Oliver Munn[footnote 10] | Chief Executive Officer | - | - | Member | 2 of 2 |
| Paul Caldwell[footnote 10] | Chief Executive Officer | - | - | Member | 0 of 0 |
| Neil Hornby[footnote 10] | Interim Chief Executive Officer | - | - | Member | 2 of 2 |
| Mark Ashenden | Business Strategic Management Director | - | - | Member | 4 of 4 |
| Dan Gilbert | RPA Finance Director | - | - | Member | 4 of 4 |
| Sophia Haughton | RPA HR Director | - | - | Member | 3 of 4 |
| Mike Rowe | Defra Farming Director (from 16 June 2025) | - | - | Member | 4 of 4 |
| Paul Dillon-Robinson | Non-Executive ARAC Chair (left 31 May 2025) | Chair | 1 of 1 | Member | 0 of 0 |
| Mark Suthern | Non-Executive Director (left 31 May 2025) | Member | 1 of 1 | Member | 0 of 0 |
| Tim Breitmeyer | Non-Executive Director (left 31 May 2025) | - | - | Member | 0 of 0 |
| Julia Grant | Non-Executive Director ARAC member (left 30 September 2025) | Member | 2 of 2 | - | - |
| Alison White | Non-Executive Director ARAC Chair (from 1 February 2026) Non-Executive Director Interim ARAC Chair (from 15 October 2025) | Chair | 2 of 2 | Member | 3 of 3 |
| David Lyall[footnote 11] | Interim Non-Executive Director | Member | 2 of 2 | Member | 2 of 2 |
| Mark Tufnell[footnote 11] | Interim Non-Executive Director | Member | 2 of 2 | Member | 2 of 2 |
| Peter Crewe | Grants Functional Standard Director (left 31 October 2025) | - | - | Member | 0 of 0 |
| Marie Hardeman | Customer Director (left 14 November 2025) | - | - | Member | 1 of 1 |
| Janet Hughes | Defra Director, Farming and Countryside Programme (left 8 June 2025) | - | - | Member | 0 of 0 |
| David Brooks | Non-Executive Director (from 1 March 2026) | Member | 0 of 0 | Member | 1 of 1 |
| Sarah Calcutt | Non-Executive Director (from 1 March 2026) | - | - | Member | 1 of 1 |
| Paul Savage | Non-Executive Director (from 1 March 2026) | Member | 0 of 0 | Member | 1 of 1 |
| Stephen Briggs | Non-Executive Director (from 1 March 2026) | - | - | Member | 1 of 1 |
Relationship with Defra
Defra’s Executive Committee (ExCo) provides effective leadership and collective oversight of the strategic direction of the Defra group. Decisions which affect more than one organisation, or which set a precedent for the future, are ultimately a matter for ExCo. ExCo is supported by a number of sub committees, drawing together Defra directors and the chief executives of relevant delivery bodies, to ensure coherent decision making and oversight across the group.
The agency operates within the governance and accountability framework set out within the Rural Payments Agency Framework Document. The Director General for Food, Farming and Biosecurity acts as Defra’s primary contact and sponsoring Director General for the agency. The Director General provides strategic oversight, acts as the principal source of advice to ministers in relation to the agency, and liaises regularly with the CEO to review performance, delivery against plans and targets, and financial outturn.
Day to day sponsorship has been strengthened and is delivered through Defra’s sponsorship arrangements formalised in 2025-26. The sponsorship team supports effective accountability and assurance, monitors performance and risk, escalates issues where necessary, and ensures that the agency is sighted on relevant policy developments and wider departmental priorities. This approach supports a collaborative relationship between Defra and the agency while maintaining clear lines of accountability.
Through these arrangements, the agency continues to contribute to and support delivery of Defra’s strategic priorities, including the Environmental Improvement Plan and the Farming and Countryside Programme, and to provide capability and expertise to cross Defra programmes and initiatives. The agency remains committed to working closely with Defra and its sponsorship team to deliver outcomes effectively and to adapt as strategic priorities and delivery requirements evolve.
Security, information risk and fraud
Throughout 2025-26 work has continued to support security compliance, with assessments against business continuity and security culture in key business areas.
This has been supplemented by a number of key systems resilience being assessed through GovAssure - the National Cyber Security Centre’s Cyber Assessment Framework. Work has also been undertaken to review critical business services and supporting information technology systems to assess their resilience and put a programme of improvement and testing in place.
Defra group security also managed the 2025-26 Departmental Security Health Check submission, which assessed compliance against the minimum baseline standards for physical and personnel security and incident management. This was a joint submission that covered the Defra group (including the agency). Assurance work will continue into next year to support ongoing compliance against the government functional standard GovS007: Security Mitigation. Work arising out of these activities will continue to be tracked through the regular agency Security Risk Owner meetings and through the existing security governance framework.
Information handling
The agency’s information governance ensures that personal data is processed in conformity with the law and government information management standards. Guided by the Defra Data Protection Officer (DPO), the agency has continued to embed the Information Commissioner’s Office Accountability Framework within its control environment, working collaboratively with the network of Information Asset Owners (IAOs). Progress has been slower than anticipated, reflecting the need to address identified data protection gaps, including undertaking a comprehensive review of data processing activities, data sharing arrangements, ingestion processes and data publication practices.
In response, a revised set of priorities has been established to accelerate progress and ensure these gaps are effectively addressed. Updates on this work have been provided to the agency’s Security Risk Owner (SRO) and the Defra DPO, with an end-of-year report submitted to the agency’s CEO and the Defra ARAC. To support the agency’s SRO and the IAOs, the agency’s Data Protection, Defra group security, Business Continuity, and the Information Rights Team serve as a focal point for the IAOs to obtain guidance on the effective management of information risk within the defined risk tolerance.
When people join the agency, the need for compliant information handling is highlighted in the induction process. This is reinforced during the annual Security and Data Protection on-line course provided by Civil Service Learning. The Security and Data Protection training (which includes a certificate of completion) is a requirement for all agency employees so that they are equipped to demonstrate their competence in personal data processing. In partnership with the office of the DPO, the agency’s data protection practitioners and the Information Rights Team provide more specialised training to the IAOs.
In December 2024, following Government Internal Audit Agency work, a significant weakness was identified in Roles Based Access Controls to the agency’s customer registration system. This reduced the effectiveness of controls over the access to, and editing of, customer data. While no financial loss or misstatement arose, management recognised that the weakness increased exposure to the risk of discrepancies in the agency’s customer data. Corrective actions were implemented during the 2025-26 financial year, with full remediation planned to be achieved in June 2026. Progress is monitored by the ARAC.
Personal data incidents
During 2025-26, a total of 165 personal data breach incidents were reported for investigation in relation to UK General Data Protection Regulation compliance (2024-25: 156). None were deemed to have fulfilled the criteria for reporting to the Information Commissioner’s Office.
Fraud referrals
Fraud referrals are assessed by the agency’s fraud referral team to consider whether a potential fraud has occurred. The agency takes appropriate recovery action on cases if the recommendation is made to recover funds. Most fraud referrals relate to external (beneficiary) fraud. At 31 March 2026, there were no internal fraud referrals outstanding (31 March 2025: 2).
| Fraud referrals | 2025-26 | 2024-25 |
|---|---|---|
| Number of new fraud referrals in year | 294 | 259 |
| Number of fraud referrals closed | 278 | 304 |
| Detected and prevented: | ||
| Detected fraud value | £341,048 | £594,539 |
| Detected number of cases | 27 | 34 |
| Detected fraud recovered value, including from previous years referrals | £176,534 | £284,223 |
| Detected fraud recovered number of cases, including from previous years referrals | 36 | 21 |
| Prevented fraud value | £161,099 | £132,457 |
| Prevented fraud number of cases | 25 | 25 |
| Number of fraud cases outstanding | 113 | 97 |
The table above includes known, detected fraud referral cases only. The agency also acknowledges that some fraud will, by its nature, remain undetected. The agency therefore estimates the level of undetected fraud and error with scheme expenditure. This is disclosed in the Parliamentary accountability and audit report.
Statement of Accounting Officer’s responsibilities
Under the Government Resources and Accounts Act 2000, HM Treasury has directed the Rural Payments Agency (the agency) to prepare for each financial year a statement of accounts in the form and on the basis set out in the Accounts Direction. The accounts are prepared on an accruals basis and must give a true and fair view of the state of affairs of the agency and of its income and expenditure, Statement of Financial Position and cash flows for the financial year.
In preparing the accounts, the Accounting Officer is required to comply with the requirements of the Government Financial Reporting Manual (FReM) and in particular to:
-
observe the Accounts Direction issued by HM Treasury, including the relevant accounting and disclosure requirements, and apply suitable accounting policies on a consistent basis.
-
make judgements and estimates on a reasonable basis.
-
state whether applicable accounting standards as set out in the FReM have been followed, and disclose and explain any material departures in the financial statements.
-
prepare the financial statements on a going concern basis.
-
confirm that the annual report and accounts as a whole is fair, balanced and understandable and take personal responsibility for the annual report and accounts and the judgements required for determining that it is fair, balanced and understandable.
The Permanent Secretary has appointed Oliver Munn, Chief Executive Officer, as Accounting Officer of the agency. The responsibilities of an Accounting Officer, including responsibility for the propriety and regularity of the public finances for which the Accounting Officer is answerable, for keeping proper records and for safeguarding the agency’s assets, are set out in HM Treasury’s Managing Public Money.
As the Accounting Officer, I have taken all the steps that I ought to have taken to make myself aware of any relevant audit information and to establish that the agency’s auditors are aware of that information. So far as I am aware, there is no relevant audit information of which the auditors are unaware.
Governance statement
The Accounting Officer is responsible for maintaining a robust system of internal control that supports the achievement of the agency’s policies, aims and objectives, while safeguarding public funds and agency assets. This is in accordance with the responsibilities assigned in HM Treasury’s Managing Public Money.
Internal controls
Second line assurance over statements made by, or where vacancies existed, in place of, directors has primarily been provided by enabling teams with oversight of the key areas covered in those returns. Where available, this has been supplemented by work undertaken by the agency’s integrated assurance team, alongside independent third line assurance of internal controls provided through audits by the Government Internal Audit Agency.
This has been a challenging year, with organisational change placing some of the agency’s established control and assurance processes under pressure. While there were some gaps in coverage during this period, the agency is satisfied that key risks were appropriately identified and managed, and that the overall control environment remained sufficient. Taken together, this work supports the statements made and provides a reasonable level of assurance that the agency has maintained satisfactory governance, risk management and internal control arrangements.
Further work is planned in 2026-27 to strengthen and stabilise assurance processes to enhance both the level and consistency of assurance that can be provided going forward.
Use of business-critical models
The agency relies on several analytical models to support the delivery of its objectives, including the calculation of scheme payments, estimation of undetected fraud and error, and forecasting of expenditure. In line with cross‑government guidance on model assurance, the agency has identified those models which are considered business critical. This is defined as models whose outputs are material to financial reporting, regulatory compliance, or operational delivery and where error could lead to significant financial, legal or reputational impact.
Business‑critical models are subject to enhanced governance arrangements, including clearly defined ownership, documentation of methodology and assumptions, periodic review, and proportionate independent validation.
The agency has identified the following models as business critical:
| Model | Purpose | Why critical | Governance / assurance |
|---|---|---|---|
| Fraud and error estimation model | Estimates the level of undetected fraud and error in scheme expenditure based on statistical sampling and extrapolation techniques. | Underpins regulatory reporting and assurance over the regularity of expenditure; outputs are subject to audit scrutiny and may influence qualification decisions. | Subject to documented statistical methodology, internal expert review, and periodic independent validation; key assumptions and confidence levels are reviewed annually. |
| Forecasting and budgeting models | Forecast scheme uptake, expenditure and cash requirements across financial years. | Inform budget management, Parliamentary reporting and financial planning; inaccuracies could lead to misallocation of resources or budgetary pressures. | Subject to periodic review, challenge and reconciliation to outturn; key assumptions are updated regularly and tested against emerging data. |
The agency operates a proportionate model assurance framework. Models assessed as lower risk or with less direct impact on financial reporting are subject to standard controls but are not classified as business critical.
Risk overview
During 2025-26, the agency continued to operate in a complex risk environment, driven by the transition from legacy subsidy schemes to more complex agricultural environment schemes. This has increased inherent delivery risk and contributed directly to the level of scheme irregularity. This remains the most significant risk facing the agency and has continued to result in a qualified regulatory audit opinion, in relation to estimated irregular grant expenditure, underscoring the importance of robust controls and effective assurance over the administration of public funds.
Alongside this, the agency faced a set of interrelated challenges in sustaining operational performance at scale, improving customer experience in a more complex delivery environment, maintaining effective financial control over demand led schemes, whilst at the same time striving to become more efficient and productive at pace. Governance and risk management arrangements were also under pressure during the year, reflecting significant leadership changes and periods where boards and committees were not operating at full strength.
In response, the agency undertook a fundamental review of its approach to strategic risk. This work moved beyond incremental improvement to provide a clearer and more focused articulation of the risks aligned to delivery outcomes and the protection of public funds.
The strategic risks now encompass customer experience; financial stewardship; operational delivery; climate and environmental disruption; service continuity; digital resilience and cyber security; governance, legislative compliance and assurance; people welfare, health and safety and workforce legislative compliance; data, insight and safe use of technology; and workforce strategy. These risks are owned at executive level, subject to regular review and supported by defined mitigations and assurance.
Following the Hancock and Corry reviews, and guided by the RPA Board, a new risk appetite framework was agreed during the year, providing clearer parameters for decision-making and prioritisation. Work is underway to embed the framework consistently across strategic and operational risk management.
Fraud risk management
During 2025-26, the agency continued to engage with the Public Sector Fraud Authority and cross‑government counter‑fraud forums, supporting the sharing of good practice, strengthening its counter‑fraud arrangements and improving its understanding of wider fraud risks, including opportunities to develop more effective approaches to prevention, detection and response.
An independently assessed review against the Counter Fraud Functional Standard confirmed good overall alignment, with a small number of targeted areas identified for further maturity. Action is underway to address these areas.
Fraud risk assessments remain in place for existing schemes and are embedded in the development of new schemes. The principal fraud risks continue to relate to irregularity in scheme expenditure, reflecting a combination of fraud and error.
Activity during the year focused on improving understanding of the drivers of irregularity, including how customers can be better supported to navigate complex schemes, and on strengthening mitigating controls.
The agency recognises the risks associated with ineffective fraud and error mitigation, including the potential impact on the regularity, effectiveness and value for money of grant expenditure.
Effectiveness of risk management statement
The executive team is responsible for maintaining effective risk management and internal control arrangements.
During 2025-26, the agency operated risk management processes aligned to HM Treasury’s Orange Book, supporting the identification, assessment and escalation of risks at appropriate levels across the organisation.
However, as set out in the risk overview, leadership changes and periods where boards and committees were not operating at full strength meant these arrangements did not operate consistently throughout the year.
Supported by challenge and direction from the Audit and Risk Assurance Committee (ARAC), the agency has undertaken a fundamental redesign and relaunch of its risk management framework which is now being embedded.
The agency also continued to develop its approach to integrated assurance, working with the Government Internal Audit Agency to better coordinate assurance activity and strengthen oversight of key risks.
Overall, the executive team considers that risk management and internal control arrangements operated with sufficient effectiveness during the year and that further embedding and focus will be needed in 2026-27.
Effectiveness of whistleblowing arrangements
During the reporting period, 5 approaches were made to nominated officers and recorded on the corporate tracker. 1 of these met the criteria for investigation under the Raising a Concern (Whistleblowing) Policy. This formed part of a wider, collective concern relating to the international remote working policy. The matter resulted in additional support to strengthen the implementation of existing processes; no changes to the policy itself were required. This case is reflected within the agency’s parent department, the Department for Environment, Food and Rural Affairs, consolidated whistleblowing reporting.
The remaining 4 approaches did not constitute whistleblowing as defined by public interest disclosure legislation. These were informal approaches concerning matters of inclusion, wellbeing, management style, and record keeping practices. No allegations of fraud were reported to nominated officers during the year.
The organisation continues to monitor the effectiveness and accessibility of its raising concerns arrangements. While results from the 2025 People Survey indicate high levels of confidence among staff in knowing how to raise concerns, “Safe to Challenge” emerged as an area of focus, suggesting that psychological safety remains an important consideration. In addition, the nature of approaches received highlights a need to further clarify the purpose and scope of the whistleblowing and speak up processes, particularly in distinguishing them from routes intended to address cultural or management issues.
Planned activity in 2026-27 will focus on strengthening understanding of the appropriate use of these processes and reinforcing a culture in which staff feel confident and supported to raise concerns at the earliest opportunity.
Internal audit opinion
The agency’s Head of Internal Audit provides an annual opinion based on the internal audit work completed during the year, in line with the audit plan agreed with the executive team and with the agency’s ARAC. All changes to the plan during the year were evaluated against the agency’s key risks to ensure continued coverage to inform her opinion. Her ‘Moderate’ opinion for 2025-26 reflects that whilst there are areas that could be improved, the agency’s frameworks for governance, risk management and control are largely operating effectively in delivering the agency’s objectives and in administering the payment schemes for which it is responsible. This was despite a prolonged period of change at all levels in the agency, resulting in executive and non-executive changes, internal restructuring and changes to the governance framework.
Of the 15 audit activities delivered, 4 were either advisory or evaluations of overlapping second-line assurance work and did not carry an assurance opinion. Of the remaining 11, 1 had a repeated limited assurance opinion, relating to customer registrations and permissions. This reflected delays in implementing management actions from 2024-25, partly due to actions changing ownership during restructuring, there is now a suite of replacement actions to address the issues.
3 audits provided substantial assurance over Countryside Stewardship forecasting processes, management of mandatory training, and the role of the Data and Insight business area in decision making.
Compliance with governance codes
An informal review was carried out by the agency’s governance team against the National Audit Office ‘Corporate Governance in Central Government Departments: Code of Good Practice 2011 Compliance Checklist’ indicated that the agency complies with the principles for an agency of its size, status, and legal framework.
Effectiveness of governance arrangements
During 2025-26, periods in which the RPA Board and ARAC were inquorate, together with changes in senior leadership, reduced the continuity and effectiveness of the agency’s governance oversight. To help mitigate this, interim non-executive director arrangements were put in place during the year, alongside additional measures to support essential decision-making, risk management and accountability while longer-term appointments were progressed.
Framework document
Rural Payments Agency’s framework document, sets out the broad framework within which the agency operates and is available on the GOV.UK website.
Effectiveness of Rural Payments Agency Board (RPA Board) and committee performance
The challenges set out in the Effectiveness of governance arrangements section above meant that the effectiveness of the RPA Board and ARAC was reduced during the year.
Executive directors maintained regular engagement with the RPA Board Chair to support oversight and discussion of RPA Board effectiveness. The RPA Board and the ARAC each undertook informal effectiveness reviews, which indicated that the quality of information provided was generally sufficient to enable effective scrutiny, challenge and advice. However, the continuity of formal oversight was affected at points during the year.
The RPA Board and ARAC reached their full complement on 1 March 2026 following the successful recruitment and appointment of additional non-executive directors.
Change of Accounting Officer and assurance
Upon joining the agency as Chief Executive and Accounting Officer on 12 January 2026, I undertook a structured handover and reviewed key documents, including internal audit reports, risk registers and RPA Board minutes. I also engaged with senior leaders and ARAC to understand the operation and effectiveness of governance, risk and internal control arrangements across the year.
On this basis, I am satisfied that, while these arrangements were not fully effective at all points during the year, sufficient arrangements were maintained overall to support accountability, decision-making and control across the financial year.
Remuneration and staff report
The remuneration and staff report provides information on people in the Rural Payments Agency (the agency) and sets out the entity’s remuneration policy for directors, reports on how that policy has been implemented and sets out the amounts awarded to directors.
Remuneration report
The framework for remunerating the Chief Executive Officer (CEO), as for all Senior Civil Servants (SCS), is set following independent advice from the Senior Salaries Review Body. Further information is available via this link Guidance on the Senior Civil Service Pay Award 2025/26 (HTML) - GOV.UK. The Cabinet Office advises the agency’s parent department, the Department for Environment, Food and Rural Affairs (Defra), of the government’s response to the Senior Salaries Review Body’s recommendations and produces guidance for departments to follow. Defra develops its SCS pay strategy within this Cabinet Office framework, ensuring that the overall pay awards are within the cost ceiling allowed.
Members of the SCS are eligible to be considered for individual levels of bonus as Non-Consolidated Performance Related Pay (NCPRP). NCPRP values, informed by each individual’s appraisal grade, based on their performance assessed relative to all others in their peer group, are paid within Cabinet Office guidelines. The table of salary and non-cash benefits shown in this report includes NCPRP paid.
Service contracts
The Constitutional Reform and Governance Act 2010 requires Civil Service appointments to be made on merit on the basis of fair and open competition. The Recruitment Principles published by the Civil Service Commission specify the circumstances when appointments may be made otherwise. Further information about the work of the Civil Service Commission can be found at https://www.civilservicecommission.org.uk/.
Unless otherwise stated below, the officials covered by this report hold appointments which are open-ended.
The CEO and executive directors are permanent civil servants required to give 3 months’ notice under the terms of their contracts. Non-executive directors are appointed on fixed term contracts with a notice period of 1 month.
The employment of the CEO and executive directors may be terminated in accordance with normal civil service procedures. Early termination, other than for misconduct, would result in the individual receiving compensation as set out in the Civil Service Compensation Scheme.
Compensation for loss of office (audited)
During the year 3 SCS, 2 of which were executive directors, received compensation under a Voluntary Exit Scheme (2024-25: none). The executive directors are shown in the remuneration table below. These departure costs have been paid in accordance with the provisions of the Civil Service Compensation Scheme (CSCS), a statutory scheme made under the Superannuation Act 1972. Compensation for leave not taken, where appropriate, is included within the salary figures in the remuneration table.
Salary
‘Salary’ includes gross salary; overtime; reserved rights to London weighting or London allowances; recruitment and retention allowances; private office allowances and any other allowance to the extent that it is subject to UK taxation. This report is based on accrued payments made by the agency and the agency’s parent department, Defra, where individuals are employed by Defra.
Benefits in kind (audited)
The monetary value of benefits in kind covers any benefits provided by the agency and treated by HM Revenue and Customs as a taxable emolument permitted by the Civil Service Management Code. In 2025-26, no director (2024-25: none) received a benefit in kind.
Bonuses (audited)
Bonuses are based on performance levels attained and are made as part of the appraisal process. The bonuses reported in 2025-26 relate to performance in 2024-25 and the comparative bonuses reported for 2024-25 relate to the performance in 2023-24. This is because the appraisal process does not allow sufficient time to accrue for individual bonuses relating to performance in the reporting year’s financial statements.
Fair pay disclosure (audited)
Reporting bodies are required to disclose the percentage change from the previous financial year for both salary and performance pay in respect of the highest paid director and the average percentage change in respect of employees of the agency taken as a whole. Only directors and employees paid directly by the agency are included in the tables below.
The non-executive directors are excluded from this disclosure, their work is part-time by nature and their inclusion would have a distorting impact on the calculation.
Mean employee remuneration includes agency staff, contractors, and directors.
In 2025-26, 9 contractors (2024-25: 2) and no permanent employees (2024-25: none) received remuneration that, on an annualised basis, would be higher than the highest paid director. The annualisation of day rates for contractors means it does not equate to the number of contractors whose actual remuneration received in-year exceeded the highest paid director.
| 2025-26 | Salary | Bonus[footnote 12] | Total |
|---|---|---|---|
| Annualised band of highest paid director remuneration | £125k-£130k | - | £125k-£130k |
| Mean employee remuneration | £35,008 | £344 | £35,352 |
| 2024-25 | Salary | Bonus | Total |
|---|---|---|---|
| Annualised band of highest paid director remuneration | £120k-£125k | £5k-£10k | £130k-£135k |
| Mean employee remuneration | £34,448 | £312 | £34,761 |
| Percentage change from previous year | Salary | Bonus[footnote 12] | Total |
|---|---|---|---|
| Highest paid director (based on midpoint of band) | 4% | (100%) | (4%) |
| Mean employee remuneration | 2% | 10% | 2% |
Total remuneration as analysed below, includes salary, non-consolidated performance related pay and benefits in kind. It does not include severance payments, employer pension contributions and the cash equivalent transfer value of pensions.
| 2025-26 | 25th percentile remuneration | Median total remuneration | 75th percentile remuneration |
|---|---|---|---|
| Highest paid director remuneration (mid-point of pay band) | - | £127,500 | - |
| All employees (excluding highest paid director) total pay and benefits | £26,225 | £30,012 | £35,322 |
| All employees (excluding highest paid director) salary component only | £26,025 | £29,768 | £35,020 |
| Total pay ratio | 4.9 | 4.3 | 3.6 |
| 2024-25 | 25th percentile remuneration | Median total remuneration | 75th percentile remuneration |
|---|---|---|---|
| Highest paid director remuneration (mid-point of pay band) | - | £132,500 | - |
| All employees (excluding highest paid director) total pay and benefits | £25,345 | £29,075 | £34,169 |
| All employees (excluding highest paid director) salary component only | £25,070 | £28,929 | £33,894 |
| Total pay ratio | 5.2 | 4.6 | 3.9 |
The median remuneration, 25th percentile pay remuneration and the 75th percentile pay remuneration is based on annualised, full-time equivalent remuneration at the end of the financial year.
The median pay ratio has decreased compared to 2024-25. This reduction reflects a combination of a lower banded remuneration for the highest‑paid director alongside increases in workforce remuneration across the 25th percentile, median and 75th percentile, driven by the 2025-26 pay award. In line with the public sector pay remit guidance, average pay awards of up to 3.25% were implemented from 1 July 2025.
The banded total remuneration for employees in the agency ranged from £30,001-£35,000 to £125,001-£130,000 (2024-25: £25,001-£30,000 to £130,001-£135,000).
Remuneration and pension entitlements (audited)
Remuneration of non-executive directors
| Name and title | Remuneration 2025-26 £000 | Remuneration 2024-25 £000 | 75th percentile remuneration |
|---|---|---|---|
| Adrian Belton Non-Executive Director, Chair (from 2 June 2025) | 5-10 (10-15 FYE[footnote 13]) | - | - |
| Alison White Audit and Risk Assurance Committee Chair, Non-Executive Director (from 1 February 2026, interim from 15 October 2025) | 5-10 (10-15 FYE[footnote 13]) | - | £34,169 |
| Paul Savage Non-Executive Director (from 1 March 2026) | 0-5 (10-15 FYE[footnote 13]) | - | £33,894 |
| Sarah Calcutt Non-Executive Director (from 1 March 2026) | 0-5 (10-15 FYE[footnote 13]) | - | 3.9 |
| Stephen Briggs Non-Executive Director (from 1 March 2026) | 0-5 (10-15 FYE[footnote 13]) | - | |
| David Brooks Non-Executive Director (from 1 March 2026) | 0-5 (10-15 FYE[footnote 13]) | - | |
| David Lyall[footnote 14] Interim Non-Executive Director (from 15 October 2025 until 14 February 2026) | 0-5 (10-15 FYE[footnote 13]) | - | |
| Mark Tufnell[footnote 14] Interim Non-Executive Director (from 15 October 2025 until 14 February 2026) | 0-5 (10-15 FYE[footnote 13]) | - | |
| Tim Breitmeyer Non-Executive Director (until 31 May 2025) | 0-5 (5-10 FYE[footnote 13]) | 5-10 | |
| Paul Dillon-Robinson Non-Executive Director (until 31 May 2025) | 0-5 (10-15 FYE[footnote 13]) | 10-15 | |
| Julia Grant Non-Executive Director (until 30 September 2025) | 0-5 (0-5 FYE[footnote 13]) | 0-5 | |
| Mark Suthern Non-Executive Director (until 31 May 2025) | 0-5 (5-10 FYE[footnote 13]) | 5-10 | |
| Elizabeth Passey Non-Executive Director (until 30 June 2024) | - | 0-5 (5-10 FYE[footnote 13]) |
Remuneration of Rural Payments Agency Board members 2025-26
Neil Hornby was Interim Chief Executive Officer from 2 June 2025 until 31 January 2026. He returned to his post as Chief Executive Officer of the Centre for Environment, Fisheries and Aquaculture Science (CEFAS) when his Interim Chief Executive Officer role at the agency ended. Neil Hornby remained on CEFAS payroll during his interim appointment, with no charge to the agency. Please view CEFAS annual report and accounts for his remuneration disclosures.
| Name and title | Salary £000 | Bonus payments[footnote 17] £000 | Benefits in kind (nearest £100) | Compensation[footnote 19] £000 | Pension benefits[footnote 18] £000 | Total £000 |
|---|---|---|---|---|---|---|
| Mark Ashenden Business Strategic Management Director | 80-85 | - | - | - | 15 | 95-100 |
| Paul Caldwell Chief Executive Officer (until 31 July 2025) | 40-45 (125-130 FYE[footnote 15]) | - | - | 90-95 | 5 | 140-145 |
| Oliver Munn Chief Executive Officer (from 12 January 2026) | 25-30 (125-130 FYE[footnote 15]) | - | - | - | 12 | 40-45 |
| Peter Crewe Grants Functional Standard Director (until 31 October 2025) | 50-55 (85-90 FYE[footnote 15]) | - | - | 90-95 | 17 | 160-165 |
| Dan Gilbert[footnote 16] RPA Finance Director | 80-85 | 0-5 | - | - | 72 | 155-160 |
| Marie Hardeman Customer Director (until 14 November 2025) | 55-60 (90-95 FYE[footnote 15]) | - | - | - | 22 | 75-80 |
| Sophia Haughton[footnote 16] RPA HR Director | 85-90 | 0-5 | - | - | 34 | 120-125 |
| Janet Hughes[footnote 16] Defra Director, Farming and Countryside Programme (until 8 June 2025) | 25-30 (140-145 FYE[footnote 15]) | 5-10 | - | - | 12 | 40-45 |
| Mike Rowe[footnote 16] Defra Farming Director (from 16 June 2025) | 85-90 (110-115 FYE[footnote 15]) | 10-15 | - | - | 16 | 115-120 |
Remuneration of Rural Payments Agency Board members 2024-25
| Name and title | Salary £000 | Bonus payments[footnote 22] £000 | Benefits in kind (nearest £100) | Pension benefit[footnote 23] £000 | Total £000 |
|---|---|---|---|---|---|
| Mark Ashenden Business Strategic Management Director (from 15 April 2024) | 75-80 (80-85 FYE[footnote 20]) | - | - | 19 | 95-100 |
| Paul Caldwell Chief Executive Officer | 120-125 | 5-10 | - | 90 | 220-225 |
| Peter Crewe Grants Functional Standard Director | 80-85 | - | - | 62 | 145-150 |
| Dan Gilbert[footnote 21] RPA Finance Director (from 9 July 2024) | 55-60 (80-85 FYE[footnote 20]) | - | - | 27 | 85-90 |
| Marie Hardeman Customer Director | 85-90 | - | - | 34 | 120-125 |
| Sophia Haughton[footnote 21] RPA HR Director | 80-85 | - | - | 32 | 110-115 |
| Janet Hughes[footnote 21] Defra Director, Farming and Countryside Programme | 135-140 | 0-5 | - | 78 | 215-220 |
| Jessie Peramal[footnote 21] Finance Director and Departmental Group Functional Lead for Grants (until 8 July 2024) | 25-30 (100-105 FYE[footnote 20]) | - | - | - | 25-30 |
Pension benefits (audited) information
Non-executive directors are not entitled to a pension so are not included within the following table.
| Name and title | Accrued pension at pension age at 31 March 2026 and related lump sum £000 | Real increase in pension and related lump sum at pension age £000 | CETV at 31 March 2026 £000 | CETV at 31 March 2025 £000 | Real increase in CETV £000 | Employer contribution to partnership pension account nearest £100 |
|---|---|---|---|---|---|---|
| Mark Ashenden Business Strategic Management Director | 45-50 plus a lump sum of 25-30 | 0-2.5 plus a lump sum of 0 | 934 | 876[footnote 24] | 5 | - |
| Paul Caldwell Chief Executive Officer (until 31 July 2025) | 65-70 plus a lump sum of 170-175 | 0-2.5 plus a lump sum of 0 | 1,625 | 1,607 | 3 | - |
| Oliver Munn Chief Executive Officer (from 12 January 2026) | 0-5 | 0–2.5 | 8 | - | 6 | - |
| Peter Crewe Grants Functional Standard Director (until 31 October 2025) | 45-50 plus a lump sum of 120-125 | 0-2.5 plus a lump sum of 0 | 1,090 | 1,074 | 14 | - |
| Dan Gilbert RPA Finance Director | 30-35 | 2.5-5 | 557 | 475[footnote 24] | 52 | - |
| Marie Hardeman Customer Director (until 14 November 2025) | 5-10 | 0–2.5 | 68 | 50 | 12 | - |
| Sophia Haughton RPA HR Director | 5-10 | 0-2.5 | 102 | 76 | 17 | - |
| Janet Hughes Defra Director, Farming and Countryside Programme (until 8 June 2025) | 20-25 | 0-2.5 | 319 | 307 | 8 | - |
| Mike Rowe Defra Farming Director (from 16 June 2025) | 50-55 | 0-2.5 | 947 | - | 4 | - |
Accrued pension and lump sum at 31 March 2026 discloses the pension that the individual would receive if 31 March 2026 were their last day in service. The pension and lump sum (if applicable to dual members with Classic or Classic Plus linked benefits) includes any benefits that have accrued from the individual buying added years, added pension or transferring in benefits from another scheme.
Cash Equivalent Transfer Value (CETV) is the capital value of the pension and is worked out using guidance provided by the scheme actuary. It is an assessment of what it costs the scheme to provide these pension benefits.
Real increase in CETV reflects the increase in CETV that is funded by the employer. It does not include the increase in accrued pension due to inflation or contributions paid by the employee (including the value of any benefits transferred from another pension scheme or arrangement).
Accrued pension benefits included in the table above for any individual affected by the Public Service Pensions Remedy have been calculated based on their inclusion in the legacy scheme for the period between 1 April 2015 and 31 March 2022, following the McCloud judgment. The Public Service Pensions Remedy applies to individuals that were members, or eligible to be members, of a public service pension scheme on 31 March 2012 and were members of a public service pension scheme between 1 April 2015 and 31 March 2022. The basis for the calculation reflects the legal position that impacted members have been rolled back into the relevant legacy scheme for the remedy period and that this will apply unless the member actively exercises their entitlement on retirement to decide instead to receive benefits calculated under the terms of the Alpha scheme for the period from 1 April 2015 to 31 March 2022.
Civil Service pensions
Pension benefits are provided through the Civil Service pension arrangements. Before 1 April 2015, the only scheme was the Principal Civil Service Pension Scheme (PCSPS), which is divided into a few different sections – Classic, Premium, and Classic Plus provide benefits on a final salary basis, whilst Nuvos provides benefits on a career average basis. From 1 April 2015 a new pension scheme for civil servants was introduced – the Civil Servants and Others Pension Scheme or Alpha, which provides benefits on a career average basis. All newly appointed civil servants, and the majority of those already in service, are in Alpha.
The PCSPS and Alpha are unfunded statutory schemes. Employees and employers make contributions (employee contributions range between 4.6% and 8.05%, depending on salary). The balance of the cost of benefits in payment is met by monies voted by Parliament each year. Pensions in payment are increased annually in line with the Pensions Increase legislation. Instead of the defined benefit arrangements, employees may opt for a defined contribution pension with an employer contribution, the partnership pension account.
In Alpha, pension builds up at a rate of 2.32% of pensionable earnings each year, and the total amount accrued is adjusted annually in line with a rate set by HM Treasury. Members may opt to give up (commute) pension for a lump sum up to the limits set by the Finance Act 2004. All members who switched to Alpha from the PCSPS had their PCSPS benefits ‘banked’, with those with earlier benefits in 1 of the final salary sections of the PCSPS having those benefits based on their final salary when they leave Alpha.
The accrued pensions shown in this report are the pension the member is entitled to receive when they reach normal pension age, or immediately on ceasing to be an active member of the scheme if they are already at or over normal pension age. Normal pension age is 60 for members of Classic, Premium, and Classic Plus, 65 for members of Nuvos, and the higher of 65 or State Pension Age for members of Alpha. The pension figures in this report show pension earned in PCSPS or Alpha – as appropriate. Where a member has benefits in both the PCSPS and Alpha, the figures show the combined value of their benefits in the 2 schemes but note that the constituent parts of that pension may be payable from different ages.
When the government introduced new public service pension schemes in 2015, there were transitional arrangements which treated existing scheme members differently based on their age. Older members of the PCSPS remained in that scheme, rather than moving to Alpha. In 2018, the Court of Appeal found that the transitional arrangements in the public service pension schemes unlawfully discriminated against younger members.
As a result, steps are being taken to remedy those 2015 reforms, making the pension scheme provisions fair to all members. The public service pensions remedy is made up of 2 parts. The first part closed the PCSPS on 31 March 2022, with all active members becoming members of Alpha from 1 April 2022. The second part removes the age discrimination for the remedy period, between 1 April 2015 and 31 March 2022, by moving the membership of eligible members during this period back into the PCSPS on 1 October 2023. This is known as “rollback”.
For members who are in scope of the public service pension remedy, the calculation of their benefits for the purpose of calculating their CETV and their single total figure of remuneration, as of 31 March 2025 and 31 March 2026, reflects the fact that membership between 1 April 2015 and 31 March 2022 has been rolled back into the PCSPS. Although members will in due course get an option to decide whether that period should count towards PCSPS or Alpha benefits, the figures show the rolled back position i.e., PCSPS benefits for that period.
The partnership pension account is an occupational defined contribution pension arrangement which is part of the Legal & General Mastertrust. The employer makes a basic contribution of between 8% and 14.75% (depending on the age of the member). The employee does not have to contribute but, where they do make contributions, the employer will match these up to a limit of 3% of pensionable salary (in addition to the employer’s basic contribution). Employers also contribute a further 0.5% of pensionable salary to cover the cost of centrally provided risk benefit cover (death in service and ill health retirement).
Further details about the Civil Service pension scheme arrangements can be found on the Civil Service website.
CETV
A CETV is the actuarially assessed capitalised value of the pension scheme benefits accrued by a member at a particular point in time. The benefits valued are the member’s accrued benefits and any contingent spouse’s pension payable from the scheme. A CETV is a payment made by a pension scheme or arrangement to secure pension benefits in another pension scheme or arrangement when the member leaves a scheme and chooses to transfer the pension benefits, they have accrued in their former scheme. The pension figures shown relate to the benefits that the individual has accrued as a consequence of their total membership of the pension scheme, not just their service in a senior capacity to which disclosure applies.
The figures include the value of any pension benefit in another scheme or arrangement which the member has transferred to the Civil Service pension arrangements. They also include any additional pension benefit accrued to the member as a result of their buying additional pension benefits at their own cost.
CETVs are calculated in accordance with The Occupational Pension Schemes (Transfer Values) (Amendment) Regulations 2008 and do not take account of any actual or potential reduction to benefits resulting from Lifetime Allowance Tax which may be due when pension benefits are taken.
Real increase in CETV
This reflects the increase in CETV that is funded by the employer. It does not include the increase in accrued pension due to inflation and contributions paid by the employee (including the value of any benefits transferred from another pension scheme or arrangement) and uses common market valuation factors for the start and end of the period.
Staff report
Total staff expenditure are disclosed in Note 2 of the financial statements.
Senior staff by pay-band
The table below provides the number of Senior Civil Servants within the agency by pay-band. The table does not include the directors who are employees of the agency’s parent department, Defra.
| Senior Civil Servants by pay-band | 31 March 2026 | 31 March 2025 |
|---|---|---|
| Pay-band 3 | - | - |
| Pay-band 2 | 1 | 2 |
| Pay-band 1[footnote 25] | 5 | 10 |
Staff composition
For the 2025-26 year, the agency’s average full-time equivalent workforce was:
| Workforce profile (audited) average full-time equivalent | 2025-26 | 2024-25 |
|---|---|---|
| Permanently employed staff | 2,536 | 2,693 |
| Other | 10 | 5 |
| Total | 2,546 | 2,698 |
At 31 March 2026, the agency had a full-time equivalent workforce as follows:
| Workforce profile (audited) full-time equivalent | 31 March 2026 | 31 March 2025 |
|---|---|---|
| Permanently employed staff | 2,372 | 2,674 |
| Other | 16 | 3 |
| Total | 2,388 | 2,677 |
The gender diversity of the agency’s permanently employed staff and non-executive directors was:
| Gender diversity average full-time equivalent | Male 2025-26 | Female 2025-26 | Male 2024-25 | Female 2024-25 |
|---|---|---|---|---|
| Rural Payments Agency Board (RPA Board) not including Defra employees | 2 | - | 4 | 6 |
| Permanently employed staff (excluding RPA Board) | 1,003 | 1,370 | 1,167 | 1,496 |
| Total permanently employed staff | 1,005 | 1,370 | 1,171 | 1,502 |
| Non-executive directors | 4 | 2 | 3 | 1 |
| Total | 1,009 | 1,372 | 1,174 | 1,503 |
In 2025-26, a net recovery of secondment costs of £4.4 million (2024-25: £4.7 million), are reported in Note 2, under recoveries in respect of secondments.
People and Culture Committee
The People and Culture Committee is a sub-committee of the executive team within the agency’s governance structure. Its purpose is to deliver the agency’s strategic ambitions for people and culture, mitigate associated risks, and provide decisions on people-related change. It supports the development of a high-performance culture and a welcoming organisation which people are proud to be part of, aligned with both the agency’s values - to be visible, engaging, respectful, inclusive, trusted, accountable and supportive - and wider Civil Service values.
Attendance management
The agency’s annual working days lost for sickness figure in 2025-26 was 7.5 (2024-25: 7.2).
Employee engagement
The agency’s Civil Service People Survey, employee engagement index in 2025 was 56% (2024: 59%). The agency recognises the decline in employee engagement during the year and the link to a particularly challenging operating environment, including sustained operational pressures, organisational change, workforce reductions, and leadership transitions. These factors have placed additional demands on colleagues and affected the overall employee experience. The agency is committed to addressing this by strengthening leadership capability, improving communication and engagement, and ensuring that colleagues are supported through change. Improving employee engagement will remain a priority in 2026-27 as part of building a more stable, resilient and high‑performing organisation.
| Civil Service People Survey Engagement Index | 2025 | 2024 |
|---|---|---|
| Rural Payments Agency employee engagement index | 56% | 59% |
| Defra employee engagement index | 60% | 62% |
| Civil Service benchmark employee engagement index | 65% | 64% |
Expenditure on contractors and agency workforce
The agency is committed to using permanently employed people when possible, but the nature of its operations means it also requires the expertise of temporary contractors and an agency workforce, see Note 2.
The agency had consultants on its payroll in 2025-26 costing £0.6 million (2024-25: £0.4 million) as reported in staff expenditure in Note 2. And agency staff on its payroll costing £0.2 million (2024-25: £0.1 million).
Agency staff were typically lower grade individuals used on a short-term temporary basis to process scheme payments and provide cover for some business-as-usual tasks. The agency had 4 agency staff in its workforce at 31 March 2026 (31 March 2025: none).
Expenditure on out-sourced consultancy companies in 2025-26 was £24k (2024-25: £8k). These costs have been incurred directly by the agency and are categorised by their nature within non-IT professional services in Note 3 of these financial statements. Consultancy costs incurred by the agency paid by Defra are recharged to the agency in the corporate overhead recharge (notional) cost, see Note 3 of these financial statements.
Staff turnover
The agency calculates department turnover (staff leaving the civil service or a particular department) as defined by the Cabinet Office, Turnover Definition.
For 2025-26 and 2024-25, the agency’s turnover is calculated by dividing the number of leavers by the average headcount over the financial year. The increase in 2026 includes the 146 leavers under the Voluntary Exit Scheme.
Staff turnover during the year:
-
2025-26: 14.0%
-
2024-25: 8.0%
Pay policy
The agency is part of the Defra departmental pay bargaining unit. In July 2025, Defra implemented an average pay increase for staff at grades AA to G6 up to 3.25%, plus an additional 0.5% to be used flexibly to address specific departmental workforce issues, with an effective date of 1 July 2025. This is in line with the Civil Service Pay Remit Guidance 2025 to 2026 which provided a framework within which departments should set pay for 2025-26. Defra engaged with trade unions during the pay increase process.
Reporting of Civil Service and other compensation schemes - exit packages (audited)
During 2025-26 the agency ran a voluntary exit scheme supporting workforce reshaping to align capacity and cost with the agency’s future delivery priorities and funding envelope (see Managing significant challenges in 2025-26 section above). Redundancy and other departure costs have been paid in accordance with the provisions of the Civil Service Compensation Scheme, a statutory scheme made under the Superannuation Act 1972. The table below shows the total cost of exit packages agreed and accounted for in 2025-26 (2024-25: none). Exit costs are accounted for in full in the year the departure is agreed. £6.8 million exit costs were paid in 2025-26, the year of departure (2024-25: £Nil). During the year to 31 March 2026, there were no compulsory redundancies (2024-25: none) and 146 voluntary redundancies (2024-25: none). Where the agency has agreed early retirements, the additional costs are met by the agency and not by the Civil Service pension scheme. Ill-health retirement costs are met by the pension scheme and are not included in the table.
| Exit package cost band | Number of compulsory redundancies | Number of other agreed departures | Total number of exit packages by cost band |
|---|---|---|---|
| <£10,000 | - | 11 | 11 |
| £10,001 - £25,000 | - | 33 | 33 |
| £25,001 - £50,000 | - | 41 | 41 |
| £50,001 - £100,000 | - | 45 | 45 |
| £100,001 - £150,000 | - | 16 | 16 |
| Total number of exit packages | - | 146 | 146 |
| Total resource cost £000 | - | 6,844 | 6,844 |
Equal treatment in employment and occupation
In support of equal treatment in recruitment, the agency continues to use the Civil Service Guaranteed Interview Scheme for those with a disability or health condition. The agency also follows the ‘blind’ application process to ensure that diversity information is not disclosed to vacancy holders and / or interviewers at any time during the application process and therefore avoid unconscious bias entering the recruitment process. Interview panels are trained in aspects of unconscious bias and its impact on decision making.
The agency does everything possible to encourage and support its disabled employees. It is committed to giving disabled employees the same opportunities to develop and progress as non-disabled employees, making sure there are no barriers in achieving their full potential. The agency will not unlawfully discriminate against disabled people in any aspect of employment including the recruitment process, training, and promotional and career development opportunities.
Off-payroll appointments
In line with the recommendations of a review of Tax Arrangements of Public Sector Appointees published by HM Treasury in May 2012 the agency put in place controls to ensure its non-payroll people earning greater than £245 per day are contractually obliged to assure the agency that they are meeting their tax obligations. Monitoring continues to take place with regular reports being supplied to Defra.
For all off-payroll existing engagements as of 31 March 2026, for more than £245 per day and that last for longer than 6 months:
| Number of existing engagements | 2025-26 |
|---|---|
| Existing engagements at 31 March 2026 | 1 |
| of which: | |
| Existed for less than 1 year at time of reporting | - |
| Existed between 1 and 2 years at time of reporting | - |
| Existed between 2 and 3 years at time of reporting | - |
| Existed between 3 and 4 years at time of reporting | - |
| Existed for 4 or more years at time of reporting | 1 |
All highly paid off-payroll workers engaged at any point during the year to 31 March 2026, earning £245 per day or greater:
| Payroll workers engaged during the year to 31 March 2026 | 2025-26 |
|---|---|
| Number of off-payroll workers engaged during the year to 31 March 2026 | 1 |
| of which: | |
| Not subject to off-payroll legislation | 1 |
| Subject to off-payroll legislation and determined as in-scope of IR35 | - |
| Subject to off-payroll legislation and determined as out-of-scope of IR35 | - |
| Number of engagements reassessed for compliance or assurance purposes during the year | 1 |
| of which: | |
| Number of engagements that saw a change to IR35 status following review | - |
Senior officials with significant financial responsibility are defined as all board level executives, non-executive directors, and finance directors.
For any off-payroll engagements of board members, and / or senior officials with significant financial responsibility, between 1 April 2025 and 31 March 2026:
| Number of existing engagements | 2025-26 |
|---|---|
| Number of off-payroll engagements of board members, and / or senior officials with significant financial responsibility, during the financial year. | - |
| Total number of individuals on payroll and off-payroll engagements that have been deemed board members, and / or senior officials with significant financial responsibility, during the financial year. | 19 |
Parliamentary accountability and audit report
This section describes how the Rural Payments Agency (the agency) meets key accountability requirements to Parliament.
Regularity of expenditure (audited)
The agency reports losses and special payments:
| 2025-26 Number of cases | 2025-26 Value £000 | 2024-25 Number of cases | 2024-25 Value £000 | |
|---|---|---|---|---|
| Cash losses - scheme | 669 | 1,737 | 1,588 | 591 |
| Special payments - Sustainable Farming Incentive 2022 | 2 | 3 | 282 | 2,992 |
| Special payments - other schemes | 161 | 173 | 140 | 232 |
| Special payments - running expenditure | - | - | 1 | 12 |
| Total | 832 | 1,913 | 2,011 | 3,827 |
During 2025-26, there were no losses which individually exceeded £300k (2024-25: none).
Cash losses represent known, specific cases where a monetary loss has been incurred, for example when overpayments made to specific customers have not been recoverable.
The agency recorded a disallowance payable to the European Commission of £251k in 2025-26 being recovery orders under the European Agricultural Fund for the Rural Development scheme. Article 71 of Regulation (EU) No 1303/2013 (the Common Provisions Regulation) sets the rules on the durability of operations. It dictates that infrastructure or productive investments must repay their EU funding if, within 5 years of the final payment, the project undergoes specific prohibited changes. This spend is classified as irregular spend due to being in relation to non-compliance with scheme rules.
During the year, the agency identified a £69k payment to a former employee for which the full expected required internal approval documentation could not be evidenced. As a result, the payment has been classified as irregular. A review of internal controls has been initiated to address the process weaknesses identified.
Regularity of grant expenditure (audited)
In addition to the known cash losses above, the agency measures the level of undetected irregularities in its grant expenditure each year. This is the implied taxpayer loss associated with grant expenditure where payments have been made which are ineligible under scheme rules or where the outcomes required by the grant agreement have not been achieved. This is covered in detail in the Managing significant challenges in 2025-26 section above.
How the agency builds its estimate of irregularity
The agency continues to improve its ability to measure the effectiveness of its schemes in achieving required outcomes, and how it supports customers to get things right in delivering their agreements. To estimate the level of undetected irregularities in the agency’s total grant expenditure, known data points from the results of randomly selected site visits and remote sensing activity are extrapolated across the whole population.
In assessing whether the results of visits and remote sensing indicate fraud or error and in quantifying the monetary value of the loss to the taxpayer, the agency refers to the specific actions required by agreements in place with customers. Those agreements reflect the Secretary of State’s wider scheme rules in accordance with the Agriculture Act and relevant regulations covering each scheme examined.
In quantifying irregularity and the associated loss to the taxpayer, the agency applies a proportionate, activity-based approach. Where delivery under an agreement is only partially met, irregularity is assessed by reference to the extent of that shortfall rather than treating the entire claim as non-compliant. For example, where an area-based action is correctly delivered across the majority of the claimed area, only the undelivered proportion is treated as irregular. The methodology also incorporates established tolerances to reflect inherent measurement uncertainty in area-based and length-based activities, such that minor measurement variances do not give rise to spurious irregularities. This ensures that estimates of irregularity are grounded in a fair and practical assessment of delivery against scheme requirements and align closely with the underlying concept of taxpayer detriment.
The agency recognises that whilst some grant claimants under-deliver on the actions and associated environmental outcomes included with their grant agreements, many claimants also deliver more than is required. Where an individual claimant who is subject to a randomly selected site visit has both under-delivered on some actions and over-delivered on others, then the agency may offset some of the under and over deliveries in determining the total value of loss to the taxpayer. During the year the agency has changed the basis on which such offsetting is undertaken, to better represent the effect upon the environmental outcomes which schemes are designed to deliver. In general, this change has resulted in a greater level of offsetting, and therefore a lower reported estimate of irregularities. The comparative figures provided for 2024-25 have not been restated in relation to offsetting in the tables below, however adopting this change would have decreased the total estimated value of irregularities reported in 2024-25 from £40.3 million to £37.2 million.
Under the revised approach, offsetting is aligned to the environmental outcomes that scheme actions are intended to deliver, rather than to payment rates. Actions are mapped to defined environmental objectives and their associated contribution levels, and the value of under‑ and over‑delivery is apportioned across those objectives on a consistent basis. Offsetting is then applied only within the same environmental objective and contribution level, and within the same agreement. This ensures that offsetting reflects genuine delivery against the intended environmental outcomes of the schemes, providing a more proportionate and environmentally meaningful measure of taxpayer loss whilst maintaining a clear and verifiable methodology.
Irregularity estimates are determined in the context of the continuing roll-out of new or enhanced schemes, such as the Sustainable Farming Incentive (SFI), which reflect the parliamentary intent for better environmental outcomes and increased value for money. These schemes are more ambitious and complex than their predecessors and have an associated higher potential for irregularity. Estimated figures reported include both percentage irregularity rates and absolute monetary values of irregularities. Because of the continued increase in spending year on year, comparison of the percentage rates is most appropriate when considering how levels of irregularities are changing over time.
Common examples of irregularities
Irregularities are found across several broad themes as shown by examples from some of the actions that contribute most to the current estimate:
-
Some claimants fail to measure or approach the need to measure in such a way that they provide an incorrect measurement for example, when claiming areas of winter bird food. They may also fail to request an update to mapping such as when they move a boundary.
-
Some can fail to correctly interpret guidance when the guidance itself is complex, leading to errors in the design and planting of actions such as hedgerow creation.
-
Others may meet eligibility requirements and carry out an action but do so in such a way that detailed specifications, such as those for installation of sheep-netting, are not fully met (resulting in proportionate error).
-
In some cases, the claimant simply does not meet basic criteria by completing capital works before an agreement starts or failing to establish an action such as herbal leys with no mitigating circumstances or attempt to inform the agency.
Approach to managing the risk of fraud and error
The estimate of irregularity is underpinned by an integrated approach to managing the risk of fraud and error within grant expenditure to understand and mitigate against it. The agency maintains a strong focus on helping its customers to avoid errors prior to receiving any payments.
Collection and analysis of data and intelligence on irregularities is increasing, particularly through the extension of heat map analysis for SFI in addition to Countryside Stewardship. The heat maps identify issues at granular action or option level alongside other factors such as action or option take-up and payment rate to identify those most at risk of resulting in significant irregularities.
During this financial year, a strategic approach to gathering intelligence on sources of irregularity has been adopted, focusing analysis by multidisciplinary teams on key areas of concern with the aim of determining interventions that will have the greatest impact on the irregularity rate. A Department for Environment, Food and Rural Affairs (Defra) led panel continues to consider evidence collated by the agency of causes of error where a change in policy approach may be an appropriate intervention. In particular, the forthcoming SFI 2026 scheme has incorporated several simplifications and improvements to guidance based upon known causes of irregularities in earlier iterations of the scheme.
Change in presentation of scheme irregularity disclosures
During the year, the agency reviewed the presentation of irregularity estimates across schemes to provide users of the financial statements with clearer, more concise information. As a result, tables in this section have been condensed into broader scheme groupings. Schemes that were previously shown separately have been combined where their operational characteristics and risk profiles are closely aligned. In addition, 1 scheme category has been renamed from “Countryside Stewardship - capital” to “Capital grants” to more accurately describe the underlying scheme offer, and to better align with disclosures elsewhere in the financial statements.
These changes affect presentation only. Prior‑year comparative figures have been adjusted to conform to the current year’s presentation, but this does not impact total reported irregularities for either year.
Irregularity rates for 2025-26
The table below summarises most likely estimated irregularity rates and values by scheme.
| 2025-26 estimated irregularity rate % | 2025-26 value £ million | 2024-25 estimated irregularity rate % (as restated[footnote 25]) | 2024-25 value £ million (as restated[footnote 25]) | |
|---|---|---|---|---|
| Countryside Stewardship – revenue | 4.65% | 24.82 | 3.77% | 21.33 |
| Capital grants[footnote 25] | 5.13% | 12.42 | 1.92% | 4.69 |
| Sustainable Farming Incentive 2023 | 3.80% | 19.63 | 4.25% | 12.64 |
| Sustainable Farming Incentive 2024 | 6.26% | 13.79 | - | - |
| Environmental Stewardship | 2.22% | 2.47 | 0.90% | 0.86 |
| Other schemes | 0.26% | 0.28 | 0.39% | 0.80 |
| Overall - all schemes | 4.23% | 73.41 | 2.87% | 40.32 |
Uncertainty associated with the estimation of irregularity
The above table contains estimates based on a random sample of site visits and geospatial analysis and is therefore subject to a degree of statistical uncertainty. The estimates are prepared within a stated range of accuracy, known as confidence intervals. The 95% confidence intervals are presented below.
| 2025-26 | Central estimate £ million | Confidence interval from £ million | Confidence interval to £ million |
|---|---|---|---|
| Countryside Stewardship – revenue | 24.82 | 14.69 | 48.10 |
| Capital grants | 12.42 | 7.61 | 21.87 |
| Sustainable Farming Incentive 2023 | 19.63 | 11.34 | 38.42 |
| Sustainable Farming Incentive 2024 | 13.79 | 9.68 | 20.81 |
| Environmental Stewardship | 2.47 | 0.67 | 9.81 |
| Other schemes | 0.28 | 0.28 | 0.28 |
| 2024-25 (as restated[footnote 26]) | Central estimate £ million | Confidence interval from £ million | Confidence interval to £ million |
|---|---|---|---|
| Countryside Stewardship – revenue | 21.33 | 14.11 | 32.45 |
| Capital grants | 4.69 | 3.26 | 7.30 |
| Sustainable Farming Incentive 2023 | 12.64 | 8.73 | 19.44 |
| Environmental Stewardship | 0.86 | 0.18 | 2.70 |
| Other schemes | 0.80 | 0.80 | 0.80 |
Where practical to do so, the agency adjusts estimates for the effects of known and probable measurement errors. However, the figures presented are estimates and have several limitations. For example, judgement must occasionally be employed by field officers in determining whether a breach of scheme rules exists, and further judgements determine whether this has resulted in irregular expenditure. Judgement may also be needed in assessing the value of loss to the taxpayer. For example, when actions are delivered which are partially compliant with requirements, the loss to the taxpayer may be judged to be less than the full value of those actions. The table below demonstrates the sensitivity of the estimated values presented to changes in the financial value of irregularities for each scheme grouping. The percentage changes of 10% selected for this sensitivity analysis are judged to be representative of the possible level of measurement errors (whether practical or judgemental), based upon management knowledge of the operation of schemes and upon insights generated by quality control processes.
| Expenditure £ million | Irregularity rate % | Irregularity value £ million | Contribution to overall irregularity value % | Impact of a 10% change in monetary value of irregularity on the overall irregularity rate % | Impact of a 10% change in monetary value of irregularity on the overall irregularity value £ million | |
|---|---|---|---|---|---|---|
| Countryside Stewardship – revenue | 533.29 | 4.65% | 24.82 | 33.81% | 0.14% | 2.48 |
| Capital grants | 242.29 | 5.13% | 12.42 | 16.92% | 0.07% | 1.24 |
| Sustainable Farming Incentive 2023 | 516.93 | 3.80% | 19.63 | 26.74% | 0.11% | 1.96 |
| Sustainable Farming Incentive 2024 | 220.40 | 6.26% | 13.79 | 18.78% | 0.08% | 1.38 |
| Environmental Stewardship | 111.21 | 2.22% | 2.47 | 3.37% | 0.01% | 0.25 |
| Other schemes | 109.75 | 0.26% | 0.28 | 0.38% | 0.00% | 0.03 |
| Overall – all schemes | 1,733.87 | 4.23% | 73.41 | 100.00% | 0.42% | 7.34 |
Gifts over £300,000 (audited)
The agency has made no gifts nor received any gifts totalling over £300k in the year 2025-26 (2024-25: £Nil) as defined by HM Treasury’s Managing Public Money.
Government Functional Standards
The agency receives corporate services from its parent department, Defra, in several areas. As part of the services delivery model, Defra and its heads of profession conduct regular benchmarking and assessments against cross government standards. These are used to determine future development areas and investment bids and requirements. Assessments have shown that for services received, half are rated as “Good” or above (“Better”, or “Best”). The Communications and Grants service provision is jointly provided between the agency and Defra. Its rating for the Communications Functional Standard is “Good” and Grants Functional Standard is “Better”. The Internal Audit Functional Standard’s Continuous Improvement Assessment Framework (CIAF) was withdrawn in February 2026, thus no “Developing”, “Good”, “Better”, or “Best” rating can be reported. To comply with Global Internal Audit Standards (GIAS), an External Quality Assessment (EQA) was conducted, and, as a result, a Quality Assurance and Improvement Plan (QAIP) is being developed which will address a small number of standards where action has been recommended, alongside suggestions to help the agency develop further.
The agency continues to report on the Functional Standards through improved and streamlined governance, reflecting increased maturity as the agency goes through a period of transition, continuing to work with Defra colleagues to strengthen working practices and compliance. The introduction of new technologies is enabling delivery against the agency’s Continuous Improvement Plan for the Project Delivery Functional Standard. While assessments are on-going for the Analysis and Data and Digital Functional Standards, the agency is building on the detailed assessment undertaken in 2024-25. The agency is focusing on strengthening alignment to the Grants Functional Standard through farm and land service system development and consideration of capability requirements, to further embed and learn from all the Functional Standards.
Fees and charges (audited)
The agency has no material income from fees and charges.
Oliver Munn
Chief Executive and Accounting Officer
7 July 2026
The Certificate and report of the Comptroller and Auditor General to the House of Commons
Opinion on financial statements
I certify that I have audited the financial statements of the Rural Payments Agency for the year ended 31 March 2026 under the Government Resources and Accounts Act 2000.
The financial statements comprise the Rural Payments Agency’s:
-
Statement of Financial Position as at 31 March 2026;
-
Statement of Comprehensive Net Expenditure, Statement of Cash Flows and Statement of Changes in Taxpayers’ Equity for the year then ended; and
-
the related notes including the significant accounting policies.
The financial reporting framework that has been applied in the preparation of the financial statements is applicable law and UK adopted international accounting standards.
In my opinion, the financial statements:
-
give a true and fair view of the state of the Rural Payments Agency’s affairs as at 31 March 2026 and its net operating expenditure for the year then ended; and
-
have been properly prepared in accordance with the Government Resources and Accounts Act 2000 and HM Treasury directions issued thereunder.
Qualified opinion on regularity
In my opinion, except for the effects of the matters described in the Basis for qualified opinion on regularity section below, in all material respects, the income and expenditure recorded in the financial statements have been applied to the purposes intended by Parliament, and the financial transactions recorded in the financial statements conform to the authorities which govern them.
Basis for qualified opinion on regularity
The Rural Payments Agency incurs grant expenditure on a number of schemes aimed to support farmers and other land managers, and to achieve environmental outcomes. The rules for these schemes are set out by the Secretary of State within a framework of statutory regulations. During 2025-26, the Rural Payments Agency measured a level of non-compliance with scheme rules resulting in estimated irregular expenditure of £73.4m. I assess this level of irregular expenditure to be material.
Basis for opinions
I conducted my audit in accordance with International Standards on Auditing (UK) (ISAs UK), applicable law and Practice Note 10 Audit of Financial Statements and Regularity of Public Sector Bodies in the United Kingdom (2024). My responsibilities under those standards are further described in the Auditor’s responsibilities for the audit of the financial statements section of my certificate.
Those standards require me and my staff to comply with the Financial Reporting Council’s Revised Ethical Standard 2024. I am independent of the Rural Payments Agency in accordance with the ethical requirements that are relevant to my audit of the financial statements in the UK. My staff and I have fulfilled our other ethical responsibilities in accordance with these requirements.
I believe that the audit evidence I have obtained is sufficient and appropriate to provide a basis for my opinion.
Conclusions relating to going concern
In auditing the financial statements, I have concluded that the Rural Payments Agency’s use of the going concern basis of accounting in the preparation of the financial statements is appropriate.
Based on the work I have performed, I have not identified any material uncertainties relating to events or conditions that, individually or collectively, may cast significant doubt on the Rural Payments Agency’s ability to continue as a going concern for a period of at least twelve months from when the financial statements are authorised for issue.
My responsibilities and the responsibilities of the Accounting Officer with respect to going concern are described in the relevant sections of this certificate.
The going concern basis of accounting for the Rural Payments Agency is adopted in consideration of the requirements set out in HM Treasury’s Government Financial Reporting Manual, which requires entities to adopt the going concern basis of accounting in the preparation of the financial statements where it is anticipated that the services which they provide will continue into the future.
Other information
The other information comprises information included in the Annual Report, but does not include the financial statements and my auditor’s certificate and report thereon. The Chief Executive as Accounting Officer is responsible for the other information.
My opinion on the financial statements does not cover the other information and, except to the extent otherwise explicitly stated in my certificate, I do not express any form of assurance conclusion thereon.
My responsibility is to read the other information and, in doing so, consider whether the other information is materially inconsistent with the financial statements or my knowledge obtained in the audit, or otherwise appears to be materially misstated.
If I identify such material inconsistencies or apparent material misstatements, I am required to determine whether this gives rise to a material misstatement in the financial statements themselves. If, based on the work I have performed, I conclude that there is a material misstatement of this other information, I am required to report that fact.
I have nothing to report in this regard.
Opinion on other matters
In my opinion the part of the Remuneration and Staff Report to be audited has been properly prepared in accordance with HM Treasury directions issued under the Government Resources and Accounts Act 2000.
In my opinion, based on the work undertaken in the course of the audit:
-
the parts of the Accountability Report subject to audit have been properly prepared in accordance with HM Treasury directions issued under the Government Resources and Accounts Act 2000;
-
the information given in the Performance and Accountability Reports for the financial year for which the financial statements are prepared is consistent with the financial statements and is in accordance with the applicable legal requirements.
Matters on which I report by exception
In the light of the knowledge and understanding of the Rural Payments Agency and its environment obtained in the course of the audit, I have not identified material misstatements in the Performance and Accountability Report.
I have nothing to report in respect of the following matters which I report to you if, in my opinion:
-
adequate accounting records have not been kept by the Rural Payments Agency or returns adequate for my audit have not been received from branches not visited by my staff; or
-
I have not received all of the information and explanations I require for my audit; or
-
the financial statements and the parts of the Accountability Report subject to audit are not in agreement with the accounting records and returns; or
-
certain disclosures of remuneration specified by HM Treasury’s Government Financial Reporting Manual have not been made or parts of the Remuneration and Staff Report to be audited is not in agreement with the accounting records and returns; or
-
the Governance Statement does not reflect compliance with HM Treasury’s guidance.
Responsibilities of the Accounting Officer for the financial statements
As explained more fully in the Statement of Accounting Officer’s Responsibilities, the Chief Executive as Accounting Officer is responsible for:
-
maintaining proper accounting records;
-
providing the C&AG with access to all information of which management is aware that is relevant to the preparation of the financial statements such as records, documentation and other matters;
-
providing the C&AG with additional information and explanations needed for his audit;
-
providing the C&AG with unrestricted access to persons within the Rural Payments Agency from whom the auditor determines it necessary to obtain audit evidence;
-
ensuring such internal controls are in place as deemed necessary to enable the preparation of financial statements to be free from material misstatement, whether due to fraud or error;
-
preparing financial statements which give a true and fair view and are in accordance with HM Treasury directions issued under the Government Resources and Accounts Act 2000;
-
preparing the annual report, which includes the Remuneration and Staff Report, in accordance with HM Treasury directions issued under the Government Resources and Accounts Act 2000; and
-
assessing the Rural Payments Agency’s ability to continue as a going concern, disclosing, as applicable, matters related to going concern and using the going concern basis of accounting unless the Accounting Officer anticipates that the services provided by the Rural Payments Agency will not continue to be provided in the future.
Auditor’s responsibilities for the audit of the financial statements
My responsibility is to audit, certify and report on the financial statements in accordance with the Government Resources and Accounts Act 2000.
My objectives are to obtain reasonable assurance about whether the financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue a certificate that includes my opinion. Reasonable assurance is a high level of assurance but is not a guarantee that an audit conducted in accordance with ISAs (UK) will always detect a material misstatement when it exists. Misstatements can arise from fraud or error and are considered material if, individually or in the aggregate, they could reasonably be expected to influence the economic decisions of users taken on the basis of these financial statements.
Extent to which the audit was considered capable of detecting non-compliance with laws and regulations, including fraud
I design procedures in line with my responsibilities, outlined above, to detect material misstatements in respect of non-compliance with laws and regulations, including fraud. The extent to which my procedures are capable of detecting non-compliance with laws and regulations, including fraud is detailed below.
Identifying and assessing potential risks related to non-compliance with laws and regulations, including fraud
In identifying and assessing risks of material misstatement in respect of non-compliance with laws and regulations, including fraud, I:
-
considered the nature of the sector, control environment and operational performance including the design of the Rural Payments Agency’s accounting policies, key performance indicators and performance incentives;
-
inquired of management, the Rural Payments Agency’s Head of Internal Audit and those charged with governance, including obtaining and reviewing supporting documentation relating to the Rural Payments Agency’s policies and procedures on
* identifying, evaluating and complying with laws and regulations,
-
detecting and responding to the risks of fraud, and
-
the internal controls established to mitigate risks related to fraud or non-compliance with laws and regulations including the Rural Payments Agency’s controls relating to its compliance with the Government Resources and Accounts Act 2000, Managing Public Money and regulations governing grant expenditure;
-
inquired of management, the Rural Payments Agency’s Head of Internal Audit and those charged with governance whether
-
they were aware of any instances of non-compliance with laws and regulations, or
-
they had knowledge of any actual, suspected, or alleged fraud; and
-
discussed with the engagement team and the relevant internal specialists, including the NAO’s modelling team, regarding how and where fraud might occur in the financial statements and any potential indicators of fraud.
As a result of these procedures, I considered the opportunities and incentives that may exist within the Rural Payments Agency for fraud and identified the greatest potential for fraud in the following areas: posting of unusual journals, complex transactions, bias in management estimates and fraud and error relating to scheme expenditure. In common with all audits under ISAs (UK), I am required to perform specific procedures to respond to the risk of management override.
I obtained an understanding of the Rural Payments Agency’s framework of authority and other legal and regulatory frameworks in which the Rural Payments Agency operates. I focused on those laws and regulations that had a direct effect on material amounts and disclosures in the financial statements or that had a fundamental effect on the operations of the Rural Payments Agency. The key laws and regulations I considered in this context included Government Resources and Accounts Act 2000, Managing Public Money, employment law, and the regulations governing grant expenditure.
In considering the Rural Payments Agency’s estimate of the risk of fraud and error within grant expenditure, I principally considered the impact of the estimated level on my opinion on regularity. While I also considered the potential impact of undetected fraud and error on the accuracy of the financial statements, I did not assess significant risk in this respect.
Audit response to identified risk
To respond to the identified risks resulting from the above procedures:
-
I reviewed the financial statement disclosures and testing to supporting documentation to assess compliance with provisions of relevant laws and regulations described above as having direct effect on the financial statements;
-
I enquired of management, the Audit and Risk Assurance Committee and in-house legal counsel concerning actual and potential litigation and claims;
-
I reviewed minutes of meetings of those charged with governance and the Board, as well as internal audit reports;
-
I addressed the risk of fraud through management override of controls by testing the appropriateness of journal entries and other adjustments, assessing whether the judgements on estimates are indicative of a potential bias, and evaluating the business rationale of any significant transactions that are unusual or outside the normal course of business; and
-
I undertook other audit procedures responsive to the risk that management’s estimates on the extent of irregularity within scheme expenditure were misstated, including the reverification of source data and model reperformance.
I communicated relevant identified laws and regulations and potential risks of fraud to all engagement team members including internal specialists, and remained alert to any indications of fraud or non-compliance with laws and regulations throughout the audit.
A further description of my responsibilities for the audit of the financial statements is located on the Financial Reporting Council’s website at: www.frc.org.uk/auditorsresponsibilities. This description forms part of my certificate.
Other auditor’s responsibilities
I am required to obtain sufficient appropriate audit evidence to give reasonable assurance that the expenditure and income recorded in the financial statements have been applied to the purposes intended by Parliament and the financial transactions recorded in the financial statements conform to the authorities which govern them.
I communicate with those charged with governance regarding, among other matters, the planned scope and timing of the audit and significant audit findings, including any significant deficiencies in internal control I identify during my audit.
Gareth Davies
Comptroller and Auditor General
7 July 2026
National Audit Office
157-197 Buckingham Palace Road
Victoria
London
SW1W 9SP
Report of the Comptroller and Auditor General to the House of Commons
1. These financial statements describe the second year in which the Rural Payments Agency’s (the agency’s) scheme expenditure has been principally constituted of agri-environmental grants, including Countryside Stewardship (CS) and Sustainable Farming Incentive (SFI). The transition to these schemes follows a period up to 2023 during which the principal element of scheme expenditure was an area-based subsidy, and implements the policy aim of the Department for Environment, Food and Rural Affairs (Defra) to link grants to the achievement of specific environmental outcomes.
2. I assess a material level of non-compliance during 2025-26 with the scheme rules which apply to the agency’s grants. This has led me to qualify my opinion on the regularity of expenditure in respect of the agency’s grant schemes. This report provides more detail on the associated issues, including recommendations for improvement.
Background
3. The agency (a delivery arm of Defra) delivers grant payments to farmers and other land managers. Grant schemes are designed by Defra, after which the Secretary of State issues detailed requirements and guidance for each scheme. These must comply with the broad frameworks approved by Parliament in statutory regulation.
4. Note 5 to the financial statements describes how the agency’s scheme expenditure changed during 2025-26. Excluding the effect of delinked payments, where negative expenditure was recognised in 2024-25 reflecting a one-off revaluation adjustment, UK-funded net grant scheme expenditure has increased during the year to £1.7bn (2024-25: £1.4bn). In both years, the most significant components of these grant schemes are grants made under the CS and SFI schemes. These include:
-
current (revenue) elements relating to ongoing actions by landowners, for example to manage or establish natural features boosting biodiversity, or to improve soil condition; and
-
capital elements (in CS and some smaller schemes) to fund specified asset purchases by landowners, often to improve farm operations or productivity.
5. The agency is required to produce an estimate (pages 64-69) of the extent to which its expenditure is irregular – where the related financial transactions do not conform to the authorities which govern them. For grant expenditure, this means considering both whether the agency has made payments in accordance with the scheme rules, and whether payments have been applied in line with those rules by grant recipients. The agency measures irregularity based on site visits and remote verification, both of which determine the extent to which the scheme requirements are being met. Where identified, irregularity is measured in proportion to the taxpayer loss it implies. For example:
-
where a portion of an area-based action (e.g. planting a seed mix) is deemed not to have been delivered, the irregularity will be determined in relation to the proportion not found, rather than the whole action;
-
where a funded item has been delivered, but there have been some breaches of the eligibility criteria within scheme agreements (often designed to protect the overall environmental outcome) then an irregularity will be assessed based on a variable percentage reflecting how impactful the breach was on the action’s intended outcomes; and
-
where a grant recipient has over-delivered against some actions, management make an adjustment to net off the value added against the irregularity assessed from under-deliveries with comparable environmental outcomes by the same grant recipient.
6. My role is to provide an opinion on whether, in all material respects, the agency’s expenditure has been applied to the purposes intended by Parliament, and that transactions conform to the relevant authorities (regularity). I consider this in the context of the overall financial statements, and my assessment on the sensitivity of users of the accounts to irregularities. In forming my opinion, I work to gain assurance over the agency’s own measurement of irregularity.
Qualification of the Comptroller and Auditor General’s audit opinion on the regularity of grant expenditure
7. As in 2024-25, I have qualified my opinion on regularity in respect of the grant expenditure recorded in the agency’s 2025-26 financial statements due to the material levels of irregularity identified by the agency in its grants. This year, the agency measured irregularity across its schemes of £73.4m – 4.23% of overall grant expenditure.
8. I have not detected evidence of material irregularity as a result of the agency itself mis-applying scheme rules when it makes payments. The irregularities reflected in this qualification relate to non-compliance by grant recipients, typically where outputs agreed with the agency have been paid for, but observation suggests they have not been fully delivered.
The agency’s approach to the prevention and measurement of fraud and error
9. These irregularities will in many cases represent genuine error by grant recipients, though some may reflect fraud, for example if an agreement holder makes an annual declaration knowingly overstating delivery.
10. It is often impracticable to distinguish between these scenarios based on the evidence at hand. Both involve under delivery based on the scheme rules, implying a taxpayer loss. The agency describes on page 65 how it considers the risk of fraud and error in the round, and seeks to target mitigations based on a heat map of specific actions or options impacting the irregularity rate, and works with Defra to inform future scheme design. It also describes a focus on supporting grant recipients, with a view to preventing errors.
11. The agency runs a programme of field visits, selected using both risk-based and random methods, with the aims of: - supporting recipients in achieving the intended outcomes and complying with scheme rules; - mitigating the risk of irregularity (fraud and error); and - measuring the extent of irregularity with statistical confidence.
12. Overall, the agency’s measurement provides a robust basis for my audit. My procedures include the reverification of a sub-sample of randomised field visit results in partnership with agency staff, and a detailed review of the agency’s model which translates ground observations into the estimates presented on pages 64-69.
How the risk of irregularity is influenced by scheme design
13. There is a link between the characteristics of each scheme and the inherent risk of irregularity, or non-compliance, attaching to them. For example, a subsidy scheme based predominantly on farm area (as in the Basic Payment Scheme, which dominated expenditure prior to 2023) has an inherently lower risk of non-compliance compared to multi option agri-environmental schemes which require the delivery of specific outputs.
14. This is, in part, because grant recipients are more likely to make genuine errors in respect of schemes with more complexity. This arises in the number and diversity of options within each scheme; the challenge of quantifying certain types of output, such as the maintenance or enhancement of natural features involving multiple linear or area measurements; and the seasonal nature of some options.
15. The extent of controls built into each scheme – features that make it easier for recipients to have confidence in their compliance, and/or less likely that they will risk claiming an amount in excess of the amount delivered – also has an impact on the inherent risk of irregularity.
The relationship between regularity and value for money
16. The considerations above about complexity do not imply that a policy with a lower regularity risk is better value for money. A low regularity risk implies a low risk of non-compliance with scheme rules, not that a programme is effective in securing benefits proportionate to its costs. For the same reason, my opinion on regularity does not reflect a conclusion on overall value for money for these schemes.
17. It is for the Department’s Accounting Officer to evaluate the mechanisms best suited to delivering the government’s desired outcomes, and Defra has moved towards agri-environmental schemes in continuity with the policy goals of Defra’s Environmental Improvement Plan and the Farming and Countryside Programme (FCP). I reported on broader aspects of how Defra is managing the FCP in a separate value for money report in 2024.
18. I also note that in some cases, environmental actions are sometimes delivered in excess of the claimed amounts by individual customers. For the purposes of the regularity opinion, these over-deliveries are rightly not offset against under-deliveries by different beneficiaries, and have no impact on the measure, or my opinion. Nevertheless, I acknowledge that the degree of these over-deliveries might be relevant to a broader consideration of taxpayer value.
My evaluation of this year’s irregularity measurement
19. I have determined the level of taxpayer loss implied by irregularities – detected by the agency and extrapolated across each grant population – to be at a material level for my opinion.
20. In 2025-26, the proportion of scheme expenditure assessed as irregular has risen to 4.23% (2024-25: 2.87%). The rate has increased across multiple schemes, as shown below, reflecting a concerning trend. Of particular concern is the assessment of 6.3% of the transactions in the latest SFI 24 scheme being irregular, 2.0% higher than SFI 23 scheme last year at a similar point following its introduction.
| 2025-26 | Scheme expenditure £ million | Estimated proportion which is irregular % | Estimated irregularity value £ million |
|---|---|---|---|
| Countryside Stewardship – revenue | 533.3 | 4.7% | 24.8 |
| Capital grants | 242.3 | 5.1% | 12.4 |
| Sustainable Farming Incentive 2023 | 516.9 | 3.8% | 19.6 |
| Sustainable Farming Incentive 2024 | 220.4 | 6.3% | 13.8 |
| Environmental Stewardship | 111.2 | 2.2% | 2.5 |
| Other schemes | 109.8 | 0.3% | 0.3 |
| Overall – all schemes | 1,733.9 | 4.2% | 73.4 |
| 2024-25 | Scheme expenditure £ million | Estimated proportion which is irregular % | Estimated irregularity value £ million |
|---|---|---|---|
| Countryside Stewardship – revenue | 566.0 | 3.8% | 21.3 |
| Capital grants | 244.5 | 1.9% | 4.7 |
| Sustainable Farming Incentive 2023 | 297.5 | 4.2% | 12.6 |
| Sustainable Farming Incentive 2024 | n/a | n/a | n/a |
| Environmental Stewardship | 95.9 | 0.9% | 0.9 |
| Other schemes | 201.0 | 0.4% | 0.8 |
| Overall – all schemes | 1,404.9 | 2.9% | 40.3 |
-
Scheme expenditure is based on the audited amounts in Note 5 to the financial statements.
-
Irregularity outturns are consistent with the agency’s estimates presented in the accountability report, including the prior year representation between categories explained in that report. ‘Capital grants’ relates to the capital element of Countryside Stewardship only – smaller capital grants are presented under ‘Other schemes’.
( Consistent with management’s irregularity analysis, scheme expenditure presented for 2024-25 does not include the one-off reduction for delinked payments which was associated with a provision remeasurement). No additional irregularity estimate was made in connection with this element, since it arose from changes in the revised best estimate of future payment rates, rather than reflecting additional expenditure.
21. It is for management to analyse the root causes of its newest scheme having the highest rate of error. However, it is worth taking note of ‘streamlining’ changes introduced for the newer SFI schemes, such as automatic payment processing, the removal of the requirement to maintain option maps, or to check or update hedgerow maps. While not the whole story, these changes may reduce the effectiveness of management’s control environment in respect of over-claims.
How I plan to assess irregularity in future audits
22. These agri-environmental schemes remain relatively new. I recognise the legitimate trade-offs in their design, particularly between a higher ambition for environmental outcomes, and a higher inherent risk of scheme rules not being followed. However, the worsening results above reflect a growing problem of value loss which the agency and Defra need to address.
23. In the long term, I want to see the agency and Defra build a clearer analysis of risk appetite in respect of the irregularity rate on these schemes, which takes into account the available actions on both scheme design and the controls which it would be cost-effective to implement.
24. I expect my future decisions on whether to qualify to be based on a judgement on whether this control environment has been effectively designed and implemented, informed by evidence on:
-
whether the agency is achieving sustained reductions in the irregularity rate;
-
the steps taken by both Defra and the agency to strengthen the control environment; and
-
their analysis of the cost effectiveness of the approach, given the resources deployed.
Actions for the agency and Defra
25. In the shorter term, it is clear given the increased error rate that there remain opportunities to improve controls towards this level. An improved control environment should make it easier from the customer perspective to comply first time, and do more to mitigate the risk of over-claims being made.
26. Specifically, Defra and the agency should:
-
perform a thorough root cause analysis of the increased irregularity levels, drawing on the agency’s heat map and other sources of data and insight, such as the agency’s field teams;
-
make targeted changes in future scheme iterations based on this analysis, being clear about the split between quick wins and longer-term actions in delivering a cost-effective control environment;
-
include the customer perspective in both lessons learned and scheme design iteration, considering what requirements or nudges could best influence accurate claims;
-
evaluate the adequacy of preventative controls over customer data associated with over-claims, including in respect of the potential for inaccuracies enabled by streamlined mapping requirements for SFI to compound over time;
-
consider whether broader preventative controls are proportionate, for example around pre-payment checks and incentives mitigating over-claims;
-
over time, set out a revised risk appetite, building on experience of the interaction between controls and other changes implemented and the irregularity rate, of the sustainable rate which could reasonably be expected in a cost-effective control environment; and
-
continue to update Parliament on fraud and error results – including on its insights on root causes, and the trade-offs accepted between irregularity and achieving other policy objectives.
Financial statements
Statement of Comprehensive Net Expenditure
for the year ended 31 March 2026
| Note | 2025-26 £000 | 2024-25 £000 | |
|---|---|---|---|
| Running expenditure | |||
| Staff | 2 | 121,474 | 112,357 |
| Other | 3 | 99,596 | 117,833 |
| Total running expenditure | 221,070 | 230,190 | |
| Income | 4 | (1,946) | (2,005) |
| Net running expenditure | 219,124 | 228,185 | |
| Scheme expenditure | |||
| Expenditure | 5 | 1,740,987 | 928,178 |
| Income | 5 | (5,457) | (13,683) |
| Net scheme expenditure | 1,735,530 | 914,495 | |
| Net operating expenditure | 1,954,654 | 1,142,680 | |
| Other comprehensive net expenditure | |||
| Net gain on revaluation of intangible assets | - | (6,653) | |
| Comprehensive net expenditure for the year | 1,954,654 | 1,136,027 |
The notes to the accounts form part of these financial statements.
Statement of Financial Position
at 31 March 2026
| Note | 31 March 2026 £000 | 31 March 2025 £000 | |
|---|---|---|---|
| Non-current assets | |||
| Property, plant and equipment | 3,207 | 1,862 | |
| Intangible assets | 6 | 54,607 | 56,276 |
| Total non-current assets | 57,814 | 58,138 | |
| Current assets | |||
| Trade and other receivables | 7 | 274,970 | 208,416 |
| Cash and cash equivalents | 8 | 50,030 | 163,460 |
| Total current assets | 325,000 | 371,876 | |
| Total assets | 382,814 | 430,014 | |
| Current liabilities | |||
| Trade and other payables | 9 | (145,120) | (449,260) |
| Lease liabilities | (719) | (794) | |
| Provisions | 10 | (21,714) | - |
| Total current liabilities | (167,553) | (450,054) | |
| Total assets less current liabilities | 215,261 | (20,040) | |
| Non-current liabilities | |||
| Provisions | 10 | (20,952) | (40,871) |
| Lease liabilities | (815) | (1,766) | |
| Total non-current liabilities | (21,767) | (42,637) | |
| Total assets less total liabilities | 193,494 | (62,677) | |
| Taxpayers’ equity and other reserves | |||
| General fund | SoCTE | 193,494 | (74,647) |
| Revaluation reserve | - | 11,970 | |
| Total equity | 193,494 | (62,677) |
The notes to the accounts form part of these financial statements.
Oliver Munn
Chief Executive and Accounting Officer
7 July 2026
Statement of Cash Flows
for the year ended 31 March 2026
| Note | 2025-26 £000 | 2024-25 £000 | |
|---|---|---|---|
| Cash flows from operating activities | |||
| Net operating expenditure | SoCNE | (1,954,654) | (1,142,680) |
| Adjustment for non-cash items included in other running expenditure | 3 | 87,398 | 104,494 |
| Adjustment for derivative financial instruments | - | 629 | |
| Increase/(decrease) in provisions | 1,795 | (756,591) | |
| (Increase)/decrease in trade and other receivables | 7 | (66,554) | 57,106 |
| (Decrease) in trade and other payables | 9 | (304,844) | (536,594) |
| Net cash outflow from operating activities | (2,236,859) | (2,273,636) | |
| Cash flows from investing activities | |||
| Purchase of intangibles | - | (4) | |
| Net cash outflow from investing activities | - | (4) | |
| Cash flows from financing activities | |||
| Financing by Defra | 2,125,000 | 2,368,000 | |
| Receipts for Rural Development Programme for England on behalf of Defra | - | 3,107 | |
| Disallowance transfer to Defra | - | (14,034) | |
| Defra schemes administered by Rural Payments Agency | - | (5) | |
| Capital element of payments in respect of lease liabilities | (1,571) | (12) | |
| Net cash inflow from financing activities | 2,123,429 | 2,357,056 | |
| (Decrease)/increase in cash and cash equivalents in the period | (113,430) | 83,416 | |
| Cash and cash equivalents at 1 April | 8 | 163,460 | 80,044 |
| Cash and cash equivalents at 31 March | 8 | 50,030 | 163,460 |
The notes to the accounts form part of these financial statements.
Statement of Changes in Taxpayers’ Equity
for the year ended 31 March 2026
| Note | General fund £000 | Revaluation reserve £000 | Taxpayers’ equity £000 | |
|---|---|---|---|---|
| Balance at 31 March 2024 | (1,400,978) | 10,358 | (1,390,620) | |
| Net operating expenditure | SoCNE | (1,142,680) | - | (1,142,680) |
| Transfer from revaluation reserve to general fund - intangible assets | 7,061 | (7,061) | - | |
| Gain on revaluation of intangible assets during the year (net) | SoCNE 6 | - | 6,653 | 6,653 |
| Comprehensive net expenditure for year | (1,135,619) | (408) | (1,136,027) | |
| Notional charge – corporate overhead recharge | 3 | 83,381 | - | 83,381 |
| Financing by Defra | 2,368,000 | - | 2,368,000 | |
| Receipts for Rural Development Programme for England on behalf of Defra | 3,107 | - | 3,107 | |
| Disallowance transfer to Defra | (14,034) | - | (14,034) | |
| Defra schemes administered by Rural Payments Agency | (5) | - | (5) | |
| Assets transfer from Defra | 21,501 | 2,020 | 23,521 | |
| Balance at 31 March 2025 | (74,647) | 11,970 | (62,677) | |
| Comprehensive net expenditure for year | SoCNE | (1,954,654) | - | (1,954,654) |
| Transfer from revaluation reserve to general fund | 11,970 | (11,970) | - | |
| Notional charge – corporate overhead recharge | 3 | 64,730 | - | 64,730 |
| Financing by Defra | 2,125,000 | - | 2,125,000 | |
| Assets transfer from Defra | 21,095 | - | 21,095 | |
| Balance at 31 March 2026 | 193,494 | - | 193,494 |
The notes to the accounts form part of these financial statements.
Notes to the financial statements
1. Statement of accounting policies
The financial statements have been prepared in accordance with the 2025-26 Government Financial Reporting Manual (FReM) and the Accounts Direction issued by HM Treasury in accordance with Section 7(2) of the Government Resources and Accounts Act 2000.
The accounting policies contained in the FReM apply International Financial Reporting Standards (IFRS) as adapted and interpreted for the public sector. Where the FReM allows a choice of accounting policy, the accounting policy which has been judged to be most appropriate to the particular circumstances of the Rural Payments Agency (the agency) for the purpose of giving a true and fair view has been selected. The accounting policies adopted by the agency are described below. They have been applied consistently in dealing with items considered material in relation to the financial statements.
Going concern
The financial statements are prepared on a going concern basis and are consistent with the FReM 2025-26 continued provision of service basis. The going concern assessment, including the continuation of service basis, was reviewed by the executive team and considered by the Rural Payments Agency’s Audit and Risk Assurance Committee and the Rural Payments Agency Board as part of the approval of the annual report and accounts.
1.1 Accounting convention
These financial statements have been prepared on an accruals basis under the historic cost convention, modified to account for the revaluation of certain financial assets and liabilities, where material.
1.2 Intangible assets
Intangible assets are recognised at deemed historical cost. Before 31 March 2025 they were revalued annually using UK Office of National Statistics price indices.
From 1 April 2025, the option to measure intangible assets using the revaluation model was withdrawn from the FReM. Accordingly, the agency has applied the cost model for intangible assets. In accordance with the FReM, the carrying values at 1 April 2025 were considered deemed historical cost. The change has been applied prospectively (implemented only for the current period and future periods, with no changes made to prior periods).
Software under development is capitalised as development expenditure but not amortised until it is ready for use. Transfers of assets developed by the agency’s parent department, the Department for Environment, Food and Rural Affairs (Defra), are provided to the agency through the general fund. For intangible assets all software projects over £100k and software licences over £10k are capitalised. Software licences purchased as a group, each costing above £500 but totalling more than £500k are also capitalised. Intangible assets are reviewed annually for signs of impairment.
1.3 Amortisation
Assets are amortised on a straight-line basis over their estimated useful life, considering any residual value. This starts from the month after the asset is ready for use.
Estimated useful lives at initial recognition are normally in the range 5 to 7 years. All information technology software assets capitalised to deliver rural scheme payments have been amortised over the period ending 31 March 2028, see Note 6. These assets therefore no longer sit within the stated useful expected life range.
1.4 Financing by Defra
The agency receives funding from its controlling party, Defra. The receipts are recorded as a financing transaction and are credited directly to the general fund in the Statement of Financial Position.
1.5 Scheme expenditure and income
Schemes administered on behalf of another government body
Where the agency makes payments on behalf of another government body which is acting as the controlling entity, expenditure and income for such schemes will be recognised by the other government body. Assets and liabilities relating to these schemes are reported in the agency’s Statement of Financial Position along with a corresponding intra-governmental balance.
Scheme expenditure recognition points
Scheme expenditure is recognised by the agency when both of the following criteria are judged to be met:
-
The customer has fulfilled their performance obligations in line with the applicable scheme rules and regulations; and
-
The value of the claim can be reliably estimated by the agency.
This commonly results in expenditure being recognised either on receipt of claims or on the last day of the agreement year (in the case of multiannual revenue schemes).
The table below sets out the specific expenditure recognition points for the agency’s principal schemes; less material schemes are omitted for conciseness.
| Scheme | Presentation within Note 5 | Expenditure recognition point |
|---|---|---|
| Countryside Stewardship - revenue | Countryside Stewardship - revenue | Expenditure is recognised on the final day of claimants’ agreement years. |
| Legacy Countryside Stewardship mid-tier capital, legacy higher tier capital and standalone capital grants | Capital grants | Expenditure is recognised upon receipt of claims. |
| Sustainable Farming Incentive 2023 and 2024 Expanded Offer | Sustainable Farming Incentive | Expenditure is recognised on the final day of claimants’ agreement years. |
| Sustainable Farming Incentive Pilot and 2022 | Sustainable Farming Incentive | Expenditure is recognised on the latter of the final day of the claimants’ agreement years, and the receipt of any necessary annual declarations. |
| Environmental Stewardship | Environmental Stewardship | Expenditure is recognised on the final day of claimants’ agreement year. |
| Farming Equipment and Technology Fund | Farming Equipment and Technology Fund | Expenditure is recognised upon receipt of claims. |
| Farming Transformation Fund | Farming Transformation Fund | Expenditure is recognised upon receipt of claims. |
| Fruit and Vegetables | Fruit and Vegetables | Expenditure is recognised upon receipt of claims. |
The agency enters into multi-annual agreements in respect of some schemes. Where such agreements contain obligations that customers have not yet performed, those elements of the agreements are not recognised as expenditure. The agency discloses the extent of these unrecognised commitments in Note 13. To the extent that customers meet their future performance obligations, the agency expects that these commitments will be recognised as expenditure in future years.
The full value of delinked payments was recognised during the 2023-24 financial year, in line with the recognition point of Basic Payment Scheme 2023 expenditure, as eligibility for delinked payments is linked to the submission of valid Basic Payment Scheme claims. These conditions are deemed to be met at the point the related scheme expenditure is recognised. The value of future delinked payments has been recognised as a provision, see Note 10.
Devolved administrations
The agency administers certain schemes for all UK claimants. Principally these schemes comprise of the Fruit and Vegetables scheme and School Milk subsidy scheme. Where the agency makes payments to claimants outside of England these amounts are reclaimed from the associated devolved administrations in Scotland, Wales and Northern Ireland.
This income is recognised by the agency when it is probable that it will receive a reimbursement from the devolved administration for scheme expenditure incurred and the amount to be received is considered reliably measurable. These conditions are deemed to be met at the point the related scheme expenditure is recognised. The income is presented in Note 5.
1.6 Value Added Tax (VAT)
Defra and its agencies share a single VAT registration and most activities are outside the scope of VAT, so input VAT is usually not recoverable. Under a HM Treasury concession, some VAT on specific contracted-out services can be reclaimed. For activities where output VAT is charged, related input VAT can be recovered under normal rules.
Amounts in the Statement of Comprehensive Net Expenditure are shown net of VAT where input VAT is recoverable, with the VAT being recognised in the Statement of Financial Position. Amounts in the Statement of Comprehensive Net Expenditure are shown inclusive of VAT where VAT is not recoverable.
1.7 Foreign currency transactions
The functional and presentational currency of the agency is sterling.
1.8 Trade receivables
Receivables mainly relate to amounts due from other government bodies and customers under the agency’s schemes. They are treated as financial assets under IAS 32. The agency’s model is to collect principal (and interest if applicable), and most large receivables are from public sector entities with very low risk of default. Income is recognised when the performance obligations are satisfied.
Receivables are measured at fair value and held at amortised cost, which is the invoiced amount less any expected credit loss provision.
1.9 Pensions
Employees are covered by 4 defined benefit schemes Principal Civil Service Pension Scheme (PCSPS) and 1 career-average scheme (Alpha), explained in Note 2.2. PCSPS is a multi-employer scheme, so the agency cannot identify its share of assets and liabilities. Under IAS 19, it is treated as a defined contribution scheme, with costs recognised as contributions fall due. The agency is not responsible for other employers’ obligations.
For all schemes, the agency recognises expected pension costs over the period employees provide services, paying contributions on an accruing basis. Future benefit liabilities remain with the pension schemes. The agency does not contribute to any other pension schemes.
1.10 Provisions
Provisions are recognised when the agency has a legal or constructive present obligation from a past event, it is probable that the agency will need to settle that obligation, and the amount can be reliably estimated.
The agency’s provision for delinked payments is measured at the best estimate of the cost to settle the obligation at the reporting date, considering risks and uncertainties. This provision is measured at present value using discount rates issued by HM Treasury. Delinked payments replaced the Basic Payment Scheme in England in 2024 and will reduce in value each year until these payments finish. These reductions are known as progressive reductions.
See Note 1.12(b) for further details of the estimation uncertainty associated with the provision element of delinked payments and Note 10 for details of the delinked payments values recognised within the Statement of Financial Position.
1.11 Early departure costs
The agency is required to meet the additional costs of benefits before normal retirement age in respect of employees who retire under early severance and early retirement schemes. The agency provides for this when a formal letter has been issued to the employee giving a leaving date and severance terms.
1.12 Critical accounting judgements and key sources of estimation uncertainty
a. Recoverability and useful lives of intangible assets
When capitalising software projects, the agency assesses whether costs meet accounting standard IAS 38, whether the assets will continue to provide benefits, and whether their useful lives remain appropriate.
Key factors include the expected lifespan of current schemes and whether existing software functionality will be used in future pilots or successor schemes.
b. Estimated progressive reduction rates for delinked payments
The agency recognised an expense in 2023-24 for all delinked payments through to 2027-28. These payments reduce progressively each year. Where not formally agreed by parliament management estimate future reduction rates based on available information, historical trends and events up to the date the financial statements are authorised. Assumptions are shown in Note 10.
c. Estimated value of other financial commitments
The valuation of scheme other financial commitments (OFCs) involves management judgement, as balances reflect the maximum level of funding realistically committed under existing scheme rules at the reporting date. OFCs are not forecasts of expected expenditure and do not assume full theoretical uptake. Instead, they are intended to present a meaningful assessment of the agency’s potential financial exposure in future years based on the non-cancellable period of the agreement.
Estimation uncertainty is greatest for schemes which do not have fixed agreement values, particularly the Animal Health and Welfare Programme. In these cases, management applies judgement in estimating a realistic maximum level of claims, informed by operational data and scheme rules. For schemes such as Sustainable Farming Incentive and Countryside Stewardship revenue, OFCs are largely derived from contracted agreement values held in scheme systems and are therefore subject to lower estimation uncertainty. Across all schemes, uncertainty relates to the amount and timing of future payments, rather than the existence of the obligation.
1.13 Cash and cash equivalents
Cash and cash equivalents include cash in hand and bank balances, which are readily convertible to known amounts of cash, with insignificant risk of changes in value and an original maturity of 3 months or less. The carrying amount of these assets approximates their fair value.
1.14 Corporate overhead recharge (notional)
Defra provides corporate services such as legal services, human resources, information technology, estate management and shared services (including payroll and finance). These costs are charged to the agency as notional (non-cash) amounts, while Defra retains the budgets and manages the services. The recharge is shown as an expense in the Statement of Comprehensive Net Expenditure, with an equal contribution from Defra recorded in equity. This avoids unnecessary cash transfers between the agency and Defra.
1.15 Adoption of new and revised standards
IFRS 17 Insurance Contracts became effective for accounting periods commencing on 1 April 2025. It requires a discounted cash flow approach to measuring insurance liabilities. The agency has assessed that there are no arrangements that currently fall within scope and therefore this has had no impact on the financial statements.
IFRS 18 will replace IAS 1 Presentation of Financial Statements and is effective for annual reporting periods beginning on or after the 1 January 2027 in the private sector. The impact of IFRS 18 on the public sector is still being assessed, and a decision has not yet been taken on an implementation date. The agency will continue to assess, if implemented, the impact on the financial statements.
IFRS 19 allows eligible subsidiaries to apply IFRS Accounting Standards with reduced disclosure requirements and is effective for annual reporting periods beginning on or after the 1 January 2027 in the private sector. The impact of IFRS 19 on the public sector is still being assessed, and a decision has not yet been taken on an implementation date. The agency has assessed that this, if implemented, will have no impact on the financial statements.
2. Staff expenditure
2.1 Staff expenditure comprises:
| Permanently employed staff £000 | Others £000 | 2025-26 Total £000 | 2024-25 Total £000 | |
|---|---|---|---|---|
| Wages and salaries | 90,688 | - | 90,688 | 84,637 |
| Social security costs | 11,174 | - | 11,174 | 8,458 |
| Other pension costs | 23,289 | - | 23,289 | 23,543 |
| Sub-total | 125,151 | - | 125,151 | 116,638 |
| Less recoveries in respect of secondments[footnote 26] | - | (4,417) | (4,417) | (4,707) |
| Agency staff | - | 185 | 185 | 63 |
| Contractors | - | 555 | 555 | 363 |
| Total staff expenditure | 125,151 | (3,677) | 121,474 | 112,357 |
No staff costs have been capitalised (2024-25: £Nil).
Individual contractors engaged to fill temporary or permanent vacancies, or provide additional resource are included within staff expenditure in Note 2.1 above. Where firms have been engaged to provide services they are not considered to be employees and are excluded from staff expenditure in Note 2.1 and are reflected within non-IT professional services in Note 3.
2.2 Pension schemes
The agency makes contributions to the following pension schemes. In 2025-26, employers’ contributions of £23.1 million were payable to the Principal Civil Service Pension Scheme, PCSPS (2024-25: £23.3 million) at 28.97% of pensionable earnings. The Scheme Actuary reviews employer contributions usually every 4 years following a full scheme valuation. The contribution rates are set to meet the cost of the benefits accruing during 2025-26 to be paid when the member retires and not the benefits paid during this period to existing pensioners.
The scheme actuary valued the PCSPS at 31 March 2020. Any changes required to employer rate contribution rates from the next actuarial valuation will be implemented from 1 April 2027. Further details are available in the Cabinet Office Civil Superannuation Annual Account.
Employers’ contributions of £252k (2024-25: £238k) were paid to the Legal & General Mastertrust stakeholder pension provider. Employer contributions are age-related and range from 8% to 14.75%. Employers also match employee contributions up to 3% of pensionable earnings. In addition, employer contributions of £8.5k (2024-25: £8.1k), 0.5% of pensionable pay, were payable to the PCSPS to cover the cost of the future provision of lump sum benefits on death in service or
ill-health retirement of these employees.
Contributions due to the partnership pension providers at the Statement of Financial Position date were £26.8k (2024-25: £20.6k). There were no prepaid contributions at that date.
3. Other running expenditure
| Note | 2025-26 £000 | 2024-25 £000 | |
|---|---|---|---|
| Non-cash items | |||
| Corporate overhead recharge (notional) | 64,730 | 83,381 | |
| Depreciation | 1,402 | 445 | |
| Amortisation | 6 | 21,145 | 20,531 |
| Finance lease interest | 121 | 137 | |
| 87,398 | 104,494 | ||
| Other expenditure | |||
| Accommodation | 4 | 75 | |
| Information technology (IT) costs | 2,384 | 2,831 | |
| Non-payroll staff costs | 2,250 | 2,590 | |
| Communications costs | 1,848 | 1,961 | |
| Non-IT professional services | 5,680 | 5,748 | |
| Other running costs | 32 | 134 | |
| 12,198 | 13,339 | ||
| Total | 99,596 | 117,833 |
The corporate overhead recharge (notional) comprises:
| Category of spend | 2025-26 £000 | 2024-25 £000 |
|---|---|---|
| Estate management costs | 9,726 | 8,901 |
| Information technology | 45,412 | 66,027 |
| Human resources services | 3,083 | 1,792 |
| Legal services | 593 | 567 |
| Communications | 567 | 562 |
| Shared services including payroll and financial | 5,029 | 5,197 |
| Auditors’ remuneration and expenses | 320 | 335 |
| Total | 64,730 | 83,381 |
The corporate overhead recharge is a charge made by Defra to the agency in respect of access to services and capacity procured centrally by Defra and shared between Defra and its arms’ length bodies. Defra instructs the amount of this charge annually, as well as a breakdown of the areas of spend (see table above) for which the charge is made. The apportionment of shared services costs by Defra to its arms’ length bodies, and between categories of spend, are made on a rational basis using available information, but are stated in these financial statements as a factual description of the charge made by Defra, rather than a fully accurate proxy of the underlying costs relating to the agency. For efficiency reasons, the charge is notional, meaning that it is instructed to the agency for recognition as expenditure in its financial statements without any cash consideration being exchanged within the departmental group, with the other side being recognised in the general fund.
For 2025-26, Defra calculated the corporate overhead recharge by multiplying the full year amount incurred by Defra in relation to the above items by the average of the agency’s proportion of costs for the previous 5 years with the exception of legal, which are based on actual costs incurred. For the agency, the average proportion applied for 2025-26 was 8.1%. For 2024-25 and previous years, costs were apportioned based on actual costs incurred, apportioned (where necessary) based on usage. No restatement has been made, since in both years, the agency has disclosed the actual charge made by Defra, but this information on the basis of the charge is provided in the interests of transparency.
During the year ended 31 March 2026, the agency received no non-audit services from the National Audit Office (2024-25: £Nil).
4. Running expenditure income
| 2025-26 £000 | 2024-25 £000 | |
|---|---|---|
| British Cattle Movement Service | (1,859) | (1,908) |
| Cattle passport fee income | (87) | (97) |
| Total | (1,946) | (2,005) |
The agency received income in 2025-26 for cattle movement services it provides for the devolved administrations, delivered on behalf of Defra, of £1.9 million (2024-25: £1.9 million). This income is expected to diminish in future as the devolved administrations are in the process of developing independent movement systems. Income in respect of cattle passport fees comes directly from recipients.
5. Schemes administered by the agency
| Scheme | 2025-26 Expenditure[footnote 27] £000 | 2025-26 Income £000 | 2025-26 Net £000 | 2024-25 Expenditure[footnote 27] £000 | 2024-25 Income £000 | 2024-25 Net £000 |
|---|---|---|---|---|---|---|
| Basic Payment Scheme | (649) | - | (649) | 1,651 | - | 1,651 |
| Basic Payment Scheme – delinked payments[footnote 30] | 1,940 | - | 1,940 | (487,146) | - | (487,146) |
| Countryside Stewardship – revenue[footnote 29] | 533,289 | - | 533,289 | 565,976 | - | 565,976 |
| Capital grants[footnote 29] | 242,285 | - | 242,285 | 244,479 | - | 244,479 |
| Sustainable Farming Incentive | 737,531 | - | 737,531 | 315,534 | - | 315,534 |
| Environmental Stewardship | 111,215 | - | 111,215 | 95,902 | - | 95,902 |
| Farming Recovery Fund | (454) | - | (454) | 58,888 | - | 58,888 |
| Farming Equipment and Technology Fund | 33,994 | - | 33,994 | 57,961 | - | 57,961 |
| Fruit and Vegetables | 40,494 | (2,230) | 38,264 | 44,190 | (3,668) | 40,522 |
| Farming Transformation Fund | 27,905 | - | 27,905 | 14,950 | - | 14,950 |
| Animal Health and Welfare Programme | 2,970 | - | 2,970 | 2,016 | - | 2,016 |
| School Milk | 4,626 | (2,776) | 1,850 | 5,463 | (3,584) | 1,879 |
| Other schemes[footnote 31] | 3,723 | - | 3,723 | 5,191 | - | 5,191 |
| Total UK Funded schemes | 1,738,869 | (5,006) | 1,733,863 | 925,055 | (7,252) | 917,803 |
| Total EU Funded schemes | - | - | - | (536) | (111) | (647) |
| Realised exchange gain | - | - | - | - | (637) | (637) |
| Unrealised exchange gain | - | (2) | (2) | - | (338) | (338) |
| Cost of hedging contracts | - | - | - | - | (3,880) | (3,880) |
| Sustainable Farming Incentive special payments | 3 | - | 3 | 2,992 | - | 2,992 |
| Other scheme related costs[footnote 28] | 2,115 | (449) | 1,666 | 667 | (1,465) | (798) |
| Total of other costs | 2,118 | (451) | 1,667 | 3,659 | (6,320) | (2,661) |
| Total Scheme expenditure/(income) | 1,740,987 | (5,457) | 1,735,530 | 928,178 | (13,683) | 914,495 |
6. Intangible assets
2025-26 Information Technology Software
Cost or Valuation
| Description | Information Technology Software (£000) | Development Expenditure (£000) | Total (£000) |
|---|---|---|---|
| At 1 April 2025 | 361,359 | 49 | 361,408 |
| Additions | 704 | 704 | |
| Disposals | (1,015) | (1,015) | |
| Transfer from Defra | 18,772 | 18,772 | |
| Reclassifications | 49 | (49) | - |
| At 31 March 2026 | 379,165 | 704 | 379,869 |
Amortisation
| Description | Information Technology Software (£000) | Development Expenditure (£000) | Total (£000) |
|---|---|---|---|
| At 1 April 2025 | 305,132 | 305,132 | |
| Charged in year | 21,145 | 21,145 | |
| Disposals | (1,015) | (1,015) | |
| At 31 March 2026 | 325,262 | 325,262 |
Net Book Value
| Description | Information Technology Software (£000) | Development Expenditure (£000) | Total (£000) |
|---|---|---|---|
| At 1 April 2025 | 56,227 | 49 | 56,276 |
| At 31 March 2026 | 53,903 | 704 | 54,607 |
Asset Financing
| Description | Information Technology Software (£000) | Development Expenditure (£000) | Total (£000) |
|---|---|---|---|
| Owned | 53,903 | 704 | 54,607 |
| Net book value at 31 March 2026 | 53,903 | 704 | 54,607 |
2024-25 Information Technology Software
Cost or Valuation
| Description | Information Technology Software (£000) | Development Expenditure (£000) | Total (£000) |
|---|---|---|---|
| At 1 April 2024 | 196,450 | 210 | 196,660 |
| Additions¹ | 53 | 53 | |
| Disposals | (252) | (252) | |
| Transfer from Defra[footnote 32] | 146,279 | 146,279 | |
| Reclassifications | 214 | (214) | - |
| Revaluations | 18,668 | 18,668 | |
| At 31 March 2025 | 361,359 | 49 | 361,408 |
Amortisation
| Description | Information Technology Software (£000) | Development Expenditure (£000) | Total (£000) |
|---|---|---|---|
| At 1 April 2024 | 150,080 | 150,080 | |
| Charged in year | 20,531 | 20,531 | |
| Disposals | (252) | (252) | |
| Transfer from Defra | 122,758 | 122,758 | |
| Revaluations | 12,015 | 12,015 | |
| At 31 March 2025 | 305,132 | 305,132 |
Net Book Value
| Description | Information Technology Software (£000) | Development Expenditure (£000) | Total (£000) |
|---|---|---|---|
| At 1 April 2024 | 46,370 | 210 | 46,580 |
| At 31 March 2025 | 56,227 | 49 | 56,276 |
Asset Financing
| Description | Information Technology Software (£000) | Development Expenditure (£000) | Total (£000) |
|---|---|---|---|
| Owned | 56,227 | 49 | 56,276 |
| Net book value at 31 March 2025 | 56,227 | 49 | 56,276 |
Included in intangible assets are assets with a deemed historic cost of £35.6 million (31 March 2025: £36.2 million) which have been fully amortised. These assets are still in use by the agency.
Included in intangible assets are software assets provided by Defra to deliver rural scheme payments. These intangible assets had a historic cost of £139.0 million and at 31 March 2026 a net book value of £33.6 million, with 2 years remaining amortised life ending 31 March 2028 to coincide with the agricultural transitional plan.
During the year ended 31 March 2026, the agency had £18.8 million of intangible assets transferred from Defra through the general fund (2024-25: £23.5 million, being £146.3 million in cost less £122.8 million amortisation).
7. Trade receivables and other current assets
| Due within 1 year | 31 March 2026 £000 | 31 March 2025 £000 |
|---|---|---|
| Due from Defra and its agencies | 1,729 | 2,166 |
| Due from other government departments | 3,235 | 5,955 |
| VAT recoverable | 313 | 293 |
| Total intra-government balances | 5,277 | 8,414 |
| Trade receivables | 3,071 | 2,564 |
| Less expected credit loss for receivables | (1,070) | (1,214) |
| 2,001 | 1,350 | |
| Scheme prepayments and accrued income (see below) | 267,321 | 198,280 |
| Running cost prepayments and other receivables | 371 | 372 |
| Total other receivables | 269,693 | 200,002 |
| Total receivables | 274,970 | 208,416 |
The credit period for trade receivables invoices is nil except in those instances where an agreement is reached between the agency and the customer to allow for recovery through the interception of future payments or extended repayment terms are agreed. The agency has an ability to charge interest on overdue scheme balances.
Breakdown of scheme prepayments and accrued income
Scheme prepayments and accrued income of £267.3 million (2024-25: £198.3 million) have been recognised, which represents cash payments made to grant scheme claimants in advance of the related expenditure recognition point for the scheme and income from devolved administrations.
Prepayments
| Scheme | 31 March 2026 £000 | 31 March 2025 £000 |
|---|---|---|
| Sustainable Farming Incentive | 235,536 | 172,328 |
| Environmental Stewardship | 29,853 | 22,511 |
| Other schemes | 189 | - |
| Total prepayments | 265,578 | 194,839 |
Accrued income
| Scheme | 31 March 2026 £000 | 31 March 2025 £000 |
|---|---|---|
| Fruit and Vegetables | 1,253 | 2,532 |
| School Milk | 490 | 909 |
| Total accrued income | 1,743 | 3,441 |
Total
| 31 March 2026 £000 | 31 March 2025 £000 | |
|---|---|---|
| Prepayments | 265,578 | 194,839 |
| Accrued income | 1,743 | 3,441 |
| Total | 267,321 | 198,280 |
8. Cash and cash equivalents
| 31 March 2026 £000 | 31 March 2025 £000 | |
|---|---|---|
| Balances held at 1 April | 163,460 | 80,044 |
| Net cash (outflow)/inflow | (113,430) | 83,416 |
| Total balance - held with Government Banking Services | 50,030 | 163,460 |
Included within the cash held with Government Banking Services at 31 March 2026 are cash securities of £3.1 million (31 March 2025: £2.3 million) received from import and export traders and held by the agency within a public bank account. These are payments made to the agency to ensure these traders comply with the obligations associated with the import and export licences they have been issued. If a trader does not meet these obligations, they may forfeit these cash securities with the cash being retained by the agency.
9. Trade payables and other current liabilities
| Due within 1 year | 31 March 2026 £000 | 31 March 2025 £000 |
|---|---|---|
| Due to Defra and its agencies | 1,293 | 1,456 |
| Due to other government departments | 4,681 | 5,385 |
| Other taxation and social security | 1,869 | 1,810 |
| Total intra-government balances | 7,843 | 8,651 |
| Trade payables[footnote 33] | 43,513 | 46,701 |
| Cash securities[footnote 34] | 3,076 | 2,268 |
| Scheme accruals (see below) | 82,812 | 386,599 |
| Running cost accruals[footnote 35] | 4,913 | 2,690 |
| Other payables | 2,963 | 2,351 |
| Total other payables | 137,277 | 440,609 |
| Total payables | 145,120 | 449,260 |
The agency considers that the carrying amount of trade and other payables approximates to their fair value.
Breakdown of scheme accruals
Scheme accruals of £82.8 million (2024-25: £386.6 million) have been recognised, which represents management’s view of the most likely amounts due to individual claimants. Where possible accruals are based on internal data regarding the values of claims which have been received but are yet to be paid out. Accruals are also recognised where the agency has a reasonable expectation that claimants have fulfilled their obligations in their grant agreement where appropriate.
| Scheme | 31 March 2026 £000 | 31 March 2025 £000 |
|---|---|---|
| Basic Payment Scheme - delinked payments | 326 | 264,985 |
| Countryside Stewardship - revenue[footnote 36] | 18,064 | 56,073 |
| Capital grants | 16,485 | 21,126 |
| Fruit and Vegetables | 15,773 | 23,502 |
| Farming Equipment and Technology Fund | 20,412 | 10,742 |
| Environmental Stewardship | 7,132 | 6,246 |
| School Milk | 747 | 1,037 |
| Farming Transformation Fund | 2,838 | 920 |
| Water Restoration Fund | 689 | - |
| Sustainable Farming Incentive 2023 | - | 795 |
| Farming Recovery Fund | - | 185 |
| Other schemes | 346 | 988 |
| Total | 82,812 | 386,599 |
10. Provisions
| Scheme related provision | Delinked payments £000 | Total £000 |
|---|---|---|
| Balance at 1 April 2025 | 40,871 | 40,871 |
| Provided in the year | 3 | 3 |
| Change in discount rate | 145 | 145 |
| Unwinding of discount | 1,647 | 1,647 |
| Balance at 31 March 2026 | 42,666 | 42,666 |
HM Treasury discount rates are revised every year and notified by means of a Public Expenditure System (PES) paper. In accordance with the 2025 PES paper the agency has applied a short-term general provision discount rate of 3.64% to the agency’s delinked payments provision.
10.1 Analysis of timing of expected discounted cash flows
| Scheme related provision | Delinked payments £000 | Total £000 |
|---|---|---|
| Not later than 1 year | 21,714 | 21,714 |
| Later than 1 year and not later than 5 years | 20,952 | 20,952 |
| Balance at 31 March 2026 | 42,666 | 42,666 |
The provision for delinked payments represents management’s best estimate of the expected future payments, discounted to reflect the time value of money. Estimation uncertainty arises primarily from assumptions about future policy decisions and the progressive reduction rates. These estimates are reviewed at each reporting date and updated when additional information becomes available.
11. Financial instruments
11.1 Significant accounting policies
Details of the significant accounting policies and methods adopted (including the basis of measurement and the basis for recognition of expenditure and income) for each class of financial asset and financial liability are disclosed in Note 1.
All financial assets and liabilities are measured at amortised cost. Due to their short-term nature, the carrying amounts of trade receivables, trade payables and cash and cash equivalents are a reasonable approximation of fair value.
Included within both cash and cash equivalents, and trade payables and other liabilities above are cash securities which are provided by certain traders, see Notes 8 and 9. No interest is paid to traders on cash balances lodged with the agency as securities. These matching cash and payables balances amounted to £3.1 million at 31 March 2026 (31 March 2025: £2.3 million).
Cash on deposit at 31 March 2026 consists of money lodged with Government Banking Services and is not subject to an interest rate charge.
| Financial Guarantee Contracts not recognised in the Statement of Financial Position | 31 March 2026 £000 | 31 March 2025 £000 |
|---|---|---|
| Non-cash guarantees | 192,000 | 320,000 |
The agency issues traders with import and export licences for which a non-cash guarantee from a bank or insurance company is required to be put into place. These non-cash guarantees are assurances that guarantee payment to the agency if the trader fails to honour certain contractual obligations to the agency. They will become cash payments to the agency in the event these obligations are not fulfilled.
Most licence holders meet their obligations therefore the guarantees are not a contingent asset. Non-cash sterling guarantees totalling £157 million, and euro guarantees totalling €40 million (£35 million) were held at 31 March 2026 (£207 million and €135 million (£113 million) at 31 March 2025).
These are not included within the Statement of Financial Position since the agency assesses, based on prior experience of trader behaviour, a minimal chance of the guarantees being called upon.
11.2 Credit risk
As the agency is a UK government entity, its own credit risk is not significant.
Credit risk refers to the risk that a counterparty will default on its contractual obligations resulting in financial loss to the agency. As part of its procedures the agency periodically reviews the counterparty credit risk.
Trade receivables consist of many unrelated customers with differing credit ratings, which serves to diversify the agency’s credit risk. An ongoing credit evaluation is performed on the financial condition of accounts receivable. Receivables are measured at fair value and held at amortised cost, which is the invoiced amount less any expected credit loss provision.
11.3 Liquidity risks
The agency is funded by HM Treasury through Defra.
11.4 Liquidity tables - non-derivative liabilities and assets
The following tables details the agency’s contractual maturity for its non-derivative financial liabilities with agreed repayment periods. The table is based on the undiscounted cash flows of financial liabilities based on the earliest date on which the agency can be required to pay. The table includes both interest and principal cash flows.
Non-interest-bearing trade payables and other current liabilities as follows:
| 31 March 2026 £000 | 31 March 2025 £000 | |
|---|---|---|
| Zero - 3 months | 142,198 | 182,216 |
| 3 - 12 months | - | 264,984 |
| Total | 142,198 | 447,200 |
The following table details the agency’s expected maturity for its non-derivative financial assets. The table below is based on the undiscounted contractual maturities of the financial assets including interest that will be earned on those assets. The inclusion of information on financial assets is necessary to understand the agency’s liquidity risk management as the liquidity is managed on a net asset and liability basis.
Non-interest-bearing trade receivables and other current assets as follows:
| 31 March 2026 £000 | 31 March 2025 £000 | |
|---|---|---|
| Zero - 3 months | 7,552 | 9,999 |
| Total | 7,552 | 9,999 |
12. Capital commitments
The agency had £346k capital commitments at 31 March 2026 (31 March 2025: £Nil) relating to intangible asset investment not otherwise included in these financial statements.
13. Other financial commitments
The agency has entered into non-cancellable contracts (which are not leases or Private Finance Initiative (PFI) contracts or other service concession arrangements) for office and information technology services. Agreements have been analysed spanning the year-end and reflecting contractual cancellation clauses. The payments to which the agency is committed (not accrued for) are as follows:
| 31 March 2026 £000 | 31 March 2025 £000 (restated[footnote 36]) | |
|---|---|---|
| Due within 1 year | 2,169 | 1,256 |
| Later than 1 year and not later than 5 years | 201 | 194 |
| Total | 2,370 | 1,450 |
Scheme financial commitments
The agency has entered into non-cancellable contracts (which are not leases, PFI contracts or other service concession arrangements) for schemes payable to farmers, land managers, schools, local authorities and other organisations.
It is possible, depending on their nature, for customers in receipt of a grant funding agreement not to proceed to claim, or to claim less than the maximum agreement value. As such, actual expenditure is typically lower than the theoretical maximum value of agreements. Payment rates in grant agreements have been adjusted by published increases in payment rates since inception of the agreements through to 31 March 2026 to reflect current values.
Under the terms and conditions of certain schemes, the agency retains the right to terminate agreements by providing 3 or 6 months’ written notice. Accordingly, the commitments disclosed below reflect the agency’s contractual exposure based on these cancellation provisions at the reporting date.
The following table shows the agency’s scheme commitments (not accrued for) based on the strict terms and conditions of the scheme.
| Scheme | Within 6 months £000 | Total 31 March 2026 £000 | Within 6 months £000 | Total 31 March 2025 £000 |
|---|---|---|---|---|
| Countryside Stewardship - revenue[footnote 37] | 278,748 | 278,748 | 289,856 | 289,856 |
| Capital grants[footnote 38] | 43,288 | 43,288 | 97,404 | 97,404 |
| Environmental Stewardship | 59,275 | 59,275 | 46,755 | 46,755 |
| Sustainable Farming Incentive | 589,703 | 589,703 | 403,420 | 403,420 |
| Farming Investment Fund | 24,951 | 24,951 | 16,388 | 16,388 |
| Water Restoration Fund | 5,305 | 5,305 | 337 | 337 |
| Animal Health and Welfare Programme | 135,534 | 135,534 | 31,073 | 31,073 |
| Total | 1,136,804 | 1,136,804 | 885,233 | 885,233 |
The delivery profile for non-capital schemes is typically even over the course of the grant agreement, supporting a straightforward estimate of related non-cancellable commitments. However, in the case of capital claims, there is uncertainty about the extent of claims that would be made within a theoretical cancellation scenario, because in respect of capital agreements with more time to run than the notice period, it is uncertain how much claimants would be able to accelerate asset purchases to meet a shortened claim window. The figures in the table reflect the claims that would arise on a continuation of the normal delivery profile, since in light of the subjectivity that would be introduced by a specific assumption on potential acceleration in this theoretical scenario, this remains the agency’s best estimate of the non-cancellable commitment. For transparency, a maximum exposure scenario – envisaging the greatest possible acceleration of claims – would produce a capital grants commitments figure of £866 million (2024-25: £785 million). Management considers this a theoretical extreme, rather than a realistic estimate, of unavoidable obligations.
14. Contingent assets and contingent liabilities
14.1 Contingent assets
The agency has no contingent assets.
14.2 Contingent liabilities
The agency is subject to an ongoing judicial review relating to Basic Payment Scheme (BPS) entitlement allocation, with a potential exposure of up to approximately £800k, including associated legal costs and potential ex gratia payments. Based on legal advice, the outcome remains uncertain and no reliable estimate of any potential liability can currently be made.
The agency is also involved in a legal dispute relating to BPS payments, with an estimated exposure of approximately £230k.
15. Related party transactions
The agency, as an executive agency of core Defra, has transactions with both Defra and the following entities within Defra group:
-
Animal and Plant Health Agency
-
Livestock Information Limited
-
Environment Agency
-
Marine Management Organisation
-
Natural England
In addition, the agency has transactions with the Food Standards Agency and Forestry Commission.
As explained in Note 1.5, the agency makes payments under certain grant schemes to claimants within Wales, Scotland and Northern Ireland on behalf of the relevant devolved administrations. Amounts paid are recovered as income from the related paying agencies. The agency discloses this information for transparency, although such bodies are independent of the agency and of Defra and therefore do not meet the definition of related parties.
Disclosure of employment
Stephen Briggs became a non-executive director and board member of the agency on 1 March 2026. He operates a family farm, Bluebell Farms Ltd, which received no scheme payments for the period in which he was a board member. At 31 March 2026, the agency owed £11k to Bluebell Farms Ltd in respect of scheme payments accrued before becoming a board member. The balance arose on standard scheme terms and is unrelated to his non-executive director and board member role.
Mark Tufnell was a non-executive director and board member of the agency from 15 October 2025 until 14 February 2026. He operates a family farm, Calmsden Farms, which received scheme payments of £135k and had £46k scheme payments outstanding whilst he was a board member. These transactions were undertaken in the normal course of business and all transactions were at arm’s length.
Tim Breitmeyer was a non-executive director and board member of the agency until 31 May 2025. He runs a family farm, Bartlow Estate, which received scheme payments of £4k (2024-25: £111k) and had £6k scheme payments outstanding during the period of his board membership. These transactions were undertaken in the normal course of business, and all transactions were at arm’s length.
The non-executive directors also received salaries set out in the Remuneration report above.
During the year, Mark Tufnell and David Lyall were interim non-executive directors of the agency from 15 October 2025 until 14 February 2026 during which time they also served as non‑executive directors of other Defra arm’s‑length bodies. Their combined remuneration totalling £9k relating to services provided to the agency was initially paid by those bodies and recharged to the agency.
At the year end, these amounts were included within amounts due to Defra and its agencies in Note 9.
16. Events after the reporting period
These financial statements have been authorised for issue by the Accounting Officer on the date the Comptroller and Auditor General’s audit certificate and report was signed.
On 29 June 2026, the Agriculture (Delinked Payments) (Reductions) (England) Regulations 2026 Statutory Instrument (SI) 599 came into force. This confirmed no change to the progressive reduction rates previously applied for 2026 and 2027 and therefore did not change the expected value of future payments under the delinked payments scheme. The agency considers that the approval of the SI as the trigger point for changing the recognition of its obligation from a provision to an accrual as there is more certainty. As this event occurred after the end of the 2025-26 financial year, the agency has recognised the liability as a provision in 2025-26 and will reclassify this liability to accruals in 2026-27.
On 1 April 2026, 64 staff (61.57 full-time equivalents) transferred from the agency to Defra. These staff had been working primarily for Defra during 2025-26, with associated staff costs recharged to Defra, see Note 2. This event does not affect the financial performance or position of the agency at 31 March 2026.
-
Performance was affected by the early-stage operation of a large-scale scheme. ↩
-
2024-25 restated to be a consistent comparison. ↩
-
2024-25 restated due to incorrectly including pet travel helpline calls ↩
-
Scope 1 and Scope 3 greenhouse gas emissions, together with gas consumption comparatives, have been restated to reflect the inclusion of refreshed data received after the original reporting period. ↩
-
Baseline 2017-18 electricity consumption was not classified as non-renewable or renewable. ↩ ↩2
-
The agency’s activities are predominantly office based, and water consumption reported is for the agency’s direct water costs only and does not include indirect water consumption which is considered to not be materially relevant. ↩
-
The agency’s water supply costs are included within corporate overhead recharge (notional), within estate management costs, see Note 3. ↩
-
There were no ultra-low emission vehicles or electric vehicles in the agency’s fleet in the baseline year. ↩ ↩2
-
Paul Caldwell stepped down as Chief Executive Officer on 11 June 2025 and formally left the agency on 31 July 2025. Neil Hornby joined the agency on 2 June 2025, taking over as Interim Chief Executive Officer after Paul Caldwell stepped down, until Oliver Munn joined the agency as Chief Executive Officer on 12 January 2026. Neil Hornby formally left the agency on 31 January 2026. Overlapping dates reflect planned handover and transition arrangements. ↩ ↩2 ↩3
-
David Lyall and Mark Tufnell acted as interim non-executive directors from 15 October 2025 until 14 February 2026. ↩ ↩2
-
No bonus was paid to the highest‑paid director in 2025-26 due to the individual joining the agency during the financial year. ↩ ↩2
-
Full‑year equivalent (FYE) represents the annualised total, assuming the individual was in post for the full year. ↩ ↩2 ↩3 ↩4 ↩5 ↩6 ↩7 ↩8 ↩9 ↩10 ↩11 ↩12 ↩13
-
David Lyall and Mark Tufnell acted as interim Non-Executive Directors from 15 October 2025 until 14 February 2026 during which time they also held appointments with other Defra group arm’s‑length bodies. Their remuneration relating to services to the agency was paid by those bodies and subsequently recharged to the agency. The amounts disclosed above represent the full remuneration earned in respect of services provided to the agency. ↩ ↩2
-
Bonus payments to Rural Payments Agency’s board members are approved at Defra group level by the Defra Remuneration Committee and paid where exceptional performance has been clearly demonstrated. The bonuses awarded are not part of any performance related contractual obligations but reflect what Defra group deem to be a reasonable payment for this exceptional performance. Consequently, the bonuses are not awarded based on any specific formula. The bonuses reported in 2025-26 relate to performance in 2024-25. ↩
-
During 2025-26 the agency ran a voluntary exit scheme where individuals were invited to apply to leave civil service employment on a voluntary basis and receive a compensation payment paid in accordance with the provisions of the Civil Service Compensation Scheme, a statutory scheme made under the Superannuation Act 1972. Prior year disclosures have been reviewed and one director voluntary exit payment was agreed in March 2025 and omitted from the 2024-25 Remuneration and staff report. This amount is included within the table above. ↩
-
The value of pension benefits accrued during the year is calculated as (the real increase in pension multiplied by 20) plus (the real increase in any lump sum) less (the contributions made by the individual). The real increases exclude increases due to inflation or any increases or decreases due to a transfer of pension rights. ↩
-
Full‑year equivalent (FYE) represents the annualised total, assuming the individual was in post for the full year. ↩ ↩2 ↩3 ↩4 ↩5 ↩6
-
Dan Gilbert, Sophia Haughton and Mike Rowe are employees of Defra. Janet Hughes was also an employee of Defra in 2025-26. ↩ ↩2 ↩3 ↩4
-
Bonus payments to Rural Payments Agency’s Board members are approved at Defra group level by the Defra Remuneration Committee and paid where exceptional performance has been clearly demonstrated. The bonuses awarded are not part of any performance related contractual obligations but reflect what Defra group deem to be a reasonable payment for this exceptional performance. Consequently, the bonuses are not awarded based on any specific formula. The bonuses reported in 2024-25 relate to performance in 2023-24. ↩
-
The value of pension benefits accrued during the year is calculated as (the real increase in pension multiplied by 20) plus (the real increase in any lump sum) less (the contributions made by the individual). The real increases exclude increases due to inflation or any increases or decreases due to a transfer of pension rights ↩
-
Full‑year equivalent (FYE) represents the annualised total, assuming the individual was in post for the full year. ↩ ↩2 ↩3
-
Dan Gilbert and Sophia Haughton are employees of Defra. Janet Hughes is an employee of the Food, Biosecurity and Trade Group. Jessie Peramal was also an employee of Defra group corporate services until 8 July 2024 and opted out of the pension scheme from 2023-24. ↩ ↩2 ↩3 ↩4
-
Mark Ashenden and Dan Gilbert’s CETV at 31 March 2025 has been restated due to last year’s PCSPS being understated. ↩ ↩2
-
See explanation within the change in presentation of scheme irregularity disclosures section above. Note that the significant year‑on‑year variation in the capital grants irregularity rate is not attributable to the change in presentation, nor to differences in the underlying schemes included within this heading. By their nature, capital grant schemes can give rise to a small number of high‑value irregular cases. Consequently, the estimated irregularity rate is subject to significant year‑on‑year volatility due to statistical (sampling) variation rather than underlying changes in performance. ↩ ↩2 ↩3 ↩4
-
Recovery of staff costs relates primarily to staff who were seconded to Defra. ↩ ↩2
-
Negative expenditure includes recoveries for historic schemes where payments have substantially ceased. ↩ ↩2
-
The estimated full liability for delinked payments was recognised in 2023-24. This was based on estimated progressive reduction rates. In October 2024, the Minister of State confirmed the 2025 progressive reduction rate would be greater than the previous assumption and estimated rates for 2026 onwards were also increased accordingly. These were subsequently reassessed in June 2025. The liability was therefore reassessed and reduced resulting in the inclusion of a credit within the amount as reported in 2024-25 above. ↩
-
The 2024-25 balance has been represented between Countryside Stewardship - revenue and Capital grants with the total agreeing to the 2024-25 published annual report and accounts. ↩ ↩2
-
The prior year comparative figure for ‘Other schemes’ (2024-25: £5.2 million) comprised a number of individually immaterial scheme lines which have been aggregated in the current year presentation for clarity. There is no impact on total scheme expenditure. ↩
-
Other scheme related costs include recoveries payable to the European Agricultural Fund for Rural Development, losses, special payments, legal fees, and movements in the expected credit losses for receivables. ↩
-
£15,936k of information technology software transferred from Defra in 2024-25 was shown as additions in the 2024-25 annual report and accounts. ↩
-
Trade payables principally comprise amounts outstanding for claims to be paid to customers. ↩
-
Traders wishing to undertake certain transactions are required to guarantee completion of the transaction by lodging a security with the agency. The security may be forfeited (in whole or in part) if the undertaking is not completely fulfilled. The security received is included within cash, see Note 8, with the corresponding liability with the trader shown above. ↩
-
Running cost accruals includes accumulated staff absences that increased at 31 March 2026 mainly due to methodology changes. ↩
-
Prior year has been restated due to being previously understated. ↩ ↩2
-
Comparative figures have been re-presented for clarity. Countryside Stewardship was previously disclosed as a single line item of £387,260k; this has been split between “Countryside Stewardship - revenue” and “Capital grants” with no impact on the total. ↩
-
The commitments disclosed for capital grants above represent management’s best estimate of expenditure that is unavoidable at the reporting date, reflecting the expected timing of claim crystallisation based on scheme rules, contracted delivery profiles and operational constraints. This approach is consistent with the FReM requirement to disclose non‑cancellable commitments not recognised in the financial statements and takes into account a contractual notice period (typically six months) for grant agreements. ↩