High-growth firms
Published 27 August 2026

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/publications/high-growth-firms/high-growth-firms
Executive summary
Context and background
Rapidly growing businesses are drivers of economic development, job creation, and innovation in the UK. These high-growth firms, or ‘scale-ups’, generally identified by rapid expansion in revenue and/or employment, are a small subset of businesses but play an outsized role in overall economic growth. These firms are often disruptors, bringing dynamism through innovating in business models, technologies and product development.
Understanding the dynamics and characteristics of high-growth firms is essential, not only for identifying the factors that enable significant and sustained growth, but also for informing effective policy interventions and support mechanisms.
The importance to the economy of firms scaling-up through achieving sustained high growth rates is well recognised. The policy challenges require continuing to deepen our understanding and coordinate effectively across organisations and government. The ScaleUp Institute, which sits on the CMA’s Growth and Investment Council, has been a leader in developing understanding of high-growth firms including on the challenges they face, their characteristics and the policy implications. It has done this through tracking the recommendations made in the inaugural Scale-Up report in 2014 and publishing extensive research on scale-ups in the UK, including on drivers of local scaleup growth (ScaleUp Institute, 2020). There has been progress, with improved ranking for the UK on a range of metrics covering scale up growth, number and density (ScaleUp Institute, 2025). We are grateful for the ScaleUp Institute’s input and support in preparing this report. We are also grateful to members of the CMA’s academic panel and numerous colleagues in government for their feedback.
Extensive previous research by the ScaleUp Institute (for example, 2025) and others (such as Haltiwanger et al., 2013 and Criscuolo et al., 2014) has shown the substantial contribution of high-growth firms to the economy. Previous research (in academic literature summarised in Hamilton and Ng, 2025, and in ScaleUp Institute Annual Reports) has also explored the number of high-growth firms; the distribution of high-growth firms by geography and sector; their financing, barriers, drivers and predictors of their growth; and a wide range of other characteristics. Across many areas, the CMA’s research in this report reinforces much of this evidence and explores additional dimensions. We reference relevant literature and other research and discuss how our findings align throughout the chapters of this report.
With industrial strategy taking on increasing prominence, including in its focus on scale-ups, this evidence base becomes even more relevant. It is important that markets and competition work to reward innovation, effort and creativity. As government seeks to use a wider set of policy levers to support growth and resilience, understanding how and when high‑growth firms emerge, scale and generate value becomes central. The challenge is not simply to identify such firms, but to design interventions that support scaling in ways that deliver lasting economic benefits for the UK.
This report is published to contribute to the existing body of evidence and explore additional dimensions, particularly regarding the relationship between high-growth firms and supply chains. Our report is therefore intended to be useful for policy makers and researchers in furthering understanding of high-growth firms and showing the value and future potential of some alternative data sources when examining these firms.
Summary of our main findings
We combine analysis of traditional firm-level microdata with more experimental data sources to advance our understanding in the following key areas:
-
we synthesise different definitions of high-growth firms used elsewhere and show how the choice of definition matters for policy making and affects our understanding of this cohort of firms and their characteristics
-
we explore the trajectories of high-growth firms, the nature of their growth episodes, and what happens following an initial period of high growth
-
we test whether some observable characteristics of high-growth firms differ from the rest of the business population before, during and after periods of high growth
-
we use experimental financial transactions data to explore firm-level supply chains and networks and investigate how these differ for high-growth firms
-
we examine to what extent experimental web data on certain categories of firms’ public announcements, which we refer to as growth signals, can offer a complementary approach to identifying high-growth firms
This research report is part of the Microeconomics Unit’s ongoing Growth Programme, supporting the government’s focus on driving economic growth and its modern industrial strategy by delivering economic research focussed on critical drivers and blockers of economic growth, alongside other work set out in our response to the Industrial Strategy Green Paper (CMA, 2024). This work includes other advice to government on issues of competition and growth. We are working with Ministry of Defence on how it can leverage increased defence spending to support competition and dynamism in the defence sector. In our market study on civil engineering, the CMA made recommendations to government on regulatory and procurement reforms which would help encourage challenger firms to enter and scale in the sector, contributing to greater dynamism.
This paper builds on our literature review “Investment and competition over the business lifecycle” (CMA, 2025), examining the existing economic research on the role that competition plays in driving investment across the lifecycle of firms, including as they seek to scale up. It also contributes to the CMA’s ongoing work on the role of competition policy in supporting UK scale ups, following our discussion paper on this topic (CMA, 2025).
High-growth firms in ONS microdata
We start by identifying and exploring the characteristics of high-growth firms in the UK using the population we can identify from Office for National Statistics (ONS) firm-level administrative and survey data.
Different definitions highlight different cohorts of firms.
High-growth firms have been defined in different ways in the literature, measuring growth on different dimensions (employment or turnover), with different thresholds and with absolute or relative measures of high growth. Our analysis focuses on a subset of these to illustrate these differences and finds that the choice of definition is important and affects the size of the cohort described as high growth.
We note that relative definitions, such as those based on the top decile of the growth rate distribution, tend to capture a wider set of firms. In contrast, the often-used definitions by the Organisation for Economic Co-operation and Development (OECD) identify a smaller group of firms – those growing employment or revenue by at least 20% per year over a 3-year period and starting that period with at least 10 employees. Firms meeting the OECD definitions are likely to grow quickly across multiple dimensions, growing both turnover and employment at significantly higher rates than average. We have focussed our subsequent analysis on firms meeting the OECD definitions, whilst noting whether a different definitional choice has a material impact on the results.
As well as making an outsized contribution to turnover and employment, high-growth firms are associated with stronger overall growth in their industry
By definition, high-growth firms grow faster than the wider economy, but we find that the gap is material across multiple dimensions. As a result, a relatively small number of firms account for a disproportionate share of overall growth, employment and turnover. This concentration underlines their importance in policy terms. We also find substantial variation in performance and growth rates within the set of firms defined as high growth, with a small number of extremely fast-growing businesses.
Understanding high-growth firms is especially important as they tend to be associated with high-growth industries, with causality likely running in both directions. Importantly, we find that having more high-growth firms in an industry is associated with faster average growth rates amongst other firms. Fast-growing firms support growth in other firms, through beneficial competitive dynamics (as high-growth firms challenge incumbents or prompt others to compete to match their growth) or other positive spillover effects (such as innovations being adopted across an industry). And growing industries support growth across firms, whilst providing greater scope for some firms to grow more quickly.
High-growth firms are present across the firm age and size distribution
On average, we find that firms reach their first high-growth period a little under 8 years old (for employment) or a little over 10 years old (for turnover). Under some distribution-based definitions, the proportion of high-growth firms declines with age, whereas under the OECD definitions this proportion is more constant.
High growth firms are spread across large, medium and small size categories, implying that we should not just look at the small firms category to understand growth dynamics.
High-growth firms are different in terms of certain observable characteristics, though these characteristics do not seem to be associated with the likelihood of becoming high growth.
Firms experiencing high growth display higher average investment levels, better management scores, higher cost markups and a higher average number of establishments (individual sites). This holds irrespective of the high-growth definition used.
However, when considering the timing of growth episodes and controlling for factors such as industry and year, we find limited evidence that observable firm characteristics are closely associated with the onset of high-growth episodes.
This suggests that the observed characteristics might be persistent features of certain types of firms (for example, higher investment is likely associated overall with expansion) rather than changes in these characteristics being drivers of high-growth episodes. Therefore, we cannot conclude on the basis of this analysis that the characteristics we have examined provide a basis for predicting future growth.
Fast growth is episodic, even amongst the minority of firms that experience high growth
The proportion of firms that experience at least one episode of high growth varies significantly between definitions. We find that around 40% of firms meet a distribution-based relative definition at some point (these tend to capture a broader set of firms), but less than 5% meet the tighter OECD-style definitions based on absolute growth rates.
The average high-growth firm spends only a small part of its life, around 15%, growing fast – though with some variation between sectors. Most firms that experience an initial year of high growth go on to meet a high-growth definition again in future years, often, but not necessarily, in the immediately following year.
Across all definitions, high-growth years are often clustered together and the average duration of a continuous period of growth is 4.5 years. These periods of continuous fast growth are relatively infrequent, with only 20 to 30% of high-growth firms experiencing more than one.
High growth in one period is a strong predictor of both the likelihood and the nature of growth in subsequent periods
The type of growth that firms first experience is instructive about how they will grow in future. Firms are most likely to continue growing along the same dimension (for example firms that are high growth in turnover are more likely to grow turnover than employment in subsequent years).
A special category of high-growth firms satisfies the OECD micro definition – starting with less than 10 employees and adding at least 8 over a 3-year period. By construction, these are smaller firms, which often only meet this definition once since they quickly grow above the initial employment threshold required to classify as micro. The vast majority of firms coming out of an OECD micro growth period keep growing substantially, though only a minority immediately meet a further high-growth definition: more than 80% of the firms that we still observe in the following year experience positive employment growth, with around 17% of firms graduating to meet the standard OECD employment definition. This is a substantially greater rate of becoming high growth than for the business population overall which indicates that identifying fast growing small businesses could be a good predictor of their future growth potential.
In sum, our analysis of ONS microdata is generally consistent with findings from previous research and re-emphasises the importance of high-growth firms to the economy. We show that high-growth firms are systematically different from other firms. However, from the characteristics we have examined, we do not find robust evidence that these are able to predict the likelihood of a firm becoming high growth in future. On the other hand, we do find that an initial period of high growth is a strong predictor of future growth.
Further insights into high-growth firms from experimental financial transactions and web data
We have supplemented our analysis using ONS microdata described above with 2 more experimental sources (financial transactions and web data) that enrich our understanding of high-growth firms. We discuss insights from these data sources in turn.
High-growth firms have different supply networks, pre-growth financial connections to government and more stable revenue
We develop experimental insights describing the supply networks of high growth firms and their financial relationships with government and financial institutions. We produce this from interbank transactions data in a collaboration with ONS and their partners Pay.UK and Vocalink, who respectively operate and provide infrastructure to the UK’s retail interbank payment systems. Account-level transactions are processed by Vocalink and provided to us by Pay.UK and ONS on an anonymised and aggregated basis, according to our research specifications. This allows us to map the UK supply network, with a specific focus on high-growth firms. The outputs describe supply networks as patterns of suppliers and customers to which each firm is connected, based on payments sent to and received from other organisations.
As this analysis is experimental, we are mindful of potential limitations in interpreting the results. For example, we cannot easily distinguish between different types of flow from the same source – such as whether a financial flow from government represents a grant or a payment for goods or services, or the different types of financing flowing from financial institutions. Our results provide novel insights, but we regard them as suggestive rather than conclusive, and indicative of potentially fertile areas for future research.
We find that high-growth firms’ supply networks display distinct patterns compared to those of other firms. During a period of growth, high-growth firms tend to have more partners upstream (sellers) and fewer downstream (buyers) than the average firm. Their supply chains are also less concentrated on average, indicating a greater diversity of buyers and sellers. At the same time, high-growth firms have deeper relationships (as measured by the share of financial flows) with their largest buyer and seller.
These supply network characteristics evolve before and during a period of high growth and are also associated with differences in the likelihood of entering a future period of high growth. For instance, higher initial seller and buyer concentration is associated with an increased likelihood of entering a period of future growth, but as firms become high growth this concentration reduces. Importantly, an examination of young firms suggests some differences in these patterns: we find that lower seller and buyer concentration is positively associated with the likelihood of becoming high growth at any future point. In addition, a wider base of trading partners is also associated with a higher likelihood of these young firms becoming high growth.
The data also allows us to examine 2 special categories of inflows: payments from government and financial institutions.
Firms starting a high-growth episode do not seem to receive a substantially different share of their inflows such as grants or contracts from the government compared to the average firm. However, firms with a higher share of central government revenue in the previous year are more likely to start a high-growth episode the following year. This holds after controlling for industry, firm and macroeconomic trends. On average, these firms reduce their dependence on government payments after becoming high growth. This suggests that, once growth takes off, successful firms diversify their customer base and increase their turnover from the private-sector, not remaining reliant on financial flows from government to sustain growth.
Our analysis also shows that high-growth firms tend to receive a higher share of their inflows from financial institutions before the onset of high growth. This share then falls during a period of high growth and, on average, accounts for a smaller share of inflows for high-growth firms than for non-high-growth firms. These results may reflect that securing finance is an important precursor to future and sustained growth.
Finally, we find that high-growth firms have on average less volatile revenue than non-high-growth firms. Firms have more volatile revenue before becoming high growth, then experience a fall in their revenue volatility over time. This suggests that the observed changes in volatility may reflect a period of adjustment as firms move into a period of high growth, and this is likely to be an effect of growth rather than a cause.
Overall, our experimental analysis of financial data describes how supply networks of high-growth firms are systematically different from other firms and suggest areas for further research to understand the causes and implications of these differences.
Complementing traditional data sources with experimental data on growth signals
The use of traditional firm-level data to identify high-growth firms may have some limitations. For example, the definitions are normally based on turnover and employment data and, in addition to being observed with a lag, these data might not capture earlier signals of growth. Given this, some researchers and other institutions have looked to non-traditional data sources, such as data derived from company websites, to understand growing business.
In this report, we explore if web data on public announcements that firms make can offer a complementary approach to identifying and tracking high-growth firms. We use an experimental dataset created by crawling online sources to collect a range of these announcements based on information on company websites and other online sources. The announcements we look at include collaborative partnerships and external relationships; market entry, expansion or product development; capital raising activity; and hiring and workforce expansion. In our analysis, we refer to the announcements we examine as growth signals, as they could indicate that a given firm is growing or intends to grow.
Our findings suggest that firms that issue growth signals are systematically different from firms that do not. On average, signalling firms are larger, in terms of employment, than non-signalling firms. Also, firms displaying investment signals are considerably larger, than those displaying other signal types (hiring, entry and innovation, and collaboration), and firms displaying multiple signal types also tend to be larger firms.
Importantly, signalling firms are not only large but also grow their employment faster than non-signalling firms and they create more and destroy fewer jobs than their size would suggest. Among signalling firms, those with investment or hiring signals, or displaying a wider variety of signals, grow the fastest.
There is some overlap between signalling firms and more traditional categories of high-growth firms. Specifically, firms we would normally identify as high growth are more likely to display signals than the average firm, and, on average, they emit more signals than the average signalling firm. There is also evidence, consistent with other research on activities of high-growth firms, that these high-growth firms are more likely to emit hiring, investment and collaboration signals than non-high-growth firms that produce signals.
Data limitations do not allow us to say if the activities captured by signals are drivers of the observed growth and potentially predictors of future performance. However, the results in this report support a potential role for web data on growth signals to complement more traditional data sources, especially in sectors where these signals are more prevalent, to help identify fast growing businesses in a timelier way and potentially capturing businesses that would not be included in more traditional data sources.
Applications to policy and further work
The findings in this report contribute to the existing body of evidence and provide further insights to deepen our understanding of high-growth firms and the important role they play in overall economic growth. The analysis has a range of potential applications to policy concerning business growth:
-
we show that experimental data sources can provide a useful complement to other measures and suggest further work that could deepen understanding of high-growth firms. Our analysis of financial transaction data shows how supply networks differ for high-growth firms and suggests areas for further analysis to explore the drivers and effects of these differences. Our analysis of web data shows that growth signals can help to identify fast growing firms, especially those that may not be captured by definitions based on turnover and employment growth. Further work, with data available for a longer period, could explore the future growth trajectory of firms displaying these growth signals. This could also be combined with data sources on other aspects of growth such as investment, market access and sourcing of inputs
-
our analysis of the supply networks of high growth firms highlights 4 specific considerations. First, the importance of designing policies to improve access to customers or suppliers and enable the diversification of a firm’s network as it grows. Second, the importance of key relationships, and understanding whether large incumbents, platforms or public-sector buyers create opportunities or bottlenecks for smaller high-growth firms. Third, the role of competition policy in enabling effective competition where high-growth firms depend heavily on a few major counterparties. Fourth, the need to understand where effects may differ for young firms and adapt approaches accordingly
-
our research implies that simple metrics will underestimate the differences between the types of firms which go through high-growth periods. This implies that policy intending to target high-potential firms requires an exercise of judgement across a range of evidence, which the analysis in this report may help inform alongside sector knowledge
-
there are a range of different definitions which capture quite different sets of firms. As selecting the definition of high-growth firms has implications for the number and type of firms captured, the definition used to identify the firms of interest should be carefully considered depending on the relevant policy goal and context
-
there is scope to track the prevalence of high-growth firms in different policy areas to further our understanding of the drivers of growth. In sectors where government has a larger direct role in determining firm growth, this could include assessing whether high-growth firms are developing wider commercial relationships, rather than measuring success solely through revenues or employment generated by continuing public expenditure. Observing the relationships between government procurement and fast growth in more detail and, hence, extending our initial analysis in this report of aggregate financial flows from government, would be a good example of this
Introduction
High-growth firms are critical to economic growth
A range of economic research has sought to improve the understanding of high-growth firms. A substantial body of evidence finds that a small number of fast-growing firms account for a disproportionately large share of net job creation and output growth, far exceeding what their numbers alone would suggest. Anyadike-Danes et al. (2009) is an early example in the UK literature, documenting that around 6% of UK firms with 10 or more employees generated over half of all net employment growth. Using US data, Haltiwanger et al. (2013) show that young firms, especially start-ups and firms in their first few years, are the primary source of net job creation in the US economy. Criscuolo et al. (2014) confirm this result across 18 countries. Recently, Hamilton and Ng (2025) have brought this evidence together in a comprehensive and systematic review of the literature on high-growth firms.
A number of organisations have contributed to the evidence base on high-growth firms in the UK, including the Enterprise Research Centre (ERC), Nesta, the Office for National Statistics (ONS), the ScaleUp Institute and the Organisation for Economic Co-operation and Development (OECD). This research has examined the prevalence, characteristics and economic contribution of high-growth firms, alongside the factors associated with firm growth and scaling, helping to improve understanding of the role these firms play in innovation, productivity, employment and economic growth.
The Scale-Up Report on UK Economic Growth (Coutu, 2014), argued that while the UK was highly successful at creating start-ups, it was less effective at helping firms scale, and recommended a coordinated national effort to support high-growth businesses. Since then, the ScaleUp Institute has produced extensive analysis on high-growth firms, including their substantial contribution to the UK economy; their distribution by geography and sector; their financing; barriers, drivers and predictors of their growth; and a wide range of other characteristics (see, for example, ScaleUp Institute, 2025).
In this report, we first explore the population of high-growth firms in the UK under different definitions, the trajectories their growth follows and the influence of their characteristics on future growth paths. We produce this analysis using the ONS firm-level administrative and survey data.
We then supplement this analysis by exploring 2 alternative and experimental data sources to understand the additional perspective they can bring to our understanding of high-growth firms:
-
we set out analysis using firm-to-firm financial transactions data to examine links between firms and other organisations based on payment flows between them
-
we explore a dataset of ‘growth signals’ – indicators of firm activity collected from publicly available online sources that may help identify current or future growth. We explore the characteristics of firms displaying these signals, and whether these signals provide a complementary way of understanding firm growth
High-growth firms in the UK
In this chapter, we complement the existing analysis of high-growth firms produced by other organisations (such as the Enterprise Research Centre, Nesta, the Organisation for Economic Co-operation and Development (OECD), the ScaleUp Institute and others).
We rely on traditional UK firm-level microdata, provided by the Office for National Statistics (ONS), to explore:
-
how different definitions of high-growth firms compare and overlap
-
the contribution of high-growth firms to employment, turnover, and wider economic growth
-
high-growth firms’ demographic characteristics, including their age and size profiles
-
how firm-level characteristics differ before, during and after a high-growth episode
-
the persistence of high growth and the trajectories that firms follow over time
We find that different definitions capture different cohorts of firms, but the widely used OECD definitions are effective in identifying a small subset of firms growing rapidly across multiple dimensions. Furthermore, and irrespective of the definition, high-growth firms make a substantial contribution to growth, employment and turnover across the economy.
We also show that high-growth firms are not confined to a particular stage of development. They are present across the firm age and size distributions, which means that rapid growth can occur in a wide range of business contexts. High-growth firms grow faster than non-high-growth firms even once differences in age, industry and year are taken into account.
Our results show that, on average, high-growth firms invest more, have better management scores, higher cost markups and a higher average number of establishments. However, looking at how these characteristics evolve around the onset of a growth episode, and controlling for other factors such as industry or year, we do not observe significant differences between firms entering a high-growth period and those which do not.
We find that many firms experience more than one period of ‘high growth’ and are much more likely than the average firm to grow rapidly following that initial year. These fast-growth years are typically clustered together, but, overall, they account for only a small share of the period for which each firm is observed.
Defining high-growth firms
Our first step in understanding high-growth firms is exploring ways to classify them. We identified more than 20 distinct definitions used in analysis of high-growth firms across policy publications, academic literature and other research. The full set of these definitions is listed in Table A.1, in the Appendix.
These definitions cover growth in employment, turnover or productivity. They also vary in whether they set an absolute or relative growth threshold, and in the minimum initial size of firm they encompass. Different definitions therefore capture quite different sets of firms and, where the concept of a high-growth firm is employed to shape policy, the choice of the definition can have a major impact on the policy analysis.
For the analysis in this report, we focus on a subset of definitions which encompass these differences, to illustrate how definitional choices can affect our understanding of fast-growing businesses. These definitions are:
- OECD employment – firms with an annualised average employment growth rate of at least 20% per year over 3 years, and a minimum initial employment level of 10 employees. This definition was first proposed in OECD (2007) and is widely used by academics, government and education and research bodies (including the Enterprise Research Centre, ONS and ScaleUp Institute, among others)
- OECD micro – firms with fewer than 10 employees, which add 8 or more employees over 3 years. This is an extension to the OECD employment definition and was proposed by Clayton et al. (2013) to capture smaller firms growing rapidly
- OECD turnover – firms with an annualised average turnover growth rate of at least 20% over 3 years, and a minimum initial employment level of 10 employees.[footnote 1] This was also proposed in OECD (2007) and is widely used by academics, government and other bodies (including the ONS and ScaleUp Institute, among others)
- top 10%, turnover (or employment) growth: firms in the top 10% of the 3-year turnover (or employment) growth-rate distribution of all UK firms. This approach avoids setting a fixed boundary for the growth rate, instead using relative distributions to identify the fastest growing firms. This approach has been applied in a range of papers, such as Decker et al. (2015) and Haltiwanger et al. (2017)
- productivity growers: firms with growing turnover and employment for which the annualised turnover growth rate exceeds the annualised employment growth rate over a 3-year period. This captures firms that are increasing their labour productivity and therefore contributing to per capita economic growth. This approach is similar to that proposed by Du and Bonner (2016; 2017).[footnote 2]
Throughout this chapter we use ONS firm-level data on turnover and employment from the Longitudinal Business Database (LBD) to identify UK high-growth firms under different definitions. We link this to the Annual Business Survey (ABS) to include richer data on firms’ expenditure and investment and to the Management and Expectations Survey (MES) to include measures of firms’ management quality. It is worth noting that our data does not allow us to distinguish between organic growth and growth coming from M&A activity.
Definitions capture quite different sets of firms
The choice of definition has a significant impact on the number of high-growth firms identified. Figure 1 shows counts of high-growth firms for the definitions outlined above. For completeness, in grey we also show counts under the alternative definitions we identified in the literature and that are not among the main ones we focus on in this report.
The definitions vary in terms of breadth. The ‘Top 10%’ distribution-based definitions are the broadest and their trend simply reflects the size of the business population in our data. Counts under these definitions are significantly larger than for other definitions. The ‘Productivity growers’ definition also captures many firms and counts under this definition have been rising after Covid-19.
On the other end of the spectrum, the OECD definitions are narrower and capture fewer fast-growing businesses. As a proportion of the whole business population, the OECD employment and OECD micro high-growth firms have remained broadly constant over time (Figure A.1 in the Appendix). The share of OECD turnover high-growth firms displays a marked increase after Covid-19, likely due to the rebound of firms’ turnover after the crisis.
Our estimates of the number of firms meeting OECD definitions are consistent with others that have followed the same approach (such as, for example, ONS, 2015, and ScaleUp Institute, 2025).
Figure 1 – The number of high-growth firms varies substantially between definitions
Yearly count of firms identified as high-growth firms according to the baseline and other definitions of high-growth firms listed in Table A.1 of the Appendix. The coloured lines represent our baseline definitions. Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
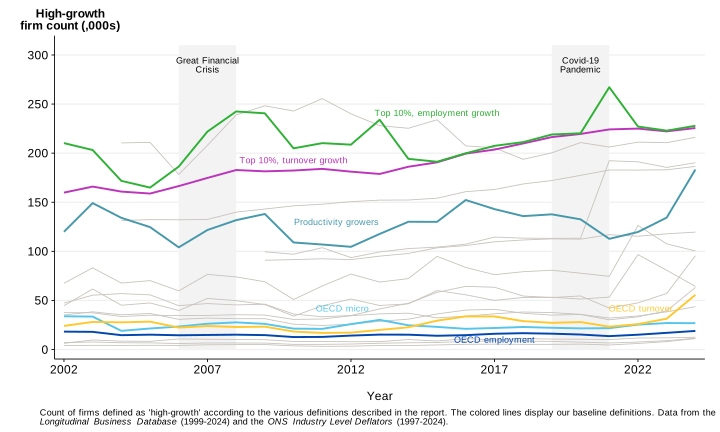
Multi-line chart showing yearly counts of firms identified as high-growth firms between 2002 and 2024. Coloured lines represent the baseline high-growth definitions (Top 10% employment growth, Top 10% turnover growth, Productivity growers, OECD micro, OECD turnover, OECD employment) and grey lines represent alternative definitions listed in Table 1 in the Appendix. Shaded bands mark the Great Financial Crisis and the COVID-19 pandemic.
Figure 2 shows the proportion of firms meeting different combinations of definitions, amongst those that meet at least one in 2024. The OECD employment definition almost completely overlaps with our other highlighted definitions. This means that most firms falling under the OECD employment definition also meet at least one other definition at the same time.
As can be seen in Figure 2, for example, 1.2% of all firms identified as high-growth firms in 2024 meet the OECD employment definition at the same time as being in all the other definitions. This corresponds to around a third of all firms in the OECD employment definition and are the firms at the intersection of the 4 circles.
Figure 2 – The degree of overlap varies for different high-growth firm definitions
Venn diagram showing the overlap between 4 definitions of high-growth firms in 2024. Each circle represents the firms classified as high growth under one definition, expressed as a share of all firms meeting at least one of the 4 definitions. The percentages in each overlapping section show the proportion of firms that satisfy that specific combination of definitions. Data from the Longitudinal Business Database (2024) and the ONS Industry Level Deflators (2024).
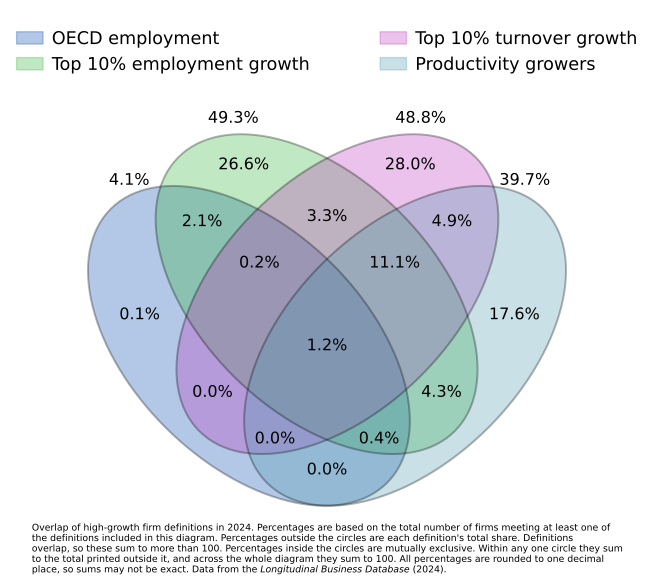
4-set Venn diagram showing overlap between OECD employment, Top 10% employment growth, Top 10% turnover growth and Productivity growers high-growth definitions in 2024. Percentages are displayed within each section to indicate the share of firms belonging to that unique combination of high-growth definitions.
In contrast, other categories have a substantial proportion of businesses that only meet that definition. This is to be expected, showing respectively:
-
firms at the top of the turnover growth distribution, that are not growing employment fast enough (28% of high-growth firms)
-
firms towards the top of the employment growth distribution, that are growing fast but are too small (less than 10 employees) to meet the OECD employment definition (26.6%)
-
firms growing their productivity but growing neither employment nor turnover fast enough to be at the top of the growth distribution for either measure (17.6%)
Figure A.2, in the Appendix, reports a broadly similar picture for the overlap between OECD turnover and the other 3 definitions (top 10% employment, top 10% turnover growth and productivity growers).
Table 1 Table reports a very similar picture focusing on the proportion of firms meeting an OECD definition that also meet other non-OECD definitions (Top 10% turnover growth, Top 10% employment growth and Productivity growers). Not surprisingly, almost all firms falling under an OECD definition based on employment are in the top 10% of the employment growth distribution.[footnote 3]
Table 1 – Pairwise overlap between OECD and other high-growth firm definitions in 2024
The percentages in the table report the share of OECD employment, OECD micro and OECD turnover firms that, in 2024, are also identified as Top 10% turnover growth, Top 10% employment growth and Productivity growers. The numbers in parentheses under each definition are the counts of firms falling in that category in 2024. Data from the Longitudinal Business Database (2024) and the ONS Industry Level Deflators (2024).
| Top 10% turnover | Top 10% employment | Prod. growers | |
|---|---|---|---|
| OECD employment (18,957) | 34.9% | 97.5% | 40.8% |
| OECD micro (26,824) | 57.9% | 99.9% | 33.2% |
| OECD turnover (55,693) | 46.5% | 20.2% | 47.6% |
More interestingly, a substantial proportion of these businesses are also growing fast in terms of turnover. Around a third of the OECD employment cohort are also in the top 10% of the turnover growth distribution, and the equivalent proportion for OECD micro firms is almost 58%. Notably, a smaller proportion (46.5%) of OECD turnover firms overlap with the top 10% turnover definition – this reflects a substantial number of firms with fewer than 10 employees growing turnover rapidly.
Taken together, this demonstrates that the OECD definitions capture a smaller number of firms and are likely to encompass firms that are rapidly growing across employment, turnover and productivity at the same time. This implies the OECD definitions fare well as a means of identifying rapidly scaling firms across multiple dimensions.
High-growth firms’ contribution to the economy
High-growth firms outperform other businesses across multiple dimensions, and their performance has slowly diverged from that of non-high-growth firms over the past 20 years
High-growth firms are defined by rapid growth in the measure used to identify them. For example, OECD employment high-growth firms have very high annualised employment growth over 3 years, while firms in the top 10% turnover-growth group have very high turnover growth over the same period.
Comparing average year-on-year growth rates across these definitions provides a more consistent basis for comparison and helps highlight differences between groups of firms. For this reason, in what follows, we focus on the average annual growth rate in employment or turnover among firms classified as high growth under each definition, irrespective of the underlying growth measure used to define high growth.
The year-on-year average employment growth rate has remained fairly stable over time for each definition over the period considered, as Figure 3 shows. While unsurprisingly, employment-based definitions have higher average employment growth rates, businesses meeting turnover-based definitions also display employment growth rates much higher than the economy-wide average.
The average growth rates for the OECD micro definition stand out for their level and volatility. This is due to the nature of the firms that this definition captures: very small businesses (starting the period with fewer than 10 employees) growing their employment by at least 8 employees over 3 years. These changes in levels, paired with the small initial size, normally translate to high percentage growth rates.
Figure 3 – All high-growth firm definitions experience faster employment growth than the average firm
Average year-on-year employment growth rate for firms identified as high growth according to the baseline definitions considered in this report. Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
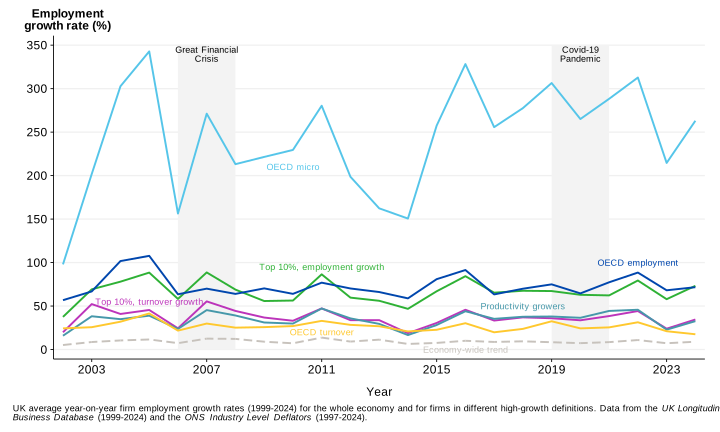
Multi-line chart showing average annual employment growth rates between 1999 and 2024 for firms identified under the baseline high-growth definitions (Top 10% employment growth, Top 10% turnover growth, Productivity growers, OECD micro, OECD turnover and OECD employment) and for the overall business population.
Figure 4 focuses on year-on-year average turnover growth rates. Again, as expected, definitions based on turnover display higher average turnover growth. Notably, though, the employment-based definitions also show very high average turnover growth. This result confirms that the OECD definitions tend to capture a smaller set of important firms growing rapidly across multiple dimensions.
Our data shows an uptick in growth after 2015, particularly for OECD micro firms. Our understanding is that this is at least partially due to a change in how the Inter-Departmental Business Register (IDBR) recorded turnover figures from 2015 onwards. This apparent surge does not fully reflect an actual increase in growth rates, but rather a correction of an underestimate present in the data prior to 2015.[footnote 4]
Figure 4 – All high-growth firm definitions experience faster turnover growth than the average firm
Average year-on-year turnover growth rate for firms identified as high growth according to the baseline definitions considered in this report. Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
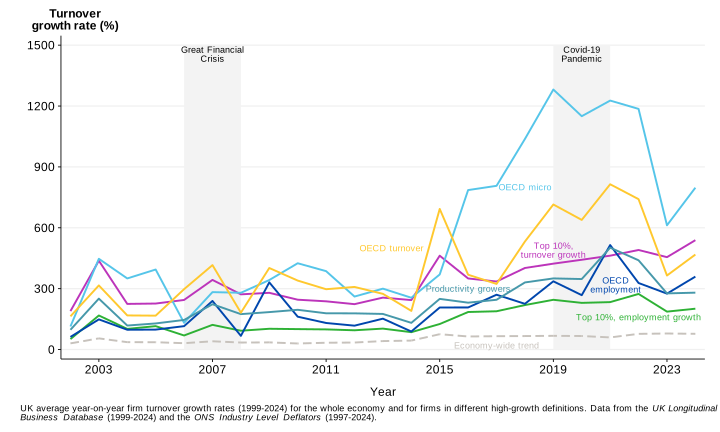
Multi-line chart showing average annual turnover growth rates between 1999 and 2024 for firms identified under the baseline high-growth definitions (Top 10% employment growth, Top 10% turnover growth, Productivity growers, OECD micro, OECD turnover and OECD employment) and for the overall business population.
Finally, we explore the performance of high-growth firms relative to the rest of the business population. To do this, we focus on the differentials in the average growth rates of turnover, employment and labour productivity between the 2 groups. As Figure 5 shows, from the start of the 2000s, the gap between high-growth firms and the rest slightly widened. The relative performance in turnover growth rate of high-growth firms picked up around 2015, while the gap in the employment growth rate has remained almost stable over time (consistent with the trends in Figure 3 and Figure 4). As a result, the labour productivity differential[footnote 5] has also widened.
While Figure 5 focuses on OECD employment high-growth firms (for ease of visualisation) similar trends are observed across all definitions as displayed in Figure A.3 in the Appendix.
Figure 5 – The performance of high-growth firms has improved relative to non-high-growth firms
Year-on-year average growth rate differentials (turnover, employment, labour productivity) of OECD employment high-growth firms vs non-high-growth firms, with Hodrick-Prescott filtered series (smoothing = 100). Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
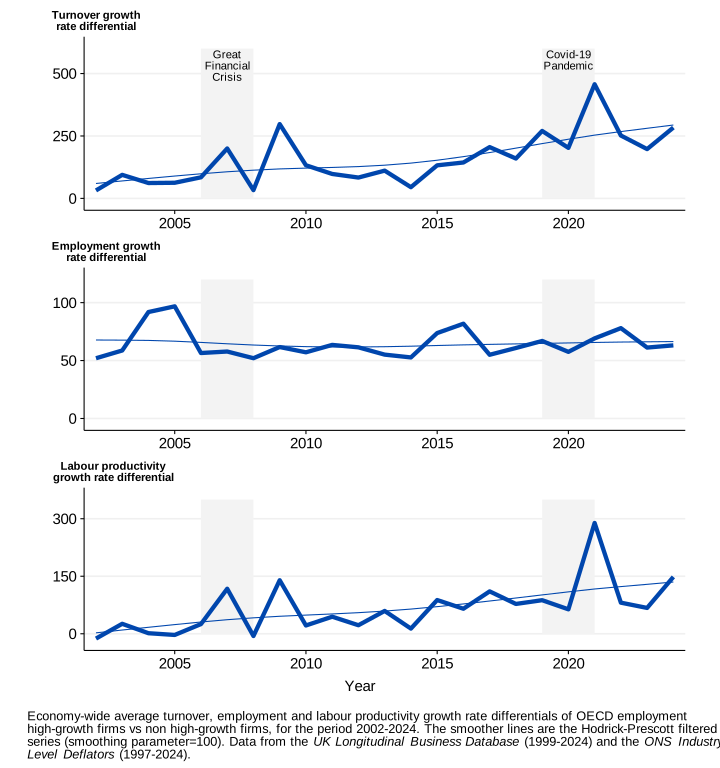
3-panel line chart showing the average turnover, employment and labour productivity growth rate differentials between OECD employment high-growth firms and non-high-growth firms between 2002 and 2024. Trend lines are also shown in each panel. Shaded bands mark the Great Financial Crisis and the COVID-19 pandemic.
We have so far focused on the average growth rates of high-growth firms as a group, but it would be wrong to think of them as a homogeneous group of firms, growing at similar speed. The average growth rates of high-growth firms mask a skewed and dispersed distribution under all definitions.
Figure 6 provides a visualisation of these distributions, reporting the 10th and 90th percentiles, mean and median employment growth rates for 2024 across our main definitions. The gaps between 10th and 90th percentiles are wide, with the median closer to the 10th percentile and the mean exceeding the median. This confirms that even within a category of high-growth firms, there is substantial variation in performance and growth rates, with a small number of extremely fast-growing businesses.
The OECD micro growth rates have been excluded from this figure due to the substantially higher dispersion and skewness in growth rates, which derives from the small size of the businesses included in the definition as discussed above. Figure A.4 in the Appendix provides a visualisation for all the definitions.
Figure 6 – The distribution of high-growth firms’ growth rates is skewed and dispersed
Distributional statistics of the year-on-year employment growth rate distribution for the whole economy and for firms identified as high growth according to the baseline definitions (excluding the OECD micro definition) in 2024. The distributional statistics include the mean, median, and 10 to 90th percentile range. Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
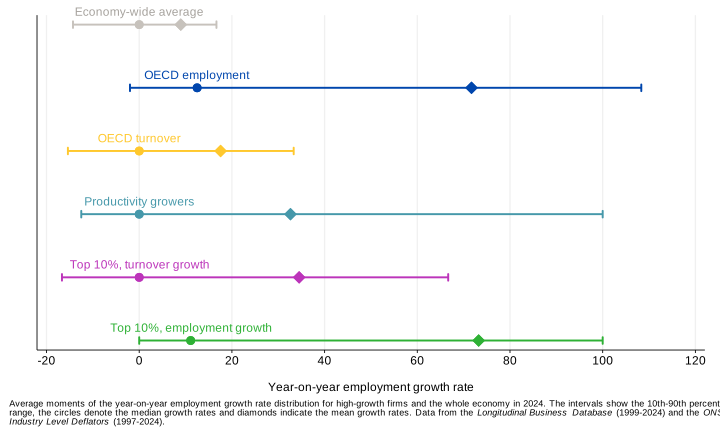
Dot-and-whisker chart showing the distribution of year-on-year employment growth rates in 2024 for firms identified under the baseline high-growth firm definitions (Top 10% employment growth, Top 10% turnover growth, Productivity growers, OECD turnover and OECD employment) and for the overall business population. Circles indicate median growth rates, diamonds indicate mean growth rates, and horizontal lines show the 10th to 90th percentile range.
High-growth firms make an outsized contribution to turnover and employment
Though high-growth firms represent a small share of the business population, they are responsible for a disproportionately large share of turnover and employment, across the economy and in different sectors.
Figure 7 shows the share of firms classified as high growth under the OECD employment definition and their contribution to employment and turnover across the whole economy and in 7 of the 8 Industrial Strategy growth-driving sectors (IS-8).[footnote 6] Whilst high-growth firms meeting the OECD employment definition make up less than 1% of firms in the economy, they are responsible for around 7.5% of UK turnover and employment. Similar results hold for the other high-growth firm definitions, as Figure A.5 and Figure A.6 in the Appendix show.
This confirms the importance of fast-growing firms for the UK economy that has been evidenced in the economic literature (Roper and Hart, 2013; Coutu, 2014; Bank of England, 2025; and the yearly ScaleUp Institute Reviews (for example 2025), among others).
Figure 7 – High-growth firms account for a disproportionate share of turnover and employment in the whole-economy and across different sectors
Share of firms classified as OECD employment high-growth firms and their contribution to sectoral employment and turnover, across the 7 of the 8 Industrial Strategy growth-driving sectors (IS-8) and in the whole economy. Data from UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
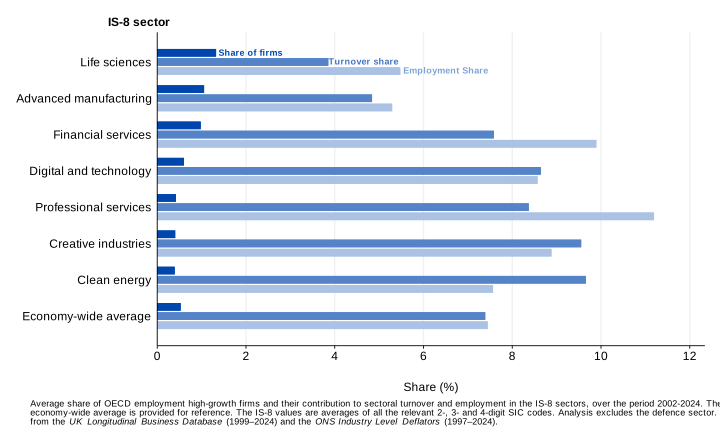
Horizontal bar chart showing the share of firms classified as OECD employment high-growth firms and their contribution to turnover and employment across Industrial Strategy growth-driving sectors and the economy as a whole. Each sector is represented by three bars showing the share of firms, share of turnover and share of employment.
Figure 8 plots the share of high-growth firms in an industry (defined using 2-digit Standard Industrial Classification (SIC) codes) against industry-wide employment growth rates (top panel) and employment growth rates of non-high-growth firms (bottom panel). The top panel in Figure 8 shows a positive correlation between the share of high-growth firms and industry-wide employment growth, suggesting that the prevalence of high-growth firms is associated with greater overall growth in an industry.
Figure 8 – High-growth firm prevalence in an industry is associated with greater employment growth overall as well as for non-high-growth firms
Share of firms categorised as OECD employment high-growth firms within an industry against the year-on-year employment growth rate in that industry (including and excluding high-growth firms), in 2024. Each bubble represents an industry (2-digit Standard Industrial Classification (SIC)) and its size is proportional to the industry total employment. Data from the UK Longitudinal Business Database (1999 to 2024).
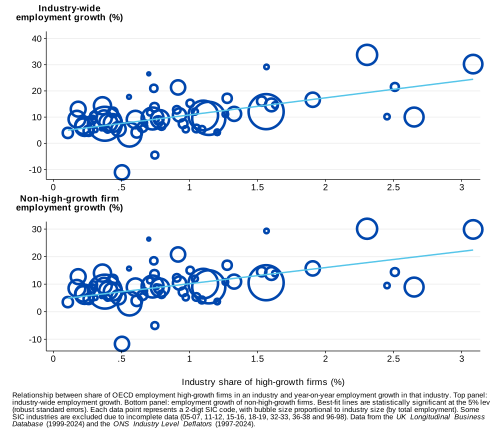
2 bubble charts comparing the share of OECD employment high-growth firms in an industry with employment growth in 2024. The top chart shows overall industry employment growth and the bottom chart shows employment growth excluding high-growth firms. Bubble size represents total industry employment.
However, the presence of fast-growing firms in an industry could come at the expense of other firms’ growth opportunities or could be part of a growth pattern shared across the industry. The bottom panel of Figure 8 therefore reports the relationship between the share of high-growth firms in an industry and employment growth rates of non-high-growth firms. The positive correlation remains, indicating that industries with a higher share of high-growth firms also tend to experience stronger employment growth among firms that are not themselves classified as high growth.
Taken together, these results suggest that fast-growing firms support growth in other firms, through beneficial competitive dynamics (as high-growth firms challenge incumbents or prompt others to compete to match their growth) or other positive spillover effects (such as innovations being adopted across an industry). And growing industries support growth across firms, whilst providing greater scope for some firms to grow more quickly. This analysis does not allow us to distinguish between these mechanisms, but it shows that high-growth firms are associated with broader industry growth rather than with weaker growth among other firms.
High-growth firm demographics
High-growth firms are present across the firm age distribution and retain a consistent growth premium at different ages
The age distribution of high-growth firms varies according to the definition used. Figure 9 shows the percentage of firms in each age category meeting the different high growth definitions in 2024. In 4 of the 6 definitions, the share of high-growth firms declines with firm age. However, irrespective of the definition, high-growth firms are observed across all age cohorts, indicating that rapid growth is not confined to young firms.
The OECD employment and OECD turnover definitions follow different patterns. We find that the share of firms meeting the OECD employment definition is lowest in age cohorts younger than 5 years, and broadly consistent across older cohorts. The small proportion of OECD employment firms aged 3 or 4 is likely due to the restrictions the definition imposes. Very young firms are less likely to have at least 10 employees and grow employment rapidly at the same time.[footnote 7]
Figure 9 – There is a non-negligible share of high-growth firms even among older firms
Share of high-growth firms in each age category by different definitions, in 2024. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
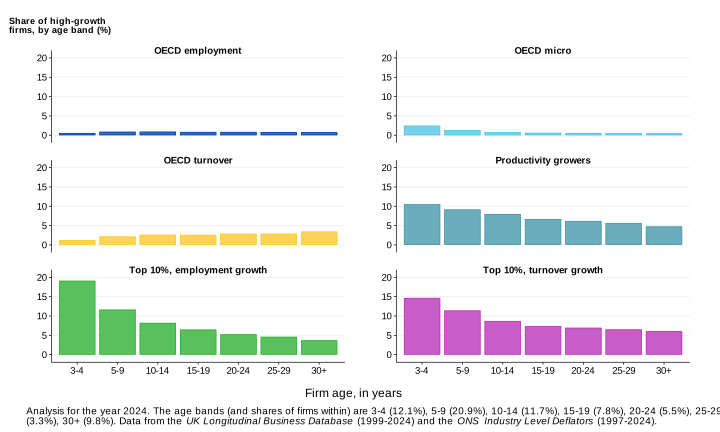
6-panel bar chart showing the share of firms classified as high growth across firm age bands in 2024. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% employment growth and Top 10% turnover growth definitions. Bars represent the share of firms meeting each definition within each age band.
Furthermore, the proportion of OECD turnover high-growth firms increases with age. This is consistent with older firms being more likely to have at least 10 employees and continue growing their turnover at the same time.
To further explore growth dynamics over the firm life cycle, we compare growth rates of high-growth firms to those of non-high-growth firms in the same age category. We define the differential between these 2 growth rates as the growth premium.
In this analysis, we include year fixed effects, to account for the fact that macroeconomic cycles will make some years more favourable than others for firms. We also control for industry to exclude variation in growth premia which is driven by industry-wide, rather than firm, characteristics. This helps to isolate the impact of firm age on growth rates. Figure 10 shows the turnover, employment and productivity growth premia for OECD employment high-growth firms that result from this analysis.
As expected, high-growth firms grow much faster than other firms. For firms identified under the OECD employment definition, the employment growth premium is unsurprising as employment growth forms part of the definition. It is more notable that firms in this category also display a large and consistent turnover growth premium. The growth premium is substantially higher when firms are young: high-growth firms aged 3 to 4 display an average turnover growth rate 450 percentage points higher than non-high-growth firms in the same age band.[footnote 8] However, the growth premium remains positive when firms get older.
Figure 10 – Growth premia for OECD employment high-growth firms over different age bands, controlling for sector and year
Average employment, turnover and productivity growth rate premia for OECD employment high-growth firms relative to non-high-growth firms in each age band. Point estimates are displayed together with 80, 90 and 95% confidence intervals. The analysis controls for year and industry (4-digit Standard Industrial Classification (SIC)) fixed effects. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
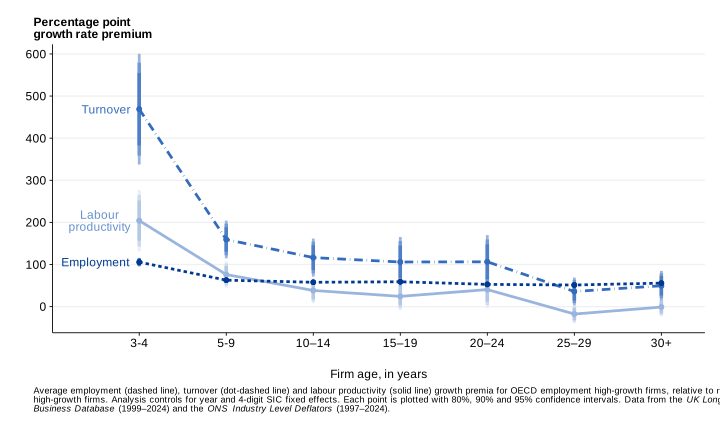
Multi-line chart showing employment, turnover and productivity growth rate premia for OECD employment high-growth firms relative to non-high-growth firms across six firm age bands. Employment, turnover and labour growth rate productivity premia are represented by dashed, dot-dashed and solid lines respectively. Points show estimated growth premia, and vertical lines show 80%, 90% and 95% confidence intervals.
We also find that, despite focusing on OECD employment high-growth firms, the turnover growth premium tends to exceed the employment growth premium, at least for firms up to 20 years old. This means high-growth firms generally display a positive productivity growth premium, further emphasising their importance as drivers of overall economic growth.
High-growth firms are present across the size distribution
The UK business population is very skewed towards micro and small firms, with the 2 combined accounting for around 99% of registered businesses. Figure 11 displays the proportion of firms in each size category that classify as high-growth firms according to different definitions. As is common in the literature, we categorise firms as micro (0 to 9 employees), small (10 to 49 employees), medium (50 to 249 employees) and large (at least 250 employees).
Figure 11 – Proportion of firms in each size category meeting different high-growth definitions
Share of high-growth firms in each size category, by different definitions, in 2024. Size bands are based on employment. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
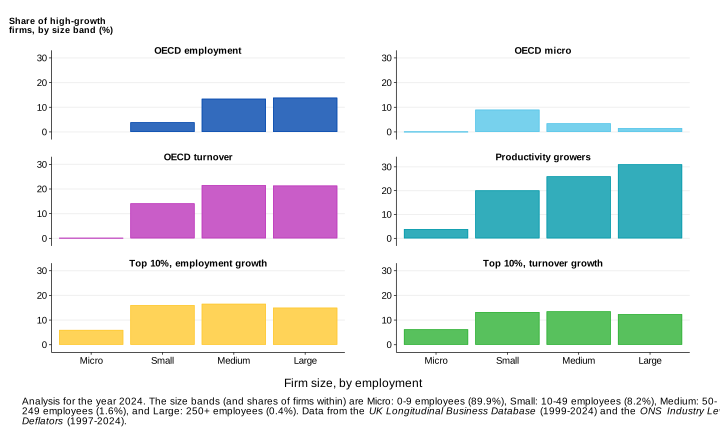
6-panel bar chart showing the share of firms classified as high growth across employment size bands in 2024. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% employment growth and Top 10% turnover growth definitions. Bars represent the share of firms meeting each definition within micro, small, medium and large firm size bands.
The different definitions behave very similarly over the size categories. As a share of the total business population in a certain size band, high-growth firms increase with size in all definitions except the OECD micro.
While it is probably more difficult for firms to grow their employment or turnover when they are already over the small size band, larger firms are likely to be the most successful and a larger proportion of them continue to grow.
As expected, a different pattern is observed among the OECD micro firms, since it is unlikely for such small firms to grow to more than 50 employees in a 3-year period, and very unlikely for them to grow to more than 250 employees.
High-growth firms on average differ in some characteristics from other firms, but they do not help predict the likelihood of entering a growth episode
The data we have available allow us to explore if high-growth firms differ on average from the rest of the population along a series of observable characteristics, and how that varies for different definitions. Dimensions we can observe in our analysis include:
-
management quality – the Management and Expectations Survey (MES) provides an index summarising different aspects of businesses’ management practices. The index spans 0 to 10, with higher scores indicating better management practices. The MES covers 2016, 2020 and 2023, so we only have at most 3 observations of the management quality index for each firm
-
investment measures – measures of investment come from the Annual Business Survey (ABS) and the Annual Respondents Database X (ARDx). We observe yearly expenditure in capital, computer software, and intellectual property
-
markups – we use measures of average cost markups estimated for the State of UK Competition report (CMA, 2024) using data from the ABS/ARDx. More details about the methodology and estimation approach are in the Appendix
-
number of establishments – the Longitudinal Business Database (LBD) reports the number of local units (or establishments) for each business we observe
Pooling all firms and years, businesses experiencing high growth display higher average investment levels, better management scores, higher cost markups and, with the obvious exception of the OECD micro definition, a higher average number of establishments. This holds true for all the high-growth firm definitions.
Importantly, these results compare the mean value of the characteristics across 2 groups of firms: firms experiencing high growth and firms not experiencing high growth at some point in time. They do not allow us to say if high-growth firms are intrinsically different, or if these differences in averages are driven by the industry in which businesses operate or other observable factors, nor if these characteristics systematically change around a growth episode.
To further our understanding, we examine the association between observable firm characteristics measured in the periods before, during, and after the start of a high-growth episode and the likelihood of entering such an episode for the first time. Comparing firms that enter a high-growth episode with firms that are neither entering nor already in one can help shed light on which characteristics are more closely associated with subsequent high growth.
If a certain characteristic was associated with entry into a first high-growth episode, we would expect firms entering a high-growth episode to exhibit different levels of that characteristic in the periods leading up to the episode, relative to firms that are neither entering nor already experiencing a high-growth episode.
Figure 12 shows some association between several variables and the likelihood of entering a first growth episode, although the statistical significance of these is limited and the pattern differs across investment in capital, price-cost markups, number of establishments and intellectual property spending.
Firm investment in capital is not associated with becoming high growth in the future. However, firms that have recently entered a growth episode tend to be associated with higher levels of capital expenditure, though the statistical significance of this result is limited. Intellectual property (IP) expenditure shows a similar pattern. Taken together, these findings suggest that higher levels of both tangible and intangible investment are more characteristic of recent high-growth firms than of firms that are about to enter a high-growth episode.
Firms entering a high-growth episode tend to be associated with higher material markups (although this relationship is only weakly statistically significant and the elevation does not persist. This suggests that higher markups may be a distinguishing feature of firms around the onset of a first high-growth episode. Importantly, as also discussed in CMA (2024), higher markups could reflect successful innovation, product differentiation, brand value, or other sources of competitive advantage.
Firms with more establishments are slightly less likely to become high growth in the subsequent year. This indicates that firms poised to grow are not already spread across a large number of sites. In contrast, firms that have recently entered a high-growth episode tend to be associated with a larger number of establishments. This pattern is consistent with firms expanding their physical footprint as they become high growth.
Overall, these results reveal limited systematic patterns around a growth episode, highlighting the difficulty of predicting which firms will subsequently become high growth. Pairing this result with the significantly different means of the 2 groups, suggests that the observed characteristics might be persistent features of certain types of firms rather than drivers of high-growth episodes.
These findings confirm the difficulties in predicting which firms will be high growth using traditional econometric approaches (for example Coad et al., 2014; Weinblat, 2017). Some initial attempts to use machine learning have also had limited success (Coad and Srhoj, 2019; Houle and Macdonald, 2023).
Figure 12 – The likelihood of becoming a high-growth firm has limited correlation with selected firm-level characteristics
Results from a linear probability model (LPM) regression with leads and lags, controlling for year, firm size (employment), firm age, and industry fixed effects (by 4-digit Standard Industrial Classification (SIC)). The independent variables are standardised, and estimates are accompanied by the 80, 90 and 95% confidence intervals. Data from the UK Longitudinal Business Database (1999 to 2024), the ONS Annual Business Survey (2021 to 2022), the ONS Annual Respondents Database (1999 to 2020) and the ONS Industry Level Deflators (1997 to 2024).
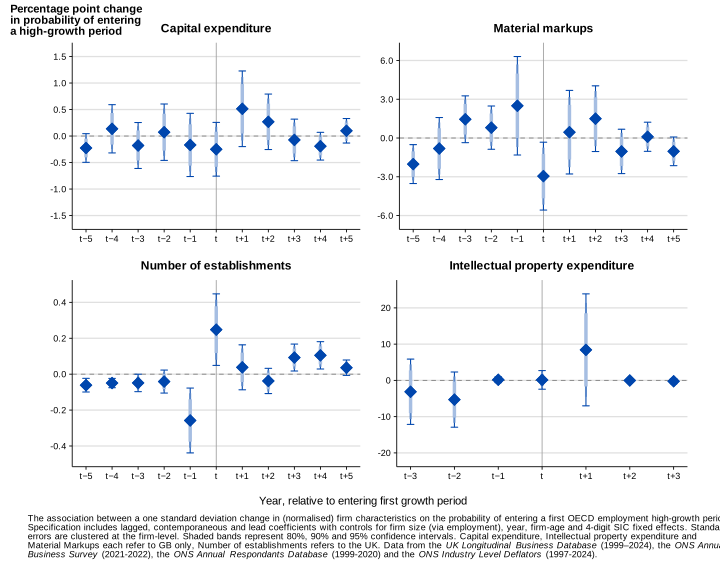
4-panel coefficient plot showing estimated associations between four firm-level characteristics (capital expenditure, material markups, number of establishments and intellectual property expenditure) and the likelihood of entering an OECD employment high-growth period at different points from five years before (t−5) to five years after (t+5) entering a high-growth period. Diamonds show coefficient estimates and vertical bars show 80%, 90% and 95% confidence intervals.
Importantly, while in this analysis we focus on the OECD employment for ease of exposition, our findings for other definitions are broadly consistent with those just discussed. More results can be found in Figure A.8-Figure A.11 in the Appendix.
An additional interesting characteristic to explore is the quality of management. Measuring management quality is challenging but work over the last 2 decades on formalising management practices has provided data to investigate the impact of management (Scur et al., 2024).
Across many countries, a higher management score (associated with adopting more “structured” management practices) is positively related to productivity, profitability, size, and propensity to export (Bloom and Van Reenen, 2007; Bloom et al., 2012). The relationship between management and performance is mediated through employee talent, effort and decision-making. Bender et al. (2016) provide evidence that employee talent is an important mediator; that is, more skilled managers raise productivity and are more likely to work in firms with high management scores. This complicates the clear channel of higher management causing higher productivity, showing that employees play a critical role. However, Bloom et al. (2013) show that higher quality management robustly raises productivity, with a management field experiment at Indian textile firms.
Differently from the other characteristics, we can only observe the management quality index in 3 non-consecutive years, and we therefore resort to separate regressions of leads and lags of the management score.
Results from these regressions show that high-growth firms are persistently and significantly better managed than non-high-growth firms, even before entering a growth episode (Figure 13 and Figure A.12 in the Appendix). This confirms the result from the pooled mean comparison and suggests that, like the other characteristics, management quality is a time-invariant or very slowly moving firm-level trait that separates high-growth firms from the rest of the business population. While firms that become high-growth firms appear to be better managed on average, there is little evidence that changes in management quality are closely associated with the timing of growth episodes themselves.
Figure 13 – High-growth firms are better managed than non-high-growth firms
Results from a linear probability model (LPM) regression, separately for each year relative to the high-growth period, controlling for year, firm size (employment), firm age, and industry fixed effects (by 4-digit Standard Industrial Classification (SIC)). The independent variable has been standardised, and the estimates are accompanied by the 80, 90 and 95% confidence intervals. Data from the UK Longitudinal Business Database (1999 to 2024), the ONS Management and Expectations Survey (2016, 2019, 2023), the ONS Annual Business Survey (2021 to 2022), the ONS Annual Respondents Survey (1999 to 2020) and the ONS Industry Level Deflators (1997 to 2024).
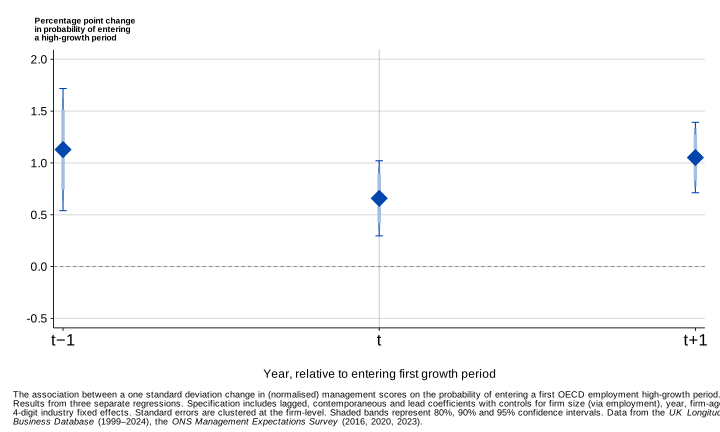
Coefficient plot showing estimated associations between management scores and the likelihood of entering an OECD employment high-growth period at three points in time: one year before, during and one year after a growth episode. Points show coefficient estimates and vertical bars show 80%, 90% and 95% confidence intervals.
High-growth firms’ trajectories and progression
Understanding how persistent growth is and what happens to firms after they experience a first period of high growth is an important part of describing their overall economic impact.
Firms can often sustain sudden and short-lived bursts of growth, and periods of high growth can be a small part of a business’ life (as noted by Roper and Hart, 2013; Mogos et al., 2021; and Esteve-Pérez et al., 2022, among others). The high-growth firm definitions that we consider partially tackle the volatility of growth by considering 3-year periods rather than one-year. This ensures that short-run transitory changes in any of the underlying variables (employment, turnover or productivity) do not inflate the analysis.
In this section, we explore:
-
what happens to firms following an initial period of high growth
-
the sequencing of different types of growth (turnover, employment or productivity)
-
the extent to which fast-growing micro firms (with fewer than 10 employees) subsequently meet the standard OECD employment definition
In what follows, we use the term ‘high-growth period’ to refer to any year in which a firm meets a high-growth definition. We use ‘high-growth episode’ to refer to any uninterrupted spell of high growth. Because the definitions are measured over 3-year windows, consecutive high-growth periods partially overlap. For example, a firm meeting the definition in 2 consecutive years is treated as having a 4 year high-growth episode, while 3 consecutive high-growth periods imply a 5-year episode, and so on.
For ease of exposition, this section focuses on 3 of the high-growth firm definitions previously considered: OECD employment, OECD turnover, and Productivity growers. We analyse firms’ first high-growth year and their subsequent growth patterns.
Fast-growth periods are often clustered, but episodes are relatively short amongst the minority of firms that experience high growth
As discussed, high-growth firms normally represent a minority of the business population, especially when focusing on the OECD definitions. Figure 14 (left panel) confirms this finding.
Restricting our analysis to firms that survive to be at least 5 years old, only 3.5% of them ever become OECD employment high-growth firms and around 6% become OECD turnover high-growth firms. The Productivity growers definition is much broader, and slightly less than 30% of businesses experience this type of growth at least once. This is a result of the less demanding thresholds that businesses have to meet to be identified as Productivity growers relative to the OECD definition requirements.
On average, firms reach their first high-growth period a little under 8 years old (for employment), over 10 years old (for turnover) and in between for productivity. This is in line with work from the ScaleUp Institute (2025), which provides a more detailed breakdown of the median age of scaling firms by industry.
Additionally, firms that experience fast growth spend a relatively small proportion of their (observed) life in a given type of growth.[footnote 9] This is consistent across the 3 definitions, and amounts to around 15% on average (right panel of Figure 14).
Figure 14 – Few firms experience fast growth, and, on average, they only grow fast for a minority of their lives
High-growth firms as share of the whole business population (left panel) and average share of a high-growth firm’s life spent in growth episodes (right panel), by different definitions. Data from the UK Longitudinal Business Database (1997 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
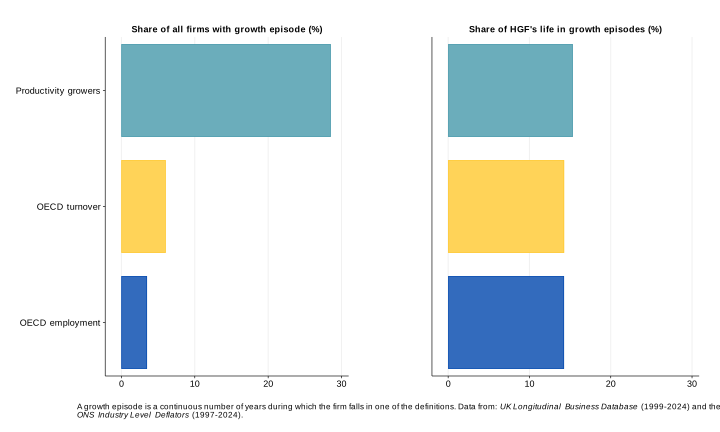
2-panel horizontal bar chart showing the share of firms that experience at least one growth episode and the average share of a high-growth firm’s life spent in growth episodes for three high-growth definitions (OECD employment, OECD turnover and Productivity growers).
Focusing on businesses that experience at least one high-growth period (and survive to be at least 5 years old), we find that many of them only live through one uninterrupted episode of rapid growth in their lifetime. Specifically, more than 80% of OECD employment high-growth firms only have one continuous OECD employment episode (just over 70% for OECD turnover and Productivity growers), and only a minority experience multiple episodes of growth with gaps between high-growth periods (Figure 15, left panel).
Importantly, this does not mean that firms only grow for one period. More than half of the OECD employment growth episodes (around 40% for OECD turnover and Productivity growers) last at least 4 years (as shown in the right panel of Figure 15), with a minority of firms growing continuously in the same category for 6 or more years. This suggests that many high-growth firms enjoy a few consecutive periods of very rapid growth clustered together rather than spread across their lives.
These results are consistent with the existing economic literature on growth persistence and repetition. The ScaleUp Institute (2019) shows that many firms experience multiple periods of scaling, while several research pieces emphasise the episodic nature and the limited persistence of fast growth (see Hamilton and Ng, 2025 for a comprehensive review of the evidence).
Figure 15 – Single growth episodes with multiple clustered periods of growth are common
Share of high-growth firms by number (left panel) and duration (right panel) of growth episodes, by different definitions. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
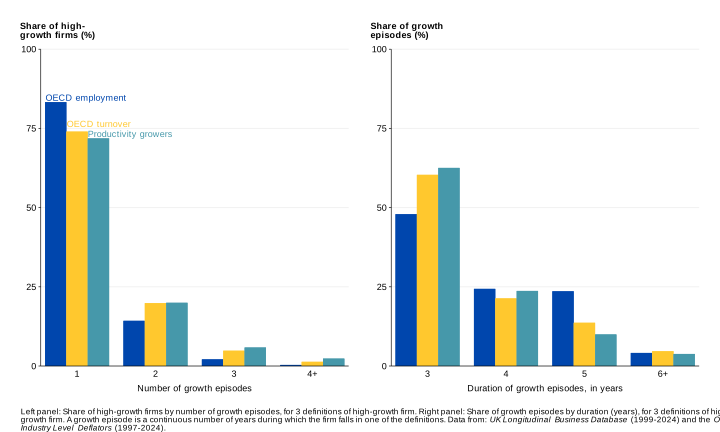
2-panel grouped bar chart showing the number and duration of growth episodes for three high-growth definitions (OECD employment, OECD turnover and Productivity growers). The left panel shows the share of high-growth firms by number of growth episodes (1, 2, 3, or 4+), while the right panel shows the share of growth episodes by duration in years (3, 4, 5, or 6+).
High-growth firm types are informative about growth persistence and the nature of future growth
OECD employment growth episodes are the most persistent: around 86% of firms repeating growth have no gap between high-growth years, and under 1% repeat an employment high-growth year after a decade or more. OECD turnover high-growth firms show some more interruption; 73% of high-growth years are consecutive spells while 18% have gaps between 2 to 10 years. Productivity growers are the most likely to experience intermittent growth of the type.
The likelihood of a subsequent high-growth period of any type depends on the nature of the first episode. Figure 16 shows that OECD employment high-growth firms are the most likely to repeat a high-growth period in any of the 3 definitions for at least another period (around 75% of the time), while OECD turnover high-growth firms are quite likely (62%) and Productivity growers are the least likely (54%).
Figure 16 – Firms that are initially high-growth by employment are the most likely to experience a high-growth period in the future
Percentage of firms experiencing a subsequent high-growth period, by their first high-growth episode (OECD employment, OECD turnover or Productivity growers). Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
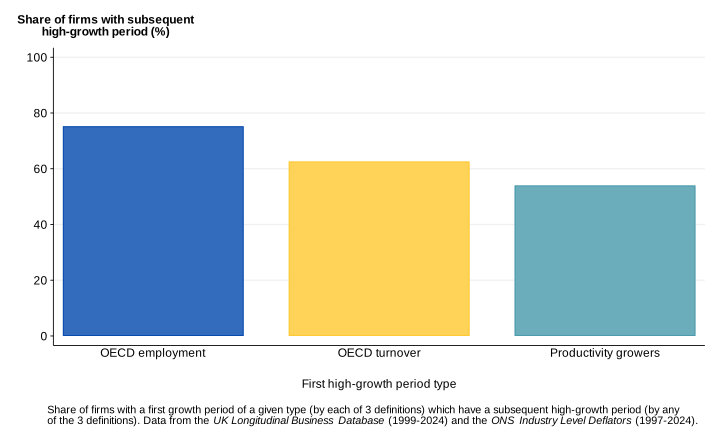
Bar chart showing the share of firms that experience a subsequent high-growth episode, grouped by the definition used to identify their first high-growth episode (OECD employment, OECD turnover and Productivity growers).
Given the government’s focus of industrial strategy on 8 sectors with high-growth potential, we explore patterns for high-growth firms in these sectors. Looking at just the OECD employment growth definition, around 36% of high-growth firms operate in the Industrial Strategy growth-driving sectors (IS-8). Of those firms, 44% grow again after a first high-growth period, which is around the same as all high-growth firms in the sample. The share of high-growth firms that grow again varies somewhat between sectors: it is 62% in Manufacturing, 48% in Construction, 43% in Wholesale/retail/transport and 45% in Services.
A firm’s initial high-growth definition also has an impact on the type of future growth they are likely to display. Figure 17 shows the proportion of firms that meet each type of definition in future, split by their first high-growth category. Notably, Productivity growers are most likely to grow again by productivity (51%) but much less likely to become OECD employment or turnover high-growth firms (around 10%). On the flip side, OECD employment high-growth firms often repeat growing by employment (60%) but are also likely to become OECD turnover high-growth firms (40%) or Productivity growers (51%).
Figure 17 – The nature of a firm’s first high-growth period is related to future growth type
Share of high-growth firms subsequently meeting the OECD employment, OECD turnover or Productivity growers definitions, or experiencing no subsequent high-growth year, by their first high-growth period. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
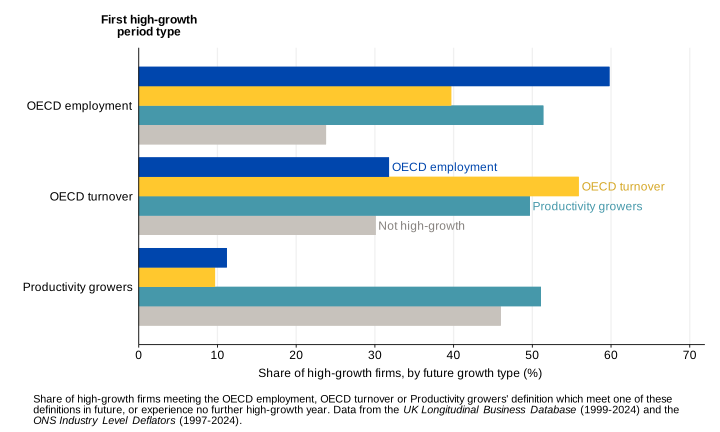
Grouped horizontal bar chart showing the share of firms that subsequently meet the OECD employment, OECD turnover, or Productivity growers definitions, or do not experience further high growth, by the type of their first high-growth episode (OECD employment, OECD turnover or Productivity growers).
For firms transitioning between high-growth periods, the dominant pattern is persistence in the same type of growth (for example employment to employment; turnover to turnover). The high shares of firms on the diagonal in Figure 18 confirm this pattern. The figure also shows that cross-type transitions are less common, although a substantial share of OECD employment and OECD turnover high-growth firms become Productivity growers in the next year.
High-growth firms are also reasonably likely to move out of high growth in the following year (see the rightmost column of Figure 18). Of the almost 560,000 OECD employment observations present in the whole dataset, over one third do not meet any of the 3 high-growth definitions in the following year. This pattern is even starker for OECD turnover and Productivity growers, with around half of them falling out of a high-growth spell in the following year.
Figure 18 – High-growth type is persistent, but a substantial share becomes non-high-growth
Probability of transitioning from a high-growth firm definition to another one or to a non-high-growth status in the subsequent year. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
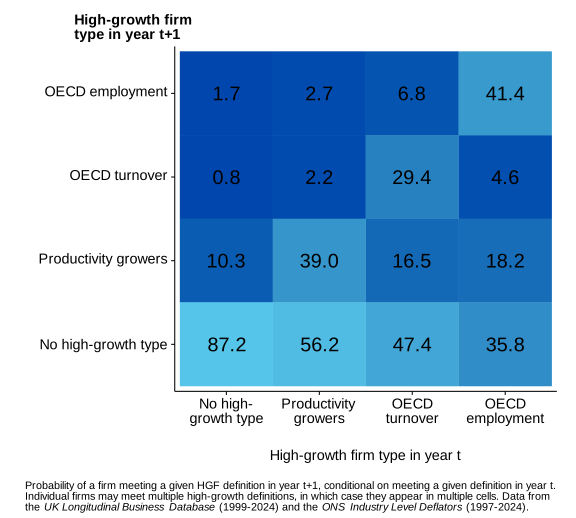
Heatmap showing the probability of transitioning between four firm types: no high-growth type, Productivity growers, OECD turnover and OECD employment. Cells display the probability of moving from the category shown on the horizontal axis in year t to the category shown on the vertical axis in year t+1. Darker colours represent higher probabilities.
Firms that experience no further high-growth episodes have a wide range of growth trajectories
After a firm’s final high-growth year, the average employment growth rate turns negative across all types. Turnover growth and productivity growth are modest but positive. These patterns are broadly stable over 3, 5 and 10 years after the final high-growth year.
On average, across all high-growth types after their final high-growth year, the average turnover growth for 3 years is around 4.5%, productivity grows at 1.4%, while employment shrinks by around 4%. This reflects that these firms are those that do not go on to have a future period of high growth, and so necessarily their growth rates are lower.
These averages mask a lot of variation. After their final high-growth year, nearly 20% of OECD employment high-growth firms shrink in employment, but over 8% grow employment by 20% or more. For turnover, this is starker, with over 61% experiencing a decline in turnover once their high-growth spell ends, but almost 15% achieving 20%+ growth.
OECD micro firms are highly likely to continue growing strongly in future
A further means of examining firm growth progression is exploring the growth of OECD micro firms, and whether they subsequently meet the OECD definitions that are restricted to larger firms.
Many OECD micro firms outgrow the initial threshold of less than 10 employees by the time they stop being OECD micro firms.[footnote 10] On average, firms in their last year as OECD micro have 28 employees and have therefore reached the status of “small” firm.
Unsurprisingly, many OECD micro firms are also young, but there is some heterogeneity: the median firm in its last OECD micro year is 6 years old, while the average age of these firms is slightly over 9.
As Figure 19 shows, the vast majority of firms coming out of an OECD micro high-growth period keep growing substantially.
Specifically, more than 80% of the firms that we still observe in the following year experience positive growth. Slightly more than 34% of firms have an annualised average growth rate of 20% or more. More than 17% of firms become standard OECD employment high-growth firms while the others grow on average at least 20% but were still below the 10-employee threshold at the start of the 3-year counting period. As fewer than 2% of firms in the overall business population become OECD employment high-growth firms in a given year, this suggests that OECD micro high-growth firms are substantially more likely than the average firm to continue growing in subsequent years.
Figure 19 – Most firms keep growing substantially after their last year of OECD micro growth
High-growth firms transition after their last year in the OECD micro category. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
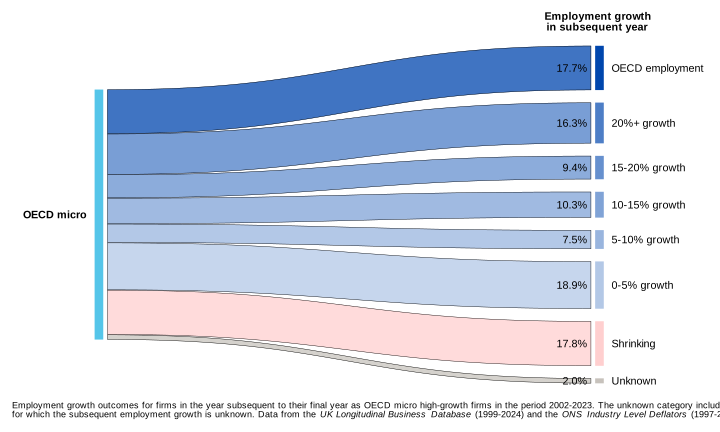
Sankey diagram showing transitions from OECD micro high-growth firms to employment growth groups (OECD employment, 20%+ growth, 15 to 20% growth, 10 to 15% growth, 5 to 10% growth, 0 to 5% growth, shrinking and unknown). Flow widths represent the share of firms moving to each subsequent growth group.
High-growth firms and their networks
In this chapter, we explore the first of 2 experimental data sources to supplement our analysis and offer a different perspective on high-growth firms. Through a collaboration with the Office for National Statistics (ONS), we use new experimental data on firms’ financial transactions to explore supply networks and how their characteristics change as firms grow.
Firms do not grow in isolation. They are part of supply chains and networks and their growth influences, and is influenced by, these connections. Relatively little is known about how supply chain structure affects or accompanies firm growth. These features are difficult to examine using standard sources of firm-level microdata, such as those explored in the previous chapter. Instead, we require information on relationships between firms and between firms and other organisations.
The evidence on production networks historically focused on stylised facts about the structure of these networks (for example Carvalho, 2014; Grassi and Sauvagnat, 2019) and how shocks propagate through networks (for example Atalay, 2017; Boehm et al., 2019; Carvalho et al., 2021; Demir et al., 2024).
A growing empirical literature on how supply chains affect growth suggests that creating or renewing buyer-seller linkages is positively related to firm growth (Hisano et al., 2017; Fujii et al., 2017) especially when supplying large companies (for example Bernard et al., 2022; Alfaro-Ureña et al., 2022).
ScaleUp Institute research provides evidence that high-growth firms play an important role in supply chains (4 in 10 firms report being part of a supply chain),[footnote 11] with 71% of scaleup companies selling to other businesses or Government and 83% collaborating with partners (ScaleUp Institute, 2025). ScaleUp Institute research has also shown the importance of Government procurement for scaling companies (2014, 2025) and the role of securing finance as a predictor of scaling (2023).
The ONS is collaborating with their partners at Pay.UK and Vocalink to provide datasets in development on industry-to-industry payment flows within the UK.[footnote 12] This collaboration expands on existing ONS work, by exploring connections between firms and other organisations based on their financial transactions.
We use this data to explore how high-growth firms differ from the rest of the business population in terms of:
-
supply chain concentration, connections, and dependence
-
the relative importance of payments from the financial sector and government
-
demand stability
This chapter presents 3 main findings that enhance our understanding of how supply chain characteristics are associated with firm growth.
Firstly, we document the differences between high-growth firms and other firms in how they trade with their partners. Our analysis suggests that a diverse supply network, combined with some deep relationships, may be important for high-growth firms. We also show that high-growth firms’ supply networks evolve as they grow.
Compared with other firms, high-growth firms tend to have more suppliers upstream, and fewer customers downstream. On average, they operate with less concentrated supplier and customer bases across their networks, despite a greater share of sales or inputs being accounted for by the largest customer or supplier.
This pattern is consistent with our analysis of changes in supply network characteristics before and during a period of high growth. This analysis finds that upon entering a high-growth period, firms experience a significant fall in supply chain concentration alongside an increase in the relative importance of their largest supplier and customer. We also find that higher concentration and a lower share for the largest customer or supplier are associated with an increased likelihood of subsequently becoming high growth.
The importance of a diverse supply network is also supported by our separate analysis of young firms, where a wider (and less concentrated) base of suppliers and customers is positively associated with the likelihood of becoming high growth at any future point.
Secondly, we find tentative evidence on the potential role of government in supporting firm expansion. High-growth firms receive their highest shares of payments from central government just before they become high growth. Subsequently, such flows become a lower share of revenue. Furthermore, the highest-growing firms are no more likely than other firms to receive payments from central government – through grants, loans, subsidies, procurement, and other payments – in the period preceding their first growth episode. In addition, their subsequent expansion coincides with new partnerships and other, non-governmental, sources of revenue. Given the experimental nature of this data, we caution against broader inferences from these findings.
Finally, we observe changes in revenue volatility as firms grow. On becoming high growth, revenue is far more stable for high-growth firms on average than for firms that grow more slowly. When looking at changes in demand volatility over time for high-growth firms, we find that volatility appears to be higher before high growth and falls once growth begins. This observed pattern may reflect a period of adjustment as firms move into a period of high growth, and this change in demand volatility is likely an effect of growth rather than a cause.
Overall, our experimental analysis of financial transactions data describes how supply networks of high-growth firms are systematically different from other firms and highlights areas for further research to understand the causes and implications of these differences.
Understanding high-growth firms and their networks using financial transaction data
Our analysis builds on the experimental financial transaction data from the Bacs Payment System (Bacs) and the Faster Payments System (FPS) networks, produced in collaboration with the ONS, Pay.UK and Vocalink. The data is aggregated from monthly financial inflows and outflows for accounts identified as businesses using the ONS methodology (ONS, 2026). Account-level transactions are processed by Vocalink and provided to us by Pay.UK and ONS on an anonymised and aggregated basis, according to our research specifications. It covers 2019 to 2025.[footnote 13]
This data creates a firm-level production network of domestic business-to-business payments. It does not include card or cash transactions, so it is not a complete picture of these payments, especially for retail-facing firms. This data does not include the Bank of England’s payment system for larger transactions, called CHAPS. This system tends to include larger transactions including property purchases and financial clearances between banks. The data covers around 40% of all the businesses in Companies House. Galanakis and Savagar (2025) find that approximately 40% of newly incorporated companies in Companies House appear in the Interdepartmental Business Register (IDBR), the database containing all firms who pay VAT or PAYE. This suggests that our 40% coverage of Companies House reflects most of the economically active business population, although we cannot confirm this is the same set of firms without further data linkage.
This data was validated against flows from national accounts data by Hötte (2025; 2026). For example, the total value of flows is consistent with the level and growth rate of Gross Domestic Product (GDP). The flows of payments between sectors in the financial transactions data are correlated with information from Input-Output Tables, which are derived from National Accounts.
This data includes the following measures used in the analysis in this chapter:
-
A proxy for firm turnover: the sum of all payments a firm receives, excluding those from the financial sector as we assume these are most likely to represent financing rather than revenue,[footnote 14]
-
annual volatility of turnover averaged over month to month, measured using a coefficient of variation, as an indicator of demand stability
-
measures of supply chain concentration for inputs and outputs
-
measures of the connections between firms and the importance of companies in the supply network
-
measures of flows from financial services companies, to give information on financing
-
measures of flows from government organisations, to understand the role of government
In this chapter, we are using a definition of high-growth firms as those in the top 10% of turnover growth rate distribution over 3 years. We compared definitions of high-growth firms, and distribution-based definitions capture a larger set of firms than the various OECD definitions. We recognise that the approach is this chapter is different to the widely used European and OECD definitions based on set growth thresholds.[footnote 15] However, we follow this approach for 2 reasons:
-
we use turnover, as this dataset lacks a reliable employment measure
-
we use a percentile threshold, since the data is noisier than ONS survey data. This identifies the 10% highest growing firms in the data. In contrast, the 20% turnover growth threshold returns far too many high-growth firms when compared to our work in the first chapter (as a proportion of all firms)[footnote 16]
The firms defined this way in this chapter likely substantially overlap with the cohorts of high-growth firms examined in the previous chapter but will not be identical. Notwithstanding, we consider this approach to be suitable to analyse the supply networks of fast-growing firms which is the focus of this chapter
The supply chains of high-growth firms
All firms are embedded in supply networks, which we define as the upstream and downstream linkages between suppliers and customers. In this section, we characterise the structure of supply chains for UK firms, and how they differ for high-growth firms.
We focus on the business-to-business elements of supply chains based on financial transactions between firms, rather than business relationships with end consumers. While we compute a variety of supply chain measurements (see A.38 in the Appendix for a full list of variables), our headline metrics are:
- upstream and downstream concentration: the Herfindahl-Hirschman Index (HHI)[footnote 17] of a firm’s suppliers (upstream) and buyers (businesses that are downstream)
- number of partners: the number of suppliers and buyers
- the importance of the largest supplier or customer: the share of incoming (outgoing) payments that comes from (goes to) the largest buyer (supplier)
A simplified visualisation of these supply chain metrics is shown in Figure 20. The example firm has 3 suppliers and 8 buyers, with variation in the relative importance among these partners. We measure upstream and downstream HHI based on the distribution of input and revenues shares. The largest partner shares are highlighted, for the most important buyer and seller.
Figure 20 - Visualisation of supply chain metrics for an example firm
Stylised network for a single firm. Each node is a firm and each arrow a payment flow between 2 firms, with arrow width proportional to the share of the focal firm’s purchases (upstream) or sales (downstream) carried by that linkage. The dark blue node and arrow in each direction mark the firm’s largest supplier and largest buyer. The panel on the right defines the 3 measures and reports their values for this example firm. Illustrative example, not based on observed data.
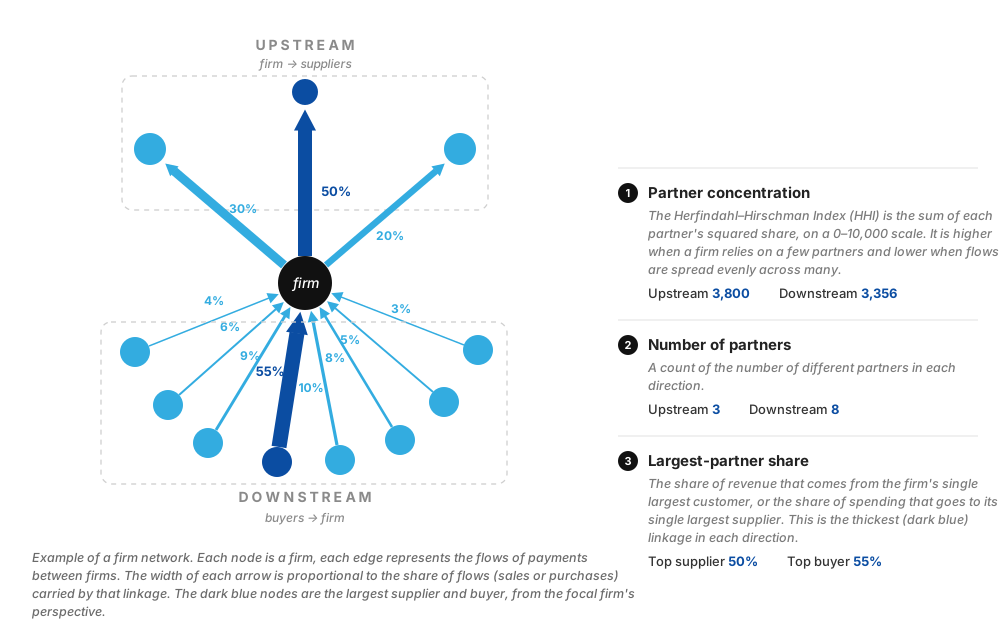
Network diagram showing an illustrative supply chain for a single firm. Supplier nodes are shown above the focal firm and buyer nodes below, with arrows representing payment flows. Arrow width reflects the share of purchases or sales associated with each connection. A panel on the right presents three measures of supply chain structure (partner concentration, number of partners and largest-partner share) and reports their values for this example firm.
We explore the above metrics using 3 different analytical approaches:
-
first, we make descriptive comparisons between high-growth firms and the rest of the business population. These describe the supply chain characteristics of firms once they are in a high-growth period
-
second, we test predictive associations to understand whether pre-existing differences in the level of these supply chain metrics are associated with a change in the likelihood of subsequently becoming a high-growth firm once we control for year, industry and firm effects
-
third, we look at within-firm changes over time for high-growth firms, to examine how these characteristics change as firms grow
On average, high-growth firms have different supply chain structures
First, our descriptive comparisons explore differences in average levels of the above supply chain characteristics between high-growth firms and the rest of the business population.
When looking at the importance of downstream trading partners (customers) for high-growth firms, Figure 21 shows that, on average, high-growth firms have a less concentrated customer base, with a 16% lower HHI. However, they have fewer customers, and their largest customer makes up a larger share of their revenue.[footnote 18]
We also examine the importance of upstream trading partners (suppliers) and find that high-growth firms have a less concentrated supplier-base, with a 23% lower HHI. They also have around 15% more suppliers. However, a greater share of their spending goes to their largest supplier. Overall, these patterns suggest that high-growth firms more often combine a deeper relationship with their largest supplier with a more diversified network of suppliers.
Our analysis also shows that high-growth firms play an important role in supply chains (see Table A.2 in the Appendix). First, they are important suppliers and buyers to their trading partners. We test this by exploring the share of a given firm within the spending or turnover of its suppliers or customers. High-growth firms have a greater average share of those payments than other firms. Secondly, high-growth firms have more connections with other high-growth firms than other firms do.
Figure 21 - Buyer and supplier concentration is lower for high-growth firms
Bar chart comparing high-growth firms with all other firms across 3 measures of supply chain structure (Concentration (HHI), number of partners, and largest partner’s share). Concentration and partner counts are percentage differences; the largest partner’s share is a percentage-point difference. Suppliers are upstream (the firm’s outflows); customers are downstream (the firm’s inflows). Firm characteristics are measured over 2020 to 2023. Experimental financial transaction data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
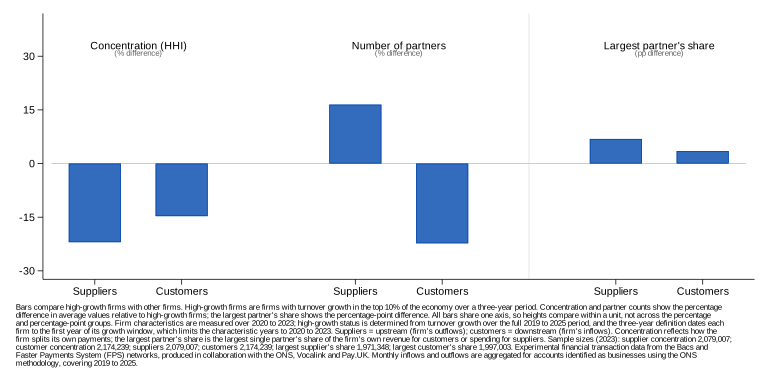
3-panel bar chart comparing differences between high-growth firms and other firms across three measures of supply chain structure: concentration (HHI), number of partners and largest partner’s share. Each panel shows separate bars for suppliers (upstream) and customers (downstream). Concentration and partner counts are displayed as percentage differences, while largest-partner share is shown as a percentage-point difference.
The structure of supply chains is predictive of future high growth, more so than the number of relationships alone
Through an analysis of predictive associations, we investigate which supply chain characteristics are associated with increased or decreased likelihood of any firm in our sample immediately starting a high-growth period.[footnote 19] We control for unobserved firm and year effects with fixed effects.
Our findings show the importance of examining the structure of a firm’s production network, beyond simply counting network relationships. Figure 22 shows that the association with the number of customers is imprecisely estimated, and the number of suppliers to a firm has a negligible association with whether that company is high growth. On the other hand, there is a clear negative association between the largest customer share and the likelihood of immediately starting a high-growth period.
Figure 22 - A range of characteristics have significant associations with future growth status
Percentage-point change in the probability of entering a high-growth period associated with a one standard deviation increase in each characteristic. Points show coefficient estimates and bars show 95% confidence intervals from separate univariate linear probability models with year and firm fixed effects and standard errors clustered by firm. Experimental financial transaction data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
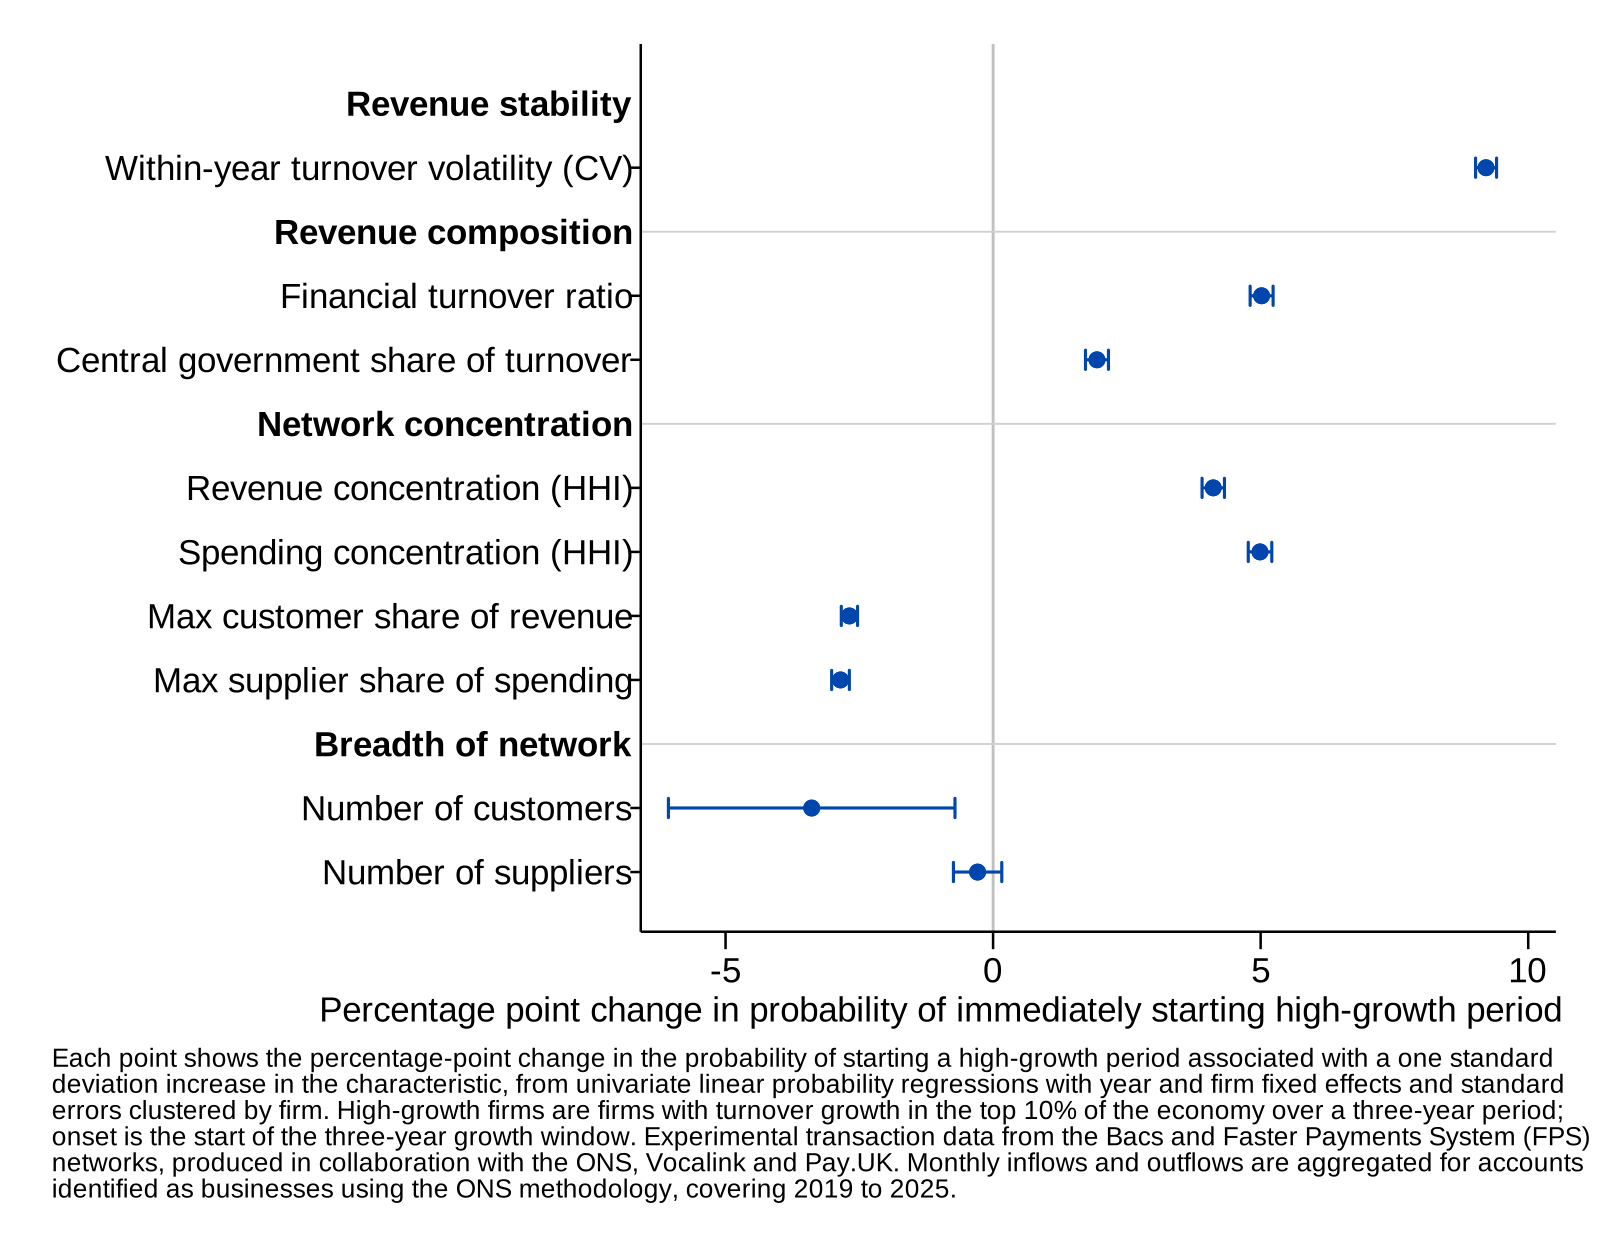
Coefficient plot showing estimated associations between nine firm-level characteristics and the probability of immediately starting a high-growth period. Characteristics are grouped into 4 categories: revenue stability, revenue composition, network concentration and breadth of network. Points show coefficient estimates and horizontal lines show 95% confidence intervals.
The concentration of suppliers and customers is also important. More concentrated inputs or outputs – as measured by a firm’s upstream or downstream HHI – are positively associated with subsequently becoming a high-growth firm. Combined with the finding on the largest customer share, this suggests that prior to becoming high growth, firms simultaneously rely less on their largest customer and distribute their sales over a narrower range of other partners.
The networks of young firms are predictive of whether they later become high-growth firms
In Figure 23 we look at predictive associations for a subgroup incorporated at the start of our sample period (and therefore those firms we can identify as “young”) and ask which of these firms become high growth at any point later in their life (within the window we observe firms in this dataset). Analysis of this sub-group complements the analysis of the whole high-growth firm cohort discussed above and allows us to explore whether supply chain characteristics matter differently for these young firms.
For these young firms, the breadth of their network in the first year or 2 is the strongest signal of subsequent high growth: a wider base of suppliers and customers is positively associated with becoming high growth at any future point. Supply chain concentration points the other way: higher upstream and downstream HHIs are associated with a lower probability of ever becoming high growth.
A firm’s centrality, which captures whether it is connected to large, well-connected partners, adds little beyond the simple number of partners. Overall, this suggests that what matters for young firms is establishing broad trading relationships early in their life, more than being connected to a few central firms. These associations hold after accounting for a firm’s size at the start, its industry, and the year it was incorporated, so they are not simply a reflection of larger firms having more partners.
The pattern of these results is notably different from the associations discussed above for the likelihood of all firms immediately entering a high-growth period. This may suggest that the role of supply chains in subsequent high growth varies depending on the age of the firm in question. Alternatively, as this analysis looks at whether young firms become high growth at any point in future, these results could be showing that longer term associations between supply chain characteristics and future high growth are different from the associations with immediately entering a high-growth period analysed in the previous sub-section. For young firms, the results suggest an increased importance in being able to access a wide base of suppliers and potential customers at an early stage in their growth.
Figure 23 - Young firms with more diversified supply networks are more likely to become high-growth firms
Estimated change in the probability of becoming a high-growth firm within the next 3 years associated with a one standard deviation increase in each characteristic. Suppliers are upstream partners, receiving the firm’s outflows; customers are downstream partners, sending the firm’s inflows. Concentration is measured by the Herfindahl-Hirschman Index (HHI) over the firm’s own payment shares. Experimental financial transaction data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
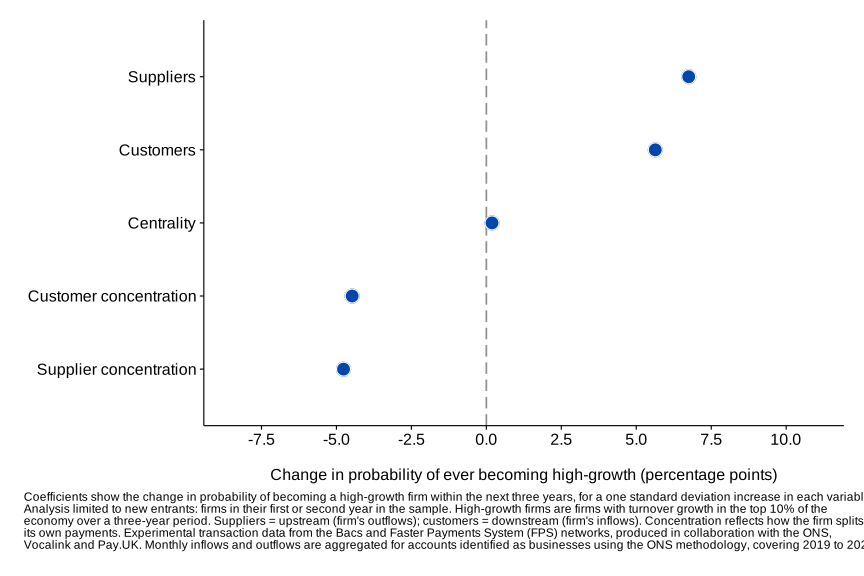
Coefficient plot showing estimated associations between five firm-level characteristics and the probability of a new entrant becoming a high-growth firm within the observed period. The characteristics are the number of suppliers, number of customers, centrality, customer concentration and supplier concentration. Points show coefficient estimates, and the dashed vertical line marks zero.
Firms’ supply chain characteristics change as they enter a period of high growth
To further explore the supply chain characteristics of high-growth firms, we look at within-firm changes over time and analyse how these characteristics change before and after entering a period of high growth. We show these changes in descriptive event study plots, where we control for firm-specific and year-specific factors using fixed effects.
Following the start of their first high-growth episode, firms experience a substantial fall in both upstream and downstream concentration (as shown in Figure 24 for customers). In principle, this could be due to re-allocation between existing partners, the addition of new partners, or a combination of both. We find suggestive evidence that the observed decrease in concentration may be driven by a rise in the number of partners more than a reallocation of transactions among existing partners. Both upstream and downstream, high-growth firms experience a sharp increase in the number of supply chain linkages after becoming high growth (as shown in Figure 24).
Finally, we also find that high-growth firms depend more on their largest customer and largest supplier once they become high growth. This increased share of payment flows from their largest customer and to their largest supplier would on its own tend to increase concentration. However, the effects of more supply chain linkages more than counteract this – resulting in the overall reduction in concentration (HHI) discussed above. Firms rebalancing across their partners outside their top partner could also contribute to this result.
Overall, this set of results on changes in these characteristics is consistent with our discussion above of the difference in average levels of the same characteristics between firms within a high-growth period and other firms. We see that high-growth firms experience a fall in supply chain concentration, an increase in the number of trading partners and an increase in their reliance on their top partner. As these firms grow, they deepen their key relationships, while also creating new partnerships.
Our results show changes in firms’ supply chain characteristics as they grow
Taken together, our 3 analytical approaches highlight how supply chains evolve as firms grow. Taking supplier and customer concentration as an example, a higher initial level of concentration is associated with an increased likelihood of subsequently becoming high growth (when looking at the overall population of high-growth firms).[footnote 20] As firms become high growth, their supplier and customer concentration falls which is consistent with the finding that on average, high-growth firms have less concentrated supply chains than other firms. The descriptive nature of this analysis, however, does not allow us to determine conclusively if these observed patterns are a result of fundamental differences between the types of firms that grow quickly and those that don’t, or if they reflect changes that occur as firms become high growth.
Figure 24 - Fall in concentration among customers and a steady rise in the number of customers once a firm becomes high growth
Revenue concentration and the number of customers around the onset of high growth. Top panel: revenue concentration, measured by the Herfindahl-Hirschman Index (HHI) over customer shares; bottom panel: the count of distinct customers. Points show estimated within-firm changes relative to the year before onset, with line segments showing 80%, 90% and 95% confidence intervals. All models include firm and year fixed effects, with standard errors clustered by firm. Experimental financial transaction data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
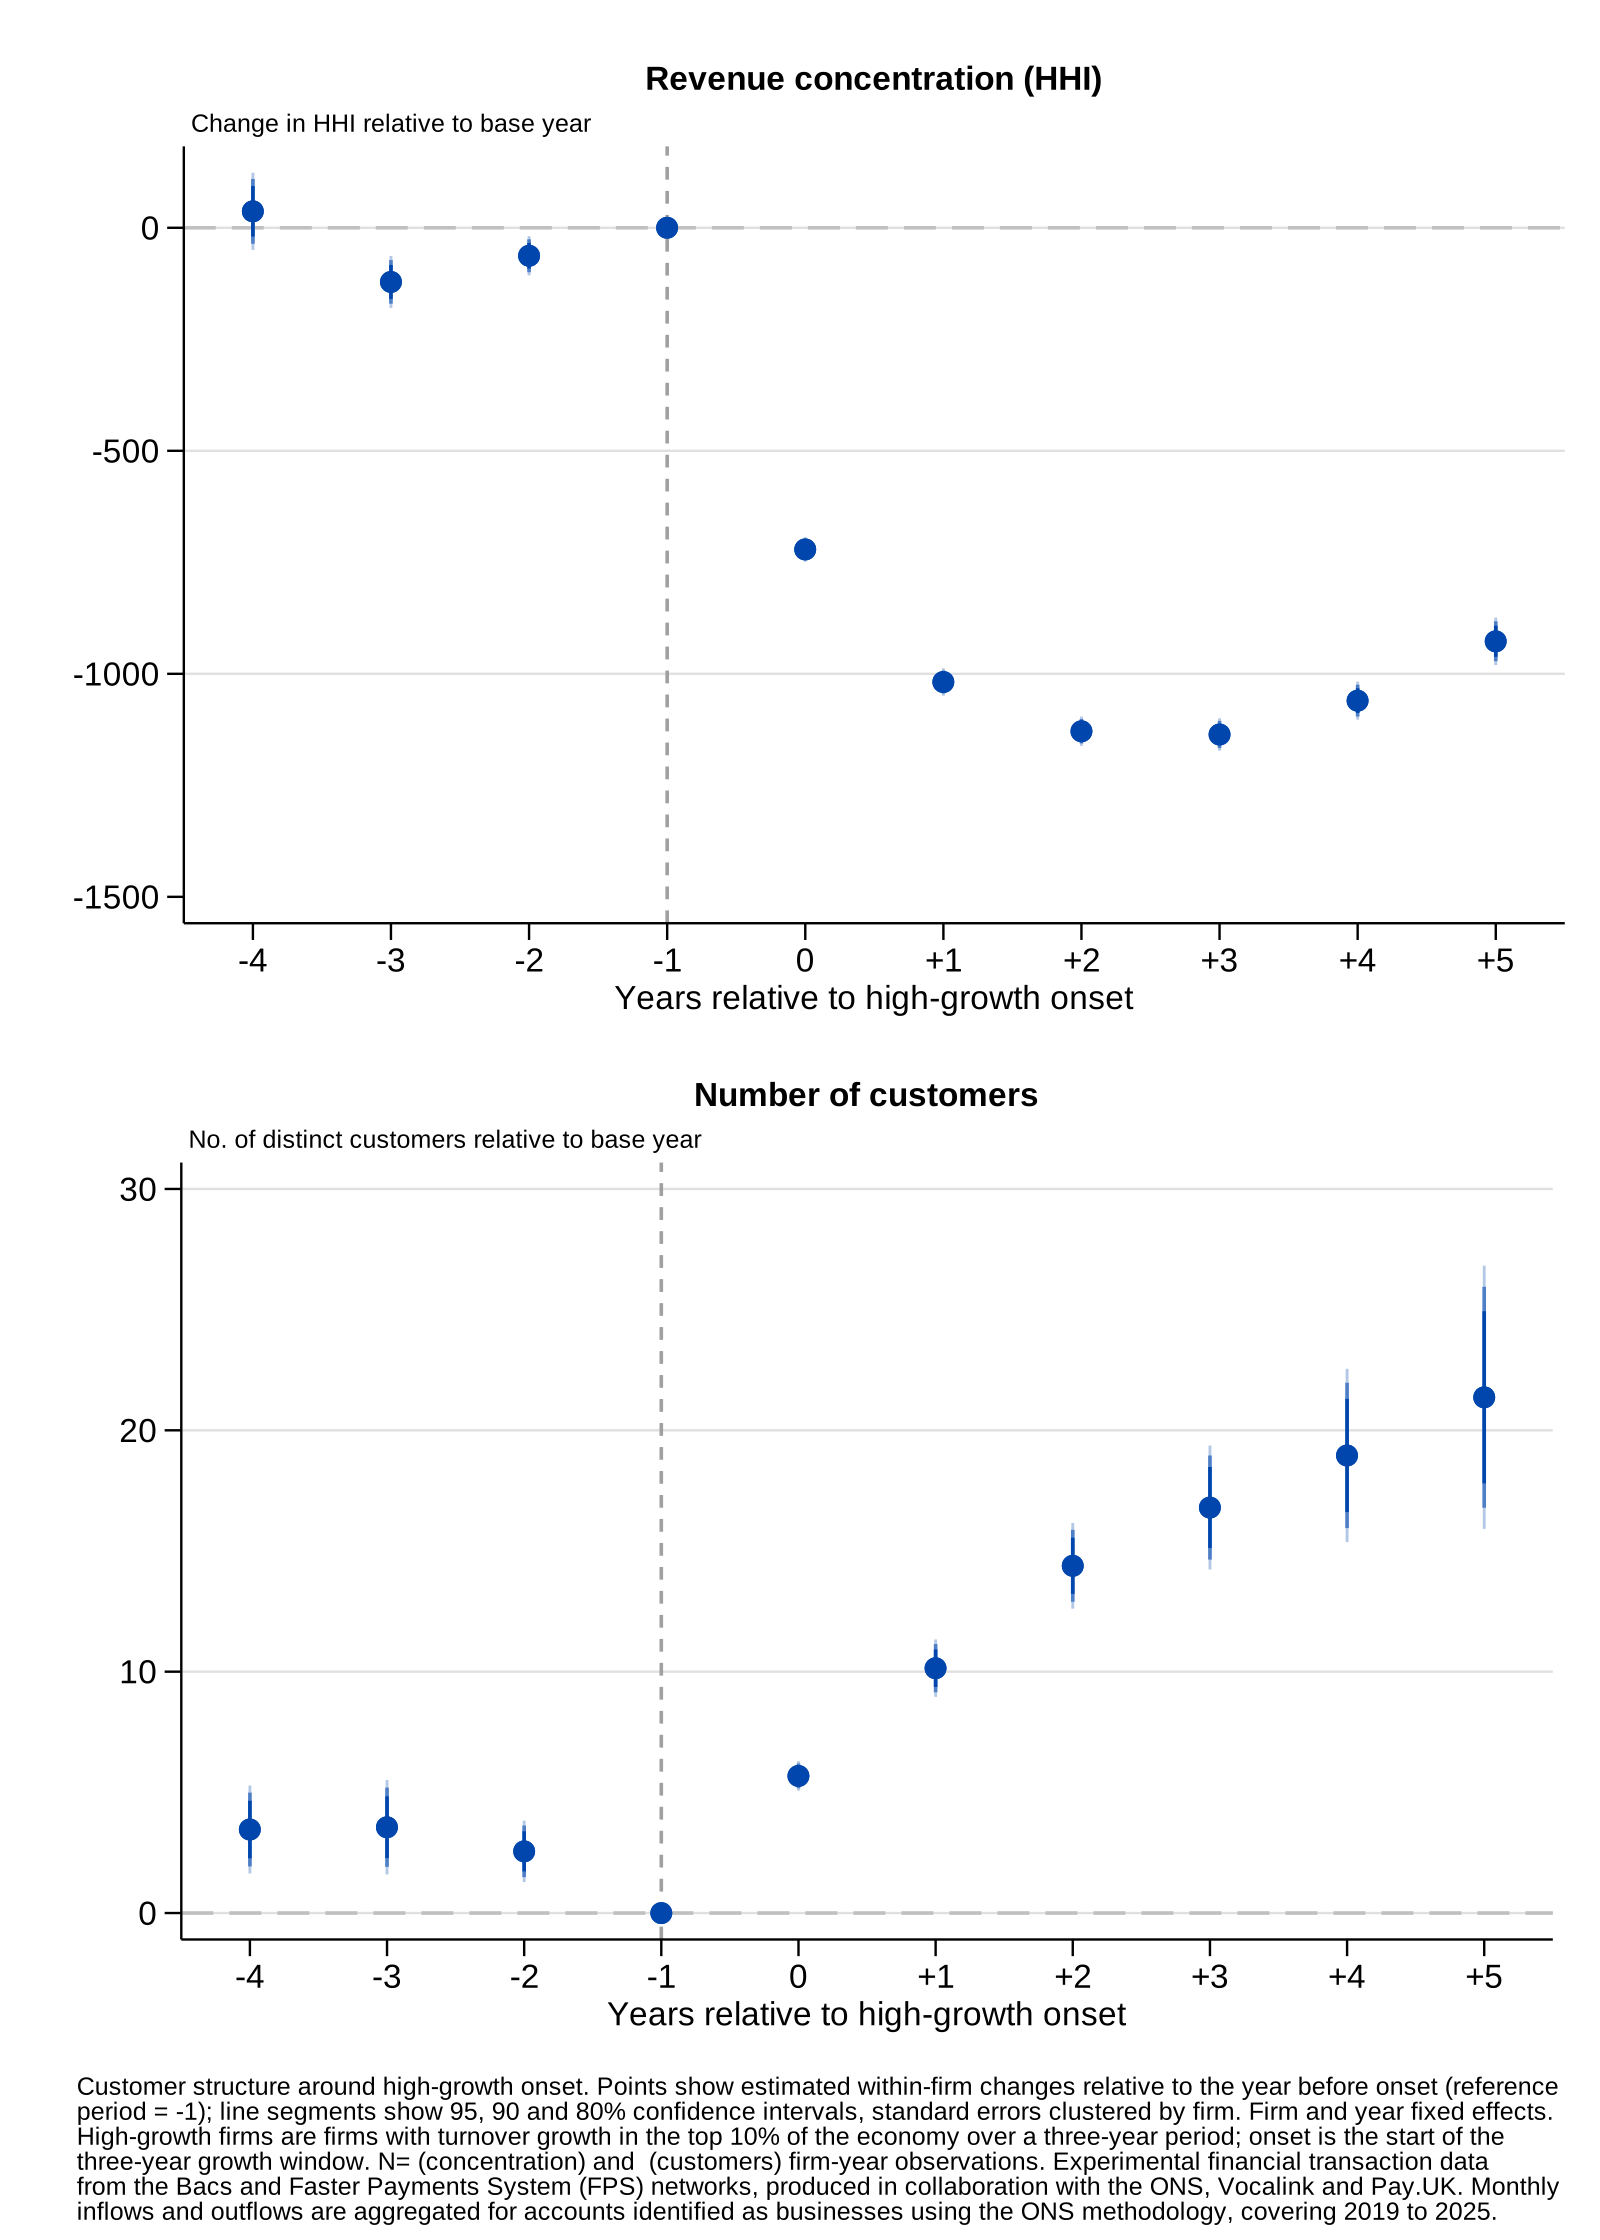
2-panel event study showing changes in customer concentration (top panel) and the number of customers (bottom panel) around the onset of high growth. The horizontal axis shows years relative to high-growth onset. Points show estimated changes relative to the year before onset, and vertical lines show 80%, 90% and 95% confidence intervals.
Composition of high-growth revenues
High-growth firms may benefit from or be constrained by access to certain sources of capital and revenue, as discussed in our literature review on investment and competition over the business lifecycle (CMA, 2025). For example, both government and finance payments may be important sources of growth for firms. Government contracts, subsidies, or loans may be critical for young firms or those in nascent industries. Such sources of capital may support firms bringing new products to market and can provide a marker of quality to other potential investors. Financial institutions can support firm growth in their early stages or through difficult periods, for example by providing start-up capital that is necessary for future growth. We investigate the importance of both payment types.
Government revenue shares are highest before high-growth episodes
The data we use allows us to measure payment flows from central government.[footnote 21] This includes a range of payments which we cannot separately identify, covering contracts to supply goods or services to government and subsidies, grants, loans, and other forms of business support.[footnote 22]
We examine the data in 3 ways. First, we make descriptive comparisons between the average share of central government payments received by firms at the start of a high-growth episode and the average of all other firms. Second, we examine the predictive associations between central government inflows and the likelihood of becoming a high-growth firm. Third, we examine within firm changes over time to show how payments from central government evolve before, during and after firms’ first high-growth episode.
Firstly, our descriptive comparisons show the share of turnover from central government is around 7% for both high-growth firms (in the first year of their high-growth episode) and for other companies in the data. Given these are shares of revenue, this finding could be interpreted in 2 ways. On the one hand, equal shares in the 2 groups could indicate that such payments are received in similar proportions by both current high-growth firms and others. On the other hand, this similarity in averages could mask where firms received a substantial share of revenue from government prior to becoming high growth, and then subsequently scaled up their revenue from other sources during a high-growth period. In addition, these 2 groups of firms are different in many ways (for example size, age, sector), so this is not a like-for-like comparison.
Secondly, we use descriptive panel regressions to examine the predictive associations between payments from central government and the probability of becoming a high-growth firm in the future. Once we control for industry and macro trends, firms with a higher share of revenue from central government are more likely to start a high-growth episode in the following year. A one standard deviation increase in the share of payments from government is associated with a 1.9% increase in the probability of immediately starting a high-growth period.[footnote 23]This may suggest a role for government in increasing the likelihood of future growth, but the descriptive and experimental nature of this analysis means we interpret this result with caution.
Finally, we investigate how payments from government change around the time of a high-growth episode. We show how they evolve within a firm before, during and after its first high-growth episode. Our results are robust to macroeconomic trends, and we control for either firm or industry effects. Each version has a slightly different interpretation. When we control for firm-specific effects we describe how government flows to high-growth firms change relative to each high-growth firm, so we obtain an average profile for high-growth firms. When we control for industry-specific effects, we compare high-growth firms to the rest of their industry.
We find that inflation-adjusted payments from central government rise after a firm becomes high growth (left panel of Figure 25). On the other hand, we find a sharp drop in the share of this revenue once a firm becomes high growth (right panel of Figure 25). This is because payments coming from the private sector are growing faster than those from government. While flows from government may still be playing a foundational role in fast growth, this implies they are not the primary source of growth for these firms.
Figure 25 - Steady fall in share of turnover coming from government payments but an increase in levels once a firm becomes a high-growth firm
Event study of central government revenue around high-growth onset. Top panel shows central government payments as a share of non-financial turnover. Bottom panel shows the underlying level in real terms. Points show estimated within-firm changes relative to the year before onset, with line segments showing 80%, 90% and 95% confidence intervals. Regressions include firm and year fixed effects, with standard errors clustered by firm. Experimental financial transaction data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
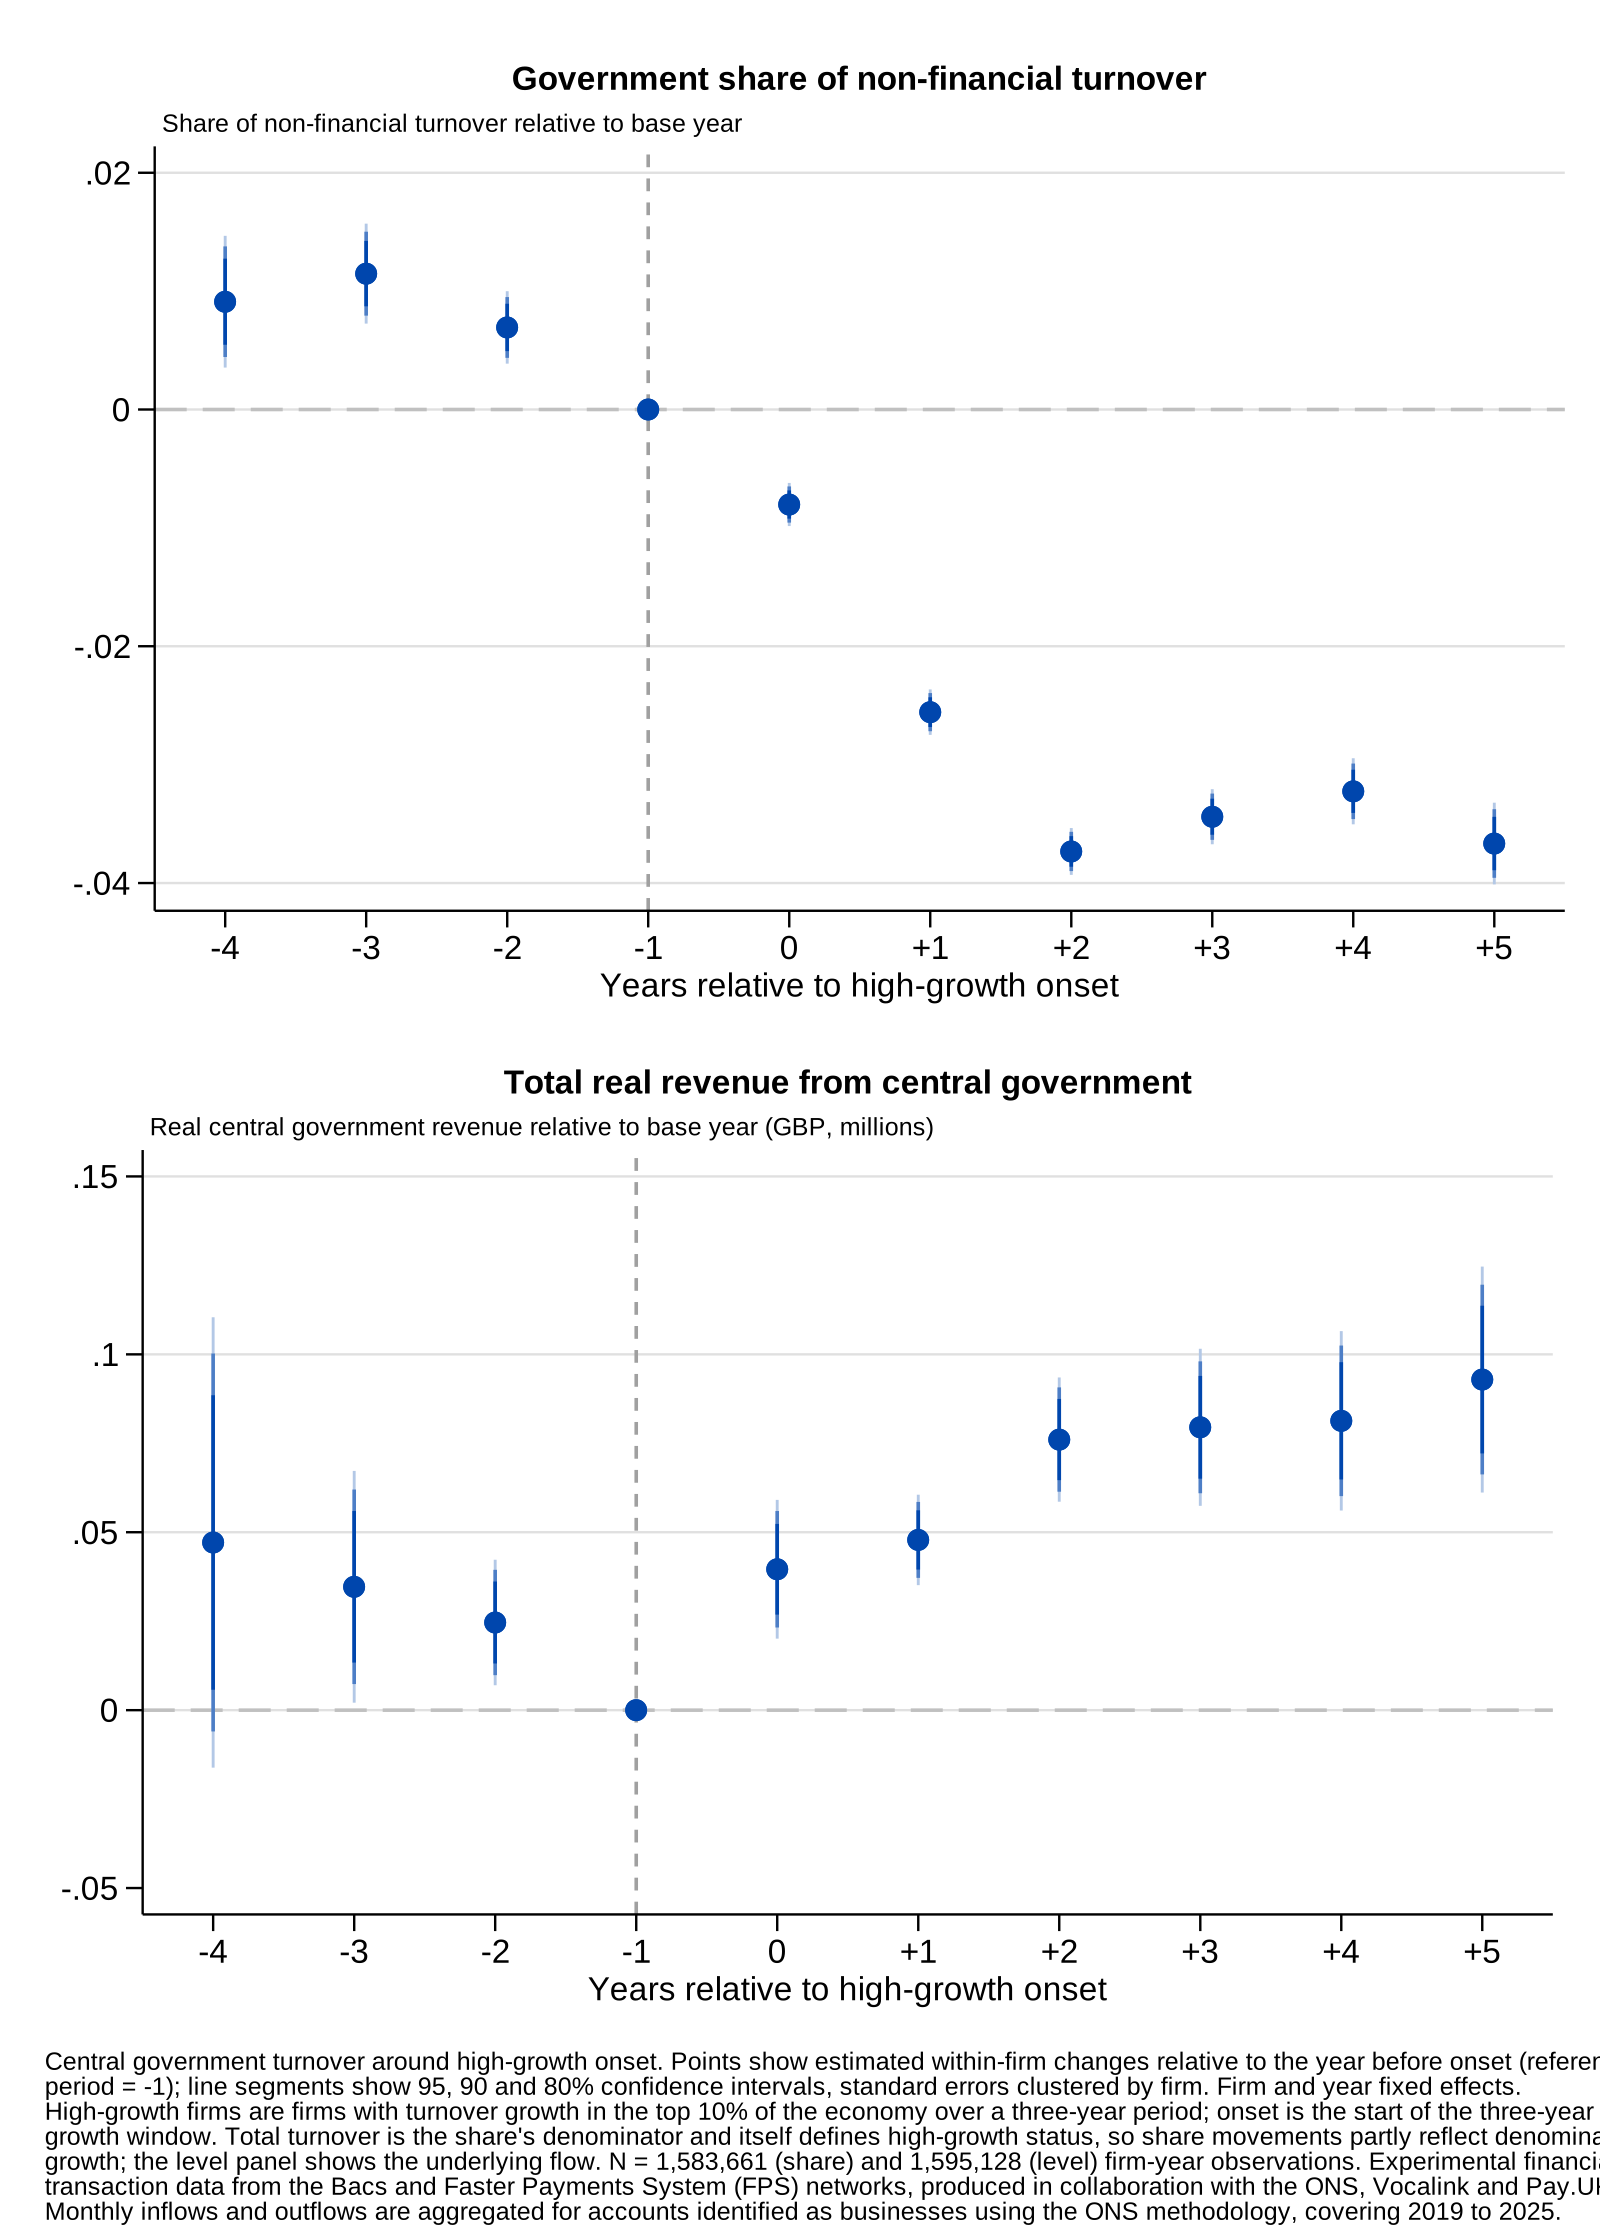
2-panel event study showing changes in central government revenue around the onset of high growth. The top panel shows central government revenue as a share of non-financial turnover, and the bottom panel shows total real revenue from central government. Points show estimated changes relative to the year before onset, and vertical lines show 80%, 90% and 95% confidence intervals.
The relative importance of financial flows peaks before high-growth episodes
Our data also allows us to separate out payments from firms in the financial sector.[footnote 24] These payments may represent a wide range of transactions, including financing and intermediary roles. These flows will include bank lending to start-ups but could also include a financial firm providing a service, such as payroll administration or invoicing.
Looking at descriptive comparisons, payments from the financial sector relative to turnover are slightly lower for high-growth firms compared to other companies. The ratio is 5.7% for high-growth firms and 6.4% for all other firms.
In our regressions testing predictive associations, we find that a one standard deviation increase in the share of payments from finance is associated with a 5% increase in the probability of a firm immediately starting a high-growth period. These results are robust to controlling for year, industry and firm-level effects.
Figure 26 shows how flows from financial institutions change around the onset of high growth, based on within-firm changes over time. The right panel shows that financial flows continue to increase as firms grow. However, the left shows financial flows as a share of total inflows peak before the onset of high-growth and fall during growth. There is also some indication that once high growth subsides, financial flows start to increase as a share of total inflows. These results are robust to controlling for industry and firm-level effects. Whilst we interpret this with caution, these results may reflect that securing finance is an important precursor to future and sustained growth.
Figure 26 - Finance inflows grow after high-growth onset while non-financial inflows grow faster
Event study of turnover from financial payers, excluding insurance, around high-growth onset. Top panel shows finance inflows as a ratio to non-financial inflows. Bottom panel shows the underlying level in real terms. Points show estimated within-firm changes relative to the year before onset, with line segments showing 80%, 90% and 95% confidence intervals. Regressions include firm and year fixed effects, with standard errors clustered by firm. Experimental financial transaction data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
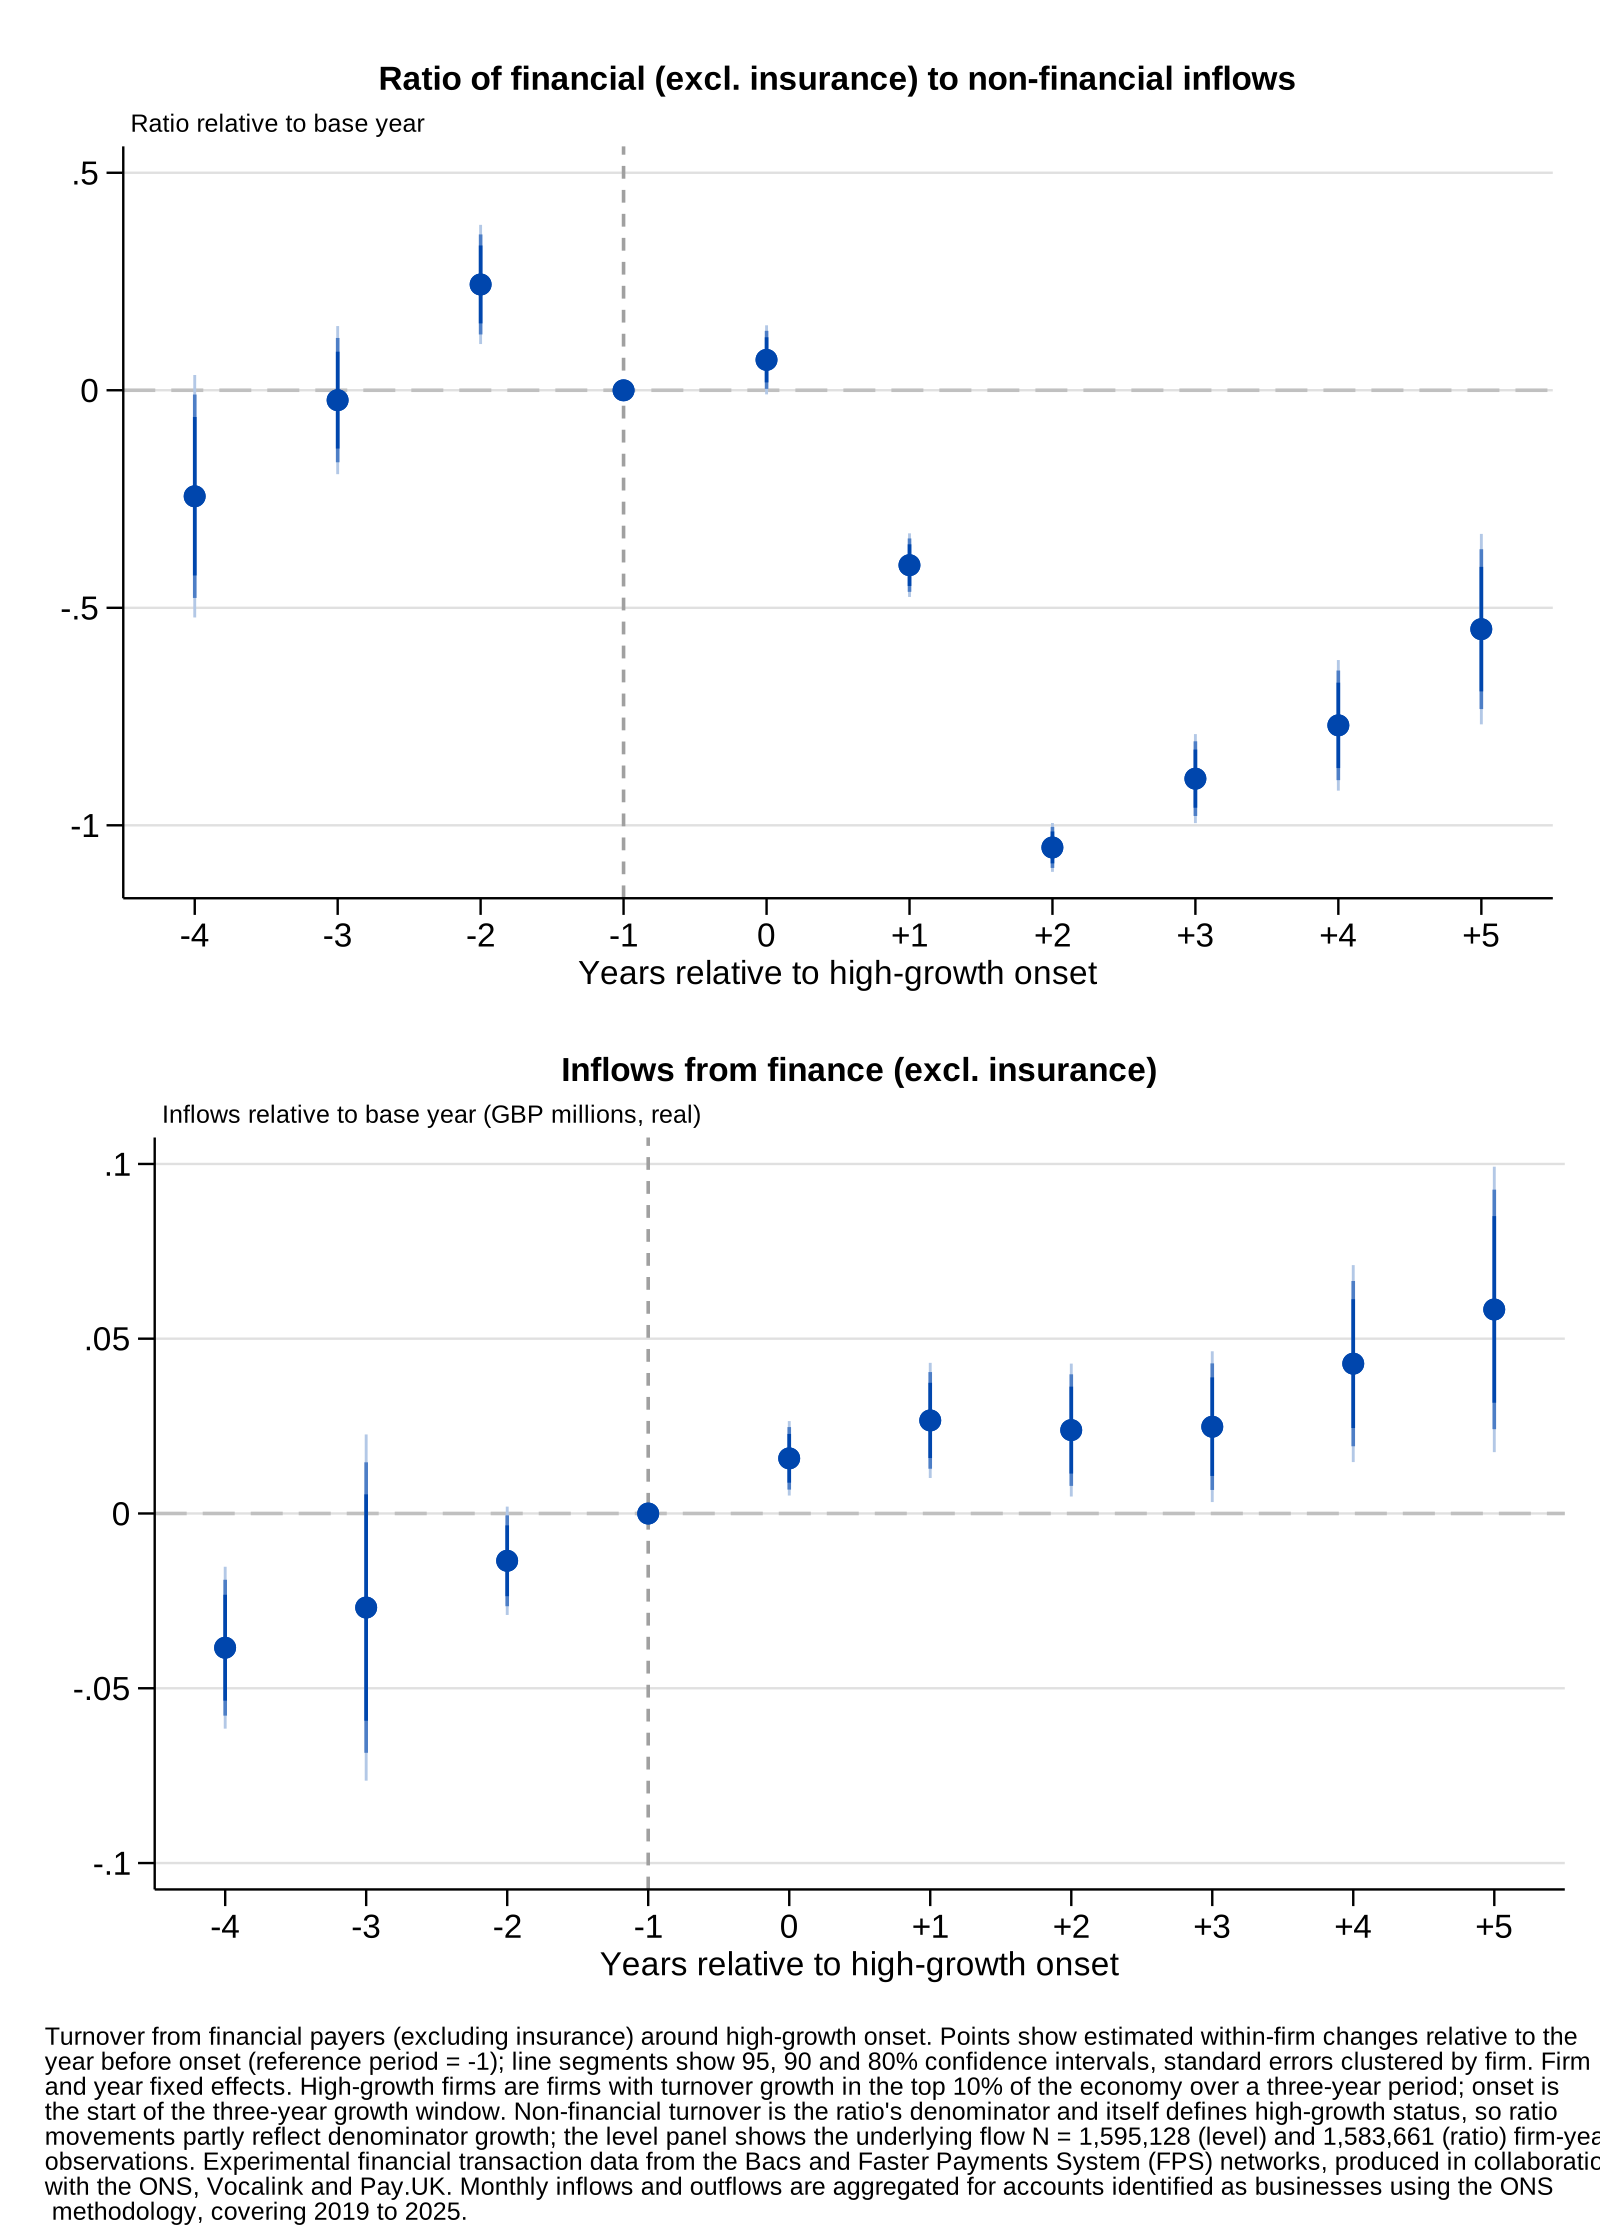
2-panel event study showing changes in turnover from financial payers around the onset of high growth. The top panel shows the ratio financial to non-financial inflows, and the bottom panel shows the real inflows from finance. Points show estimated changes relative to the year before onset, and vertical lines show 80%, 90% and 95% confidence intervals.
Demand stability of high-growth firms
High-growth rates require sufficient demand but may also benefit from a sufficiently stable demand environment. Bloom et al. (2006) show that uncertainty makes firms more cautious in responding to demand shocks. Investing in capacity is largely irreversible, so firms respond to uncertainty by waiting to see how demand evolves instead of committing to investments.
We investigate the stability of firms’ demand to help explain which firms experience periods of rapid growth.
In descriptive comparisons, we find that, on average, high-growth firms have lower month-to-month volatility of turnover compared to other firms. This can be seen in Figure 27, comparing the coefficient of variation[footnote 25] for turnover (excluding finance) of high-growth firms to all other firms in the economy.
However, in our descriptive regressions examining predictive associations, more volatile sales are positively associated with becoming a high-growth firm in later years, accounting for sectoral and macro trends. A one standard deviation increase in volatility is associated with a 9.2% increase in the probability of immediately entering a high-growth period. This is robust to controlling for year, industry and firm effects.
Figure 22 compares the descriptive regression results across revenue stability, composition and network position. It shows that the turnover volatility is the strongest predictor of a firm immediately starting a high-growth period.
Figure 27 - Sales volatility is substantially lower for high-growth firms relative to other firms
Bar chart comparing high-growth firms with the rest of the business population. The outcome is the within-year coefficient of variation of monthly non-financial turnover, where higher values mean more variable revenue across the months of the year. Bars show pooled means over 2020 to 2023. Experimental financial transaction data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
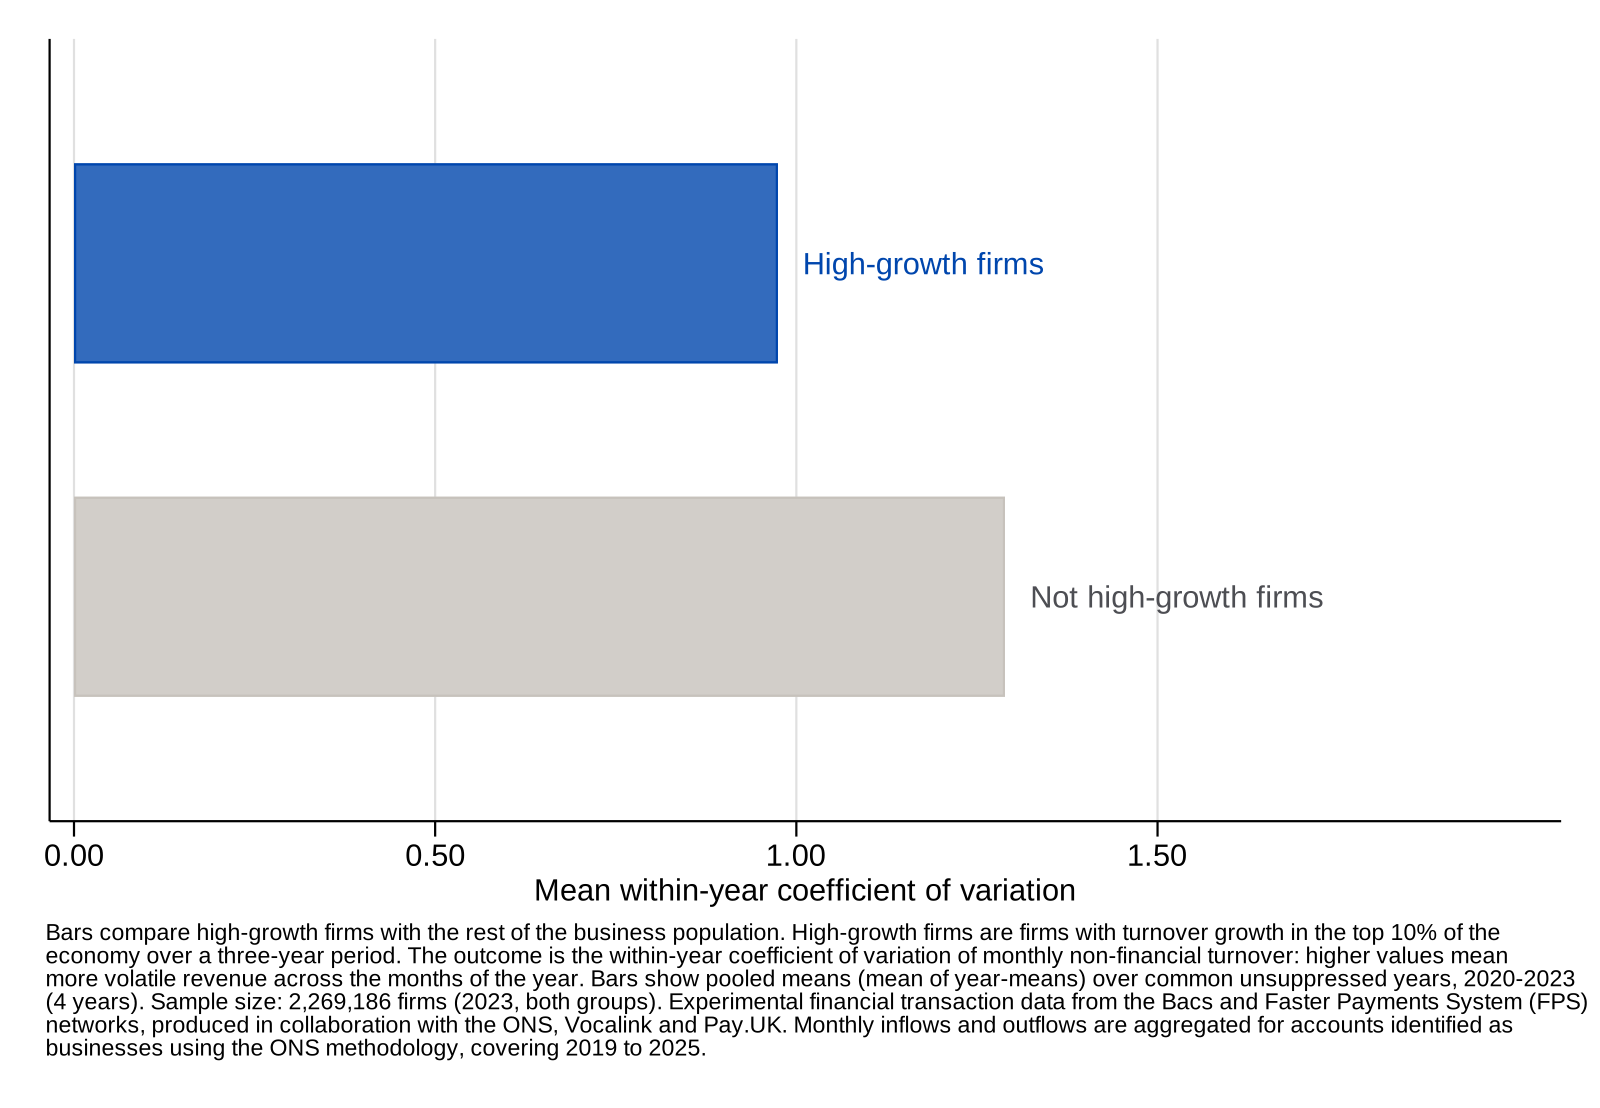
Horizontal bar chart comparing within-year turnover volatility for high-growth firms and non-high-growth firms. Two bars show the mean coefficient of variation of monthly non-financial turnover, with higher values indicating greater variation in revenue across months.
Looking at within-firm changes over time, we find that on becoming high-growth firms experience a sharp fall in demand volatility. This means such firms see increased stability of revenues as they grow. Figure 28 shows volatility peaks the year before they grow. This is robust to controlling for industry or firm-level effects and suggests that our result of lower average turnover volatility for high-growth firms is likely to be robust to these effects.
Taken together with the other results discussed above, volatility appears to be higher before high growth and to fall once growth begins. This suggests that the observed changes in volatility may reflect a period of adjustment as firms move into a period of high growth, and this is likely an effect of growth rather than a cause.
Figure 28 - Monthly turnover volatility falls once a firm becomes high-growth
Event study of revenue volatility around high-growth onset. The outcome is the within-year coefficient of variation of monthly turnover, where higher values mean more variable revenue across the months of the year. Points show estimated within-firm changes relative to the year before onset, with line segments showing 80%, 90% and 95% confidence intervals. Regressions include firm and year fixed effects, with standard errors clustered by firm. Experimental financial transaction data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
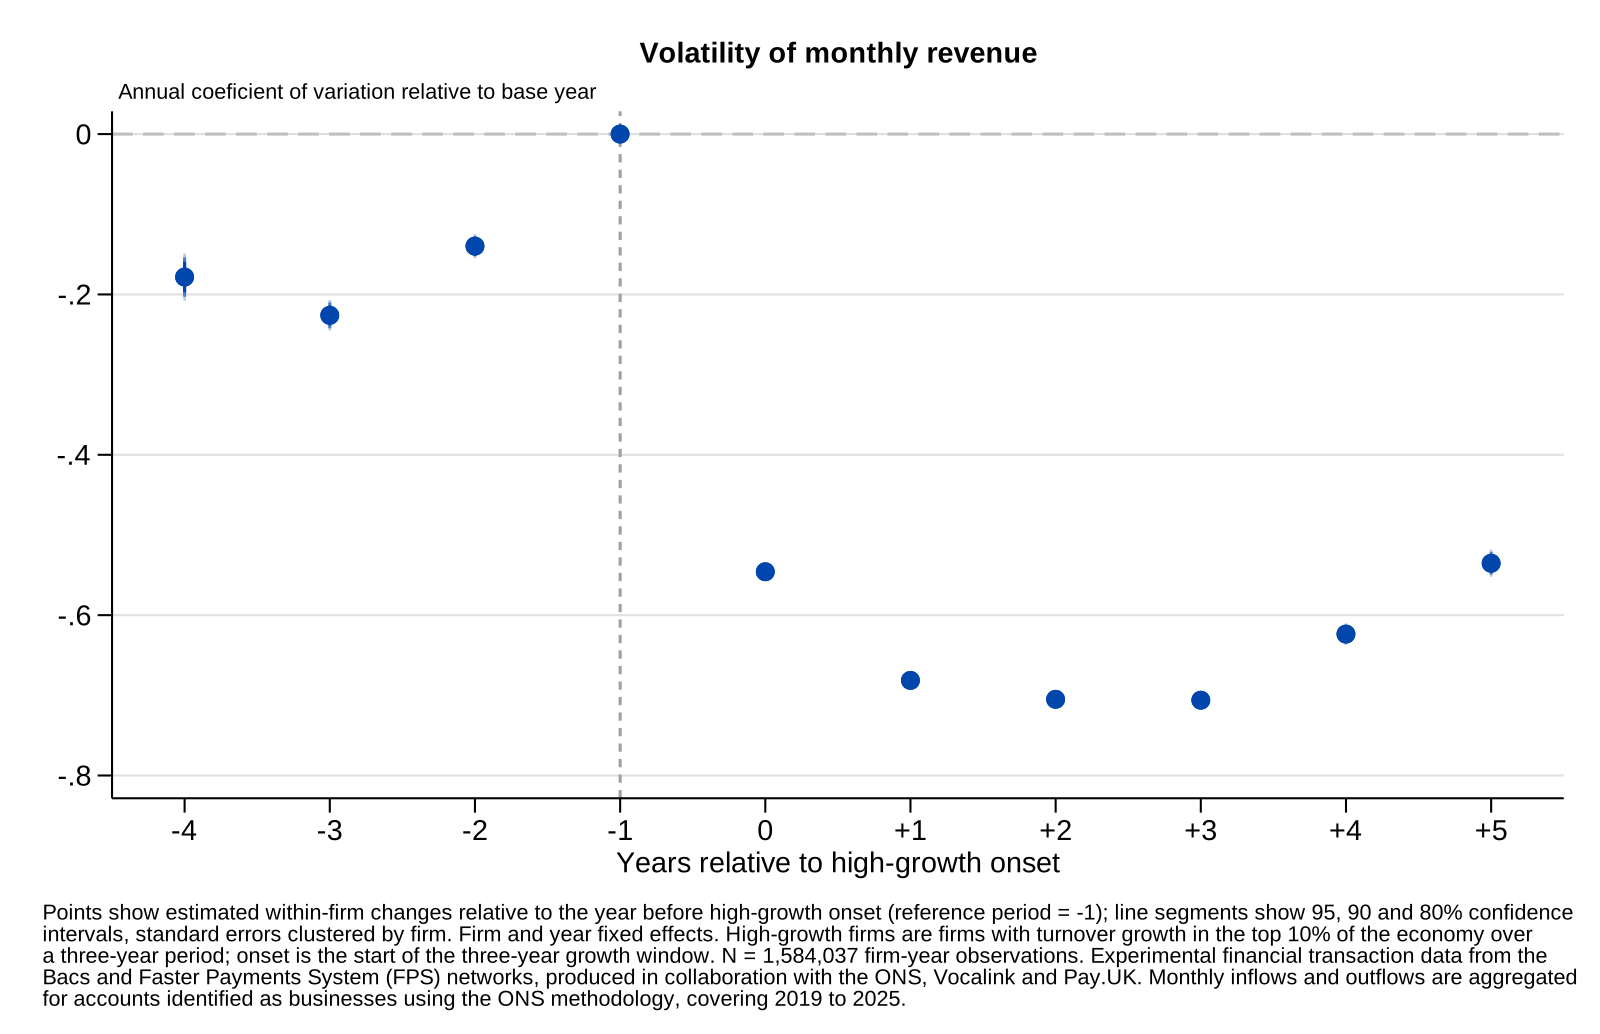
Event study showing changes in turnover volatility around the onset of high growth. Points show estimated changes in the within-year coefficient of variation of monthly turnover relative to the year before onset, and vertical lines show 80%, 90% and 95% confidence intervals.
Opportunities for future research with firm-to-firm transaction data
New large-scale data on firm-to-firm payments can help uncover important relationships that cannot be investigated with traditional economic data. This type of data is increasingly used to understand the behaviour of firms and supply networks across the world (Carvalho et al., 2021; Silva et al., 2022).
Internationally firm-to-firm transaction datasets are becoming more readily available. Researchers have begun comparing the structure and shape of countries’ national supply chains. This research has many potential applications, including improving the evidence base on supply chain resilience, growth spillovers and industrial policy (OECD, 2025a; OECD, 2025b; OECD, 2025c).
In the UK, such data are still experimental and novel; there is still a lot to learn about the linkages between firms and the structure of the production network. The Microeconomics Unit’s report on supply chains uses aggregated data from financial transactions to investigate the structure of UK supply chains.
Such data is collected from individual transactions rather than being constructed from aggregated survey data (as are traditional input-output tables, which take survey data but are made consistent with national accounts). As such, this data brings challenges as well as opportunities. For example, there is uncertainty as to whether short-run fluctuations in transactions represent changes in real economic behaviour, or payment preferences. It is also challenging to disentangle the role of financial intermediation from actual production activities. Further data development or the addition of other measures (such as improved estimates of employment) could also improve the specificity of analysis in this section, for example by allowing a more granular classification of payment types and exploration of employment growth.
Further work is necessary to establish the opportunities and limits of such data to better understand the UK economy, especially on topics including the spillover effects of firm growth and bottlenecks in the production network.
Growth signals
In this chapter, we use experimental web data to explore whether observable firm-level announcements and activities can offer a complementary approach to understanding how firms grow and identifying and tracking high-growth firms.
Firms regularly share information with the public and key stakeholders through channels including their websites, social media or media coverage. These public announcements offer a window into a firm’s current activities, strategic direction or future growth intentions. [footnote 26] Such announcements might include the launch of a new product or service, expansion into a new market or industry, the formation of a new partnership or the securing of a new round of investment or funding. We refer to these kinds of announcements as ‘signals’ or ‘growth signals’, as they may reflect activities commonly associated with firm growth (or an intention to grow).
Growth signals of this kind can complement traditional administrative and survey data, such as the data sources used in Chapter 3, which capture firm growth outcomes but often do not record the underlying activities and decisions that drive those outcomes. Signals can capture more granular and timely firm-level information on these activities and decisions, including for firms that are largely absent from administrative records, for example because they are too small to meet VAT or reporting thresholds.
Signals are observable through firms’ digital footprints and online data collection provides a scalable means of capturing them systematically. As the volume and accessibility of digital information has grown, web crawling has emerged as an increasingly common method for gathering firm-level data for research purposes. Economic applications include price measurement[footnote 27] (Cavallo and Rigobon, 2016), labour markets (Turrell, et al., 2018; 2021; Romanko and O’Mahony, 2022; Djumalieva and Sleeman, 2018), productivity (Nathan and Rosso, 2022), innovation (Ashouri et al., 2022), sector mapping (Mateos-Garcia and Richardson, 2022; Nathan and Rosso, 2015) and startup strategy and financing outcomes (Guzman and Li, 2023).
The use of web-derived data has also extended to research on high-growth firms. The ONS Data Science Campus (2019) combined administrative business data with non-traditional data sources, including web data provided by Glass.AI, to explore the characteristics of high-growth firms. The study found a higher incidence of high-growth firms among businesses with an online presence and high-growth firms to be better connected (based on online network measures). Website analysis also found that high-growth firms tend to emphasise management and team-related language on their websites, suggesting a stronger focus on people and organisational processes among these firms.
Like any data source of this kind, online data has inherent and well-documented limitations (see for example Nathan and Rosso (2022) and Ashouri et al. (2022)). Only 68% of UK businesses had a website in 2024 (DSIT, 2024) and even among those firms with an online presence, the quality, consistency and completeness of online information vary considerably across firms. Less digitally engaged businesses are therefore likely to be underrepresented in the data. Coverage is also likely to be less complete in earlier years of the dataset because web content and platform usage changes over time and some information may no longer be available to scrape.
Bearing these limitations in mind, in this chapter we focus on where analysis of signalling firms can be informative in identifying fast growing firms, and how this compares to high-growth firm definitions used elsewhere in this report. Before doing so, we describe the dataset and the nature of growth signals and signalling firms, to explore the insights web data can provide into how firms grow. We specifically look at:
-
signals coverage and common patterns in the way firms signal,
-
how signalling firms are distributed across industries and regions and the characteristics of signalling firms compared to non-signalling firms
-
whether signalling firms grow their employment faster than non-signalling firms [footnote 28]
-
if signalling firms overlap with high-growth firms and what, if anything, distinguishes high-growth firms from the average firm in terms of signals they display
-
an exploratory analysis of whether signals can predict subsequent firm employment growth
We find that firms that issue growth signals are systematically different from firms that do not. Signalling firms tend to be larger, in terms of employment, than non-signalling firms. Among firms that signal, size is also associated with both the type and greater variety of signals displayed: firms displaying investment signals are considerably larger on average than those displaying other signal types (hiring, entry and innovation, and collaboration), and firms displaying multiple signal types also tend to be larger firms.
Importantly, signalling firms are not only large but they also grow their employment faster than non-signalling firms, and they create more and destroy fewer jobs than their size would suggest. Among signalling firms, those with investment or hiring signals, or displaying a wider variety of signals, grow the fastest.
Firms identified as high growth are more likely to display growth signals than the average firm in our data. Additionally, when these firms signal, they tend to do so more frequently than the average signalling firm. There is some evidence that high-growth firms issue significantly more hiring, investment and collaboration signals than non-high-growth signalling firms. Given the uneven coverage of growth signals across sectors, growth signals are likely to be most useful as a tool for identifying high-growth firms and those that have the potential to become high-growth firms within specific sectors rather than across the economy as a whole.
Our exploratory analysis does not allow us to conclude that signals are predictive of subsequent firm growth, largely due to current data limitations. However, we find evidence of a partial but discernible overlap between high-growth firms and signalling firms. This suggests that signals could help identifying fast growing businesses in a timelier way and potentially capturing businesses that are less visible in more traditional data sources.
Signals and signalling firms
Growth signals collection and coverage
The analysis draws on a custom-built dataset of growth signals, which was commissioned from Glass.AI (Telectica Ltd) through a public tender process. Glass.AI researched the available online activity of UK firms with a web presence in late 2025, to identify and classify growth signals (as described further below). The dataset covered around 1.8 million UK firms with a web presence (equivalent to around 32% of the estimated private sector business population).[footnote 29]
These firms were then matched to Companies House records to obtain employment, turnover and firm characteristics (for example, firm age and sector). A total of 39% of businesses were successfully matched. Among matched firms, employment data is available for around 62% of firm-year observations and turnover data for only 8%.[footnote 30] Given its considerably better coverage, we use employment data throughout the analysis in this chapter.
It is worth noting that employment data is only available up to 2024 due to lags in firms submitting financial reports. This limits the analysis in 2 respects: first, growth signals recorded in 2025 cannot yet be linked to firm-level outcomes and secondly, we cannot yet observe firms’ economic performance in the years following the most recent growth signals in 2025.
Finally, as the dataset draws on multiple online sources, the same signal for an individual firm may be captured more than once across different platforms. Without accounting for this, signal counts would risk reflecting the volume of online coverage rather than the number of distinct growth events. This is a well-documented issue in web data (Romanko and O’Mahony, 2022), that we address by removing duplicate signals at the firm level, ensuring each signal in the dataset represents a unique firm-level activity.
For the analysis that follows, the sample is restricted to firms matched to Companies House data over the period 2020-2025, with firm-year as the unit of observation.[footnote 31] The sample covers approximately 1.0 million unique firms. Approximately 38,000 firms (3.8% of firms in our data) display at least one growth signal over the period 2020-2025, accounting for around 81,000 individual signals.[footnote 32] Firms can display multiple signals of the same or different type within the same year and can exhibit signals in one year but not another.
We use 23 different growth signals in our data. These signals are grouped into 4 categories, summarised in Table 2. Collaboration signals capture external relationships and partnerships that can open new markets and revenue streams. Entry and innovation signals relate to product development and market expansion, reflecting a firm’s longer-term growth strategy. Investment signals reflect access to capital, which is a prerequisite for scaling. Hiring signals reflect a firm’s intention to expand its workforce and announcements of key hires.
Together these categories capture different dimensions of firm growth and draw on a range of publicly available data (such as companies’ websites, news sources, LinkedIn).
Table 2 - Growth signals categories
| Description | Signals | Data from | |
|---|---|---|---|
| Collaboration | Partnerships and external relationships | Joint ventures, industry awards, engagements, new partners, research partners, new customers, new suppliers | Company websites, news sources, social media |
| Entry & Innovation | Signals of market expansion or product development | New products, new services, entry into new industries, entry into new geographic markets, new premises | Company websites, social media, news sources |
| Investment | Capital raising and investment activity | Initial public offerings (IPOs), mergers and acquisitions (M&A), debt financing, private equity, venture capital, public funding, other investment activity | Company websites, news sources, official government sources, contracts finder |
| Hiring | Workplace expansion | Hiring plans, job listings, key hires, other hiring activity | Company websites, LinkedIn, recruitment platforms |
Among signalling firms, hiring is the most common signal type (displayed by 44% of signalling firms), followed by entry and innovation (41%), collaboration (37%), and investment (16%).
The coverage of growth signals increases considerably over time, as shown in Figure 29. This pattern could reflect growing use of digital channels by firms, or it could reflect features of the data collection process. Specifically, older web content is more likely to have been removed or archived by the time web crawling was conducted in 2025. Given that firms were already widely online by 2020, we expect this data collection effect to be large and account for much of the pattern observed.
It is important to note that coverage gaps may affect some signal types and sources more than others. A job posting, for example, is typically removed once a role is filled, while a news article about an investment round may remain accessible for much longer on the web.
Figure 29 – The coverage of growth signals is the highest in 2025
Proportion of firms in each year exhibiting each type of growth signal and exhibiting any type of growth signal. Data from Glass.AI-CMA growth signals (2020 to 2025).
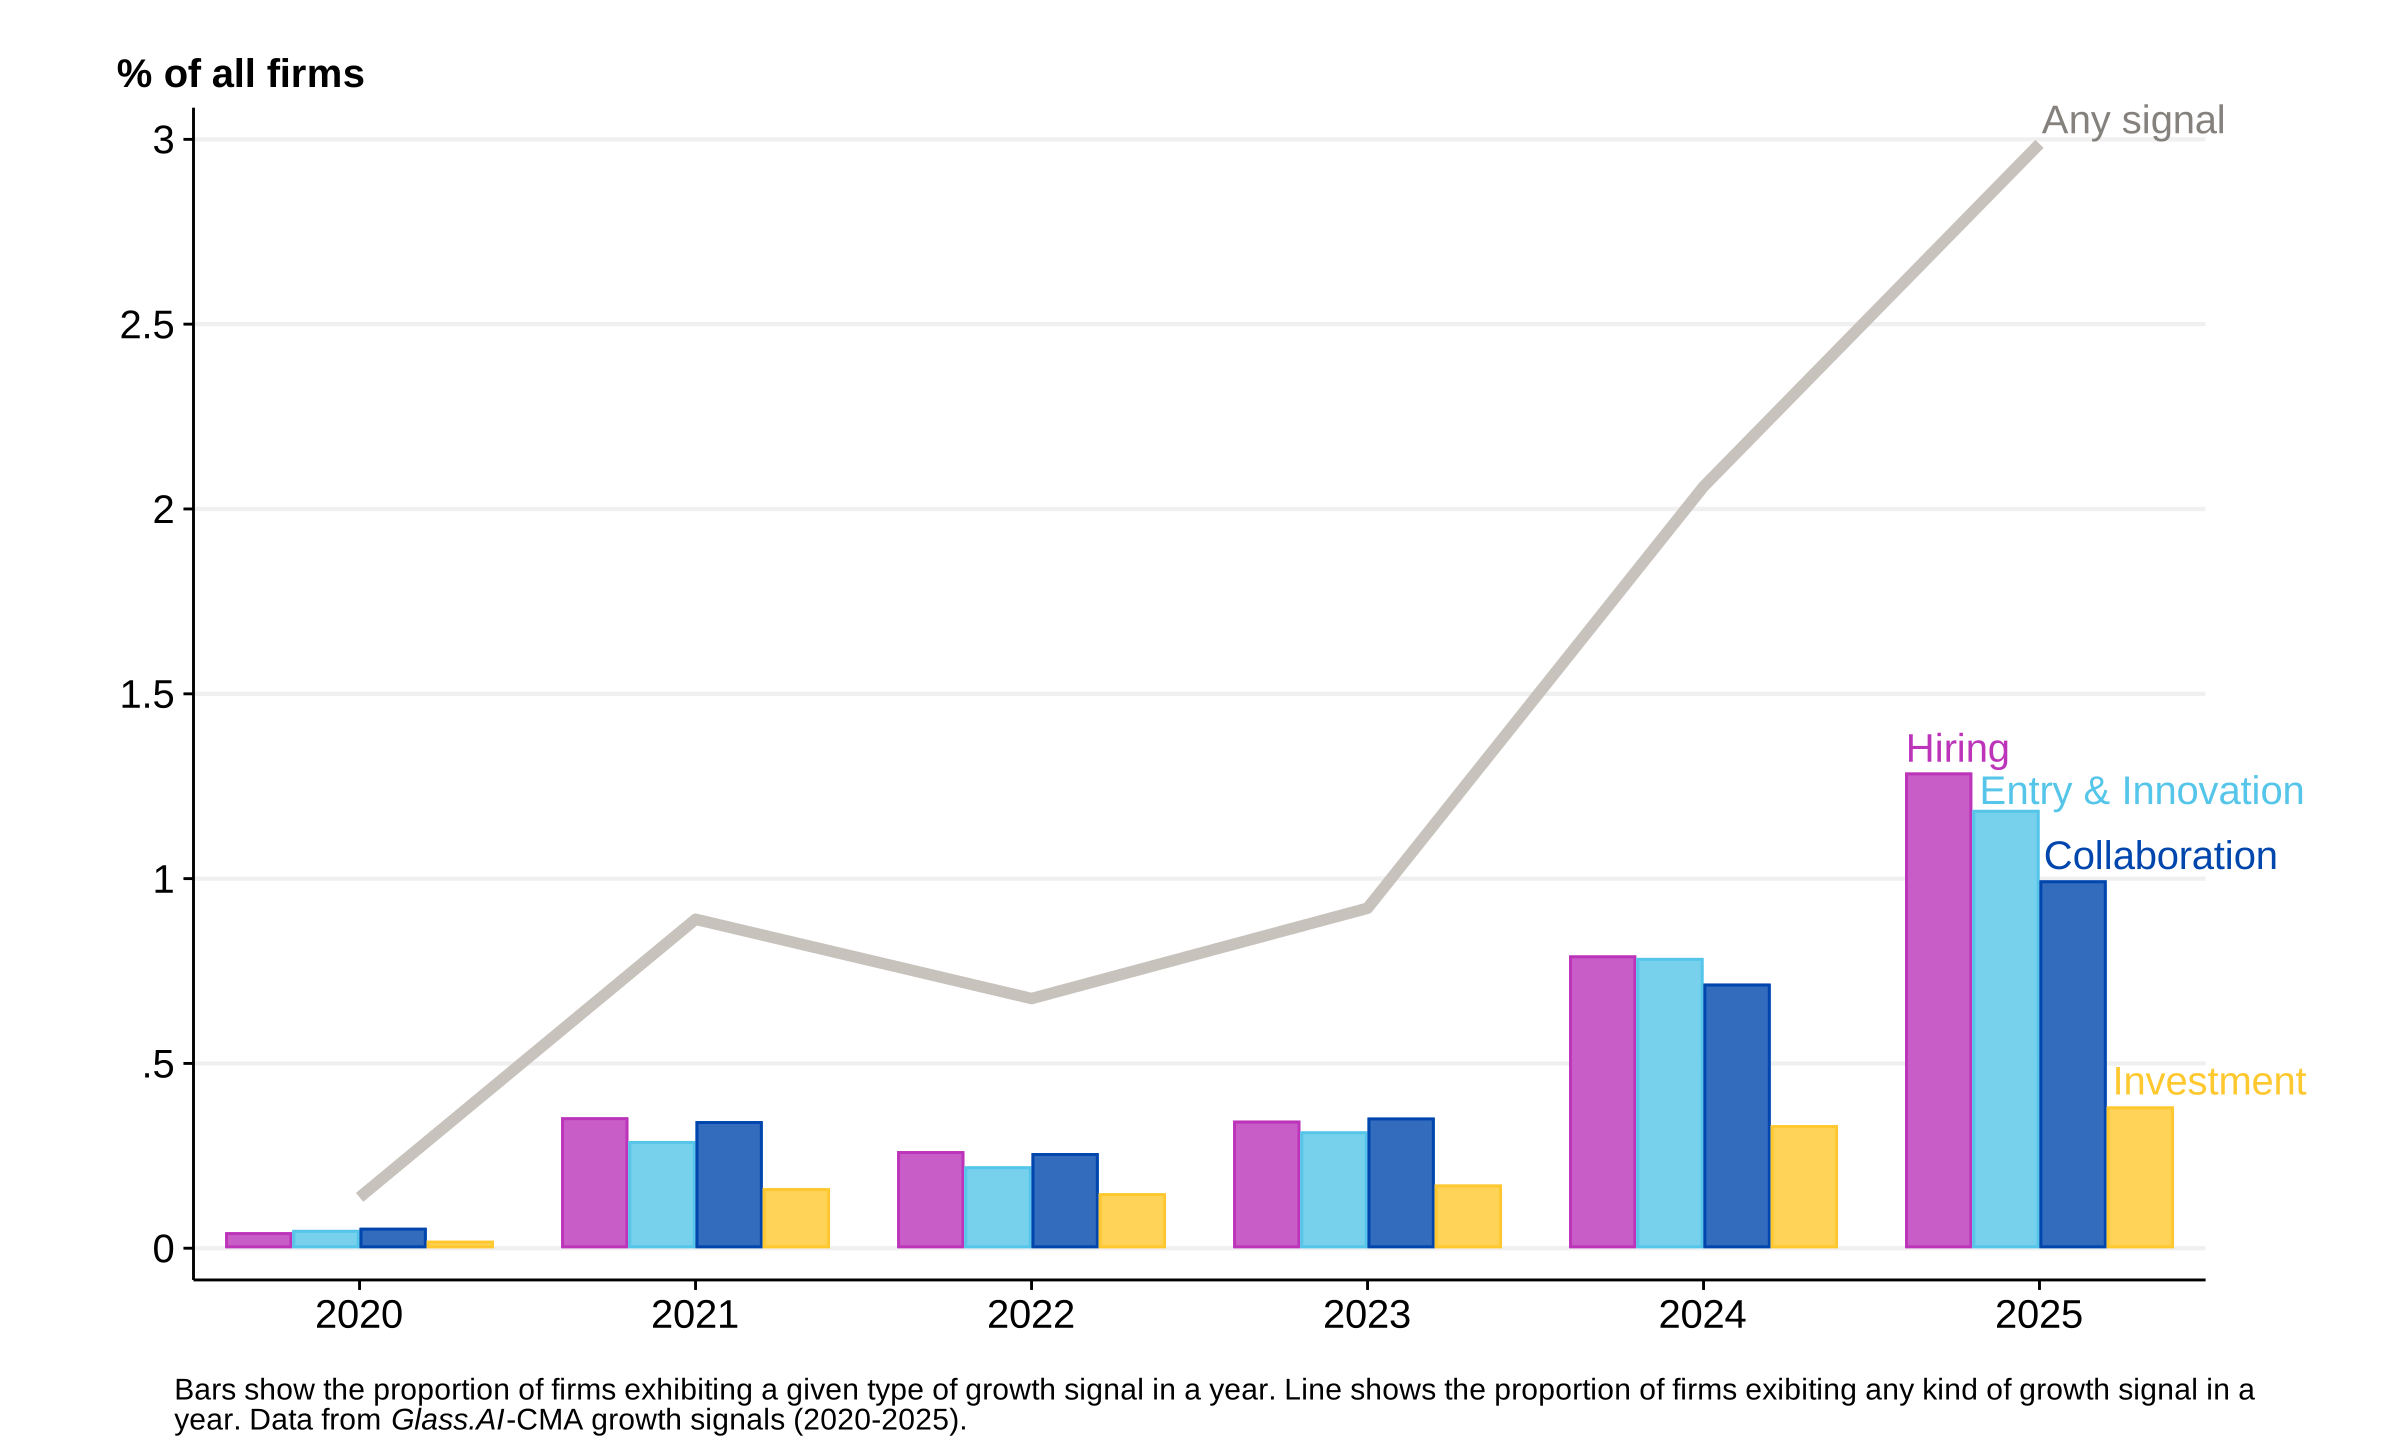
Combined line and bar chart showing the proportion of firms exhibiting different growth signals between 2020 and 2025. Coloured bars show the share of firms with hiring, entry and innovation, collaboration, and investment signals in each year, while a line shows the share of firms exhibiting any growth signal. The horizontal axis shows years and the vertical axis shows the percentage of firms.
Consistent with Romanko and O’Mahony (2022), we find that some sectors are overrepresented (for example, the Information and Communication sector) while others are under-represented (for example, Agriculture, forestry and fishing) in our dataset. This is likely to reflect the extent to which firms in these sectors rely on digital channels to communicate their activities and have a web presence.
The uneven coverage of signals over time and the partial overlap with Companies House data highlight the experimental nature of this dataset and limit the analysis that we can carry out. There are several ways coverage could be improved in future work. Repeating the web crawling exercise over time rather than conducting it once would create a longer and richer longitudinal dataset. Matching the dataset with alternative sources of financial data, or using different matching approaches, could also increase the overlap with firm-level outcome data. These are outside the scope of this report but represent natural next steps for future research.
Most broad growth signal types are uncorrelated, but firms seeking one type of investment tend to seek additional investment sources
In this section we explore whether there are common patterns in the way firms signal, and whether certain signal types tend to appear together or precede one another. We explore patterns at 2 levels: across the 4 broad signal categories (macro) and across more granular signal types within each category (micro). This provides insights into the different ways in which firms grow.
As Figure 30 shows, firms do not often emit signals in different macro categories at the same time. The largest negative association is between hiring signals and other signal types; meaning that a firm expanding its workforce is generally not announcing new products, entering new markets or forming partnerships at the same time, and vice versa. This continues to be the case after controlling for firm size, industry in which they operate and the calendar year.
Partly, the negative association between some signal types can be explained by the persistence of some signals relative to others. Hiring activity may be observed across multiple consecutive years as a firm steadily builds its workforce, whereas a major partnership or market entry is typically a one-off activity. Over time, this creates periods where hiring signals are observed without other signal types and may drive the negative correlation with hiring signals and other signal types.
A negative association may also reflect something about how firms grow. A firm expanding through a partnership, for instance, may simply have less need to take on additional staff if the partner is supplying the required capability. That said, the expected direction of some relationships is not obvious, and they could plausibly go in either direction. For instance, entering a new market or launching a new product could require additional hiring in the same year (positive association), or it could require staff to be hired earlier (negative association). The association between certain signals, therefore, warrants further investigation in future research. Better understanding of the interaction of these signals could provide deeper insights into the pathways through which firms grow.
Figure 30 – There is little positive association between macro signal categories
Matrix of correlation coefficients between different growth signal categories. Data from Glass.AI-CMA growth signals (2020 to 2025).
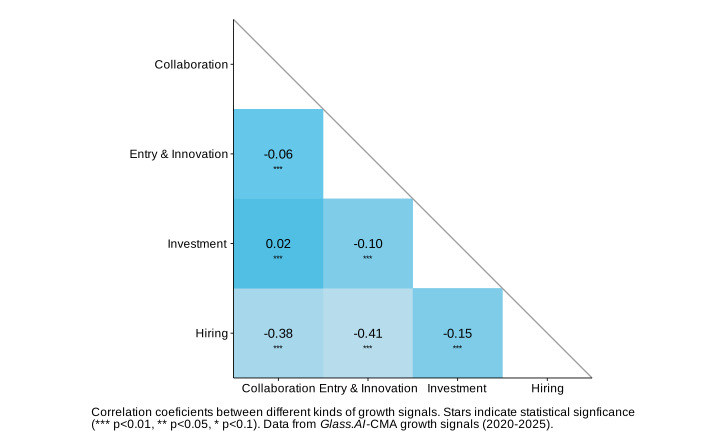
Triangular correlation matrix showing correlations between collaboration, entry and innovation, investment, and hiring growth signals. Each cell displays a correlation coefficient, with darker shading indicating stronger correlations.
Figure 31 examines associations between micro signals within the same macro category to explore whether certain signal types are more likely to appear together. For each possible pair of signals within a signal macro category (investment, collaboration, entry and innovation, and hiring), a positive correlation indicates that the 2 signals tend to appear together, while a negative correlation suggests they tend not to co-occur.
Investment signals stand out as the most strongly positively correlated category of signals (Figure 31). This means that when a firm records one type of investment signal, for example an M&A activity, it is relatively likely to record another investment-related signal, such as private equity or debt financing. However, this pattern is concentrated within a relatively small subset of firms. Investment signals are uncommon overall: only around 16% of signalling firms record any investment signal, and only 4% record more than one investment signal type. This may reflect the fact that firms typically raise capital in discrete funding rounds rather than continuously through their lifetime.
Within the other macro signal categories (collaboration, entry and innovation, and hiring), pairwise associations between signals are weaker or more mixed. Collaboration signals exhibit only modest positive correlations, while entry and innovation signals include both positive and negative relationships. Hiring signals are similarly mixed where, job listings tend not to coincide with key hires or hiring plans. This could imply that volume recruitment and more strategic key hiring may happen at different times.
Further research into these relationships, in particular, exploring which combinations of signals are associated with faster growth, could deepen our understanding of the pathways through which firms scale and improve further insight into how different growth-related activities are associated with firm growth.
Figure 31 – Investment signals are likely to occur together
Correlation coefficients between pairs of signals within each signal type, where the correlation is statistically significant at the 1% level, for signalling firms. Data from Glass.AI-CMA growth signals (2020 to 2025).
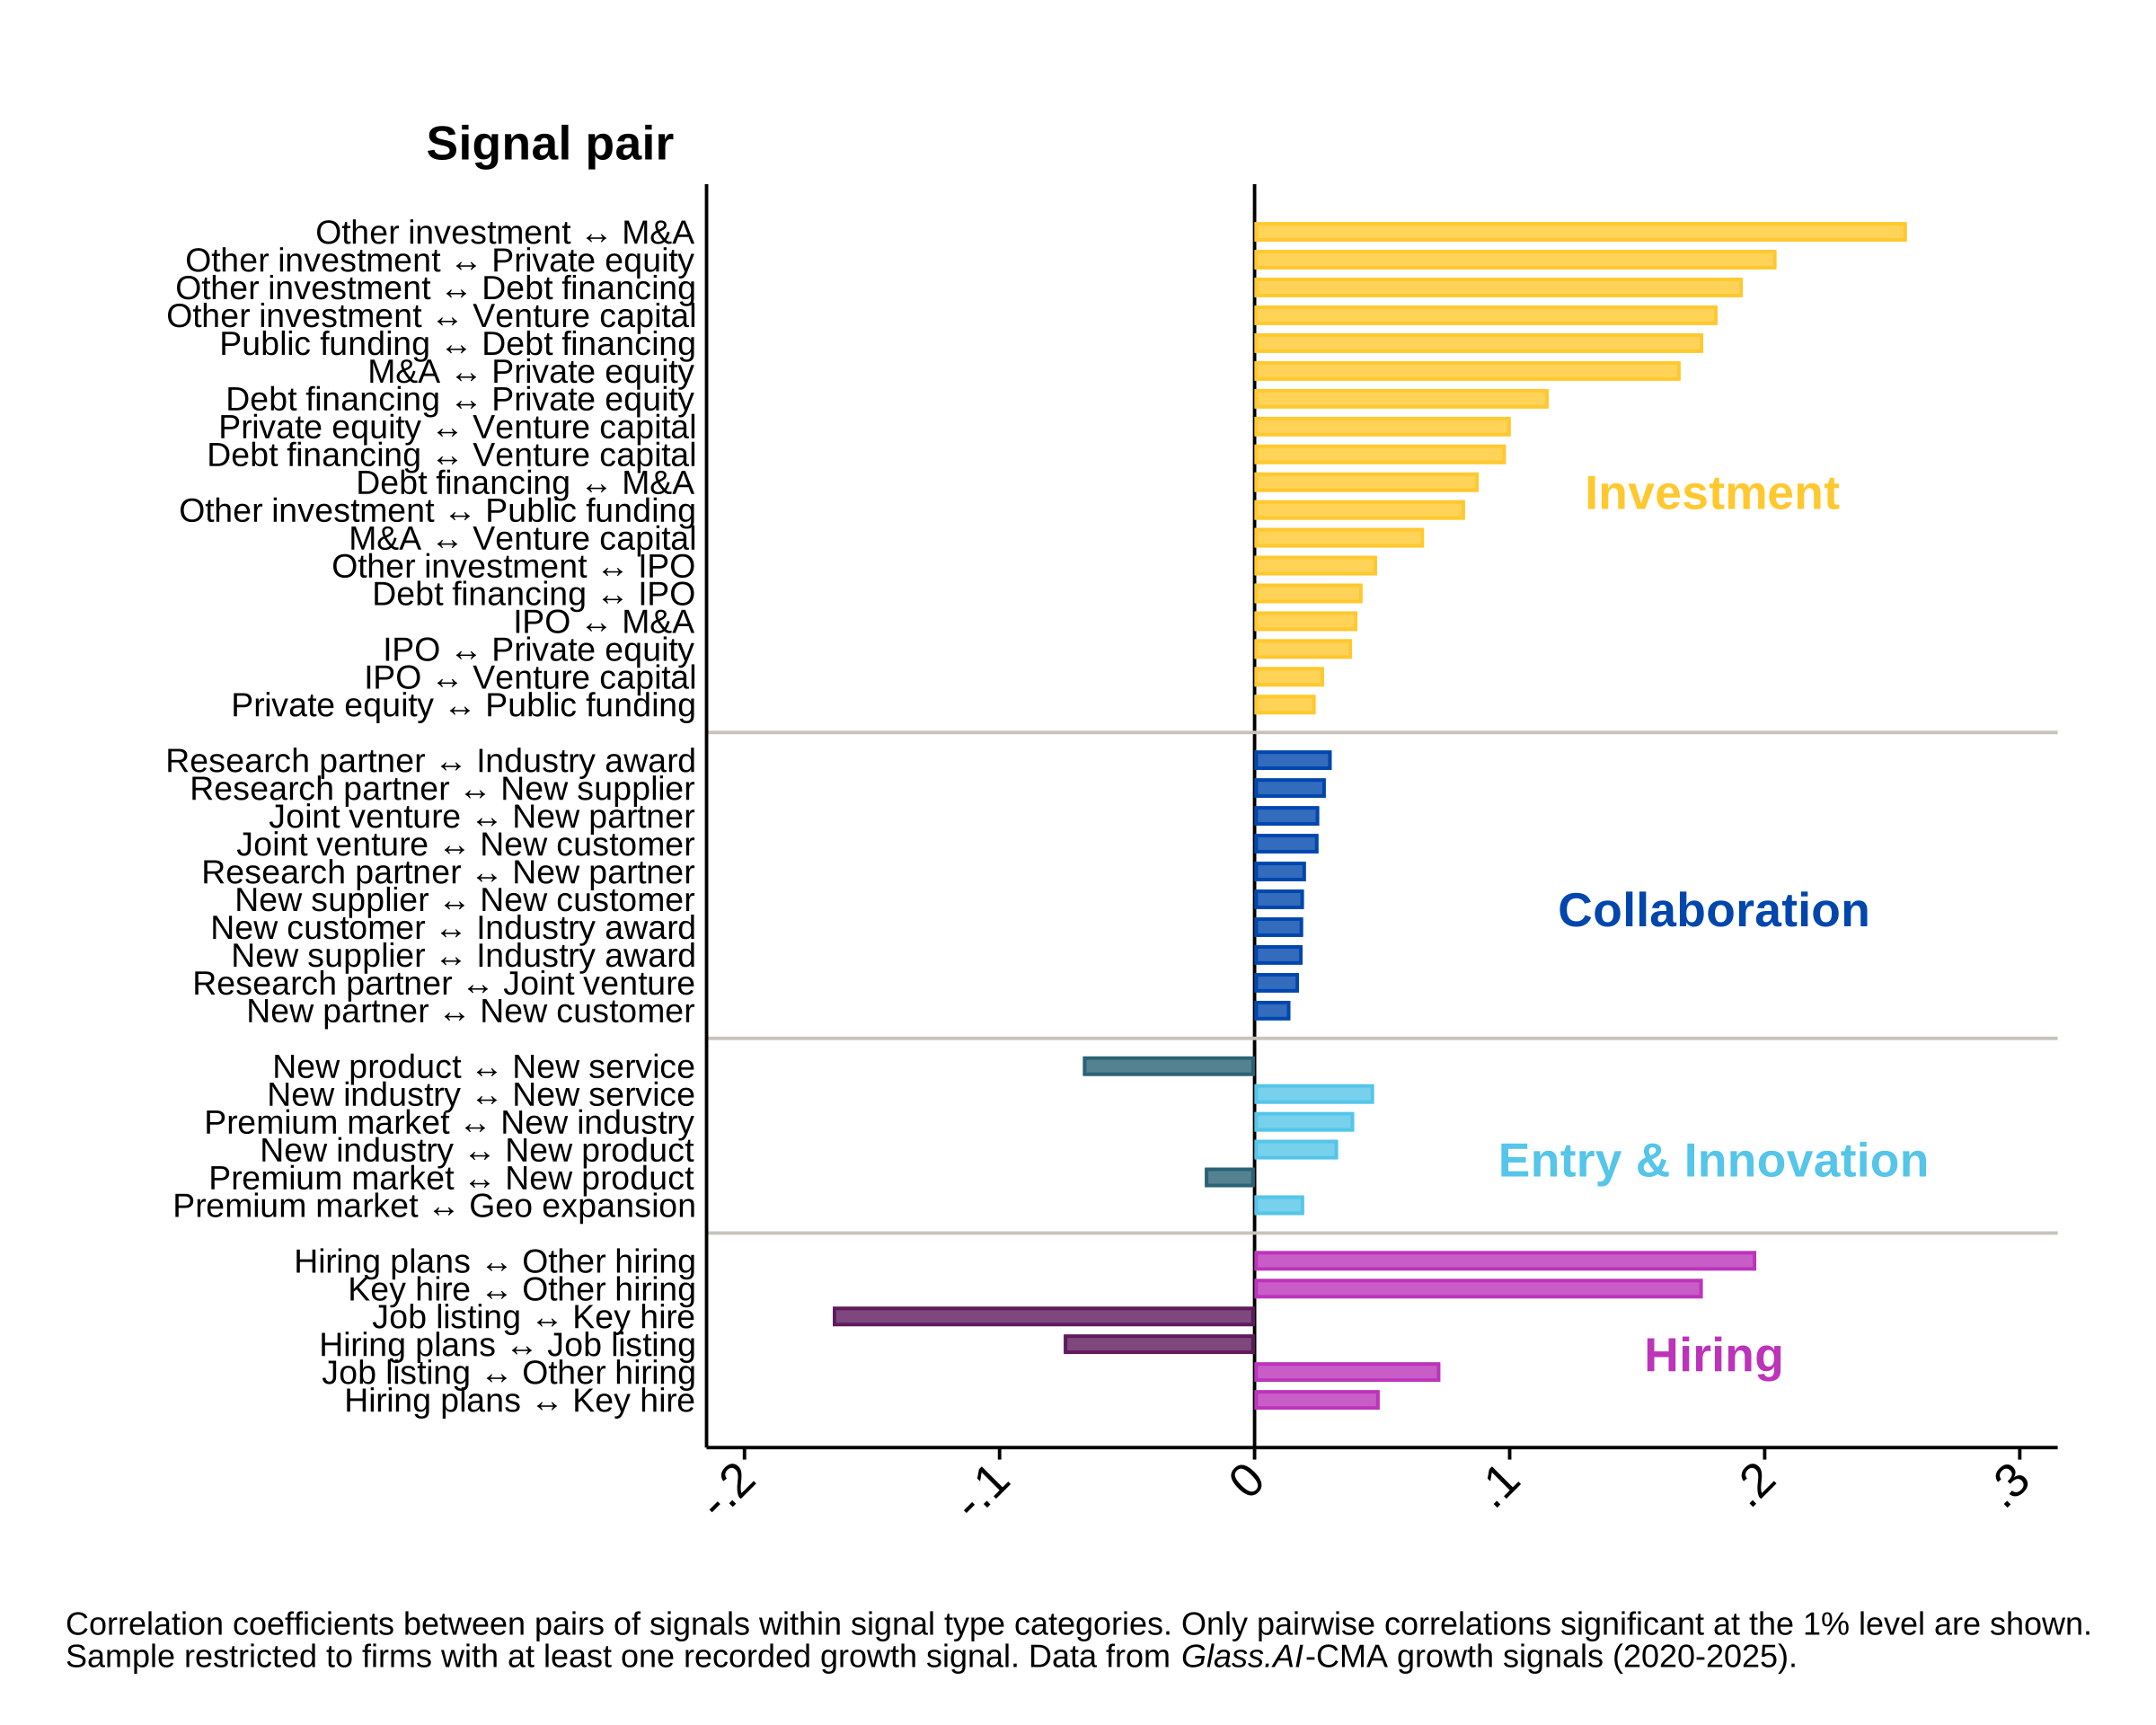
Horizontal bar chart showing statistically significant correlations between pairs of signals within four signal types: investment, collaboration, entry and innovation, and hiring. Bars extend either side of 0 to show the direction and strength of the correlation between each signal pair.
Lastly, we undertake an exploratory analysis of whether some signal types are more likely to follow others over time. We examine all combinations of signals against earlier signals a firm may display, using a linear probability model and controlling for variation driven by year, firm size, age and sector.[footnote 33] Firms which announce entry and innovation activities are more likely to subsequently announce collaboration, and vice versa, while firms which announce investment are more likely to subsequently announce collaboration activities. These likelihoods are statistically significant, suggesting that collaboration activity may follow periods of investment and market expansion. All other relationships between macro categories were either negative or statistically insignificant (see Appendix A30-A34 for more details).
However, these findings should be interpreted with some caution. The data covers a relatively short time period and the relatively limited number of signal observations per firm makes it difficult to reliably identify the order in which signals appear over time. The results should therefore be viewed as suggestive evidence of potential growth pathways rather than definitive patterns. Future research, using longer time series and more comprehensive data, could provide a more robust assessment of these relationships, helping to realise the potential of growth signals to understand firms’ growth journeys over time.
Signalling activity varies across UK sectors and regions, with higher prevalence in technology, financial services and London
In this section we look at the distribution of signalling activity across industries and regions. For each dimension, we explore the prevalence of signalling (the extensive margin, measured by the share of firms that signal) and the intensity of signalling (the intensive margin, measured as the average number of signals by signalling firms). Together this tells us where signalling activity is most and least common.
Firms across all sectors produce growth signals but the prevalence and intensity of these signals vary by sector. Firms in Information and communication, and Finance and insurance activities are among the most active signallers. As shown in Figure 32, around 6% of firms in these sectors produce growth signals with around 2.5-3 signals per signalling firm on average. Firms in Mining and quarrying also produce at least one growth signal at a high rate (6.1%) and firms in Electricity, gas, steam and air conditioning produce on average a high number of signals per signalling firm (3.1 signals). Construction has the smallest percentage of firms with at least one growth signal (1.8%), and Education has the lowest average number of signals among signalling firms (1.5 signals).
Figure 32 - Firms in Information and communication, and Financial and insurance activities sectors are among the most active signallers – both in prevalence and intensity
Proportion of firms in each industry with at least one growth signal (extensive margin) and average number of signals per signalling firm (intensive margin), with economy-wide average. Industries are defined by Standard Industrial Classification (SIC) sections. Data from Glass.AI-CMA growth signals (2020 to 2025).
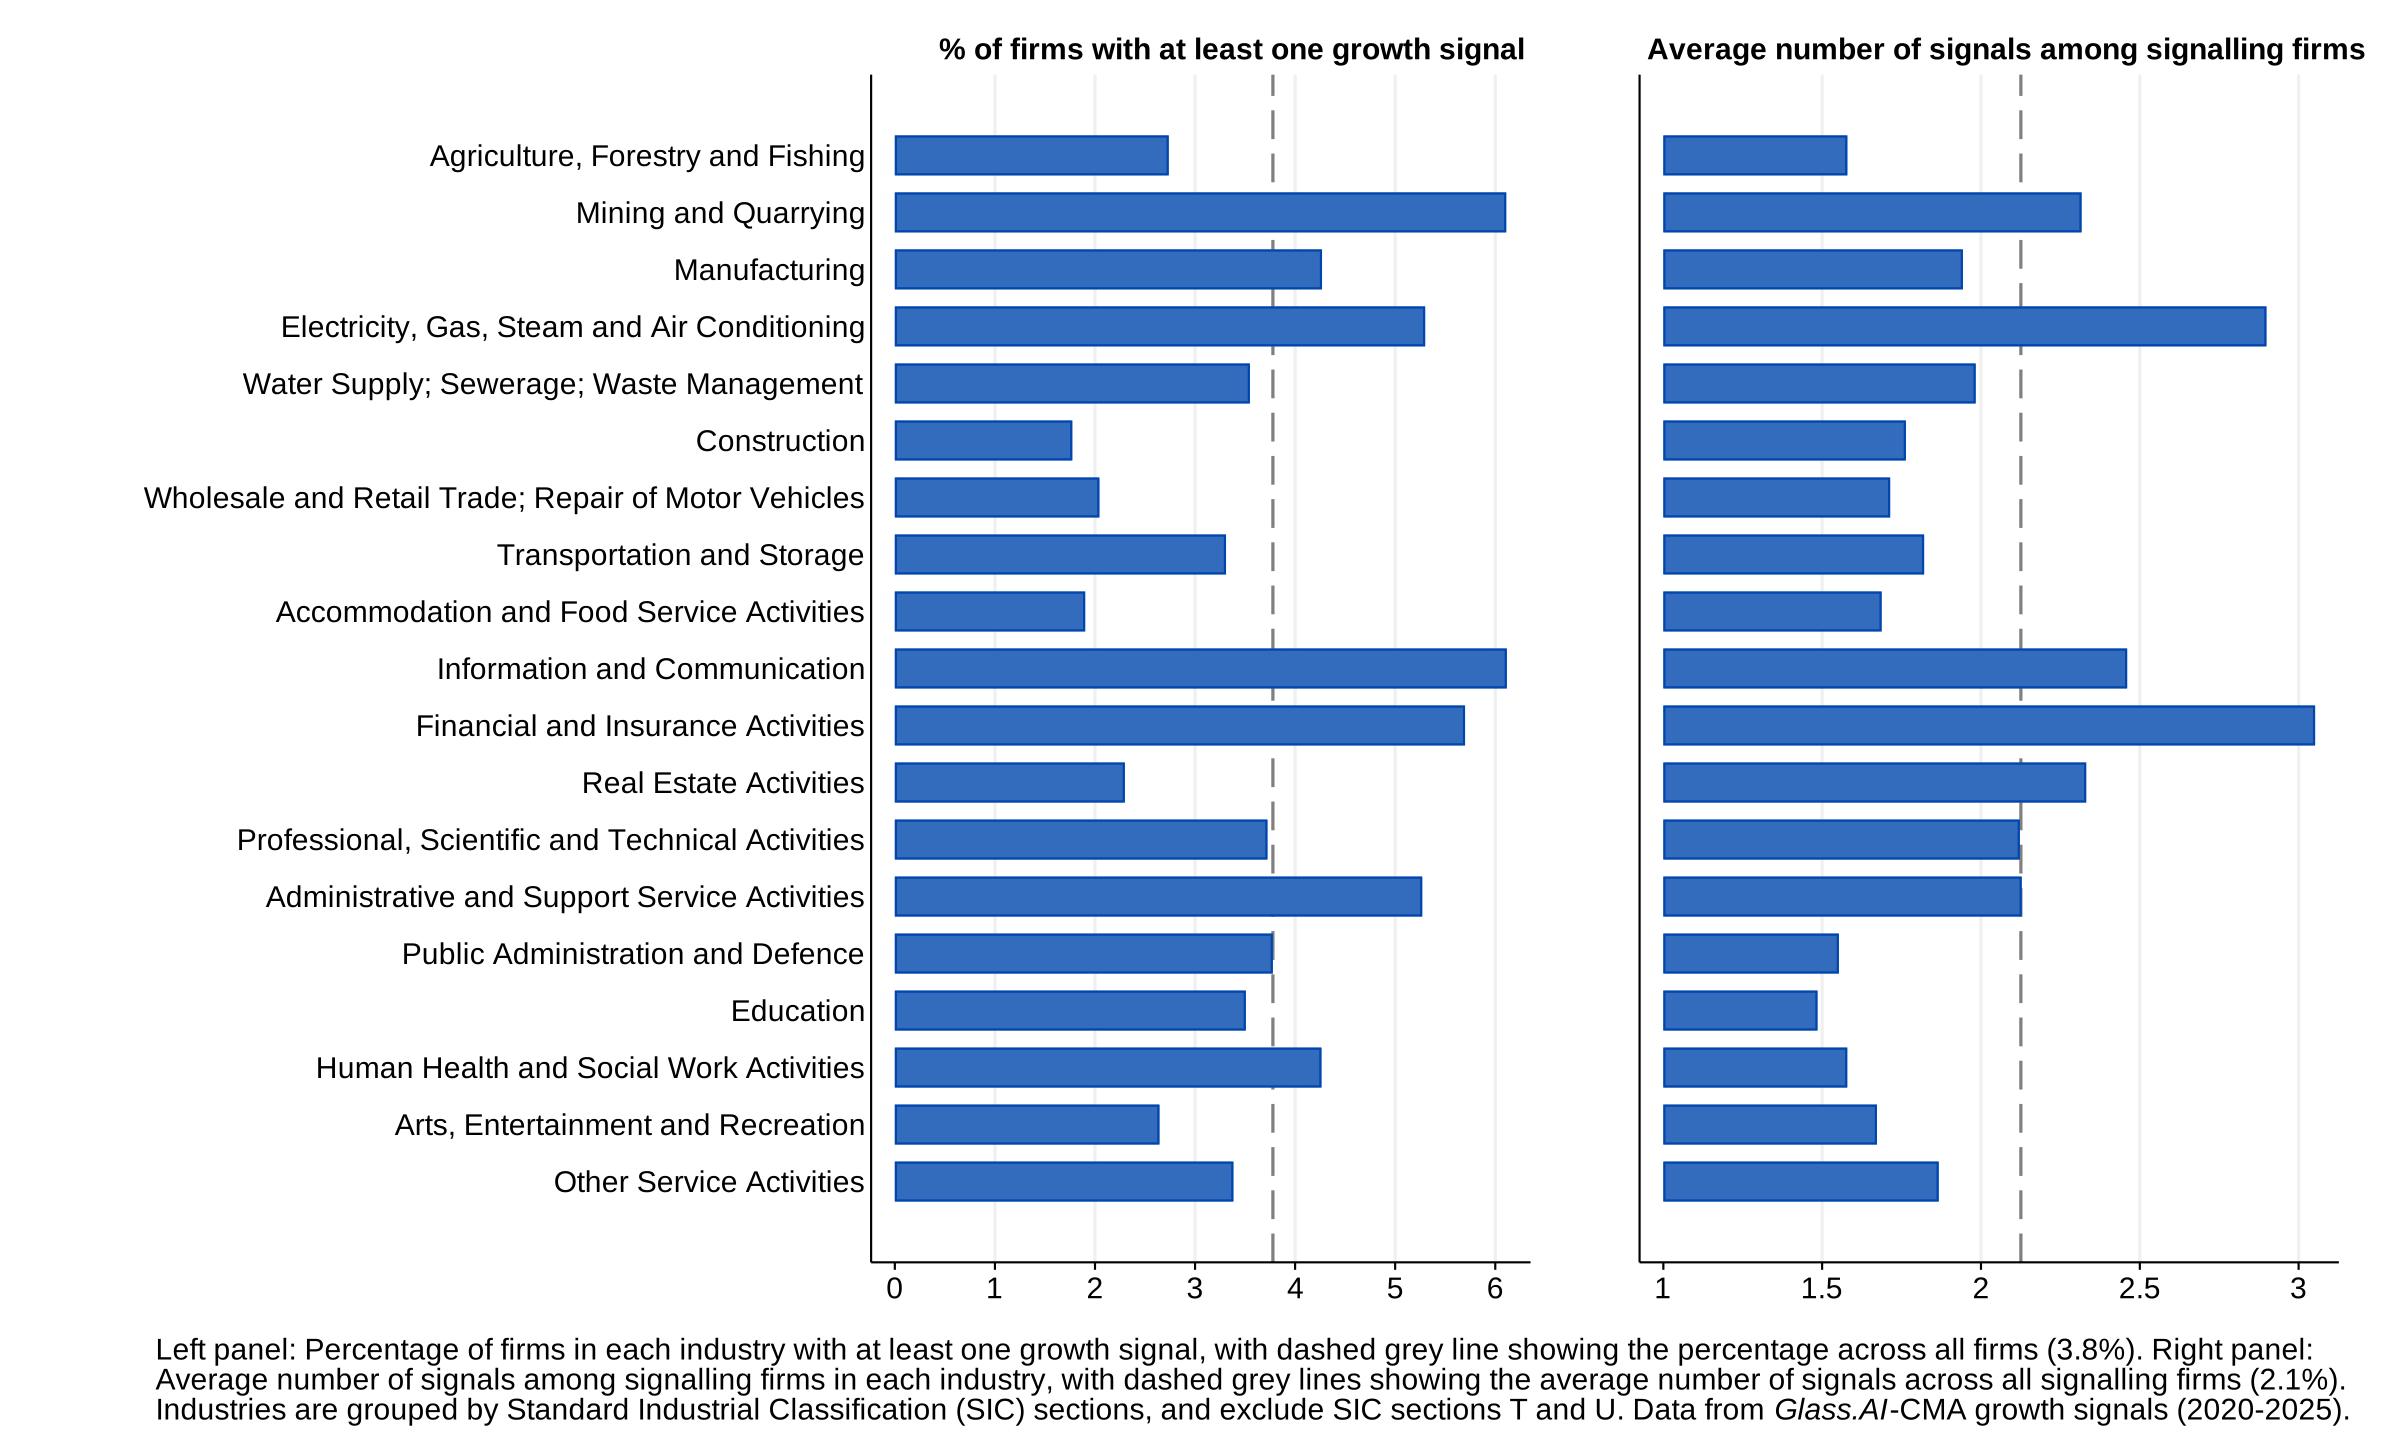
2-panel horizontal bar chart comparing industries by the prevalence of growth signals (left panel) and the average number of signals among signalling firms (right panel). Industries are shown on the vertical axis, and dashed vertical lines indicate the economy-wide average in each panel.
Looking specifically at the 8 Industrial Strategy growth-driving sectors (IS-8),[footnote 34] 7.5% of firms in the Digital and technology sector display at least one signal, with an average of 2.5 signals. Firms in the Life sciences sector also have higher than average proportion of signalling firms (6.6%). Around 4.6% of firms classified in the Financial services IS-8 sector produce a signal and these firms have the highest signal intensity across all 8 sectors, with an average of 2.9 signals per signalling firm. The Defence sector has the lowest proportion of signalling firms (3.8%) and also the second lowest average signal intensity (on average 2.0 signals per signalling firm).
These patterns likely reflect several factors. In some sectors, being visible and communicating publicly is itself part of how firms compete, attracting investors, building customer trust and drawing in talent. In others, business models and the nature of how firms use online platforms may simply mean there is less need to have a digital footprint. As a result, growth signals might capture a more complete picture of growth activity in some parts of the economy than others.
Signalling firms are distributed across the UK. The regions with the highest proportion of firms classified as signalling firms are London (4.9%), Northern Ireland (3.8%) and the North West (3.4%). The regions with the lowest proportion of signalling firms are South West (2.9%) and Wales (2.7%). Signalling firms in London produce the most signals (2.6 signals on average) followed by North West with an average of 2.2 signals per signalling firm. The region with the fewest number of average signals is East Midlands (1.8 signals) and South West (1.8 signals).
Signalling firms tend to be larger, more established and account for a disproportionate share of employment across firms in the data
Here we describe how the prevalence and intensity of signalling vary by firm size and age, and how signalling firms compare to non-signalling firms in terms of employment.
Signalling is more prevalent and more intense among larger (left panel) and older firms (right panel), as shown in Figure 33. This is broadly expected as established firms (larger and older) tend to have a stronger online presence and have been able to build their digital footprint over time.
Consistent with these findings, Figure 34 shows that signalling firms are considerably larger, in terms of employment, than non-signalling firms on average. Signalling firms employ around 70 people, on average, compared to just 17 for non-signalling firms. This difference between the 2 groups is statistically significant. The wider confidence interval for signalling firms indicates greater uncertainty around this estimate, which likely reflects the smaller sample size of signalling firms relative to non-signalling firms.
Figure 33 – Signalling activity is more prevalent and intense among established (larger and older) firms
Binned scatterplot showing proportion of firms with at least one growth signal (extensive margin) versus the average number of signals per signalling firm (intensive margin). Left panel: Firms binned by size band (based on most recent year of employment data). Right panel: Firms binned by firm age band. Data from Glass.AI-CMA growth signals (2020-2025).
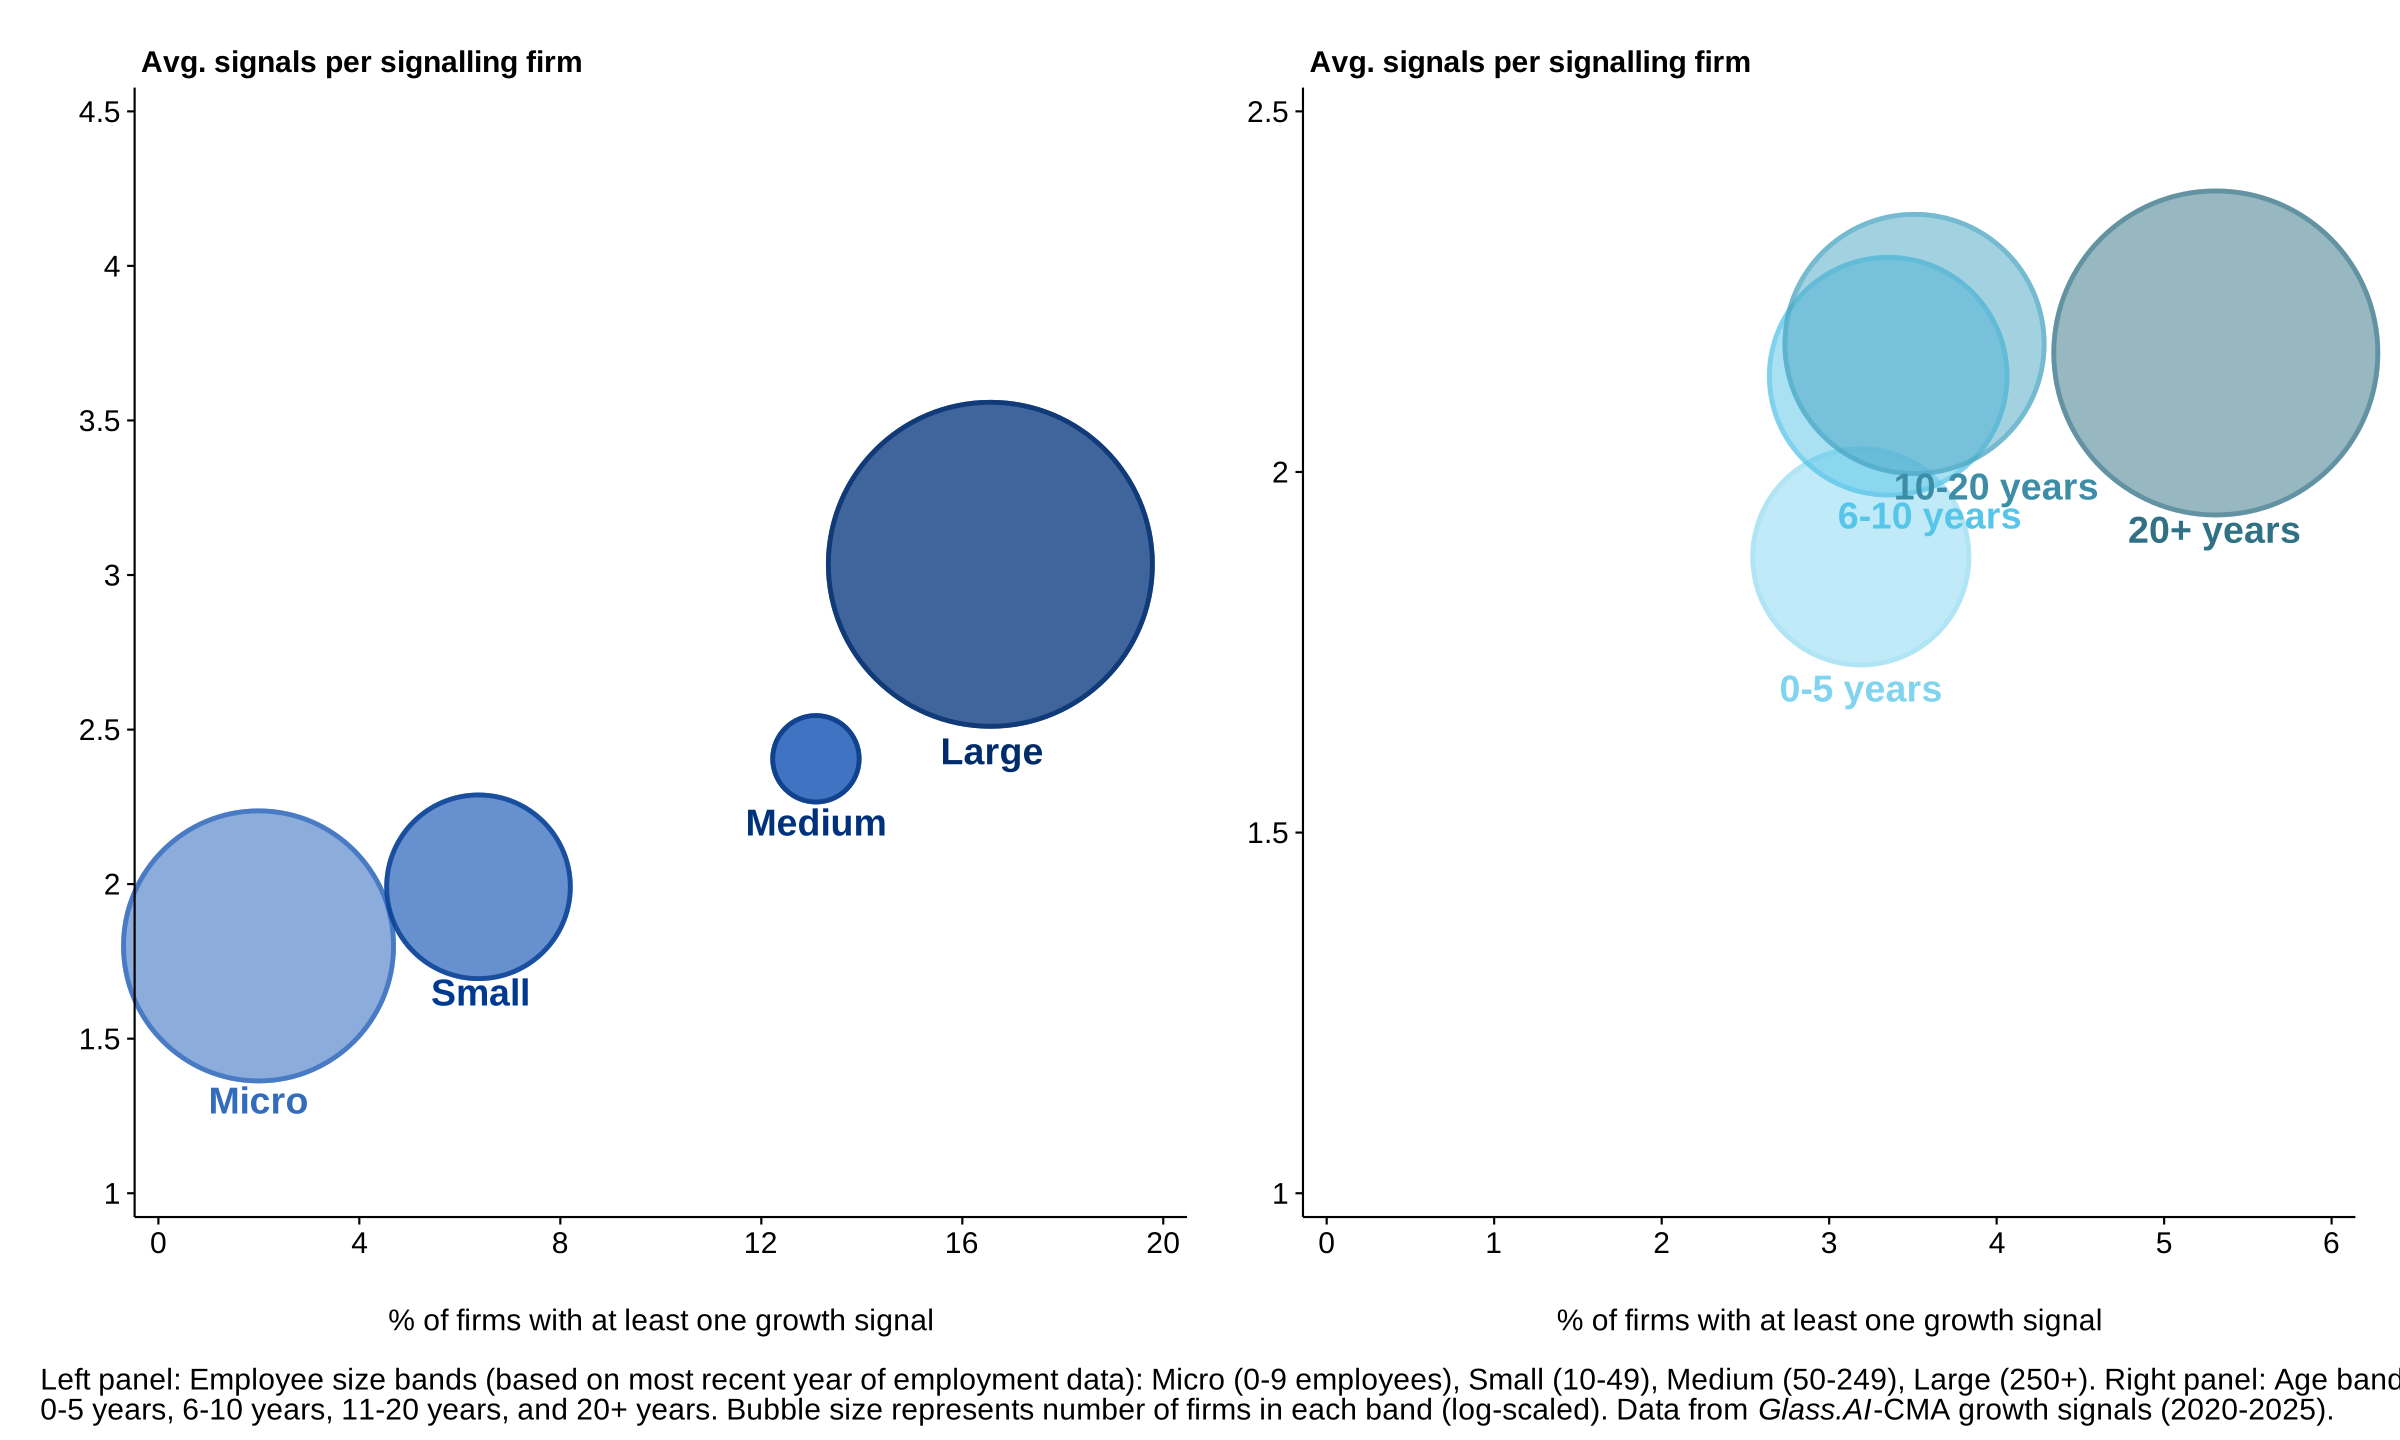
2-panel bubble chart showing the relationship between the share of firms with at least one growth signal and the average number of signals among signalling firms. The top panel groups firms by size band and the bottom panel groups firms by age band. Each bubble represents a group, with bubble size proportional to the number of firms in that group.
Figure 34 - Signalling firms have higher employment than non-signalling firms, on average
Mean employment of signalling and non-signalling firms over the period 2020 to 2024, with 95% confidence intervals. Data from Glass.AI-CMA growth signals (2020 to 2024).
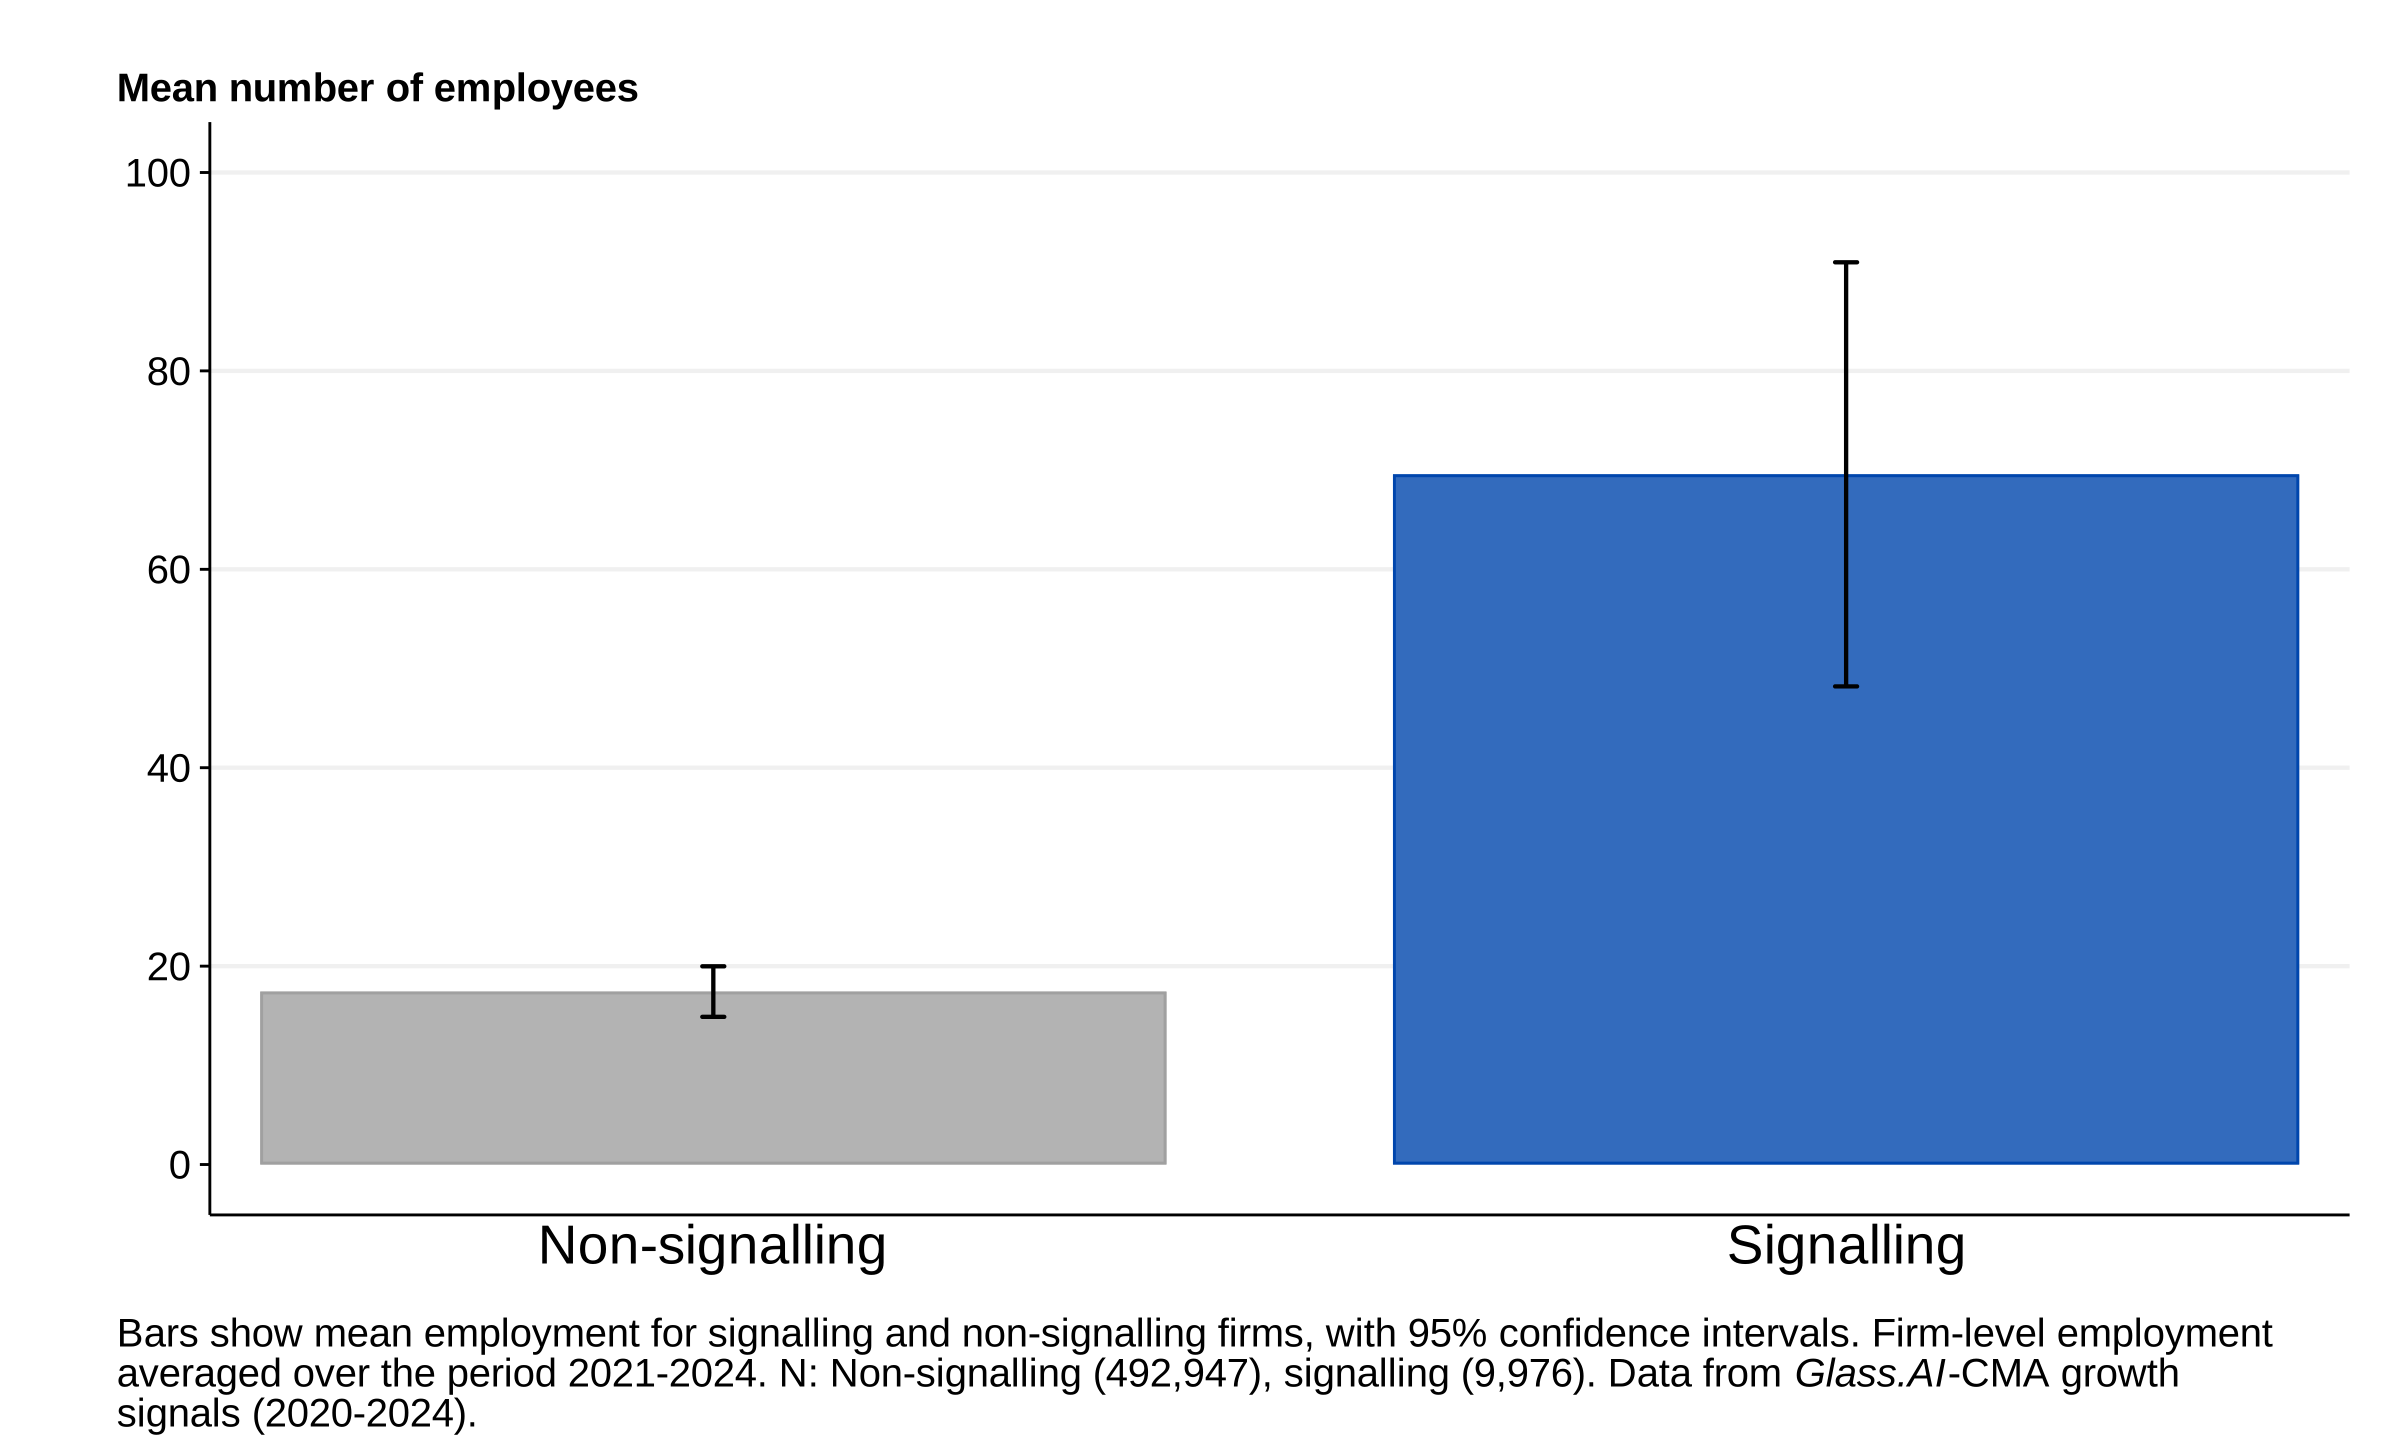
Bar chart comparing mean employment for signalling and non-signalling firms. Bars show average employment for each group, and vertical lines show 95% confidence intervals.
Figure 35 shows that firm size is also associated with both the type and variety of signals displayed. The left panel shows that firms displaying a wider range of signal types also tend to be larger: those displaying one signal type have around 45 employees on average, rising to around 400 employees for firms displaying all 4 signal types. The right panel shows that amongst signalling firms, the firms displaying investment signals are considerably larger on average, around 230 employees, than those displaying collaboration, entry or hiring signals (below 120 employees).
Figure 35 - Firms with investment signals and broader variety of signals are larger on average
Mean employment of signalling firms, binned by how many different types of signals they displayed (left panel), and whether they displayed each type of signal (right panel), over the period 2021 to 2024. Data from Glass.AI-CMA growth signals (2021 to 2024).
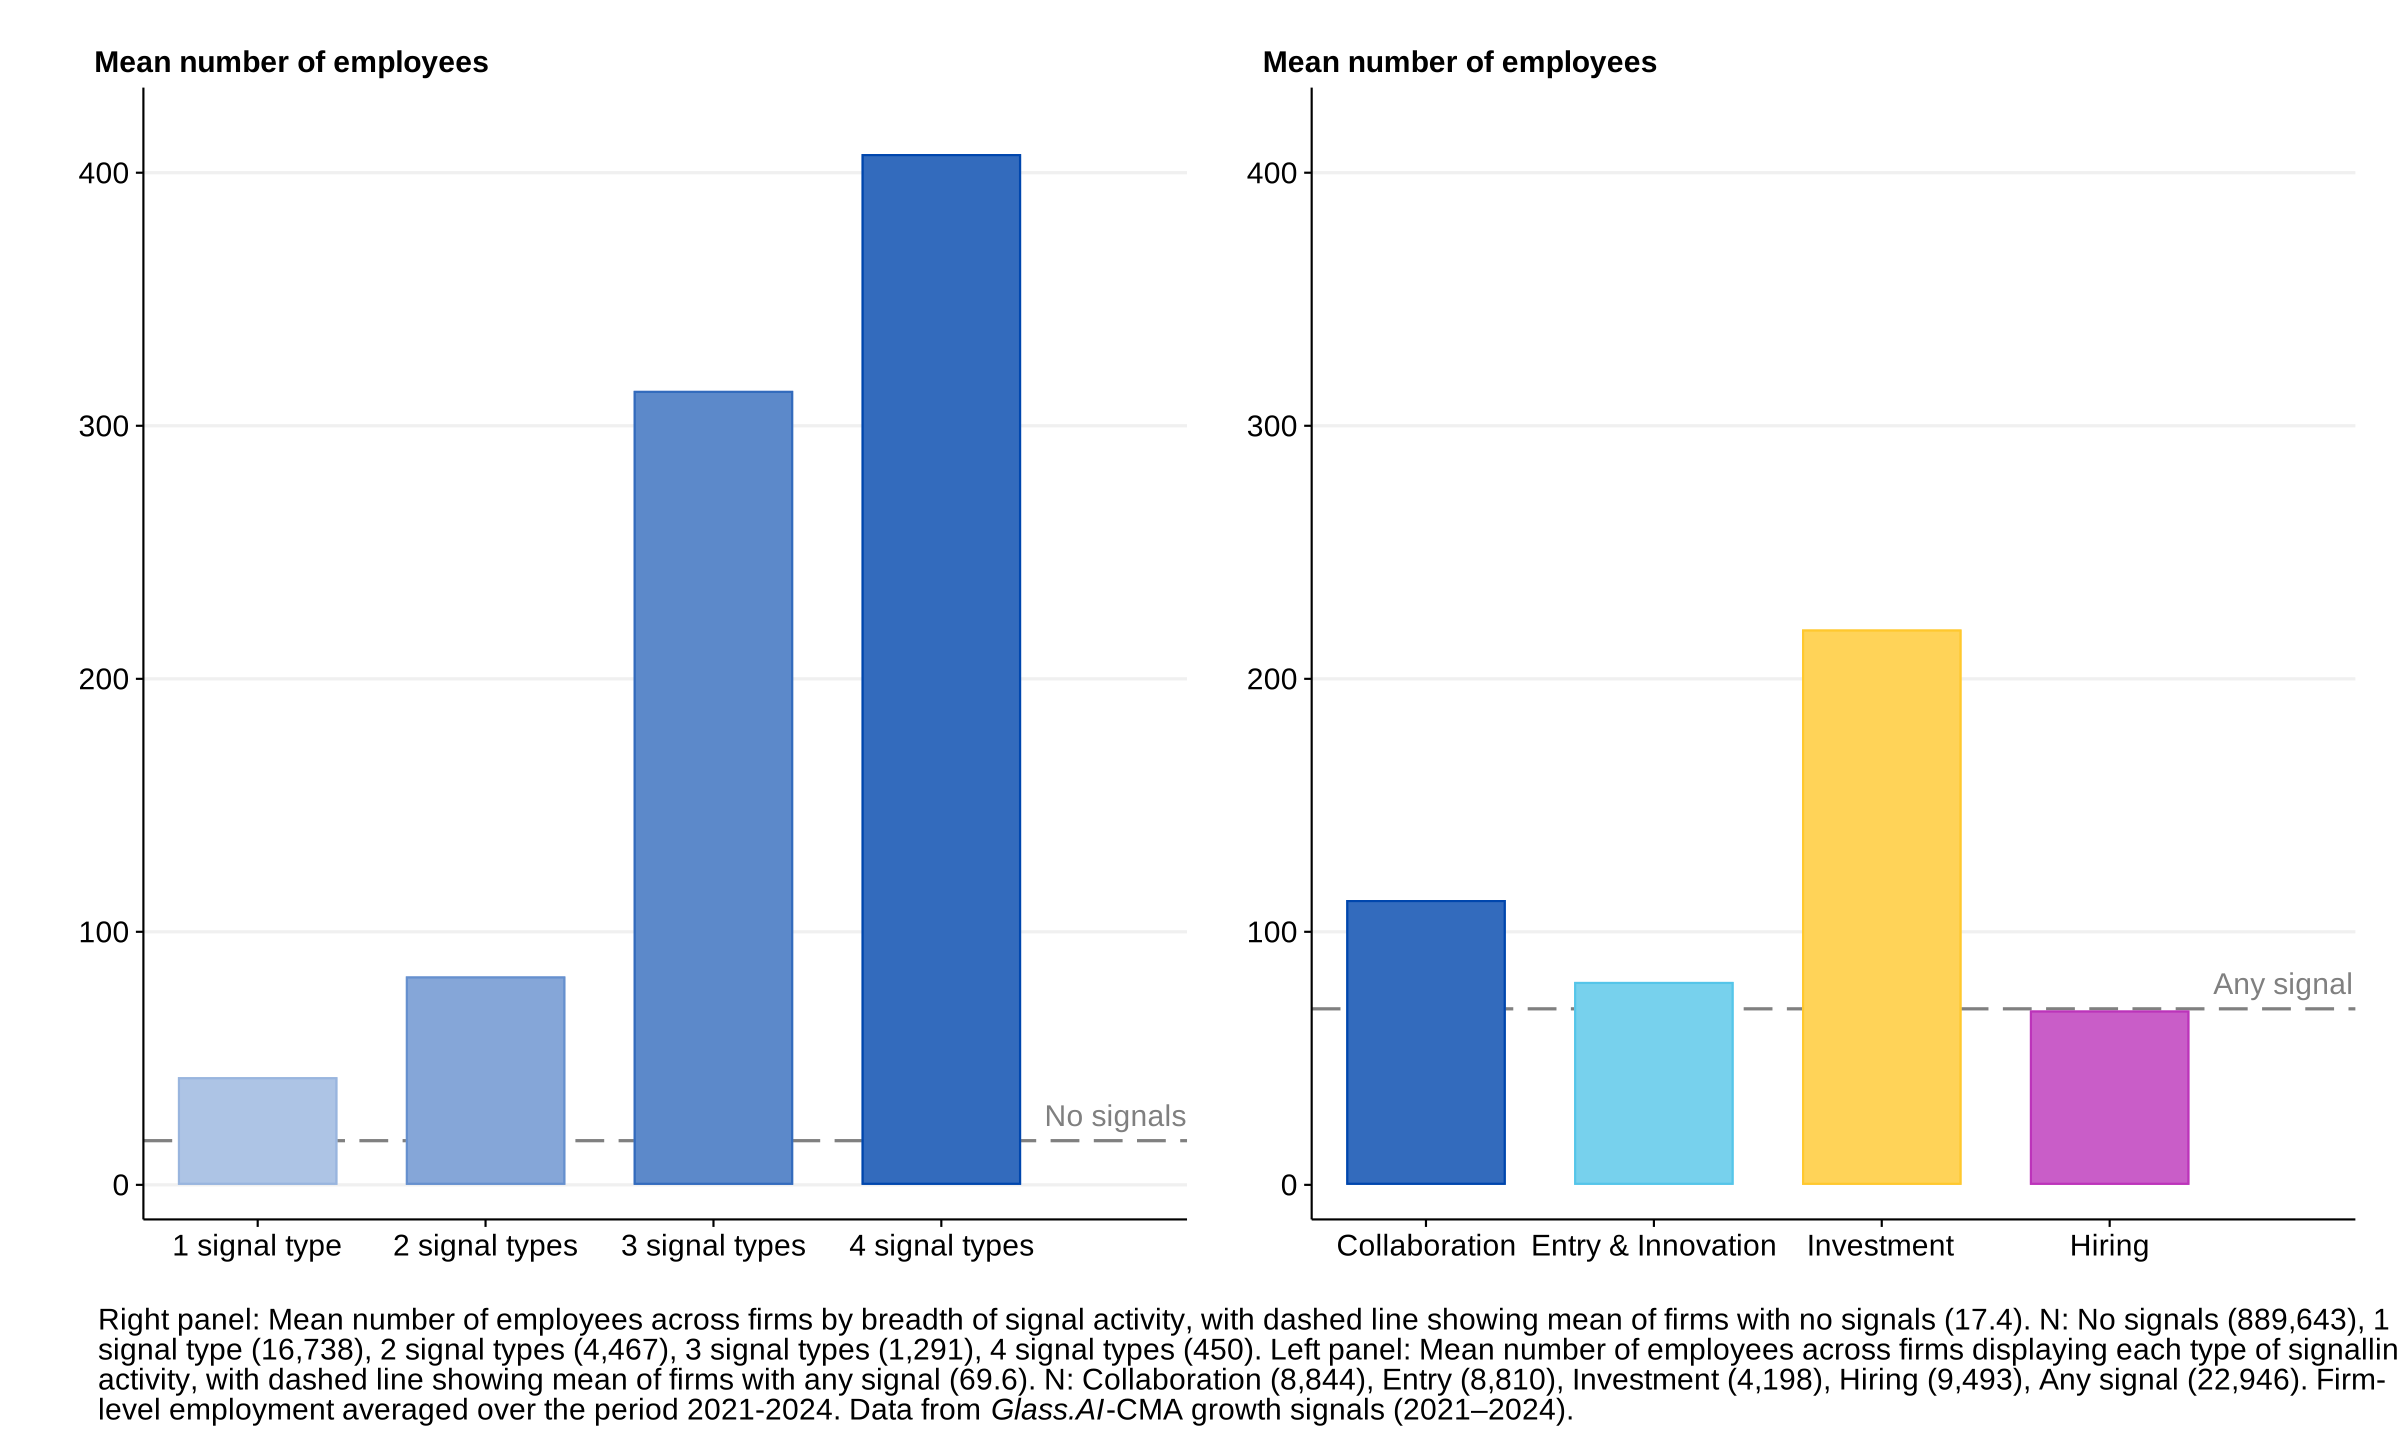
2-panel bar chart showing mean employment among signalling firms. The left panel groups firms by the number of signal types displayed, and the right panel groups firms by signal type. Dashed horizontal lines indicate the mean employment of non-signalling firms (left panel) and all signalling firms (right panel).
Taken together, these patterns confirm that despite making up a small fraction of all firms in the data (3.8%), signalling firms are important players in the economy and they account for 11.2% of total employment over 2020 to 2024, which is nearly 3 times their share of firms.
Signals as a marker of firm growth
The previous section described the nature of growth signals and the firms that display them, to help us understand the different ways in which firms grow. In this section, we examine whether signals are potentially a good way of identifying fast growing firms. To do this, we explore 3 questions:
-
do signalling firms grow faster than non-signalling firms?
-
do signalling firms overlap with high-growth firms?
-
are signals predictive of higher growth following the signal?
Signalling firms grow employment faster than non-signalling firms
Signalling firms grow their employment roughly twice as fast as non-signalling firms, at around 20% a year on average (Figure 36). The difference in mean growth rates between the 2 groups is statistically significant. The median growth rate is zero for both groups, suggesting that the majority of firms, whether signalling or not, have stable employment over the period.
Figure 36 – Mean employment growth is higher in signalling firms than non-signalling firms
Comparison of mean and median year-on-year growth rates between signalling and non-signalling firms, over the period 2021 to 2024. Lines show 10 to 90th percentile range. Data from Glass.AI-CMA growth signals (2021 to 2024).
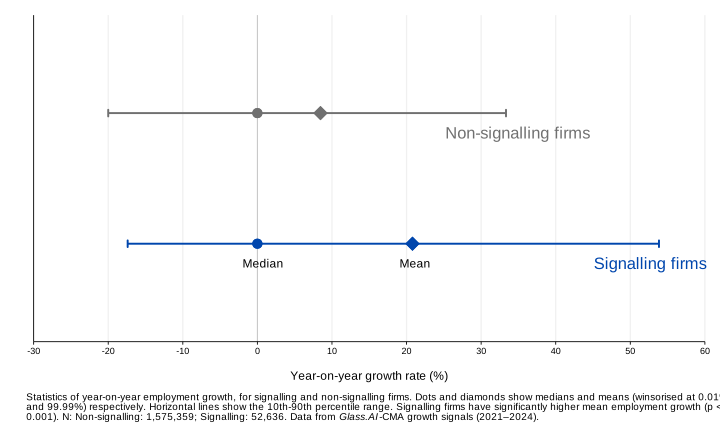
Distribution plot showing year-on-year employment growth for signalling and non-signalling firms. Dots indicate median growth rates, diamonds indicate mean growth rates, and horizontal lines show the 10th to 90th percentile range.
Additionally, signalling firms display considerably more variation in growth rates than non-signalling firms. This suggests the higher average among signalling firms is driven by a group of very fast-growing firms within the group, while the proportion of signalling firms growing slowly or decreasing employment is similar to that among non-signalling firms.
As shown in the Figure A.13 in the Appendix, signalling firms also create more jobs and destroy fewer jobs than expected given their employment share. Specifically, signalling firms created around 5% more jobs than expected and destroyed around 25% fewer in 2024 and this result is consistent over time.
As discussed earlier in the chapter, signalling firms tend to be larger and older than non-signalling firms. These characteristics could themselves explain some of the growth differential between the groups rather than signalling behaviour itself. However, Figure 37 shows that signalling firms grow employment faster, on average, than non-signalling firms in the same age bands, even after controlling for their size, industry in which they operate and calendar year. While the inclusion of controls slightly reduces the estimated growth differential, the overall pattern remains unchanged. The difference is greatest when firms are young, with signalling firms growing around 20 percentage points faster, on average, than non-signalling firms of the same age group. Further details of specifications are provided in Appendix A35-A39.
Figure 37 – Employment growth is higher in signalling firms than non-signalling firms, with the difference greatest for young firms
Difference in employment growth rate between signalling and non-signalling firms over the firm life cycle (relative to age 0 to 2 years) with and without controls. Data from Glass.AI-CMA growth signals (2020 to 2025).
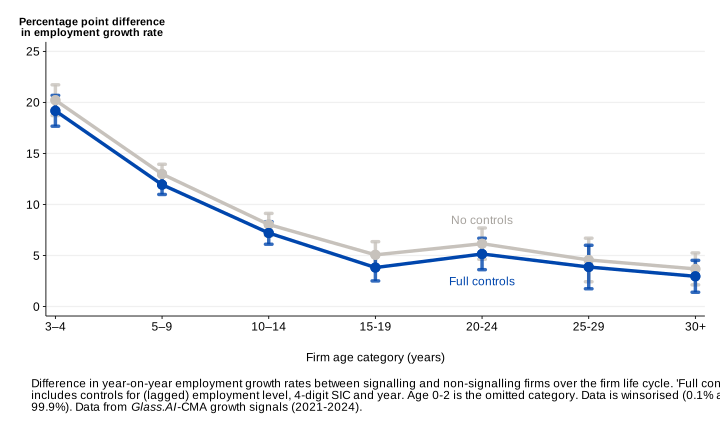
Line chart showing the difference in employment growth between signalling and non-signalling firms across firm age bands. Grey and blue lines show estimates without and with controls, respectively, and vertical lines show 80%, 90% and 95% confidence intervals.
Figure 38 shows that the pattern of faster employment growth holds across all 4 signal types, although the magnitude varies. Firms displaying investment or hiring signals experience the highest growth rates (around 24%), while firms displaying collaboration signals grow around 22%. Firms displaying entry and innovation signals grow more slowly (around 18%), albeit still faster on average than non-signalling firms (mean growth rate of 8.5%). The difference is statistically significant for each signal type. This suggests that the type of signal firms display may be informative about the rate at which it is growing, not just whether it is growing at all.
Figure 38 – Mean employment growth is higher across all signalling firm types
Mean year-on-year employment growth rate of firms displaying each growth signal type, compared to non-signalling firms. Data from Glass.AI-CMA growth signals (2020 to 2024).
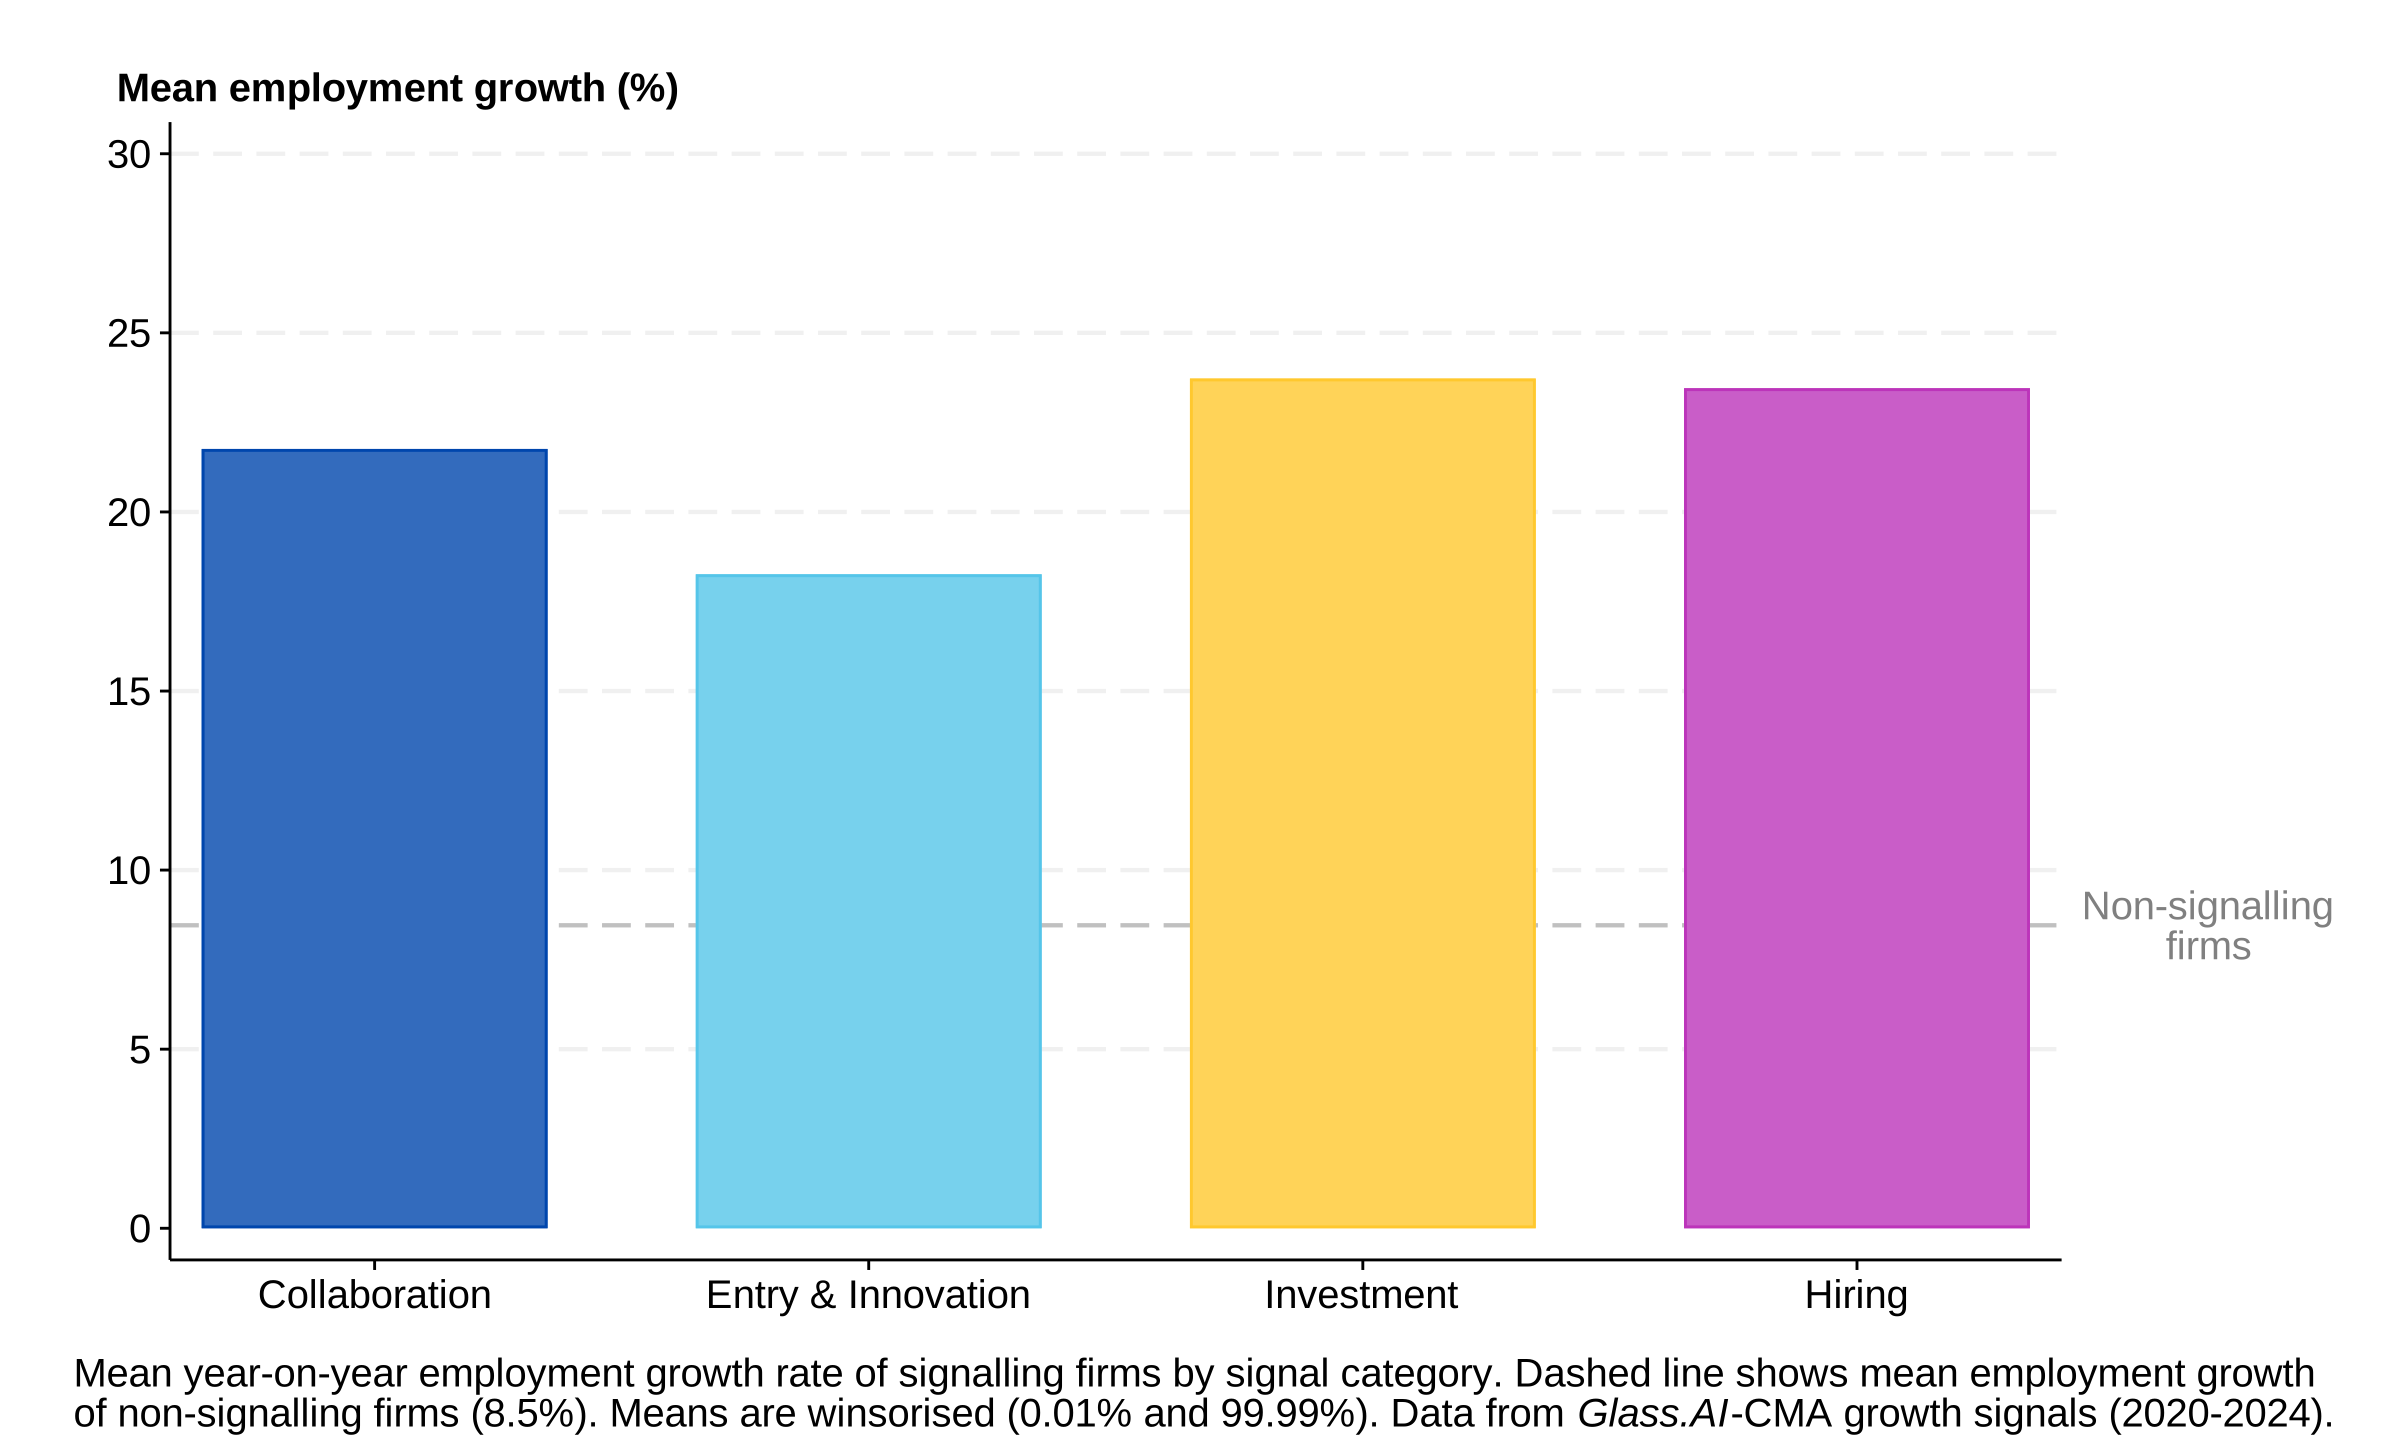
Bar chart showing mean employment growth for signalling firms displaying collaboration, entry and innovation, investment, and hiring signals, alongside a dashed horizontal line indicating the mean employment growth of non-signalling firms.
Focusing only on signalling firms, those displaying a variety of signal types grow employment faster on average than firms that have a lower variety of signals. Figure 39 shows that average year-on-year employment growth is significantly faster for firms with 3 to 4 signals compared to those with 1 to 2 signals. The difference may reflect that strong firm growth comes from the combination of a variety of different activities – such as combining entry into a new market with securing new financing and hiring more workers. However, this finding should be treated with caution given the relatively small number of firms displaying 3 or 4 signal types.
Figure 39 – Firms displaying 3 or 4 types of signals might grow faster
Mean year-on-year employment growth over the period 2021 to 2024 for signalling firms displaying 1 to 2 different types of signals versus 3 to 4 types, with 95% confidence intervals. Data from Glass.AI-CMA growth signals (2020 to 2025).
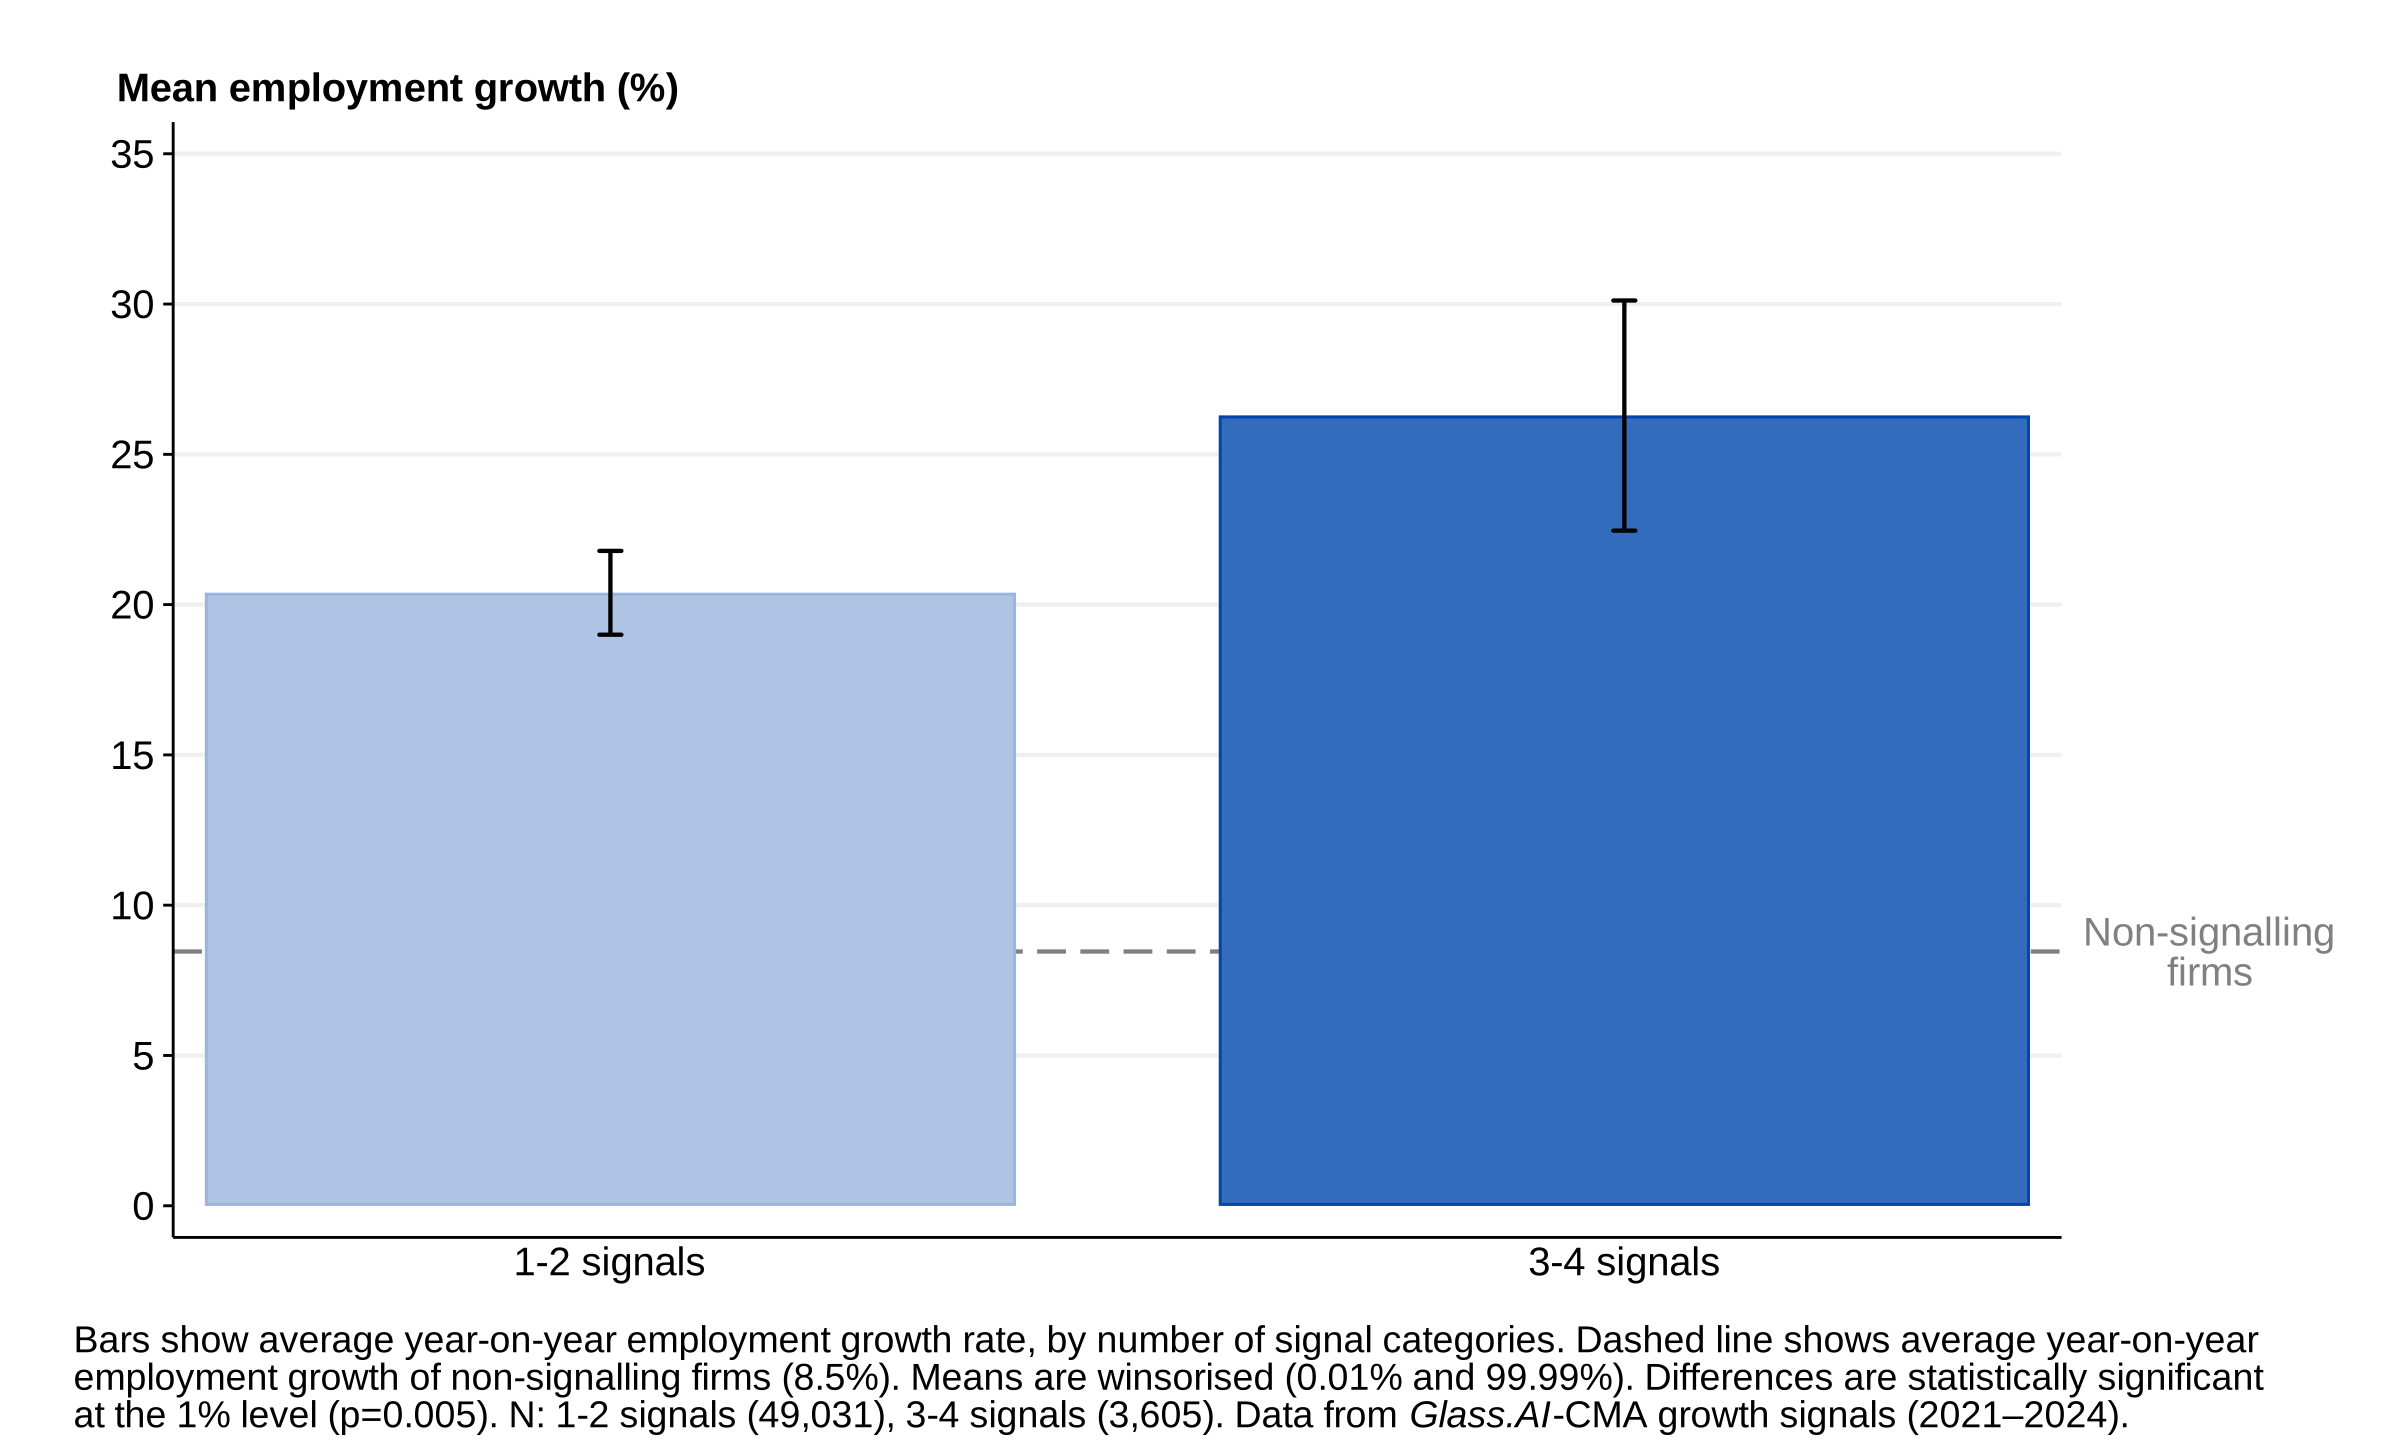
Bar chart showing mean year-on-year employment growth for signalling firms displaying 1 to 2 signal types and 3 to 4 signal types. Bars show average growth rates, vertical lines show 95% confidence intervals, and a dashed horizontal line indicates the mean employment growth of non-signalling firms.
While the results in this section suggest that signalling firms grow faster, they do not tell us whether signals are driving that growth or simply reflecting it. Faster-growing firms may be more likely to signal in the first place. There may also be unobservable factors (for example, management quality, organisational capability, or broader market conditions), that simultaneously drive both faster growth and more signalling activity. The results may also simply capture an underlying survivorship bias: firms that survive long enough to signal may already be the stronger performers. Unpicking this fully would require matching the signals data to other sources and remains an important avenue for future research.
Signalling firms partially overlap with high-growth firms, suggesting that signals may help identify fast-growing businesses
Having established that signalling firms grow employment faster on average, we now look directly at whether they overlap with high-growth firms.[footnote 35] Given the short panel structure of the data and to maximise the number of observations, the definitions of high-growth firms used in this analysis are based on year-on-year growth rates. They therefore do not exactly match any of the baseline definitions analysed in Chapter 3.
We use 3 definitions of high-growth firms:
-
20%+ annual employment growth: firms with annual employment growth of at least 20% and a minimum of 10 employees
-
annual employment growth (micro firms): firms with fewer than 10 employees that add at least 8 employees in a given year
-
annual top 10%: firms in the top 10% of the employment growth distribution in a given year
Our analysis shows that a higher proportion of ever-high-growth firms (firms identified as high-growth at least once between 2020 and 2025) display signals than the average firm in the dataset, and conditional on signalling, these firms also display more signals on average than other signalling firms. (Figure 40).
Firms growing employment at 20% or more annually are the most likely to signal, with around 9% displaying at least one growth signal. These firms also produce on average 2.3 signals. The finding on prevalence broadly aligns with the ONS Data Science Campus (2019) research, which found that 8.9% of businesses in a combined dataset incorporating web-derived data were classified as high-growth firms.
While the overlap between signalling firms and high-growth firms is partial, it is discernible. The fact that high-growth firms are more likely to signal than other firms, including those in high-signalling Industrial Strategy growth-driving sectors (IS-8) such as Digital and technology (as discussed above), is an encouraging finding and points to signals and traditional high-growth definitions as potentially complementary tools for identifying fast-growing firms.
Figure 40 – High-growth firms exhibit both higher signalling prevalence and intensity than the economy-wide average
Proportion of firms with at least one growth signal (extensive margin, left panel) average number of growth signals per signalling firm (intensive margin, right panel) for firms classified as high-growth firms by 3 definitions, versus average across all firms. Data from Glass.AI-CMA growth signals (2020 to 2025).
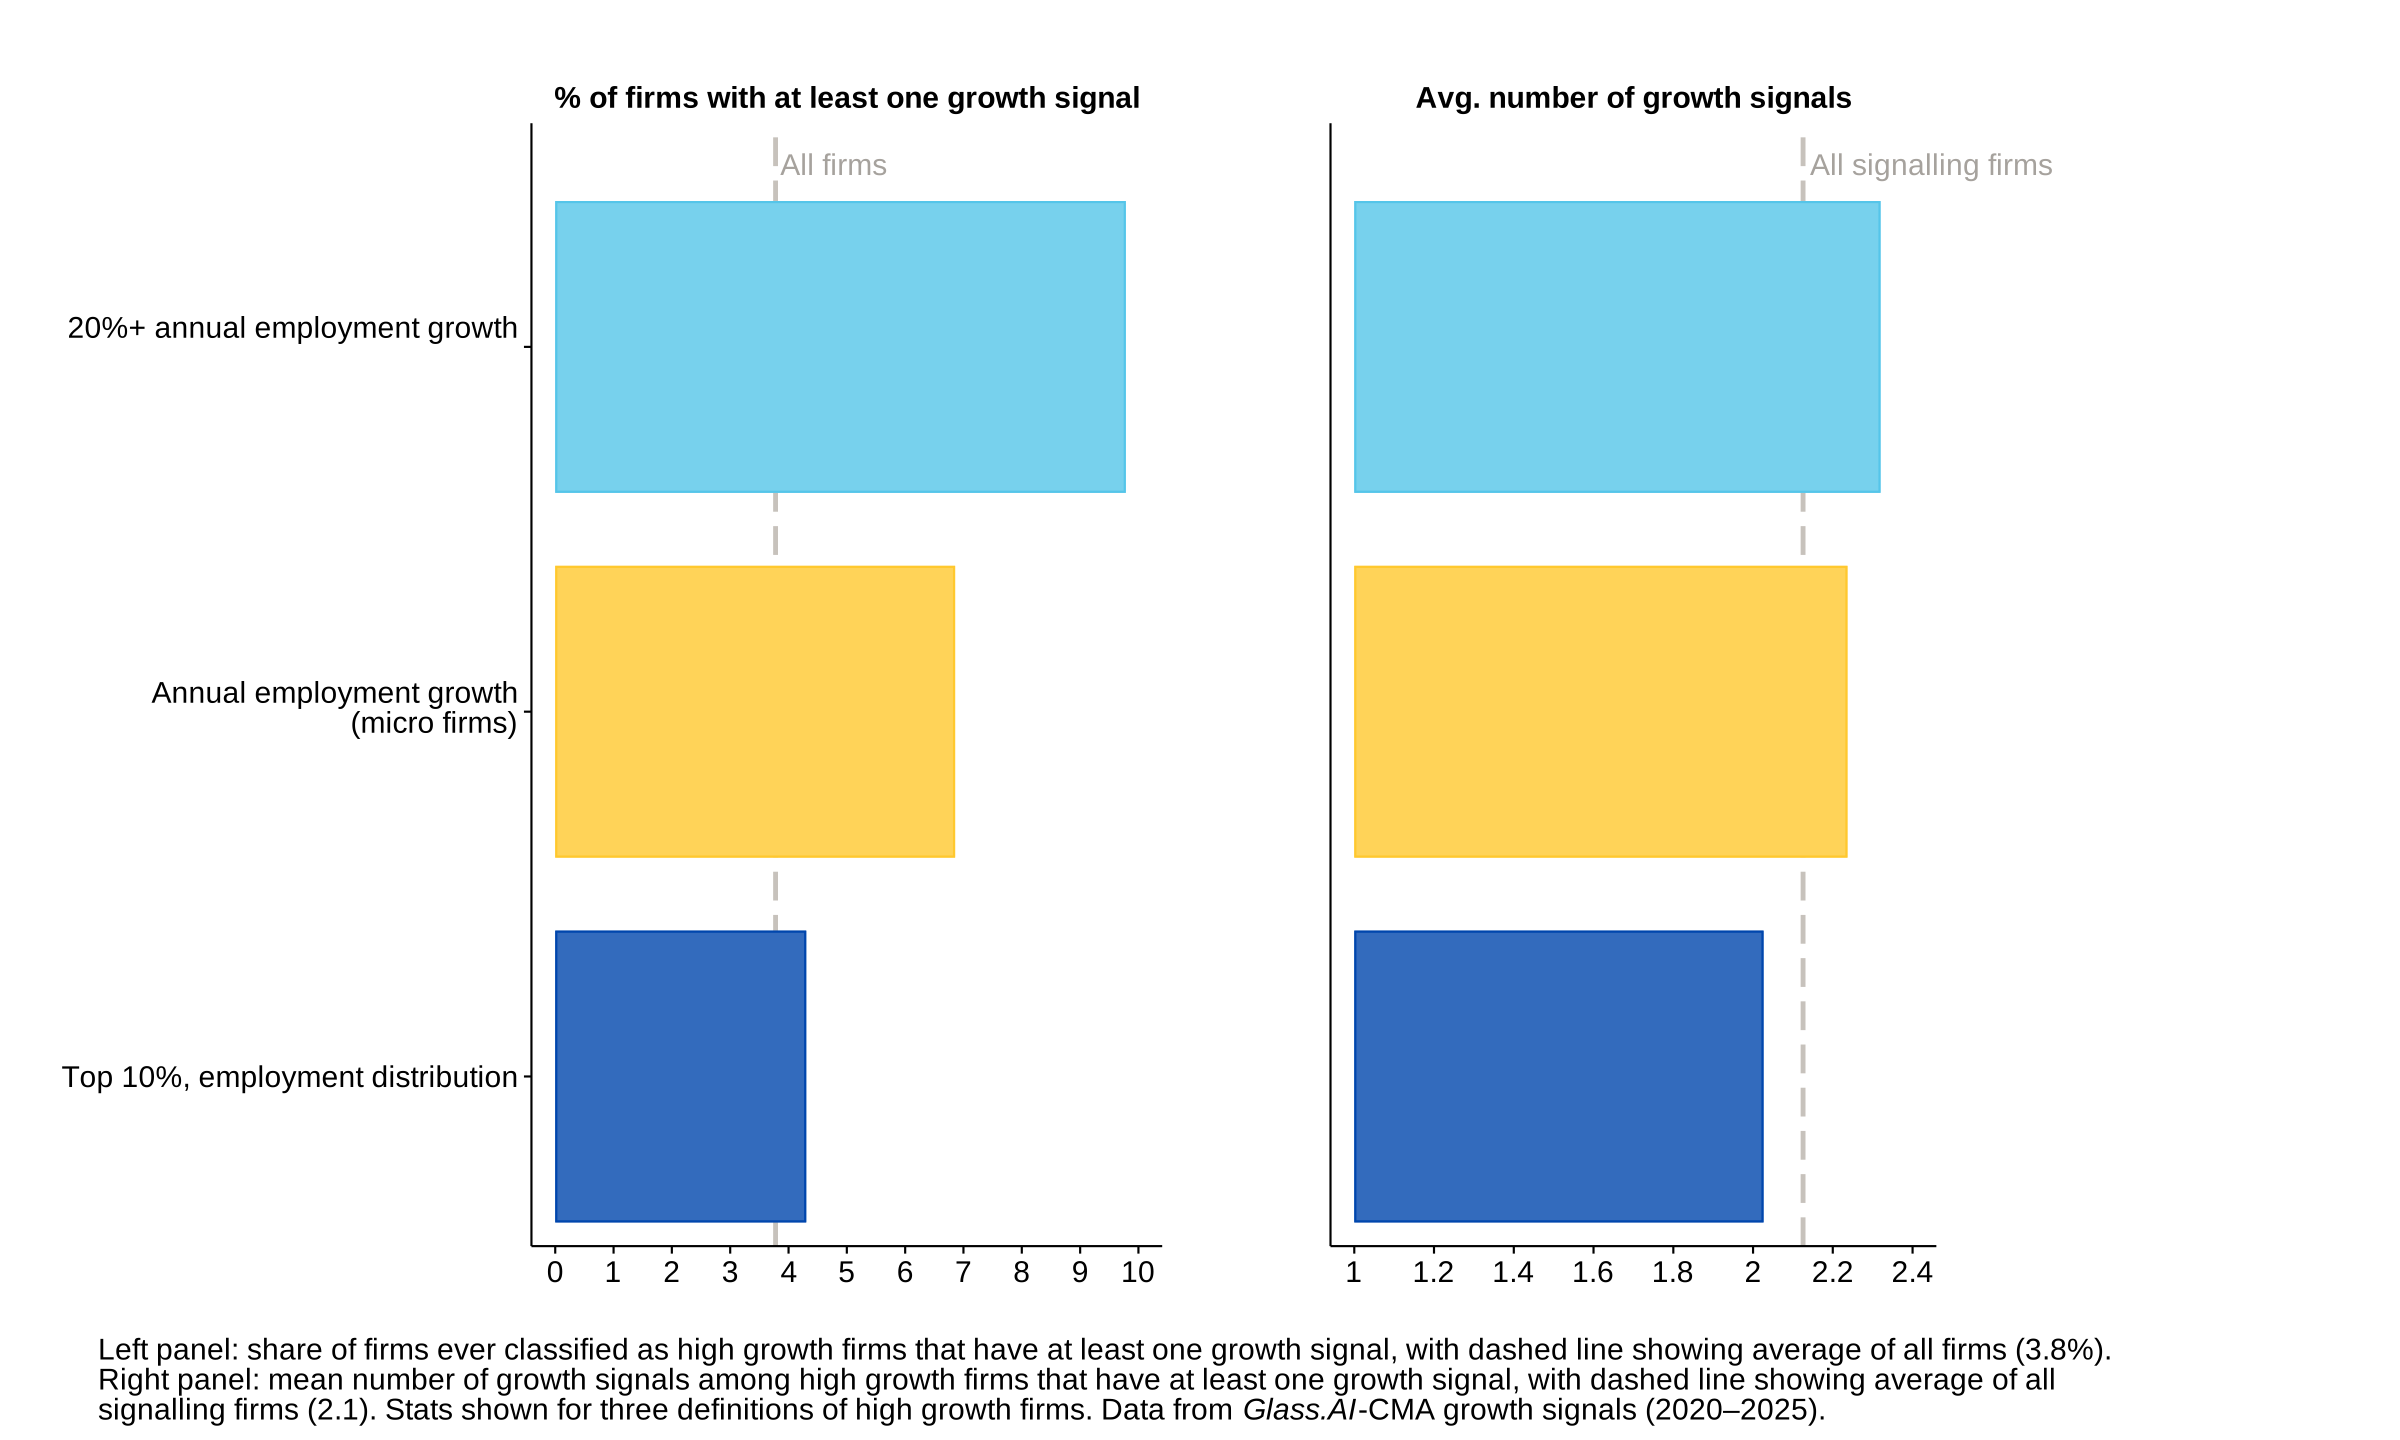
2-panel horizontal bar chart showing growth signal prevalence and intensity among firms classified as high-growth firms under three different definitions. The left panel shows the share of firms with at least one growth signal, and the right panel shows the average number of growth signals among signalling firms. Dashed vertical lines indicate the average across all firms (left panel) and all signalling firms (right panel).
Conditional on signalling, high-growth firms are more likely to issue certain types of signals than other signalling firms. Focusing on the 20%+ annual employment growth definition, high-growth firms have a higher share of collaboration (a difference of 13 percentage points (pp)), investment (12 pp) and hiring (15 pp) signals than non-high-growth signalling firms, as shown in Figure 41. These differences are all statistically significant. By contrast, there is no significant difference in entry and innovation signals between high-growth firms and other signalling firms. These patterns are consistent across the other high-growth firm definitions used in this chapter.
Figure 41 – A higher share of high-growth firms issue hiring, investment and collaboration signals than non-high-growth signalling firms
Proportion of high-growth firms and non-high-growth firms with at least one growth signal of each category (collaboration, entry and innovation, investment and hiring). High-growth firms categorised using the 20%+ annual employment growth definition. Data from Glass.AI-CMA growth signals (2020 to 2025).
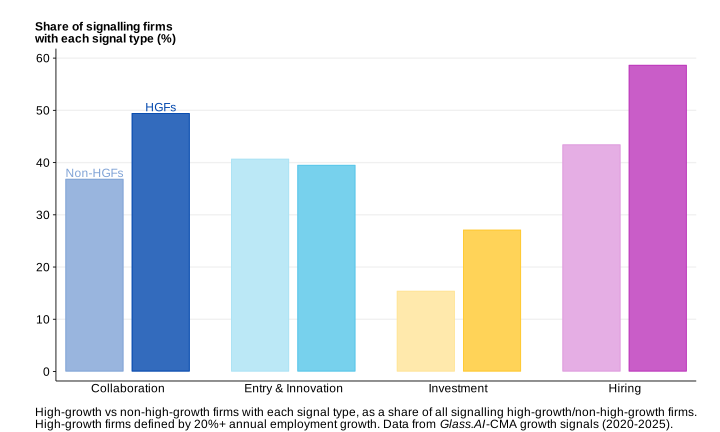
Grouped bar chart showing the share of signalling firms displaying collaboration, entry and innovation, investment, and hiring signals. Separate bars are shown for high-growth firms and non-high-growth firms within each signal category.
The higher prevalence of these signal types (collaboration, investment and hiring) among high-growth firms suggests that signal type may provide useful information when identifying high-growth firms. However, as the differences are modest in magnitude, signal data should be used in combination with other firm characteristics.
Employment growth is fastest before a firm’s first signal, not after it
The final question we explore is whether signals tend to appear before periods of growth or simply accompany it. Specifically, we ask whether a firm’s first growth signal coincides with the start of faster employment growth, or whether it follows a period of growth that is already underway.
Figure 42 tracks firms’ employment growth in the years around their first growth signal. On average, employment growth is at its highest in the year before the first signal and slows in the years that follow. This finding holds after controlling for firms’ age band, their size, industry in which they operate and calendar year, suggesting that the pattern is not simply explained by differences in these characteristics.
Figure 42 - Employment growth among signalling firms is highest just before the first signal
Regression coefficients estimating firms’ employment growth rate in years preceding and following a firm’s first growth signal, relative to the year prior to its first signal (t-1). Controls for firm employment level, firm age, industry (4-digit Standard Industrial Classification (SIC)) and year. Data from Glass.AI-CMA growth signals (2020 to 2024).
Coefficient plot showing differences in employment growth before and after a firm’s first growth signal, relative to the year before the signal. Points show estimated differences, vertical lines show 80%, 90% and 95% confidence intervals, and the dashed horizontal line marks zero.
This association also holds across a range of different approaches, including restricting the analysis to firms we can observe over a continuous period of time, using specific signal types, and varying the controls. Appendix provides a further breakdown of these results and specifications.
The analysis above offers suggestive evidence that signals tend to appear during or shortly after periods of rapid employment growth rather than preceding them. Importantly, however, the results in this section should be seen as an initial exploration of whether growth signals have the power to identify firms that will experience persistent growth. The analysis is severely limited by the absence of employment data in 2025 and 2026, which means signals recorded in 2025 (which account for the majority of signals, see Figure 29) cannot be linked to contemporaneous or subsequent growth outcomes.
The fact that growth signals do not precede employment growth does not necessarily make them less valuable in identifying fast growing firms. Firstly, growth signals capture different aspects of firms’ growth activity in real time: firms hire, invest and form partnerships during periods of expansion and these activities promptly become visible online. Secondly, signals have the potential to provide greater coverage of firms that fall below traditional reporting thresholds, as well as richer information on the nature of firms’ growth-related activities. Therefore, growth signals could still provide useful, timely, and comprehensive source of information for identification of high-growth firms and understanding the activities associated with their growth.
Future research could build on this analysis as additional outcome data becomes available. Longer periods of post-signal observation would allow researchers to better assess whether growth signals precede episodes of rapid firm employment growth. Further work could also examine whether particular types of signals are more strongly associated with subsequent growth outcomes than others, and whether signal data can improve the identification of high-growth firms when combined with more traditional administrative and financial datasets.
Appendix
Acknowledgements
This report was produced by Tom Farmer, Fizza Jabbar, Joel Kariel, Rajssa Mechelli, Rob Mitchell, Stanislas Lalanne, Matthew Lister, Jakob Schneebacher, Borbala Szathmary and Luke McWatters on behalf of the CMA’s Microeconomics Unit.
We are grateful to a number of CMA colleagues for feedback, advice and support in developing and reviewing the report, including Jenny Haydock, and Simon Roberts. We thank Marco Nerino for advice on methods, Shaun Reidy, Hugo Wallis and Nick Wortley for help and advice on drafting. We also thank colleagues who contributed to proofreading the report, including Amanda Ereyi, Samir Doshi and Amar Shuja.
We are grateful to the CMA’s academic panel; Giacinta Cestone, Diane Coyle, and Joel Stiebale for their feedback on methods and results.
We also thank numerous colleagues in Government for their feedback, the Scale Up Institute for their comments and input on this work.
This work was undertaken in the Office for National Statistics (ONS) Secure Research Service (SRS) using data from ONS and other owners and does not imply the endorsement of the ONS or other data owners.
We thank the ONS (particularly Joseph Colliass and Keith Lai), Pay.UK and Mastercard for providing us with the analysis of UK interbank transactions data.
The authors would also like to thank Glass.AI (Telectica Ltd) for producing the growth signal dataset for the purposes of this research. This does not imply the endorsement of Glass.AI’s wider products or services.
Glossary
Cost markups: Cost markups are defined as the difference between the price at which a good or service is sold and its marginal cost. They are often expressed as a ratio of price to marginal cost. Cost markups are a measure of market power. In a perfectly competitive market markups are close to zero (or to one when defined as a ratio), meaning firms set their prices equal to their marginal cost of production. Monopolists and oligopolists have positive markups (or greater than one when defined as a ratio). For given fixed costs, the larger the markup, the greater the profit margin earned by the firm and the higher its market power.
Centrality: Centrality is a measure of how important a firm is within the supply network, accounting for its size and how connected it is to other sectors, either directly or indirectly through supply chains. Firms with high centrality play a key role in supplying other firms, either directly or through wider supply chains.
Extensive and intensive margins: Economists refer to the decision to take an action at all as the ‘extensive margin’ and to the decision of how much to do as the ‘intensive margin’. In this report, the extensive margin measures the share of firms that display at least one growth signal, while the intensive margin measures the average number of signals displayed by signalling firms.
Growth premium: Growth premium refers to the difference in growth rates between 2 groups of firms. It measures the extent to which one group outperforms another on a given growth metric (such as employment, turnover, or productivity). A positive growth premium indicates that one group is growing faster than the other, while a zero or negative premium indicates comparable or slower growth. Growth premia are used to assess performance gaps and competitive advantages across different firm characteristics or cohorts.
Herfindahl-Hirschman Index (HHI): The Herfindahl-Hirschman Index (HHI) is one common way to measure the concentration in a market or industry. It is calculated by summing the squared market shares of each firm competing in a market. By squaring the market shares the HHI measure gives greater weight to larger firms. The HHI can range from zero for a perfectly competitive market to a maximum value of 10,000 for a monopolistic market. A market is generally said to be concentrated if the HHI is above 1,500 and highly concentrated if HHI is above 2,500.
Industrial Strategy growth-driving sectors (IS-8): The 8 Industrial Strategy growth-driving sectors (IS-8) are sectors prioritised under the UK’s Modern Industrial Strategy (2025) as having the greatest potential to raise national investment and productivity, support well-paid jobs, and strengthen economic security and resilience. The 8 sectors are: Advanced Manufacturing, Clean energy industries, Creative industries, Defence, Digital and technologies, Financial services, Life sciences, and Professional and business services.
Market concentration: Market concentration is the degree to which a small number of companies control a large part of the sales in a market. When market concentration is high, it indicates only a few firms dominate the market. This may be the case in in oligopolistic or monopolistic competition. Conversely, low market concentration can indicate a more competitive market structure. However, other factors like production technologies also influence the concentration of a market. In this report, we compute one commonly employed measure of concentration, the Herfindahl-Hirschman Index (HHI).
Market power: Market power refers to the ability of a firm, or a group of firms, to influence the price of goods or services in a market. In economic theory, market power is associated with the firm’s ability to set prices above its marginal costs, and therefore higher than they would be in a competitive market. Market power can come from a cost advantage, a strong brand, the creation of a product consumers like or from the creation of barriers to entry and the acquisition of rival firms.
Supply chain: The sequence of businesses involved in the producing and delivering goods and services, from the supply of initial inputs and production through to the final customer. In an economy-wide context, many supply chains overlap and form a wider supply network.
Web crawling: Web crawling refers to the automated process of systematically collecting information from publicly available online sources using specialised software tools. A web crawler searches websites and other digital platforms, identifies relevant information and records it in a structured format. Web crawling can be undertaken at scale across multiple websites and over extended periods, allowing large datasets to be constructed from firms’ digital footprints and other online content.
Data sources
High-growth firms in the UK
The Annual Respondents Database X (ARDx; 1997 to 2020) and the Annual Business Survey (ABS; 2021) are the 2 main data sources used for markup estimation. They are also the source of our estimates of firms’ capital investment and intellectual property investment.
A) The ABS (which replaced the Annual Business Inquiry in 2009) is the Office for National Statistics’ (ONS) largest business survey, with around 62,000 questionnaires sent out across Great Britain and around 600 questions asked every year.
B) The ABS’s sampling scheme aims to produce best estimates of the population totals from a random sample stratified by Standard Industrial Classification (SIC), employment, and country using the information from the Inter-Departmental Business Register (IDBR). The sampling scheme selects all the largest businesses with a progressively smaller fraction of smaller businesses.
C) The survey collects variables such as the total value of sales, the value of purchases of goods, materials and services, capital expenditure, and total employment costs that are key to the analysis in this report.
D) The ARDx is a research dataset created by the ONS from 2 surveys: the Annual Business Inquiry (ABI) for the period 1997-2008 and the ABS (supplemented with employment data from the Business Register and Employment Survey) which replaced the ABI from 2009. The ARDx is complemented by the ARDx Capital Stock dataset that provides estimates of the reporting units’ level of capital stock generated using the Perpetual Inventory Method. Unfortunately, the ARDx coverage stops in 2020
We use the Business Structure Database (BSD; 1997 to 2023) for the estimation of concentration, persistence, and turnover weights. This database contains information on employment, turnover, foreign ownership, industrial activity and year of birth and death for almost all businesses in the UK. The BSD is primarily derived from annual snapshots of the Inter-Departmental Business Register (IDBR).
The IDBR is a live registry of UK businesses used as the main sampling frame for business surveys carried out by the ONS or other government departments. The main sources of input for the IBDR are Value Added Tax (VAT) and Pay As You Earn (PAYE) records from HMRC. The IDBR represents 97% of turnover and 88% of employment in the UK. Very small businesses that do not meet the thresholds for VAT or PAYE may not be included in the IBDR.
We use the Longitudinal Business Database (LBD; 1999 to 2022) for estimates of entry and exit, job reallocation and some M&A analysis. This database provides longitudinal information by using consecutive snapshots from the IDBR to deduce changes to business structure and continuity of business activities.
We use the Management and Expectations Survey (MES; 2016, 2020, 2023) to analyse differences in management quality between high-growth firms and the wider business populations. The MES is an ONS survey that collects information on management practices, business expectations and organisational characteristics from businesses with 10 or more employees. We use the management quality score constructed by the ONS from firms’ survey responses.
High-growth firms and their networks
We use experimental financial transaction data from the Bacs Payment System (Bacs) and the Faster Payments System (FPS) networks, produced in collaboration with the ONS, Pay.UK and Vocalink. The data is aggregated from monthly financial inflows and outflows for accounts identified as businesses using the ONS methodology (ONS, 2026). The data is linked to Companies House, which is where the industry information is from.
Growth signals
We use a custom-built dataset of ‘growth signals’, commissioned from Glass.AI (Telectica Ltd). The dataset is derived from company websites, social media platforms, news articles and official sources. Using artificial intelligence and natural language processing techniques, Glass.AI extracts structured information on firms’ activities, products and services, locations and organisational characteristics. The dataset contains a range of growth-related indicators, including recruitment activity, product launches, innovation and R&D activity, investment events, international expansion, and major customer or contract announcements.
Methodological notes
High-growth firms in the UK
In this chapter we use the following derived variables:
- high-growth period: A growth period refers to any year in which a firm meets a high-growth definition
- high-growth episode: A growth episode refers to an uninterrupted spell during which a firm is categorised as high-growth in consecutive years under a given definition of high-growth firms
Regressions of growth rate premium over firm age (Figure 10, Figure A.7).
We investigate the relationship between high-growth firms’ age and growth rate, to analyse the growth premia of high-growth firms compared to non-high-growth firms across different age bands. The estimating equation has the following form:
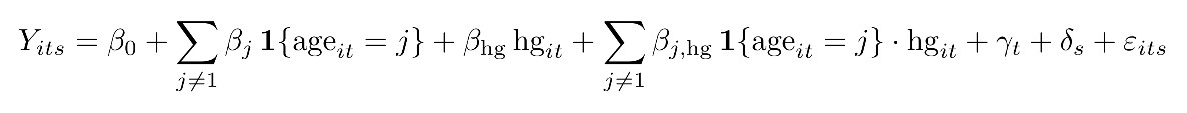
Equation. Outcome Y for firm i in year t equals the sum over age bands, excluding the omitted age band, of age-band indicators, plus a high-growth indicator, plus interactions between age-band indicators and high-growth status, plus year fixed effects, sector fixed effects, and an error term.
We use 3 dependent variables Y1, Y2 and Y3, which each represent a different metric of year-on-year firm growth:
- Y1 represents year-on-year employment growth rate
- Y2 represents year-on-year turnover growth rate
- Y3 represents year-on-year labour productivity growth rate (labelled as productivity growth rate)
We regress the growth rate of each firm (Y) on its age band (age), a dummy variable indicating the high-growth status of the firms (hg) and their interaction. We include year and industry (4-digit SIC) fixed effects. The youngest age band is the omitted category, so β_hg measures the growth premium for high-growth firms in that band and each β_j,hg measures how the premium in band j differs from it. Subscript i denotes the firm, t the year and s the 4-digit industry. We estimate the equation separately for each of the 3 growth measures above. We compute 80, 90 and 95% confidence intervals for each point estimate. Standard errors are clustered at the firm level.
The figures in the report do not show the raw coefficients of the regressions, but the estimated discrete effect of being high growth at different ages.
We repeat this regression for high-growth firms according to the 6 baseline definitions (as displayed in Figure A.7).
Likelihood of entering a first growth episode (Figure 12, Figure 13, Figure A.8-Figure A.12).
We investigate how the likelihood of entering a first high-growth episode is associated with firm characteristics. The estimating equation has the following form:
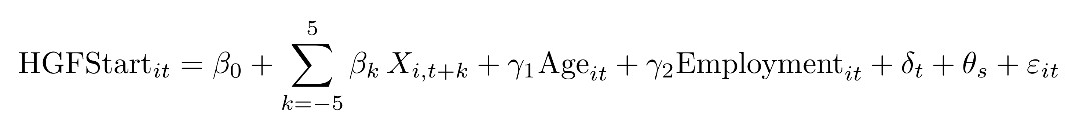
Equation. High-growth start for firm i in year t equals the sum over years before and after a firm characteristic, plus controls for firm age and employment, plus year fixed effects, sector fixed effects, and an error term.
The outcome variable (HGFStart) is a dummy variable identifying firms entering a first growth episode. HGFStart equals 0 for all those firms which have not yet experienced high growth or which never do in the observed period.
The right-hand side variables X are alternatively:
-
capital expenditure (from the ARDx/ABS)
-
material markups (from our estimates using ARDx/ABS)
-
number of establishments (from the LBD)
-
intellectual property expenditure (from the ARDx/ABS)
In all regressions, the independent variables are standardised, and we include 5 lags and 5 leads in addition to the contemporaneous (to the onset of high growth) observation. The regressions include survey weights where applicable.
The full control specification includes firm size (employment) and age, and year and industry (SIC 4-digit) fixed effects. Standard errors are clustered at the firm level.
We also test the association between management quality and the likelihood of entering a first growth episode. The estimating equation has the following form:
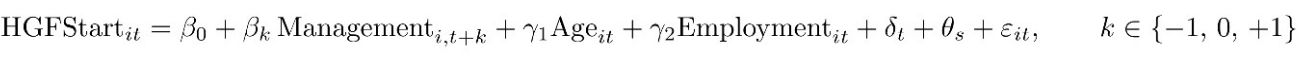
Equation. High-growth start for firm i in year t equals management score measured one year before, during, or one year after a high-growth period, plus controls for firm age and employment, plus year fixed effects, sector fixed effects, and an error term.
The specification of these regressions are very similar to the above but, due to data limitations we are restricted to 1 lead and 1 lag and we include them in separate regressions.
High-growth firms and their networks
Derived variables
The complete list of the derived variables used in this chapter of the report is:
- upstream concentration: the Herfindahl-Hirschman Index computed from supplier shares of the firm’s spending. For each supplier, their share of the firm’s total outflows is computed, then the squared shares are summed and multiplied by 10,000. The index ranges from 0 to 10,000, where higher values indicate spending concentrated among fewer suppliers
- downstream concentration: the same computation as for upstream concentration, but on the customer side. For each customer, their share of the firm’s total inflows is computed. Higher values indicate revenue concentrated among fewer customers
- number of suppliers: the count of distinct firms to which the firm makes payments in that year
- number of customers: the count of distinct firms that make payments to the given firm in that year
- largest supplier share: the share of the firm’s total outflows accounted for by its single largest supplier
- largest customer share: the share of the firm’s total inflows accounted for by its single largest customer
- customer dependence on the firm: a flow-weighted average, across the firm’s customers, of how much each customer spends with the firm as a share of that customer’s total outflows. A high value means the firm is an important supplier to its customers. This differs from the largest customer share, which measures the firm’s own portfolio composition rather than its partners’ reliance on it
- supplier dependence on the firm: the same computation as for customer dependence but on the supplier side. A flow-weighted average, across the firm’s suppliers, of how much of each supplier’s total revenue comes from the firm
- centrality: the PageRank algorithm is used to measure how important each firm is in the supply network. The importance of firms in a network is measured based on the quantity and quality of incoming links, assigning higher scores to nodes connected to other high-scoring firms
- first-degree upstream high-growth firm exposure: the share of a firm’s outflows going to suppliers classified as high growth. This captures what fraction of spending goes to high-growth suppliers
- first-degree downstream high-growth firm exposure: the share of a firm’s inflows from customers classified as high growth. This captures what fraction of revenue comes from high-growth customers
- number of high-growth suppliers: the count of distinct suppliers classified as high-growth that the firm makes payments to in that year
- number of high-growth customers: the count of distinct customers classified as high-growth that make payments to the firm in that year
- central government share: the share of the firm’s non-financial turnover accounted for by payments from central government. This includes contracts to supply goods or services to government, subsidies, grants, loans, and other forms of business support, which cannot be separately identified in the data
- central government turnover: the level of inbound payments from central government, deflated to real terms and expressed in millions of pounds
- financial sector ratio: the ratio of payments received from the financial sector (excluding insurance) to non-financial turnover. This can exceed one because the denominator excludes financial sector revenue. Values are winsorised at the 99th percentile of the non-zero distribution to limit the influence of outliers
- financial sector turnover: the level of inbound payments from financial sector payers (excluding insurance), deflated to real terms and expressed in millions of pounds
- turnover volatility: the coefficient of variation of monthly non-financial turnover within each year, computed as the standard deviation of monthly values divided by their mean. This measures within-year revenue lumpiness rather than year-on-year growth variance
Descriptive comparisons (Figure 21 and Figure 27)
The descriptive comparisons[footnote 36] compare yearly averages between high-growth firms and the rest of the business population. In the main body, we take the mean of these annual means to give us a single average, and display this in a single bar.
Predictive associations (Figure 22)
The relationship between lagged firm characteristics and the probability of entering a high-growth period is estimated using a linear probability model.[footnote 37] The estimating equation has the following form:
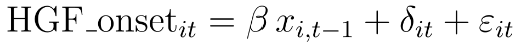
Equation. High-growth onset for firm i in year t equals beta times the lagged characteristic x, plus fixed effects delta, plus an error term.
The outcome variable is a binary indicator equal to one if the firm is in the first year of a high-growth period and zero otherwise. A high growth period is defined as the first year of a 3-year window in which the firm’s non-financial turnover growth is in the top 10% of the economy-wide distribution.
The model is estimated separately for each lagged characteristic. Each characteristic, on the right-hand-side of the equation, enters separately in a univariate specification.
In the estimating equation, i denotes firms, t denotes year, xi,t-1 is a lagged characteristic standardised to have mean zero and unit standard deviation, and δit represents the fixed effects included in each specification. The coefficient β is reported in standard deviation units and represents the change in the probability of entering a high-growth period associated with a one standard deviation increase in the characteristic in the prior year. Standard errors are clustered at the firm level.
The analysis progressively increases the set of fixed effects included in the model. The specifications are: i) pooled; ii) year fixed effects only, which absorb aggregate time trends; iii) year and 2-digit SIC industry fixed effects, which additionally absorb time-invariant industry differences; iv) year interacted with 2-digit SIC fixed effects, which absorb industry-specific trends; and v) firm and year fixed effects, which absorb all time-invariant firm characteristics and identify only within-firm changes over time.
Coefficients that survive the addition of firm fixed effects reflect within-firm changes that precede high-growth episodes. The right-hand-side variables are endogenous, so these associations should not be interpreted as causal.
Young firm analysis (Figure 23)
The young firm analysis uses a separate sample and a separate design from the panel regressions.[footnote 38] It asks whether a firm’s trading network shortly after incorporation is associated with future high growth.
The sample is restricted to entrants. An entrant is a company incorporated between 2019 and 2022, according to Companies House incorporation dates, and first observed in the payment data at age zero or one. This restriction matters. The payment data begins in 2019, so for companies incorporated before then we observe their network at panel entry rather than at founding. The cohort restriction to 2019 to 2022 ensures every firm can be observed for the full outcome window. This yields approximately 745,000 entrants. The same exclusions apply as elsewhere: financial sector (SIC division 64) and public administration (SIC division 84) are dropped, and firm-year observations with non-financial turnover below £10,000 are excluded.
The outcome variable is a binary indicator equal to one if the firm is flagged as high growth in any of the 3 years following its entry year, and zero otherwise. A high-growth firm is defined using the same 3-year economy-wide definition as the main analysis. The outcome is measured over a fixed window from entry+1 to entry+3 for every firm. A fixed window is necessary because entry cohorts are observed for different lengths of time. Approximately 16% of entrants meet the outcome definition.
The right-hand-side variables are measured in the firm’s entry year and standardised to have mean zero and unit standard deviation within entry cohort. Standardisation is done within cohort because the centrality measures are normalised separately in each year of the network. Each right-hand-side variable enters separately in a univariate specification. The estimating equation has the following form:
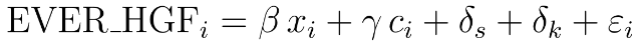
Equation. Ever high growth for firm i equals beta times the standardised entry-year characteristic x, plus gamma times a vector of controls c, plus industry fixed effects, plus cohort fixed effects, plus an error term.
In the estimating equation, i denotes firms, s denotes 2-digit SIC industry and k denotes entry cohort. The variable xi is a single standardised entry-year characteristic, and ci is a vector of controls comprising entry-year log non-financial turnover and the number of months the firm is observed in its entry year. δs and δk are additive industry and cohort fixed effects. Standard errors are heteroskedasticity-robust. The coefficient β is reported in standard deviation units and represents the change in the probability of becoming high growth within 3 years associated with a one standard deviation increase in the characteristic at entry.
The industry and cohort fixed effects enter additively and are not interacted. Industry-specific shocks in particular years are therefore not absorbed. The entry-year size control is used as partner counts and centrality both scale with measured payment volume. Without conditioning on size, the results would restate the fact that larger entrants grow. Months observed controls for firms that enter part-way through a calendar year and therefore record fewer partners mechanically.
Centrality is measured from a separate set of network statistics computed on the payment graph. These are available for around 57% of entrants. Smaller new firms with few or low-value relationships fall below the thresholds used to construct the graph and so do not appear in it. The centrality specification is estimated using this subsample only, meaning it is more likely to omit smaller firms. The partner count and concentration specifications use the panel measures directly and cover the full entrant sample.
The descriptive associations reported in Chapter 4 describe which entrants experience subsequent high growth. They should not be read as the causal effect of network breadth on growth.
Event study regressions – within-firm changes over time (Figure 24, Figure 25, Figure 26 and Figure 28)
The event study specification estimates how firm characteristics change in the years before and after a firm’s first high-growth episode.[footnote 39] The event is dated to the first year of the 3-year growth window. For example, if a firm’s 3-year growth rate first enters the top 10% over the period 2021 to 2023, the event is dated to 2021. Relative time is measured as the number of years before or after this onset year. The year immediately before onset serves as the reference period.
Each variable is estimated in a separate regression to avoid multicollinearity among correlated supply chain characteristics and to provide a clear ranking of individual associations.
The sample covers 2019 to 2025 and is drawn from a 10% random subsample of companies in the matched payment flow data. Firms in the financial sector (SIC division 64) and public administration (SIC division 84) are excluded. All firm-year observations with non-financial turnover below £10,000 are excluded.
The estimating equation has the following form:
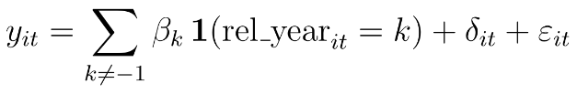
Equation. The outcome Y for firm i in year t equals the sum over event times k, excluding minus one, of beta k times an indicator that relative year equals k, plus fixed effects, plus an error term.
In the estimating equation, i denotes firms, t denotes year, rel_yearit is the number of years between t and the firm‘s first high-growth onset, and 1(.) is an indicator function that identifies each event year relative to the onset. The reference category is k = -1, so all coefficients are estimated relative to the year before onset. Standard errors are clustered at the firm level.
The set of fixed effects included in the model are progressively increased. The specifications are:
- year fixed effects
- year and 2-digit SIC industry fixed effects
- firm and year fixed effects. The firm fixed effects specification is the primary specification shown in Chapter 4
The interpretation of the coefficients differs across specifications. Under year fixed effects only, the coefficients compare high-growth firms at each event time to the economy-wide average, after removing common time trends. Under year and 2-digit SIC industry fixed effects, the coefficients compare high-growth firms to other firms in the same industry and year, showing how high-growth firms differ from their industry peers around the time of their growth episode. Under firm and year fixed effects, the coefficients reflect within-firm changes over time: how the firm’s characteristics at each event time differ from its own characteristics in the year before onset.
The coefficients βk trace out the time path of the outcome variable around the onset of high growth. Pre-event coefficients (k \ 0) show whether changes persist after the onset of high growth.
The event window is restricted to 4 years before and 5 years after onset. The same sample restrictions apply as for the panel regressions. The event study is descriptive and does not identify causal effects.
Growth signals
Data cleaning
Each signalling event records the firm, the date, the web source and the associated text snippet containing relevant evidence.
Duplicate signals are removed to avoid-counting the same underlying growth activity more than once. This includes fully identical observations, repeated evidence captured across multiple webpages or websites and multiple observations of the same signal type for a firm on the same date. We also remove signals of the same type occurring within 7 days of each other for the same firm, as these typically reflect the same activity reported multiple times across online sources. Seasonal variation in hiring activity, documented by Romanko and O’Mahony (2022), does not affect our analysis because signals are aggregated to the firm-year level, which absorbs any within-year fluctuations.
Firms are matched to Companies House data using a combination of fuzzy matching on company names and addresses, together with registered company names and company numbers where these appear on company websites. As Companies House data is annual, signalling events are aggregated to firm-year observations, which record the number of signals issued by a firm in a given year.
Negative signals, such as announcements of redundancies, hiring freezes or closures, are not included in the analysis. These signals are relatively rare, limiting the scope for meaningful analysis.
We use employment figures from Companies House and screen for implausible values consistent with known errors in administrative survey data, such as potential field misclassification. We remove observations when they exhibit extreme year-to-year jumps relative to adjacent observations within a firm or when reported employment exceeds 850,000 employees – following manual inspection which suggested these values were not credible. We warn that regression results can be susceptible to the choice of cut-off.
For the employment growth estimates and regressions, employment growth is winsorised at the 0.1% level at both tails.
Association between signal types
We investigate the relationship between different types of growth signals by examining whether firms displaying one type of signal are more likely to display a different type of signal in the following year. We estimate a linear probability model of the following form:
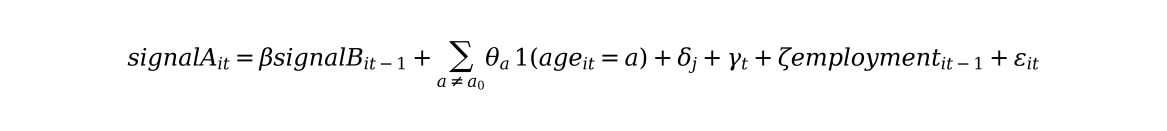
Equation. An indicator that firm i issues a signal of type A in year t equals beta times signal B in year t minus 1, plus the sum over age bands a, excluding the omitted band, of theta a times an indicator that firm age equals a, plus industry fixed effects, plus year fixed effects, plus zeta times lagged employment, plus an error term.
The outcome variable is a binary indicator equal to one if a firm displays a signal of type A in year t, and zero otherwise. The main explanatory variable is a binary indicator equal to one if the same firm issued a signal of type B in year t-1. We test the model for different combinations of macro signals (hiring, collaboration, entry and innovation, and investment) as both signal type A and signal type B.
In the estimating equation, i denotes firms, j industry (4-digit SIC industry), t year, a0 the excluded age band, and 1(.) is an indicator function. The model includes industry (δj) and year (γt) fixed effects, age-band controls (θa) and lagged employment (ζ). Errors are clustered at the 4-digit SIC level.
As the outcome variable is binary, coefficients are interpreted as changes in the probability of a signal of type A associated with displaying a signal of type B in the previous year. We estimate a linear probability model because the outcome variable is binary and the inclusion of multiple fixed effects is more straightforward than in non-linear models. As a robustness check, we also estimate pooled logit models with a reduced set of fixed effects and obtain similar results.
The sample is restricted to firm-year observations with at least one signal of any type to ensure that the firm was covered by the data collection process. This restriction may bias the associations upwards.
Signalling firm growth differentials (Figure 37)
The analysis estimates employment growth differentials between firms with and without growth signals and whether these differences vary by age groups. The estimating equation has the following form:
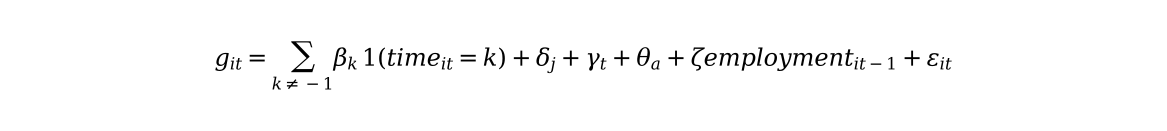
Equation. Employment growth g for firm i in year t equals the sum over age bands of theta a times an age indicator, plus the sum over age bands of beta a times the age indicator multiplied by a signalling indicator, plus industry fixed effects, plus year fixed effects, plus zeta times lagged employment, plus an error term.
The outcome variable is annual employment growth (g), and the main explanatory variable (signal) is a binary indicator equal to one if a firm displays at least one growth signal during 2020 to 2025, and zero otherwise.
In the estimating equation, i denotes firms, j industry (4-digit SIC industry), t denotes year, a0 the excluded age band. The coefficient βa measures the difference in employment growth between signalling and non-signalling firms within each age band.
As with other analyses in this report, the result should be interpreted as descriptive associations rather than causal relationships. Firms displaying growth signals may differ from other firms in ways that are not fully captured by the controls in the specification.
As a robustness check, we estimate alternative specifications that weight observations by first-observed employment, use hiring signals instead of the aggregate growth signal measure and sequentially add controls. The results are qualitatively similar across specifications.
First signal event study (Figure 42)
The analysis estimates employment growth before and after a firm’s first signal. We estimate an event study specification of the following form:
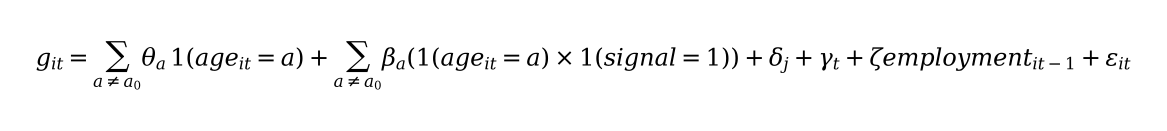
Equation. Employment growth g for firm i in year t equals the sum over event times k, excluding minus one, of beta k times an indicator that event time equals k, plus industry fixed effects, plus year fixed effects, plus age band controls, plus zeta times lagged employment, plus an error term.
The event is dated to the first year in which a firm displays a growth signal. Relative time is measured as the number of years before or after the first signal. The year immediately before the first signal serves as the reference period.
The outcome variable is employment growth (g) and the coefficient (βk) measures the difference in employment growth k years before or after a firm’s first signal relative to the year before its first signal.
In the estimating equation, i denotes firms, j industry (4-digit SIC industry), t denotes year. The model includes industry (δj) and year (γt) fixed effects, age-band controls (θa) and lagged employment (ζ). Errors are clustered at the 4-digit SIC level. The excluded event time is k = -1, the year before the first signal. As firm fixed effects are not used, coefficients are partly identified from cross-sectional comparisons between firms observed at different event times.
As a robustness check, we estimate alternative specifications that weight observations by first-observed employment, restrict the sample to firms observed in years -1, 0 and 1 relative to the first signal, use hiring signals instead of the aggregate growth signal measure, and sequentially add controls. All specifications find that employment growth in the years following the first signal that is observed for a firm is either lower than in the year before or statistically indistinguishable from it.
Additional figures
Figure A.1 - The proportion of the business population meeting the OECD definitions has remained broadly constant over time
Share of firms identified as high-growth firms according to the different definitions listed in Table A.1 of the Appendix. The coloured lines represent our baseline definitions. Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
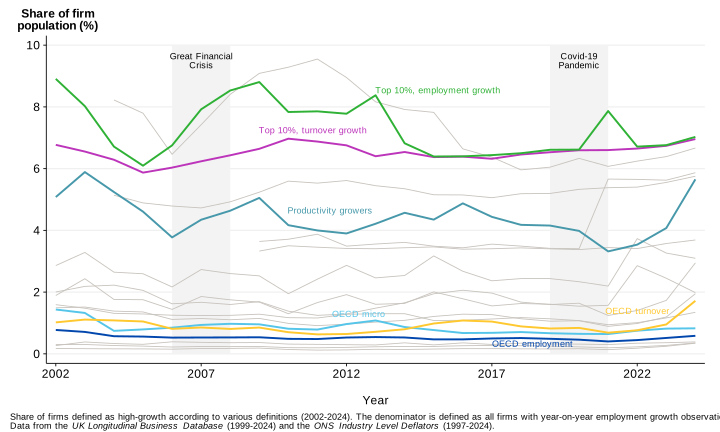
Multi-series line chart showing the share of firms classified as high growth under different definitions between 2002 and 2024. Coloured lines represent the baseline high-growth definitions (Top 10% employment growth, Top 10% turnover growth, Productivity growers, OECD micro, OECD turnover, OECD employment) and grey lines represent alternative definitions listed in Table 1 in the Appendix. Shaded bands mark the Great Financial Crisis and the COVID-19 pandemic.
Figure A.2 - The degree of overlap varies for different high-growth firm definitions
Venn diagram displaying the overlap between 4 different definitions of high-growth firms (OECD turnover, Top 10% turnover growth, Top 10% employment growth, Productivity growers) in 2024. Each section reports the share of firms designated as high-growth firms by each of the 4 definitions as a proportion of the firms designated by any of those definitions. Data from the Longitudinal Business Database (1999 to 2024).
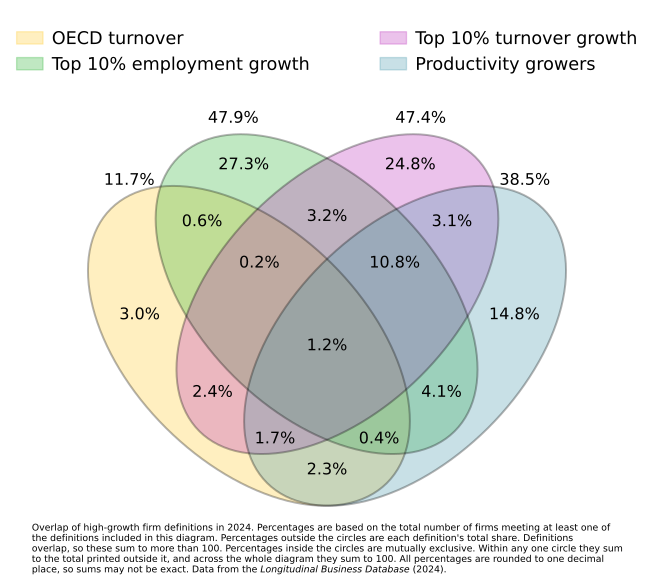
4-set Venn diagram showing the overlap between OECD turnover, Top 10% turnover growth, Top 10% employment growth and Productivity growers in 2024. Percentages are displayed within each section to indicate the share of firms belonging to that unique combination of high-growth definitions.
Figure A.3 – For all definitions, the performance of high-growth firms has improved relative to non-high-growth firms
Year-on-year average growth rate differentials (turnover, employment, labour productivity) between high-growth firms and non-high-growth firms based on 3 definitions of high-growth firms (OECD employment, Productivity growers, OECD turnover), with Hodrick-Prescott filtered series (smoothing = 100). Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
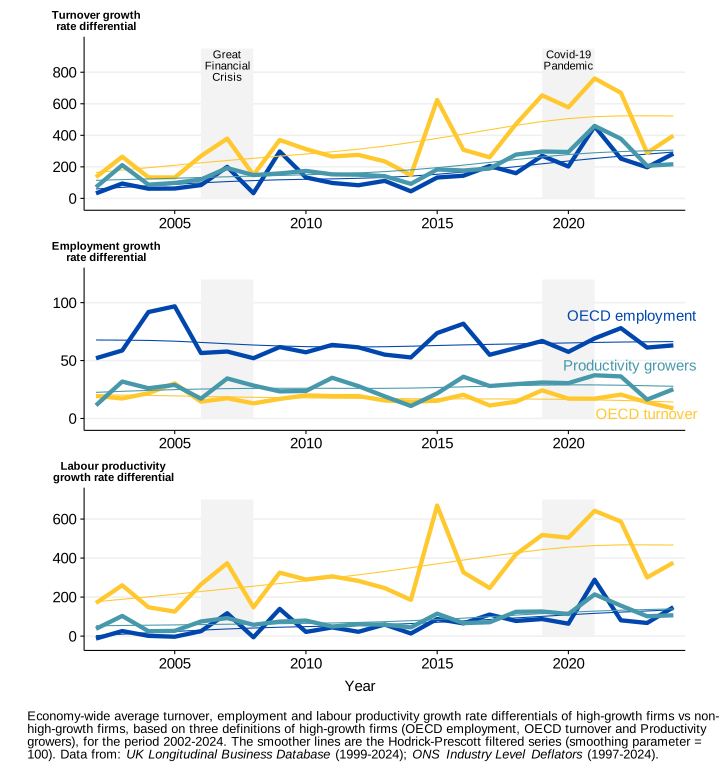
3-panel line chart showing differences in turnover growth, employment growth and labour productivity growth between high-growth firms and non-high-growth firms over time. Each panel displays separate series for OECD employment high-growth firms, OECD turnover high-growth firms and productivity growers, alongside smoothed trend lines. Shaded bands mark the Great Financial Crisis and the COVID-19 pandemic.
Figure A.4 – Distribution of year-on-year employment growth rates for high-growth firms, including OECD micro definition
Distributional statistics of the year-on-year employment growth rate distribution for the whole economy and for firms identified as high growth according to the baseline definitions (OECD employment, OECD turnover, Productivity growers, Top 10% turnover growth, Top 10% employment growth and OECD micro) in 2024. Distributional statistics include the mean, median, and 10 to 90th percentile range. Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
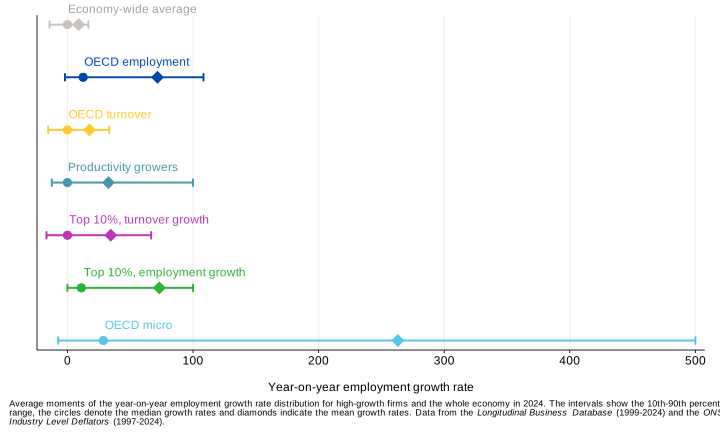
Distribution plot showing year-on-year employment growth for the economy overall and firms meeting the baseline high-growth firm definitions (OECD employment, OECD turnover, Productivity growers, Top 10% turnover growth, Top 10% employment growth and OECD micro) in 2024. Circles indicate median growth, diamonds indicate mean growth, and horizontal lines show the 10th to 90th percentile range.
Figure A.5 – High-growth firms account for a more than their proportional share of turnover across different sectors
Share of firms and turnover accounted by high-growth firms across Industrial Strategy growth-driving sectors (IS-8) for the baseline definitions of high-growth growth. Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
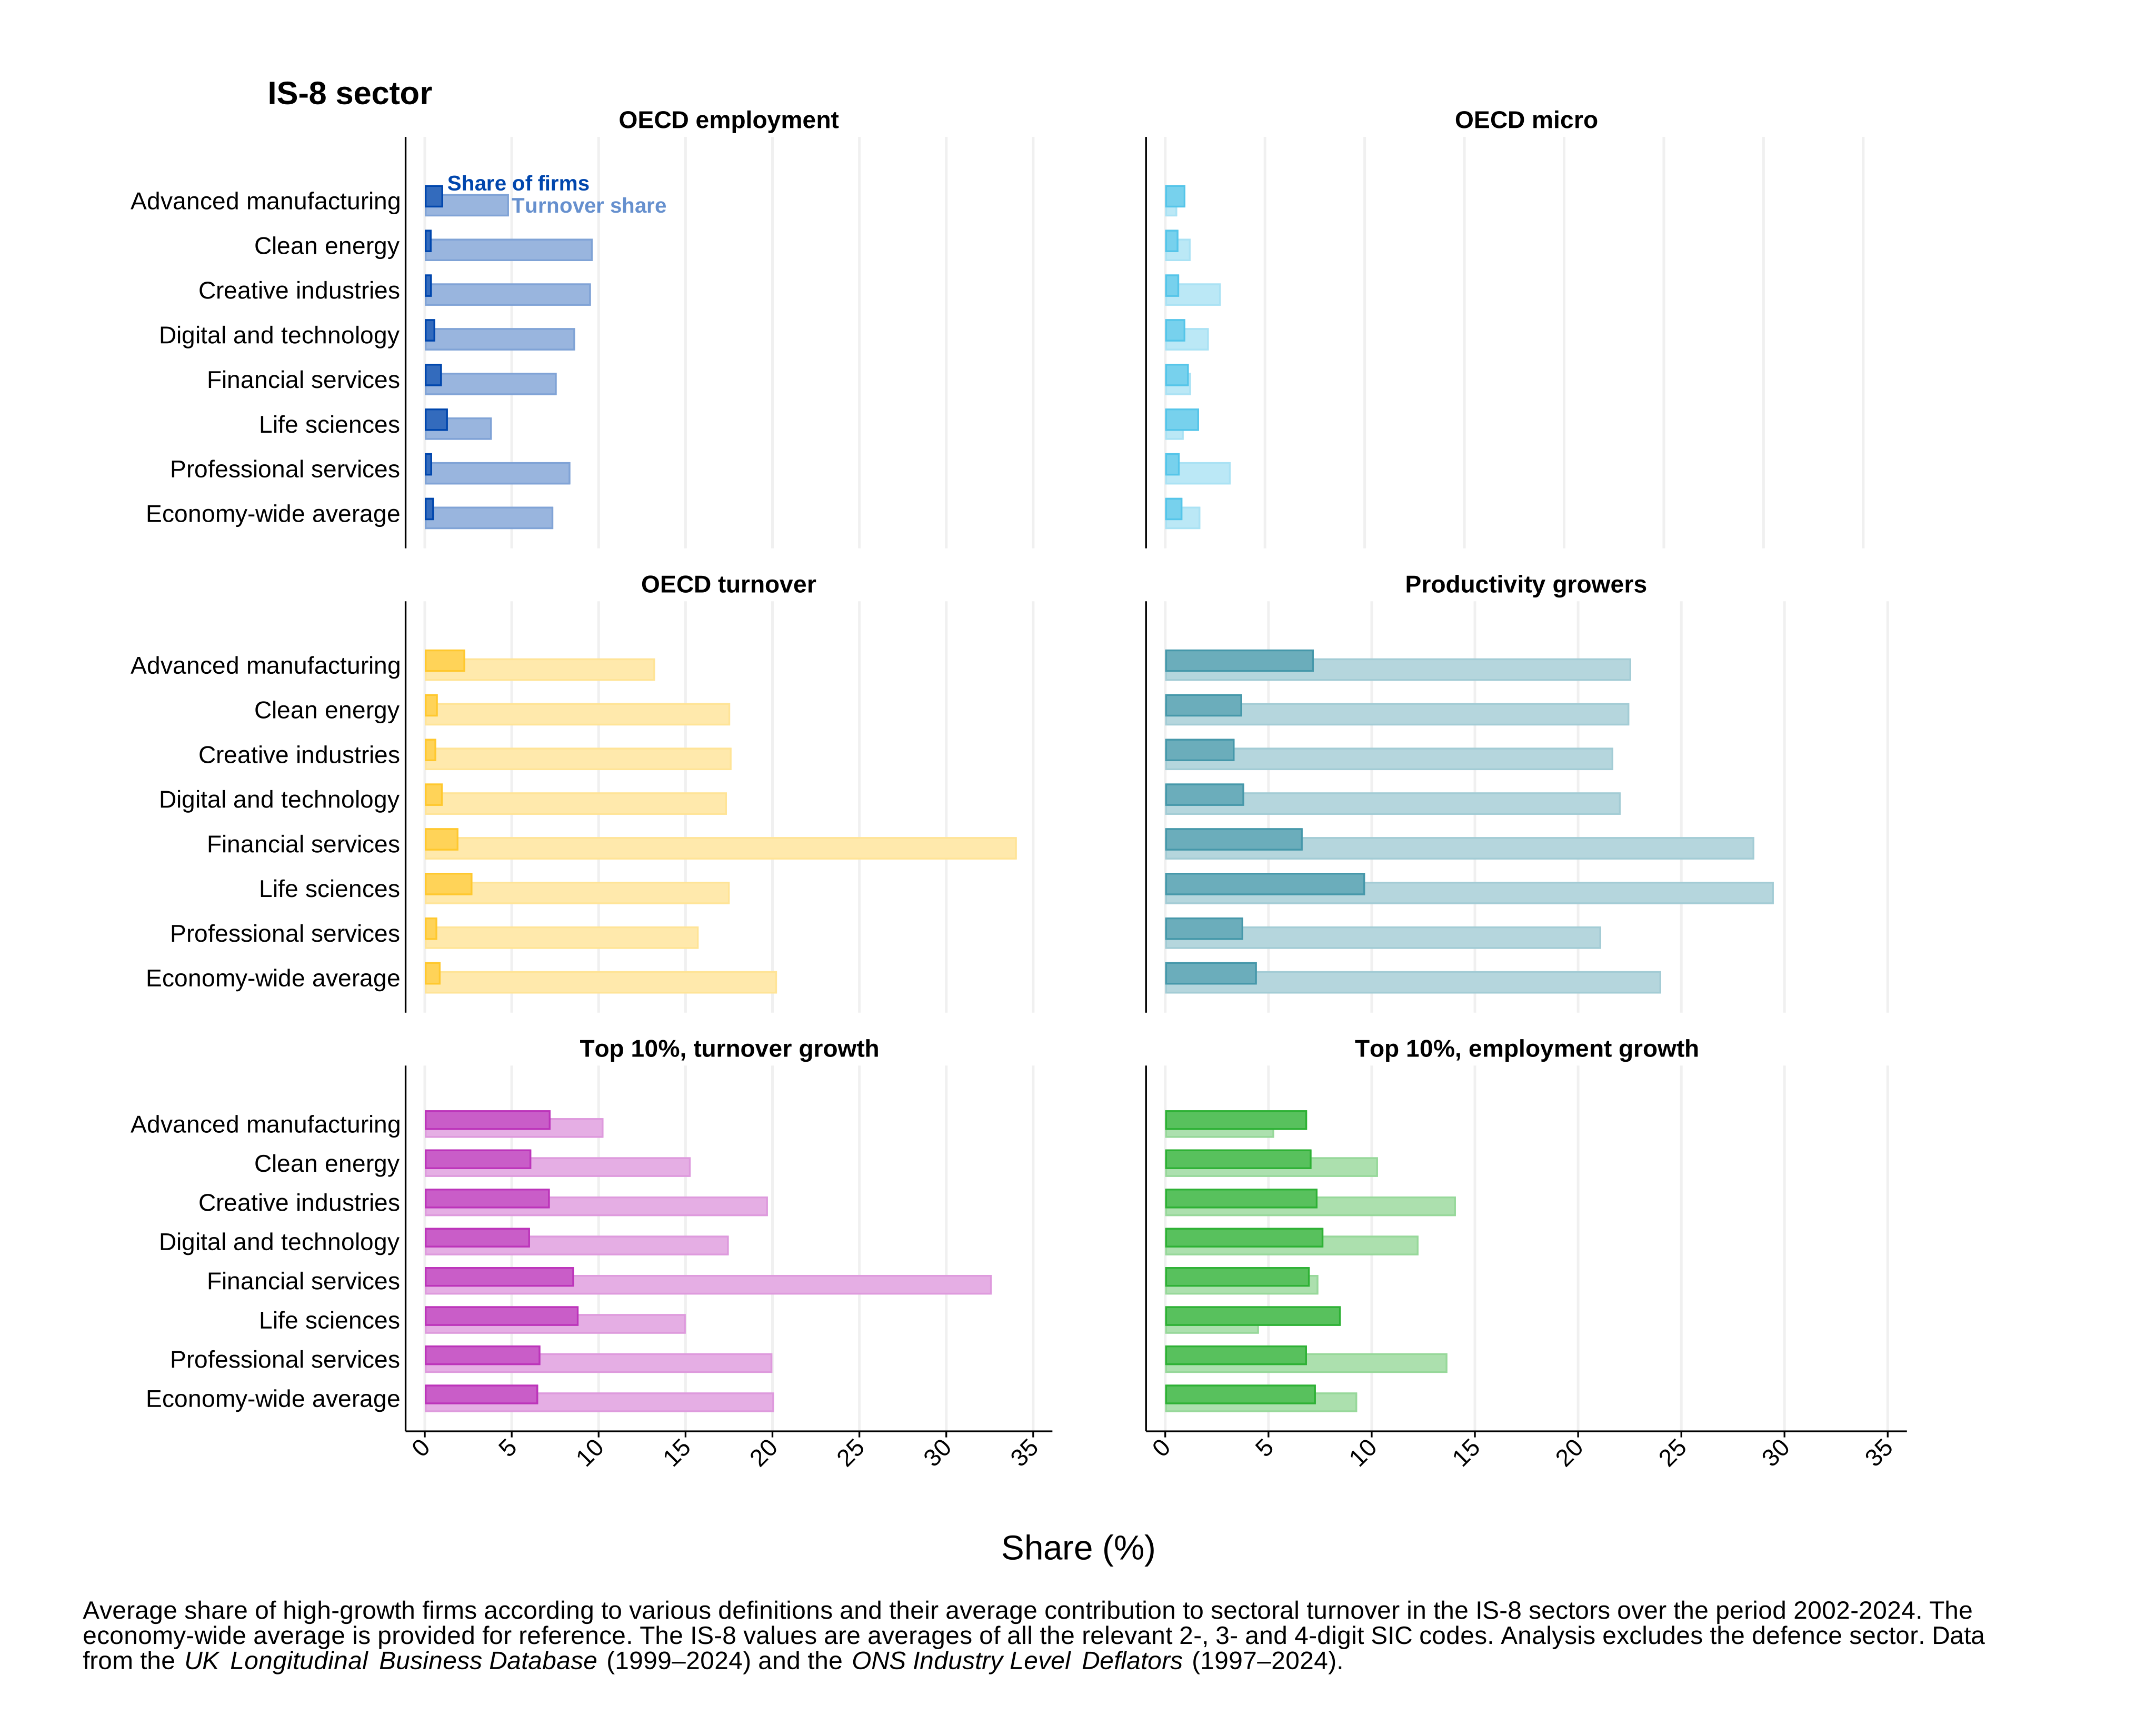
6-panel horizontal bar chart showing the share of firms and share of turnover accounted for by high-growth firms across Industrial Strategy growth-driving sectors. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% turnover growth and Top 10% employment growth definitions. Each sector is represented by two bars, one showing the share of firms and the other showing the share of turnover.
Figure A.6 - High-growth firms account for a more than proportional share of employment across different sectors
Share of firms and employment accounted by high-growth firms across Industrial Strategy growth-driving sectors (IS-8) for the baseline definitions of high-growth growth. Data from the Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
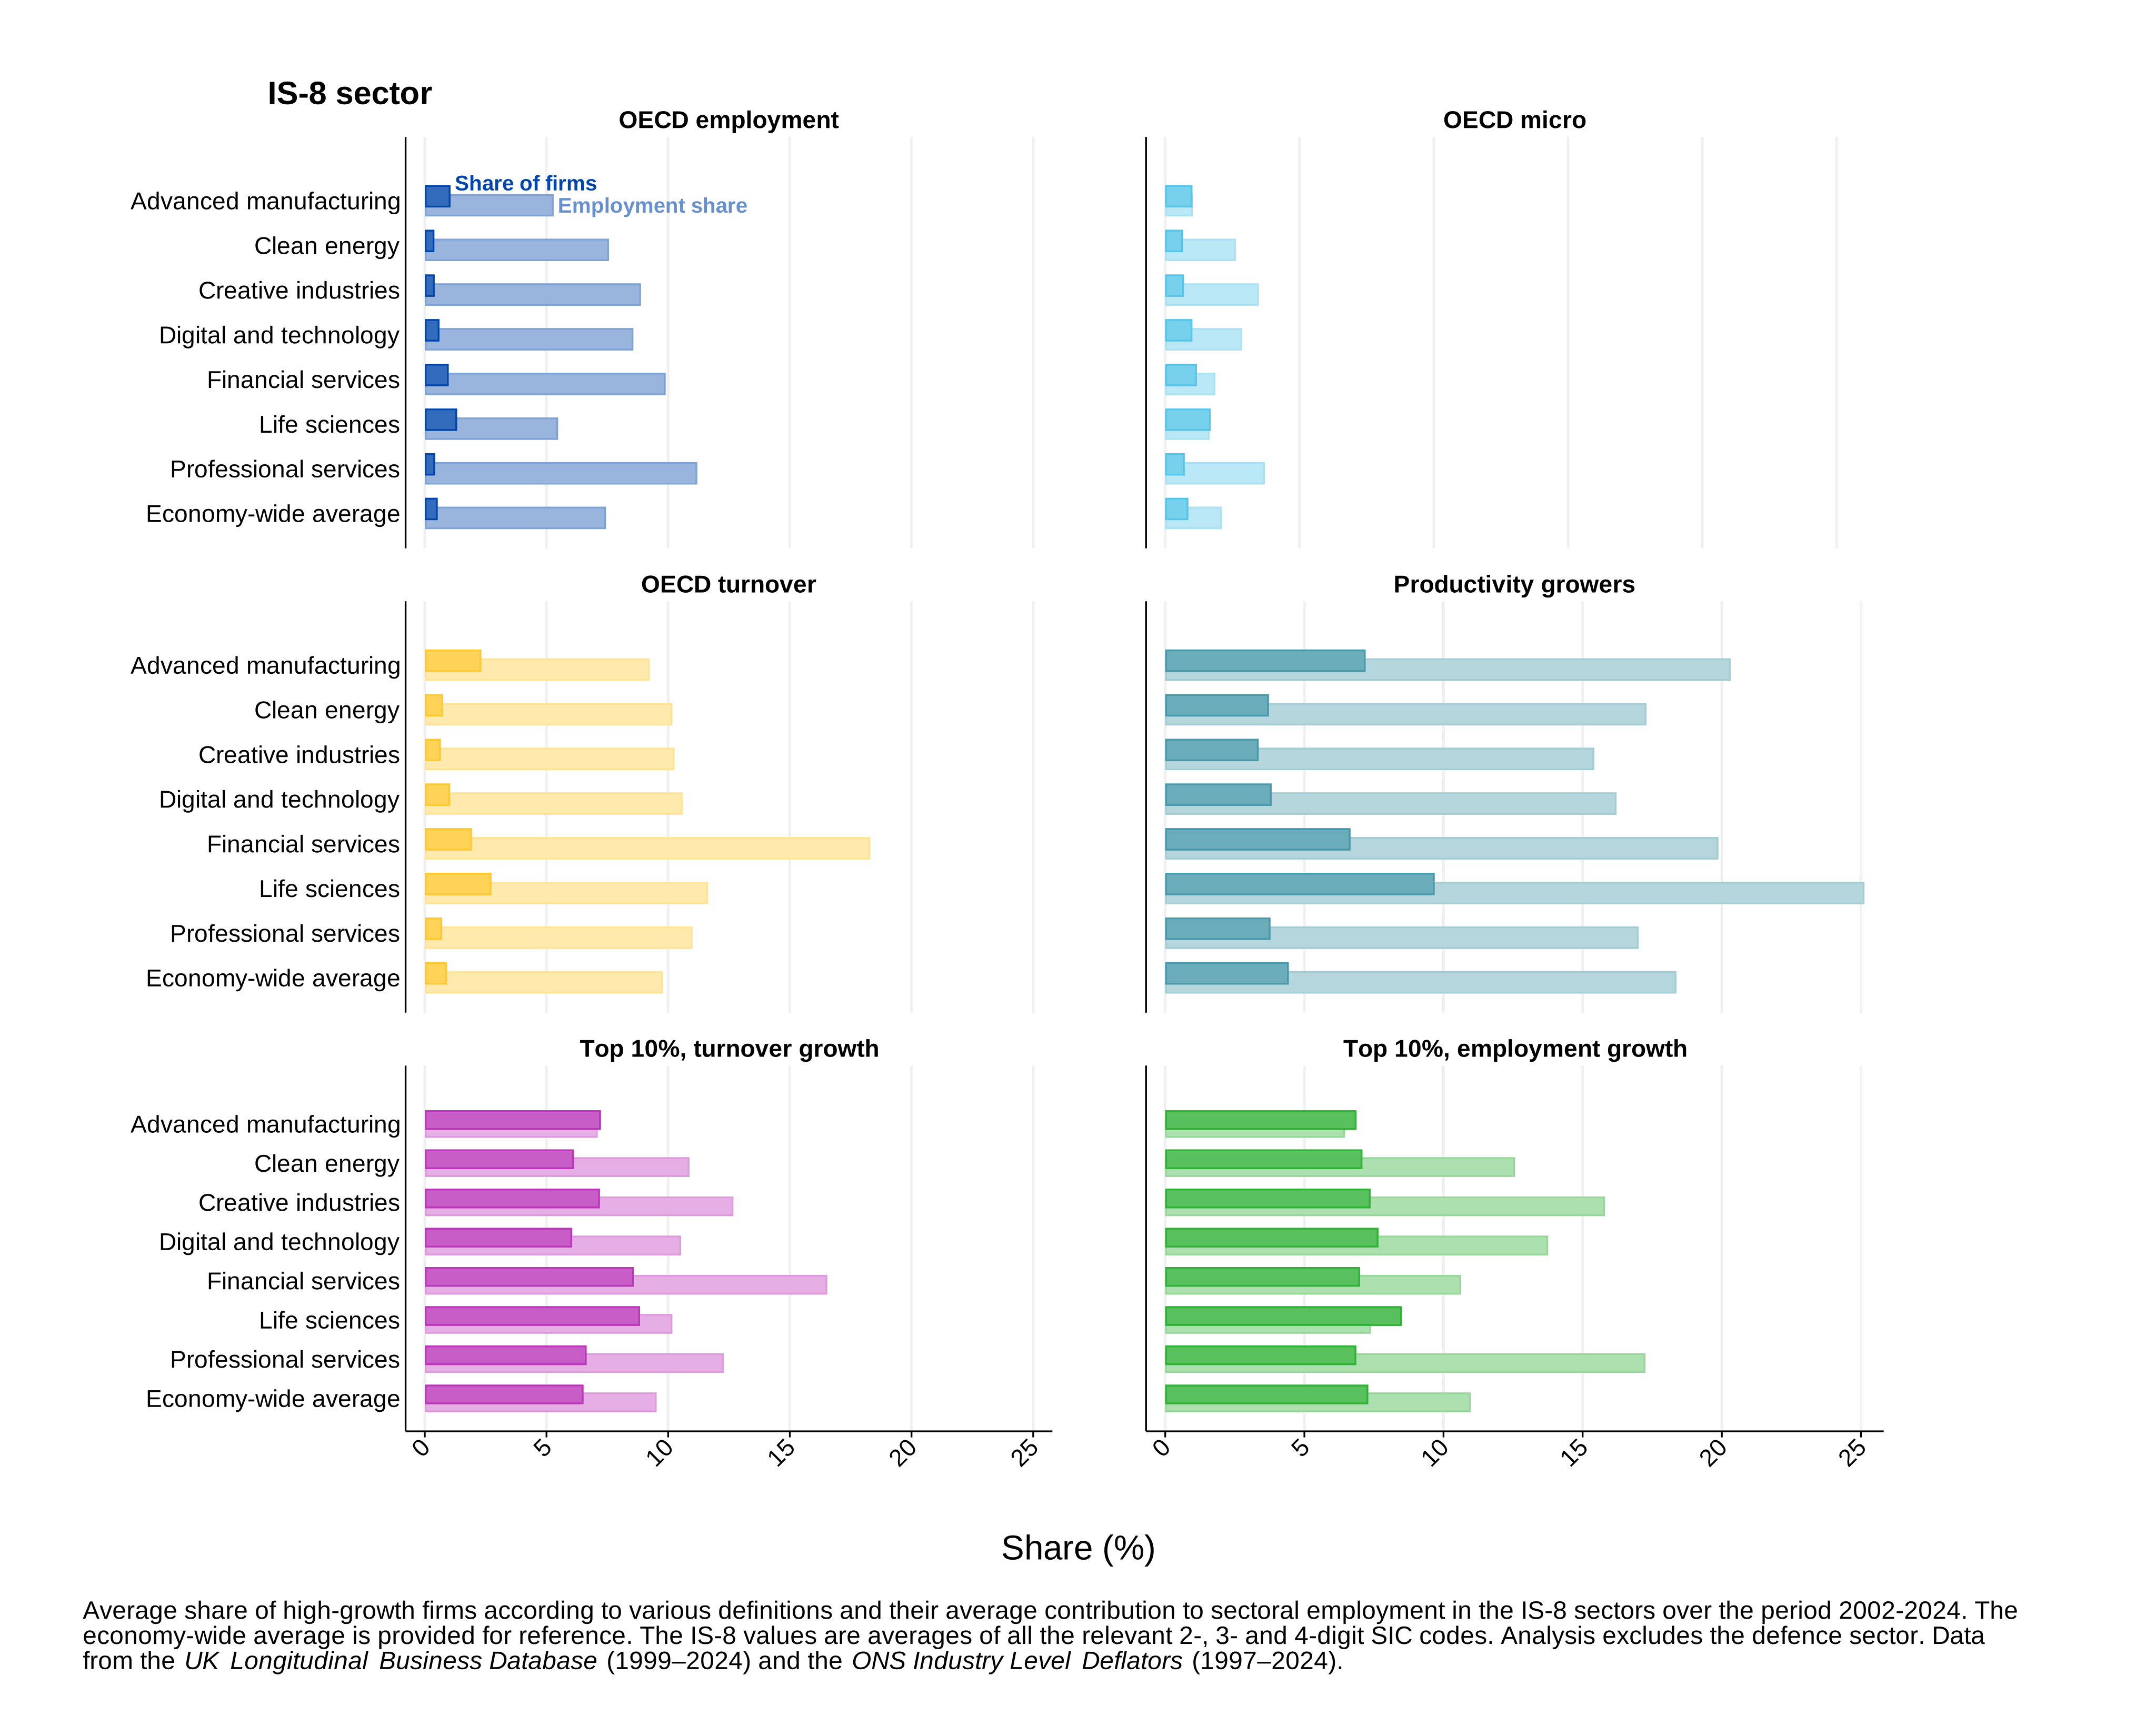
6-panel horizontal bar chart showing the share of firms and share of employment accounted for by high-growth firms across Industrial Strategy growth-driving sectors. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% turnover growth and Top 10% employment growth definitions. Each sector is represented by two bars, one showing the share of firms and the other showing the share of employment.
Figure A.7 – Growth premia for high-growth firms in different age bands, across different definitions
Average employment, turnover and productivity growth rate premia for high-growth firms relative to non-high-growth firms across age bands for the baseline definitions of high-growth firms. Point estimates are displayed together with 80, 90 and 95% confidence intervals. The analysis controls for year and industry (4-digit Standard Industrial Classification (SIC)) fixed effects. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
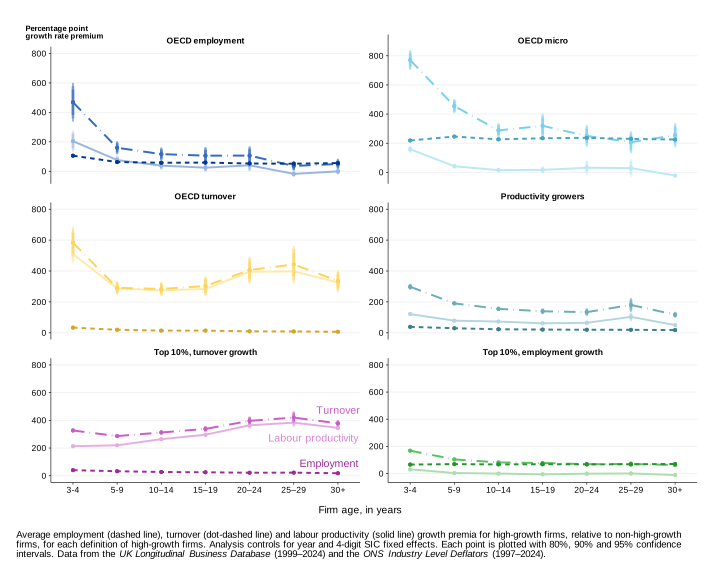
6-panel line chart showing employment, turnover and labour productivity growth premia for high-growth firms relative to non-high-growth firms across firm age bands. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% turnover growth and Top 10% employment growth definitions. Dashed, dot-dashed and solid lines represent employment, turnover and labour productivity growth premia respectively, and vertical lines show 80%, 90% and 95% confidence intervals.
Figure A.8 – The likelihood of becoming high-growth firm does not correlate with capital expenditure
The likelihood of becoming a high-growth firm, under alternative high-growth firm definitions, based on capital expenditure. Results from linear probability model (LPM) regressions with leads and lags, controlling for year, firm size (employment), firm age, and industry fixed effects (by 4-digit Standard Industrial Classification (SIC)). Point estimates are accompanied by 95% confidence intervals. Data from the UK Longitudinal Business Database (1999 to 2024), the ONS Annual Business Survey (2021 to 2022), the ONS Annual Respondents Database (1999 to 2020) and the ONS Industry Level Deflators (1997 to 2024).
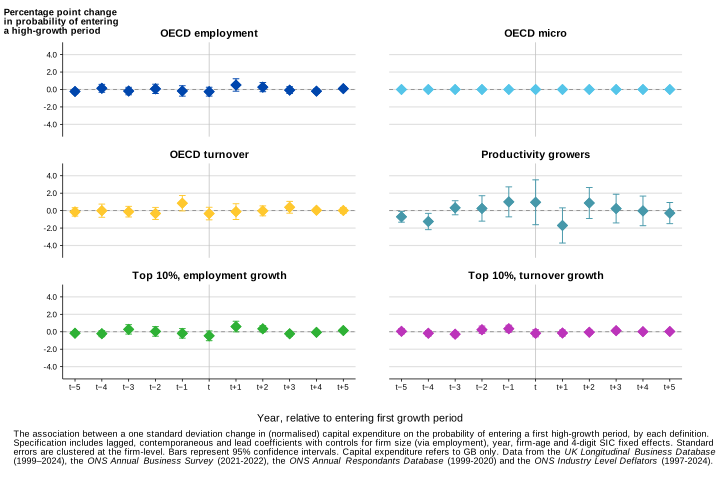
6-panel coefficient plot showing estimated associations between capital expenditure and the probability of becoming a high-growth firm under different high-growth definitions. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% employment growth and Top 10% turnover growth definitions. Points show coefficient estimates, and vertical lines show 95% confidence intervals.
Figure A.9 - The likelihood of becoming high-growth firm does not correlate with cost markups
The likelihood of becoming a high-growth firm, under alternative high-growth firm definitions, based on material markups. Results from linear probability model (LPM) regressions with leads and lags, controlling for year, firm size (employment), firm age, and industry fixed effects (by 4-digit Standard Industrial Classification (SIC)). Point estimates are accompanied by 95% confidence intervals. Data from the UK. Longitudinal Business Database (1999 to 2024), the ONS Annual Business Survey (2021 to 2022), the ONS Annual Respondents Database (1999 to 2020) and the ONS Industry Level Deflators (1997 to 2024).
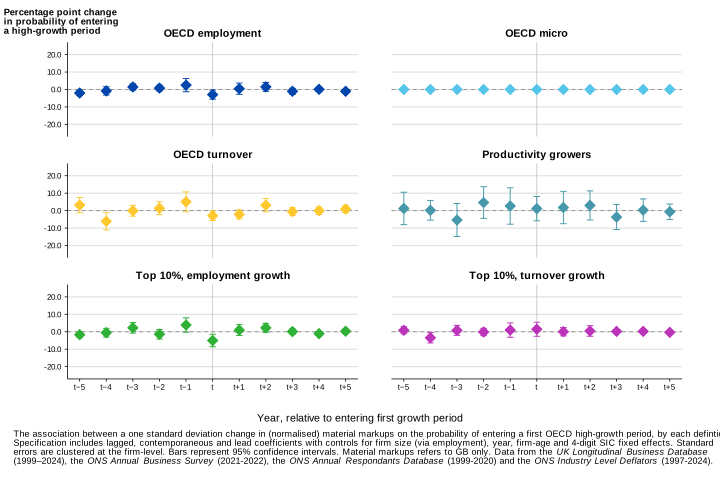
6-panel coefficient plot showing estimated associations between material markups and the probability of becoming a high-growth firm under different high-growth definitions. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% employment growth and Top 10% turnover growth definitions. Points show coefficient estimates, and vertical lines show 95% confidence intervals.
Figure A.10 - The likelihood of becoming high-growth firm does not correlate with the number of establishments
The likelihood of becoming a high-growth firm, under alternative high-growth firm definitions, based on number of establishments. Results from linear probability model (LPM) regressions with leads and lags, controlling for year, firm size (employment), firm age, and industry fixed effects (by 4-digit Standard Industrial Classification (SIC)). Point estimates are accompanied by 95% confidence intervals. Data from the UK Longitudinal Business Database (1999 to 2024) and the ONS Industry Level Deflators (1997 to 2024).
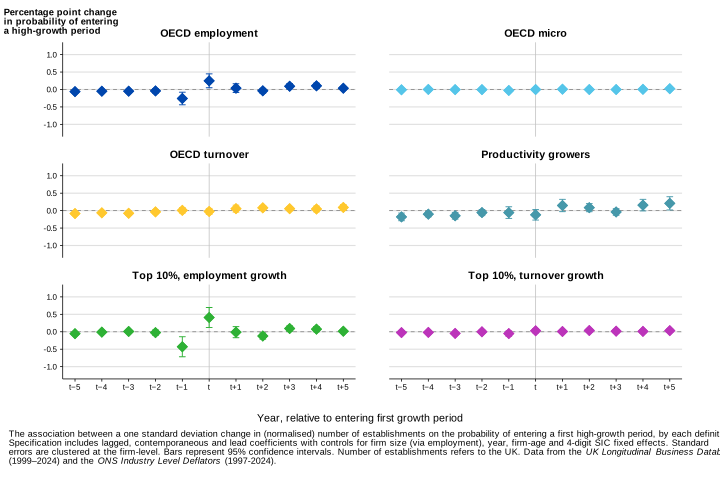
6-panel coefficient plot showing estimated associations between the number of establishments and the probability of becoming a high-growth firm under different high-growth definitions. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% employment growth and Top 10% turnover growth definitions. Points show coefficient estimates, and vertical lines show 95% confidence intervals.
Figure A.11 - The likelihood of becoming high-growth firm does not correlate with intellectual property expenditure
The likelihood of becoming a high-growth firm, under alternative high-growth firm definitions, based on intellectual property expenditure. Results from linear probability model (LPM) regressions with leads and lags, controlling for year, firm size (employment), firm age, and industry fixed effects (by 4-digit Standard Industrial Classification (SIC)). Point estimates are accompanied by 95% confidence intervals. Data from the UK Longitudinal Business Database (1999 to 2024), the ONS Annual Business Survey (2021 to 2022), the ONS Annual Respondents Database (1999 to 2020) and the ONS Industry Level Deflators (1997 to 2024).
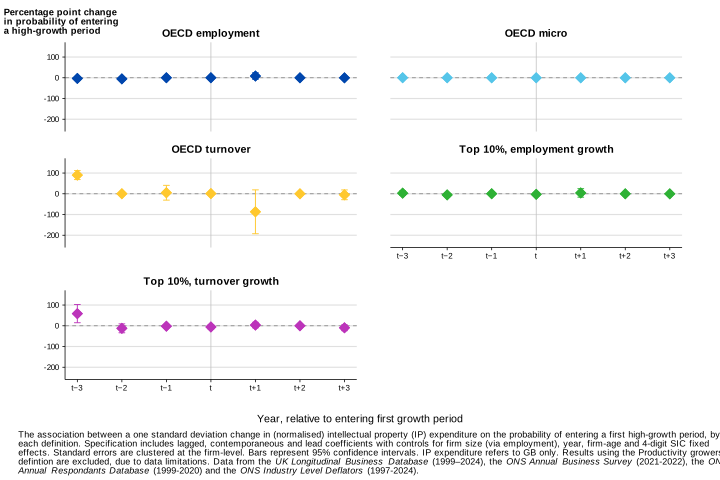
5-panel coefficient plot showing estimated associations between intellectual property expenditure and the probability of becoming a high-growth firm under different high-growth definitions. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Top 10% employment growth and Top 10% turnover growth definitions. Points show coefficient estimates, and vertical lines show 95% confidence intervals.
Figure A.12 – High-growth firms are on average better managed than non-high-growth firms
Results from linear probability model (LPM) regression, separately for each year relative to high-growth period. Shows the estimated association of management scores with the likelihood of a first growth episode occurring in a given year, with 80, 90 and 95% confidence intervals. Full fixed effects specification controls for year, firm size (by employment), firm age, and industry fixed effects (by 4-digit SIC). Data from the UK Longitudinal Business Database (1999 to 2024), the ONS Management and Expectations Survey (2016, 2020, 2023) and the ONS Industry Level Deflators (1997 to 2024).
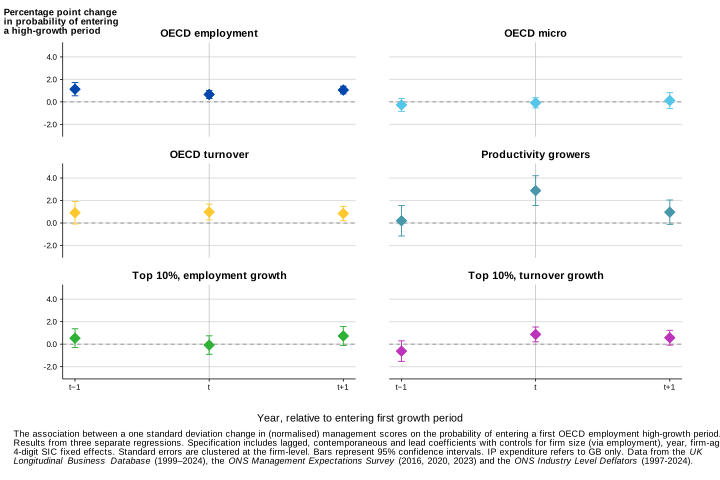
6-panel coefficient plot showing estimated associations between management scores and the probability of becoming a high-growth firm under different high-growth definitions. Separate panels are shown for OECD employment, OECD micro, OECD turnover, Productivity growers, Top 10% employment growth and Top 10% turnover growth definitions. Points show coefficient estimates, and vertical lines show 80%, 90% and 95% confidence intervals.
Figure A.13 - Signalling firms consistently create more jobs and destroy fewer jobs than expected given their employment share
Share of job creation and job destruction attributable to signalling firms, relative to their lagged employment share during 2020 to 2024. Data from Glass.AI-CMA growth signals (2020 to 2024).
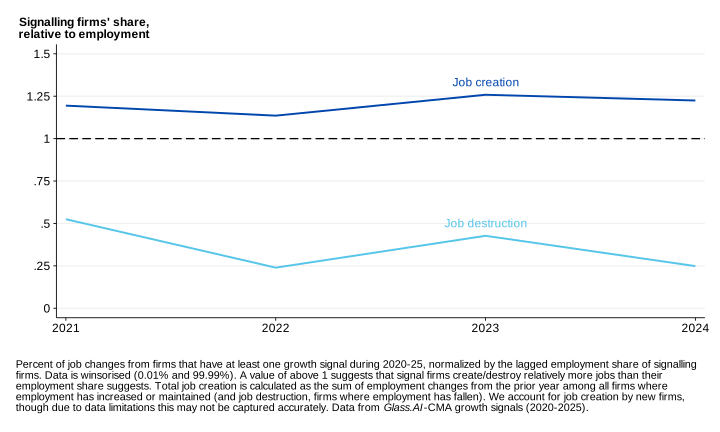
Line chart showing signalling firms’ share of job creation and job destruction relative to their employment share from 2021 to 2024. Separate lines show job creation and job destruction, and a dashed horizontal line marks a value of one.
Additional tables
Table A.1 – Full list of high-growth firm definitions
The table contains the full list of definitions considered in the report. The definitions in dark grey rows (rows 1 to 5) are those used as baseline in the analysis.
| Name | Description | Source |
|---|---|---|
| OECD employment | Annualised employment growth rate of 20% over a 3-year period for firms having at least 10 employees at the beginning of the period | OECD (2007) |
| OECD micro | Employment growth of at least 8 employees over a 3-year period for firms having less than 10 employees at the beginning of the period | Clayton et al. (2013) |
| OECD turnover | Annualised turnover growth rate of 20% over a 3-year period for firms having at least 10 employees at the beginning of the period | OECD (2007) |
| Top 10, employment growth | Firms in the top 10% of the cumulative (3-year period) employment growth rates distribution | Decker et al. (2015) and Haltiwanger et al. (2017) |
| Top 10, turnover growth | Firms in the top 10% of the cumulative (3-year period) turnover growth rates distribution | Decker et al. (2015) and Haltiwanger et al. (2017) |
| Productivity growers | Firms that increase labour productivity over a 3-year period and exhibit positive growth in both turnover (numerator) and employees (denominator) | Adapted from Du and Bonner (2016; 2017), Hart and Bonner (2024) |
| Eurostat employment | Annualised employment growth rate of 10% over a 3-year period for firms with at least 10 employees at the beginning of the period | OECD-Eurostat |
| Eurostat turnover | Annualised turnover growth rate of 10% over a 3-year period for firms with at least 10 employees at the beginning of the period | OECD-Eurostat |
| Annual employment growth 10% (20%) | Firms growing employment more than 10% (20%) over a one-year period and at least 10 employees at the beginning of the period | CMA-derived variant based on OECD approach |
| Annual turnover growth 10% (20%) | Firms with turnover growth of more than 10% (20%) over a one-year period and at least 10 employees at the beginning of the period | CMA-derived variant based on OECD approach |
| OECD turnover OR employment | Firms identified as either “OECD turnover” or “OECD employment” | CMA-derived variant based on OECD approach |
| OECD employment AND turnover | Firms identified as “OECD turnover” and “OECD employment” at the same time | CMA-derived variant based on OECD approach |
| Top 10 employment cumulative (5- and 10-year period) | Firms in the top 10% of the cumulative (5- or 10-year period) employment growth rates distribution | CMA-derived variant to other top 10 distribution definitions |
| Top 10 turnover cumulative (5- and 10-year period) | Firms in the top 10% of the cumulative (5- or 10-year period) turnover growth rates distribution | CMA-derived variant to other top 10 distribution definitions |
| Productivity superheroes | Firms that increase labour productivity over a 3-year period (as the productivity growers above) and have initial labour productivity above their industry average. | Adapted from Du and Bonner (2016; 2017) |
| Initial scaling firms | Firms reaching at least £1 million in turnover 3 years after their birth[footnote 40] | State of Small Business Britain (ERC, 2025) |
| Established scaling firms | Firms over 3 years old with a turnover of £1-2 million and scaling to at least £3 million over a 3-year period | State of Small Business Britain (ERC, 2025) |
Table A.2 - Average characteristics of high-growth firms versus other businesses
Mean values by high-growth status. High-growth firms are firms with turnover growth in the top 10% of the economy over a 3-year period, dated to the first year of the growth window. Experimental financial transactions data from the Bacs and Faster Payments System networks (2019 to 2025), produced in collaboration with the ONS, Vocalink and Pay.UK.
| Variable | High-growth firms | Other firms |
|---|---|---|
| Supply chain concentration and breadth | ||
| Upstream concentration (supplier HHI) | 3,647 | 4,675 |
| Downstream concentration (customer HHI) | 5,268 | 6,176 |
| Number of suppliers | 29.4 | 25.2 |
| Number of customers | 20.2 | 26.0 |
| Largest supplier share | 0.223 | 0.154 |
| Largest customer share | 0.182 | 0.147 |
| Partner dependence | ||
| Customer dependence on firm | 0.064 | 0.055 |
| Supplier dependence on firm | 0.074 | 0.054 |
| High-growth firm exposure | ||
| Upstream high-growth exposure | 0.051 | 0.026 |
| Downstream high-growth exposure | 0.061 | 0.043 |
| Number of high-growth suppliers | 0.7 | 0.4 |
| Number of high-growth customers | 0.7 | 0.6 |
| Revenue composition | ||
| Central government share | 0.073 | 0.074 |
| Central government turnover (GBP millions) | 0.076 | 0.073 |
| Financial sector ratio (excl. insurance) | 0.578 | 0.640 |
| Financial sector inflows, excl. insurance (GBP millions) | 0.100 | 0.063 |
| Demand stability | ||
| Turnover volatility (CV) | 0.974 | 1.289 |
-
Turnover values in this report are deflated using the domestic output industry deflators provided by the ONS. The reference year is 2023. ↩
-
Du and Bonner (2016; 2017) originally identified what they termed ‘growth heroes’ - firms increasing both turnover and employment with concurrent productivity gains over a 3-year period. We adopt their conceptual framework but modify the implementation by using annualised growth rates rather than cumulative growth to ensure consistency with OECD high-growth firm definitions. We also adjust the terminology to ‘productivity growers’ to avoid misrepresenting the precise definitions. ↩
-
The definitions based on the top 10% of employment growth and top 10% of turnover growth are distribution-based, meaning the threshold required to meet them varies from year to year. In 2024, this threshold was slightly above the 20% annualised average growth rate used in the OECD employment and OECD turnover definitions. As a result, some businesses that meet the OECD definitions do not fall within the percentile-based category. ↩
-
Previously, turnover for small firms not captured by the ABS was often based on outdated estimates provided at VAT registration and rarely updated. However, from 2015-2016, the Office for National Statistics (ONS) began systematically integrating current VAT return data from HMRC into the IDBR (ONS, 2015 and ONS, 2018 among others). This update replaced old, underestimated figures with more accurate and timely values for thousands of small businesses, resulting in a step-change in measured turnover and it happened over a prolonged period. Industry inclusion was staggered until 2019 at least, and quite likely there were some additional later updates happening as more firms showed up in the VAT data. ↩
-
Labour productivity is measured as turnover per employee. The labour productivity differential is defined as the difference between the average labour productivity growth rates of high-growth and non-high-growth firms. ↩
-
The IS-8 are Advanced manufacturing, Clean energy industries, Creative industries, Defence, Digital and technologies, Financial services, Life sciences, and Professional and business services. See the Industrial Strategy Sector Definitions List for the sector definitions. Our data does not allow us to carry out this analysis for the Defence sector. ↩
-
There are 2 competing forces which make it more and less likely for firms to be OECD employment high-growth firms as they age. On the one hand, older firms can more easily meet the 10-employee threshold and therefore be eligible for the OECD employment definition. On the other hand, if they are getting larger, it is also more difficult for them to grow their employment base as fast in percentage terms, because it requires a large absolute increase. These 2 effects offset each other, so the share of high-growth firms is stable across the age distribution. ↩
-
The likely presence of a disproportionate amount of small high-growth firms aged 3-4 years might partially explain this result – as small high-growth firms tend to have higher growth rates than larger high-growth firms. ↩
-
Here life means the observed presence of the businesses in our dataset. This limits the analysis in 2 ways. First, we only have data since 1999 even for businesses born before the establishment of the Business Registry. Secondly, the analysis includes active businesses for which, by definition, we do not observe future life. ↩
-
As discussed at the beginning of the Chapter, when introducing the different definitions, to qualify as an OECD micro, a firm must have less than 10 employees at the beginning of the growth period. However, but there is no constraint on how many employees these firms have after completing the growth period. ↩
-
Evidence from the ScaleUp Institute (2025) shows that 36% of scaleup companies report they are in National Government Supply Chains, 39% in Local Government Supply Chains and 36% in Large Corporate Supply Chains. ↩
-
Pay.UK and Vocalink are the operators and infrastructure providers to the UK’s retail interbank payment systems, including Bacs Payment System (Bacs) and Faster Payment System (FPS). Using this payments data, the ONS explored flows between industries and regions (ONS, 2026). The CMA made use of this data in its report on the relationship between supply chains and market power (CMA, 2026). ↩
-
This data covers the pandemic, including the likely substantial effects on business relationships. Our empirical specifications account for unobserved effects over time, which accounts for any pandemic effect that hits all firms equally. Furthermore, we are interested in the average differences between the fastest-growing firms and the rest of the business population, but not how this has evolved over calendar years. ↩
-
There are many reasons a company might receive a payment that would not typically count as turnover. For example, there may be companies within a corporate group who send payments among themselves. This might not be counted as turnover in traditional microdata but would be counted in this turnover proxy. In this project, we could not feasibly categorise the purpose of every payment. We excluded flows from financial and insurance companies to reduce noise. However, this is imperfect. Our turnover measure should be considered a proxy rather than an exact measurement. ↩
-
See OECD-Eurostat and OECD (2007) ↩
-
One consequence of this definition is that the average high-growth firm experiences a slight dip in turnover before their high-growth period. Since we are looking at the top 10% of the growth rates across the economy and nothing else, we are capturing some mean reversion. ↩
-
The sum of the squares of the share of flows to or from each supplier or customer of the firm. A higher HHI indicates a more concentrated supplier or customer base. HHIs range between 0 and 10,000. If a firm has one supplier, then HHI=100^2=10,000 and has highly concentrated inputs. If they have infinitely many small suppliers, then they would have an upstream HHI close to 0. ↩
-
One characterisation consistent with these patterns would be a high-growth firm with one particularly large customer and a handful of medium sized ones, compared to another firm from the rest of the business population with a few fairly large customers and a longer tail of smaller ones. ↩
-
The regressions look at the relationship between each characteristic in t-1 with the probability of beginning a 3-year growth period spanning period t through t+2. All subsequent regressions predicting high-growth firm status follow this format. ↩
-
In contrast, when looking at young firms specifically, a wider and less concentrated base of suppliers and customers is positively associated with the likelihood of becoming high growth at any future point ↩
-
We match accounts to a list of all central government departments in the data pipeline. Flows from these accounts are grouped together to calculate what share of our turnover proxy comes from central government. ↩
-
The structure of this data means we are unlikely to reliably capture some payments from government. ↩
-
That is, firms who begin a 3 year high-growth period the following year. These firms meet the top 10% 3-year turnover definition in year t+2. Our predictive regressions use this pattern in what follows. ↩
-
The financial sector is defined here as any company in the Financial and insurance activities (Standard Industry Classification (SIC) section K). This includes banks, building societies and investment funds. ↩
-
The coefficient of variation is a measure of volatility, calculated as the ratio of the standard deviation to the mean. It describes the spread of a variable relative to its average value. It is a ratio, which allows for straightforward comparison across groups where the means differ. A lower value implies less variability. This is not a perfect measure of demand predictability since some firms may have predictable monthly spikes in demand, for instance at Christmas many firms experience a boost in sales. Such increases will increase our measure of demand volatility but may not always reflect a genuine increase in uncertainty. ↩
-
Consistent with academic evidence (Segarra and Teruel, 2014; Demir et al., 2017; Santoleri, 2020; Ando, 2026), the ScaleUp Institute (2020, 2023) has identified several of these growth-related activities (undertaking innovation, securing equity finance, and expanding talent) to be common among scaling firms. ↩
-
The Office for National Statistics (ONS) is incorporating alternative data sources, including web-scraped prices, into UK consumer price statistics (ONS 2020; 2026) ↩
-
The analysis uses employment values throughout as it is more consistently reported than turnover in Companies House data, and employment growth is a standard measure in the high-growth firms’ literature. ↩
-
According to business population estimates, the number of private sector businesses in the United Kingdom (UK) at the start of 2025 was 5.7 million. Business population estimates for the UK and regions 2025: statistical release - GOV.UK ↩
-
Based on Glass.AI’s own analysis, approximately 228,000 active businesses in the UK disclosed turnover in their Companies House filings as of late 2025, around 5% of all active companies on the register. Comparable studies using Companies House data report similar coverage; for example, De Loecker, Obermeier and Van Reenen (2022) report revenue data for around 8% of UK companies in 2016. ↩
-
As Companies House data is annual, signalling events are aggregated to firm-year observations, which record the number of signals issued by a firm in a given year. However, this may introduce temporal mismatches between observed growth signals and measured firm growth. ↩
-
This is distributed across 48,000 firm-year observations. ↩
-
Linear probability is used despite a binary outcome variable (signal or no signal) to allow for multiple fixed effects, such as sector. The results are robust to using a logit specification instead. ↩
-
Industrial Strategy growth-driving sectors (IS-8) sectors are identified in the UK’s Modern Industrial Strategy; the UK Government’s 10-year plan to increase business investment and grow the industries of the future. They are: Advanced manufacturing, Clean energy industries, Creative industries, Defence, Digital and technologies, Financial services, Life sciences, and Professional and business services. For detailed information on specific Standard Industrial Classification (SIC) codes and sub-industry mappings of these sectors, see the Industrial Strategy Sector Definitions List. ↩
-
As discussed, the analysis in this chapter focuses on employment rather than turnover due to the better coverage we get in the dataset. ↩
-
Discussed in paragraphs on average, high-growth firms have different supply chain structures, descriptive comparisons, looking at descriptive comparisons, and descriptive comparisons. ↩
-
Discussed in structure of supply chains, descriptive panel regressions, regressions testing predictive associations, and descriptive regressions examining predictive associations ↩
-
Discussed in the networks of young firms are predictive of whether they later become high-growth firms ↩
-
Discussed in paragraphs firms’ supply chain characteristics change as they enter a period of high growth, government revenue shares are highest before high-growth episodes, paragraph about figure 26 and summary of figure 27. ↩
-
In the analysis the birth year of a firm is the one in which the firms first appear in the dataset. For firms in the Longitudinal Business Dataset since 1999 (first year of availability of the dataset) we use the year of birth of the parent enterprise. ↩