Safeguarding Stability, Enabling Growth: Consultation on Ring-fencing reform
Published 14 July 2026

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/consultations/safeguarding-stability-enabling-growth-consultation-on-ring-fencing-reform/safeguarding-stability-enabling-growth-consultation-on-ring-fencing-reform
How to respond to this consultation
The purpose of publishing this consultation document is to enable any interested parties or stakeholders to make representations on the government’s proposed approach to reforming the ring-fencing regime via changes to secondary legislation. This consultation is published on HM Treasury’s website and will be open for 8 weeks.
Responses are invited by 11:59pm on Tuesday 8 September 2026 and should be sent to ringfencing_review@hmtreasury.gov.uk. Responses may be shared with the Bank of England (the Bank), Prudential Regulation Authority (PRA), and Financial Conduct Authority (FCA). Further information about responding to this consultation and the way in which personal data will be processed can be found in Chapter 6.
1. Introduction
Background
At Mansion House 2025, as part of the Financial Services Growth and Competitiveness Strategy, the Chancellor confirmed her intention to uphold the ring-fencing regime to protect depositors and financial stability while taking forward meaningful reform to support the government’s growth agenda.
HM Treasury, working in close collaboration with the Bank of England and PRA, subsequently undertook a Review of the regime. The outcomes of the Review were published in Safeguarding Stability, Enabling Growth on May 18, 2026. The review set out the government’s intention to take forward a package of proposals in primary legislation (as part of the ongoing Financial Services and Markets Bill), secondary legislation and the PRA rulebook.
Through this document, the government is now consulting on the technical details of implementing the aspects of the package that will be delivered via secondary legislation. These relate to the New Growth Allowance, expanding the range of products RFBs are permitted to offer, expanding the range of counterparties RFBs are permitted to have exposures to and the management of pension schemes.
In parallel, the PRA has today published a consultation paper confirming its intention to consult on deleting rules 9.1, 9.2 and 9.3 of the Ring-fenced Bodies Part of the PRA Rulebook, fulfilling its commitment to provide firms with further flexibility on the provision of shared services.
The government will consider respondents’ feedback to this consultation, following which it will publish a draft Statutory Instrument. The final Statutory Instrument will be laid in 2027 following approval by Parliament of the Financial Services and Markets Bill, and subject to parliamentary time.
2. Summary of Proposals
| Issue | Proposal |
|---|---|
| A. The New Growth Allowance | |
| A.1 Size and operation of the allowance | The allowance will be 10% of an RFB’s Pillar 1 risk-weighted assets (RWAs) for credit risk (including counterparty credit risk). RWAs generated by credit risk, market risk, settlement risk and credit valuation adjustment risk exposures will count towards the allowance. |
| A.2 Measuring the allowance | The allowance will be measured using quarterly data averaged over a 36-month period, calculated using the same methodology (IRB or standardised approach) as used for calculating the bank’s capital requirements. The allowance will be applied at the RFB sub-consolidated group level. |
| A.3 Approach to other allowances | The allowance will incorporate existing SME exemptions and the Relevant Financial Institution de minimis. |
| A.4 Disclosures | RFBs using the allowance will be required to disclose how it is being used to support the UK economy. |
| B. Expanding Permitted Products | |
| B.1 Permitted Products | The ring-fencing legislation on permitted derivatives will be brought into line with Basel 3.1 and permit RFBs to offer customers a wider suite of derivative products which are not in scope of the market risk Relevant Risk Add-On (RRAO) as defined in the PRA Rulebook. |
| C. Prohibited Counterparties | |
| C.1 Relevant Financial Institutions | RFBs will be able to hold exposures to Undertakings for Collective Investment in Transferable Securities. |
| C.2 Structured Finance Vehicles for Small and Medium Sized Enterprise lending | RFBs will be permitted to hold exposures to Structured Finance Vehicles set up for the purpose of securitising SME loans. |
| C.3 Special Purpose Vehicles for Infrastructure Projects | RFBs will be permitted to hold exposures to Special Purpose Vehicles investing in a wider range of infrastructure projects. |
| C.4 Public Financial Institutions | RFBs will be permitted to hold exposures to financing vehicles which are i) managed/advised by UK Public Financial Institutions, ii) debt funds with UK Public Financial Institution Equity Stakes, iii) Community Development Finance Institutions, iv) guaranteed by a UK Public Financial Institution |
| D. Pensions | |
| D.1 Pensions | RFB defined benefit pension schemes will be able to transfer a surplus to other schemes within the wider banking group, subject to conditions. |
3. Policy Position and Proposed Changes
A. The New Growth Allowance
Background
In its 18 May announcement, the government committed to introducing a New Growth Allowance (the allowance), permitting firms to undertake activities otherwise prohibited by the regime up to a limit of 10% of Pillar 1 credit risk RWAs, in order to support financing for the real economy.
Currently, ring-fencing does not prevent RFBs from providing loans to SMEs or infrastructure projects, but it does prevent them from offering certain products or serving certain institutional clients. This means that as businesses grow and require more sophisticated products, they must either transfer to the non-ring-fenced body (NRFB) or find a new bank or non-bank provider. This places additional costs and uncertainty on fast-growing businesses, while preventing our largest banks from supporting them through their lifecycle.
These regulatory frictions can impact the cost of financing faced by UK businesses. Research shows that within ring-fenced banks, retail deposit funding was around 70 basis points cheaper than wholesale funding between 2010-2019. Further evidence shared with HMT as part of the review suggested the gap between wholesale and retail funding costs could in practice be considerably wider.
This consultation seeks feedback on the proposed scope, measurement and size of the allowance.
A.1. Size and operation of the allowance
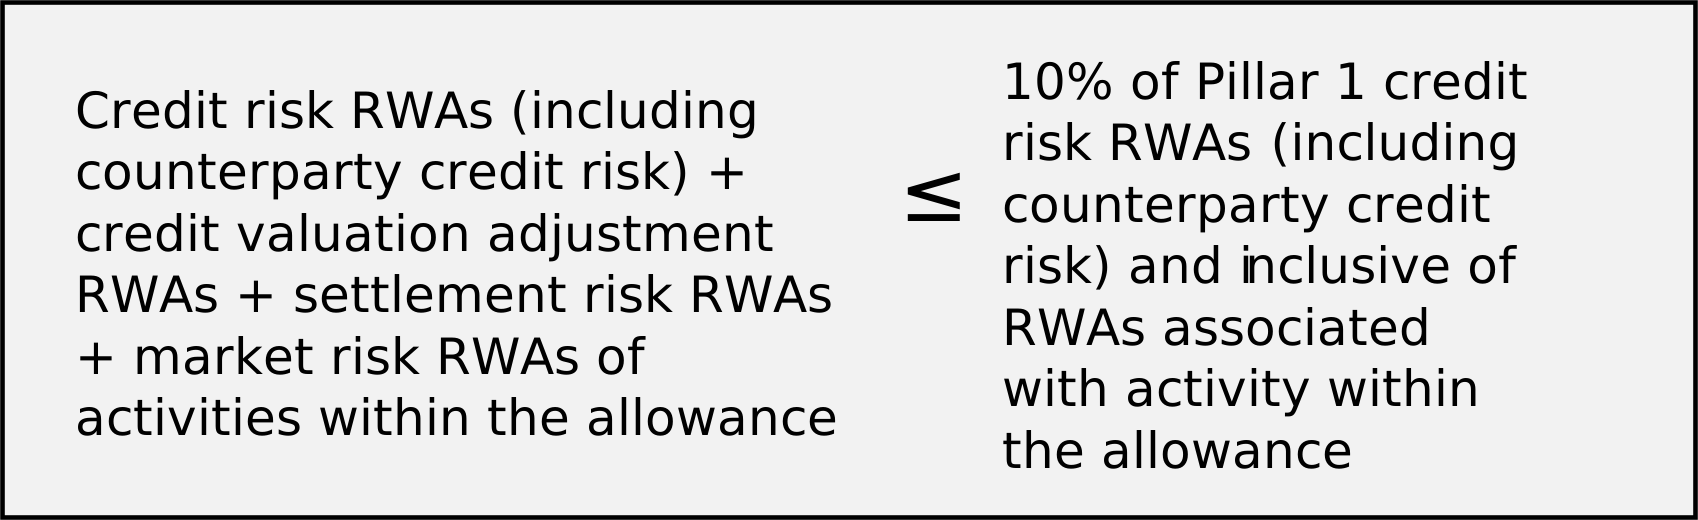
Proposal A1 – The allowance will be 10% of an RFB’s Pillar 1 risk-weighted assets (RWAs) for credit risk (including counterparty credit risk). RWAs generated by credit risk, market risk, settlement risk and credit valuation adjustment risk exposures will count towards the allowance.
In line with the review announcement, the government will set the growth allowance at 10% of RFB’s Pillar 1 RWAs for credit risk. For the avoidance of doubt, this calculation will include RWAs generated by activities undertaken within the allowance itself.
The government proposes that, where an RFB offers a product or service through the allowance, the RWAs from the associated credit risk (including counterparty credit risk), credit valuation adjustment, settlement risk and market risk should count towards the allowance. This will ensure that activities undertaken through the allowance are measured by reference to their overall risk profile. Operational risk is excluded because it is calculated at firm level and cannot readily be attributed to a specific subset of exposures.
Fig.1: calculating the size and operation of the allowance:
Alongside consulting on the size and operation of the allowance, the government is also seeking feedback on whether the existing caps on market risk will need to be amended to ensure that RFBs can use the allowance as intended. These caps currently require that:
- The net market risk must be less than 0.5% of an RFB’s own funds for transactions entered with customers, and those which are for the purpose of managing the RFB’s own risk in relation to those customer transactions.
- Total relevant risk requirements must be less than 25% of the RFB’s credit risk capital requirement for transactions entered for customers.
- Total relevant risk requirements arising from options and swaptions entered into with customers must be less than 20% of the total market risk of an RFB’s derivative activity.
Question 1
Do respondents agree with the proposal to include the RWAs generated by activity undertaken under the allowance within the 10% RWA calculation?
Question 2
Do respondents agree to the proposed approach to calculating the RWAs that count towards the allowance (i.e., counting all RWAs except operational risk)?
Question 3
Do respondents have views on whether the market risk caps will affect the ability of RFBs to use the allowance to support the real economy?
A.2. Measuring the allowance
Proposal A2 – The allowance will be measured using quarterly data averaged over a 36-month period, calculated on the same basis as the bank’s capital requirements. The allowance will be applied at the RFB sub-consolidated group level.
To ensure that this measurement can be adequately operationalised, the government proposes the following approach:
- Measuring the overall size of the allowance and the activities taken forward through it using quarterly data, averaged over a 36-month period. This will minimise the risk of the size of the allowance fluctuating significantly if a firm experiences short term changes in the size of its RWAs.
- Aligning how a bank’s allowance is calculated to the methodology used to calculate its capital requirements more broadly i.e. where a firm is using an internal ratings-based (IRB) approach to calibrate their Pillar 1 credit risk requirements, this will be used to calculate the size of their allowance.
- Applying the allowance at a sub-consolidated (RFB sub-group) rather than a solo/entity level to give banks maximum flexibility to make use of its allowance across the sub-group structure.
Question 4
Do respondents agree that the allowance and the activity undertaken within it should be calculated using an average quarterly measurement from the preceding 36-month period?
Question 5
Do respondents agree that RFBs should use the same methodology (IRB or standardised approach) for calculating the size of their allowance as they are using for calculating their capital requirements?
Question 6
Do respondents agree that the allowance should apply at the sub-consolidated level of the RFB group?
A.3. Approach to other allowances
Proposal A3 – The allowance will incorporate existing SME exemptions and the Relevant Financial Institution de minimis.
In the Review announcement the government set out its intention to incorporate existing flexibilities introduced as part of the Smarter Ring-Fencing Reforms in February 2025 into the allowance.
Exemptions for SME equity investments
Exemptions for SME equity investments allow RFBs to i) acquire and dispose of shares in UK SMEs in which an RFB holds a minority stake, ii) invest in SME investment funds investing at least 50% of its capital in UK SMEs and iii) acquire equity warrants in UK SME borrowers, up to a cap of 10% of a bank’s Tier 1 capital.
Industry feedback suggests that RFBs have made limited use of these exemptions and that very few funding structures meet the SME investment fund exemption criteria. Data submitted by RFBs to the PRA also suggests that all RFBs are within their 10% SME investment cap, which itself is significantly smaller than the allowance. Consolidating these exemptions within the allowance could therefore avoid introducing further complexity into the regime.
The Relevant Financial Institution de minimis
The Smarter Ring-Fencing Reforms also introduced a de minimis threshold for Relevant Financial Institutions (RFIs) of up to £100,000, to reduce the compliance burden for RFBs in relation to small breaches of the regime.
As the allowance will allow RFBs to hold exposures to RFIs beyond this exemption, the government also proposes to incorporate this threshold into the allowance.
Question 7
Do respondents agree with the proposal to incorporate the SME equity investment exemptions within the allowance?
Question 8
Do respondents agree with the proposal to incorporate the RFI de minimis within the allowance?
Question 9
Are there any other thresholds or exemptions within the regime that the government should consider absorbing within the allowance?
A.4. Disclosures
Proposal A4 – RFBs using the allowance will be required to disclose how it is being used to support the UK economy.
In its review, the government made clear its intention to require RFBs to disclose how they are using the allowance, including how it is supporting the real economy. In particular, these disclosures will seek to: - Ensure transparency in relation to the activities banks are undertaking within the allowance, and the types of customers they are supporting. - Ask banks to provide a breakdown of the use of the allowance by sector. - Set out the proportion of clients served by activity taken through the allowance who are headquartered in the UK.
Question 10
Do respondents agree with the proposal to require banks to disclose the activities and sectors supported by the allowance or have feedback on how disclosures should be operationalised?
A.5. Interactions with other aspects of the regime
The government is keen to ensure that the implementation of the allowance does not inadvertently affect the operation of other elements of the regime.
In particular, the government has considered whether the allowance would affect the calculation underpinning the secondary threshold (set out as the Trading Assets Condition in Article 13A of the Ring-Fenced Bodies and Core Activities Order), which exempts retail-focused banks with trading assets of less than 10% of tier 1 capital, except where they are part of a GSIB.
The government assesses that the secondary threshold will continue to operate as intended following the introduction of the New Growth Allowance. This is because the secondary threshold is measured in terms of financial assets held for trading, which should not be significantly impacted by the allowance. However, the government welcomes respondents’ views on this point, and on whether the operation of any other elements of the regime might be affected by the allowance.
Question 11
Do respondents agree that the introduction of the allowance would not create unintended consequences for the calculations of the secondary threshold?
Question 12
Are there any other elements of the regime whose operationalisation could be affected by the implementation of the allowance?
B. Expanding permitted products
Proposal B1 – Bring the ring-fencing legislation into line with the Basel 3.1 and permit RFBs to offer customers a wider suite of derivative products which are not in scope of the market risk RRAO as defined in the PRA Rulebook.
Background
Currently, RFBs are permitted to do ‘simple’ derivatives that can be fair valued through observable inputs (level 1 and level 2 inputs under IFRS 13). The list of permitted derivatives is set out in secondary legislation, which includes FX swaps, forwards and options interest rate swaps, FX and commodity swaptions, commodity forwards and options and inflation swaps, with tenors less than 3 to 5 years. The recent Review concluded that the list of permitted derivatives set out in the Excluded Activities and Prohibitions Order 2014 (EAPO) is too narrow.
Proposal
The Basel 3.1 Fundamental Review of the Trading Book has introduced changes to the market risk framework. These were implemented by the PRA through the Market Risk Part of the PRA Rulebook. One of the changes is to introduce a residual risk add-on (RRAO) which captures riskier and more exotic derivatives whose risk profiles cannot be approximated using standard risk sensitivities. The RRAO can therefore be used as a proxy for identifying complex derivatives instruments.
The government is therefore proposing to bring the ring-fencing legislation into line with the Basel approach and the prudential framework and permit RFBs to offer customers a wider suite of derivative products which are not in scope of the market risk RRAO as defined in the PRA Rulebook (which will come into force from 1 January 2027).
The government assesses that this approach will permit the removal of existing tenor restrictions on some of the options and swaptions, allowing ring-fenced banks the flexibility to offer clients derivative products with longer tenor.
In applying this approach, the government proposes that the requirement on ring-fenced banks to only use derivatives for customer offering and their own risk management purposes should remain.
The government is also consulting on the impact of retaining the following financial stability safeguards; i) the requirement that only derivatives ‘mark to market’ (International Financial Reporting Standards (IFRS) level 1 and 2 inputs) will be permitted, and ii) the policy that RFBs are not permitted to offer derivatives with cryptoassets as underlyings.
We also note the calibration of market risk capital requirements is changing under the PRA’s implementation of Basel 3.1. Given the changes in the advanced standardised approach under Basel 3.1, - the government is also considering whether the existing calibration of the market risk thresholds is appropriate. EAPO 12 (1) (b) and 12 (1) (c) set gross market risk thresholds, and EAPO 12 (1)(a) sets a net market risk threshold. The government invites industry comments on this, supported by quantitative evidence.
Question 13
Do respondents agree with the proposal to permit RFBs to offer a significantly wider range of simple derivative risk management products, using market risk residual risk add-on criteria and the existing safeguards?
Question 14
Do respondents have views on the impacts retaining the safeguards detailed in section 3.23, and if this could be detrimental to the RFBs ability to effectively support their customers?
Question 15
Do respondents have any comments (with quantitative evidence) on the calibration of the existing gross and net market risk thresholds?
C. Permitted Exposures
C.1. Relevant financial institutions
Proposal C1 – RFBs will be able to hold exposures to Undertakings for Collective Investment in Transferable Securities.
Background
Ring-fencing prohibits RFBs from having exposures to other financial institutions to avoid indirectly exposing themselves to financial markets in which RFBs themselves were not permitted to trade. As a result, ring-fencing legislation sets out a list of Relevant Financial Institutions in the EAPO preventing ring-fenced bodies from holding exposures to certain types of financial institution unless specific exemptions apply.
The Review found that the regime is preventing banks from holding exposures to firms which offer services that could already be performed by an RFB. As such, the intention has been to identify financial institutions whose activities or client base resemble that of the RFB (for instance, undertaking activity as agent or having a retail focus), with a view to allowing RFI exposures where that is the case.
Proposal
Following further analysis, the government is consulting on removing collective investment schemes that are authorised as UCITS funds from the list of RFIs. UCITS funds, like RFBs, market to retail rather than more sophisticated institutional clients and are subject to FCA regulations to ensure they do not take on excessive debt or engage in significant levels of proprietary trading. Removing restrictions on these funds will allow banks to provide more short-term lending facilities to these funds without introducing significant new risk to ring-fenced banks
The government considered the possibility of a broader carveout for financial institutions that deal only as agent. However, this appears impractical, as many financial institutions (including UCITS) will need to execute specific activities as ‘riskless’ principal, thereby breaching such a carveout despite overwhelmingly dealing on behalf of clients.
The government is also mindful that firms have consistently expressed a desire for the regime to be simpler to operate, and that an alternative approach of requiring firms to satisfy themselves of the activities undertaken by individual counterparties may be burdensome.
Question 16
Do respondents agree with the proposal to permit RFBs to hold exposures to Undertakings for Collective Investment in Transferable Securities funds?
Question 17
Do you agree with the government’s decision not to create a legislative carveout for firms that deal purely as agent?
Question 18
Are there any other financial institutions which in your view meet the criteria for removal from the list of prohibited counterparties set out in this consultation?
C.2. Structured Finance Vehicles for Small and Medium Sized Enterprise lending
Proposal C2 – RFBs will be permitted to hold exposures to Structured Finance Vehicles set up for the purpose of securitising SME loans.
The Review found that there has been a rise in the use of structured finance vehicles to support SME access to finance, complementing more traditional, direct lending to SMEs. The regime already currently exempts infrastructure Special Purpose Vehicles (SPVs) from prohibited counterparty rules and exempts a broader range of securitisation undertakings and structured finance vehicles where these have been set up by the ring-fenced body.
Encouraging lending to SME and scale-up firms is a government priority and the government proposes to create a parallel exemption for vehicles which are set up for the purpose of securitising SME loans, where the originator or the structure itself would otherwise be considered an RFI. This would be defined as Structured Finance Vehicles in which at least 50% of the portfolio is in UK SMEs.
Question 19
Do respondents agree with the proposal to permit RFBs to hold exposures to Structured Finance Vehicles set up for the purposes of securitising SME loans?
C.3. Special Purpose Vehicles for Infrastructure projects
Proposal C3 – RFBs will be permitted to hold exposures to Special Purpose Vehicles investing in a wider range of infrastructure projects.
The ring-fencing regime exempts infrastructure SPVs from RFI rules, recognising the importance of these structures in infrastructure financing chains. In its current form, Article 19A of the EAPO sets out the following definition of infrastructure:
- housing,
- water, electricity, gas, telecommunications, sewerage or other services,
- railway facilities (including rolling stock), roads or other transport facilities,
- health or educational facilities,
- court or prison facilities.
The government is conscious that this list is not exhaustive and is seeking respondents’ views on if it should be amended to allow wider RFB investment.
Question 20
Do respondents agree with the proposal to broaden the definition of infrastructure and if so, what should be captured?
C.4. Public Financial Institutions
Proposal C4 – RFBs will be permitted to hold exposures to financing vehicles which are i) managed/Advised by UK Public Financial Institutions (PuFins), ii) debt funds with UK PuFin Equity Stakes, iii) Community Development Finance Institutions (CDFIs), iv) guaranteed by a PuFin.
Background
The Review noted that current ring-fencing rules prohibit RFBs from holding exposures to various funds, specialised structures, and entities (‘financing vehicles’) which are supported by the UK’s Public Financial Institutions (PuFins) - despite RFBs already lending directly to many of the underlying assets supported by PuFin access-to-finance programmes.
Such programmes are crucial to closing financing gaps and delivering the government’s June 2025 Industrial Strategy. For example, the British Business Bank’s (BBB’s) ‘Growth Guarantee Scheme’ has worked with 30-40 different types of structures to guarantee over £3bn of SME lending by its delivery partners to date.
Retail banks (including RFBs) are already heavily involved in assisting these efforts, and the Industrial Strategy specifically calls upon the banking sector to provide further vital credit to key sectors like SME lending. Accordingly, the Review set out the government’s intention to ensure RFBs can fully participate in financing schemes that are guaranteed or offered by UK PuFins across their mandates – the government now intends to accomplish this using a targeted exemption.
Proposal
In order to clarify which PuFins are relevant to this exemption, the government proposes to add relevant organisations to the schedule of EAPO, focusing on the following PuFins which undertake activity that is directly relevant to retail banking activity and supports the UK domestic economy:
- The National Wealth Fund
- The British Business Bank
- UK Export Finance
This will have the additional benefit of making it explicit that said organisations should not be subject to any wider restrictions on exposures.
To remove relevant impediments, the government proposes introducing a targeted exemption to financial institution exposure rules in the EAPO to allow RFBs to hold exposures to certain types of structured financing vehicles in four main instances:
(1) PuFin Managed/Advised Vehicles
The exemption would apply where a PuFin or its subsidiaries are investment advisors to a vehicle or directly manage it as a General Partner. It would allow RFBs to provide financing to vehicles (particularly funds) directly owned or advised by PuFins – which are one method by which they mobilise capital. One example of a relevant structure is the British Growth Partnership, a fund which is advised by BBB Investment Services, an FCA-authorised entity wholly owned by the BBB.
(2) Debt Funds with PuFin Equity Stakes
The exemption would apply where a PuFin has an equity stake as a Limited Partner alongside private investors in a debt fund or majority debt mixed asset fund. This would allow RFBs to provide financing to funds that are investing in areas that demonstrably align with PuFins’ mission to improve access to finance.
To ensure the exemption remains focused on relevant investments, the government intends to set a minimum numerical threshold of PuFin involvement of 10%. A PuFin financial interest in a fund must make up more than that threshold in order for the fund invested in to become exempt from exposure rules. The threshold would apply only at the point the PuFin commitment is made – this would allow PuFins to sell down stakes in a fund without unintentionally impacting their other financing arrangements.
The government is not proposing to include equity funds as part of this proposal, on the basis that debt funds align significantly better with banks’ commercial appetites.
(3) Community Development Finance Institutions (CDFIs)
The exemption would apply to all CDFIs and not-for-profit lenders and structures that are expressly constructed to support the financing of CDFI activity. These structures, such as those used for delivery of the BBB’s Community ENABLE Funding programme, are an increasingly important channel for SME financing. For this reason, the Government is considering an exemption for CDFIs with minimal qualifications.
(4) PuFin Guarantees
The exemption would apply where a PuFin provides a financial guarantee to support the origination of lending by another financial institution. The measure is designed to supplement the existing infrastructure EAPO exemption, and proposal C2 creating an exemption for SME SPVs. It ensures RFBs can hold exposures to the full suite of financing vehicles used to support lending to government priority sectors.
The government notes that sometimes PuFins only guarantee a relatively small portion of a lenders’ overall portfolio and a broad range of structures are used for relevant lending, including sub-funds and nested trust arrangements. This adds additional complexity, as the government would only want to exempt vehicles predominantly supporting government priorities.
The government consequently intends to design this exemption in such a way that it is only used to allow RFBs to finance the specific areas of portfolios with PuFin guarantees, while retaining simplicity to aid market interpretation. The government welcomes views on how to balance these competing objectives in the design of this exemption.
Additional Considerations
The government will work with the PuFins to ensure market participants have sufficient clarity around the types of vehicles eligible for an exemption as and when PuFins establish programmes that meet one of the four instances set out above.
Question 21
Do respondents agree with the list of Public Financial Institutions that will be relevant to this exemption?
Question 22
Do respondents agree with the proposal to create an exemption for ring-fenced bodies participating in structured finance vehicles involved in Public Financial Institutions’ activities?
Question 23
Do respondents agree with the government’s proposed 10% minimum equity stake threshold for RFB involvement in debt funds?
Question 24
Do respondents agree that these exemptions should not apply in the case of equity funds?
Question 25
Do respondents believe any additional structures or instances should fall within the purview of this exemption?
Question 26
Do respondents have views on how this exemption can be designed to ensure that market participants are able to clearly identify eligible vehicles (thus minimising operational frictions)?
D.1. Pensions
Proposal D1 – RFB defined benefit pension schemes will be able to transfer a surplus to other schemes within the wider banking group, subject to conditions.
The current ring-fencing legislation does not permit an RFB to become liable for pension liabilities that arise within the banking group outside the ring-fence. This is intended to prevent an RFB from becoming liable for the pension liabilities of another bank within the same group but outside the ring-fence. Whilst it is right to ensure RFBs are protected from ongoing liabilities, feedback from industry has suggested that the legislation also acts as a barrier to surplus in an RFB pension scheme being used in a more flexible way. The government therefore committed to exploring and consulting on targeted legislative changes to enable more flexibility in how surplus within RFB pension schemes can be used across the ring-fence.
The current prohibitions on RFB pension schemes are set out in the Financial Services and Markets Act 2000 (Banking Reform) (Pensions) Regulations 2015 (the “2015 Regulations”), which were enacted using powers under section 142W and 428(3) of the Financial Services and Markets Act 2000. The government proposes to amend the 2015 Regulations to allow, subject to conditions, surplus within an RFB Defined Benefit (DB) pension scheme to be shared with schemes within the wider banking group.
To enable this, the government proposes adding a new “prescribed case” in the 2015 Regulations, setting out the circumstances and conditions whereby transfer of surplus funds will be permitted from a DB scheme in the RFB to a Defined Contribution (DC) scheme in the NRFB. The conditions under this new prescribed case are proposed to include:
- Both schemes party to a transfer must be part of the same trust;
- The transfer must be one-off, must not give rise to any ongoing obligations from the RFB or ceding scheme, and must ensure that no rights or liabilities in relation to the transferred assets remain with the RFB or ceding scheme after completion;
- The receiving scheme must be a DC scheme and must not be one in which the RFB becomes an employer;
- The ceding scheme must be a DB scheme; and
- Trustees must notify the PRA following a transfer of surplus from an RFB DB scheme to a DC scheme in an NRFB.
Other legislative rules and requirements in connection with transfers of surplus between schemes under a single trust, as well as the fiduciary duties of trustees, would continue to apply.
The Pension Schemes Act 2026 introduced reforms enabling more trustees of well-funded DB schemes to share surplus funds with employers and benefit members. On 10 June 2026, the government published a consultation on draft regulations, setting out the conditions that trustees must meet before surplus can be released, including protections designed to ensure that members’ promised benefits remain secure.[footnote 1] As the government’s proposed changes to ring-fencing legislation relate to the transfer of surplus between schemes under the same trust, and are not concerned with surplus payments to employers or members, these conditions will not apply where surplus is transferred from an RFB DB scheme to an NRFB DC scheme.
Question 27
Do respondents agree with our proposal to allow RFB schemes flexibility in use of surplus funds?
Question 28
Do respondents agree with the proposed conditions under the new prescribed case?
E.1. Other areas
The government is seeking to understand if any further technical changes could be made to address barriers to RFBs supporting the UK real economy.
Question 29
Are there other areas where respondents consider that technical changes to ring-fencing legislation are needed to remove material barriers to RFBs supporting the UK real economy?
4. Preliminary considerations for the Impact Assessment and Equalities Impact
Impact Assessment
The proposals in this consultation aim to retain the foundations of the regime and preserve important financial stability protections, while remodelling them to be more flexible and responsive to changes in the economy, financial markets and the wider prudential and resolution regimes.
The government is required to undertake an impact assessment of the proposed reforms, considering the package of reforms as a whole, as well as individual proposals. The assessment will be published alongside the final secondary legislation that will give effect to the reforms.
The impact assessment will notably cover the impact on:
- economic growth
- competition in the UK banking sector (both for assets and liabilities);
- the competitiveness of the UK banking sector;
- customers – both individuals and businesses; and
- the UK’s financial stability.
The government will use evidence already gathered through the Review, which drew on significant engagement with the ring-fenced banks and other industry participants, as well as evidence gathered through the Skeoch Review.
The impact assessment will also include an assessment of the costs of implementing the reforms and will consider any potential unintended consequences and associated costs that any of the proposed reforms could have.
The government welcomes views from stakeholders on the potential costs and benefits of implementing the proposed near-term reforms to inform its impact assessment.
Environmental Impact
The 2021 Environment Act requires policymakers to have ‘due regard’ to the Environmental Principles Policy Statement (EPPS) when making policy. This means that HMT needs to carefully consider potential environmental impacts throughout the policymaking process whilst carefully adhering to the five principles laid out in the statement.
The government will undertake a full assessment to fulfil its obligations under the EPPS. Its preliminary view is that the proposals designed to increase the flow of finance to infrastructure projects may have very minor environmental impacts, but these are likely to be net neutral or positive given relevant consultation proposals largely focus on expanding financing of renewable energy infrastructure.
Question 30
Do you agree with the provisional assessment that the government’s proposed reforms will have a negligible or slightly positive environmental impact?
Question 31
If you disagree, do you have any further data you can provide on the potential impacts on the environment?
Equalities Impact
When developing its policy proposals, the government is required to comply with the Public Sector Equality Duty (PSED) in s.149 of the Equality Act 2010. The PSED requires the government to have due regard to the need to:
- eliminate discrimination;
- advance equality of opportunity; and
- foster good relations (between people who share a protected characteristic and people who do not share it).
The government will undertake a full assessment to fulfil its obligations under the PSED. Its preliminary view is that the proposals will not have an impact on those sharing protected characteristics.
Question 32
Do you agree with the provisional assessment that the government’s proposed reforms will not have an impact on those sharing particular protected characteristics?
Question 33
If you disagree, do you have any further data you can provide on the potential impacts on persons sharing any of the protected characteristics?
5. Summary of questions
Size of the allowance
Question 1 - Do respondents agree with the proposal to include the RWAs generated by activity undertaken under the allowance within the 10% RWA calculation?
Question 2 - Do respondents agree to the proposed approach to calculating the RWAs that count towards the allowance (i.e., counting all RWAs but excluding operational risk)?
Question 3 - Do respondents have views on whether the market risk caps will affect the ability of RFBs to use the allowance to support the real economy?
Measuring the allowance
Question 4 - Do respondents agree that the allowance and activity undertaken within the allowance should be calculated using an average quarterly measurement from the preceding 36-month period?
Question 5 - Do respondents agree that RFBs should use the same methodology (IRB or standardised approach) for calculating the size of their allowance as they are using for calculating their capital requirements?
Question 6 - Do respondents agree that the allowance should apply at the sub-consolidated level of the RFB group?
Approach to other allowances
Question 7 - Do respondents agree with the proposal to incorporate the SME equity investment exemptions within the allowance?
Question 8 - Do respondents agree with the proposal to incorporate the RFI de minimis within the allowance?
Question 9 - Are there any other thresholds or exemptions within the regime that the government should consider absorbing within the allowance?
Disclosures
Question 10 - Do respondents agree with the proposal to require banks to disclose the activities and sectors supported by the allowance or have feedback on how disclosures should be operationalised?
Interactions with other aspects of the regime
Question 11 - Do respondents agree that the introduction of the allowance would not create unintended consequences for the calculations of the secondary threshold?
Question 12 - Are there any other elements of the regime whose operationalisation could be affected by the implementation of the allowance?
Permitted Products
Question 13 - Do respondents agree with the proposal to permit ring-fenced bodies to offer a significantly wider range of simple derivative risk management products, using the market risk residual risk add-on criteria and the existing safeguards?
Question 14 - Do respondents agree with the retention of the safeguards detailed in section 3.23, and if this could be detrimental to the RFB’s ability to effectively support their customers?
Question 15 - Do respondents have any comments (with quantitative evidence) on the calibration of the existing gross and net market risk thresholds?
Relevant Financial Institutions
Question 16 - Do respondents agree with the proposal to permit RFBs to hold exposures to Undertakings for Collective Investment in Transferable Securities funds?
Question 17 - Do you agree with the government’s decision not to create a legislative carveout for firms that deal purely as agent?
Question 18 - Are there any other financial institutions which in your view meet the criteria for removal from the list of prohibited counterparties set out in this consultation?
Structured Finance Vehicles for Small and Medium Sized Enterprise lending
Question 19 - Do respondents agree with the government’s proposal to permit RFBs to hold exposures to Structured Finance Vehicles set up for the purposes of securitising SME loans?
Special Purpose Vehicles for Infrastructure projects
Question 20 - Do respondents agree with the government’s proposal to broaden the definition of infrastructure and if so, what should be captured?
Public Financial Institutions
Question 21 - Do respondents agree with the list of Public Financial Institutions that will be relevant to this exemption?
Question 22 - Do respondents agree with the proposal to create an exemption for ring-fenced bodies participating in structured finance vehicles involved in Public Financial Institutions’ activities?
Question 23 - Do respondents agree with the government’s proposed 10% minimum equity stake threshold for RFB involvement in debt funds?
Question 24 - Do respondents agree that these exemptions should not apply in the case of equity funds?
Question 25 - Do respondents believe any additional structures or instances should fall within the purview of this exemption?
Question 26 - Do respondents have views on how this exemption can be designed to ensure that market participants are able to clearly identify eligible vehicles (thus minimising operational frictions)?
Pensions
Question 27 - Do respondents agree with our proposal to allow RFB schemes flexibility in use of surplus funds?
Question 28 - Do respondents agree with the proposed conditions under the new prescribed case?
Other Areas
Question 29 - Are there other areas where respondents consider that technical changes to ring-fencing legislation are needed to remove material barriers to RFBs supporting the UK real economy?
Environmental Impact
Question 30 - Do you agree with the provisional assessment that the government’s proposed reforms will have a negligible or slightly positive environmental impact?
Question 31 - If you disagree, do you have any further data you can provide on the potential impacts on the environment?
Equalities Impact
Question 32 - Do you agree with the provisional assessment that the government’s proposed reforms will not have an impact on those sharing particular protected characteristics?
Question 33 - If you disagree, do you have any further data you can provide on the potential impacts on persons sharing any of the protected characteristics?
6. Privacy notice
Introduction
This Privacy Notice should be read alongside HM Treasury’s Personal Information Charter. The Charter sets out:
- the standards you can expect from HM Treasury when we use your personal information;
- the contact details for our Data Protection Officer;
- how to exercise your Data Protection Information Rights (including access);
- how to exercise your right to complain to the Information Commissioner’s Office.
https://www.gov.uk/government/organisations/hm-treasury/about/personal-information-charter
This Privacy Notice supplements the Personal Information Charter and outlines additional information in relation to the consultation.
Data Controller
A data controller makes decisions about processing activities. They exercise overall control of the personal data being processed and are ultimately in charge of and responsible for the processing.
The data controller for this processing activity is HM Treasury.
Data Processors
A data processor is an organisation or company that handles personal information on our behalf, following our instructions. Data processors do not use your information for their own purposes; they only process it as directed by us.
The following organisations are directed to process your personal information on our behalf:
| Processor Name | Function |
| Microsoft | Provision of enterprise IT services including email, document storage, collaboration tools, and infrastructure support |
Who we process personal data about
The table below outlines the categories of individuals whose personal data we will process in this activity, alongside the types of personal data we will use.
| Category of Individual | Types of Personal Data | Special Category Data |
| Individuals responding to this consultation | • Respondents’ names, • email addresses, their • job titles, • employer details |
N/A |
HM Treasury do not require, and do not request, special category or criminal convictions data to process responses to this consultation.
Source of your Personal Data
Personal data of the individuals listed above will be collected in the following ways:
Directly - from respondents’ email submissions.
Purpose and Lawful Basis
We will process your personal data for the following purposes and using the specified lawful bases:
| Purpose | Lawful Basis | Further Information |
| To receive feedback and representations from interested parties on the government’s proposed approach to reforming the ring-fencing regime via changes to secondary legislation | UK GDPR Article(6)(1)(e) – processing is necessary for the performance of a task carried out in the public interest | This task is consulting on the development of departmental policies or proposals to help us to develop good effective policies |
Who we share your personal data with
Your personal data will only be shared internally with HMT staff who have a business need to access it.
We will share your responses, including your personal data, with the following types of external recipients:
- The Prudential Regulation Authority (PRA)
- The Financial Conduct Authority (FCA)
International Transfers
Your personal data will not typically be transferred to an international recipient during this activity. However, through the use of Microsoft services, your personal data might be transferred to a processor based outside of the United Kingdom. Where Microsoft or its authorised sub-processors transfer personal data outside the UK, we will ensure an appropriate legal mechanism applies and the relevant conditions are met. For more information on Microsoft processing, please see their Privacy Statement: Microsoft Privacy Statement – Microsoft privacy.
How long we hold your personal data
We will retain the personal data only for as long as necessary to fulfil the purposes for which it was collected – for this activity, it will be held until the consultation process has been completed and the policy is implemented. After this, we will retain personal data for a maximum of 5 additional years.
Automated Decision-Making and Profiling
This activity does not involve automated decision making or profiling. This means that decisions which may affect you are not made solely by automated means without human involvement, and your data is not subject to analysis intended to evaluate or predict aspects such as your behaviour, preferences, or interests.
Annex A: Glossary of Terms
BBB – British Business Bank
DB – Defined Benefit
DC – Defined contribution
EAPO – Excluded Activities and Prohibitions Order 2014
EPPS - Environmental Principles Policy Statement
FCA – Financial Conduct Authority
FPC – Financial Policy Committee
FSBRA - Financial Services (Banking Reform) Act 2013
FSMA - Financial Services and Markets Act 2000
CDFIs - Community Development Finance Institutions
GSIB – Global Systemically Important Bank
HMT – His Majesty’s Treasury
ICB - Independent Commission on Banking
IFRS - International Financial Reporting Standards
IRB – Internal Ratings-Based
MREL - Minimum Requirement for own funds and Eligible Liabilities
NRFB – Non-Ring-Fenced Body
PRA – Prudential Regulation Authority
PSED - Public Sector Equality Duty
PuFins – Public Financial Institutions
RFB – Ring-fenced Body
RFIs – Relevant Financial Institutions
RRAO - Residual Risk Add-On
RWA – Risk-Weighted Assets
SME - Small and Medium Enterprise
SPV – Special Purpose Vehicle
SRFRs - Smarter Ring-Fencing Reforms
The 2015 Regulations - The Financial Services and Markets Act 2000 (Banking Reform) (Pensions) Regulations 2015
The Allowance – New Growth Allowance to permit firms to undertake activities otherwise prohibited by the regime up to 10% of Pillar 1 risk-weighted assets for credit risk to support financing for UK businesses.
The Skeoch Review - Independent review of the operation of the ring-fencing regime. This review was undertaken by a panel of independent experts led by Sir Keith Skeoch and it delivered its final report in March 2022.
UCITS - Undertakings for Collective Investment in Transferable Securities