Consultation on proposals for a revised system of financial support for abattoirs and game handling establishments
Updated 4 September 2026
Applies to England, Northern Ireland and Wales

© Crown copyright 2026
This publication is licensed under the terms of the Open Government Licence v3.0 except where otherwise stated. To view this licence, visit nationalarchives.gov.uk/doc/open-government-licence/version/3 or write to the Information Policy Team, The National Archives, Kew, London TW9 4DU, or email: psi@nationalarchives.gov.uk.
Where we have identified any third party copyright information you will need to obtain permission from the copyright holders concerned.
This publication is available at https://www.gov.uk/government/consultations/consultation-on-proposals-for-a-revised-system-of-financial-support-for-abattoirs-and-game-handling-establishments/consultation-on-proposals-for-a-revised-system-of-financial-support-for-abattoirs-and-game-handling-establishments
1. Purpose of the consultation
This consultation seeks views on proposals for a revised system for financial support for abattoirs and game handling establishments in England, Wales and Northern Ireland to be delivered, subject to ministerial agreement and central funding, through discounts to charges for Food Standards Agency (FSA) official controls (inspections).
The consultation invites views and evidence on:
-
the FSA’s rationale for change and the proposed revisions to the system of support to meet that rationale.
-
alternative views or suggestions that could help refine the proposals before final decisions are made by the FSA Board and ultimately Ministers in the three nations.
-
the potential impact on food business operators (FBOs), consumers, and the wider food system that would arise from the changes.
The responses will inform the final policy and ensure that any changes to the discount framework that are recommended to the FSA Board and ultimately ministers are evidence-based, proportionate and transparent.
There are two distinct elements to the FSA’s meat charging regime: The charges for official controls, and the financial support provided via a discount scheme. At this stage the FSA is not consulting, or inviting views, on any changes to the system beyond those outlined in this consultation which relate solely to proposals for a revised system of financial support via discounts to charges for official controls.
2. Geographical scope of consultation
This consultation extends to the FSA’s geographical remit of England, Wales and Northern Ireland.
3. This consultation will be of most interest to:
-
food business operators (FBOs) in the meat industry whose activities are subject to inspections charged for by the FSA including the operators of approved slaughterhouses, cutting plants and game handling establishments in particular those who receive a discount on their charges.
-
trade bodies representing such FBOs.
-
customers of such FBOs (including primary producers) and their trade associations, such as Farmers Unions.
-
professional bodies representing those who carry out inspections in meat premises.
-
associations and groups representing interests of consumers in relation to food or managing public money.
4. How to respond
Please respond using the online consultation response form. Alternatively, you can respond via e-mail at: meatchargingpolicy@food.gov.uk. (See Section 13)
5. Introduction
5.1 General background
The FSA is responsible for meat hygiene official controls in approved slaughterhouses, cutting plants and game handling establishments in England, Wales and Northern Ireland. This includes the inspection of animals and products to ensure they are fit for human consumption, and the verification of FBO processes and procedures to ensure they have complied with food safety/hygiene legislation. In England and Wales, these functions are carried out by FSA-authorised Official Veterinarians (OVs) and Meat Hygiene Inspectors (MHIs). In Northern Ireland these functions are carried out by FSA-authorised DAERA OVs and MHIs under the terms of a Service Level Agreement. Abattoirs and game handling establishments cannot operate unless the competent authority is present to carry out controls.
The FSA charges FBOs for the time spent by officials carrying out official controls in England, Wales and Northern Ireland. Whilst general charging arrangements are the same across England, Wales and Northern Ireland, the delivery model in Northern Ireland is different. More detail on general charging arrangements can be found on the ‘Charges for controls in meat premises’ page on the FSA website.
In this consultation, unless otherwise specified, the term ‘abattoir’ is used collectively to cover establishments potentially eligible for support such as abattoirs and game handling establishments.
6. Approach to financial support
6.1 History of support
Between 2001 and 2009, the UK operated a charging system for official meat controls that allowed operators to pay the lower of either species-based rates (set by EU minimums) or time charges for veterinary and inspection staff. This system did not cover the full costs.
A discount scheme was introduced in 2009 with time-based charging and using 2008/09 throughput data. This scheme was eventually deemed unsuitable, it risked distorting competition by resulting in widely varying charges for similarly sized abattoirs, offered little motivation for efficient use of inspection resources, and was criticised for its lack of transparency and clarity for food business operators.
6.2 Current discount scheme (from 2016/17)
The current discount scheme was designed to replace the 2009 scheme with a ‘fairer’ system for distributing a ‘discount pot’. The scale of the pot was based on retaining the overall support provided in the previous year not on a new calculation of absolute need. The approach was implemented by the FSA from 2016/17.
Discounts are applied to charges for red meat slaughterhouses, poultry slaughterhouses, on farm slaughtering facilities and game handling establishments. Charges to cutting plants are not discounted nor, from 2023/24, are charges relating to formal enforcement action or charges for export-related activity. In Northern Ireland there are no charges applied to export-related activities. The scheme is structured to provide support to all operators and whilst the greatest proportional support goes to the smallest, larger operators receive greater support in cash terms.
Functionally, discounts are applied based on the hours of OV and MHI resource deployed to meet operators’ needs on a progressive basis. The total amount available for discount in that financial year (the “discount pot”) is apportioned according to bands of hours of OV/MHI time to which each is allocated a percentage discount.
Further information on the current discount scheme can be found in the 2026/27 Charges Guide for England and Wales, the 2025/26 Charges Guide for Northern Ireland and in the technical ‘Guide to Meat Charging Discount System’ (September 2016).
6.3 Managing public money guidance
As Accounting Officer, the FSA Chief Executive is accountable for the stewardship of public money and assets by the FSA. Their responsibilities are outlined in Managing Public Money, Managing Welsh Public Money and Managing Public Money NI (“Managing Public Money guidance”).
The application of a discount to charges means that the FSA is not recovering the full cost of its services in line with Managing Public Money guidance. The guidance requires full cost recovery as the default expectation for public sector organisations providing services to users, although the guidance does provide for discretion with ministerial agreement. In Northern Ireland, as this is a cross-cutting issue, Executive agreement is required if the Minister chooses not to apply the full cost of service.
6.4 FSA evaluation of the current discount scheme
With the current discount scheme approaching its tenth financial year of operation in 2025/26, the FSA began an evaluation of the scheme in autumn 2024, as it is the responsibility of a regulator to review delivery. The aim of this work was to establish a clear and current rationale for any continued support that could be presented to ministers alongside proposals for the approach to its delivery.
The FSA’s initial assessment of the discount scheme identified two major issues:
-
there was no clear rationale for the funding that could be used to support an evidenced case to ministers for continued support to the sector in line with current Managing Public Money guidance. While the greatest proportional support currently goes to the smallest businesses, the largest businesses receive the majority of the discount budget and there was no clear justification for either, requiring the FSA to explore this in more depth during our evaluation.
-
the current scheme is based on the distribution of total OV and MHI hours used by industry into bands of hours, effectively determining the size of businesses relative to each other based on hours they use. These bands are then used to distribute the pot of available money. Within this relative system the business size profile, discount pot and cost profiles have all changed substantially since the scheme was conceived. This has resulted in a complex system where it is difficult for businesses to predict and FSA to calculate the level of support they might receive each year.
The FSA has reviewed the effectiveness, fairness, and sustainability of the existing discount arrangements and considered evidence from industry, internal operations and other stakeholders. This consultation continues the collaborative approach the FSA has taken throughout its evaluation and development of proposals and provides an opportunity to comment formally on the proposals.
Detailed information on the engagement that has taken place before this consultation can be found in the section on ‘Engagement and consultation process’. The FSA has also carried out a preliminary economic analysis and will produce a full impact assessment, informed by independent research conducted by external contractors (see Section 11 on ‘Impacts’) and responses to this consultation, ahead of any Ministerial decisions.
7. Main proposals
The proposals presented in this consultation are for a revised system of financial support for abattoirs and game handling establishments to be provided via discounts to FSA charges (“the revised system”) that meets the rationale identified following extensive stakeholder engagement and agreed by the FSA board. This would (a) end the current system of universal support under which operators receive some discount regardless of size, albeit with support specifically targeted towards smaller businesses, and (b) depart from an approach of determining discounts based on relative bands of hours to one based on historical throughput. It would have the following key features:
-
eligibility for support determined annually based on historical throughput.
-
level of support for eligible operators determined annually based on throughput as a single percentage discount to be applied to all eligible charges in a financial year
-
discretion for the FSA to address any exceptional circumstances at the request of / with the agreement of ministers, in line with Managing Public Money Guidance
Full details, including on the potential options for particular elements of the proposed revised system can be found in Section 8 (‘Detailed Proposals’).
7.1 Rationale for support
The proposals are underpinned by a number of assumptions that have been developed and tested through stakeholder engagement to date and evidence from a Call for Evidence (see Section 7). This work established the hypothesis that the current range of abattoir businesses supports diversity in farming and consumer choice. These are desirable public benefits and therefore this is something that should be maintained and/or grown. This formed the basis of initial recommendations and was agreed by the FSA Board.
Different scales of abattoir service different customers both up and down the supply chain, with reasonably distinct market segmentation in England and Wales (Northern Ireland is different as discussed in Section 6). While there will always be exceptions, it was found in general that: smaller abattoirs support both smaller farms and smaller retail; the largest abattoirs service larger farms and/or collection centres and larger retail and commercial customers.
As a result of this, there are two factors which combine to put pressure on smaller abattoir businesses:
-
smaller businesses struggle to absorb increased costs; both the smaller abattoirs and the smaller businesses they service
-
the manner in which we deliver regulatory controls is most efficient for the largest businesses therefore small abattoirs encounter a disproportionate regulatory burden (see ‘Equalising regulatory burdens’)
Together these mean that if we were to remove the existing support for smaller abattoirs, the significant increase in costs they would experience could damage both their viability and that of the businesses they service either through closure or the need to pass on unsustainable costs to other small businesses. This in turn would damage the wider aim of retaining diversity and choice. Maintaining support that equalises the regulatory burdens for smaller businesses addresses this risk and the need for this has been a consistent theme of our engagement.
Conversely, there no evidence has been identified to date that continuing support to larger abattoirs is necessary to maintain diversity as they are much more able to either absorb or pass on costs and our regulatory delivery is most efficient at the largest scales as discussed in ‘Equalising regulatory burdens’.
7.2 Equalising regulatory burdens
There are a wide range of factors that affect the business model and operational efficiency of a particular abattoir. It is not for the FSA as a regulator to attempt to equalise these across all businesses, however, we should aim to avoid creating any additional market distortions arising from the manner in which the FSA charges for and delivers controls.
By their nature our controls are most efficient in the largest abattoirs where several officials are required full time and throughputs are high. At very low throughputs in small abattoirs some of the efficiency is lost as not all tasks scale in the same way. The impact of this is most simply illustrated with a calculation of average regulatory cost per animal processed – the total annual charge for a business divided by total throughput.
By looking at this calculation across all businesses there is a clear trend that on average the smallest businesses have a greater regulatory cost per animal than same species large abattoirs. Equalising this burden through the provision of a discount avoids creating a market distortion arising from the manner in which the FSA delivers controls.
There are many other factors that cause cost variation between abattoirs related to their business models and as such we can only equalise burdens based on broad averages. Individual businesses may still experience significant differences.
By its nature, if we are equalising a burden, there needs to be a benchmark against which everything else is compared and adjusted. Our controls are at their most efficient for the largest abattoirs, so this is an appropriate benchmark. Both the current discount system and the proposed revised system to some extent equalise burdens and both require some form of subsidy to do this. The difference is that in the current system the largest abattoirs – the benchmark - also receive support resulting in a system of universal subsidy which goes beyond equalisation.
An alternative benchmark avoiding the need for any subsidy would be some form of “average cost for the average abattoir” approach. However, such an approach while equalising regulatory burdens would create a cross-subsidy with the largest abattoirs paying more per animal than they would otherwise need to in order for the smallest to pay less. This is undesirable and has therefore not been considered as an option.
To ensure burden equalisation and avoid either over distortion or cross subsidy, supported abattoirs should not, on average, have a lower subsidised cost per animal than the equivalent average unsubsidised large abattoir.
In discussions with the Board and stakeholders, equalising regulatory burdens was identified as an important function for any support mechanism. Our evidence to date suggests that smaller abattoirs rely on the discount equalising these burdens to be sustainable and deliver the positive outcomes identified, as set out in Section 6. Therefore, this is both a key feature of the proposals set out in this consultation and a reason for the support for wider outcomes to be delivered through a subsidy on charges rather than other mechanisms.
8. Northern Ireland: overview
As demonstrated by evidence gathered via the FSA’s stakeholder engagement to date and noted by the FSA Board, there are differences in both the abattoir and farming industry structures in Northern Ireland where, unlike in England and Wales, large abattoirs, particularly in the red meat sector, provide services to many small producers. This includes services that would generally be delivered by smaller abattoirs in England and Wales.
Northern Ireland stakeholders have advised that this structure creates additional challenges to abattoir efficiency that may affect regulatory burdens. An additional complexity is that animals may be moved across the border to the Republic of Ireland for slaughter. Charges for official controls in the Republic of Ireland are notably less than those in Northern Ireland, resulting in competitive pressure for the meat processors in Northern Ireland.
Based on the evidence presented to date, it is assumed that the Northern Ireland beef/lamb/pork sector would pass any extra costs they could not absorb themselves on to producers through lower farm gate prices. Conversely it is assumed the poultry sector would absorb or pass cost increases down the supply chain to retailers. While these patterns are likely to be mirrored in England and Wales for abattoirs of a similar scale, the consequences in Northern Ireland may be different due to the different market structures previously outlined.
This creates a challenge in seeking to meet the FSA Board’s rationale for support detailed in Section 6 as some of the assumptions underpinning the proposed model may differ. In particular, the ability for large abattoirs to absorb and/or pass on costs, the impacts of doing so on farmers and the appropriate benchmark for equalising regulatory burdens.
It is potentially beneficial to have the same overall model of support in Northern Ireland as in England and Wales but including recognition of the differences, as is the case with the current discount scheme. Under the current approach, this means different band percentages and maximum discount in Northern Ireland. The proposed model no longer has bands that can be manipulated in this way, however, should sufficient evidence be established, ministers advised by the FSA could request the FSA to provide discretionary support to those larger Northern Ireland abattoirs. Should evidence support the use of discretion, this could help avoid any negative effects on smaller farmers which rely on their services due to the different agricultural structures.
To inform our recommendations to Ministers we are seeking further evidence on the differences in the agri-food chain in Northern Ireland compared to England and Wales, the potential impacts these have on abattoir operations and as a consequence the potential impact of any changes in discount on the wider system.
How discretion could potentially be exercised should Ministers determine it is necessary and to which sectors it should apply is discussed in Section 8.
8.1 Consultation questions - differences in abattoir and farming sectors in Northern Ireland
These questions seek evidence around the case for a different approach in Northern Ireland.
-
In what ways, if any, does the structure of the Northern Ireland agri-food supply chain present additional challenges which cannot be mitigated by the large abattoirs?
-
What are the potential impacts for the Northern Ireland agri-food supply chain, if any, of removing all financial support including the meat charging discount for large abattoirs in Northern Ireland? Please provide evidence to support your view.
-
Are the assumptions for the red meat and poultry sectors in Northern Ireland, detailed in Section 6 correct or incorrect?
-
What evidence can you provide to support your view?
9. Options development
9.1 Engagement and consultation process
In autumn 2024, the FSA began its evaluation of the scheme with a Call for Evidence on the impact of discounts on charges and how they provide benefits to businesses and consumers. A recurring theme in the responses received, principally from the meat industry and its representative bodies, was that smaller operations rely heavily on the discount for their continued viability. Responses also highlighted the important role that small abattoirs can play in local communities and economies and the potential animal welfare benefits via animals travelling shorter distances to slaughter.
The FSA Board considered a paper providing context to the evaluation and detailing the initial findings from the Call for Evidence at its public meeting on 11 December 2024. The Board directed FSA officials to conduct further stakeholder engagement to seek views on the purpose and objective of the discount, its impact on the meat industry and views on the use of taxpayers’ money. A video of the meeting and the minutes are available.
The FSA’s further work was informed by three face-to-face sessions with industry stakeholders in Belfast, Cardiff and London in February/March 2025. Over 250 establishments in receipt of the discount were notified of the sessions and encouraged to engage ahead of them, with representative organisations attending or to contact the FSA directly with their views. On 2 June 2025, the FSA hosted an online stakeholder session to reflect what it had heard during the face-to-face sessions, provide an opportunity for further comments and advise stakeholders of next steps.
The FSA Board reviewed progress of the evaluation at its public meeting on 18 June 2025, informed by a paper prepared in the light of the further stakeholder engagement and economic analysis. A formal Summary of Responses to the Call for Evidence was published alongside the paper. At the meeting, the Board agreed there was rationale for future support around delivering ‘public goods and benefits’ in the form of maintaining or increasing diversity in both farming and consumer choice and directed FSA officials to develop proposals in line with these. In so doing, the Board:
-
acknowledged that smaller businesses face a greater proportional regulatory burden; the importance of the discount to their viability; and the importance of continued support for small and some medium-sized abattoirs in the interests of consumers, businesses, the wider rural economy and supporting diversities in food supply
-
agreed there were no persuasive arguments or evidence forthcoming for the FSA providing support to large abattoirs, whilst noting the differences in industry and agriculture systems structure in Northern Ireland
-
discussed the need to provide for growth by avoiding cliff edges and how support could be targeted to recognise other factors such as compliance with standards and animal welfare
-
recognised the importance of a future support system that is simplified and operational within existing legislative parameters
A video of the meeting and the minutes are available.
Proposals for a revised support system were developed, informed by a further round of face-to-face stakeholder engagement in Cardiff, Belfast and London in September/October 2025 and further economic analysis, with individual businesses notified of how to participate as before. On 5 November 2025, the FSA hosted an online stakeholder session to reflect what it had heard during the face-to-face sessions, provide an opportunity for further comments and advise of next steps.
At its public meeting on 10 December 2025, the FSA Board considered a paper setting out proposals for a revised support system, provided direction on the potential options within the proposed system and agreed that a full public consultation on the proposals set out in the paper should be held. In so doing, the Board:
-
noted the evidence, based on responses to the Call for Evidence from farming and sustainability groups and industry engagement, of how important smaller abattoirs are for some communities and to consumer choice.
-
agreed that under the proposals for the revised system:
-
the smallest abattoirs should receive maximum support via a 90% discount on charges, noting that more smaller abattoirs would benefit from the maximum support levels under the revised system
-
some medium-sized abattoirs should receive support determined according to a decreasing taper to help minimise barriers to growth and help equalise regulatory burdens
-
the largest businesses should not receive any support as the available evidence provided no justification for continued support
-
potential additional elements to the revised system (which would not be part of the initial implementation) should be explored in the consultation
A video of the meeting and the minutes are available.
Separately, the FSA commissioned Riber Consultants, between August 2025 and February 2026, to carry out independent research, collecting evidence from abattoirs across England, Wales and Northern Ireland to inform the impact assessment.
This consultation continues the collaborative approach the FSA has taken to its evaluation of the current discount scheme and development of proposals for a revised support system.
Further to this consultation the ultimate decisions on any future support across the geographical remit of the FSA will be made by Ministers in England, Wales and Northern Ireland, advised by the FSA and in accordance with relevant Managing Public Money Guidance.
9.2 Alternative options
The FSA’s evaluation of the current discount scheme sought to establish a clear and current rationale for any continued support to present to ministers alongside proposals for an approach for its delivery. As previously set out, as a result of extensive engagement with stakeholders and the FSA Board, a lead option of a revised system is being proposed.
Whilst this is the main proposal it is important to note that two other options were considered and have been dismissed. These were:
- maintenance of universal support through the band system
- no discount (full cost recovery)
For completeness we will briefly set out the reasons for dismissing these options and are seeking any further evidence that may challenge or support the conclusion to do so.
In developing the proposals for any revised system aligned with the rationale, the FSA identified the following key objectives:
-
to meet Managing Public Money guidance with Ministerial agreement to the policy rationale for support
-
to provide value to UK taxpayers
-
to focus on need
-
to help equalise regulatory burdens
-
to provide a simplified system giving greater certainty for business
-
to provide a firm link between discount and costs that helps drive government efficiency in delivering controls
(a) Maintenance of universal support through the band system
Evidence was sought to inform the evaluation, which indicated from the outset the importance of smaller abattoirs to local communities and economies. No evidence has been forthcoming to date that supports the continued provision of support to large businesses although any such evidence would be welcomed in responses to this consultation.
In considering the current discount scheme, the conclusions of the evaluation were that:
-
it does broadly equalise regulatory burdens between small and large businesses
-
while the highest proportional support is to smaller businesses, it allocates the majority of the money available for support to large businesses where there is no evidence of need for support
-
the system is complex and difficult for FBOs to understand and for the FSA to administer
-
the relative basis is sensitive to changes in the market and FSA budget and does not provide certainty for businesses
-
it does not provide a link between the discount cost to government and cost to industry so does not directly drive government efficiency in delivering controls
The overall conclusion was that while the current scheme does broadly equalise burdens and could continue to be used to focus support on smaller businesses through reduction in support to the upper bands and changes in the hours included in the remaining lower bands, it cannot meet these needs sustainably. As the discount pot is reduced to fit within available budgets it would not be possible to maintain the levels of discount in the lower bands due to the bulk of the funding still going to the largest businesses. Consequently, the smaller businesses we are seeking to support would become disadvantaged further over time. With no rationale for supporting the largest businesses and within a fixed pot, supporting larger businesses is to the detriment of support to the smaller businesses, resulting in poor value to the taxpayer.
These conclusions have been borne out by the discount calculations for 2026/27 where, even while maximising the support to smaller businesses, the number of hours in Band 1 (90%) and Band 2 (75%) have had to be reduced to balance the budget available for discount, while larger abattoirs continue to receive a significant proportion of it.
No discount
The conclusions of the evaluation in respect of the no discount option were that:
-
it would meet Managing Public Money guidance, delivering full recovery of the costs for which we are able to charge
-
while there would be less cost to the taxpayer it may not be best value due to the potential outcomes and does not drive government efficiency in delivering controls
-
it would not focus on need and leave regulatory burdens unequally applied to the smaller abattoirs
-
a straight charge would be simpler for businesses and easier to administer
There was an argument that the outcomes of supporting diversity in farming and for consumers were not for the FSA but fell to other departments responsible for wider agricultural policy and as such the FSA should not continue to provide a discount. If funding were required to deliver these outcomes there was an argument that it should be provided through other mechanisms. However, this does not take account of the uneven regulatory burdens as a result of the manner in which the FSA delivers regulatory controls.
Evidence from the Call for Evidence and wider engagement was also clear on the potential impact of removing the discount and thus the equalisation of regulatory burden for smaller businesses. The overall conclusion was therefore that the potential consequences of unequal burdens does fall within the FSA remit and therefore there is a rationale for keeping some form of direct support from the FSA. As such the option of removing the discount altogether was dismissed.
The FSA has only considered options to reform the discount element of the charging regime. We have not considered options to reform the charging element of the regime as the drivers and rationale for doing so are different.
9.3 Consultation questions: options
The FSA has conducted an extensive engagement process including a Call for Evidence, in-person and online stakeholder engagement along with published papers informing three discussions by the FSA Board in open session to date. Through this engagement we have identified and considered a number of options, taking account of the evidence obtained to date, and our overall conclusions have shaped proposals for our lead option of a revised system.
- What additional evidence can you provide to support or challenge the conclusions the FSA has drawn?
10. Detailed proposals
This section seeks views on the range of parameters that might make up a threshold-based model for determining discount eligibility. To ensure we collect the most robust information please answer the consultation questions with respect to this specific approach.
10.1 Model for determining eligibility / level of support
Overview
To ensure a consistent approach, the FSA proposes that a model for determining annual eligibility, and the level of support for eligible establishments, would apply across the FSA’s geographical remit of England, Wales and Northern Ireland. The model would help provide certainty around support for smaller abattoirs and be designed to help minimise barriers to their growth.
Subject to central funding, the FSA would, under existing legislative powers, provide support to establishments, determined annually to be eligible for support, by means of discounts to its charges to those establishments.
There would be the facility for the FSA to exercise discretion to address any exceptional circumstances at the request of / with the agreement of Ministers in the three countries, in line with Managing Public Money Guidance.
The proposed model and its attributes are described in Section 8 of this consultation document. Where the term ‘model’ is used in this document, it should be taken to mean the application of a set of consistent criteria to determine an establishment’s eligibility for, and the level of support to be provided to eligible establishments via, a discount to FSA charges.
Legislative powers
As with the current discount scheme, discounts for eligible establishments under the revised system would be provided by the FSA using powers available to it under:
-
Article 79 of Assimilated Regulation 2017/625 (Official Controls), applicable in Great Britain
-
Article 79 of Regulation (EU) 2017/625 (Official Controls), applicable in Northern Ireland
-
Paragraphs 1 and 2 of Schedule 2 to The Meat (Official Controls Charges) (England) Regulations 2009 (SI 2009 No. 1574)
-
Paragraphs 1 and 2 of Schedule 2 to The Meat (Official Controls Charges) (Wales) Regulations 2009 (SI 2009 No. 1557 (W. 152))
-
Paragraphs 1 and 2 of Schedule 2 to The Meat (Official Controls Charges) Regulations (Northern Ireland) Regulations 2009 (SR 2009 No. 247)
Basic approach
For each financial year, the FSA would determine each establishment’s eligibility for support according to the model. For simplicity, the FSA proposes that for each eligible establishment a single percentage discount (determined based on its historical throughput) be applied.
This discount would be applied to charges for all hours required to carry out the FSA official controls referred to in Section 5 in eligible establishments in a financial year. It would remain the case that charges for any time spent on export activities or enforcement activities would not be subject to a discount, noting that in Northern Ireland charges are not applied to export-related activities).
The FSA would determine eligibility by placing each establishment in one of three categories based on historical throughput (determined using legislative Livestock Unit (LSU) conversion rates or numbers of animals) as a proxy for business size:
-
maximum support - for establishments with historical throughput up to a Threshold (Threshold 1)
-
tapered support – for establishments with historical throughput above Threshold 1 and below a higher threshold (Threshold 2) with the discount percentage determined according to a linear taper from the point maximum support ends (Threshold 1) down to the point eligibility ends (Threshold 2)
-
no automatic support – for establishments with throughput above Threshold 2
10.2 Consultation question - basic approach
The FSA is proposing an annual determination of eligibility and level of support for each eligible establishment according to the model.
- To what extent do you agree or disagree that for each eligible establishment, the model should provide an annual determination of a single percentage discount applied to all eligible charges?
-Please provide reasons for your answers including alternatives, if appropriate.
Figure 1: Application of model - examples
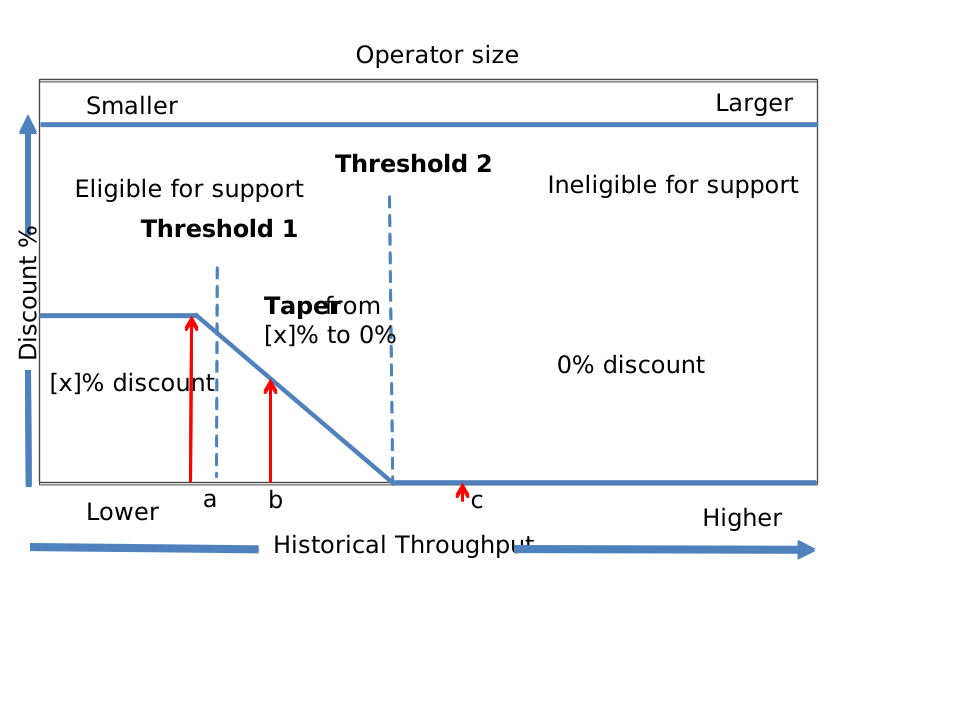
Figure 1: Application of model - examples
Description: For a given financial year, an establishment with historical throughput “a” would receive maximum discount (x%). An establishment with historical throughput “b” would receive a discount between the maximum discount (x%) and 0%. An establishment with historical throughput “c” would receive no discount.
The FSA considered a number of options that could potentially be used as a proxy for determining operator size (and hence eligibility for support / the level of any support), testing these in our engagement with stakeholders. They included: the number of days per week establishments operate; the number of staff employed; and the hours of OV/MHI time used. Challenges identified making these less reliable proxies included: the additional administrative burden of collecting and processing information on staff numbers; the number of days establishments operate not necessarily being indicative of their size; and, in respect of OV/MHI hours used, the use of Poultry Inspection Assistants (PIAs) for certain controls in the poultry sector whose hours are not captured on FSA systems.
The use of financial information such as turnover or profit was also considered and whilst potentially the most robust proxy, this information is not readily available and would be administratively burdensome to collect and process. The FSA therefore determined that for common understanding, simplicity and effectiveness, throughput would be the best proxy.
10.3 Consultation question - historical throughput
The FSA proposes to use historical throughput as a proxy for business size to determine establishments’ eligibility for support and the level of support for eligible establishments shown in Figure 1.
-
To what extent do you agree or disagree that historical throughput is an appropriate basis for determining eligibility for financial support?
-
Please provide reasons for your answers including alternatives, if appropriate.
10.4 Throughput determination
(a) Throughput time base
The FSA proposes that eligibility (and where appropriate the level of support an establishment would receive) is determined based on its historical throughput. This is to provide a proxy for business size. Using annual throughput will help to mitigate the impact of seasonal fluctuations to ensure at whatever point in the year data is taken it provides a reasonable proxy for business size. Furthermore, using a three-year rolling average may help mitigate for any unplanned or unforeseen occurrences which result in significant fluctuations in either the animal supply chain or food distribution chain across years. The preferred approach is to determine historical throughput on a three-year rolling basis to deliver these benefits on the basis that it would help smooth effects of any significant year-on-year differences. However, throughput based solely on the previous year is an alternative approach which is also being considered.
10.5 Consultation question - throughput time base
The FSA’s preferred approach to help mitigate significant fluctuations in the animal supply chain or food distribution chain is to determine throughput using historical data on a three-year rolling basis as explained in Section 8.
-Which, if any, of the following approaches do you prefer?
-
Three-year rolling basis
-
Previous year basis
-
Other (please specify)<
Please explain your choice and provide supporting evidence.
10.6 (b) Throughput categories
Under the current discount system different bandings apply depending on whether the livestock is red meat/game or poultry. Throughput is very different when comparing for example a large red meat abattoir where it is measured in thousands of animals and a large poultry abattoir where it is measured in millions. However, using throughput as a proxy for business size requires some adjustments in this approach in the categorisation of game. This is because from the perspective of relative throughput an abattoir processing small game is more similar to one processing poultry than red meat. The FSA therefore proposes simplifying the distinction to:
-
red meat and large game where throughput will be determined by LSUs
-
poultry, lagomorphs and small game where throughput will be determined by number of animals
As throughput is being used as a proxy for business size these categories provide the most accurate classification and will have different numerical thresholds for determining eligibility.
10.7 Consultation question - throughput categories
To ensure throughput is an effective as possible proxy for business size we have identified two categories which will have different threshold values as detailed in Section 8.
To what extent do you agree or disagree with establishments being placed into the following two categories:
- red meat / large game -poultry / lagomorphs / small game
Please provide reasons for your answers including alternatives, if appropriate.
10.8 (c)Throughput conversion (red meat / large game)
In determining the LSUs to use in relation to red meat and large game, the FSA considered the conversion rates set out in legislation detailed in Table 1.
Table 1: LSU conversion rates set out in legislation
| Species | Conversion Rate | |
|---|---|---|
| — | (LSUs) | LSUs |
| Regulation 1099/2009 (Animal Welfare) * | Regulation 2019/624 (Official Controls) * | |
| Adult bovine animals the live weight of which is more than 300kg and Equidae | 1 | 1 |
| Other bovine animals | 0.50 | 0.50 |
| Pigs with a live weight of over 100kg | 0.20 | 0.20 |
| Other pigs | 0.15 | 0.15 |
| Sheep and goats | 0.05 | 0.10 |
| Lambs, kids and piglets of less than 15kg live weight | 0.05 | 0.10 |
| Small (< 100 kg live weight) Deer | N/A | 0.10 |
| Other Large Game | N/A | 0.20 |
*Article 17(6) of Assimilated Regulation 1099/2009 (England and Wales) and Article 17(6) of Regulation (EU) 1099/2009 (Northern Ireland) / Article 7(2) of Assimilated Regulation 2019/624 (England and Wales) and Article 7(2) of Regulation (EU) 2019/624 (Northern Ireland).
To simplify the proposal, and to fit with data routinely collected, the FSA proposes to determine historical throughput using a single value per species based on the legislative values as set out in Table 2.
Table 2: Proposed LSU conversion rates for use in measuring throughput for the purposes of determining eligibility for support
| Species | FSA Proposed Conversion Rate |
|---|---|
| — | (LSUs) |
| Bovine animals, Equidae | 1 |
| Pigs (including piglets) | 0.2 |
| Sheep and goats (including lambs and kids) | 0.1 |
| Large game | 0.2 |
10.9 Consultation questions - throughput conversion rates
In determining throughput, the FSA proposes to use the livestock unit conversion rates set out in Table 2 for red meat and large game to avoid having to introduce additional data collection and to use numbers of animals for poultry, lagomorphs and small game.
-
Do you think Livestock Units (using the conversion rates in Table 2) are an appropriate method for measuring historical throughput for red meat and large game?
-
Do you think the number of animals is an appropriate method for measuring historical throughput for poultry, lagomorphs and small game?
Please provide reasons for your answers and any appropriate evidence.
10.10 Determining historical throughput where there is inadequate data
There may be establishments that have been operating for less than the proposed three years for determining historical throughput or where the FSA determines that the period is not representative as there has been a significant change in operations that would make the data an invalid proxy for business size (such as the closure of a significant line).
In such cases where between 1 and 3 years inclusive of historical data is available, throughput would be calculated based on a rolling average of each whole year available. Only whole years would be used in order to avoid seasonal effects, so for example if 2.5 years of data was available throughput would be determined based on the last two years.
For new establishments, or where less than one year of equivalent historical data is available, throughput would be determined nominally based on information gathered from the approval application and other pre-approval activity (such as to develop the Statement of Resources) on a pro rata basis where necessary.
If a standard period of less than 3 years is adopted as the time base for determining historical throughput (like the previous year as mentioned in Section 8) this approach would be scaled accordingly.
10.11 Determining historical throughput for mixed category establishments
The proposed approach expects throughput determination for red meat and large game to be based on Livestock Units whereas poultry, lagomorphs and small game would be based on number of animals. Historical throughput could be determined for each category and a potential discount derived from these.
The applied discount would be the lower of the two relevant discount percentages determined by applying the appropriate model thresholds to the throughput data. This should ensure that the discount applied is for the category that most effectively reflects the overall nature of the business. For example, if an establishment was determined to be eligible for 54% discount based on its historical throughput for red meat and 73% discount based on its historical throughput for poultry it would receive a single percentage discount on all its eligible charges of 54%.
10.12 Consultation questions - throughput (other factors)
There may be circumstances where the broad approach to determining throughput doesn’t work. We have considered alternative approaches in Section 8.
-
To what extent do you agree or disagree with the proposed approach for determining throughput where there is insufficient historical data?
-
Please provide reasons for your answer and any appropriate evidence.
-
To what extent do you agree or disagree with the proposed approach for determining throughput for mixed category establishments?
Please provide reasons for your answer and any appropriate evidence.
10.13 Model parameters
This section seeks views on the functioning and value of key parameters in the model. It should be considered in conjunction with the evidence set out in the draft impact assessment.
The current discount system which places an establishment within bands was designed based on a relative decile ranking. This means the smallest 10% of businesses in a category measured by the OV/MHI hours they use should fall in Band 1, the next 2 deciles in Band 2 and so on up to Band 6 which would be the largest 10% of businesses. This system is based on trying to accommodate relative rather than absolute need in order to divide a subsidy pot.
This means that as businesses grow or consolidate, or smaller businesses close, all of which has happened to a significant extent since the system was designed, objectively larger establishments which do not experience disproportionate regulatory burdens become assigned in lower bands. Conversely, a new business wishing to open could not be certain of its discount year on year as changes elsewhere could impact significantly on its discount by affecting the relative ranking, presenting a barrier to new entrants.
One of the main characteristics of the proposed model is that the level of support is linked to absolute rather than relative measures of size. By doing so, a number of the objectively smallest businesses would see an increase in the support they receive, and support would be more predictable year on year.
Eligibility would be determined for each establishment annually, for the full financial year ahead. For eligible establishments, a percentage discount would be applied to charges for all eligible OV/MHI hours used by that establishment during the financial year.
10.14 Maximum level of support (maximum percentage reduction on full cost for eligible establishments)
The FSA proposes that under the revised support system the maximum level of support to be applied to eligible charges for eligible establishments in England, Wales and Northern Ireland in a financial year should be 90%. This will equalise regulatory burdens as far as possible while maintaining a cost incentive for effective industry use of OV/MHI time.
10.15 Consultation question - maximum support
The FSA proposes a maximum level of support for eligible establishments in England, Wales and Northern Ireland of 90%.
To what extent do you agree or disagree with the proposed maximum discount level?
Please provide reasons for your answer.
10.16 (a) Threshold 1
Threshold 1 is the point beyond which maximum support (90% discount) ends. The intention is that Threshold 1 should not be subject to annual change and be linked to an objective definition of ‘small’ to ensure simplicity and clarity. The FSA proposes that this should be based on the “low capacity” definitions in legislation, namely Article 7(1)(a) of Assimilated Regulation 2019/624 (England and Wales) and Article 7(1)(a) of Regulation (EU) 2019/624 (Northern Ireland):
- 1,000 livestock units per year for red meat / large game
- 150,000 poultry/ lagomorphs / small game per year
If the FSA believes that if any change to Threshold 1 is required to continue to meet the Board’s rationale and objectives, for example as a result of any periodic review or a change in the legislation on which Threshold 1 is based, the FSA would retain the discretion to do this and would consider the nature of any change in conjunction with stakeholders.
10.17 Consultation question - Threshold 1
The FSA proposes that Threshold 1 should be the point beyond which maximum support ends and should be set at 1,000 livestock units per year for red meat / large game and 150,000 poultry/ lagomorphs / small game per year.
- To what extent do you agree or disagree with setting Threshold 1 at 1,000 livestock units per year for red meat / large game and 150,000 poultry / lagomorphs / small game per year?
Please provide reasons for your answer.
10.18 (a) The taper and Threshold 2
The taper provides a graduated reduction in support for establishments with historical throughput that falls between Threshold 1 and Threshold 2. The tapered rate would begin at Threshold 1. There would be a linear reduction in support from Threshold 1 (90% discount) down to Threshold 2 (0% discount). Any establishment with historical throughput which places it on the taper will receive a percentage discount of between 90% and 0% applied to all its eligible charged hours in a financial year.
Threshold 2 is the point at which the taper, and hence eligibility for any support, ends. Where Threshold 2 is placed will also determine the angle of the taper and hence the historical throughput range over which tapered support reduces from Threshold 1 (90% discount) down to 0% discount.
The primary role of the taper is to avoid a sudden ‘cliff edge’ reduction in support, an immediate barrier to growth for small establishments whose historical throughput increases beyond Threshold 1. To achieve this objective, Threshold 2 would need to be set in such a way as to allow a small establishment in receipt of the maximum discount to grow to a realistic extent with continuing support during that growth.
This effectively sets a lower boundary for deciding where to place Threshold 2. If it is too close to Threshold 1 there is no scope for growth before experiencing a significant loss of discount. Realistic growth for such establishments might for example be to add a second production line or to work additional days. On this basis we have assumed a lower boundary for the placing of Threshold 2 to be two to three times Threshold 1.
As noted in Section 6, a key element of the proposed approach is equalising the regulatory burden for businesses. The maximum discount up to Threshold 1 does this for the smallest businesses. The position of Threshold 2, extending the taper, can be used as a mechanism to further equalise the average regulatory burden between the smaller and larger establishments. However, there is an upper limit to the benefits of this. If Threshold 2, and therefore the taper, is too large those establishments between Threshold 1 and Threshold 2 can be ‘overcompensated’ where they experience an effective regulatory burden per LSU/animal less than the benchmark of the most efficient abattoirs.
Engagement to date indicates this is undesirable and that small abattoirs on average should not be supported to this extent. This constraint effectively creates an upper limit for where Threshold 2 can be placed. To ensure that we have sufficient flexibility both to meet those two requirements and to move Threshold 2 to manage within funding allocation without potentially breaching either of these constraints, FSA proposes that Threshold 2 should be set at 5 times Threshold 1 which translates as 5000 LSUs for red meat / large game and 750,000 animals for poultry, lagomorphs and small game.
10.19 Consultation questions - the taper and Threshold 2
The FSA is proposing to remove discounts for the largest businesses (those with historical throughput above Threshold 2 in the model), and to introduce a taper between Threshold 1 (beyond which maximum support ends)and Threshold 2 to reduce barriers to growth for smaller businesses.
-
To what extent do you agree or disagree that providing a taper between Threshold 1 and Threshold 2 will help to avoid a sudden ‘cliff edge’ drop in support?
-
Please provide reasons for your answer.
-
To what extent do you agree or disagree that the model will allow for realistic business growth for smaller abattoirs?
Please provide reasons for your answer.
-
To what extent do you agree or disagree that the principles used to set the boundaries of Threshold 2 create a fair balance between supporting smaller business and avoiding unfair competition or over-compensation?
-
Please provide reasons for your answer.
Questions on the impact of specific numbers can be found in Section 10 on ‘Impact’.
11. Additional features
11.1 Managing within FSA funding allocation
The FSA will need to fund the 2027/28 and 2028/29 discount support within its current Spending Review Settlement (see Section 10). From 2029/30 it will need to bid for funding to provide a discount according to the model as part of each Spending Review. Within each Spending Review period, there may be some variation between the settlement and our annual allocation due either to cost increases or efficiency savings. The ability of the FSA to modify the position of Threshold 2 (and hence the angle of the taper) annually would provide a mechanism to manage these variations.
Year on year cost changes are modelled as far as possible and funding bid for and managed accordingly. Most change would be managed through these systems. Additional adjustment to the taper would only be made if needed and as part of the annual discount setting process. Changes would not be made in year.
Modifying the position of Threshold 2 would have an impact on the level of discount for businesses receiving support according to the taper. As we are proposing that Threshold 1 would be fixed, the variation would be least for the smallest businesses with historical throughput just beyond Threshold 1. Any change would be greatest for those nearest Threshold 2. The impacts of this mechanism for managing variation within budgets is consistent with the overall policy approach as it would have the least impact on those smallest businesses seeking to grow beyond Threshold 1 and a relatively small change in the level of cost equalisation achieved by the taper for those near Threshold 2. This is illustrated in Figure 2.
11.2 Figure 2: Illustration of the variation of Threshold 2
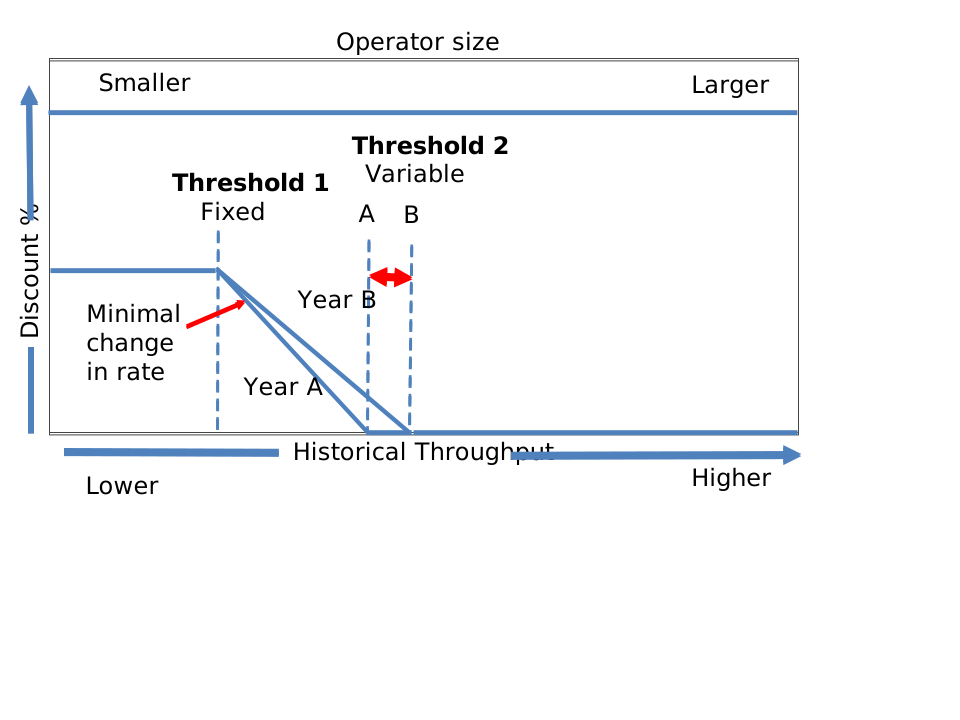
Figure 2: illustration of the variation of Threshold 2
11.3 Discretionary support
Under the proposed system, the FSA would retain discretion to address any exceptional circumstances. This is in line with the well-established principle that government should not fetter its discretion and refuse to consider valid exceptions to rules when exercising its powers, including the provision of funding. It is expected that use of this discretion would be at the request of Ministers, advised by the FSA, in line with Managing Public Money Guidance. The intention would be for any changes to be applied as part of the annual discount and charge setting process rather than making any in year changes.
The FSA would have the ability to address any circumstances which might lead to outcomes prejudicial to establishments to which the system is intended to provide support without making fundamental changes to the overall system. This would also enable the FSA to respond to any suspected manipulation of the system. The FSA is not proposing to create any mechanism where individual businesses can apply for discretionary support.
12. Northern Ireland approach
This section sets out potential approaches to addressing the specific business environment in Northern Ireland (subject to evidence and justification).
The agricultural and business structures in Northern Ireland are broadly different from England and Wales, and the Northern Ireland budget is devolved. To account for this, charges, while set on a similar basis, are determined separately, as are some elements of the current discount scheme.
There is some evidence from both the 2024 Call for Evidence and subsequent stakeholder engagement that as a result of differences in the Northern Ireland agri-food supply chain, there may be justification for providing discretionary support to larger abattoirs in Northern Ireland, specifically due to:
-
the structure of the farming system in Northern Ireland having a much greater prevalence of small farms
-
the potential impact of these structures on operational efficiency of controls in Northern Ireland abattoirs
-
the potential for cross border movement of animals for slaughter in more highly subsidised Republic of Ireland businesses
As set out in Section 6 we are seeking further evidence to determine the impact of these differences on successfully delivering the desired outcomes in Northern Ireland according to the FSA Board’s rationale. The remainder of this section seeks views on principles for how the impacts of these differences might be mitigated if the need for this is supported by the evidence provided. This is preparatory work to ensure we have consulted publicly on potential approaches and have the best evidence to hand to advise Ministers. Any difference in Northern Ireland could be implemented alongside the England and Wales scheme avoiding short term divergence. It does not pre-empt any Ministerial decision.
As with the current approach, it is desirable to have the same basic model apply in England, Wales and Northern Ireland and this is the basis of the overall proposal. However, if sufficient evidence can be presented to Ministers in Northern Ireland, they may use the discretion available, to decide that discretionary support to larger abattoirs is justified.
12.1 Integration with the basic model
The original rationale and assumptions for supporting smaller abattoirs will still hold in Northern Ireland. Therefore, we need to ensure that any discretionary support to larger Northern Ireland abattoirs would not occur to the detriment of support to smaller ones, existing or potential. To ensure this, it is proposed the following principles are applied:
-
any discretionary support for larger abattoirs would be superimposed on the basic model such that it remains within the funding allocation
-
any smaller abattoirs who qualify for support under the basic model, receive the equivalent benefits to those in England and Wales in percentage discount terms
-
support to smaller abattoirs would not be modified to balance budgets. This would instead be done by modifying any discretionary support element of the funding allocation. If no support is provided on a discretionary basis, then budget management would follow the basic model proposal of adjustment to Threshold 2
-
as with the basic proposal, eligibility for discount and the level of discount for eligible establishments would be determined annually and not in-year (except for any new establishments entering the sector in-year).
12.2 Principles for discretionary support
As set out in Section 6 there are two factors which combine to drive the need to support smaller abattoirs:
-
smaller businesses struggle to absorb increases in costs themselves; both the smaller abattoirs and the smaller businesses they service.
-
the manner in which the FSA delivers regulatory controls is most efficient for the largest businesses therefore, small abattoirs encounter a disproportionate regulatory burden.
Conversely, there is no evidence to suggest these factors apply to large abattoirs in England and Wales, so it is assumed they are able to pass on costs and provide the benchmark for efficiency. However, there are areas where the differences in Northern Ireland agricultural structures might make these challenges applicable, to a degree, to larger Northern Ireland abattoirs, namely:
-
while the abattoirs themselves are not small, there is a disproportionate number of small farms that supply them, exacerbating the negative impact of passing on regulatory costs
-
managing the process with large numbers of small suppliers may result in greater regulatory burdens than similar sized abattoirs in England and Wales as not all regulatory activities may scale, so the efficiency benchmark may be different
-
additionally, abattoirs in Northern Ireland face competition with cross border abattoirs, both in procurement of livestock and for marketing of product
As noted in Section 6 on equalising burdens, there are a range of factors that affect business models and it is not for the FSA to address them all. From a regulatory burden perspective, discretionary support would only be used to address otherwise unavoidable impact arising from the proposed revised discount system, specifically impacts on small farmers, regulatory efficiency or cross border competition. This is the basis of the following principles.
To avoid overcompensating for change in terms of setting the level of any discretionary support for larger Northern Ireland abattoirs, the two overarching principles proposed are:
-
the overall total support (including any discretionary support) should not exceed the 2026/27 levels
-
no individual establishment should get greater effective percentage discount than in 2026/27
In order to determine eligibility for any discretionary support for larger Northern Ireland abattoirs, the principles proposed are:
-
to take a sector-based (in other words, red meat/poultry etc) approach rather than creating a burdensome process to assess establishments’ individual circumstances
-
eligible sectors would be:
-
where there is evidence that additional costs cannot be absorbed and will be passed directly to small farmers
-
where there is evidence that the nature of the farmers supplying the abattoirs and/or the manner in which they do so, results in processes that reduce regulatory efficiency
-
ineligible sectors would be:
-
where neither of the eligibility criteria apply and there is no significant evidence of cross border competition
-
where there is evidence that costs are likely to be absorbed or passed through the chain to the consumer
-
sector eligibility would not be subject to regular change, but will be kept under review to ensure continued alignment with the FSA Board’s rationale for support
Sector eligibility would be established based on these principles, subject to any change which might be necessary based on further evidence presented in response to this consultation.
12.3 Potential approaches to determining discretionary support for larger abattoirs within an eligible sector
In order to determine the level of any discretionary support for larger Northern Ireland abattoirs within the overarching principles, we have identified two potential approaches, each with a different underpinning assumption of how regulatory burdens vary with size for establishments with throughput above Threshold 2 in Northern Ireland:
-
(a) an assumption that all larger abattoirs within an eligible sector are subject to equivalent burdens regardless of size. Each establishment would receive the same percentage discount on all eligible hours. When combined with the second overarching principle that no establishment should have a greater effective discount than in 2026/27 which is equivalent to benchmarking the maximum discount to that received by the largest (theoretically most efficient) establishment. The actual level of discount would also be constrained by the first principle that total support (including any discretionary support) should not exceed 2026/27 levels, so it could be below the 2026/27 level.
-
(b) an assumption that there is a size-based effect on regulatory efficiency between larger abattoirs within an eligible sector. Each establishment would receive a percentage discount on all eligible hours based on a throughput-related taper extending beyond Threshold 2, with the largest establishments in the sector getting proportionally less support. The start and end points of the taper would depend on the allocated funding for discretionary support.
Subject to the provision of strong evidence demonstrating that the criteria for support are met, the level of any discretionary support for larger Northern Ireland abattoirs within eligible sectors would be established based on the potential approaches outlined in Section 9 unless other evidence is presented in response to this consultation suggesting that there is a need to consider changes or alternatives.
12.4 Consultation questions - Northern Ireland approach
The questions in section 9 seek evidence for the need for additional discretionary support in Northern Ireland. The questions that follow seek evidence on how such support should be applied if the need is demonstrated.
-
To what extent do you agree or disagree with the principles set out in Section 9 for integrating the basic model with any discretionary support in Northern Ireland?
-
Please provide reasons for your answer and evidence if applicable.
-
To what extent do you agree or disagree with the overarching principles for setting the level of support for each establishment?
-
Please provide reasons for your answer and evidence if applicable.
-
To what extent do you agree or disagree with the eligibility principles?
-
Please provide reasons for your answer and evidence if applicable.
-
We have identified two potential approaches to applying discretionary support to larger abattoirs. Which of the following assumptions about need for discretionary support do you think best reflects the situation in Northern Ireland?
- Need is the same for all larger abattoirs
- Need varies by abattoir size -Don’t know<
-
Other (please specify)
- Do you agree the two approaches effectively apply the overarching in Section 9 for setting the level of support?
Please provide reasons for your answers and evidence, if applicable.
We have set out principles on how discretion may be applied based on our current understanding of the particular situation in Northern Ireland. However, we recognise responses to this consultation may alter this understanding. What alternative proposal(s), if any, do you have for applying any discretionary support in Northern Ireland?
Please explain why you think your approach would be better than the proposal in this consultation and how it would benefit diversity in farming and consumer choice.
13. Transition and review
13.1 Transition to the proposed system
The current Spending Review period runs for three financial years from 2026/27 to 2028/29 and allows change to be implemented over that period. The FSA proposes that the revised system of support would itself commence from 2027/28 with transition complete by the end of the Spending Review Period.
At its June and December 2025 public meetings, the FSA Board indicated that the discount for the 2026/27 financial year should meet the desired outcomes for the revised system as far as possible within the constraints of the current scheme. As such the transition towards the desired rationale and outcomes will begin in 2026/27 although the scheme itself will not change until 2027/28.
In working to deliver the Board’s rationale as far as possible in 2026/27, the FSA will protect the highest discount band (90%) and maintain the discount percentage in Band 2 (75%), this will result in a reduction in the hours in Band 2. Bands 3-6 will be set to zero discount. This approach aims to:
-
ensure the discount continues to provide the greatest proportional support to the smallest abattoirs meeting the Board’s rationale
-
minimise the possibility of establishments eligible for a discount under the revised support system receiving significantly less support in 2026/27 than they would receive under the revised system and likewise avoid alternating effects for large businesses to facilitate planning
-
ensure a smooth transition from the current system to the revised system by introducing changes at each end of the 2026/27 financial year which have a reasonably equivalent impact.
The revised system would be introduced in financial year 2027/28 as another transitional year. To achieve this, it is proposed that:
-
Threshold 1 is set at its final value so those smaller businesses that will benefit from the change do so immediately
-
Threshold 2 is set at a higher throughput than its final value so more medium sized abattoirs continue to benefit from a discount in the transition year
-
this will be done in such a way to, as far as possible, ensure a smooth transition between the 2026/27 state and the end point
-
the overall cost of support will be within the available funding allocation with priority given to meeting the 90% commitment to smaller businesses
13.2 Consultation question - transition and review
The FSA recognises the need for a smooth transition to the revised system of support and has set out its proposals for transition in Section 10.
-
To what extent do you agree or disagree with the principles of the transitional arrangements?
-
Please provide a reason for your answer including alternatives, if appropriate.
13.3 Review of the proposed system
As well as continuous monitoring of the revised system, including as part of the annual process to set charges, establish eligibility and levels of discount for eligible operators for each forthcoming financial year, the FSA proposes that it would:
-
undertake a review of the operation of the revised system of support after it has been in place for 5 financial years (such as review in 2032/33)
-
undertake a fundamental review of the revised system of support after it has been in place for 10 financial years (such as fundamental review in 2037/38)
13.4 Potential future additional elements to the proposed system
The FSA proposes that the revised system would initially operate as described in this consultation but is also taking the further opportunity afforded by this consultation to seek stakeholders’ views on elements that could potentially be introduced in the future. These are further refinements that have been suggested during stakeholder and FSA Board engagement to date but were felt needed further consideration and evidence. Any additional elements discussed in this section would not be implemented as part of the change to a revised support system from April 2027, but may be considered for future implementation, subject to further stakeholder engagement, with due regard to relevant responses to this consultation.
13.5 Linking eligibility for and level of support to wider factors
The FSA Board has asked us to consider potential future additional elements including how support could additionally be targeted to recognise factors such as compliance with quality standards and animal welfare.
Stakeholder engagement elicited mixed views on linking support to compliance. Some stakeholders suggested that any habitual non-compliance should affect eligibility for support and others indicated that the FSA already has powers and enforcement sanctions available to address non-compliance. Some felt that structural limitations could mean that small operators might be unfairly penalised and reduced support arising from non-compliance might restrict their ability to take the necessary remedial action and therefore be counterproductive.
The FSA is also seeking stakeholders’ views on the potential to make eligibility for support conditional on additional parameters beyond historical throughput, what those parameters and associated metrics might be and how they could be integrated into the revised system proposed in this consultation.
13.6 Charges eligible for discount: unworked time
As mentioned in Section 5, charges relating to formal enforcement action in England, Wales and Northern Ireland and export-related activity in England and Wales are not discounted and this will continue. (In Northern Ireland charges are not applied to export-related activities).
Currently, charges for unworked time within the Statement of Resource where staff are unable to be redeployed (coded IUWT) are discounted. The FSA is taking this opportunity to seek initial views on removing discounts from these charges. The objectives of such a change would be to encourage better utilisation of FSA resource deployed according to Statements of Resource and encourage FSA/FBO reviews of Statements of Resource where levels of unworked time are of concern. The overall aim would be to realise potential for FSA resource to be deployed elsewhere to support operations thereby improving efficiency.
13.7 Consultation questions - potential future elements
What evidence do you have to support or challenge potential future revisions of the system?
What evidence do you have to support or challenge the assertion that removing discounts for unworked time when staff cannot be redeployed in future revisions would encourage reviews of Statements of Resource and thereby improve efficiency?
Please provide reasons for your answers including alternative approaches and suggestions for future additional elements to the discount system that could be considered to improve industry support, efficiency and / or value for UK taxpayers.
14. Impacts
In line with best practice the FSA will produce an impact assessment of the revised discount regime. This will be provided to Ministers alongside our final advice to inform them in making their final decision on the scheme. The impact assessment will be published when complete.
Annex A sets out the main options and parameters that will be monetised in the impact assessment. These will be used to estimate the overall impact of the proposals. The assessment will be informed by information received to date from stakeholder discussions, data held by the FSA, research conducted by Riber Consultants and data and evidence provided in response to this consultation.
In the remainder of this section, we have provided preliminary evidence and models to aid individual businesses to understand the impact on them and therefore to inform their responses to this consultation.
The questions at the end of this section relate to both the individual impacts and the overall impacts and should be considered having read both this section and Annex A.
14.1 Individual business impacts
The cash impact on individual establishments will be dependent on their actual historical throughput being considered and the actual level of charges in the year being assessed. As these are not yet available for the first year of the revised system the estimates given in the bullets that follow should be considered illustrative and should not be used for business planning purposes.
Using the parameters set out in the bullets, and their own data, businesses will be able to approximate the likely discount percentage they might receive under the revised system and therefore estimate the impact on them. The figures provided all assume the parameters recommended in this consultation are adopted:
- maximum discount at or below Threshold 1 = 90%
- discount above Threshold 2 = 0%
- Threshold 1 is set at 1,000 LSUs/150,000 animals
- Threshold 2 is set at five times Threshold 1
For establishments with historical throughput at or below Threshold 1 this would give a discount of 90%. Using throughput and hours data from 2024/25, we estimate the number of abattoirs in England and Wales that will be eligible for a 90% discount on all their eligible hours will increase by up to 50% compared to the current discount system. Using this estimate, nearly a third of abattoirs in England and Wales would be in receipt of the maximum discount.
For establishments with throughput between Threshold 1 and Threshold 2 the discount percentage would be given by the equation
Discount % = Max discount – Max discount x (TH-T1),
T2-T1
where T1 and T2 are Threshold 1 and Threshold 2 respectively, and TH is the historical throughput of the business expressed either as LSUs or number of animals depending on the species.
For the parameters proposed in this consultation this is equivalent to
-
red meat/large game Discount % = 112.5 - 0.0225*TH.
-
poultry/lagomorphs/small game Discount % = 112.5 – 0.00015*TH.
Using throughput and hours data from 2024/25, we estimate around 21% of abattoirs in England and Wales would fall on the taper line, and around 51% of abattoirs will receive some financial support under the proposed scheme.
For establishments with a historical throughput greater than Threshold 2, the discount rate would be 0%. We estimate in the region of 49% of abattoirs will not receive a discount.
This data is summarised for an example selection of different throughputs in table 3.
14.2 Table 3: Example discount levels under the proposed basic model
| Threshold | Red meat/Large game LSUs | Poultry/ Lagomorphs/ |
|---|---|---|
| Small game throughput | Example discount under basic model | |
| Threshold 1 | Up to and including: |
| 1,000 LSUs | Up to and including: |
| 150,000 animals | 90.0% | |||
| 2 x Threshold 1 | 2,000 LSUs | 300,000 animals | 67.5% | |
| 3 x Threshold 1 | 3,000 LSUs | 450,000 animals | 45.0% | |
| 4 x Threshold 1 | 4,000 LSUs | 600,000 animals | 22.5% | |
| Threshold 2 (5 x Threshold 1) | 5,000 LSUs and above | 750,000 animals and above | 0.0% |
14.3 Consultation questions - impacts
Section 11 and Annex 1 provide the main options, parameters and models, based on preliminary evidence, to aid businesses’ understanding of the impact of these proposals upon them. In order to quantify the costs and benefits for the impact assessment, we are seeking quantifiable evidence.
In Table 3 we show example discounts for different levels of throughput, based upon the parameters proposed in this consultation. Do you have any evidence about how using these parameters would affect individual businesses? If possible, please include:
- Numerical information (such as impact on profit or turnover)
- Narrative information on expected outcomes or consequences
How do you think changing the value of Threshold 2, such as using a different multiple of Threshold 1, would affect the impacts you described?
Familiarisation costs:
In Section 15, we identify the staff roles expected to familiarise themselves with the new guidance. Do you agree that these are the roles?
If you disagreed, please tell us which roles should be added, removed, or amended and why.
Impact on consumers:
To what extent do you agree or disagree with our assessment that the proposed changes will have a negligible impact on consumers?
Please explain your answer and include evidence, if appropriate.
Benefits on the administrative burden:
What administrative time changes (savings or gains), if any, do you anticipate as a result of the revised discount system? Please provide quantifiable evidence such as estimated minutes or hours saved or required per month, where possible.
Wider economic impacts:
Do you have any comments on the wider economic impacts of the proposed changes? Please provide reasons for your answer, including evidence, if appropriate.
What other impacts from the implementation of the proposed revised scheme do you foresee, beyond those we have identified? Please provide reasons for your answer and provide quantifiable evidence, where possible.
15. Communicating with food business operators on matters relating to meat charging
The FSA is also exploring efficiencies within the current charging system and would like, where legally possible, to explore moving towards communicating with operators of approved establishments on matters relating to meat charging (such as to inform them of annual charge rates and alert them to consultations of interest to them such as this one) via electronic means. This would enable the FSA to share information on meat charging more efficiently and ensure that all operators get the same information at the same time.
The FSA proposes to write to all operators of approved meat establishments for whom we do not hold electronic contact details in September 2026 with a view to obtaining this information by the end of the year and, where legally possible, moving to electronic communication from January 2027.
15.1 Consultation question – communications on meat charging
- To enable the FSA to communicate with food business operators more efficiently on matters relating to meat charging, would you be happy for us to send all future communications electronically, where this is legally possible?
16. Responses
Responses are required by 12 June 2026.
Please respond using the online consultation response form.
Alternatively, you can respond by e-mail to meatchargingpolicy@food.gov.uk stating in your response whether you are replying as an individual or on behalf of an organisation. Please also state the location where you are based, England, Wales, Northern Ireland or other and the size of your organisation:
- 9 or fewer employees (micro)
- 10–49 employees (small)
- 50–249 employees (medium)
- 250 or greater employees (large)
For information on how the FSA handles your personal data, please refer to the Consultation privacy notice.
17. Consultation question - general
- If you would like to add any further evidence on your responses or any other suggestions relevant to the proposals discussed, please do so here.
18. Further information
If you require a more accessible format of this document, please send details to the named contact for responses to this consultation and your request will be considered.
This consultation has been prepared in accordance with HM Government consultation principles.
Thank you on behalf of the Food Standards Agency for participating in this public consultation.
Meat Charging Policy Team
Food Policy Directorate
Food Standards Agency